Transporte
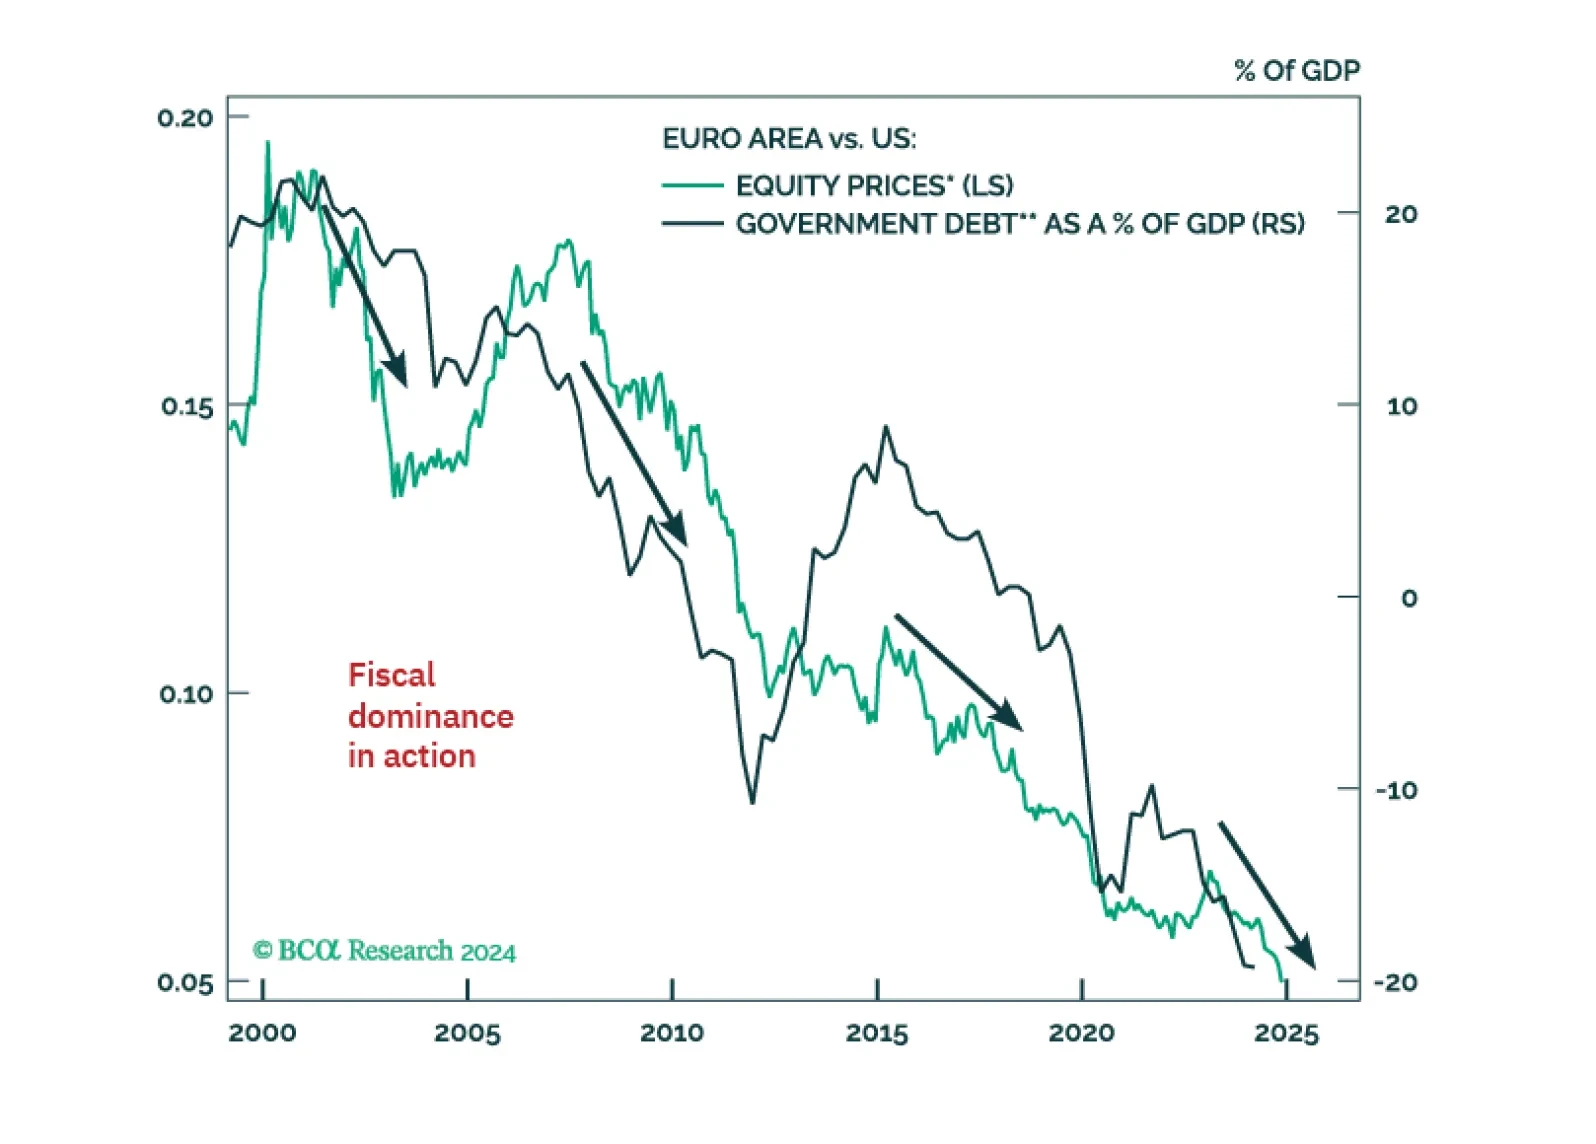
Los inversores han renunciado a los activos europeos, que ahora cotizan con descuentos excepcionales respecto a los activos estadounidenses. Sin embargo, una política fiscal estadounidense más restrictiva, el fin de la austeridad y del desapalancamiento en Europa, el tsunami de GNL a punto de golpear las costas europeas y el capex global impulsado por la Tríada Geopolítica Imposible significan que el momento de gloria de Europa pronto volverá.
Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.

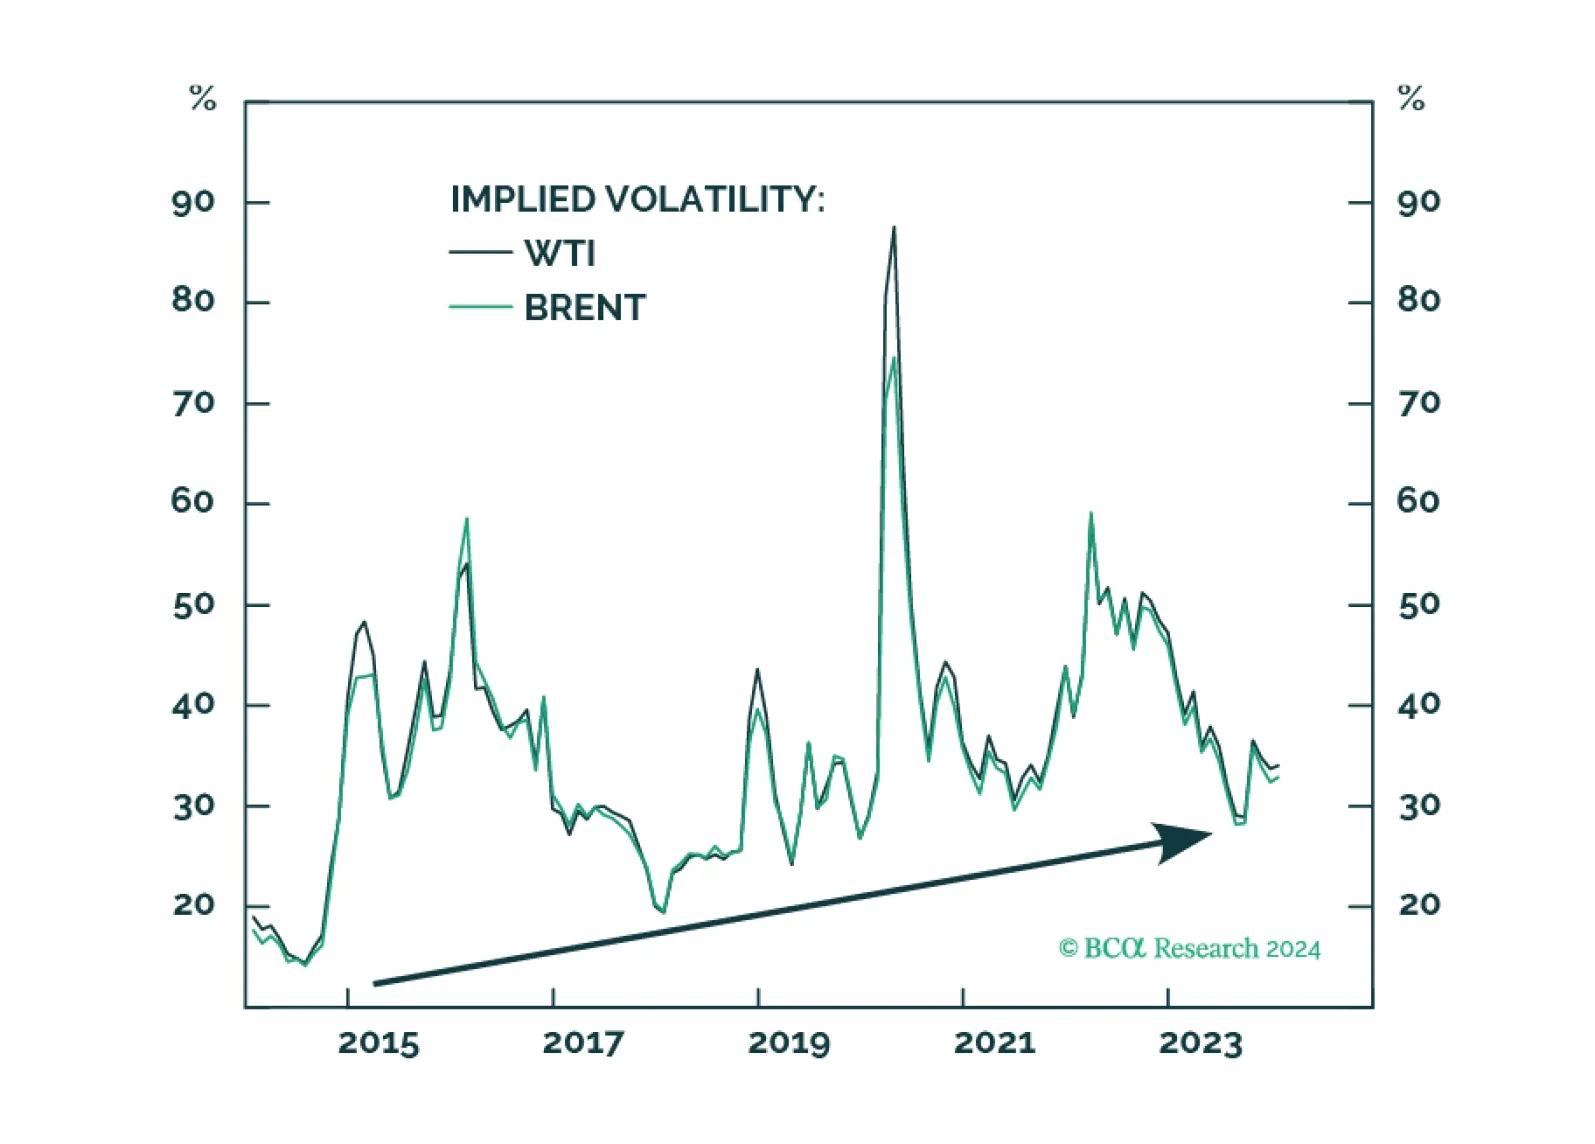
Commodity volatility will continue its rising trend since 2014. The US is on the brink of a major election, the outcome of which could reduce its willingness to engage with the outside world. So, states seeking to carve out their own spheres of influence are incentivized to raise the economic costs to the US and discourage its influence in their regions. These states can do this by interfering in key trading routes in their regions. As a result, geopolitical threats to maritime chokepoints are a structural as well as cyclical problem and will persist due to the revival of superpower competition.
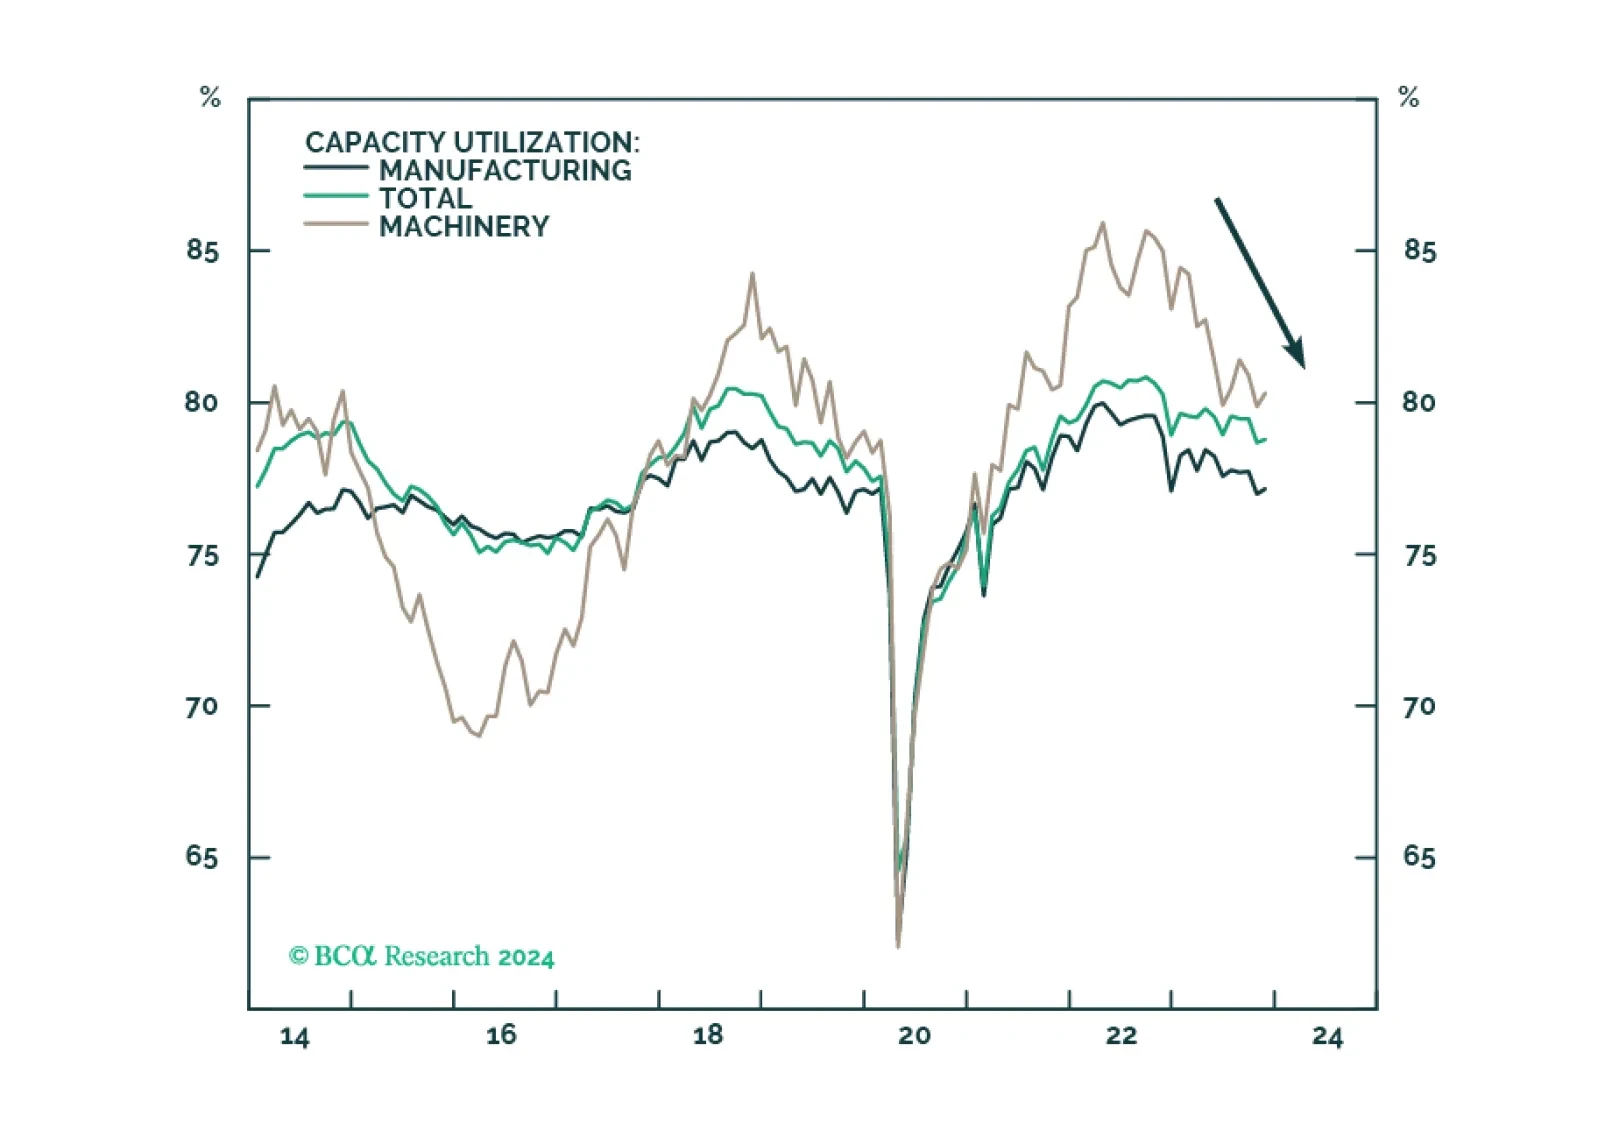
The US manufacturing renaissance, spurred on by reshoring, automation, and government spending, is running its course but progress has slowed on the back of tight monetary conditions and the manufacturing recession. The deceleration of these positive trends weighs on the outlook for the Capital Goods industry group, impeding its performance over the short term. However, we reiterate that positive long-term trends for the industry remain intact. We downgrade Capital Goods to a tactical underweight. It remains a strategic overweight.
Domestic auto sales in China will likely have anemic growth over the next three years. Yet, Chinese automakers are set to gain a larger share of the global market. Go long Chinese automakers / short global ones.

The trajectory of China’s infrastructure investment in 2023H2 will be like what occurred in 2021H2. Growth will likely drop from the current nominal 10% to 0-2% in the next six months. China will continue promoting environmentally friendly infrastructure projects that may prevent a contraction in infrastructure investment in 2023H2.