Monedas en profundidad
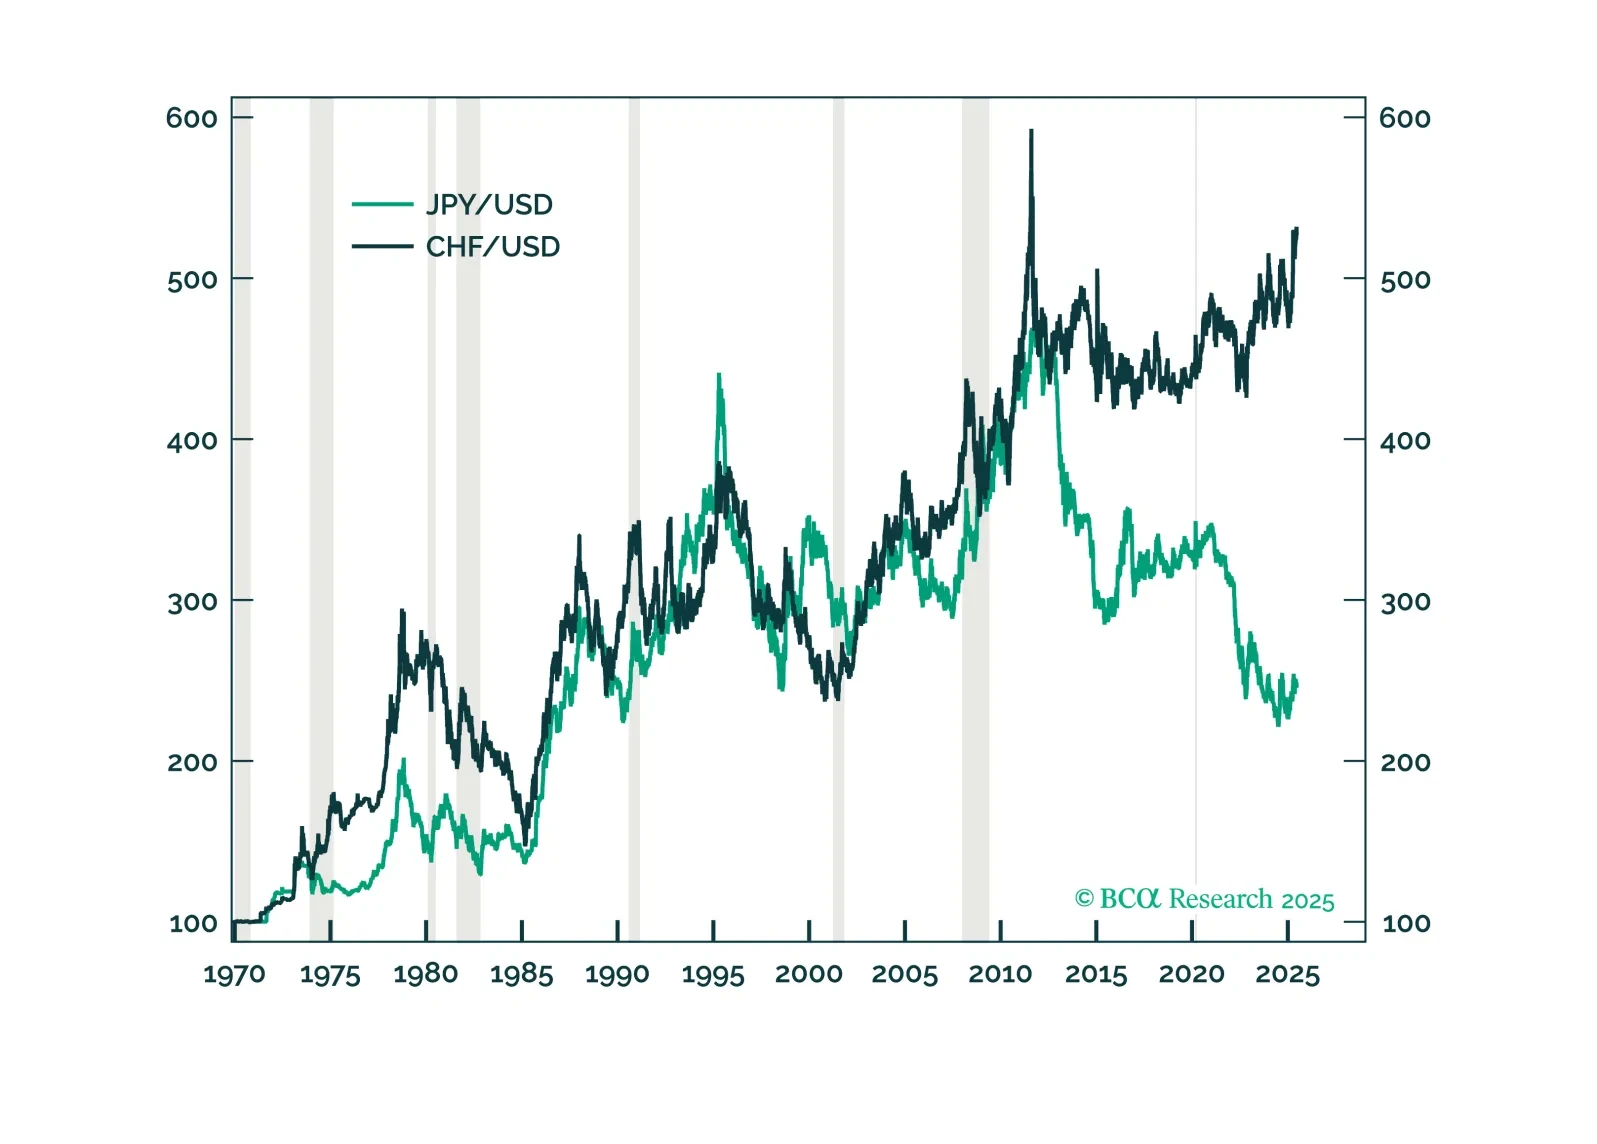
En este análisis, destacamos nuestras operaciones de alta convicción basadas en las reuniones de los bancos centrales realizadas por el Banco de Inglaterra, el Banco de Noruega, el Banco Nacional Suizo y el Riksbank.
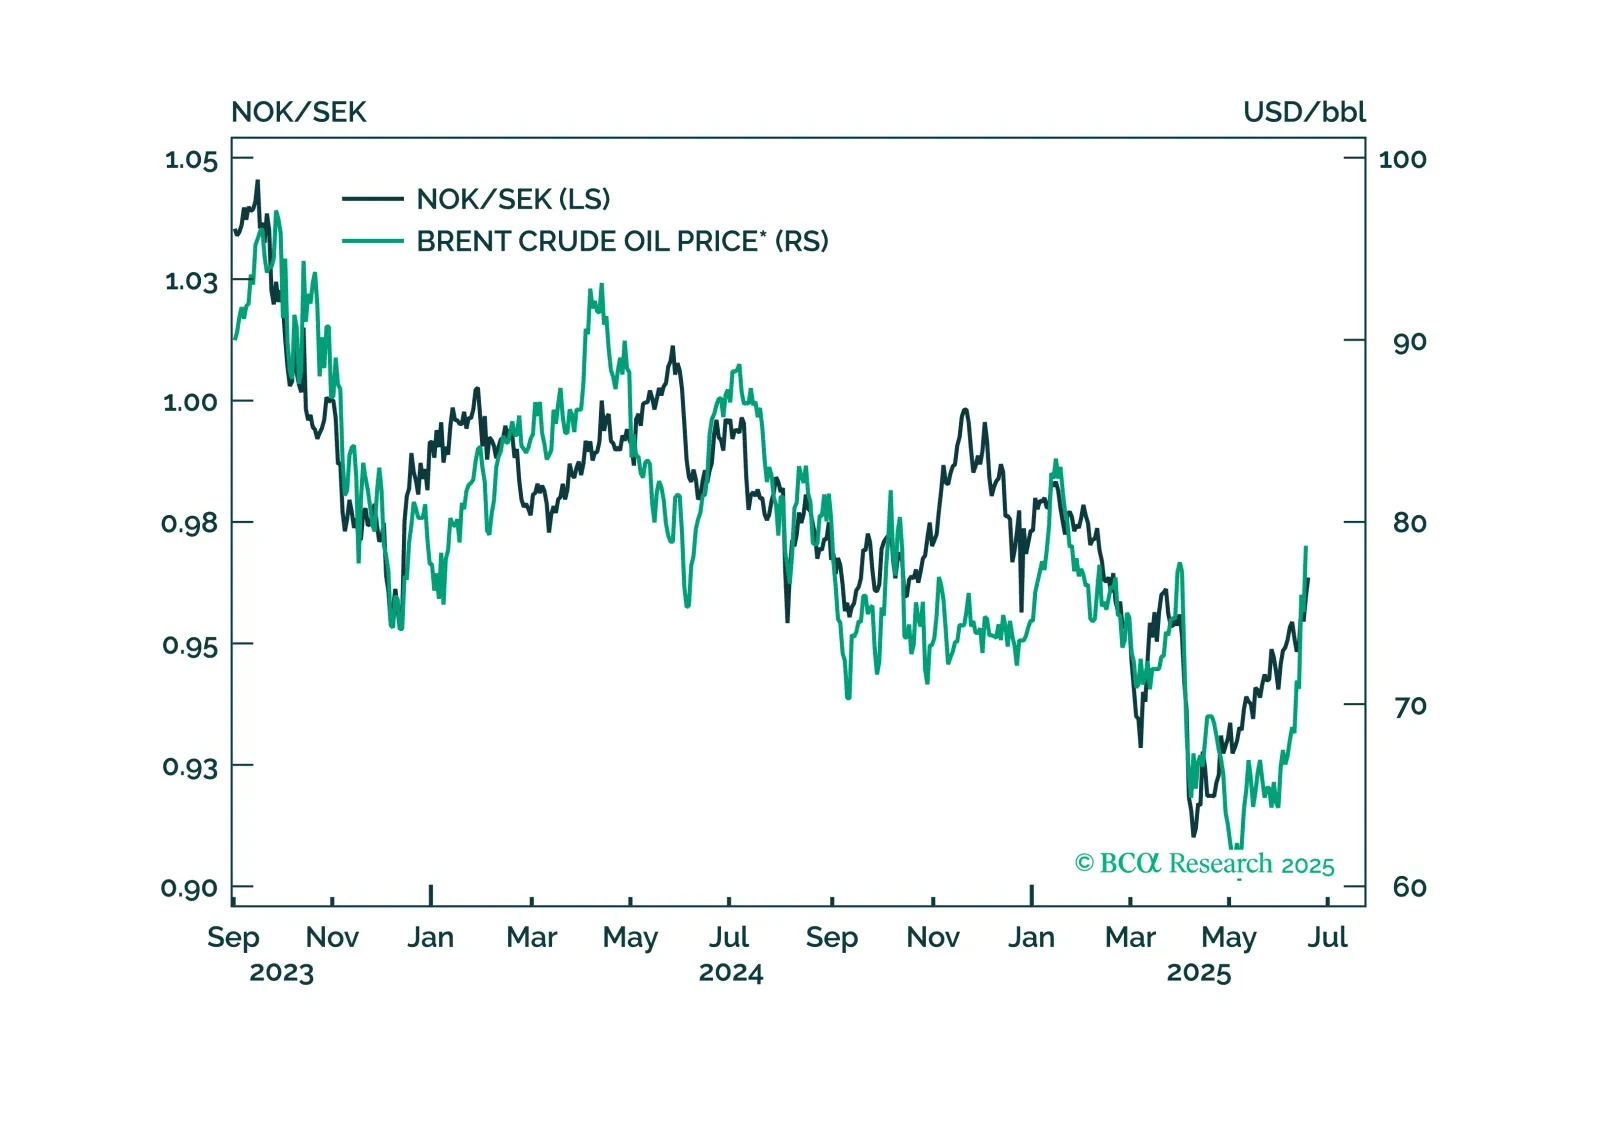
En este análisis, examinamos la mejor idea de negociación tras la reciente reducción de tasas por parte del Riksbank.
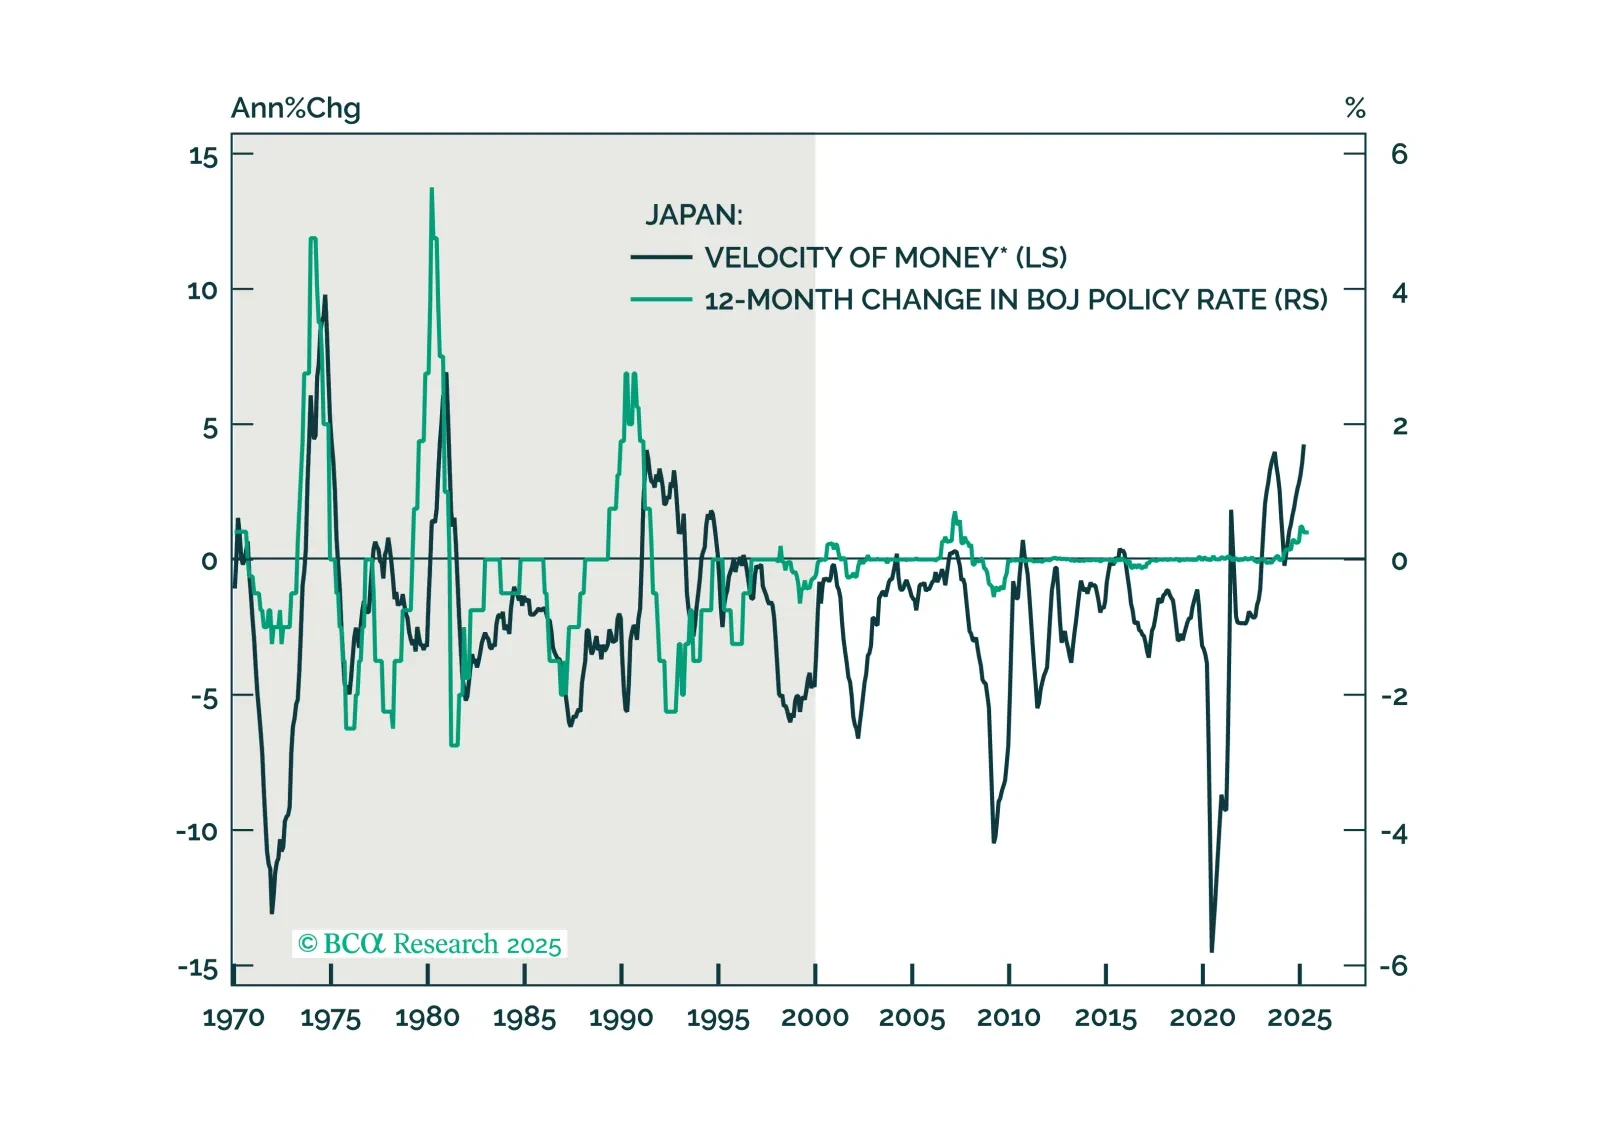
En esta nota, reafirmamos nuestra posición de infraponderación en los JGBs y posiciones largas en yenes dada la reunión del BoJ durante la noche.

In this FX note, we provide a rationale for why it is important to pay attention to technical indicators, while still keeping your eyeball on the structural factors that drive currencies. This report answers the following questions: 1. Should you buy or sell the USD over a three-to-six month period from the pure lens of our proven technical indicators and 2. What are the best tactical cross trades among currencies.
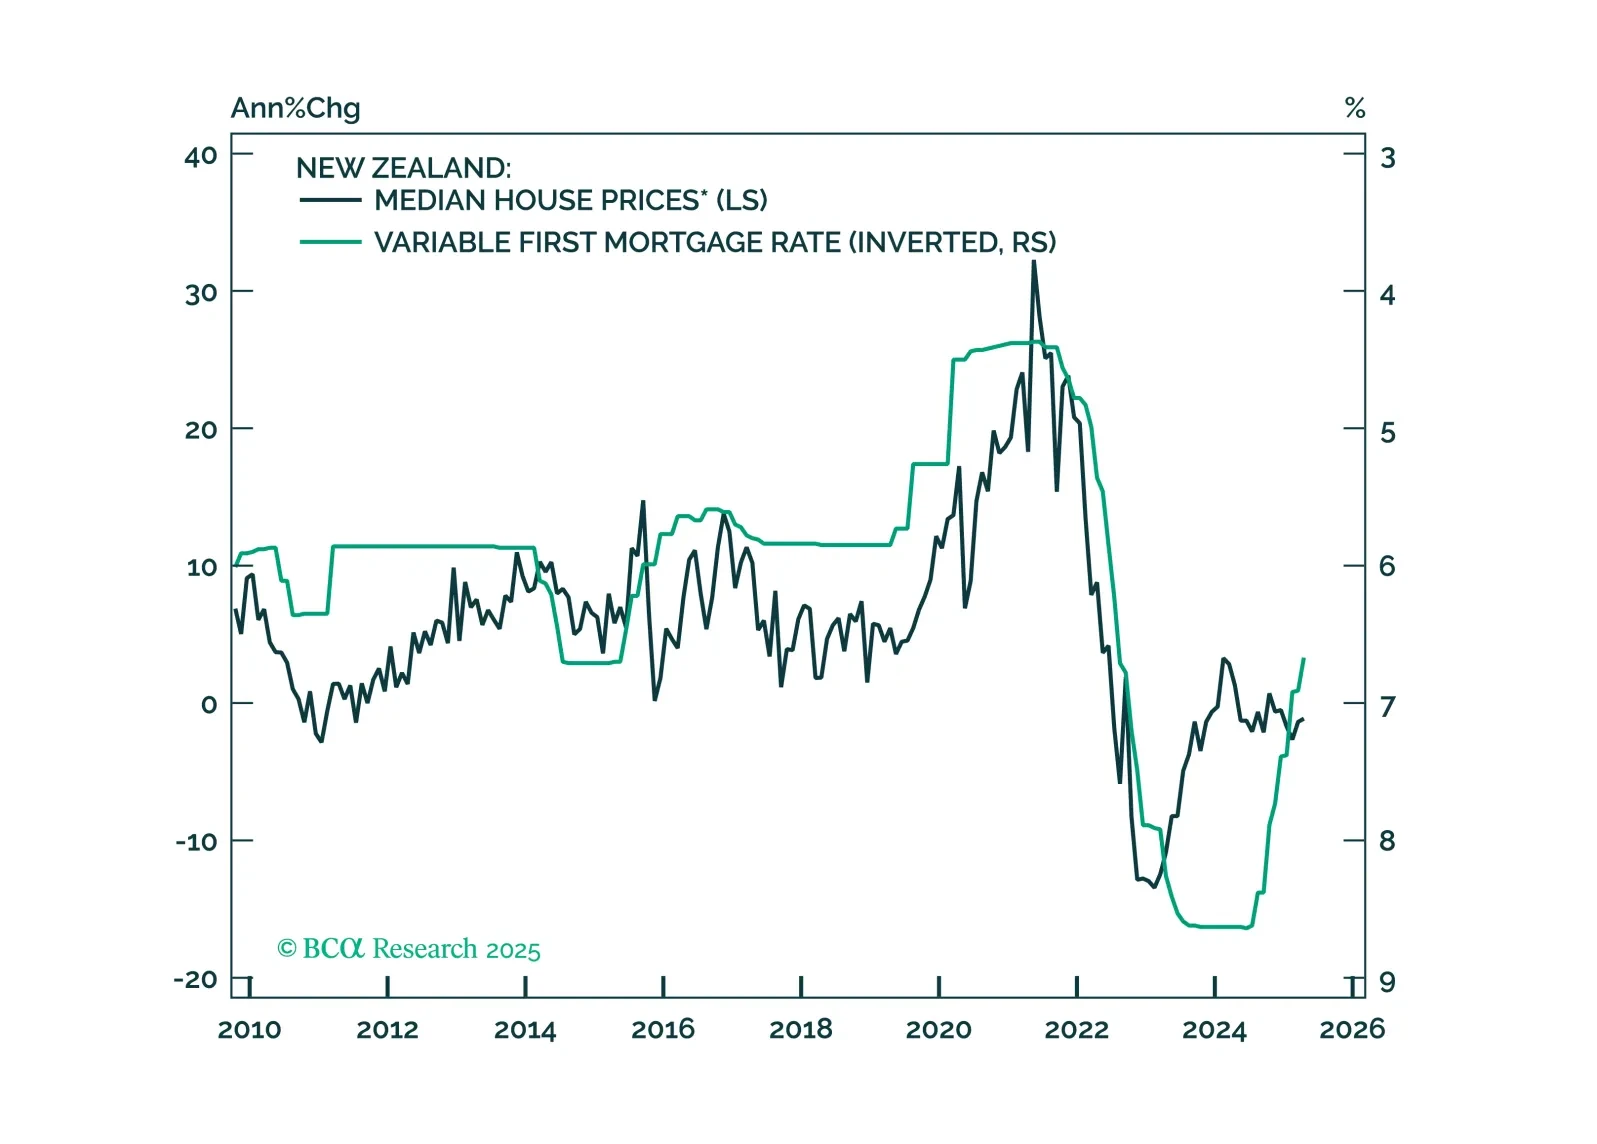
This Insight looks at the implications of the RBNZ’s rate cut on New Zealand assets.
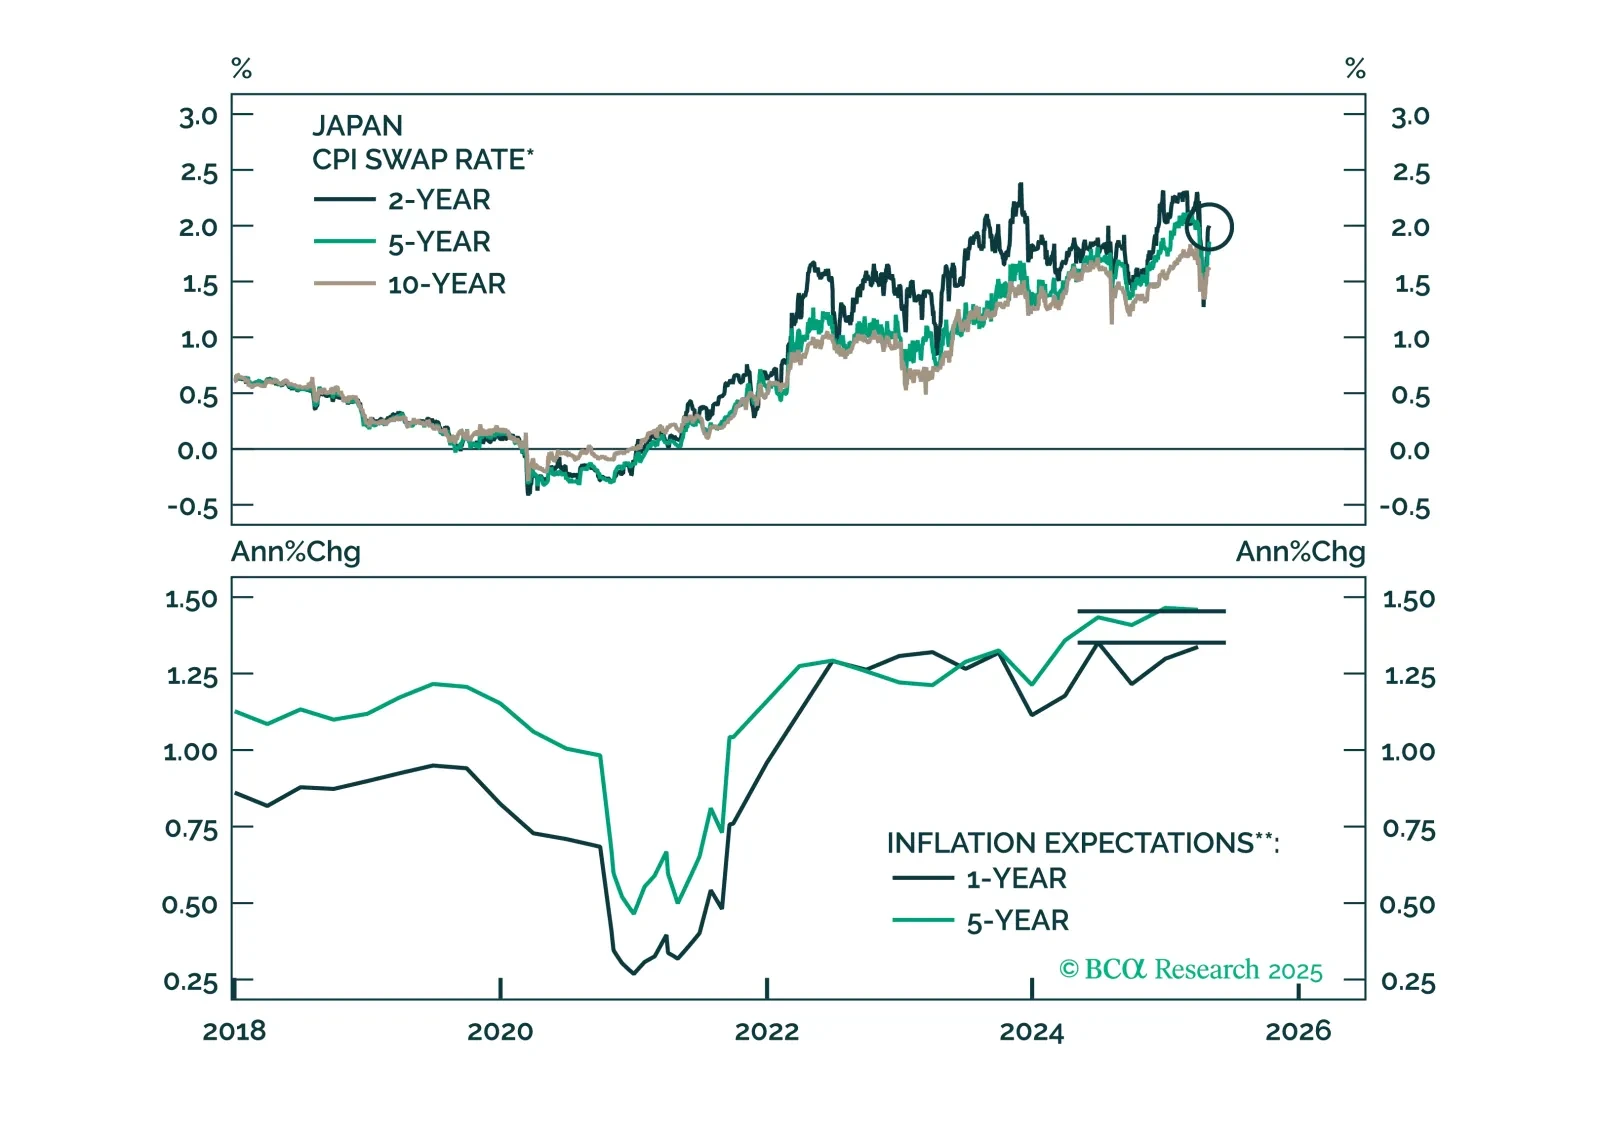
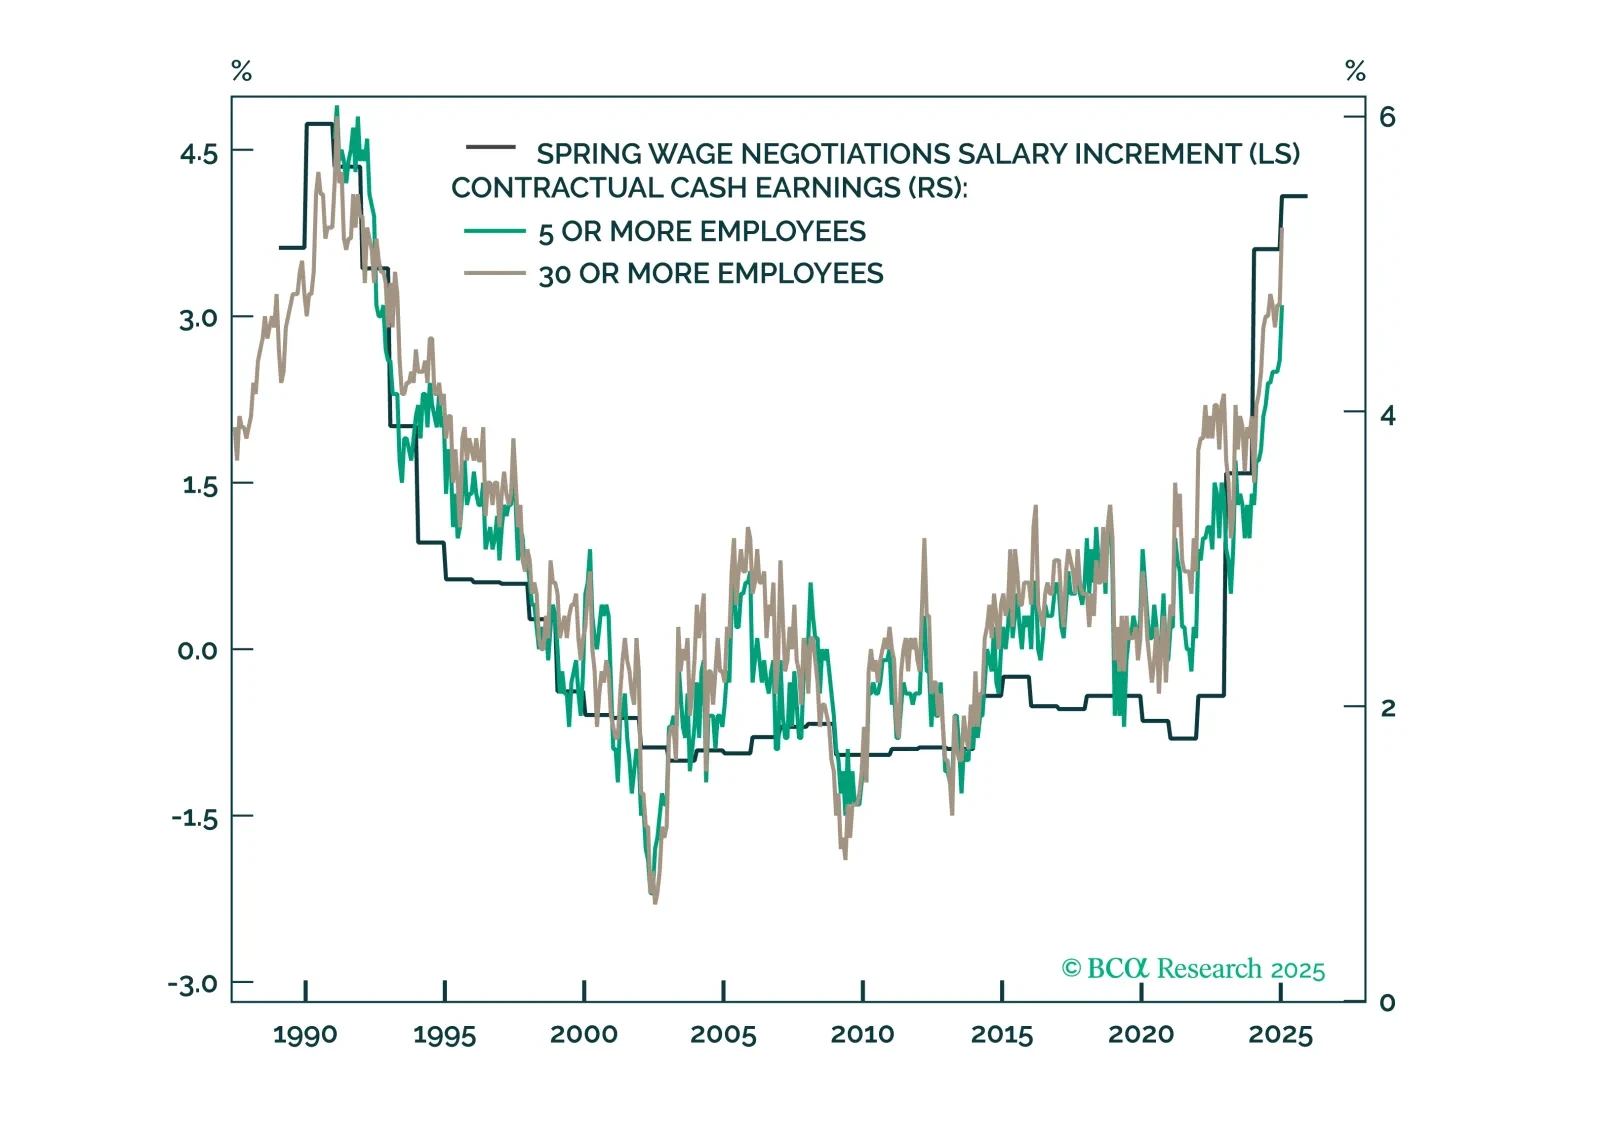
This week’s report looks at Japan, with the recent BoJ meeting. While a trade war has injected uncertainty into the Japanese economy, our conviction remains high that JGBs will underperform other government bond markets, and the yen will ultimately rally. That said, JPY is due for a tactical pullback.
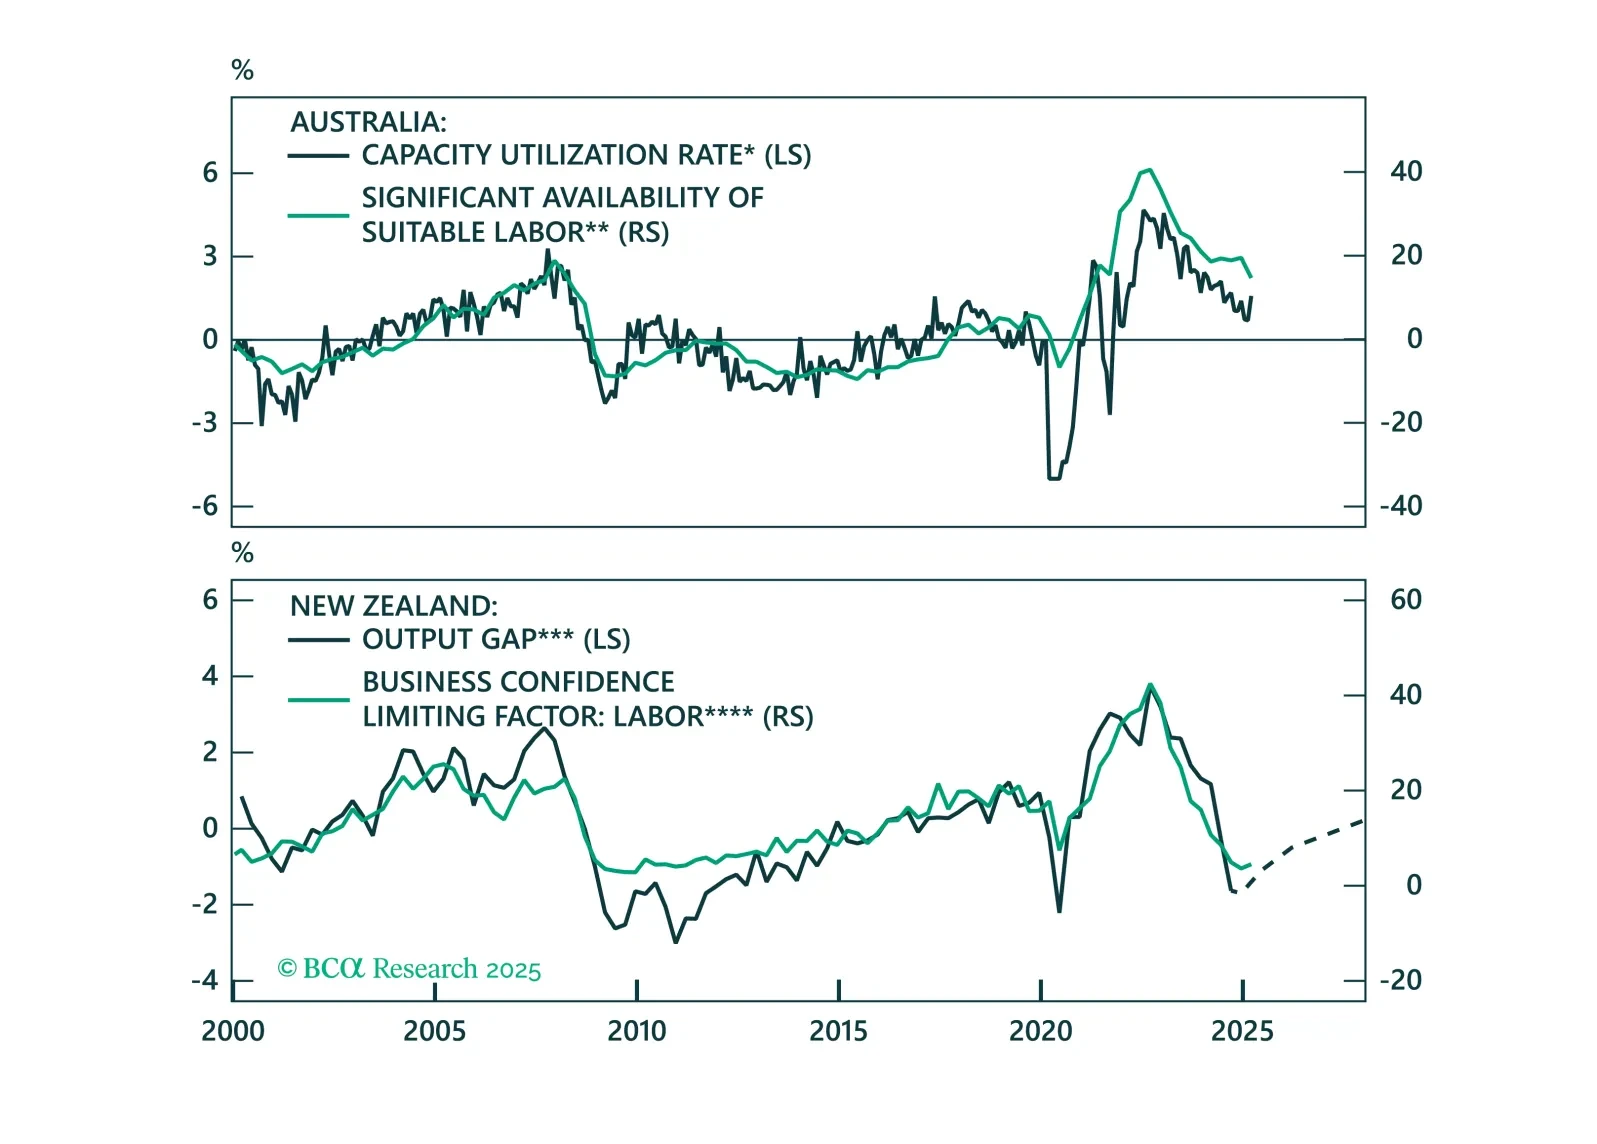
Following the escalation of the US-China trade war, the Reserve Bank of Australia is priced to cut rates most aggressively among its G10 peers. Across the Tasman Sea, the Reserve Bank of New Zealand has already cut rates aggressively, but the economy has yet to respond to this policy easing. This Special Report will examine the prospects of monetary policy for both of these central banks.
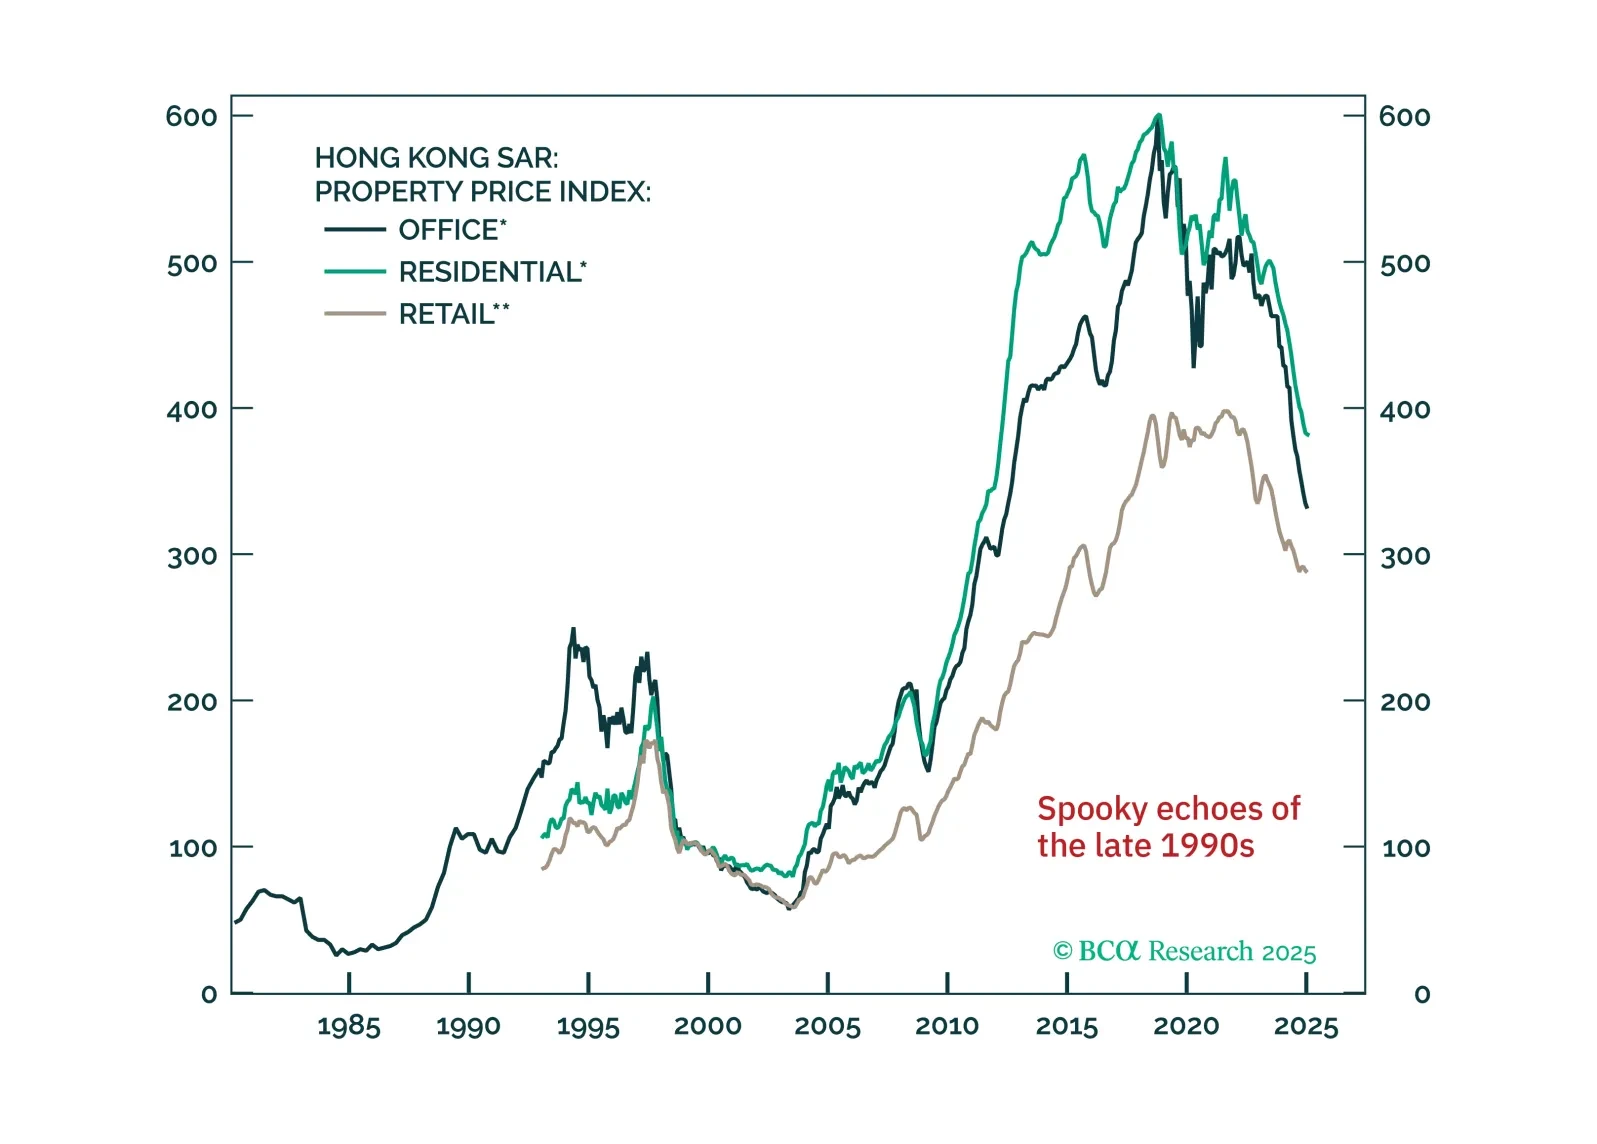
This week, we look at the sustainability of the HKD peg as the next whale to move markets, given what is happening to tariffs. After careful analysis, our bias is that it is here to stay. With the DXY dipping below 100, we are likely to see a rebound, which is actually bad news for the Hong Kong region of China, since it will tighten financial conditions. We have no new short-term trades, but if the peg broke, you want to be short HKD/JPY.
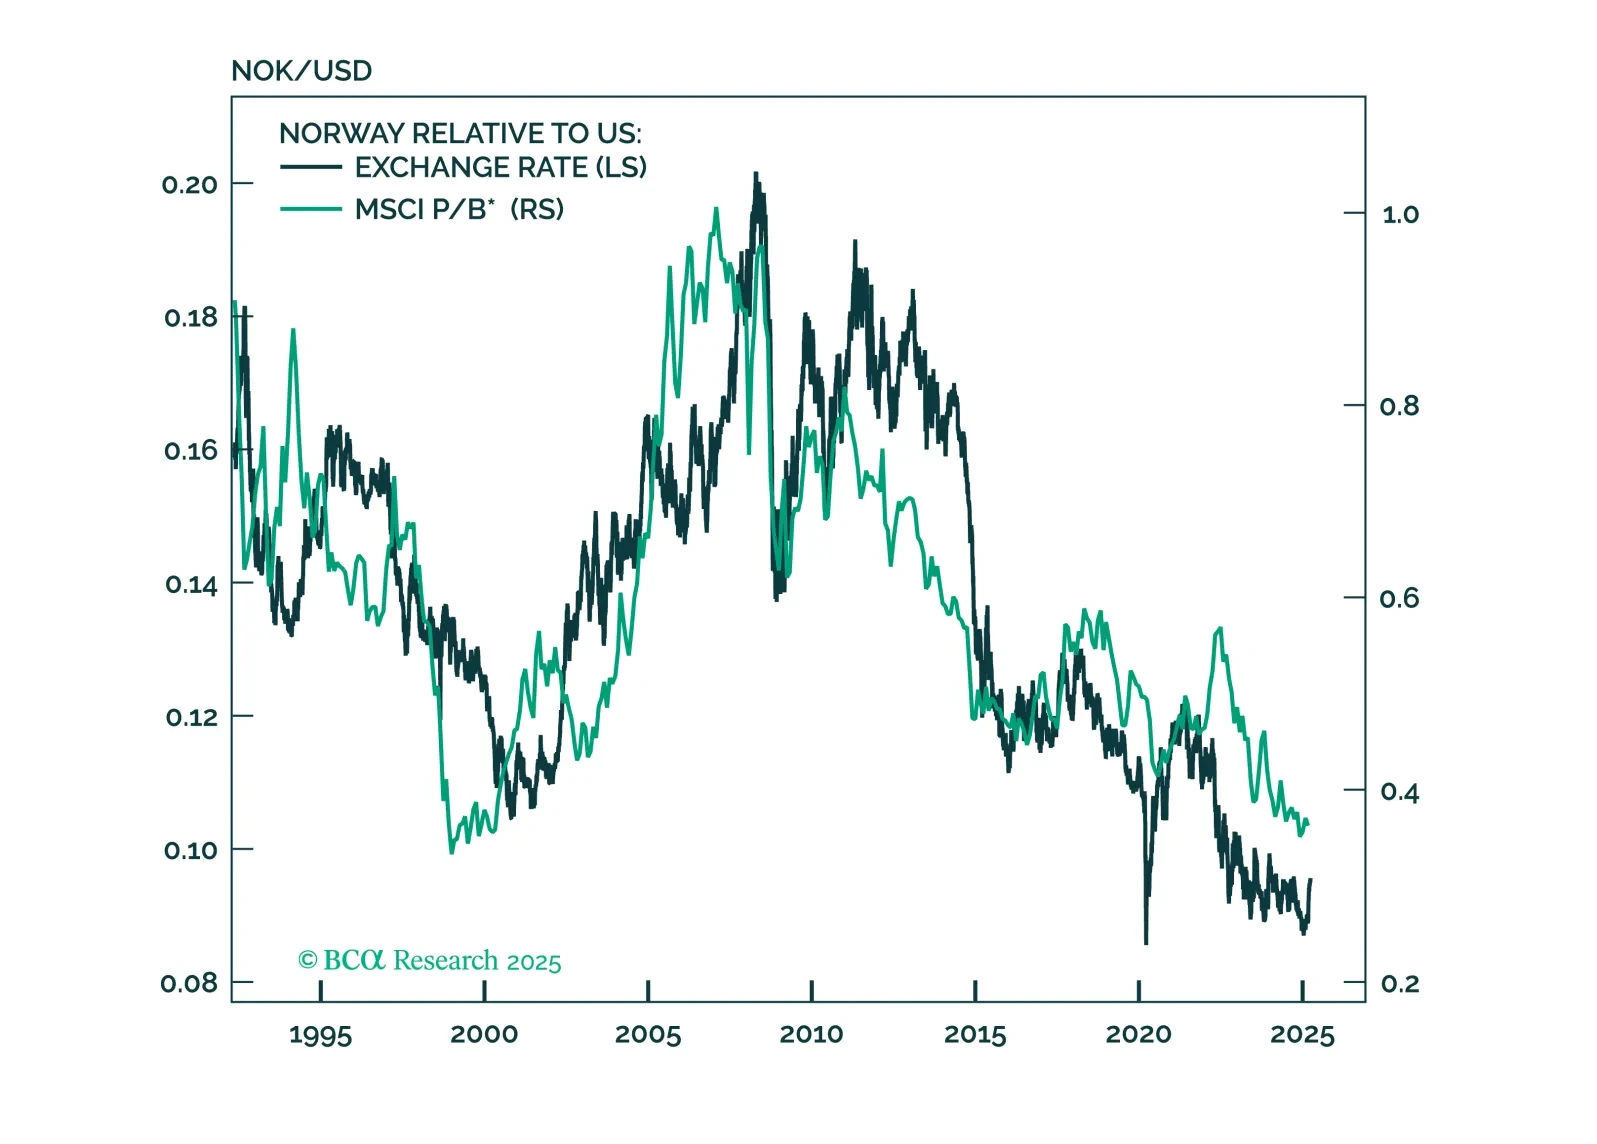
This report looks at investment implications, for Norwegian assets, given the recent meeting, from the Norges Bank.
Given the meetings between the Bank of Japan, the Bank of England, and the Swiss National Bank, our highest convictions views are:
Overweight UK Gilts. It is also time to sell sterling. We are short sterling, as of 1.30.
Underweight JGBs. Correspondingly, be long the yen.
A short CHF/JPY position remains a core holding. Selling GBP/JPY is also a great trade.