Sorry, you need to enable JavaScript to visit this website.
Saltar al contenido principal

Mega temas

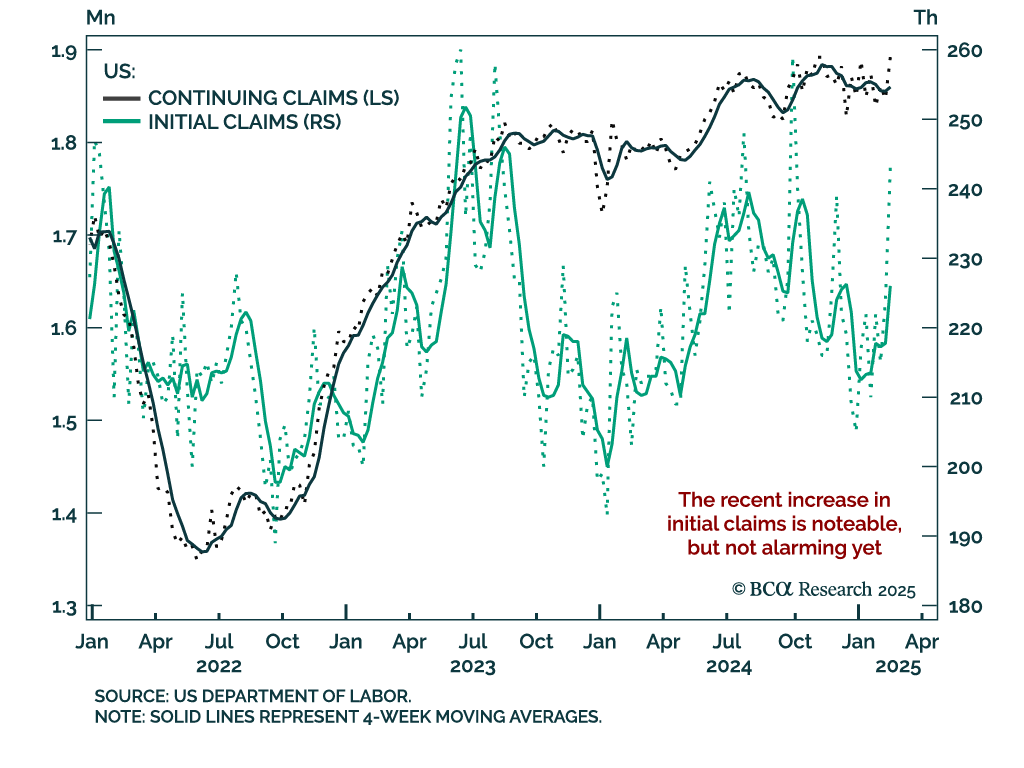
Weekly initial claims ticked up to 242k, near 2024 highs. The data is under the spotlight as the Trump administration implements a reduction of the federal workforce through the DOGE. Initial claims are not alarming yet; they remain near historical lows. The…
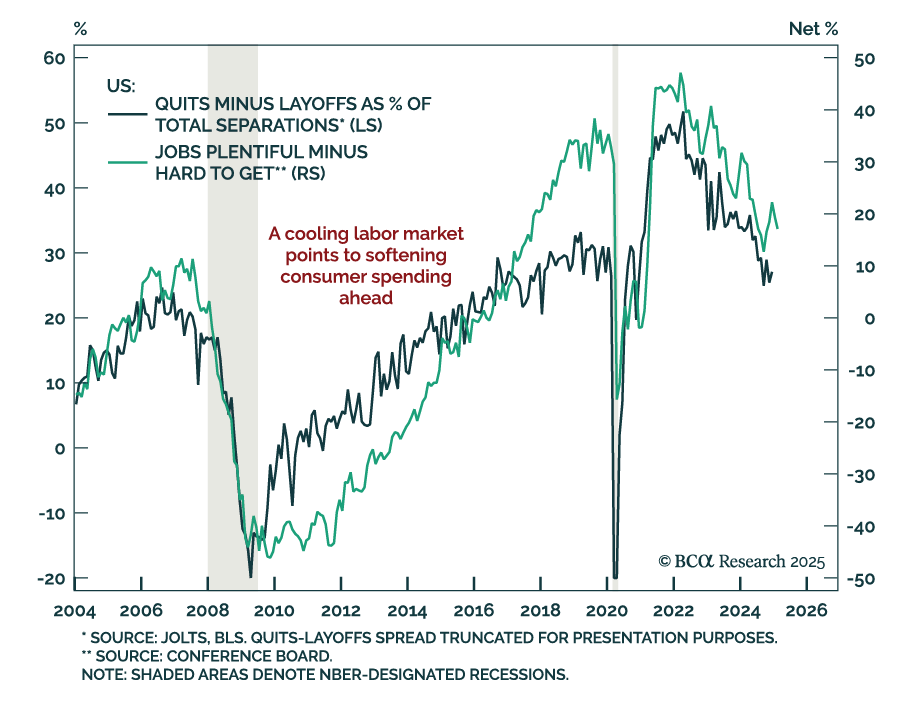
The February Conference Board Consumer Confidence index missed estimates for the third month in a row, falling to 98.3 from 105.3. Consumers’ assessment of both their current situation and their expectations worsened, with the latter falling close to 10…
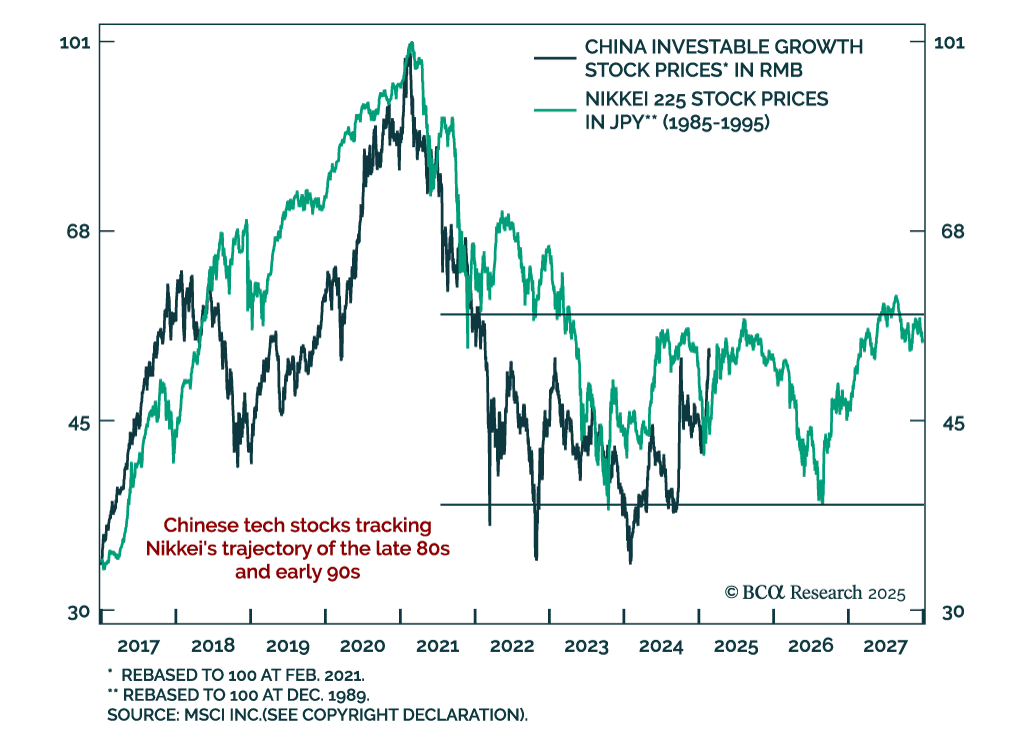
Our China strategists assessed the outlook for Chinese stocks in the aftermath of the DeepSeek hype. DeepSeek’s innovations will boost China’s productivity and technological advancement but are unlikely to create a strong competitive moat for large listed…

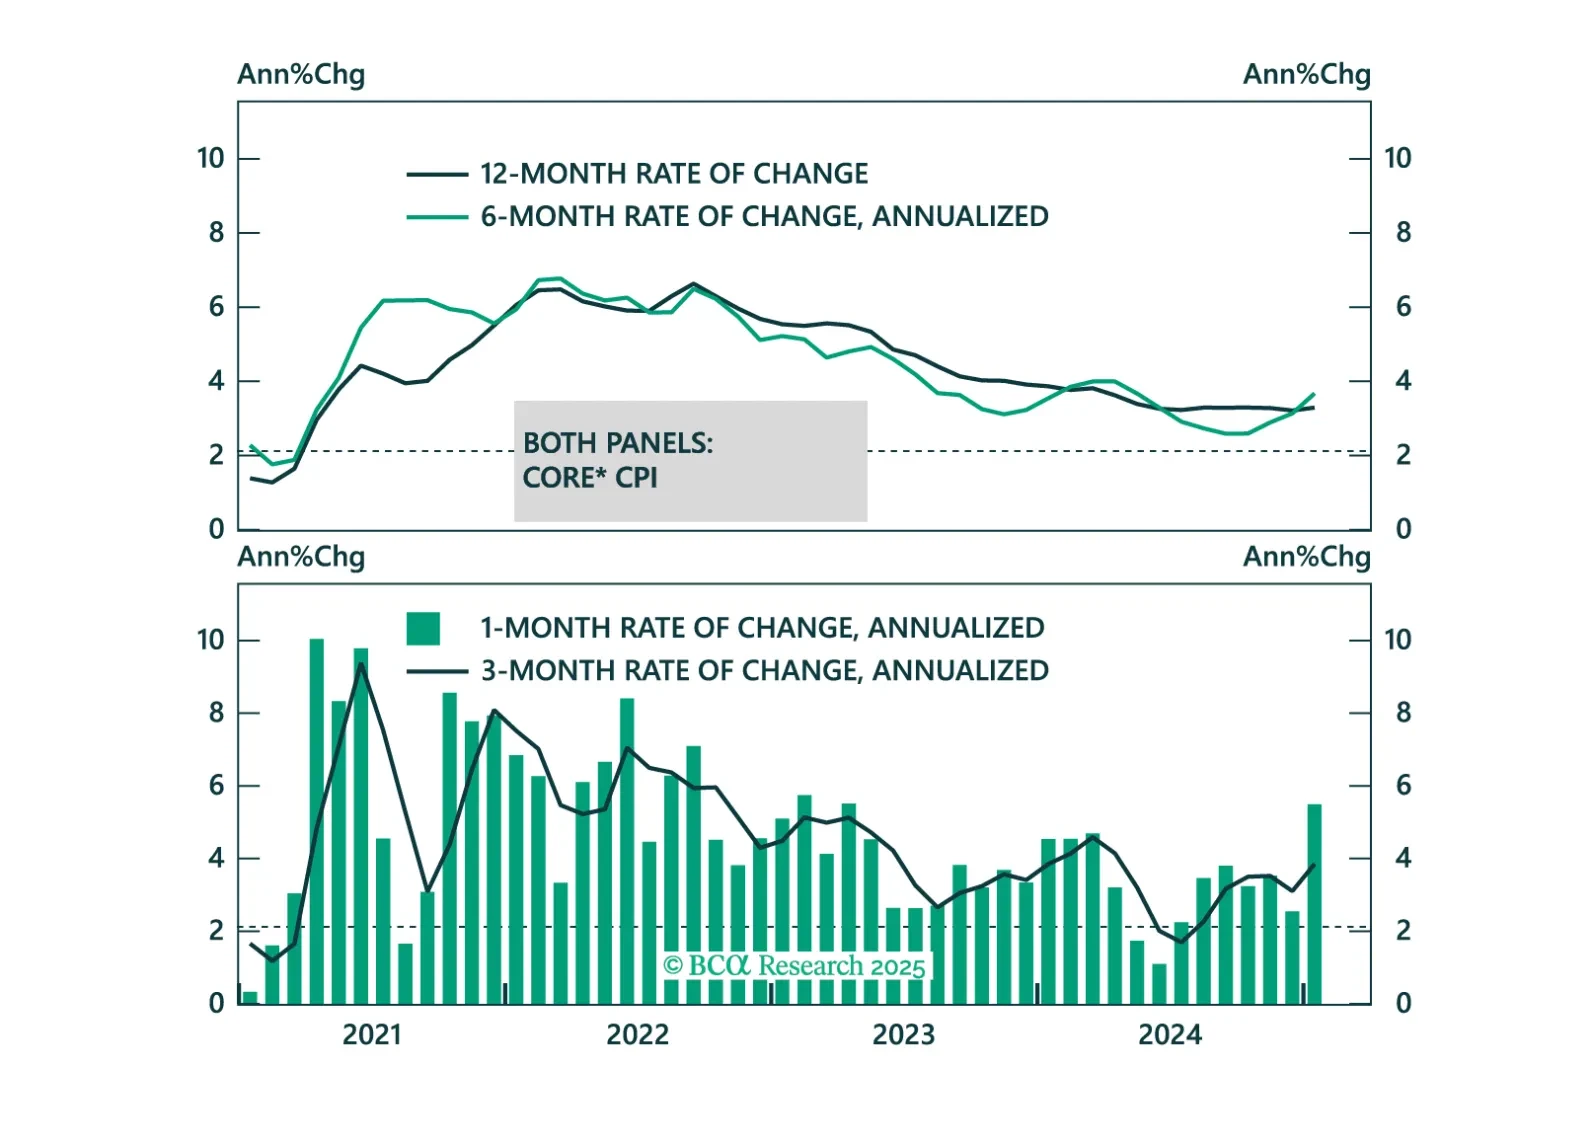
Some thoughts on this morning’s CPI report and its implications for the Fed and Treasury yields.
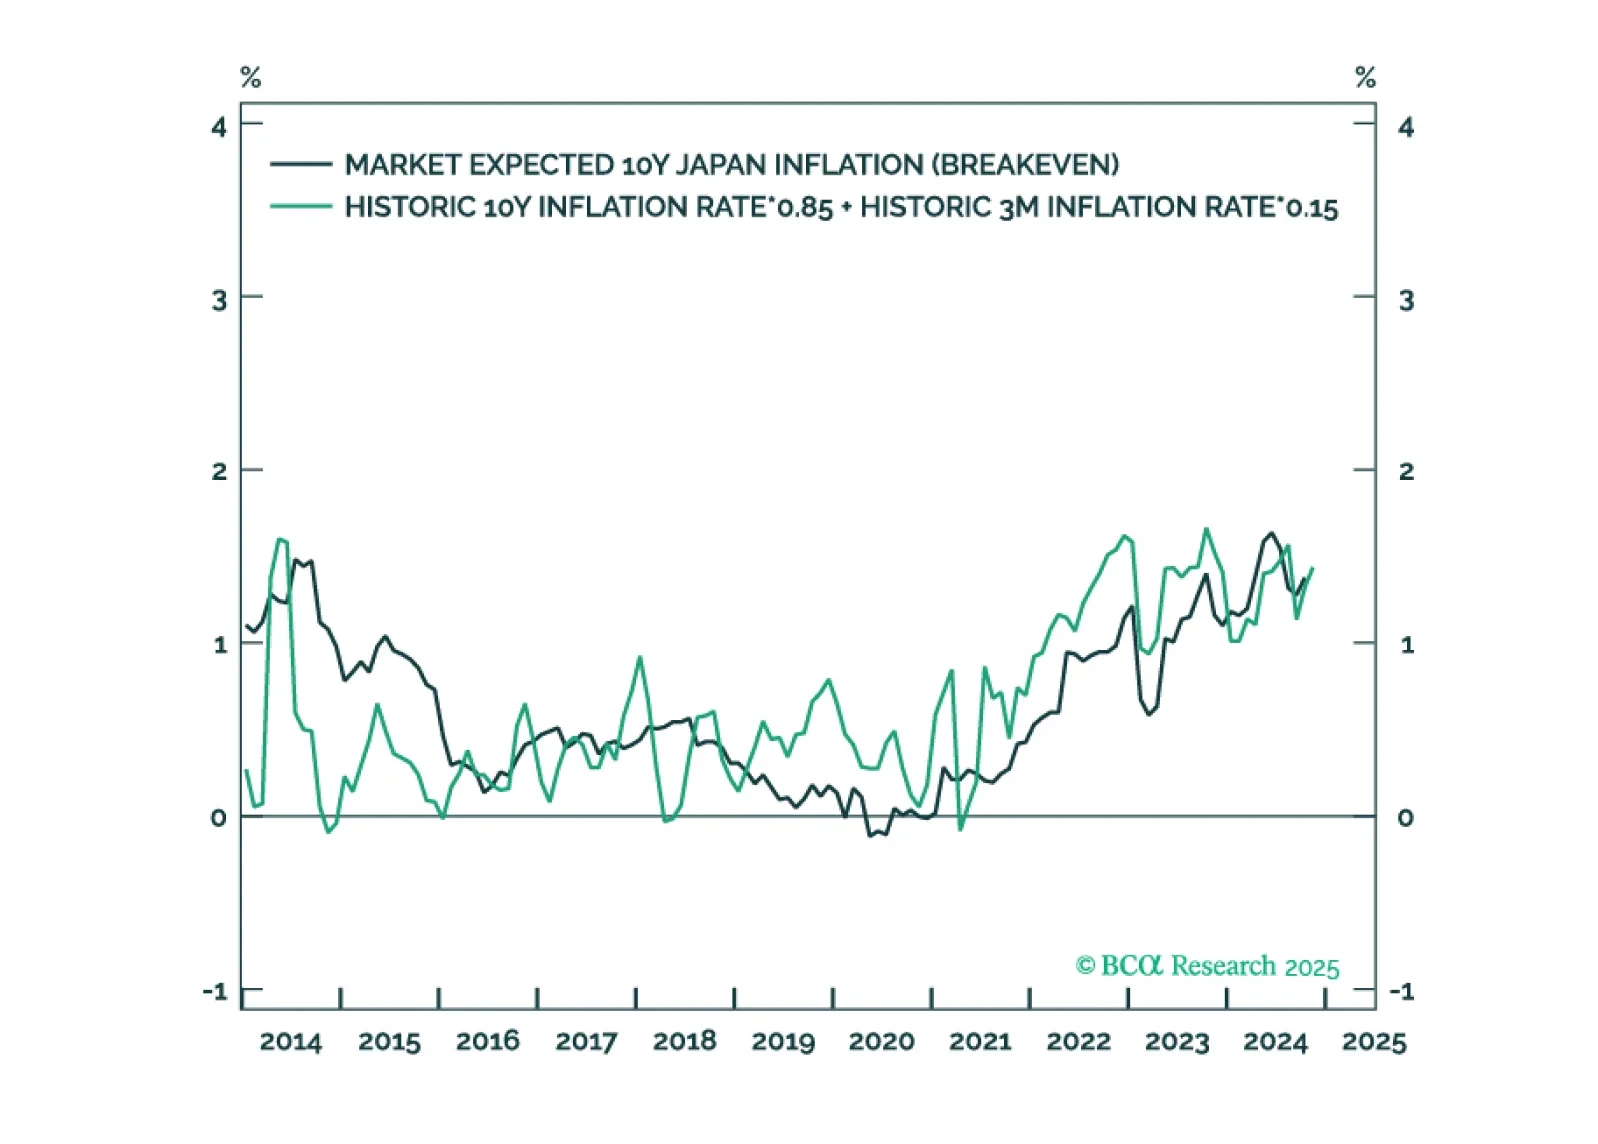
In most developed economies, rising inflation expectations will lift them further above the 2 percent target, limiting the scope for further interest rate cuts. But in Japan, rising inflation expectations will lift them up to the BoJ’s 2 percent target, removing the BoJ’s justification for its zero-interest rate policy. The normalisation of Japan’s monetary policy poses a big structural risk to stocks because Japan has been the main source of financial market liquidity, and thereby, of rising stock market valuations. From a timing perspective though, wait until the complexities of the price trends in USD/JPY and/or Nasdaq versus 30-year T-bond have collapsed. Plus: go tactically long copper.
This week we conduct a thorough audit of our open positions by revisiting the original basis and subsequent performance of all 13 cyclical recommendations. Following the review, we recommend closing 6 of the 13 positions.
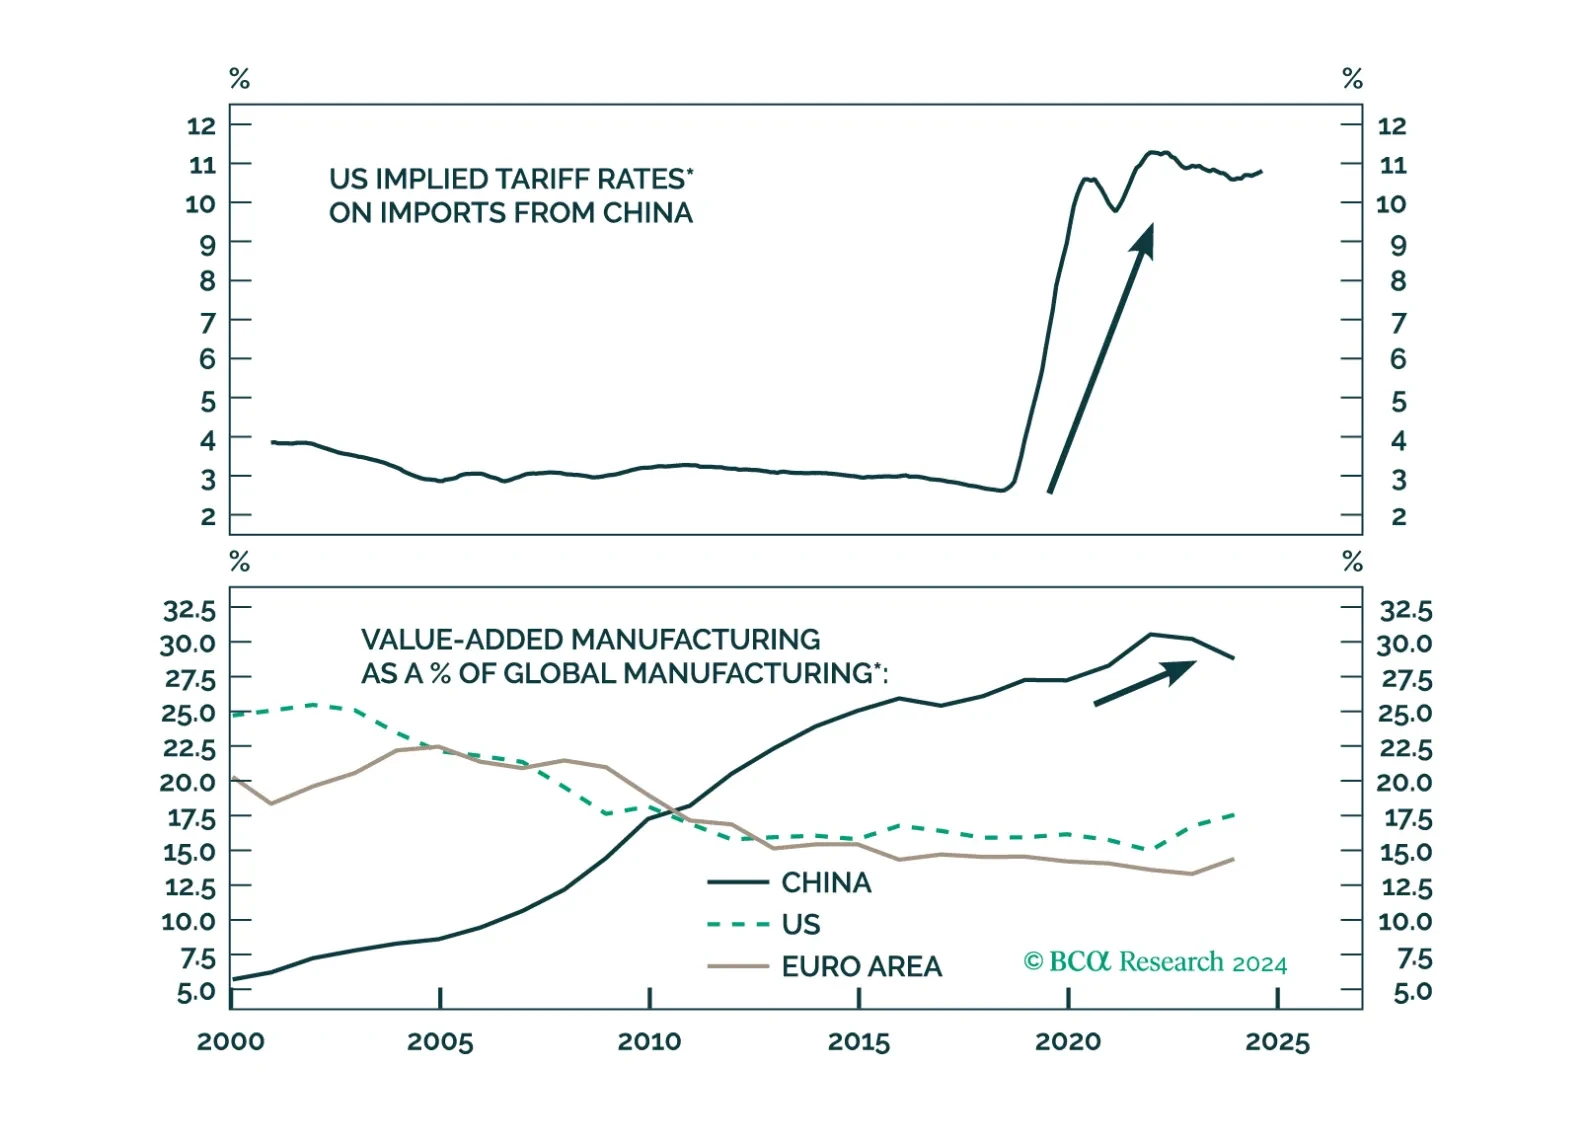
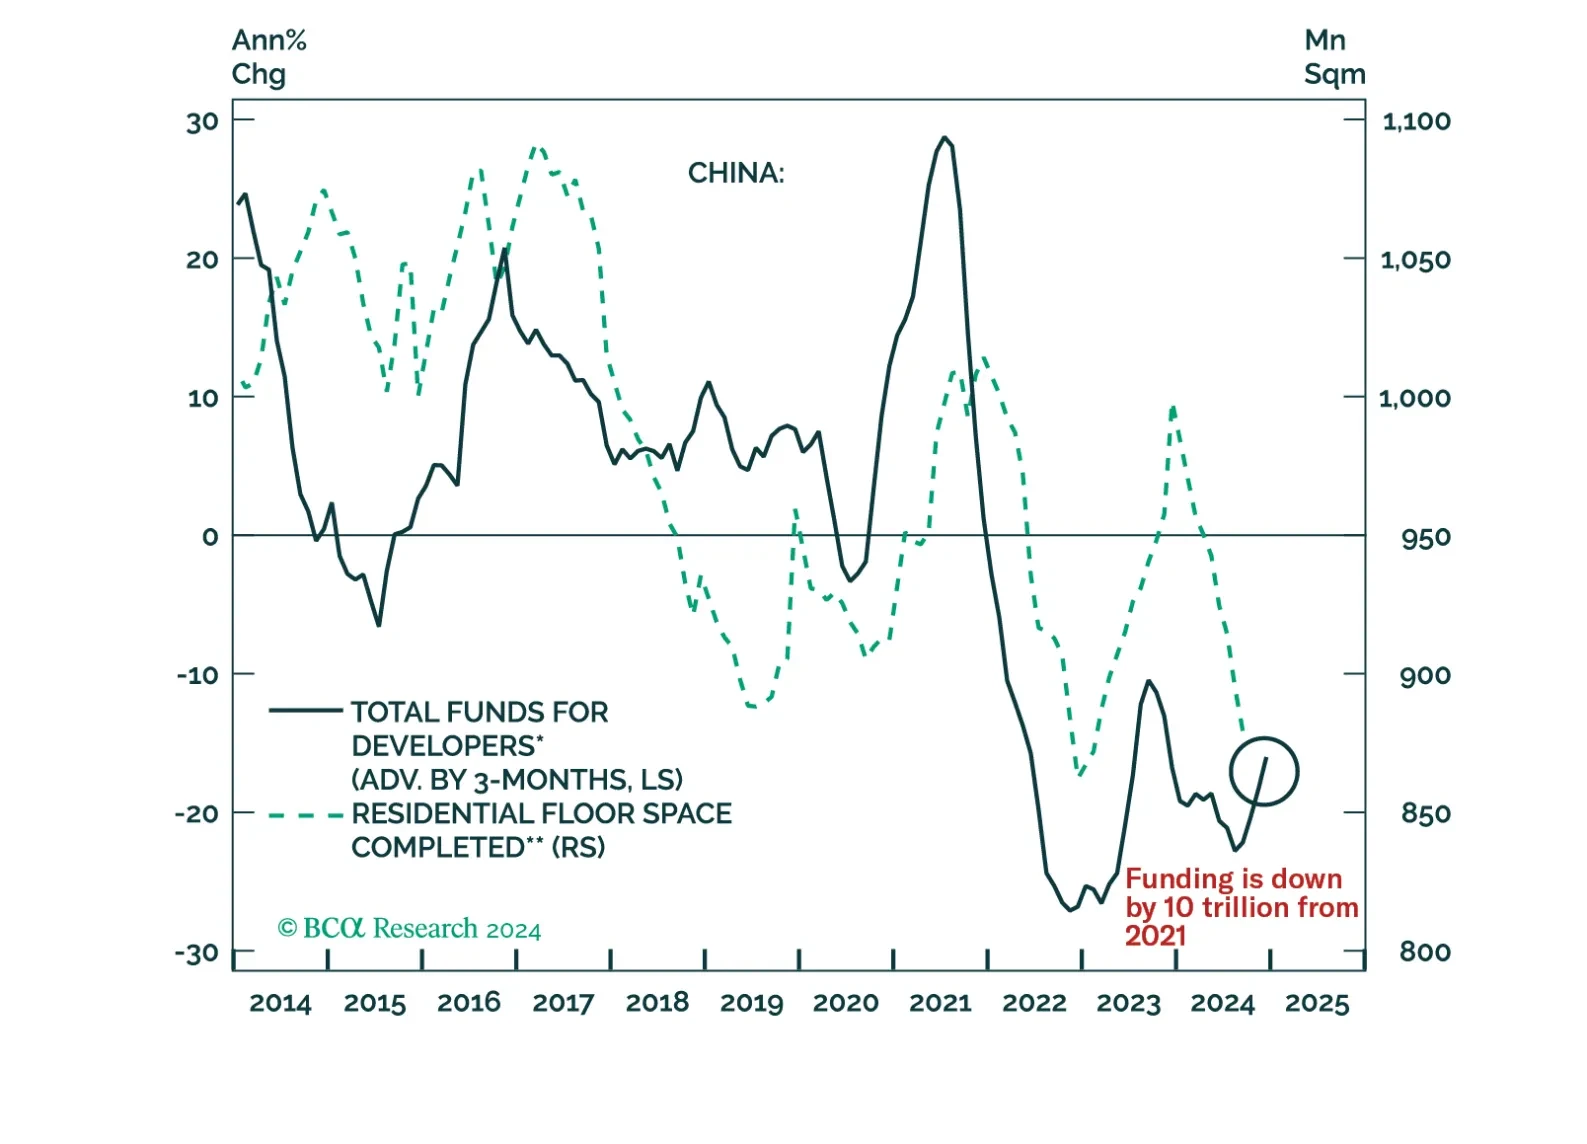
La reelección presidencial de Trump convierte los aumentos de aranceles de EE. UU. sobre las exportaciones chinas en una amenaza inminente. Beijing ha realizado amplios esfuerzos para reducir la exposición al riesgo de la economía doméstica y diversificar el comercio alejándolo de EE. UU. Sin embargo, China no está hoy mejor posicionada que en 2018 para soportar el impacto de una guerra comercial renovada.
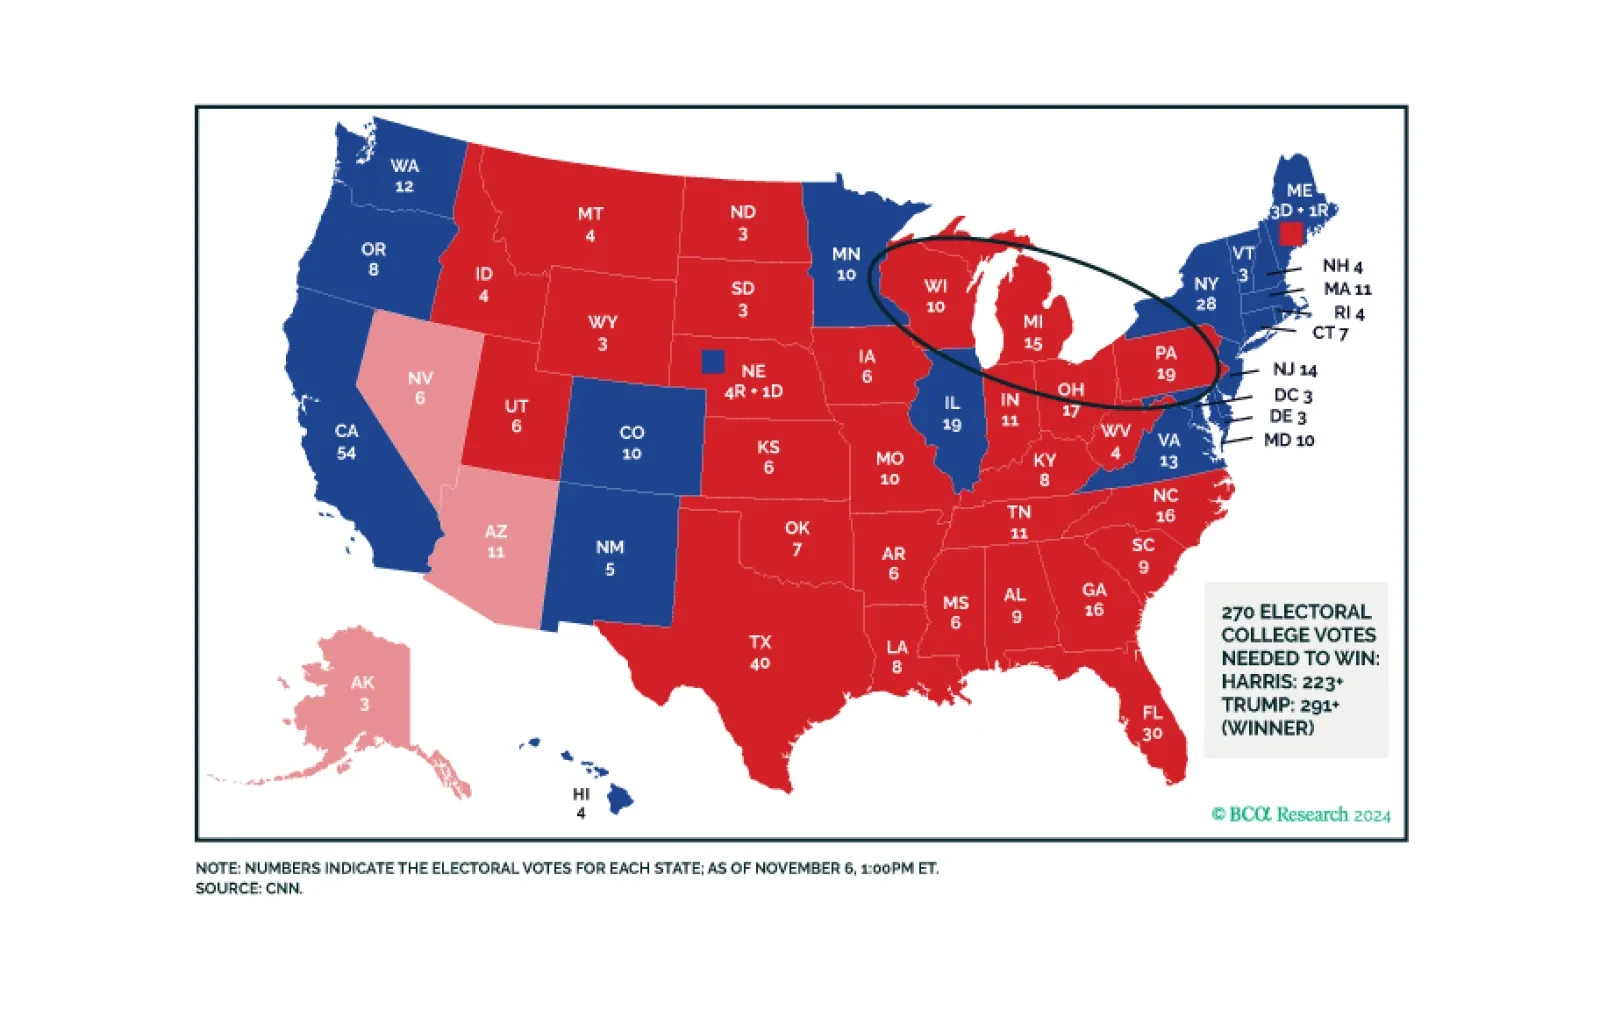
Informe especial La victoria contundente de Trump trae un mandato popular que garantiza la desregulación y aranceles comerciales más altos. Un mayor déficit presupuestario y una reforma migratoria también están en el horizonte, ya que los republicanos parecen poder lograr por poco una estrecha mayoría en la Cámara de Representantes. La política exterior se volverá más unilateral, con los activos estadounidenses rindiendo mejor al principio.

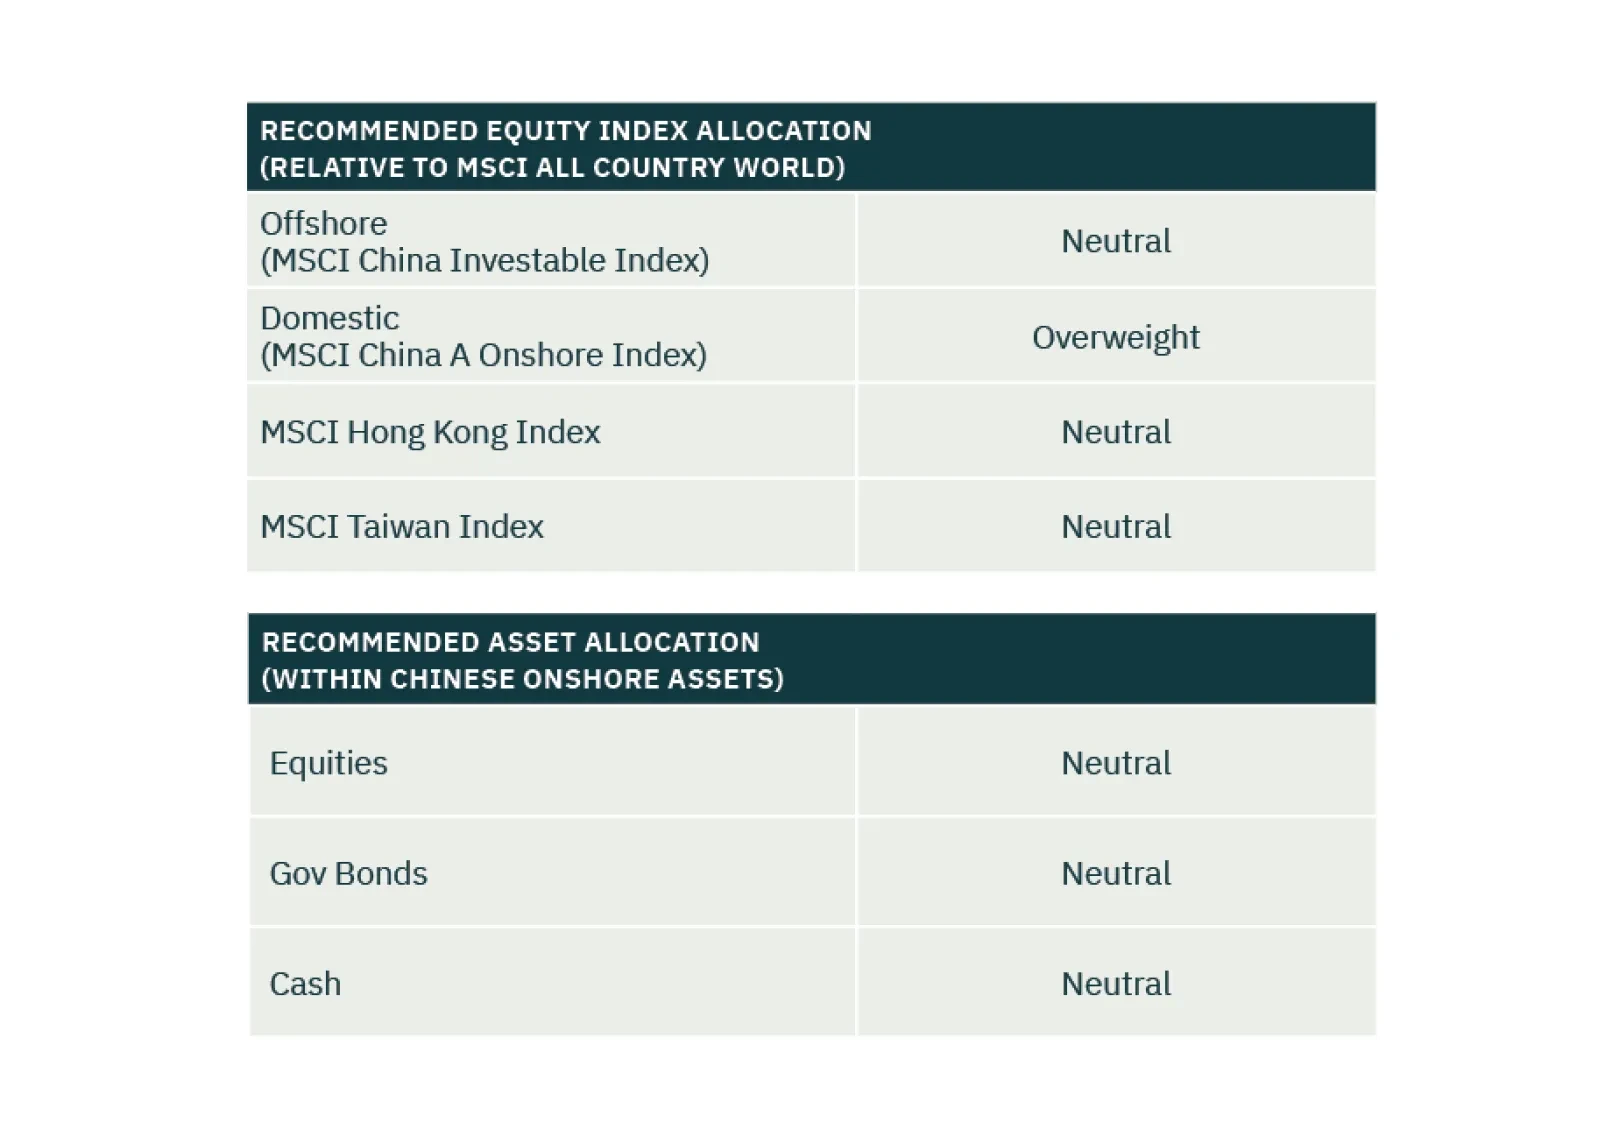
We spent last week visiting our clients in China. In this report, we share some of the key questions from the client meetings as well as our responses.