Inflation
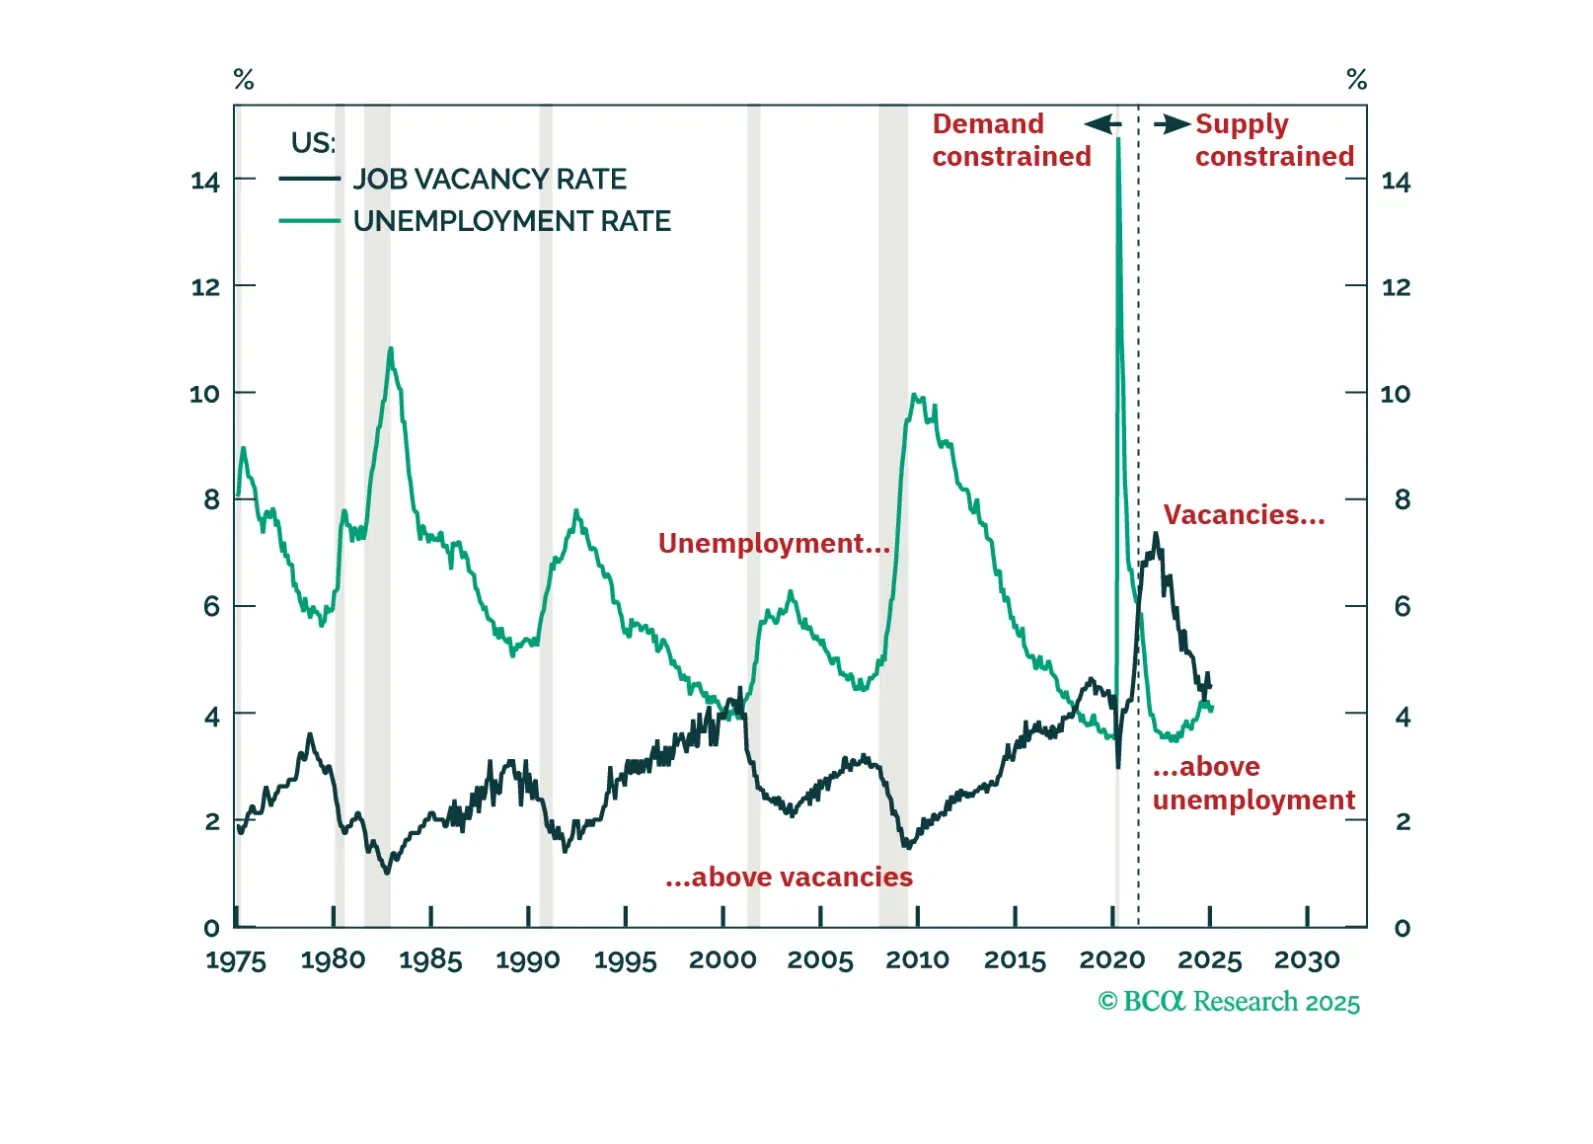
The US economy has never entered a demand-driven recession without labour demand running below labour supply and without the job vacancy rate running below the unemployment rate. Right now though, US labour demand is still running 1.7 million workers above labour supply, and the job vacancy rate is running comfortably above the unemployment rate. This suggests that the labour market is still supply-constrained, and that a demand-driven recession is not imminent. We discuss the investment implications. Plus, more about our ‘trade of the century’: long cotton versus coffee.
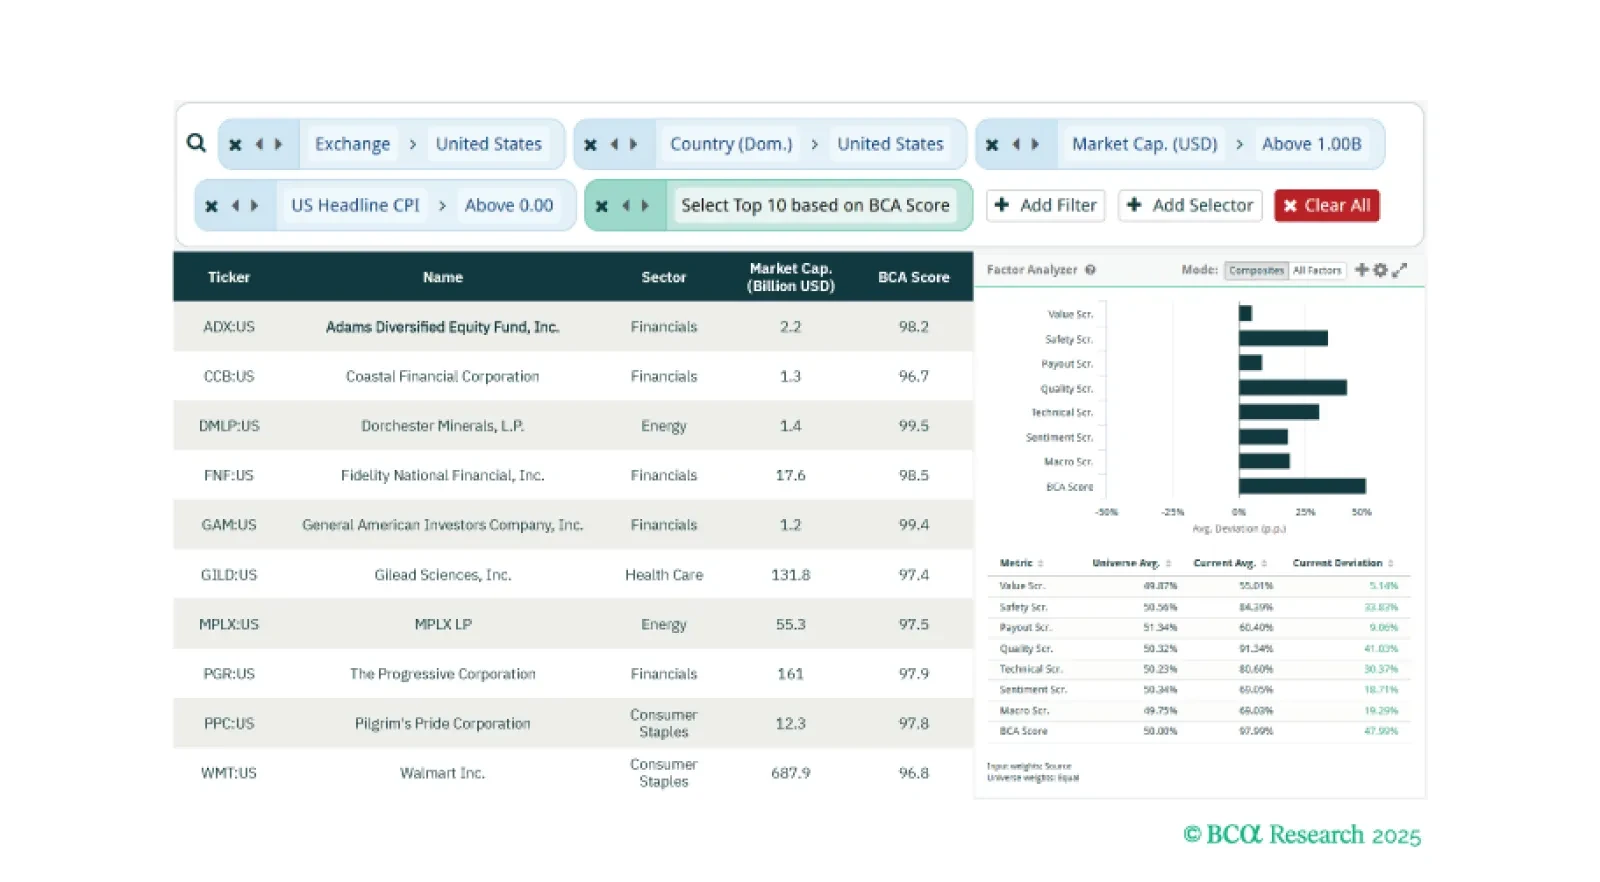
This week, our three screeners cover equity plays for “transitory” inflation impacts from US tariffs, a correction in sentiment within the European Aerospace and Defense industry, and Value Investor, Warren Buffett’s Philosophy.
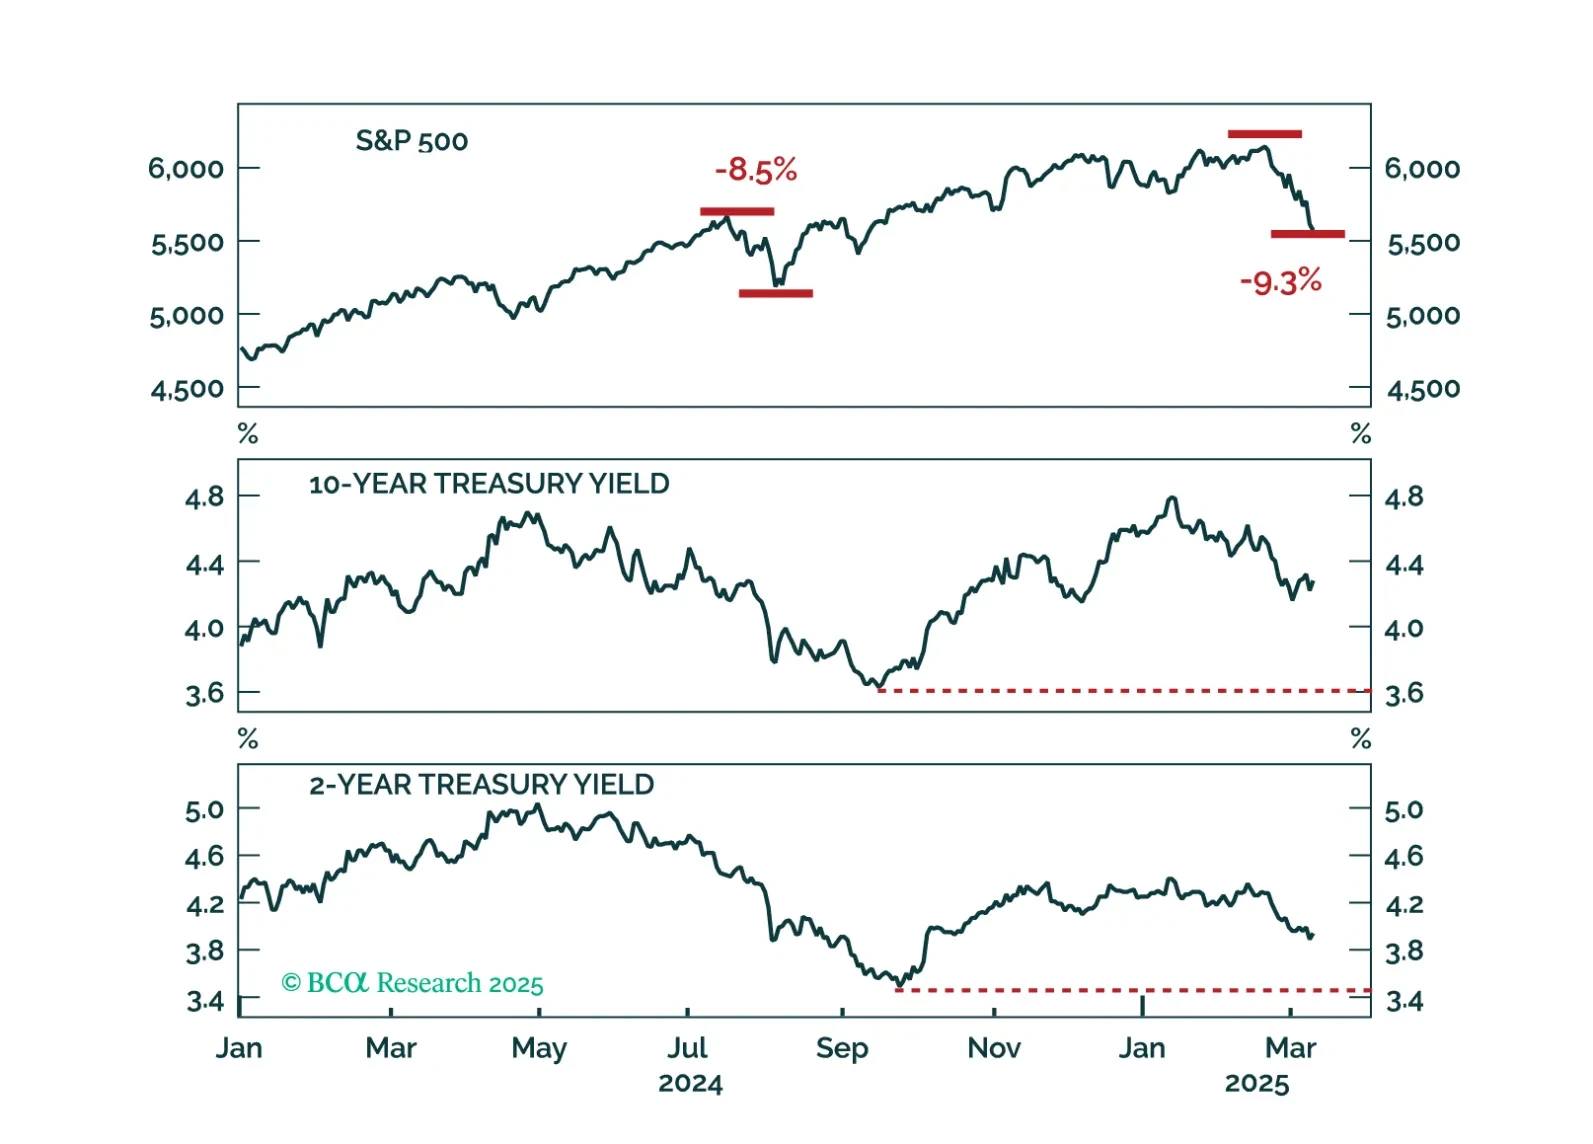
A falling stock market and sticky bond yields represent the worst of both worlds for investors. We interrogate why bond yields haven’t dropped more given the large selloff seen in equities.
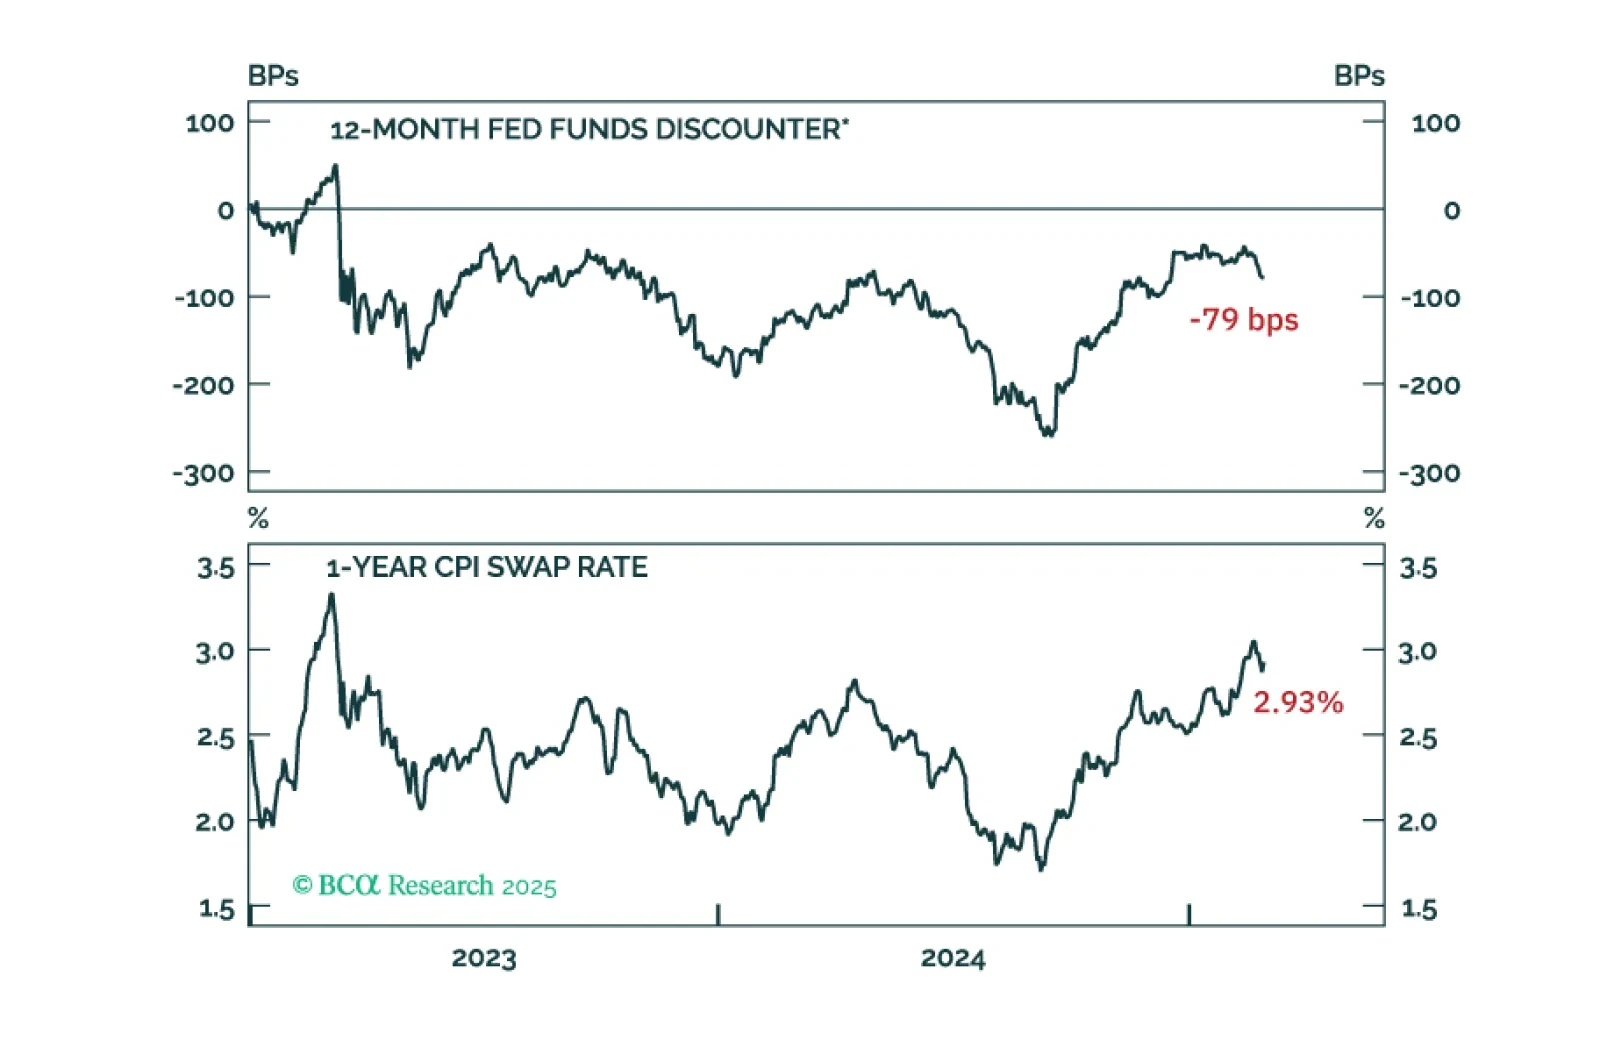
La inflación subyacente del PCE estuvo contenida esta mañana, pero, con grandes aranceles en el horizonte, anticipamos lecturas de inflación más altas en los próximos meses.
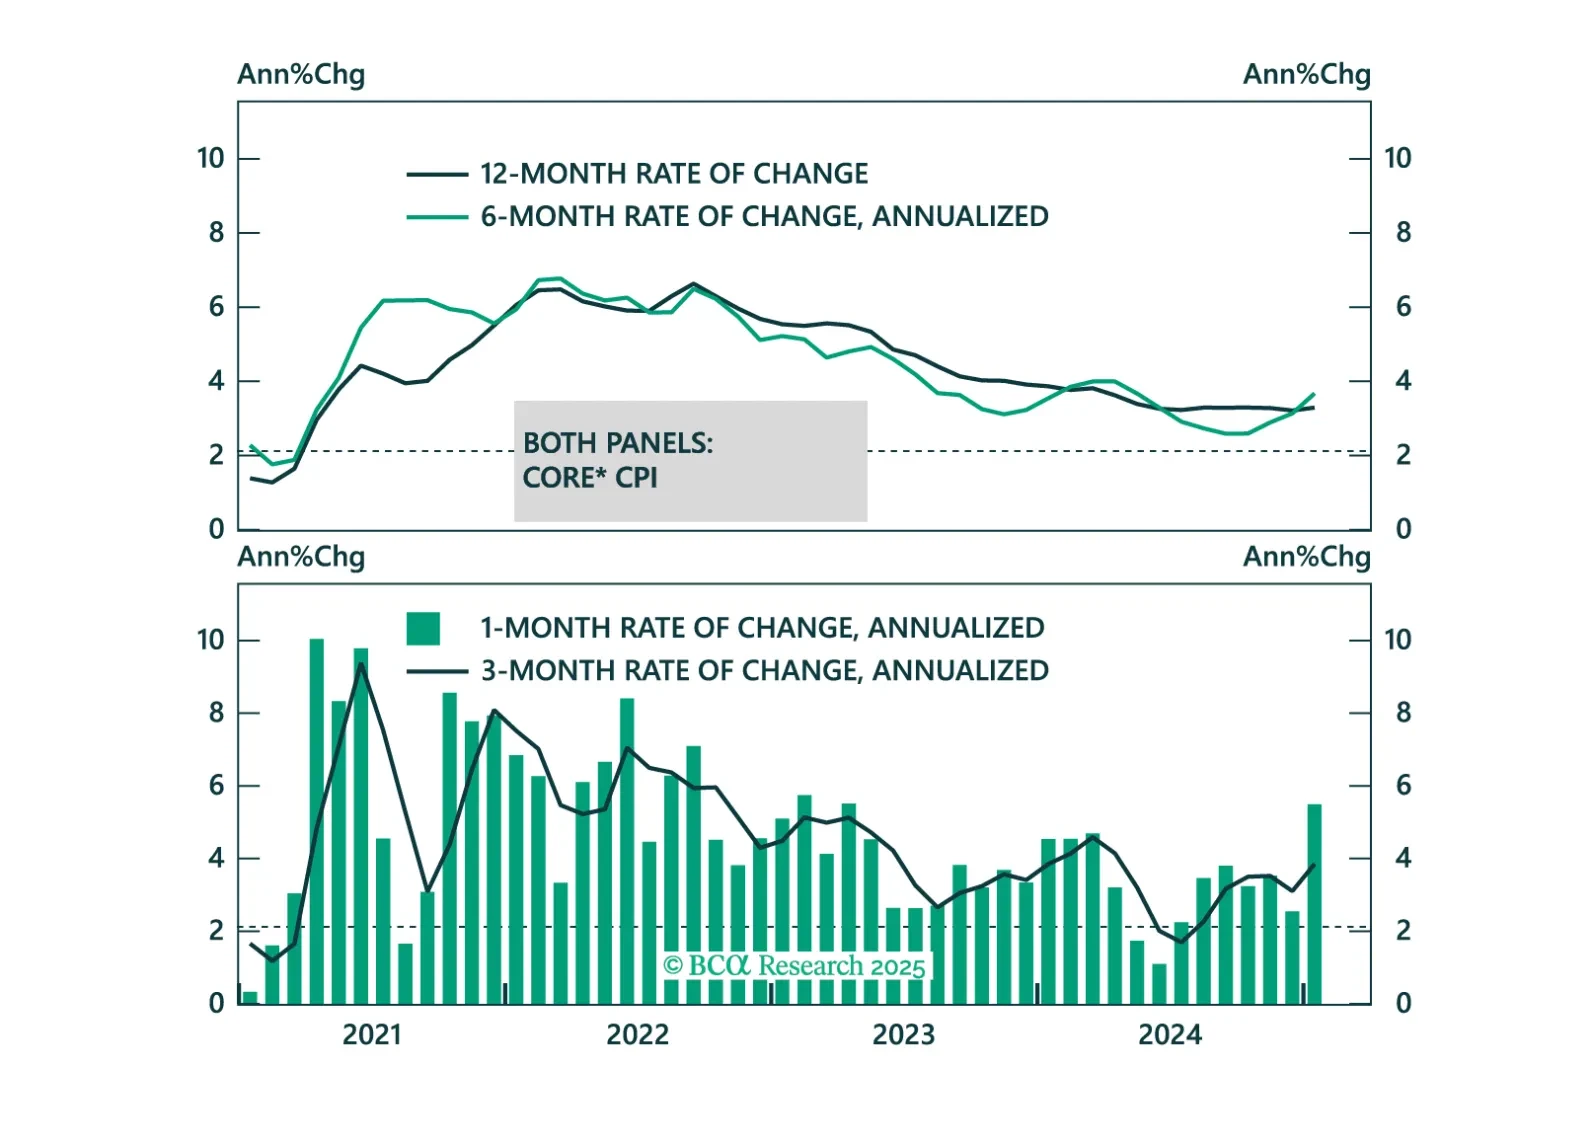
Some thoughts on this morning’s CPI report and its implications for the Fed and Treasury yields.
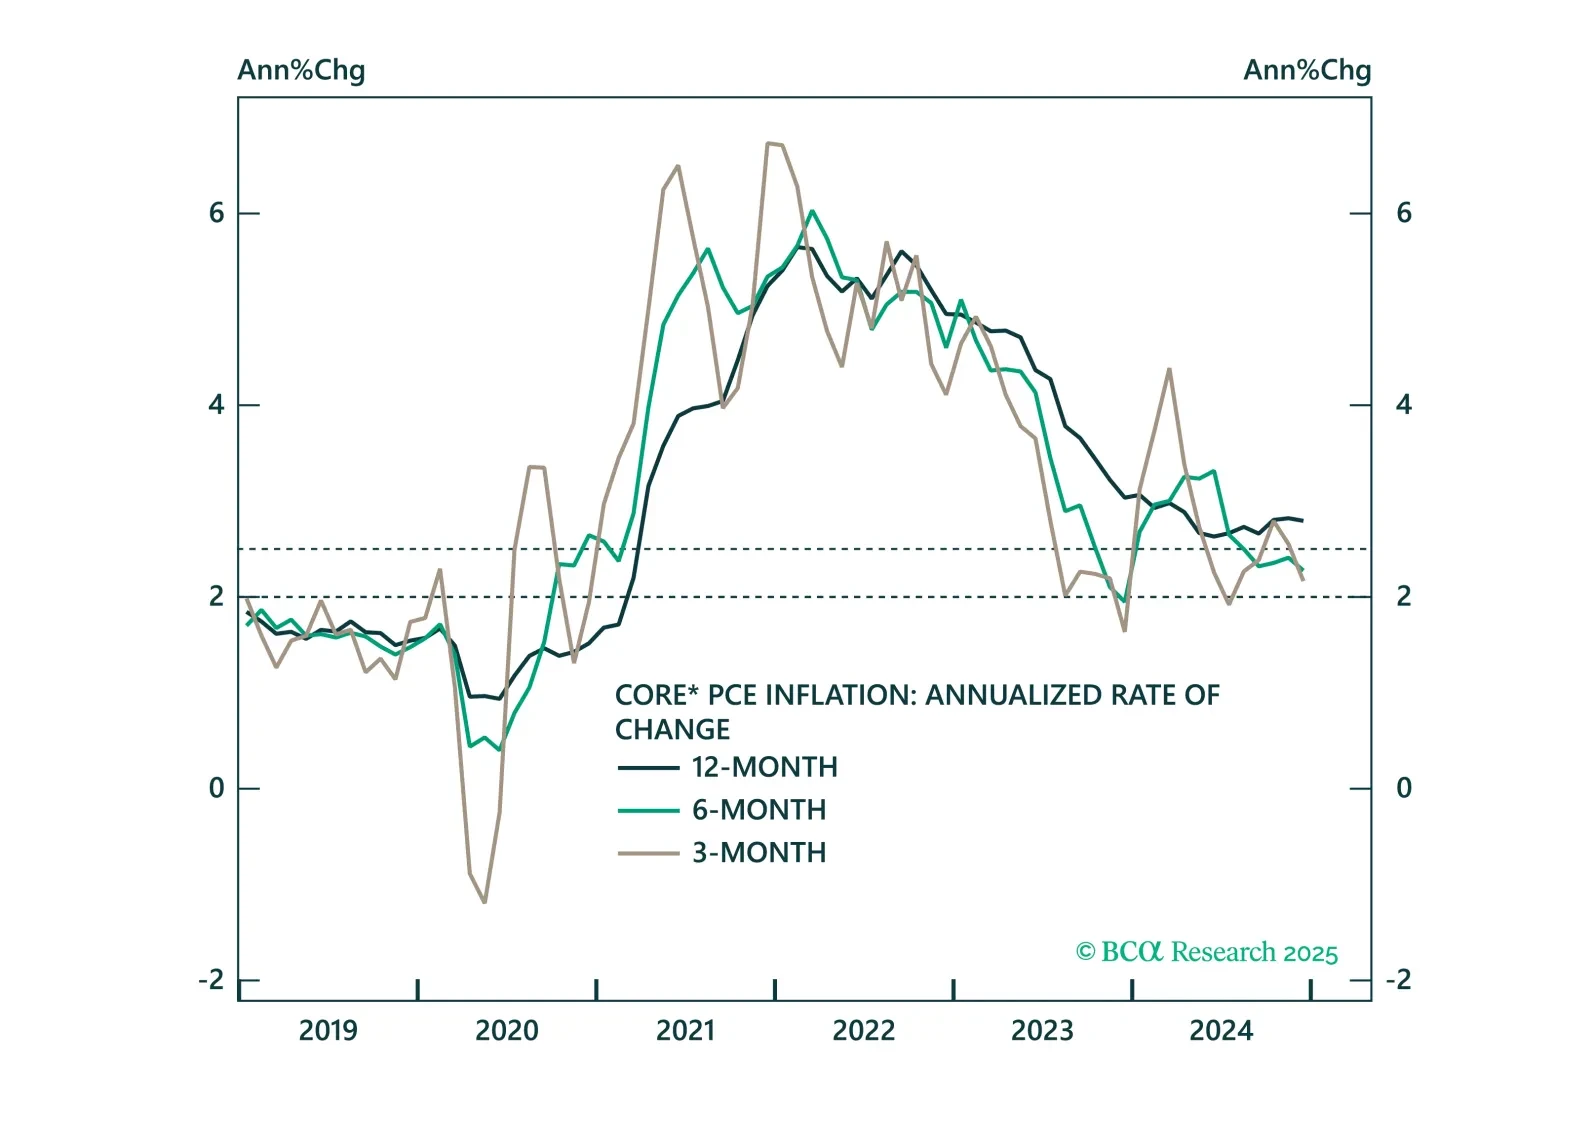
Core PCE inflation came in soft this morning and is tracking well below the Fed’s 2025 forecast. We highlight three upside risks to inflation and preview next week’s employment report.
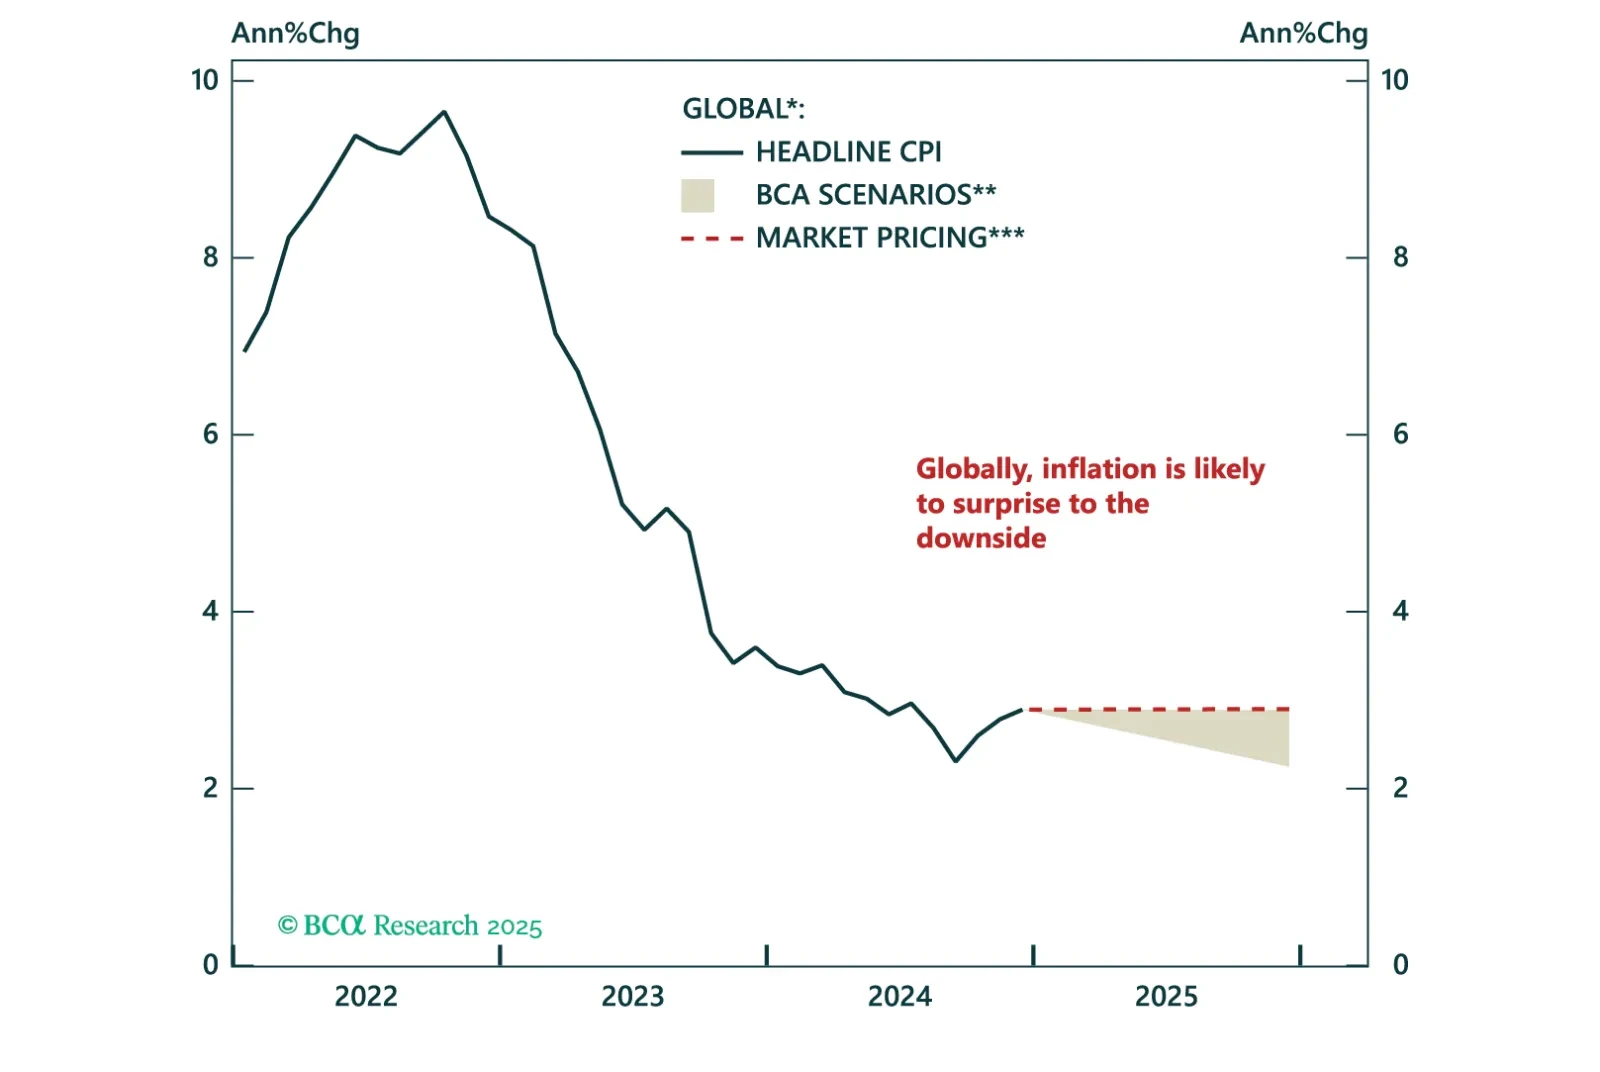
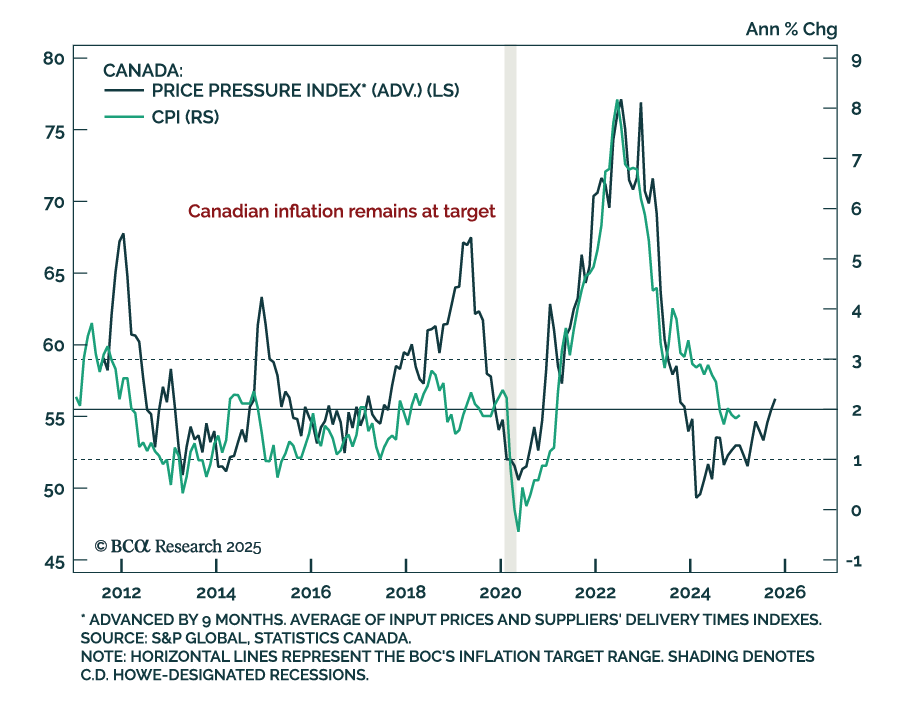
Inflation concerns are starting to ramp up again due to potentially inflationary policies from the new Trump administration. These concerns mostly affect the US inflation outlook. Evidence from forward-looking indicators shows that the global disinflationary trend remains intact. Today’s Special Report covers the global inflation outlook in 2025 and the implications for inflation-linked bonds.