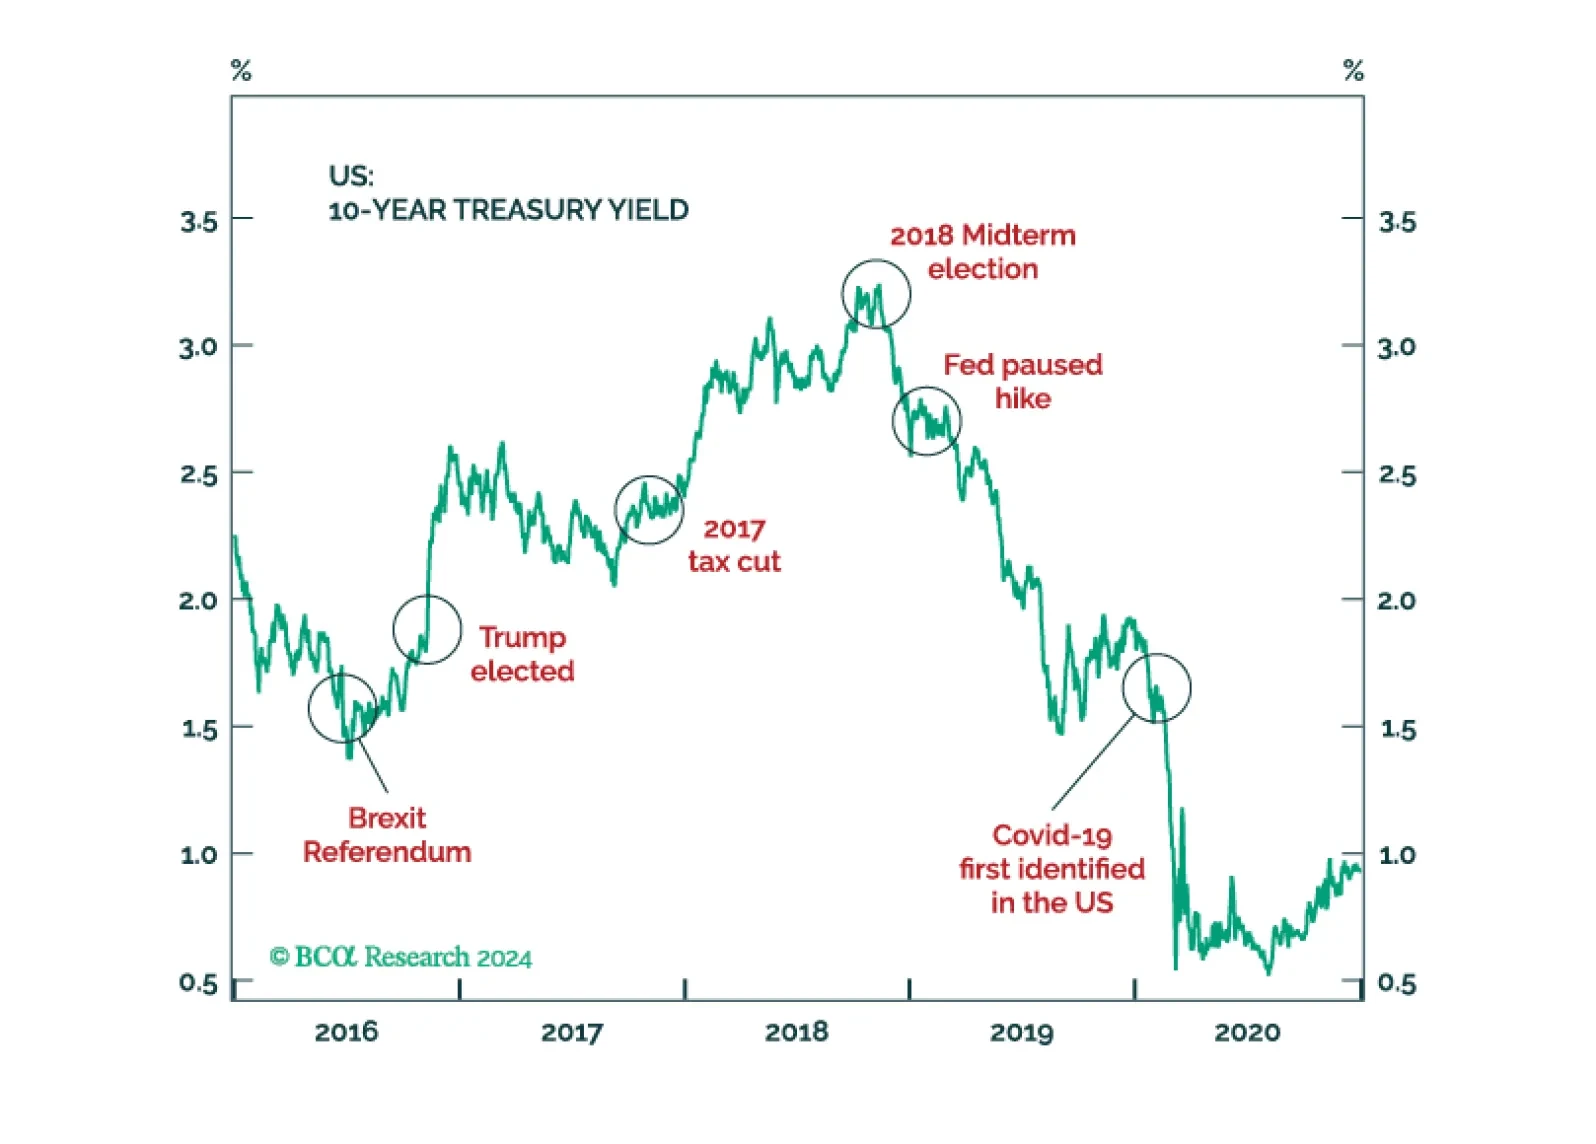
Gob. Soberanos/Tesorerías
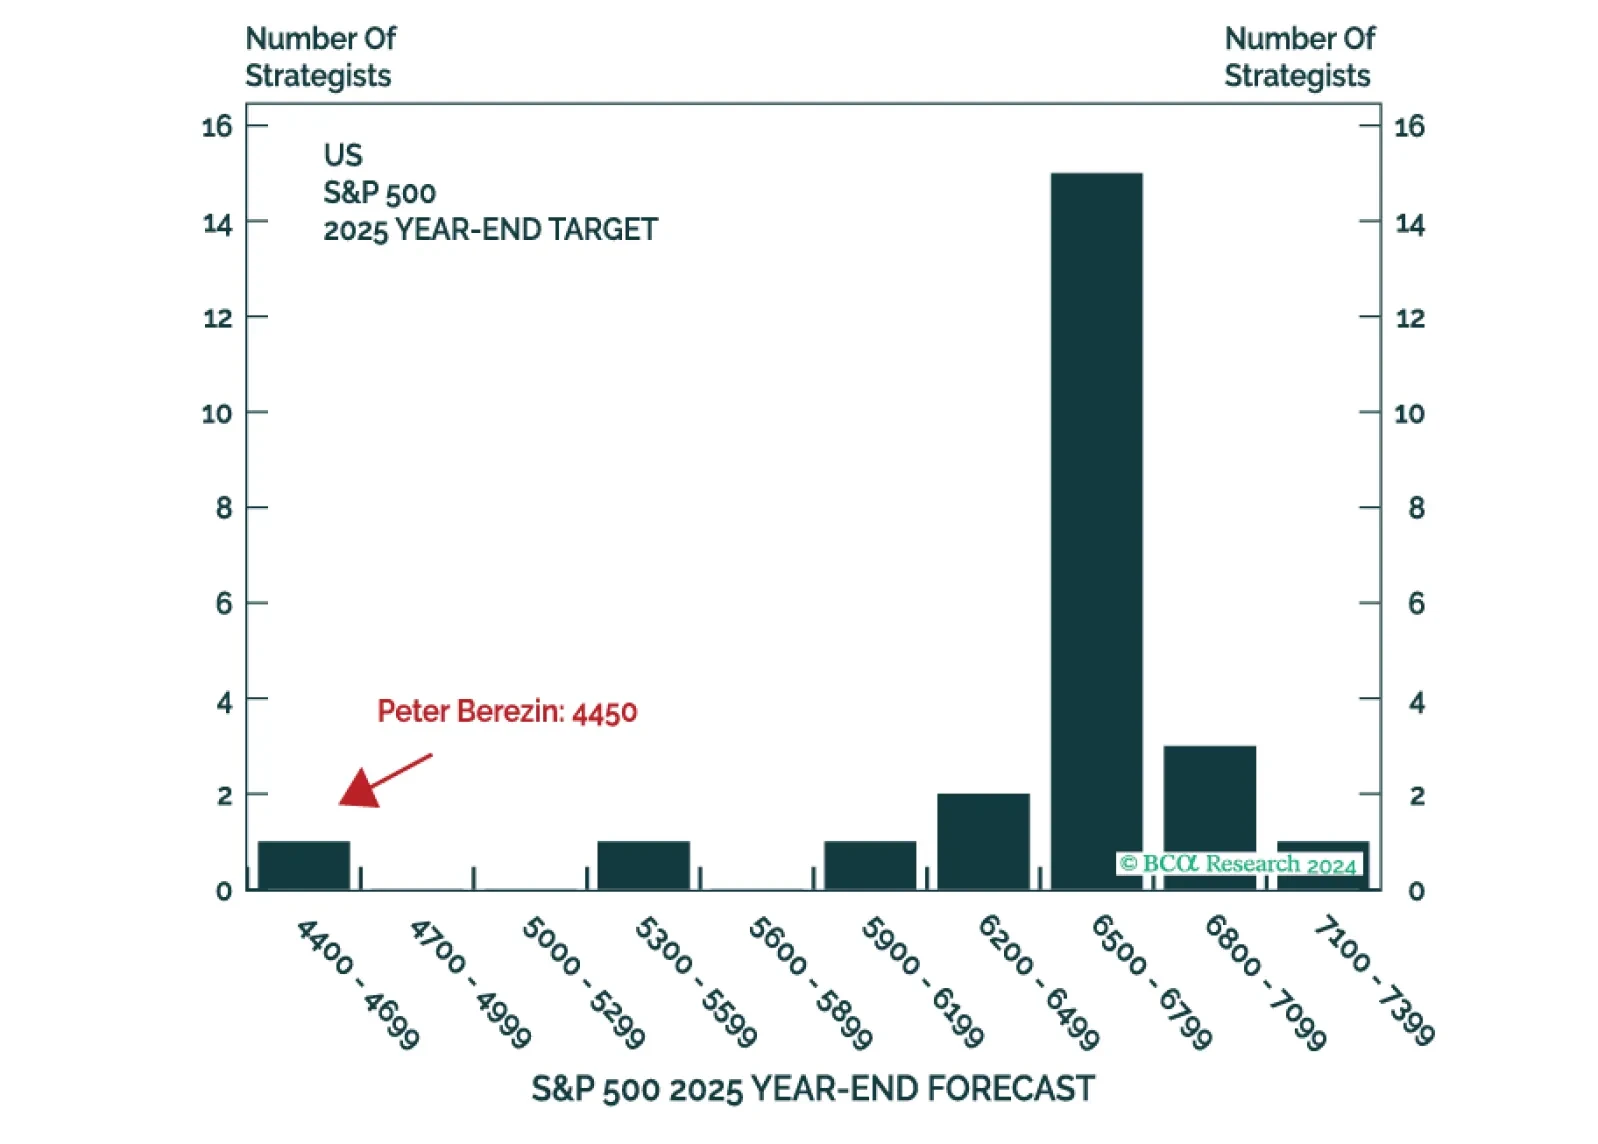
This is the time of the year when strategists are busy sending out their annual outlooks. Here on the Global Investment Strategy team, we decided to go one step further. Rather than pontificating about what could happen in 2025, we decided to harness the power of the multiverse to tell you what did happen (in at least one highly representative timeline).
Next week, please join me for a Webcast on Tuesday, December 17 at 10:30 AM EST (3:30 PM GMT, 4:30 PM CET) to discuss the economy and financial markets.
And with that, I will sign off for the year. I wish you and your loved ones a very happy and healthy 2025. We will be back in the first week of January with our MacroQuant Model Update.
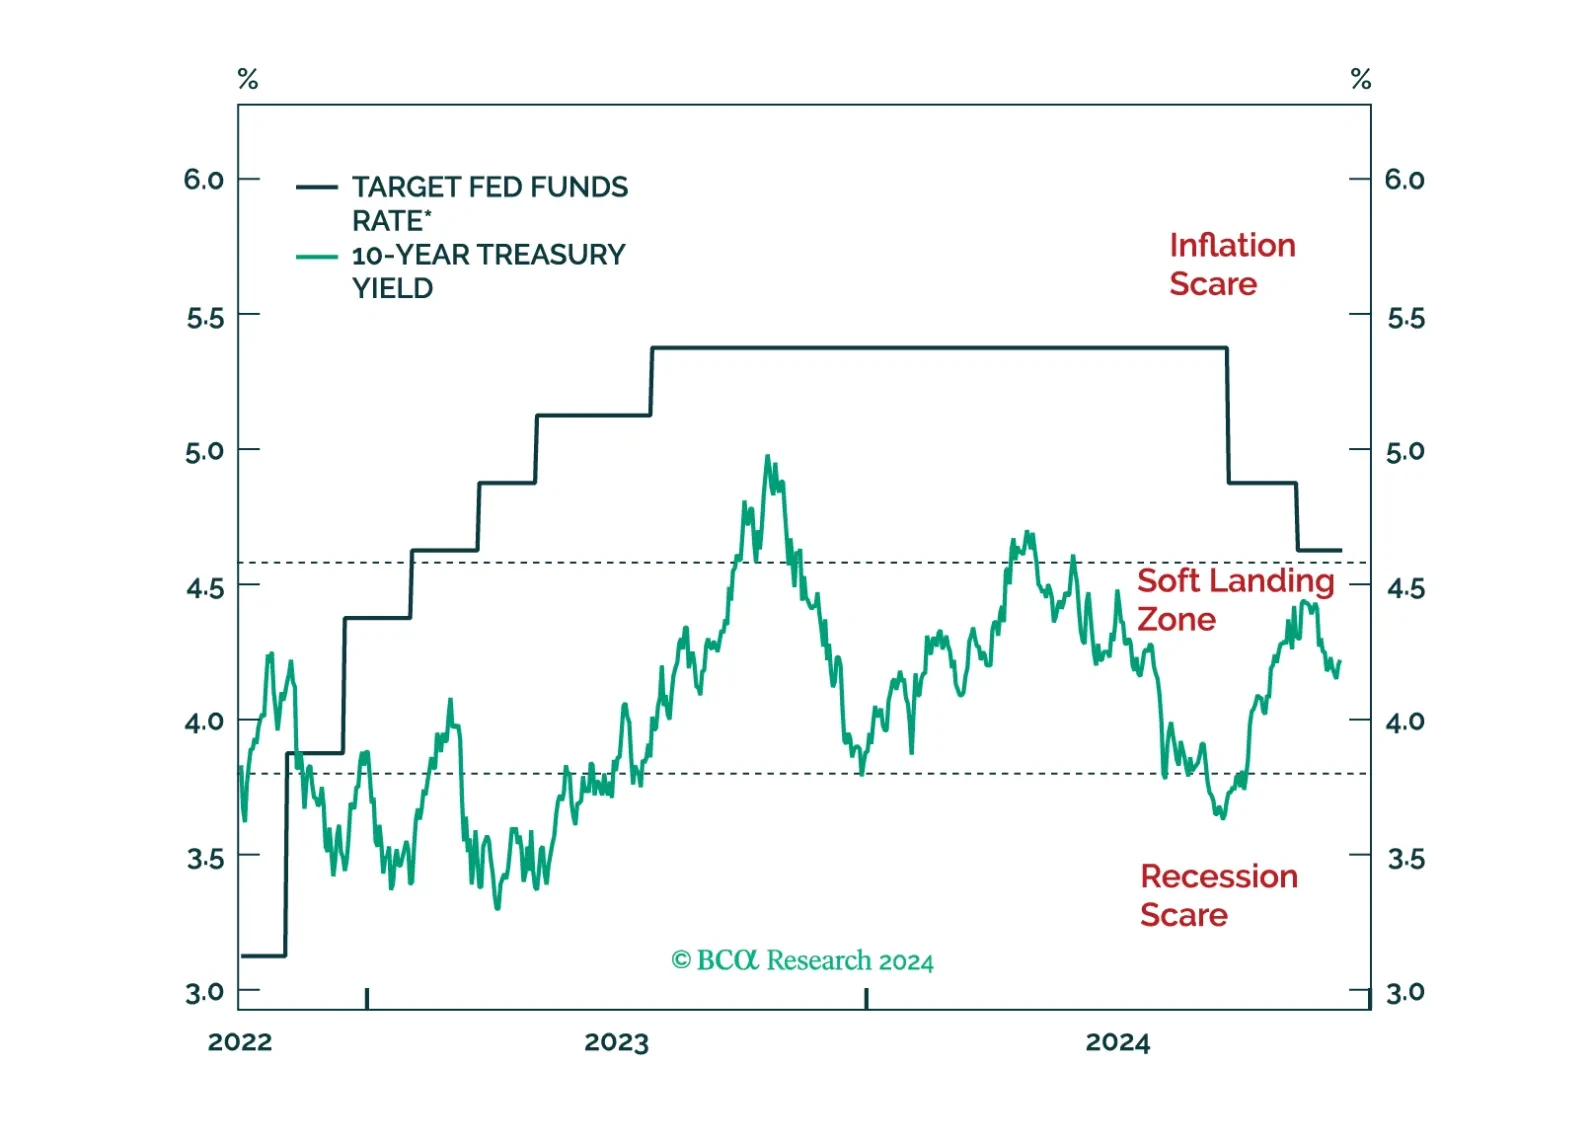
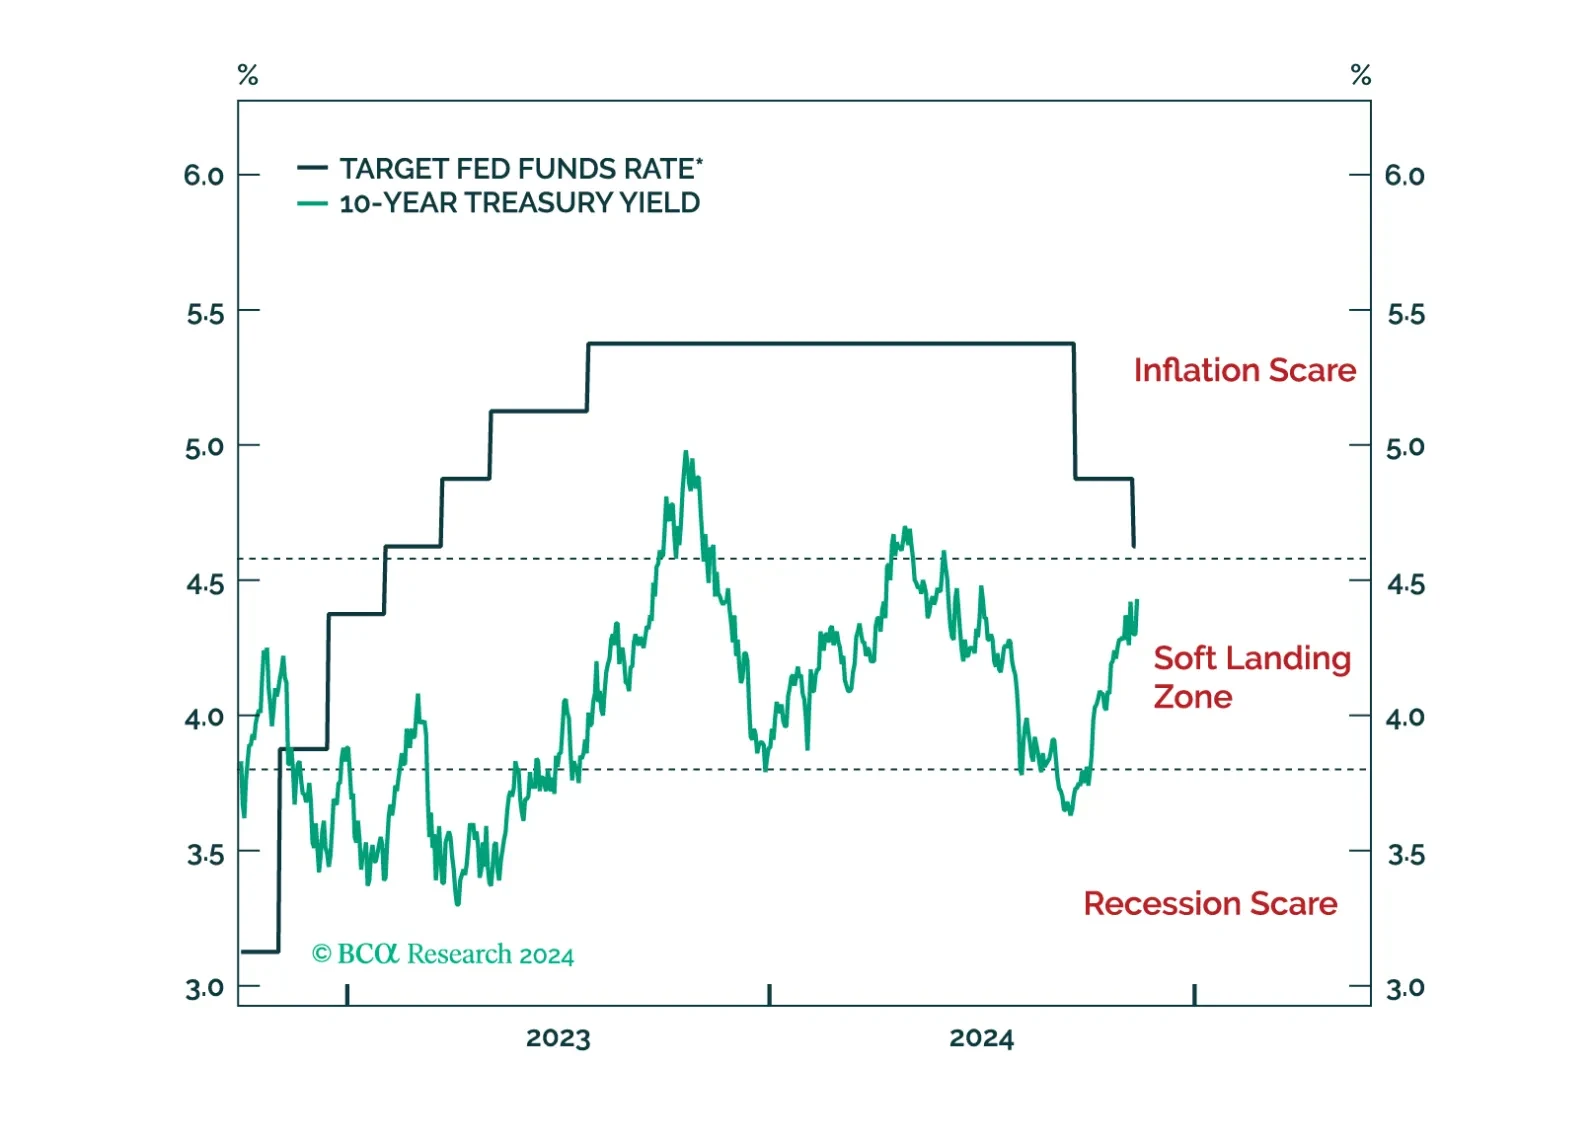
We offer 5 key investment views for US fixed income markets in 2025.
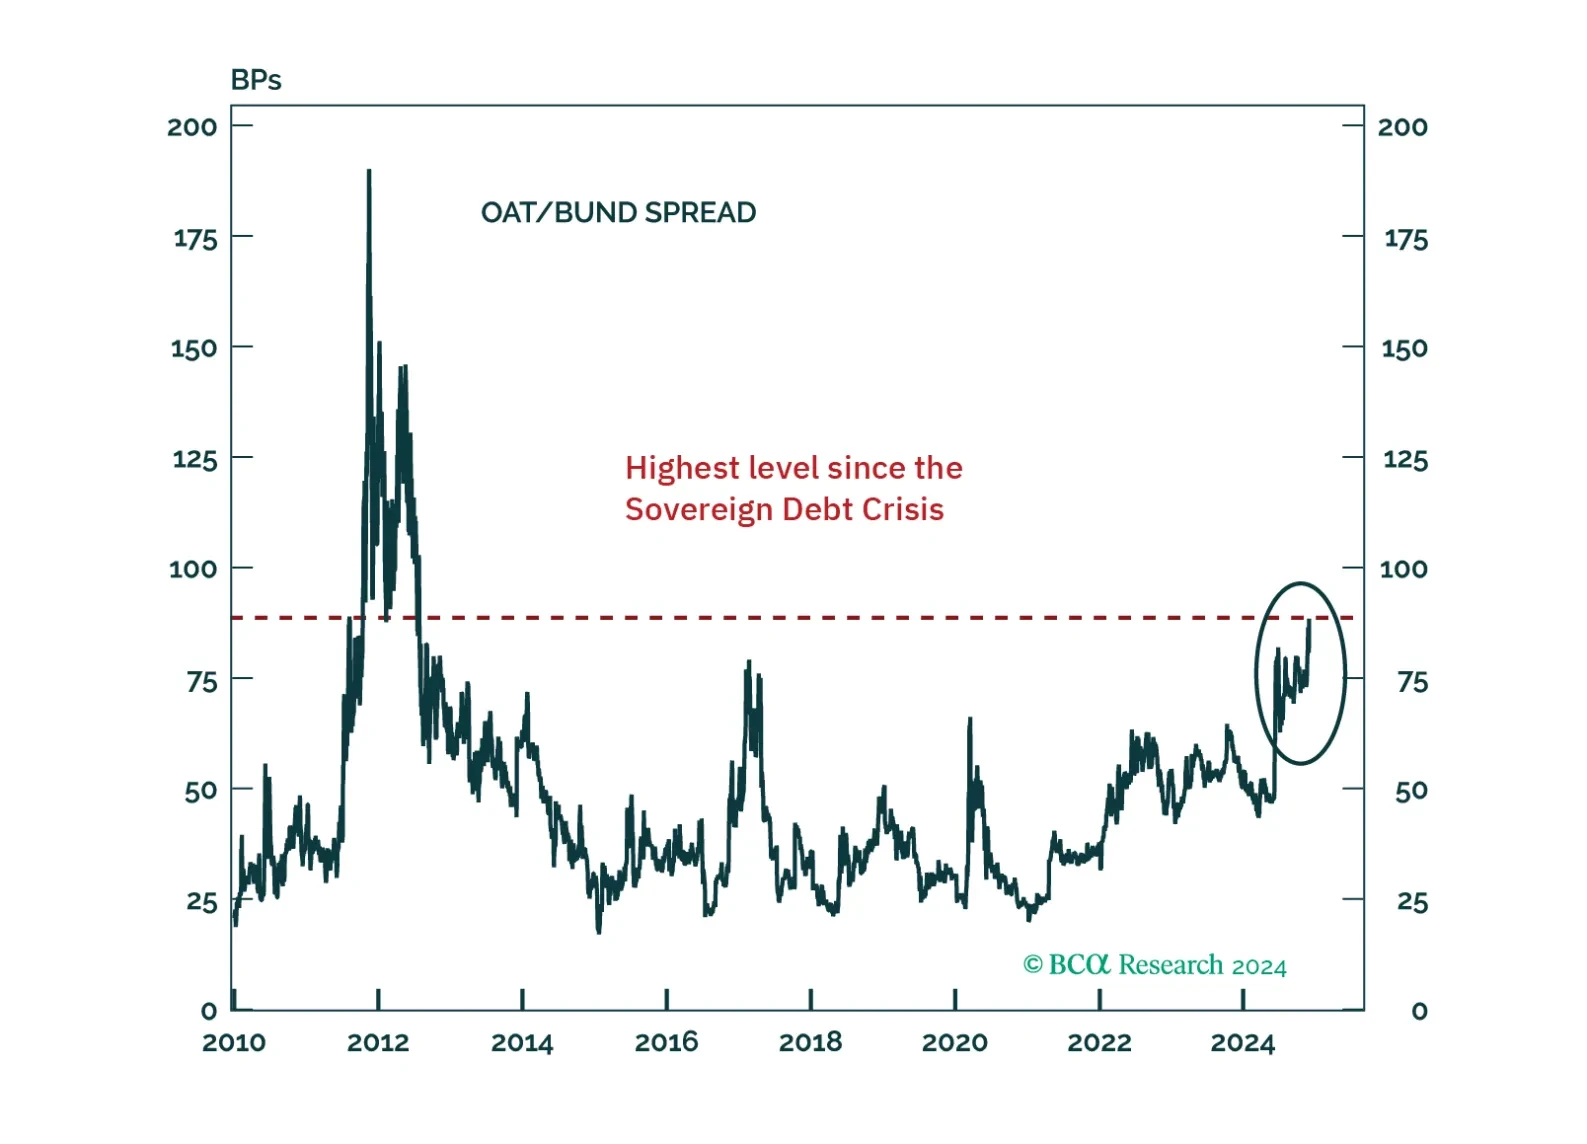
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors?

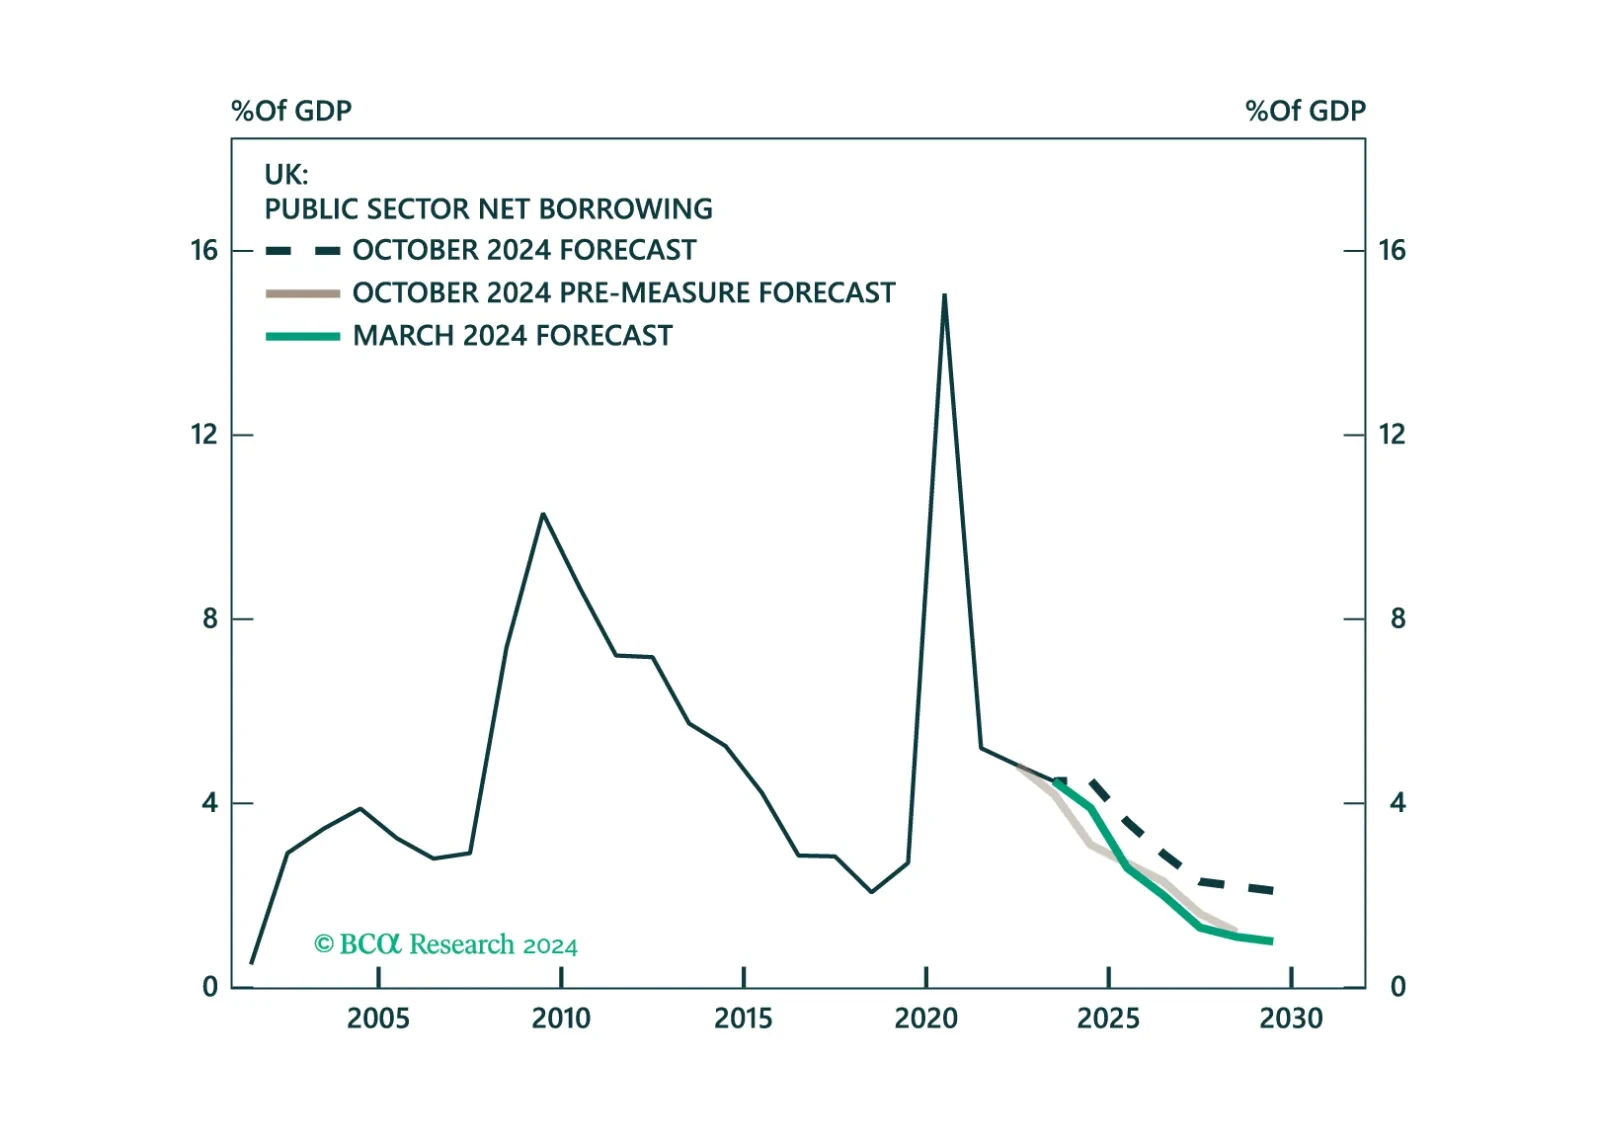
Este Strategy Insight presenta nuestra opinión sobre el recorte de tipos de interés anunciado hoy por el Bank of England, así como sobre el presupuesto anunciado por el gobierno del Reino Unido la semana pasada.
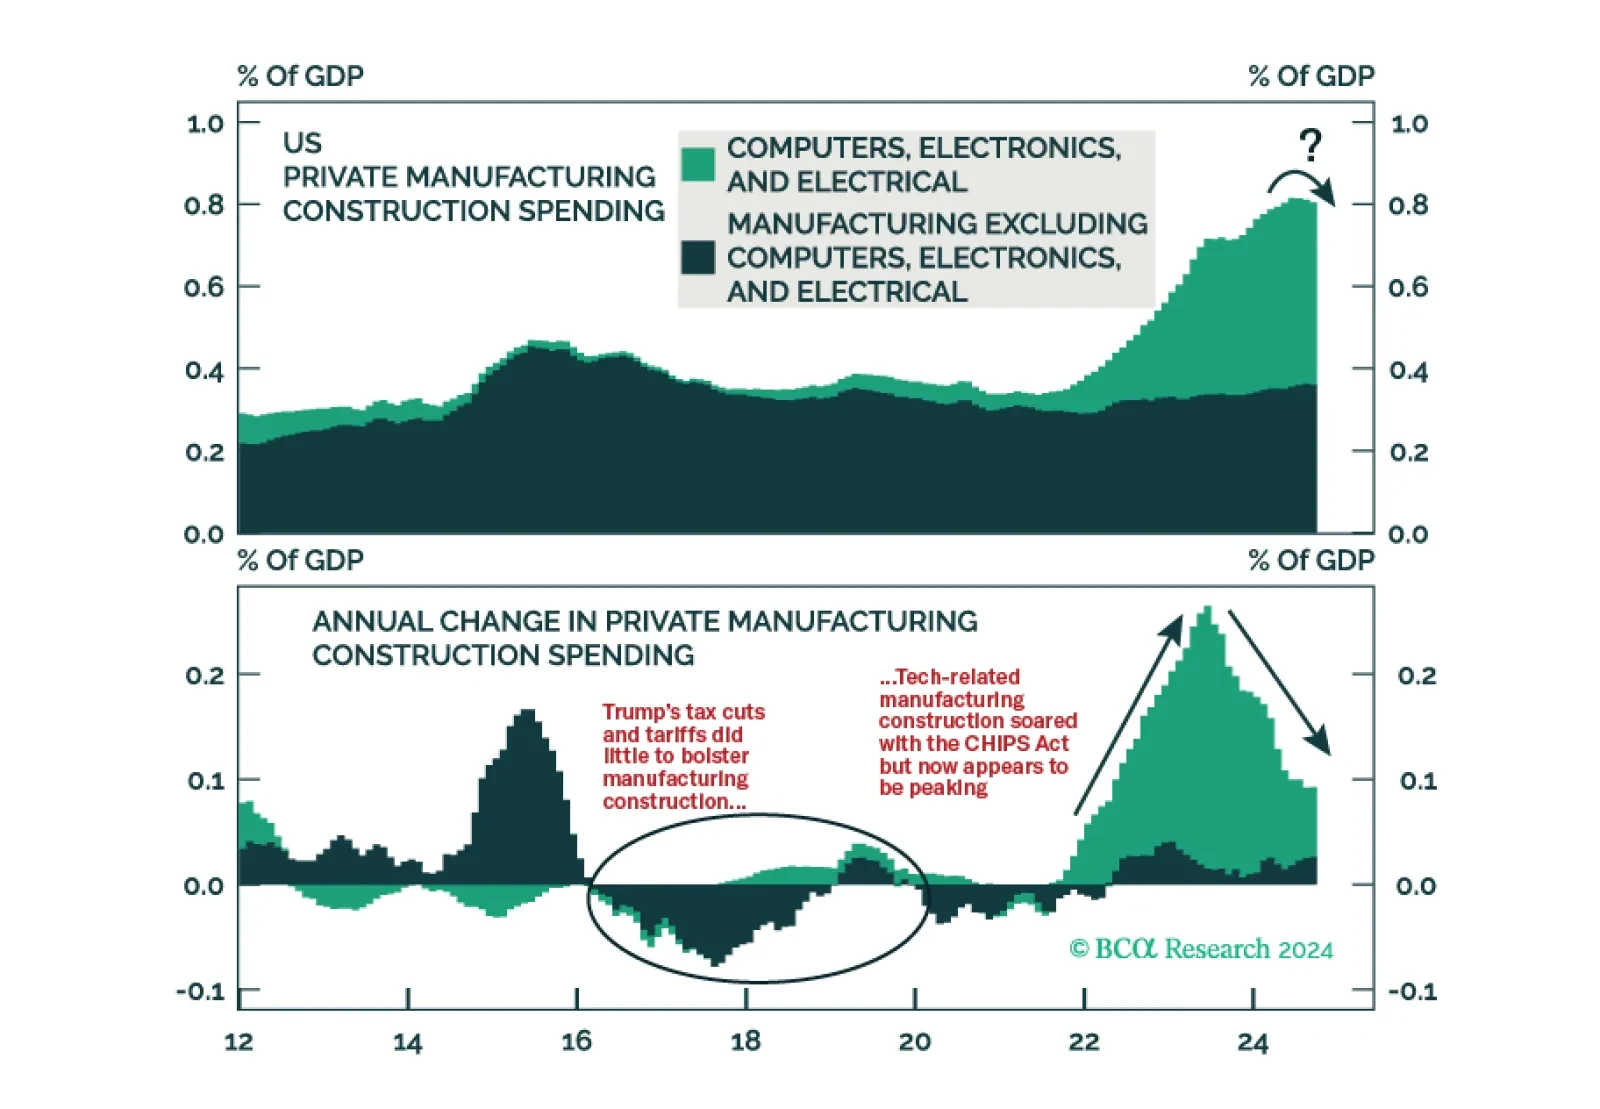
La perspectiva de una nueva guerra comercial compensa con creces las demás partes proempresariales de la agenda de Trump. Con el mercado laboral ya debilitándose de cara a las elecciones, estamos elevando nuestra probabilidad de recesión en Estados Unidos a 12 meses del 65% al 75%.

Our thoughts on the bond market’s reaction to the election and this afternoon’s FOMC meeting.