España
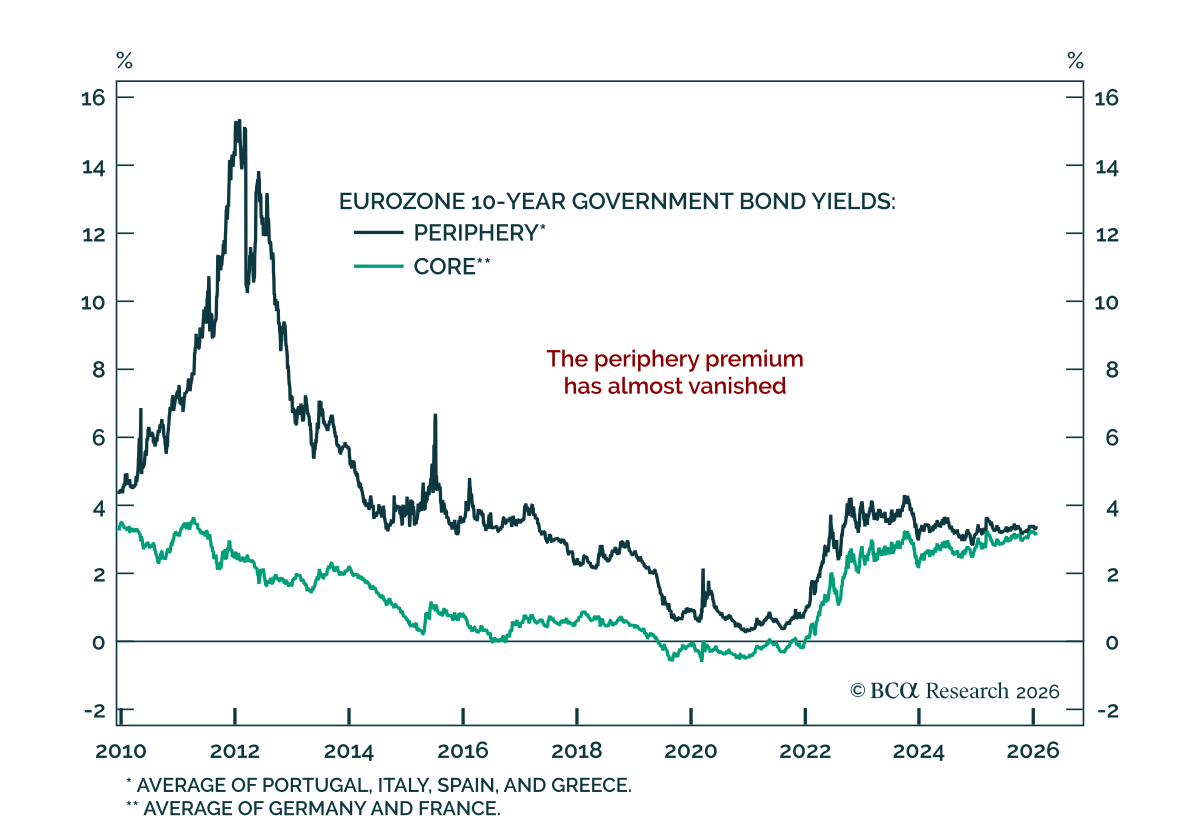
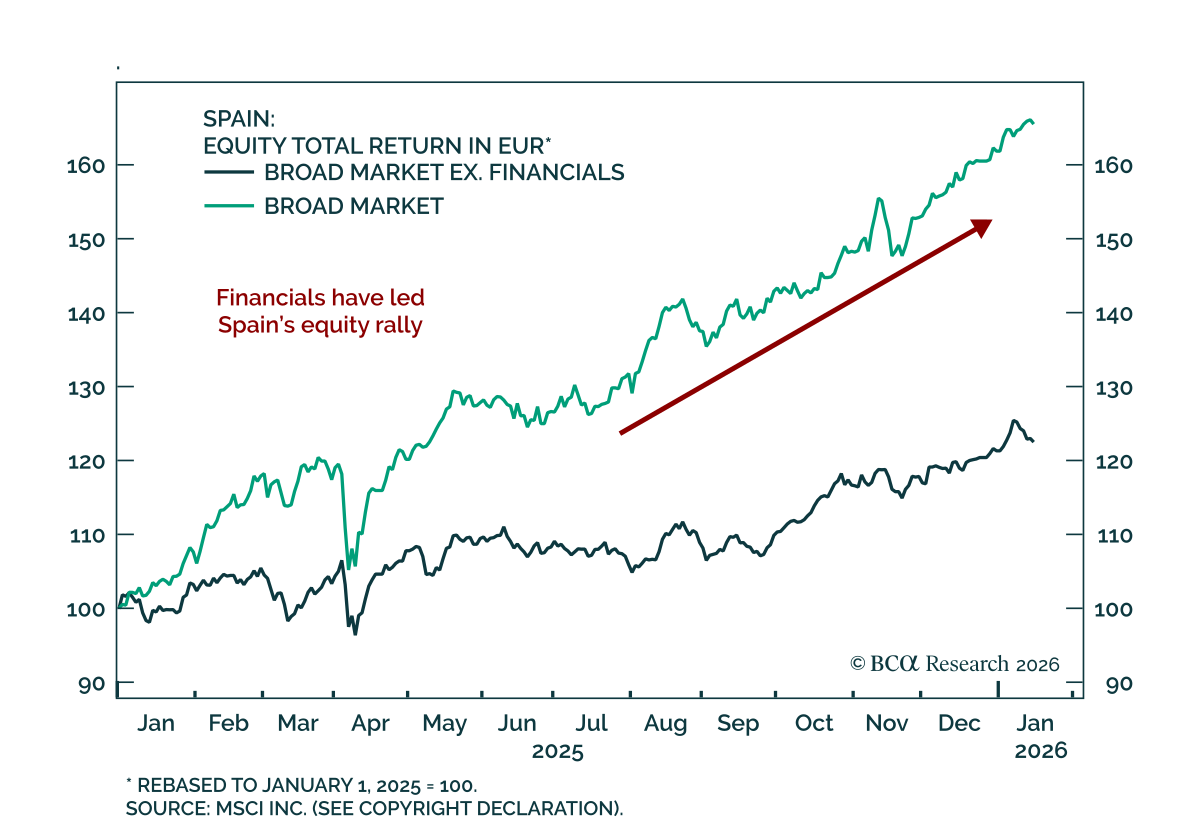
El rendimiento superior de las acciones y los bonos de España refleja una verdadera reparación fundamental: menores préstamos morosos, mayor rentabilidad y mejoras sostenidas en las ganancias. Las valoraciones siguen siendo poco exigentes a pesar del repunte. La productividad es el principal riesgo estructural, pero los fundamentos a corto plazo continúan sorprendiendo al alza.
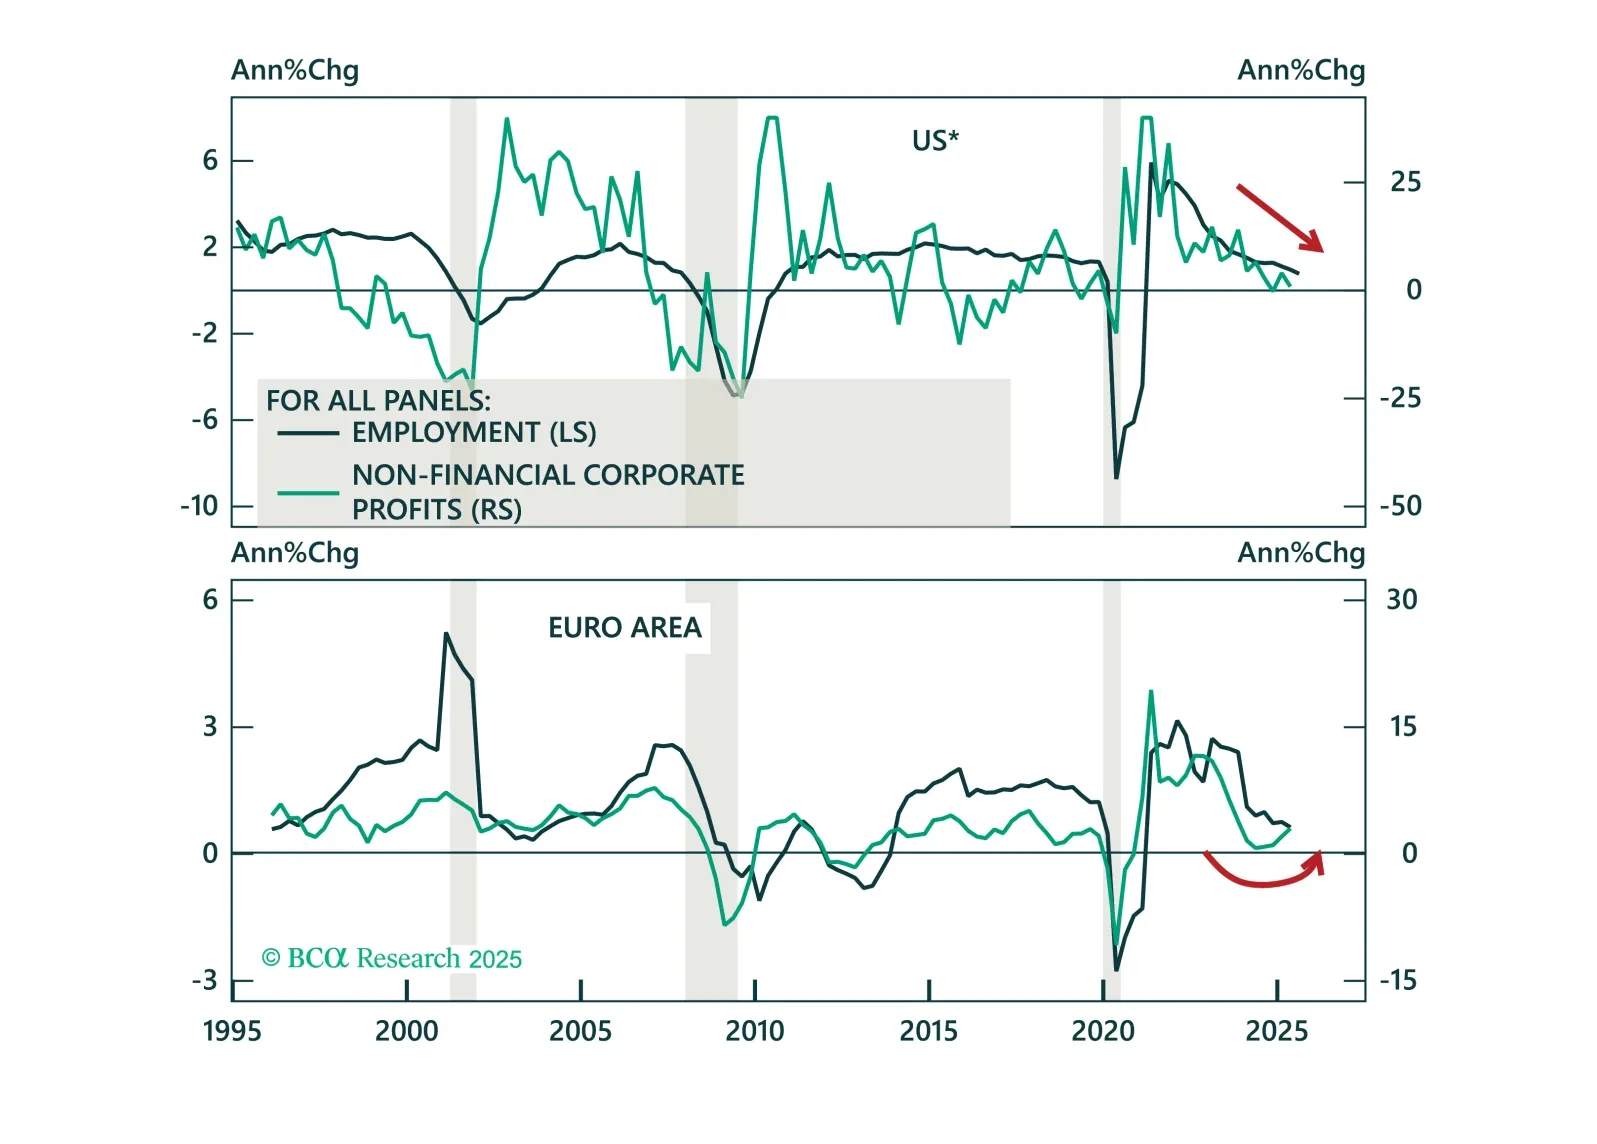
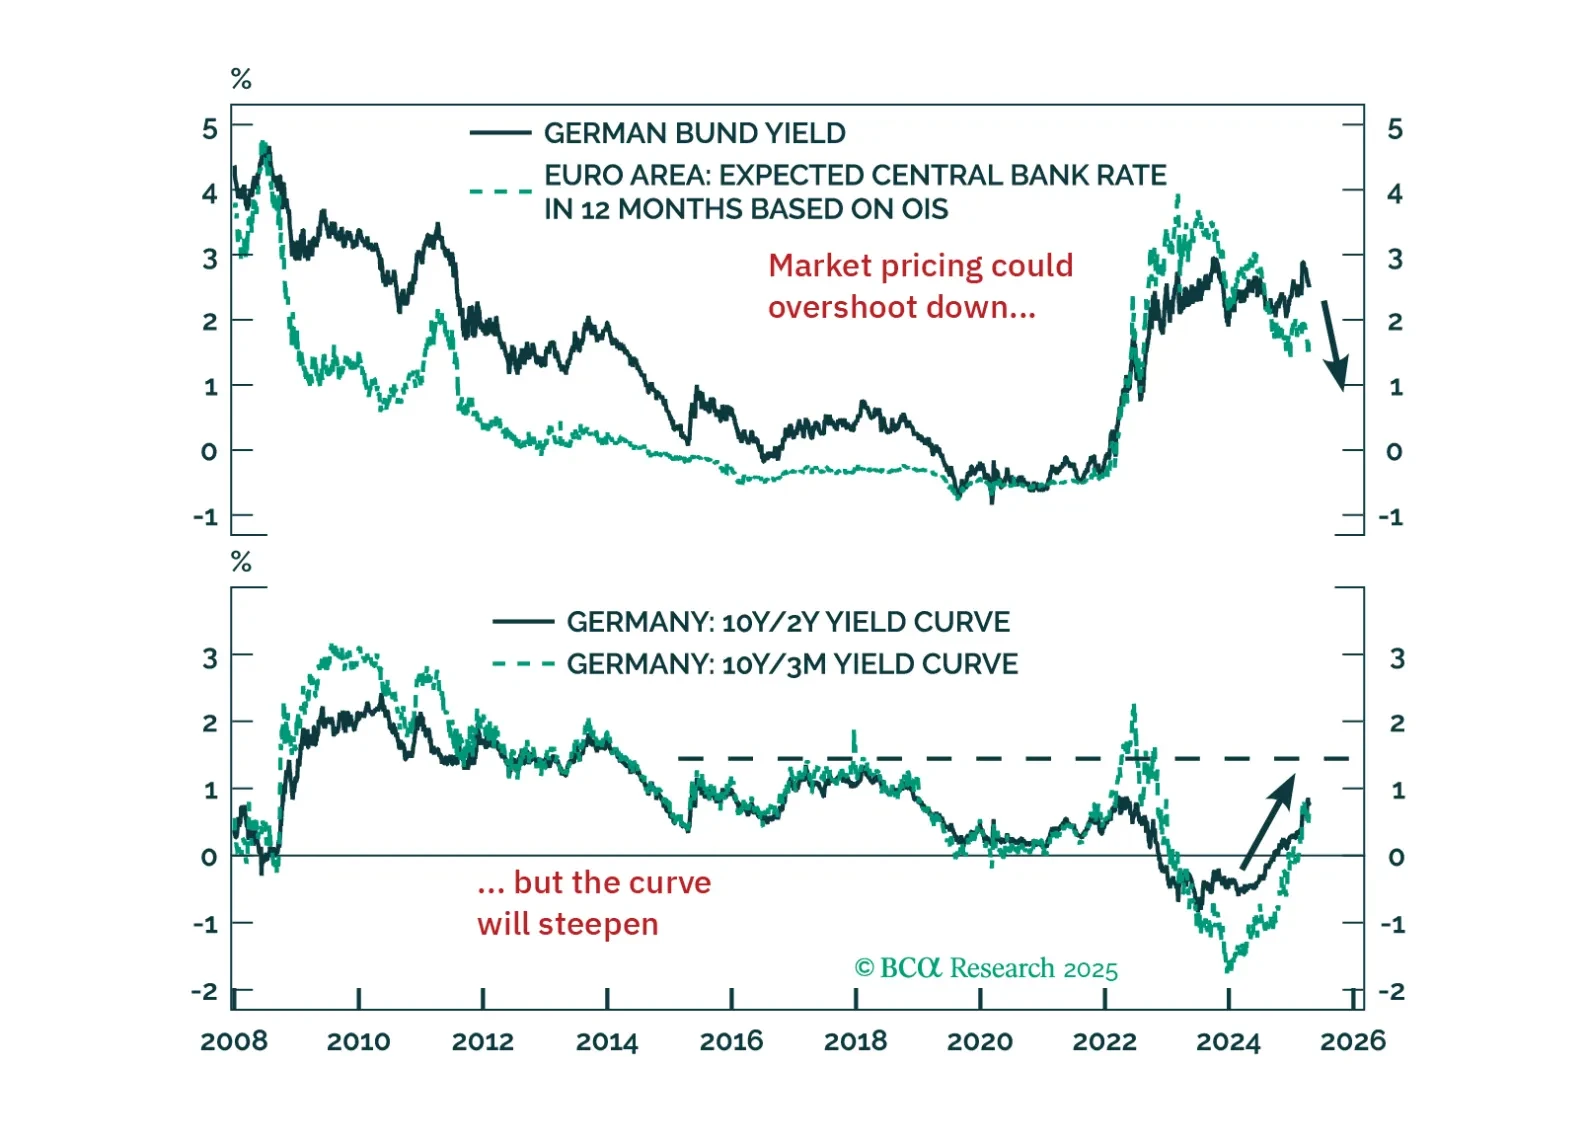
Europe’s deflation problem is getting harder to ignore. This week’s ECB cut is just the beginning — tariffs, the euro’s rally, and softening demand all point to more easing ahead. We explain what it means for yields, equities, and EUR/USD.
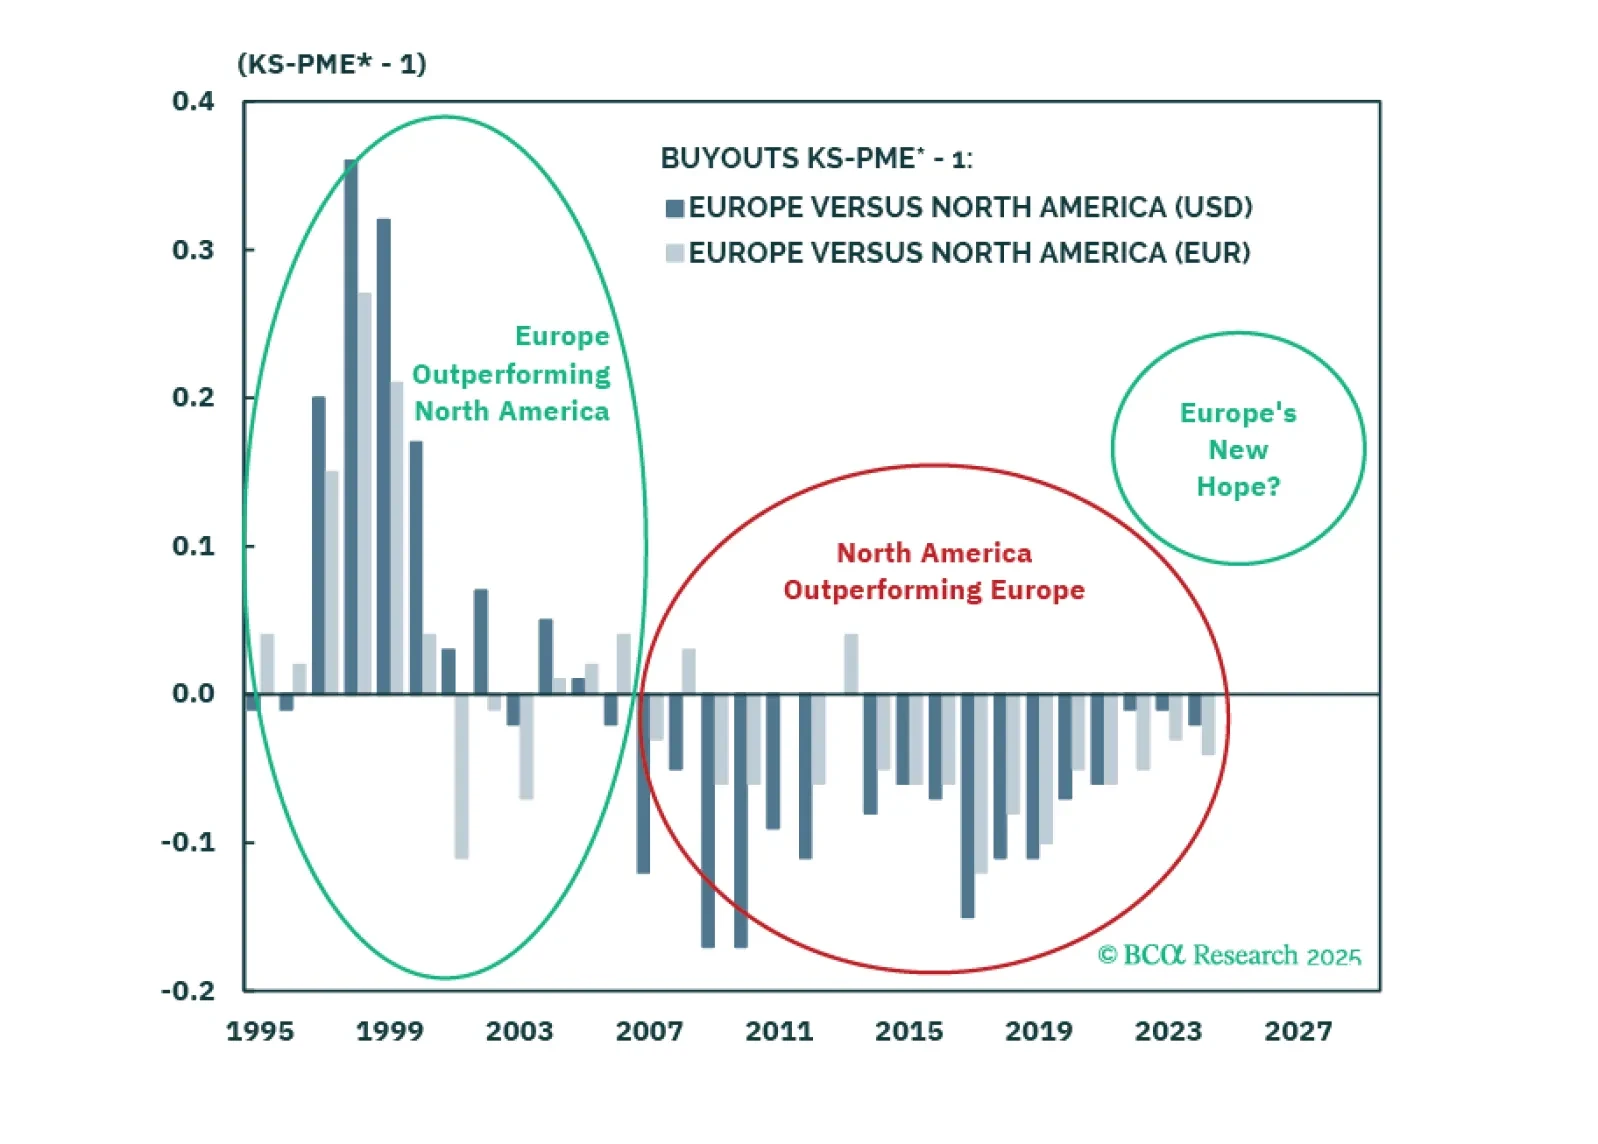
We are at a pivotal moment for Europe, supported by structural reforms and macro catalysts. While expanding credit markets and lower rates favor Private Equity over Private Credit, opportunities vary by segment. Large+ Buyouts are attractive as markets have priced in structural challenges. We downgrade Europe Private Credit, remain neutral on Europe Private Equity broadly but overweight Europe vs. North America in PE portfolios.
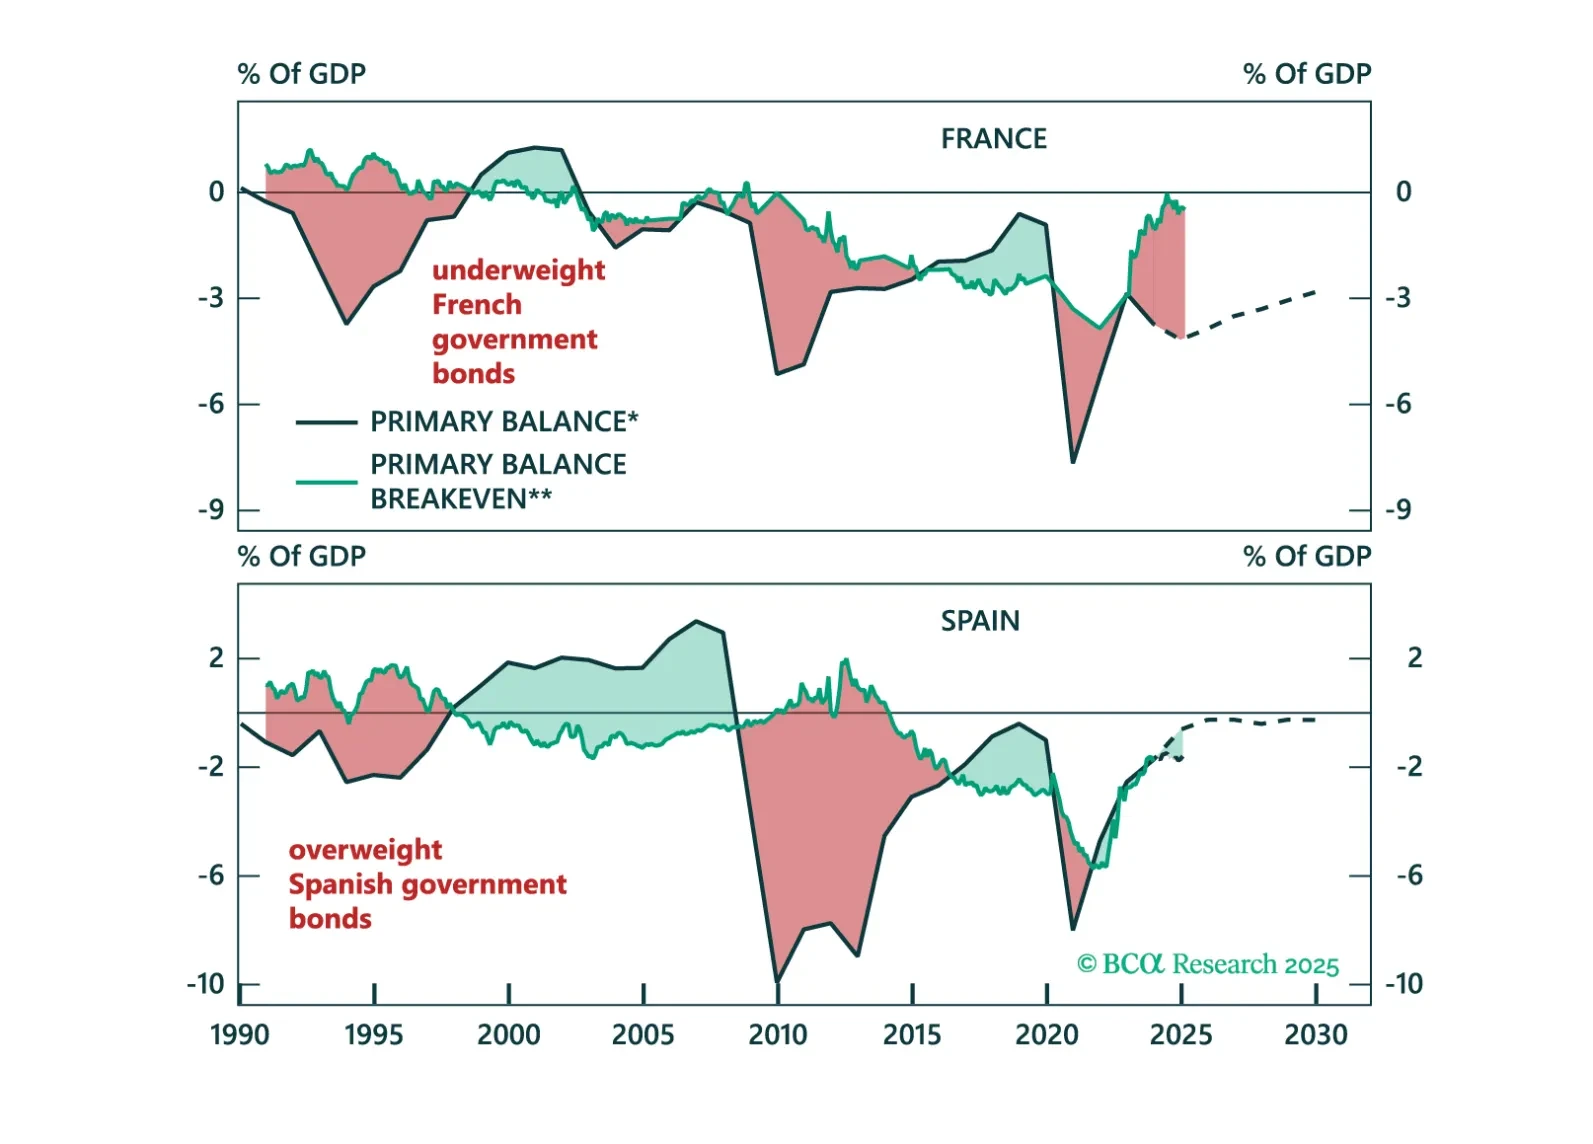
Questions about fiscal risks and their impact on bond markets have become more frequent in client conversations. This Special Report provides a framework to assess a country’s fiscal sustainability and how it affects its bond market outlook. On an individual country basis, Spain has shown a remarkable turnaround in its fiscal sustainability outlook while the fiscal outlook for France continues to deteriorate.

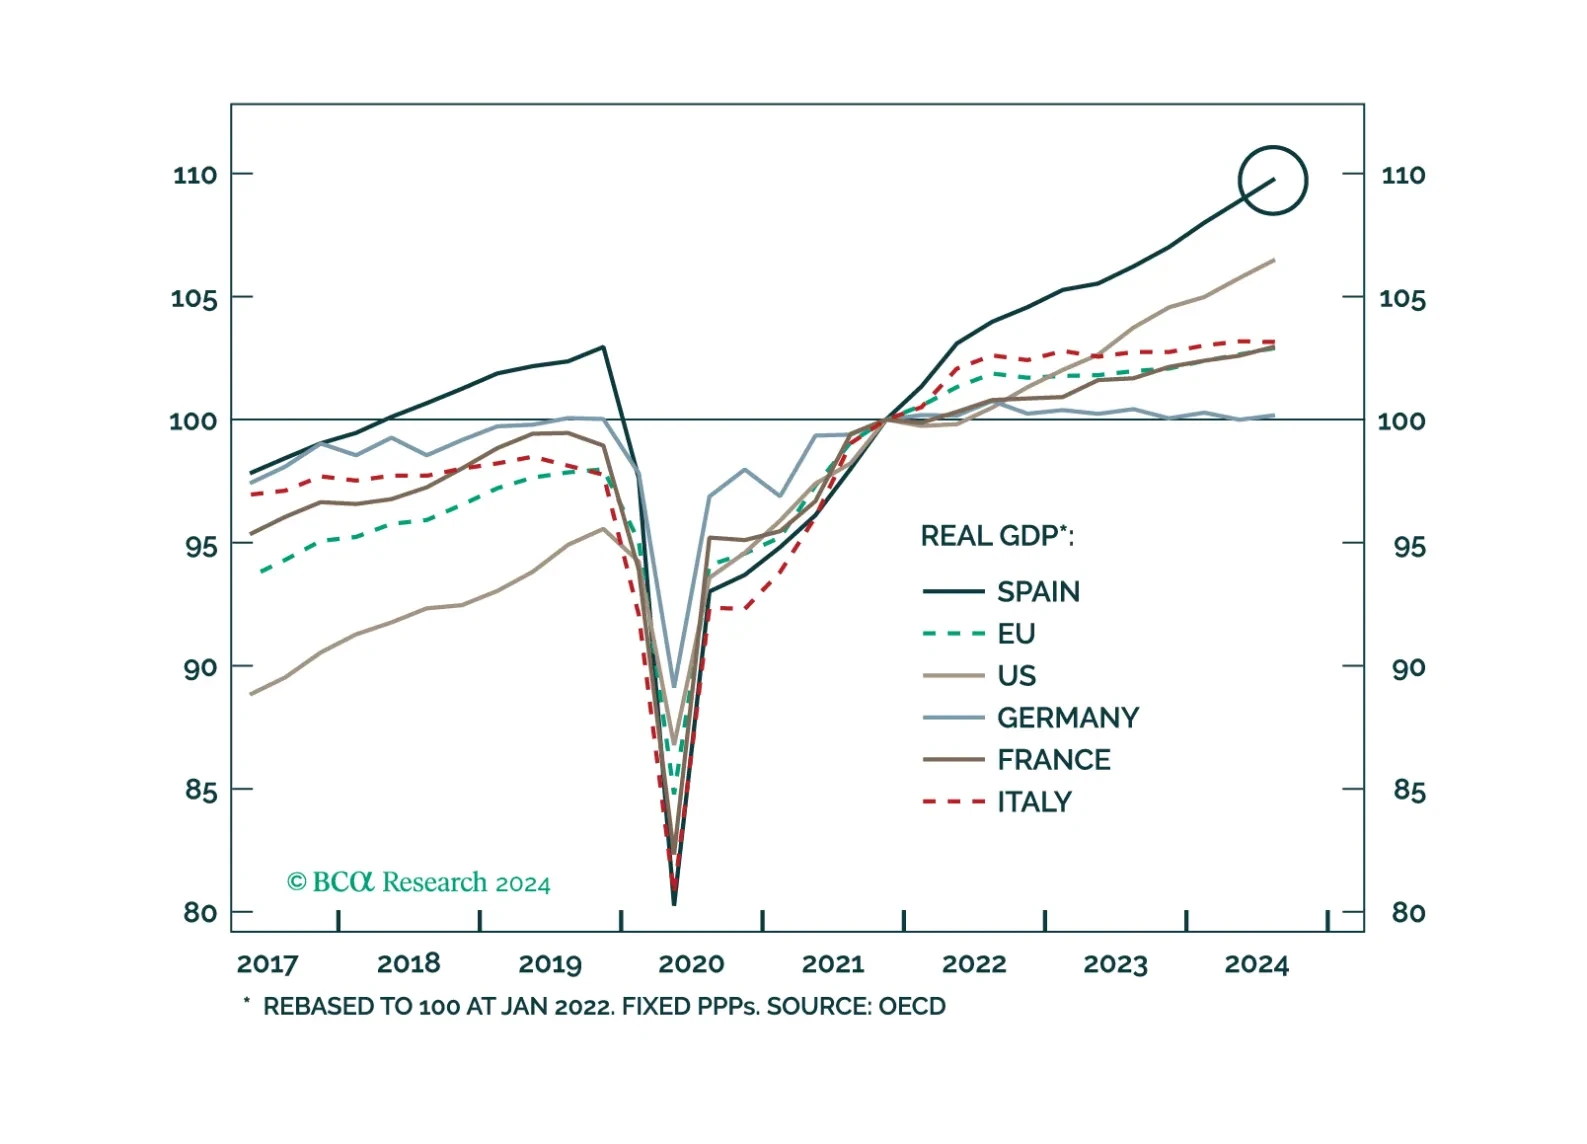
Spain has outperformed most developed markets since 2022 – real economic output and risk assets alike. Can it last?
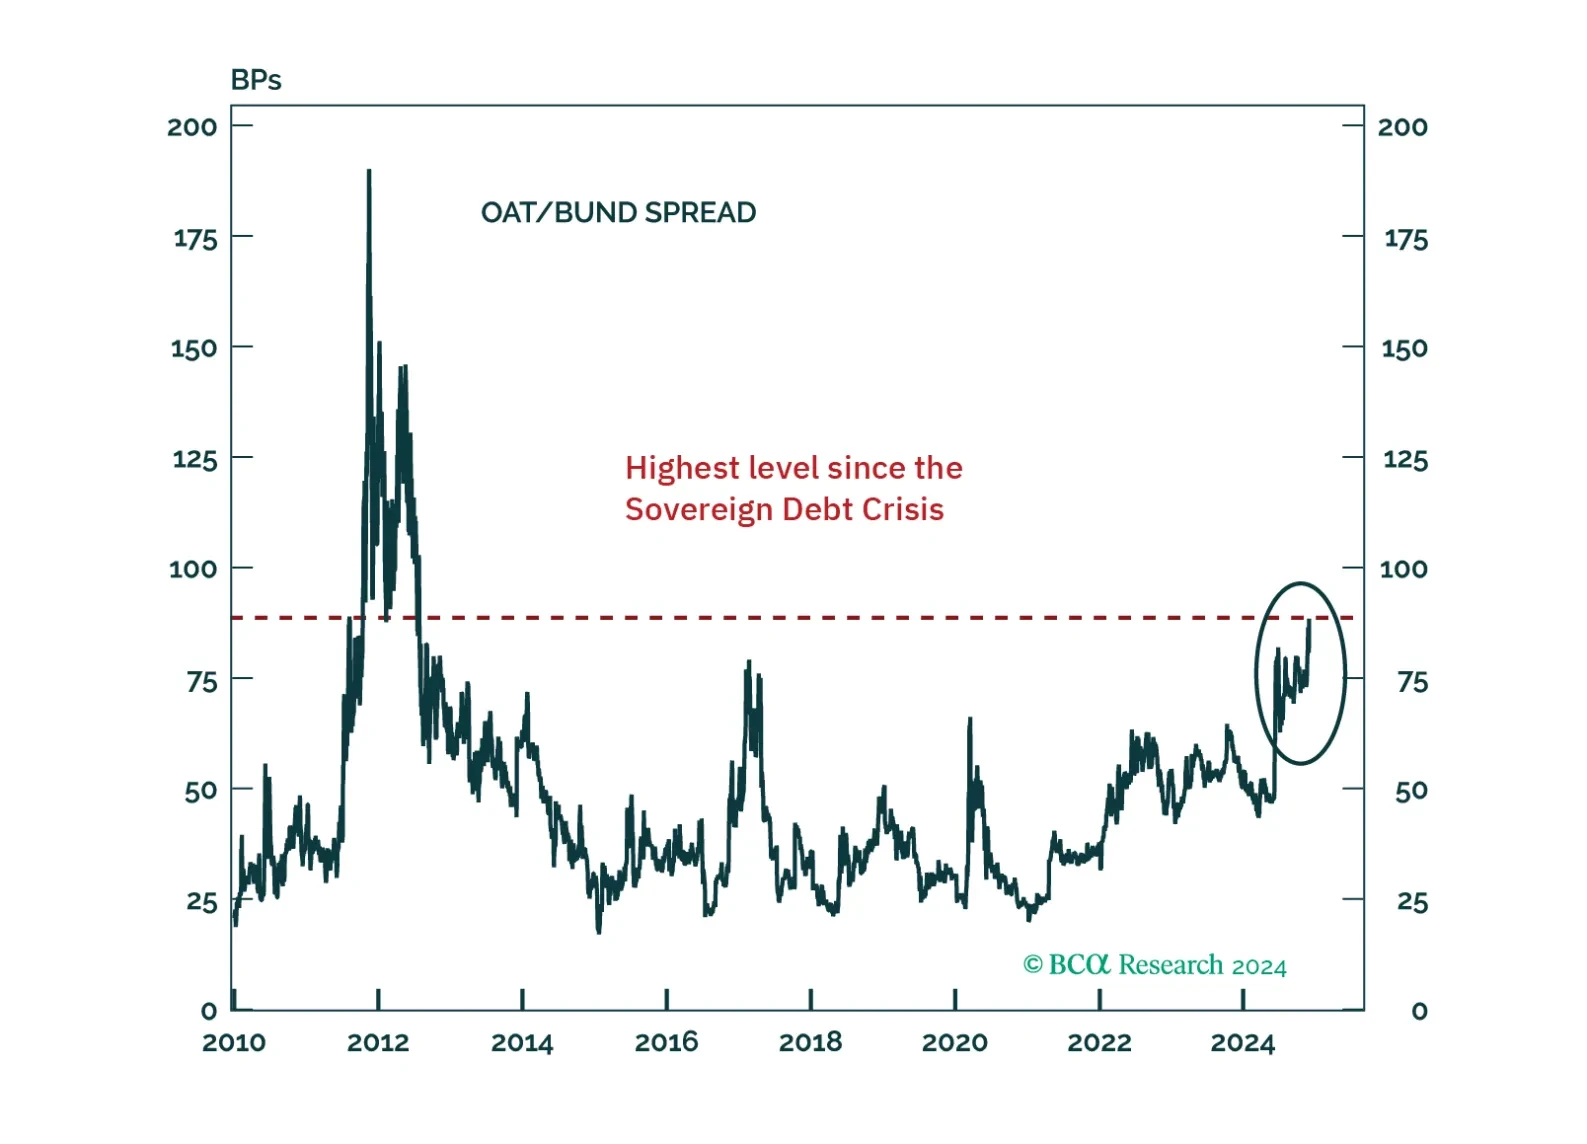
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors?