 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
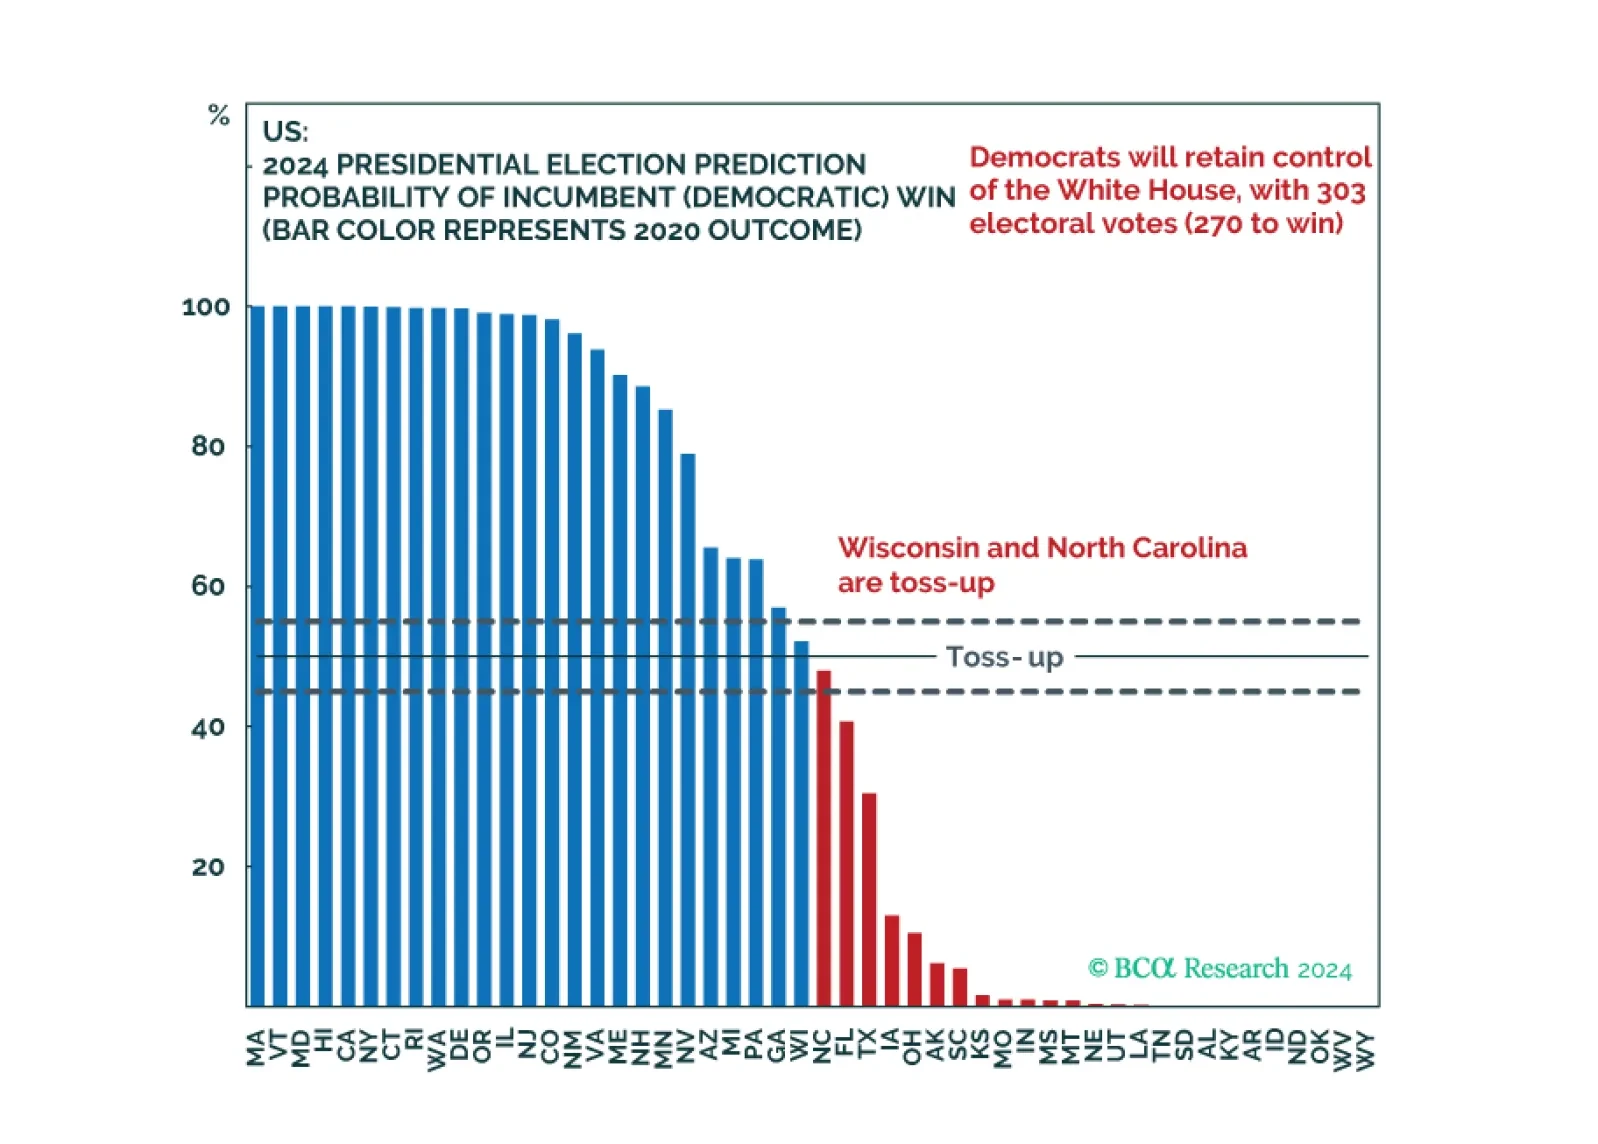
Our quant model shows Democrats winning the election at a 56% probability, with 303 electoral college votes. But swing state economies are slowing and Democrats’ odds in Michigan fell. Trump can win with Georgia, Michigan, plus one other state. Neither the Fed nor China’s stimulus should reduce one’s odds of a Republican upset.
Markets are rallying on Fed rate cuts and China stimulus but there will also be October surprises ahead of the US election, which Trump could still win. Russia’s conflict with the West is escalating and the Middle East is destabilizing further. Investors should favor US bonds but they should add some risk in emerging markets in response to China’s policy turn.
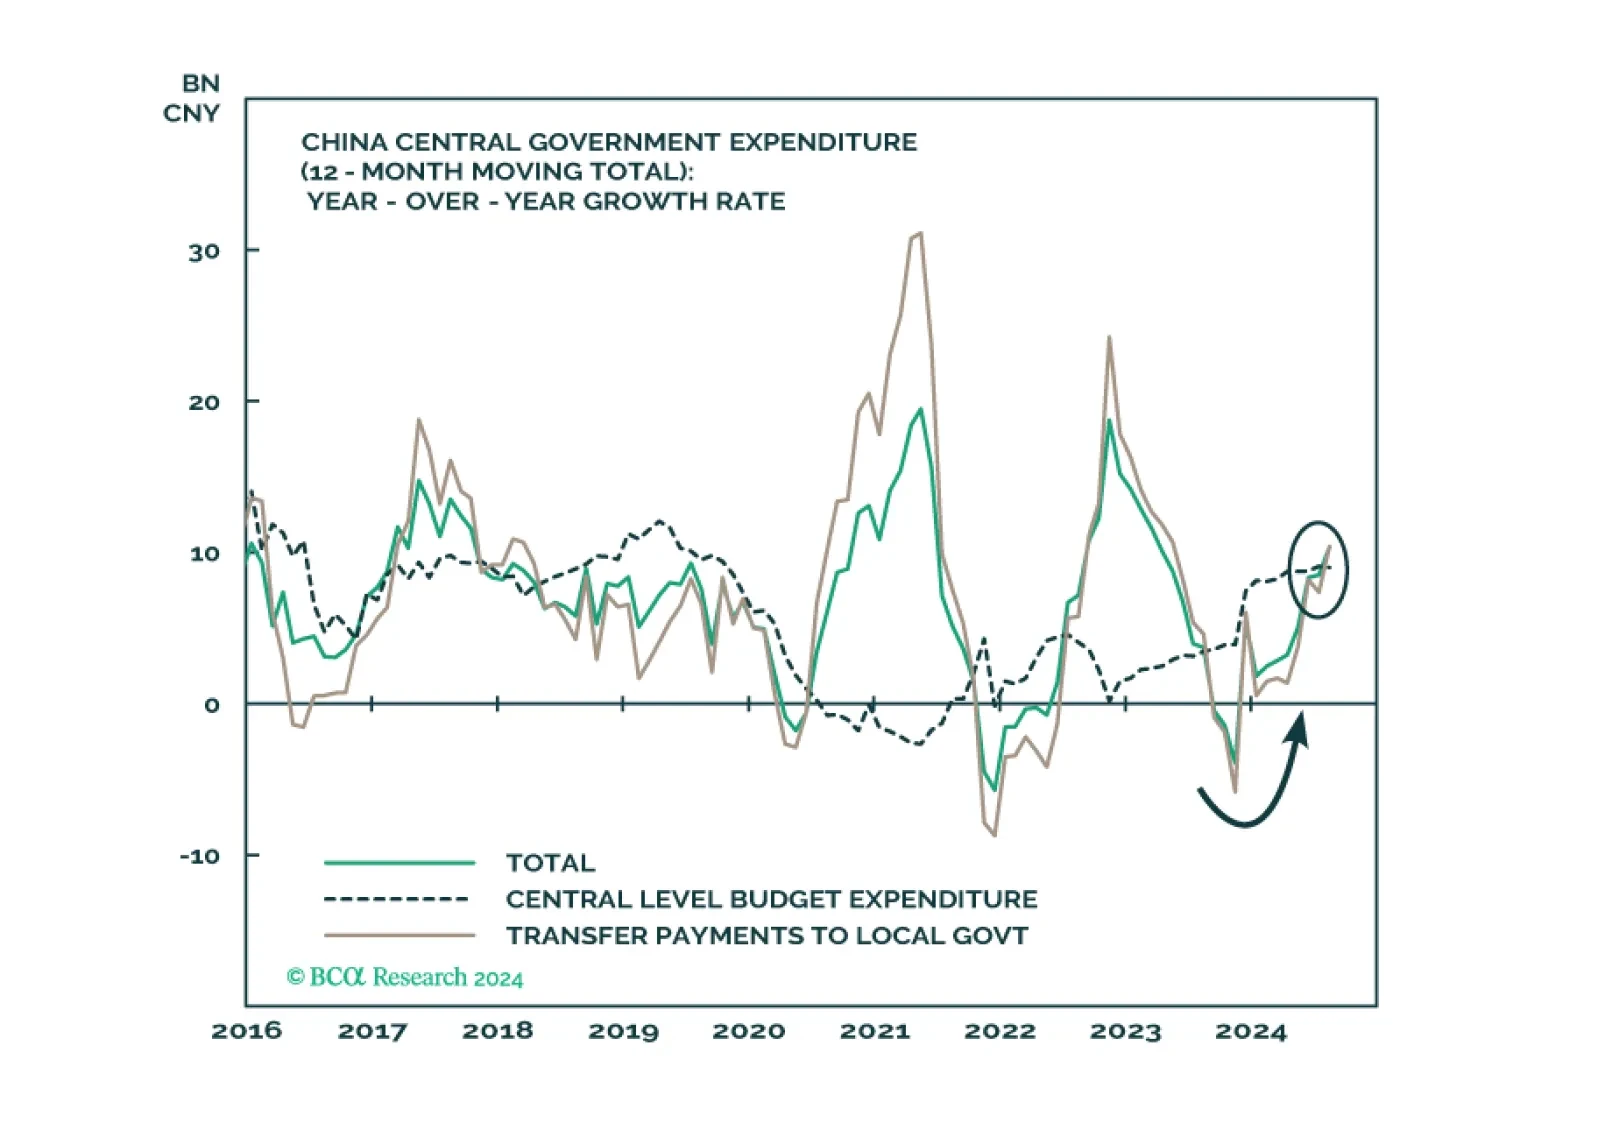
Chinese stimulus measures announced on September 24 found few structural optimists in the global macro community, us at BCA Research included. This is for good reason. China is mired in secular stagnation that cannot be unstuck by monetary policy alone.
It is not every day that we reference a Tucker interview as market relevant. His sit down with the VP candidate JD Vance caught our attention.
Investors should de-risk tactically in expectation of shocks and surprises ahead of the US election and an uncertain aftermath. Democratic victory with a gridlocked Congress is our base case but would bring minor tax hikes and nuclear brinksmanship with Russia. A Republican single-party sweep offers huge tax cuts but also a global trade war. Recession looms regardless.
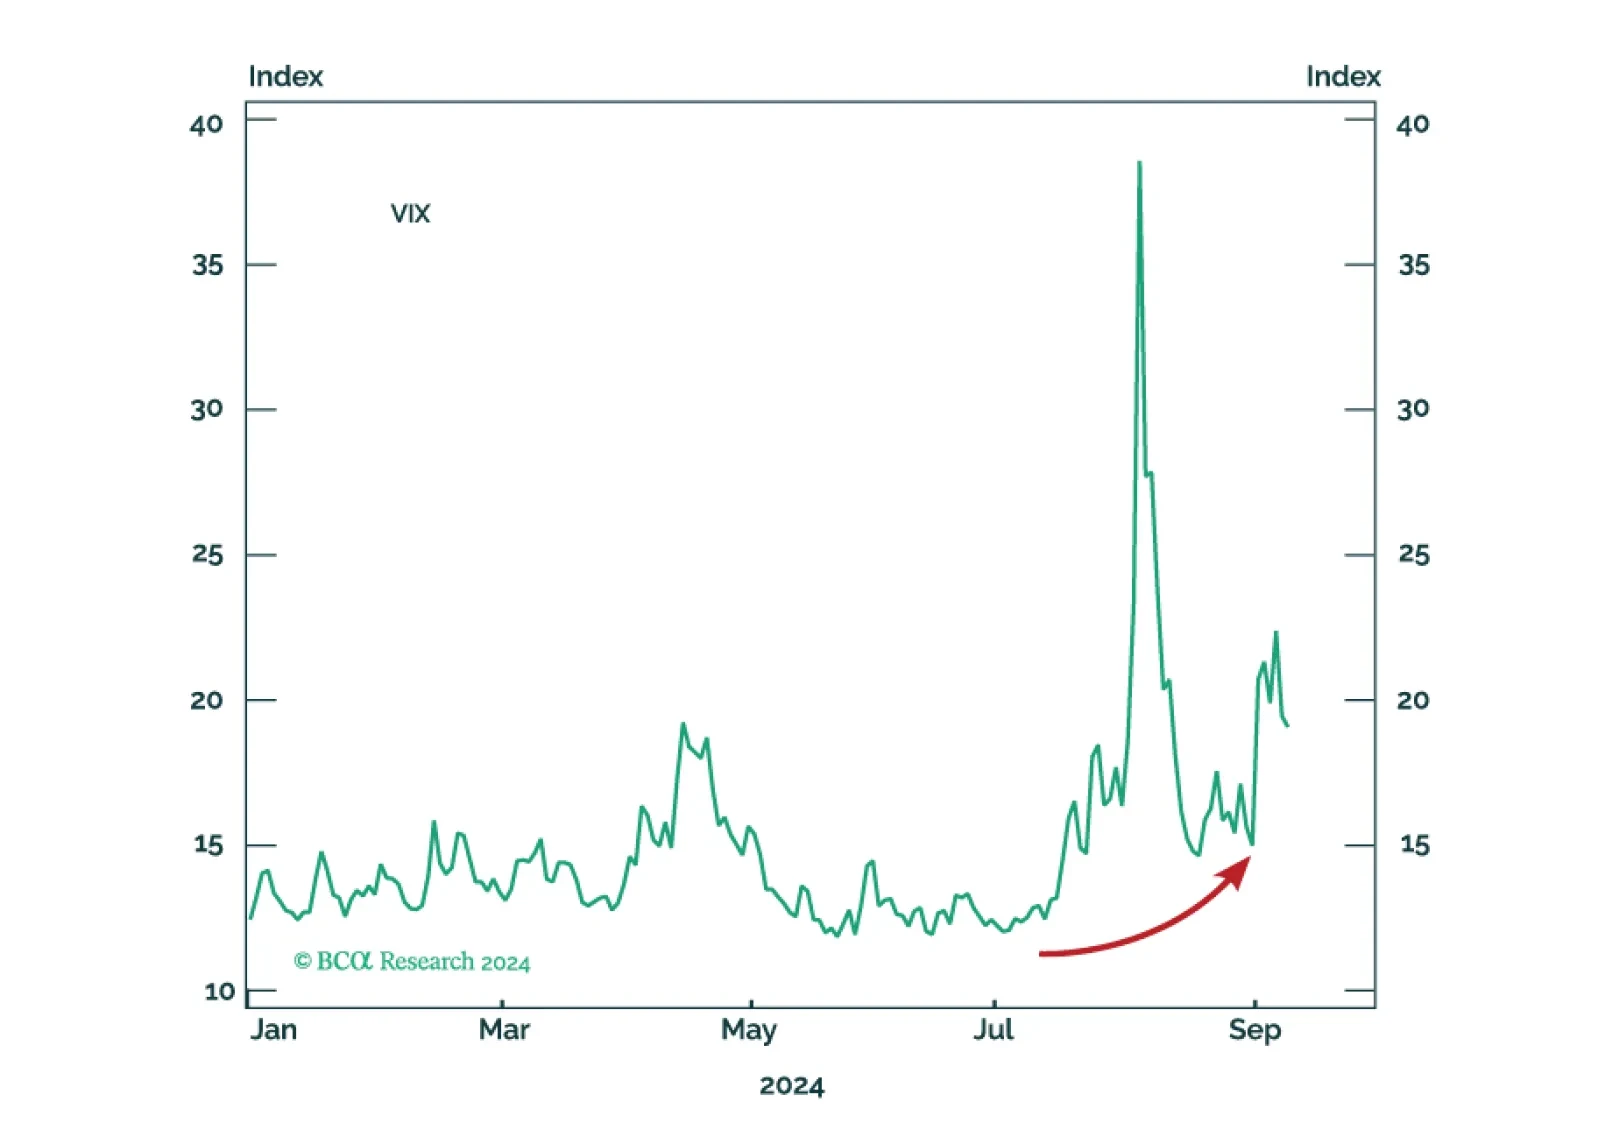
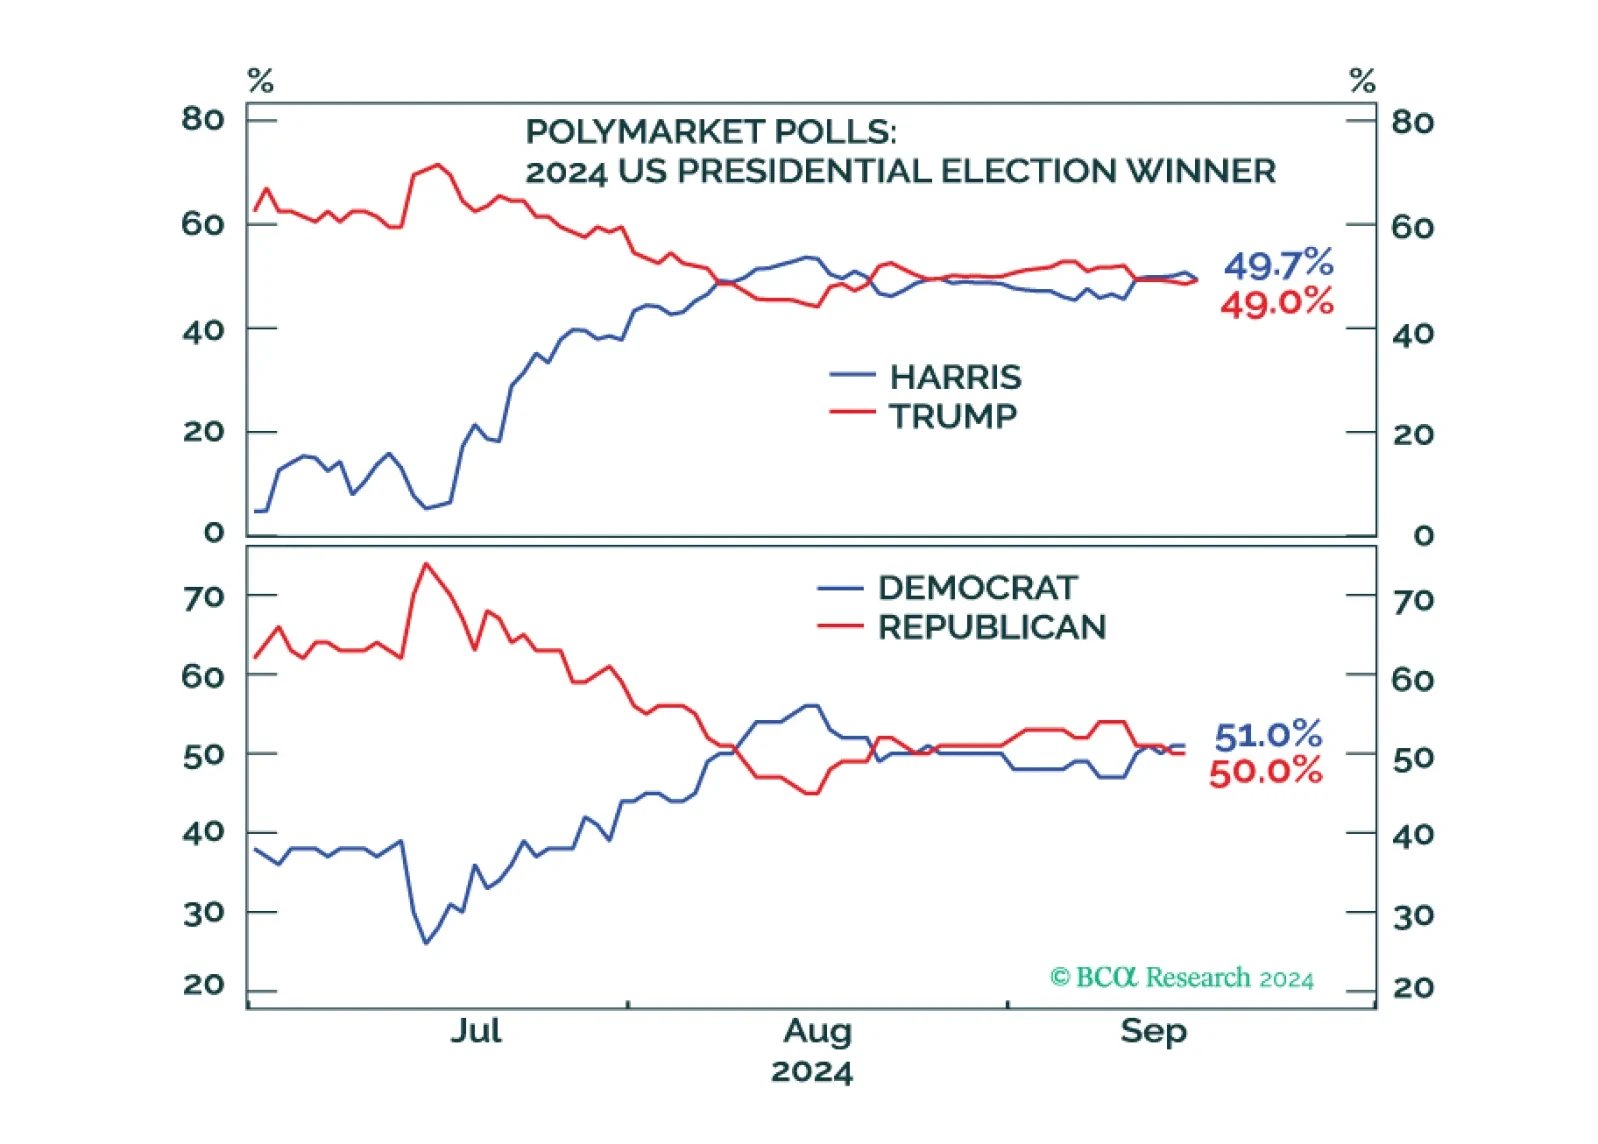
Despite the disastrous performance by former President Trump in the debate with Vice President Kamala Harris, there are still paths for him to come back to power. The economy and global instability could flare up anytime between now and election day, while quirks in the Electoral College ensure that the election will be close. The race is still competitive and policy uncertainty and volatility will be elevated.
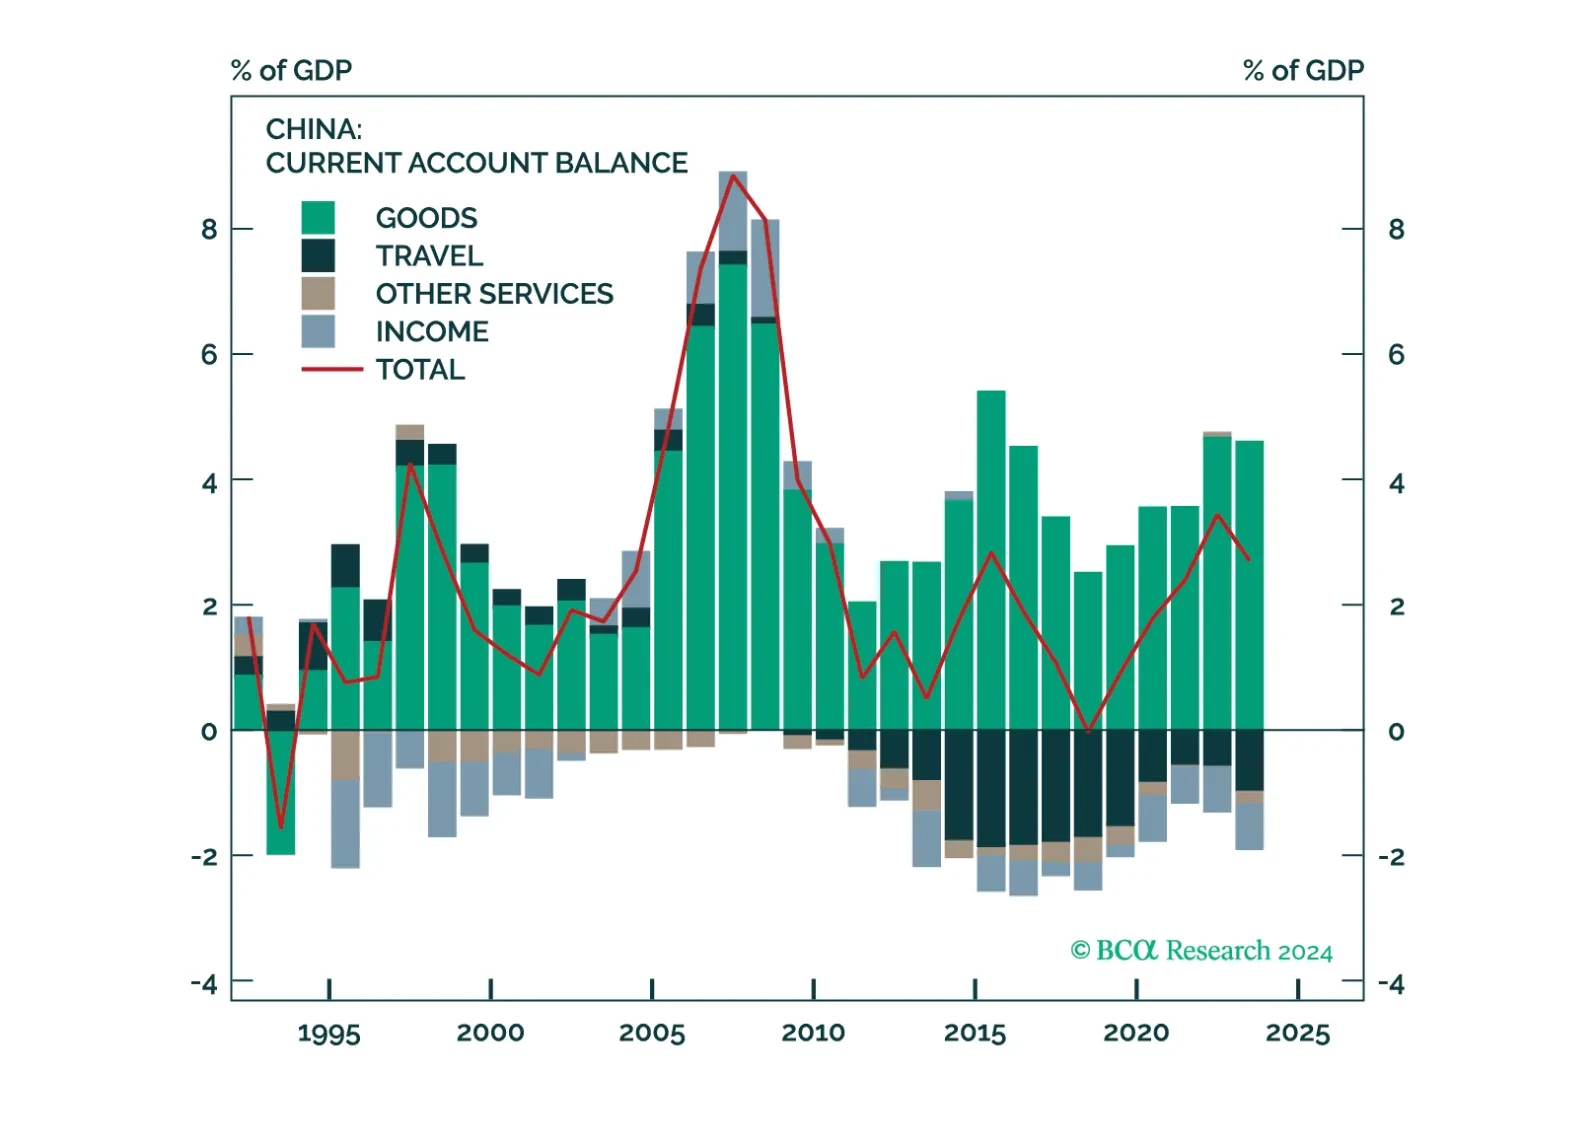
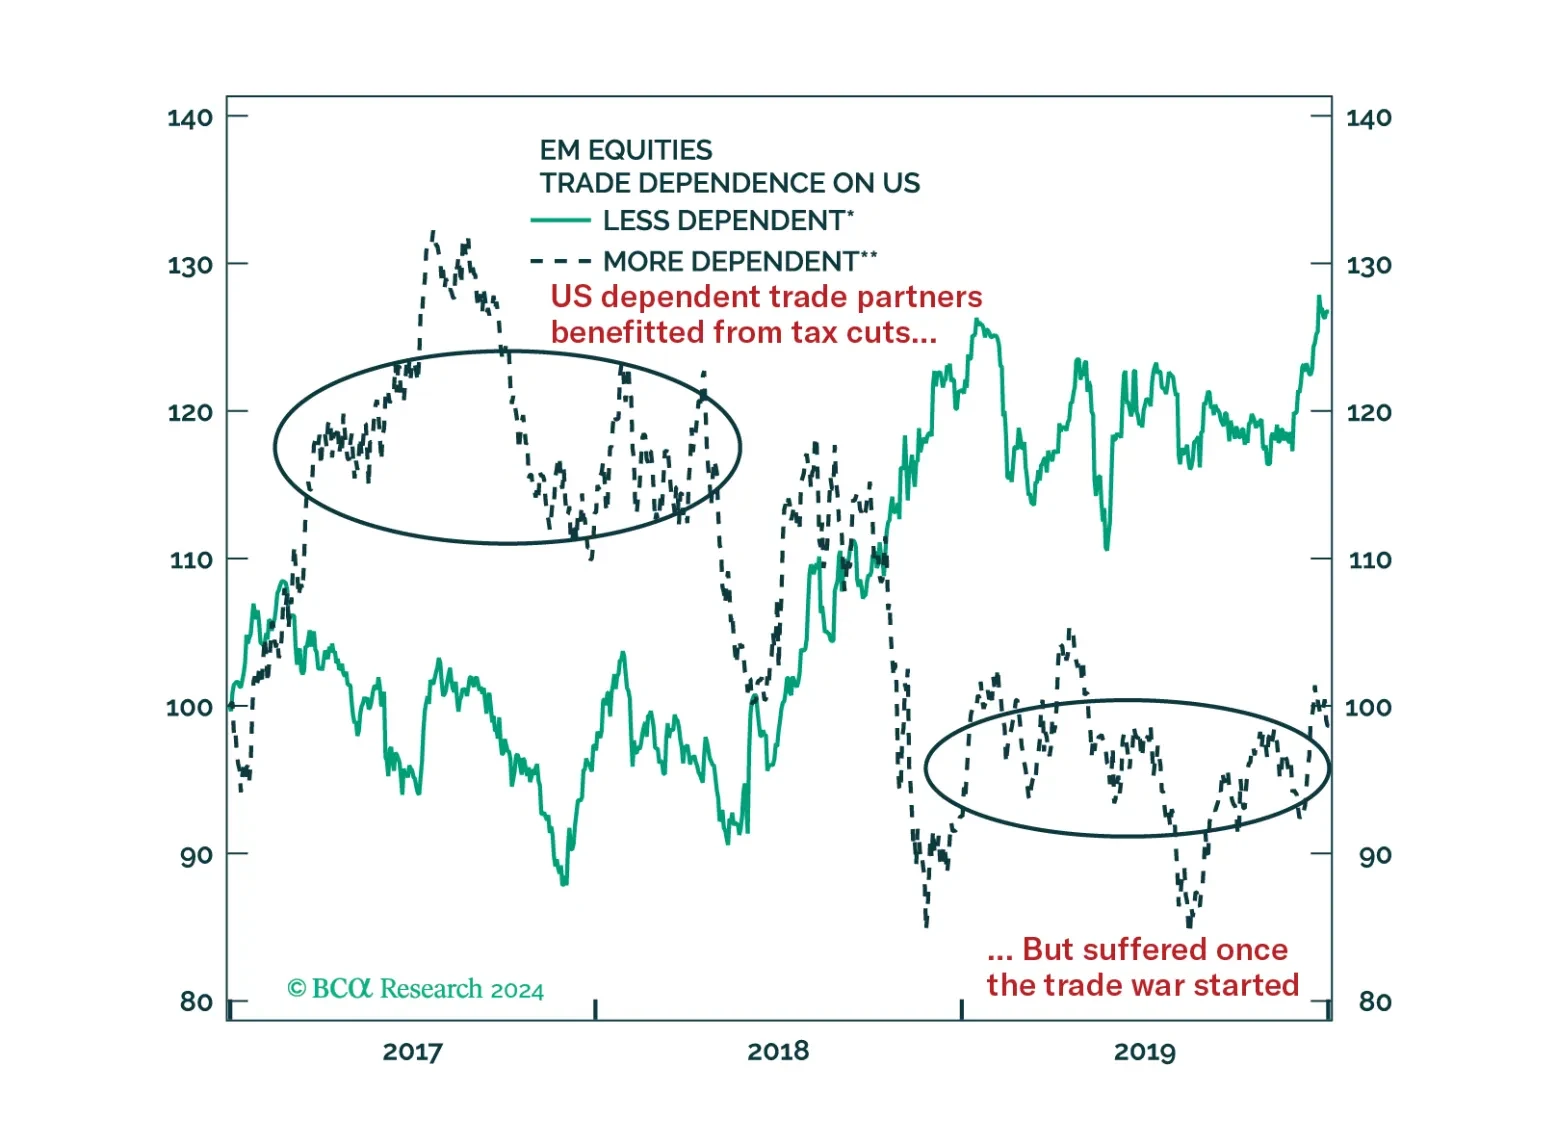
Waging trade wars in a global multipolar order is folly. The US trade war against China has been an utter disaster for Washington, DC. None of its goals have been accomplished, whereas Beijing is making significant inroads into new markets. Somewhat heretically, we suggest that American policymakers will eventually realize this reality and pivot towards a surprising new strategy.
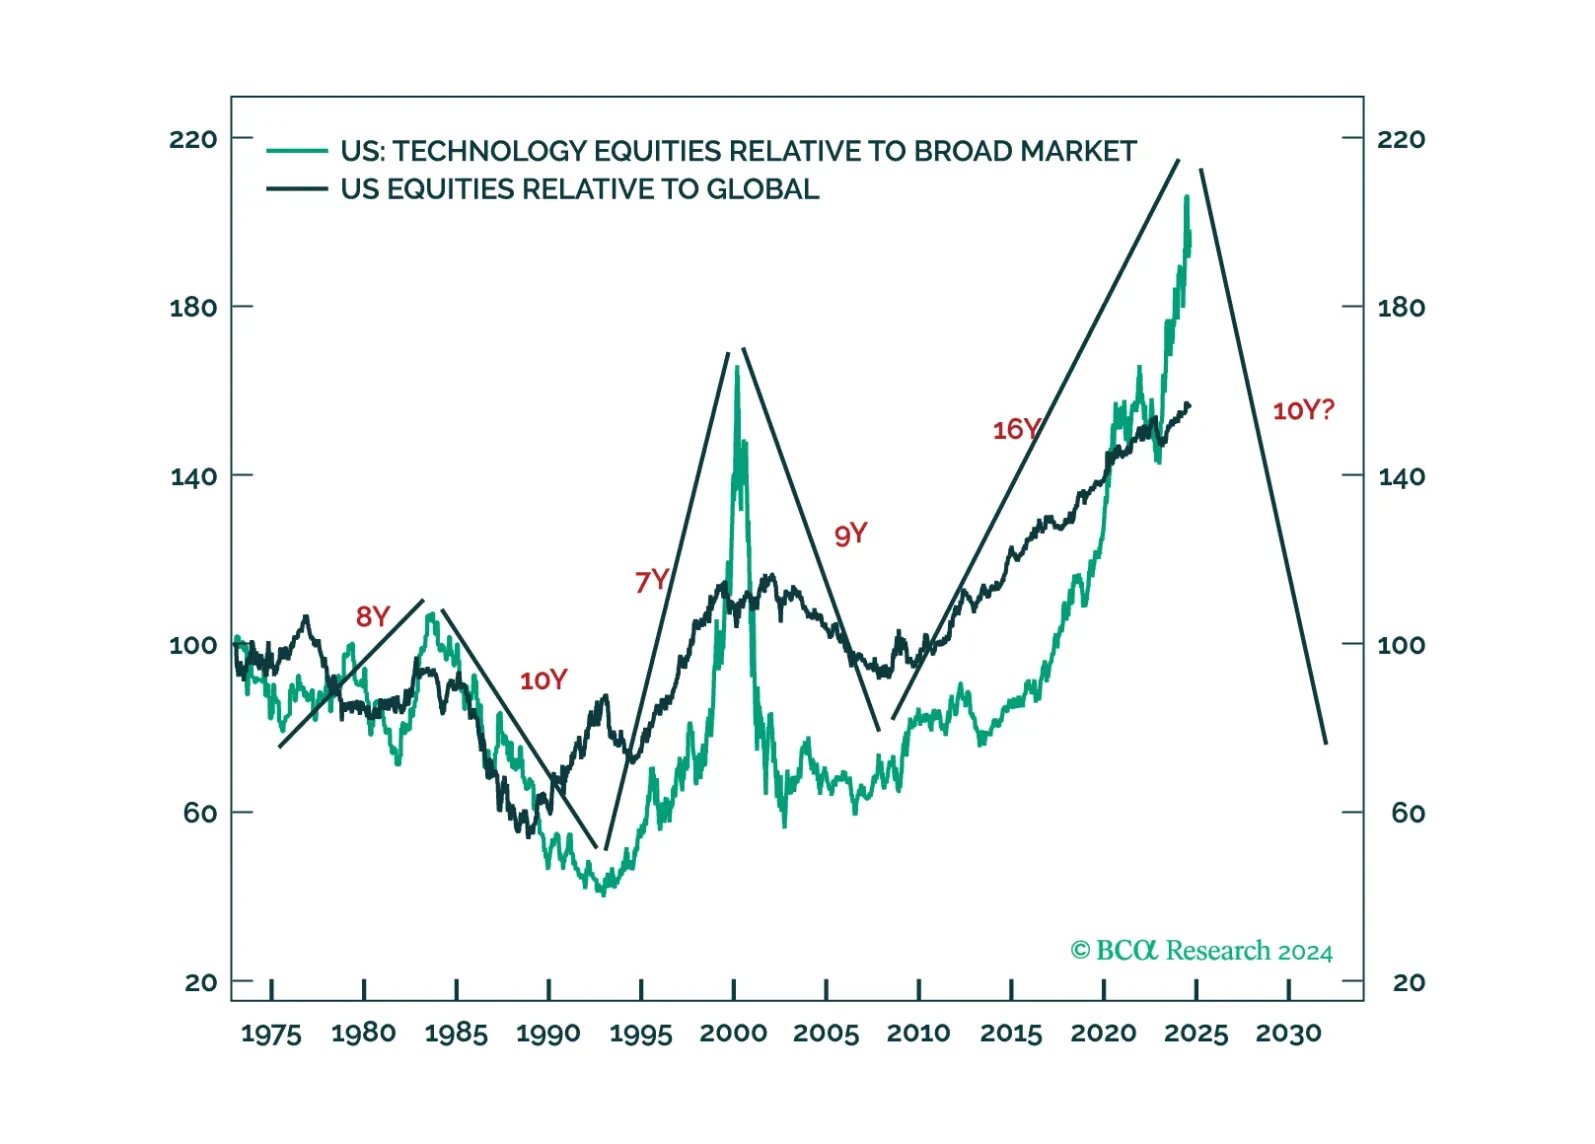
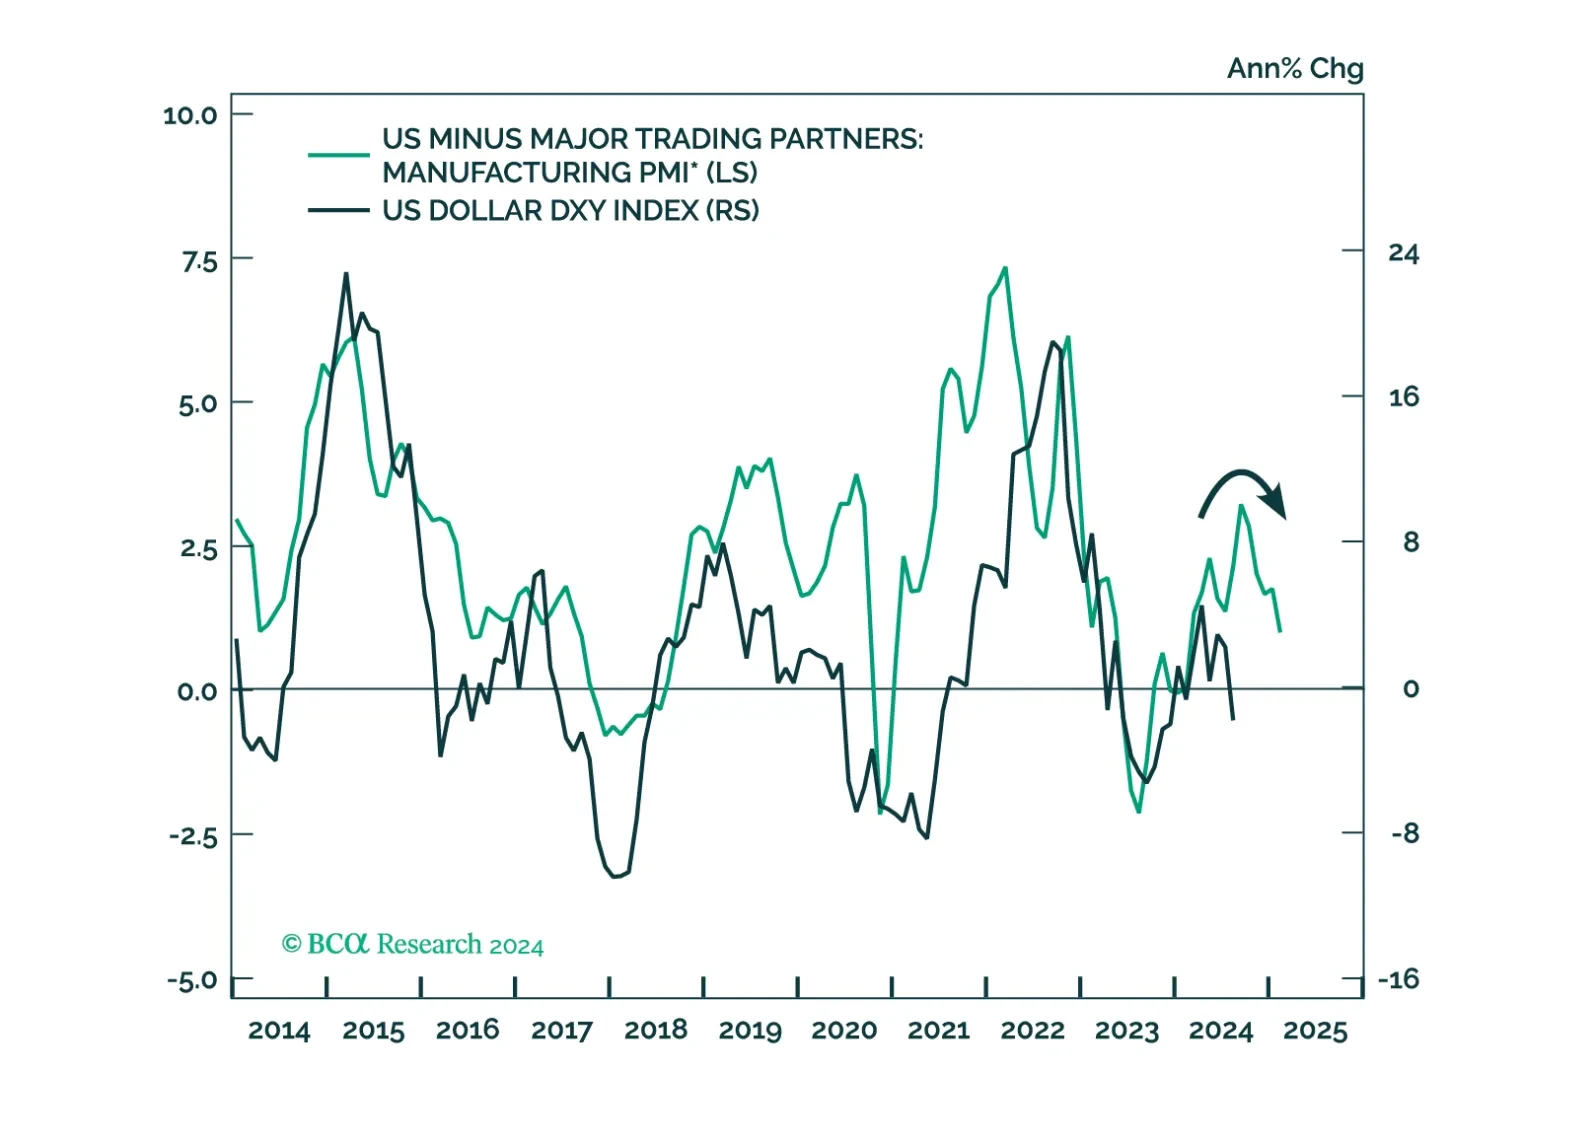
We remain concerned that the risk-reward for equities is limited above our end-of-the-year target of 5,500 for the S&P 500. There is seasonality to consider, as well as positioning and sentiment. As such, we are not necessarily bearish because a recession is certain. But, rather, that the upside to the AI mania is uncertain. Long term? The real bubble may be in America, broadly speaking. As such, more downside to USD could be ahead.