Saltar al contenido principal

GeoMacro

A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
Explore GeoMacro
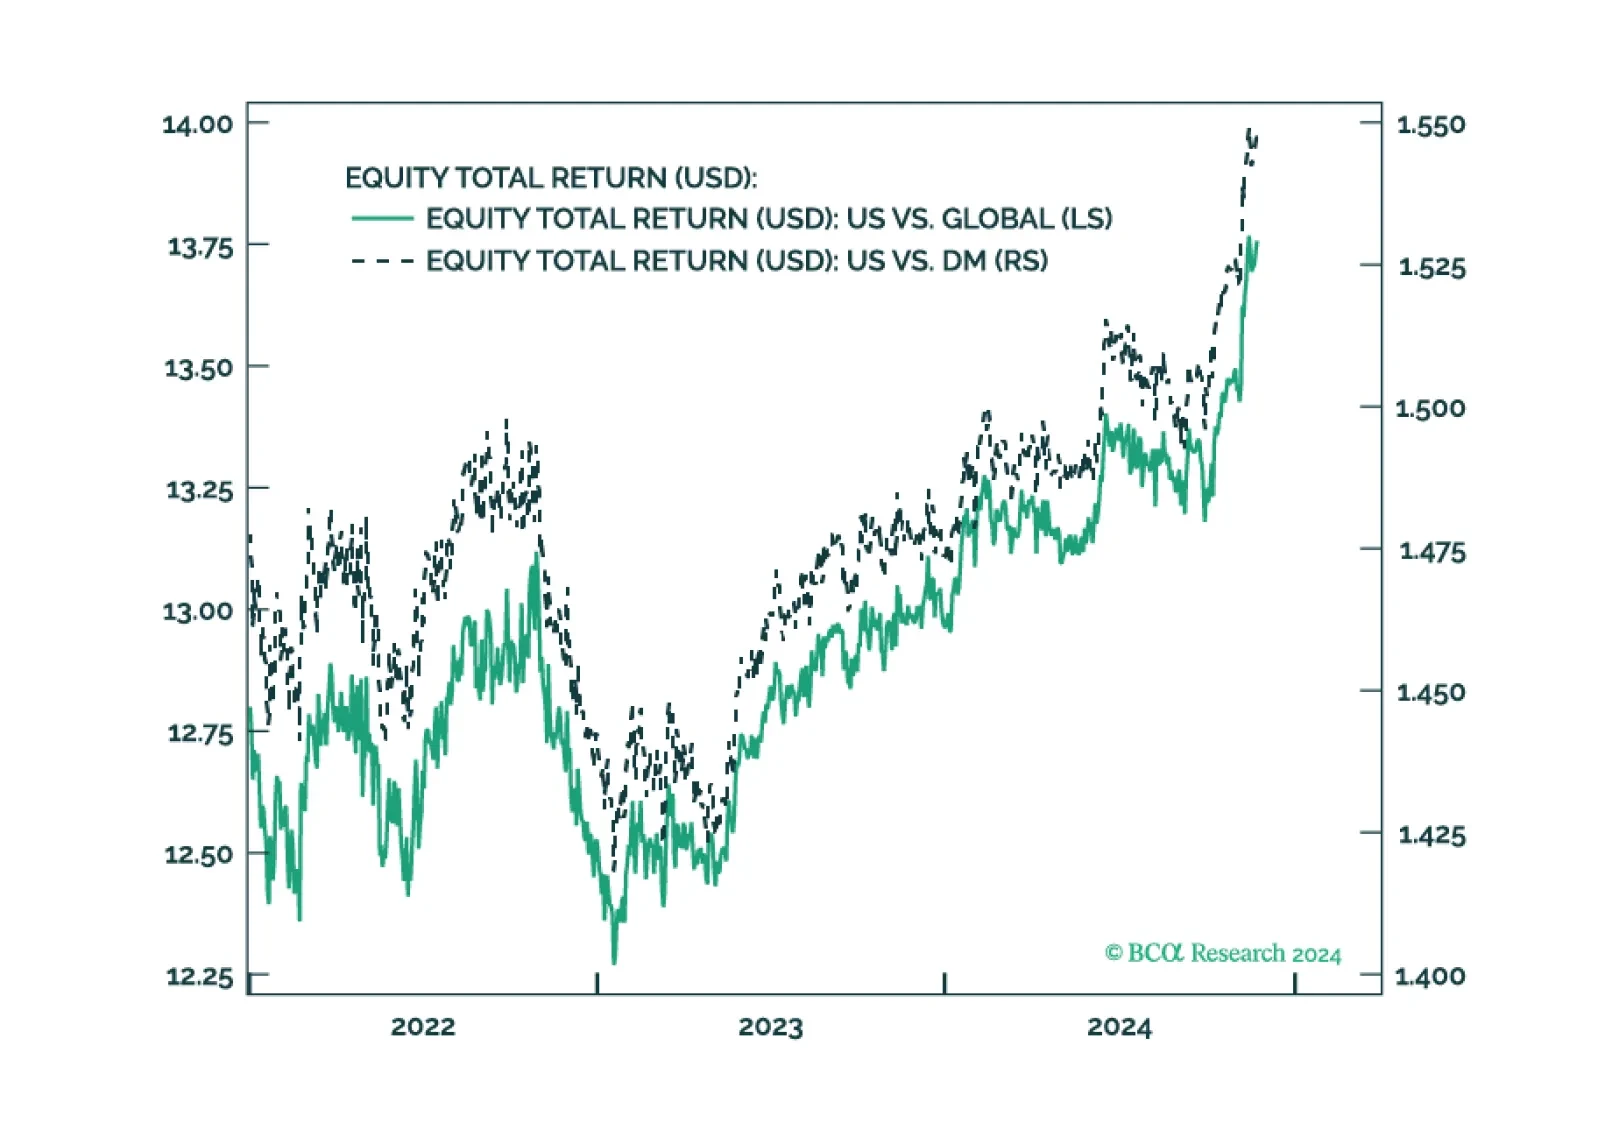
We were far too bearish on the US economy in 2024 – but the global economy remained sluggish and we got the critical geopolitical calls right. We predicted the Republican sweep in the US and the outbreak of direct military hostilities between Israel and Iran. We anticipated the escalation in Ukraine and Russia-NATO tensions that is taking place as we go to press. We stayed overweight US assets relative to global. We did not get blindsided by any of the elections in this “year of elections” – we traded several of them successfully. However, we disfavored cyclical sectors. We fought momentum stocks and lost. Many other trades turned sour. Equity volatility picked up substantially in 2024 as expected, but our attempts to take advantage of this shift fell flat.
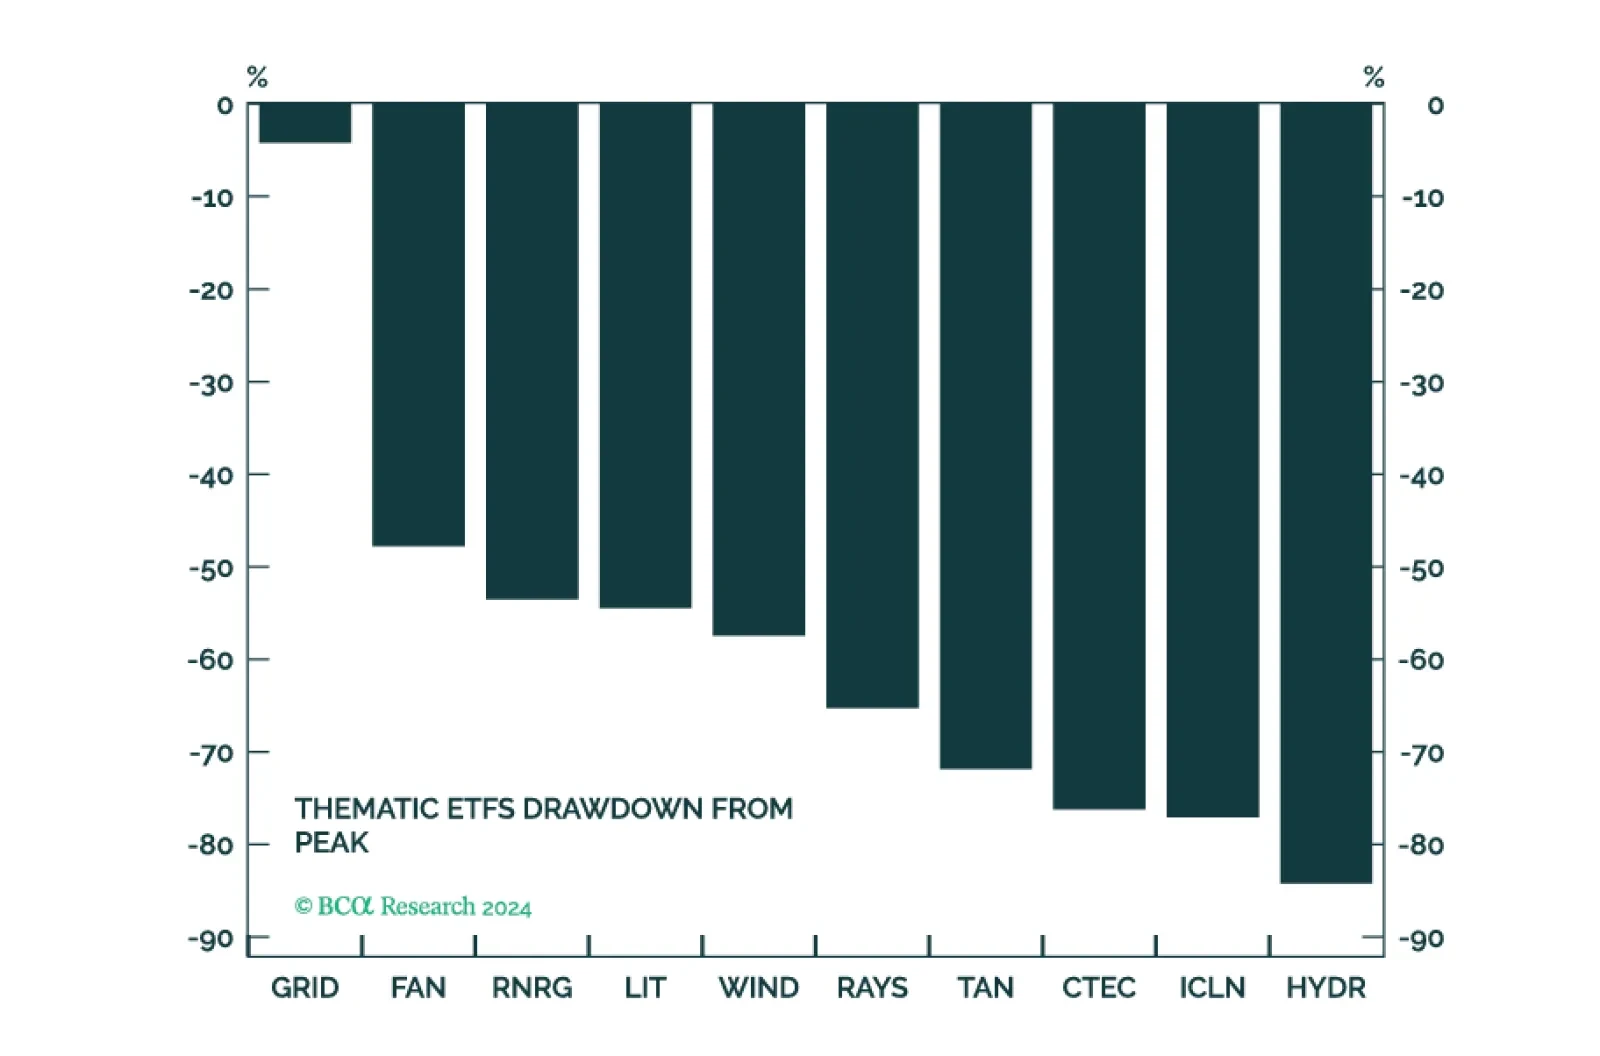
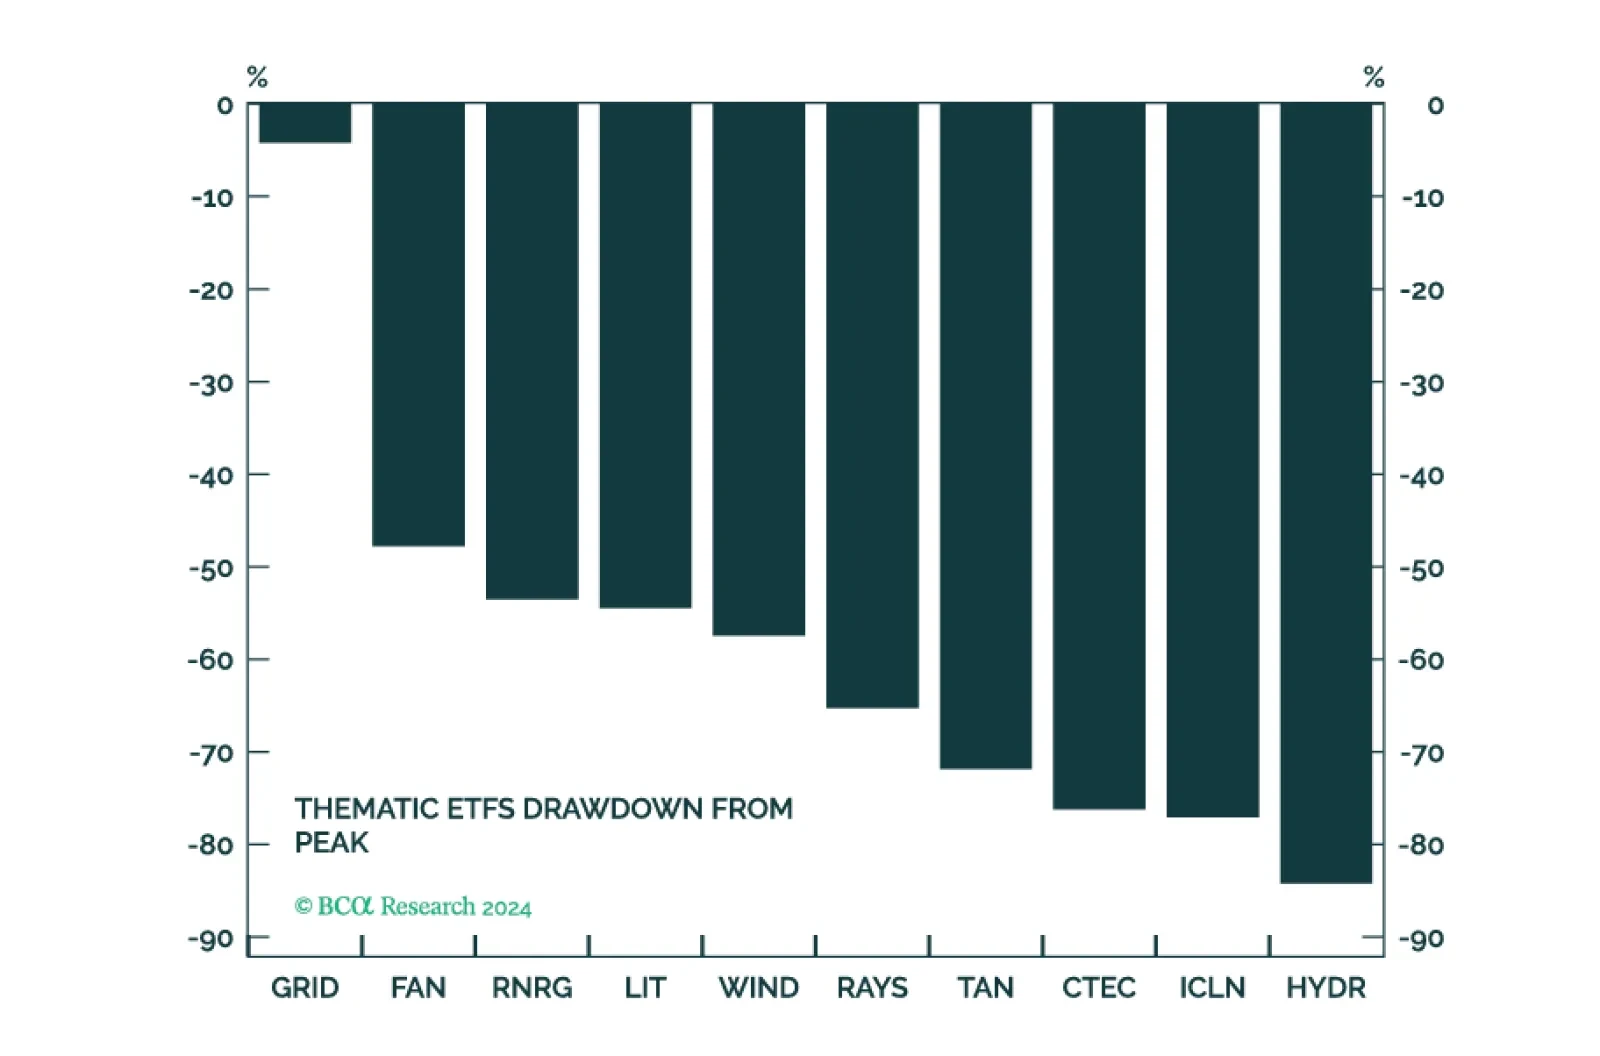
Informe especial While some of these headwinds facing G&C are abating or at least are now priced in, it is hard to see the industry rebounding over the short investment horizon unless monetary conditions ease. However, long-term trends supporting a transition to renewable energy are intact – strong demand for energy from Big Tech, falling prices of renewable energy generation, and overall infrastructure buildout. Green energy is here to stay, and we overweight G&C on the strategic investment horizon.
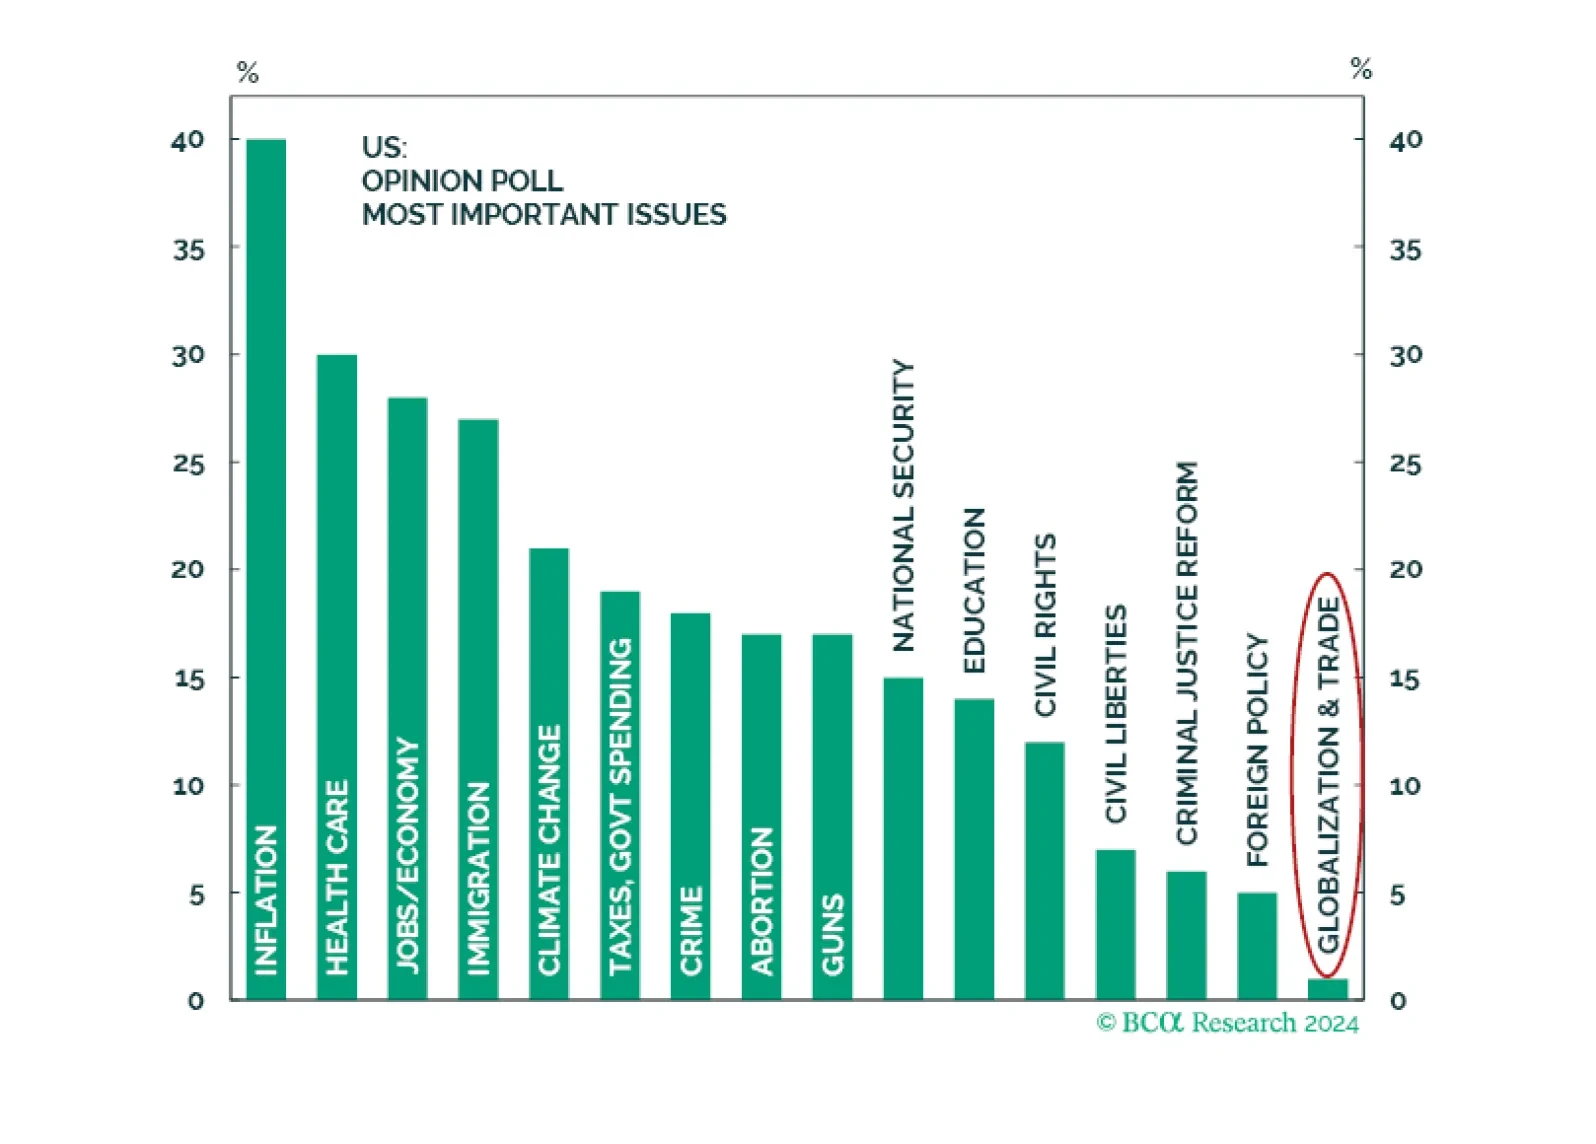
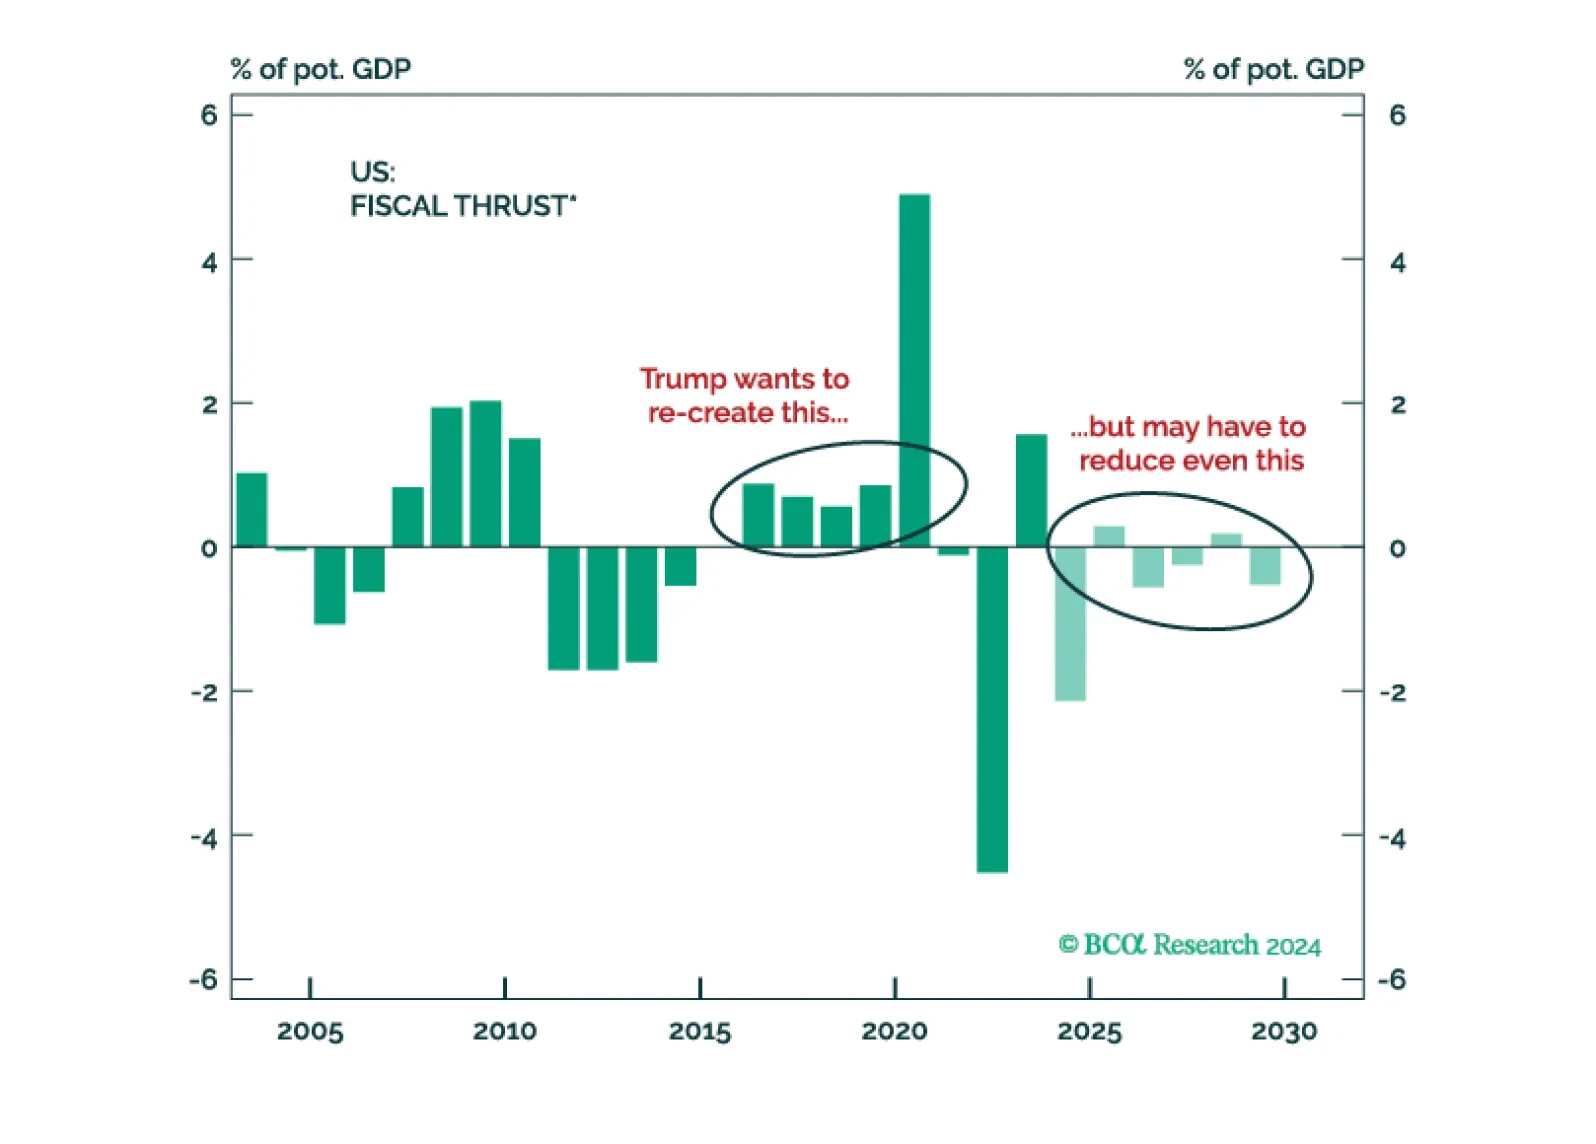
Informe especial Investors are overstating the positive fiscal impact of the Trump presidency. The bond market will have something to say about the scope for further deficit expansion via tax cuts. As such, the trade after the trade of the Trump 2.0 administration may involve less growth out of the US, not more. In the interim, however, investors should continue to expect higher yields and increased equity volatility. There are plenty of risks ahead, including geopolitics, trade, and uncertainty surrounding fiscal policy. Ultimately, 2024 is not 2016 — a seemingly obvious point, but one with market relevance. In 2016, voters gave Trump a strong mandate for nominal GDP growth. It is not clear if this is the case today. Inflation is the most important issue, least relevant is trade and globalization. As such, Trump’s renewed mandate is for supply side reforms, not more populism and protectionism.
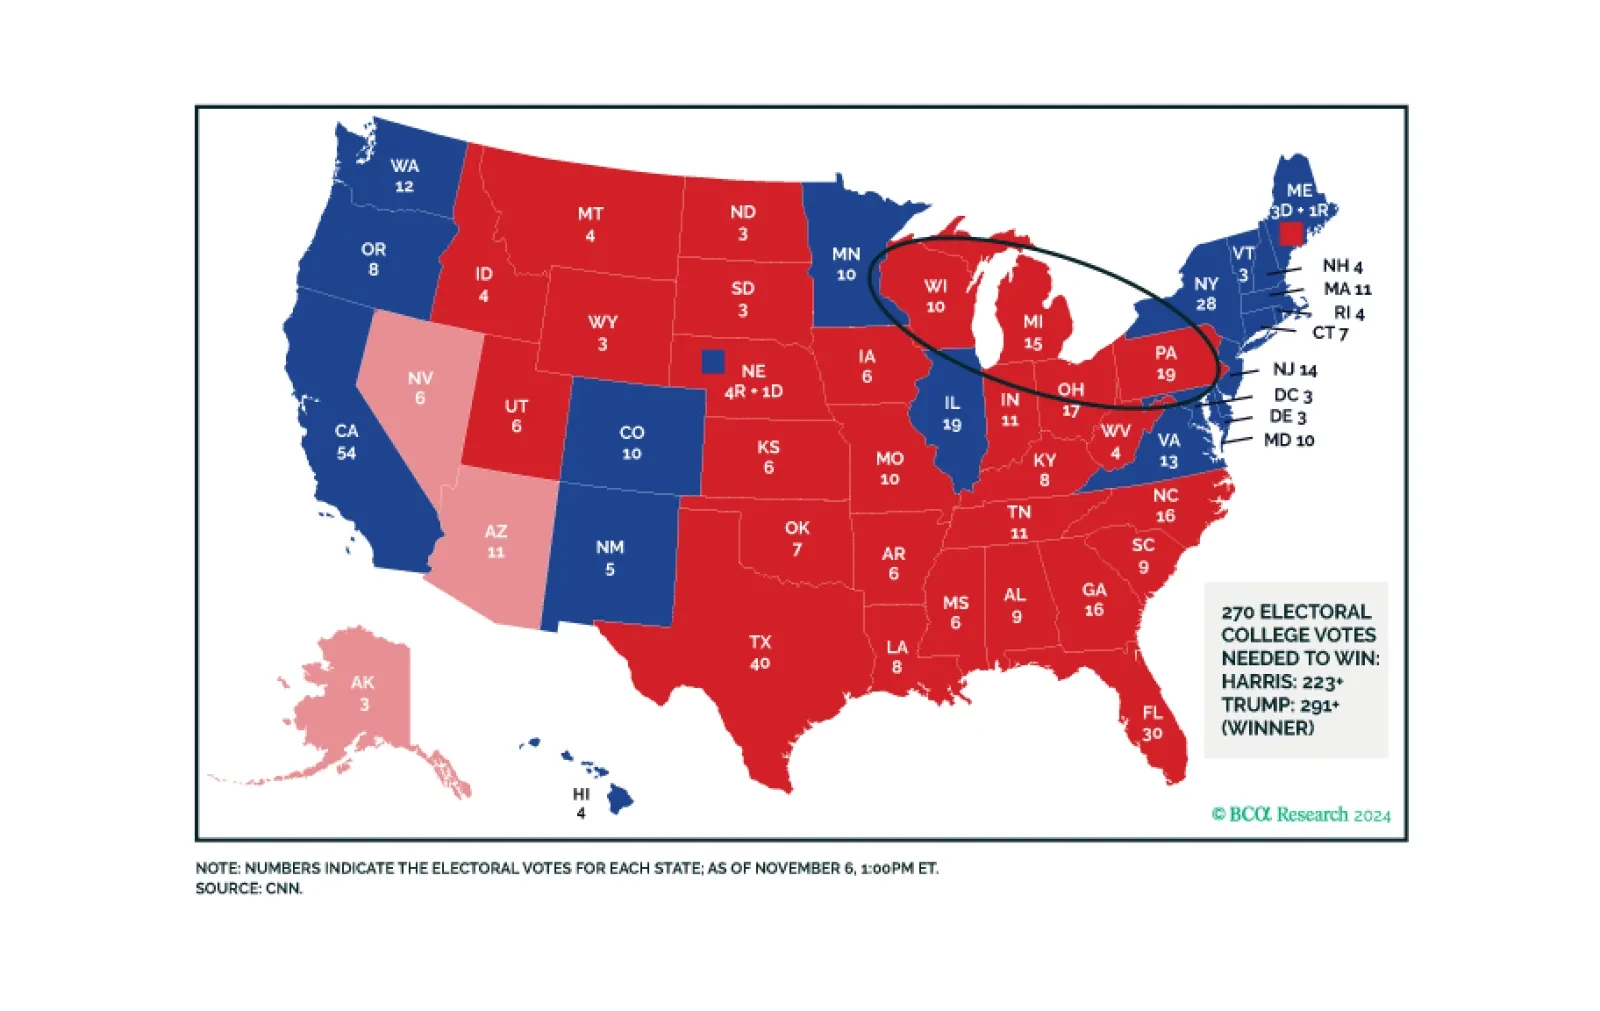
The month of November has brought us S&P 6,000! President Trump has won a “Red Sweep” (as we expected all year) and has ushered in a regime change in America. For now, we are open to chasing momentum. However, the biggest risk to the market are bond yields, which should rise as investors start to price President Trump’s policies and their impact on deficits.
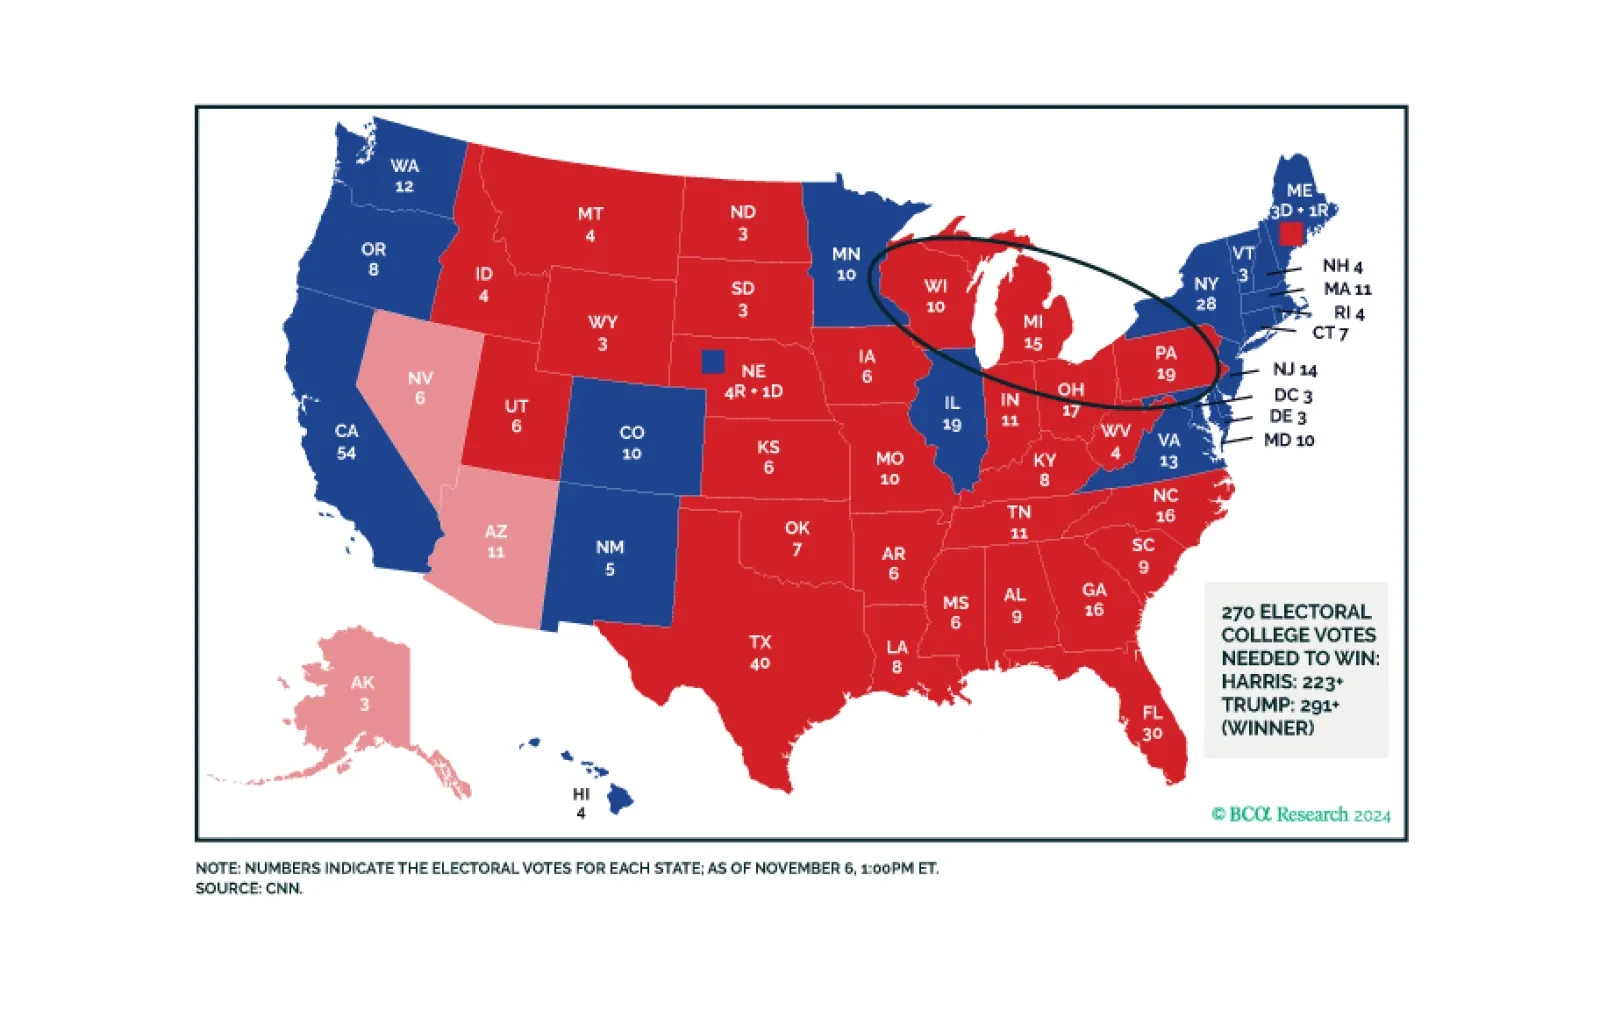
Informe especial Trump’s resounding victory brings a popular mandate that ensures deregulation and higher trade tariffs. Higher budget deficit and immigration reform are also in the cards as the Republicans look like they may squeak a thin margin in the House of Representatives. Foreign policy will become more unilateral, with US assets outperforming initially.
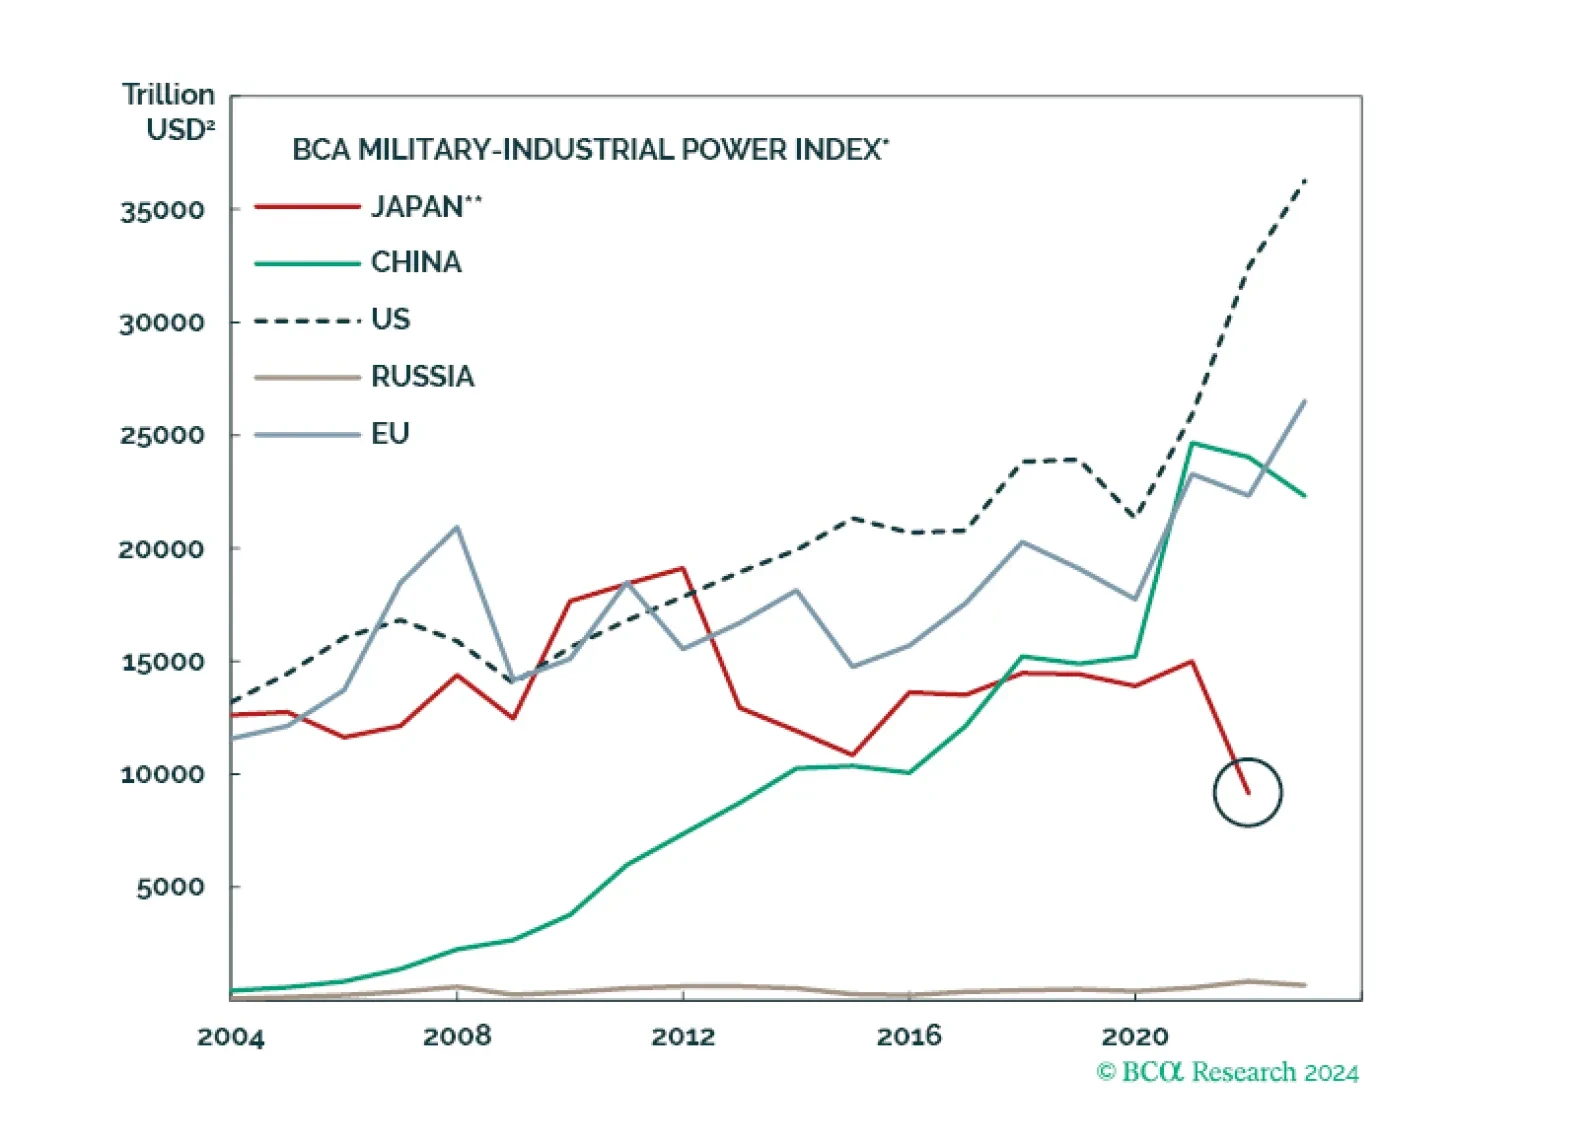
Over the next few months, Japan’s new government will ease fiscal policy, which will improve domestic demand on the margin. Monetary policy may tighten further in the short run but not too much over the long run. The geopolitical setting drives Japan into accommodative economic policy.
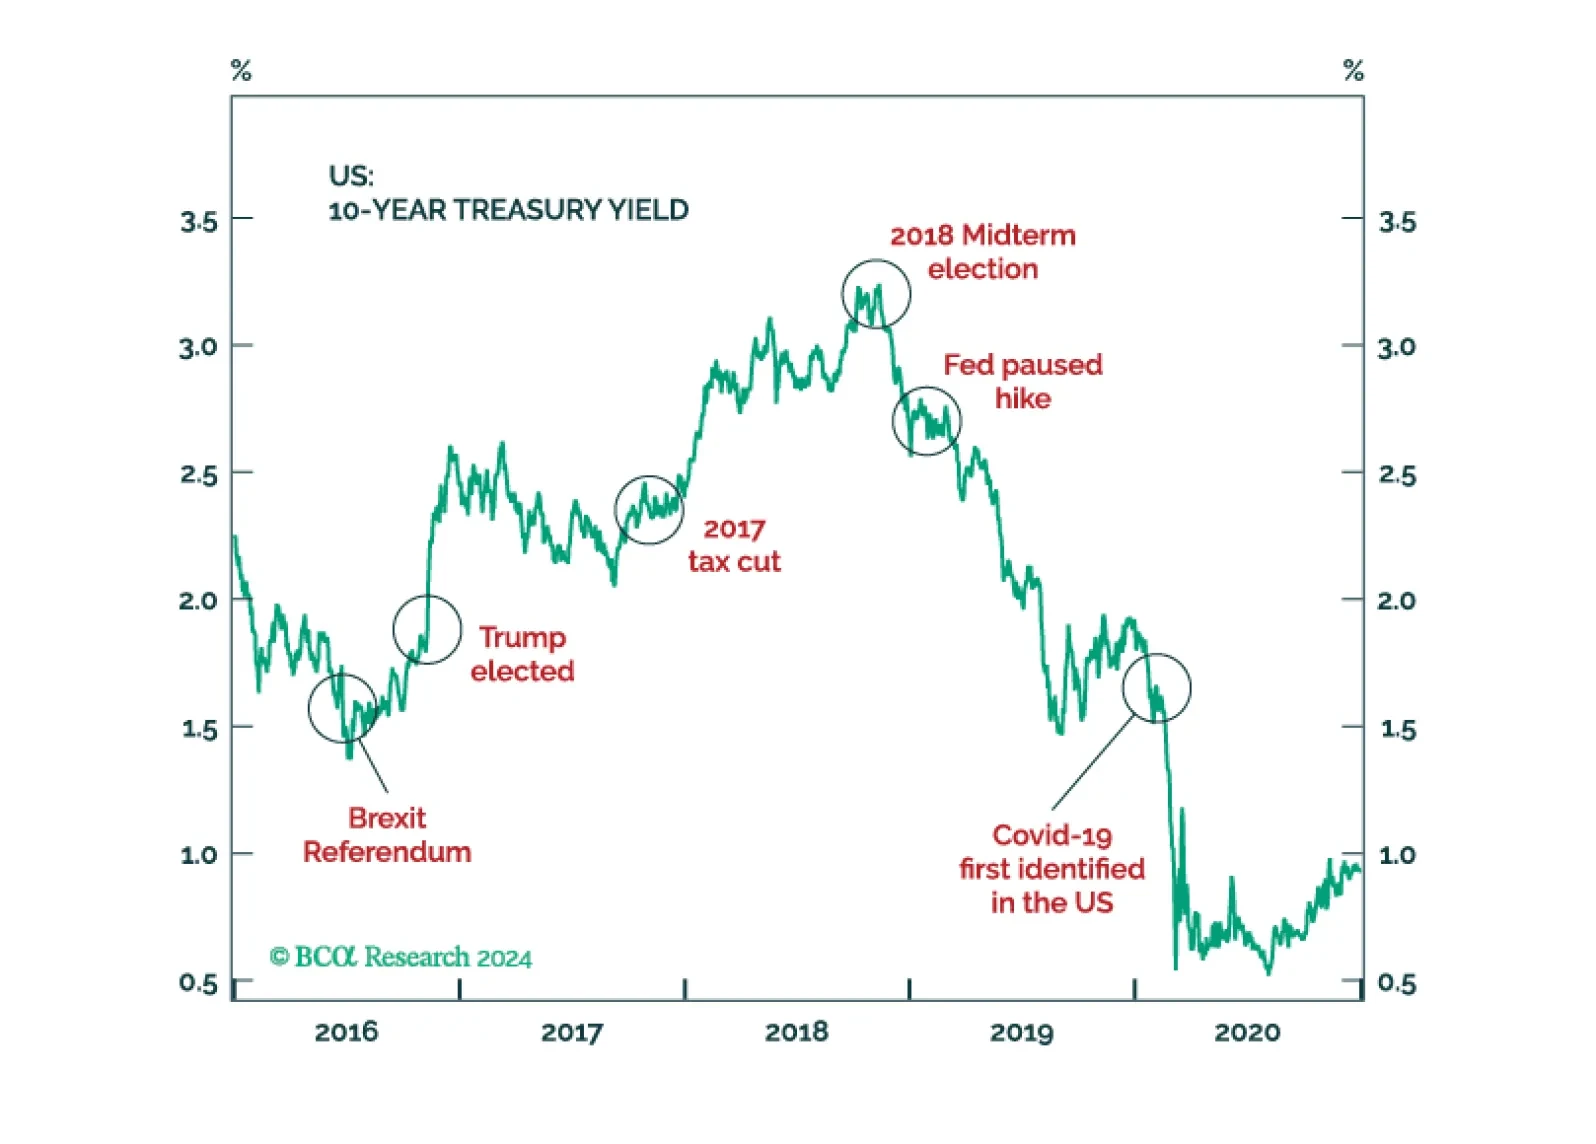
The Election Day is finally upon us. No, there is no final “silver bullet” forecast contained in this email. Just our long-term forecast of how the election will, no matter who wins, impact the markets.
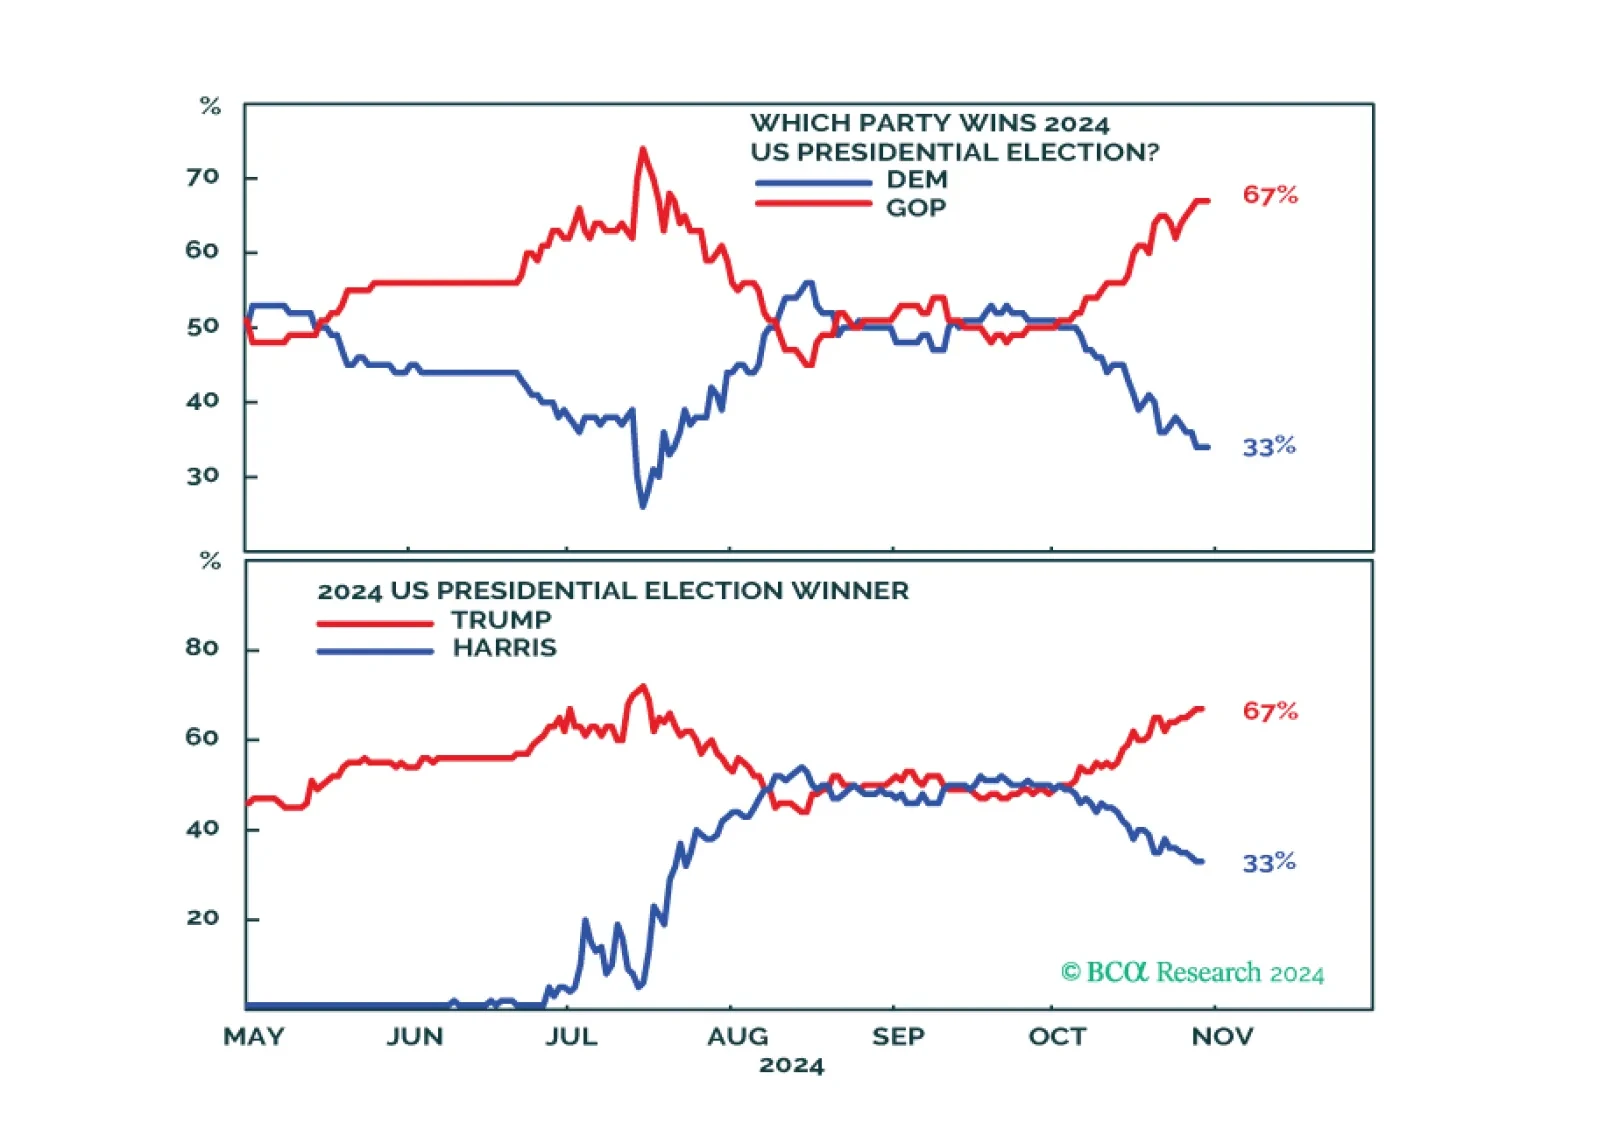
Trump may be favored, but Harris is now underrated. The Senate is highly likely to go Republican – Harris would be gridlocked if she pulled off a victory. If Trump wins it will be a full sweep. Expect volatility in the short term.