FICC
Find out more
This Strategy Insight discusses the bond market and currency implications of the Fed’s “hawkish pause”.
This Strategy Insight discusses the bond market and currency implications of the Fed’s “hawkish pause”.
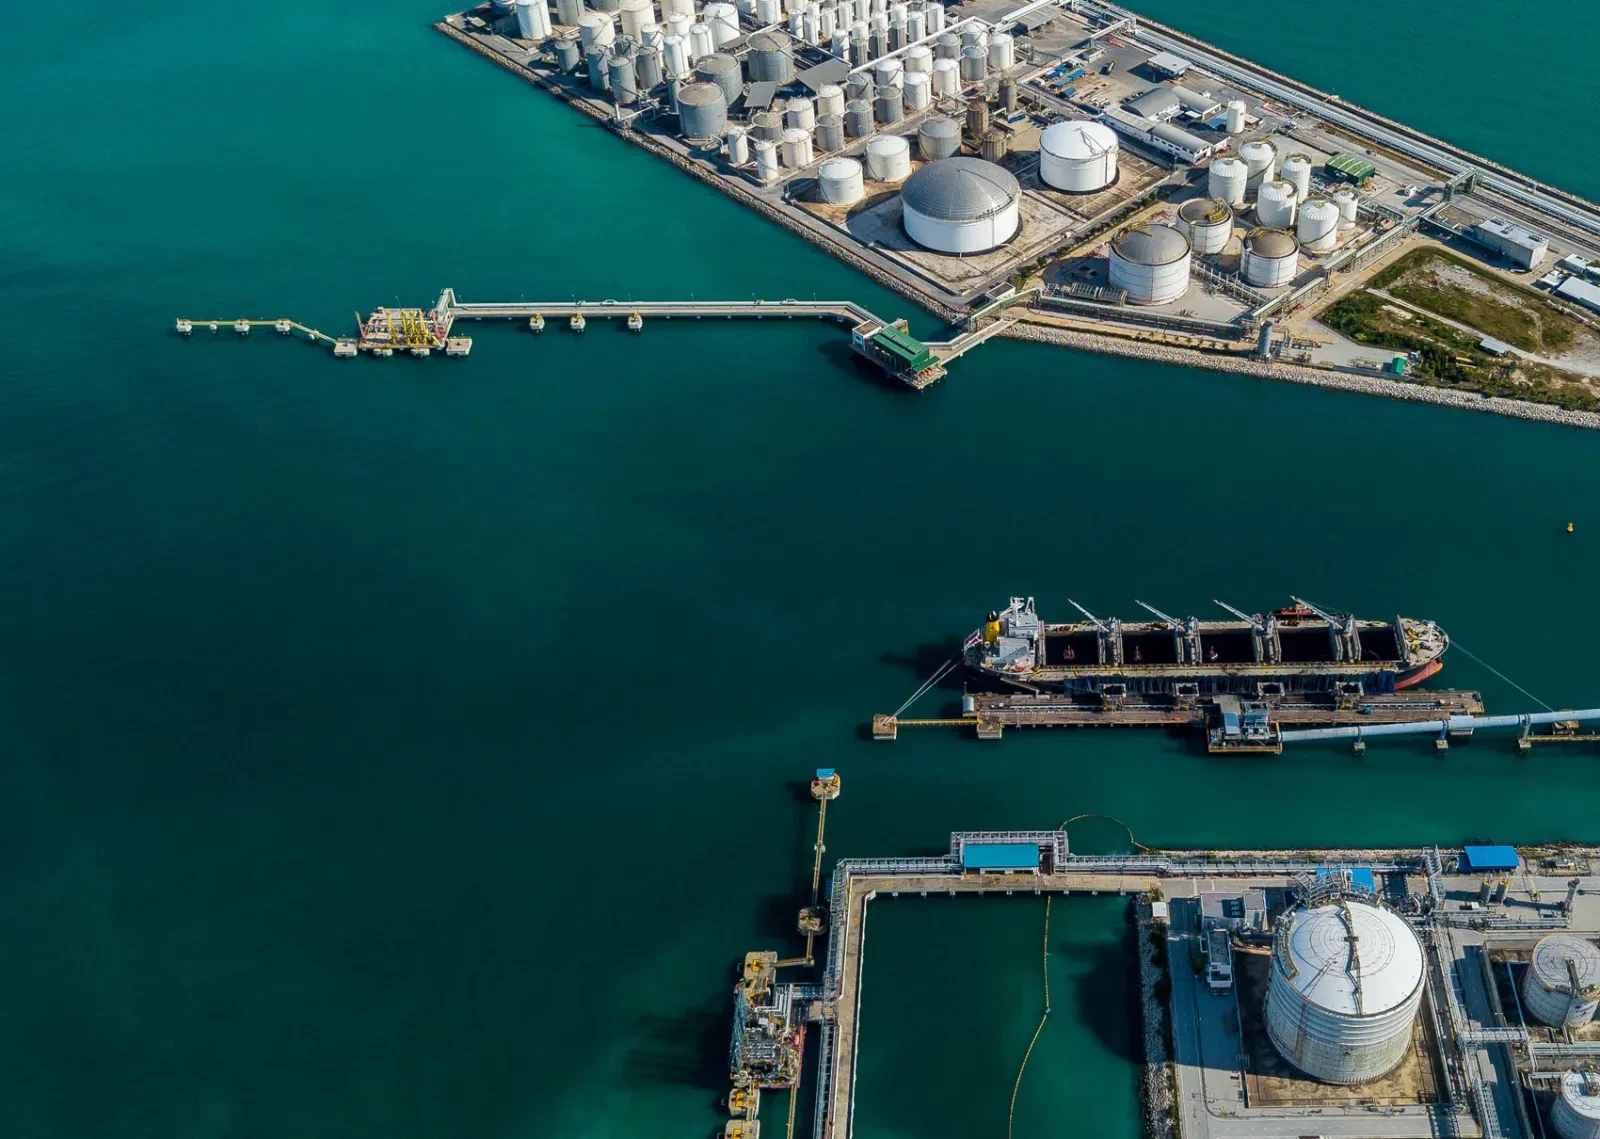
Oil and metals reacted positively to the PBOC's 10 bp cut in the seven-day reverse repo rate, which will be part of the larger monetary and fiscal support needed to revive the economy. While deposit rates at state-owned banks have been reduced, additional rate cuts are expected. On the fiscal side, tax breaks and credit support are planned for the domestic EV market, while authorities are reportedly mulling further assistance for the property market.
In this Insight, we answer a few crucial questions: Do the BoC and RBA decisions have any impact on what we can expect from other major central banks next week? Are there any profitable trades that can be put on, given the recent hawkish shift by these two central banks? How should global bond investors be positioned in a fixed income portfolio?
In this Insight, we answer a few crucial questions: Do the BoC and RBA decisions have any impact on what we can expect from other major central banks next week? Are there any profitable trades that can be put on, given the recent hawkish shift by these two central banks? How should global bond investors be positioned in a fixed income portfolio?
Slowing manufacturing PMI indices globally indicate the slowdown in economic activity will persist. Manufacturing demand for commodities will also soften, weighing on industrial commodity prices. Geopolitical tensions and the race to the green energy transition will upend enmeshed global supply chains, which will also impact manufacturing activity. It is possible that stimulus in China will arrest the decline in the state’s manufacturing activity, which will have positive spillover effects to its key trading partners.
Following this weekend’s OPEC 2.0 meeting, KSA announced a 1mm b/d crude output cut, slated for this July or August, as it attempts to support weak oil prices. The new output quotas, reduced to reflect members’ weak crude oil production will continue until end-2024. UAE’s quota was the only one raised in acknowledgement of its higher production capacity. On the back of this announcement, we continue to expect brent prices will average $90/bbl this year.