 FICC
Find out more
In this week’s report, we assess the key reasons why the dollar has risen, and if that is set to continue.
The CCP’s fiscal measures and property-market support are important steps to deal with China’s liquidity trap. The fiscal measures are the first such direct aid to households and small firms seen since 2020, which included tax relief and waived social security contributions, according to the IMF. The size of the programs has not been disclosed. If they are successful, global commodity demand will get a boost at the margin, particularly oil and base metals. We remain long equity ETFs to retain exposure to energy and metal producers and refiners, and long the COMT ETF for direct commodity exposure.
US bond investment takeaways from this week’s PCE and employment releases.
In this report, we explore what a new BRICS+ union means for the dollar over the next 6-to-9 months.
The Fed and ECB talked a good game as they redoubled their commitments to returning core inflation to 2% p.a. at Jackson Hole. However, their outmoded inflation-fighting playbooks do not address supply tightness in commodity and energy markets, which keeps inflation risk elevated. The proposed expansion of the BRICS states seeks to capitalize on these trends, and supports efforts to weaken the centrality of the USD in global trade. We remain long commodity exposure via ETFs to retain exposure to energy and metals producers and refiners.
We comment on Jay Powell’s Jackson Hole speech and recommend shifting to a barbelled allocation along the Treasury curve.
In this report, we review our FX trade recommendations with suggestions on how to position for the next few months.
In this report, we assess the best opportunities in inflation-linked bonds in the major developed economies, based on trends in growth, inflation and the stance of monetary policies in each country. We conclude that the environment is turning more challenging for European inflation-linked bond performance versus nominal government bonds, while the opposite is true in Japan. In the US, US TIPS breakevens have likely peaked, particularly at the short end.
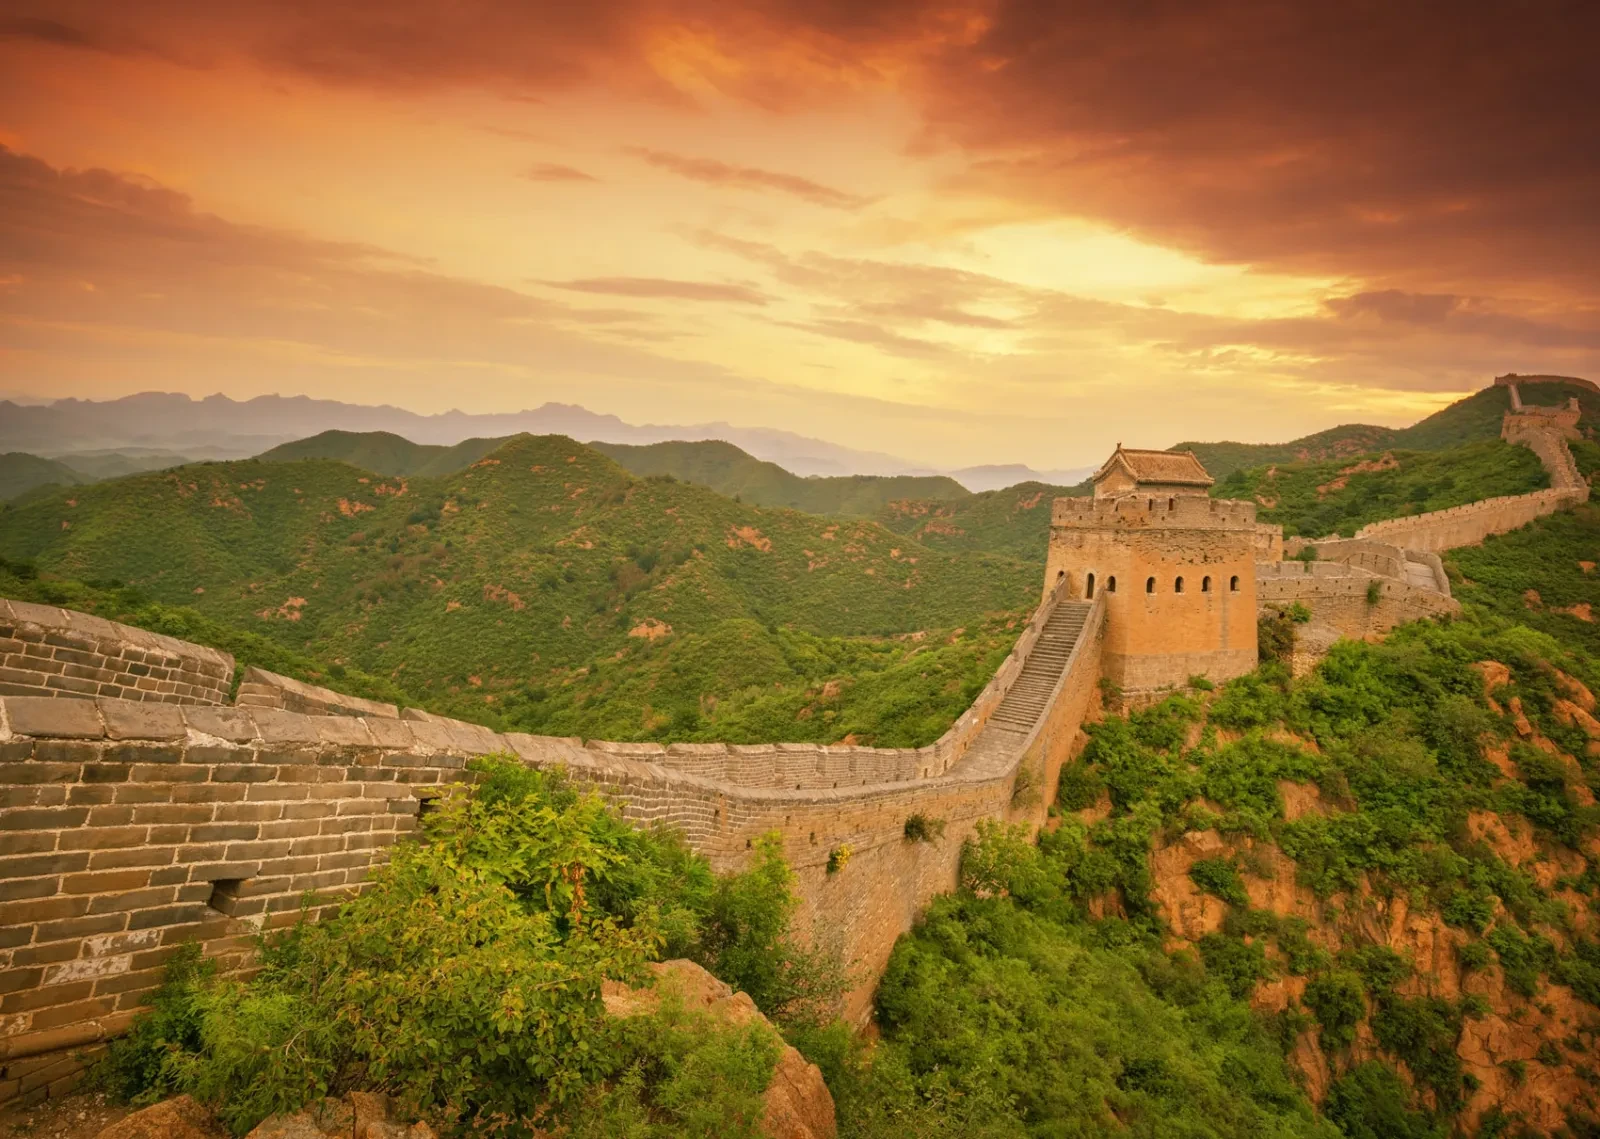
Most diagnoses of China’s liquidity trap miss the point that policies arising from these theories were developed for market-based economies with governments accountable to their electorates, not autocracies pursuing autarky. As the CCP widens and deepens mass-mobilization campaigns, the echo of the Cultural Revolution will grow louder and lead to further retrenchment by households and firms. China has space at the center for significant fiscal stimulus, which, if deployed, could break its liquidity trap and boost commodity demand.
While the bearish bond trade currently has a lot of momentum, we continue to think that Treasury yields are close to a cyclical peak and will be lower on a 6-12 month horizon.