 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
There are a number of warning signs that the global and EM equity bounce is unsustainable. The latest episode of housing recovery in China will prove temporary due to still-large imbalances. Overweight Indian stocks: the credit cycle in India is less vulnerable compared to other EMs. However, the outlook for Indian equities in absolute terms is not bullish.
The RMB has moderated considerably since mid-last year, which should lead to improved capacity utilization and easing PPI deflation. There is a strengthening case for an upswing in China's profit cycle, driven by falling interest rates and a weaker RMB, while investors are ill-prepared for any positive earnings surprises.
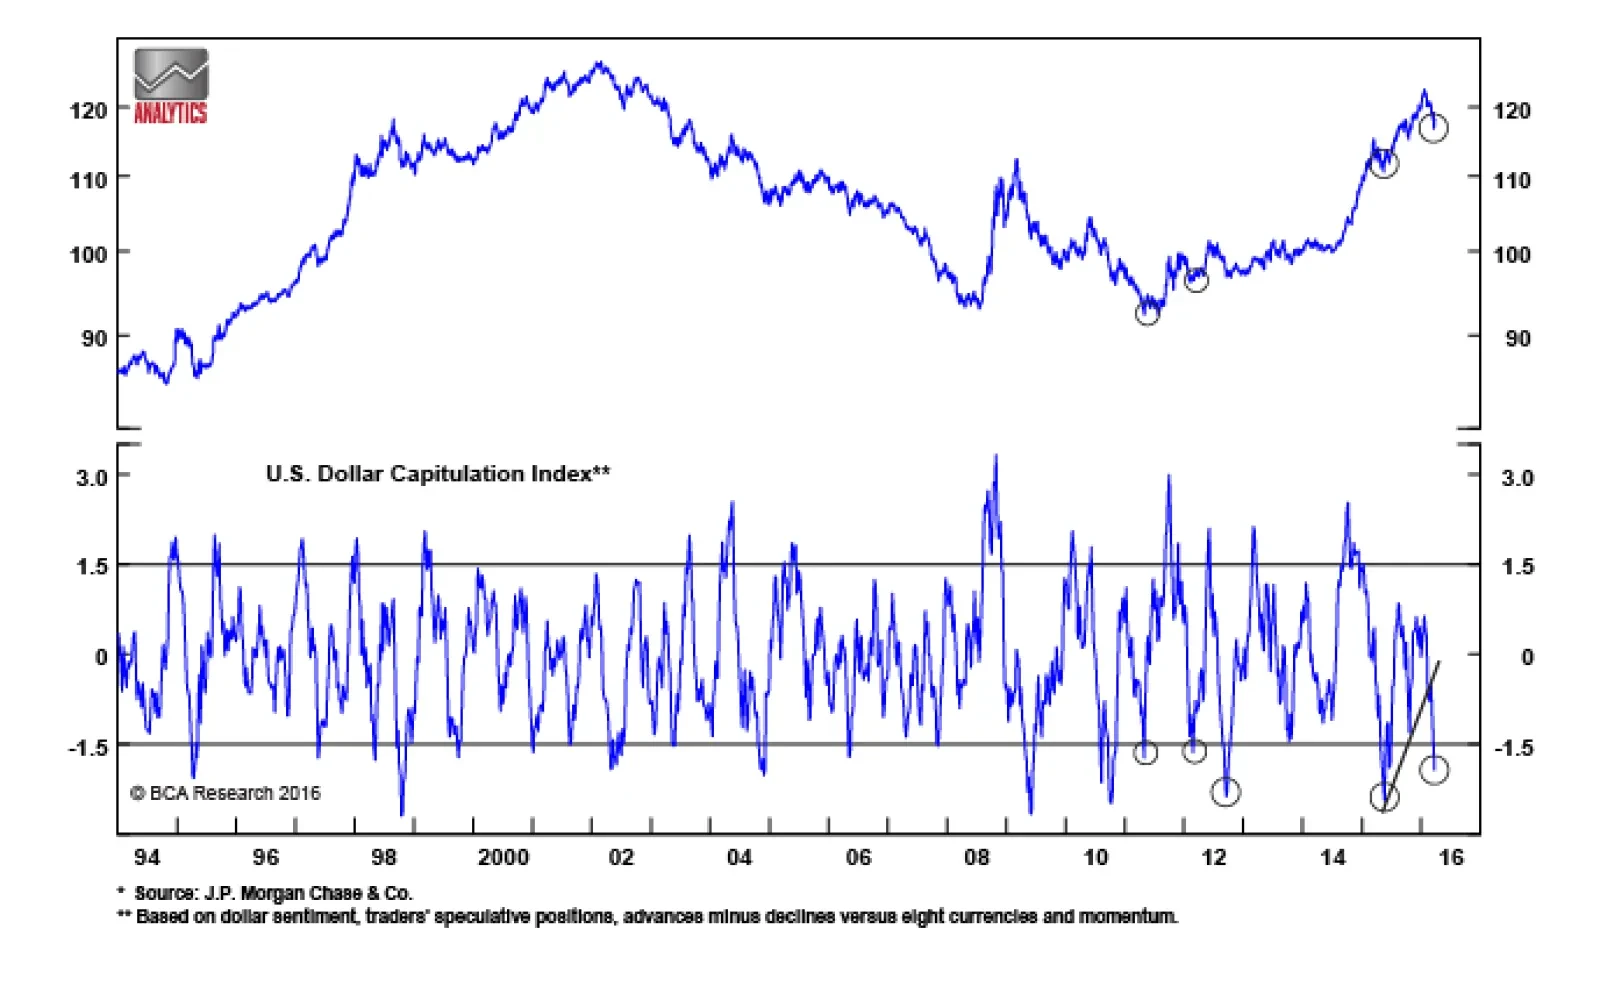
The rally in risk assets could persist. Dollar and oil moves are not yet exhausted. But valuations and poor earnings quality warrant a cautious approach.
For the month of March, the model outperformed both global and U.S. equities in U.S. dollar terms. For April, the model has further pared back its equity risk exposure, shifting the allocation into cash. While Europe remains the largest equity overweight, there was a modest recalibration to defensive markets such as the U.S. and Switzerland. The allocation to EM was also nudged up a bit, on momentum and valuation grounds. In the fixed-income space, the model is sticking with U.S., Italian and Spanish paper.
A global comparison suggests that China's capacity utilization does not appear particularly weak compared to other countries. The excess capacity problem is not unique to China, and therefore cannot be explained by China's investment-driven growth model. Chinese stocks have been unduly punished by the "overcapacity" stigma, which is unwarranted and will eventually correct.
There are no indicators that consistently lead share prices or can differentiate cyclical bull markets from short-term oversold rebounds. Investors who are right on the big-picture view will be rewarded, and vice versa. From a big-picture perspective, our bias remains that EM/China growth will not pick up sustainably, and that EM EPS will not recover materially in the next 12 months. Therefore, we recommend fading this rally.
The Fed's decision to scale back intended interest rate hikes reflects economic reality.