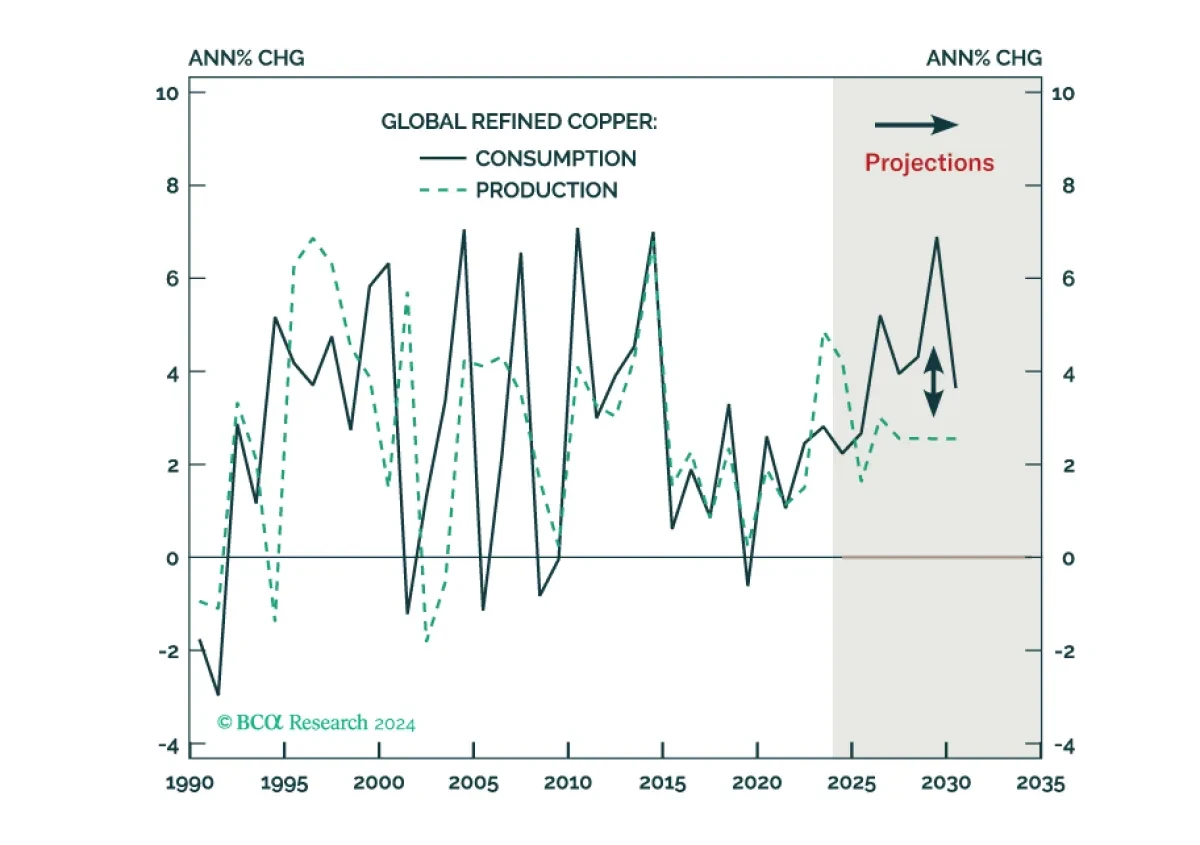
We expect a copper supply-demand deficit to emerge in 2026 and widen into the end of the decade. This will provide a tailwind for copper prices over a long-term horizon. That said, we believe a better opportunity to position for a structural uptrend in copper prices will arise over the coming six-to...
The force of the post-election momentum leads us to believe we could be stopped out of our defensive positioning before the week is out, but we still believe in our recession call. If we are eventually stopped out, we will seek a more opportune entry point to bet against risk assets once the electio...
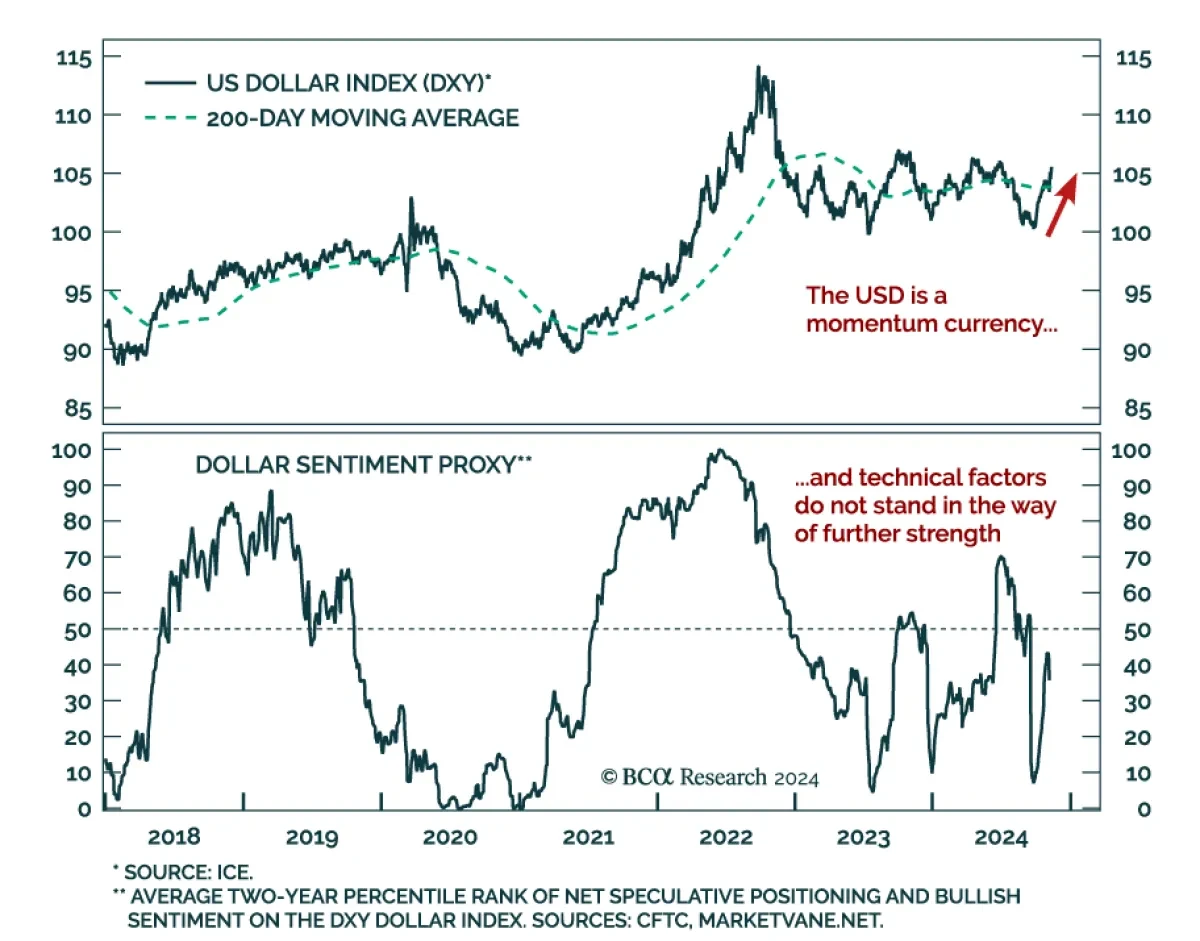
The US dollar steamrolled its peers since early October. After breaking out above its 200-day moving average, it is now fast approaching recent highs. Multiple factors drove this rally, among them are the stronger-than-expected US economic data, weaker data overseas, and Trump’s victory. In the very...
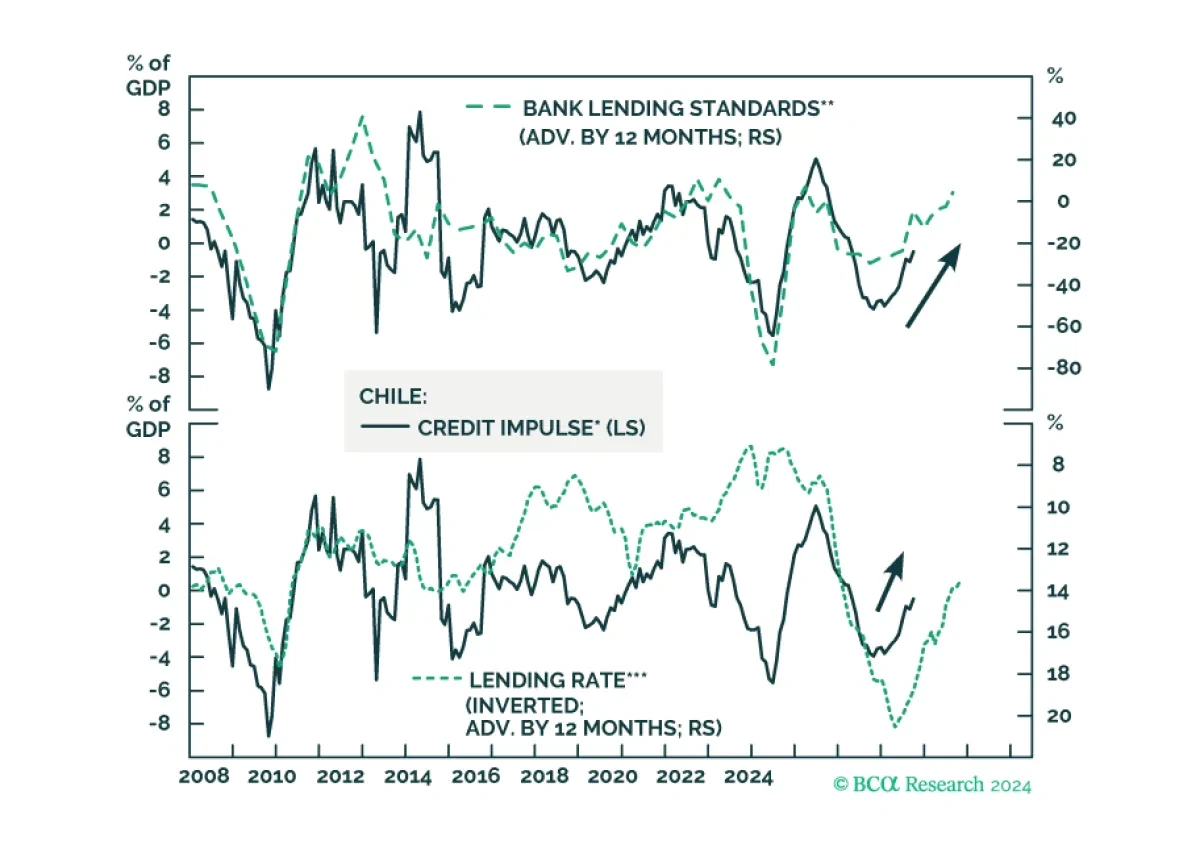
In absolute terms, Chilean markets and the currency will fall given a strengthening trend in the US dollar and weak global trade. However, Chile’s economy can withstand the global trade slump relatively well due to substantial monetary easing at home, which will help Chilean markets outperform EM pe...
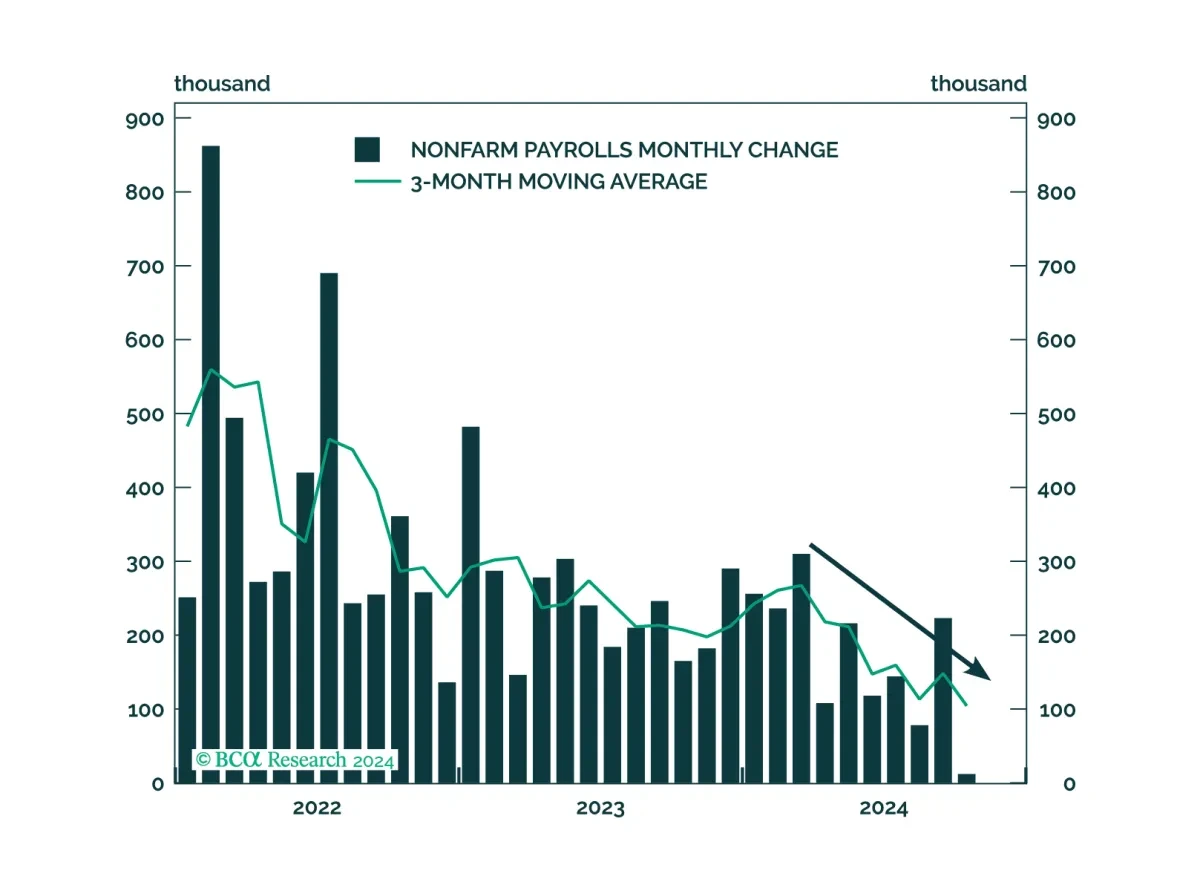
The prospect of a new trade war more than offsets the other pro-business parts of Trump’s agenda. With the labor market already weakening going into the election, we are raising our 12-month US recession probability from 65% to 75%....
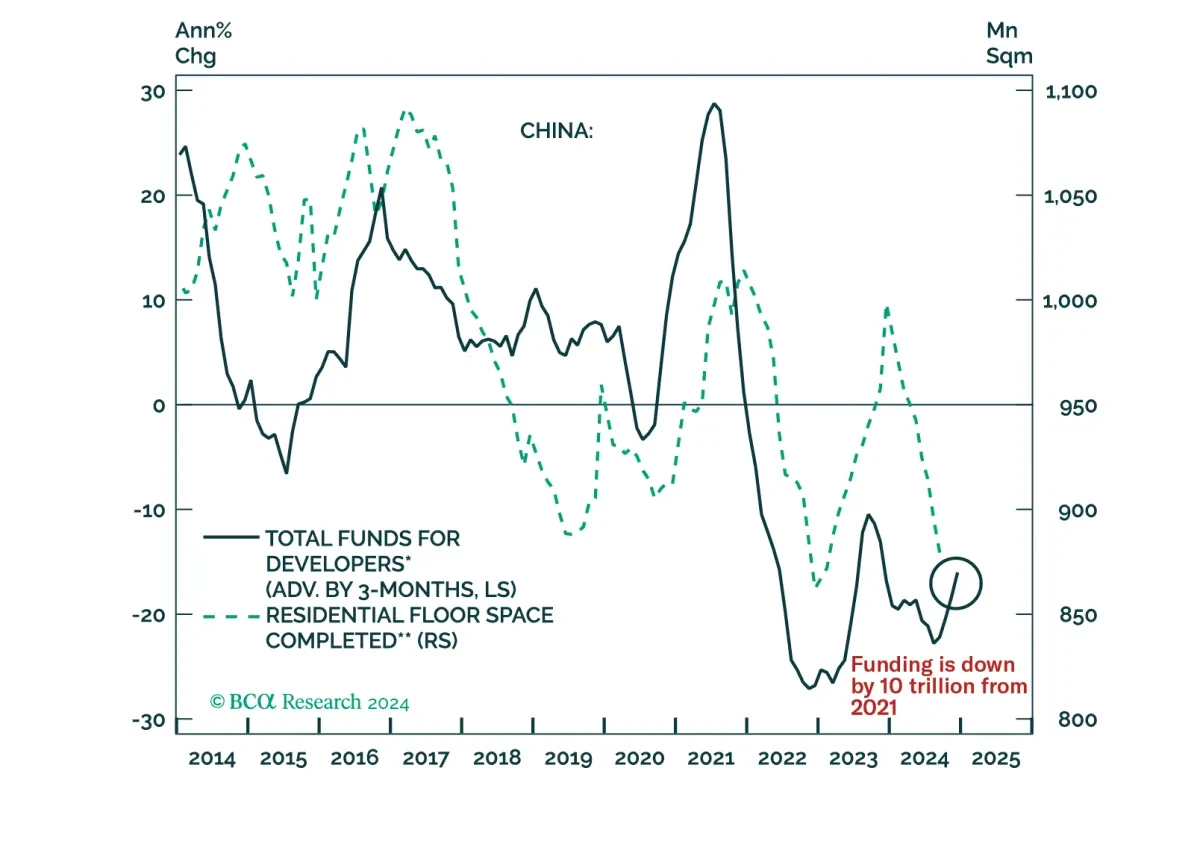
We spent last week visiting our clients in China. In this report, we share some of the key questions from the client meetings as well as our responses....
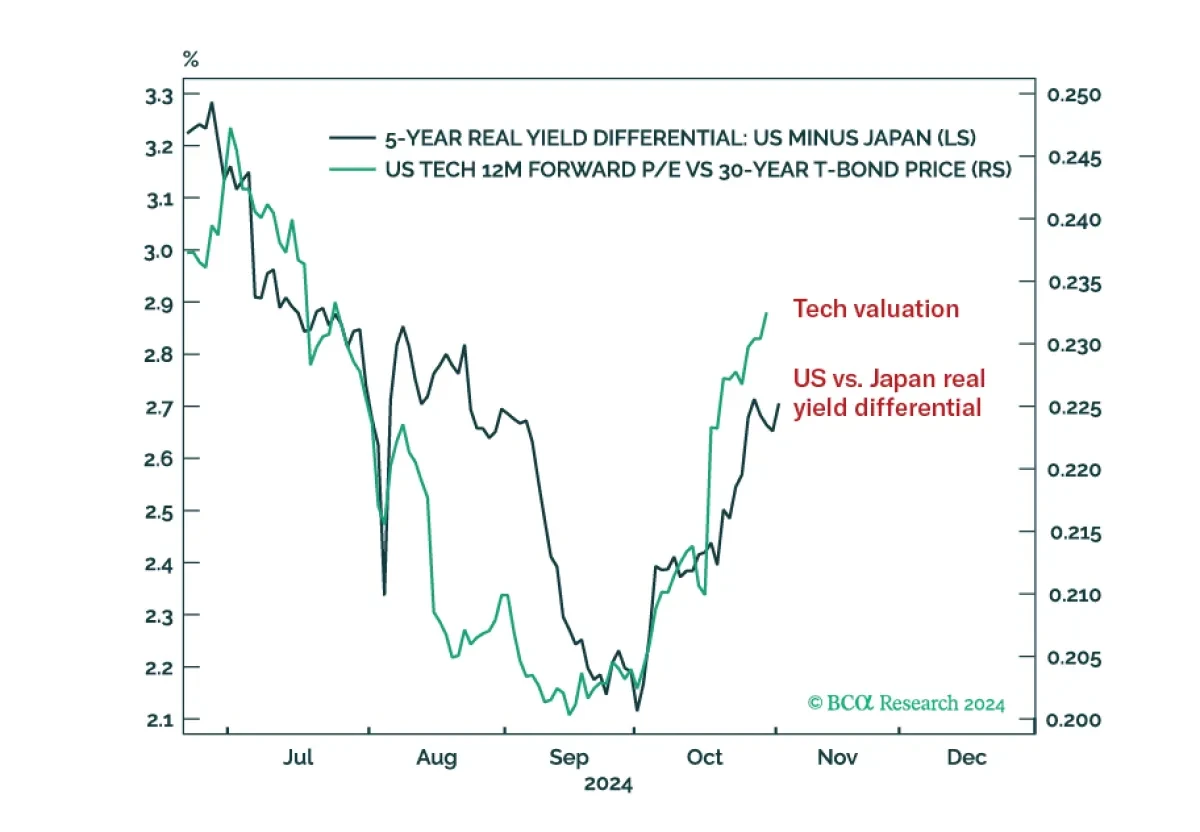
The most important transmission mechanism of a Trump presidency on the stock market will be via its impact on the US-Japan real yield differential. This is because Japan’s extreme negative real yield versus the US is the dominant source of global liquidity right now, and thereby the main driver of s...
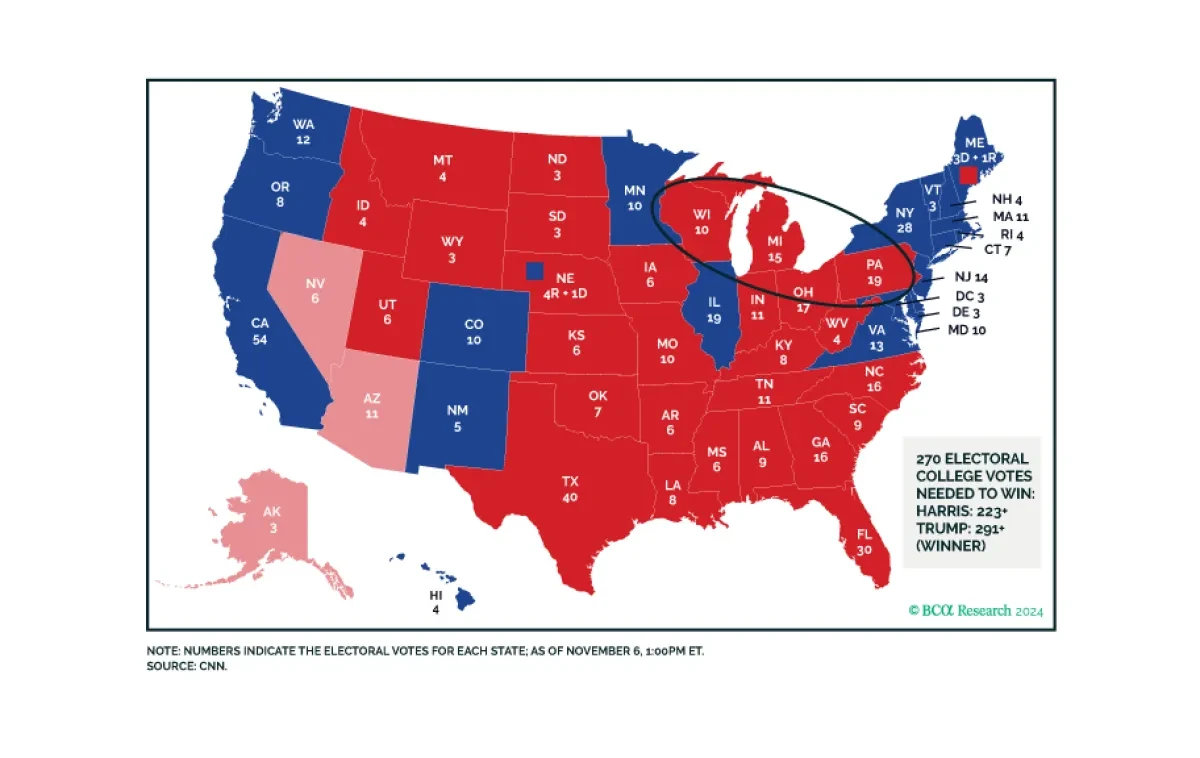
Trump’s resounding victory brings a popular mandate that ensures deregulation and higher trade tariffs. Higher budget deficit and immigration reform are also in the cards as the Republicans look like they may squeak a thin margin in the House of Representatives. Foreign policy will become more unila...