Latest from BCA Research
It is highly unusual for equities to enter a bear market without the economy going into recession. Since we see the risk of recession as low, we recommend a neutral allocation between bonds and equities.
Spread product performance has been foreshadowing changes in market rate hike expectations since early last year, and the recent bout of weakness means it is probably time for the Fed to temper its hawkishness.
The oversold bounce is not supported by policy or profits, and should be treated as countertrend. Lift machinery to neutral and differentiate between pharmaceuticals and the unwinding of the biotech mania.
Any recovery in risk assets and selloff in safe havens is unlikely to extend into the cyclical horizon.
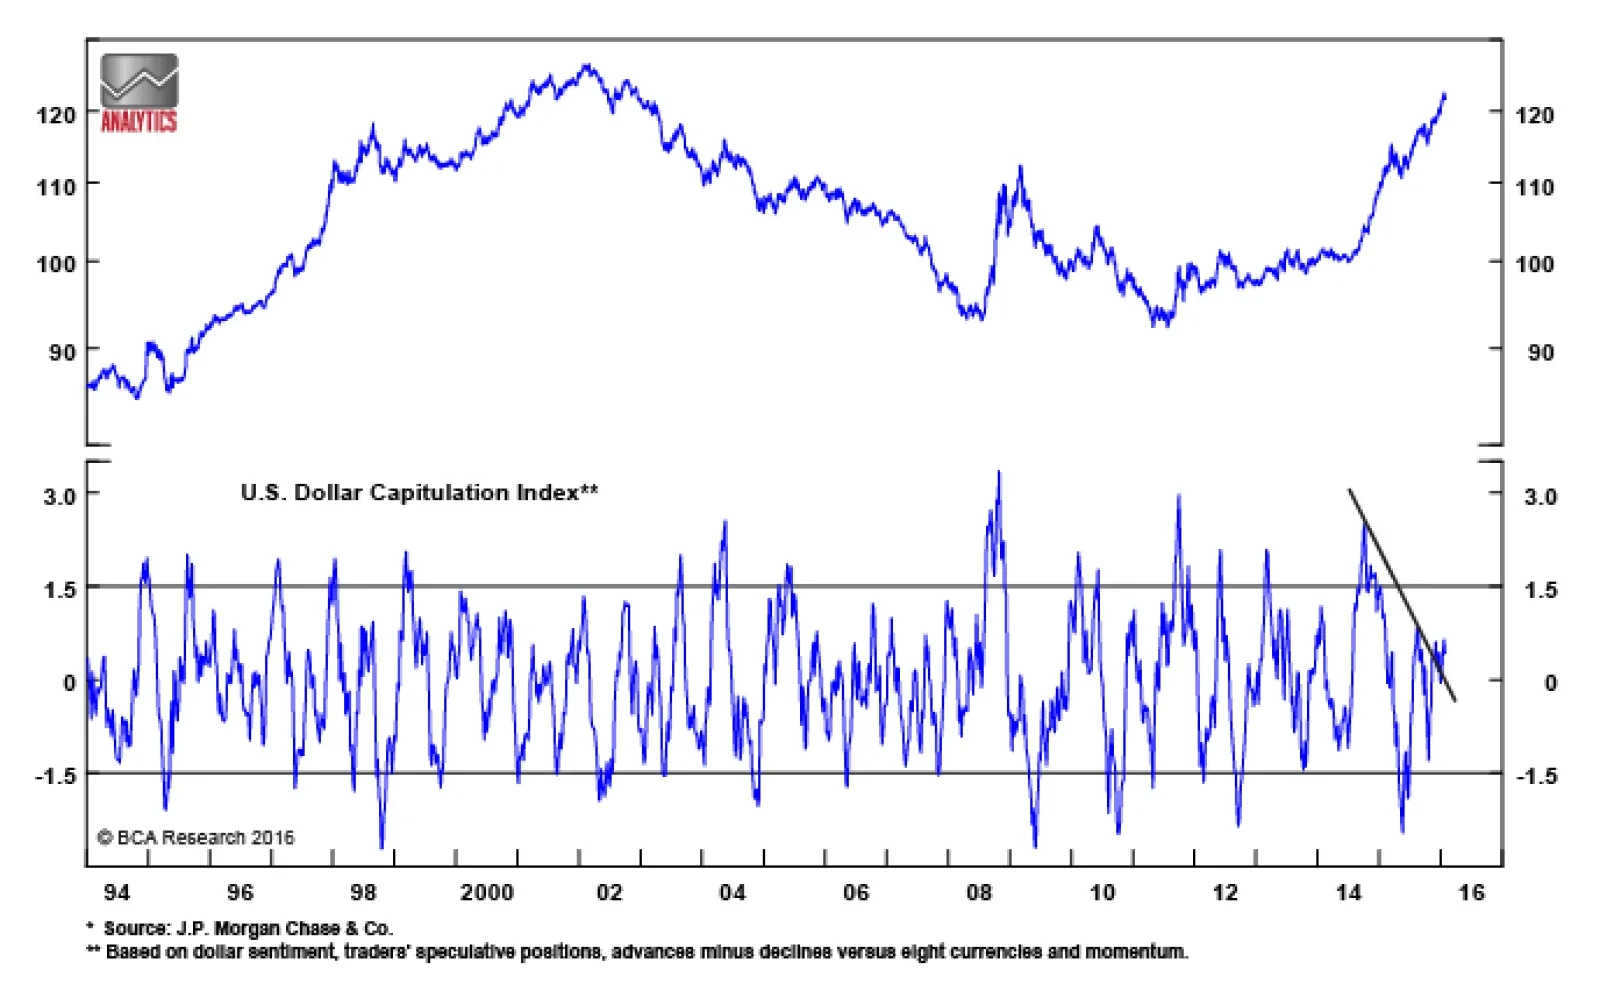
Last month, the model outperformed both global and U.S. equities in local-currency and U.S.-dollar terms. For February, the model is aggressively increasing its risk exposure and has included a bet on commodities for the first time since 2012. For equities, the largest overweight remains Europe, but EM and Canada enjoyed significant upgrades. For bonds, the model favors the European periphery.