Latest from BCA Research
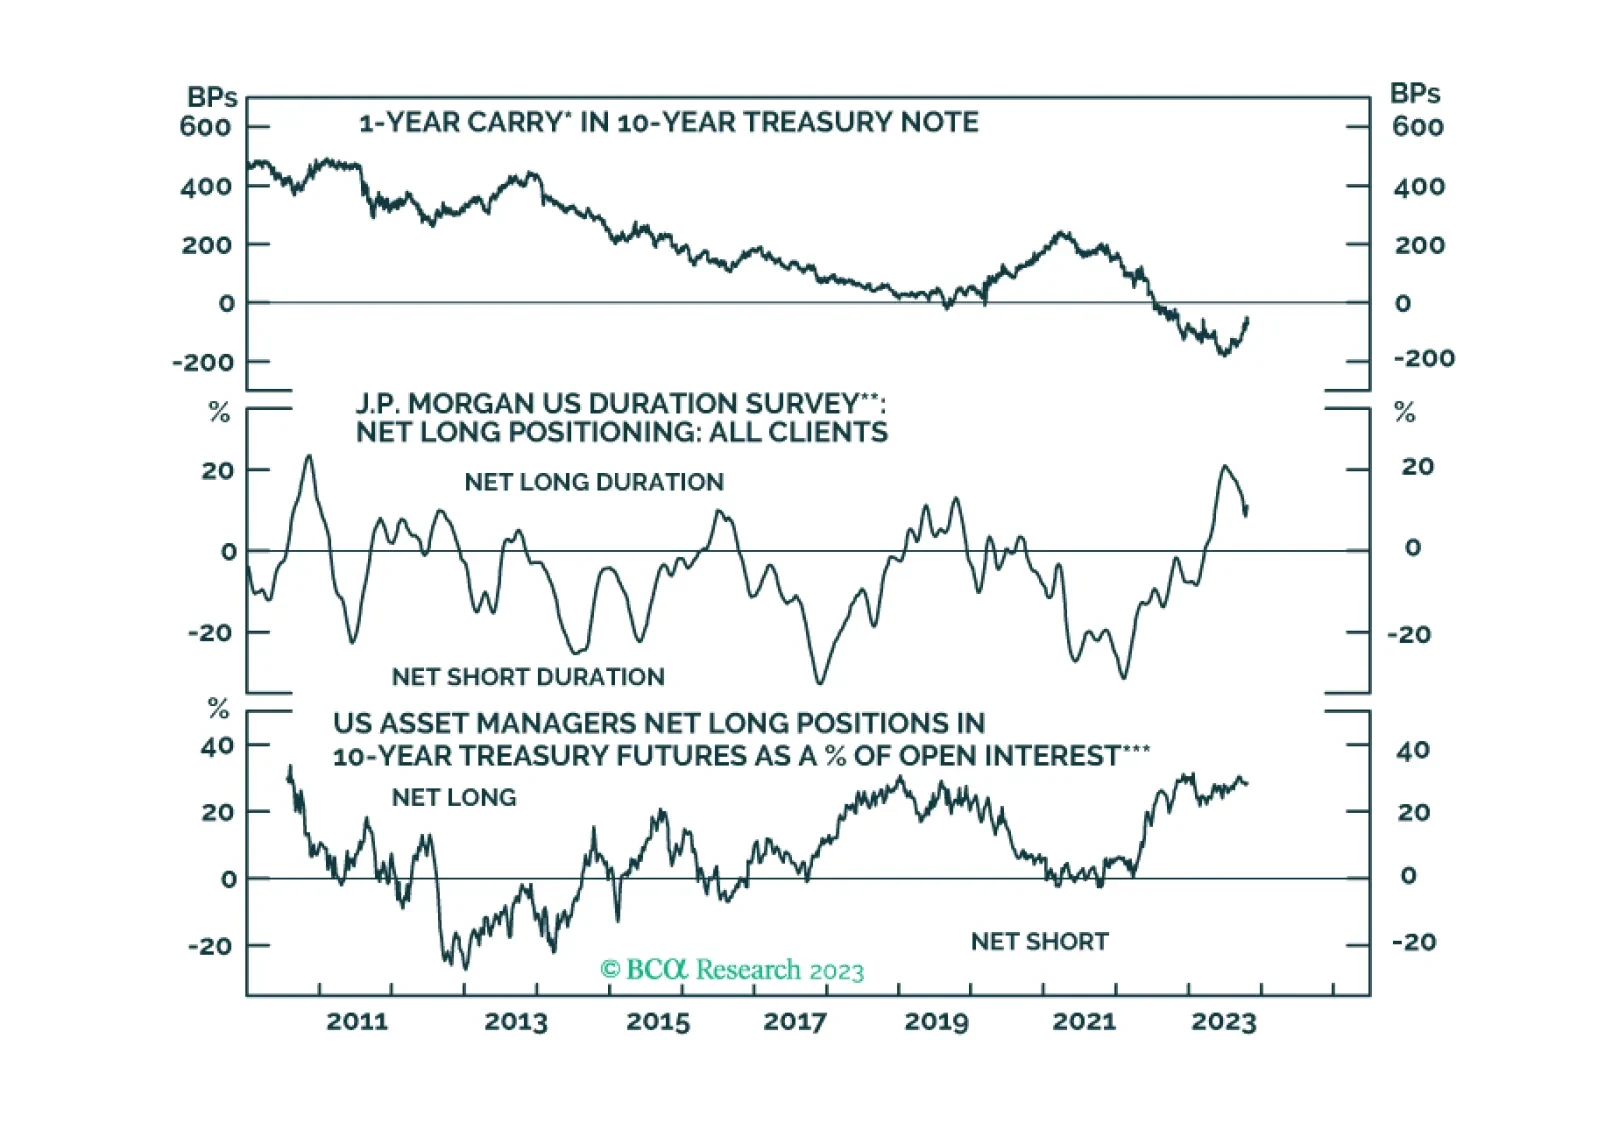
This week’s report contains an update on the Treasury curve’s recent bear-steepening trend and a look at different measures of long-maturity Treasury valuation.
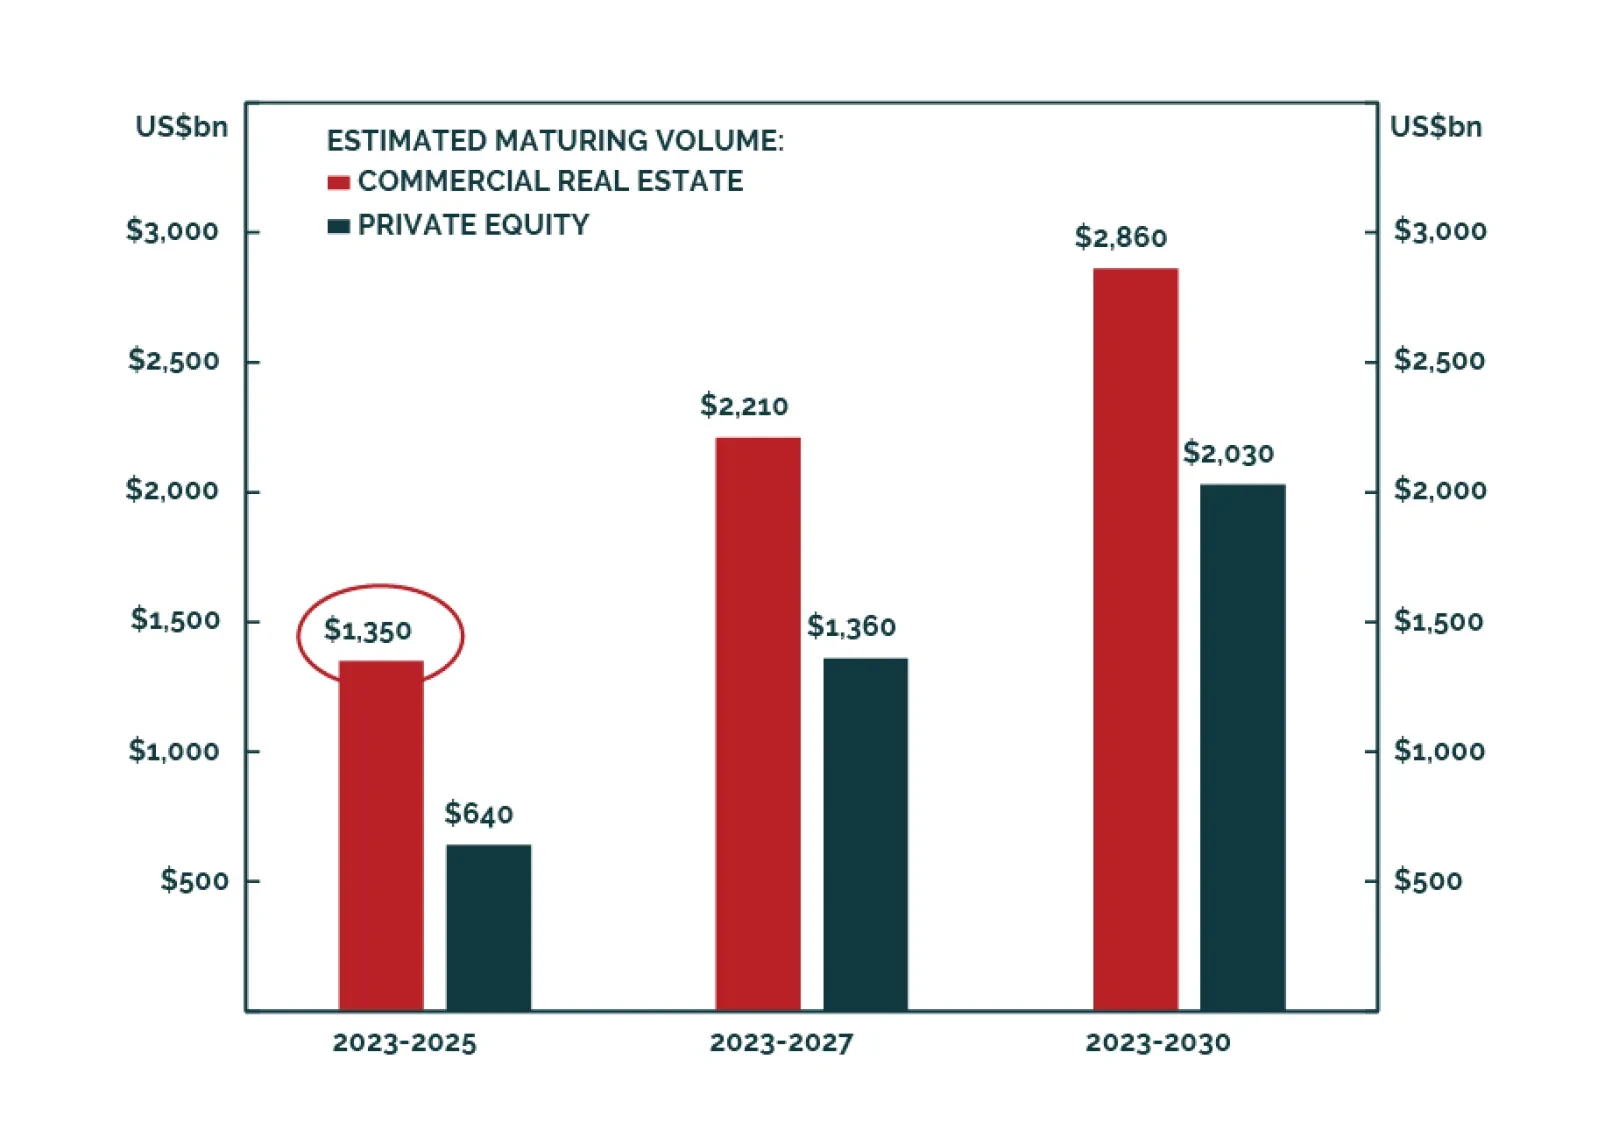
The wall of maturities for Office and Multifamily Real Estate is upon us. The impact of rising interest rates is also being felt by Private Equity and Venture Capital. The difficulties faced by smaller US banks is providing further tailwinds to Direct Lenders. Hedge Funds will benefit from a more volatile backdrop over the next 1-2 years. Now is the time to resize Crisis Risk Offset portfolios.
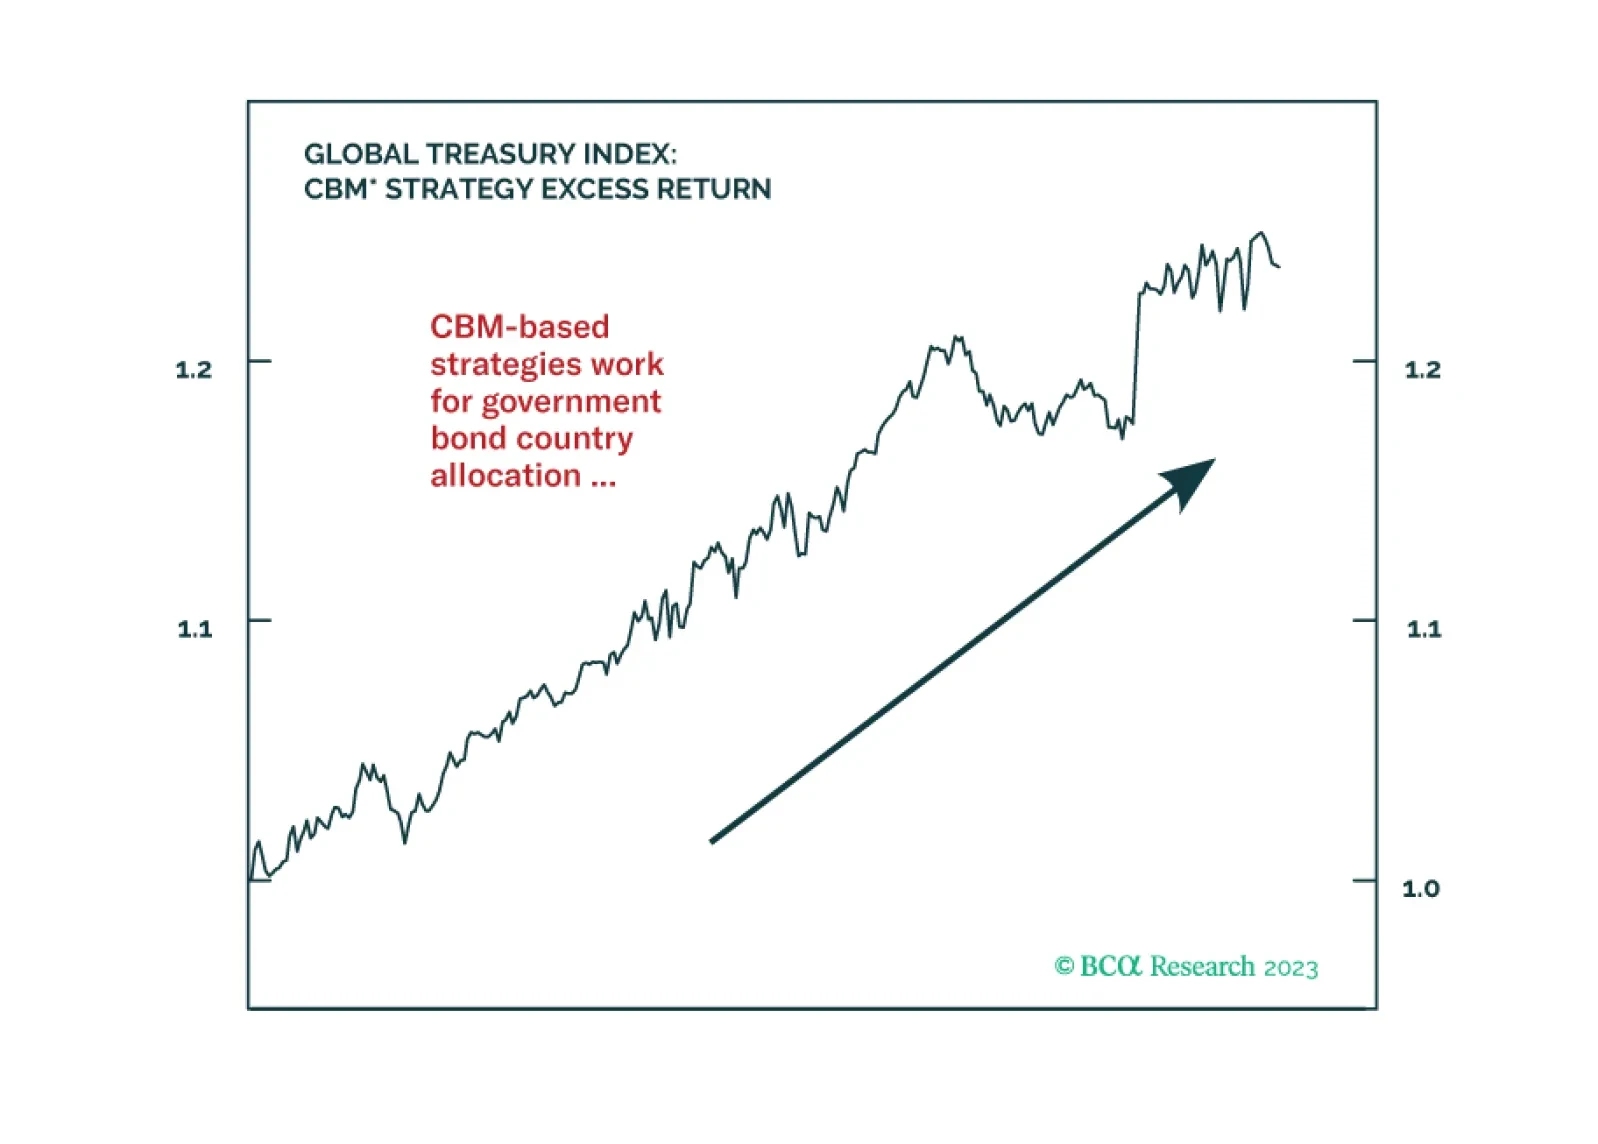
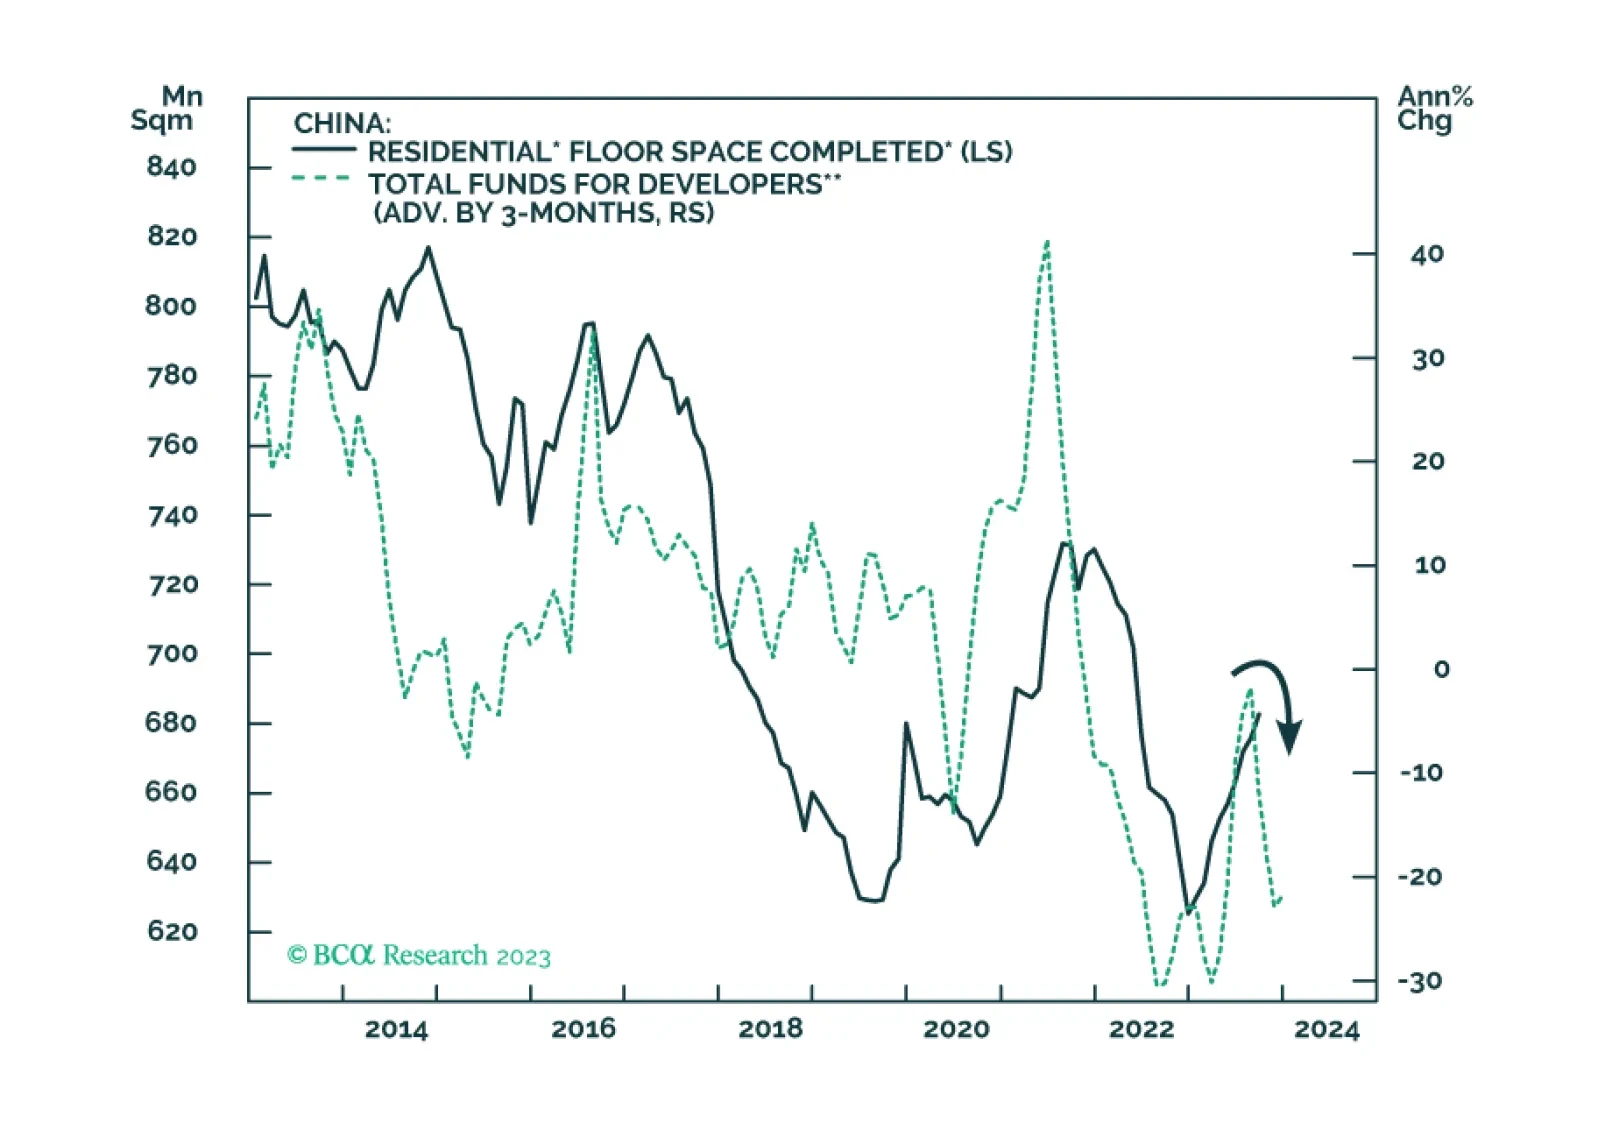
China’s economic growth will stagnate, at best, rather than revive. Lower valuations of Chinese equities are justified, and share prices have more downside. The RMB will continue to depreciate versus the US dollar.
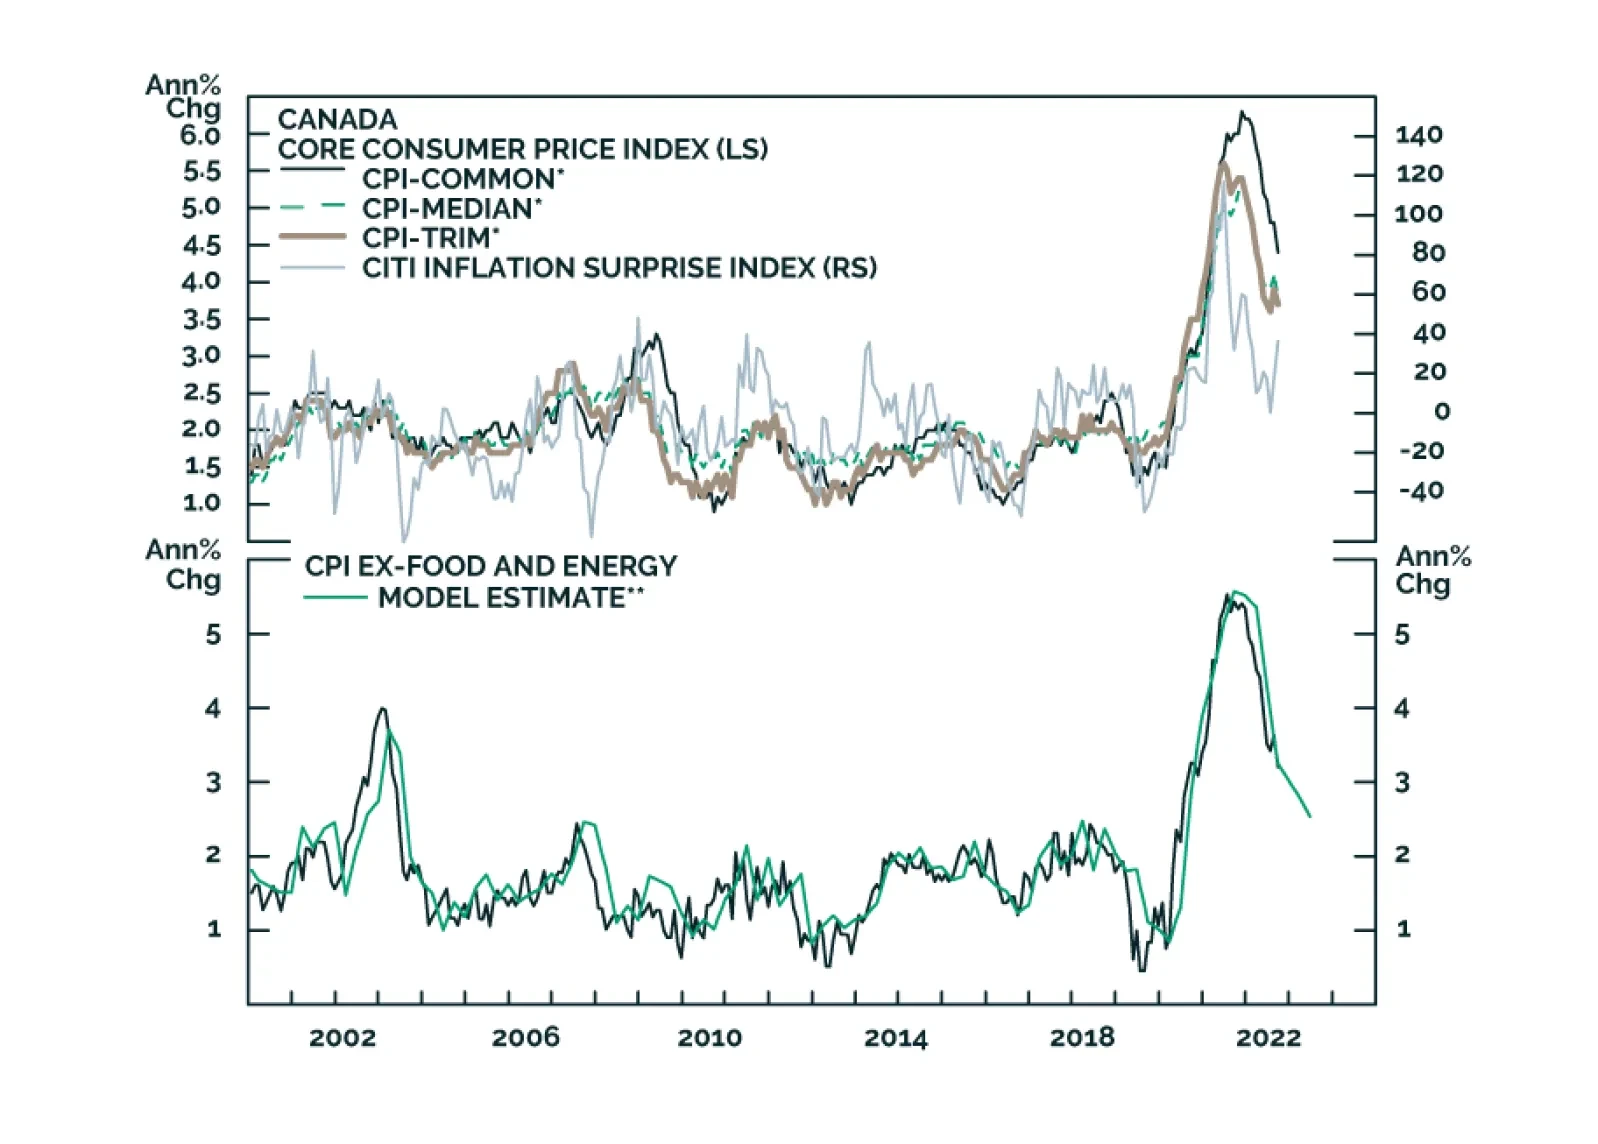
In this insight, we look at whether the recent data justifies a shift by the BoC, and some potential trades.
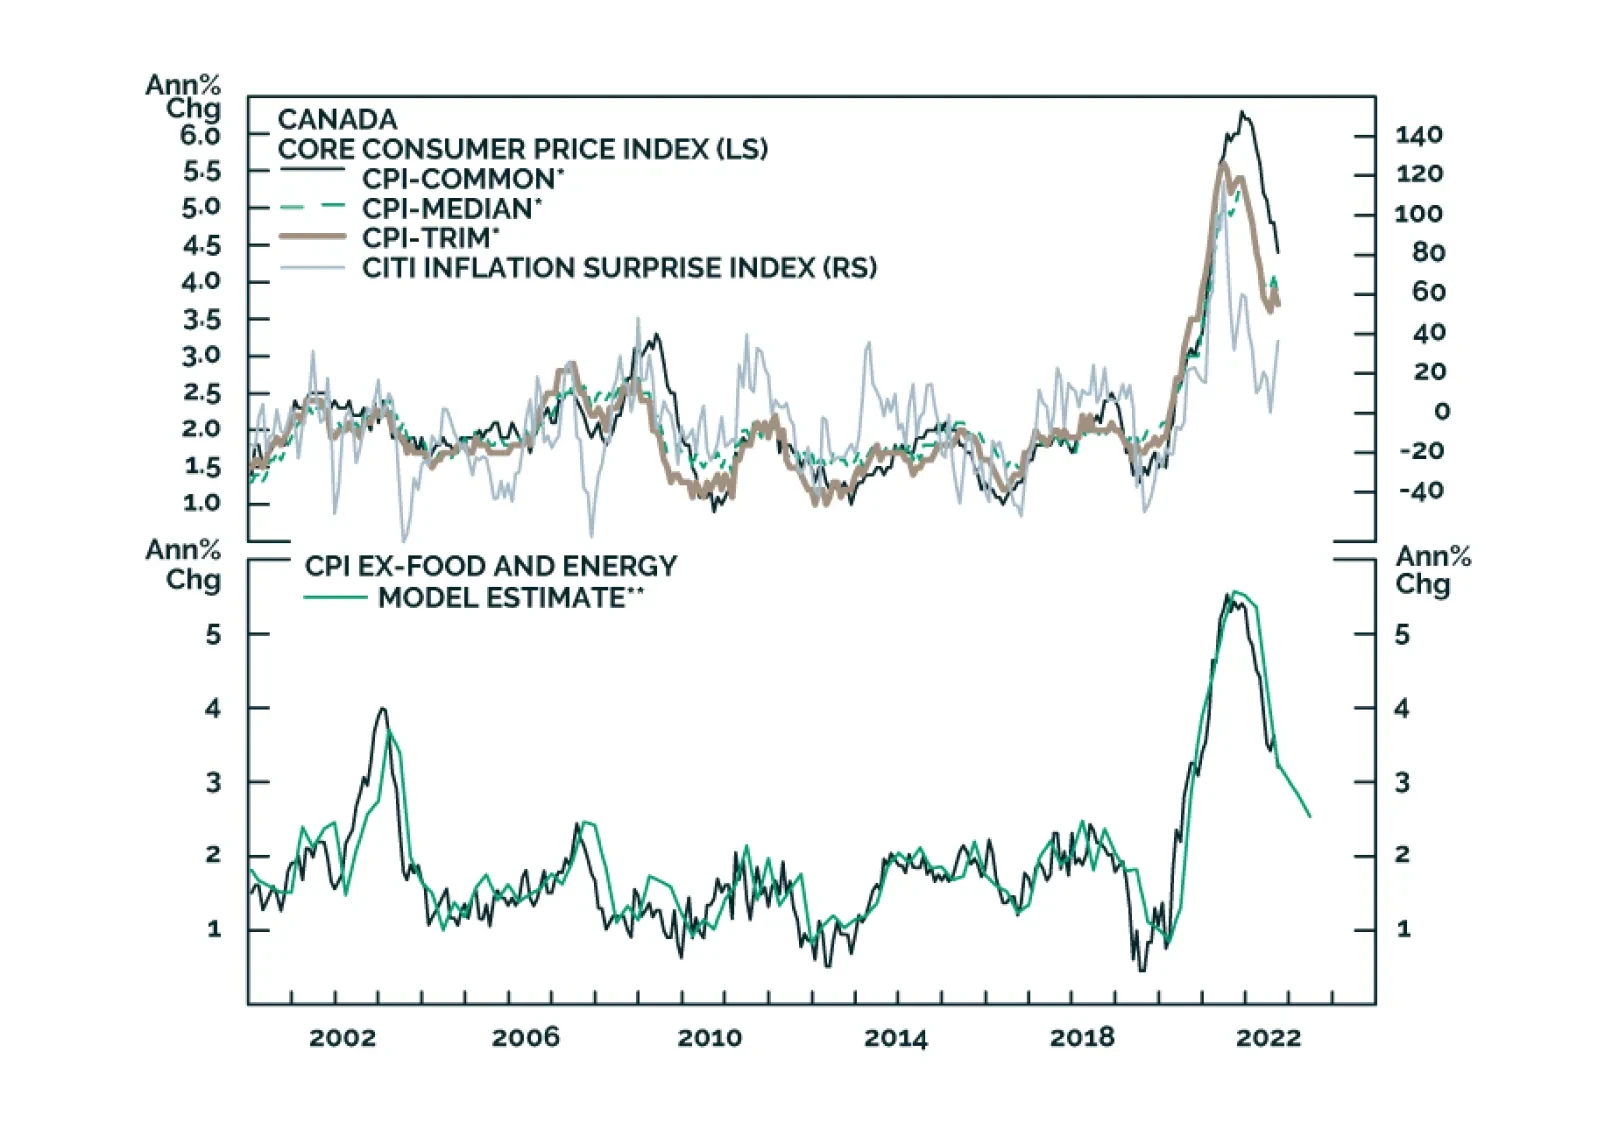
In this insight, we look at whether the recent data justifies a shift by the BoC, and some potential trades.
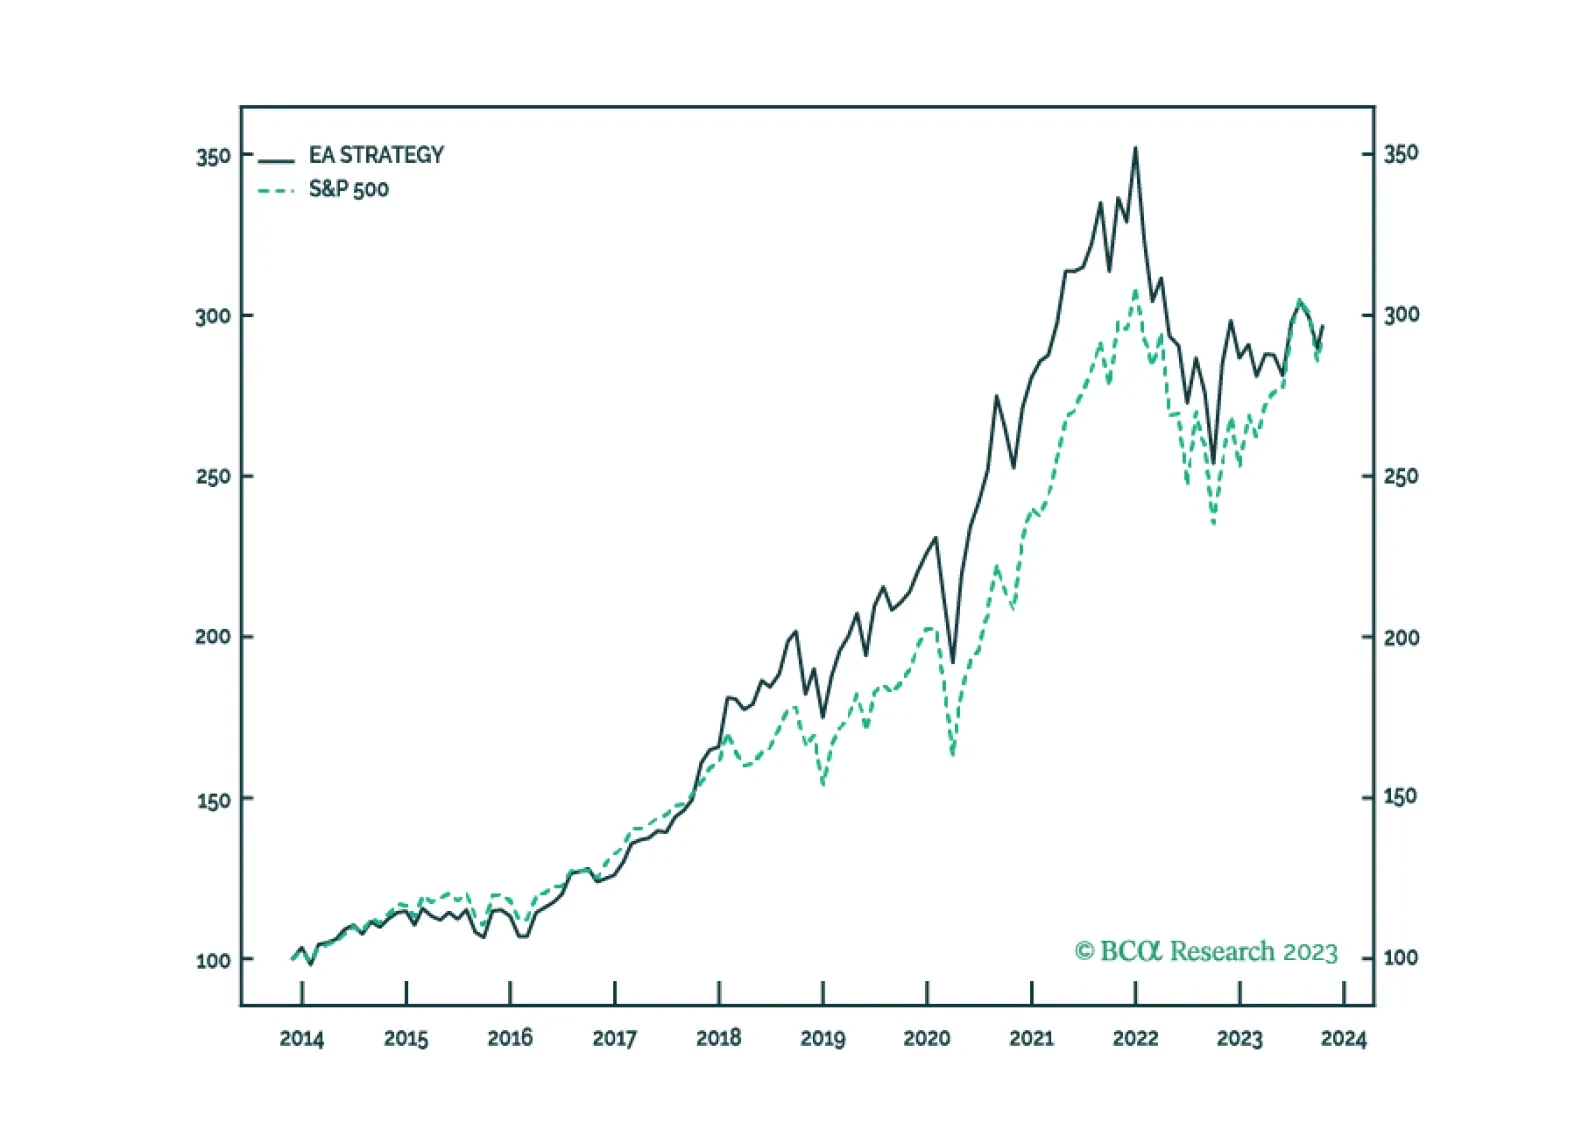
In this insight we suggest two ways clients can use Equity Analyzer to navigate the evolving crisis in the Middle East. The first minimizes commodity exposure and the second uses relies on the BCA Score to add exposure to high quality Energy and Aerospace and Defense stocks.
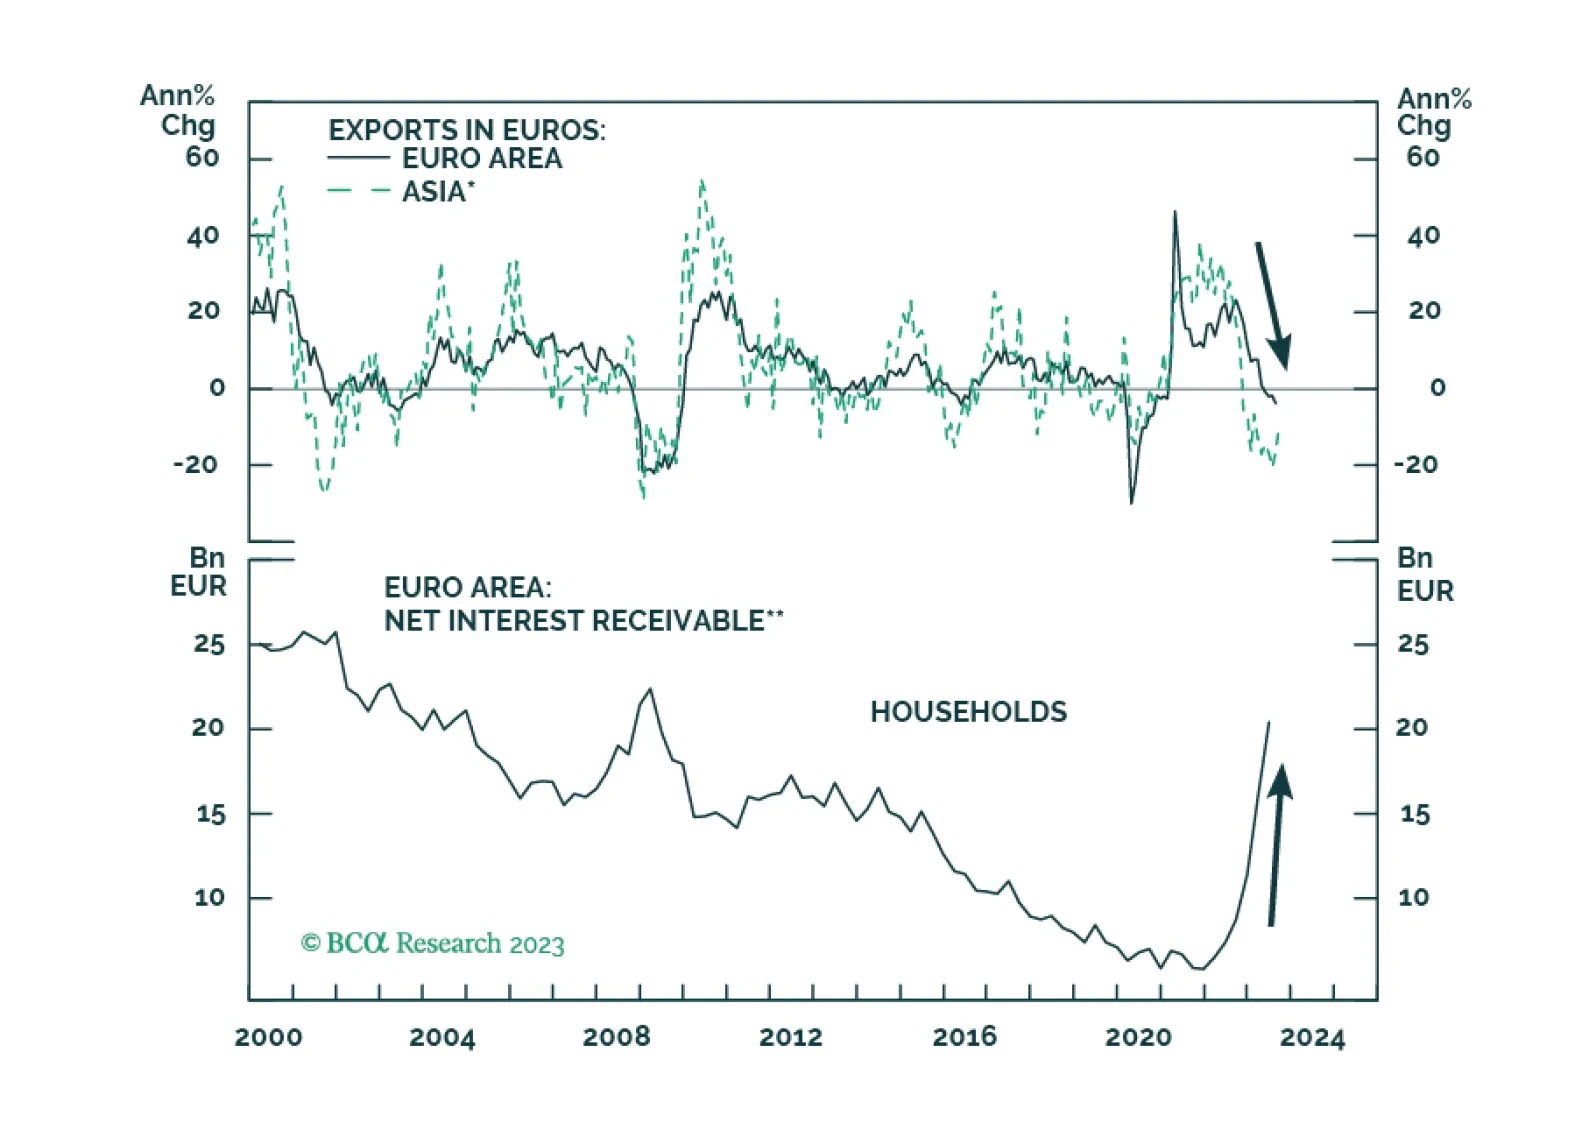
Europe’s weak patch is not about the ECB’s policy tightening, at least not yet. 2024 is another story, and the ECB’s policy will prompt a Eurozone’s recession around the summer.
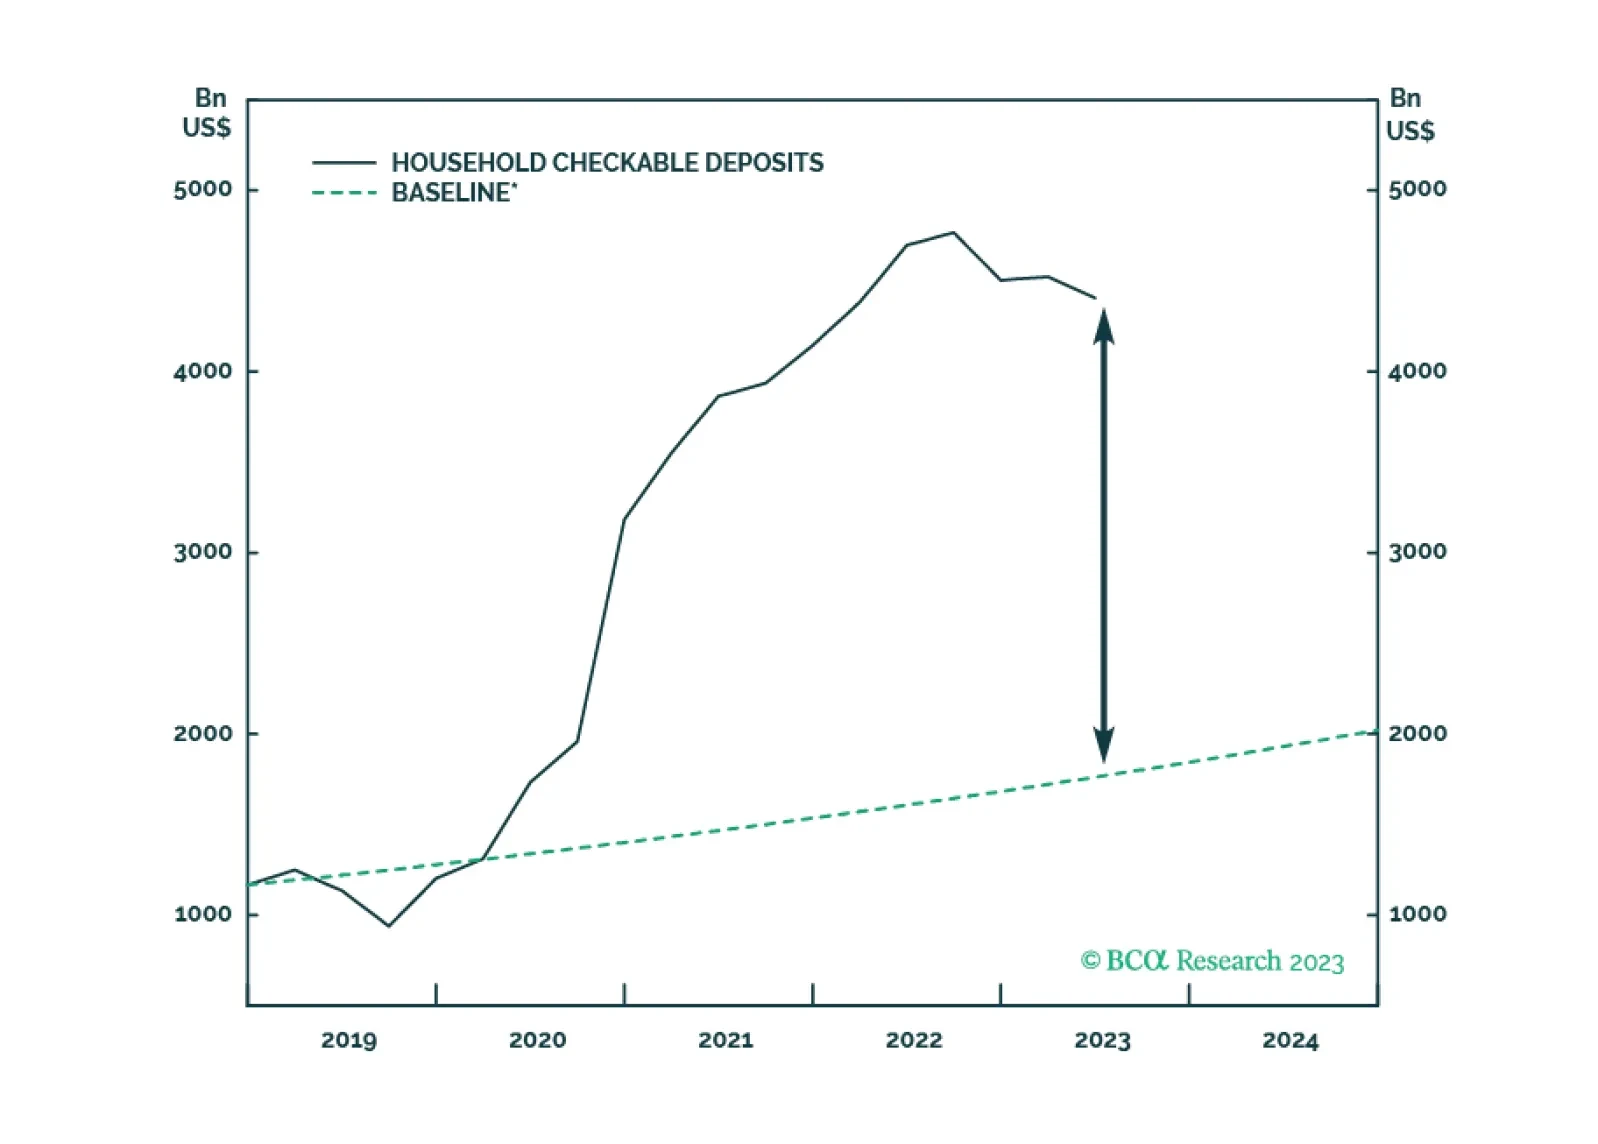
The biggest banks report that consumer credit card delinquencies still have yet to get back to pre-COVID levels and other credit performance indicators, leading and lagging, remain solid. There is still a great deal of cash sloshing around the banking system, though consumption has clearly slowed. We reiterate our view that a recession is coming, but not before the year is out.
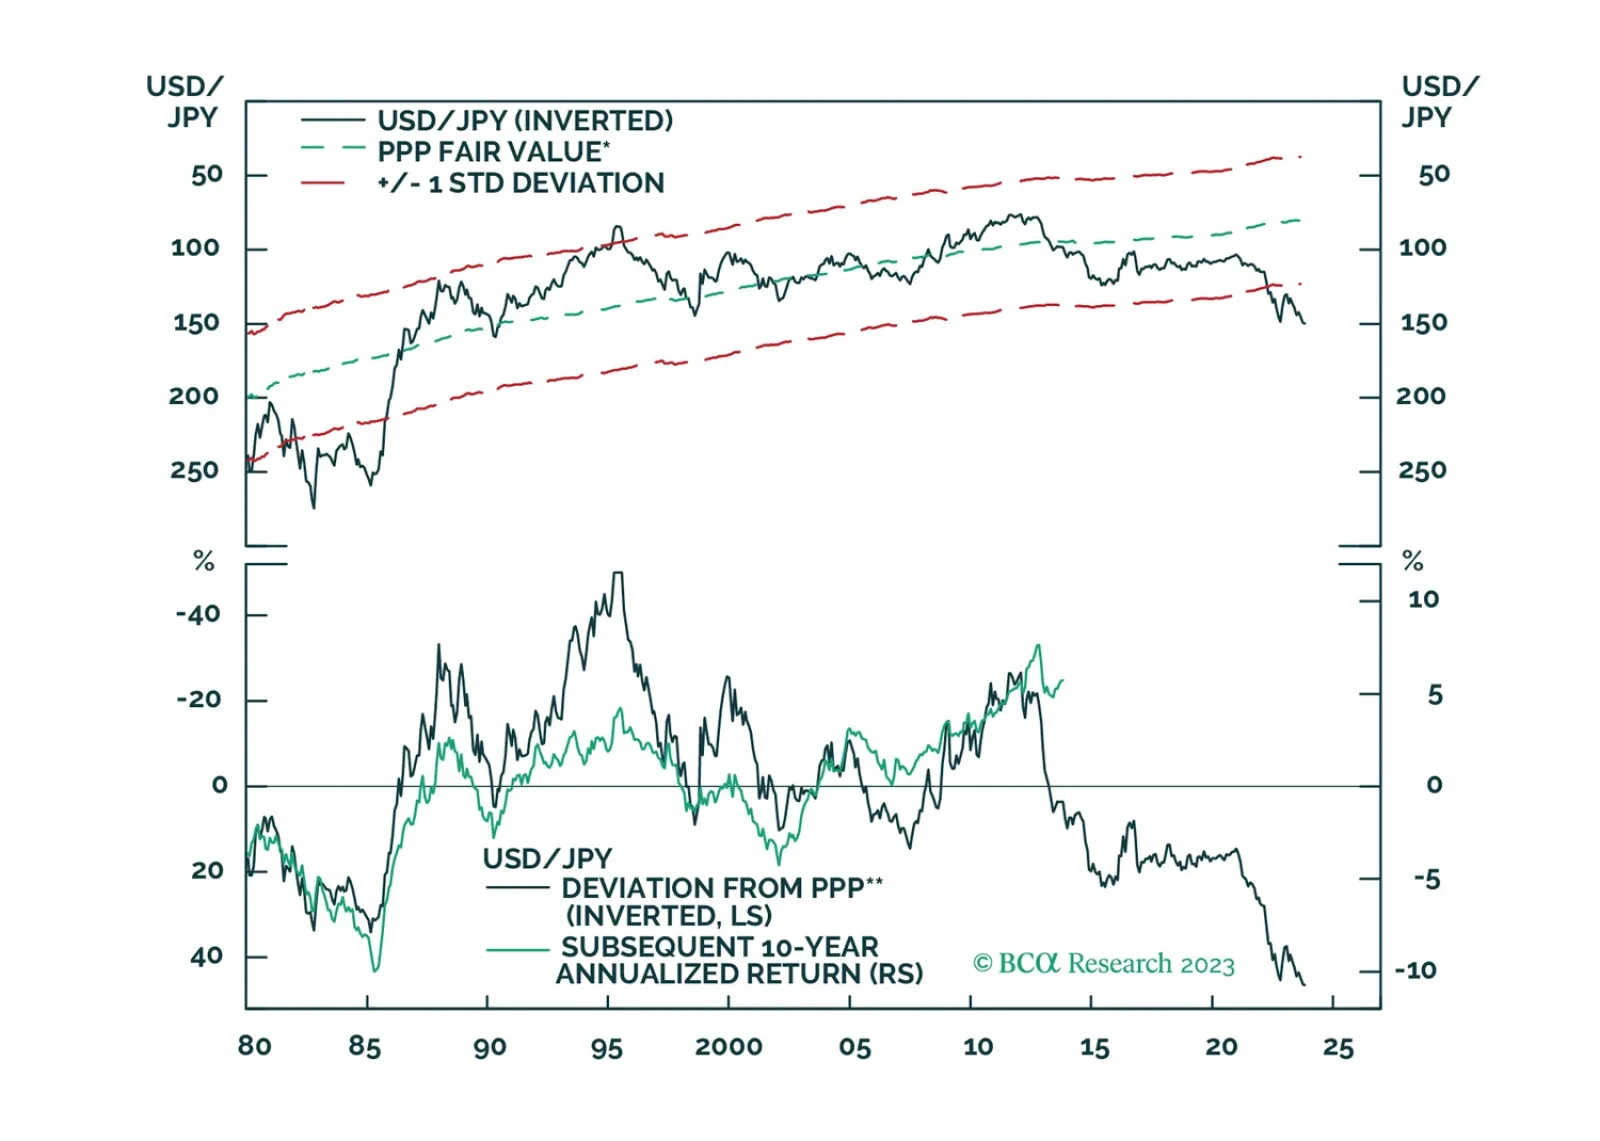
There is a high probability that the global economy will tip into recession in the second half of 2024. A long yen position is an excellent hedge against that risk.