Latest from BCA Research
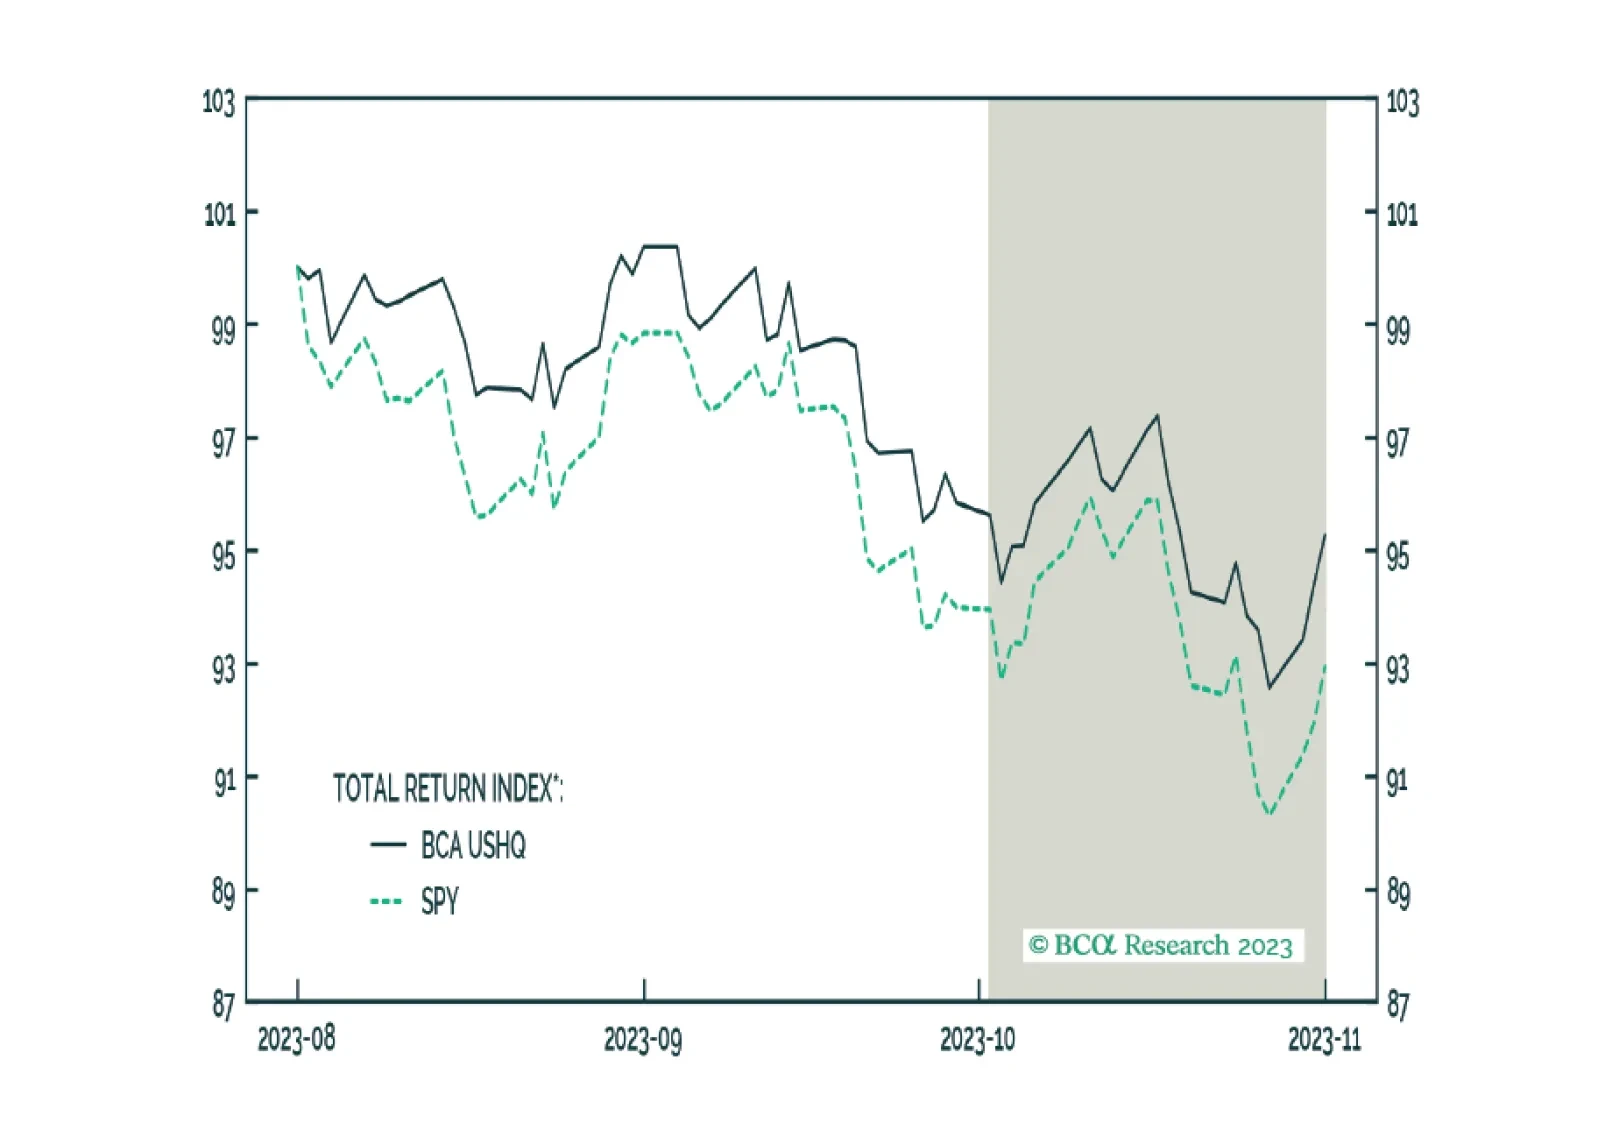
Both USHQ portfolios outperformed inline with their benchmarks and the BCA Score L/S had another strong month. Increased market volatility continues to benefit the BCA Score.
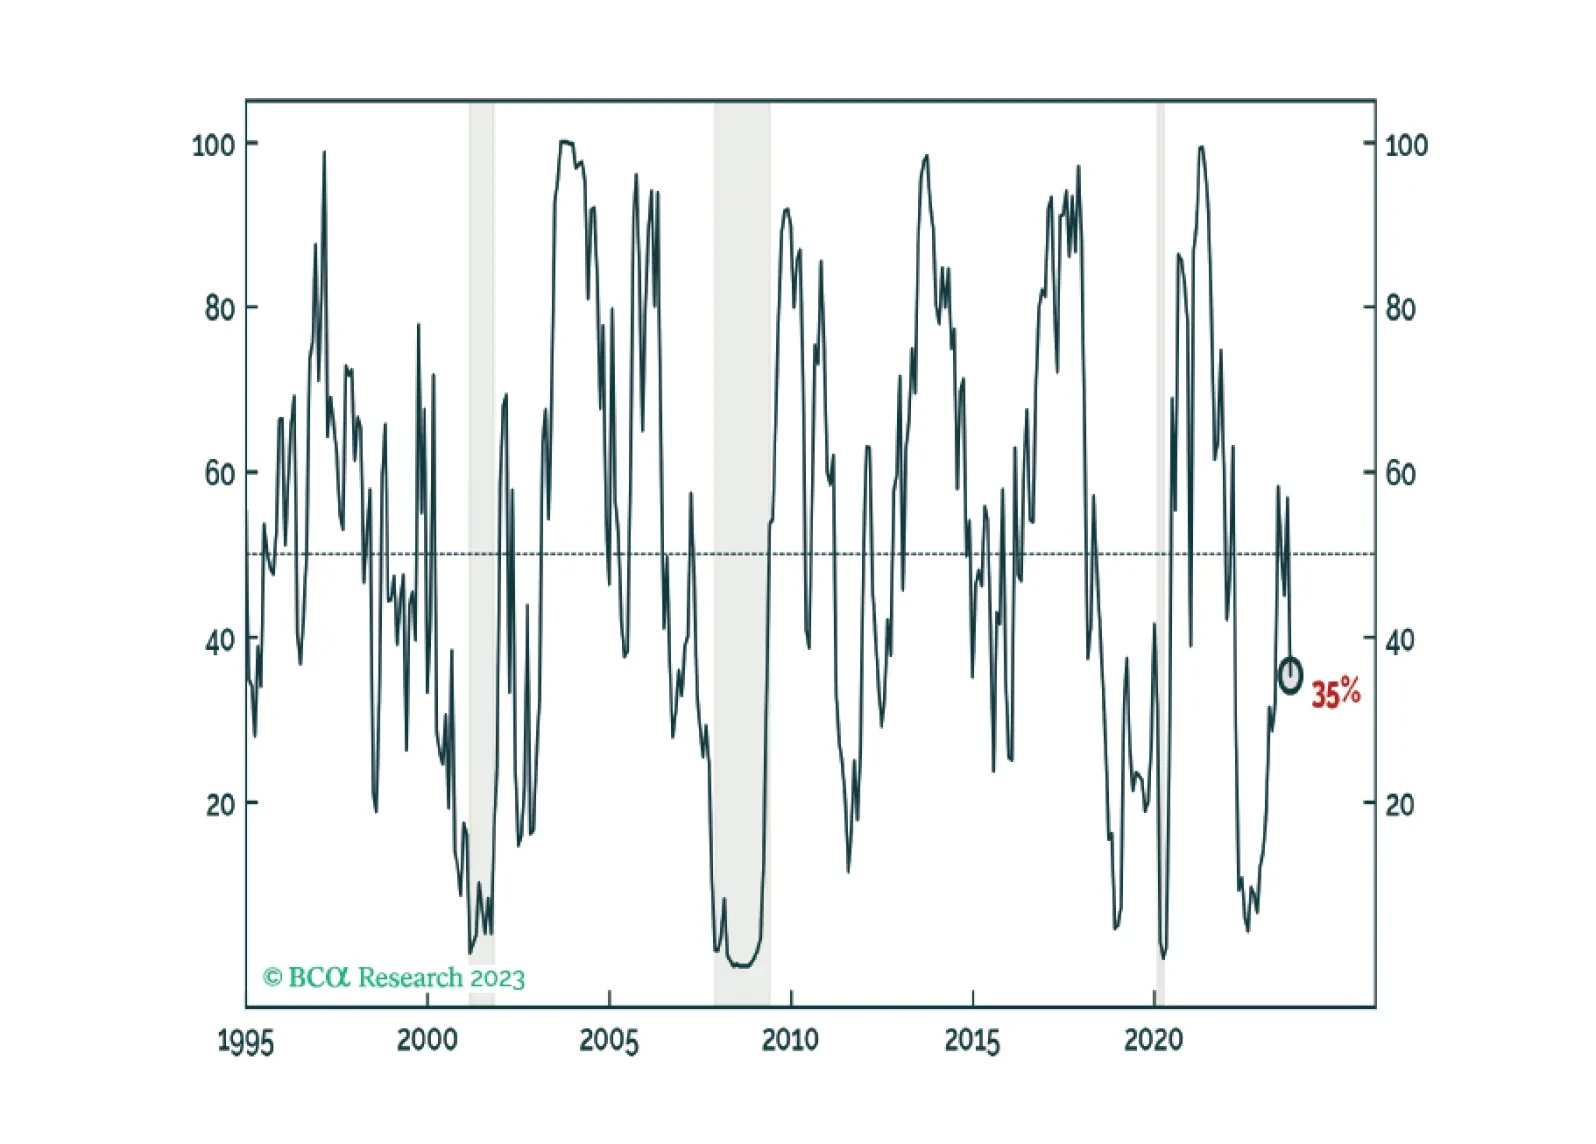
This month the Global Equity Score turned bearish after hovering in neutral territory for a few months. As a result, the sector model upgraded Consumer Staples to bullish. We also explore the remarkable year-to-date performance of the Composite Value Composite Score and propose a screen.
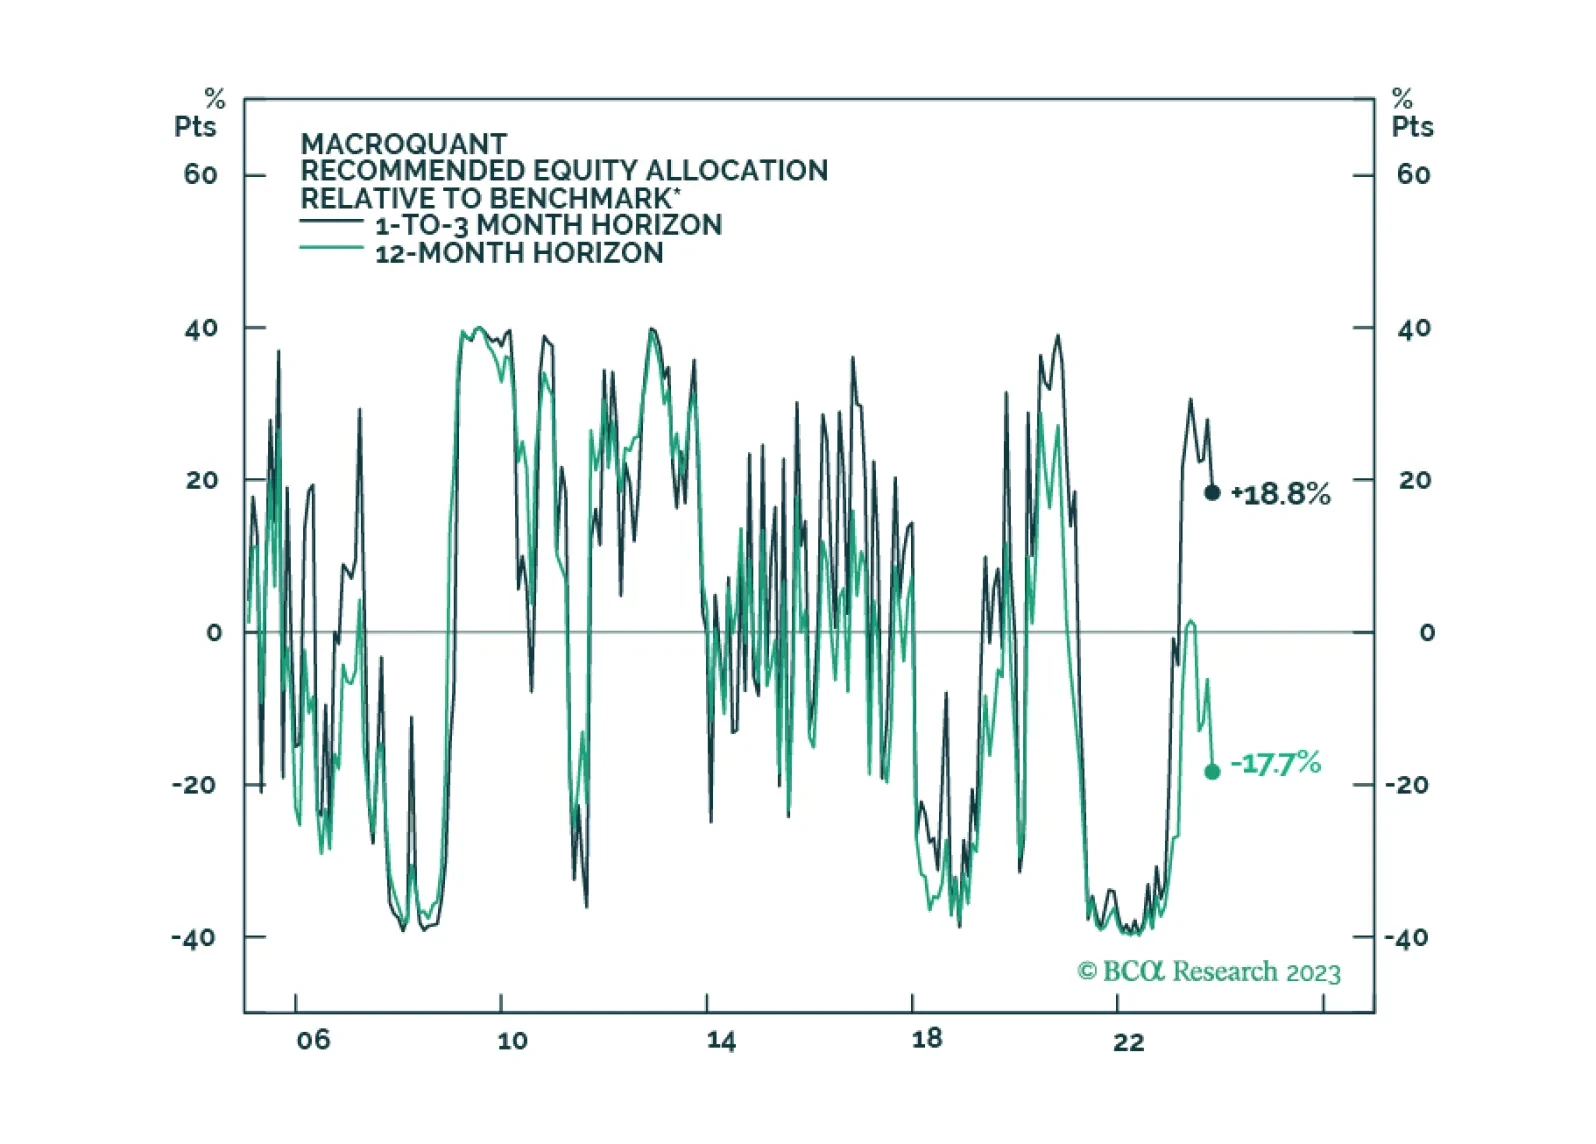
We are approaching another phase transition from boom to bust. Stocks should rally into year-end, but investors should look to reduce equity exposure early next year while increasing bond exposure.
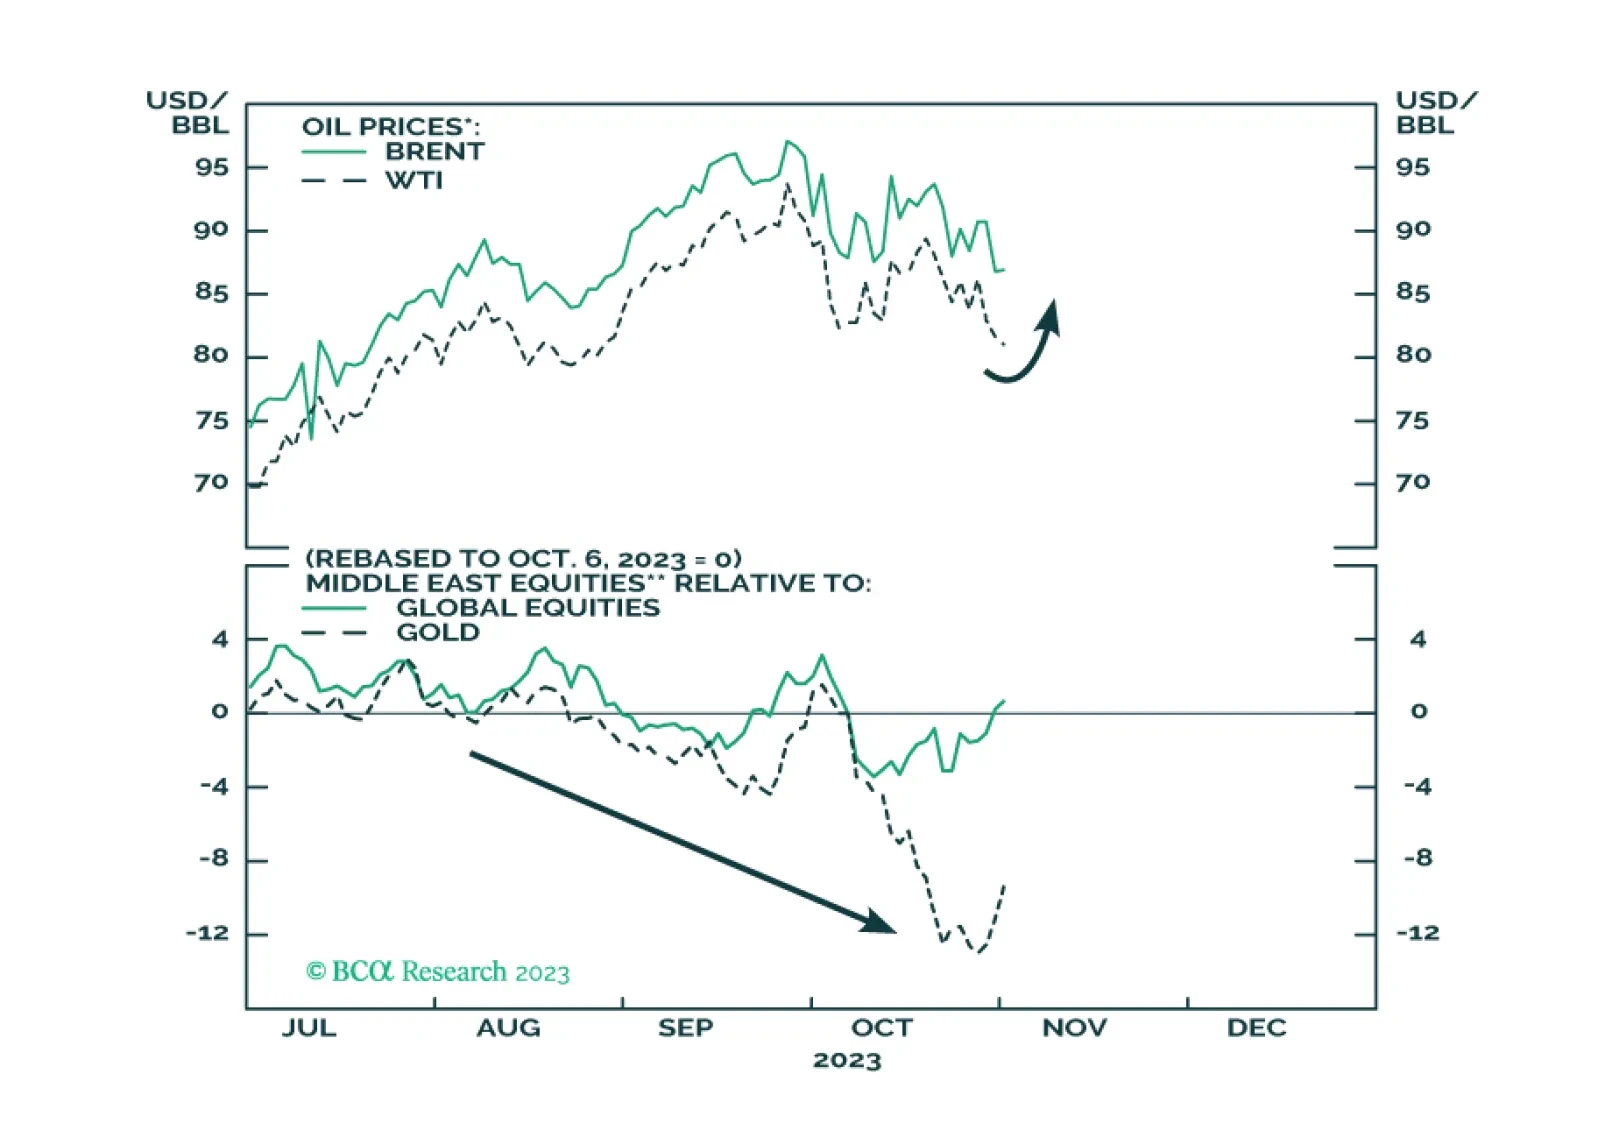
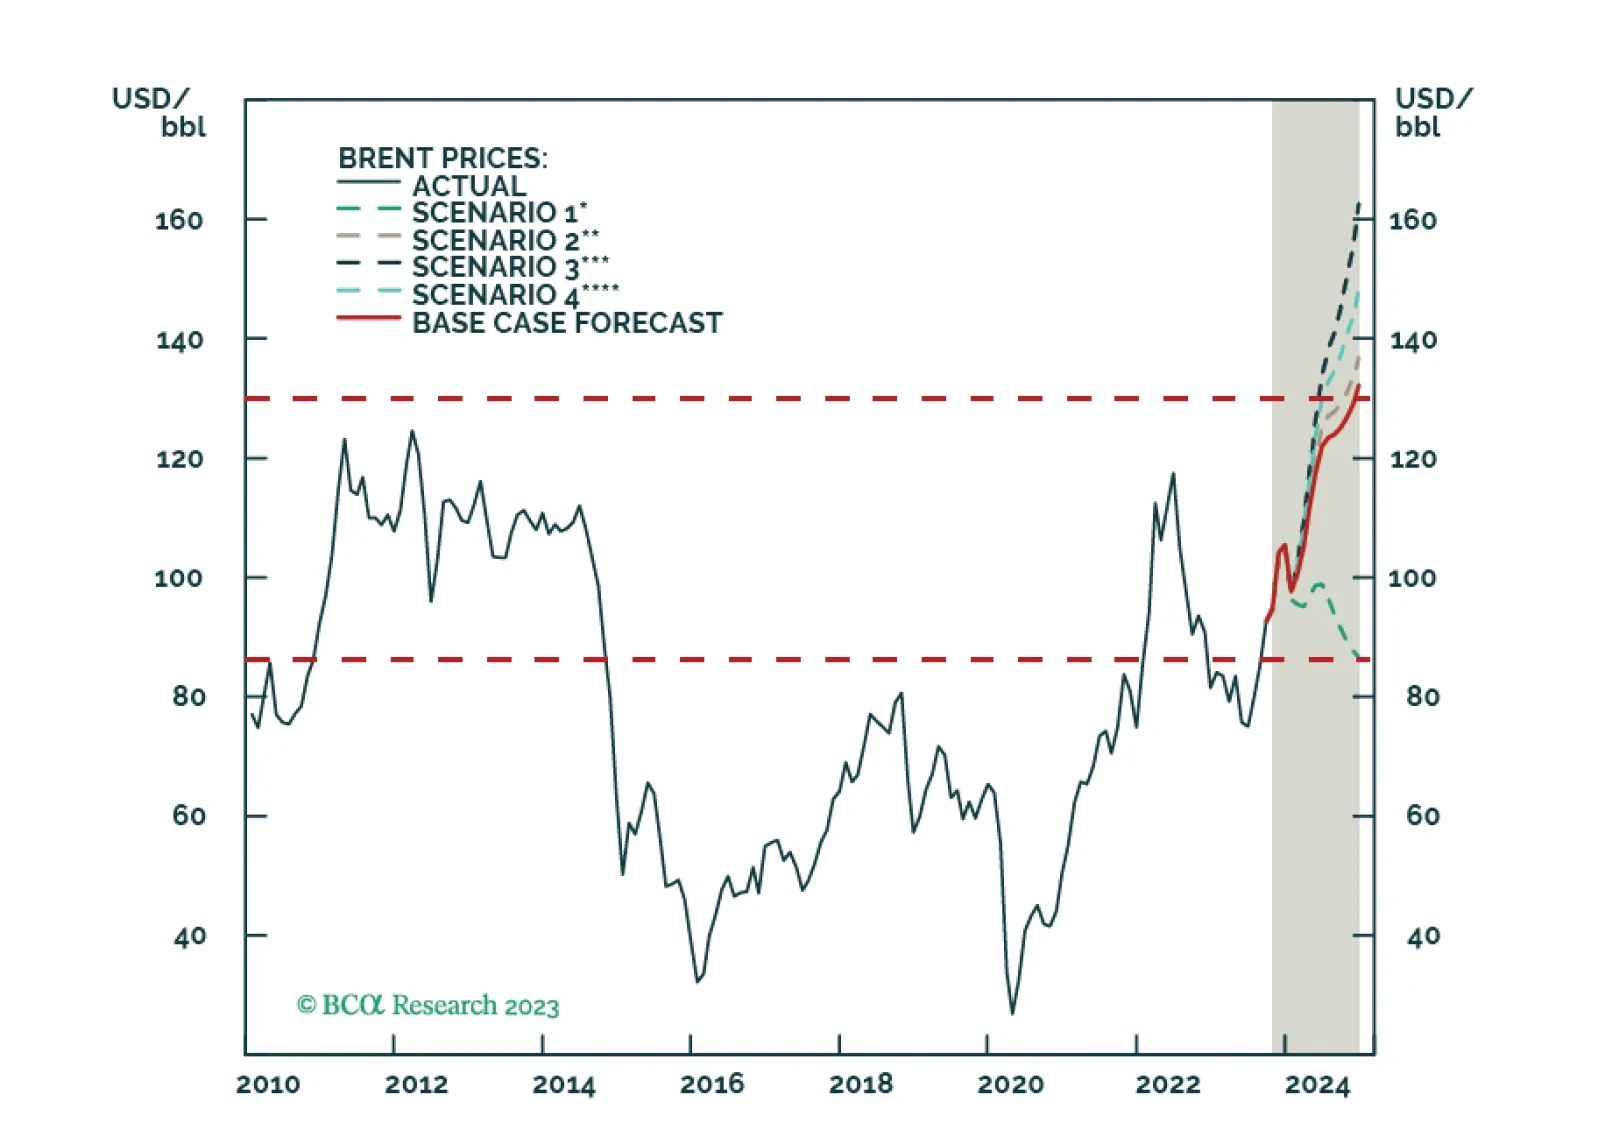
Investors should reduce risk, increase allocation to safe havens, and brace for oil price volatility and supply disruptions stemming from the Middle East over the next zero-to-12 months.
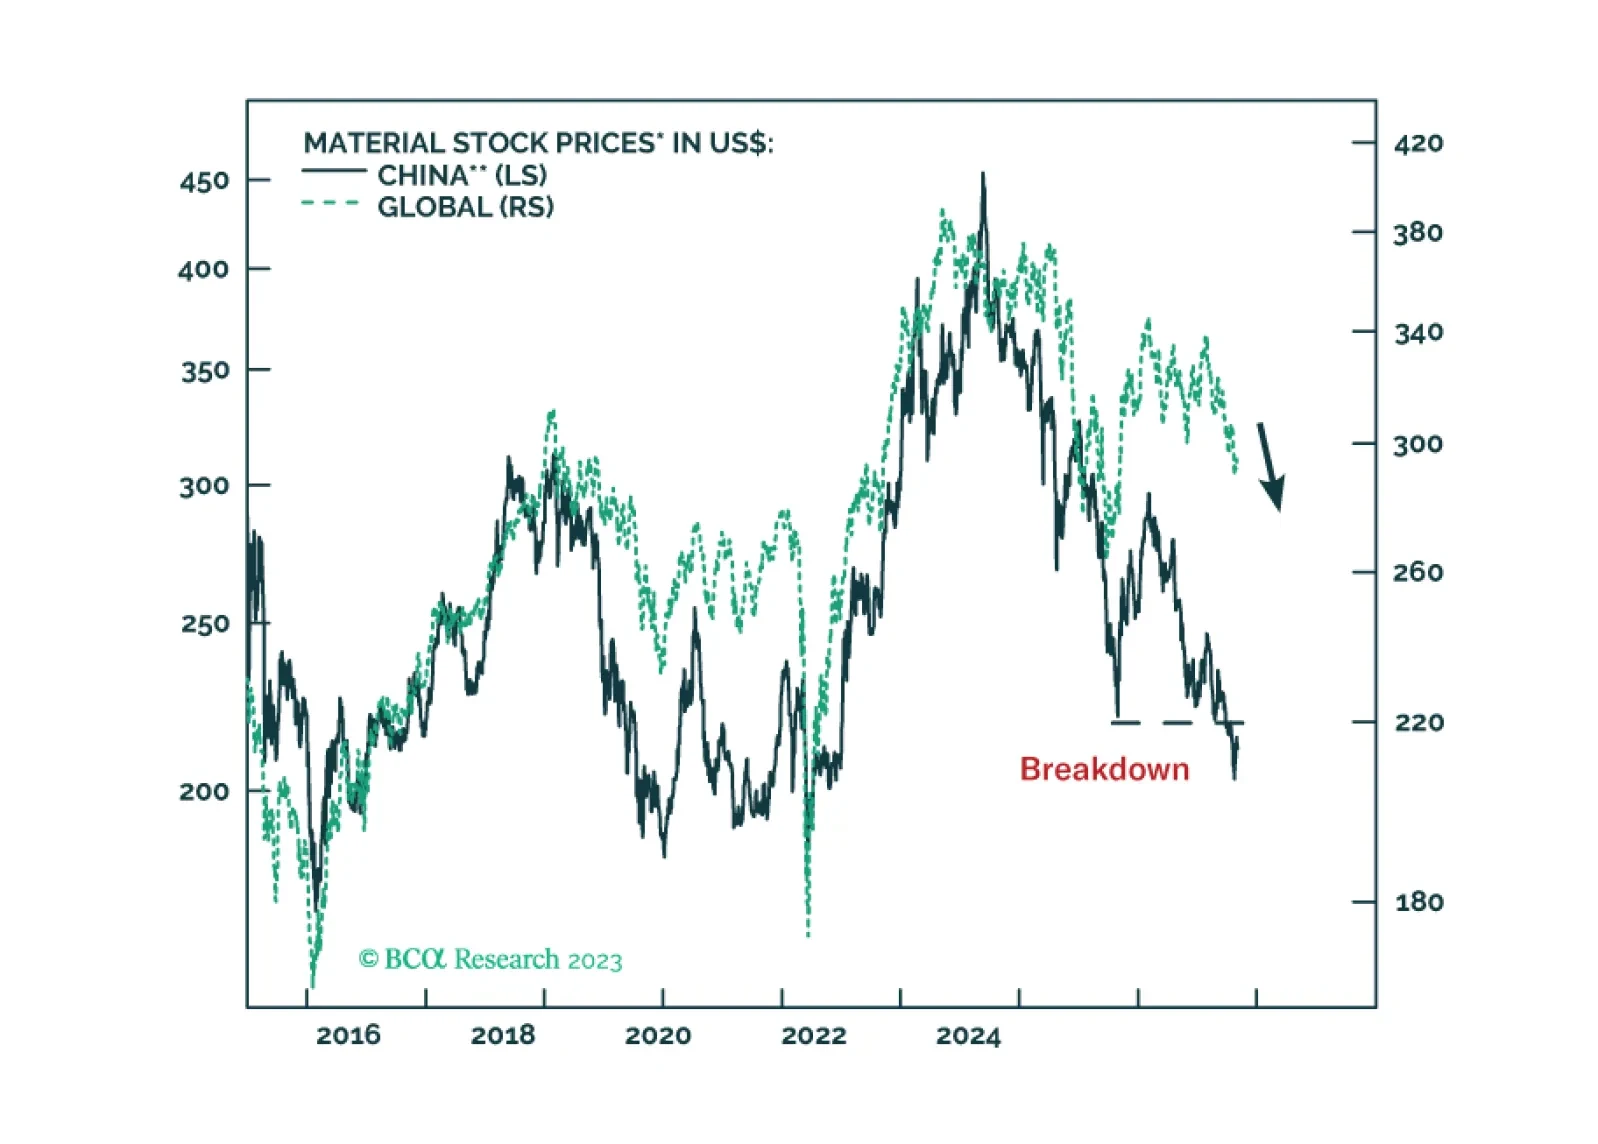
In financial systems, cracks typically begin on the periphery and then expand to the center. Hence, the ruptures on the fringes often act as an early warning. These fissures tend to widen and spread to the core, causing a breakdown in the S&P 500. Investors should consider buying US Treasurys aggressively when the S&P 500 slips below 4,000.
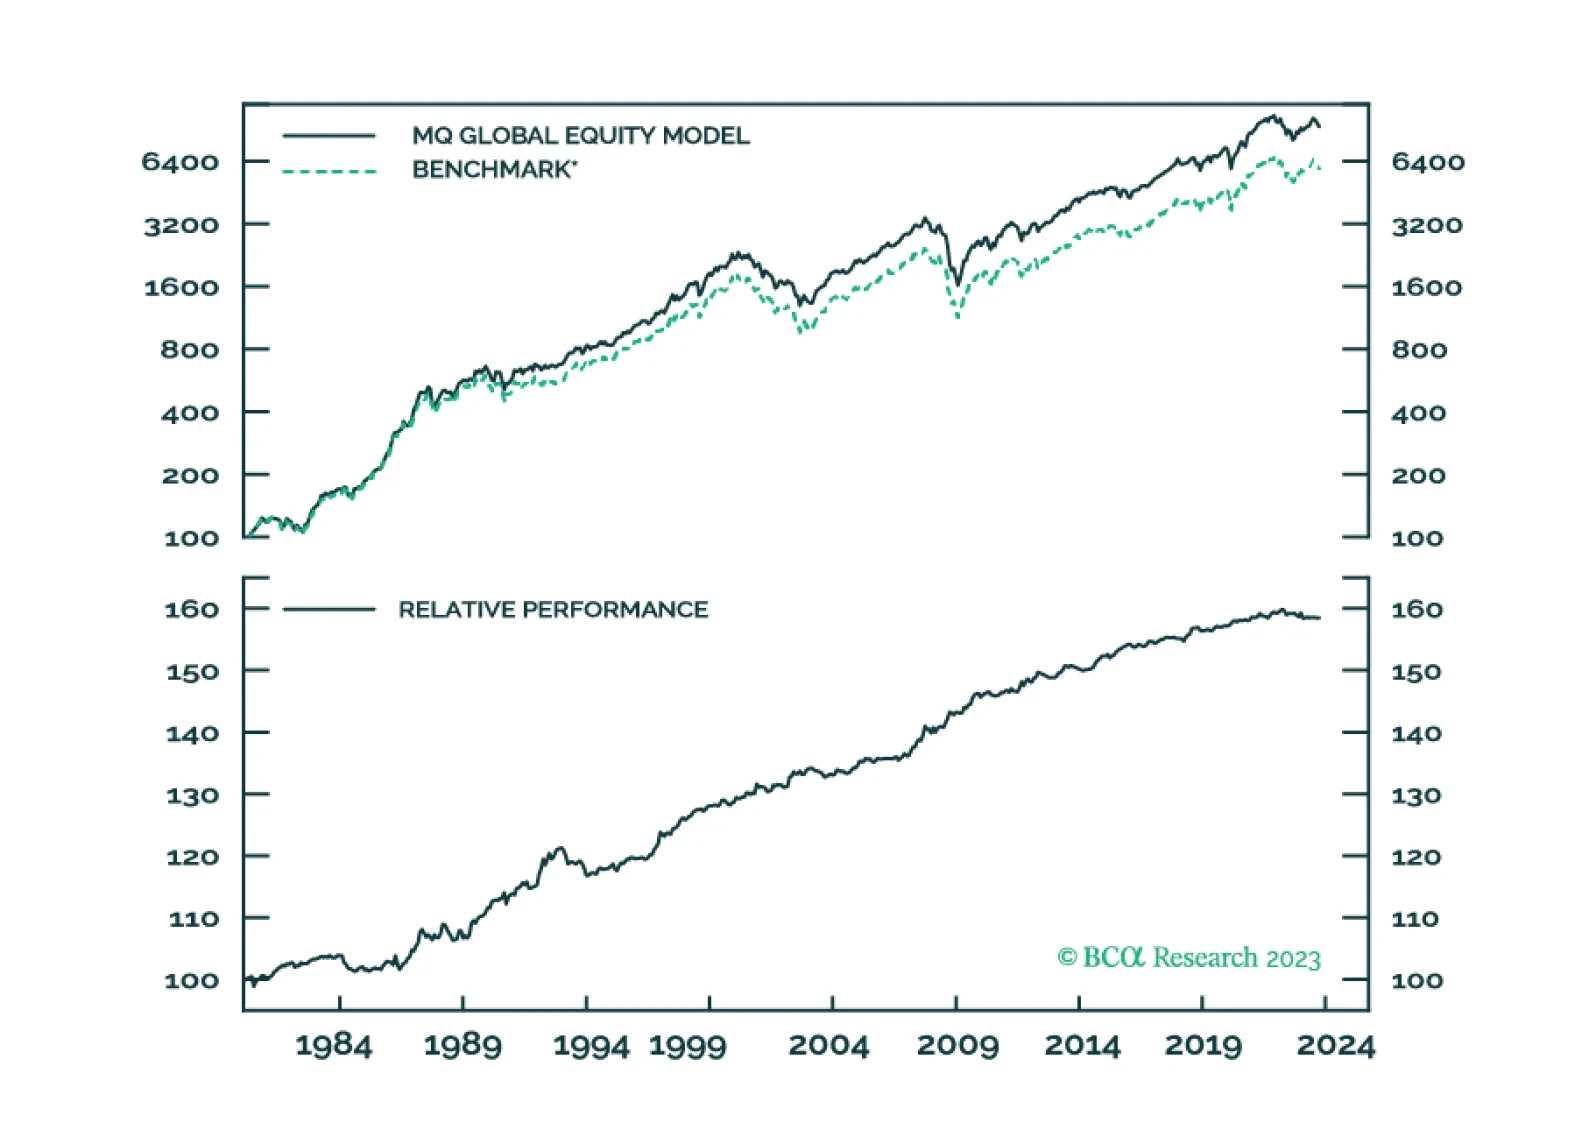
MacroQuant is holding a near neutral positioning with a slight tilt towards equities and bonds and away from cash.
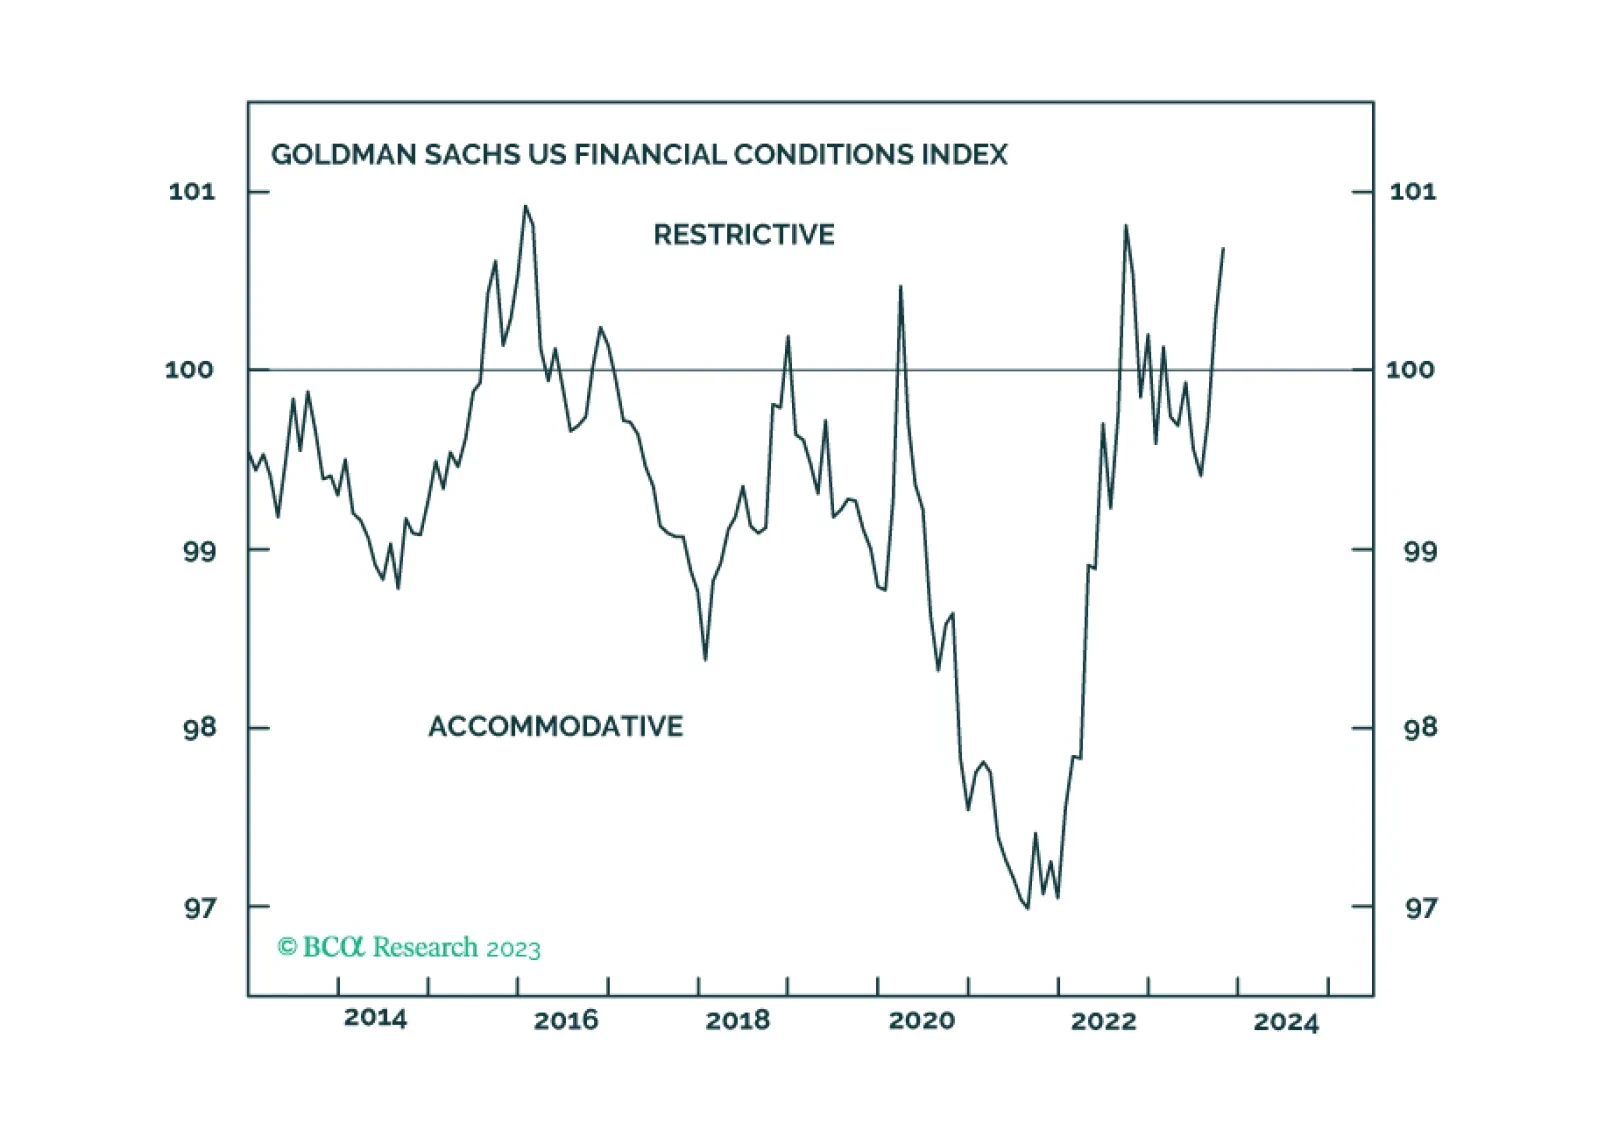
Our reaction to today’s FOMC meeting and the Treasury’s Quarterly Refunding Announcement.
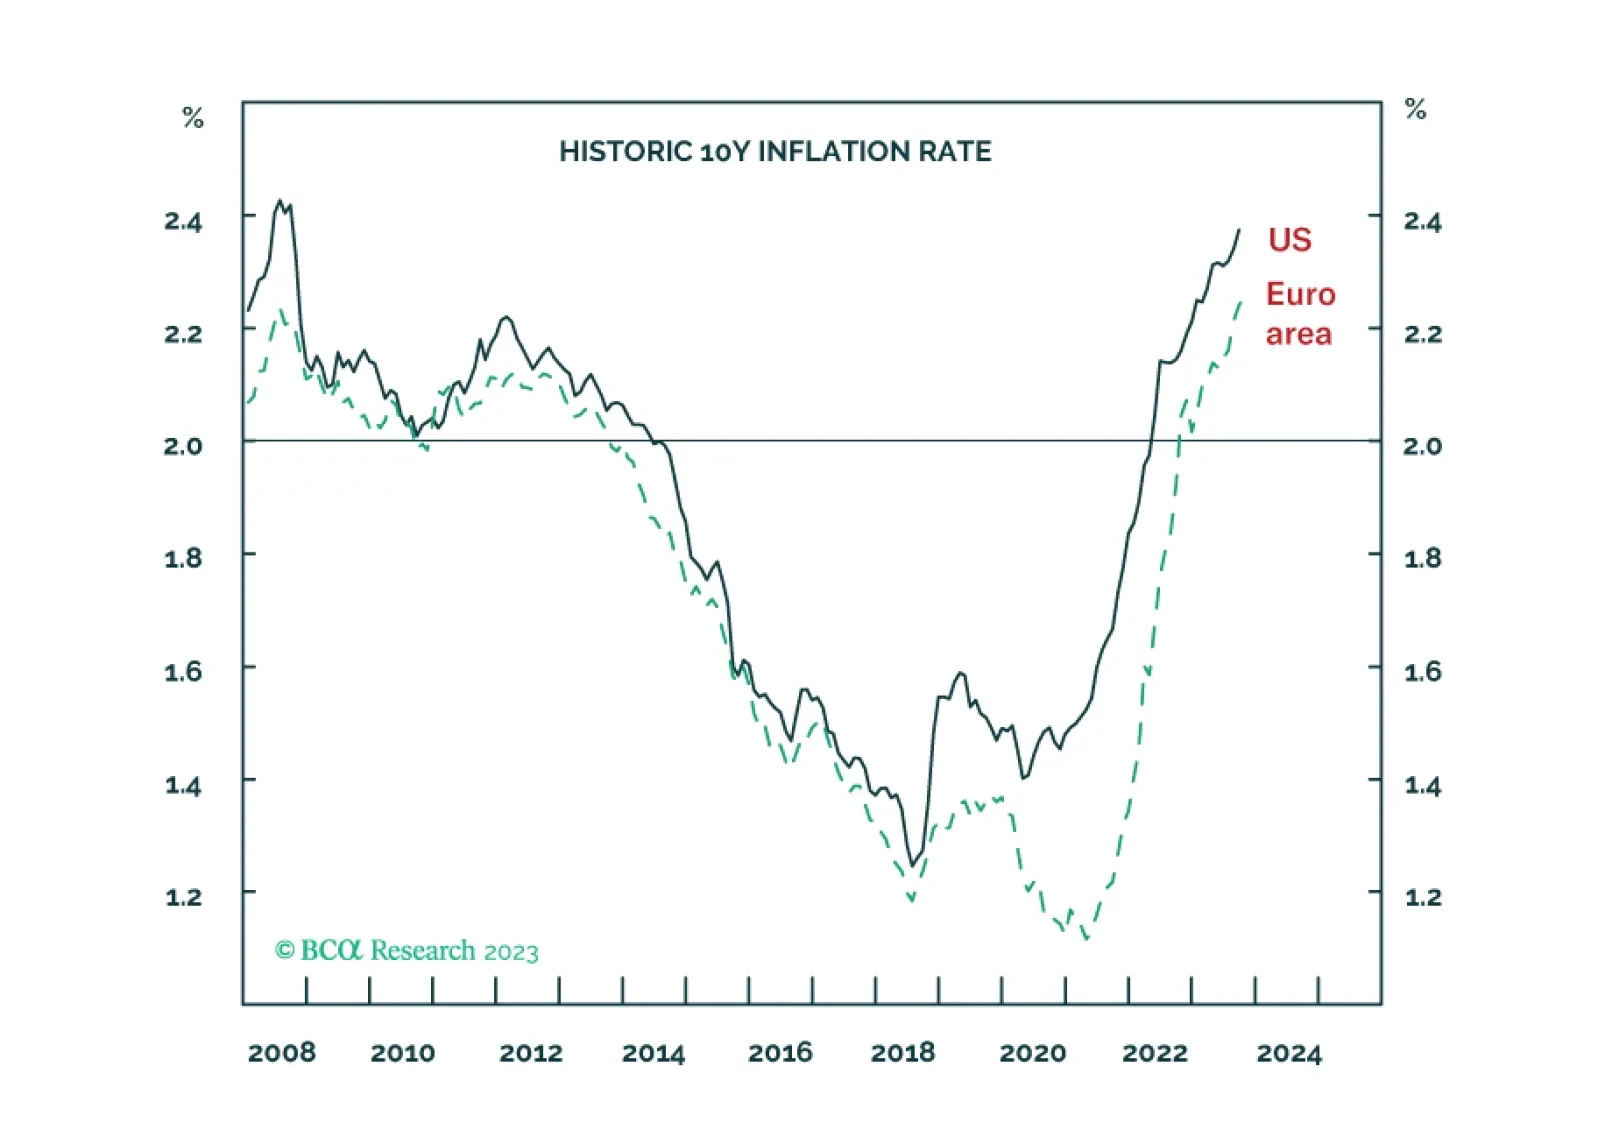
The fundamental component of long-term inflation expectations has climbed to its highest level since 2008 in both the US and the euro area. This means that both the Fed and the ECB will need to engineer inflation to undershoot 2 percent for an extended period if they are to maintain their 2 percent inflation targets. We explain what this means for investment strategy over the coming 6-12 months. Plus, we pinpoint what to focus on in this Friday’s US jobs report. And we identify food and beverages (PBJ) and the Indonesian rupiah (IDR/USD) as excellent rebound candidates.
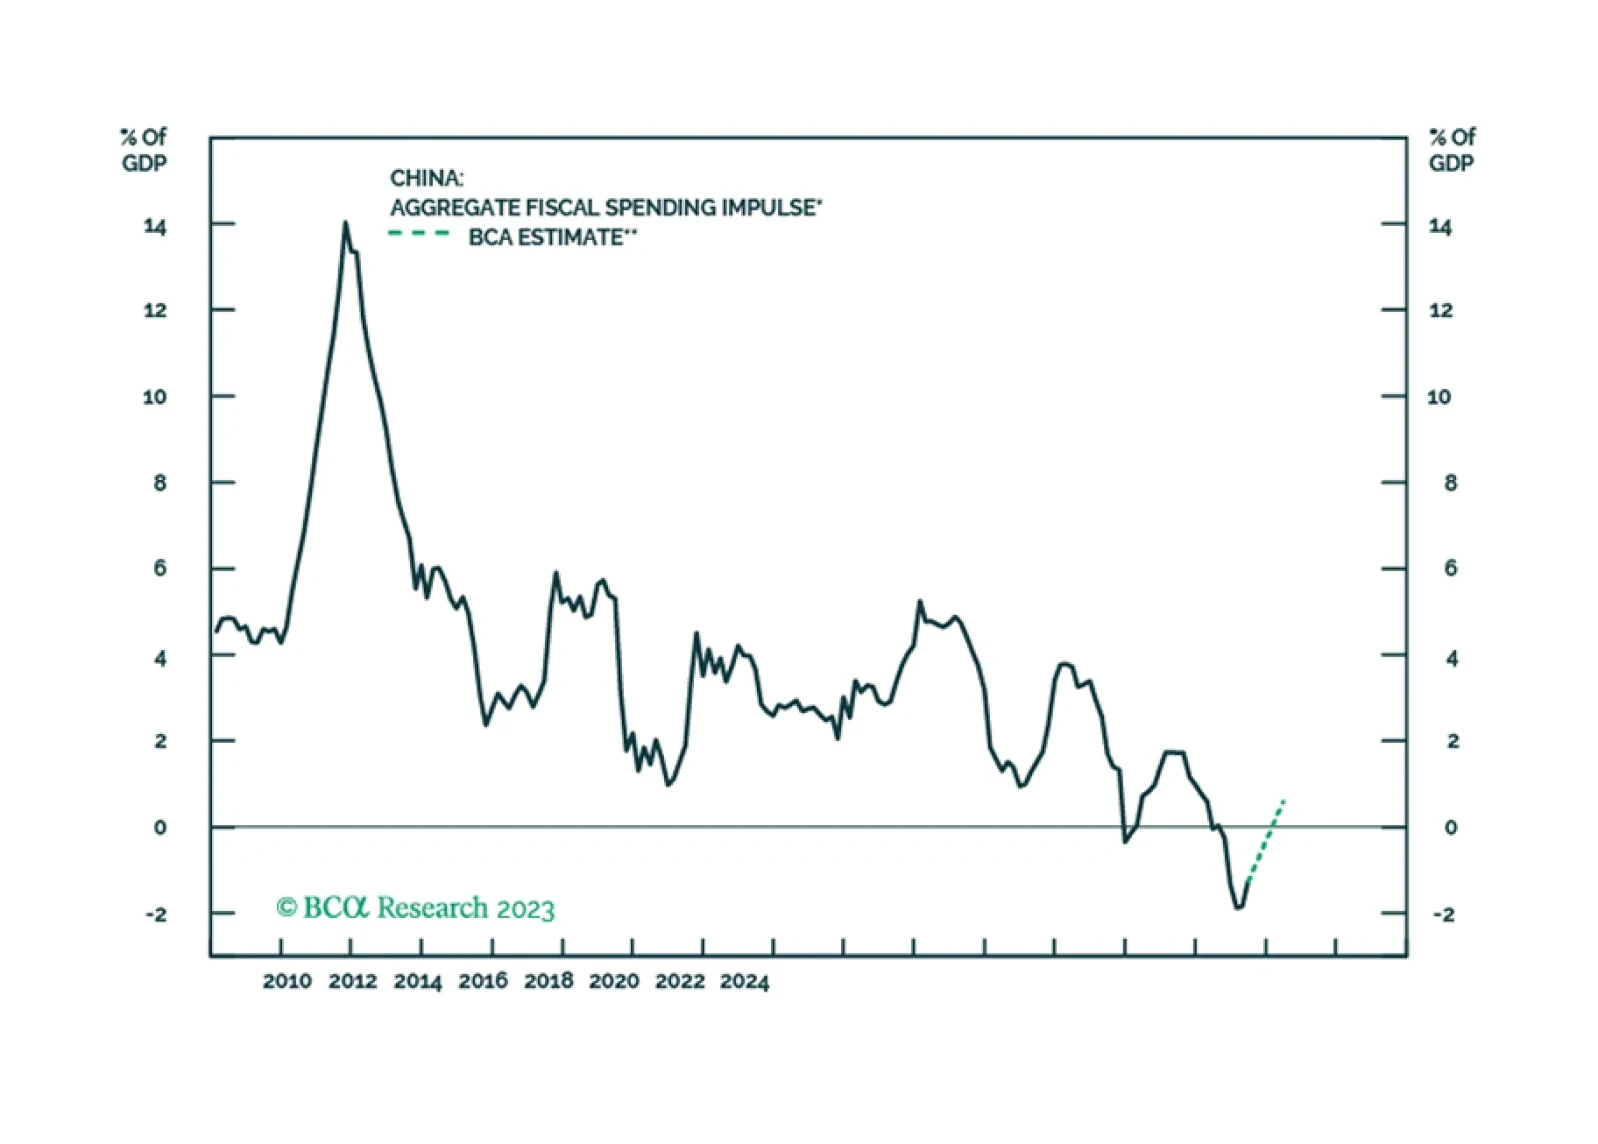
We maintain our view that China’s economic growth in the coming months will remain lackluster. Beijing's recent measures to provide additional financing may help to bridge the gap in government spending in the rest of 2023 and into 2024, but the impact on growth will be very limited.