Latest from BCA Research
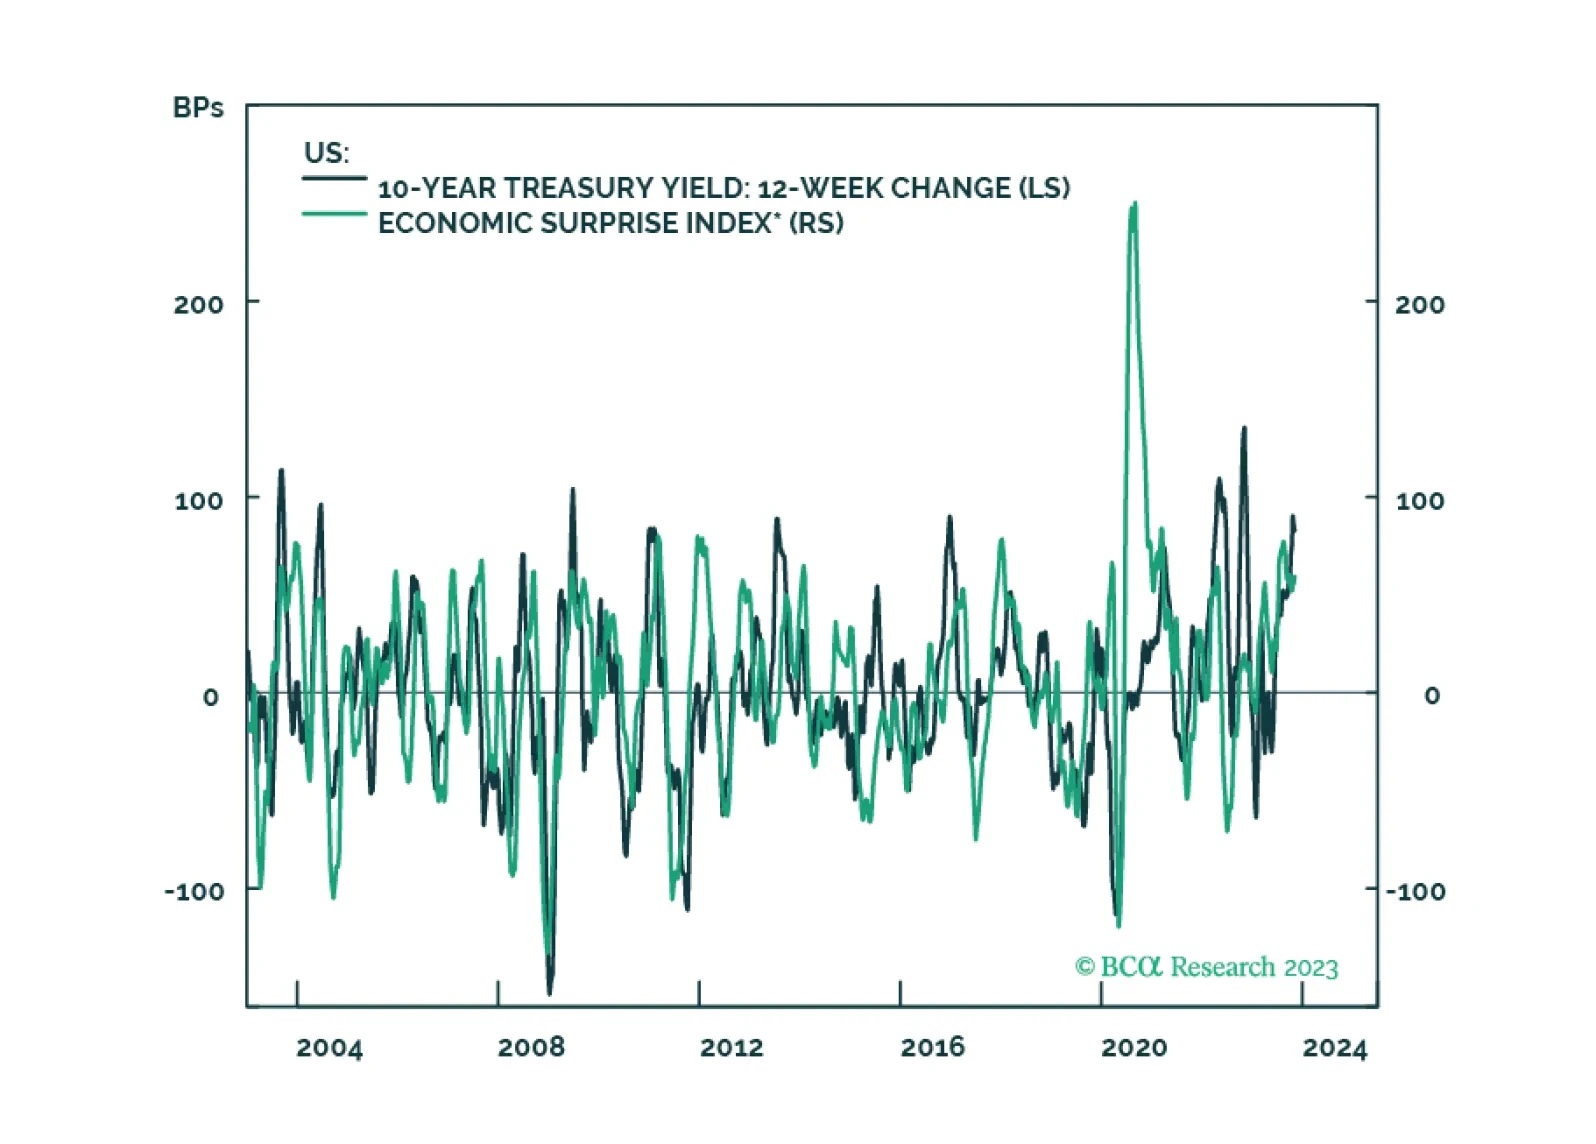
High interest rates will eventually cause growth to slow. Signs of stress are already starting to show. Stay cautiously positioned.
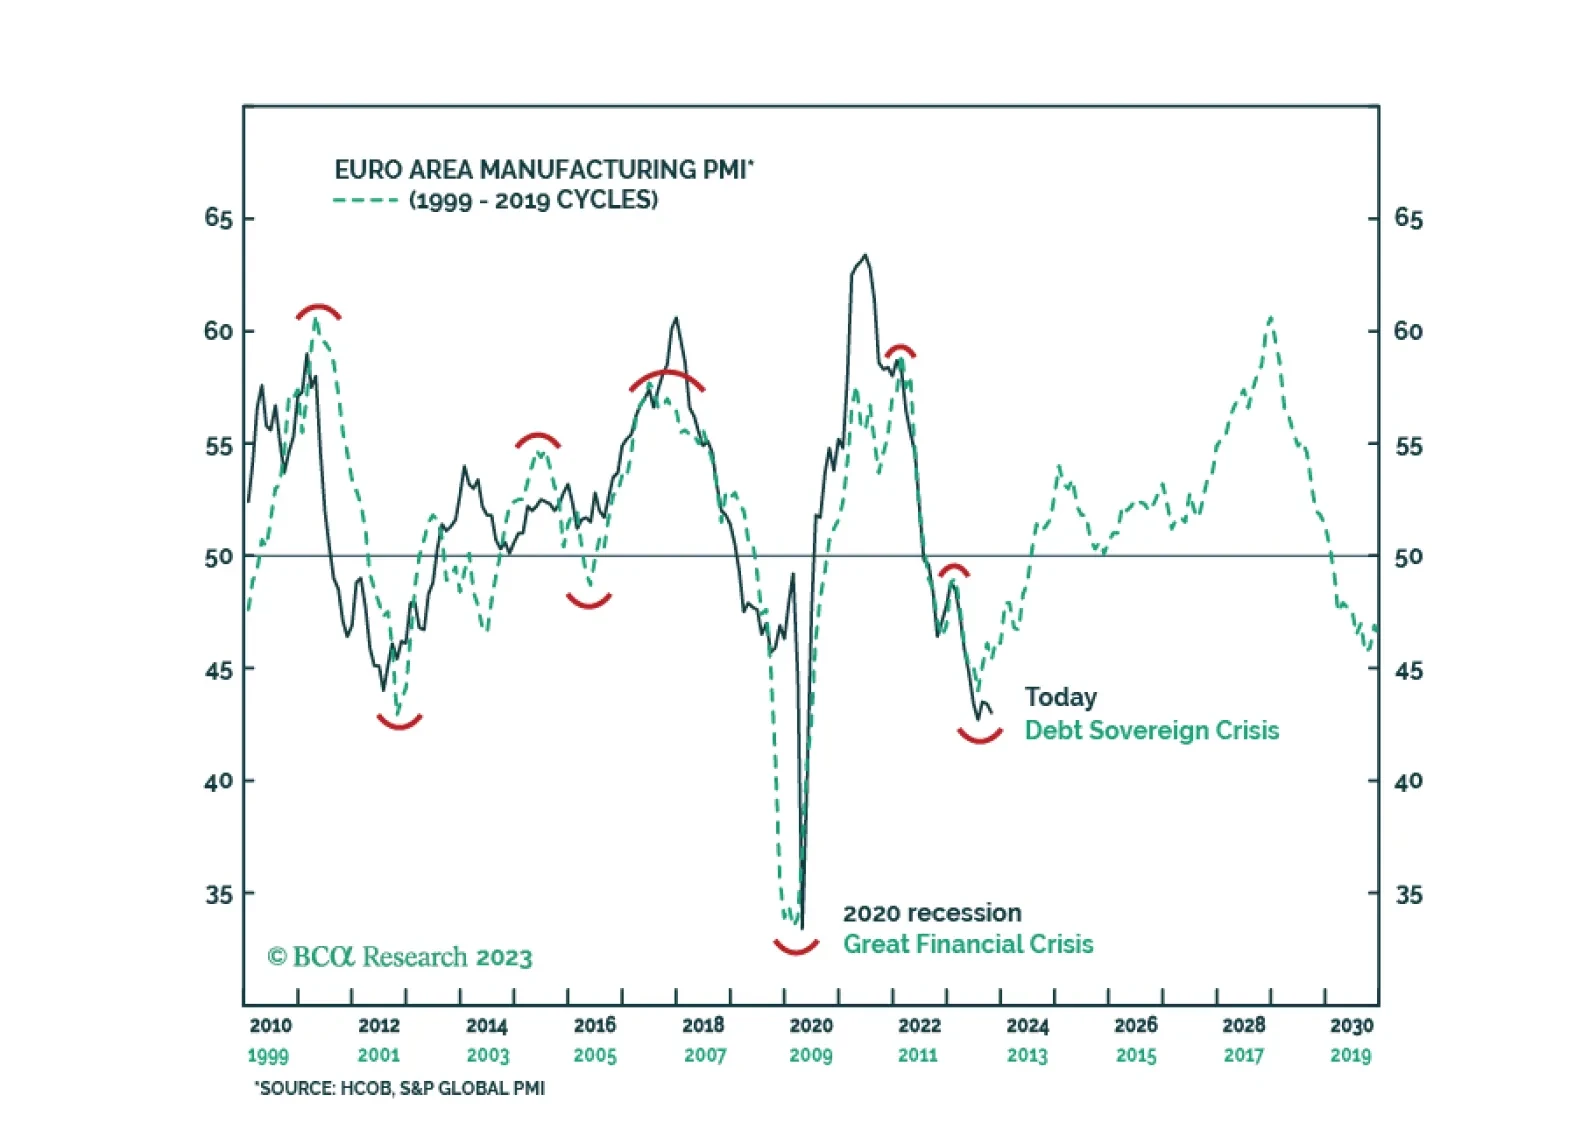
What will the next manufacturing cycle look like in Europe and how will risk assets perform? Lessons from the recent past.
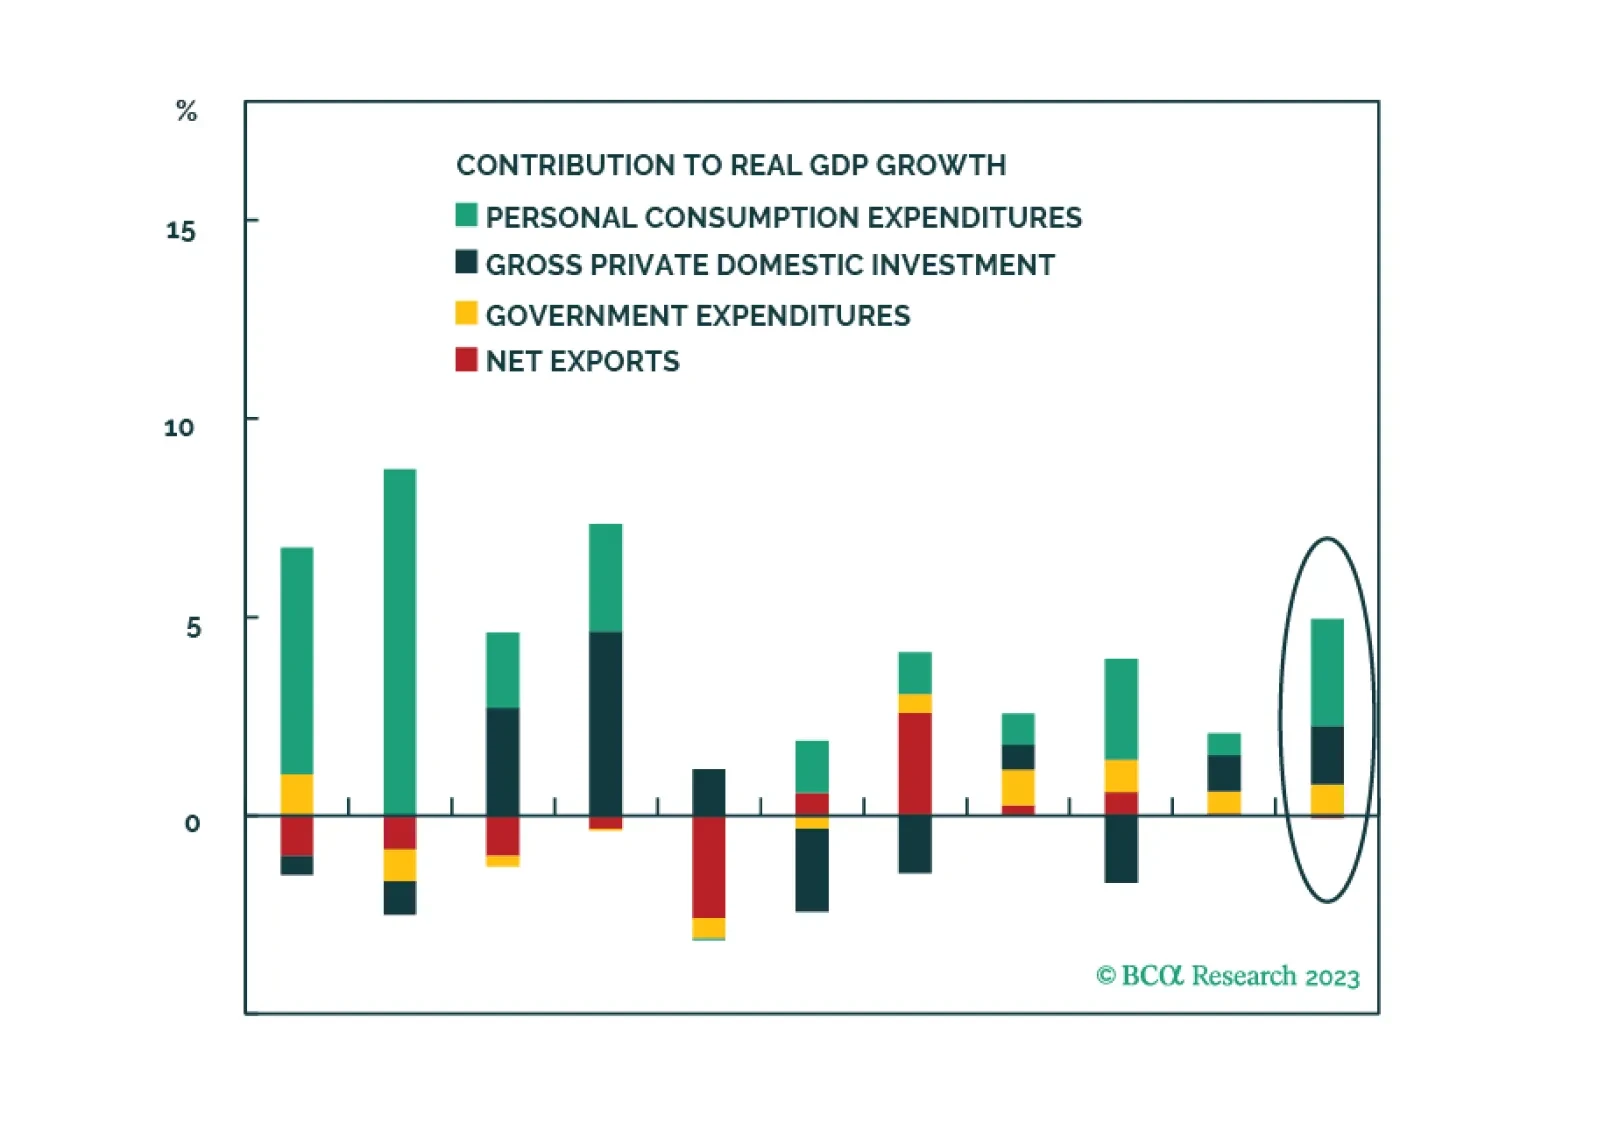
Stronger US growth elicits a response from the House Republicans. But a government shutdown is not devastating to the economy. What is more devastating would be a crisis in the Middle East, Europe, and Asia. Stay long US defense, energy, and large caps stocks.
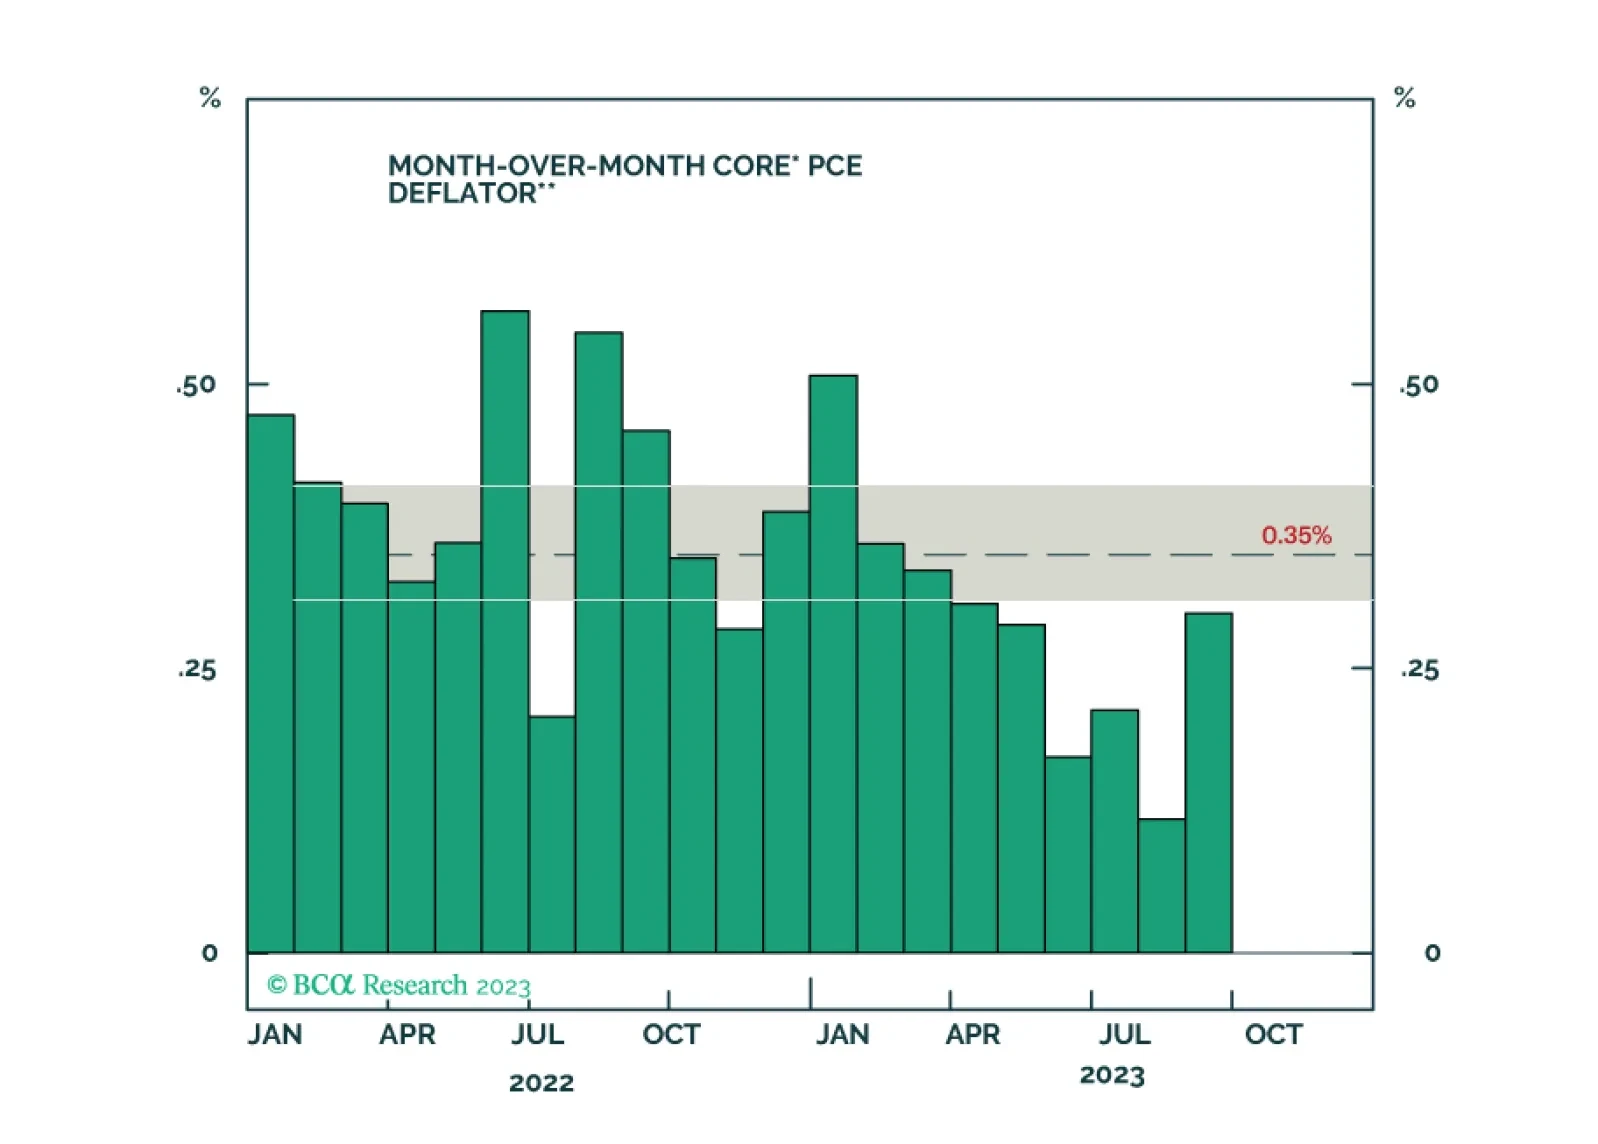
A look at recent data on economic growth, inflation and the labor market, and a discussion of the implications for Fed policy and bond strategy.
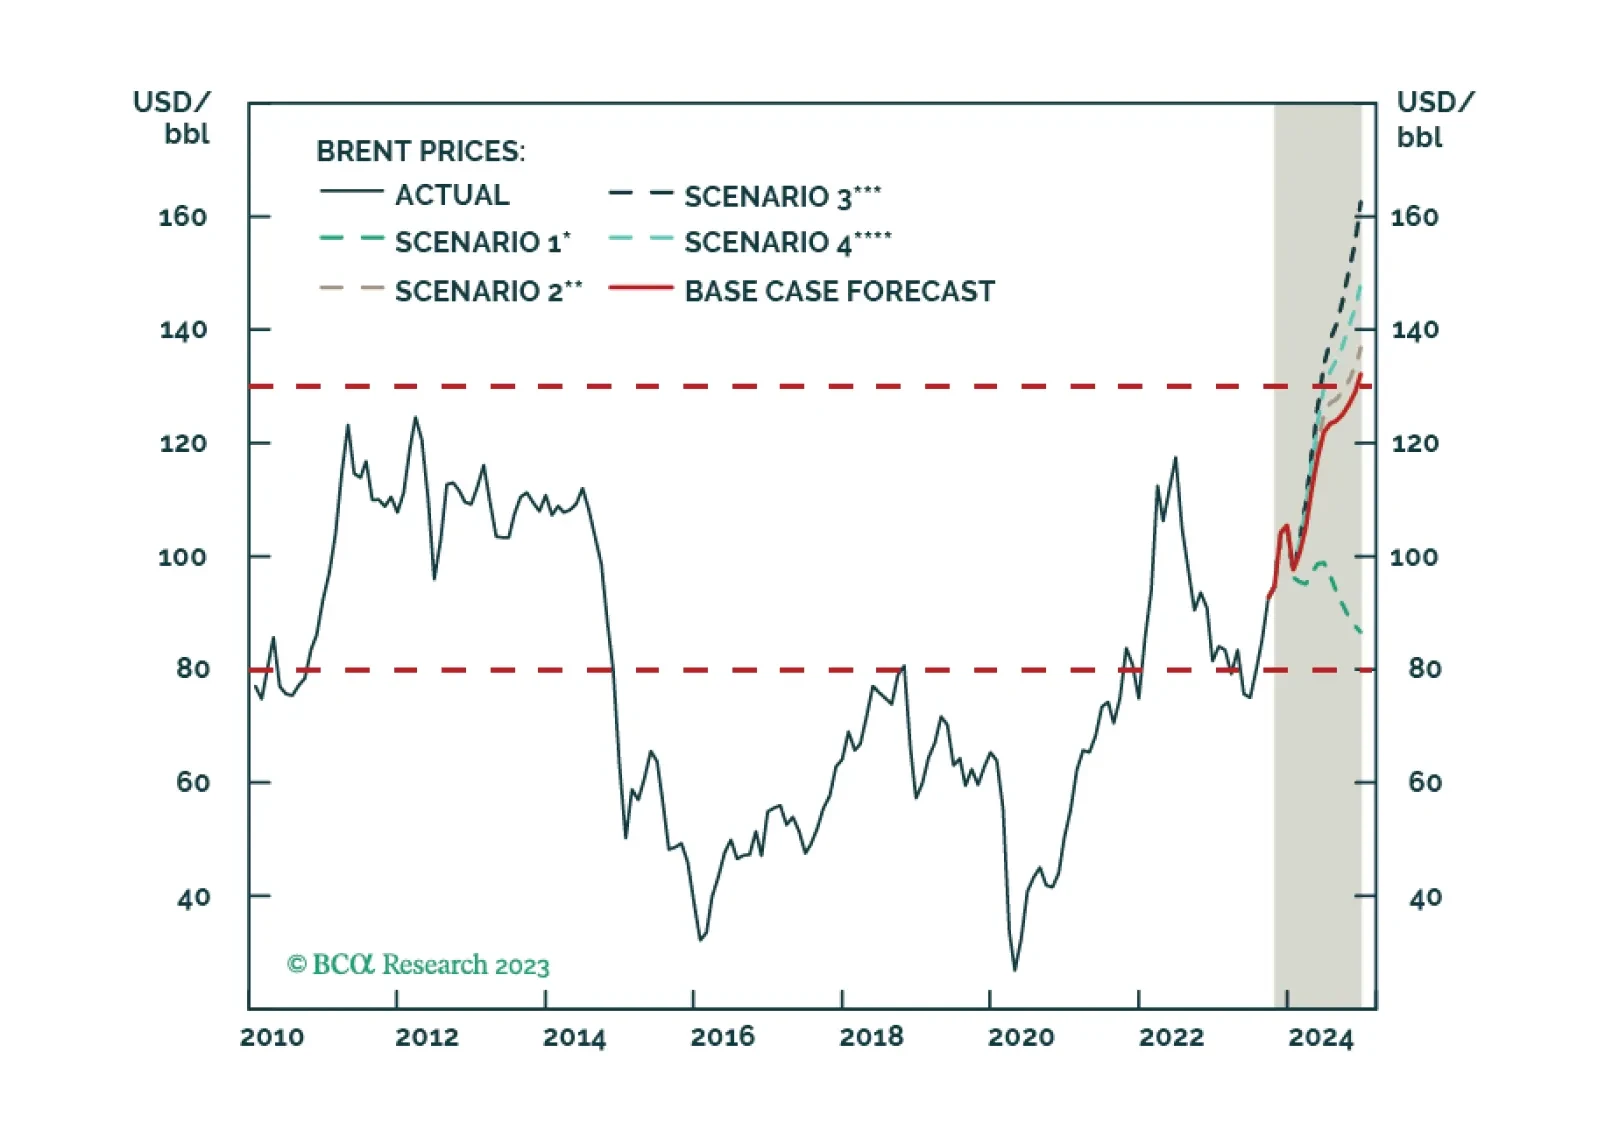
The US and core OPEC 2.0 are – wittingly or not – laying the groundwork for a price band with a floor and cap on oil prices – at $79/bbl and $130/bbl, respectively – “at least” to May 2024. This accommodates multiple goals for both. To meaningfully support policy, the US would need to scale up purchases to refill its SPR. We remain long the XOP and COMT ETFs for direct exposure to energy E+P equities and commodities.
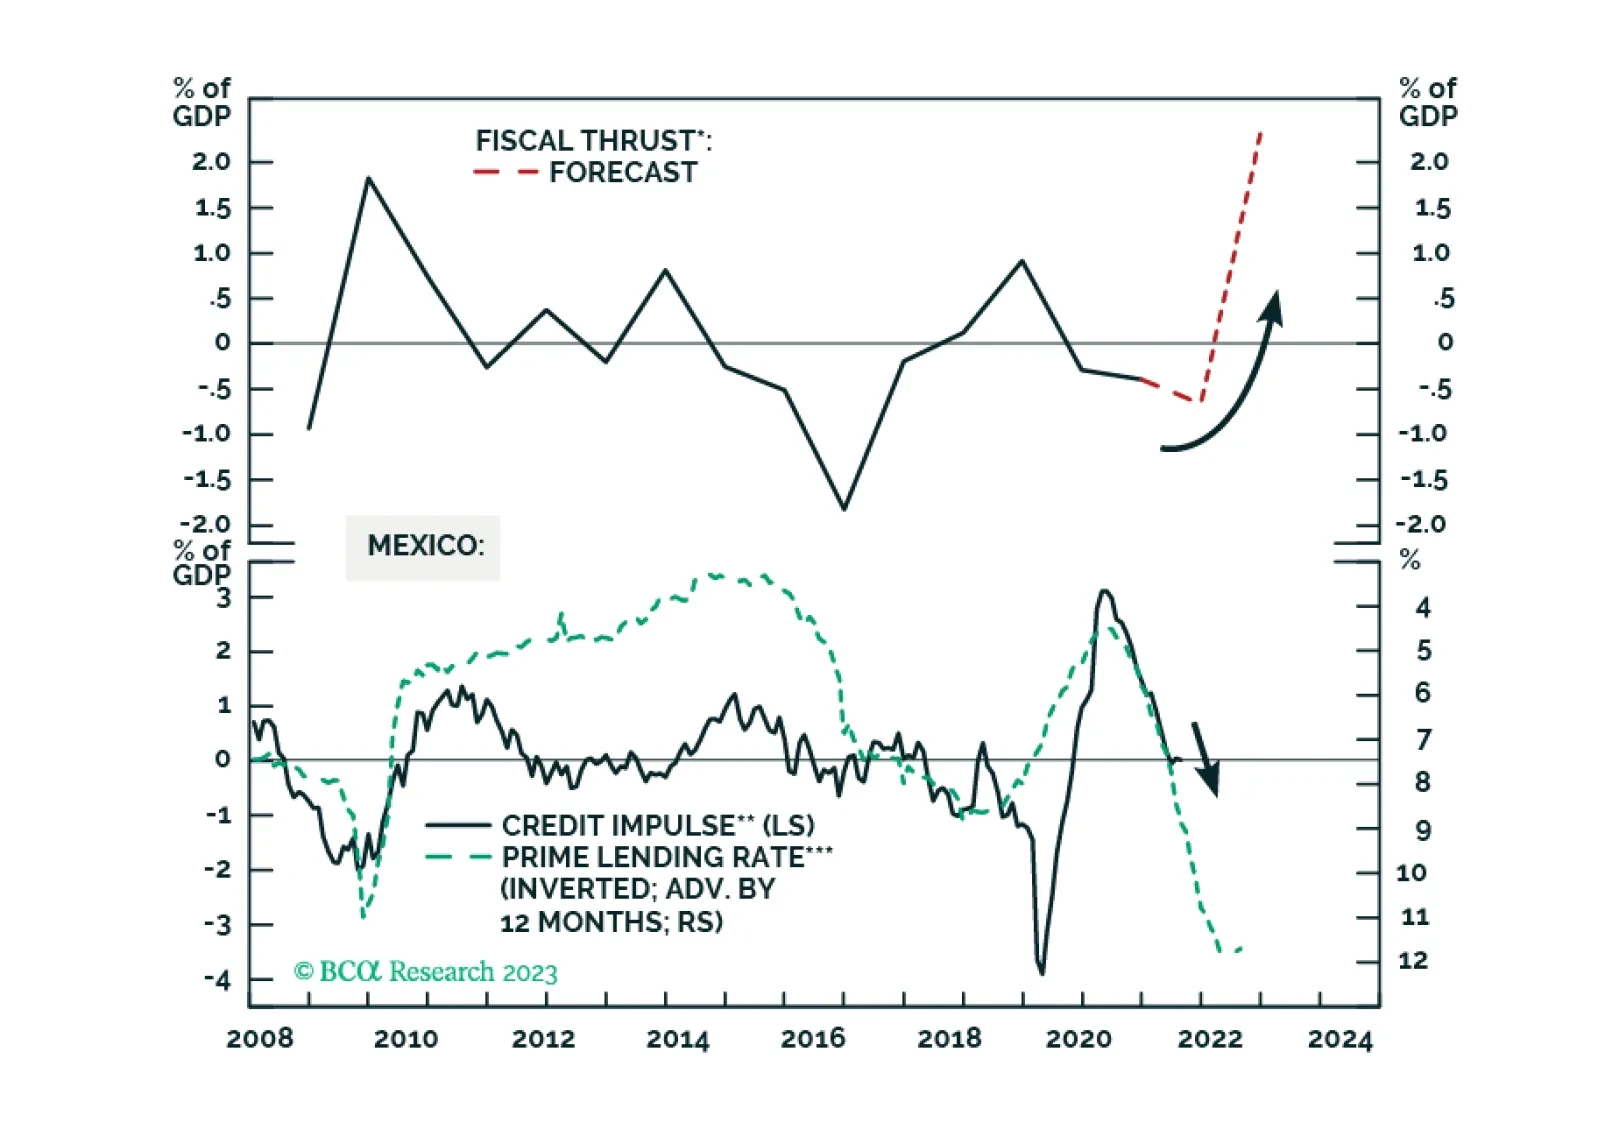
While Mexican markets will continue selling off in absolute terms, their recent underperformance versus their EM peers is a temporary setback in a cyclical and structural bull market. Domestic politics are evolving from stable to bullish: the new president will rule in a technocratic manner, respecting private sector interests. The Mexican economy will achieve a soft landing even if the US enters a recession.