Skip to main content

Latest from BCA Research
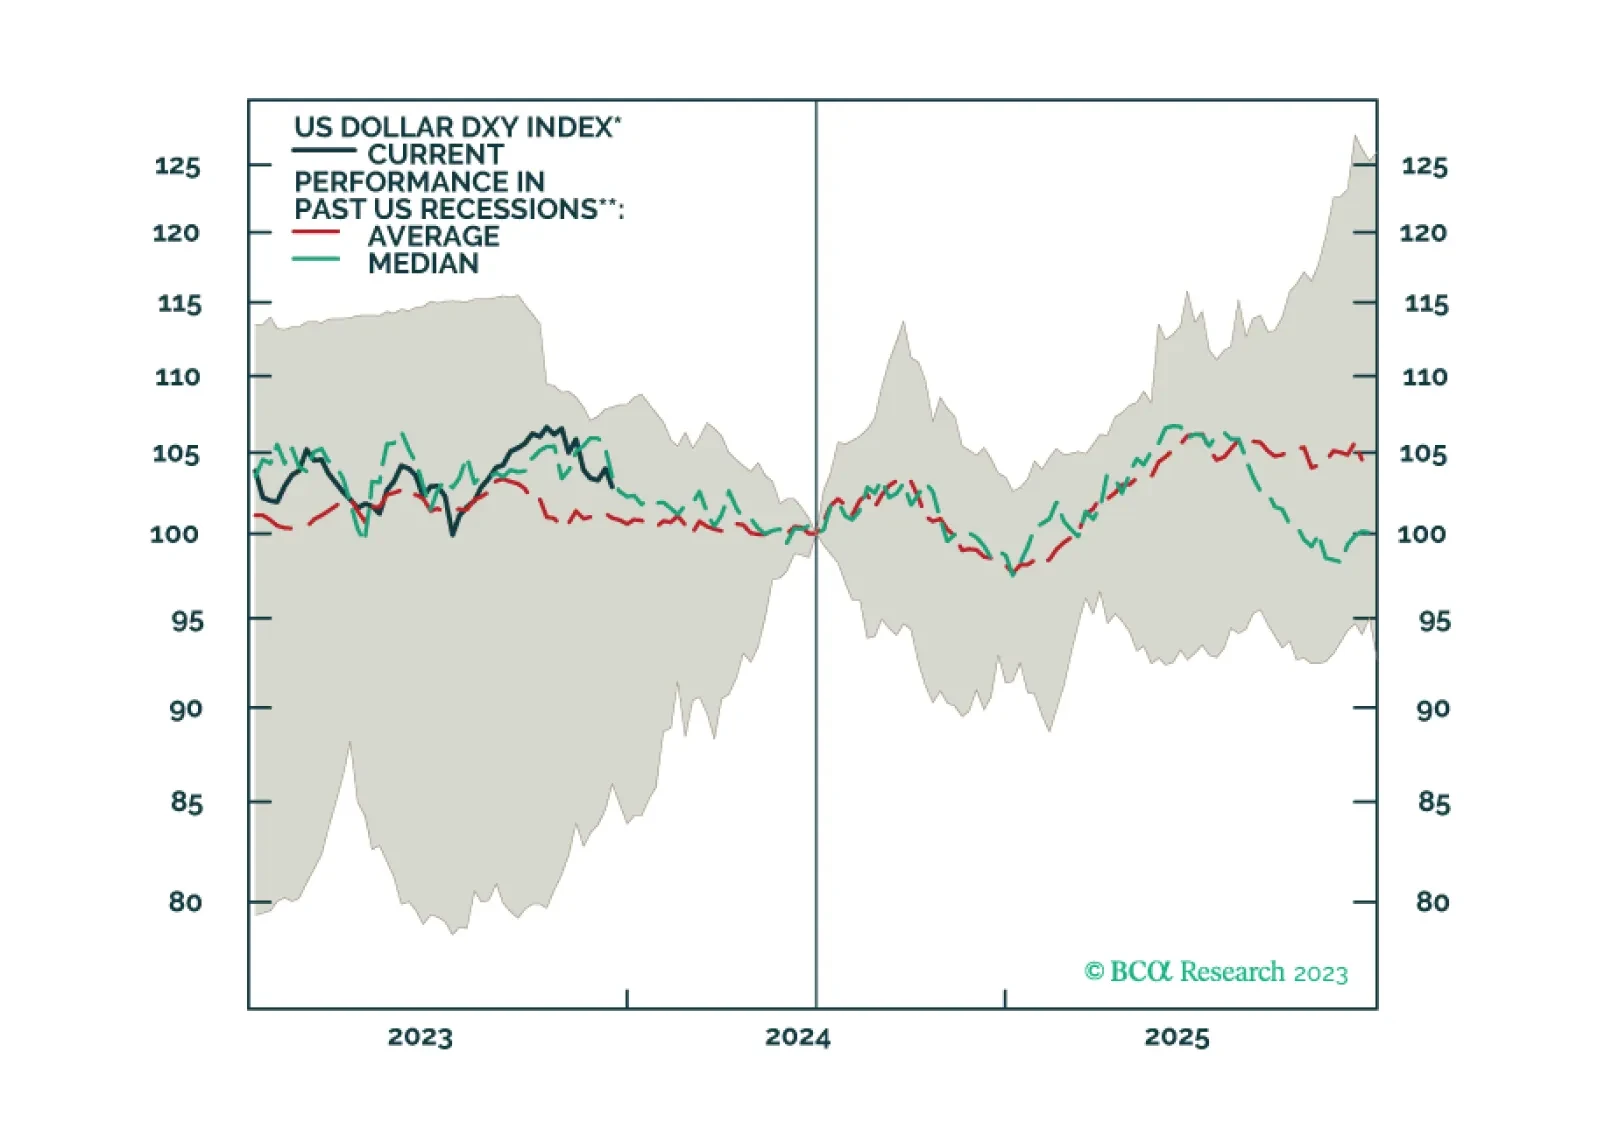
Special Report In this week’s report, we present our dollar view for 2024 and beyond, with a few trade ideas.
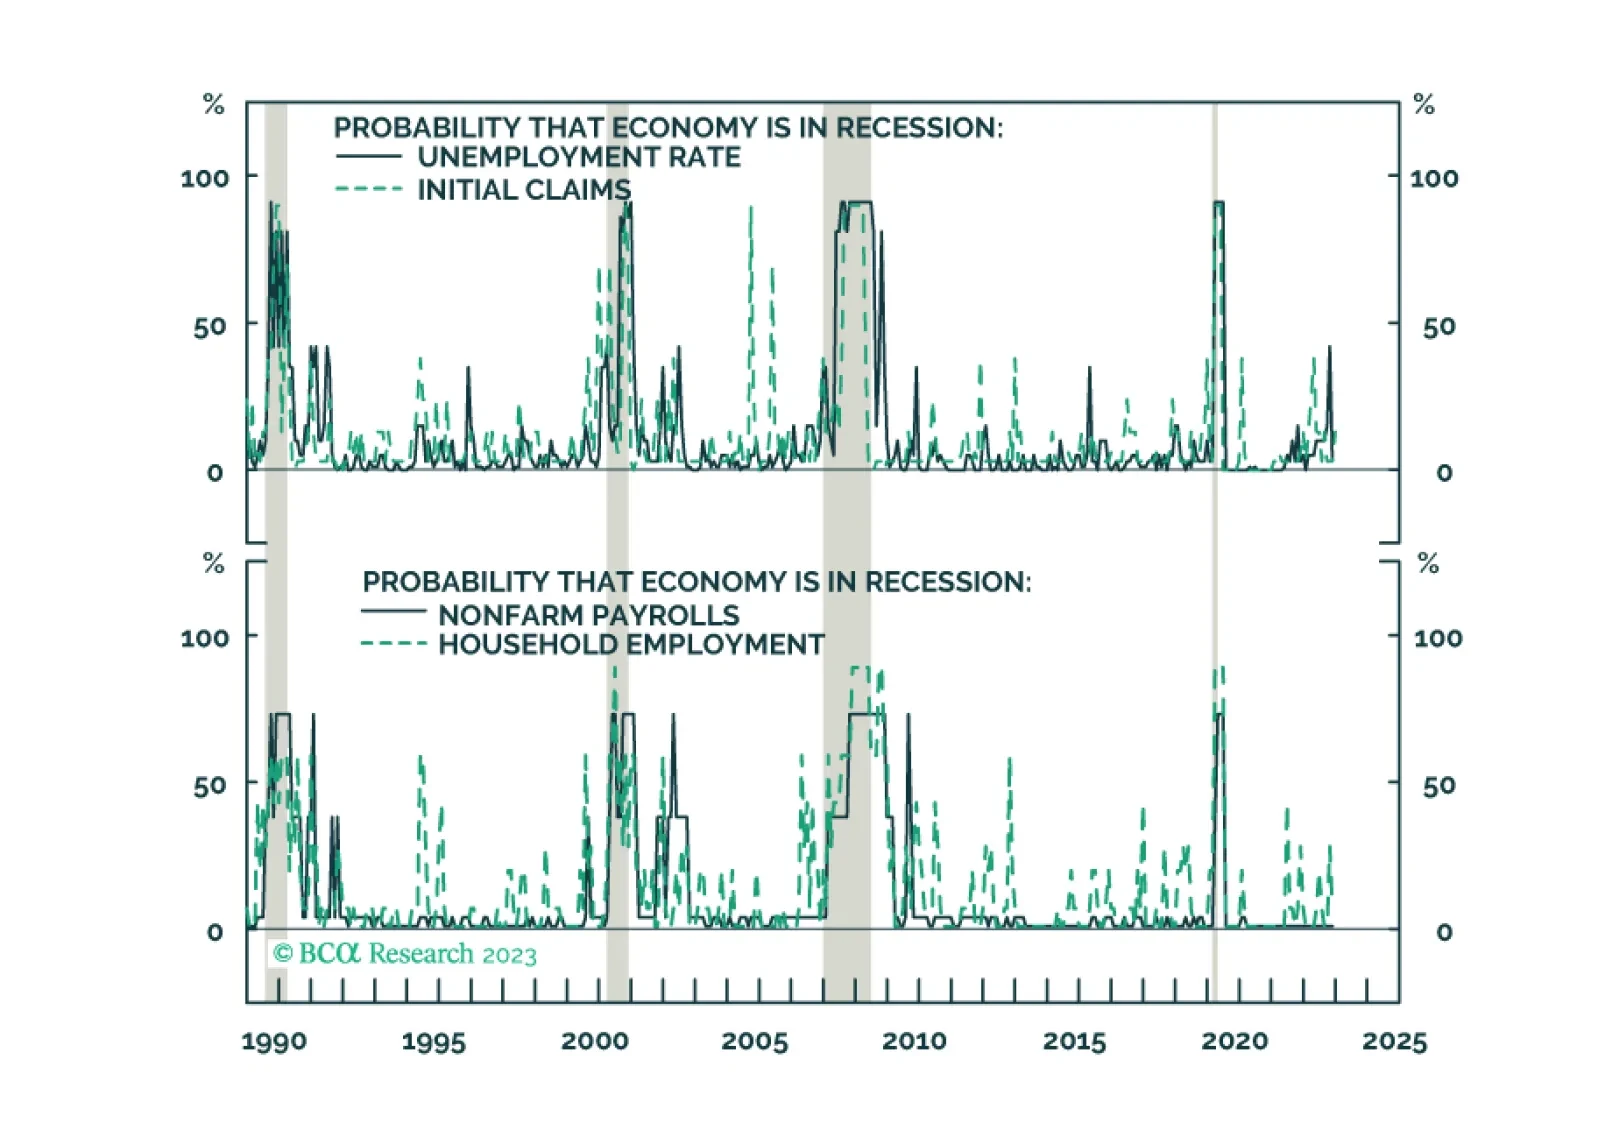
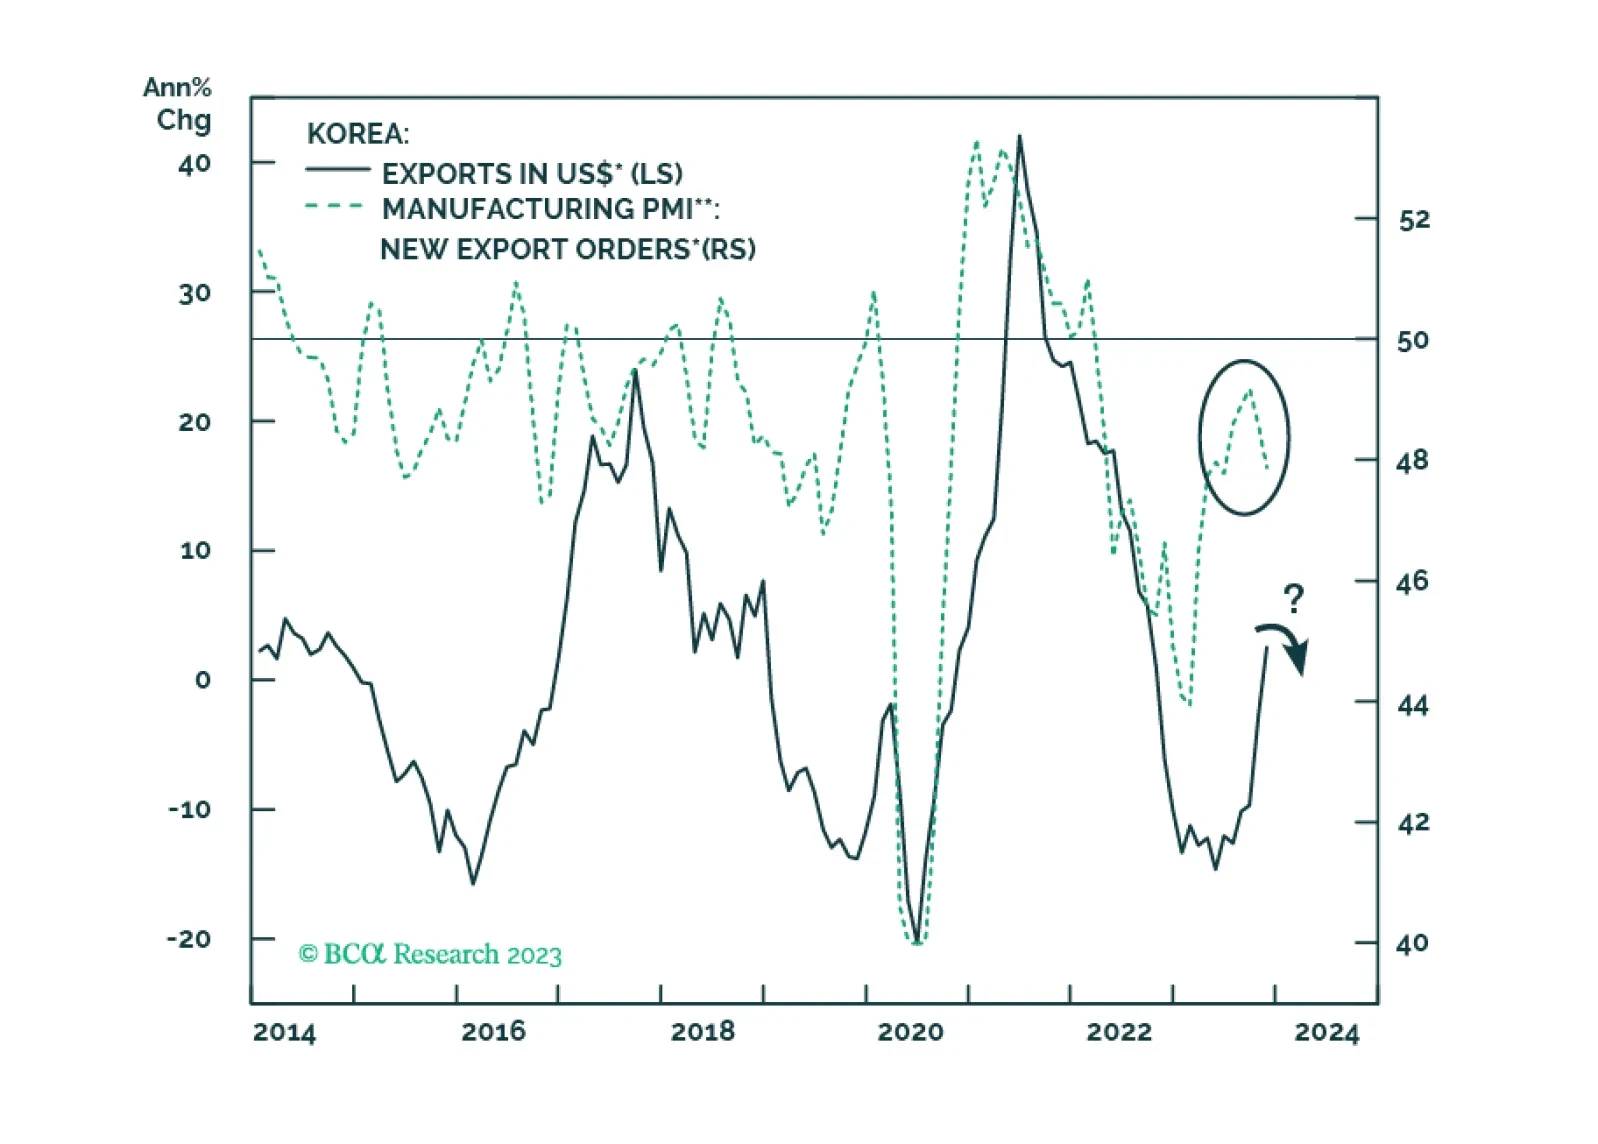
Special Report The major question facing EM investors in 2024 is whether or not EM will cross the Rubicon. The path to a soft landing in the US remains elusive. The recent improvement in global manufacturing/trade will likely prove to be a mid-cycle bounce rather than the beginning of a cyclical recovery.
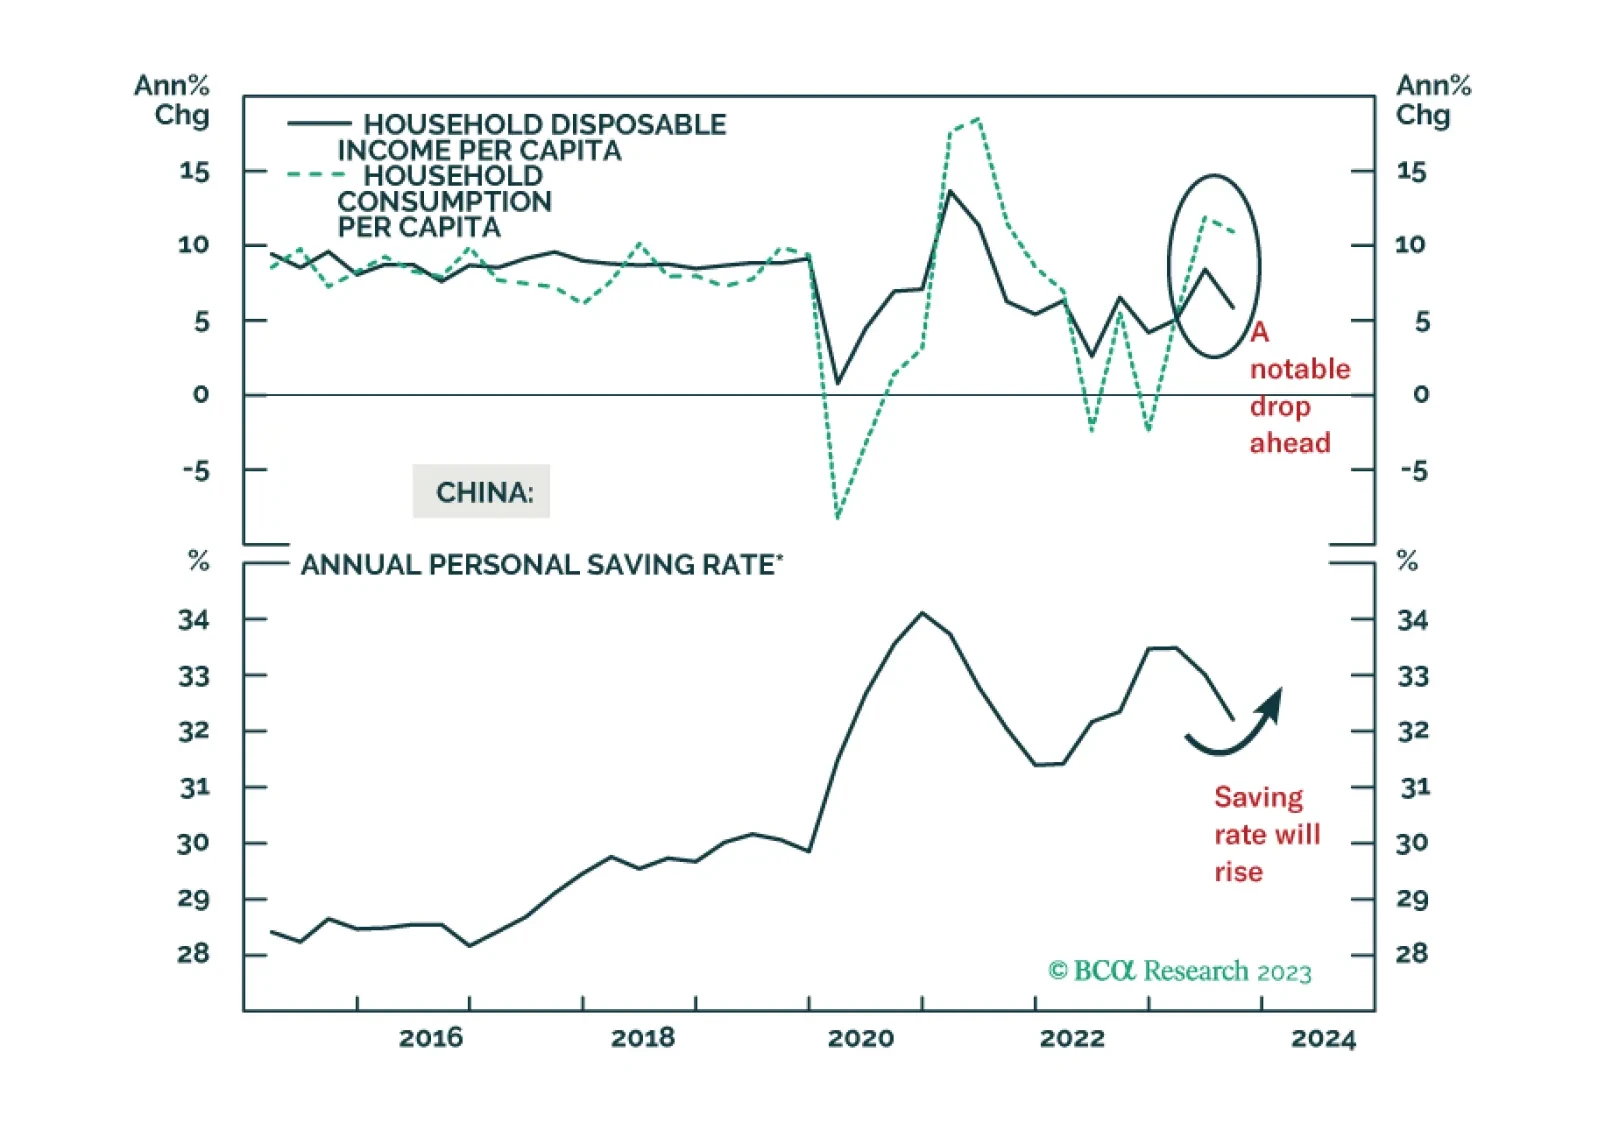
Special Report Nominal household spending growth in China will slow in 2024. Strong headwinds will arise from a slower household income expansion, falling house prices, a downbeat employment outlook, and shrinking exports. Spending on healthcare services will post solid gains but durable goods consumption will experience anemic growth in 2024. We favor consumer staples and healthcare stocks versus the domestic benchmark.
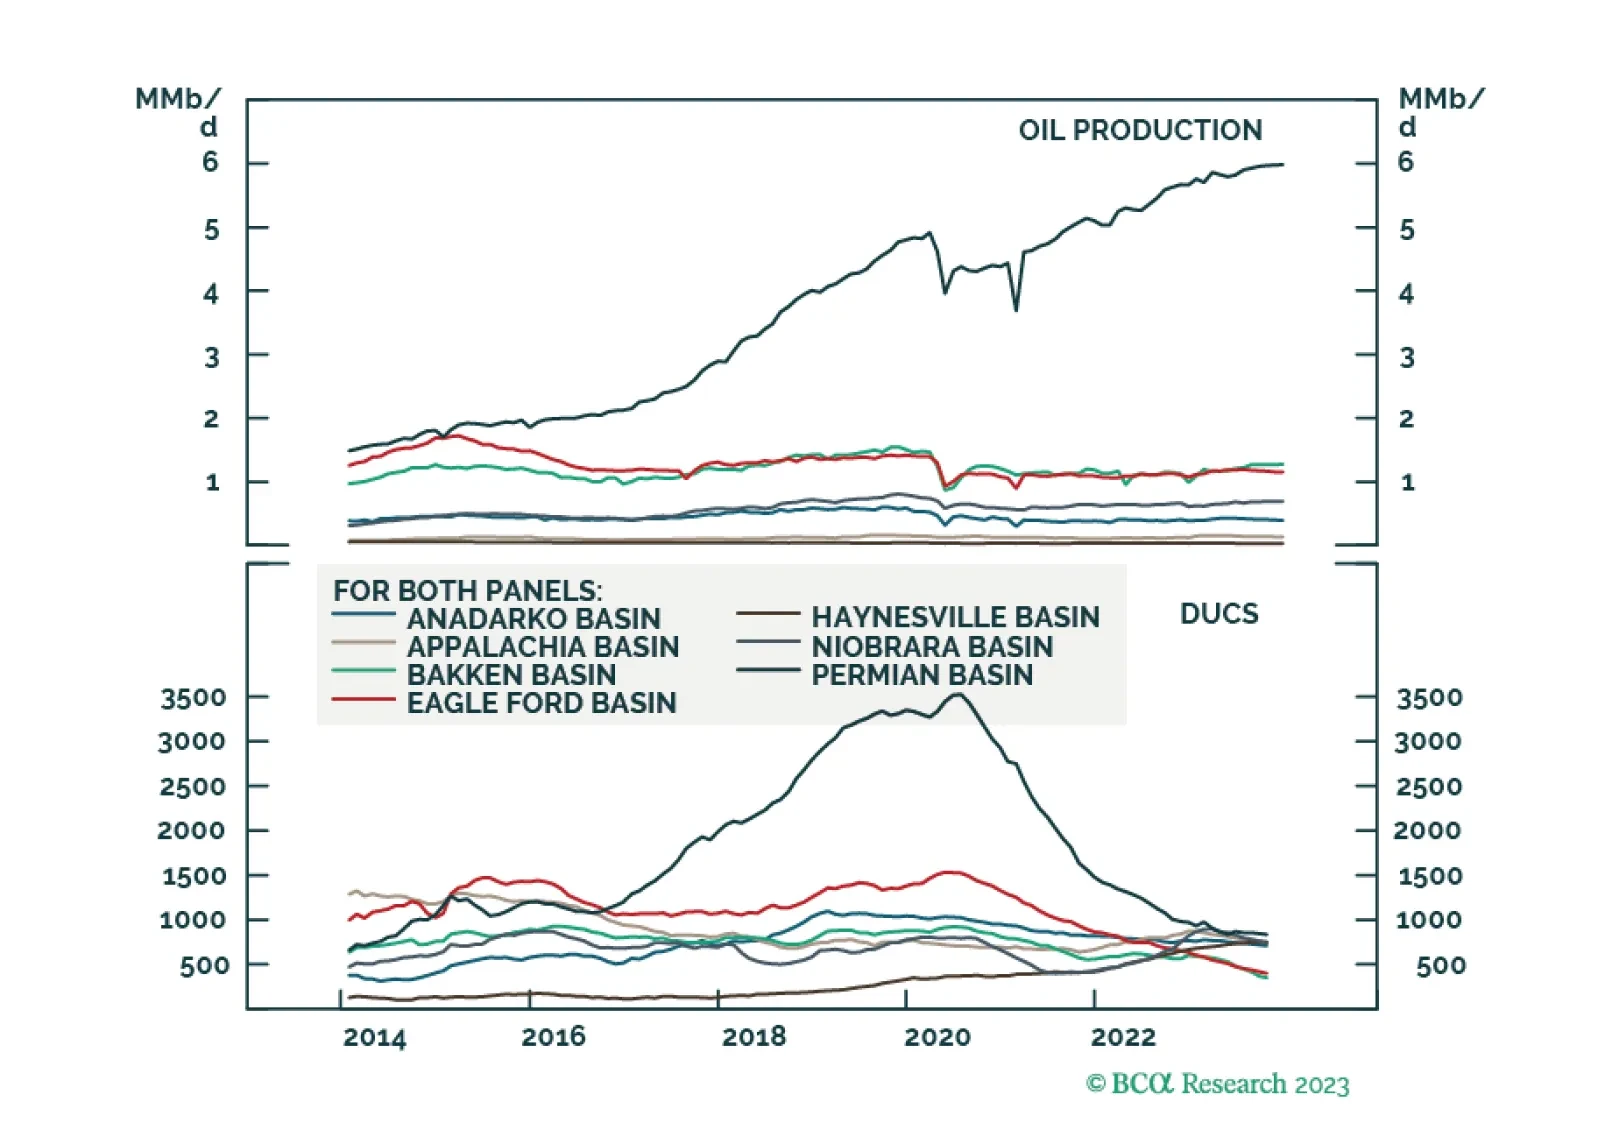
Special Report Political economy dominates fundamentals going into 2024, as states prepare for war and de-risk supply chains. Asynchronous global growth will elevate commodity-price volatility. We expect oil to trade above $100/bbl in 2024 and continue to favor equity exposure to oil-and-gas producers. Given weak capex, we also favor metals miners and refiners. We remain long the Gold, the XME and COMT ETFs We were stopped out of our XOP ETF with a 12.5% gain; we will re-establish it at tonight’s close.
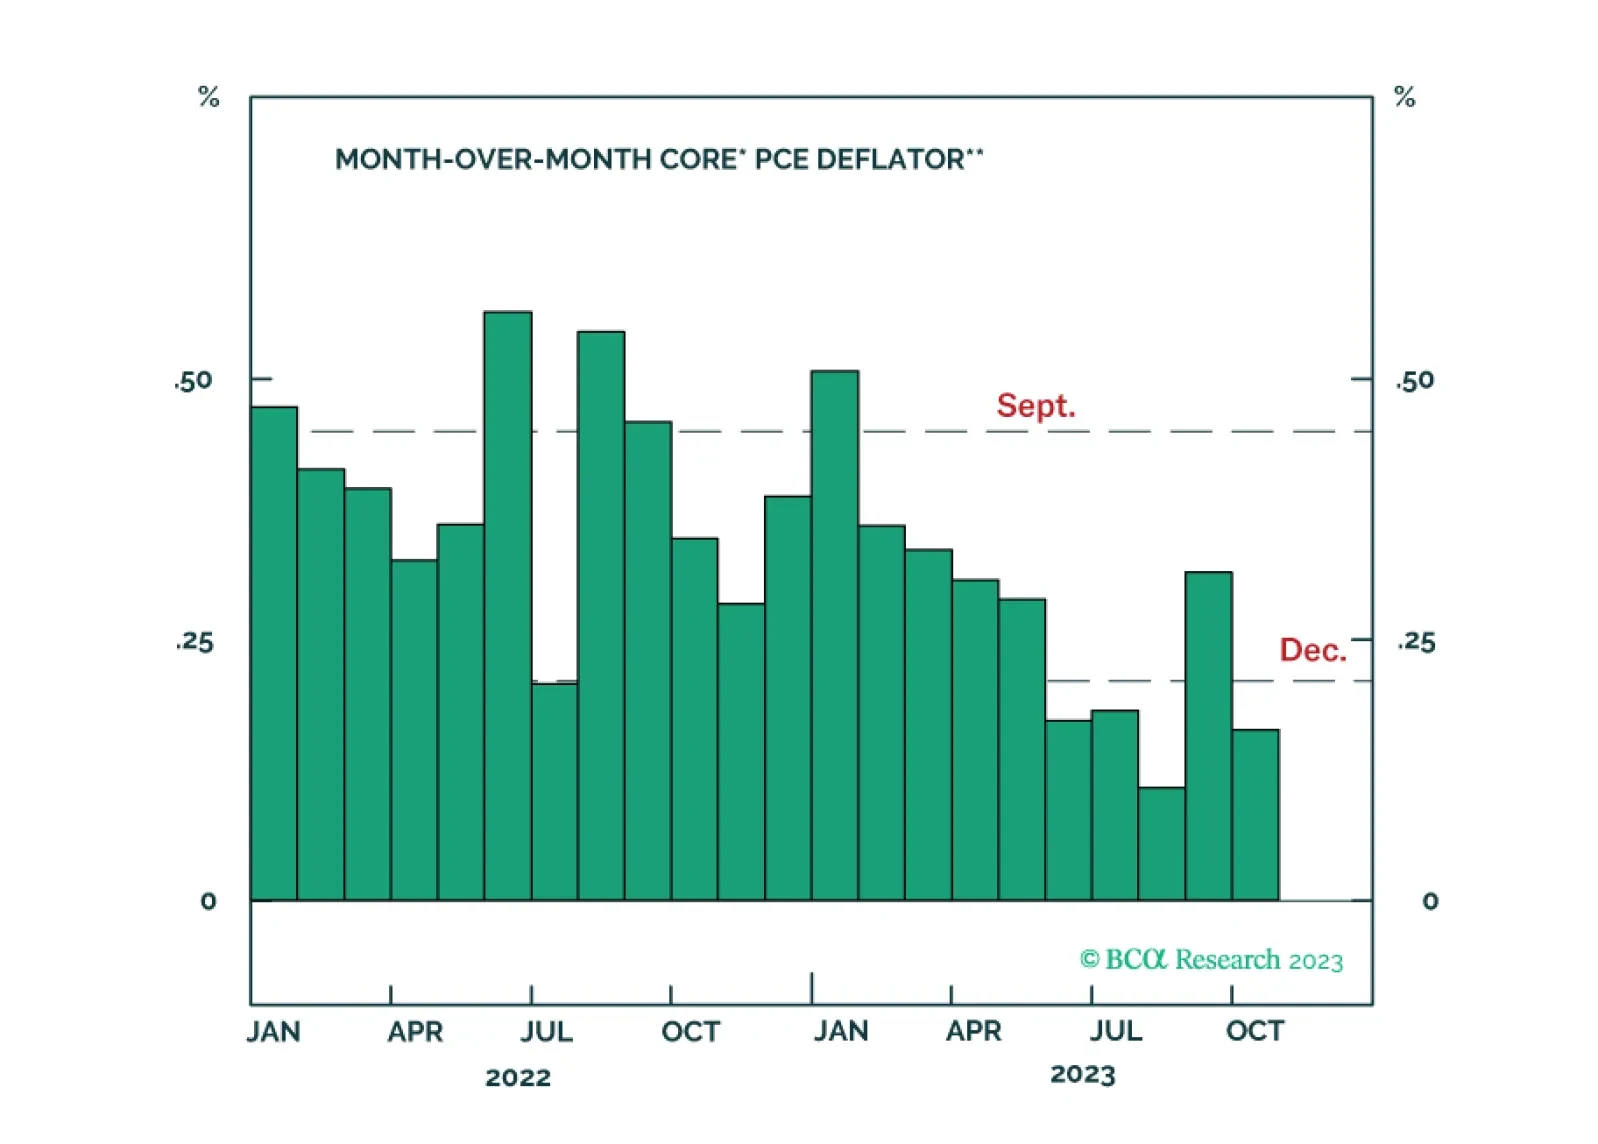
Our US bond team’s thoughts on this afternoon’s FOMC meeting and yesterday’s CPI release.
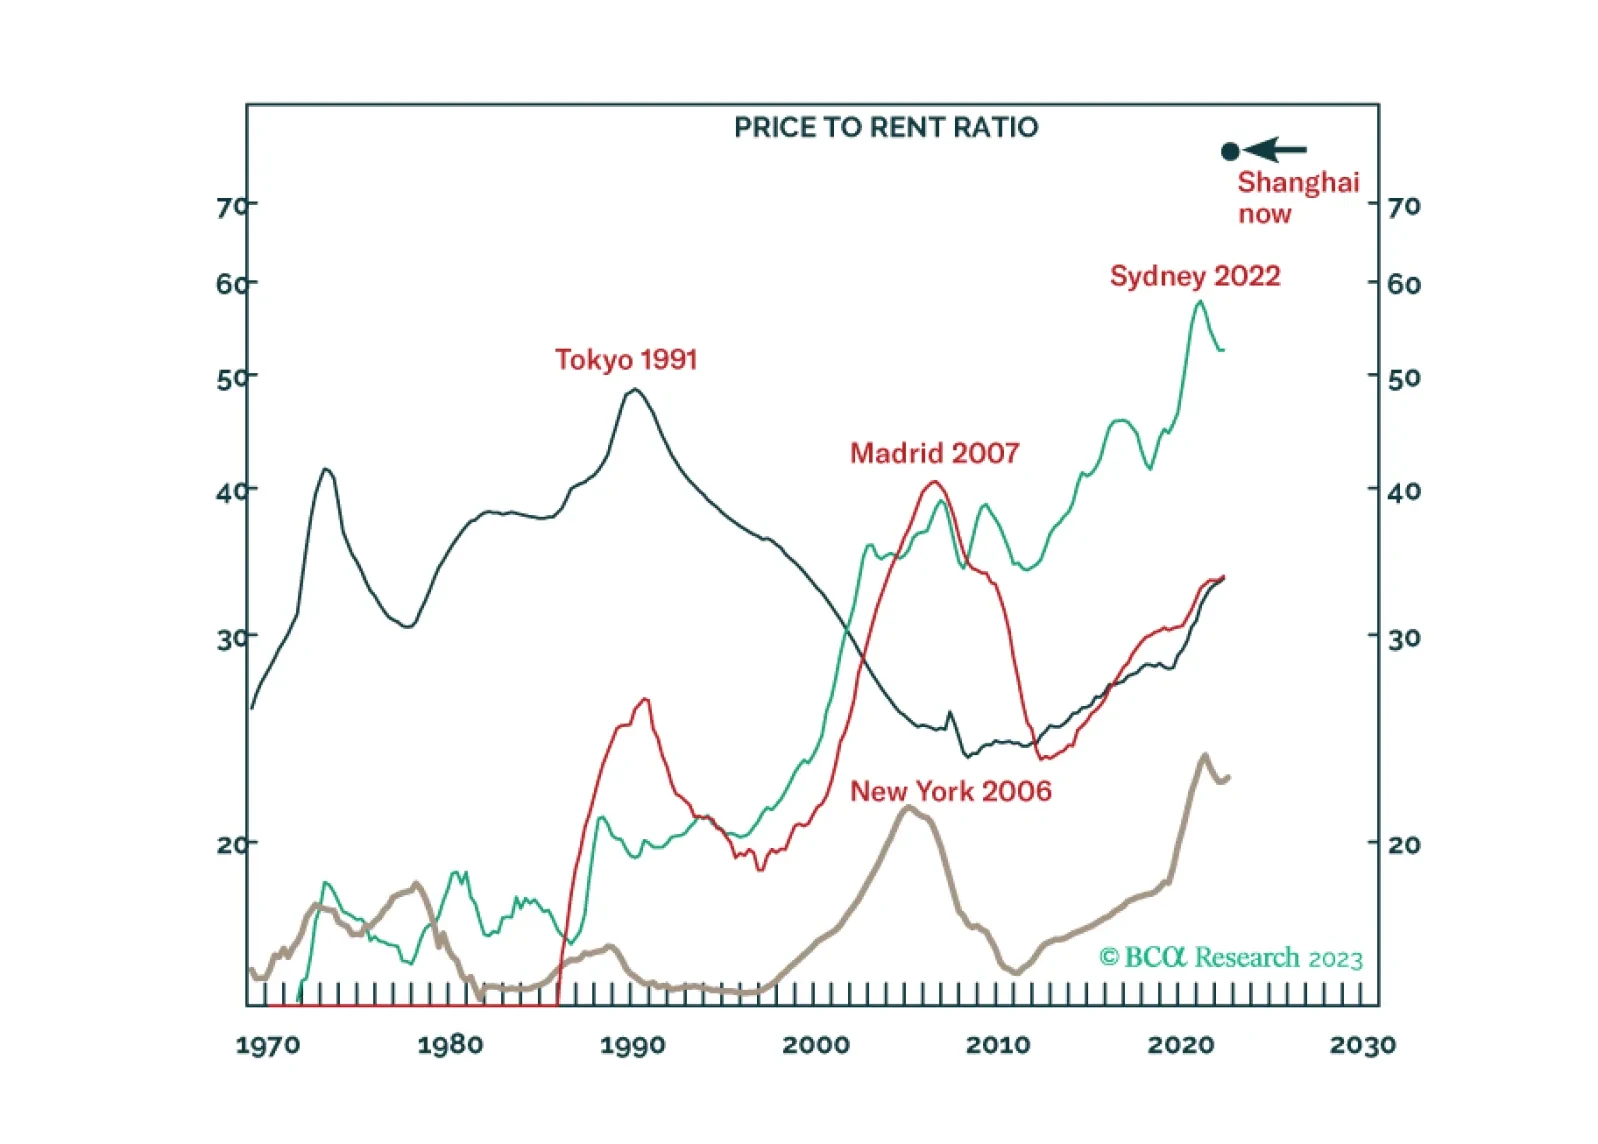
Special Report Our 2024 outlook can be encapsulated into just 39 words and three key views. Key view 1: The end of China’s housing boom means the end of the world’s main growth engine. Key view 2: If the Fed and ECB don’t kill the economy, they won’t kill inflation. Key view 3: The AI gold rush will struggle to find any gold. We go through the investment implications for the year ahead.
Special Report Our recommendations for blogs and X’s (on the economy, financial markets, asset allocation, bonds, quants, energy, real estate, geopolitics, and specific countries and regions) to try over the holidays.
Special Report Our US fixed income team’s key investment views for 2024.
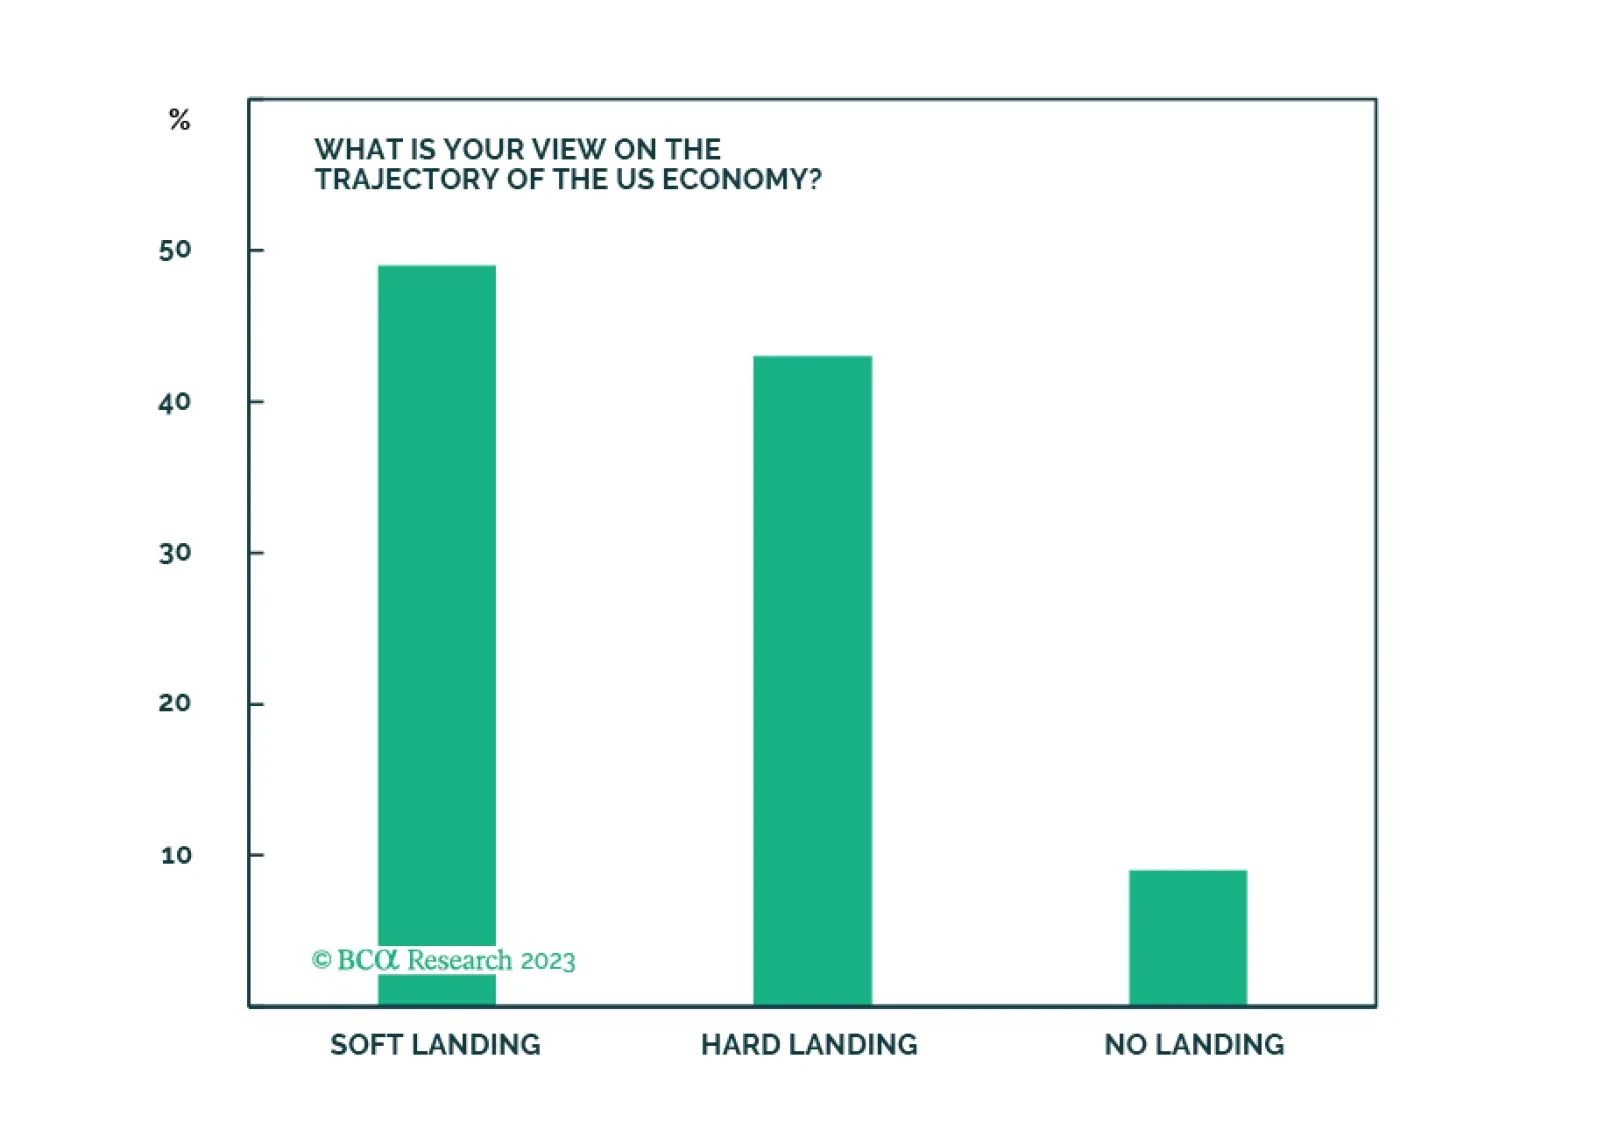
The Santa Claus rally is a repricing of the "soft landing" scenario as a likely economic outcome. Yet, many investors remain cautious, and harbor significant cash balances. Next year, repricing of various scenarios will continue, and volatility will be elevated. We remain in a "hard landing" camp and recommend defensive stance on a strategic investment horizon.
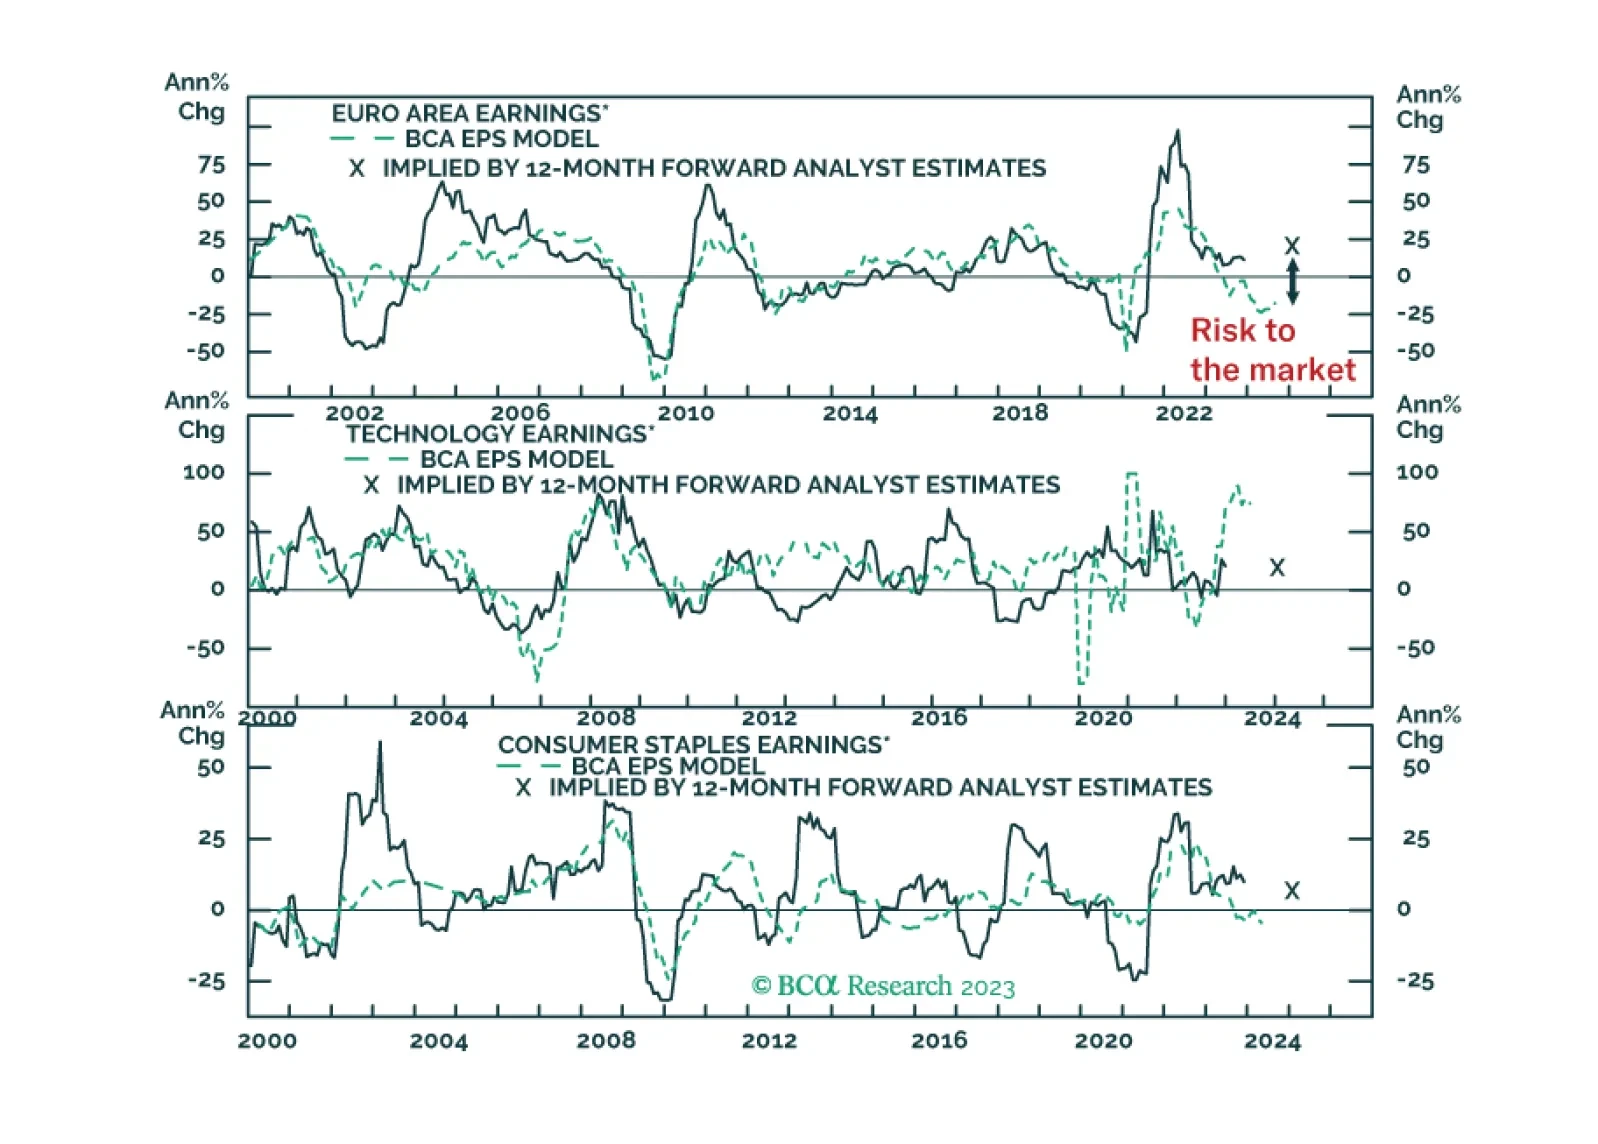
The recent decline in yields has powered European equities higher, however, this rally cannot last if earnings decline meaningfully. With this in mind, are our earnings models flagging risks for stocks next year?