Latest from BCA Research
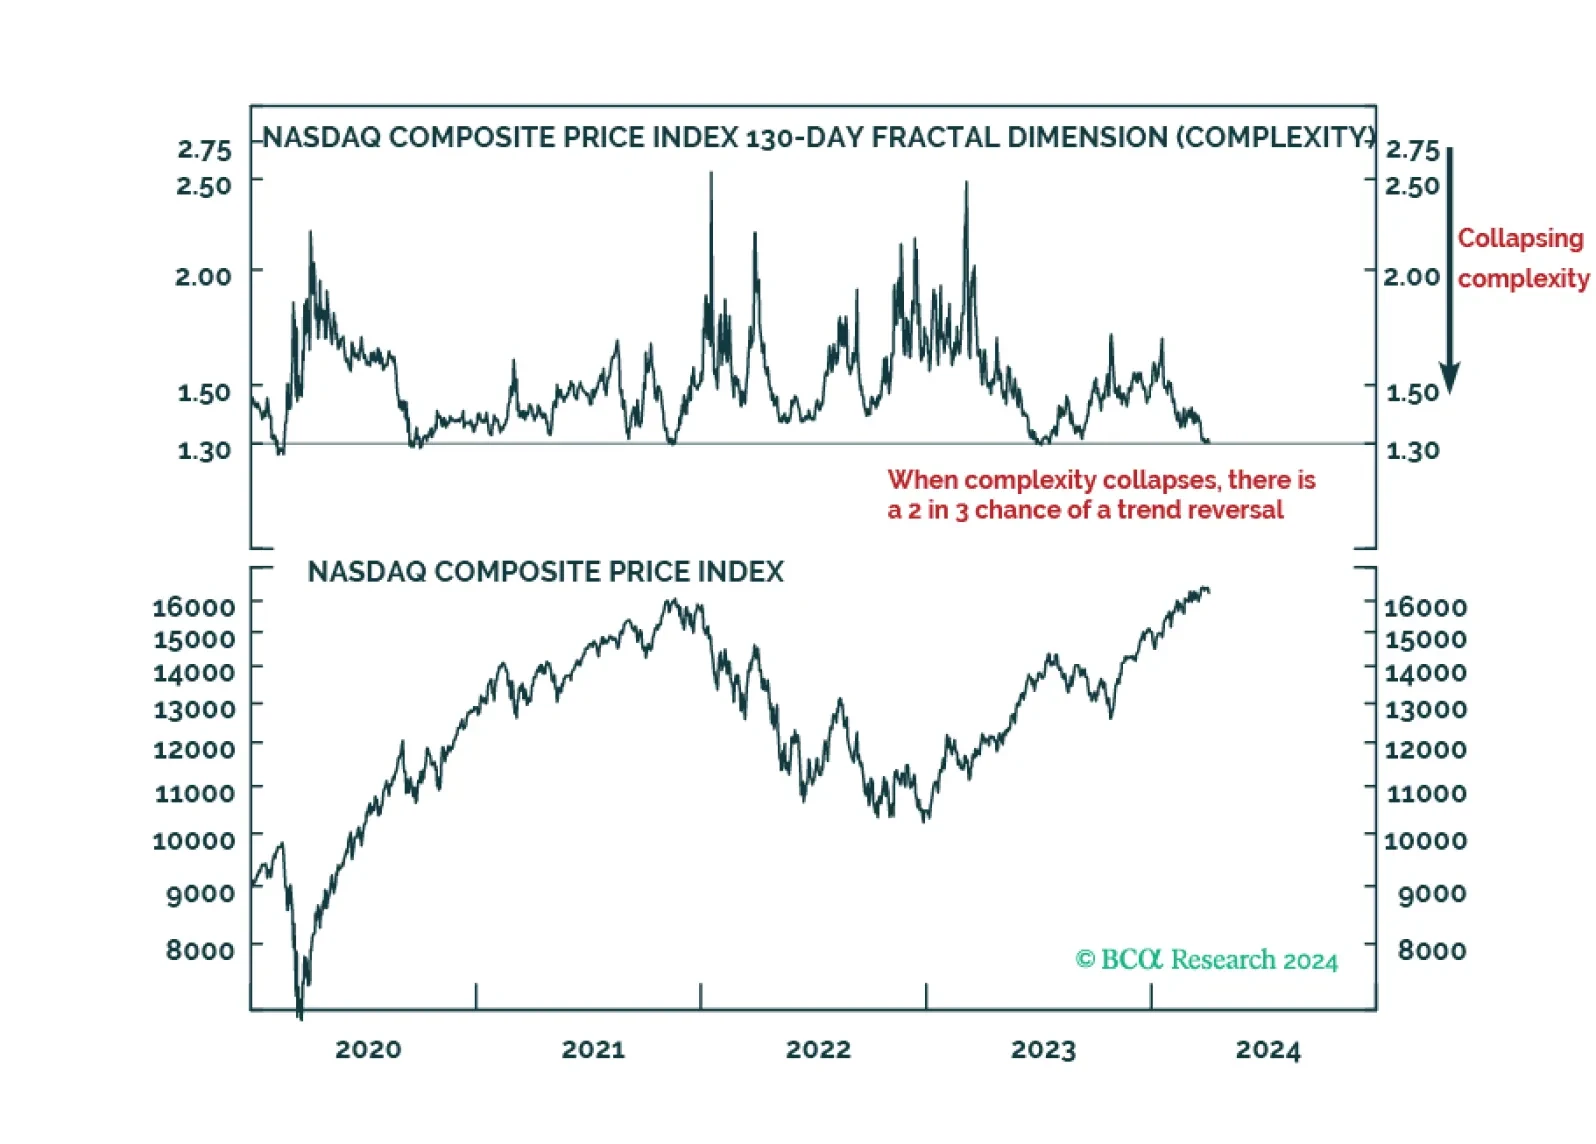
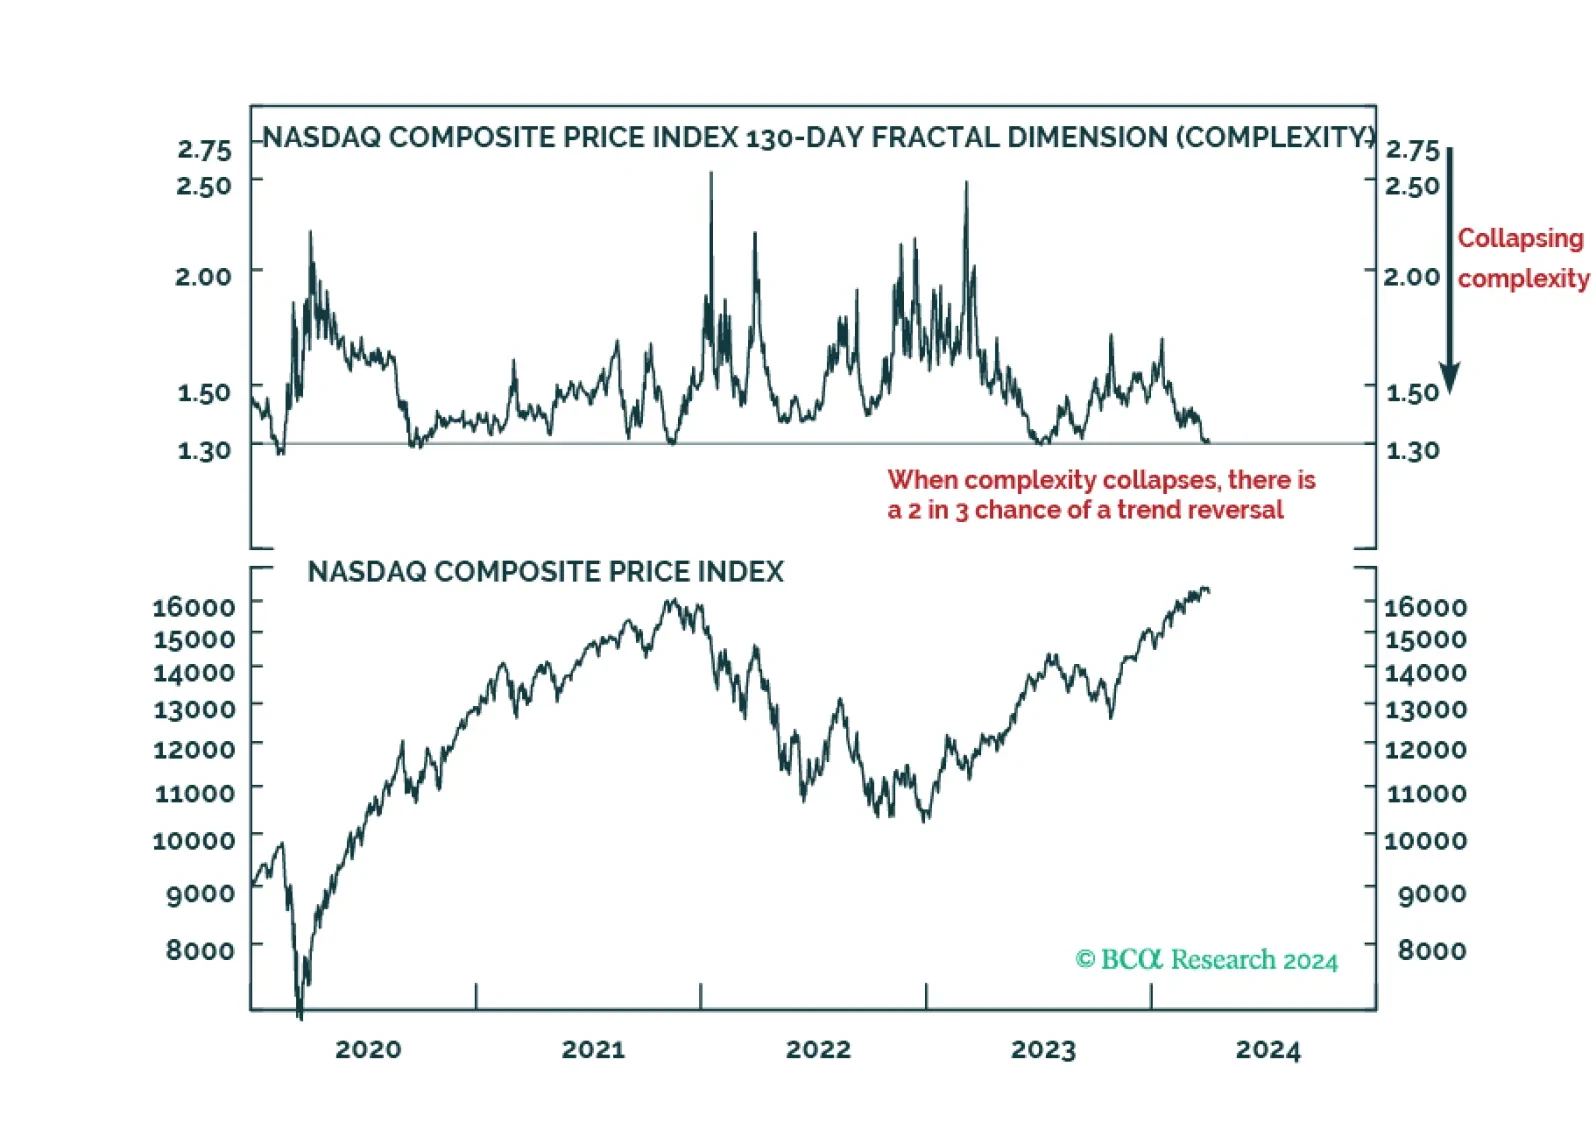
The analysis of complexity is a massive competitive advantage in investing, and from today, clients will be able to monitor the complexities of the world’s 17 major investments on our webpage in real-time.
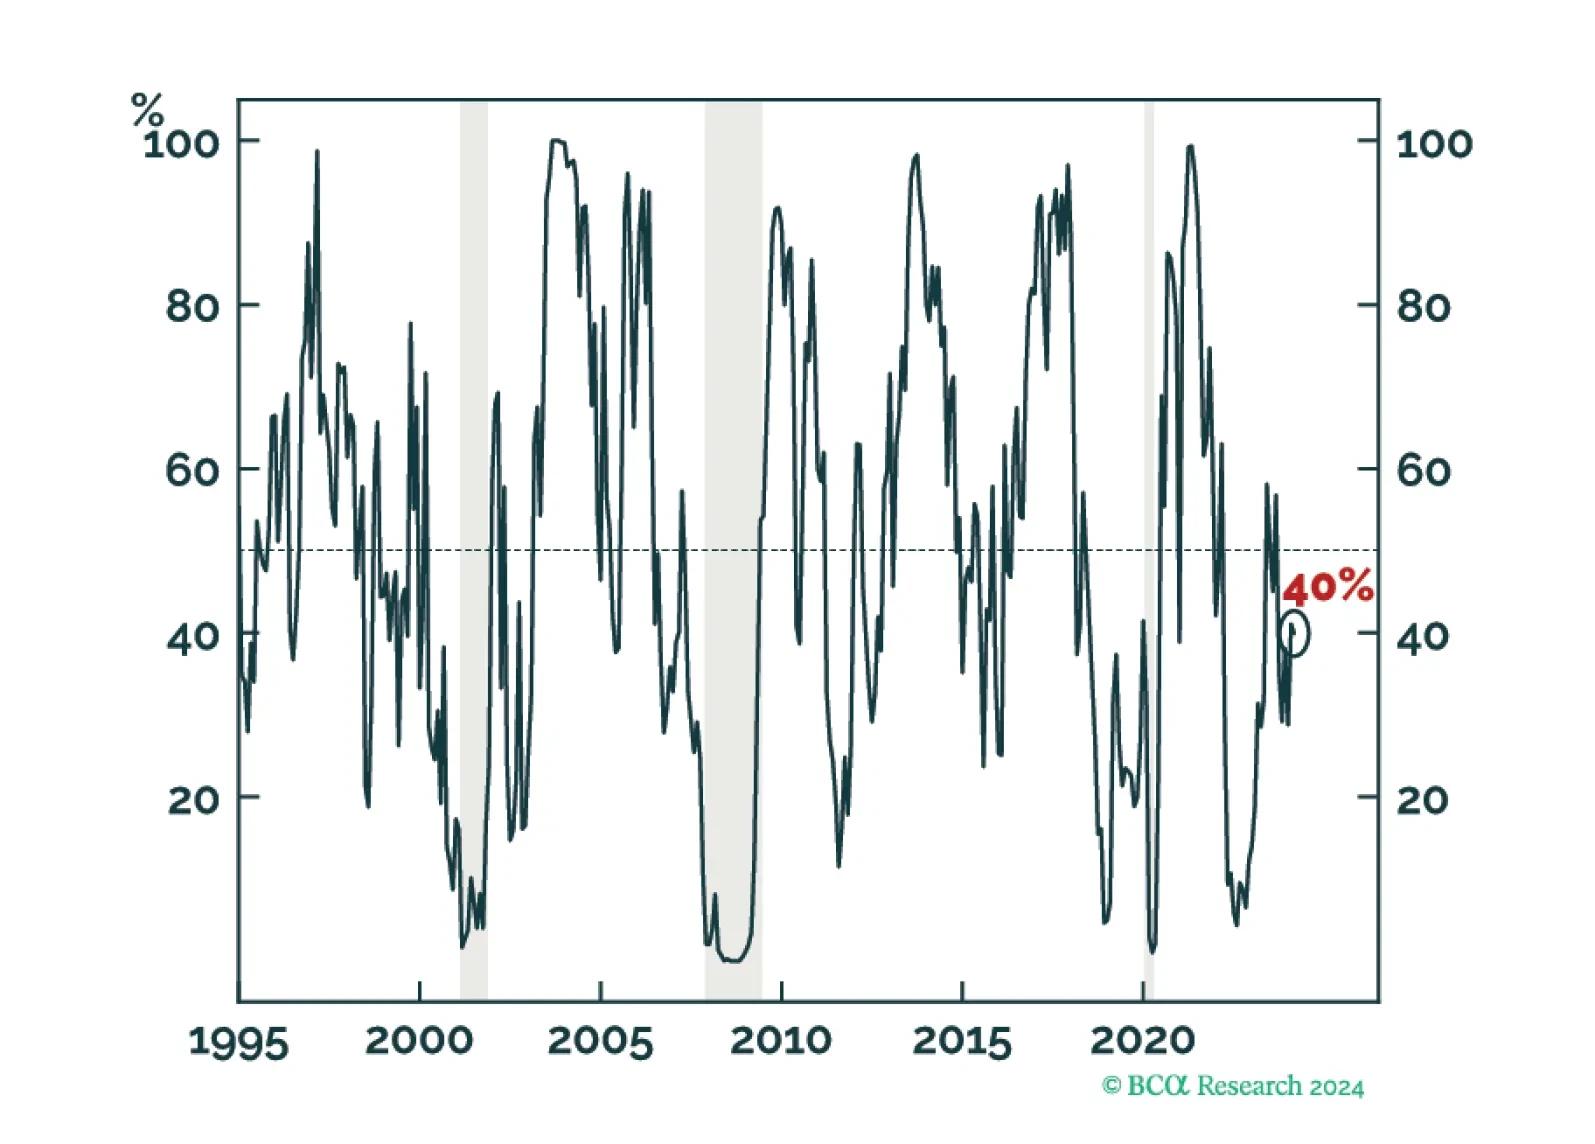
This month the Equity Score flatted out after a sharp increase last month. Three out of the four model inputs driving the sector views are near neutral, suggesting we may see a rotation in sector preference over the next few months. The Style Indicator continues to align with Large-Cap Value.
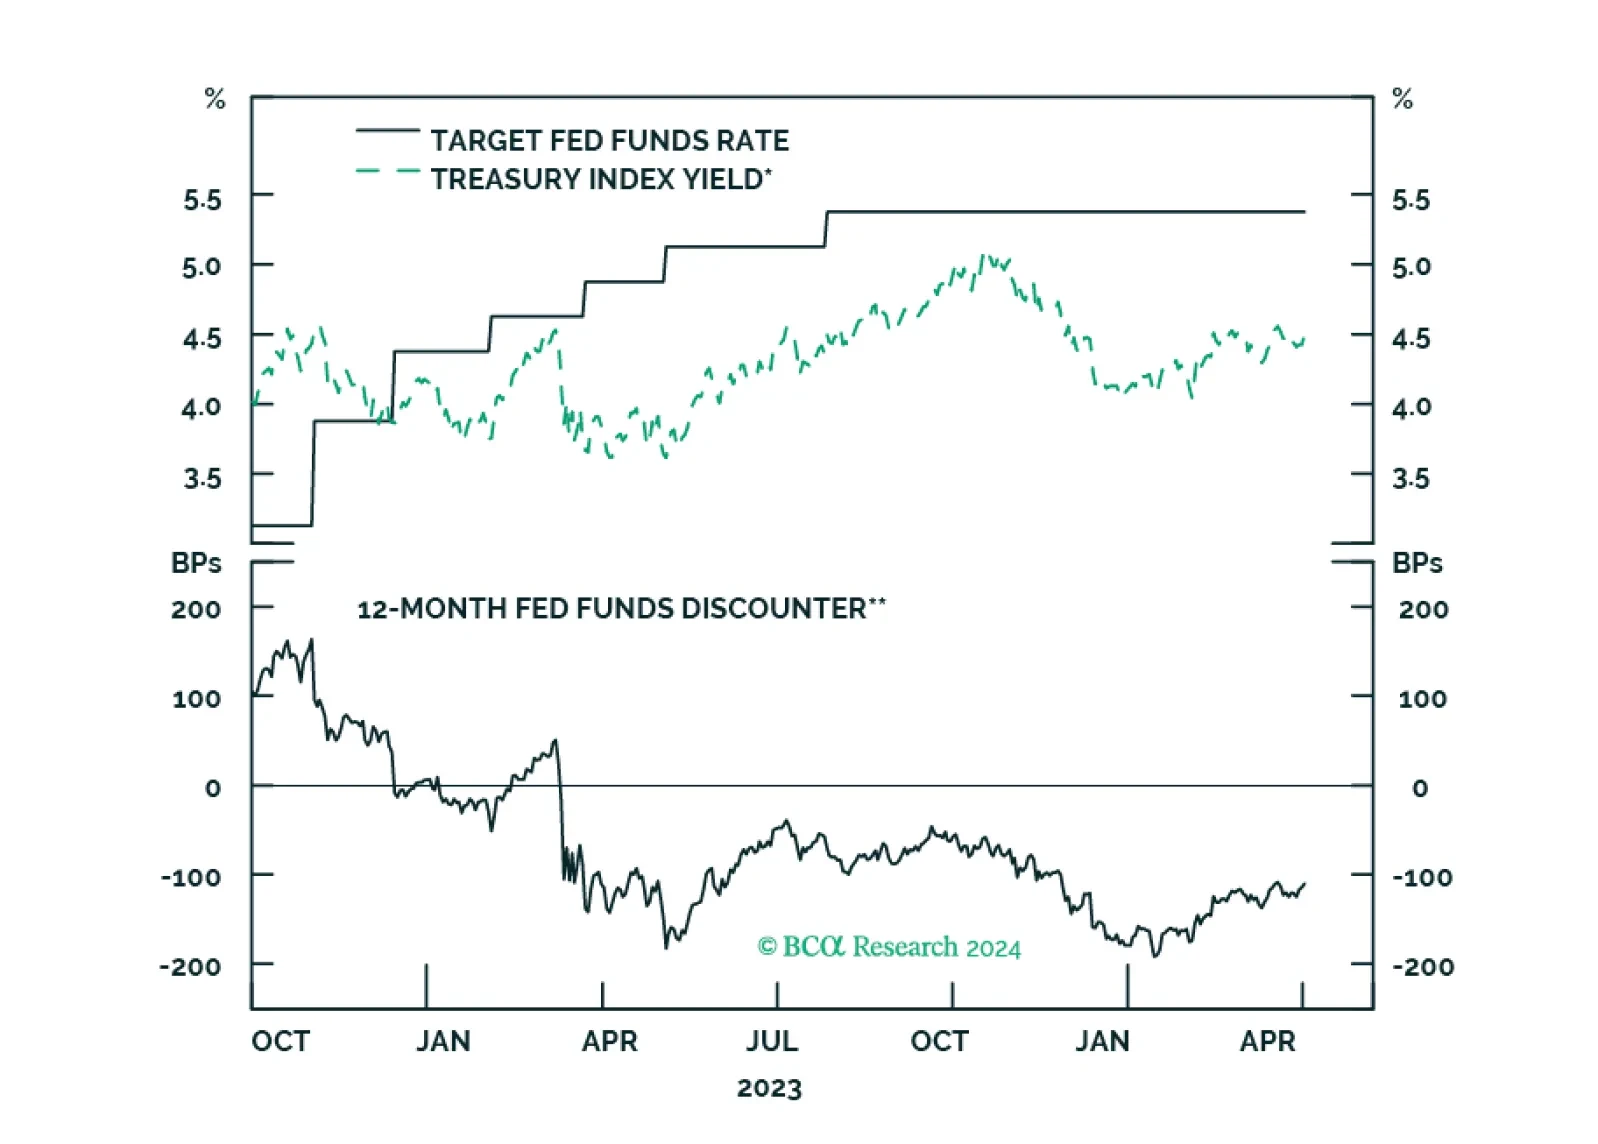

The equity rally extended into March as hard landing outcome was priced out. It has broadened, as money flowed into less over-loved pockets of the market. Our models signal that margins are about to stabilize, and earnings growth will accelerate as the year progresses. However, companies are raising prices again and the no-landing outcome and fewer than three rate cuts this year are increasingly likely.
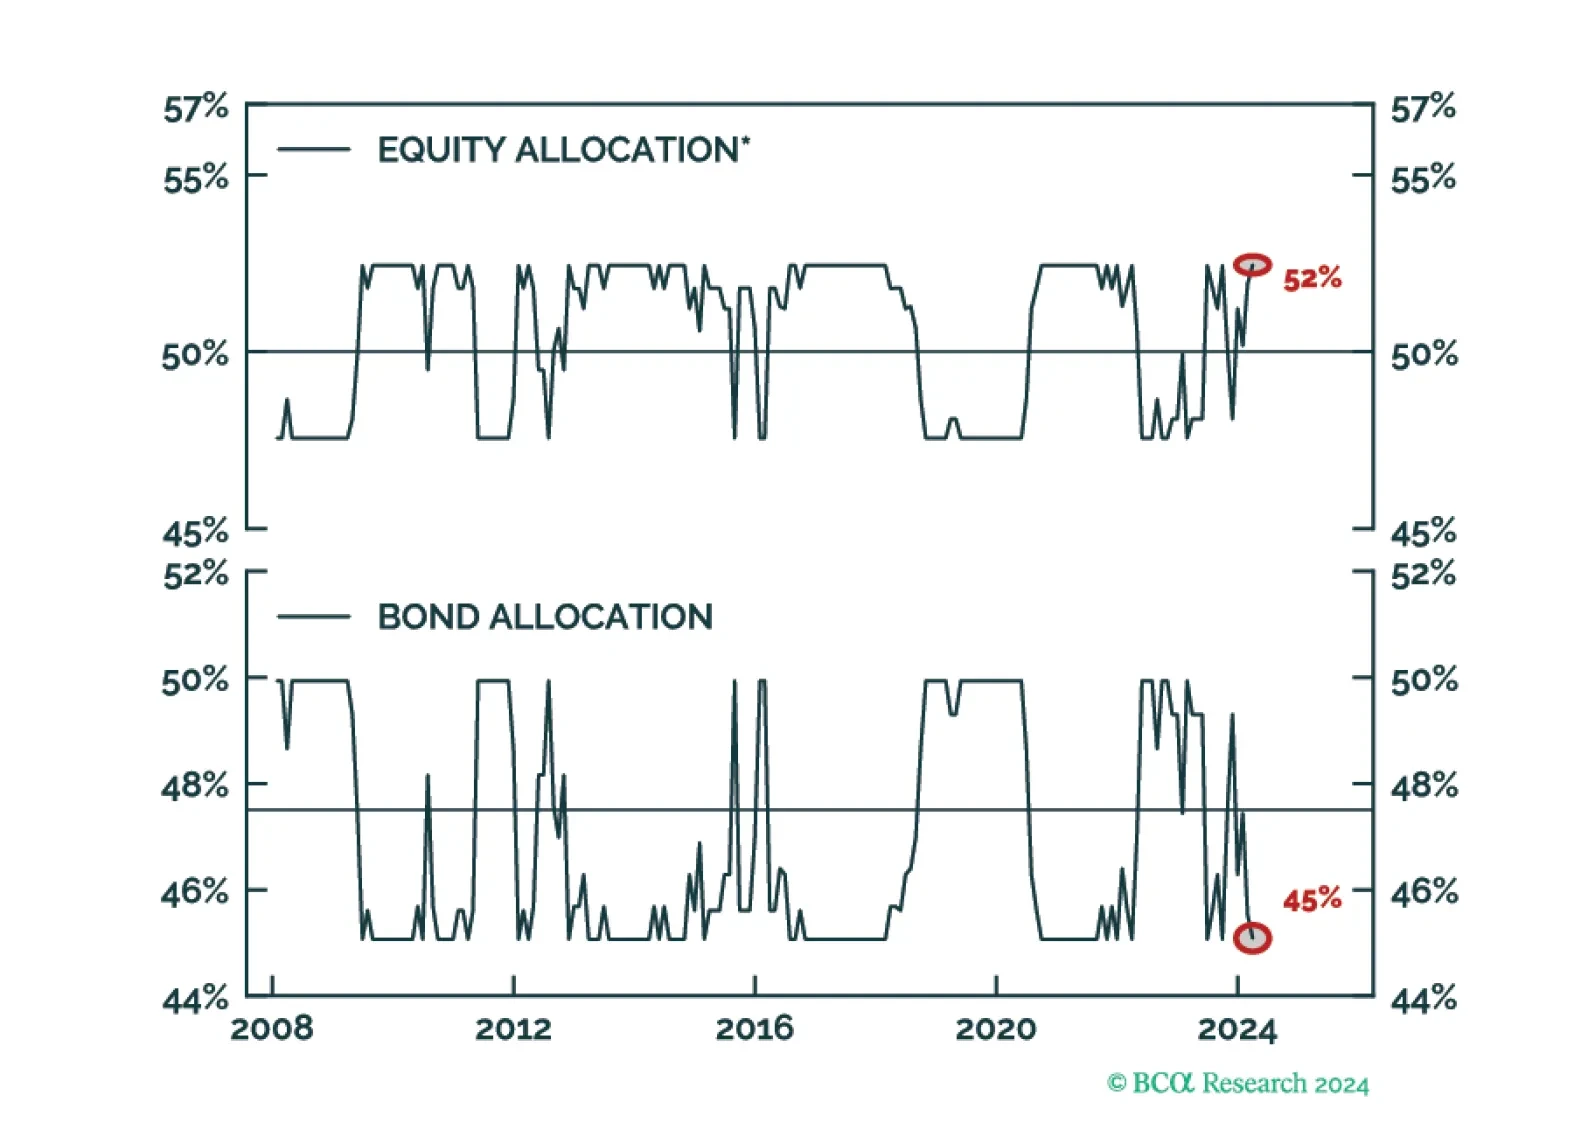
At the asset class level, the GAA Quant model is overweight equities, underweight bonds, and neutral cash.
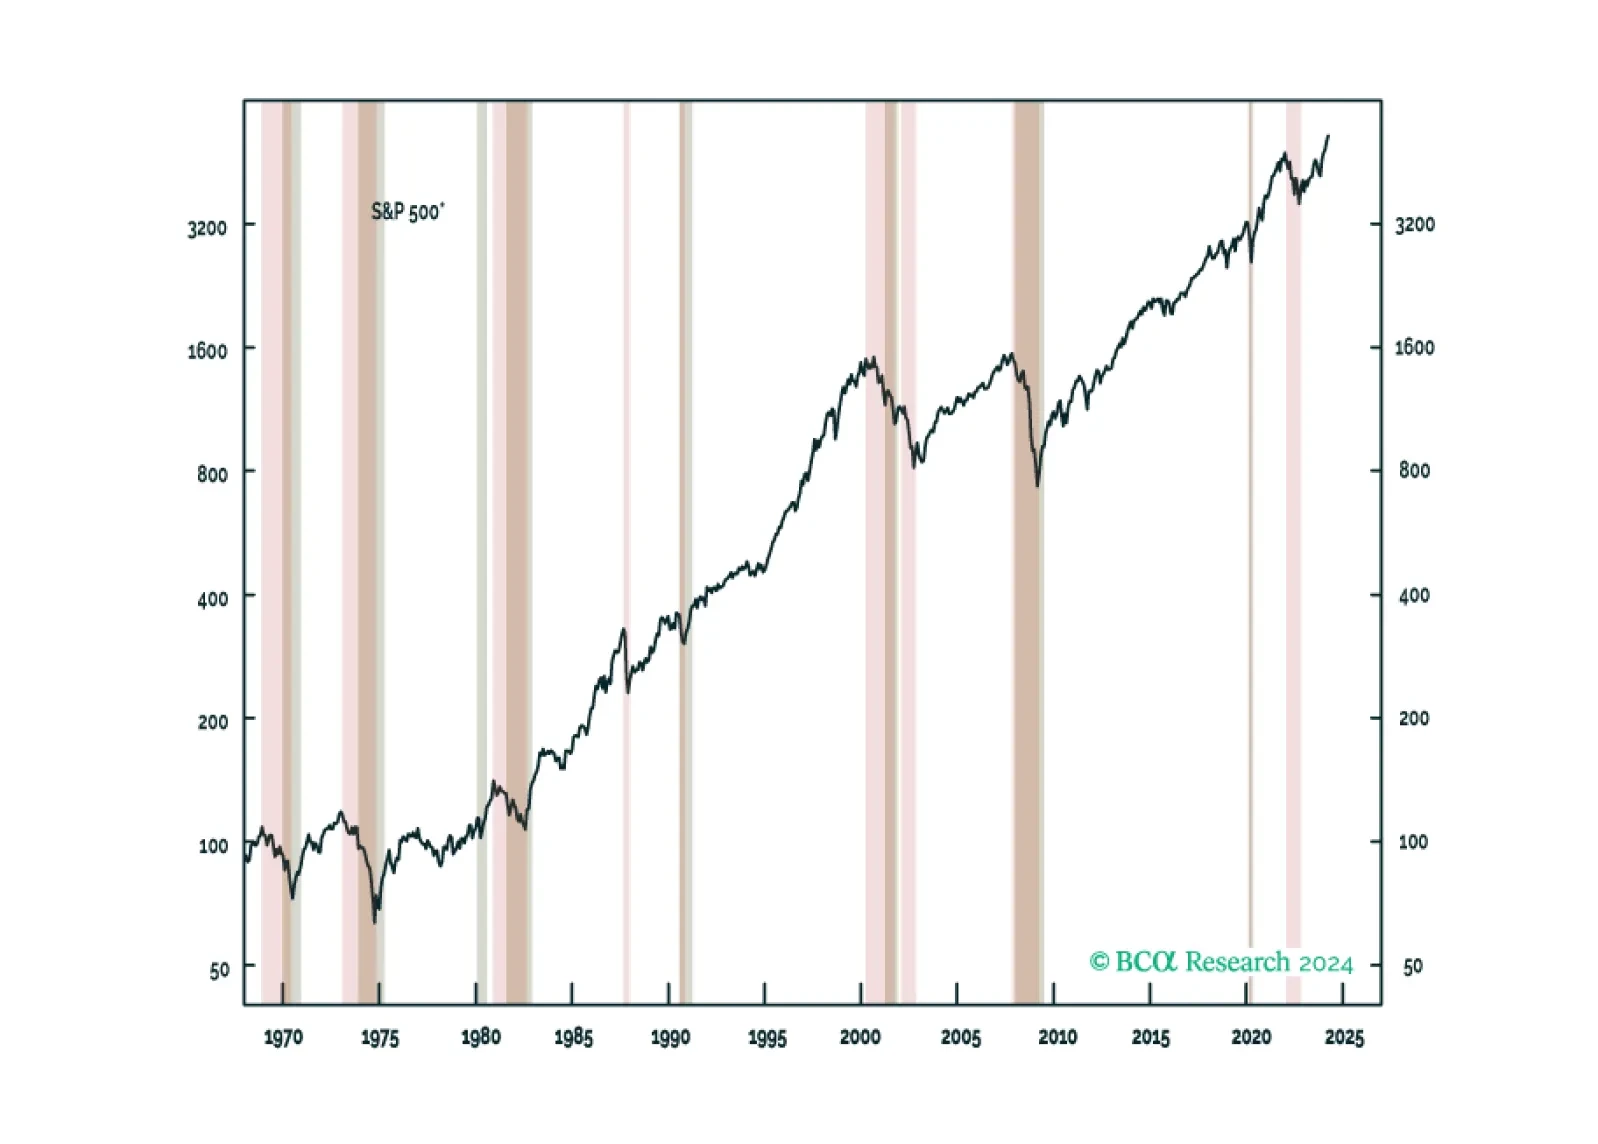
We are not yet ready to downgrade equities on a tactical basis but continue to expect we will eventually do so. We present a checklist of indicators that we are watching to determine when to de-risk.
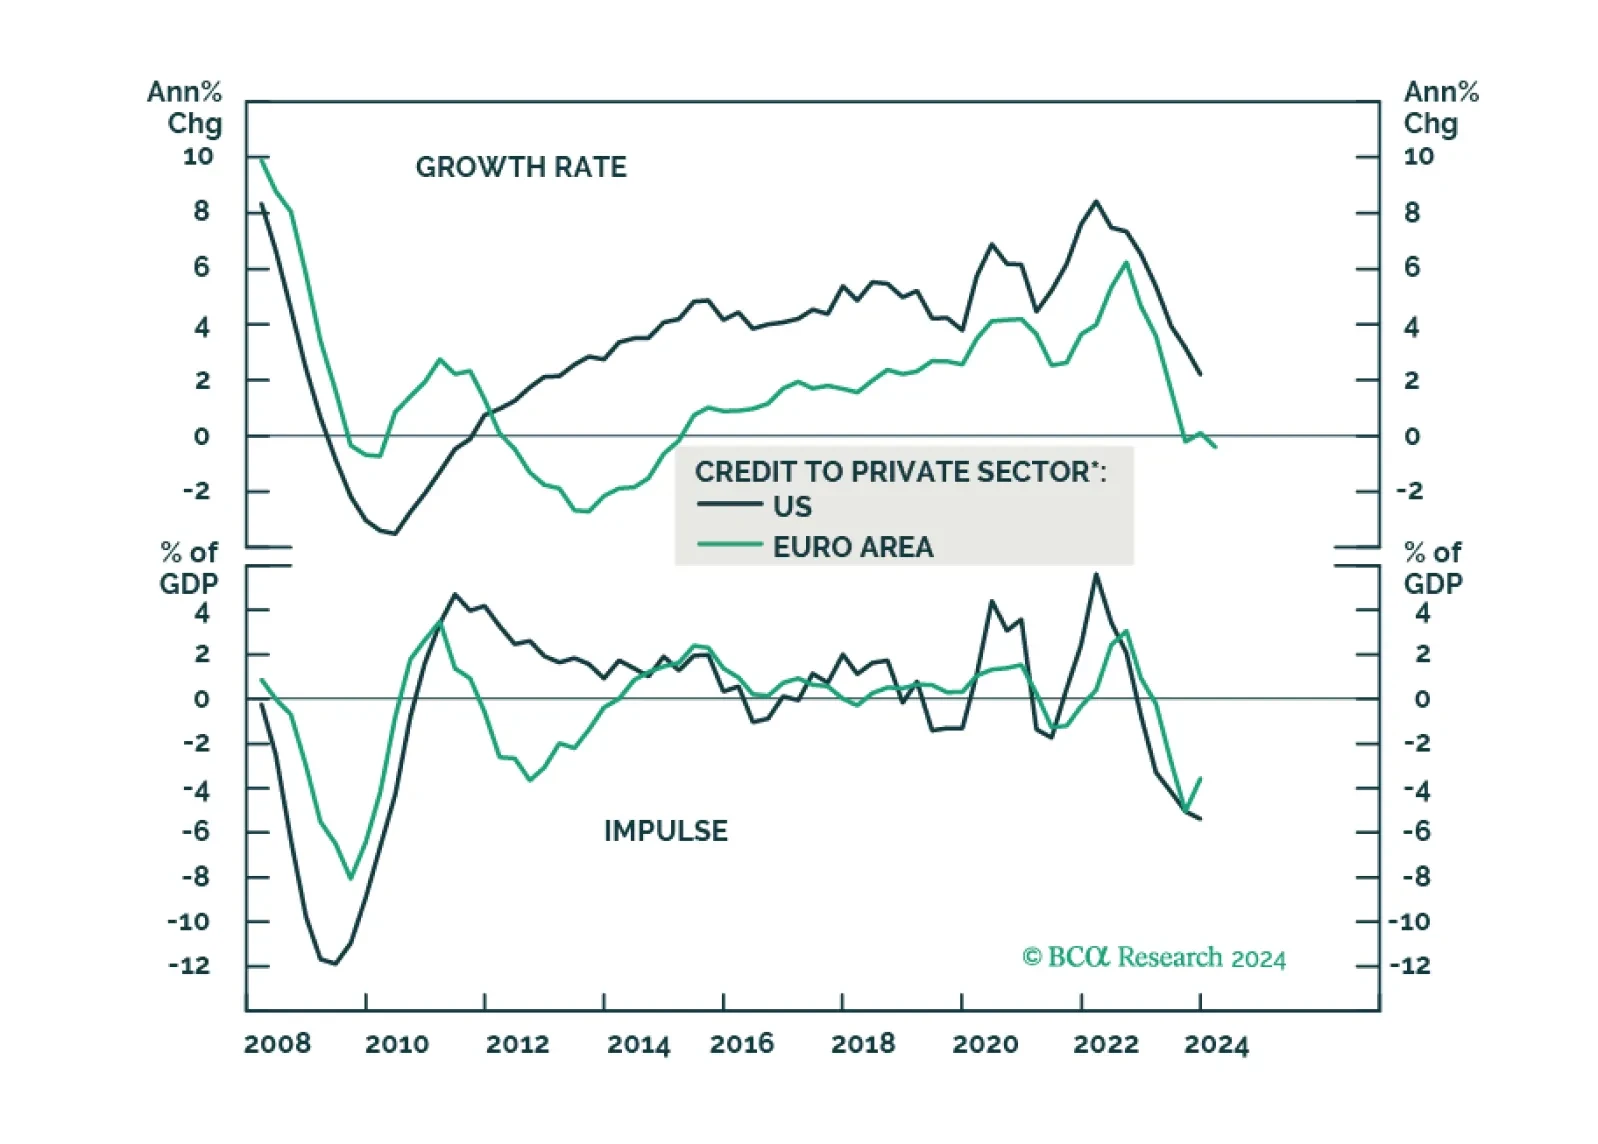
The global economy is wobbling precariously between slowing growth and reaccelerating inflation. This is unlikely to end well. Stay cautious, and hedge against both recession and inflation.