Skip to main content

Latest from BCA Research
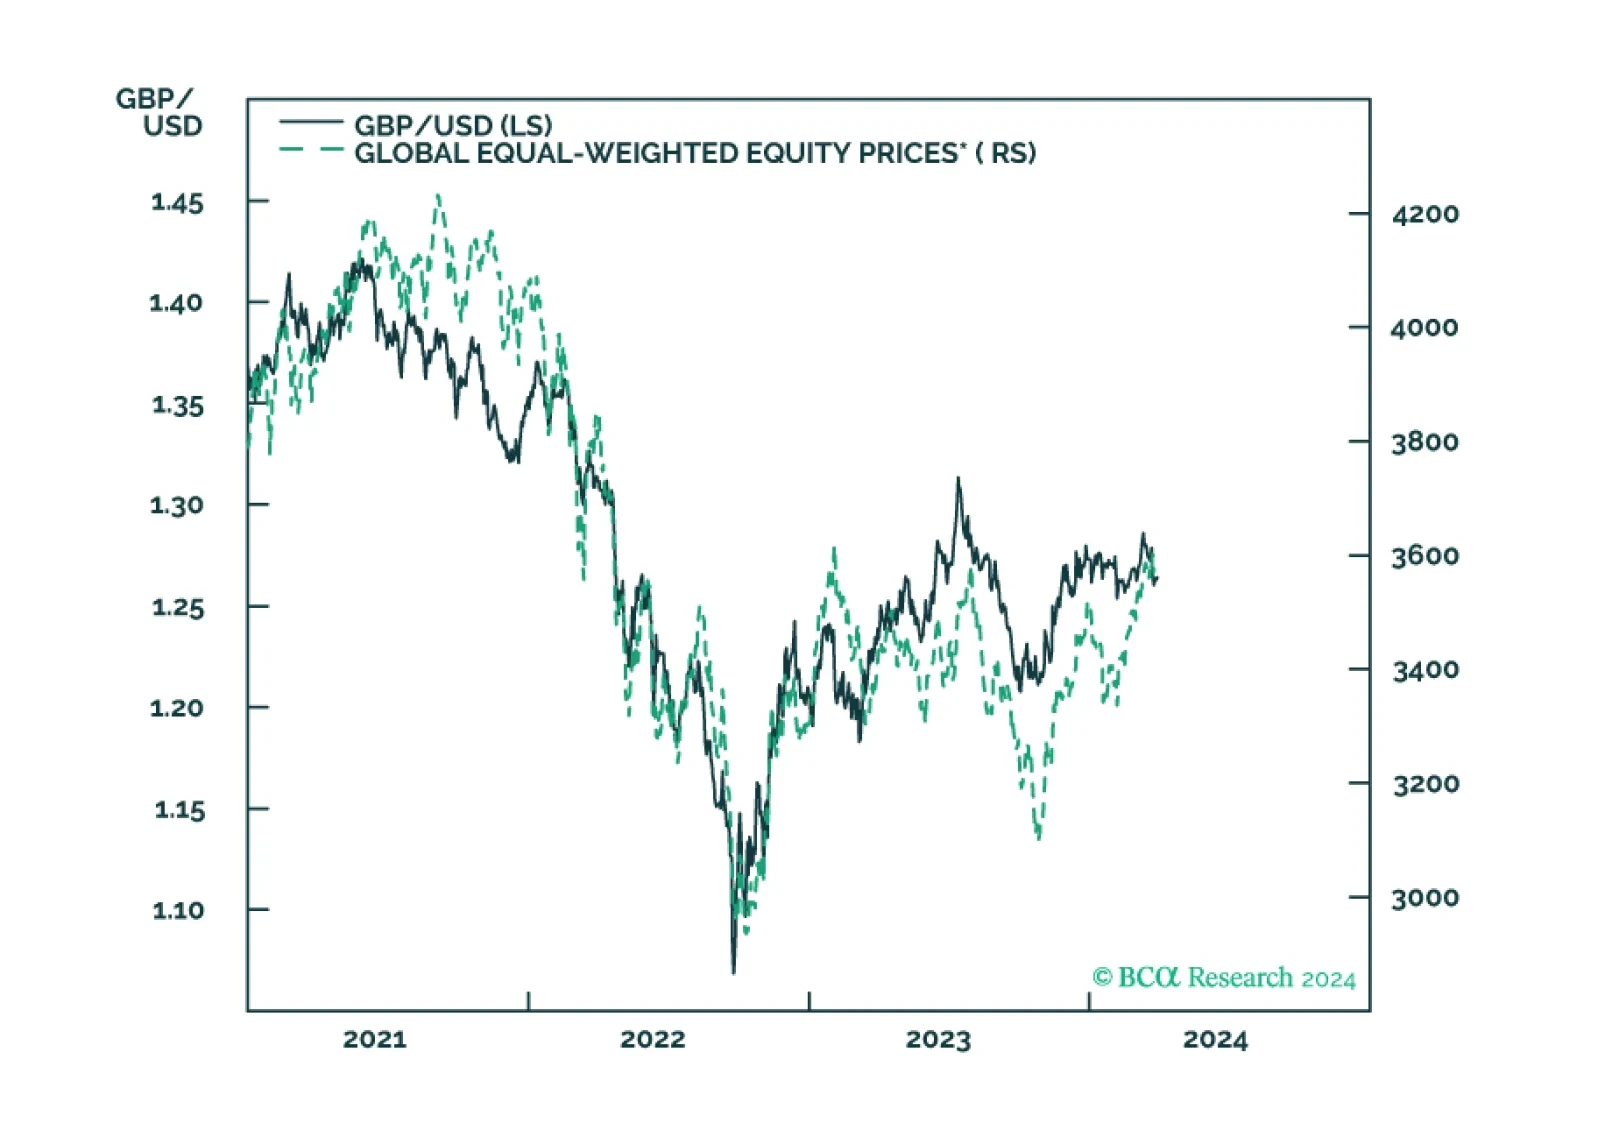
In this Insight, we discuss our rationale for a short sterling position.
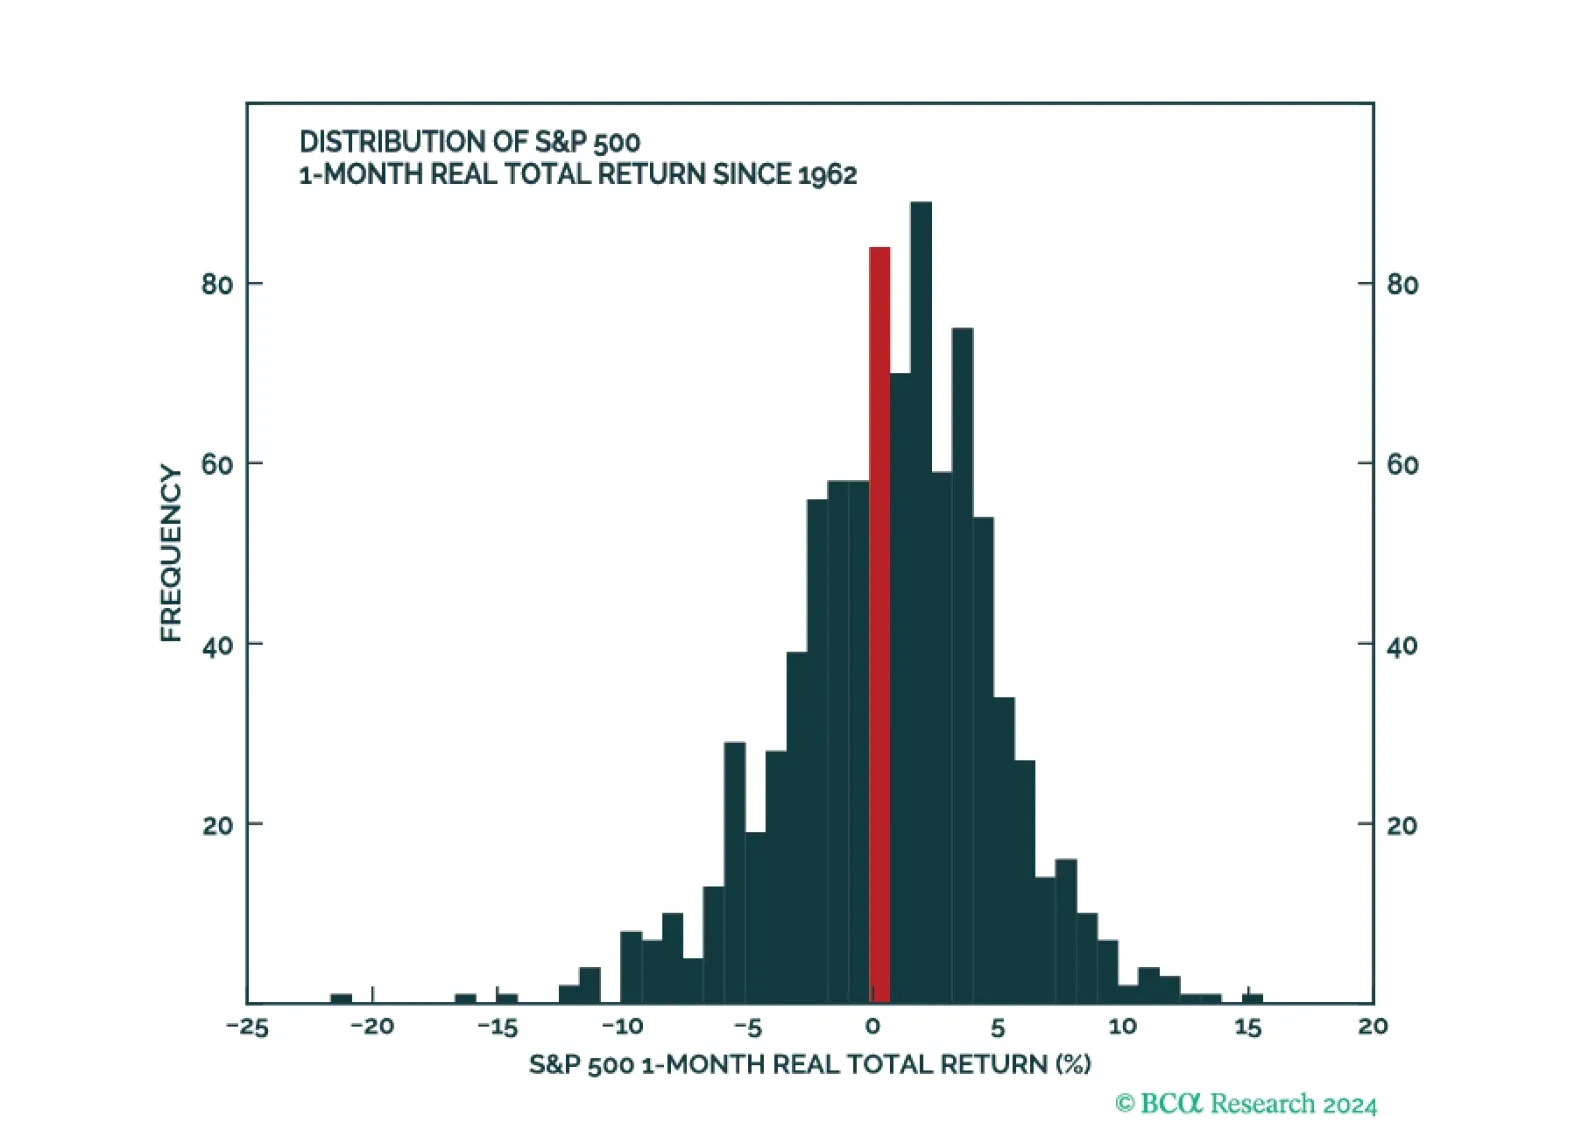
MacroQuant downgraded equities from overweight to neutral on a 1-to-3 month horizon. The model maintains a neg­ative view on stocks over a 12-month horizon.
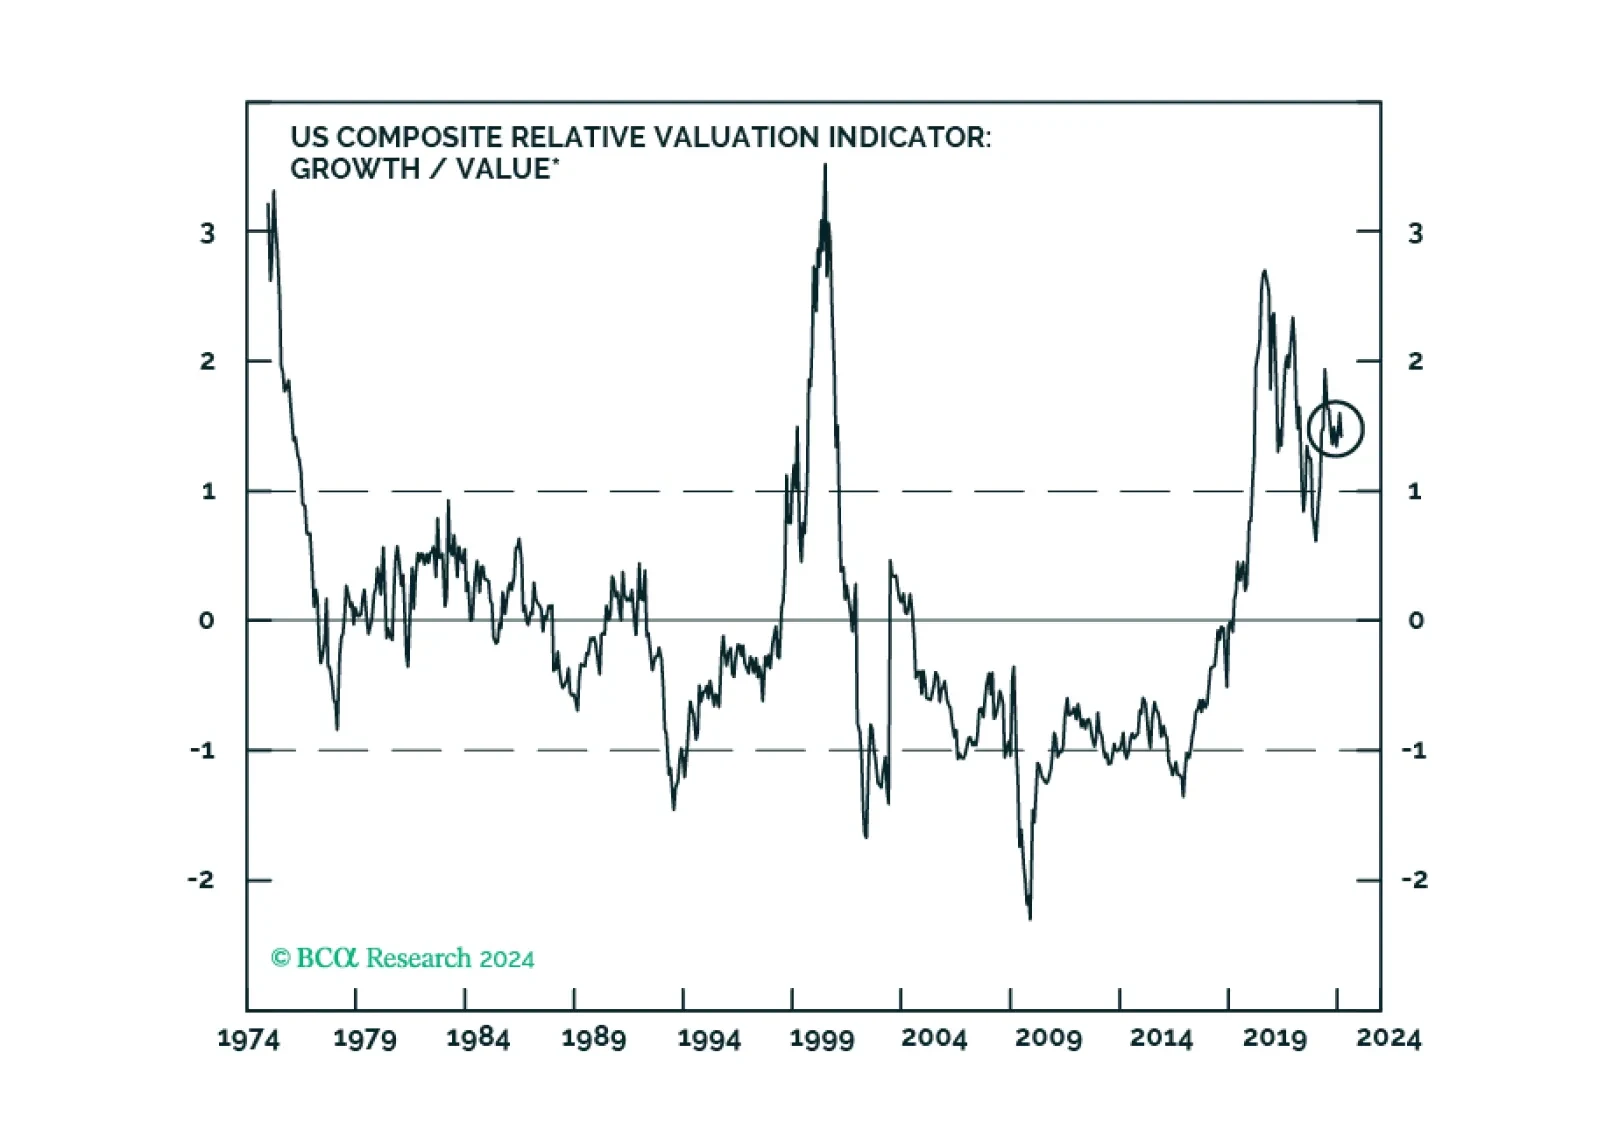
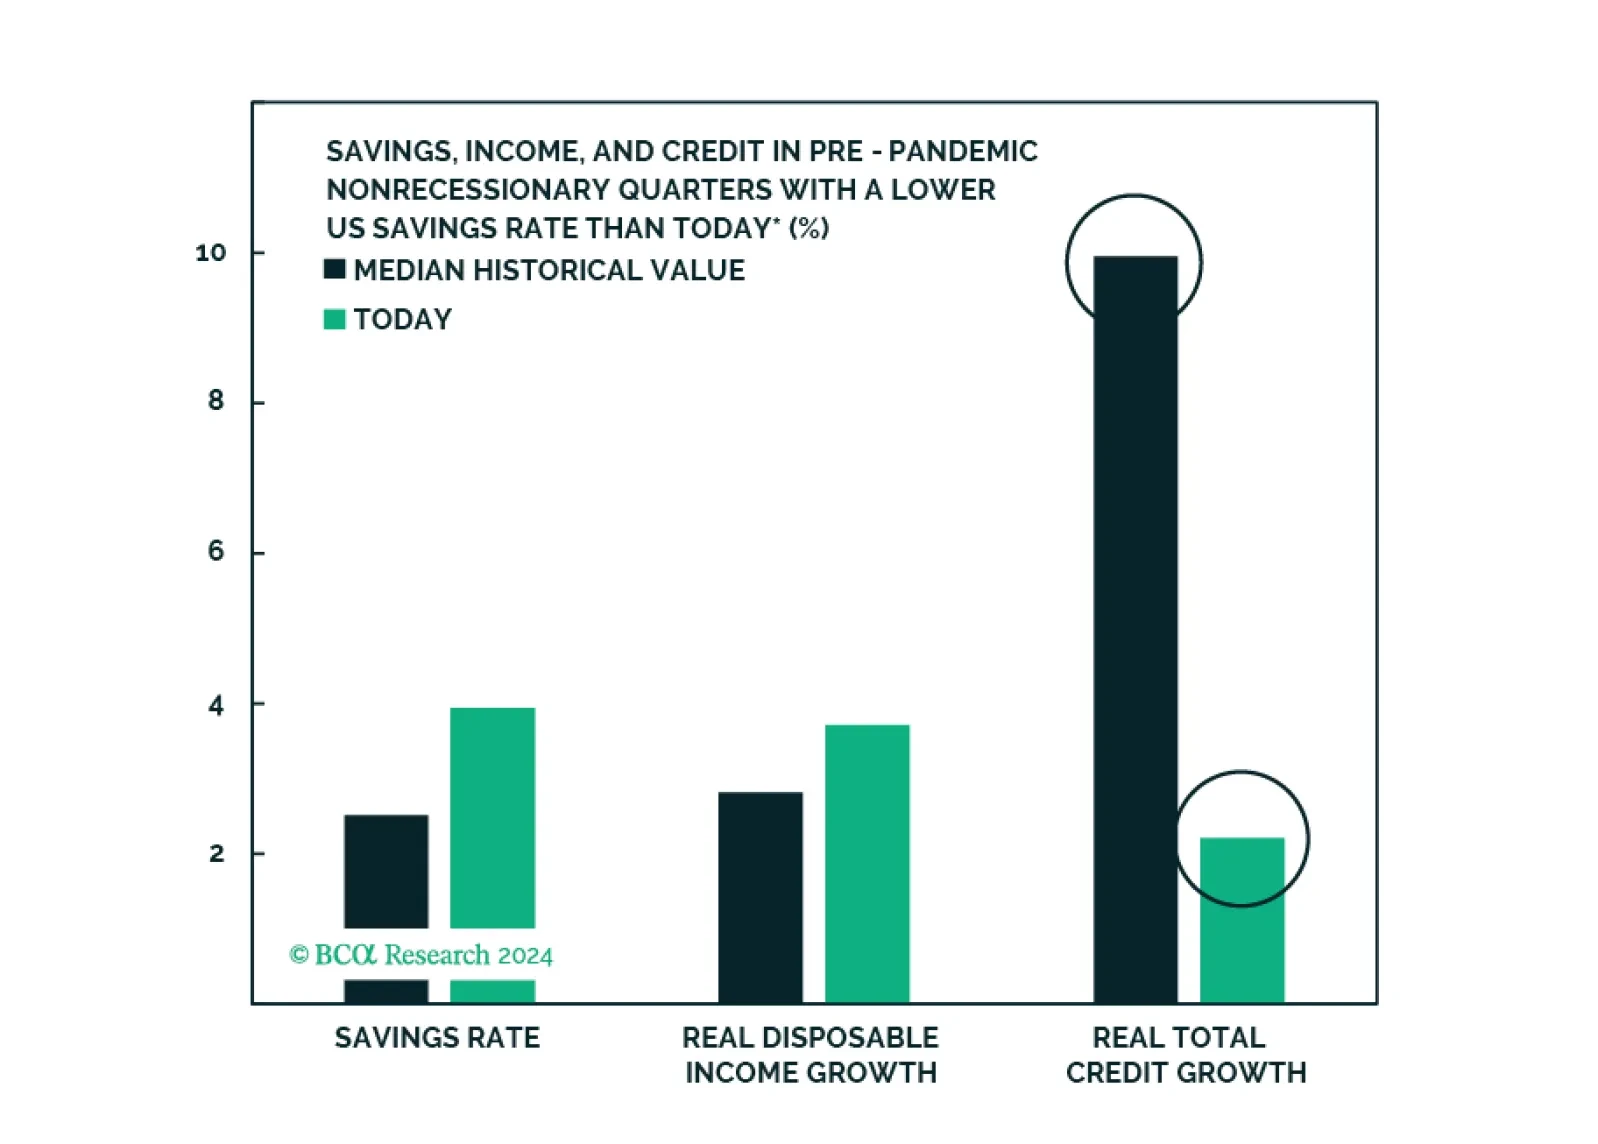
Bank Credit Analyst In Section I, we acknowledge that investors may wish to be neutrally positioned toward risky assets even over a 6-12 month time horizon. Our confidence in an eventual recessionary outcome has not changed, but a recession may be delayed by a Fed-driven easing in financial conditions. We are not prepared to change our investment recommendations today, but strong evidence of sustained growth and continued disinflation could lead us to recommend increasing exposure to risky assets for the sake of portfolio risk management. In Section II, we ask whether growth stocks will outperform value stocks during the next US recession. We examine historical performance of style during recessions dating back to 1926, and conclude that growth stocks are likely to underperform value during the next US recession. That assessment will change if growth stocks sell off significantly in advance of a contraction in output, or we see signs of significant sector-specific effects impacting value indexes.
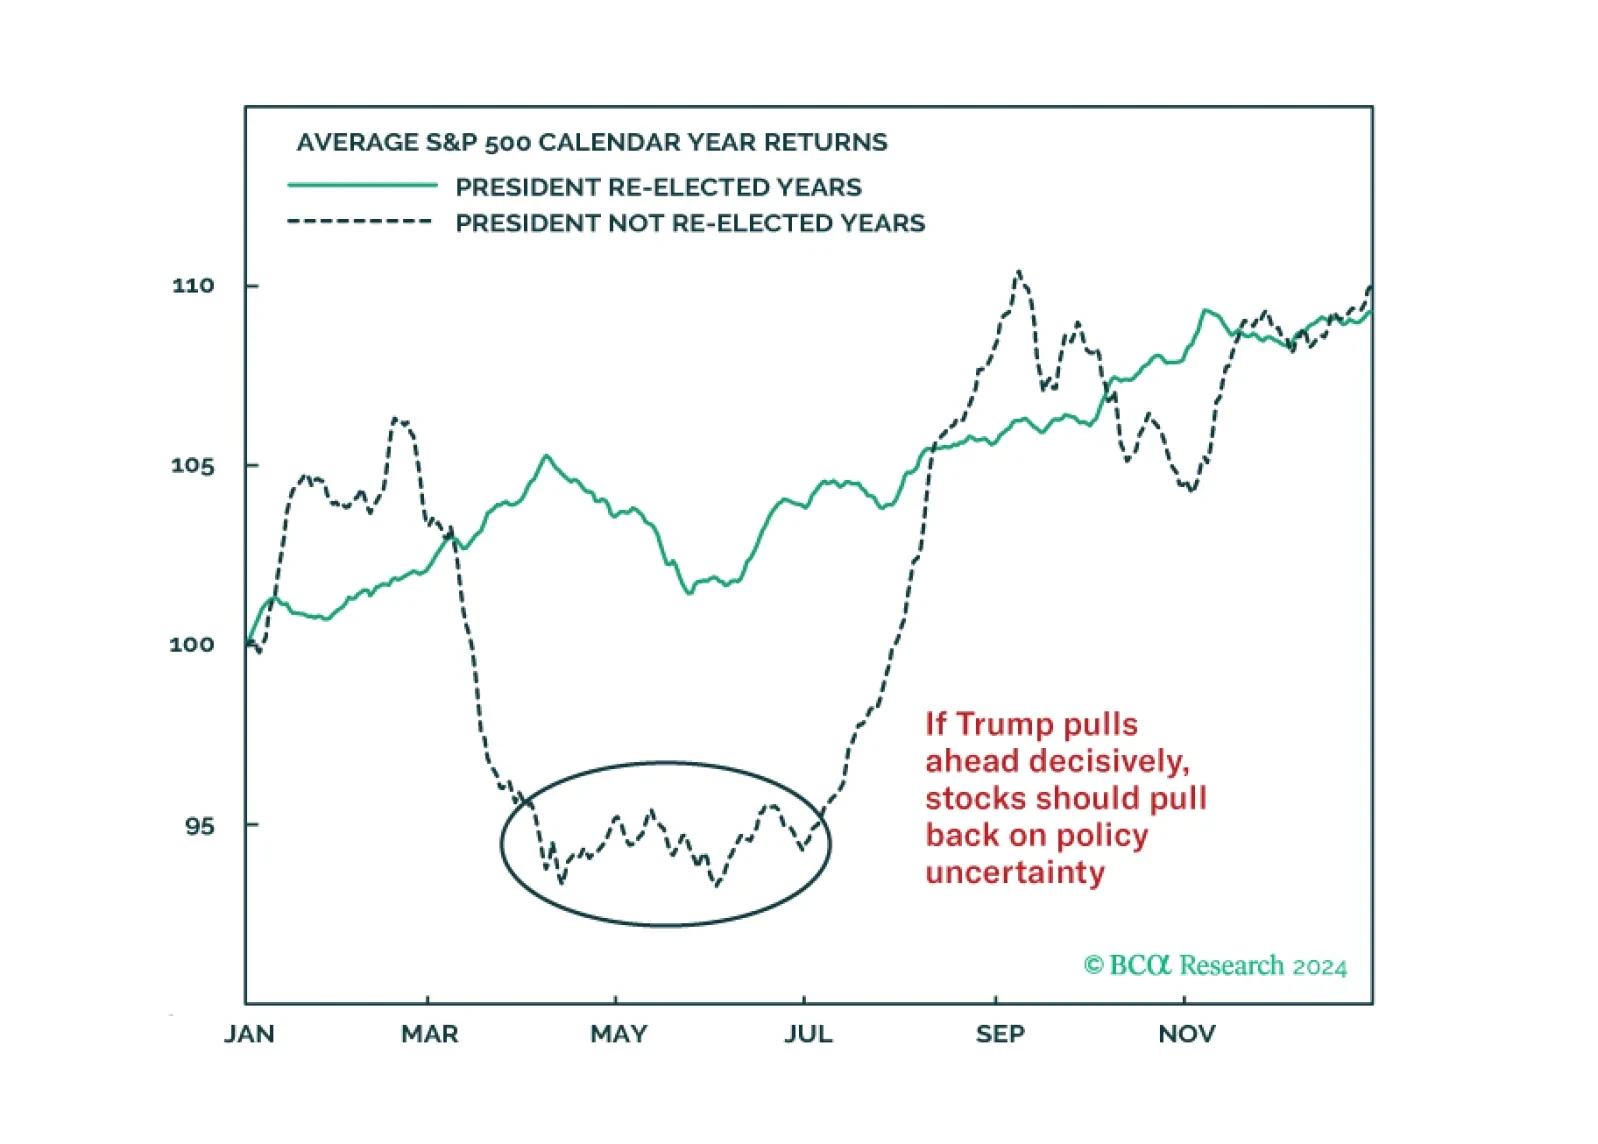
Investors around Europe and North America are concerned that the stock market is increasingly overbought and vulnerable to exogenous risks. We agree and have good reasons to fear that festering geopolitical risks and the US election season will deal negative surprises.
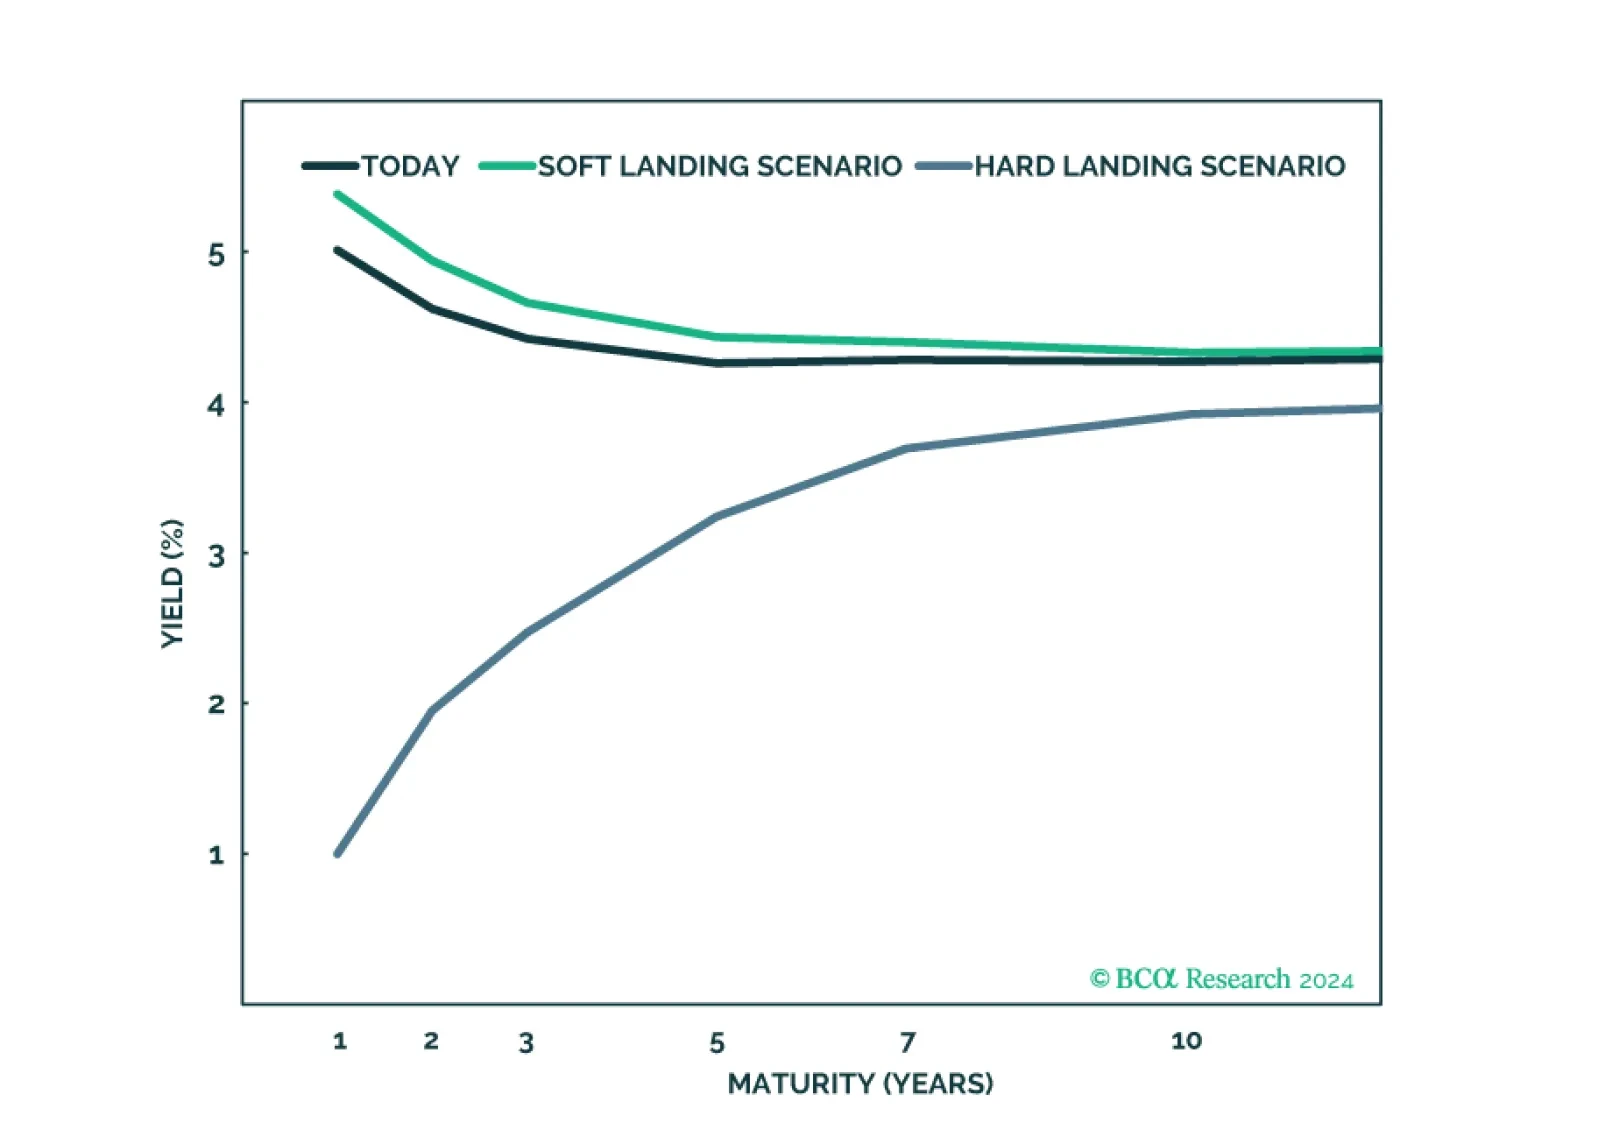
We expand our risk/reward analysis of US investment grade corporate bonds to focus on the 44 industry groups included in the Bloomberg index.
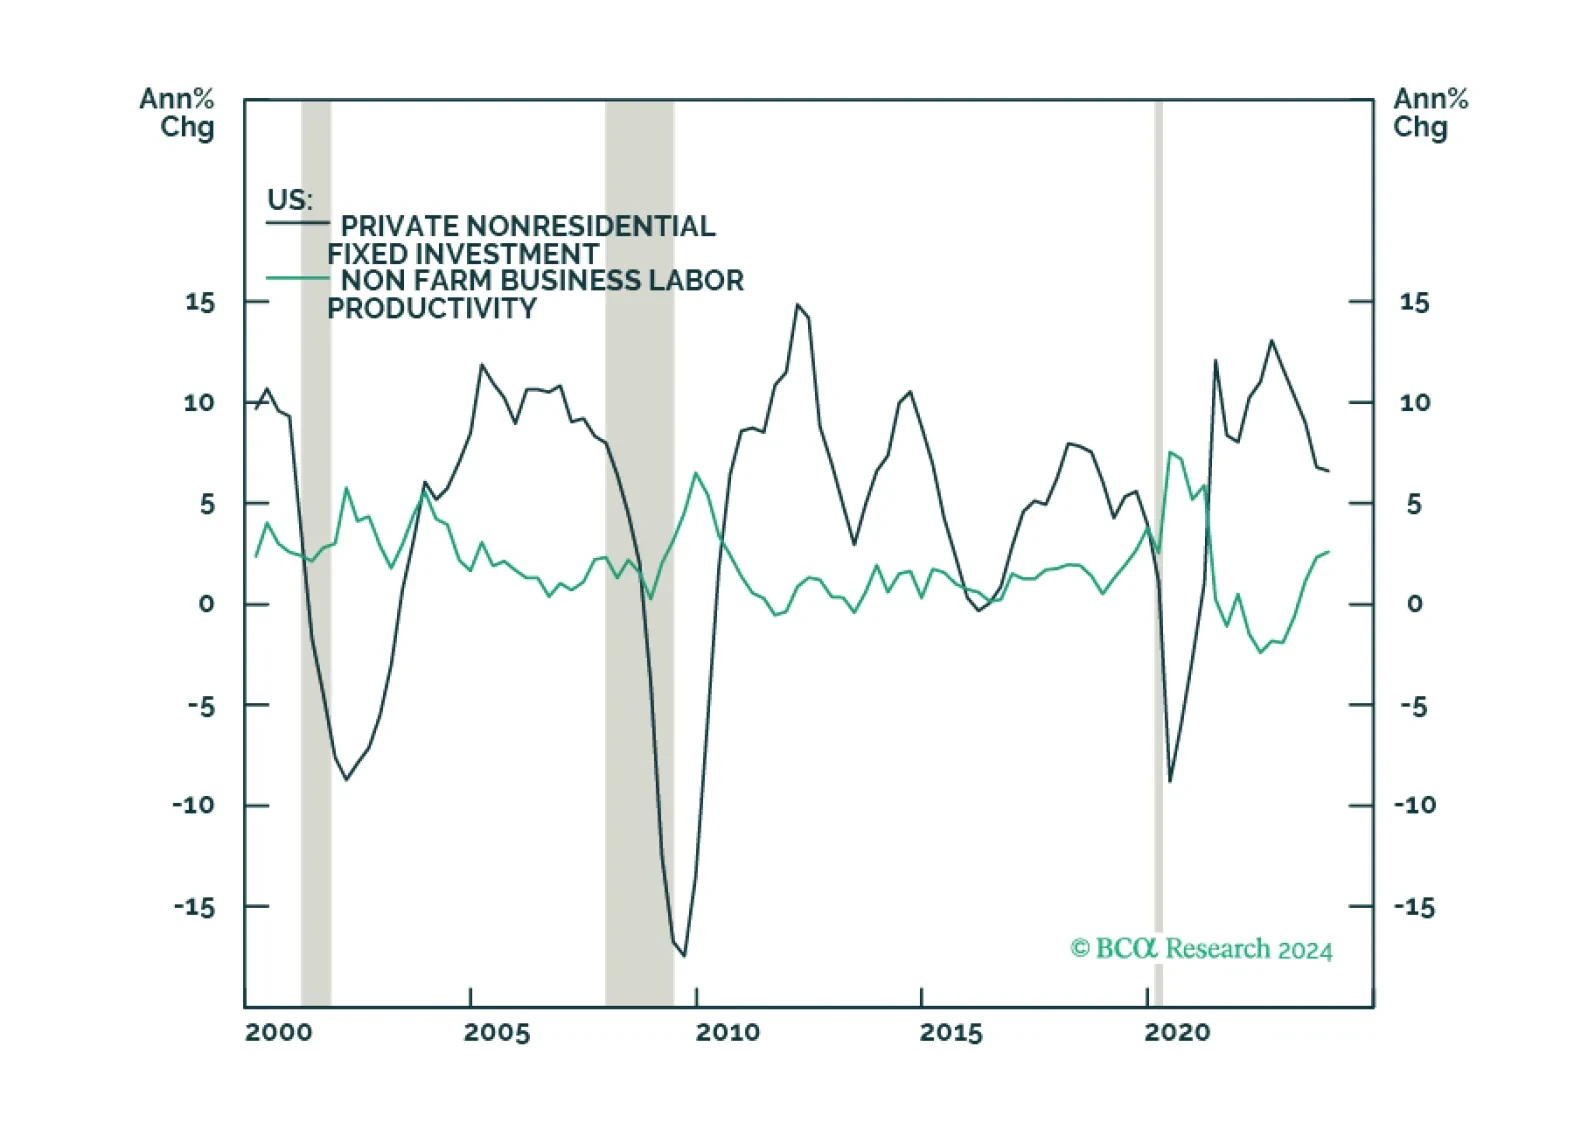
Inflationary pressures this year will remain subdued as labor-productivity growth – driven by strong capex and R+D spending – continues. This will make the Fed more confident in beginning its policy-rate-cutting cycle in June, and will keep gold well bid. We are raising our gold target to $2,300/oz. We continue to expect no recession this year.
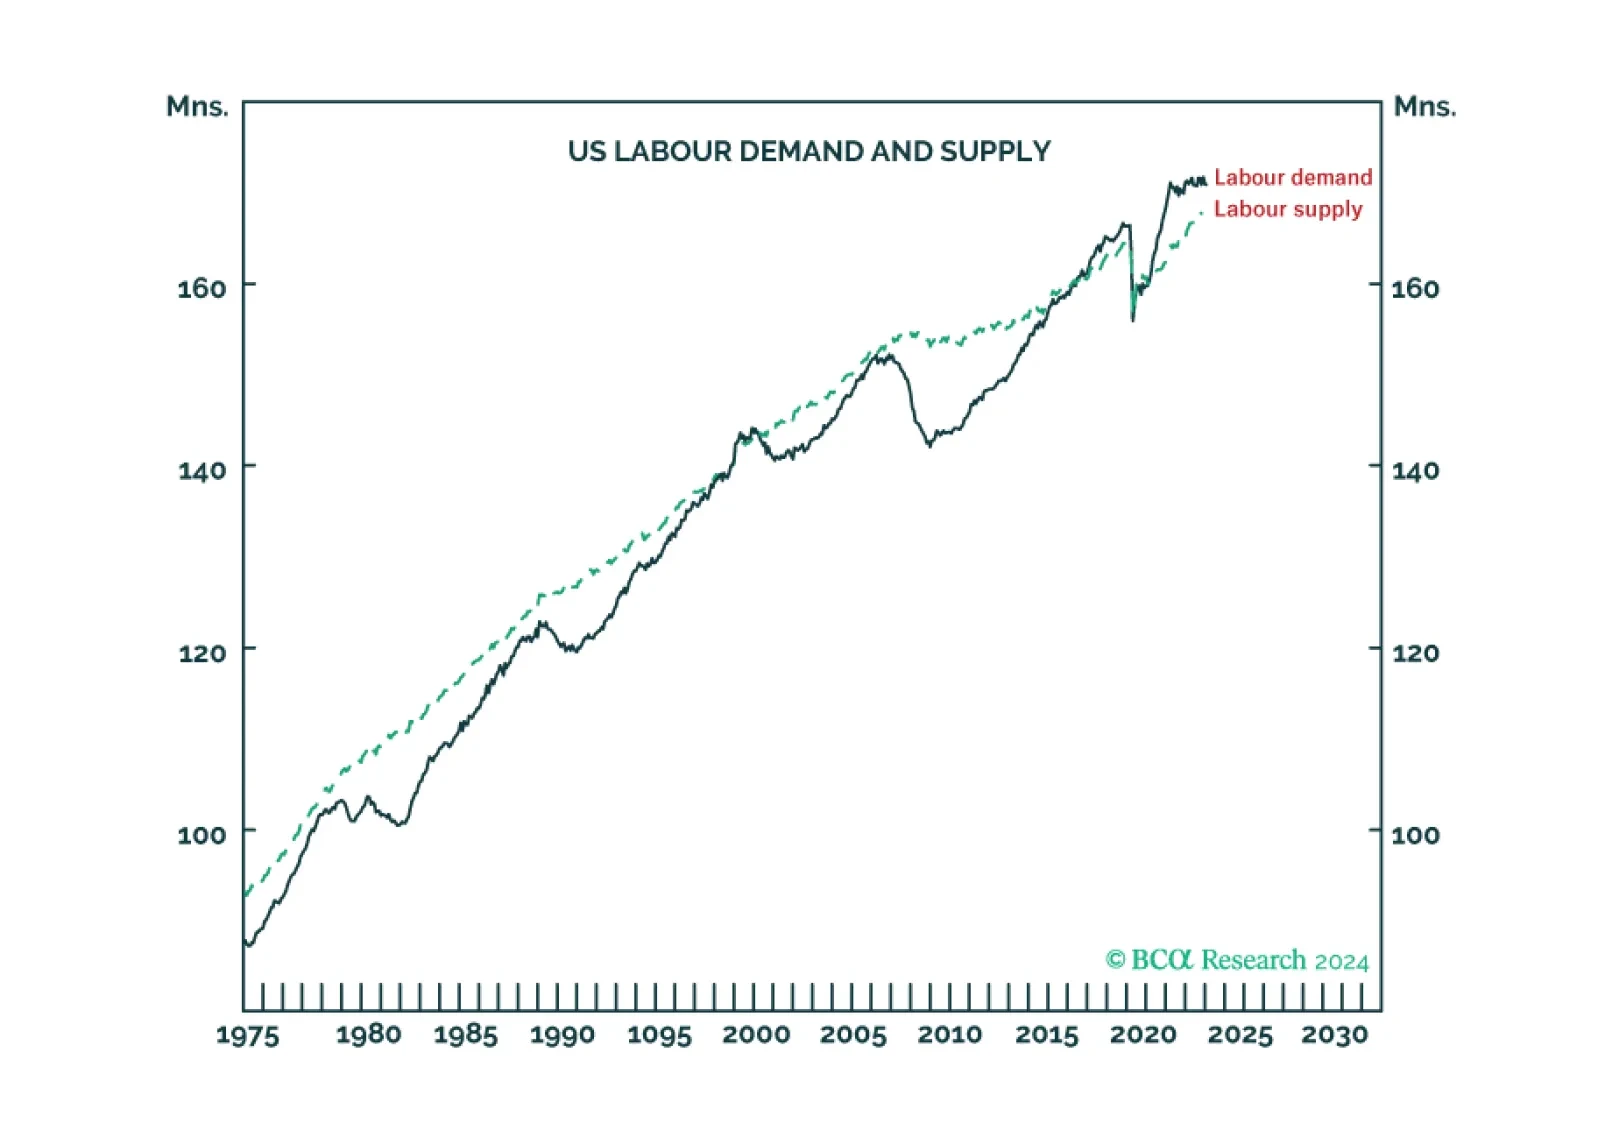
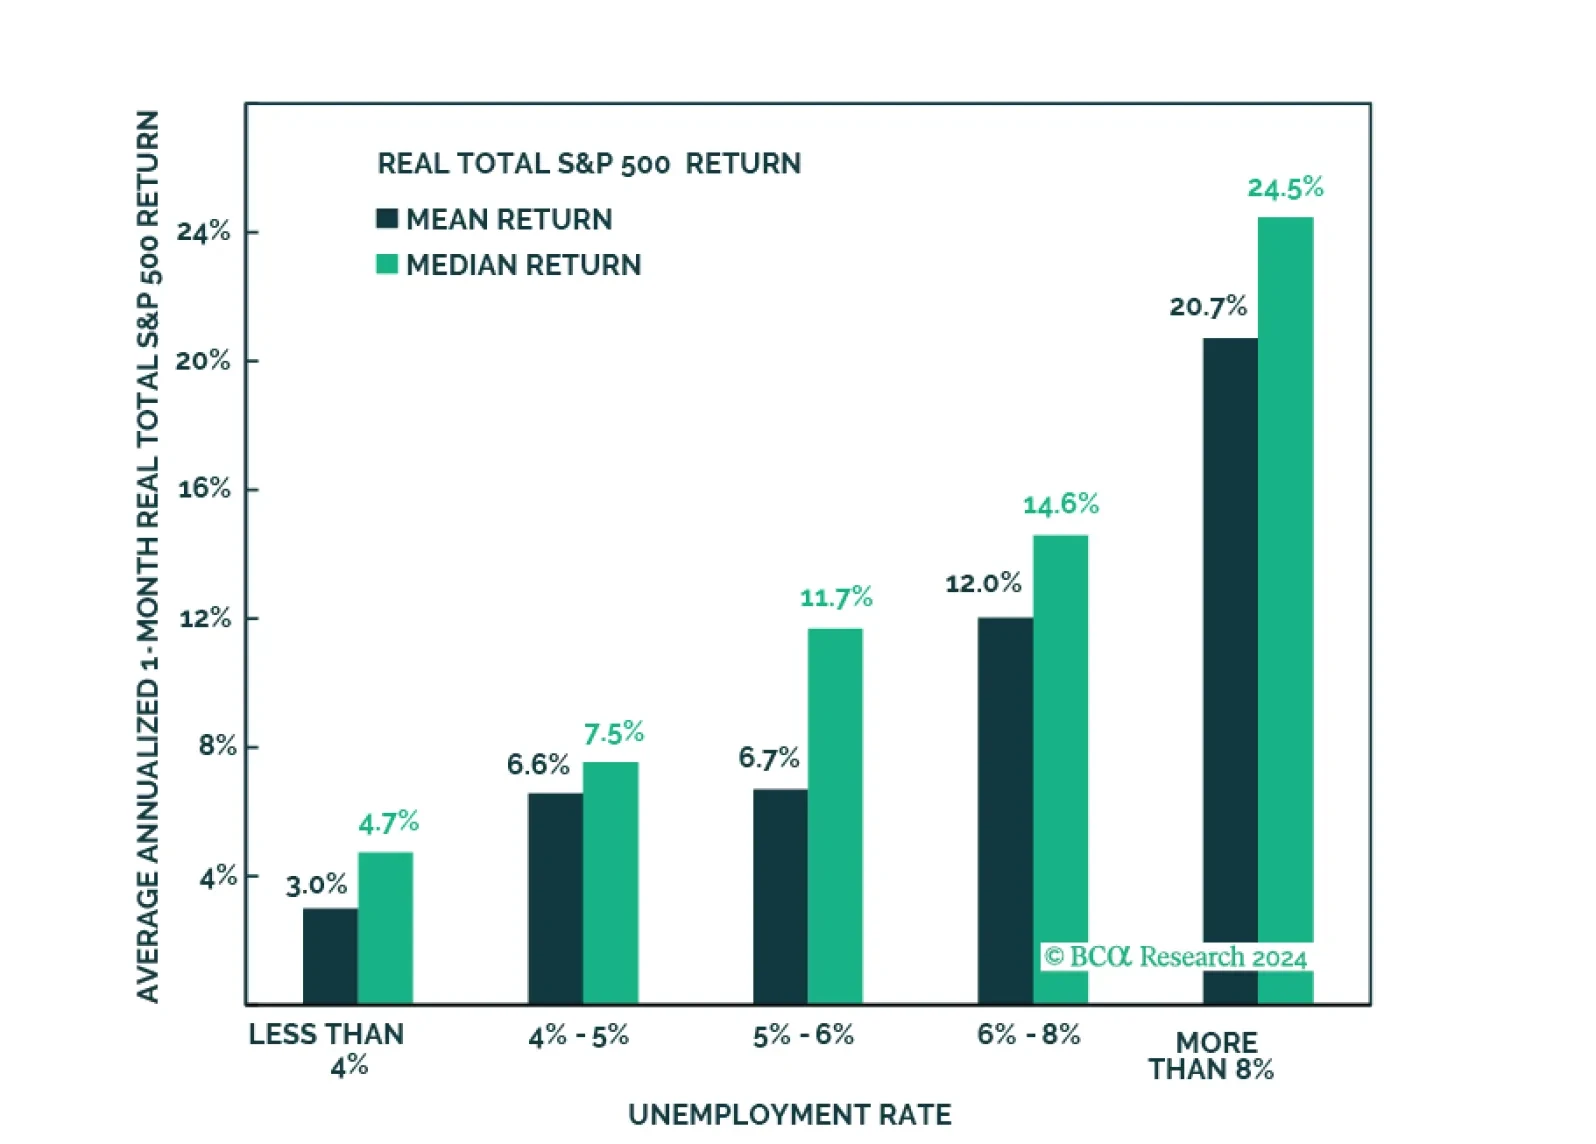
For the first time in at least fifty years, US labour supply is running well below labour demand, meaning the US economy is ‘inverted’. We discuss how and why the economy inverted, and what it means for recession, inflation, and asset allocation. Plus: NVDA is at a consolidation point.
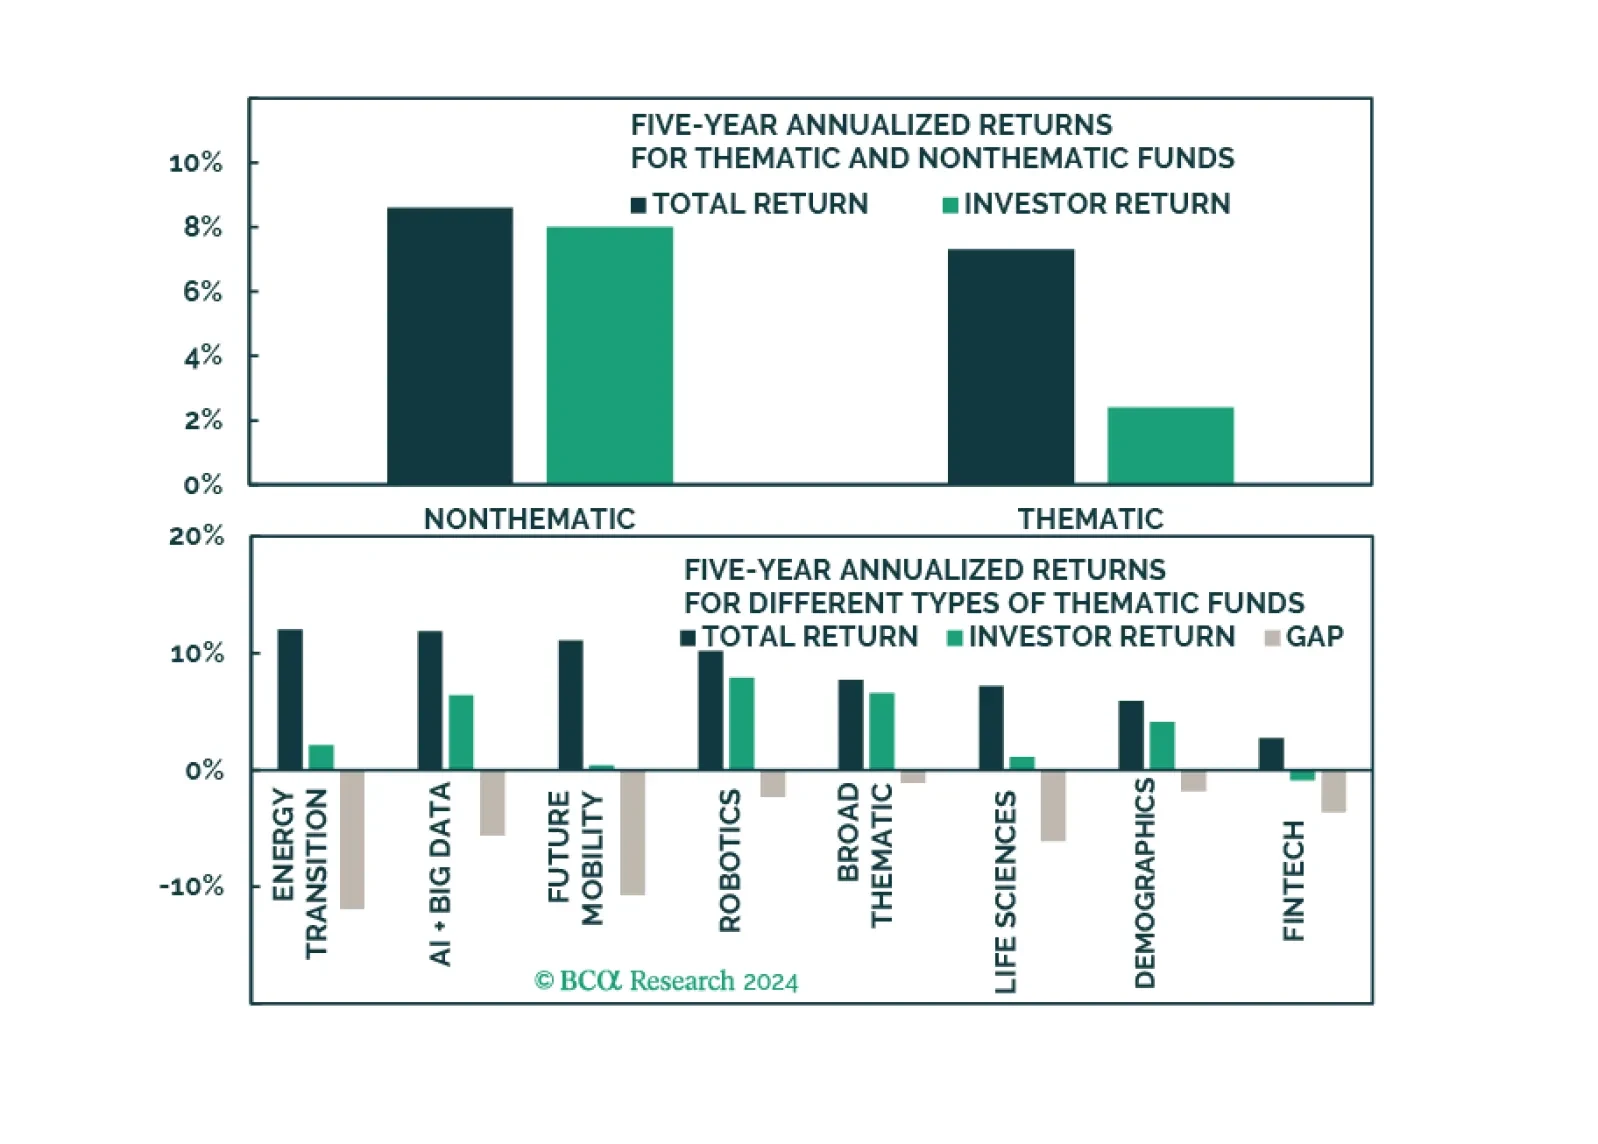
Special Report Thematic investing has become increasingly important for investors over the past few years. However, the vast majority of investors underperform when investing in thematic strategies. In this report we provide three tips for investors who wish to allocate to thematic strategies. These tips have little to do with identifying transformative paradigm shifts, but rather with how to profitably take advantage of them in markets.
In this Strategy Outlook we examine why, contrary to popular perception, the odds of a global recession over the next 12 months are rising not falling.