Skip to main content

Latest from BCA Research
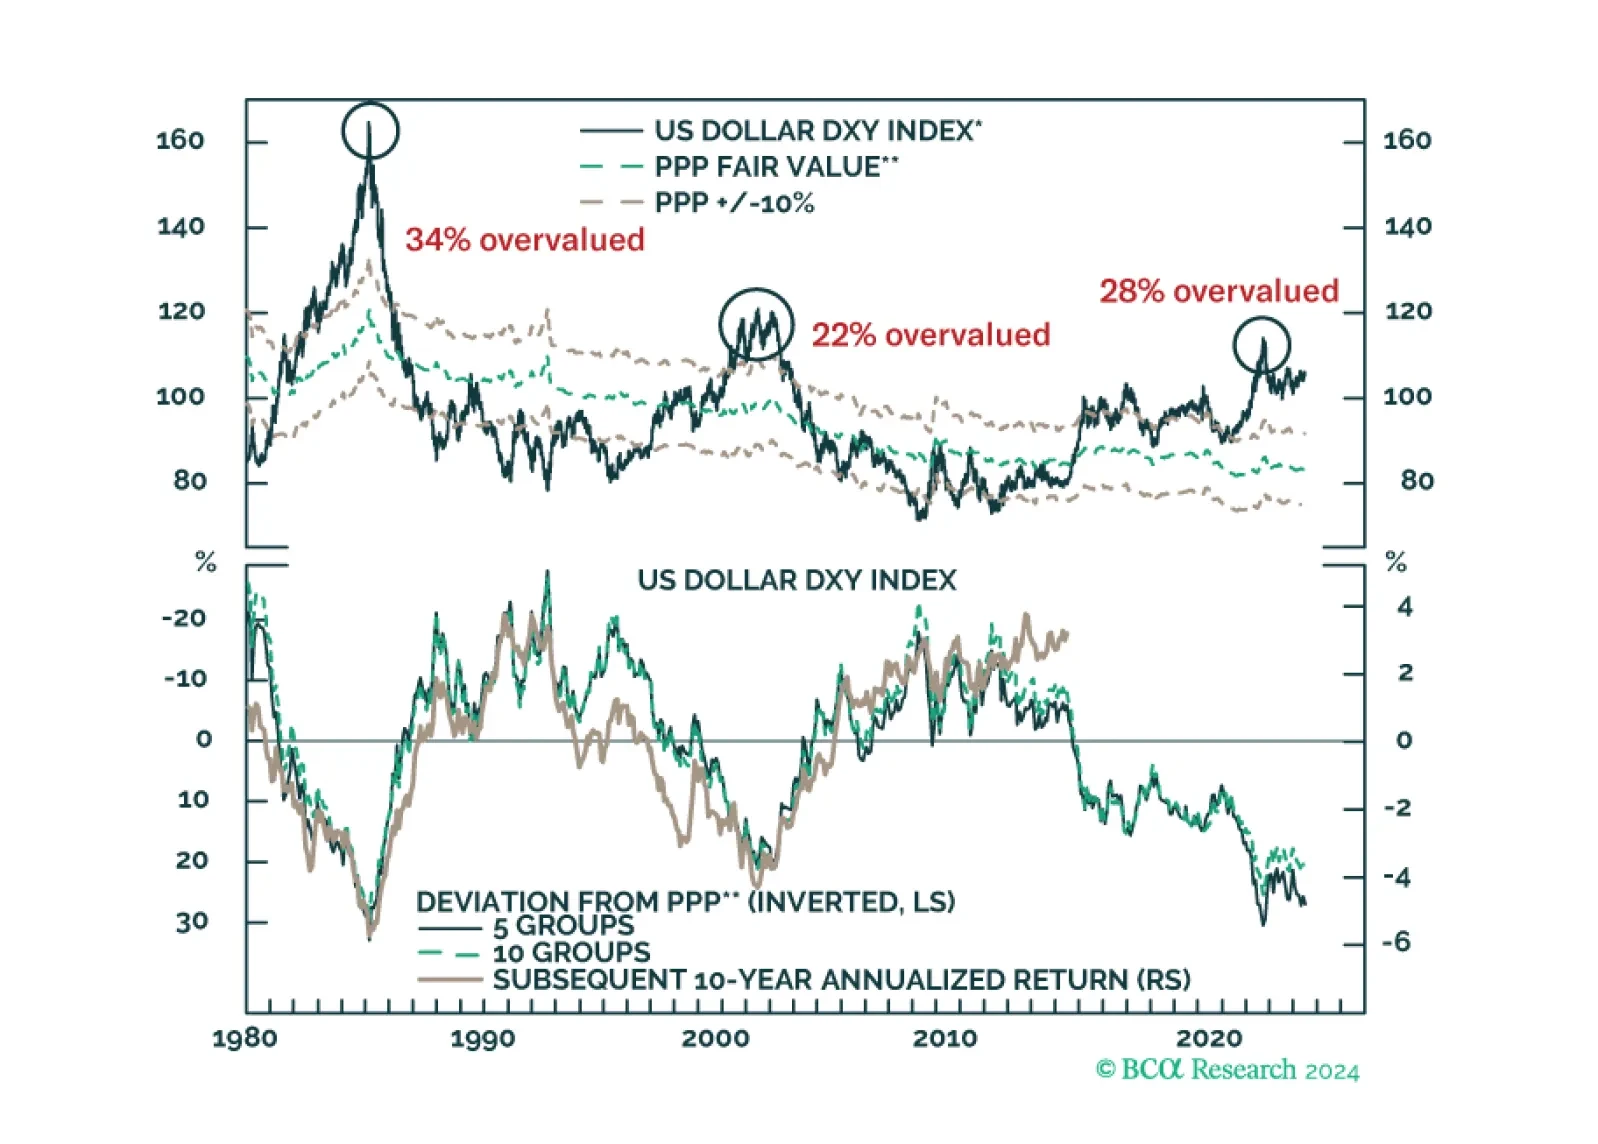
Special Report In this report, we try to gauge how long the exceptional performance of the US can last, but from a more nuanced angle – inflows into US assets and the impact on the dollar and bond yields. Our work suggests that investors should not make any huge bets on the dollar today, but should be short over the longer term (3-5 years). Empirical evidence also suggests you want to be long US bonds into any downturn, relative to global-ex-US duration-matched government securities, but that view becomes less certain if the global economy avoids a downturn in the next few months. What is interesting in this report are high some conviction views across currencies, bonds and precious metals.
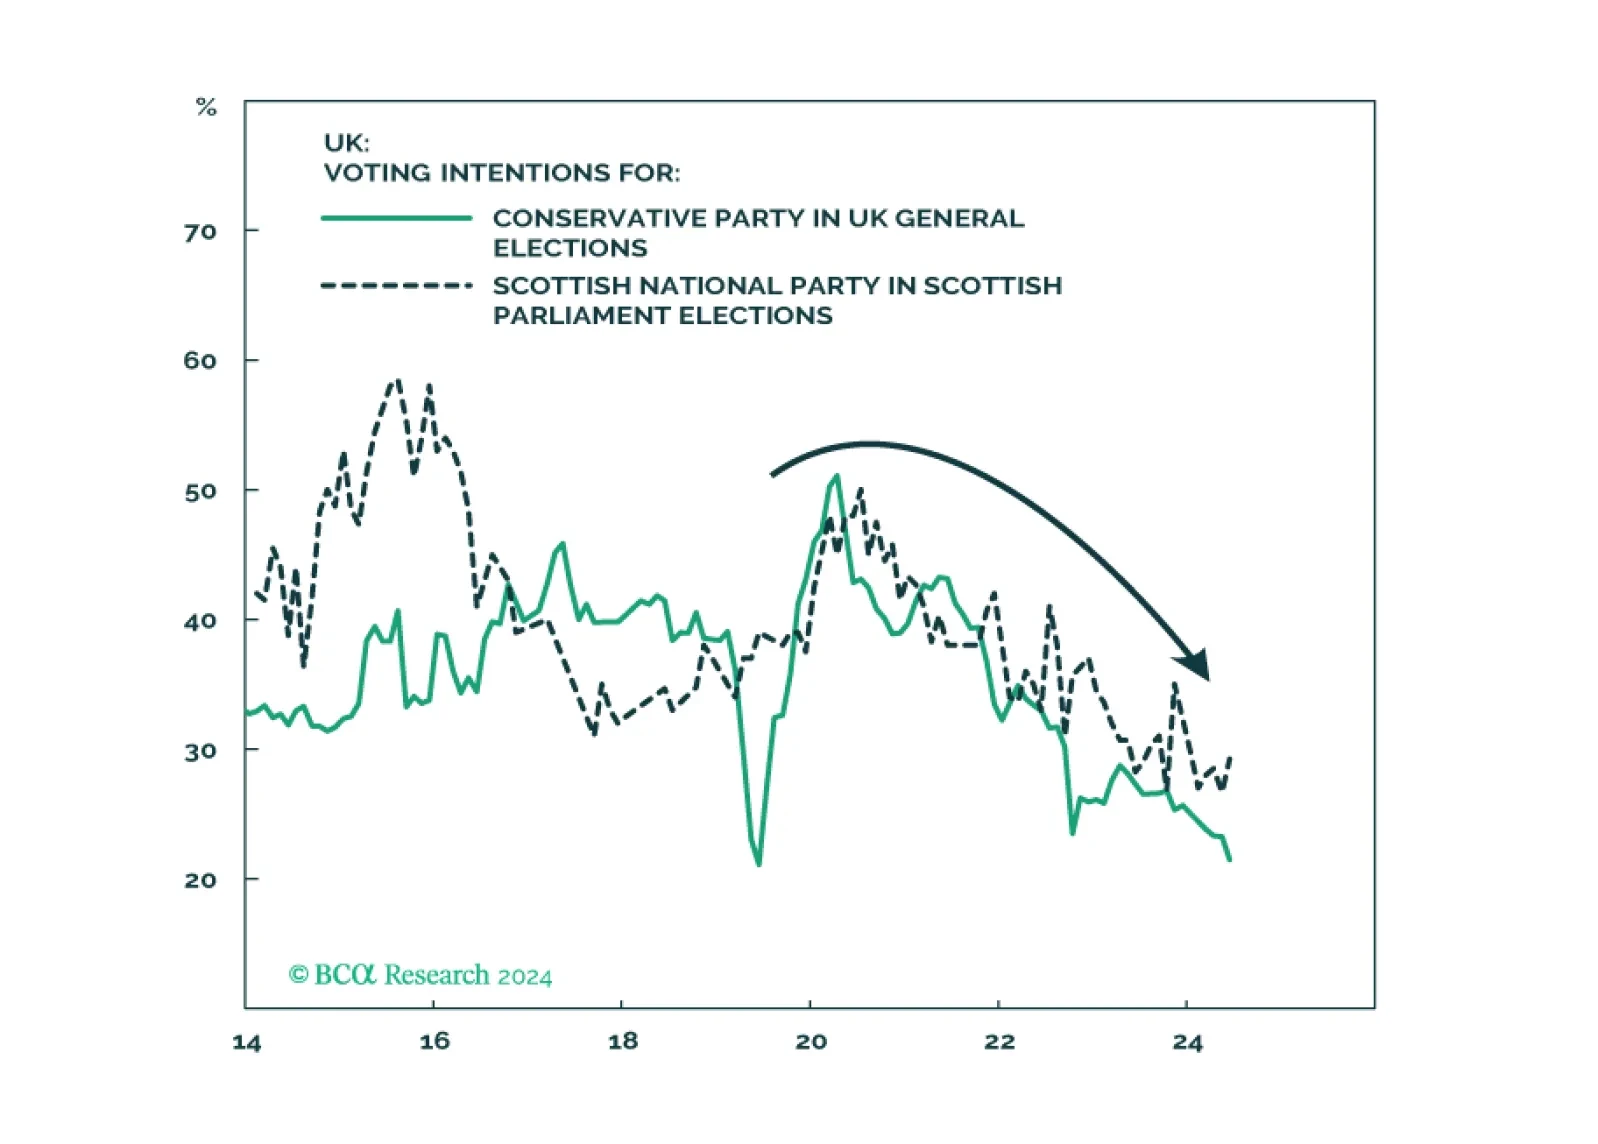
Special Report The Labour Party’s comeback in the UK is widely expected and will lead to fiscal stimulus consisting of increased public spending with minimal tax hikes. But a sweeping single-party majority will reduce social unrest only at the cost of higher taxes over the medium term. The paradigm has shifted away from the Thatcherite low-tax regime of the now-discredited Tories. v
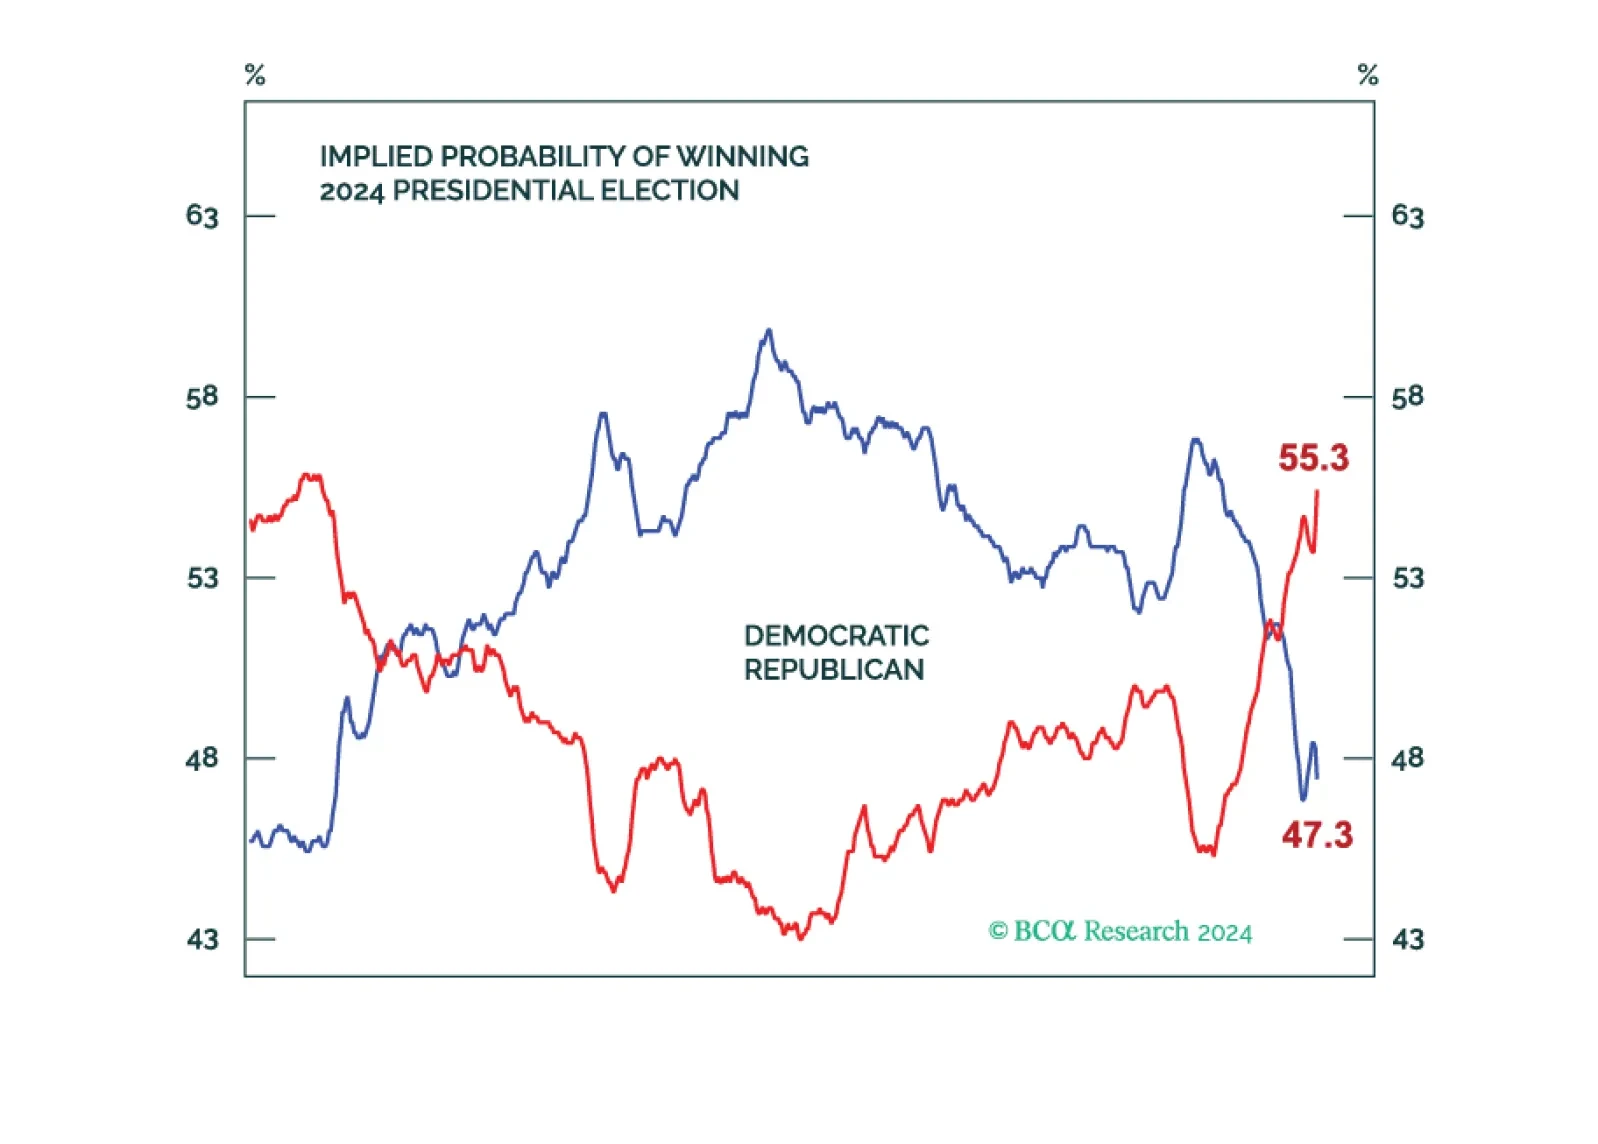
The bond market should sell off and drag stocks down on higher odds of a single-party sweep, policy uncertainty, unorthodox Trump presidency, aggressive tariffs, large tax cuts, large budget deficits, labor shortages, a fired Fed chair, and higher inflation.
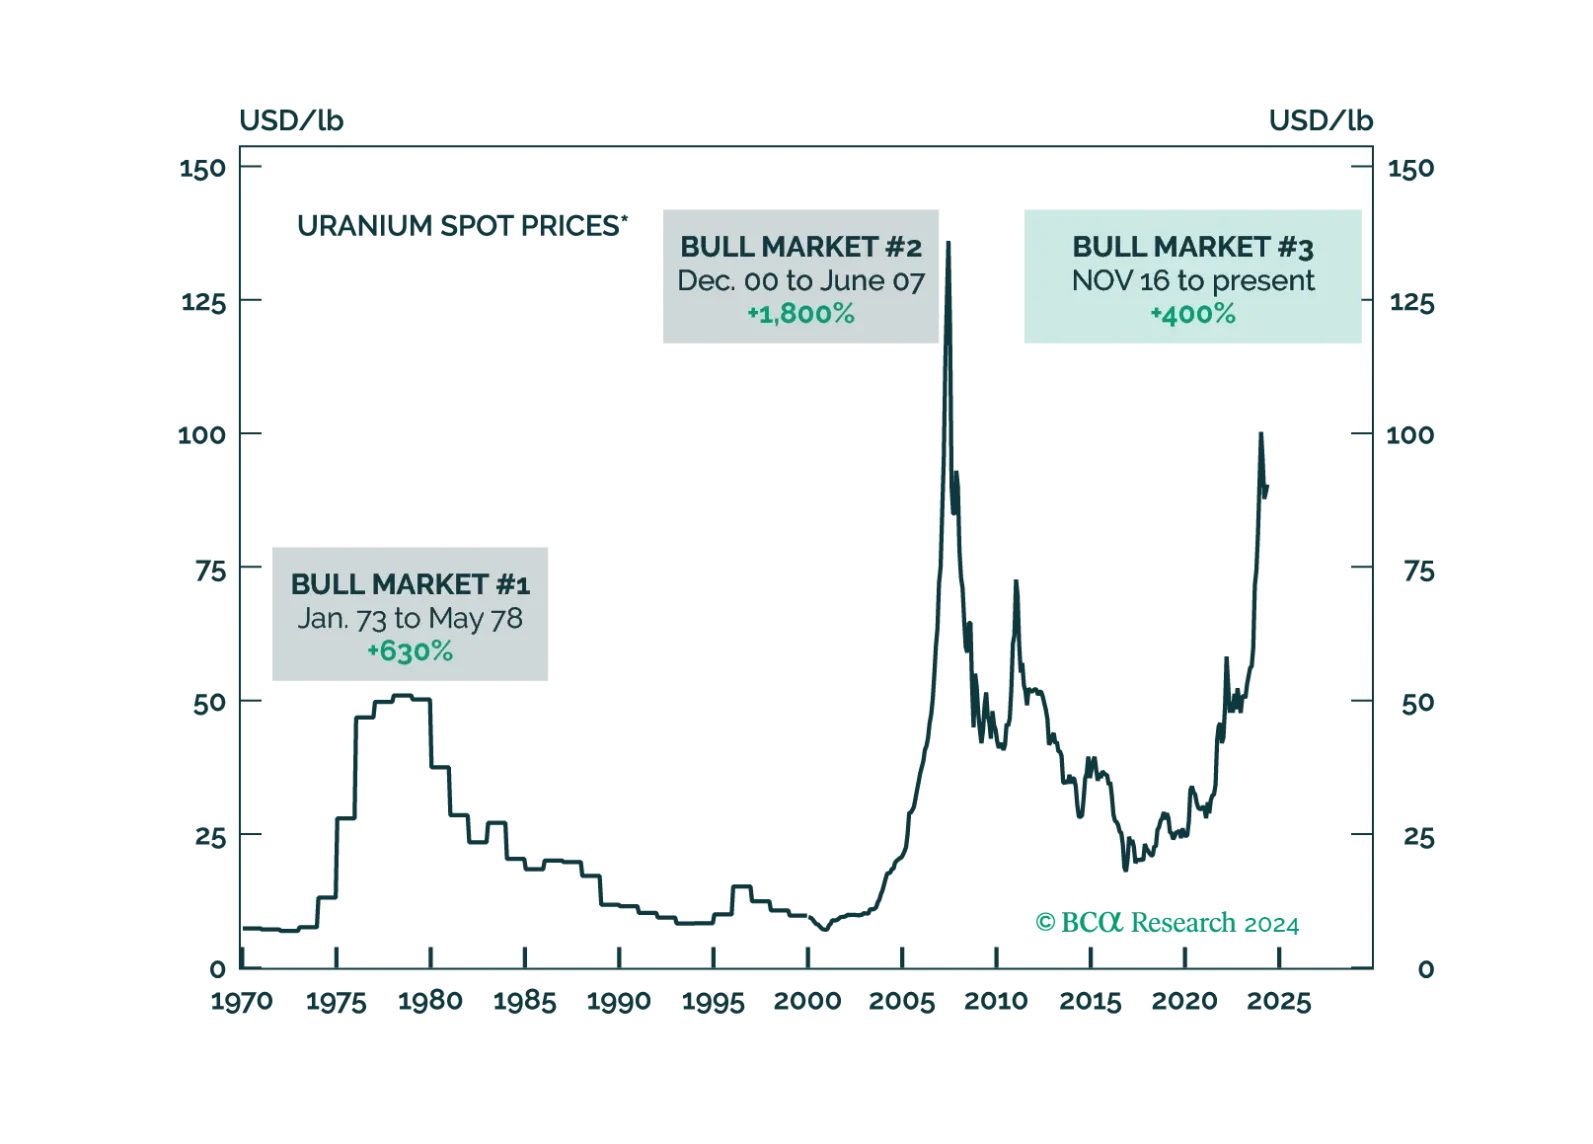
Bank Credit Analyst The uranium bull market is climbing a wall of doubt. Read more about the underlying supply-demand fundamentals supporting the current bull market.
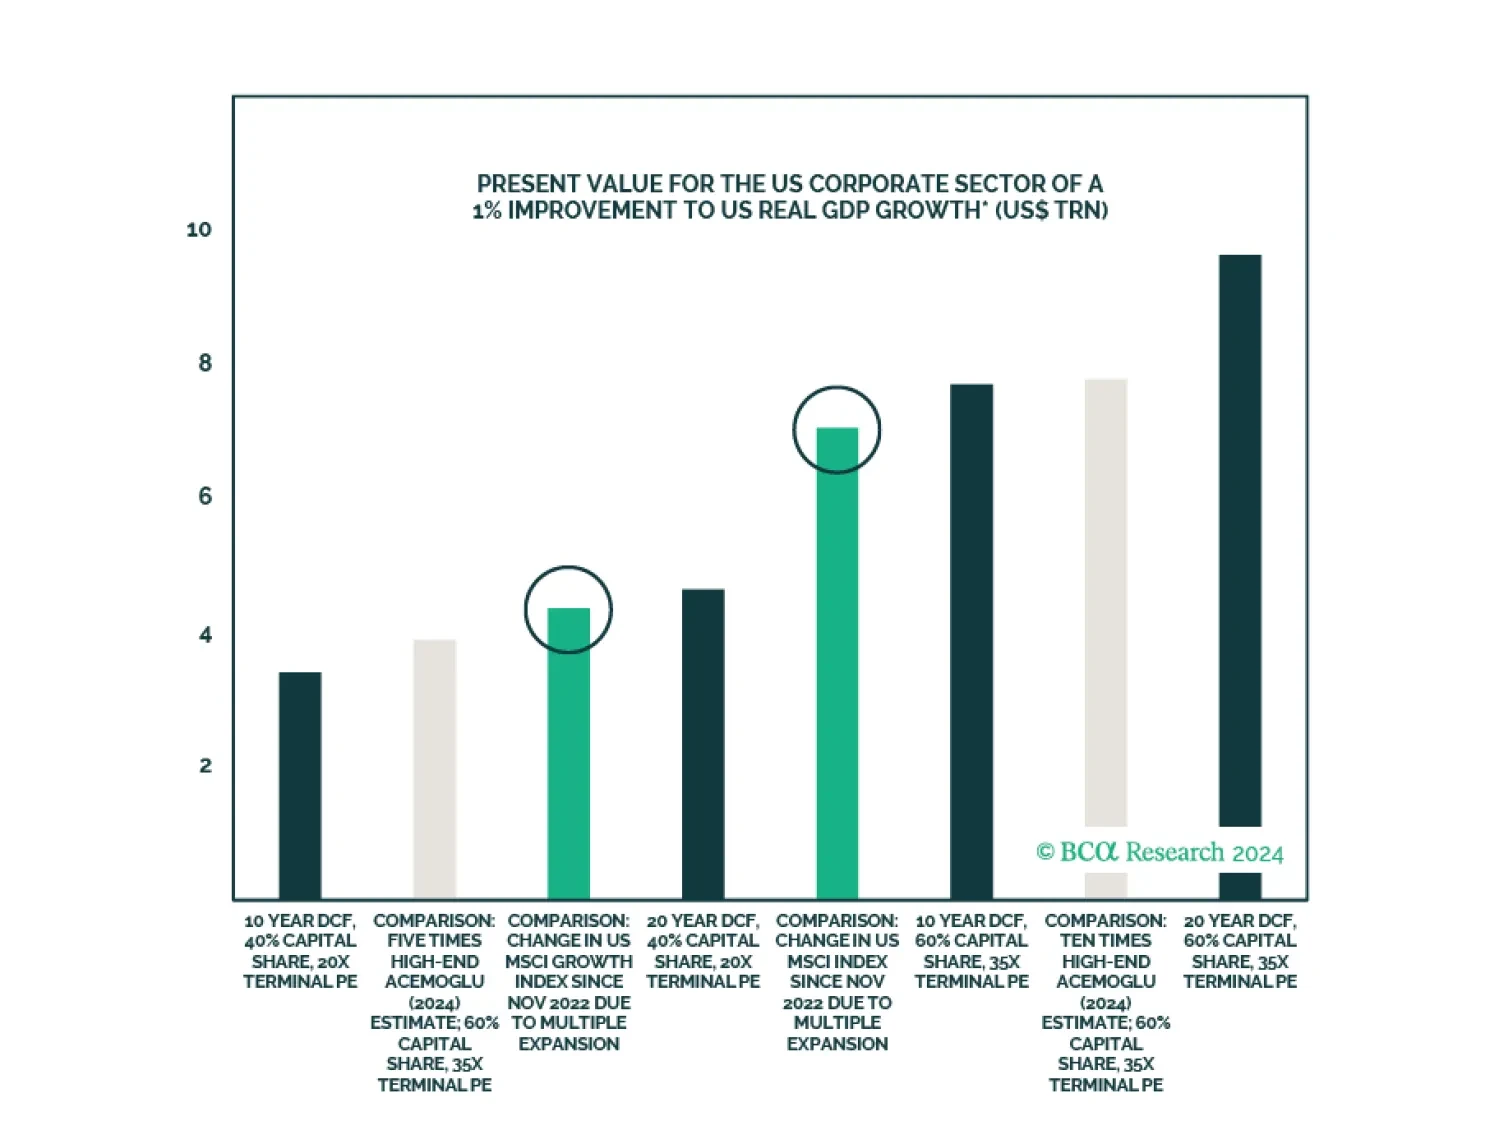
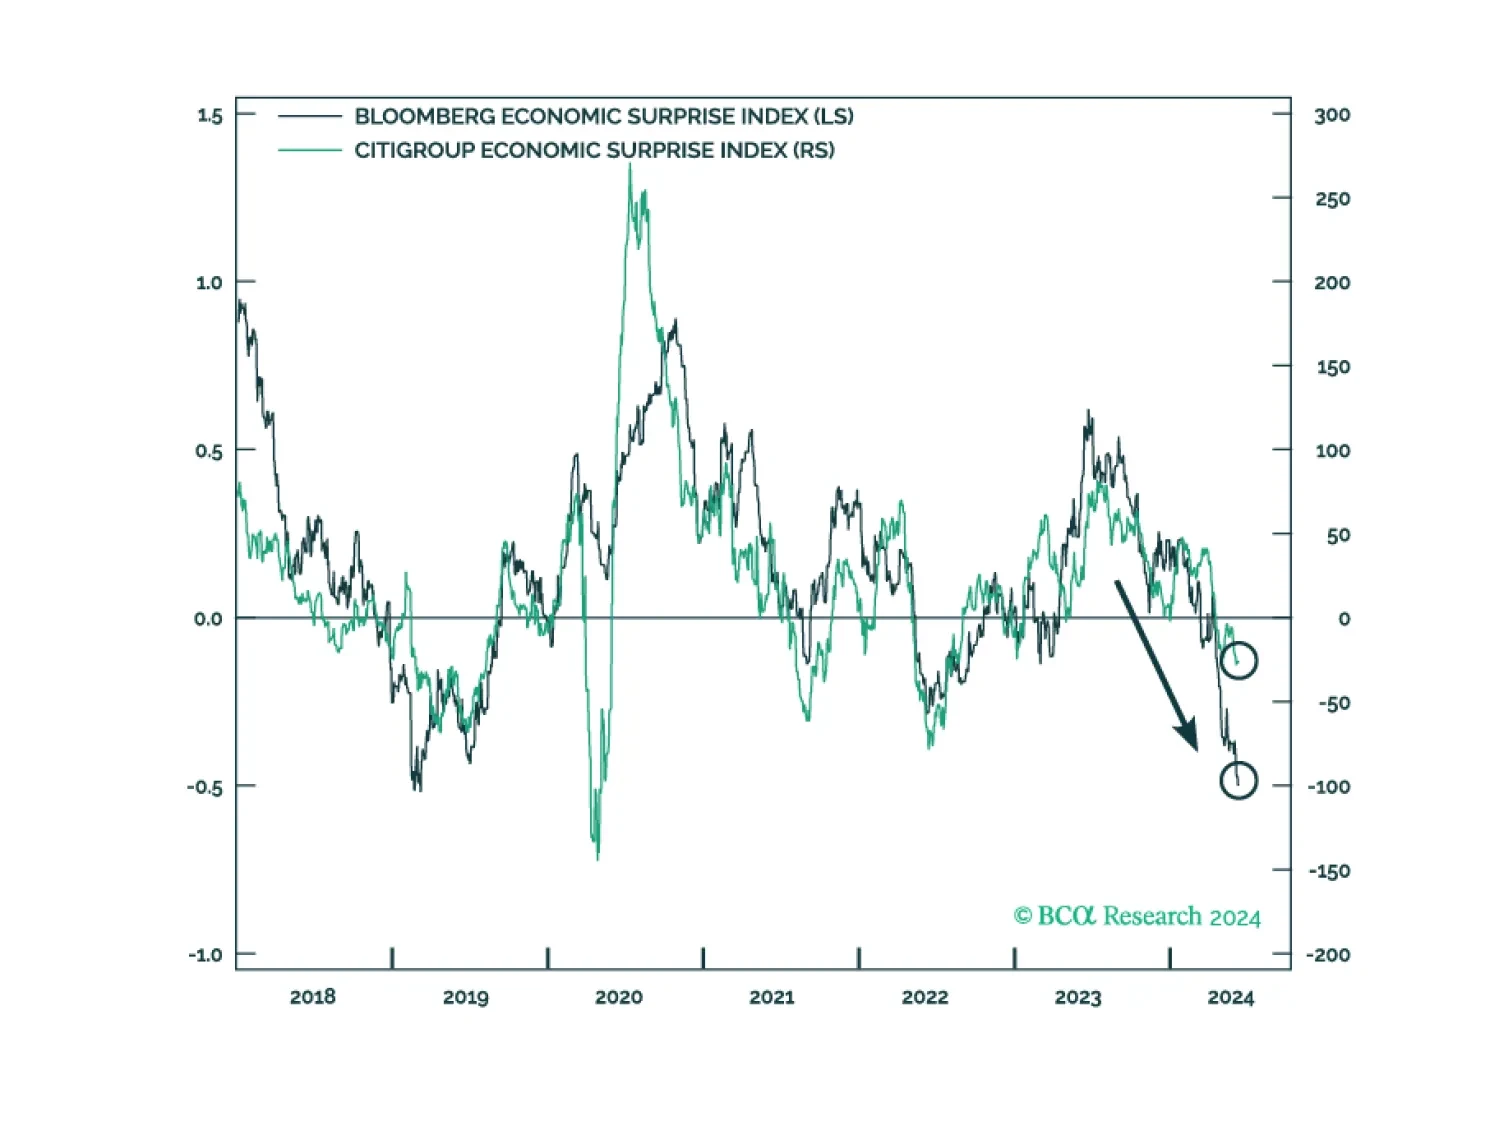
Bank Credit Analyst In Section I, we examine some concerning signs of US economic weakness that emerged in June. We also discuss portfolio positioning in the face of falling interest rates and cross-check our recommended US equity overweight in the face of extremely optimistic expectations about AI’s impact on growth. We conclude that defensive positioning continues to be warranted. In Section II, we dig into those optimistic expectations for AI. We find that the US equity market is significantly overvalued unless the deployment of AI technology causes a 10-to-20 year productivity surge in line with what occurred during the IT revolution of the 1990s, with persistently high margins on the revenue generated from the improvement in growth. We doubt that AI will end up truly boosting economic activity by this magnitude.
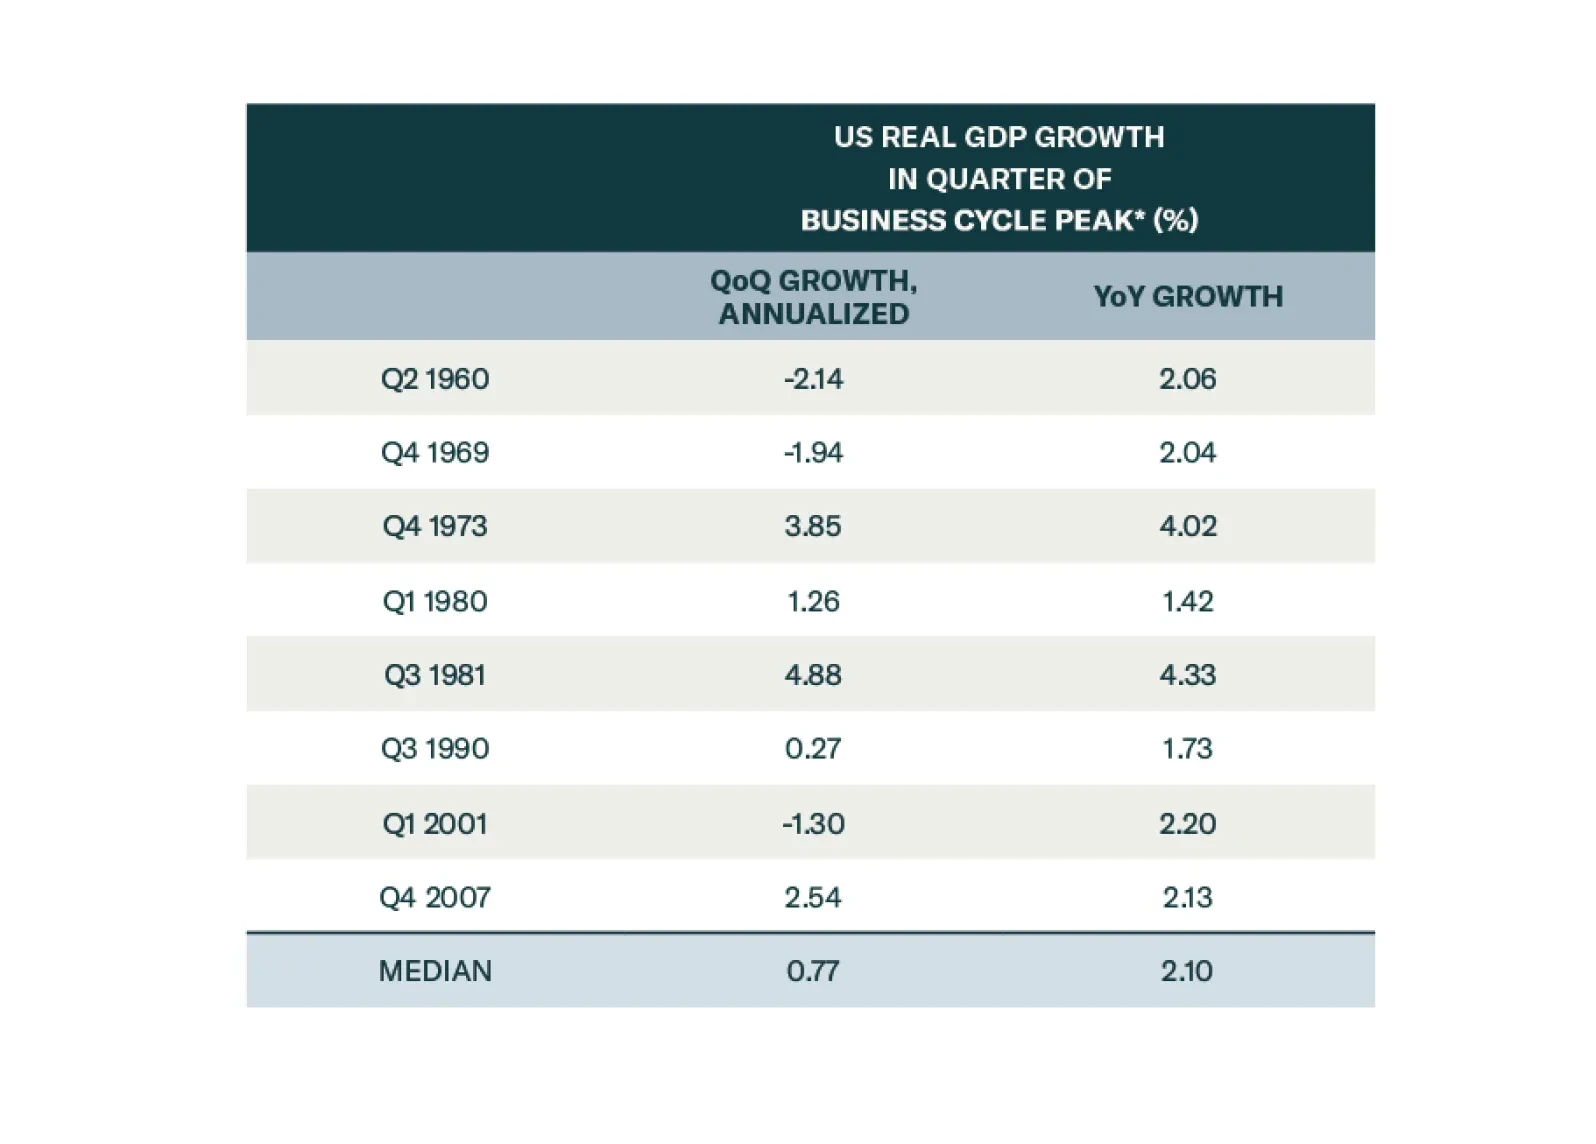
The consensus soft-landing narrative is wrong. The US will fall into a recession in late 2024 or early 2025. We were tactically bullish on stocks most of last year, turned neutral earlier this year, and are going underweight today. We conservatively expect the S&P 500 to drop to 3750 during the coming recession.
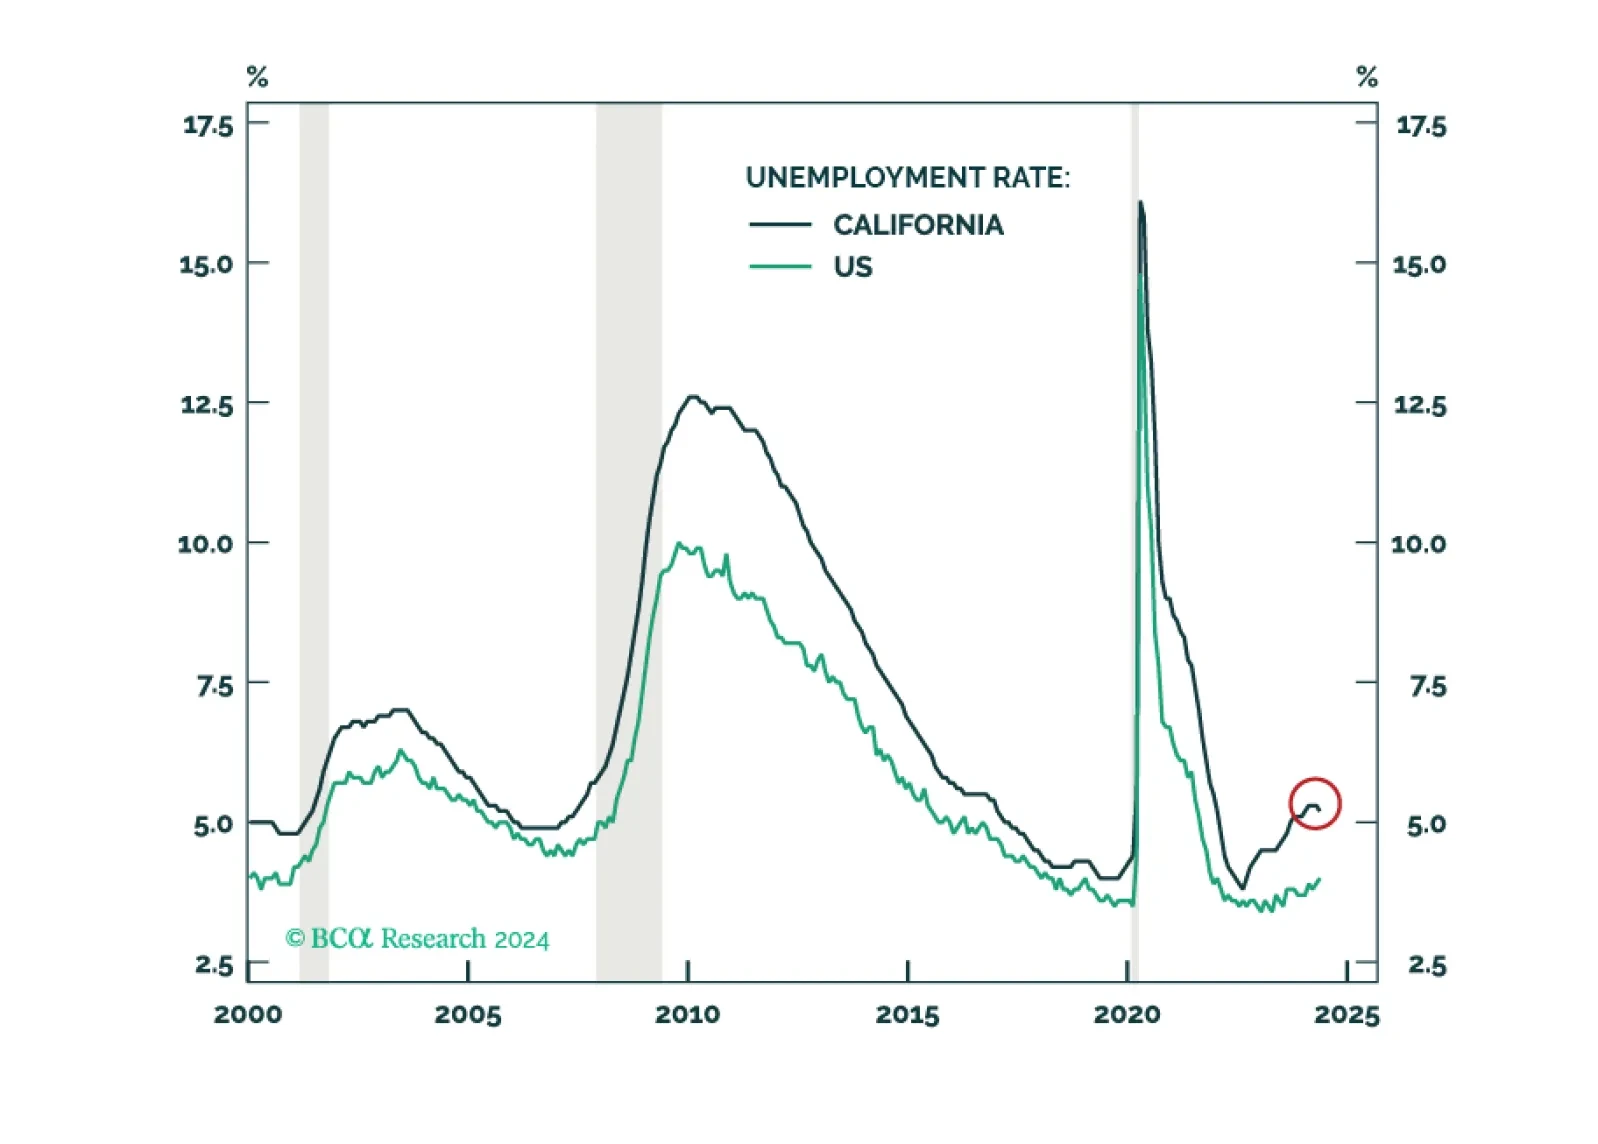
Special Report California and Technology are currently in a downturn but is not apparent from the performance of the NASDAQ. On its own, the job losses in the Tech sector are not significant enough to precipitate a US recession. However, when coupled with direct and indirect spill-over effects into other service sectors, the impact on consumption could trigger a recession. In North America, we are overweight Venture Capital and Private Credit, becoming more optimistic on CRE, and underweight Private Equity.
The end of China’s exponential credit growth will impede structural rallies in Chinese stocks and commodities, but US superstar stocks’ bubble-like valuations will impede them too. Leaving European stocks as the likely structural outperformer. Plus: copper is correcting, NVDA is consolidating.
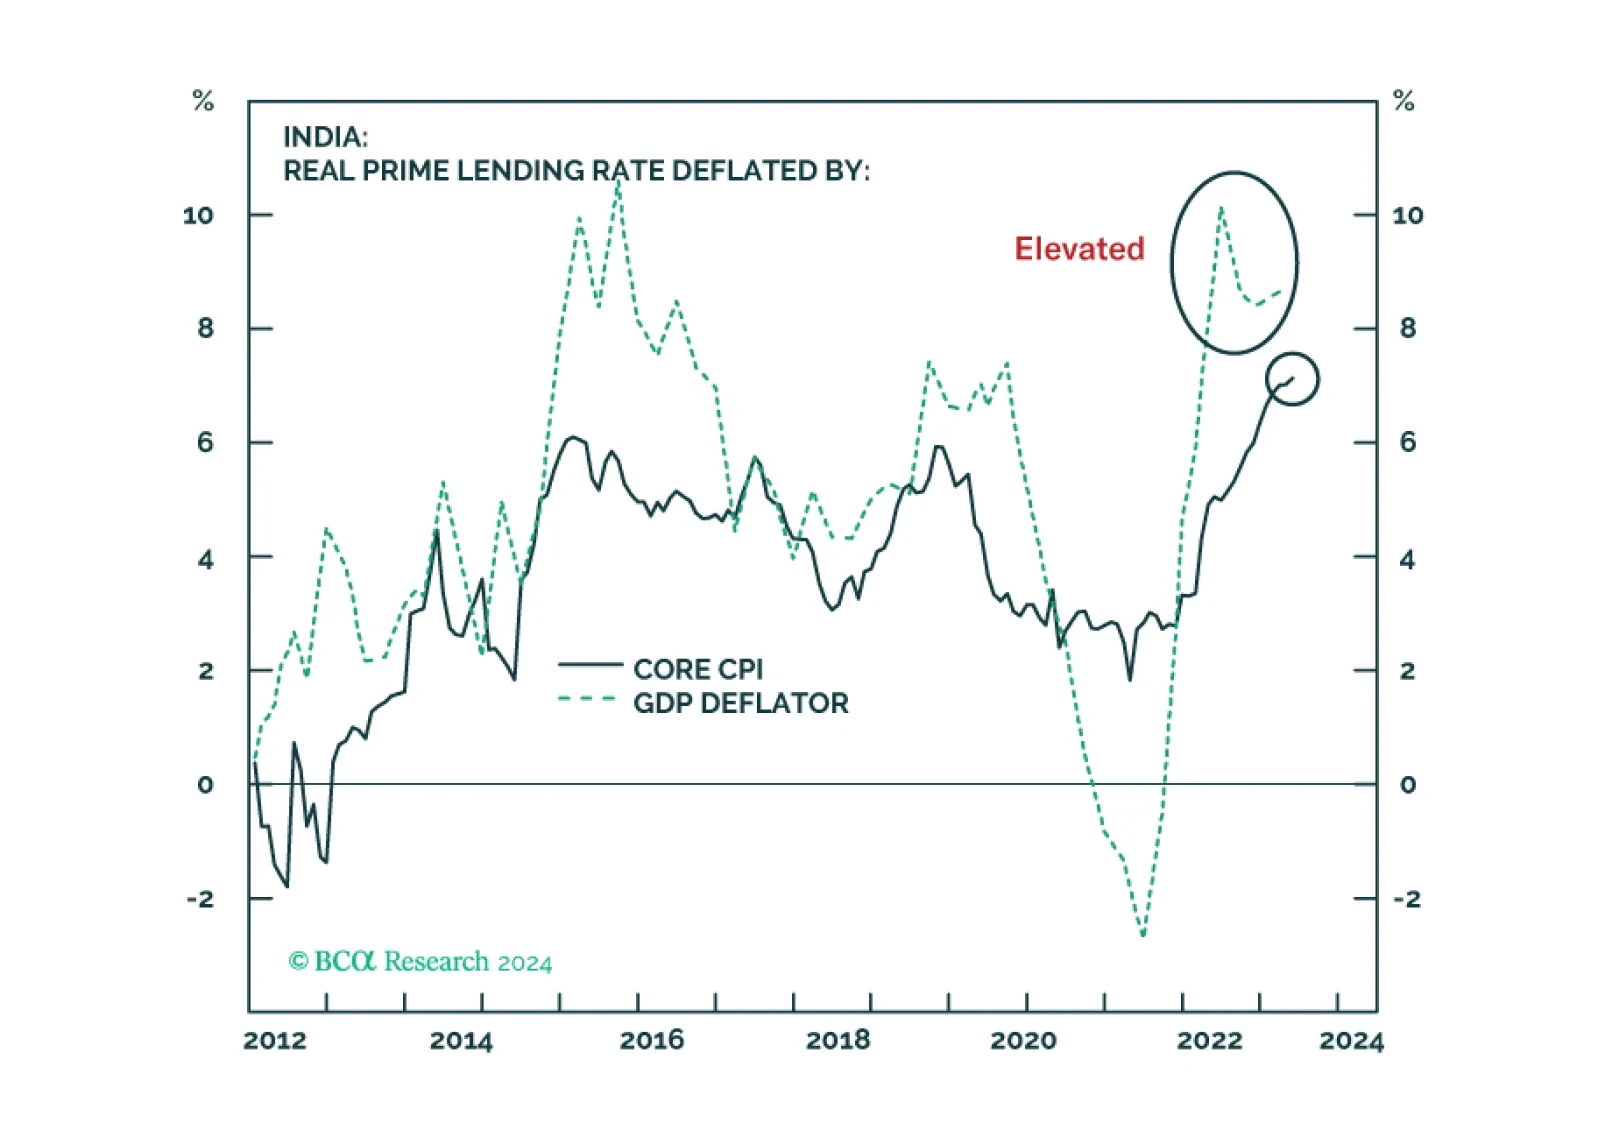
The Indian election outcome is a positive development for the country’s long-term socio-economic outlook. Indian stocks, however, remain vulnerable in the near term due to sharply slowing nominal sales and surging real borrowing costs. Indian domestic bonds, on the other hand, are a buy.