Latest from BCA Research

Is the BoE making a mistake moving toward rate cuts before the end of the summer? What would such a move mean for UK asset prices?
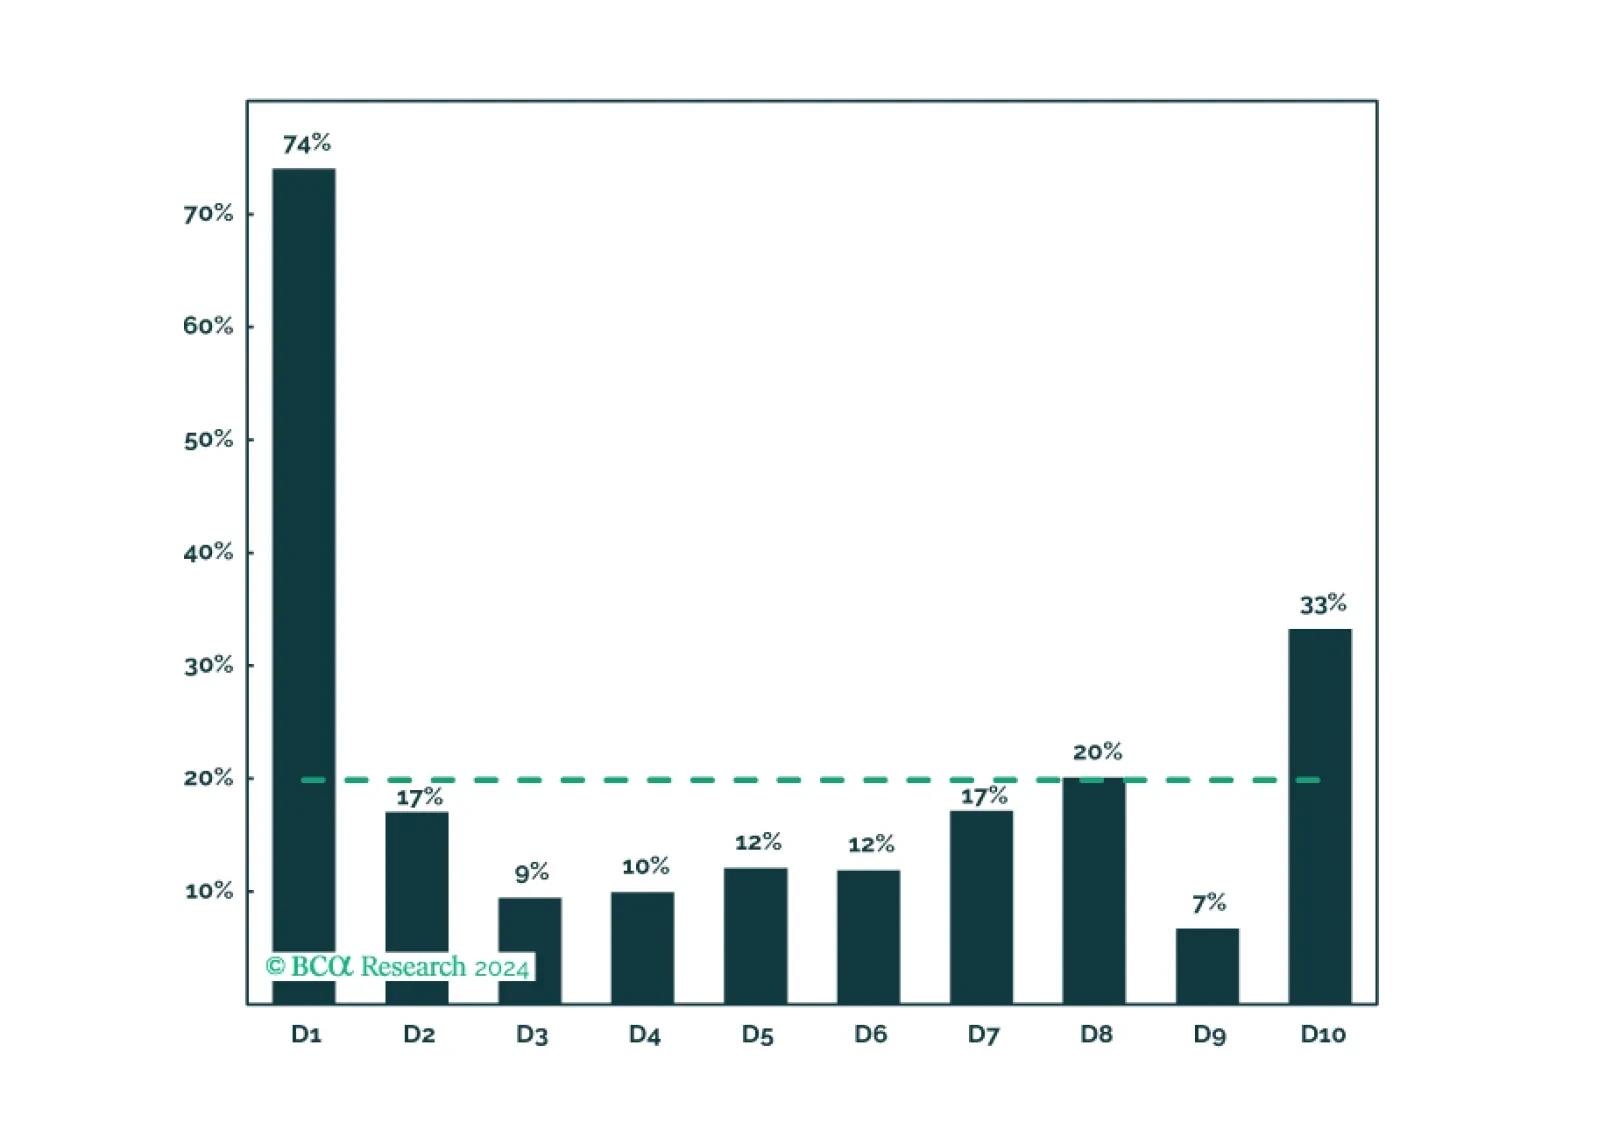
Today’s report recaps last week’s webcast and elaborates on its themes, delving into the empirical evidence underpinning our conviction that asset allocators should underweight equities sparingly and fleetingly. We remain tactically neutral and cyclically bearish.
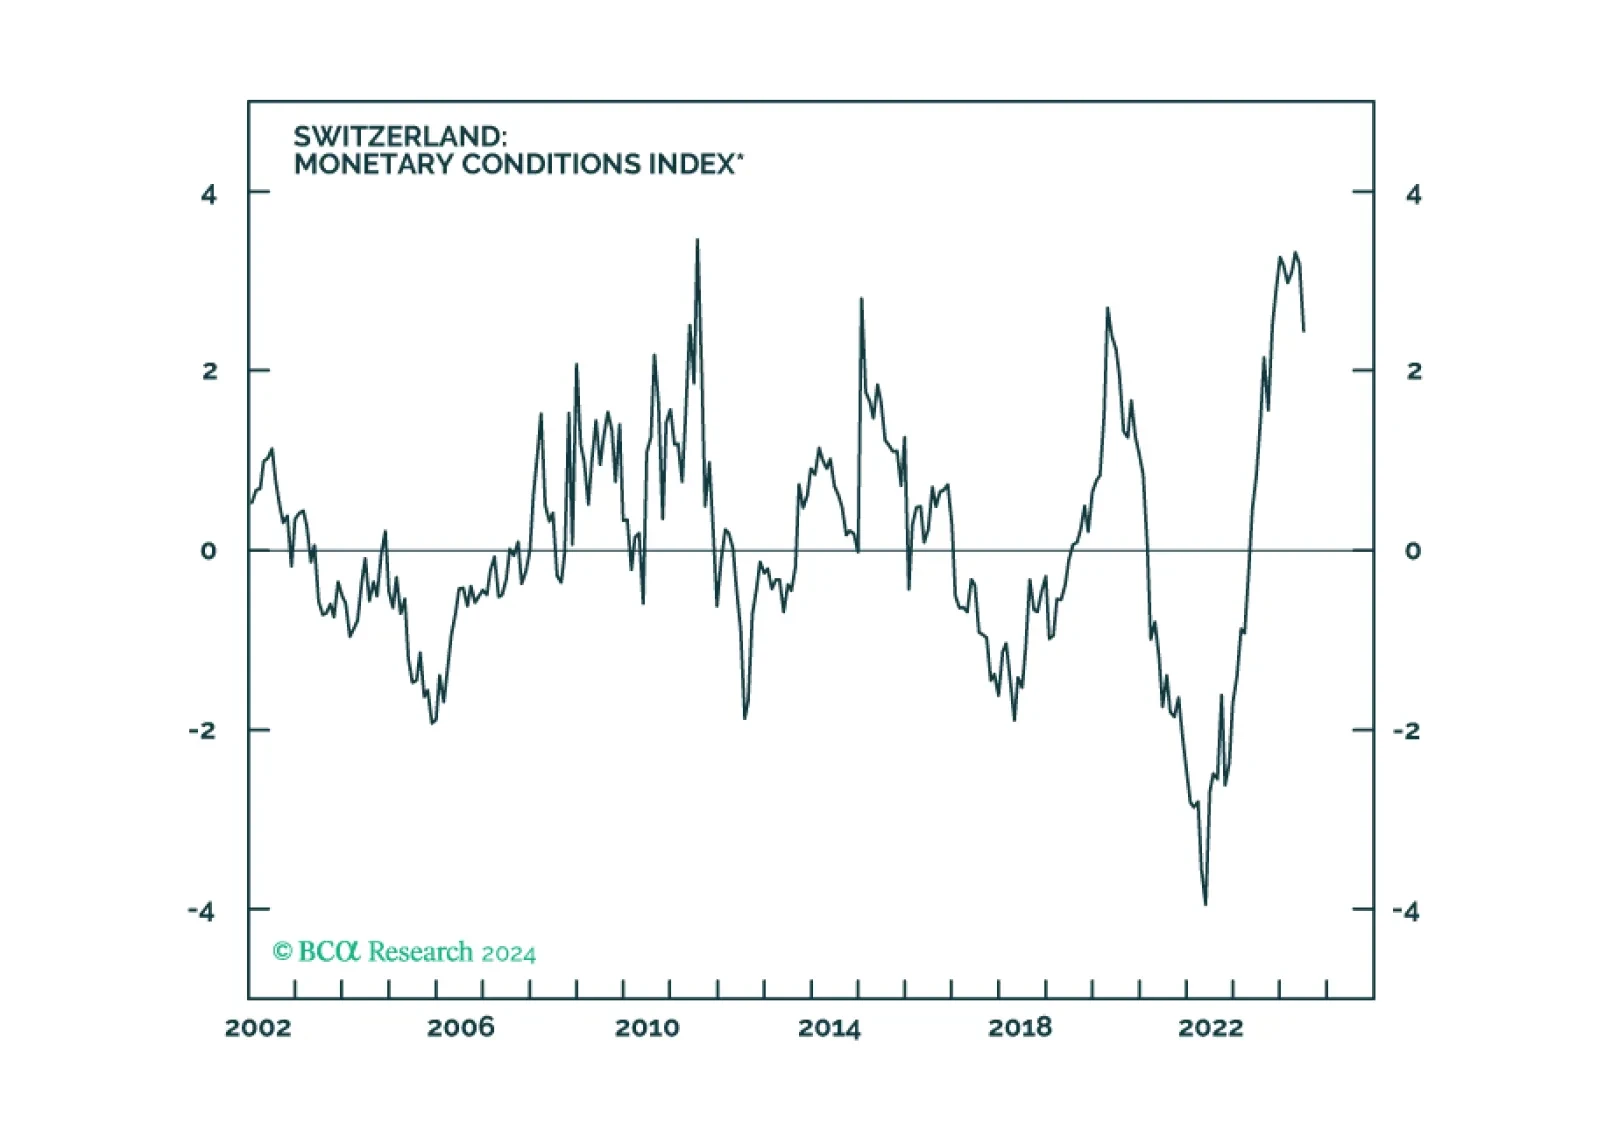
We look at the implications a various European central bank meetings this week, for currency strategy.
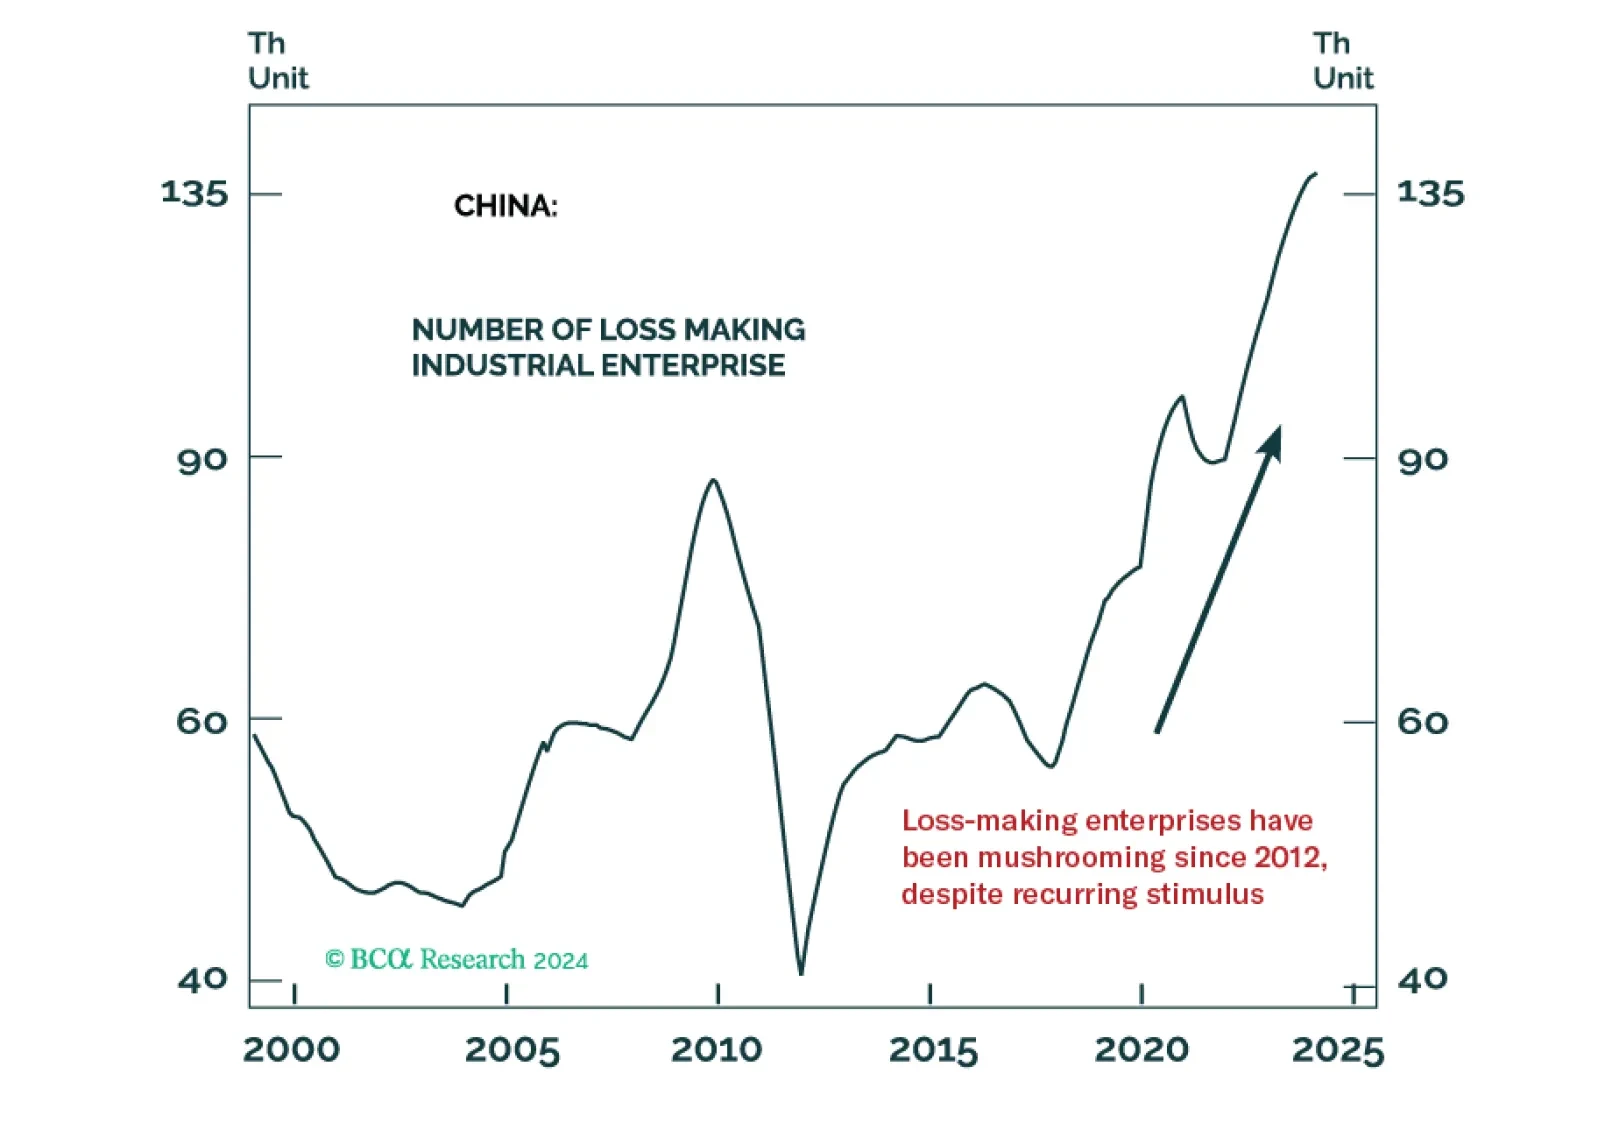
To reduce the Chinese economy’s addiction to credit and use new credit to foster growth, authorities must restructure or shut down numerous negative cash flow enterprises. Slumping US and global growth will lead to lower US bond yields. Yet, the trade-weighted greenback will likely appreciate if global risk assets sell off.
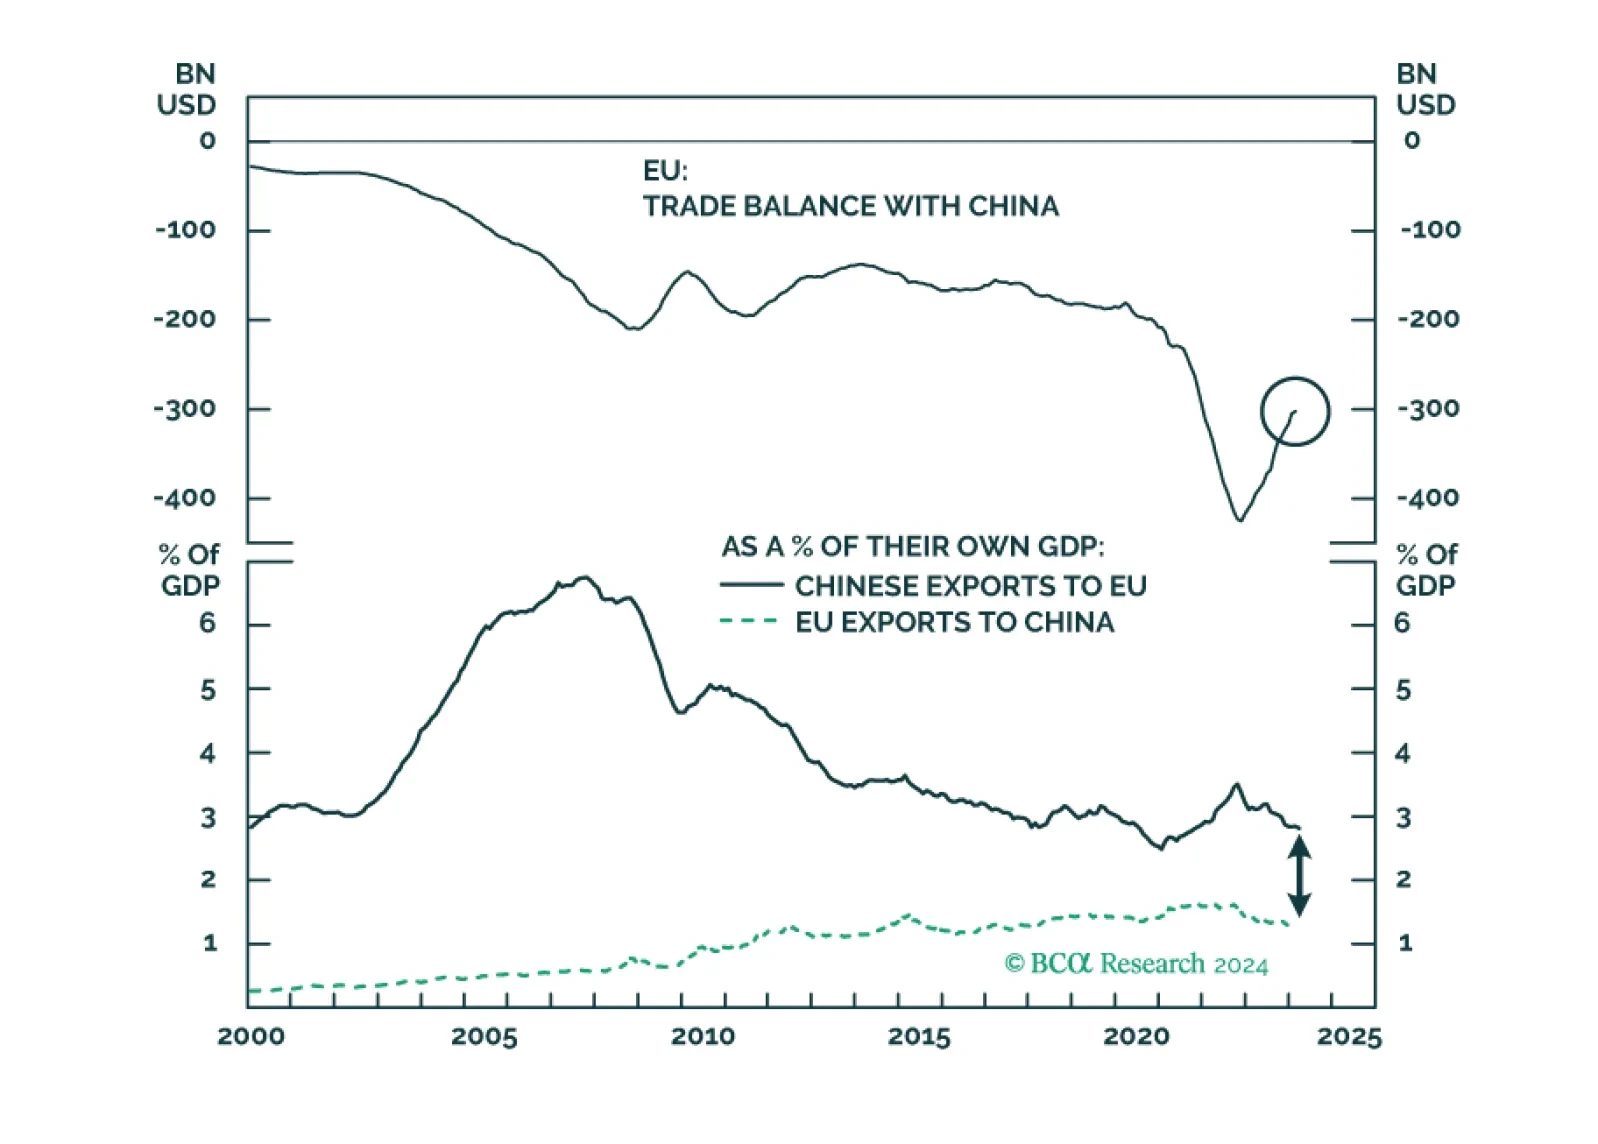
The EU's import tariff increases on Chinese EVs are expected to have a minimal impact on China's overall exports. We anticipate that most Western-brand EV shipments from China will be less affected by the EU import tax hike. Beijing will likely pursue continued negotiations with the EU rather than resort to harsh retaliatory measures.
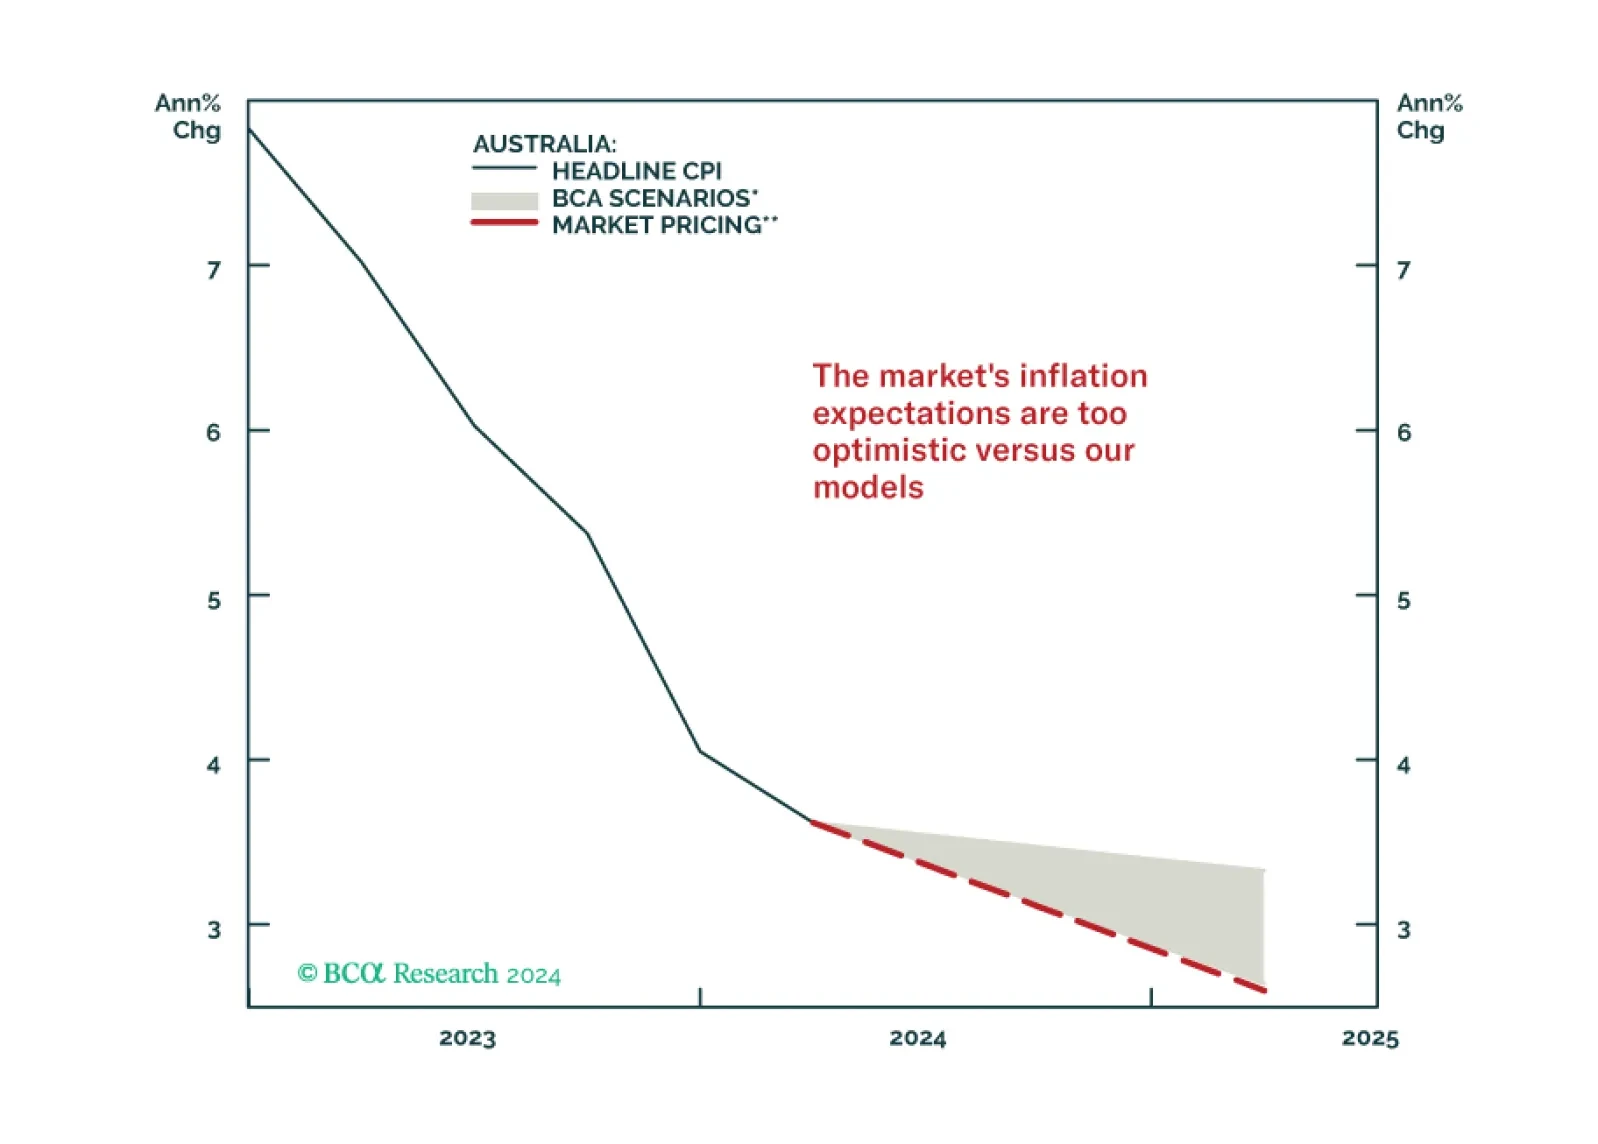
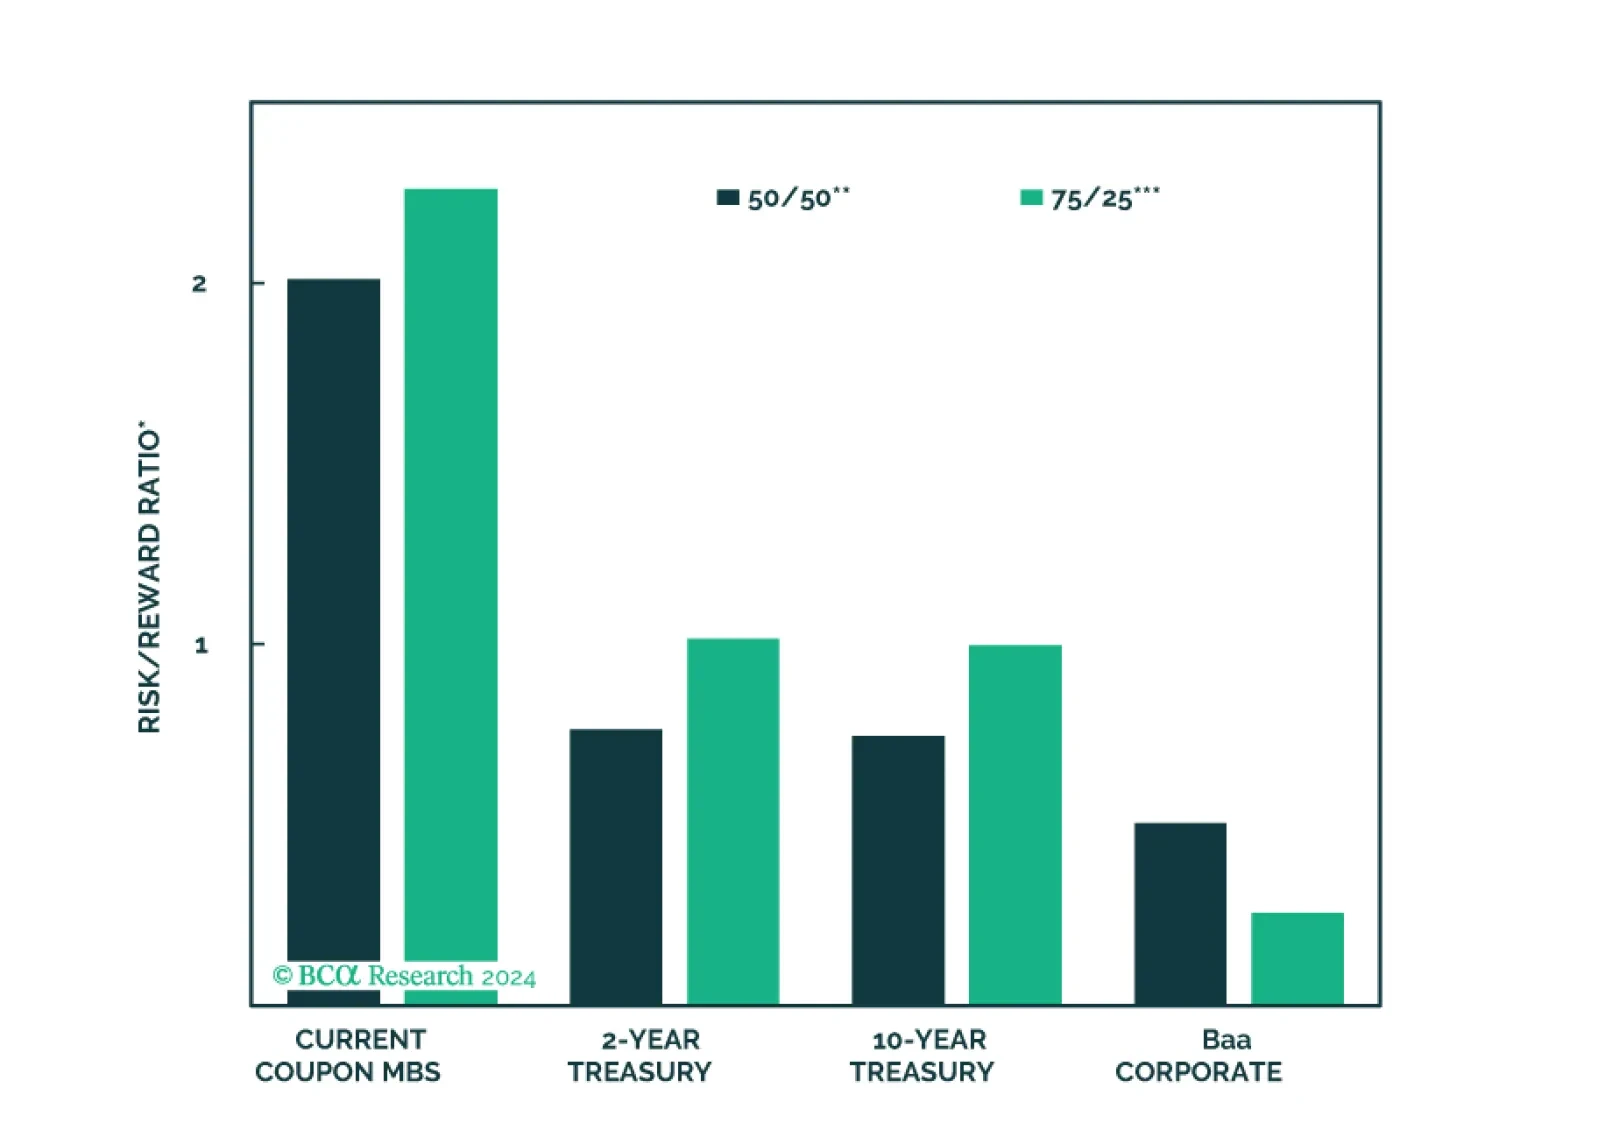
In light of this week’s RBA decision to keep policy on hold, we look at the best possible trades in fixed income markets. In our view, inflation-linked bonds, relative to nominals remain a good bet.

Gold prices might experience a correction or consolidation over the near term. However, cyclical and structural forces will ultimately cause the yellow metal to trend upwards.
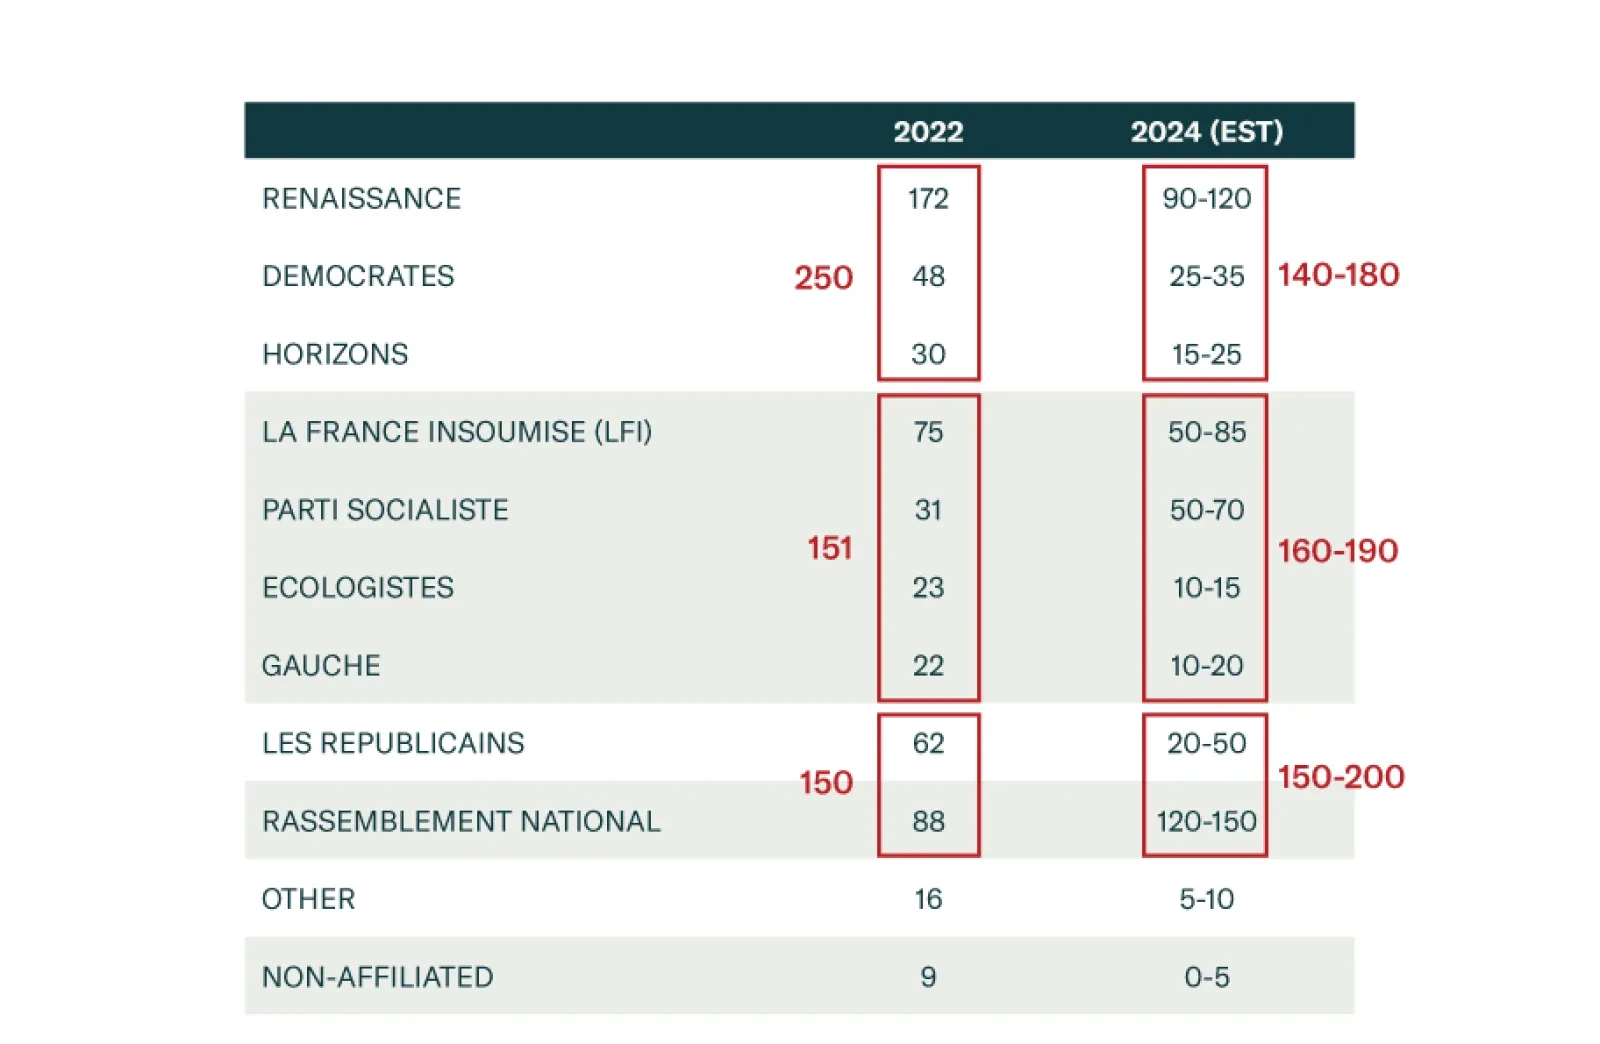
European assets are selling off as investors panic about the upcoming French election. Is this panic justified, and if so, for how long?