Latest from BCA Research
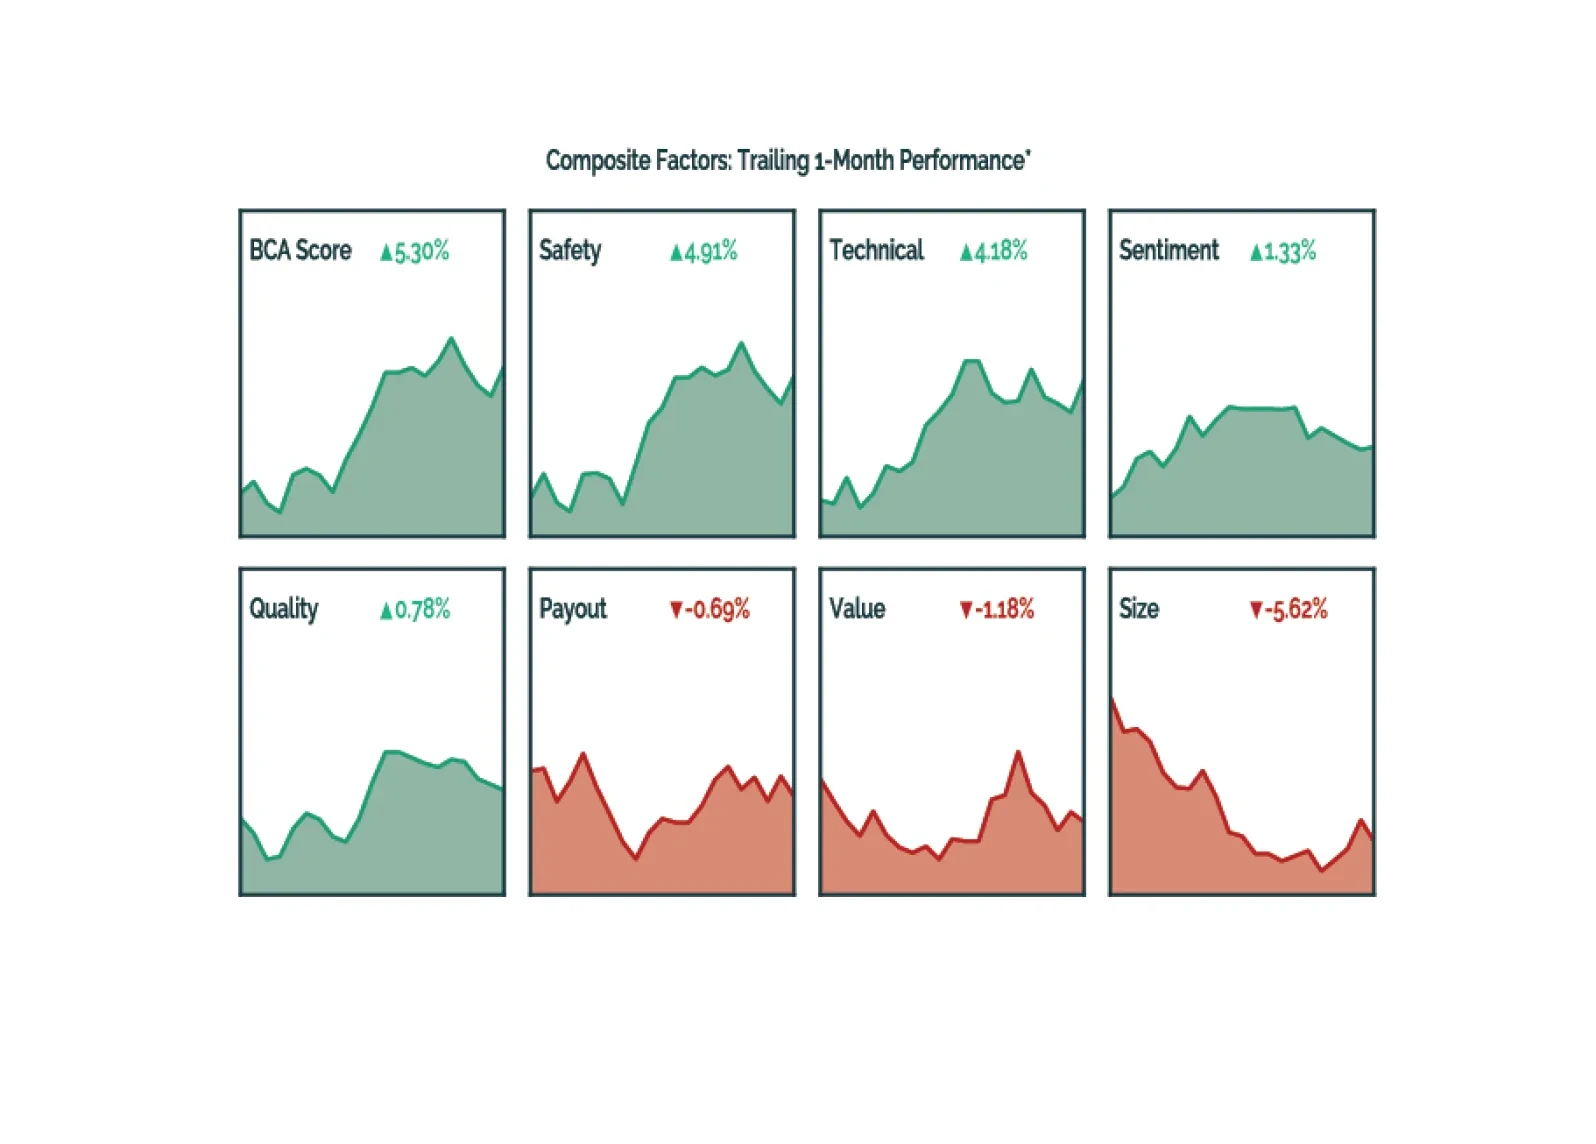
US High-Quality Strategy outperforms on the back of the BCA Score. Safety and Technicals lead the factor landscape, and while small caps struggled, the SMID portfolio also outperforms.

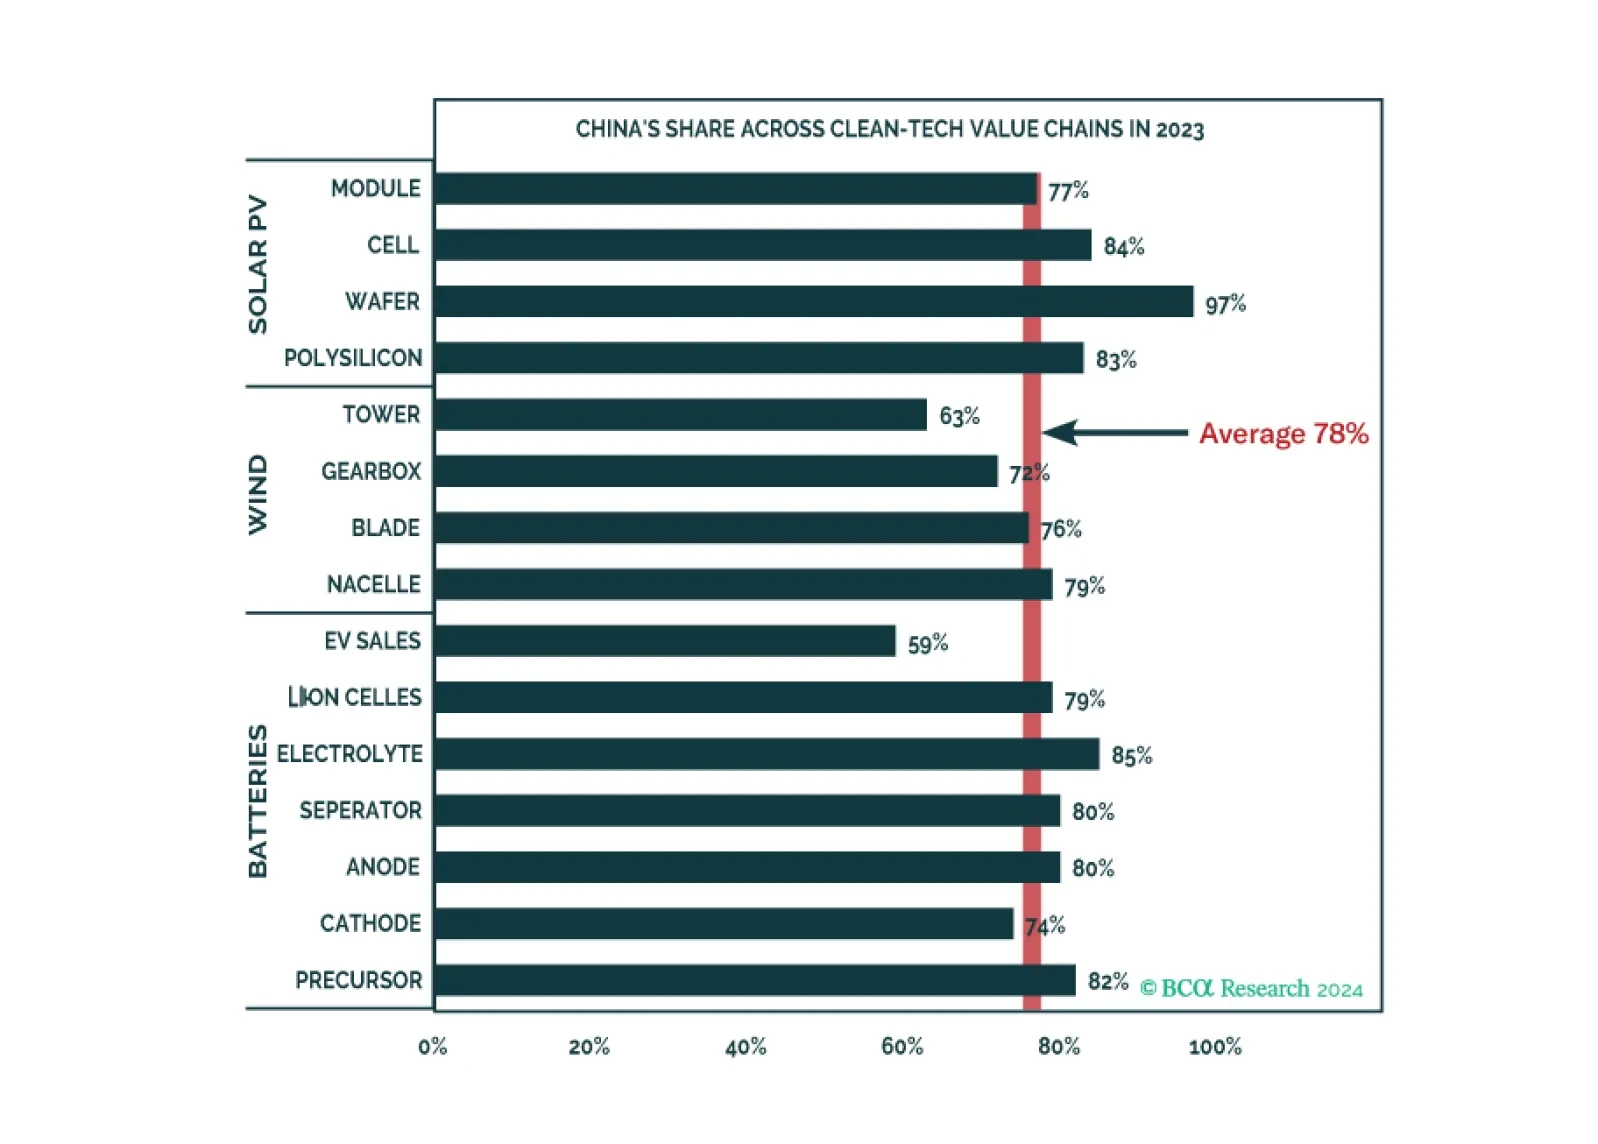
The PBoC appears increasingly uncomfortable with the rapid decline in the Chinese government bond yields. While the PBoC will succeed in temporarily curbing investors’ enthusiasm for bonds, the central bank will be unwilling to raise interest rates and unable to intervene in the bond market in any meaningful and lasting way.
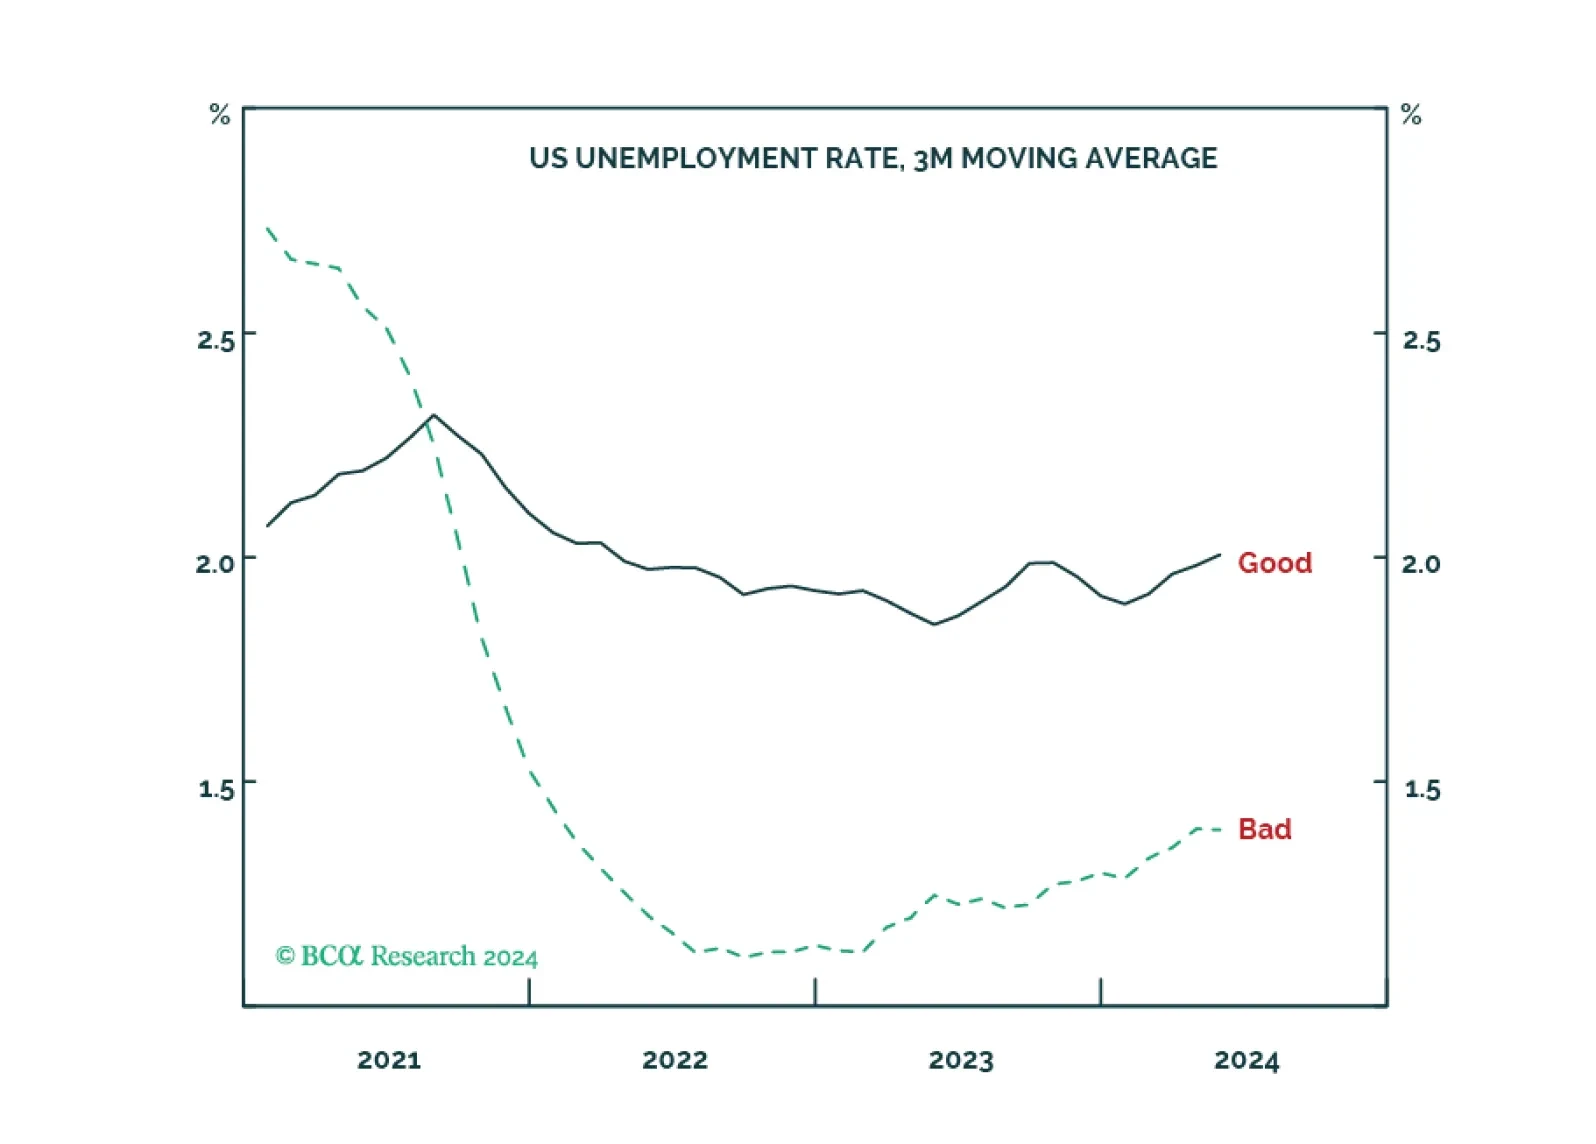
We explain how to distinguish between ‘good’, ‘bad’ and ‘ugly’ unemployment, why bad unemployment is a much better gauge of the jobs market than headline unemployment, and what this means for the tactical positioning in bonds and stocks. Plus: base metals (XBM) have already sold off sharply, so take profits in the short position and open a tactical overweight in global materials (MXI).
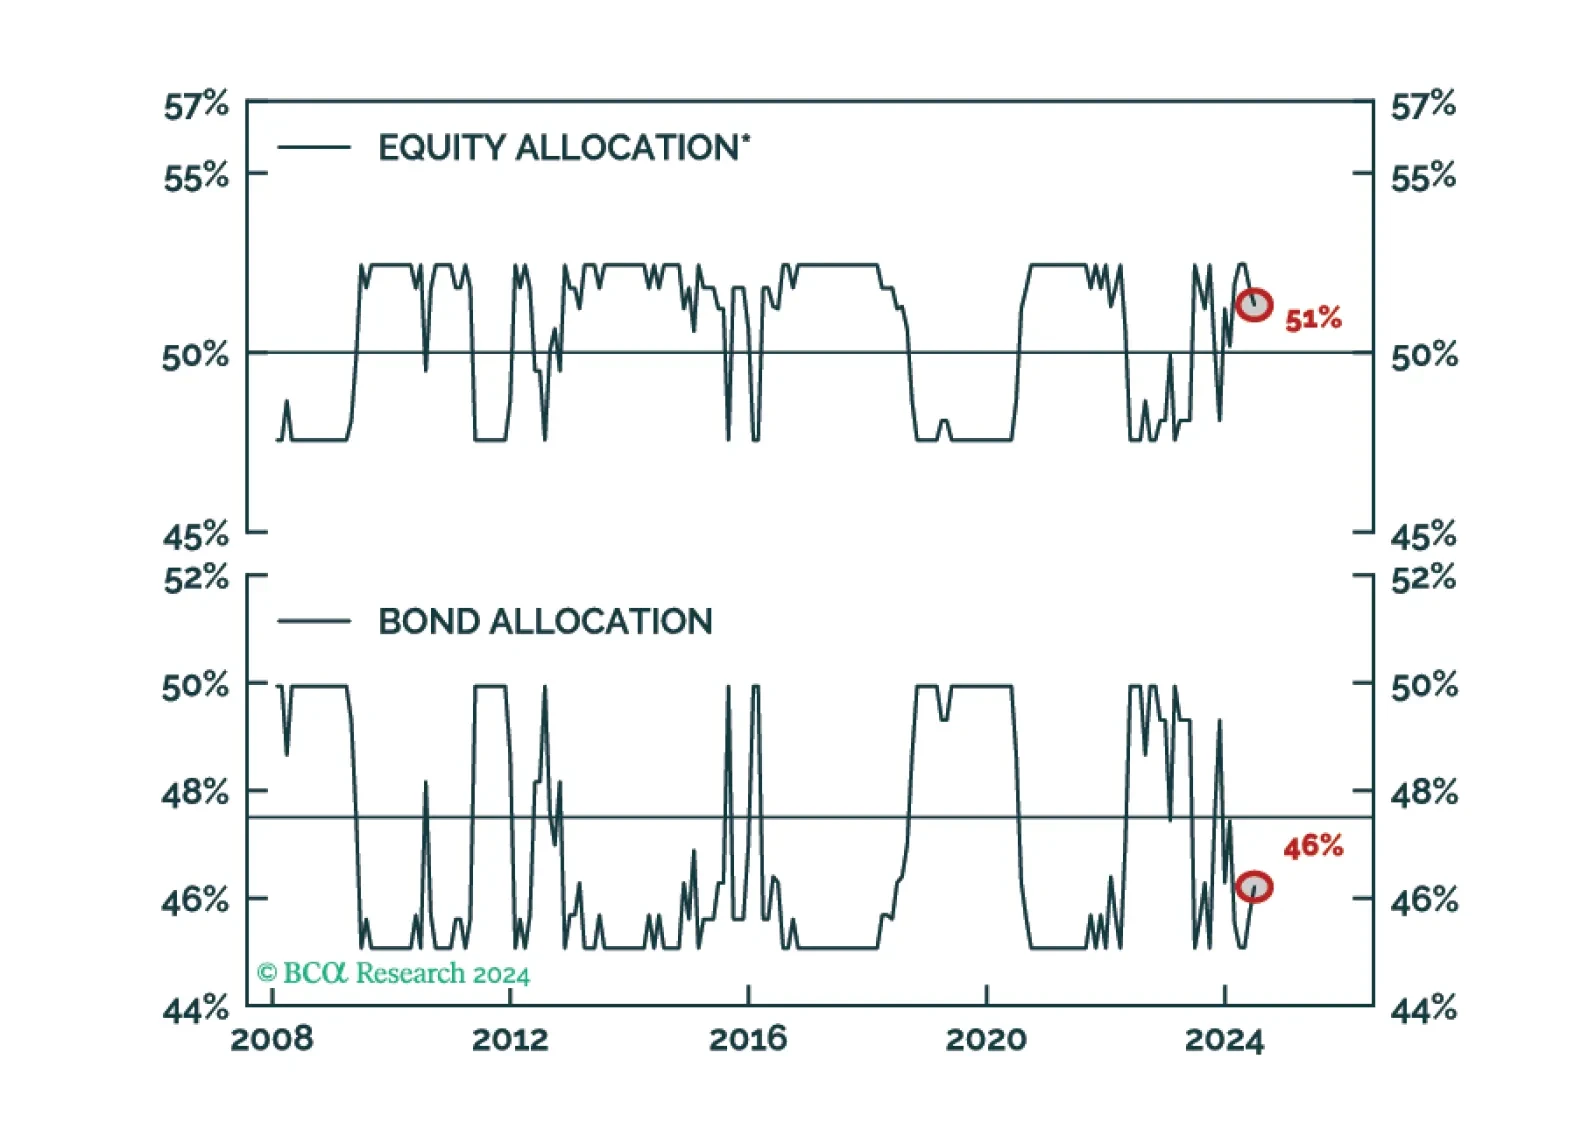
At the asset class level, the GAA Quant model is overweight equities, underweight bonds, and neutral cash.
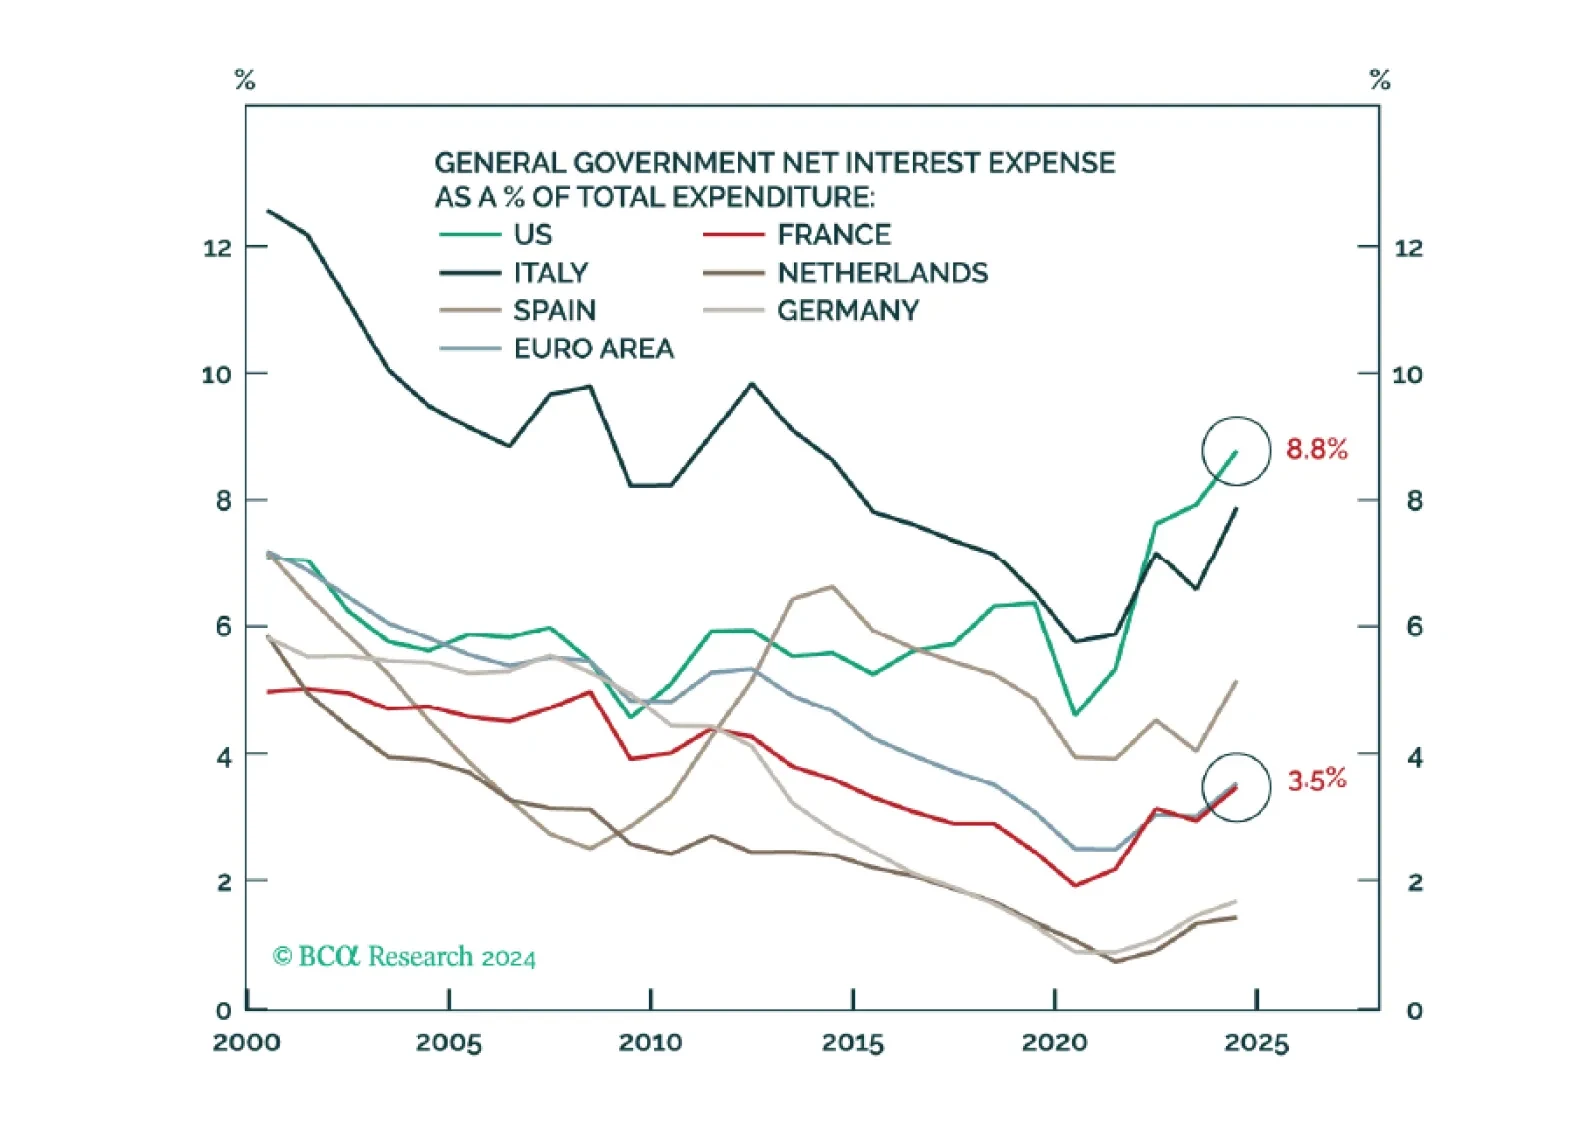
In our Volume I – The Alpha Report – we posit that the French bond market reaction is a mere amuse bouche for what is coming to the US. All year, we have warned investors that US politics could induce a bond market riot. This moment is nigh. Act accordingly!
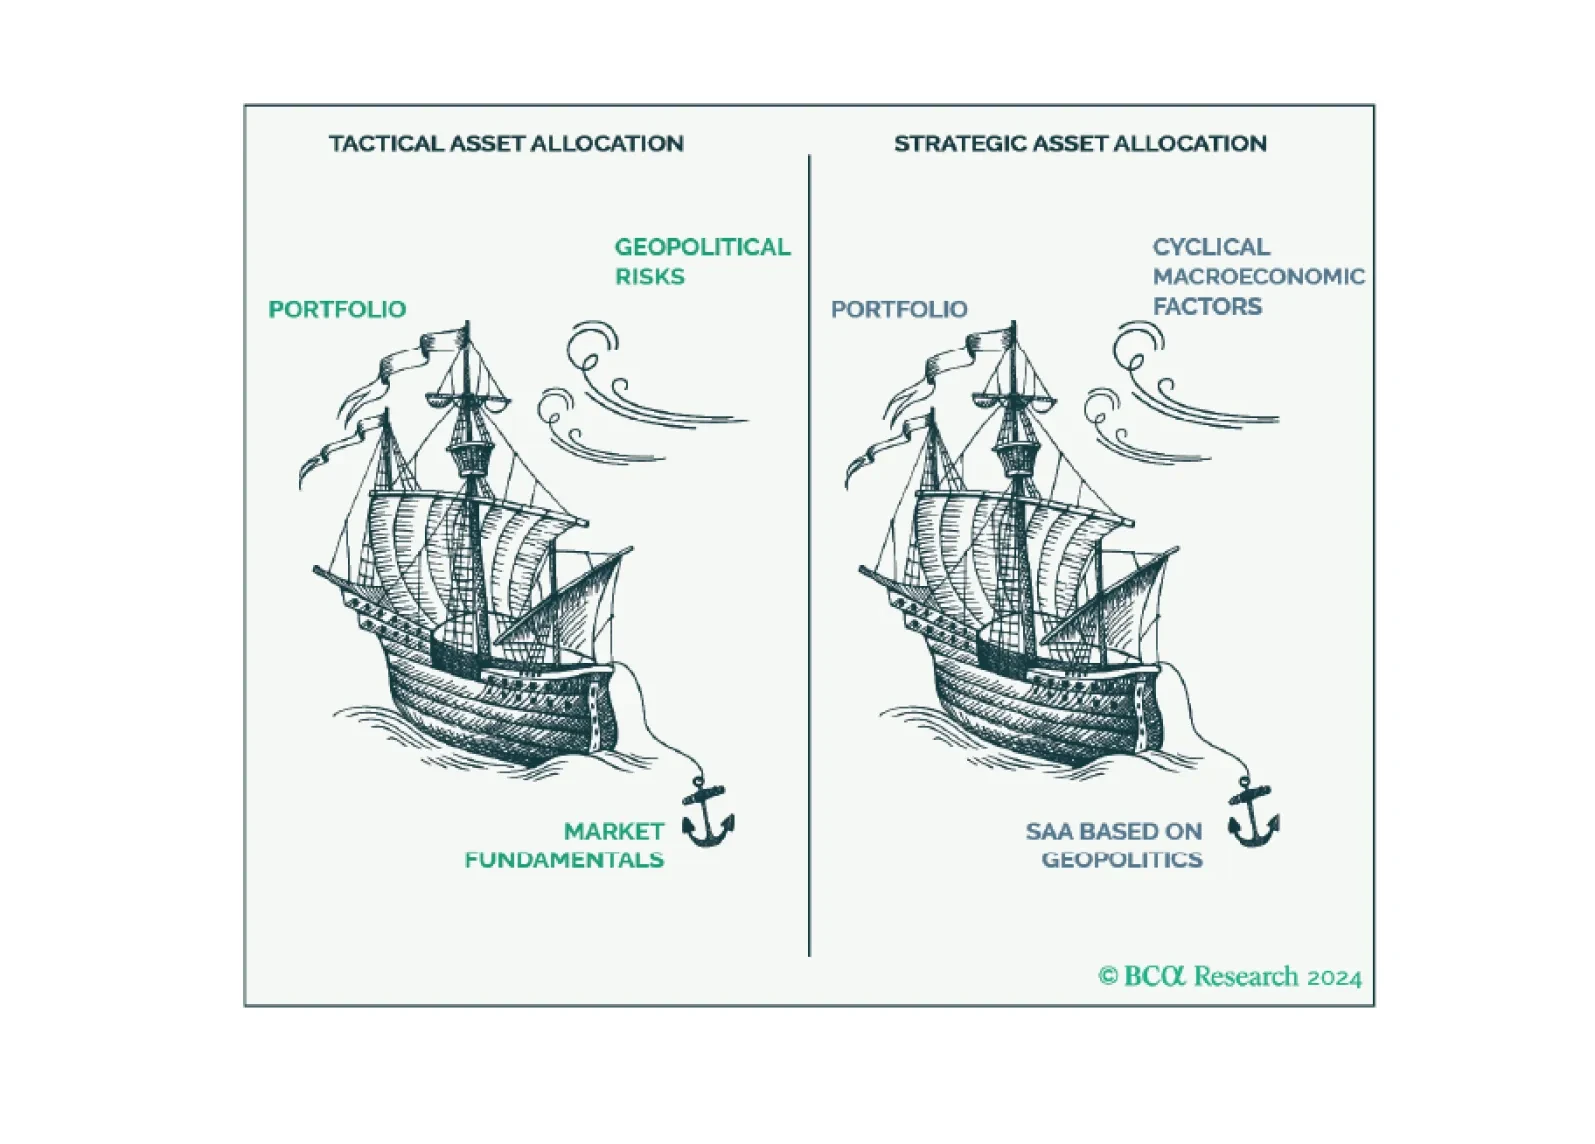
There are many different paths to macro investing. In our Volume II – The Beta Report – we present our own, which we have dubbed GeoMacro. We are very confident that we are “on to something,” but are humbled constantly by the markets, brilliant applications of different frameworks, and the confidence that, at BCA Research specifically, GeoMacro Strategy is housed in a collective of other approaches and methodologies that will greatly enhance our own capabilities. Our conclusion is simple: When it comes to searching for beta, nothing but geopolitics and politics matters. When it comes to searching for alpha, the macro fundamentals far outweigh geopolitics and politics.
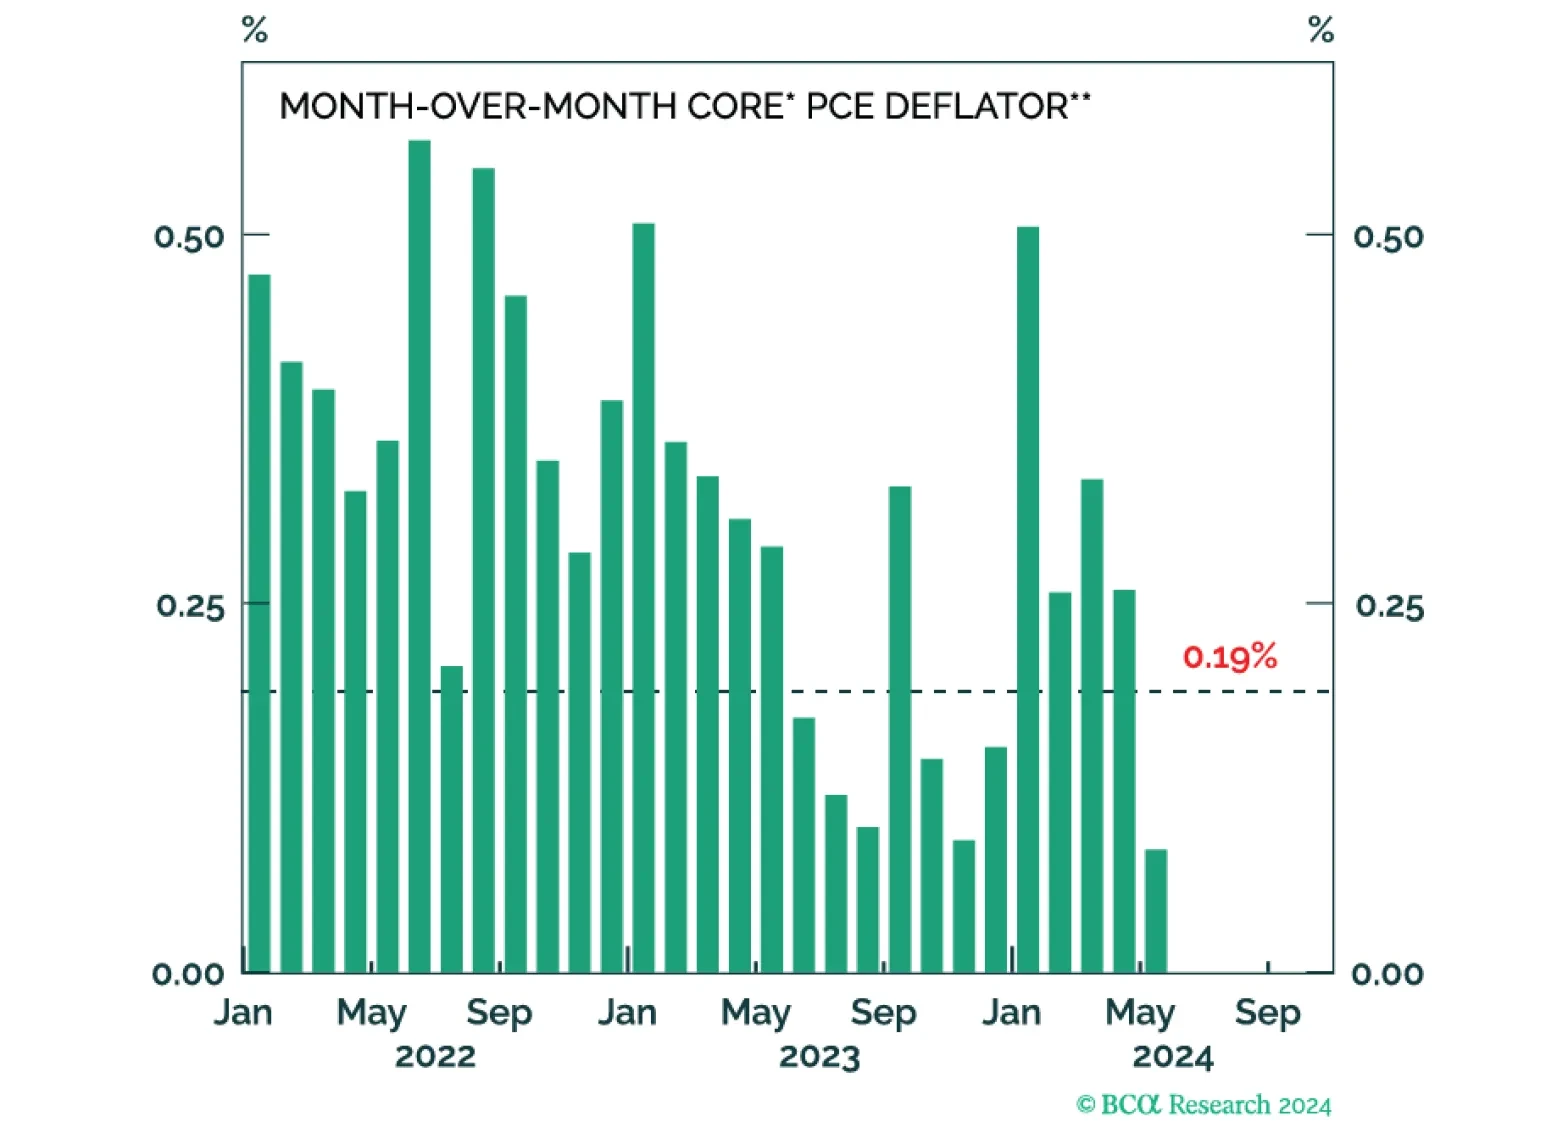
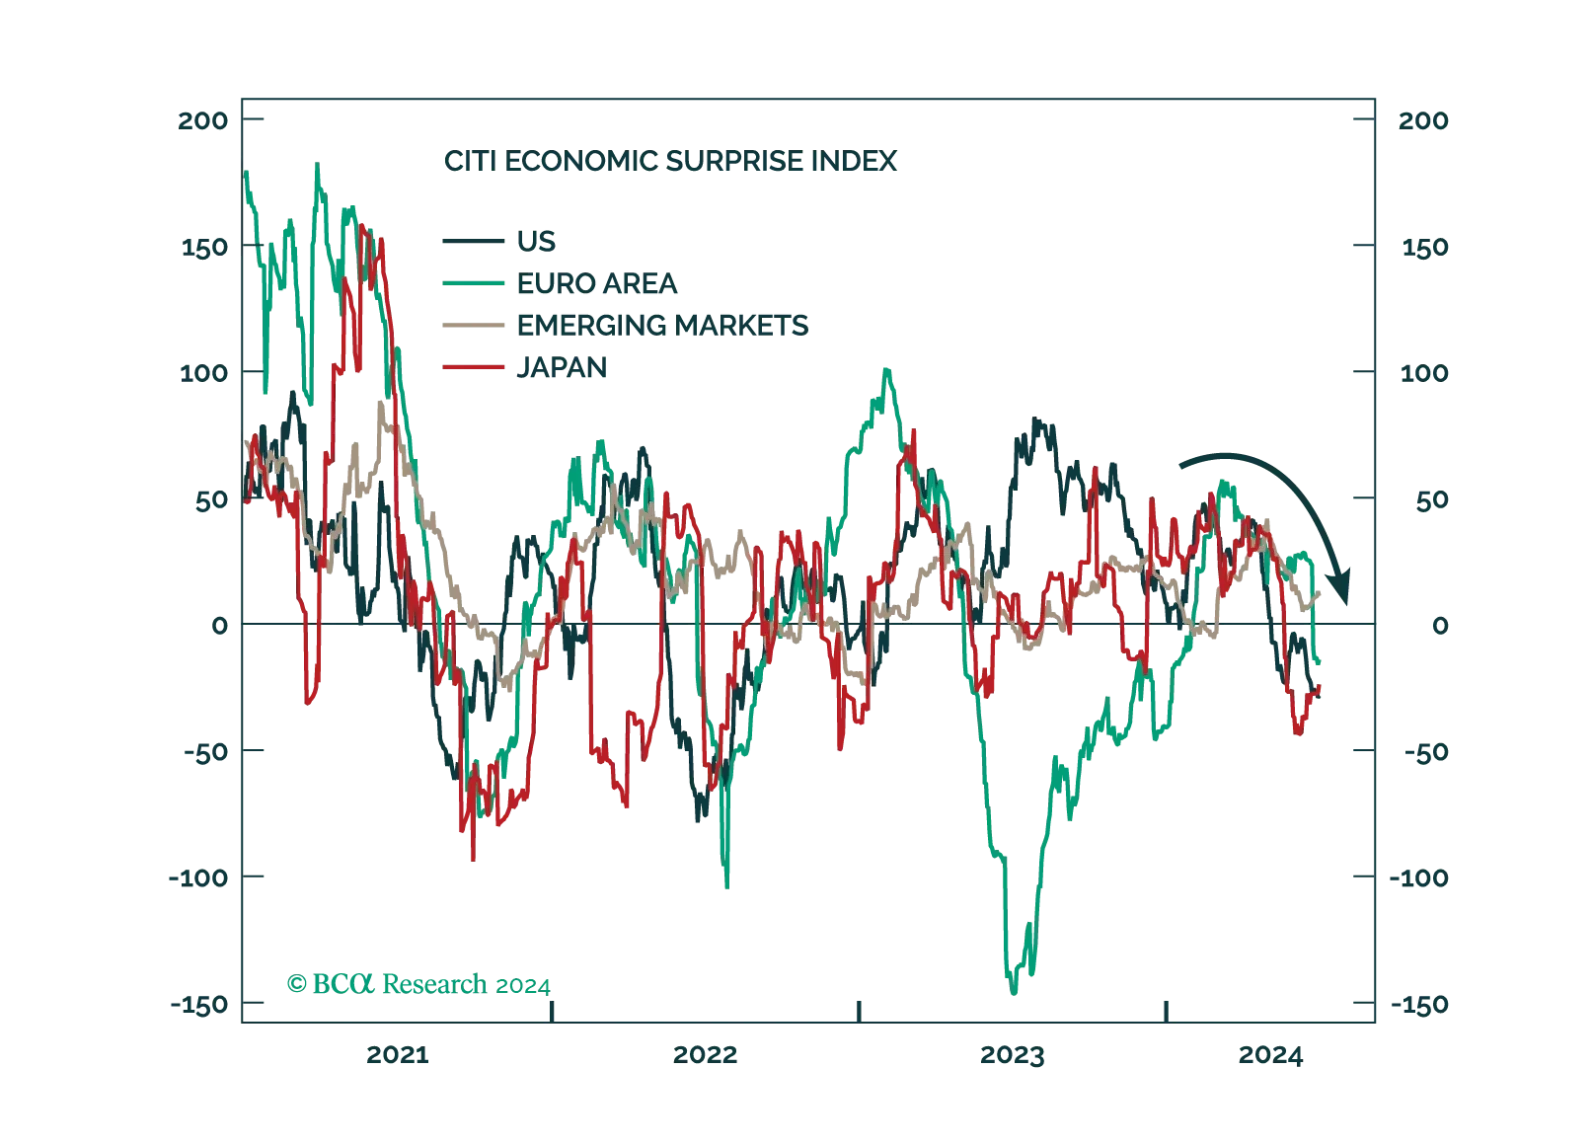
Concerns about the global economy have shifted from sticky inflation to faltering growth. Tight monetary policy is finally starting to bite. We suggest increasing portfolio defensiveness.
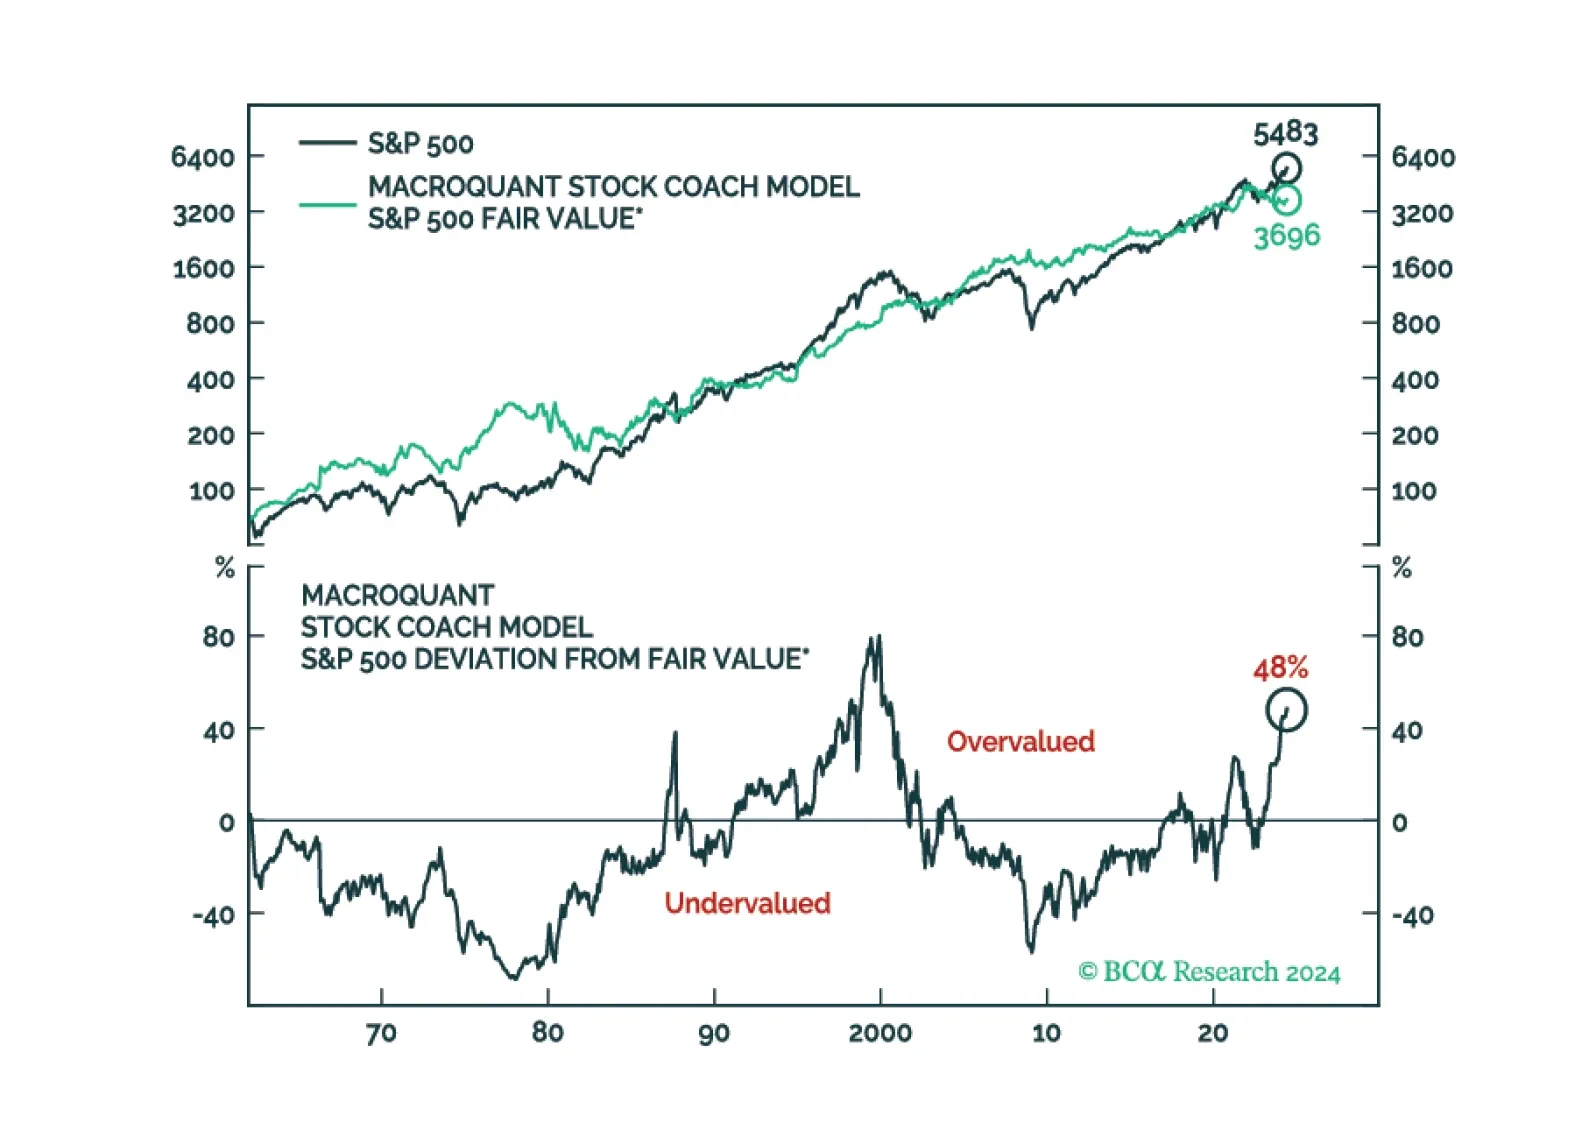
The Global Investment Strategy team downgraded global equities to underweight earlier this week. The latest reading from our MacroQuant model is consistent with this decision.