Latest from BCA Research
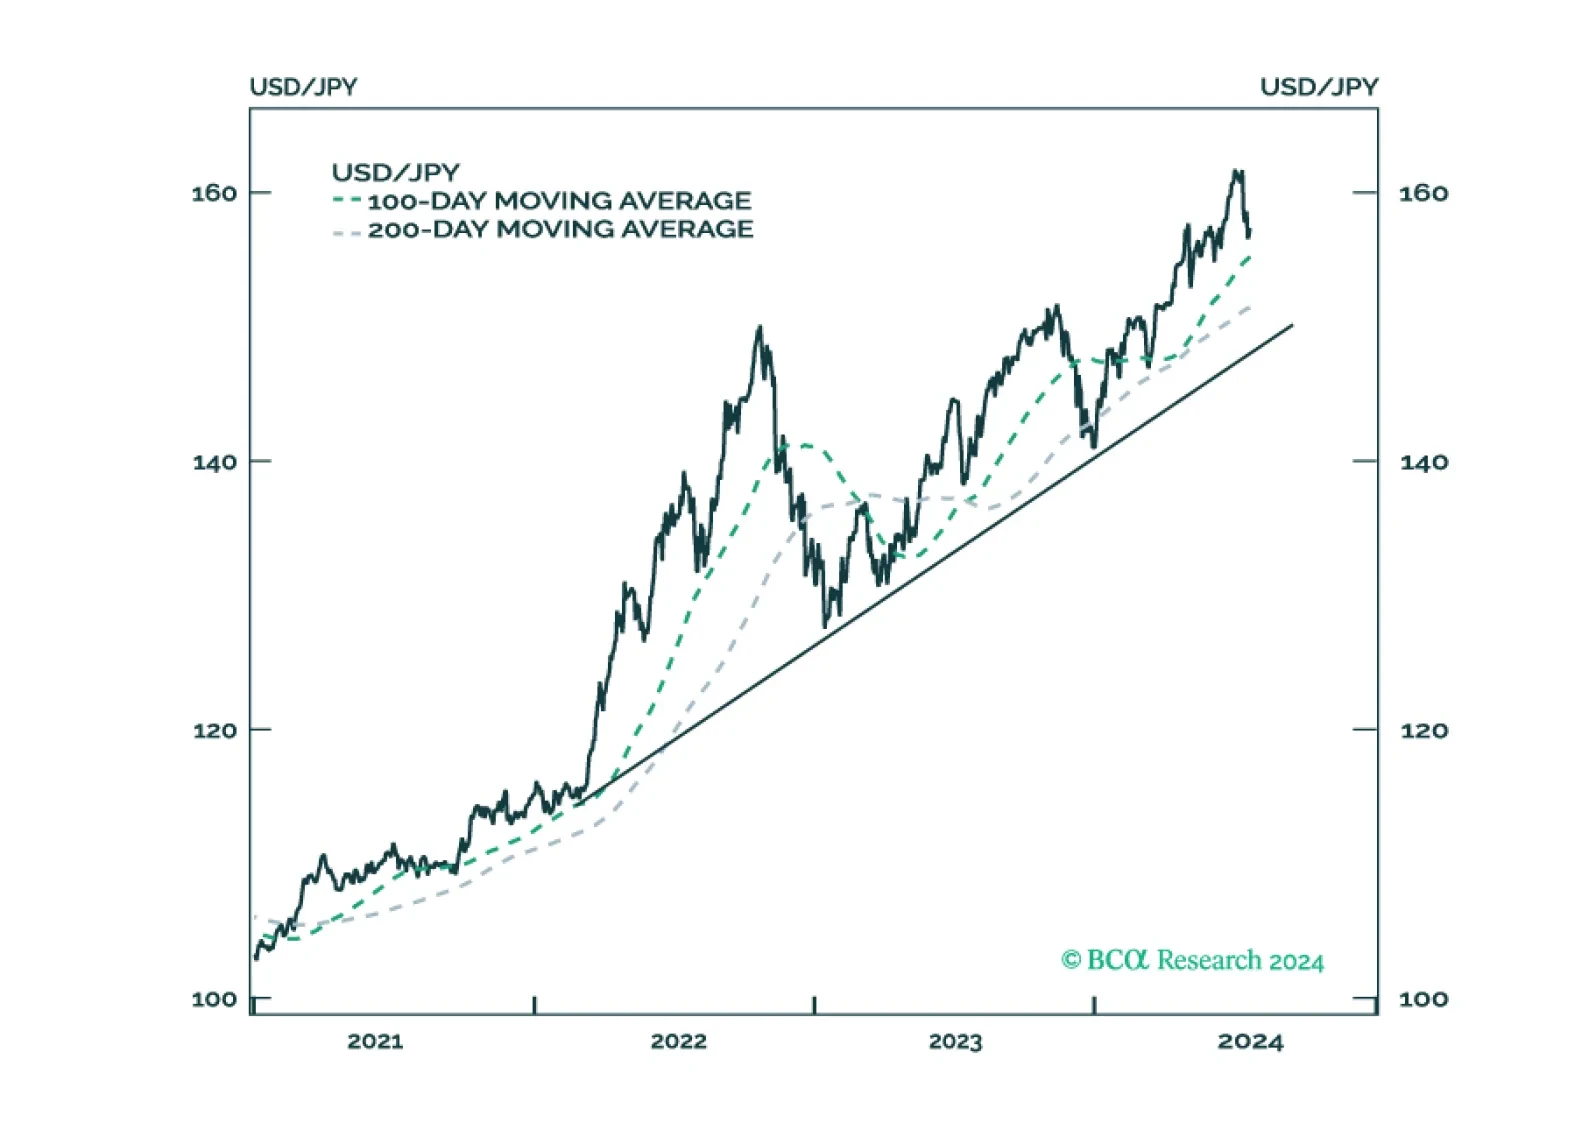
We review some of the key data releases this week that we find have an impact on our currency strategy. Long yen positions make sense today. Long sterling and the euro bets are more of a judgment call, and we will fade any strength in these currencies. This report delves into these nuances, and suggests a few trade ideas.
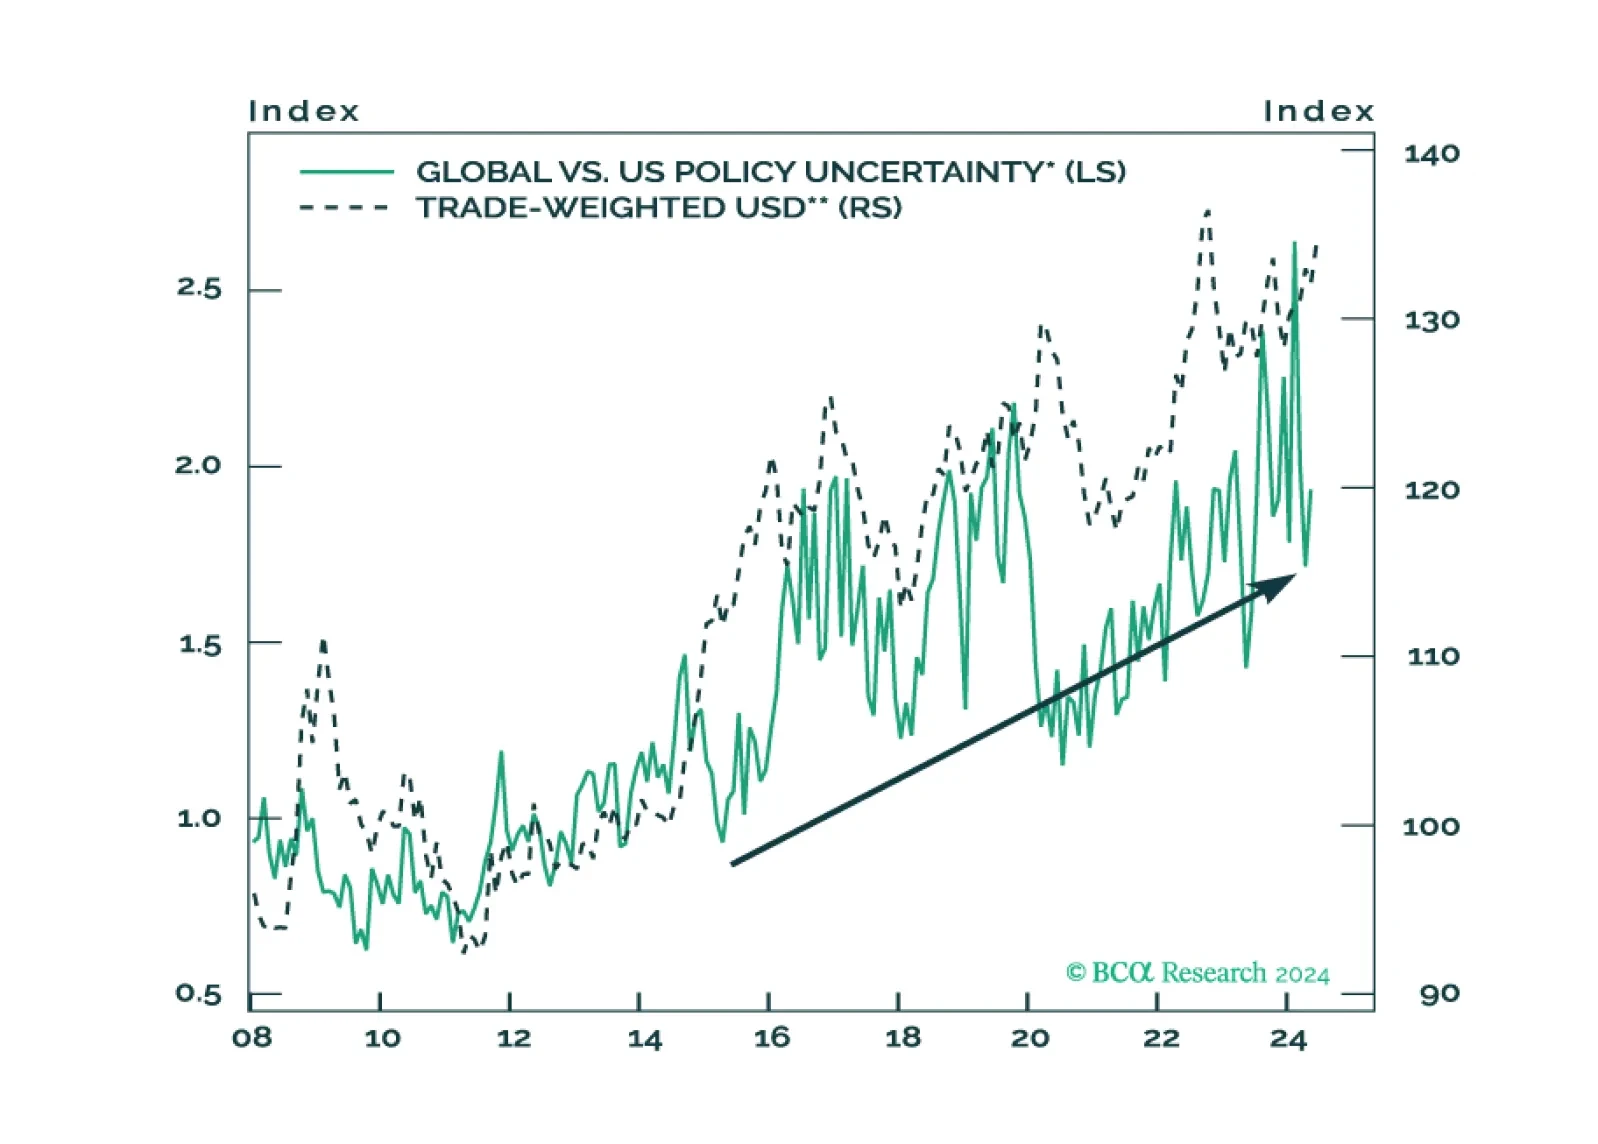
Investors should overweight US assets and de-risk their portfolios in anticipation of a major increase in policy uncertainty and geopolitical risk surrounding the US election and its global ramifications.
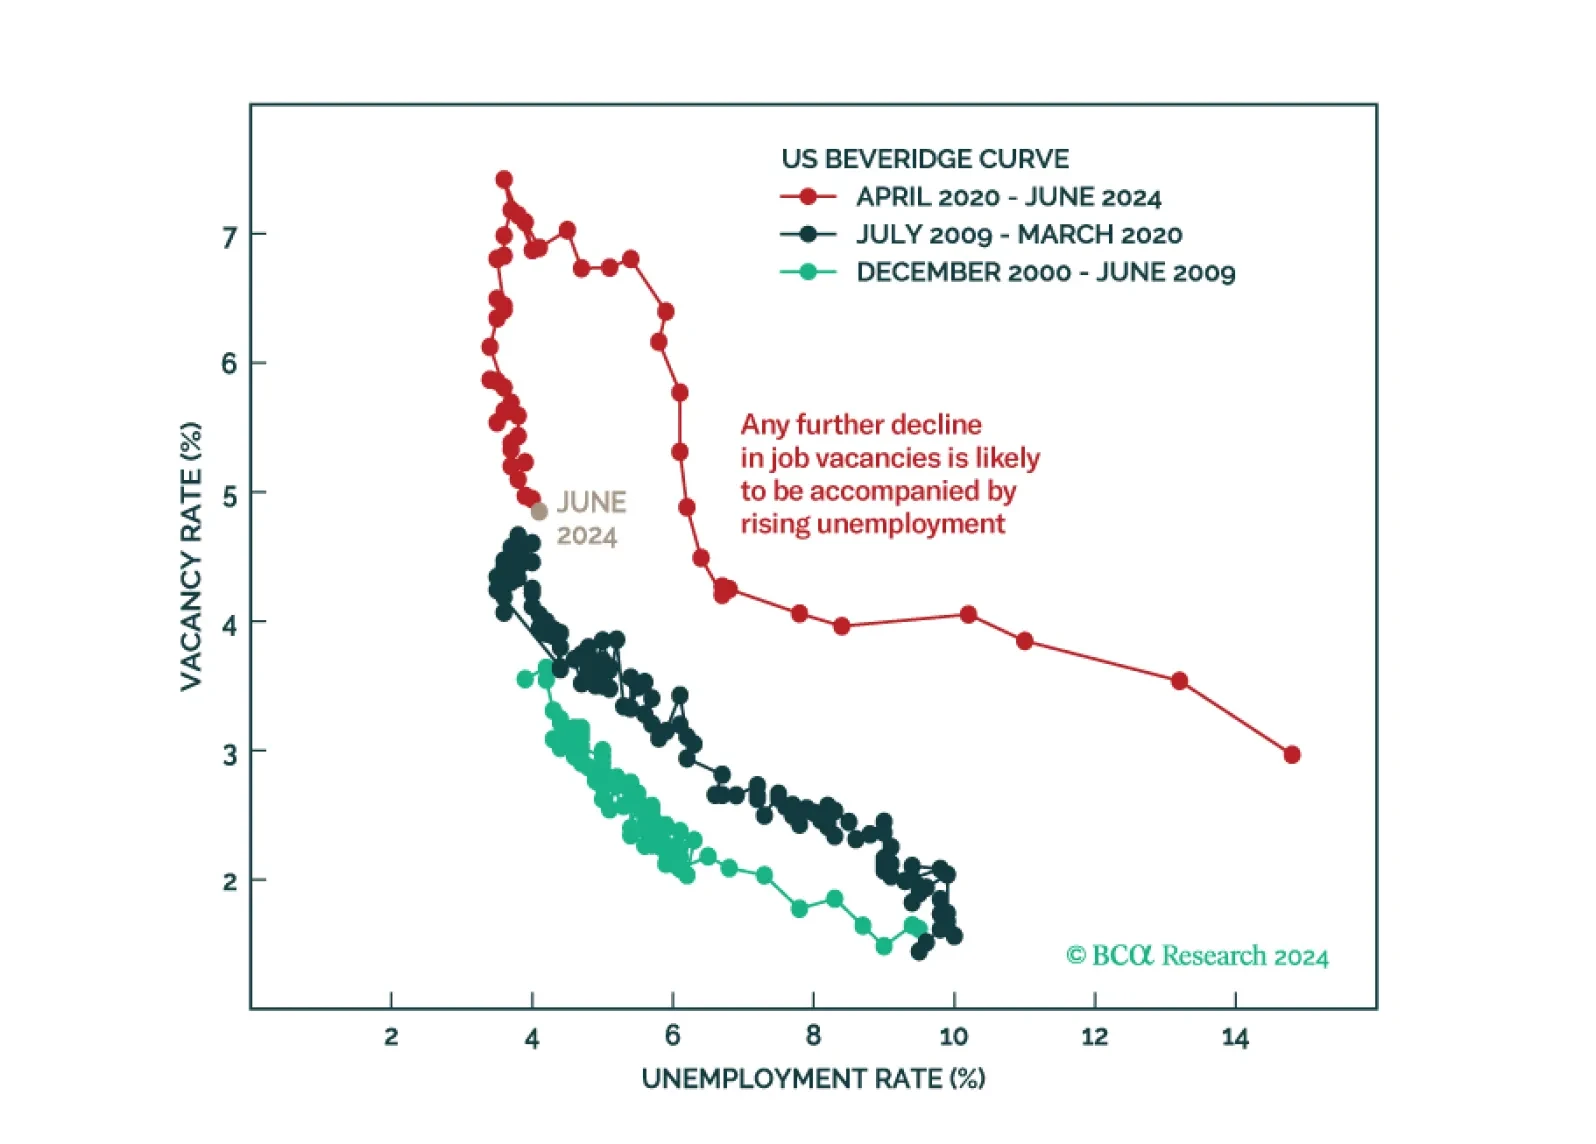
Don't buy the dip. The equity bull market is over. The US will enter a recession in late 2024 or in early 2025.
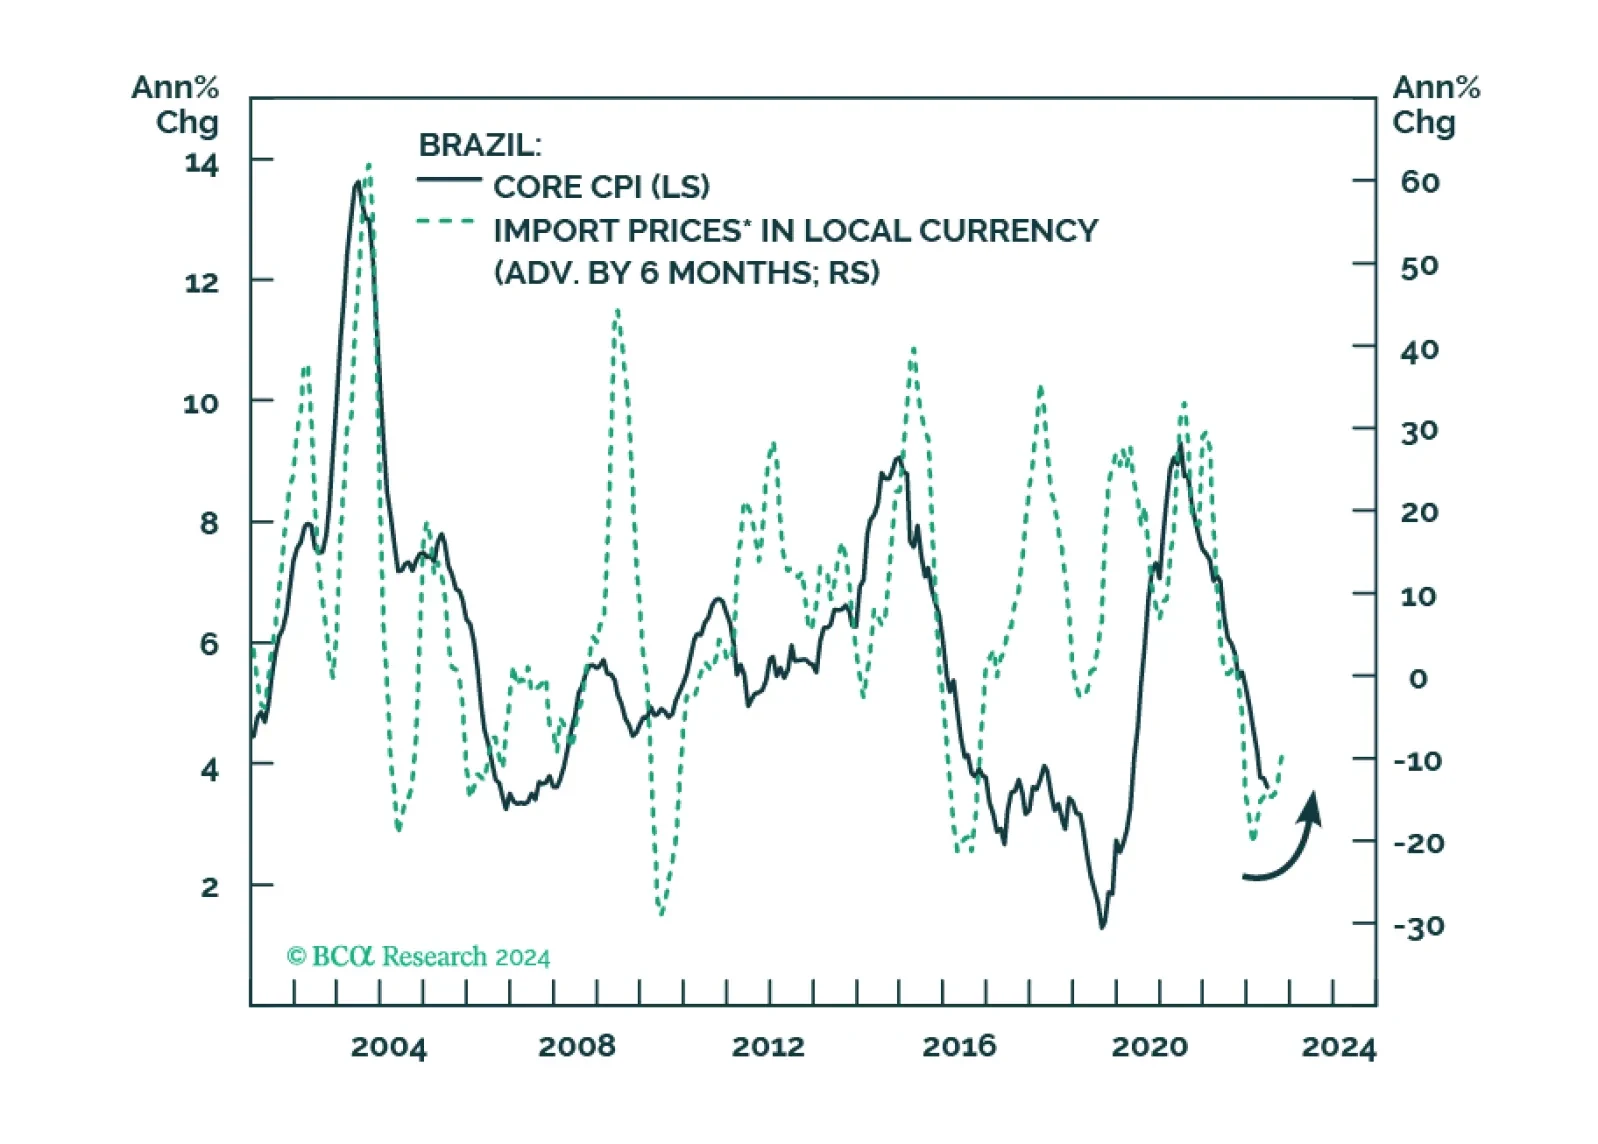
Brazil’s two macro demons – a rising public debt-to-GDP ratio and inflation – have resurfaced and will worsen over the coming months. Yet, President Lula will pay lip service to fiscal concerns without enacting meaningful cutbacks. In addition, a politicized COPOM will cut rates aggressively next year and fall behind the inflation curve. All in all, the selloff in Brazilian markets still has legs.
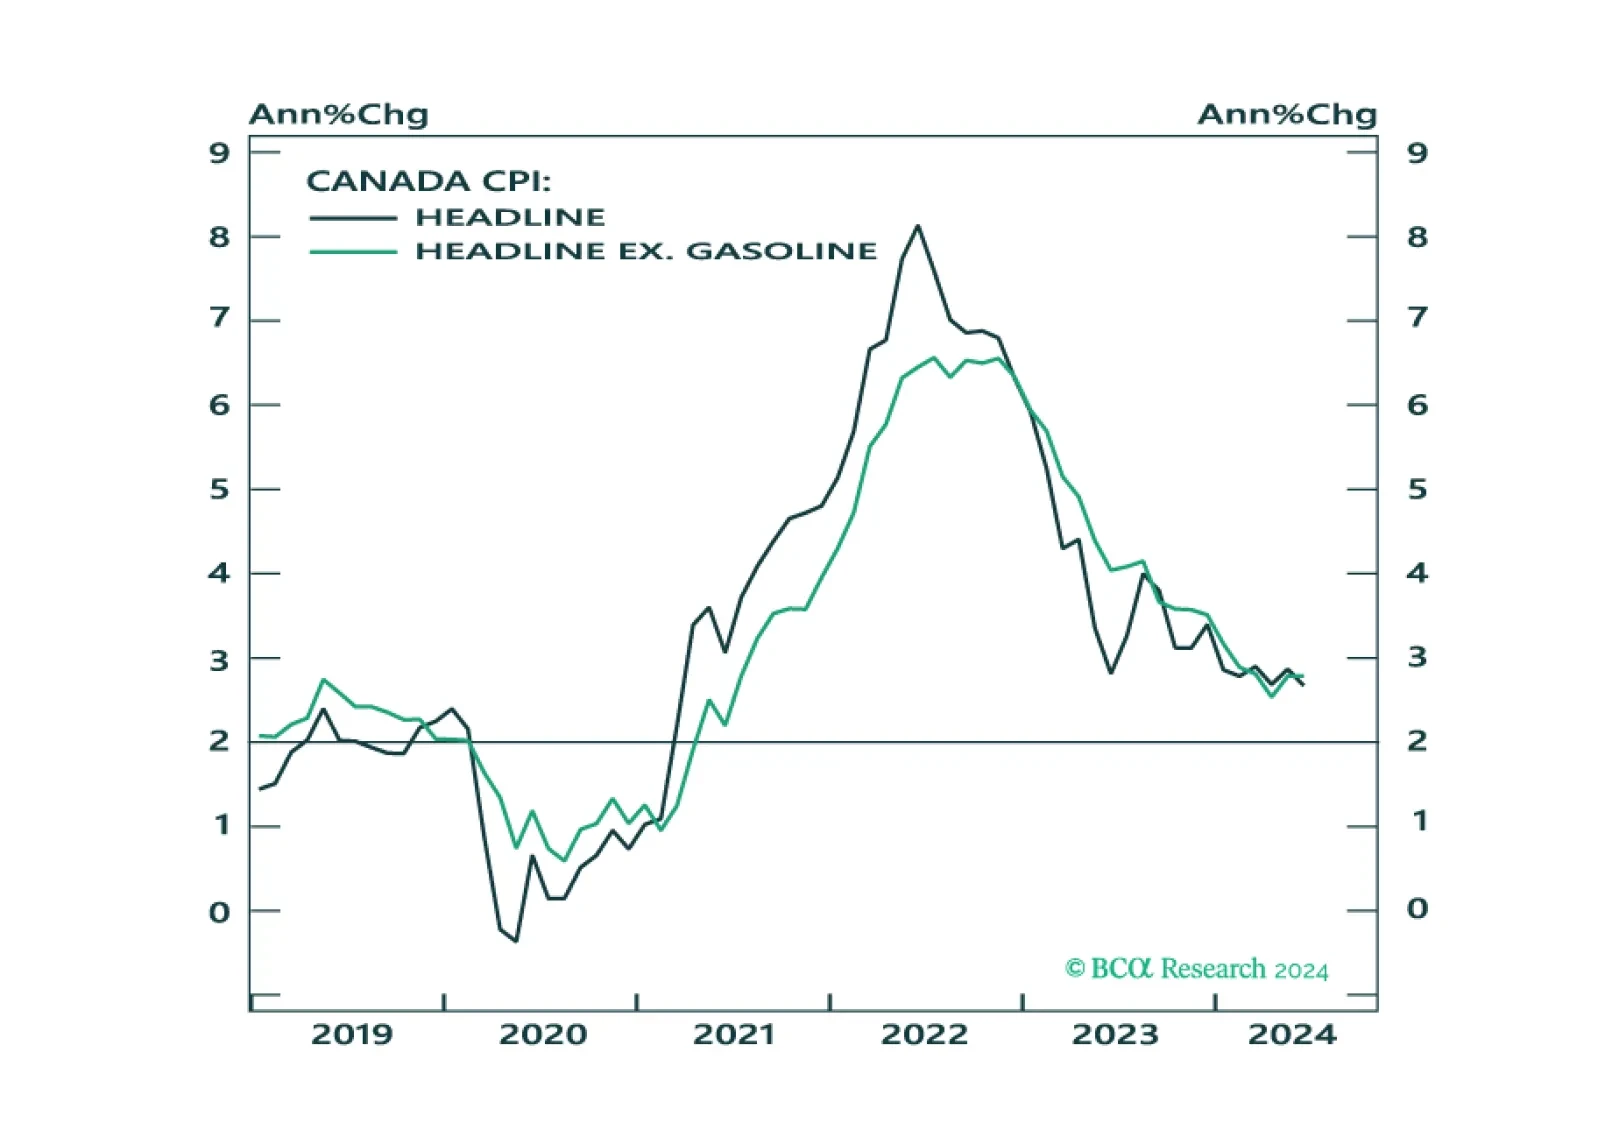
In this Insight, we look into the recent CPI release in Canada, and the possible implications for fixed-income market trades.
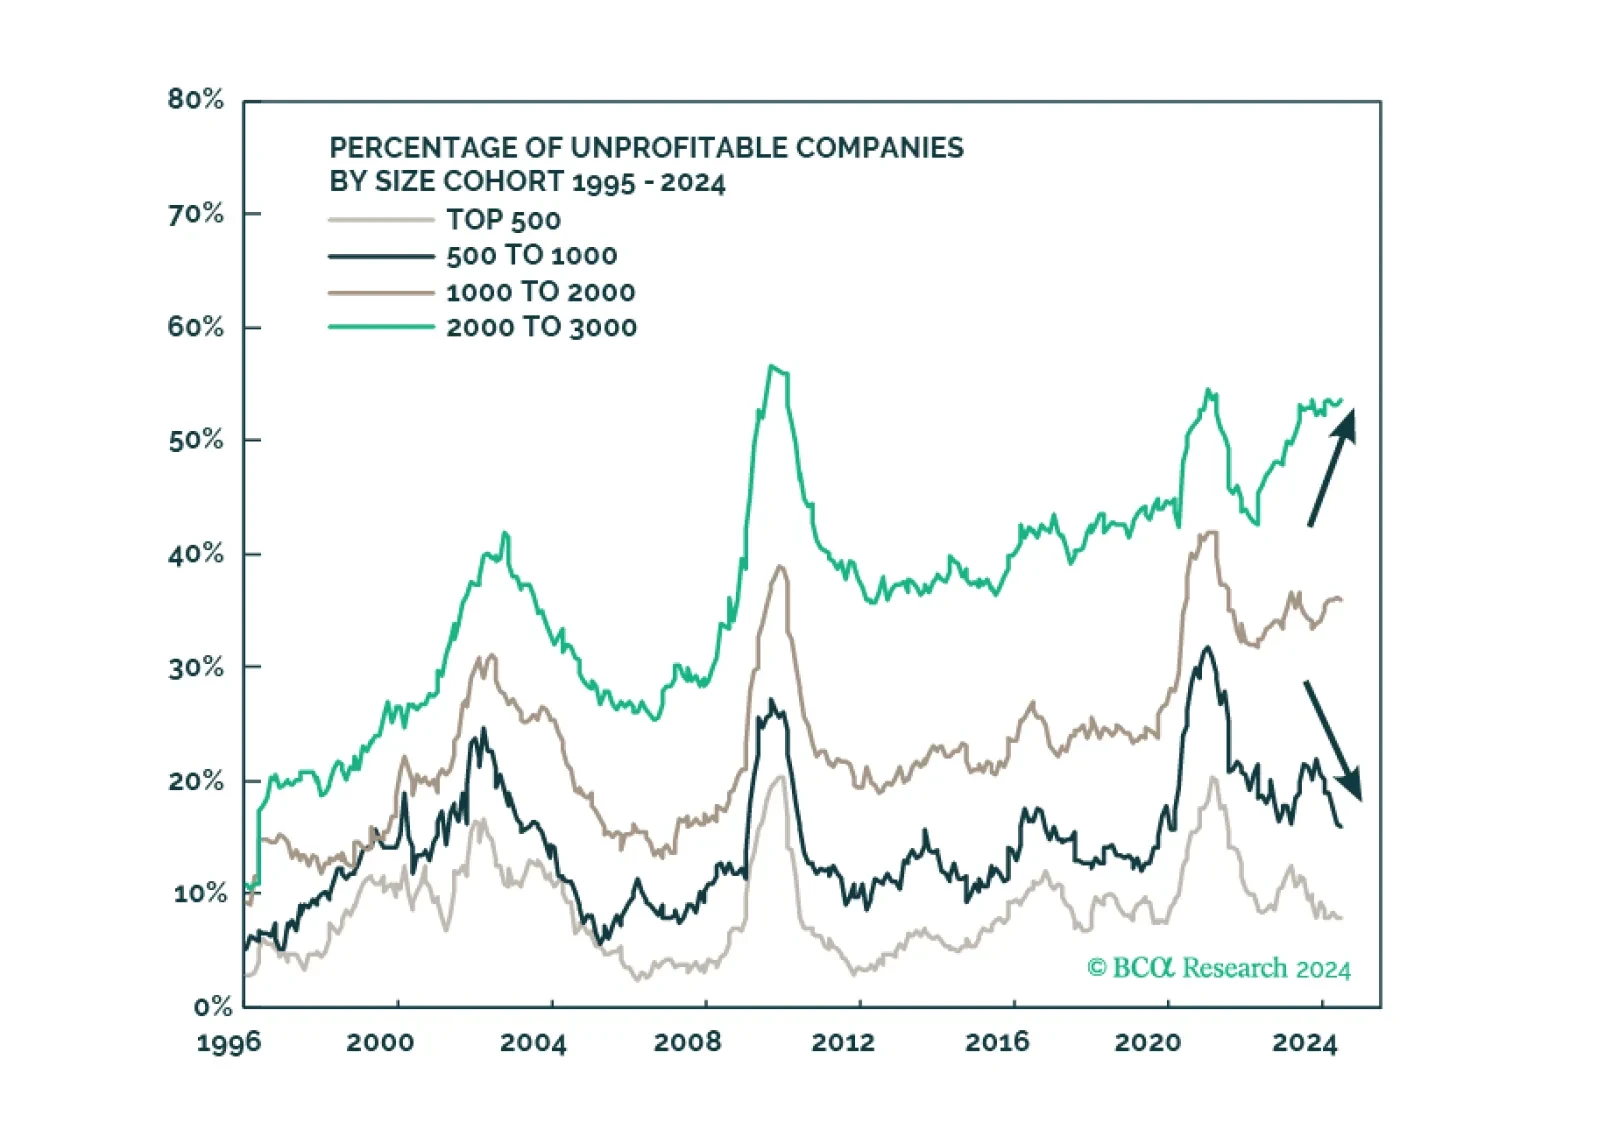
There is a broad-based deterioration of the economic data and a slowdown in consumer spending. On the bright side, inflation prints are better behaved. Rate cuts appear increasingly likely, but they won't stave off a recession. It is time to take profits from the GAI-related industries and bolster the defensive properties of the portfolios. Position for rate cuts.

The real threat to European equities is growth, not political risk. How low will Eurozone earnings fall during the coming recession and how much will equities decline in response?

The cyclical economy is slowing today. Republicans are now more likely to win a full sweep, crack down on immigration and trade, and at least modestly stimulate the economy. Uncertainty and volatility will rise.
Today’s attempted assassination against President Trump challenges the consensus view. It will ensure that President Trump’s supporters are highly motivated for the upcoming general election. And it may return many supporters who had drifted away from the former president back into the fold.
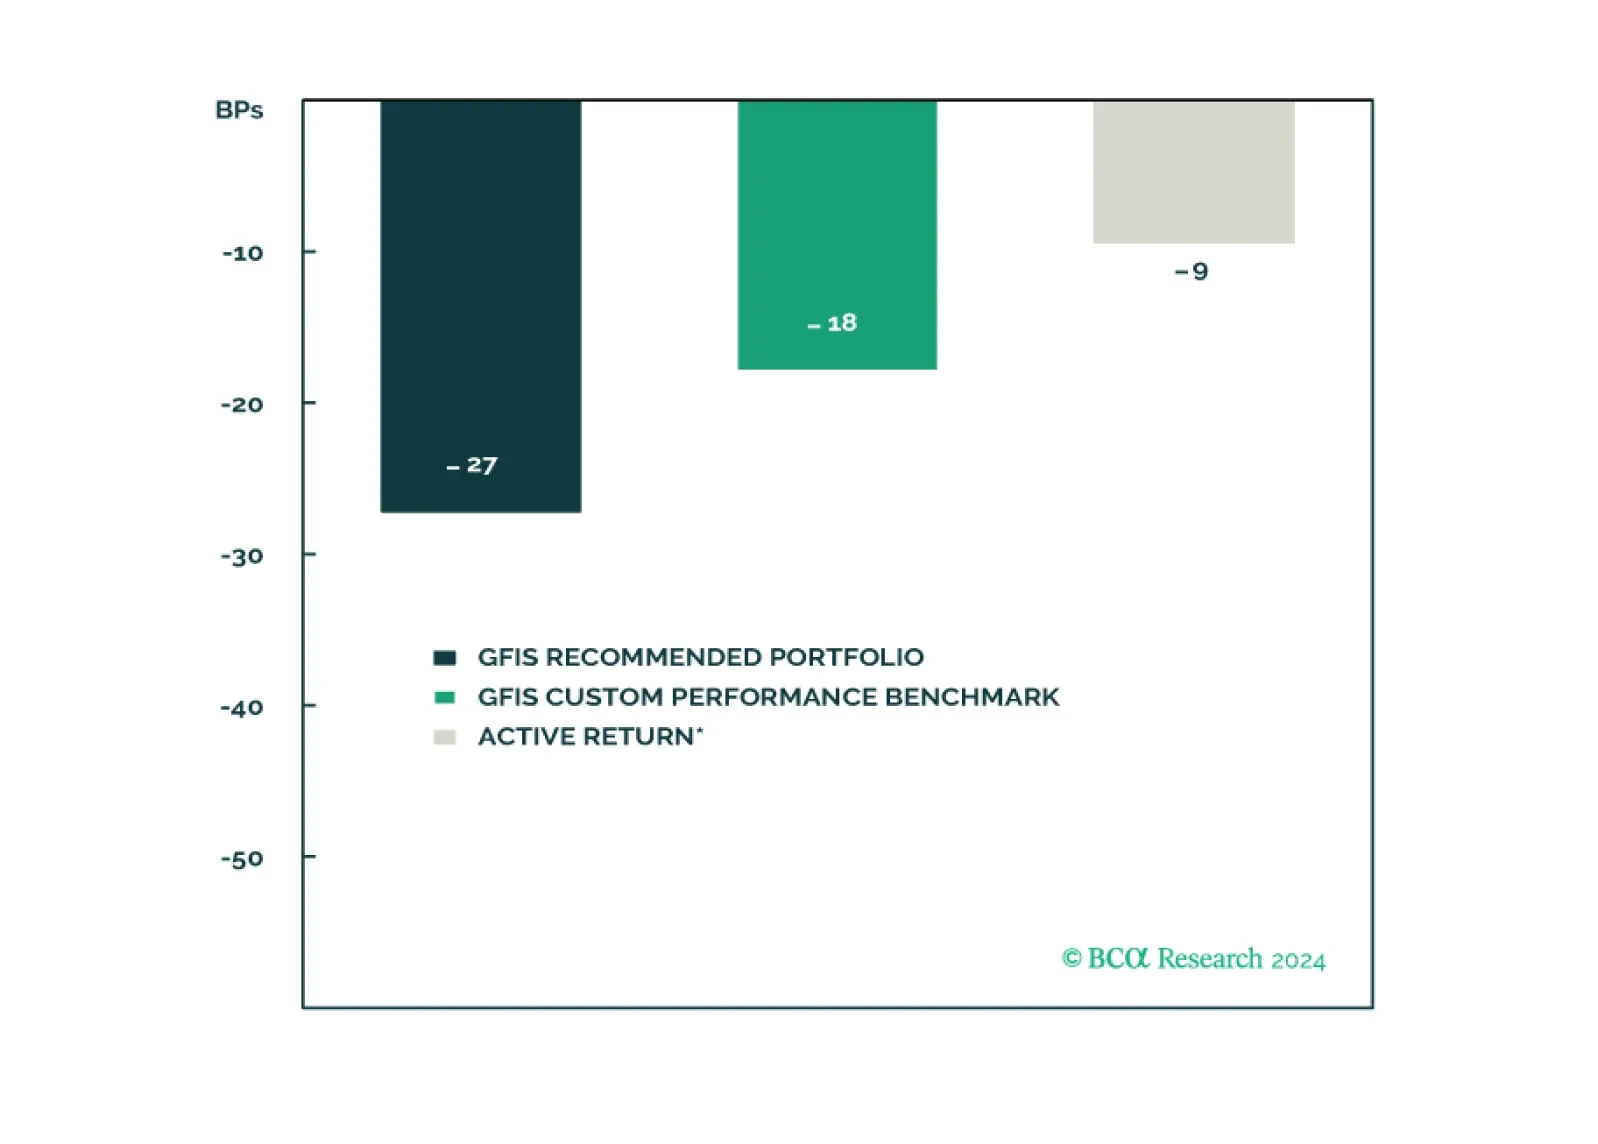
In this report, we present the quarterly review of our Model Bond Portfolio. Rebounding growth and political instability led to slightly negative portfolio performance in Q2/2024. As global growth starts to moderate, we continue to favor government bonds over credit. Maintain a defensive portfolio stance.