Latest from BCA Research
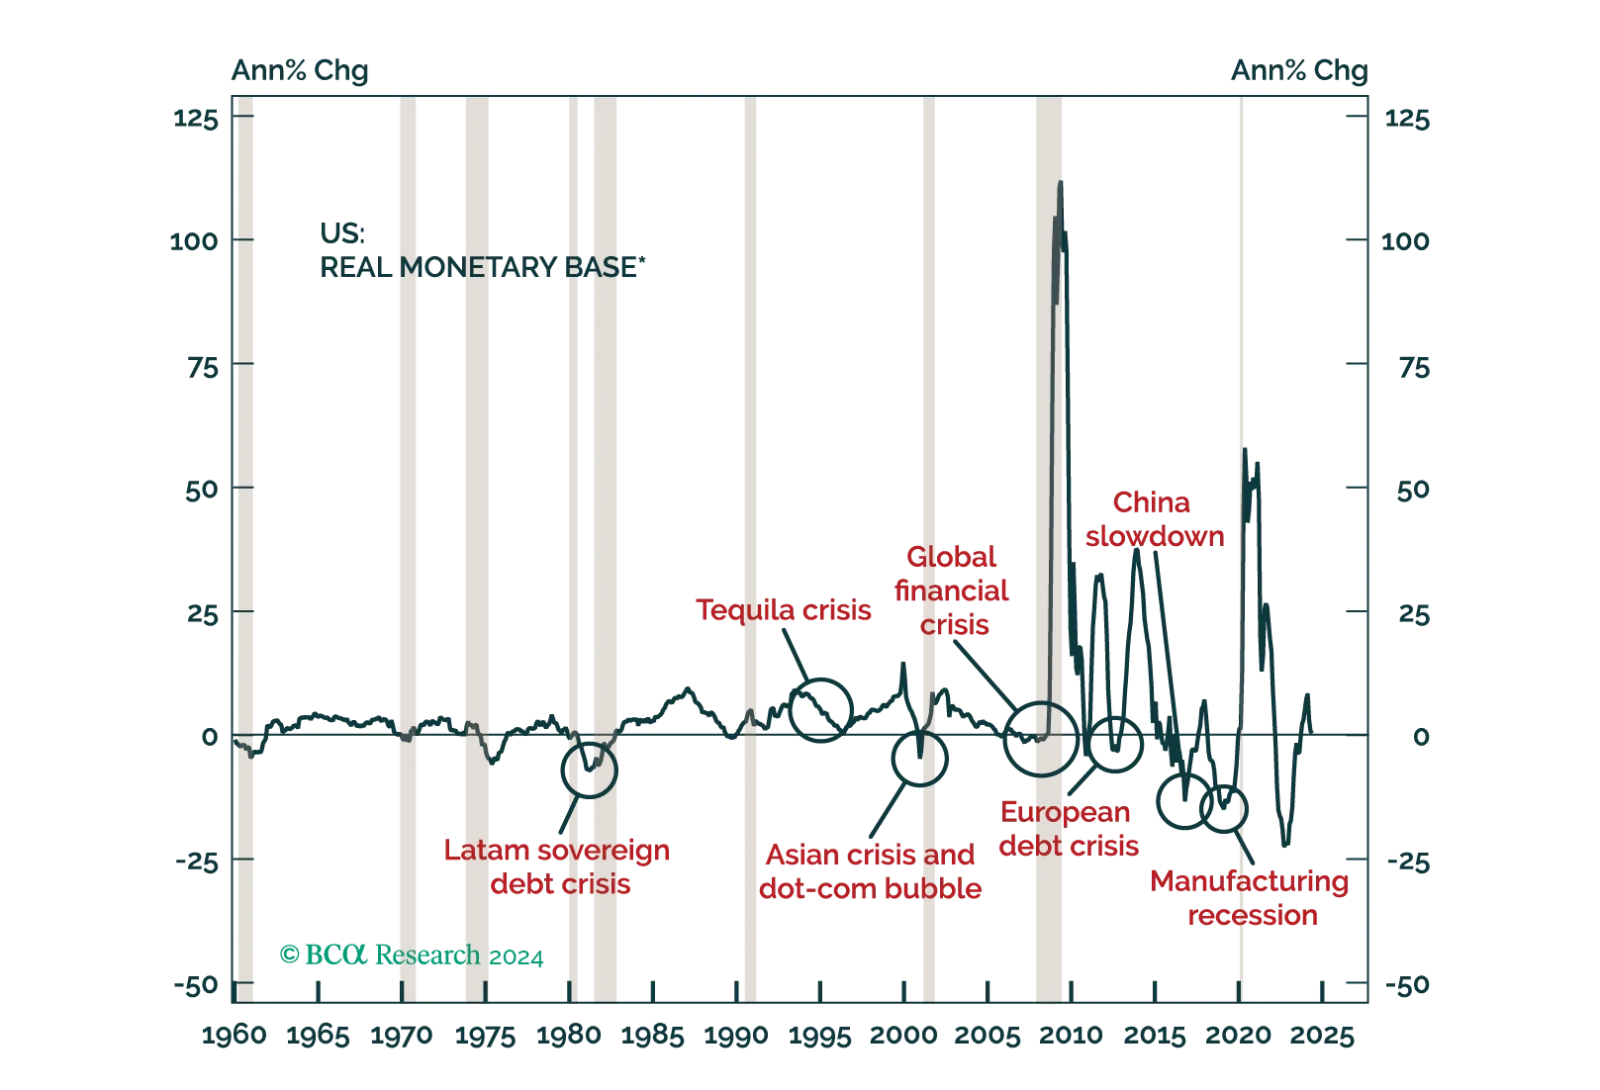
US dollar liquidity has been shrinking, which has important ramifications for global asset prices, including currencies. In this report, we delve into the process of dollar liquidity creation and the outlook for currencies over the next six-to-twelve months.
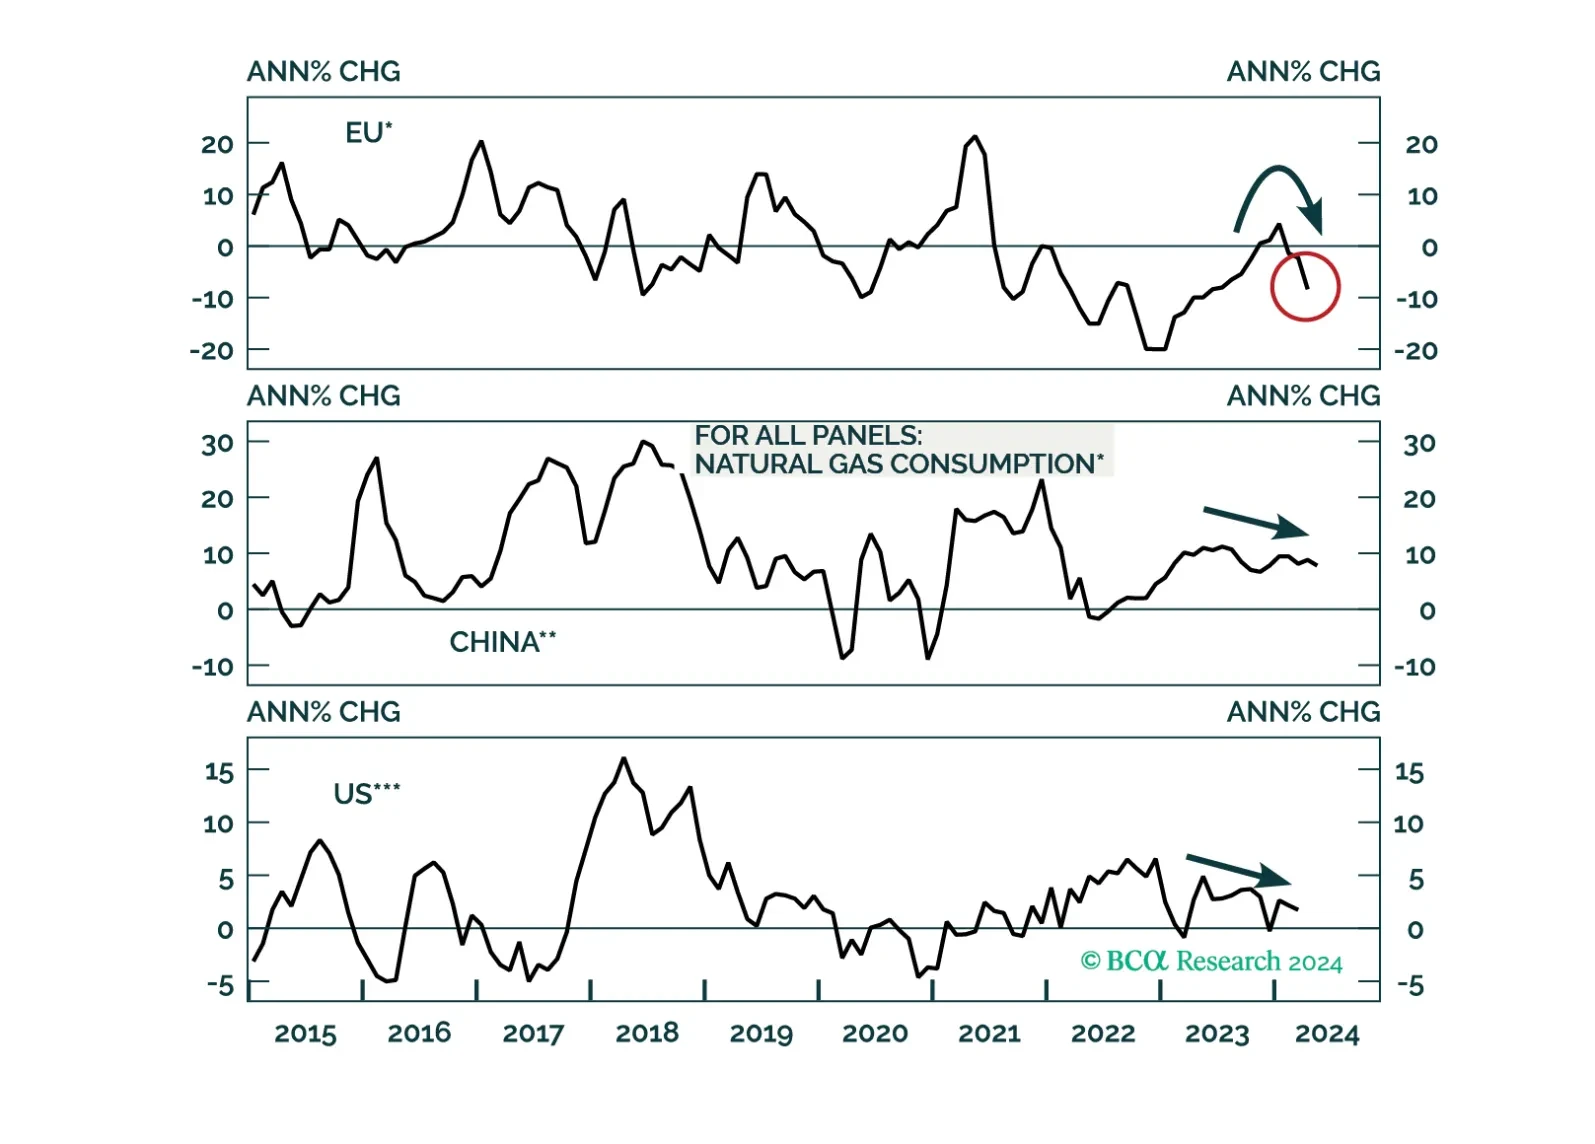
A global economic downturn will be a headwind for natgas prices over the cyclical horizon. Thereafter, LNG capacity additions will help keep the market in balance into the end of the decade. That said, Europe’s increased dependence on global LNG flows raises its exposure to market dynamics in the rest of the world. This will keep volatility elevated versus pre-Ukraine war.
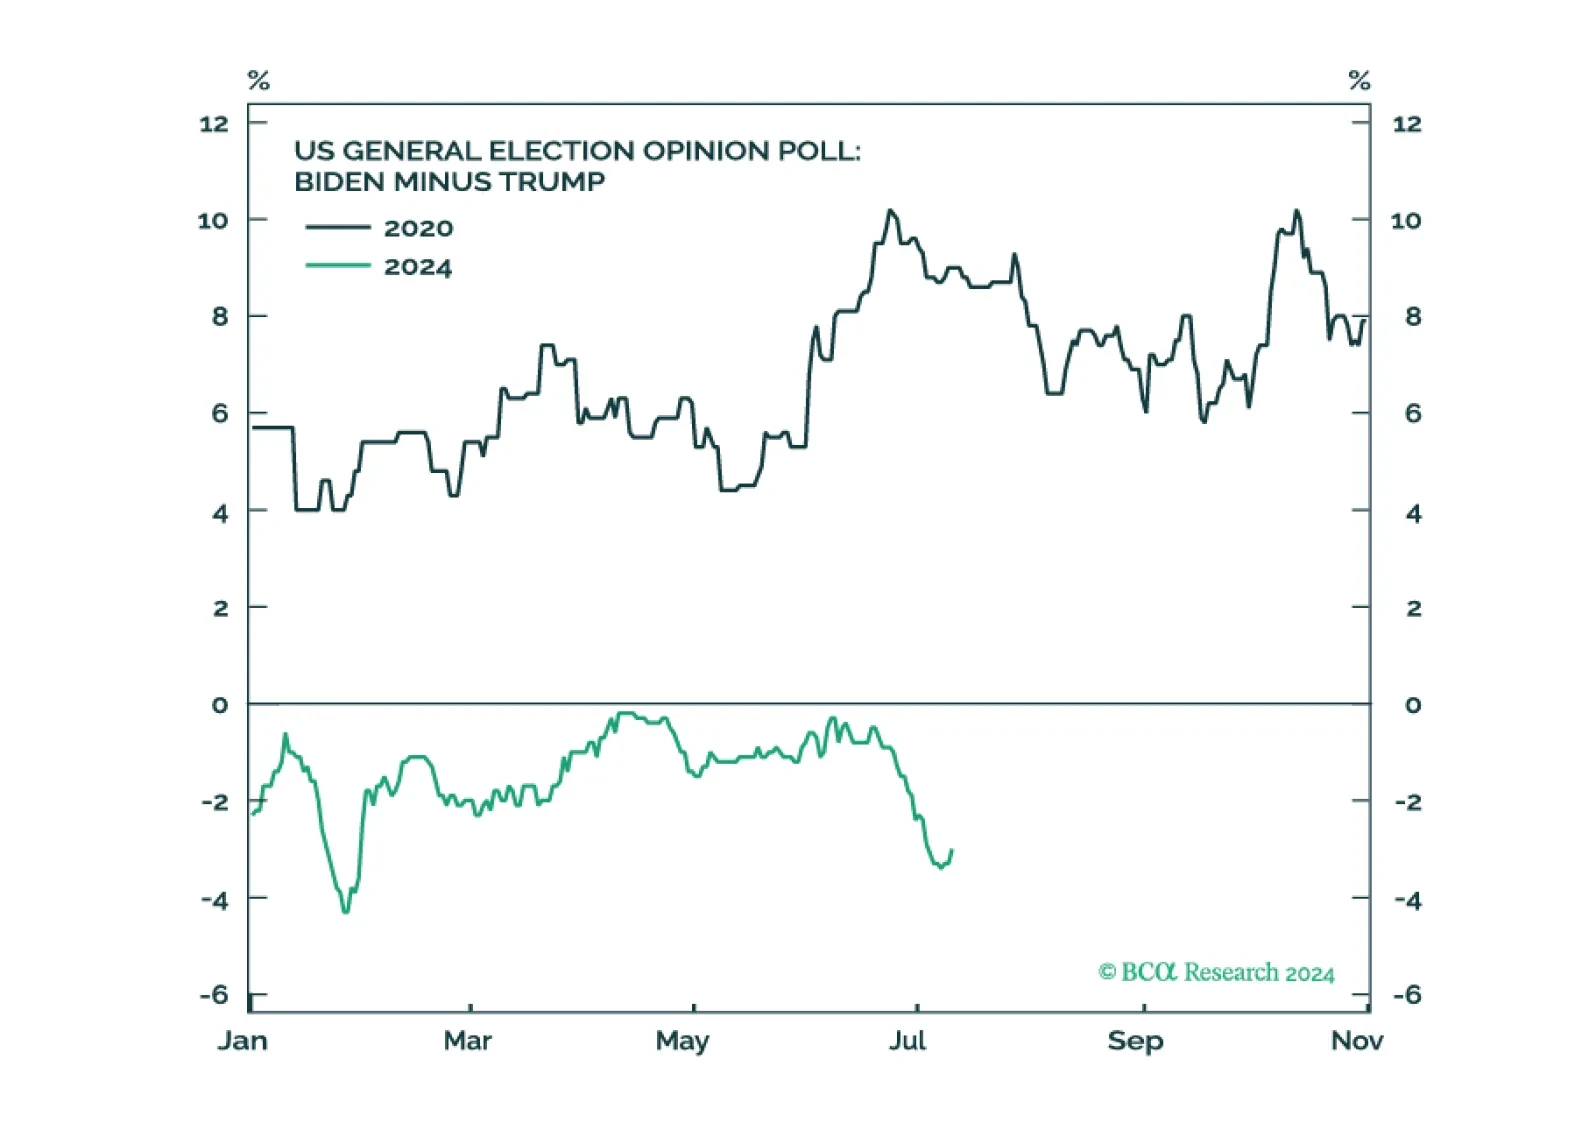
The conventional wisdom is wrong: Trump is not going to substantially cut taxes once in office; he is going to raise taxes by jacking up tariffs. To the extent that this dampens economic activity, it is bad news for stocks but good news for bonds.
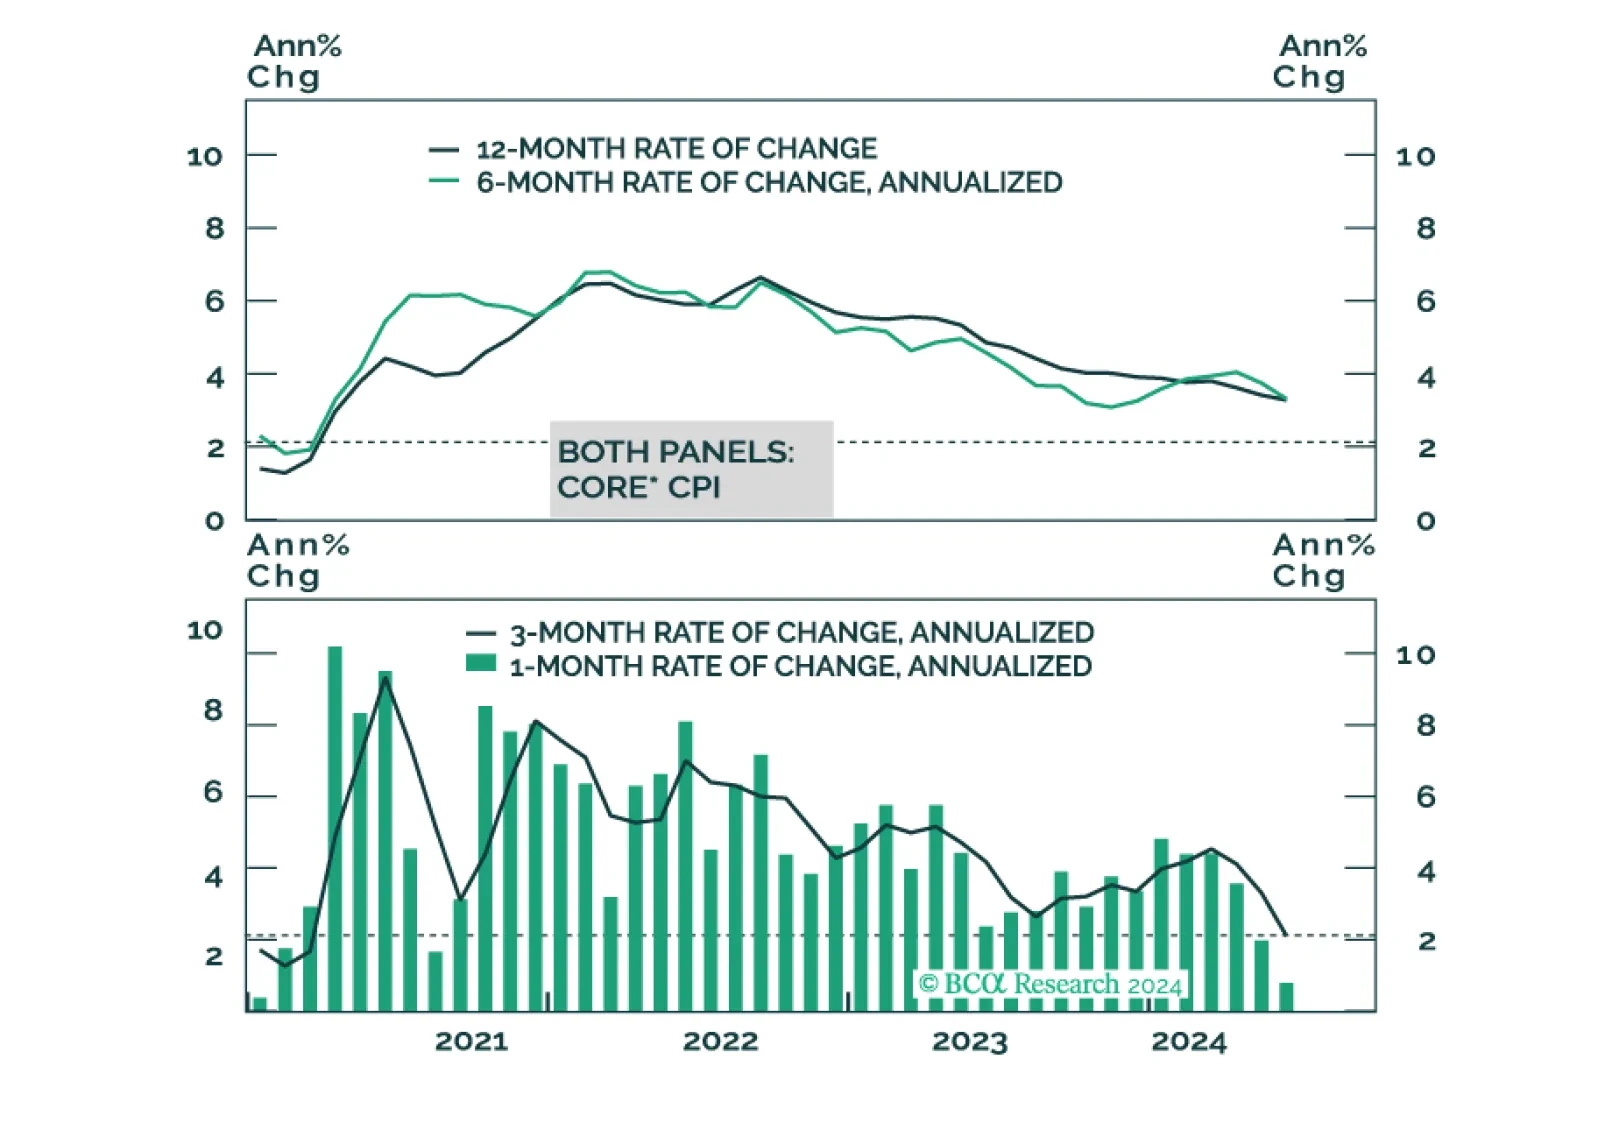
In light of last week’s employment report and this morning’s CPI, it’s time for the Federal Reserve to cut rates.
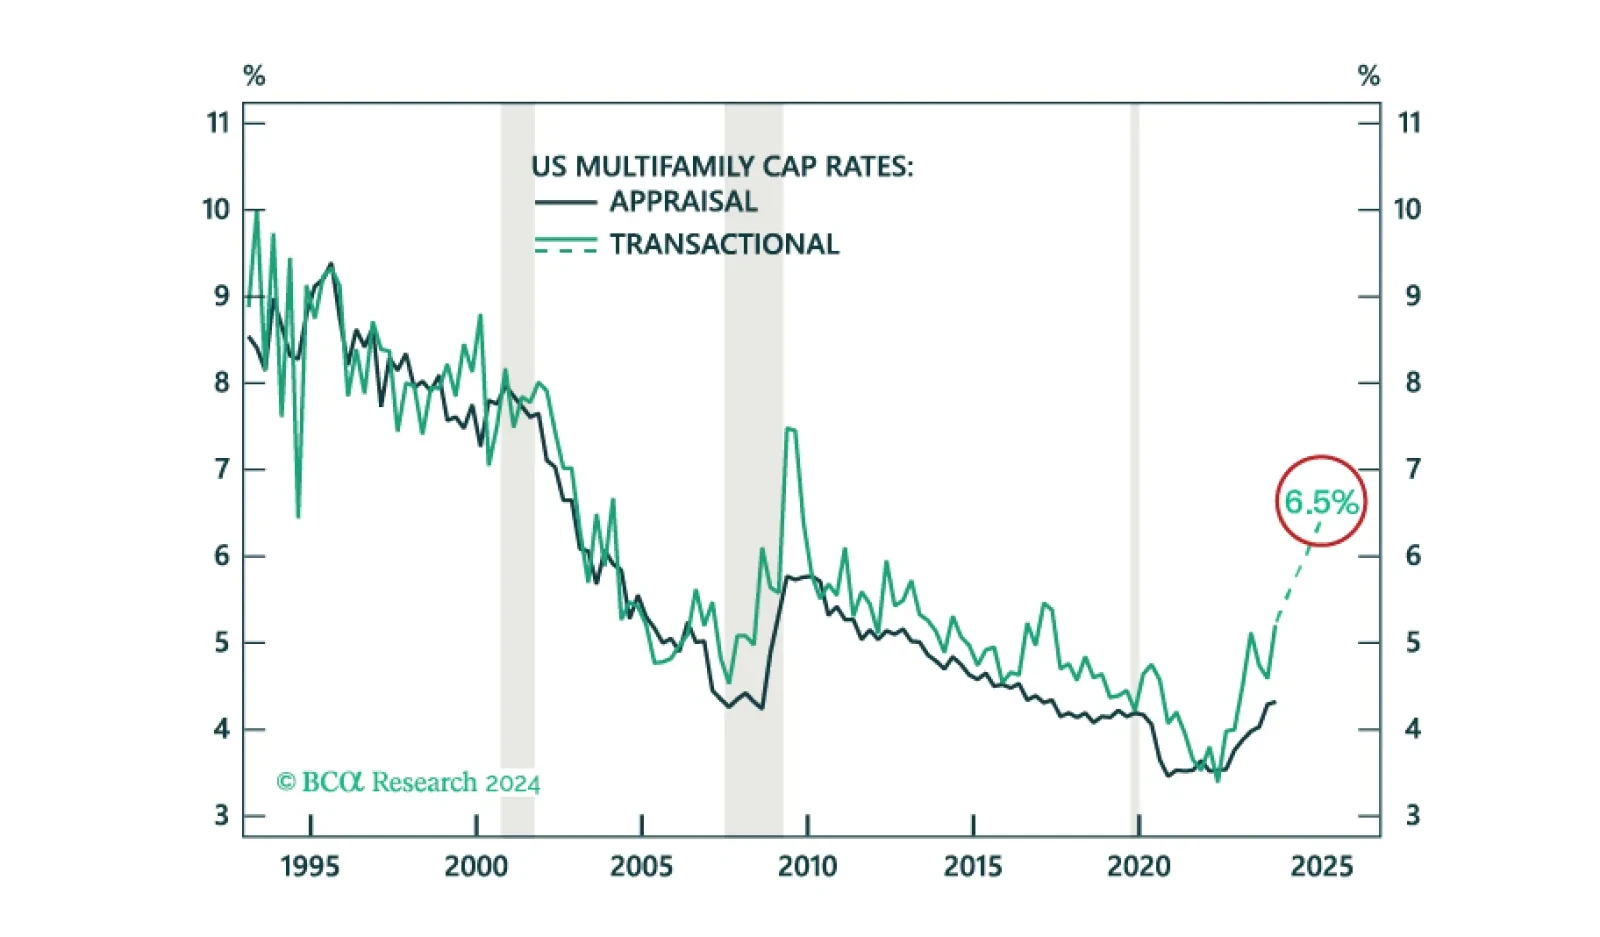
We project US Multifamily cap rates to increase from 5.2% to 6.5%. While we find an unfavorable risk-adjusted return on the asset, especially relative to other opportunities in CRE, cap rates are moving closer to peak.
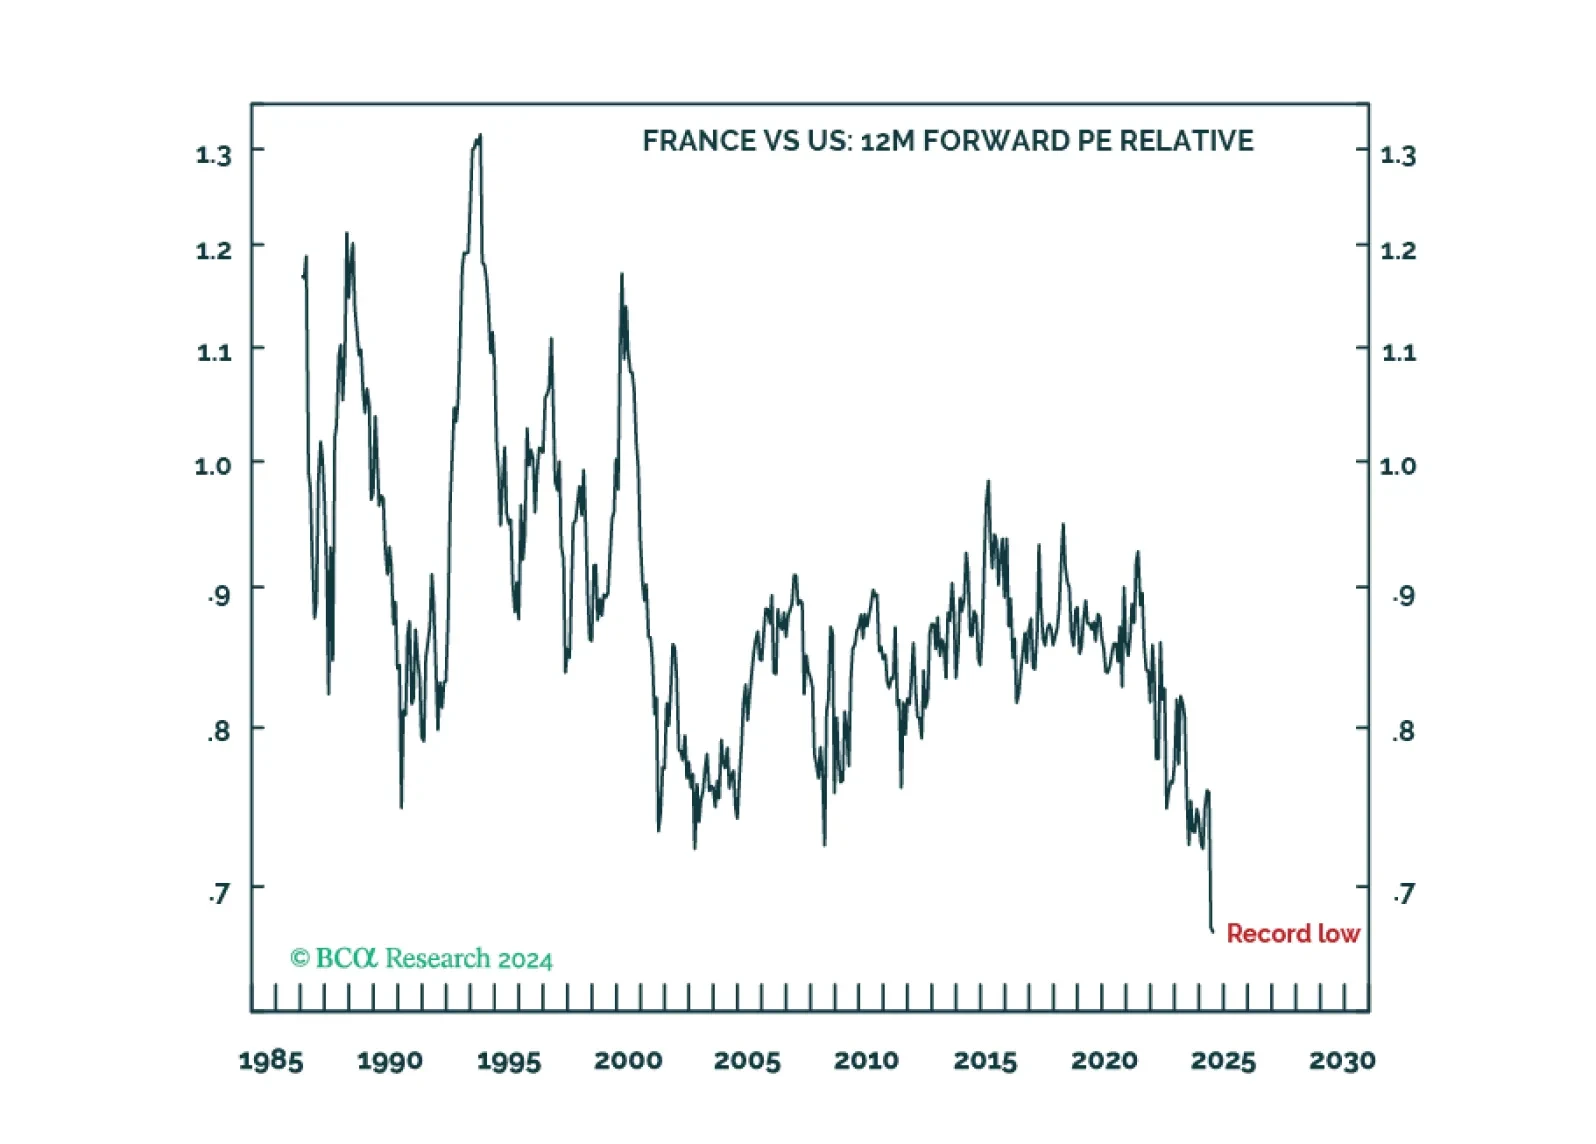
The French stock market has never been so cheap versus the US. And its sharp underperformance on its recent political events is irrational given the CAC 40’s limited exposure to French domestic economics and politics. This provides a great buying opportunity both tactically and for the longer term. Plus: stocks versus bonds approaching a potential consolidation phase.
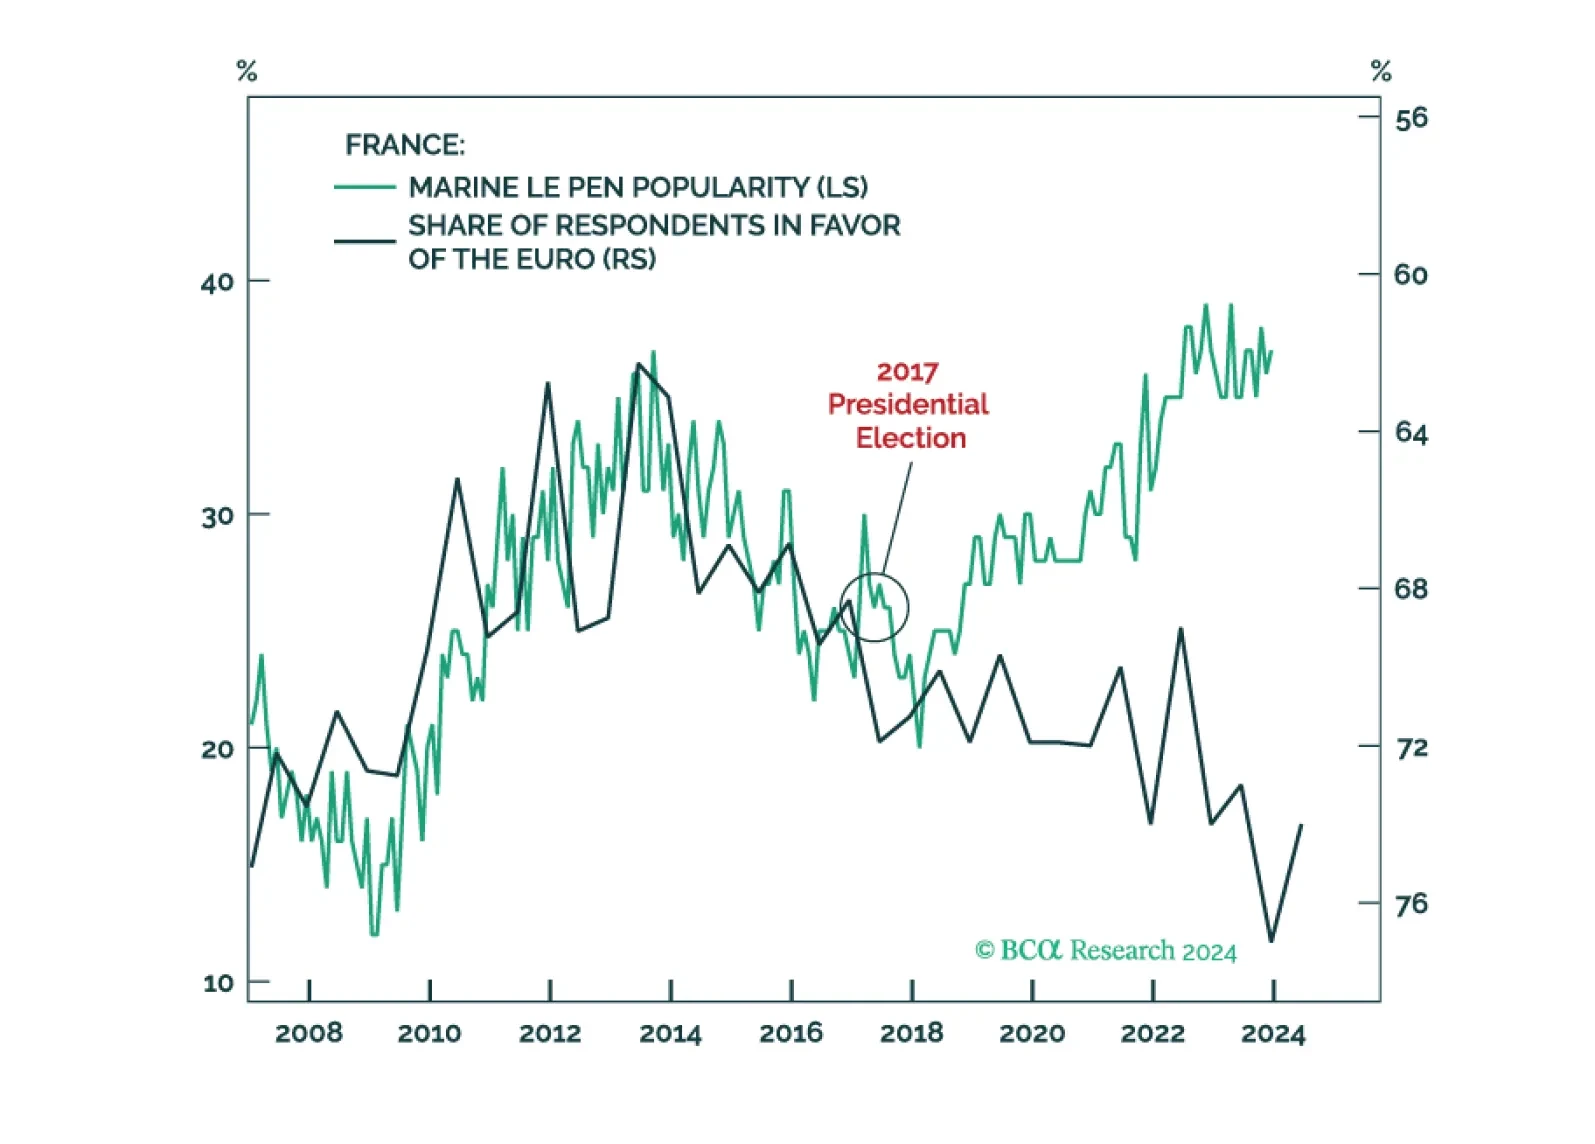
Investors in European sovereign bonds should find solace that continental voters are not turning away from support for EU integration. As such, populist parties are not really that “far” left or right. And as long as they want to maintain popular support, they will have to abide by the fiscal rules imposed by Brussels. No such supranational constraint exists in the U.S., the real risk for global bond operators.
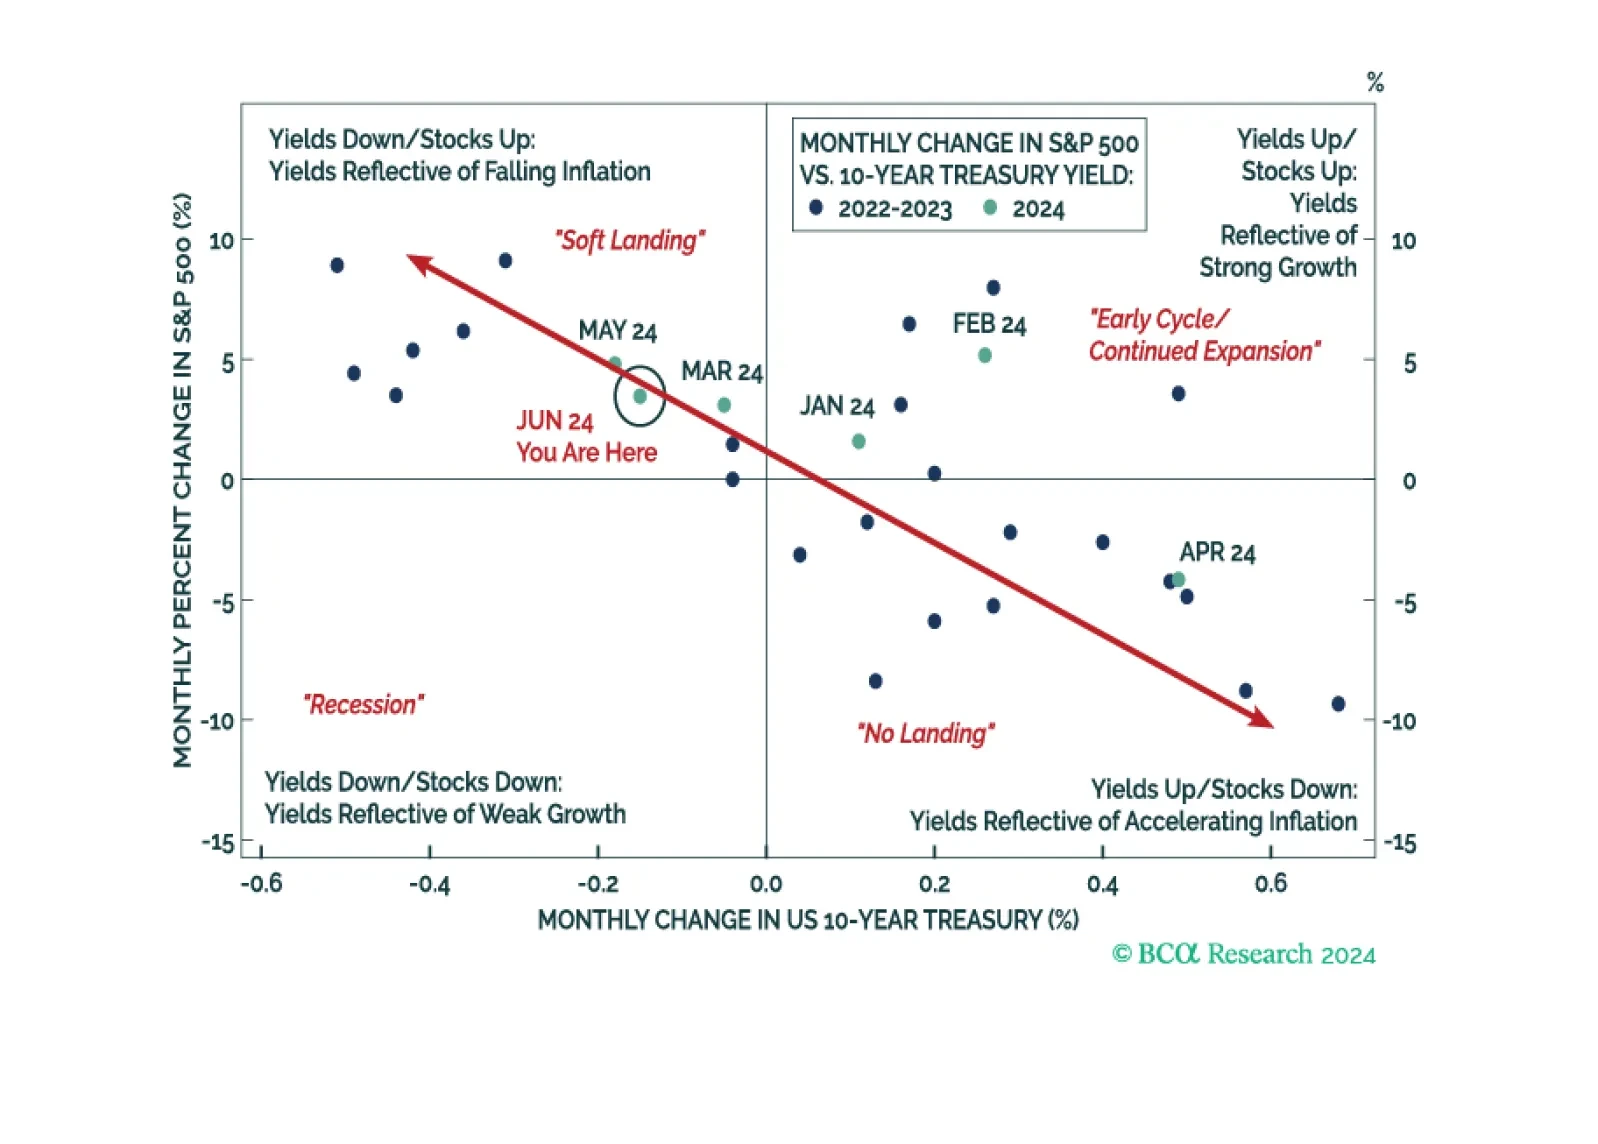
We have turned cautious on equities for the first time since August 2022. Our end-of-the-year target for 2024, 5,500 on the S&P 500, has been reached. From here on out, any upside is gravy. However, we worry about US – not European – politics. In fact, we think investors could profit from the recent selloff in France. The real risks are in the US.