Latest from BCA Research
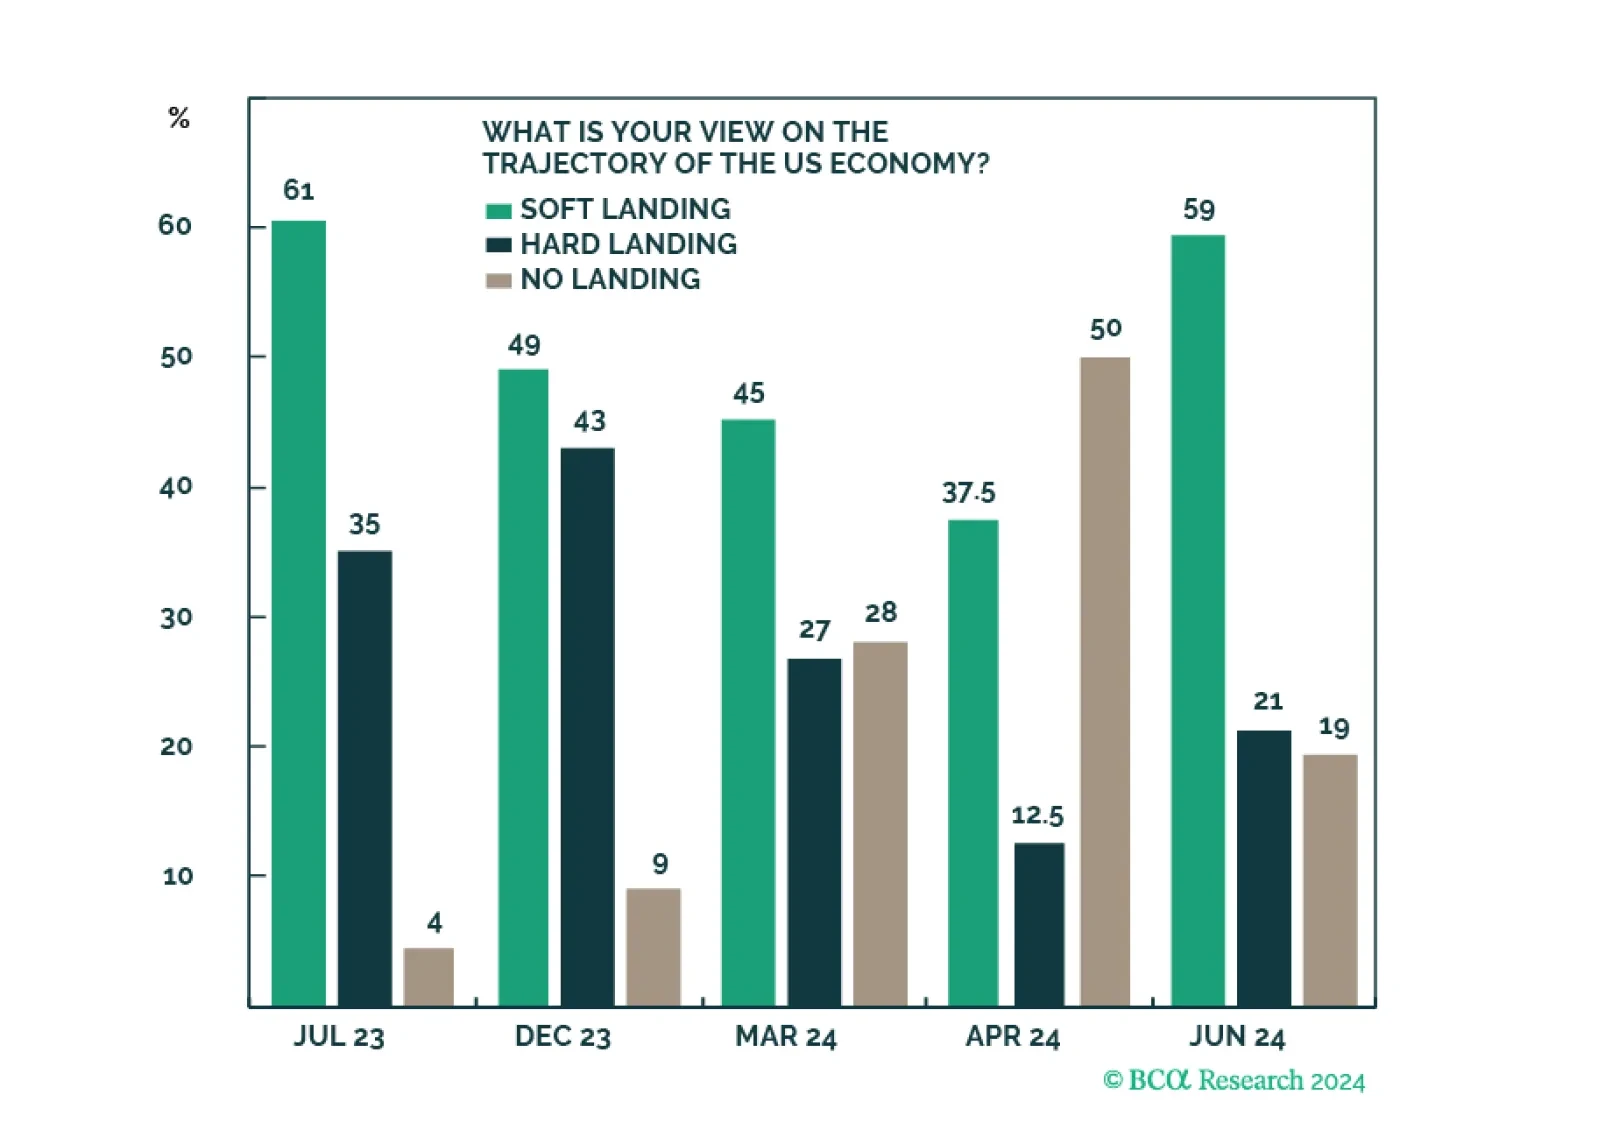
Investors are increasingly more optimistic about the trajectory of the US economy and believe that the “Fed put” is in play limiting the downside. While the majority still have cash to put to work, many are waiting to see if the rally broadens thanks to earnings rebound across non-GenAI sectors. Fairly conservative positioning and expectations of the rangebound markets point to a consensus view that the market may be fully valued, and a soft-landing outcome along with rate cuts, are priced in.

At first glance, France has moved to the far left. However, this coalition is fragile, and Macron’s allies still hold the balance of power. What are the assets that will benefit from this new political setup, and those that will not?
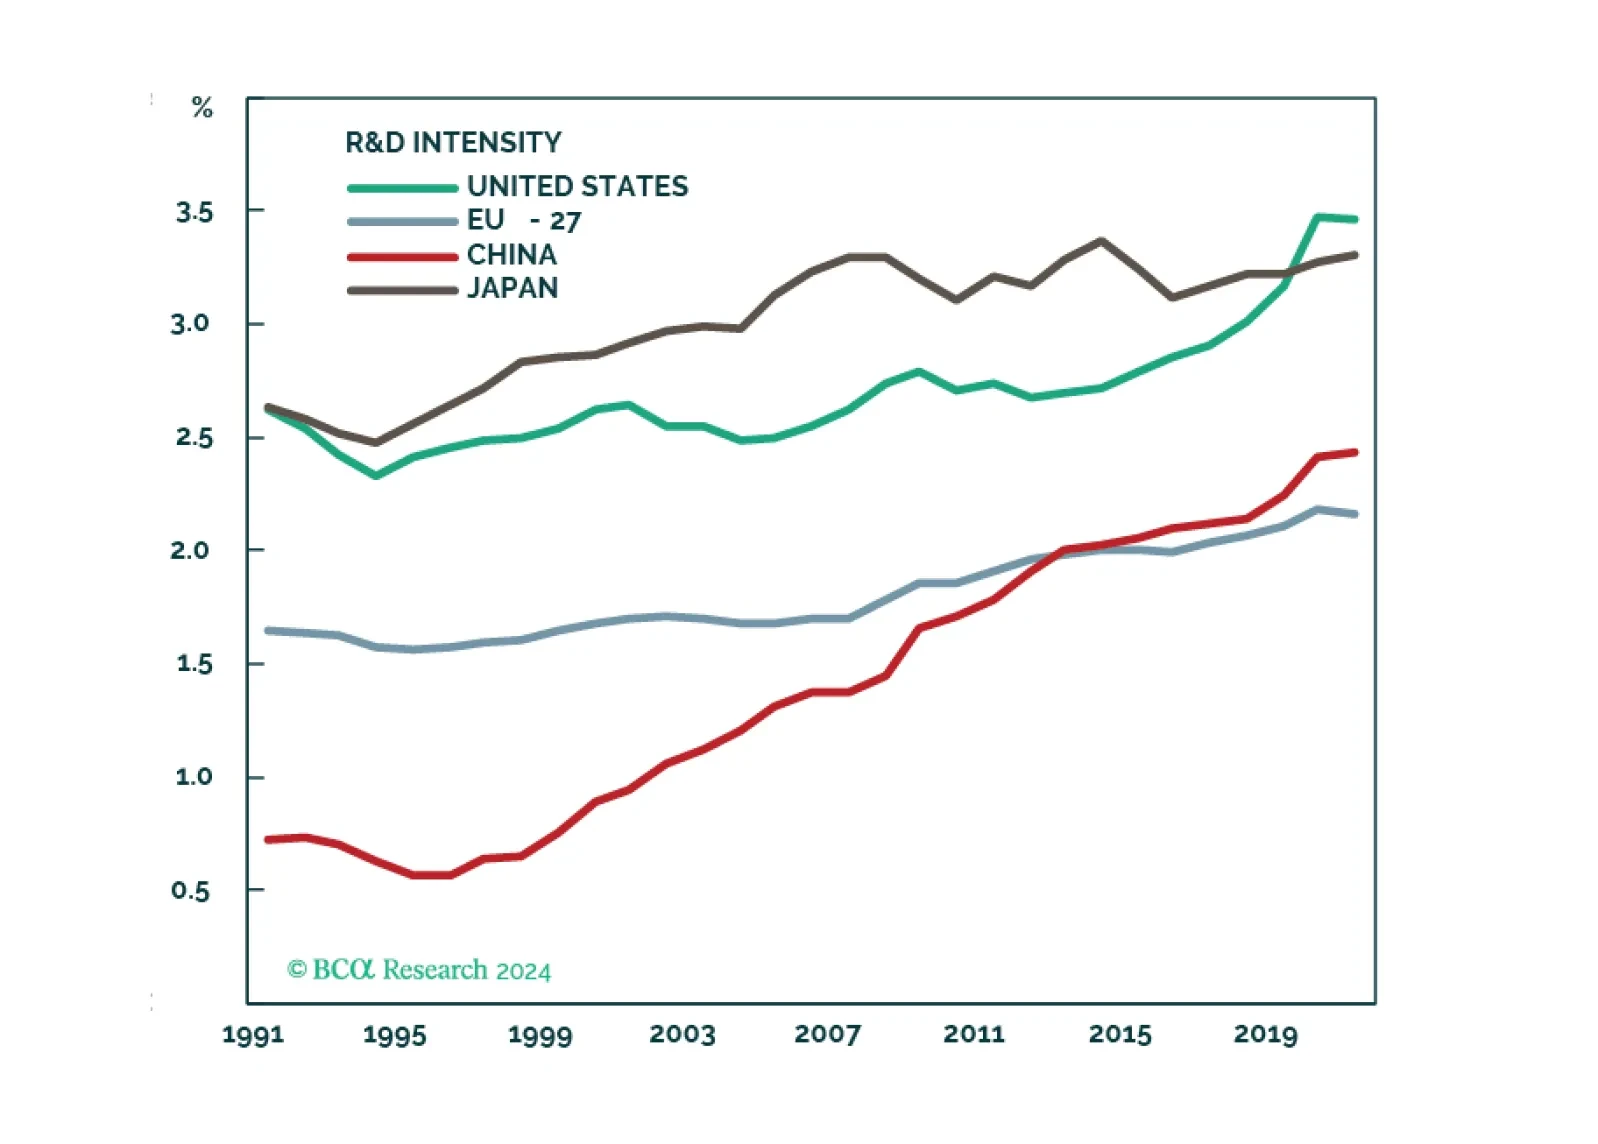
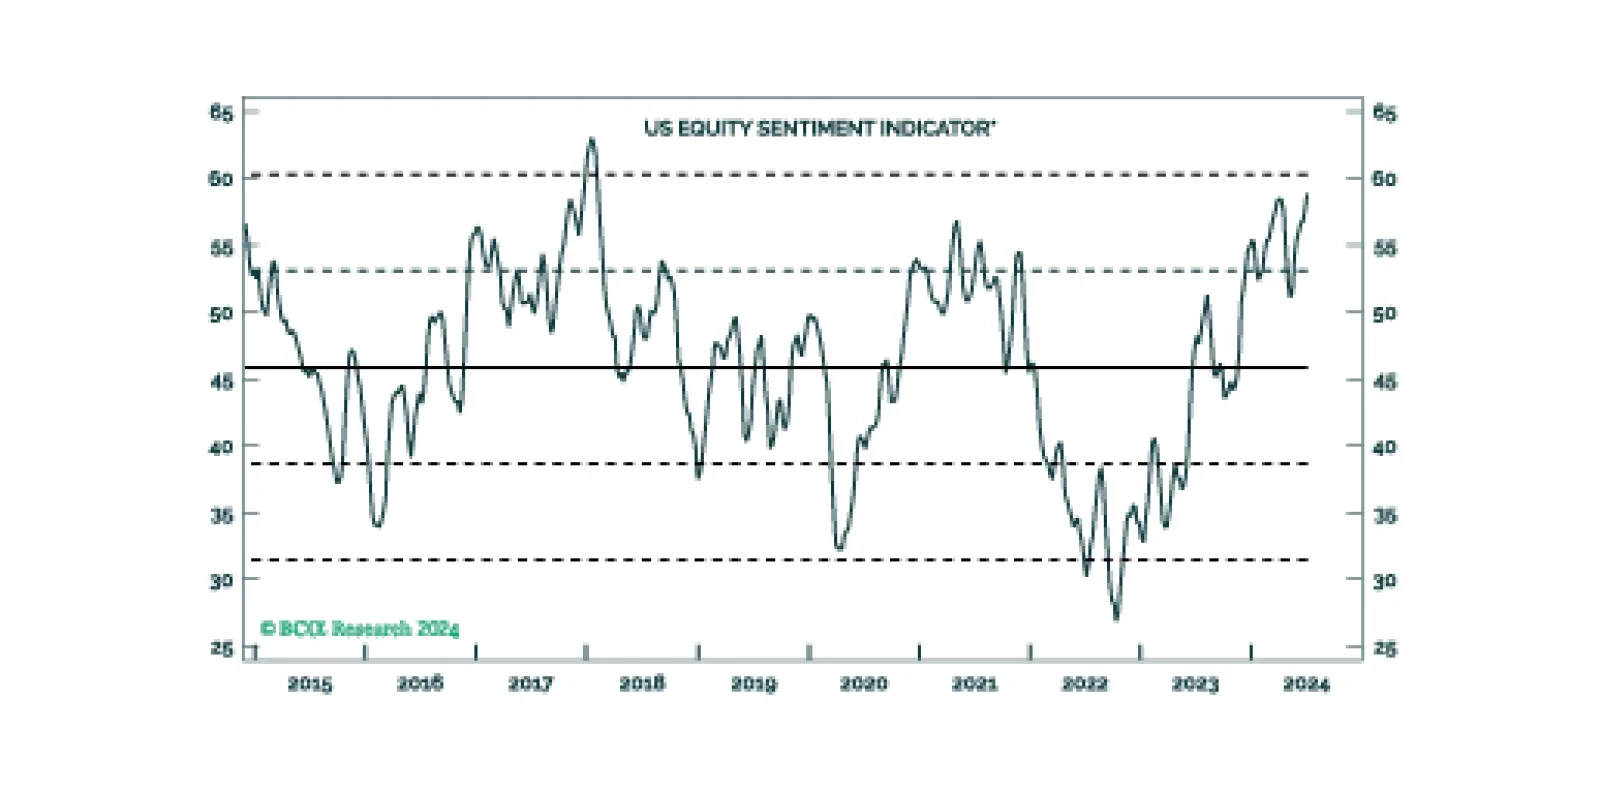
Although we ticked a second box on our checklist, the incoming data still do not indicate that a recession is imminent. We remain tactically equal weight equities with a strong bias to underweight them, but we’re not exiting the party just yet.

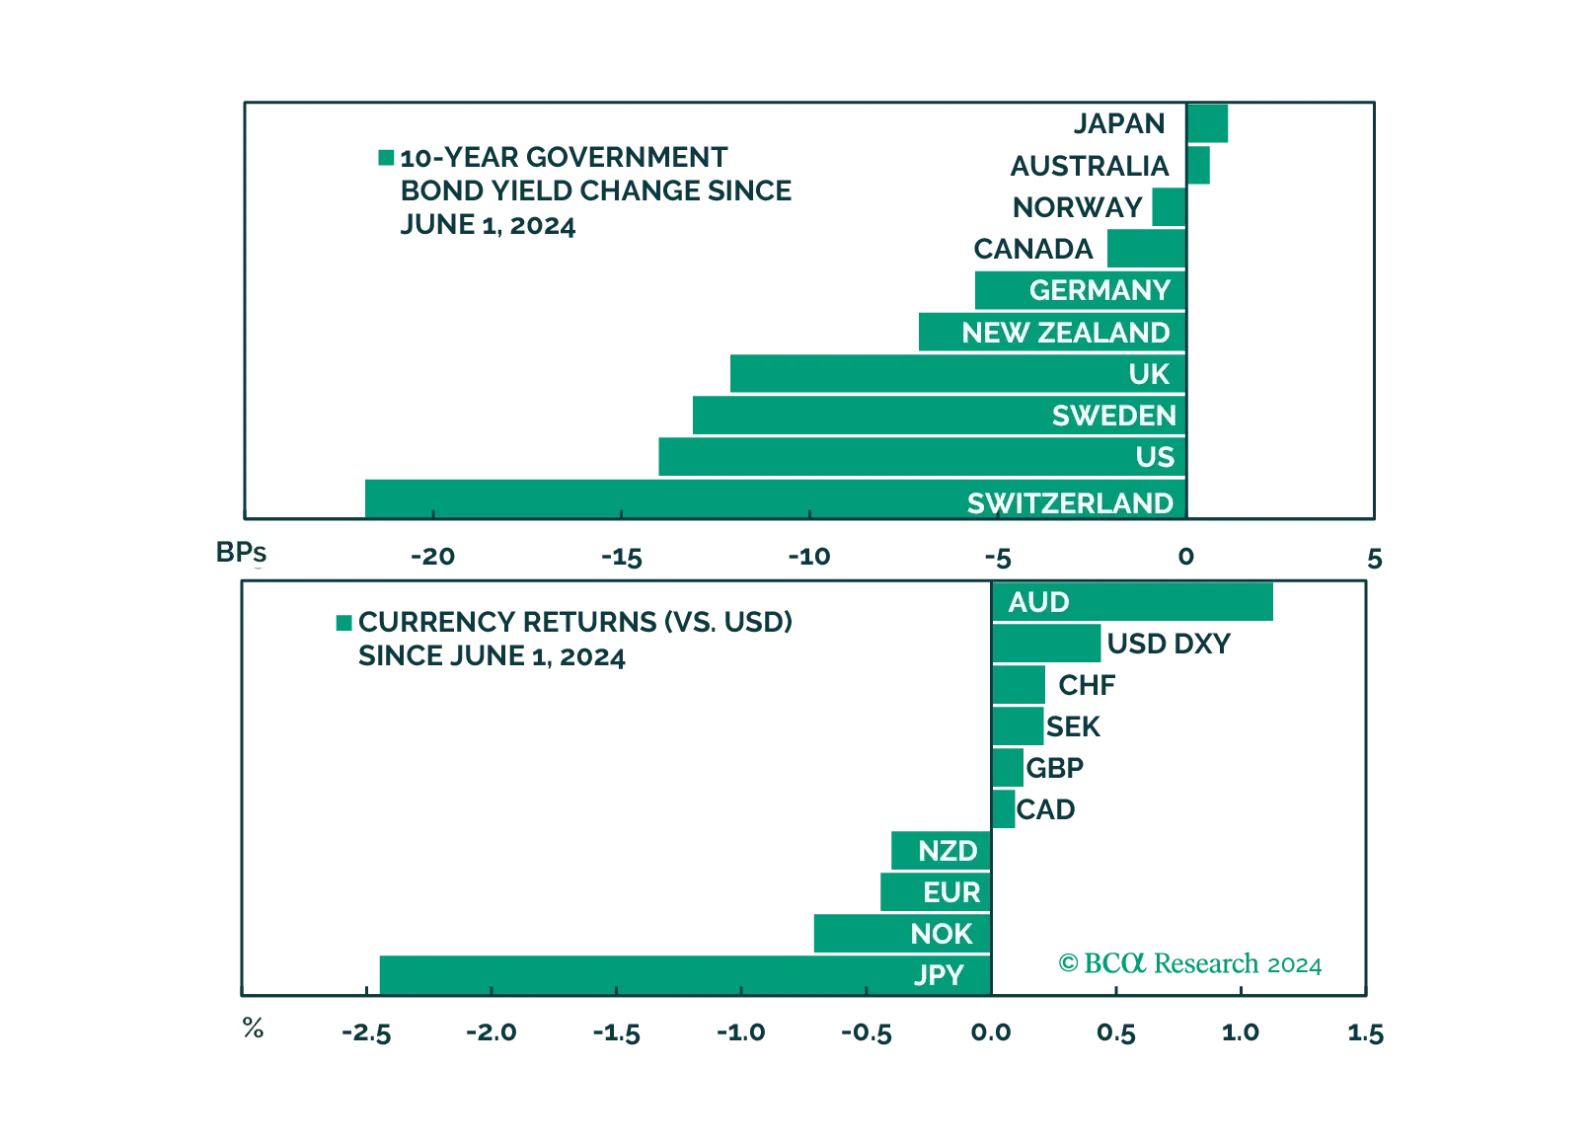
In this week's report, we review the impact of political developments, as well as incoming fundamental data, on our positioning.
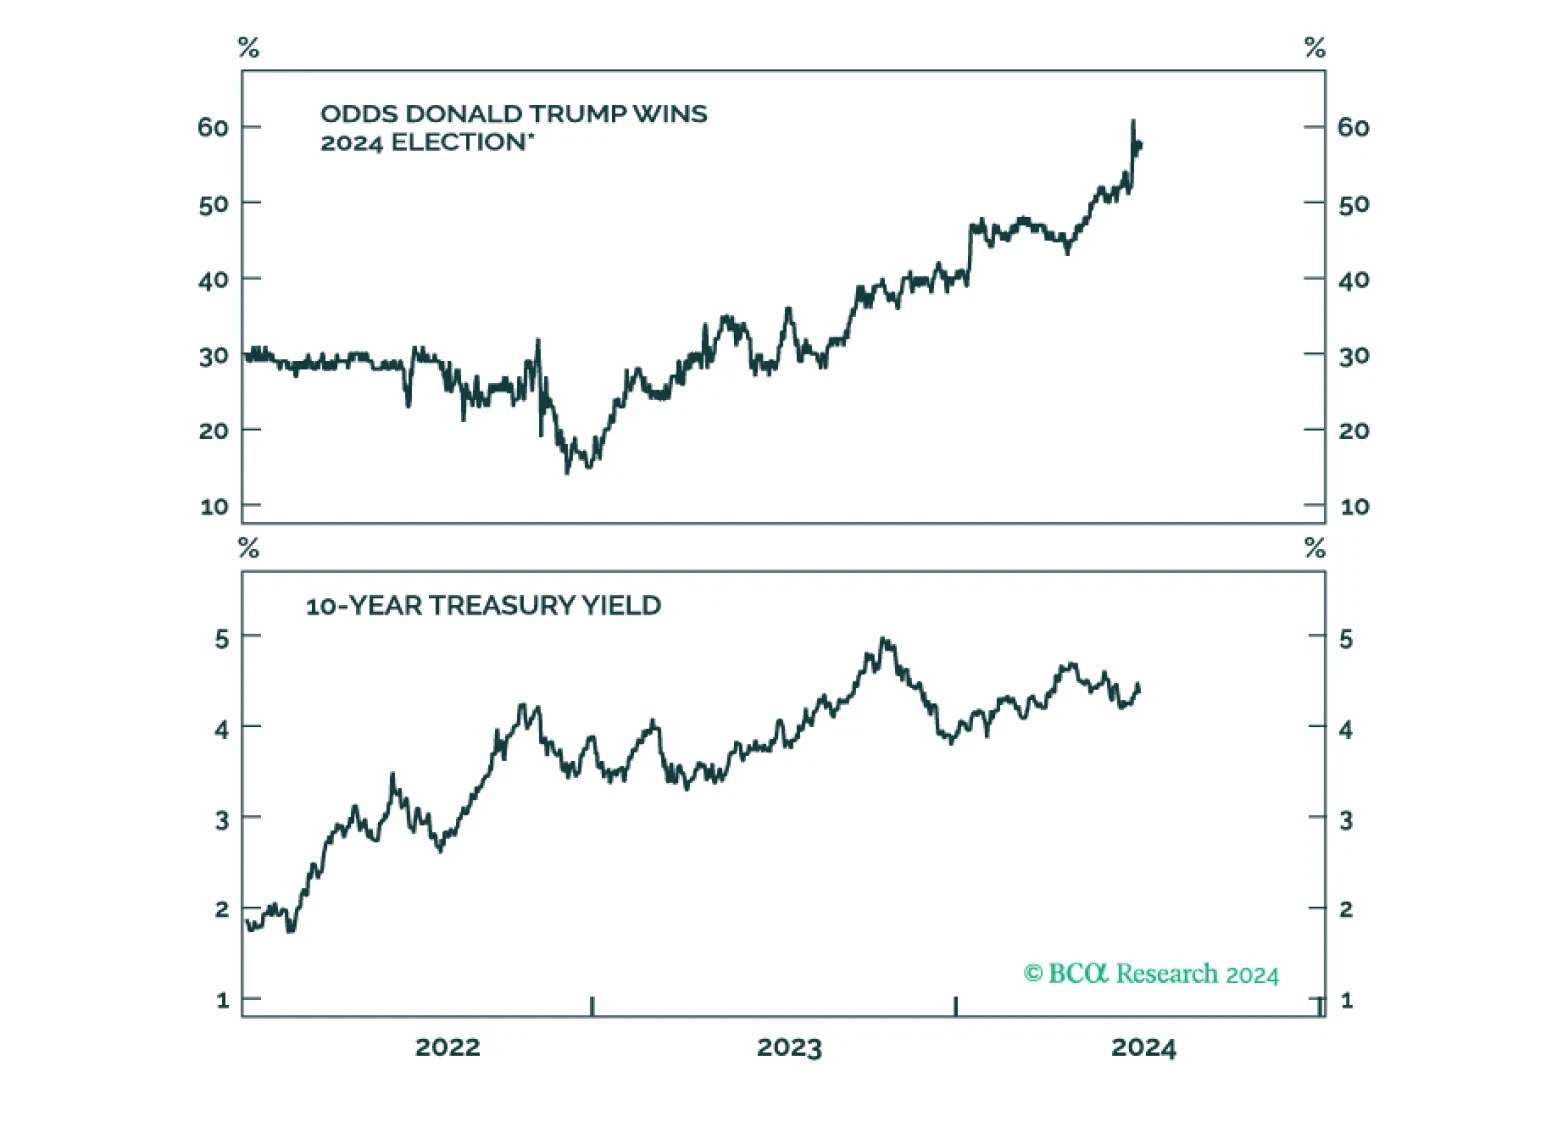
Our labor market indicators have softened meaningfully during the past month but aren’t yet signaling an imminent recession. That said, the Fed can no longer ignore the labor market with the unemployment rate above 4% and rising.
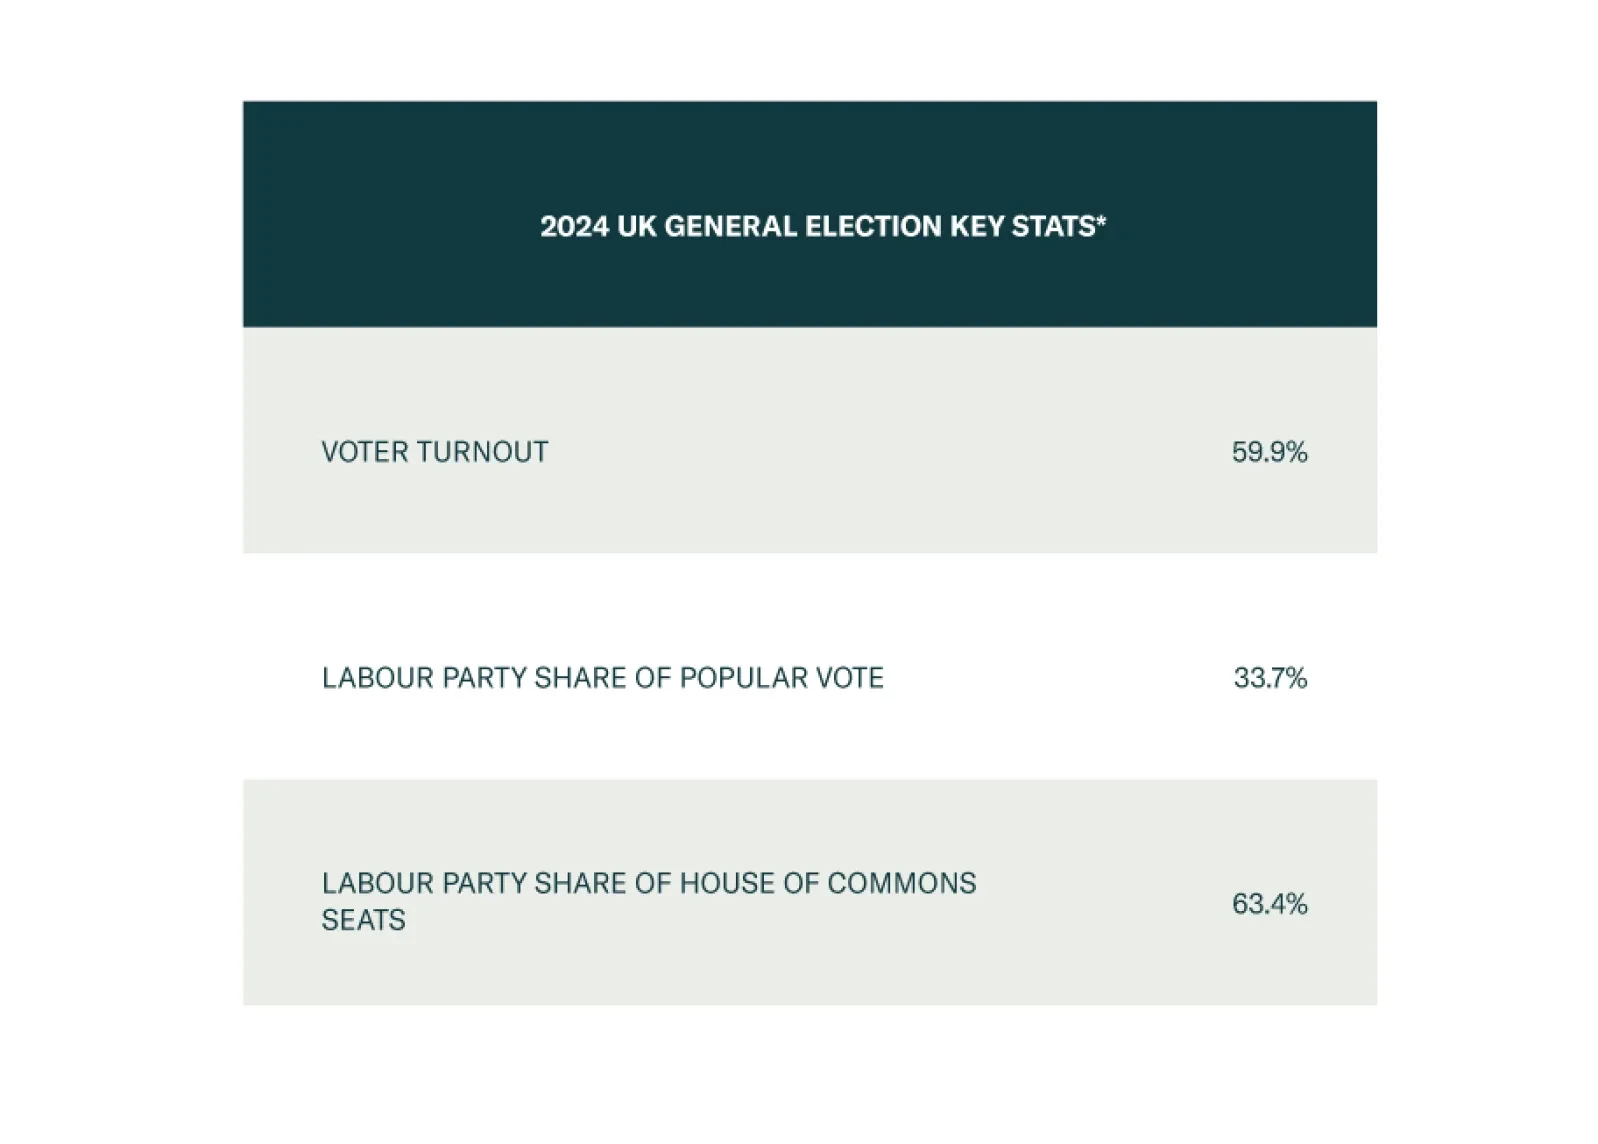
The new Labour government will have flexibility to respond to macro shocks, which is positive for the UK in general, namely GBP-EUR, and also gilts in absolute terms. But over the long run, tax hikes will likely surprise to the upside, which poses a risk to corporate earnings.

Does the incipient slowdown in European data herald a soft landing and a goldilocks period for equities? We have our doubts.
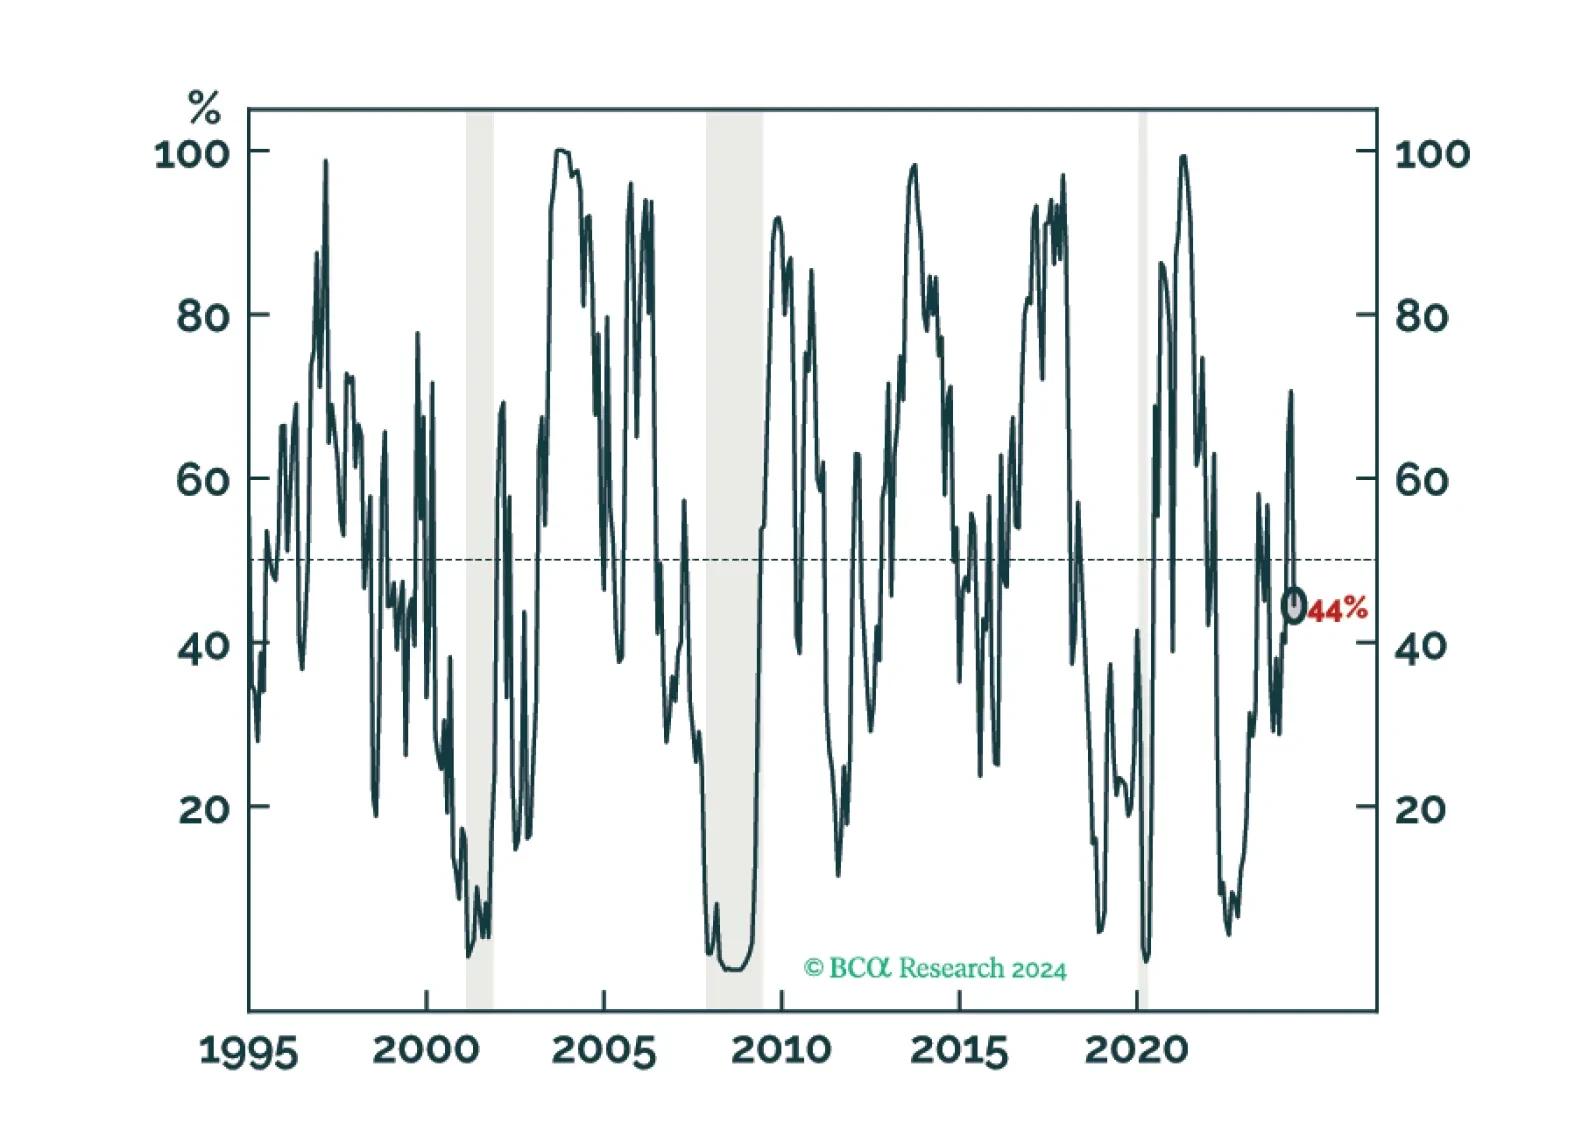
Global Equity Score drops to neutral. Sector model upgrades Tech and Real Estate, while downgrading Industrials and Base Materials.