Latest from BCA Research
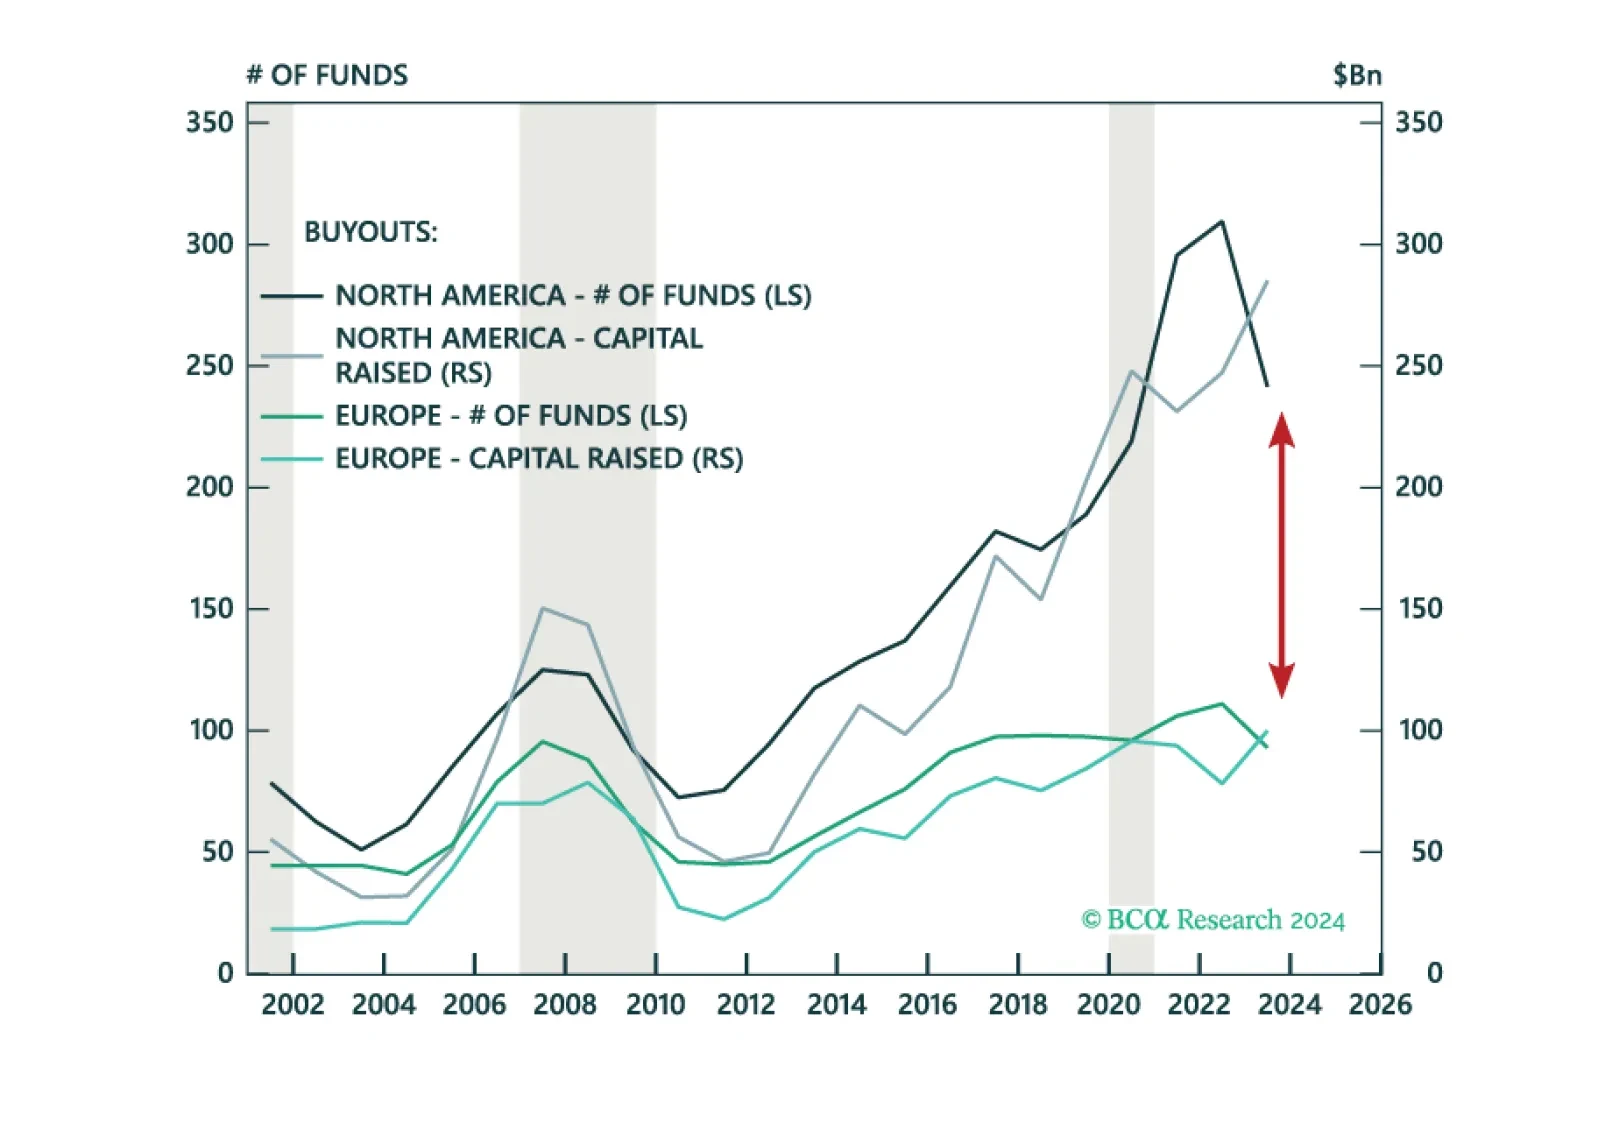
We are growing positive on Growth assets with recession expectations increasing our optimism on entry points. Equities are led by APAC Private Equity, North America Venture Capital, and Europe Buyouts. Our outlook continues to improve on CRE within the Inflation & Diversification bucket while we are underweight Multi-Strategy amongst Hedge Funds. We maintain an overweight to Senior Direct Lending for Income with a preference for North America.
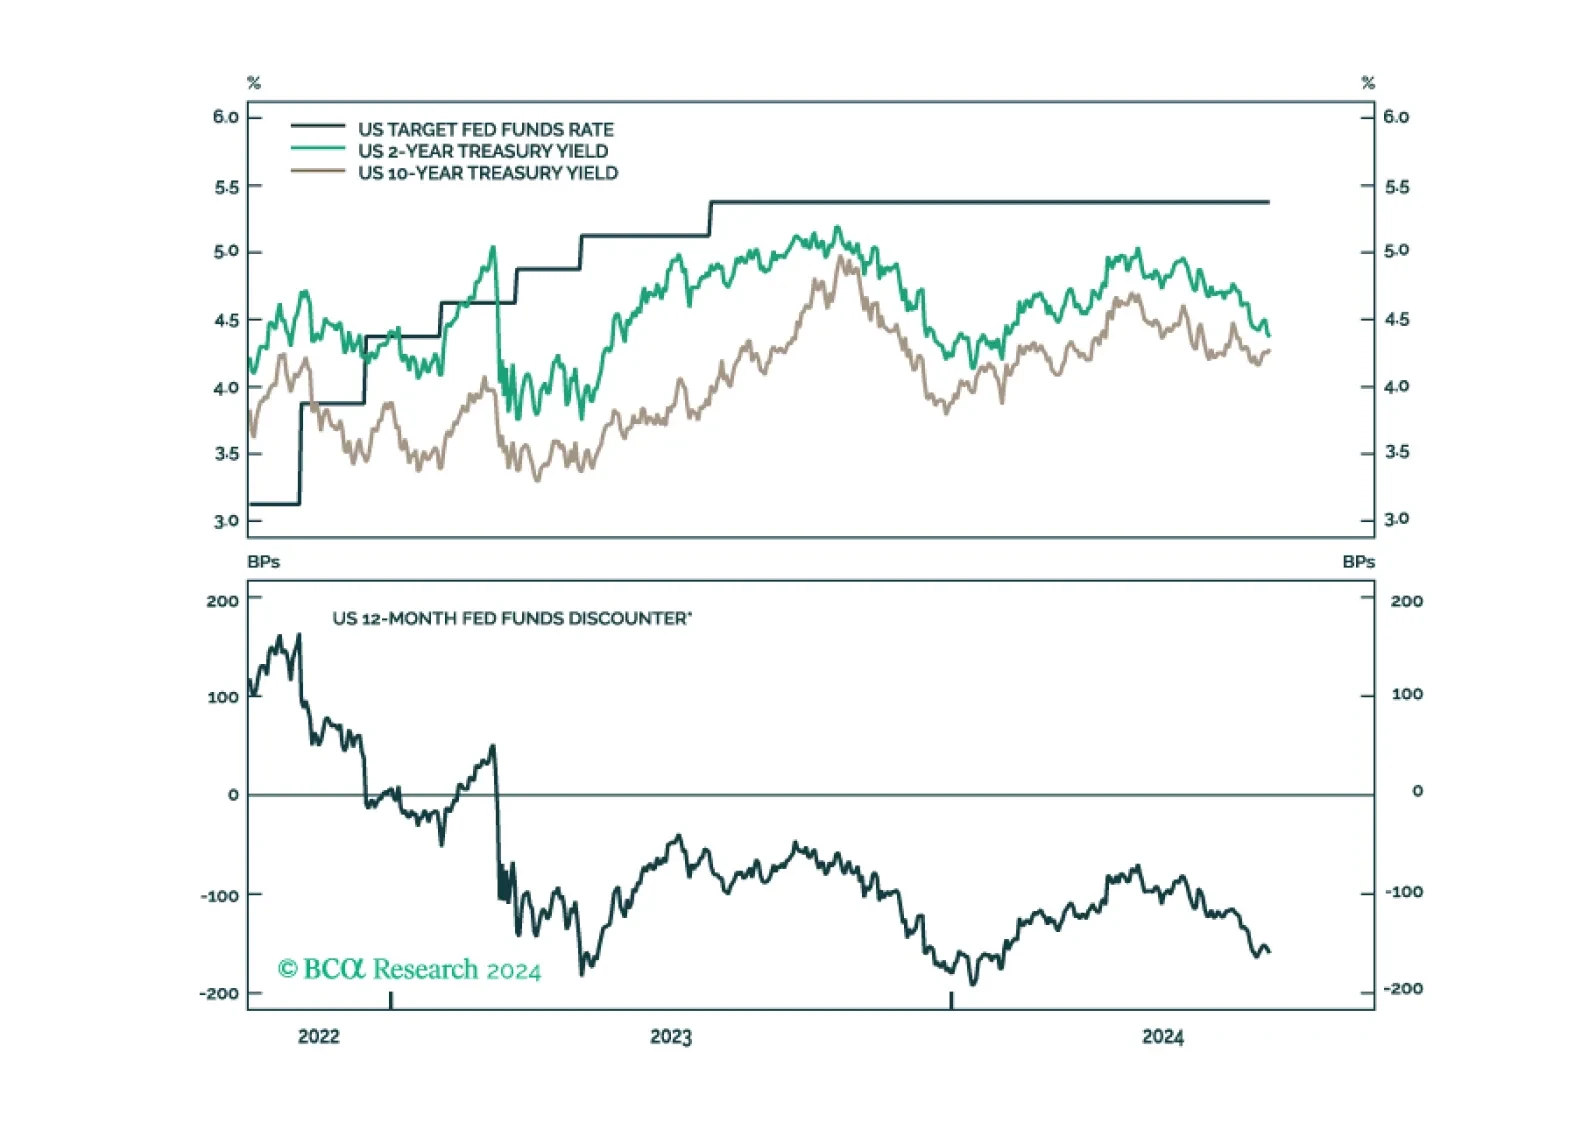
After this morning’s jobless claims number, we have now seen enough deterioration in our preferred labor market indicators to increase portfolio duration from “at benchmark” to “above benchmark”.

This report provides our framework for interpreting the messages from last week’s Third Plenum, and the potential implications for the economy and investors.
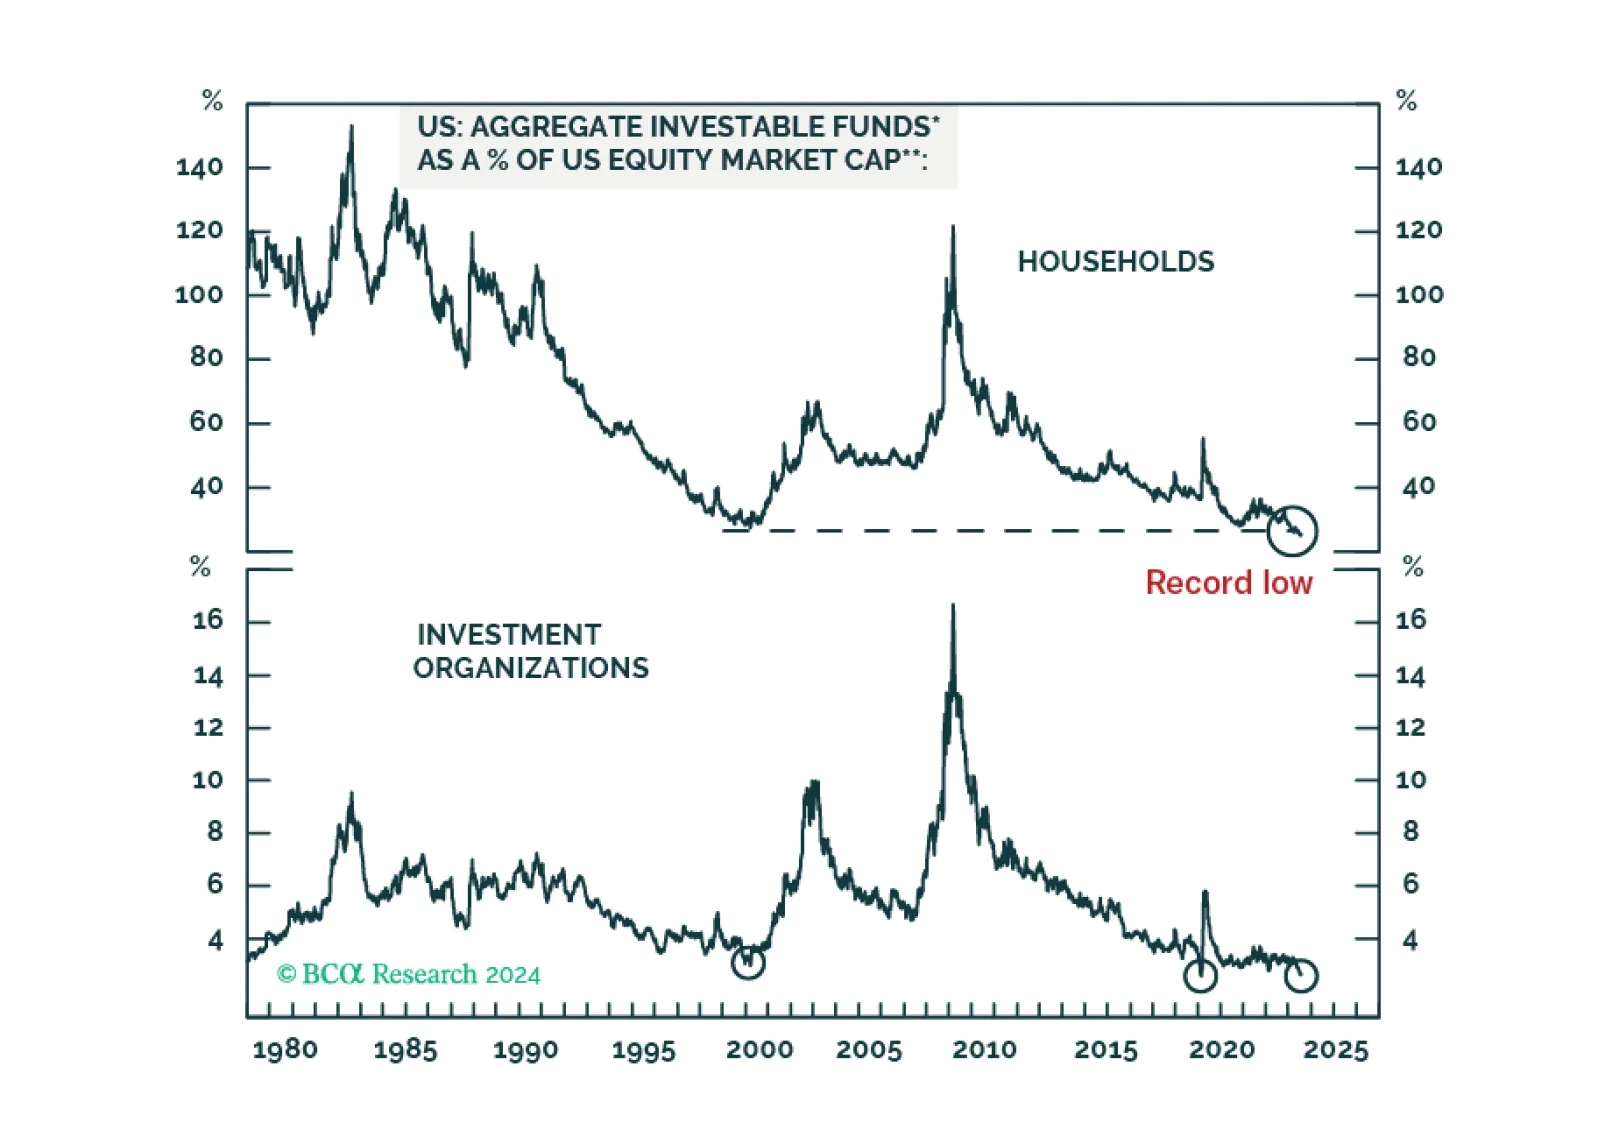
“Cash on the sidelines” as a share of the US equity market cap has declined to a record low. This is true for investable funds of both households and investment firms. Hence, there is little firepower left to sustain the equity rally.
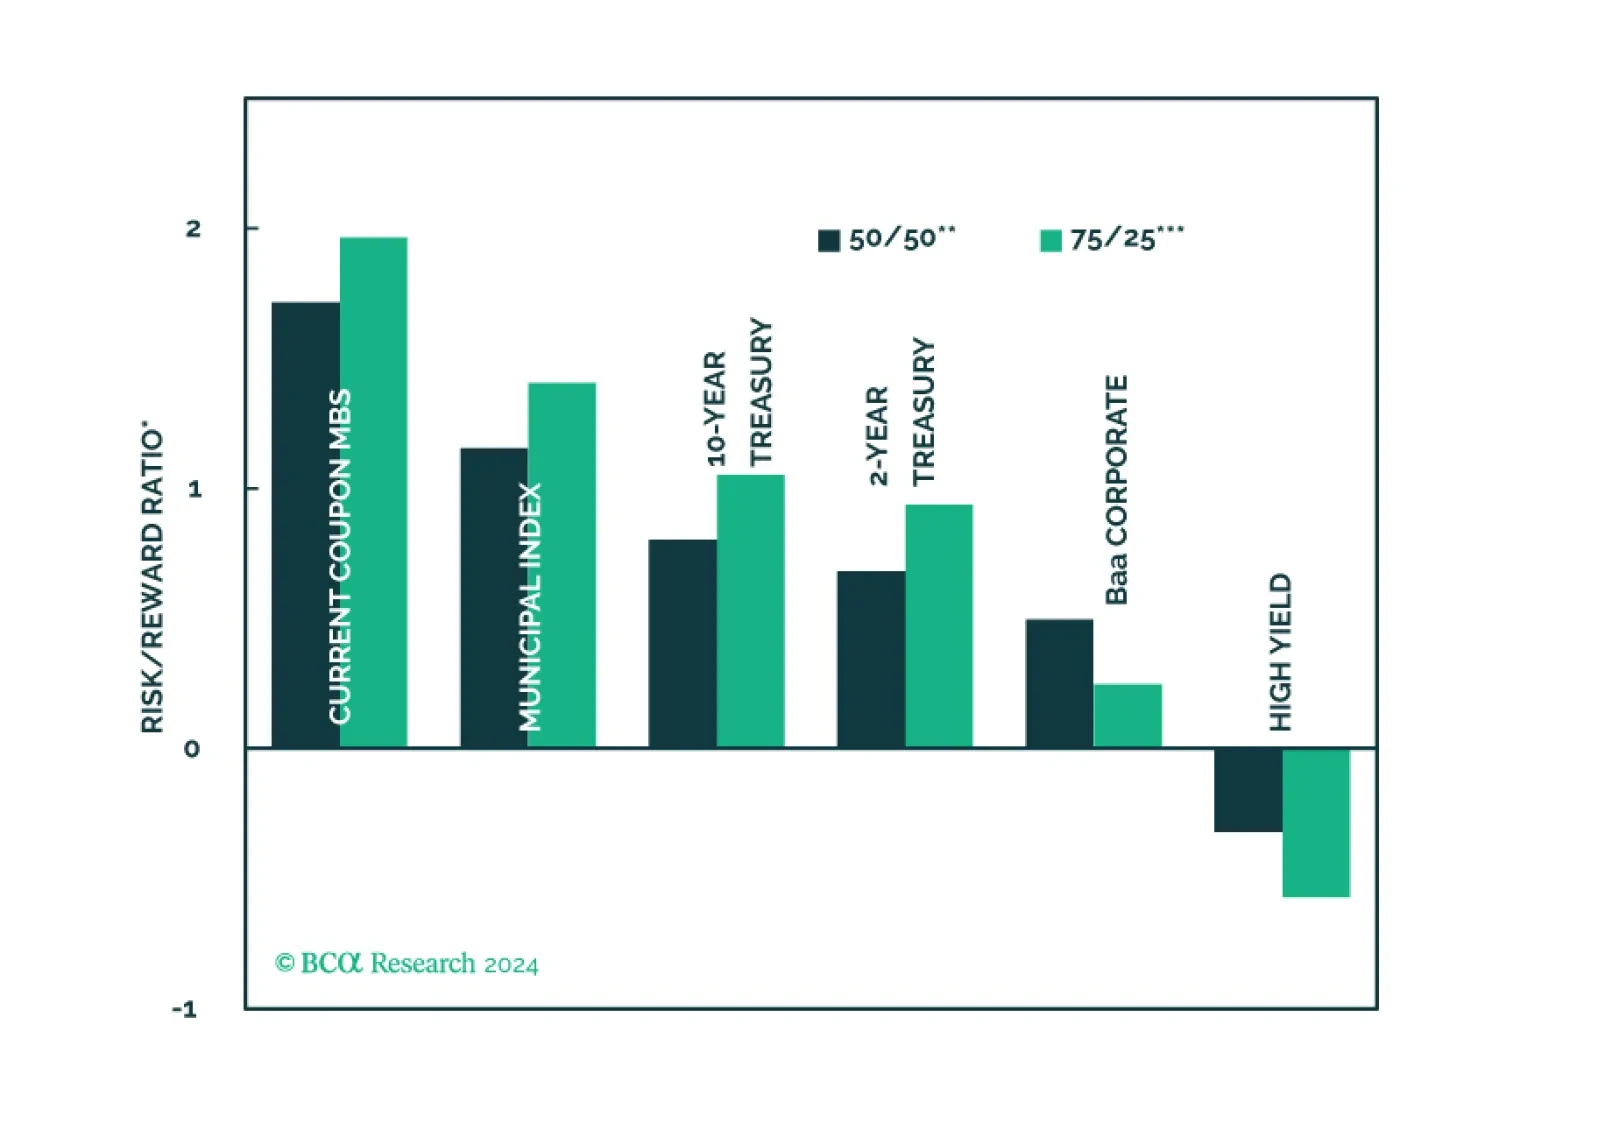
We calculate expected returns for several different US fixed income sectors with a focus on how municipal bonds stack up against the investment alternatives.
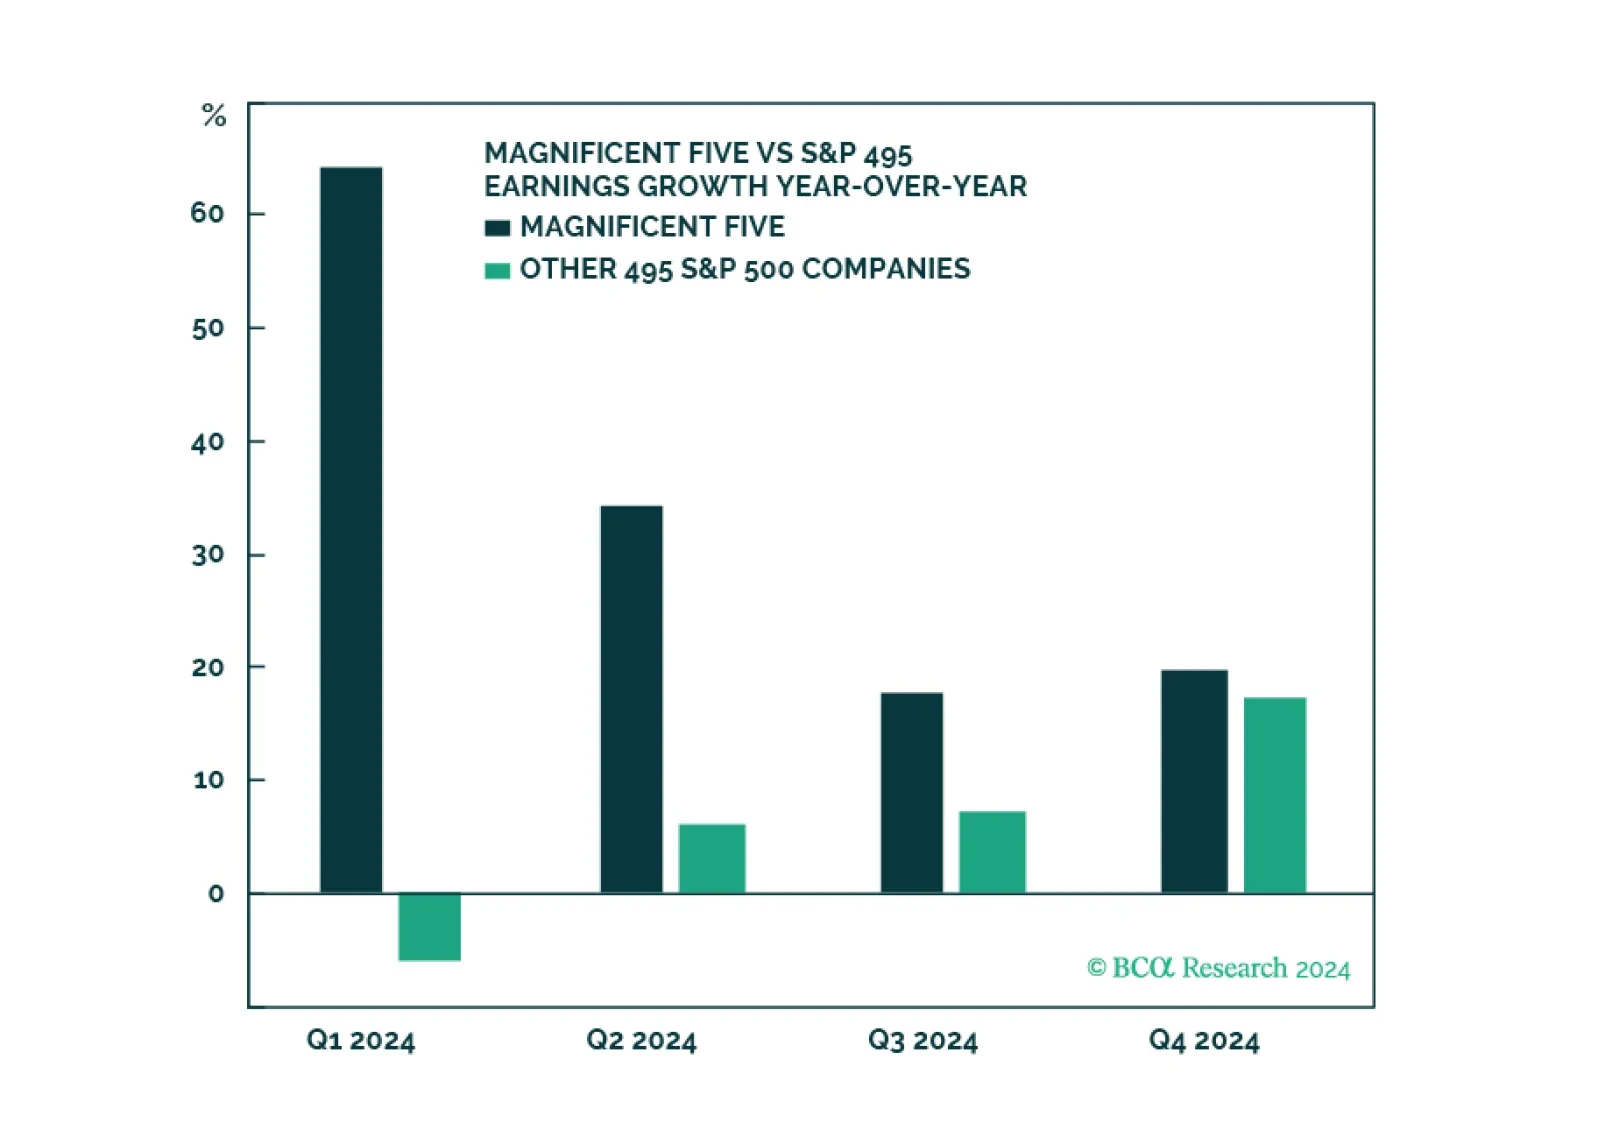
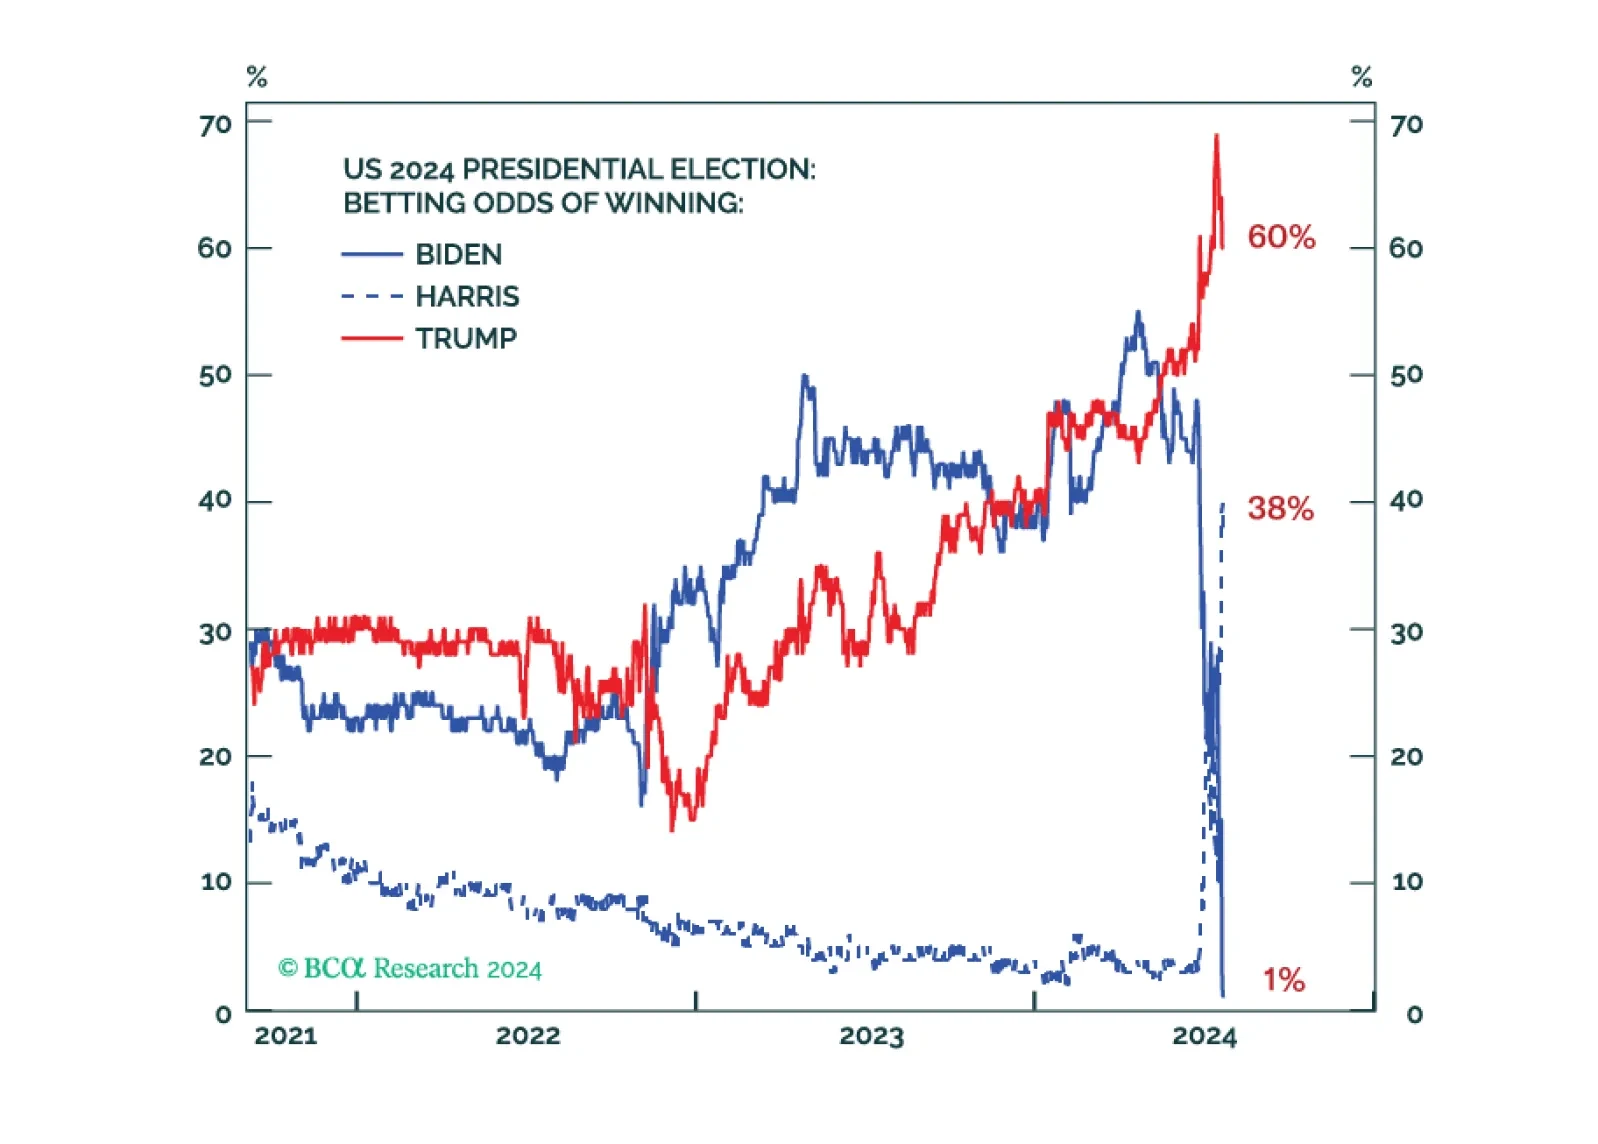
Investors should focus on growth concerns rather than the “Trump trade.” Bond yields will fall in the short run due to cyclically disinflationary economic slowdown, rather than rise in anticipation of a Republican full sweep and inflationary policies, which are likely but not yet a done deal.
President Biden has announced his withdrawal from the presidential race. The news will no doubt come to dominate the news cycle in the upcoming week of July 22, which is unfortunate as it will drown out some important developments from the preceding week.
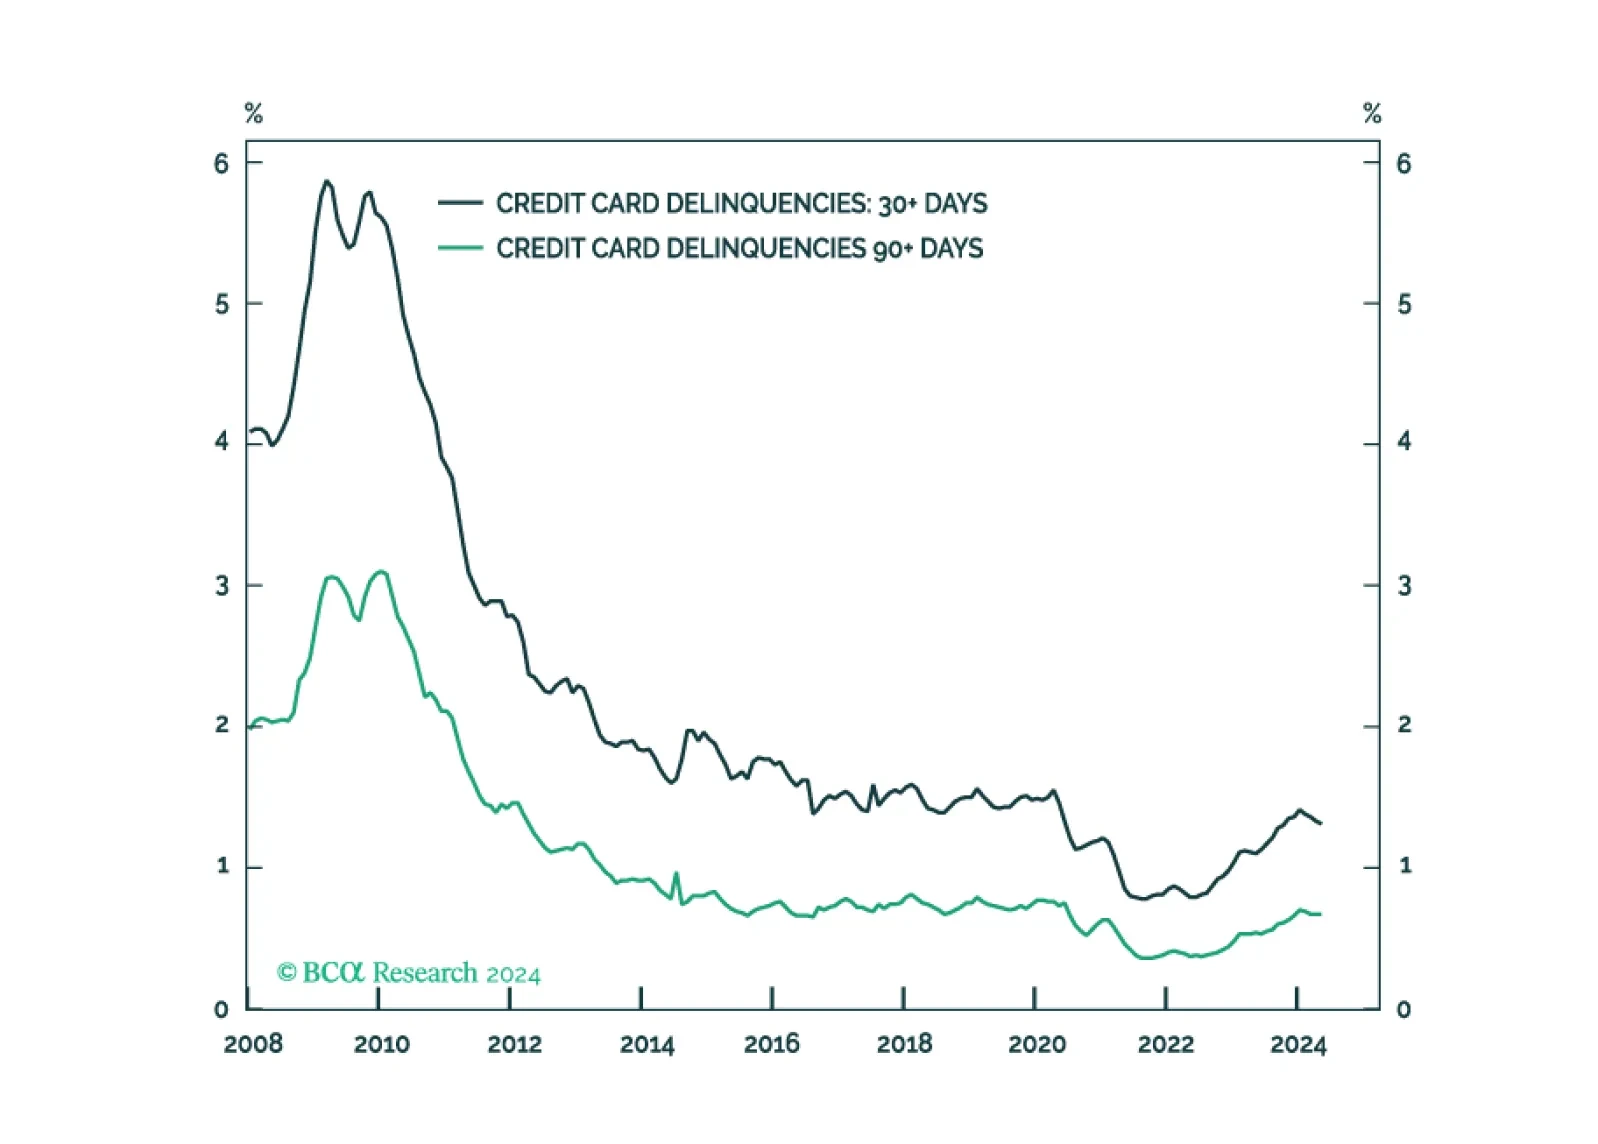
It’s status quo for the SIFI banks, as they don’t see consumer credit performance materially worsening from now-normalized levels and they are not meaningfully exposed to commercial real estate losses.
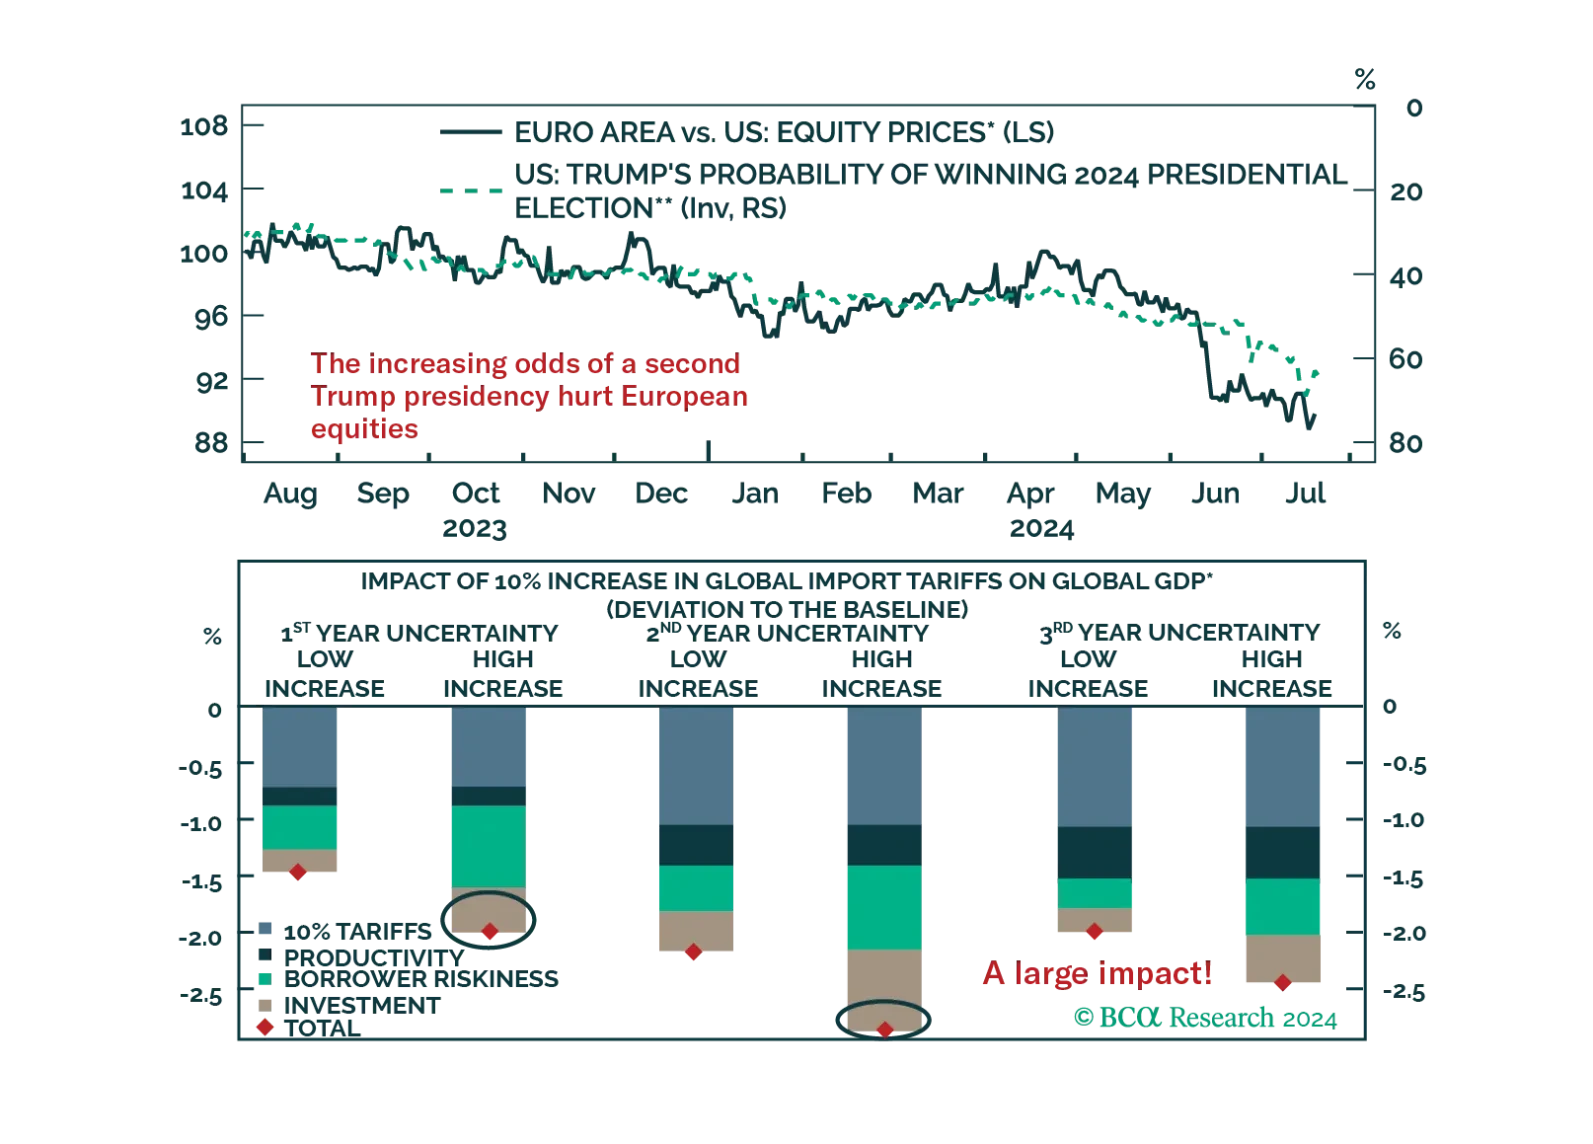
As Trump’s victory odds rise, the underperformance of European equities deepens. How negative would a global trade war be for European assets?