Latest from BCA Research
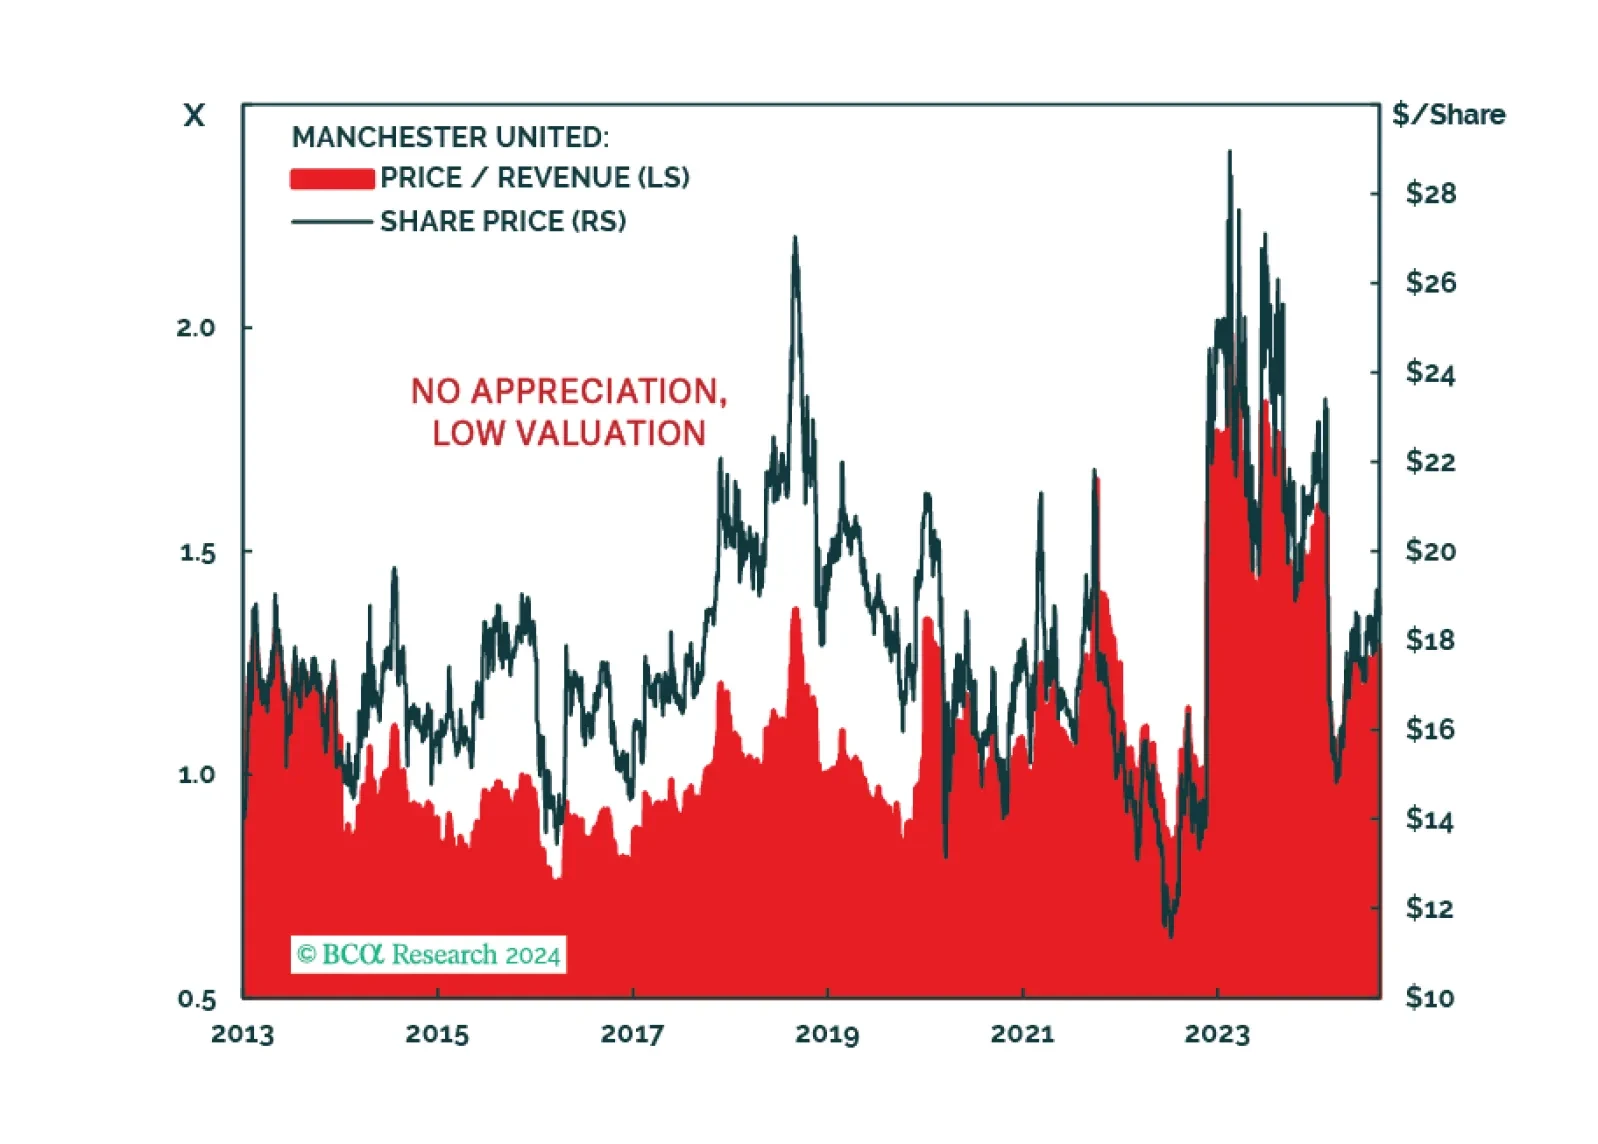
The NFL is opening the gates to the barbarians. No majority ownership is allowed...yet. However, that will not limit the upside in Growth Equity investments. Investors should cheer, so should fans.
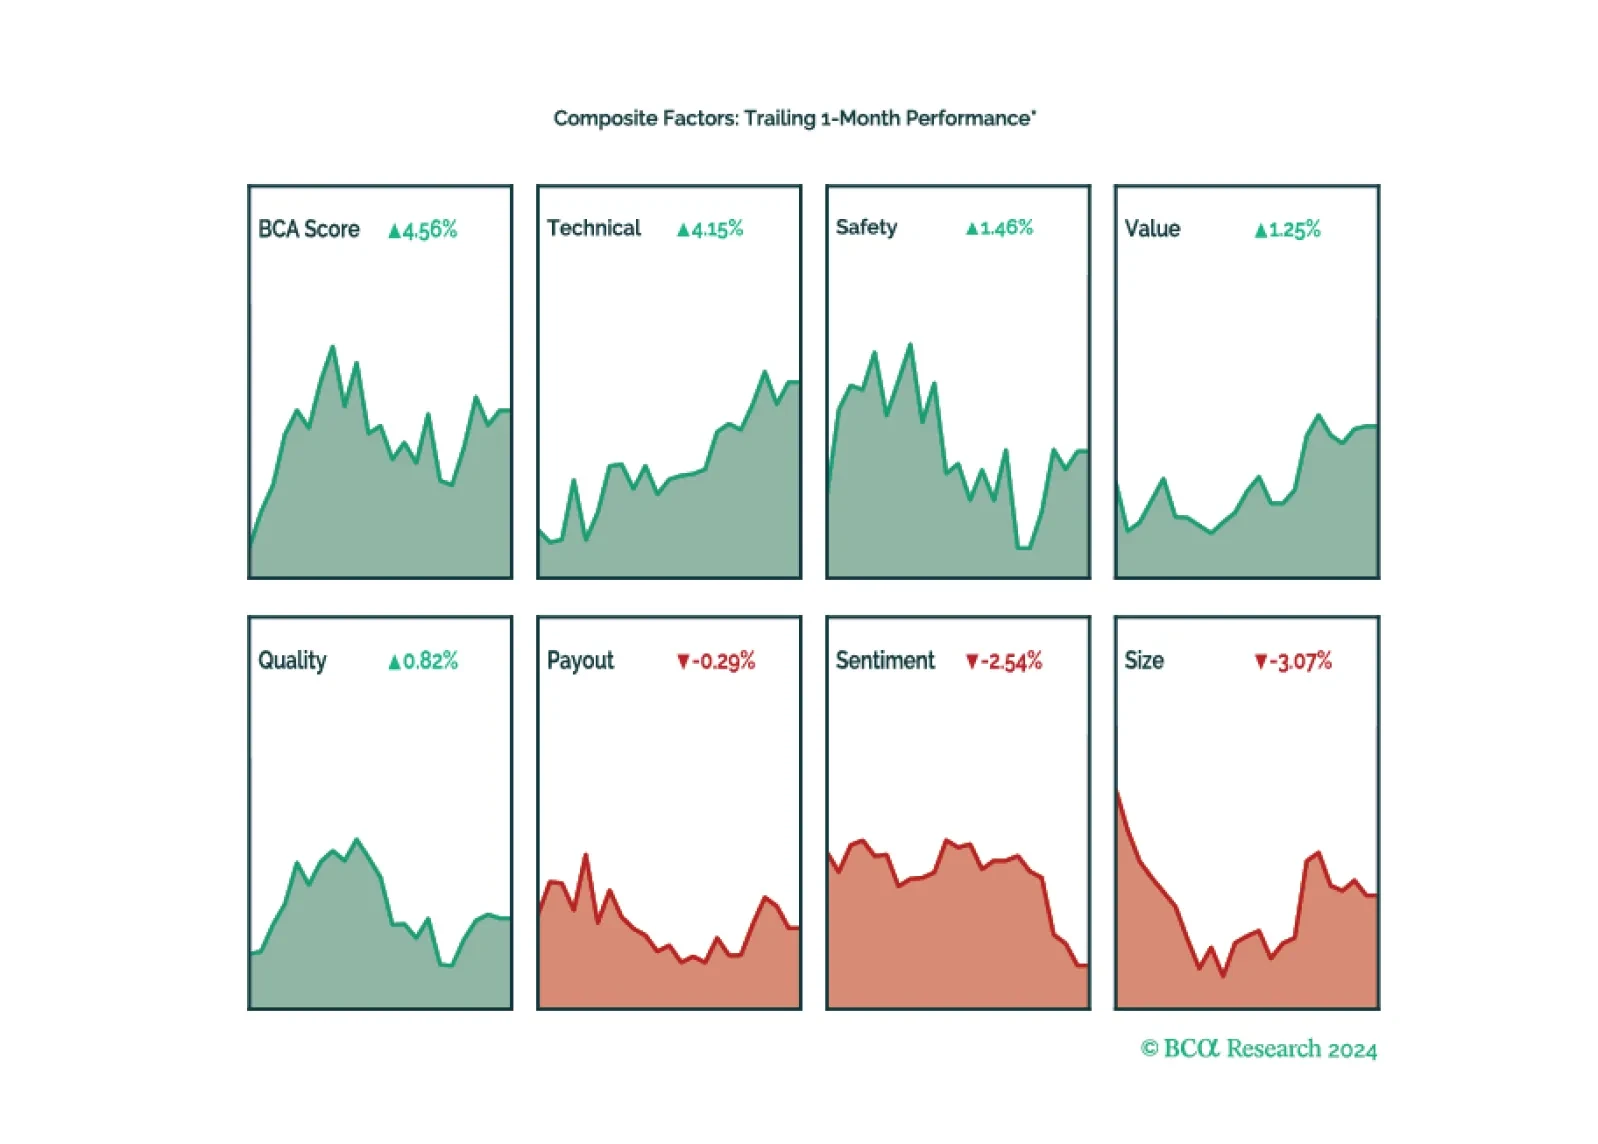
Technicals and Safety lead the way in August. USHQ outperformed its benchmark, despite early month market sell-off.
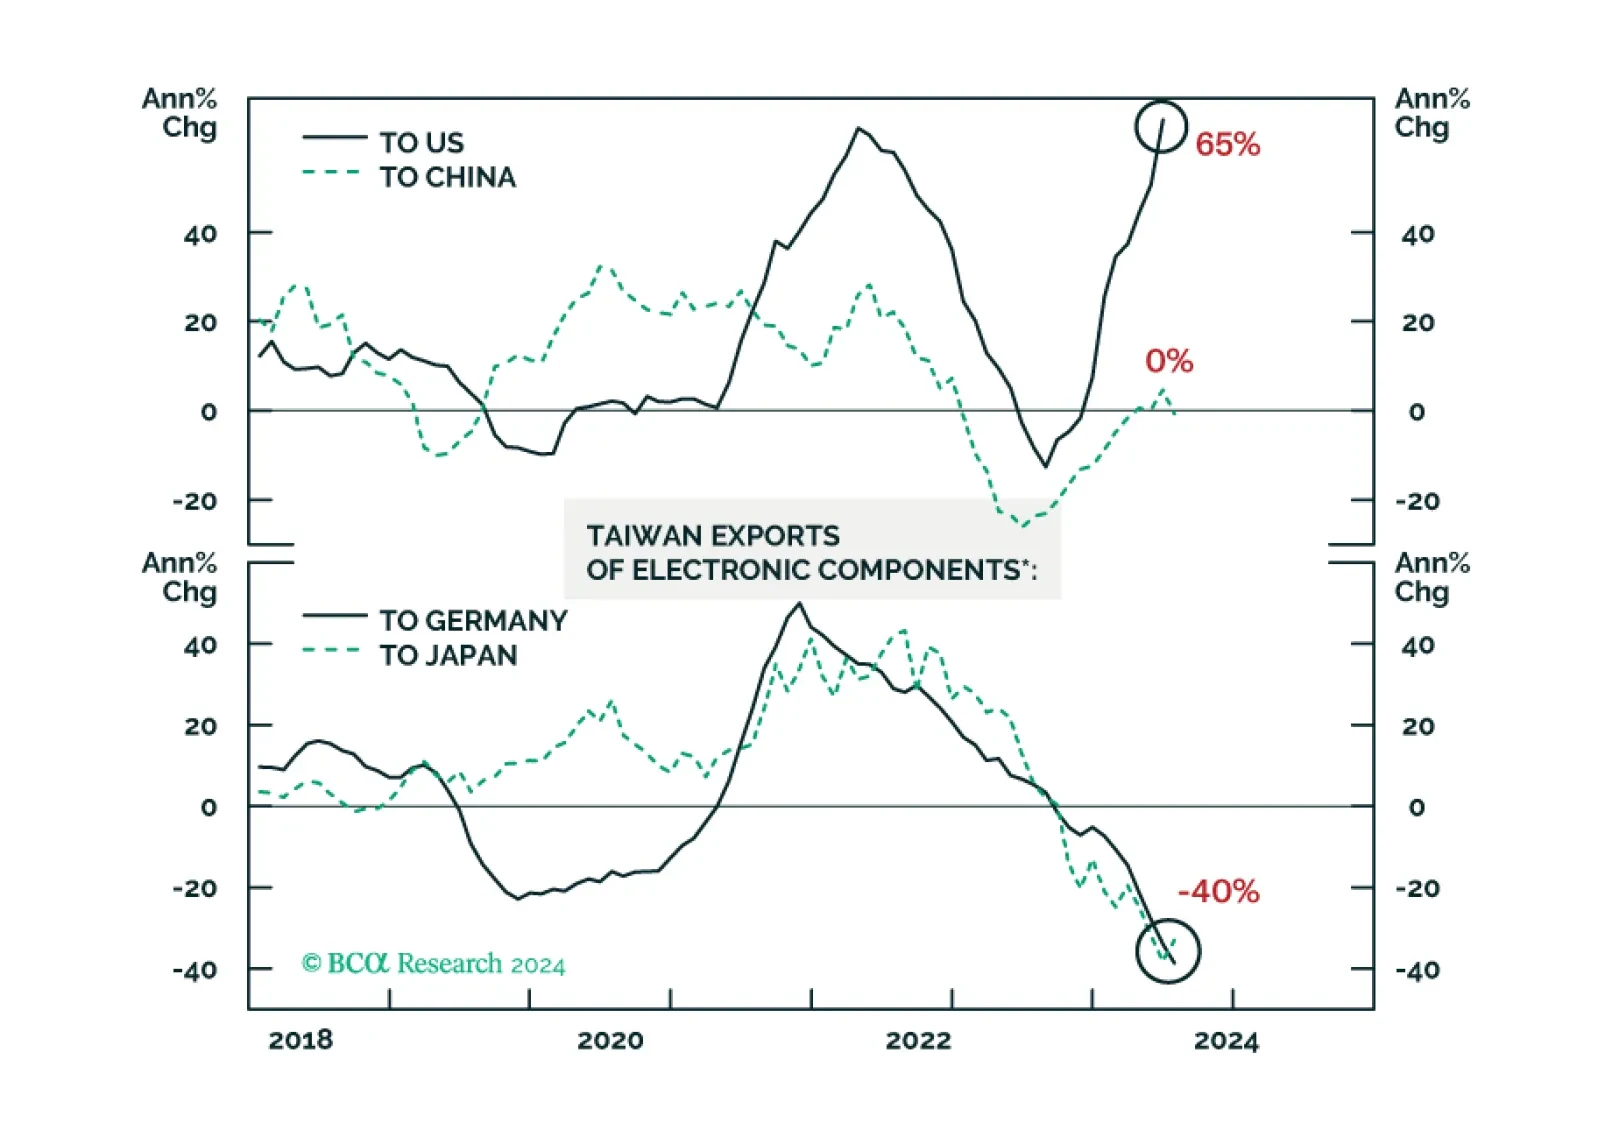
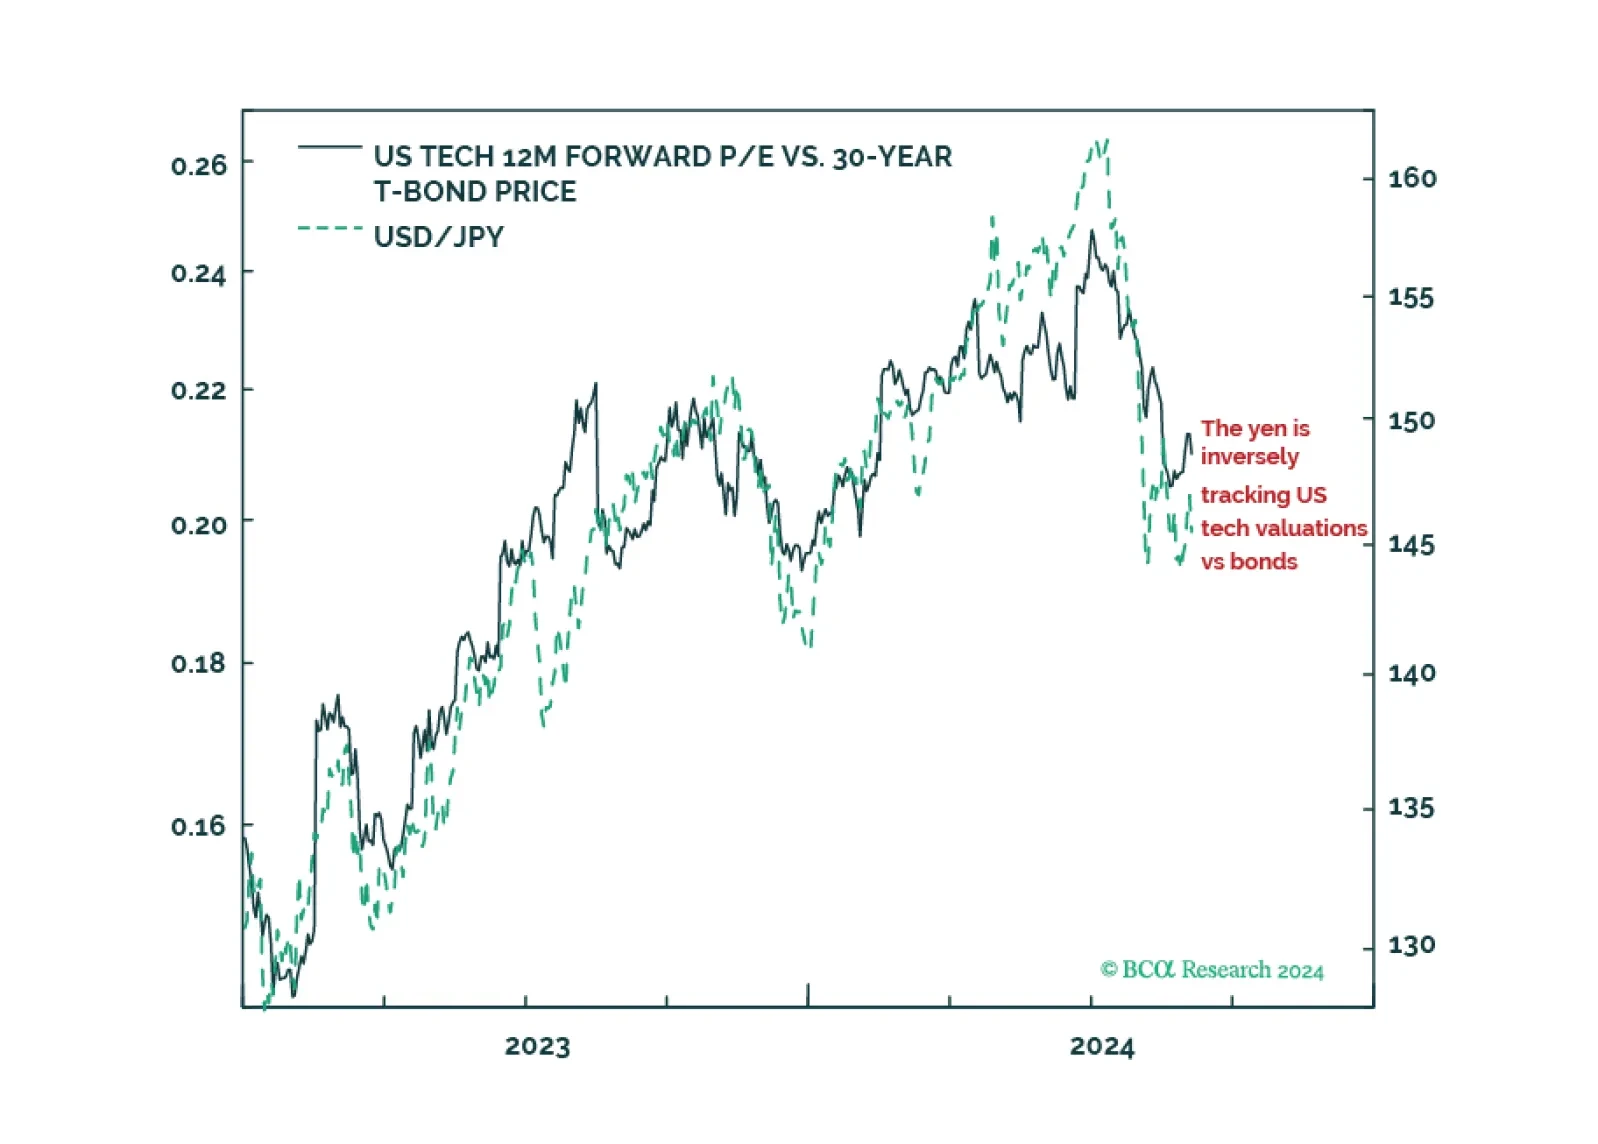
The 15 percent slump in the relative valuation of US tech stocks versus bonds is a bubble starting to burst. Yet the adjustment has been relatively benign so far because a large part has come from the bond price going up. Unfortunately, the adjustment has much further to run and could ultimately turn ugly. The easiest way to play the AI bubble bursting is to go structurally overweight the yen.
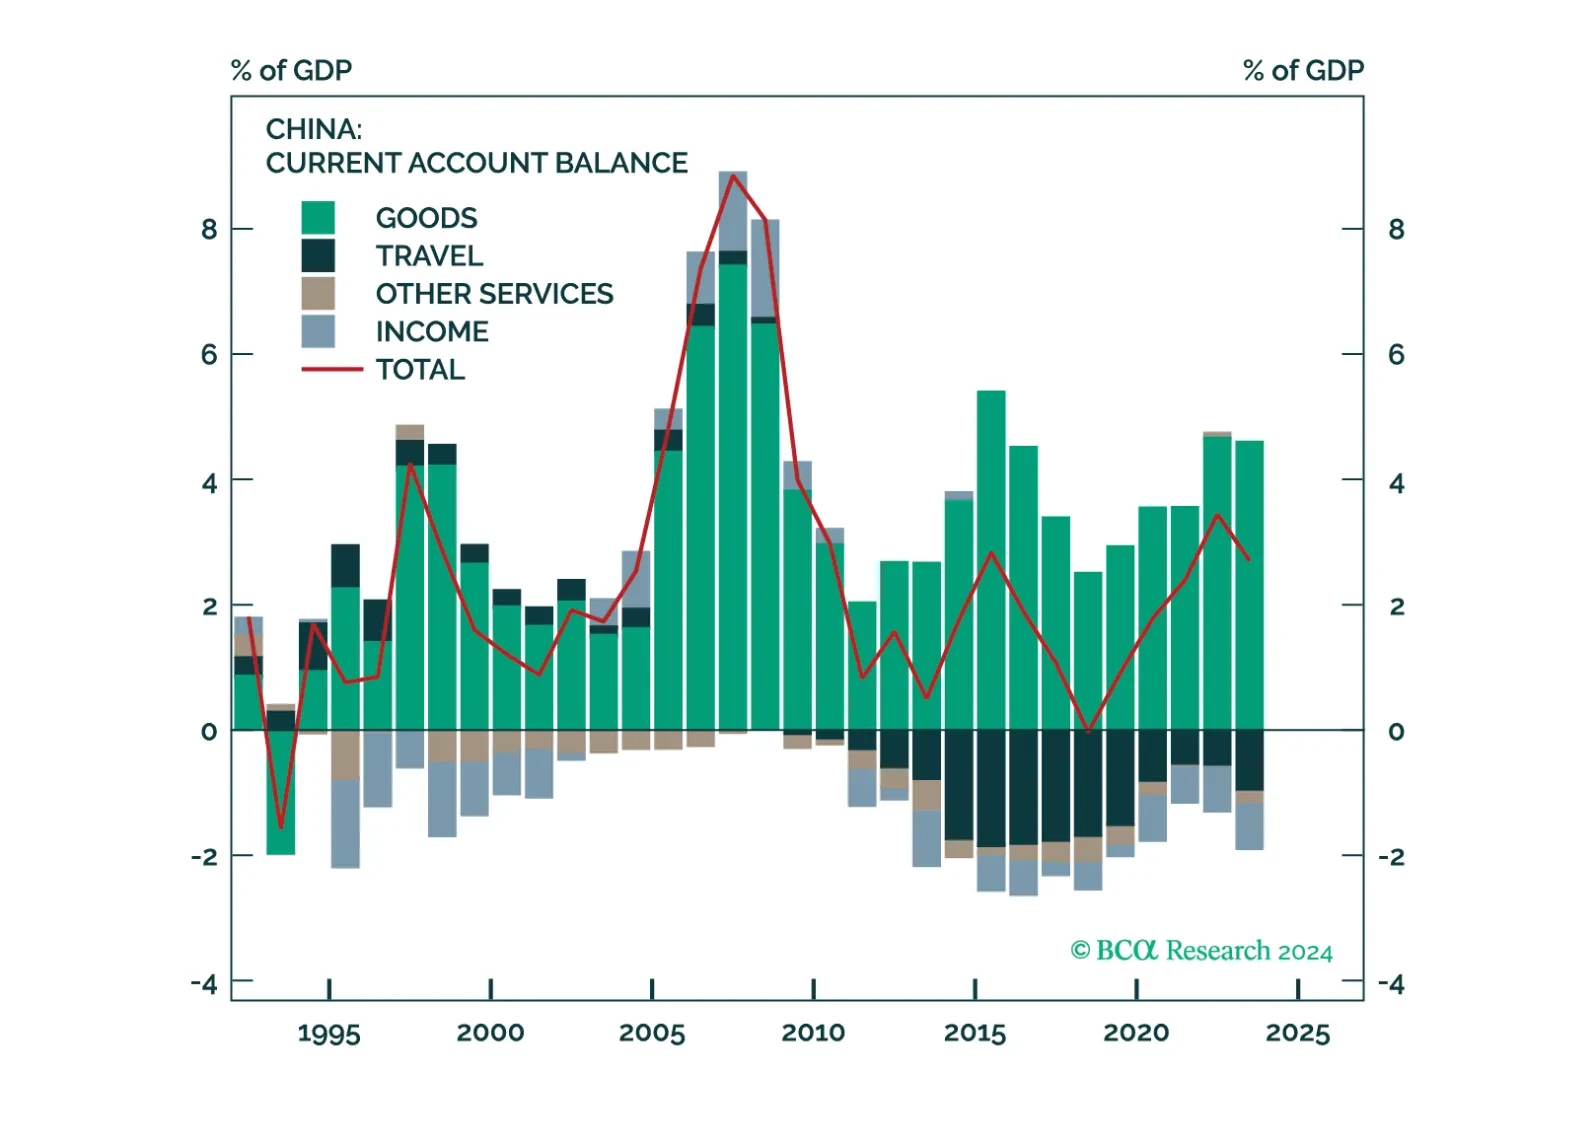
Waging trade wars in a global multipolar order is folly. The US trade war against China has been an utter disaster for Washington, DC. None of its goals have been accomplished, whereas Beijing is making significant inroads into new markets. Somewhat heretically, we suggest that American policymakers will eventually realize this reality and pivot towards a surprising new strategy.
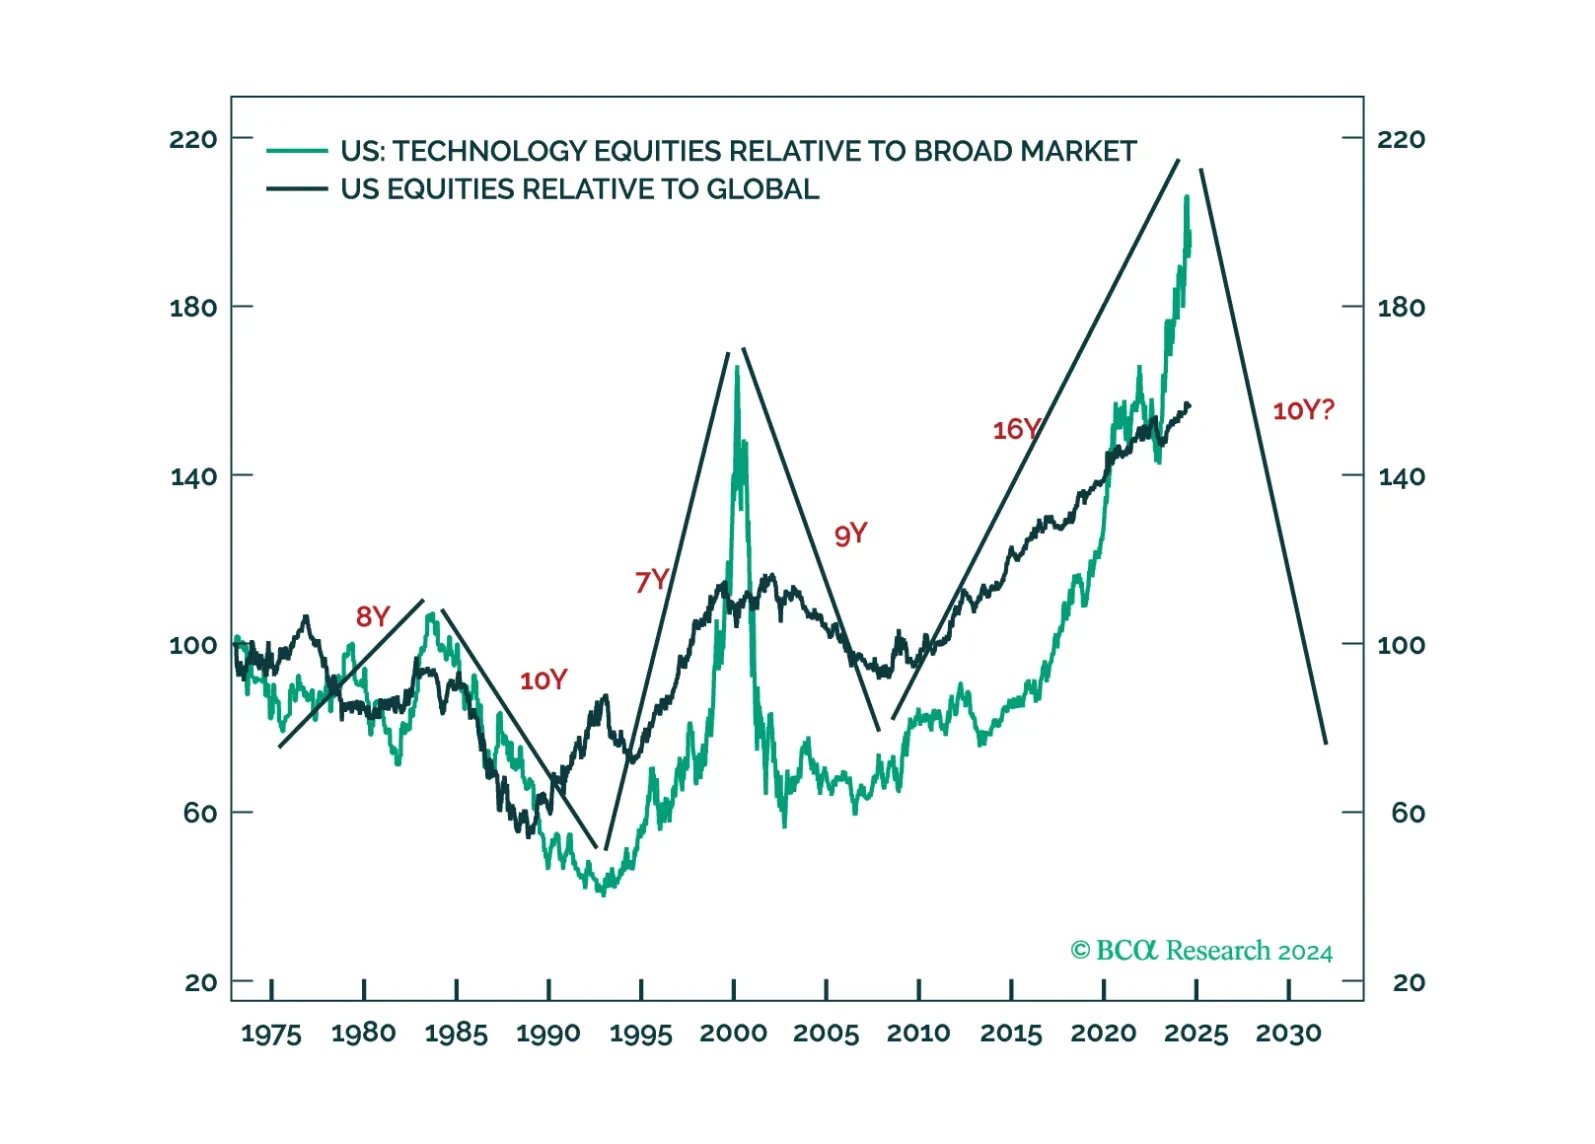
We remain concerned that the risk-reward for equities is limited above our end-of-the-year target of 5,500 for the S&P 500. There is seasonality to consider, as well as positioning and sentiment. As such, we are not necessarily bearish because a recession is certain. But, rather, that the upside to the AI mania is uncertain. Long term? The real bubble may be in America, broadly speaking. As such, more downside to USD could be ahead.
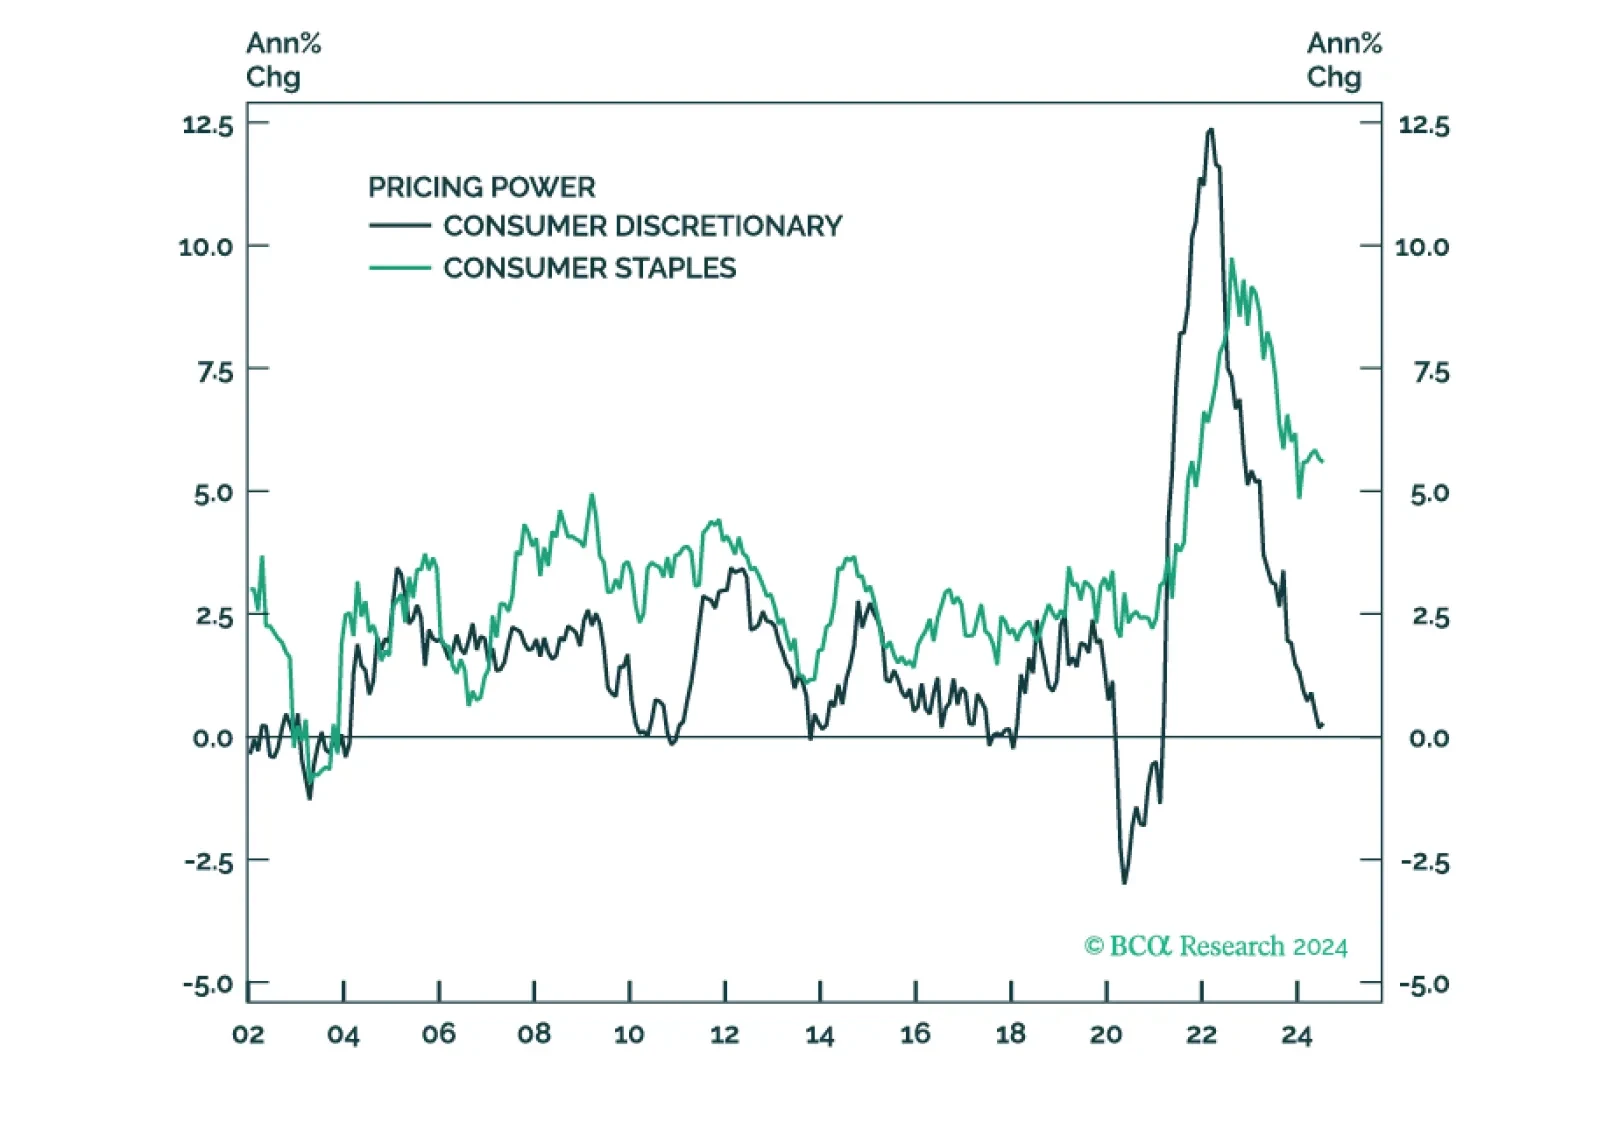
Q2 Earnings season has been strong, with sales and earnings growth accelerating and broadening across sectors. However, companies' results and commentaries are stoking some concerns. GAI monetization will take longer than most investors expect. Companies are also reporting that lower- and middle-income US consumers are strapped. We recommend defensive positioning, as solid earnings growth is insufficient to rule out a recession later this year.
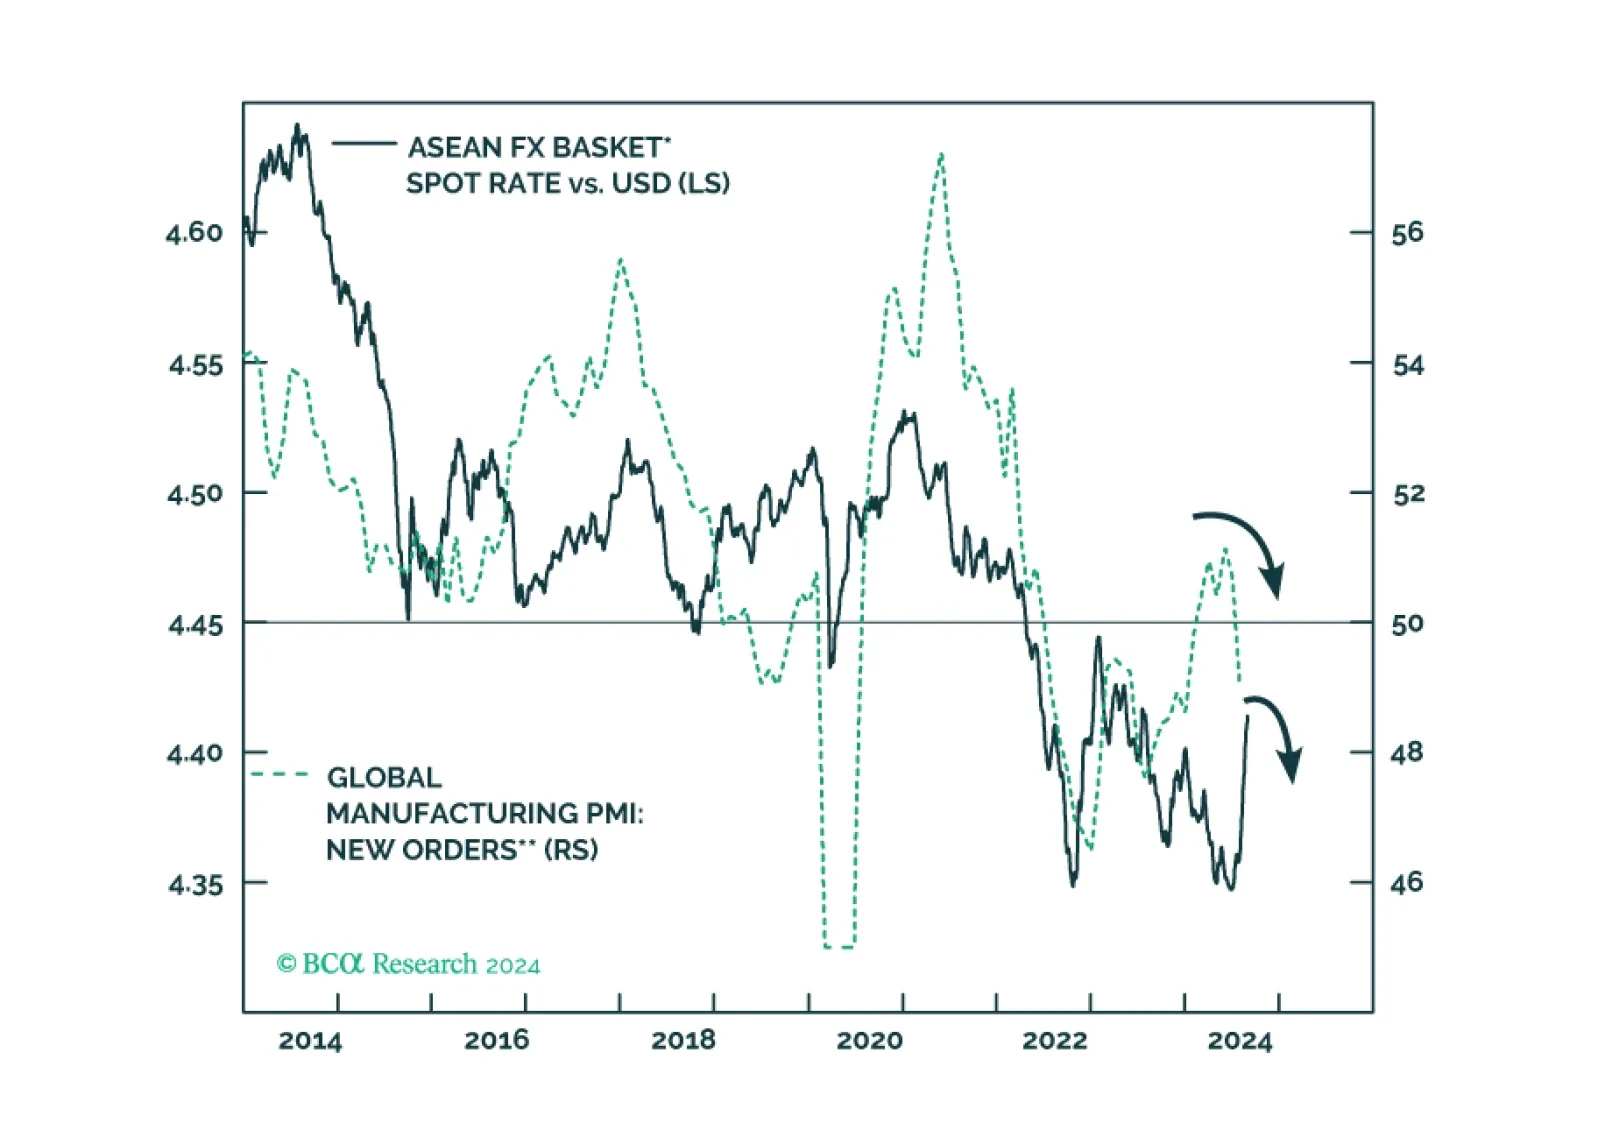
The ongoing rally in ASEAN currencies will fizzle sooner rather than later as they are not supported by fundamentals. The ringgit and the baht, however, will fare better than the peso and the rupiah during the coming global risk-off period. This report explains why.
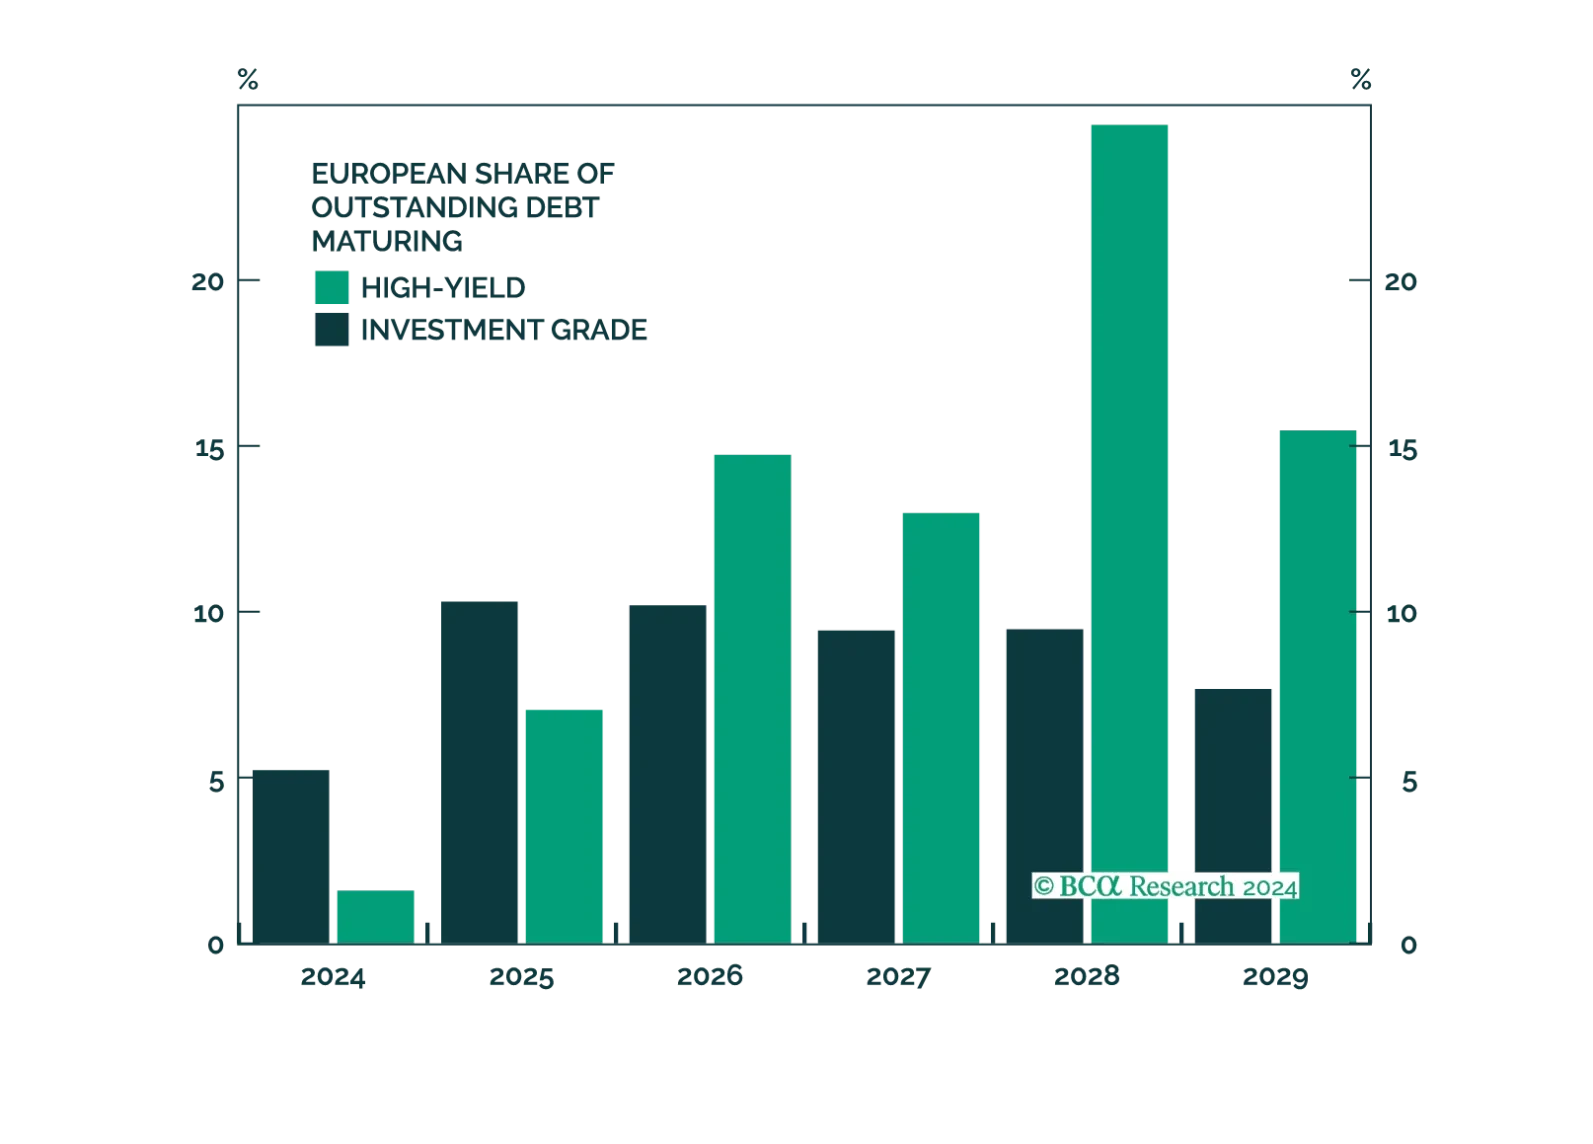
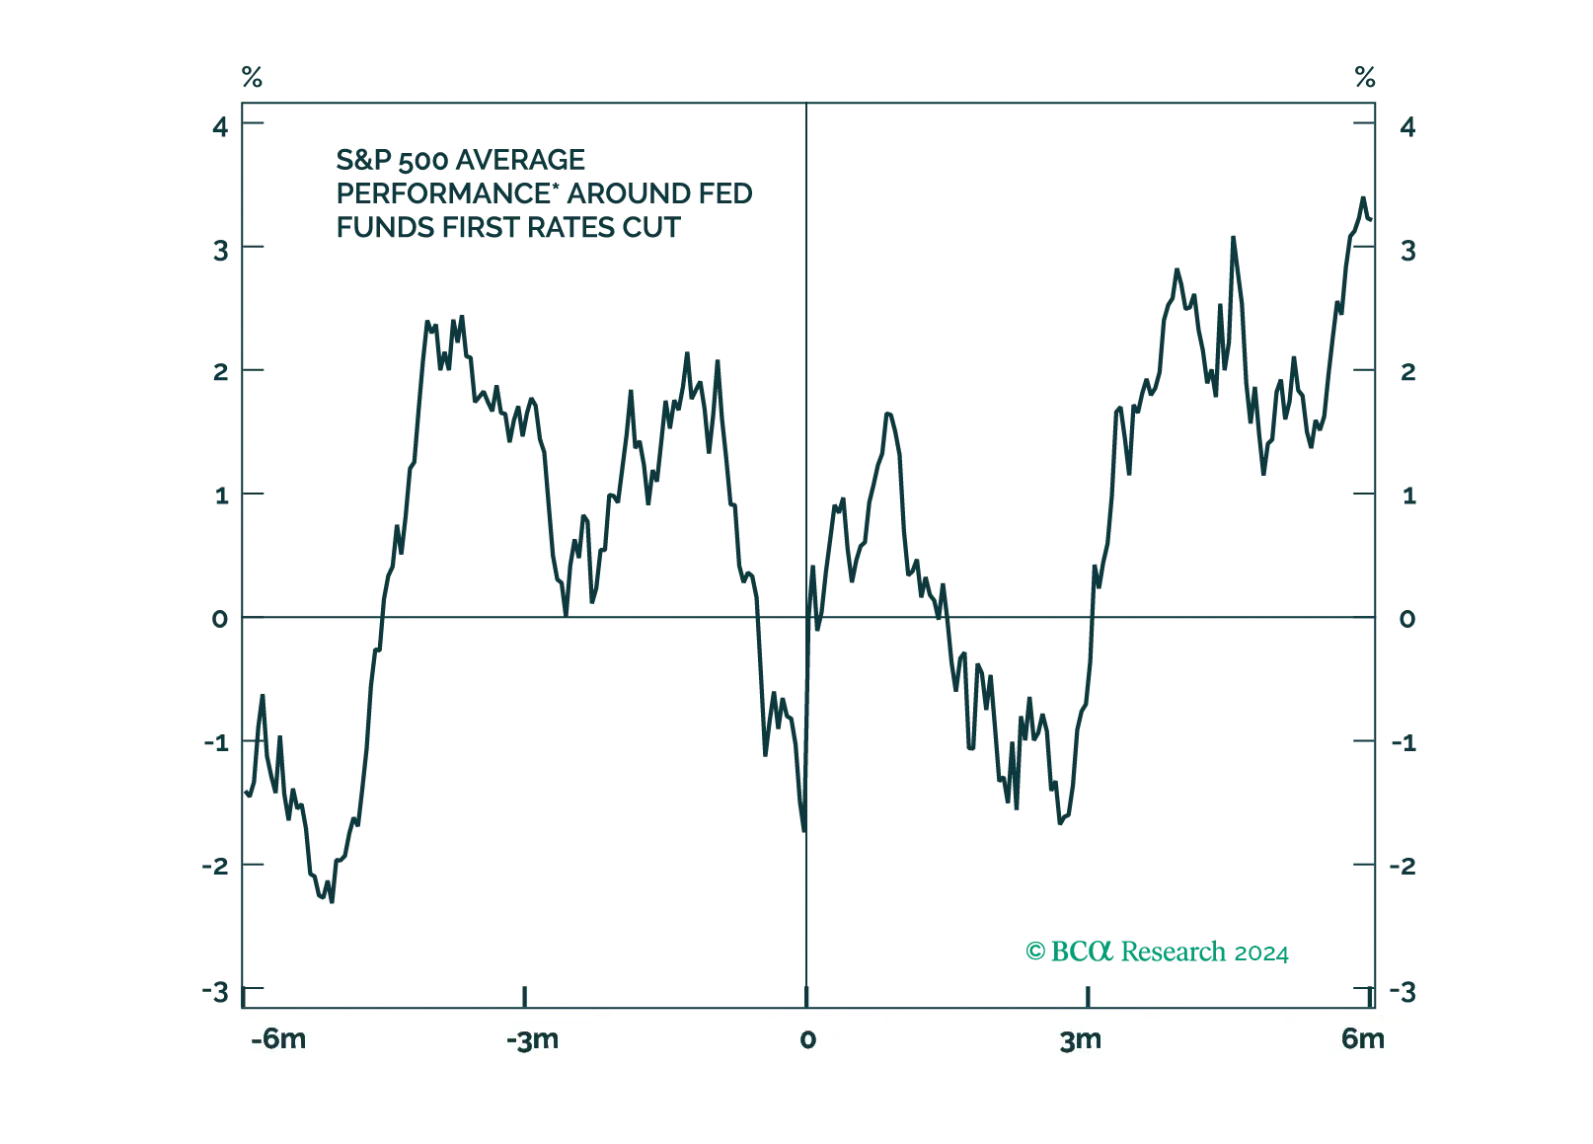
Even after the Fed cuts rates, policy will remain restrictive for some time. Moreover, in history, stocks have tended to fall around the first rate cut. We remain cautious on the outlook for the economy and risk assets.