Latest from BCA Research
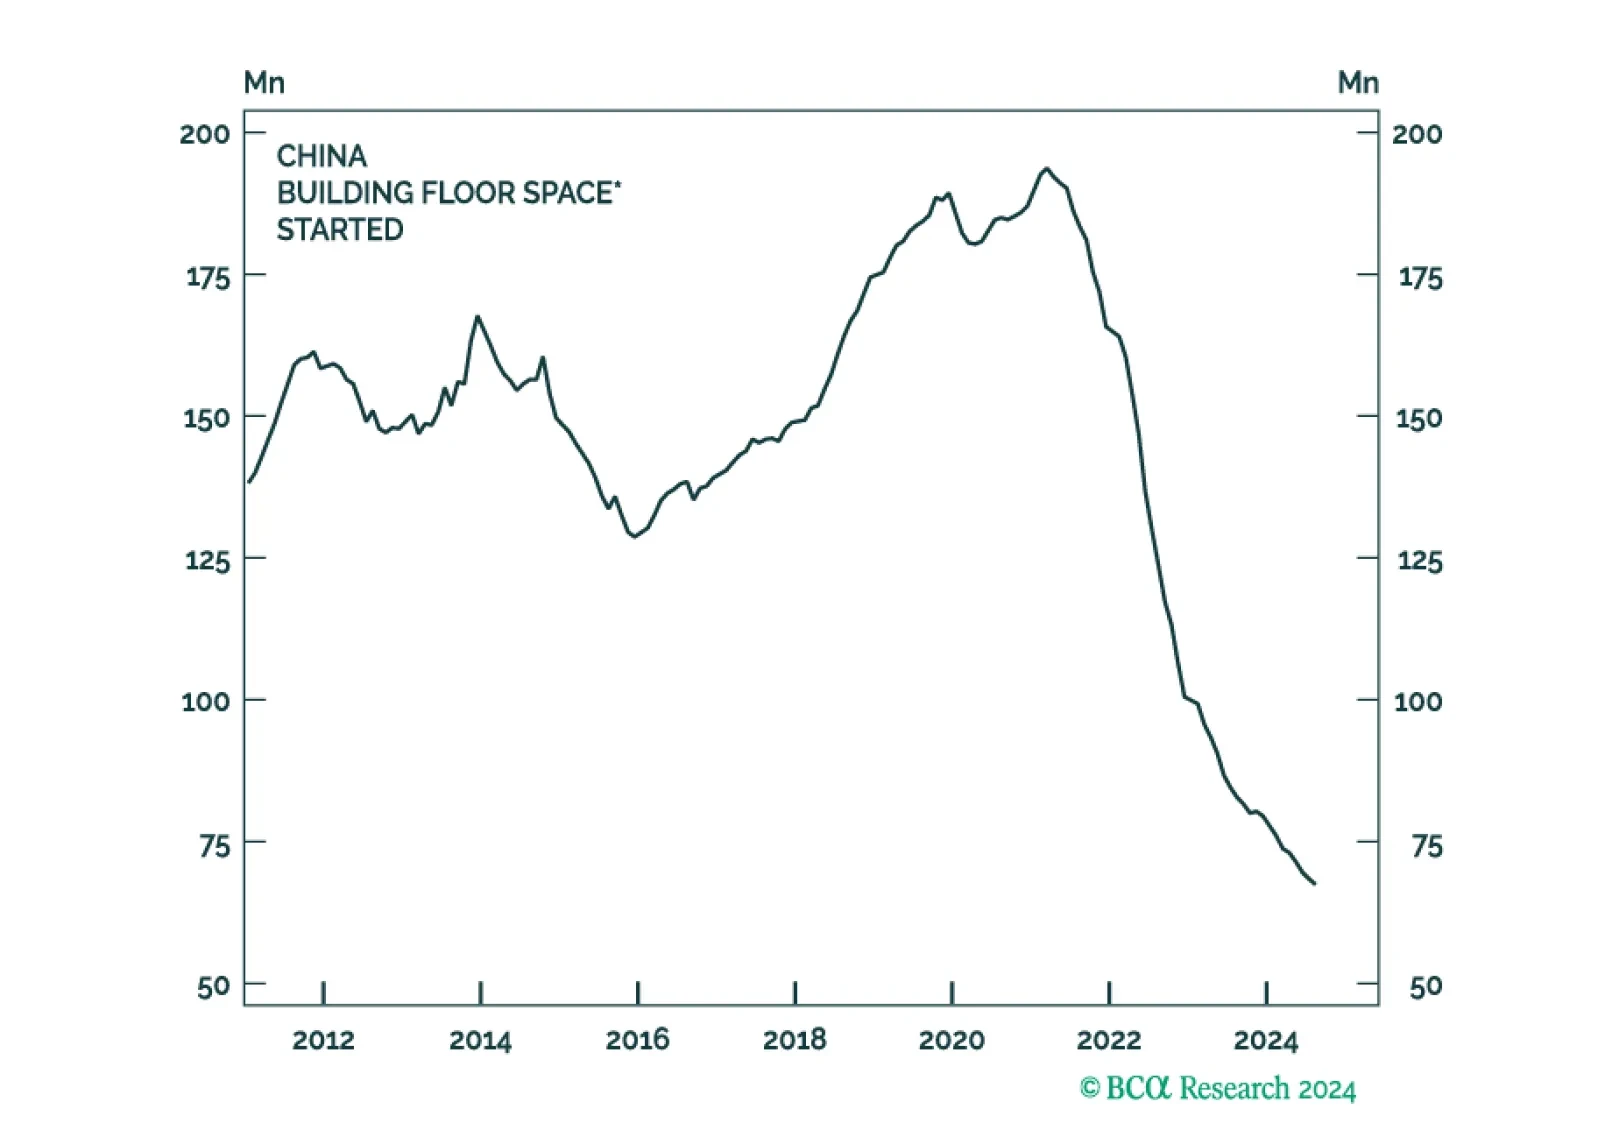
The Chinese government had no choice but to act this week. Housing starts are down 65% from their peak.
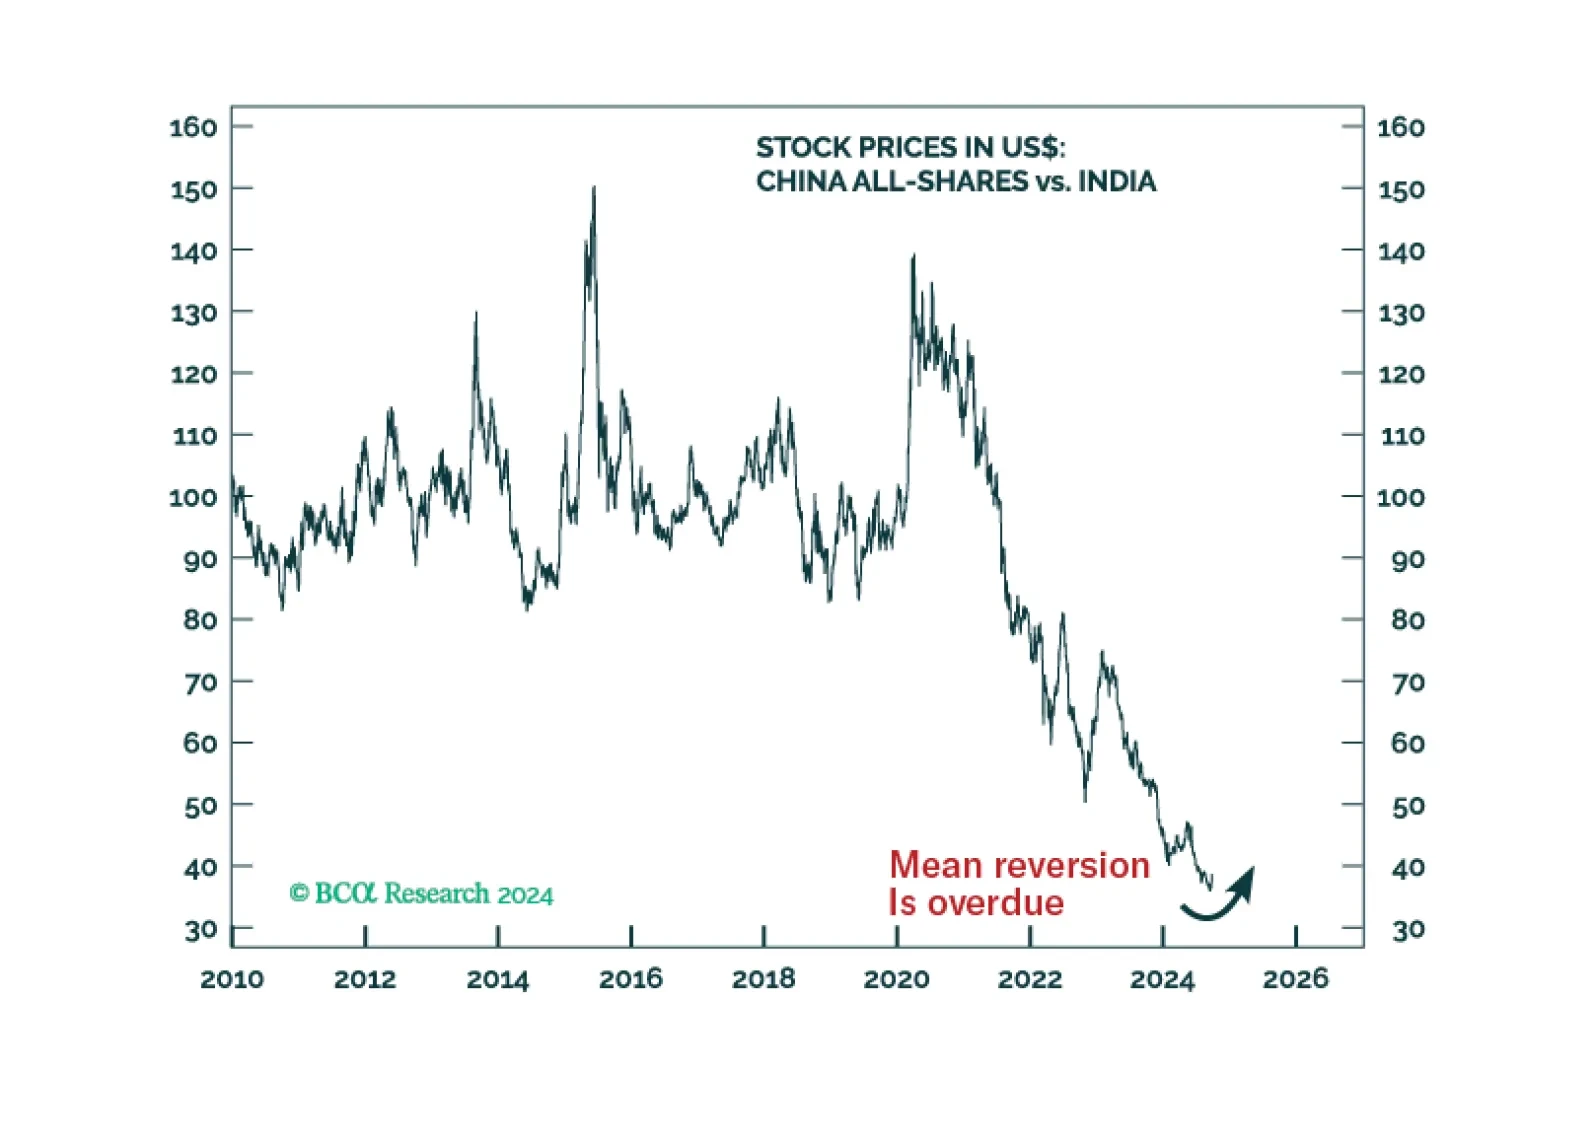
The adrenaline from the recent policy stimulus might be sufficient to produce a window of outperformance for Chinese equities and China-plays in financial markets. However, this adrenaline will not extend to China's real economy. Net-net, we are upgrading the allocation to EM in a global equity portfolio from underweight to neutral.
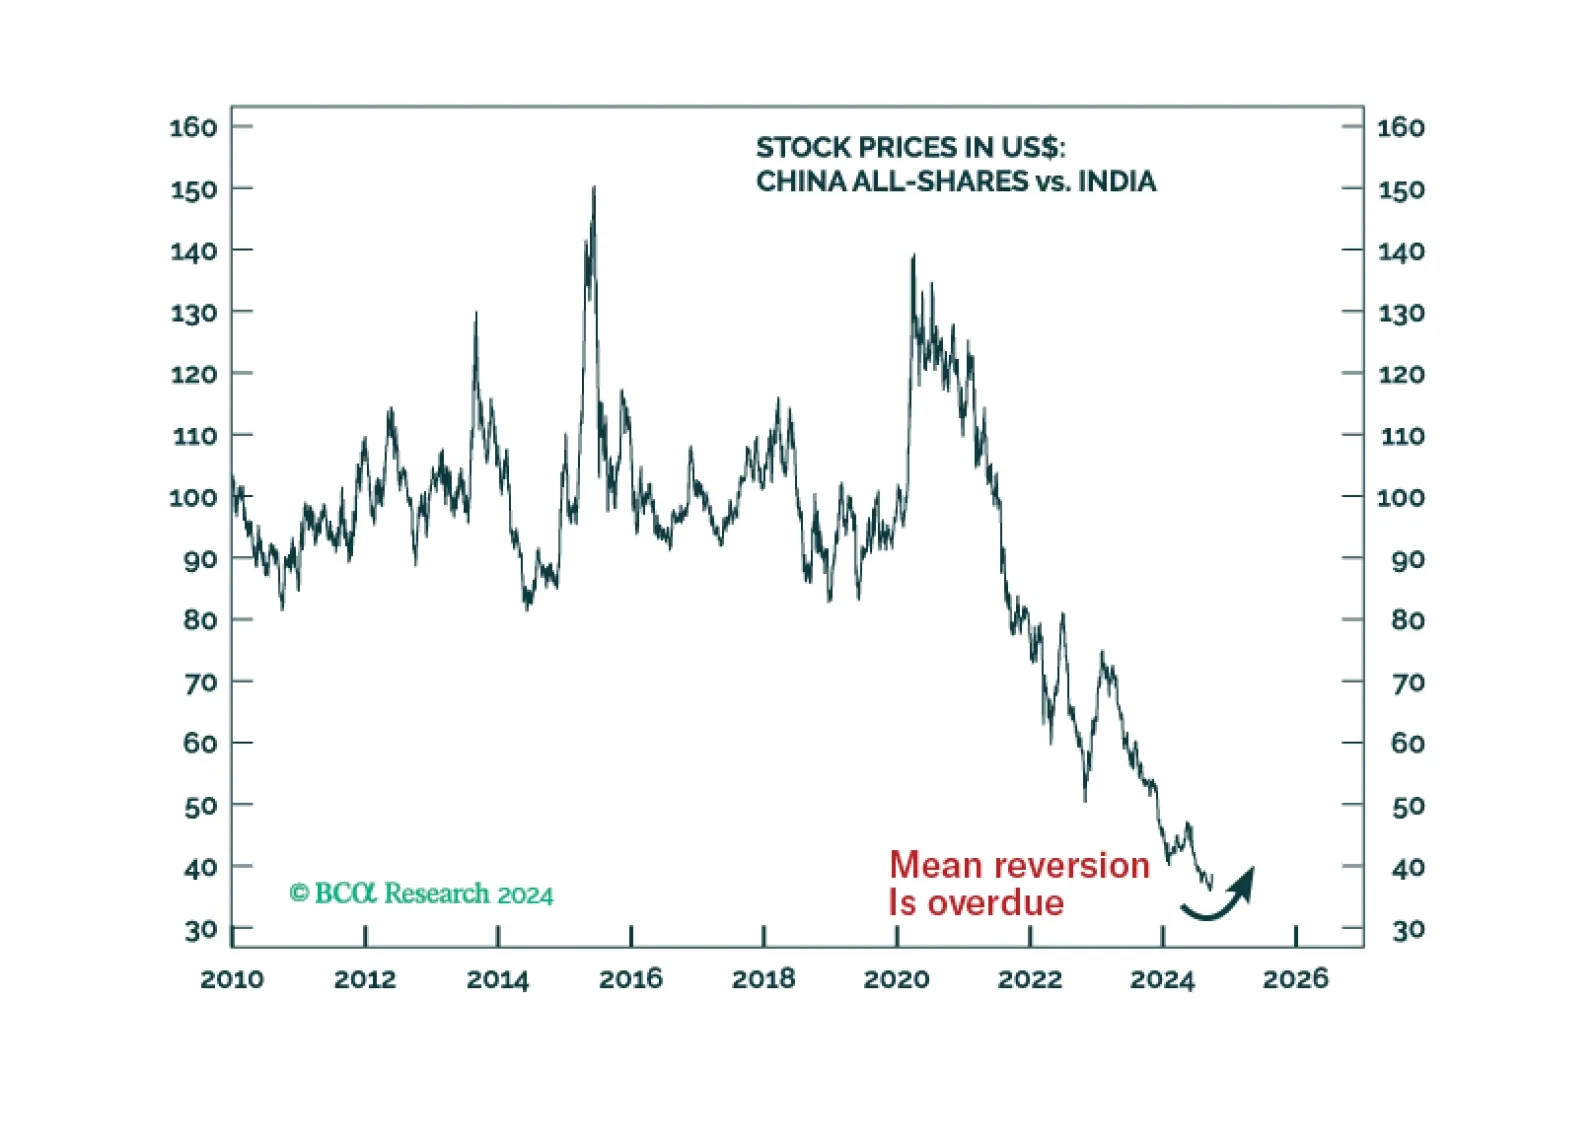
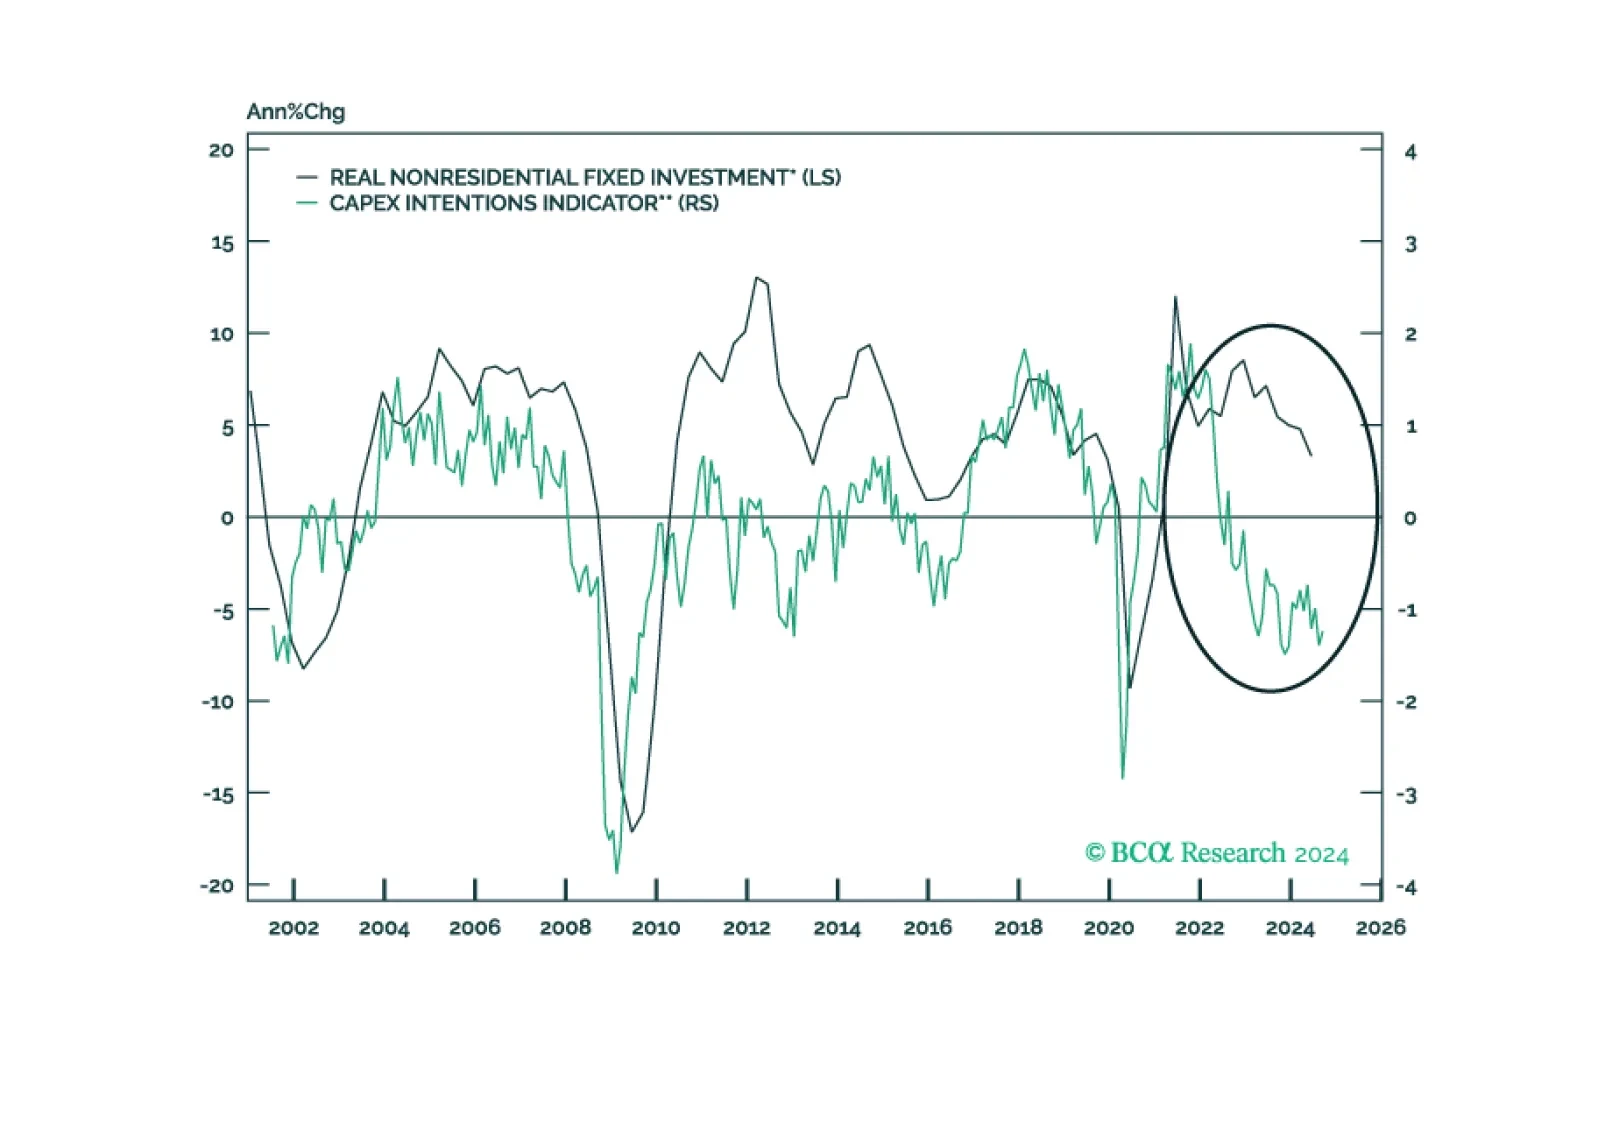
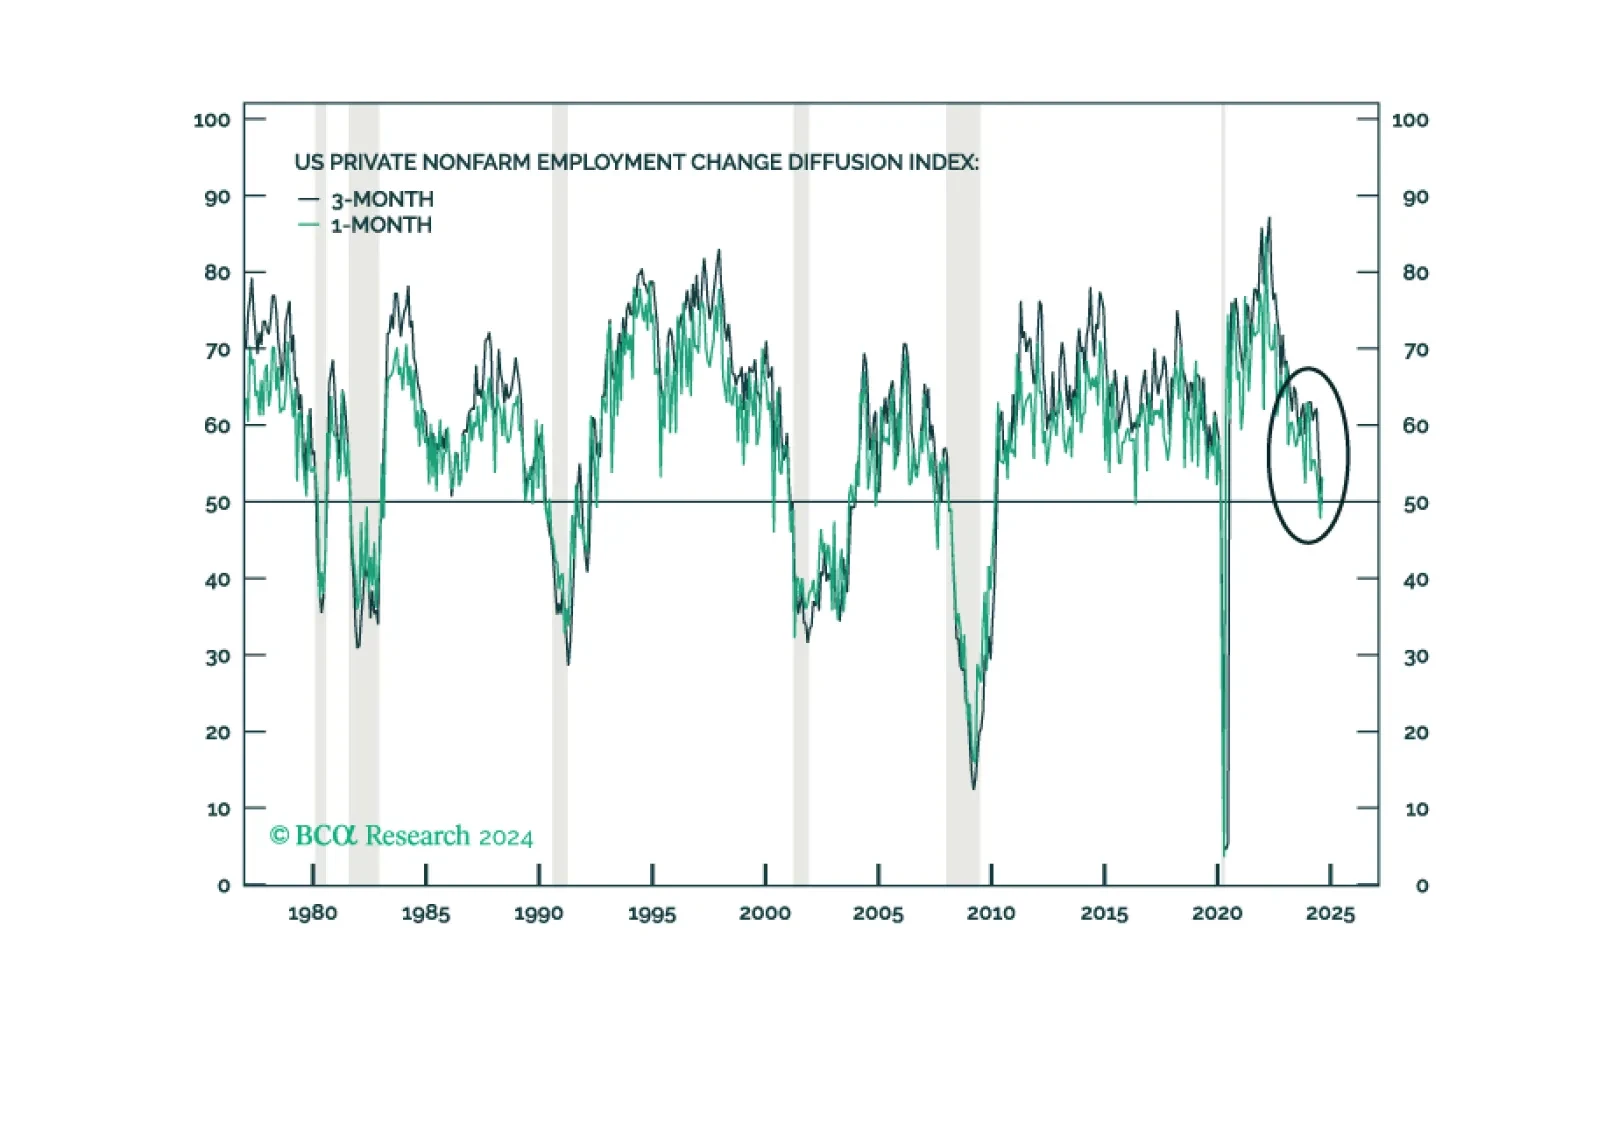
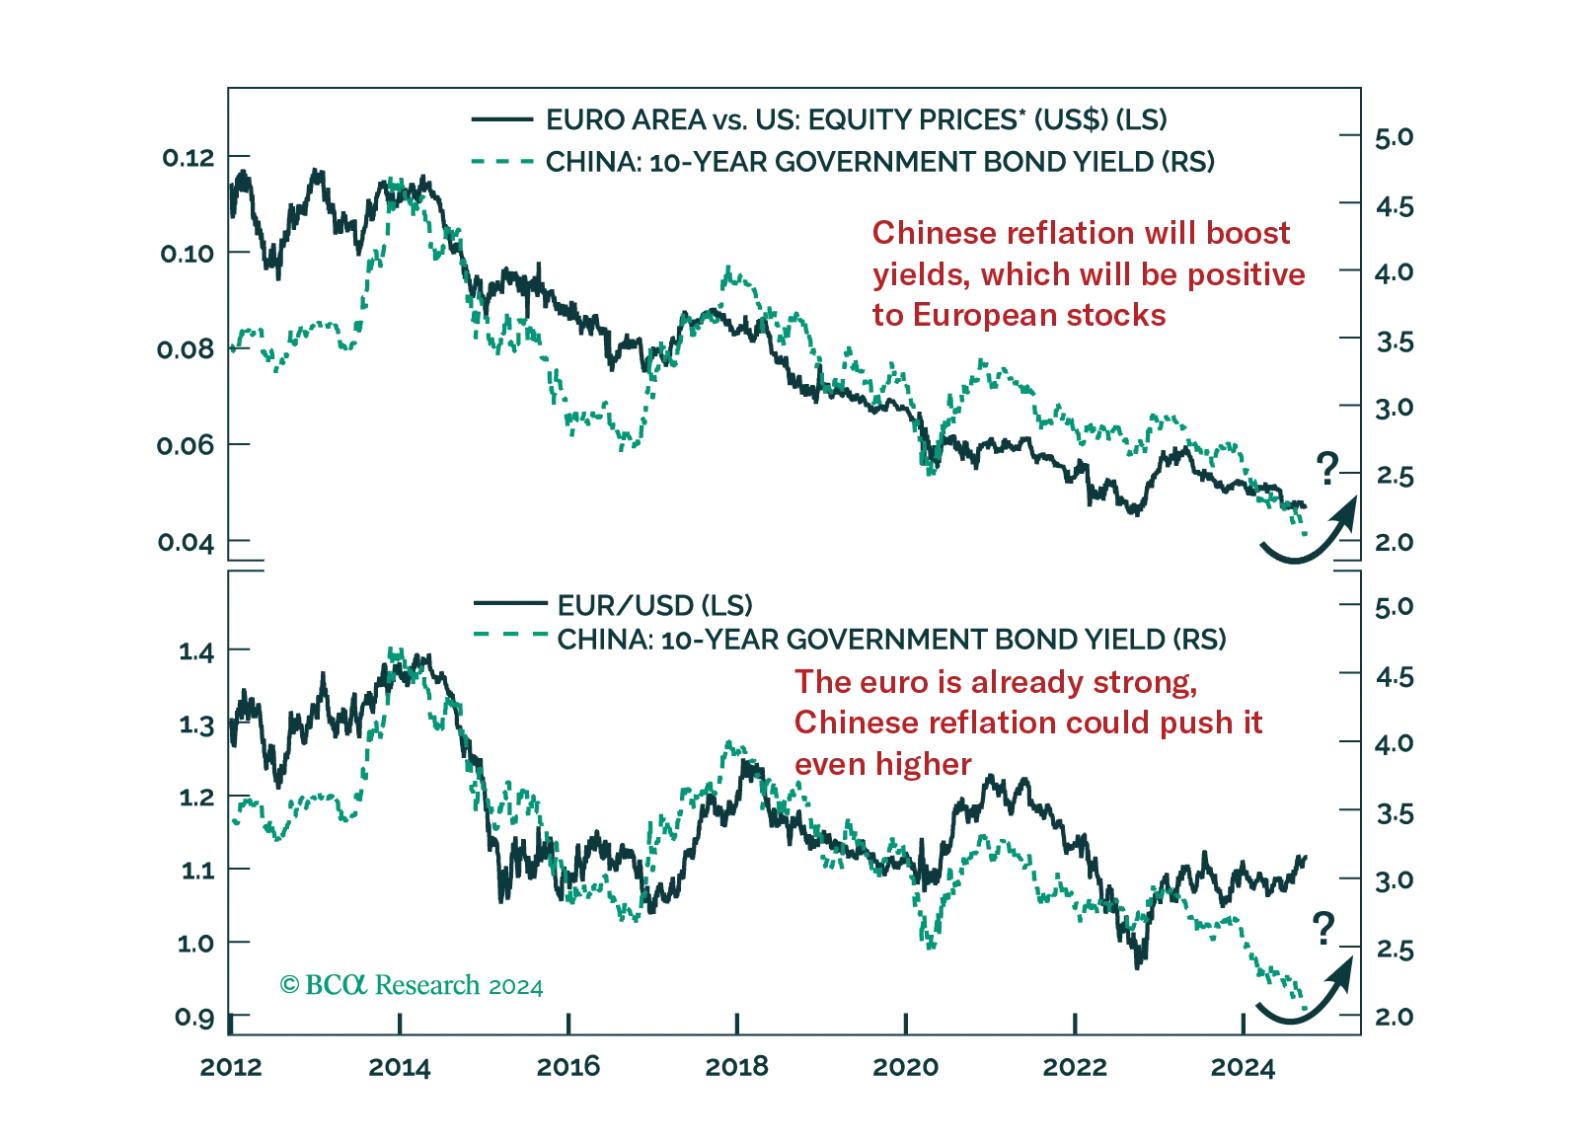
China’s Politburo announcement is likely to lead to a repricing of China’s growth in the near-term. Read how investors can hedge against this potent threat to our defensive investment stance.
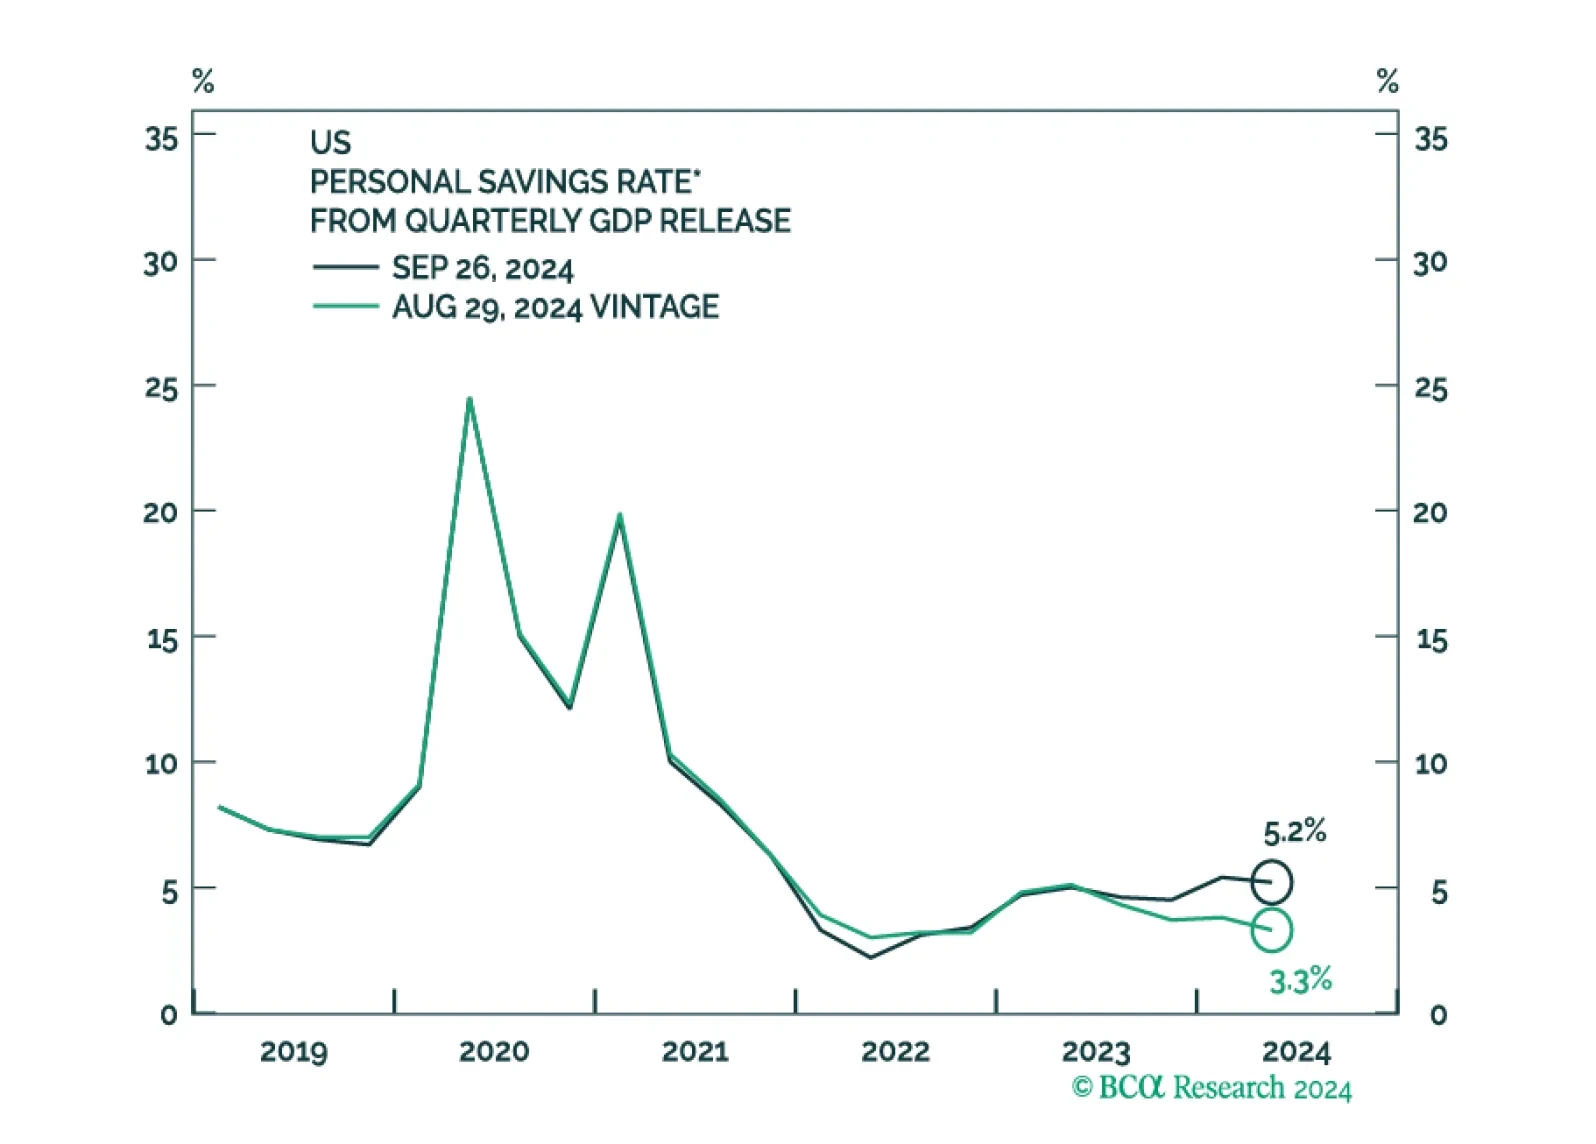
In my view, the revisions resolve a big puzzle that has developed over the past two years, which is how employment growth could have been so strong while personal income growth was so weak. Well, as it turns out, income growth was quite strong too.
Chinese stimulus measures announced on September 24 found few structural optimists in the global macro community, us at BCA Research included. This is for good reason. China is mired in secular stagnation that cannot be unstuck by monetary policy alone.
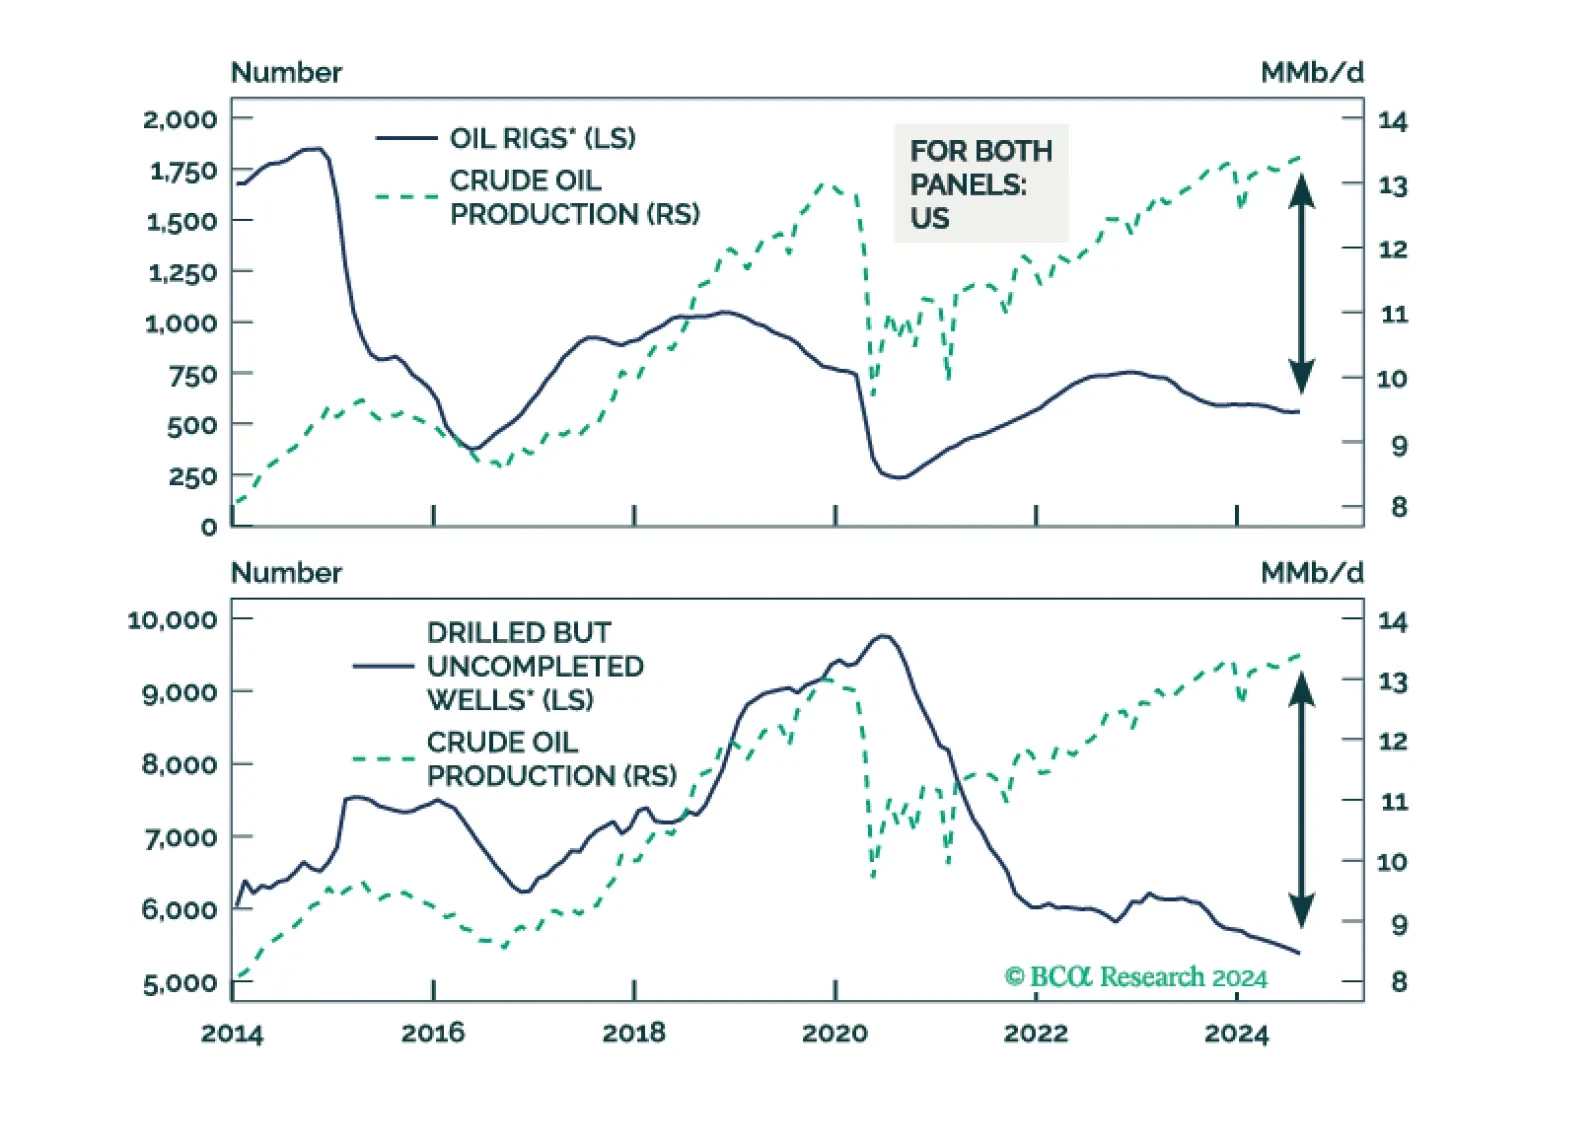
US crude oil output has not peaked. It will continue to increase. A continued expansion of US production, even if it is moderate, along with a possible increase in OPEC+ output, will lead to an oversupplied oil market. Moreover, we expect the demand headwind from the business cycle slowdown to weigh on crude prices. Over a 6-to-12-month horizon, the path of least resistance for oil prices is to the downside.