Latest from BCA Research
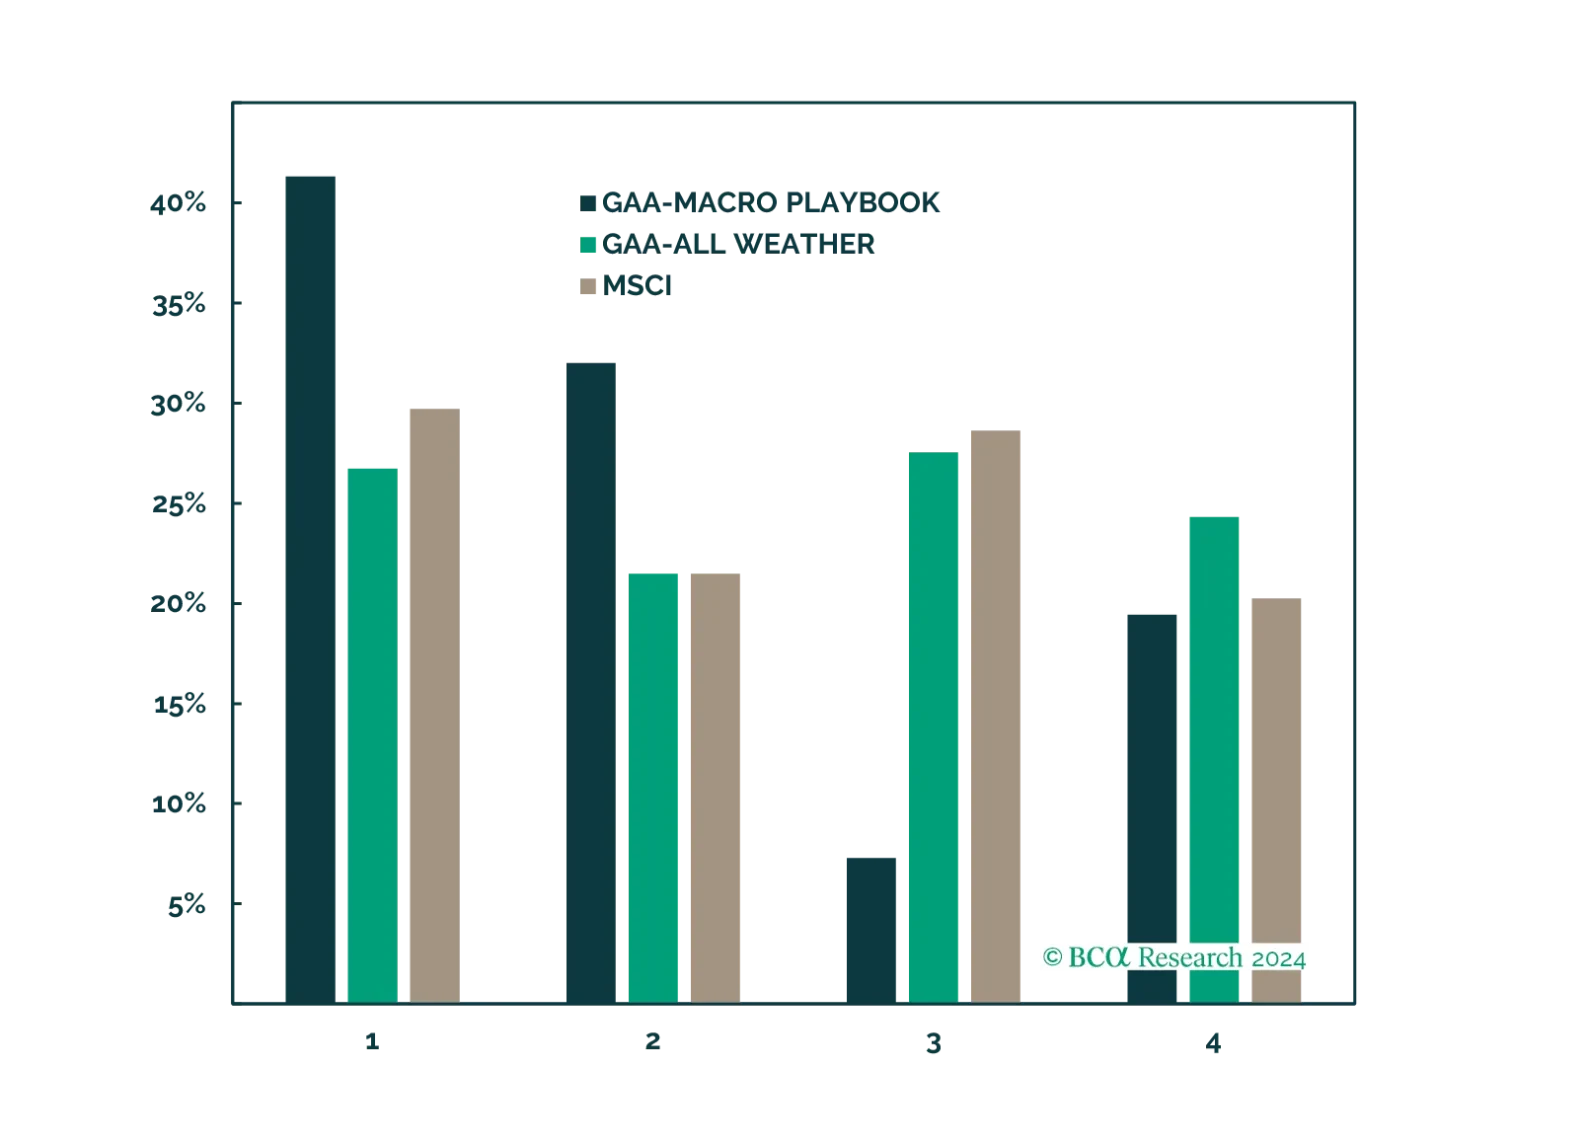
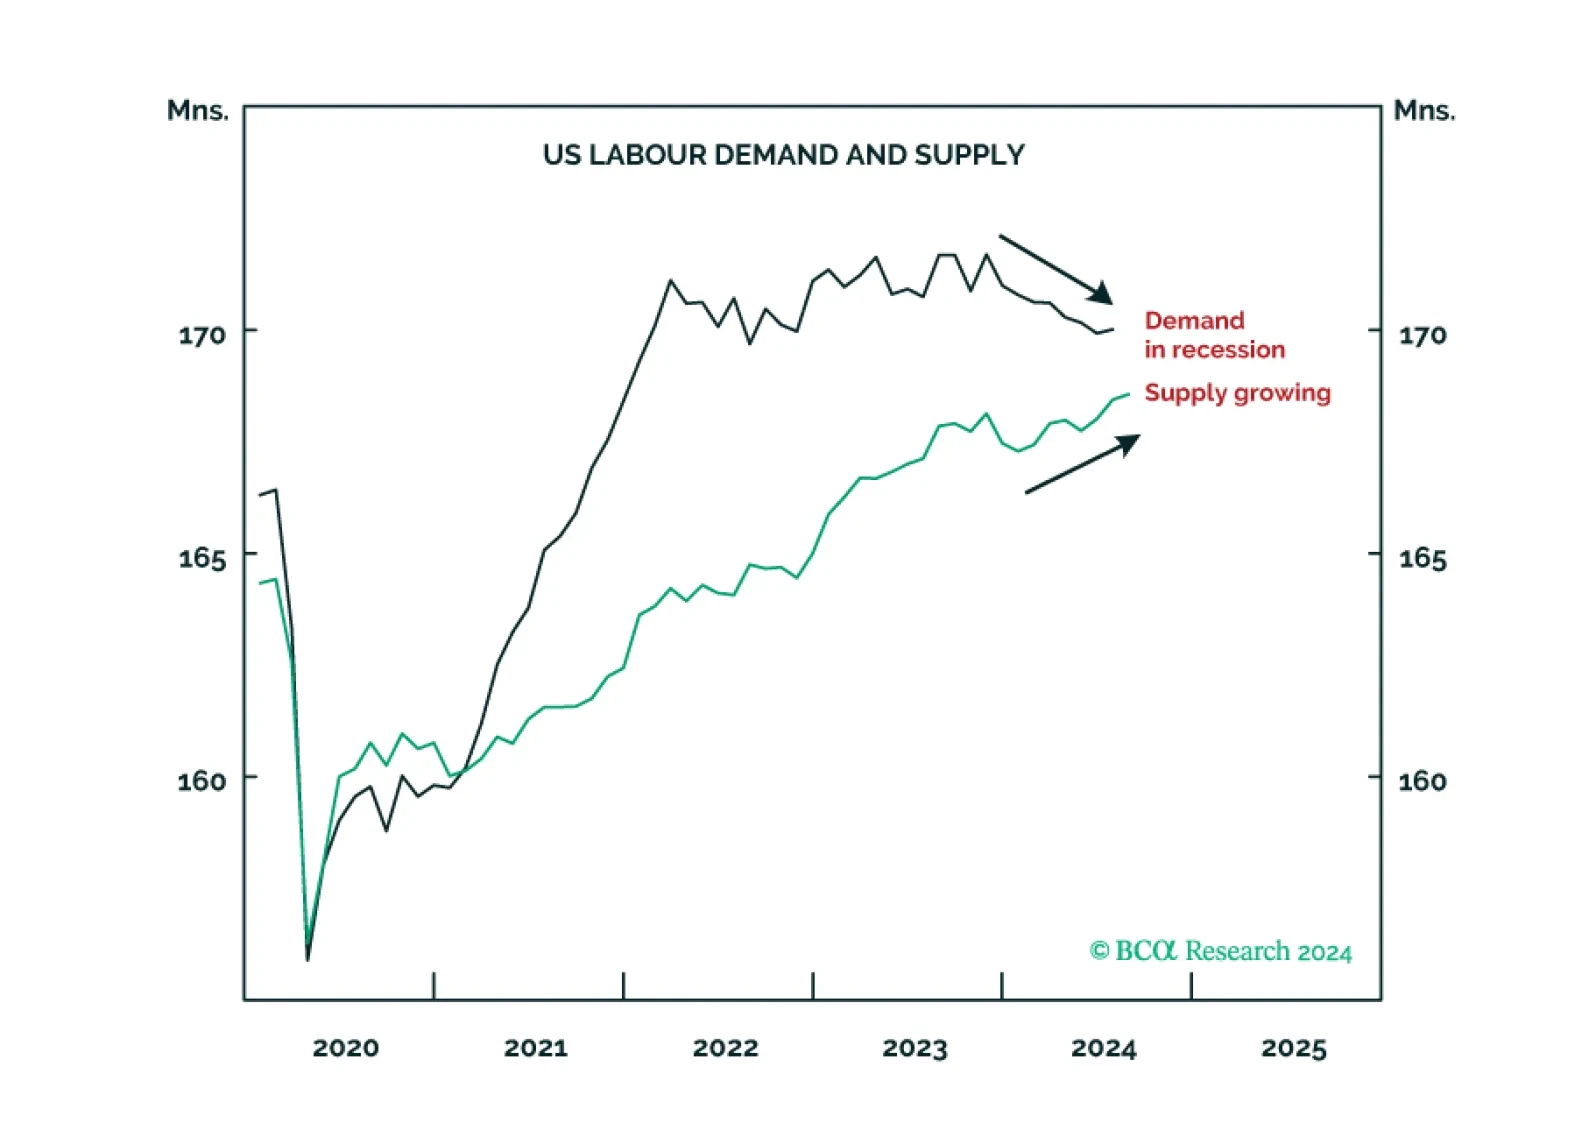
Just like the market for Oasis 2025 reunion tour tickets, the US labour market is ‘supply-constrained’. This means the US will not go into a GDP recession in the next few months and has a good chance of cheating one for longer. Without a GDP recession, there is unlikely to be an economy-wide profits recession. This leads to three recommendation changes on a cyclical (12-month) horizon which we highlight. Plus: the tactical rally in Chinese stocks can continue.
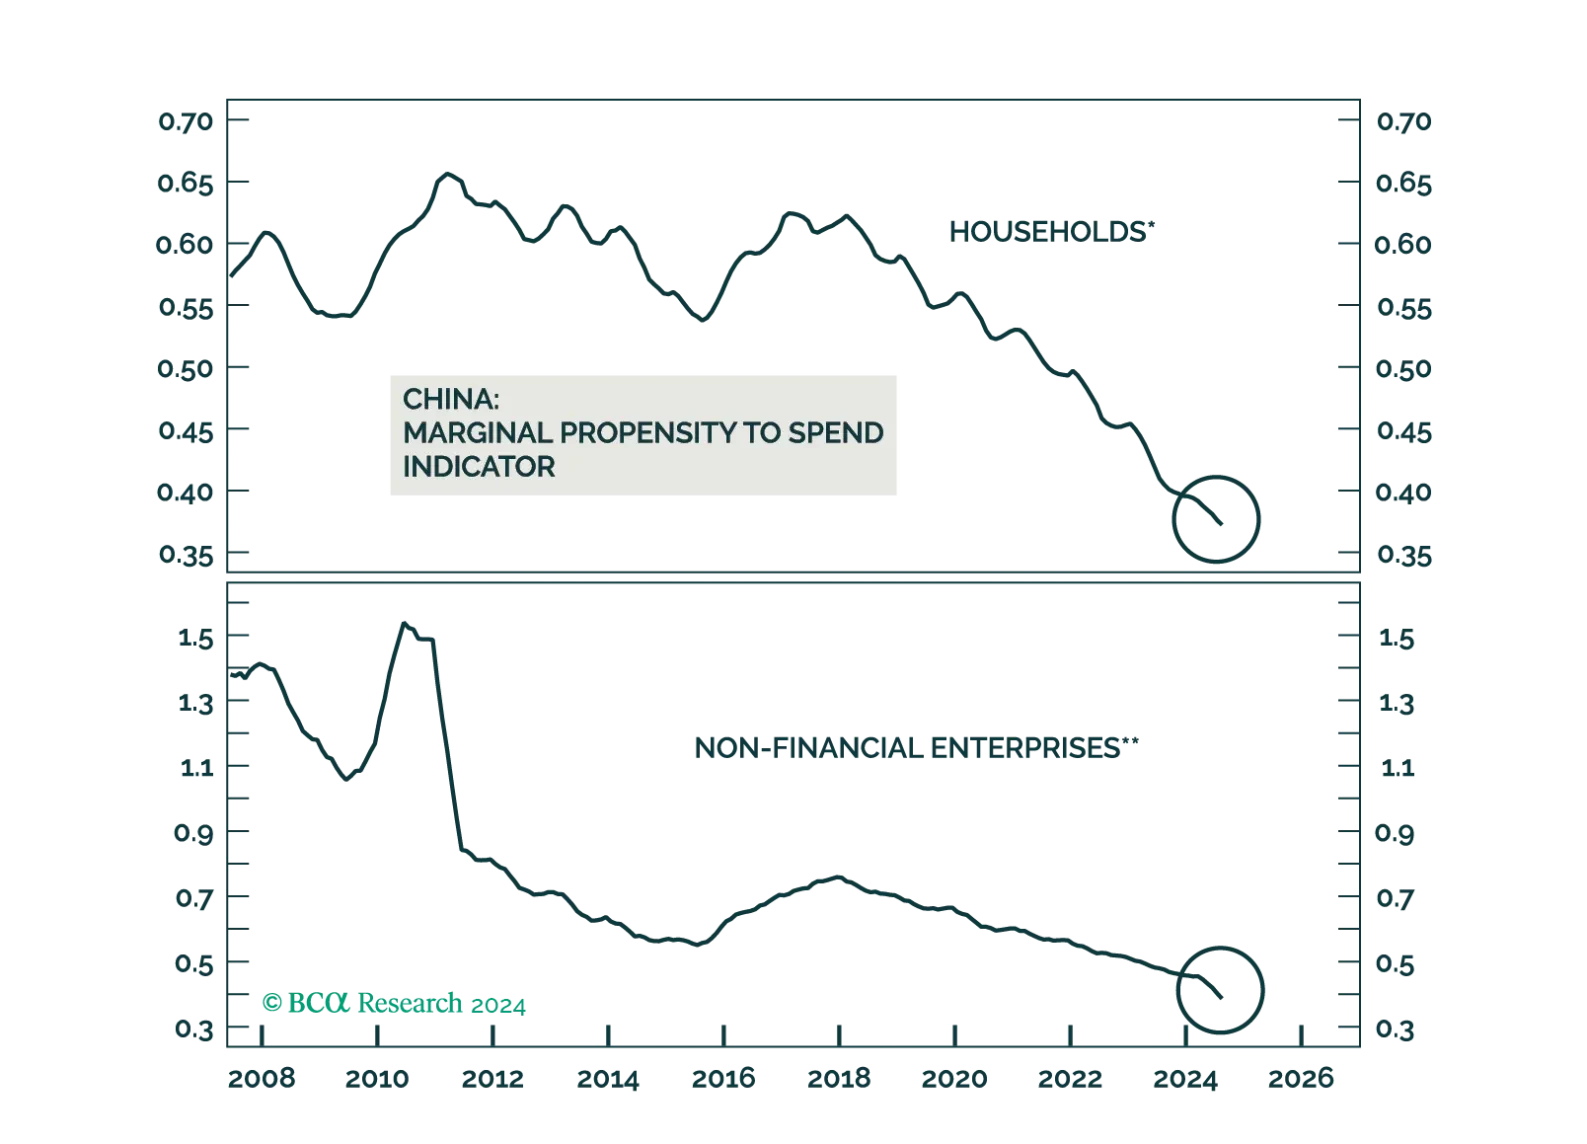
We believe the PBoC’s recent policy stimulus might bolster investor confidence, potentially stabilize onshore Chinese equity prices, and provide modest support to offshore stocks. However, they are unlikely to significantly boost economic growth in the mainland.
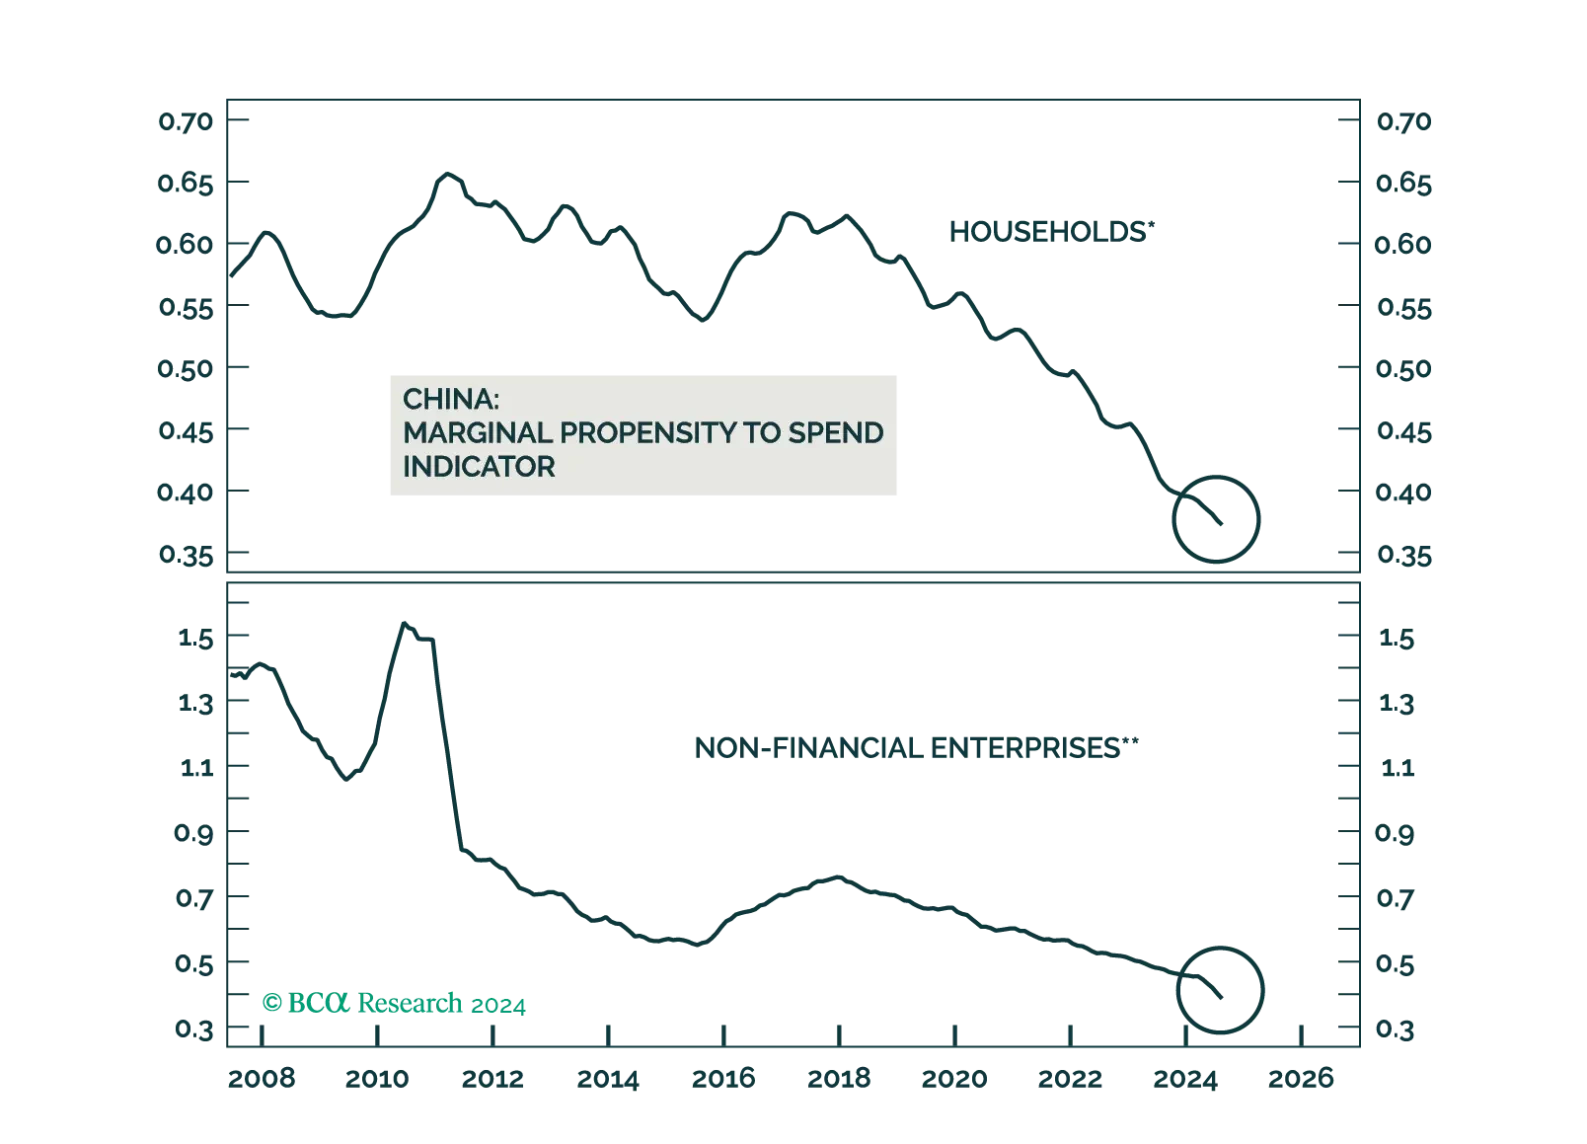
We believe the PBoC’s recent policy stimulus might bolster investor confidence, potentially stabilize onshore Chinese equity prices, and provide modest support to offshore stocks. However, they are unlikely to significantly boost economic growth in the mainland.
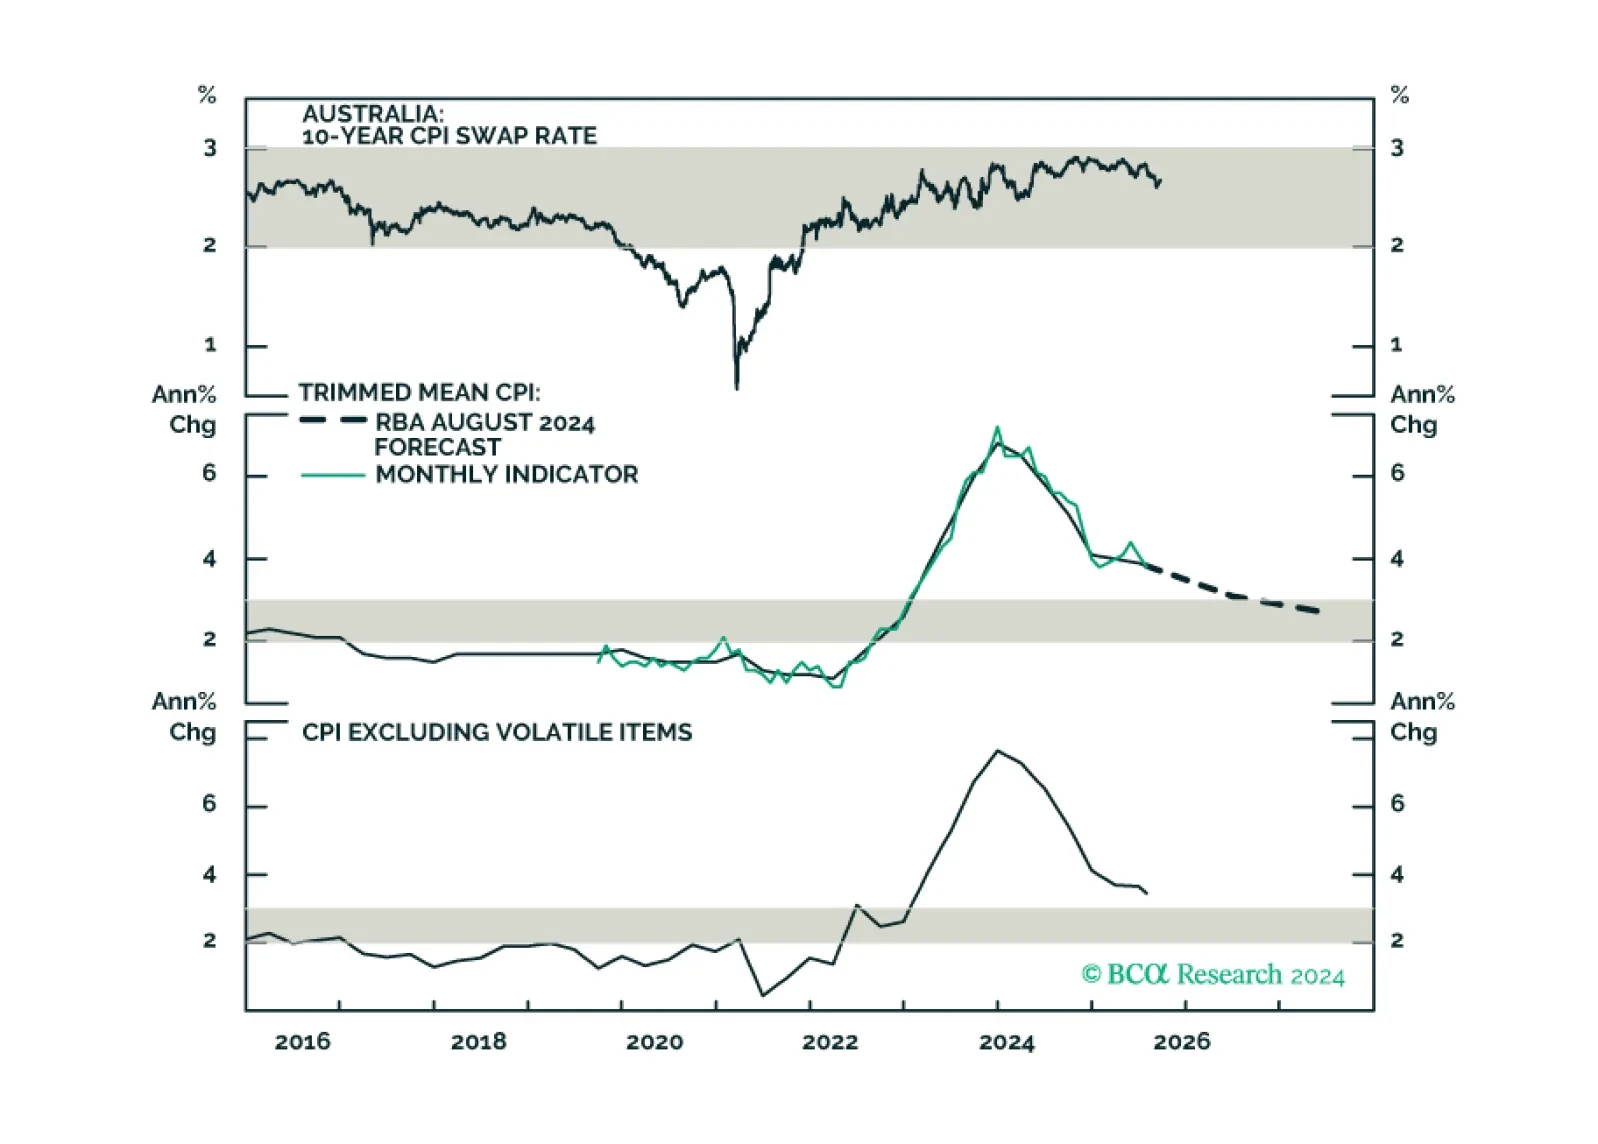
This insight parses through the RBA’s latest policy decision, and makes recommendations on whether to expect any rate cuts in 2024, and beyond.
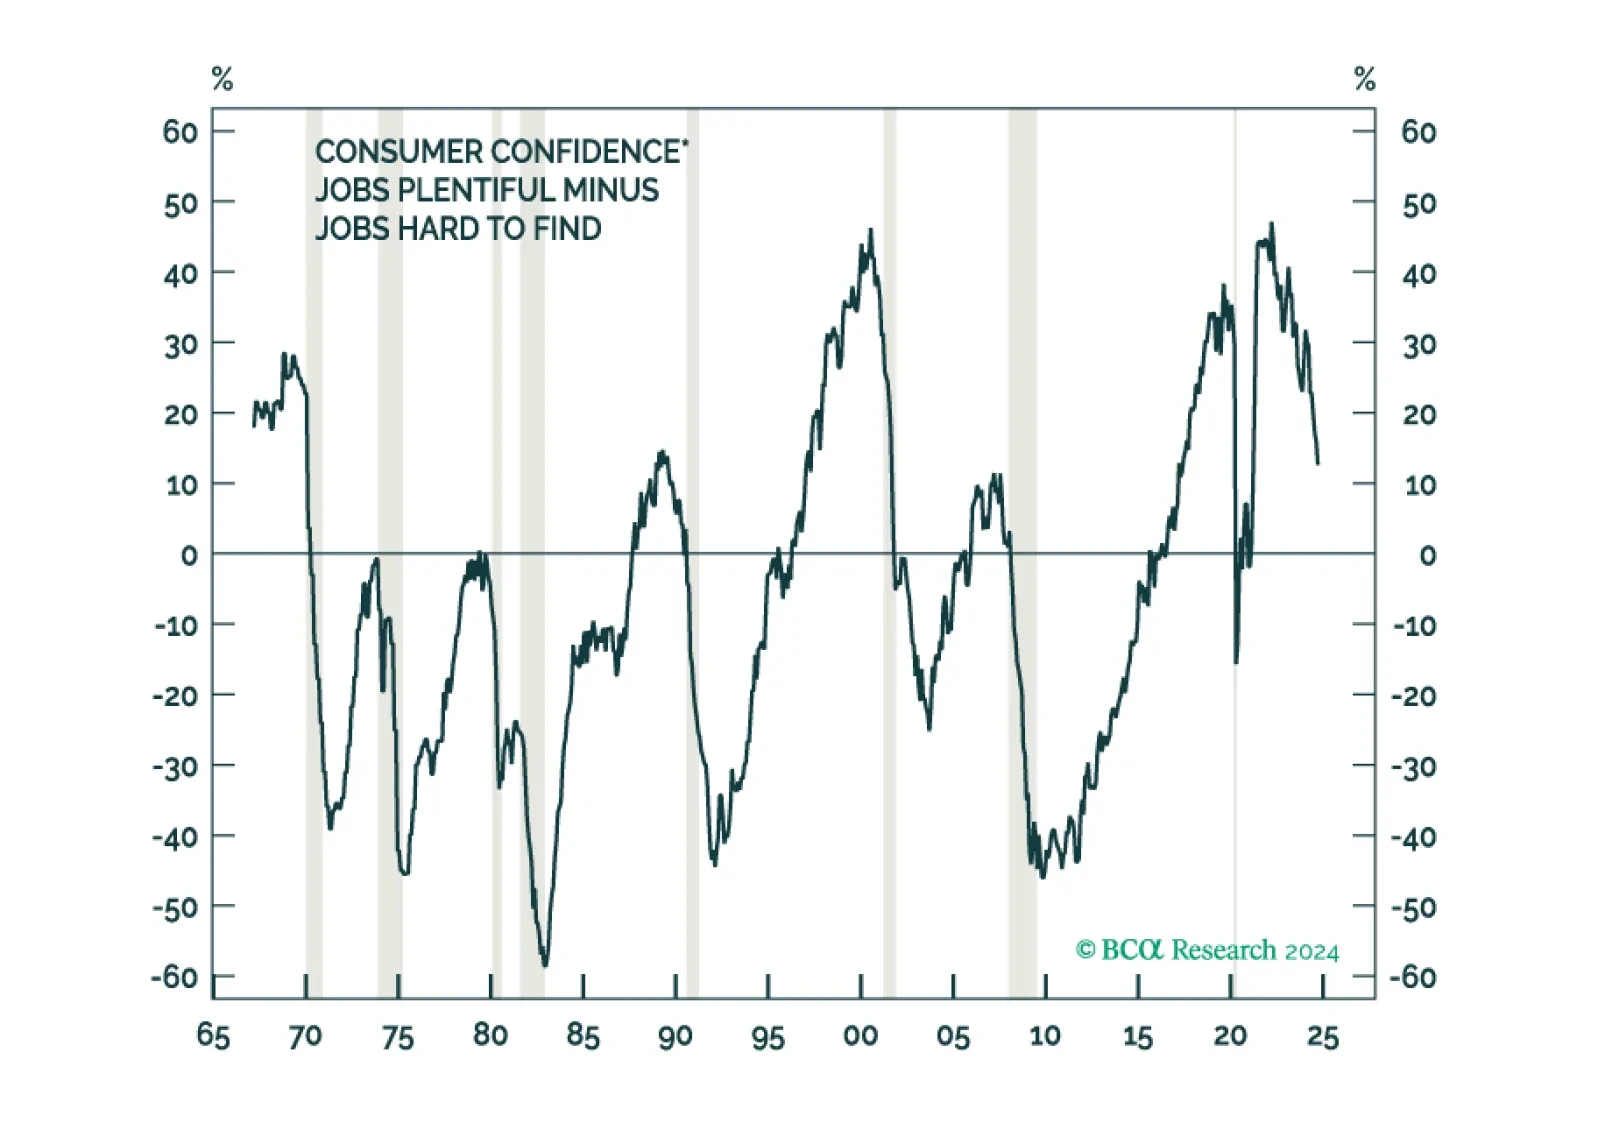
Two days ago, I flagged how the number of people in the US who are working part time but would rather be working full time is rising, which usually only happens in the early stages of recessions.
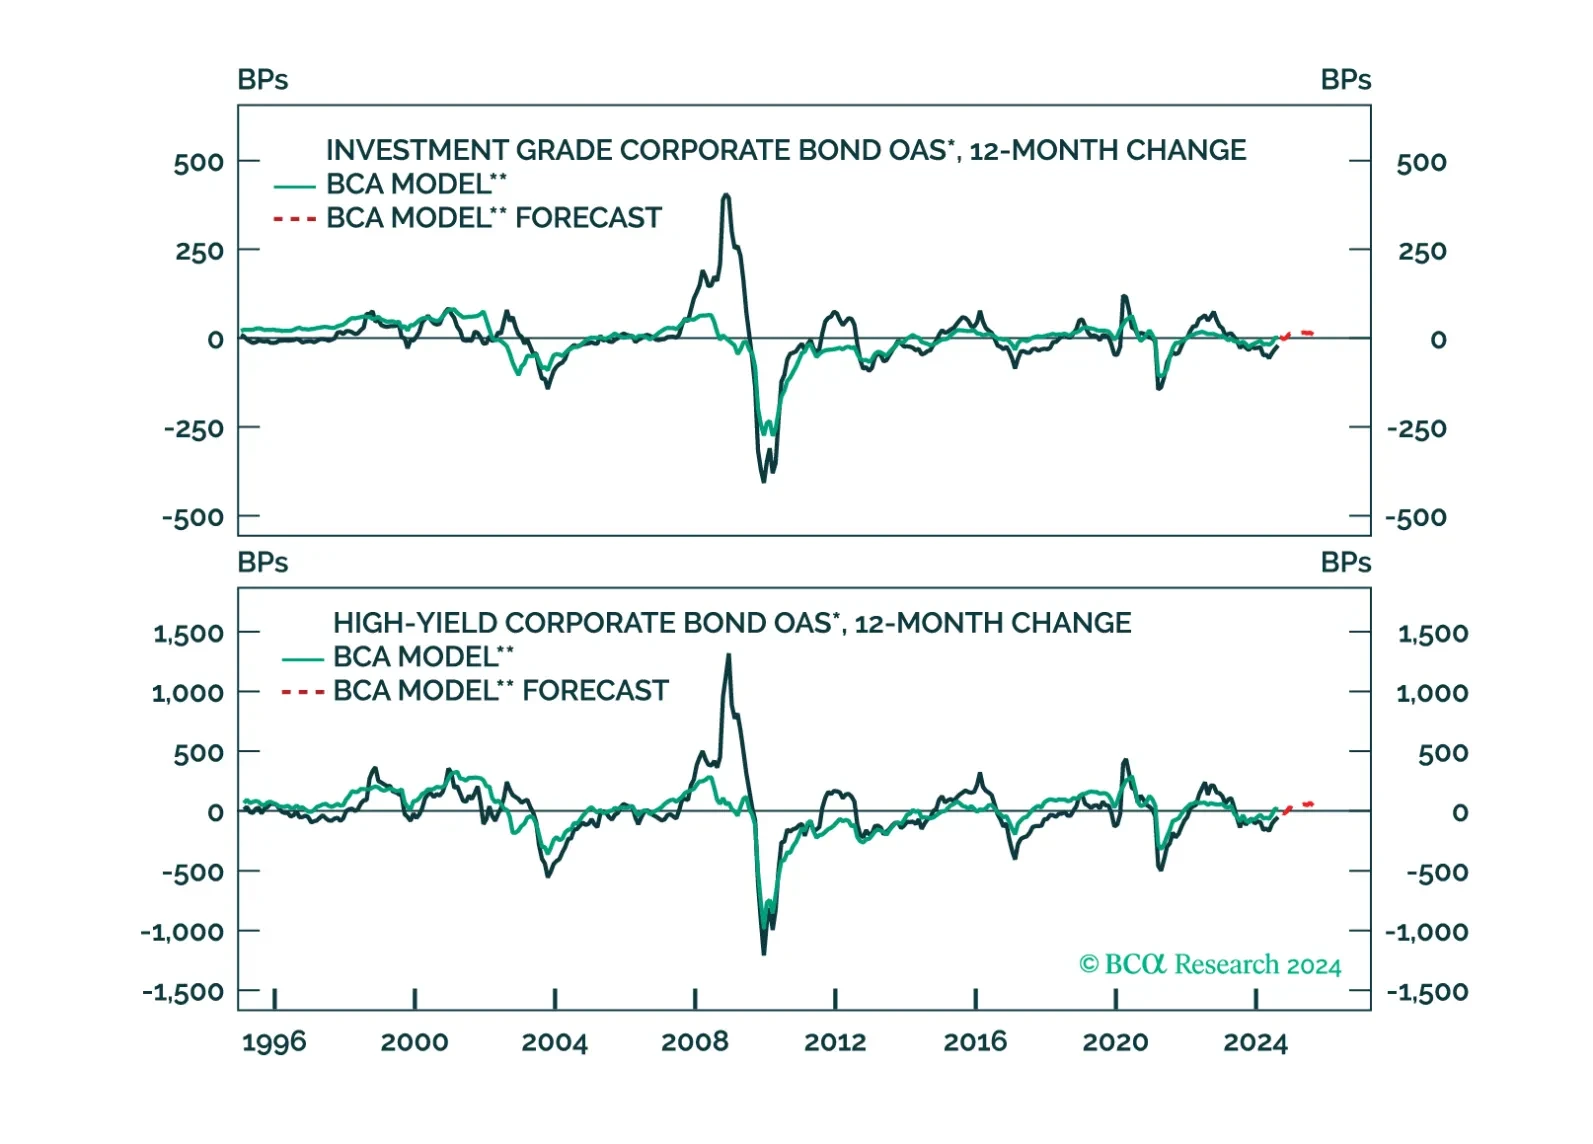
We update our corporate default rate model and consider the implications for corporate bond spreads.
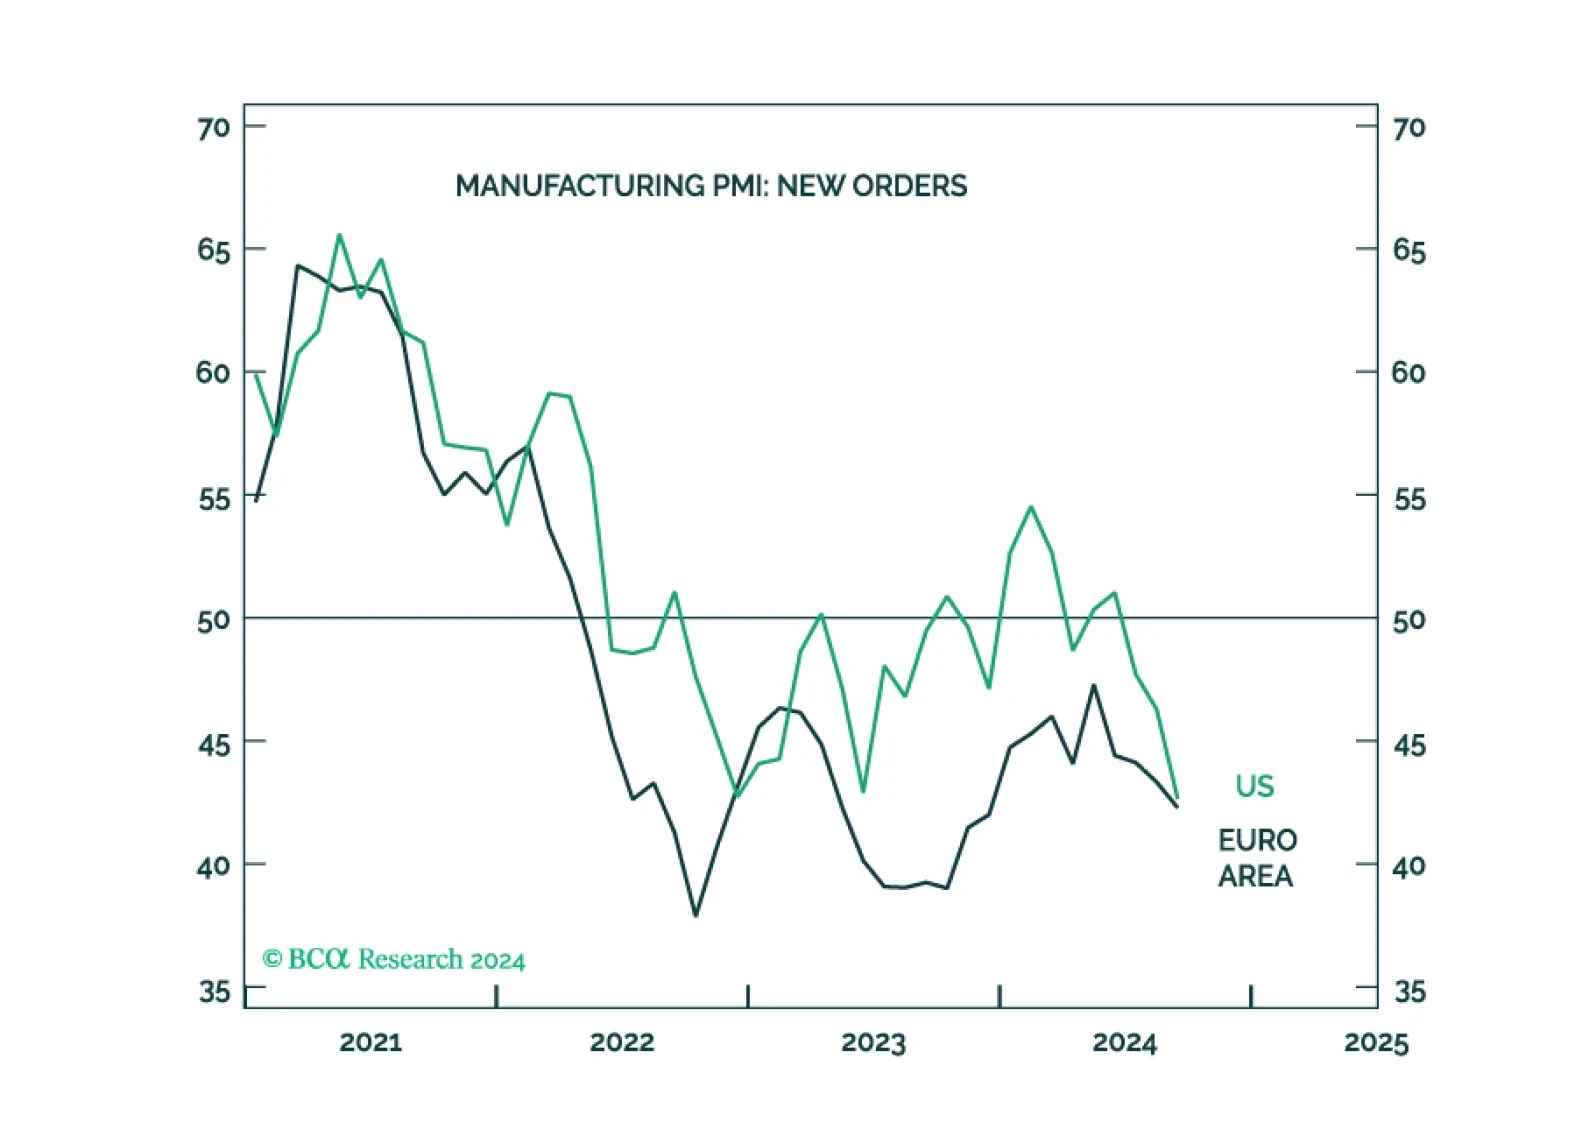
The S&P Global flash PMIs released yesterday showed that the contraction in manufacturing activity accelerated on both sides of the Atlantic in September. The forward-looking new orders component fell to a 9-month low of 42.3 in the euro area and a 21-month low of 42.7 in the US.