Latest from BCA Research
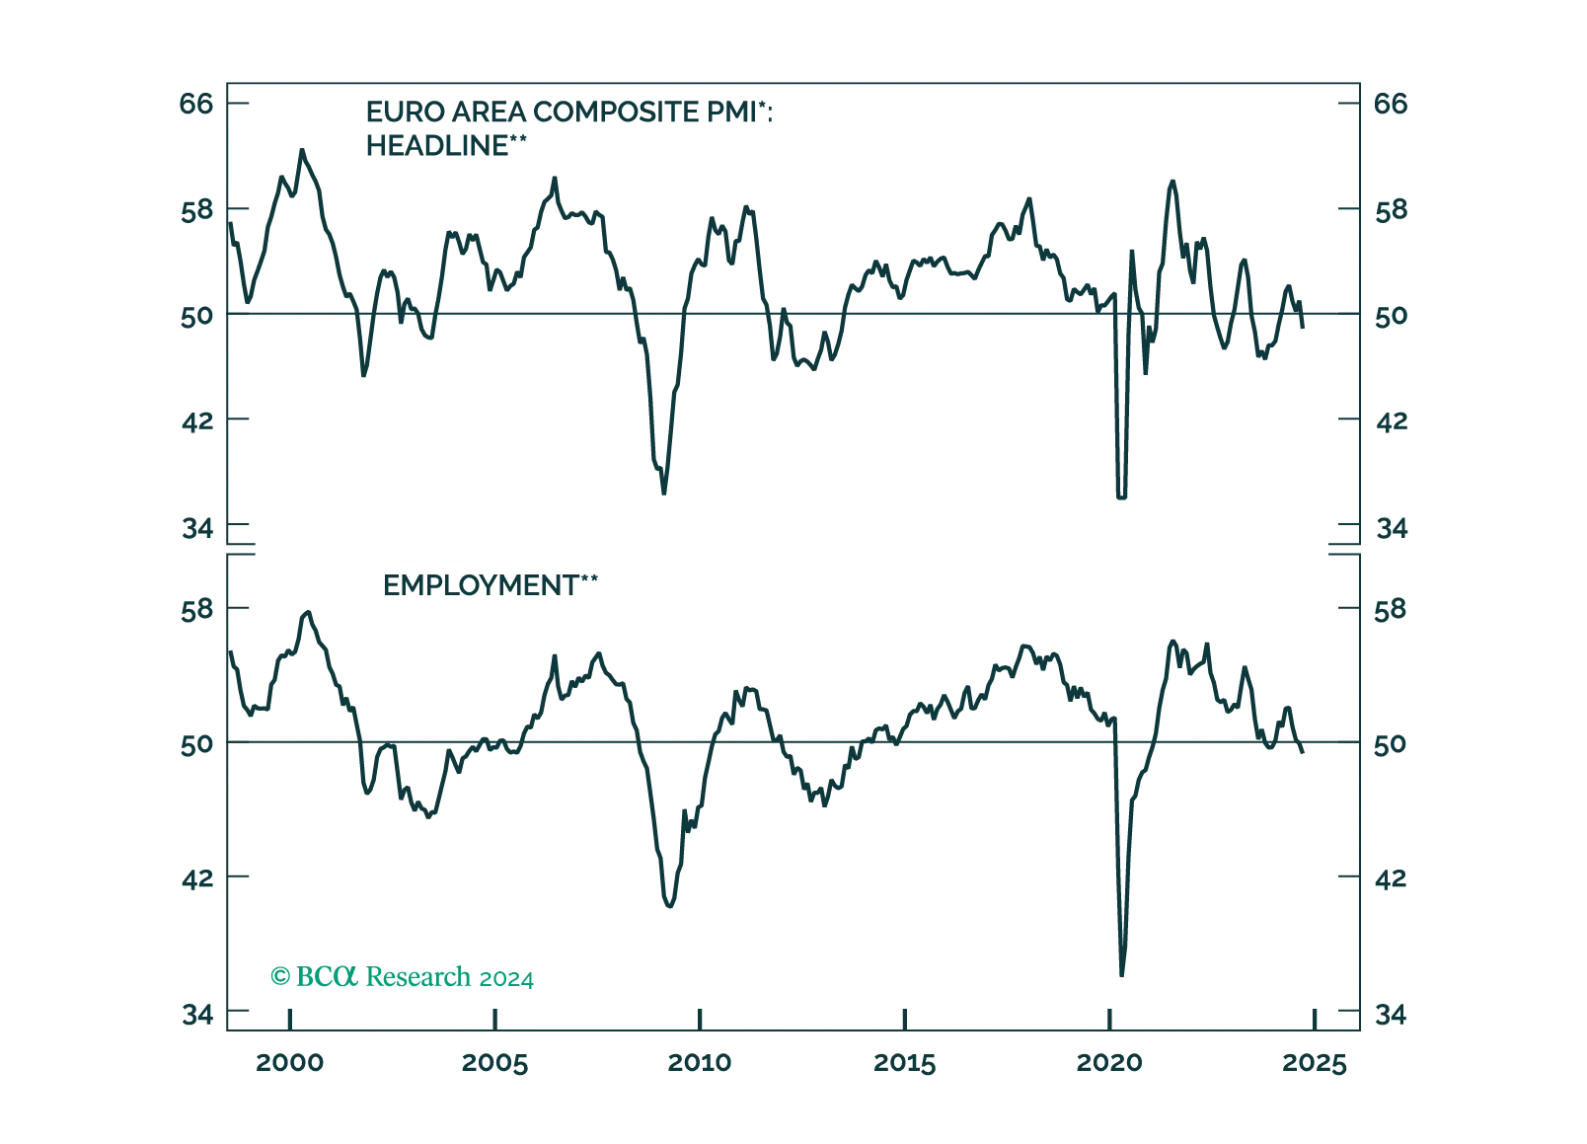
The September Euro Area Flash PMI release confirms that the region's economic outlook is deteriorating. Manufacturing activity is now fully contracting, and the new orders-to-inventory ratio is deteriorating anew. Services activity is losing some of its shine, especially in France, now that the Olympics are over.
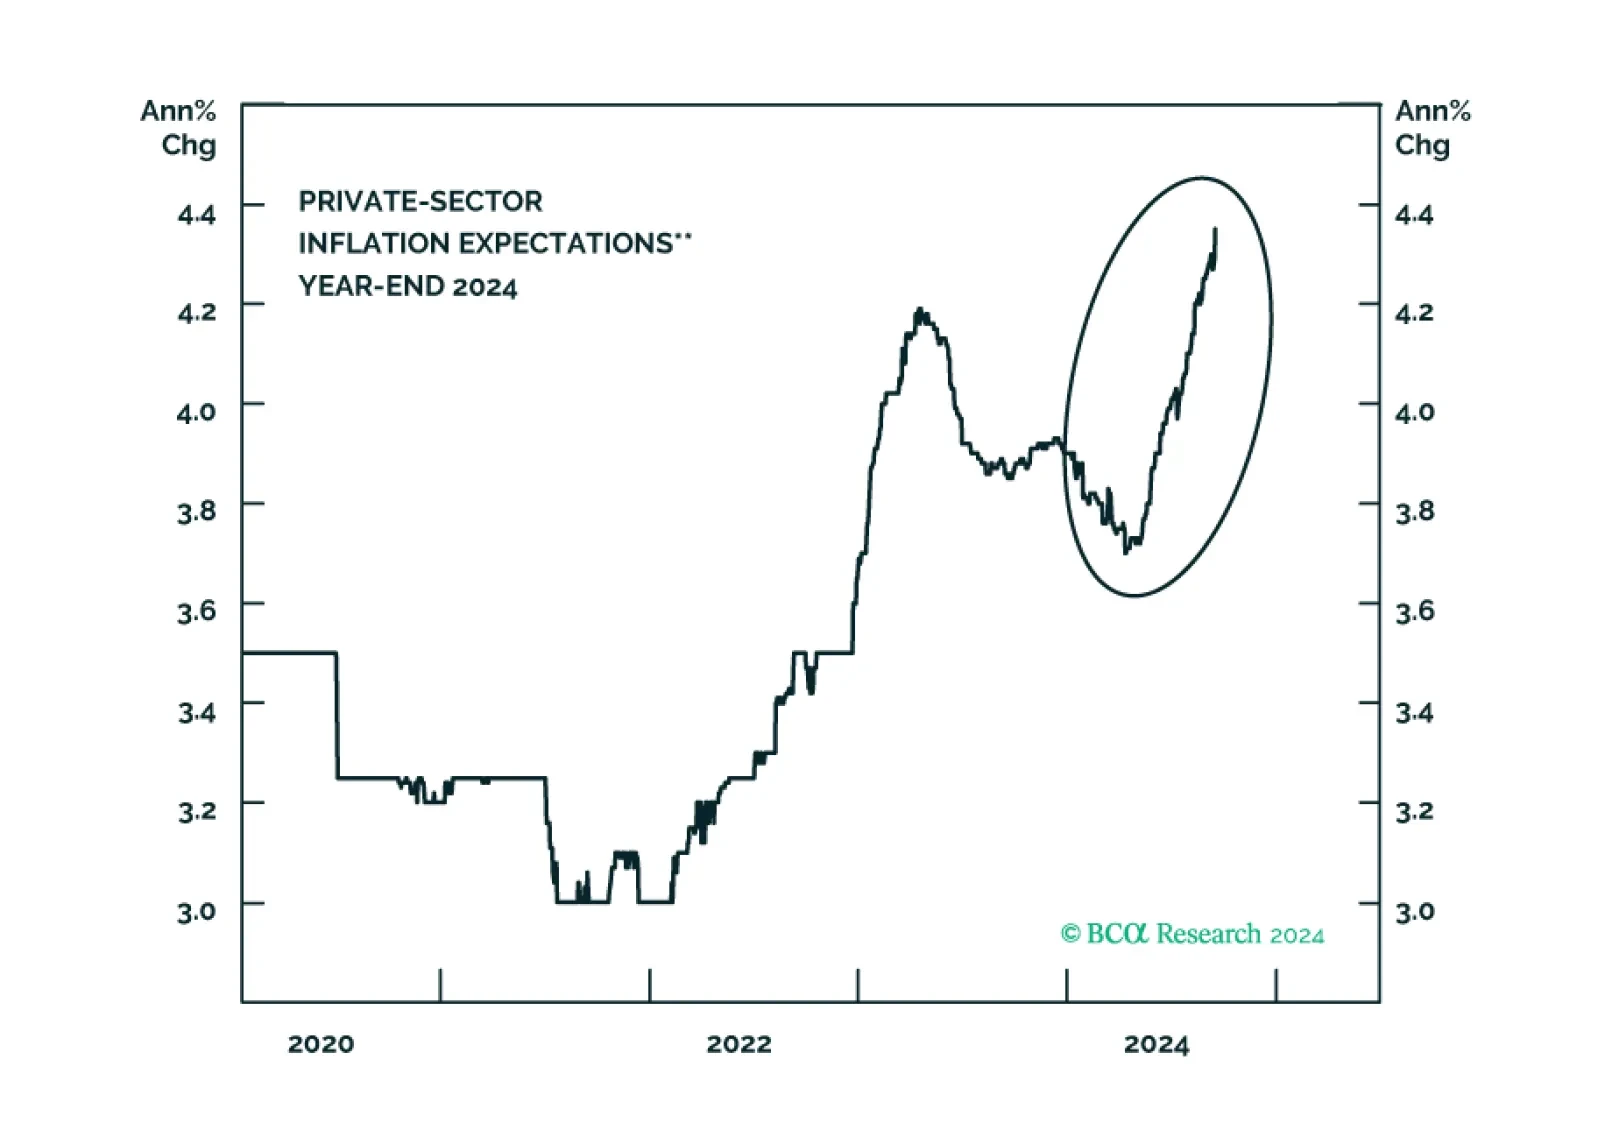
The Central Bank of Brazil (BCB) raised interest rates last week. Is this the commencement of a major tightening cycle that will persist well into next year? Despite this move, we maintain that the BCB will cut interest rates substantially next year. We believe the Lula-nominated board members are playing the long game: voting to hike rates until year-end to establish credibility with financial markets in order to get a pass at easing monetary policy in early 2025.
It is not every day that we reference a Tucker interview as market relevant. His sit down with the VP candidate JD Vance caught our attention.
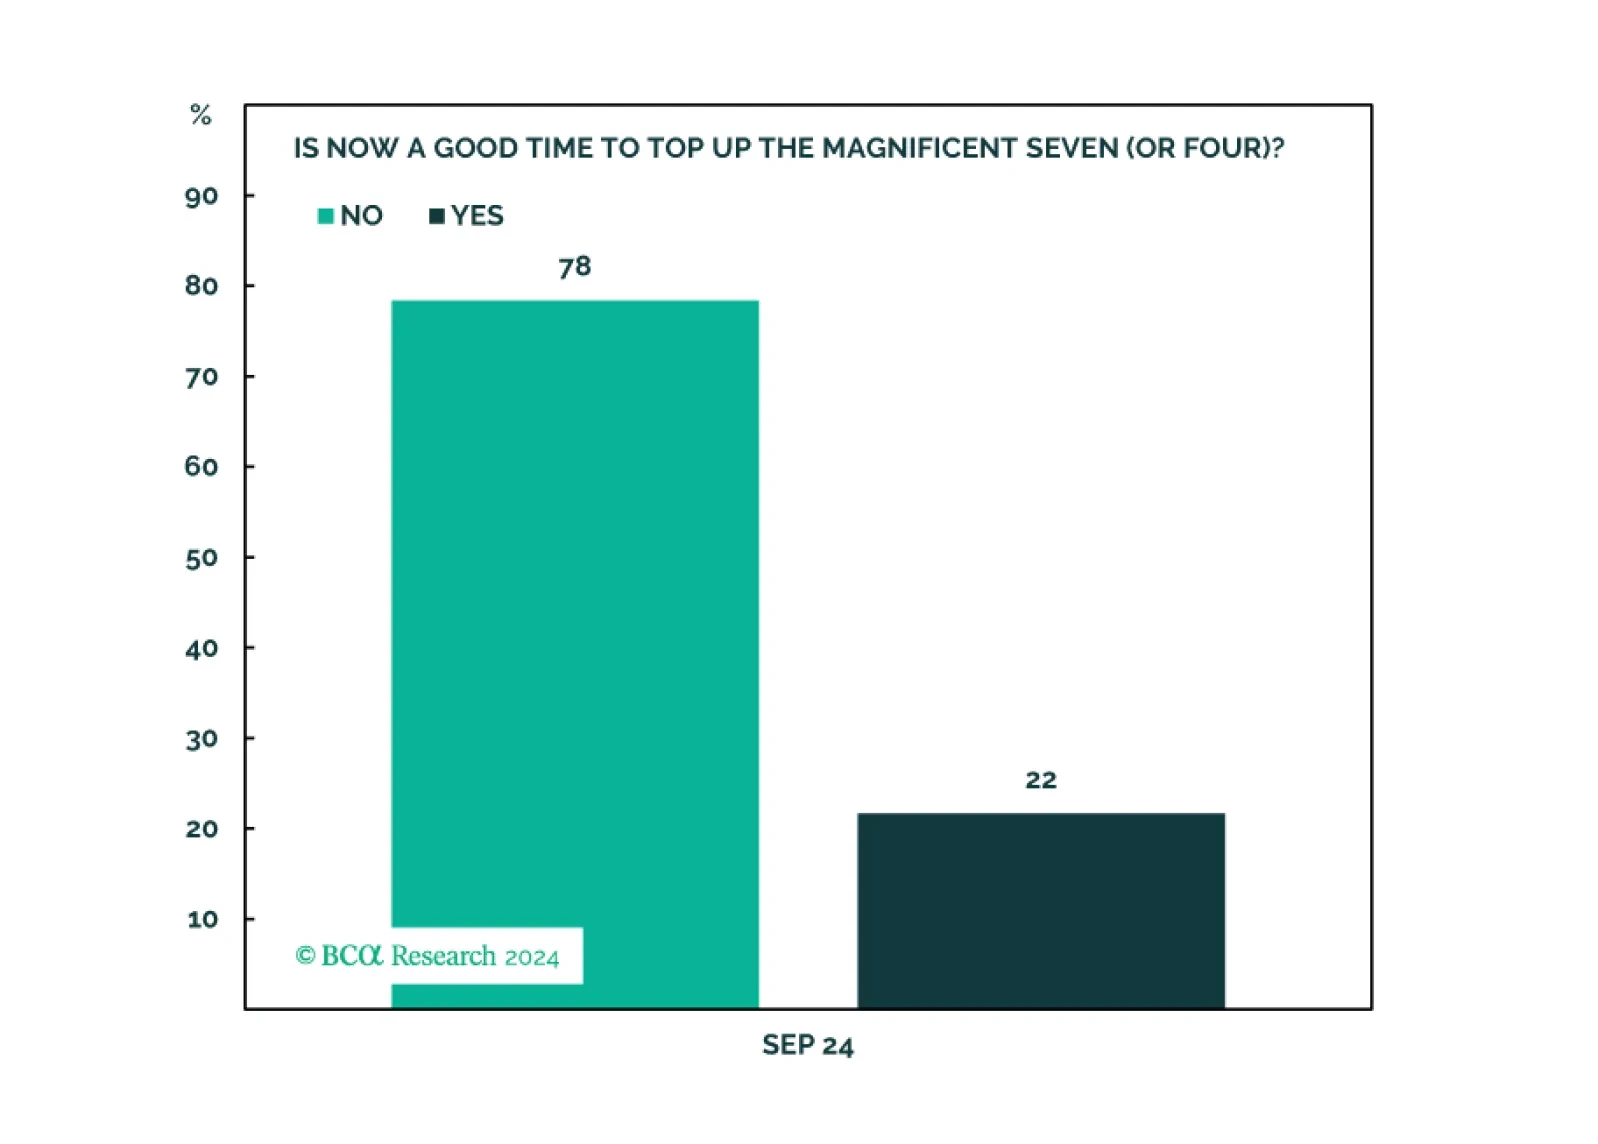
In this report, we follow up on the Roundtable that we hosted on September 11. We summarize the results of the client polls and answer a few questions on top of investors’ minds.
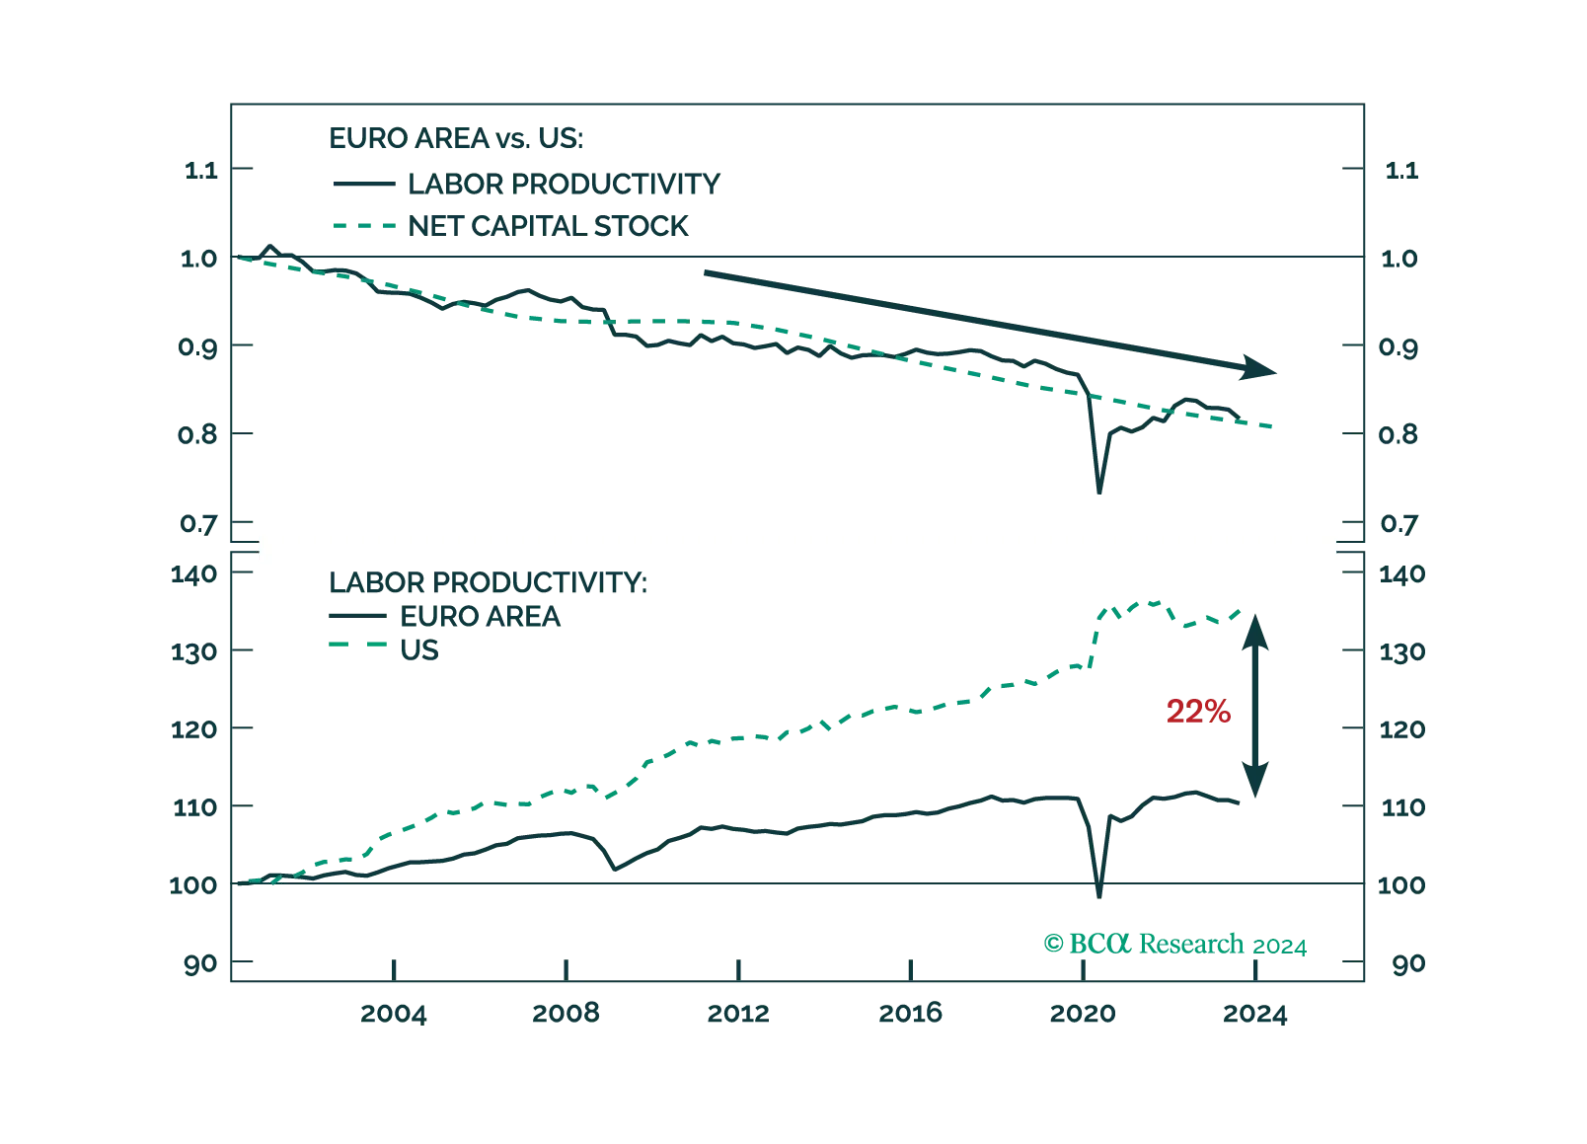
The Draghi report highlights sensible reforms that would address many of Europe’s productivity shortcomings. Whether European capitals heed Mario Draghi’s advices remains to be seen.
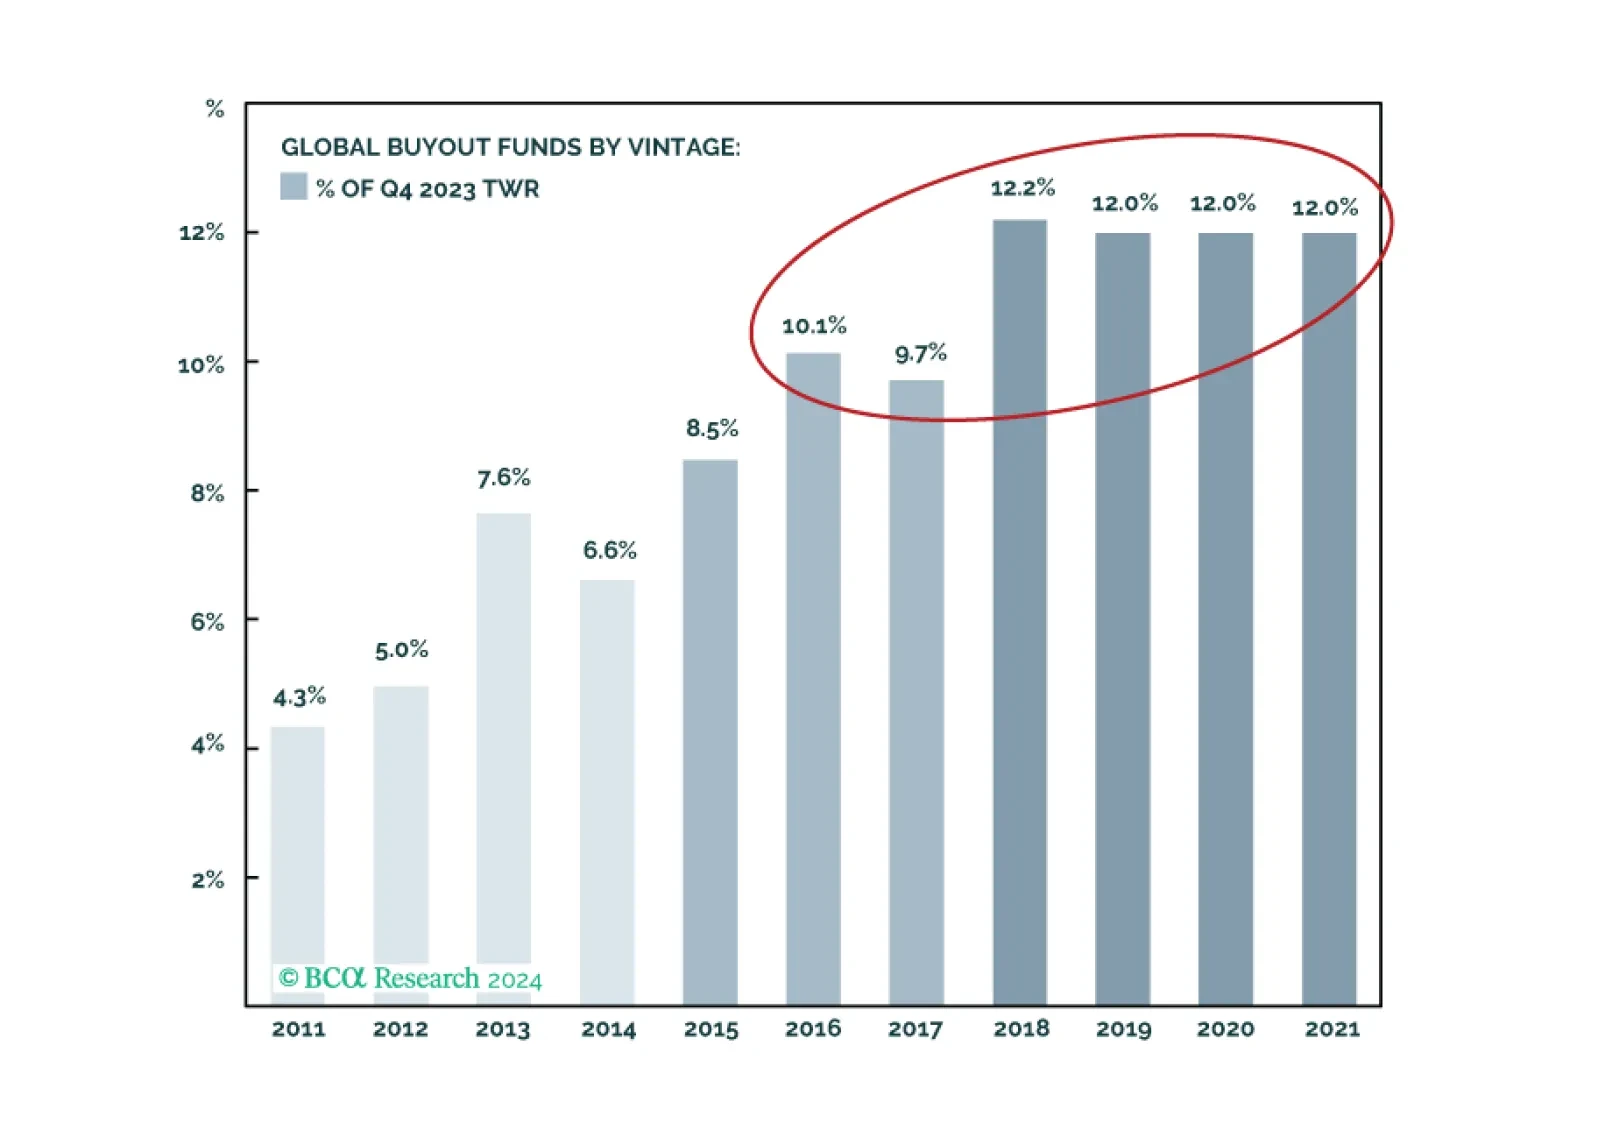
Unlike public markets, performance in private markets is complex and multifaceted. In this report we present multiple metrics across time and sources, offering investors a comprehensive range of benchmarks to assess their relative performance. Differences across sources will surprise.
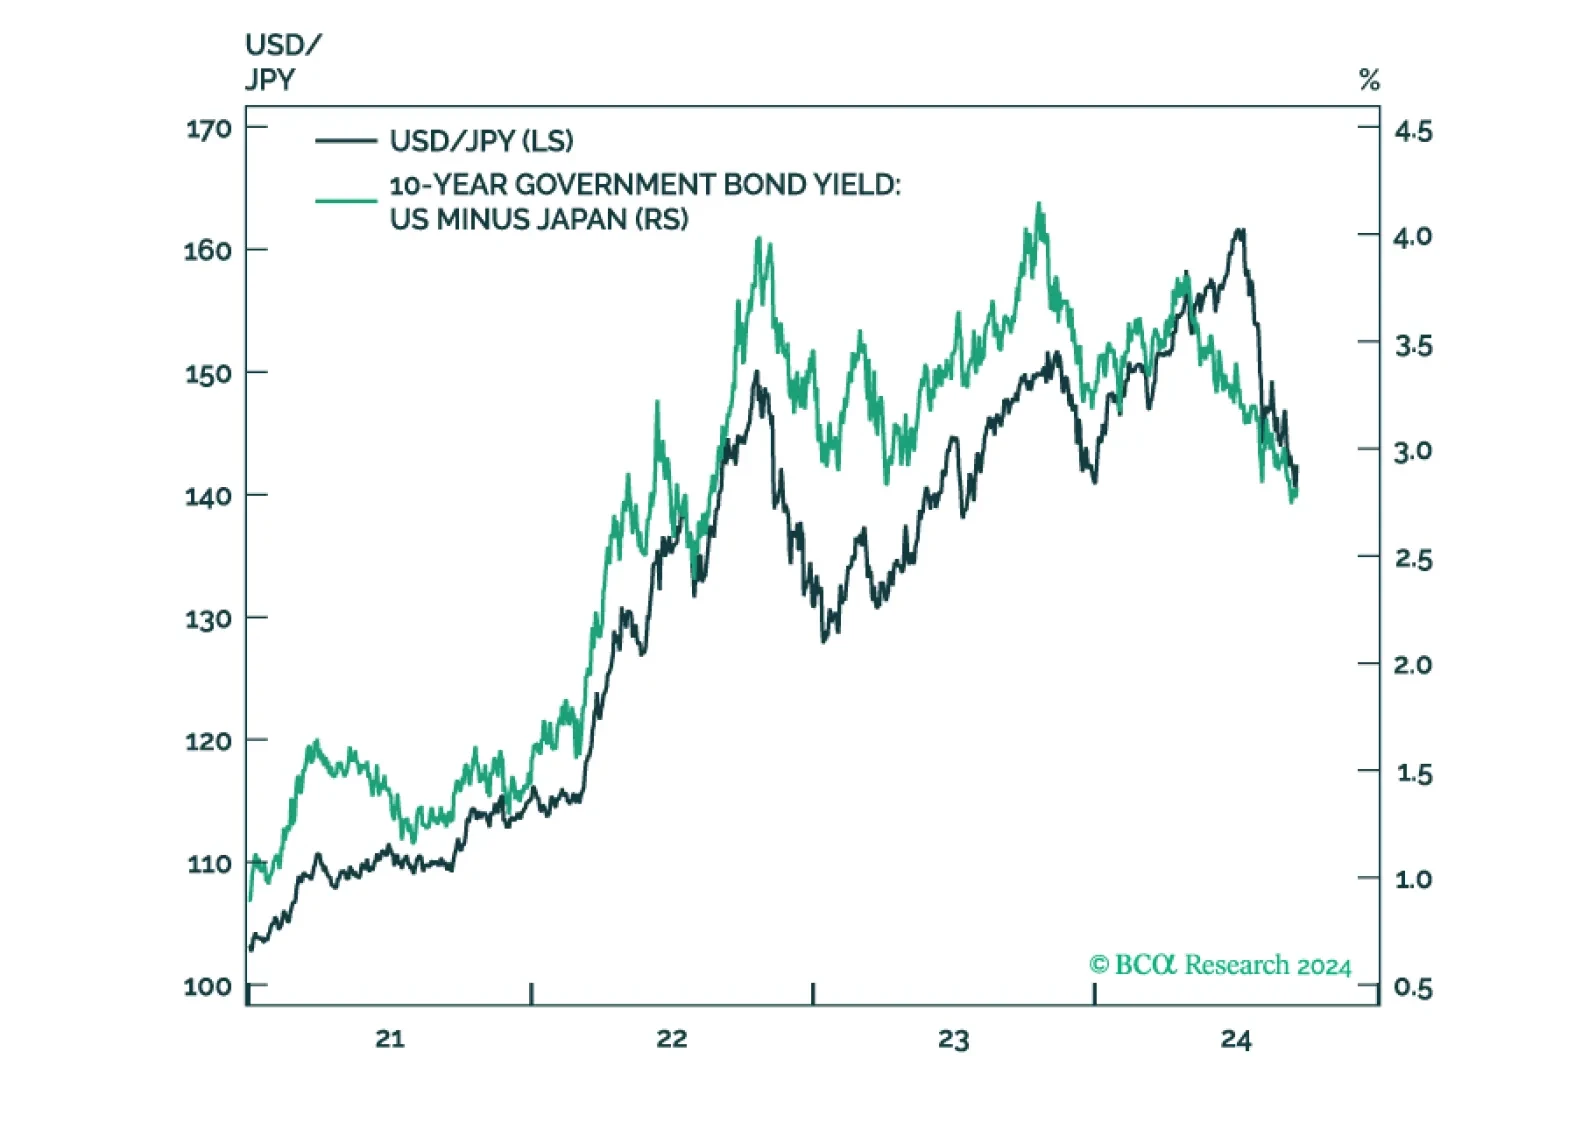
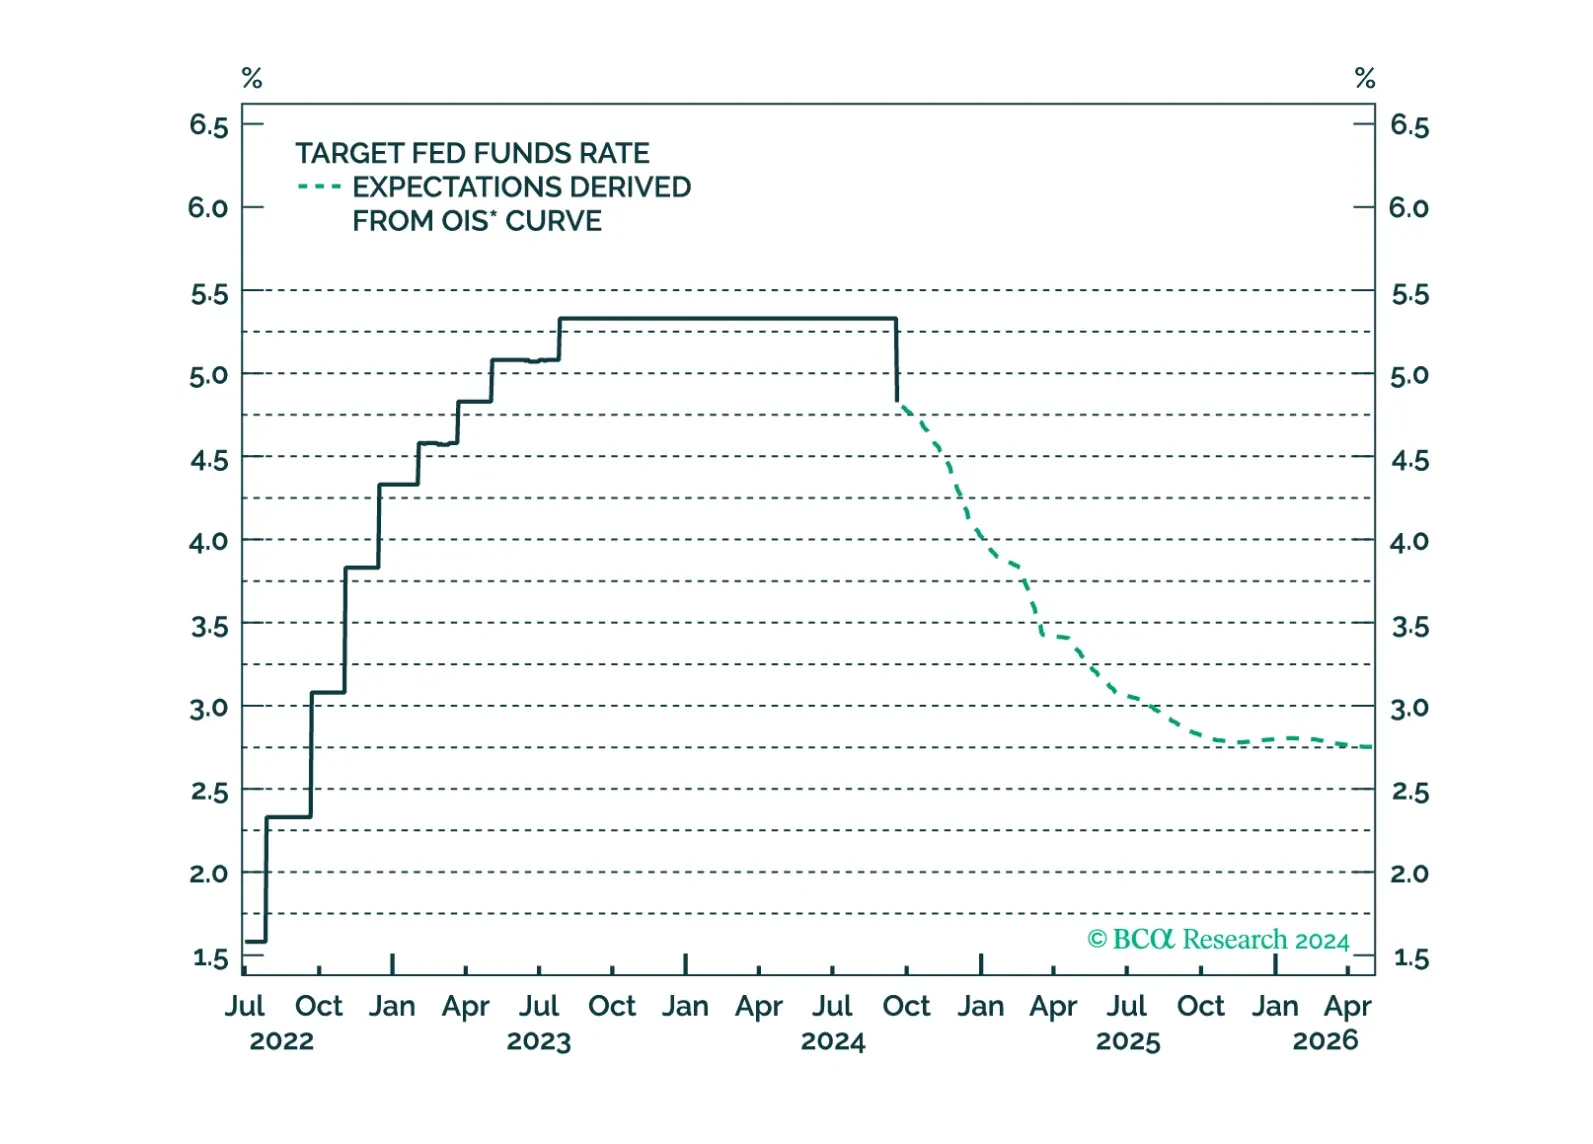
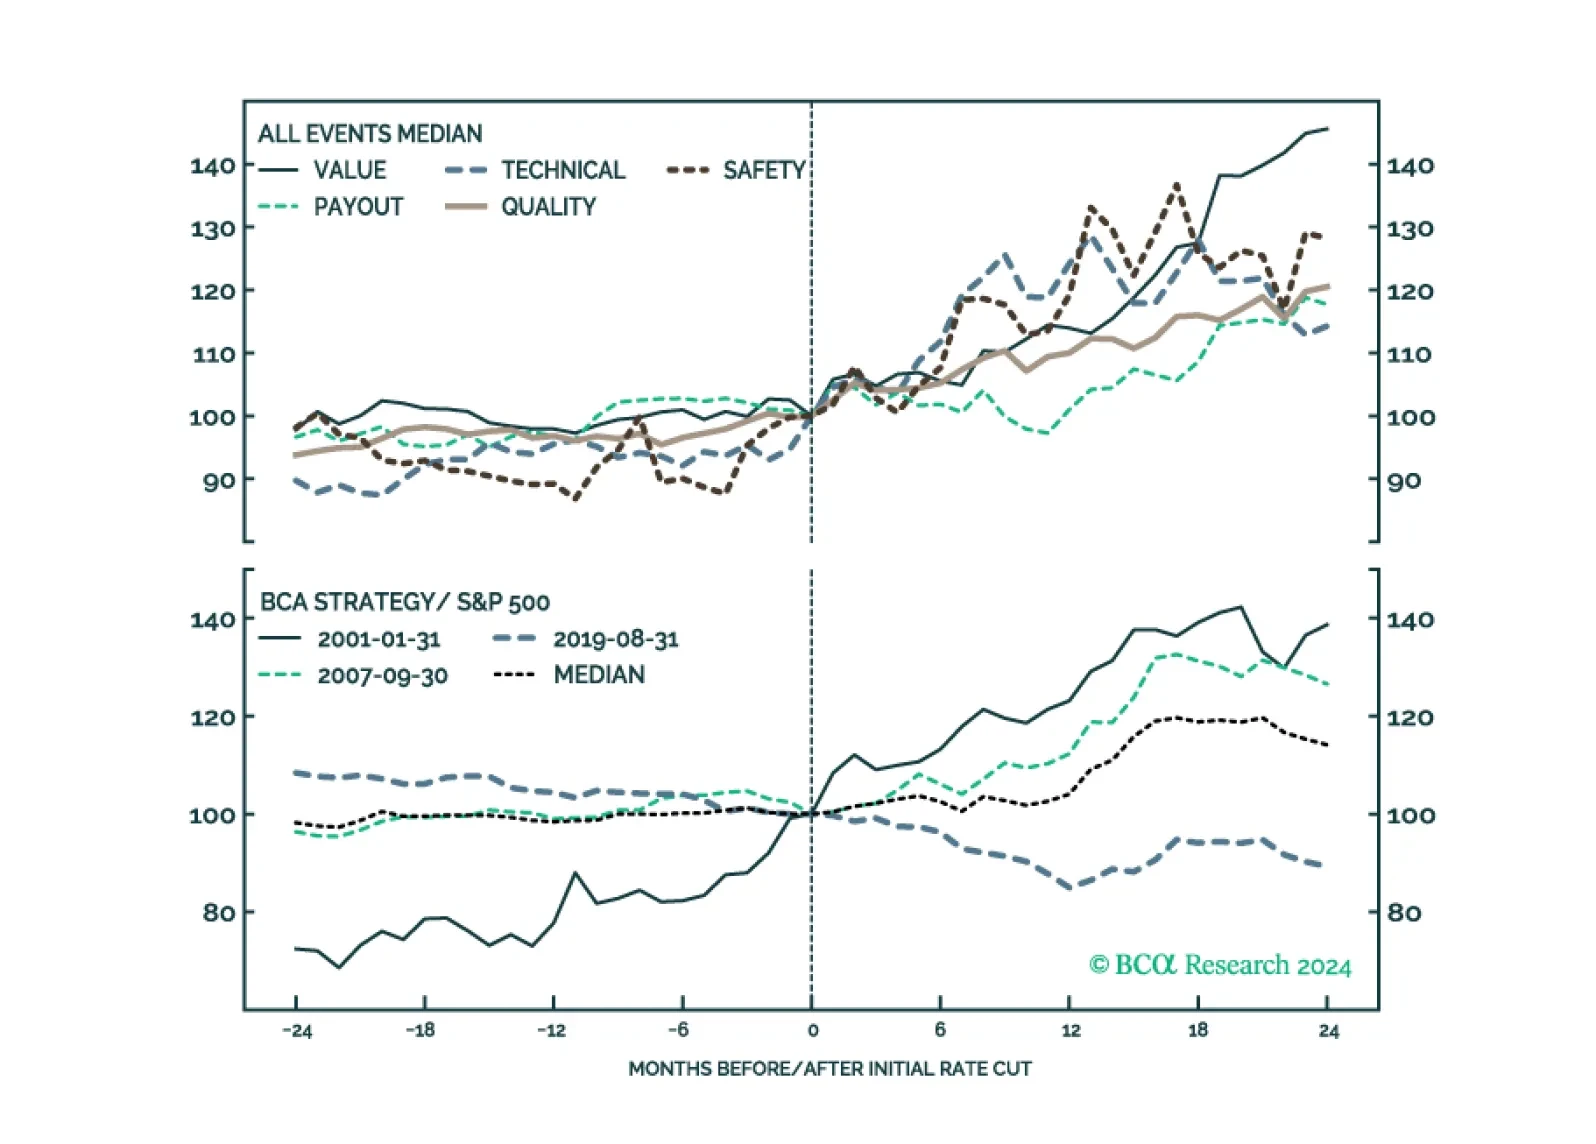
Initial rate cuts are not statistically significant for Equity Analyzer’s factors, though we still note Value and Safety as top performers. Sectors are the same. Defensives spike but lose traction as Cyclicals come into favor later. If a hard landing materializes as we expect, equities will move lower, even in the face of further rate cuts.
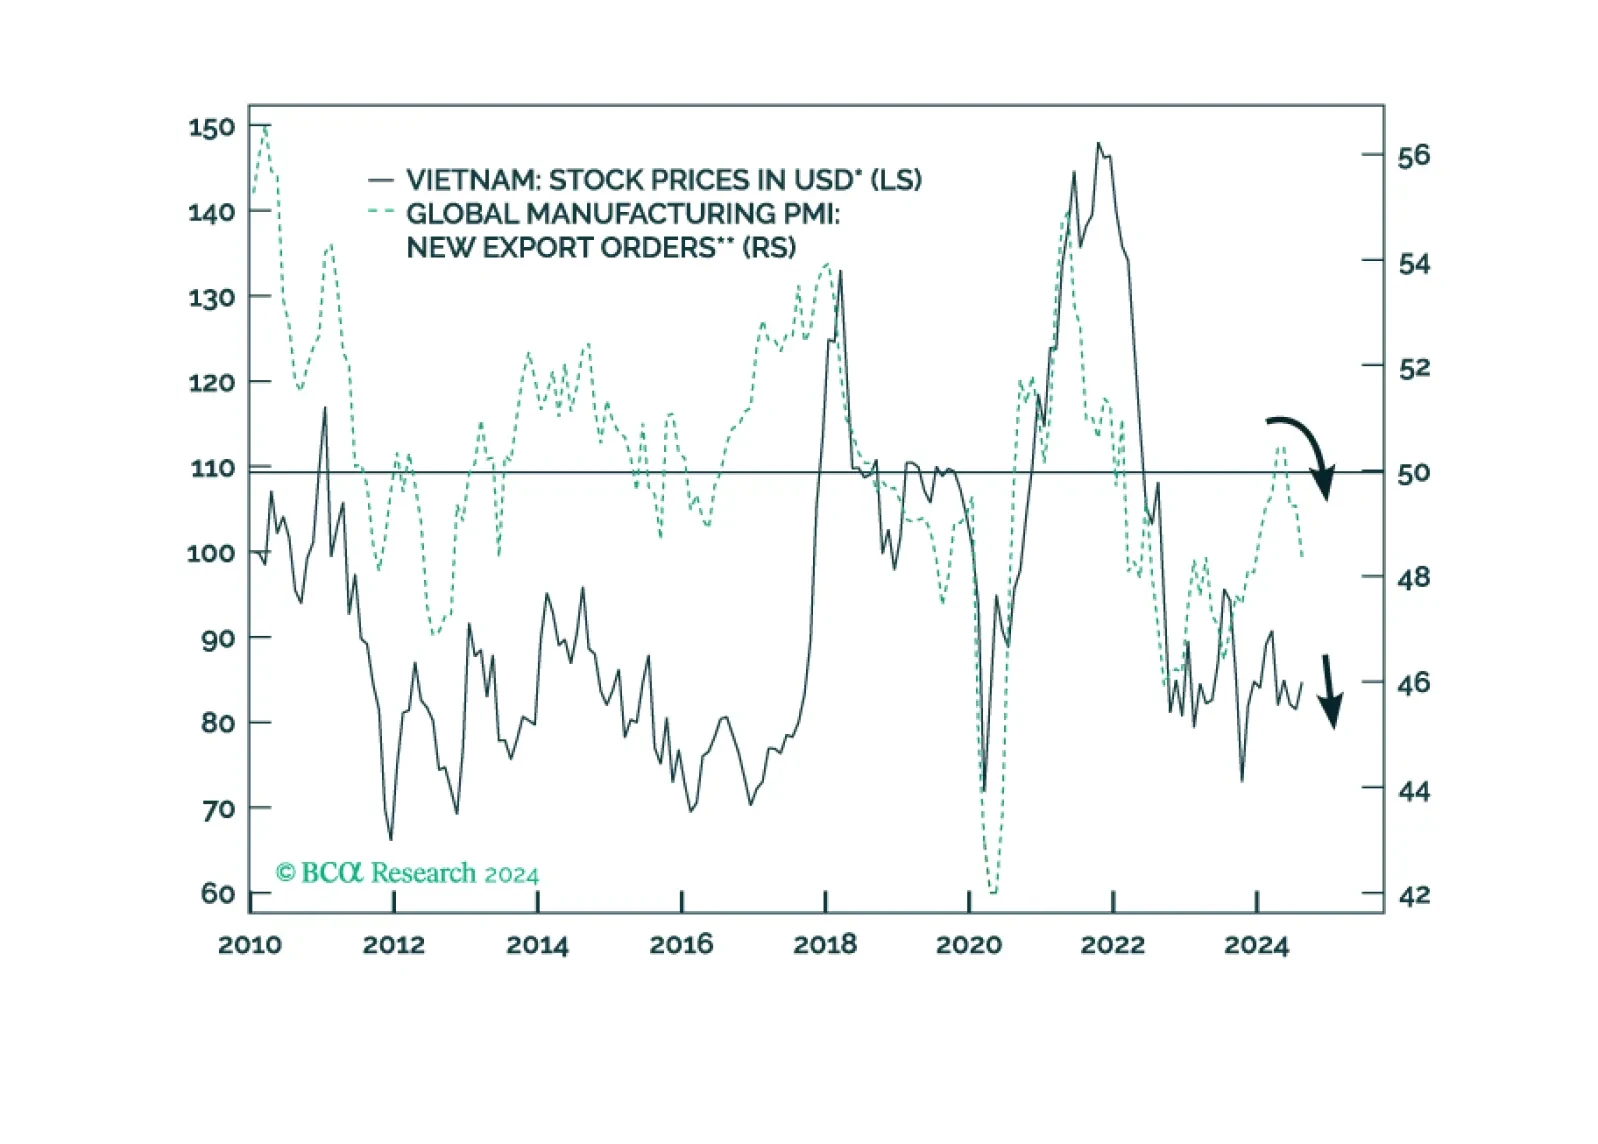
The Vietnamese economy is growing at a strong 7%. Why, then, are Vietnamese stocks struggling? Should investors expect a revival soon?