Latest from BCA Research
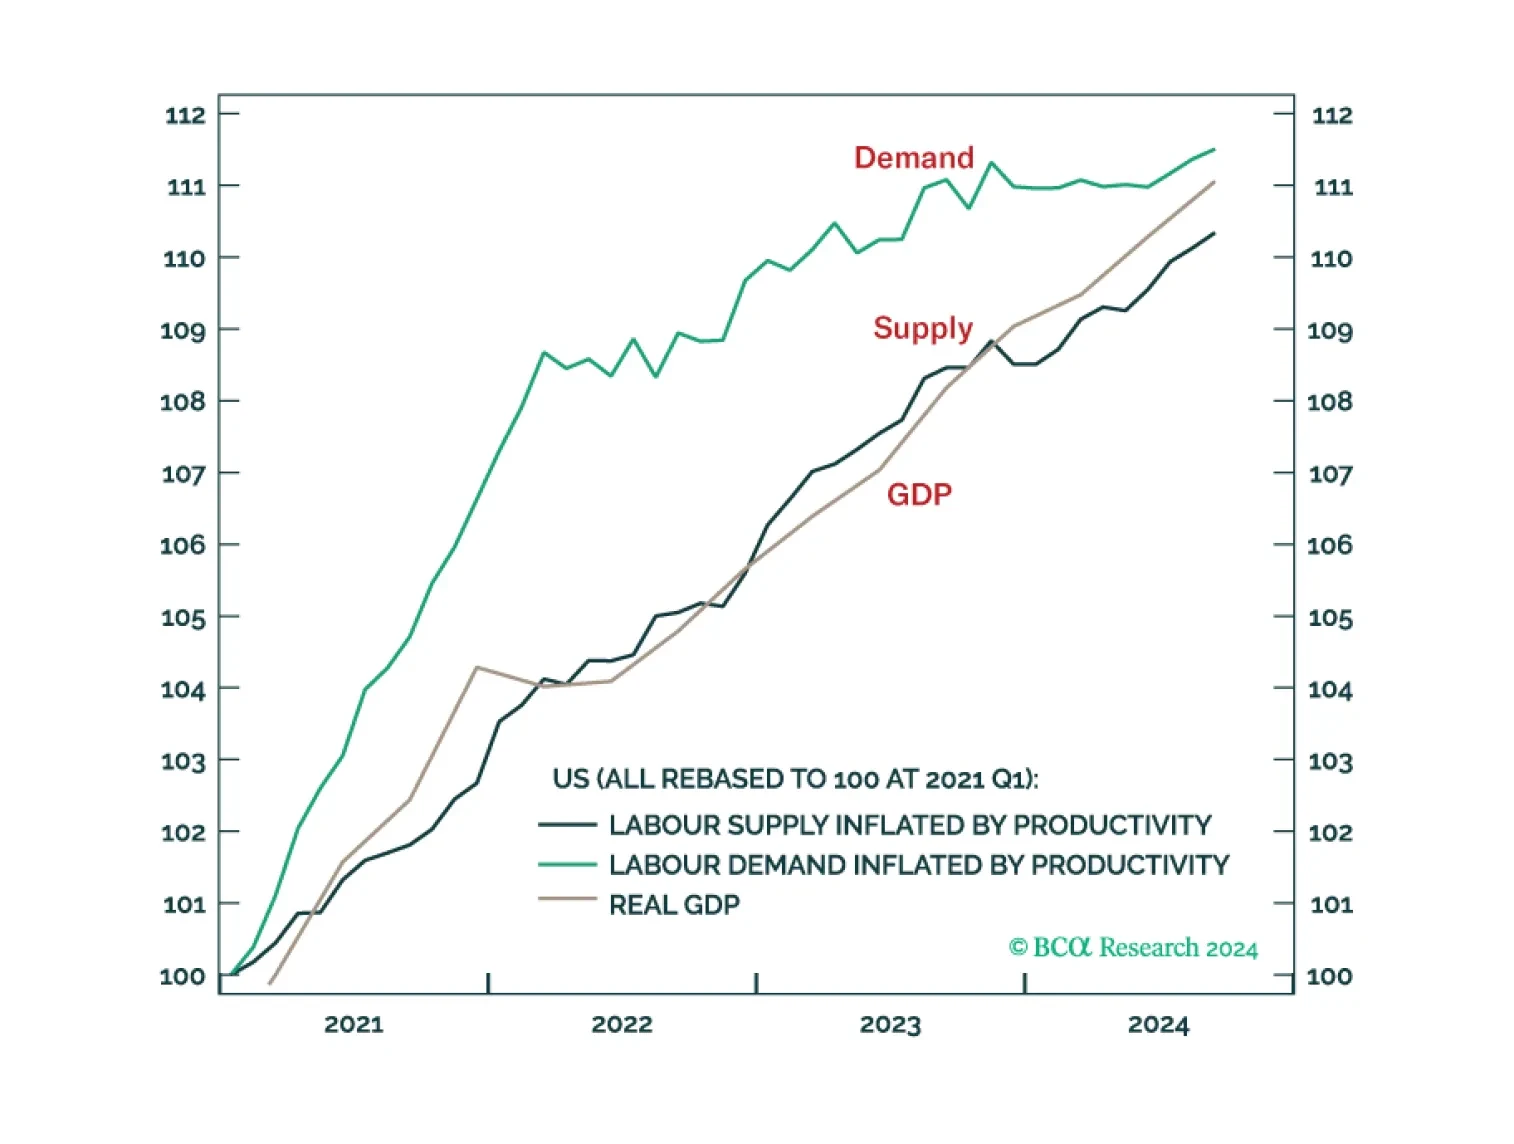
A Trump victory offers a buying opportunity for bonds; a Harris victory offers a selling opportunity for bonds. We explain why.

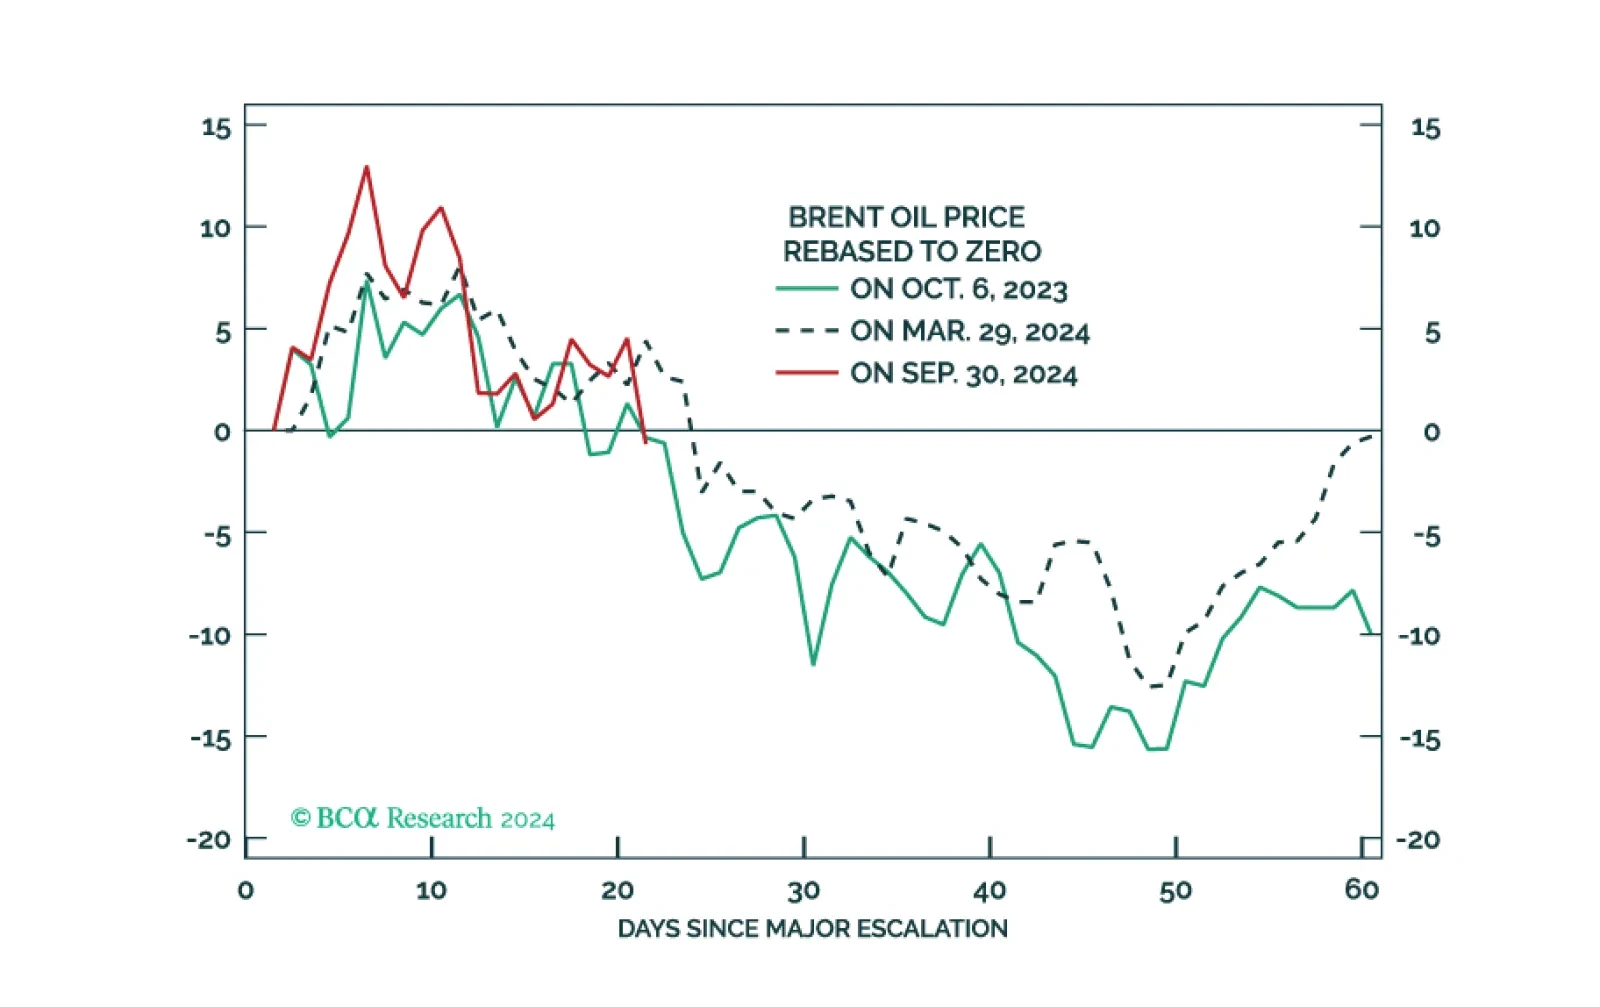
The global political system is destabilizing and the US will turn more hawkish in foreign policy, trade policy, or both, regardless of the election outcome. Tactically go long the dollar.
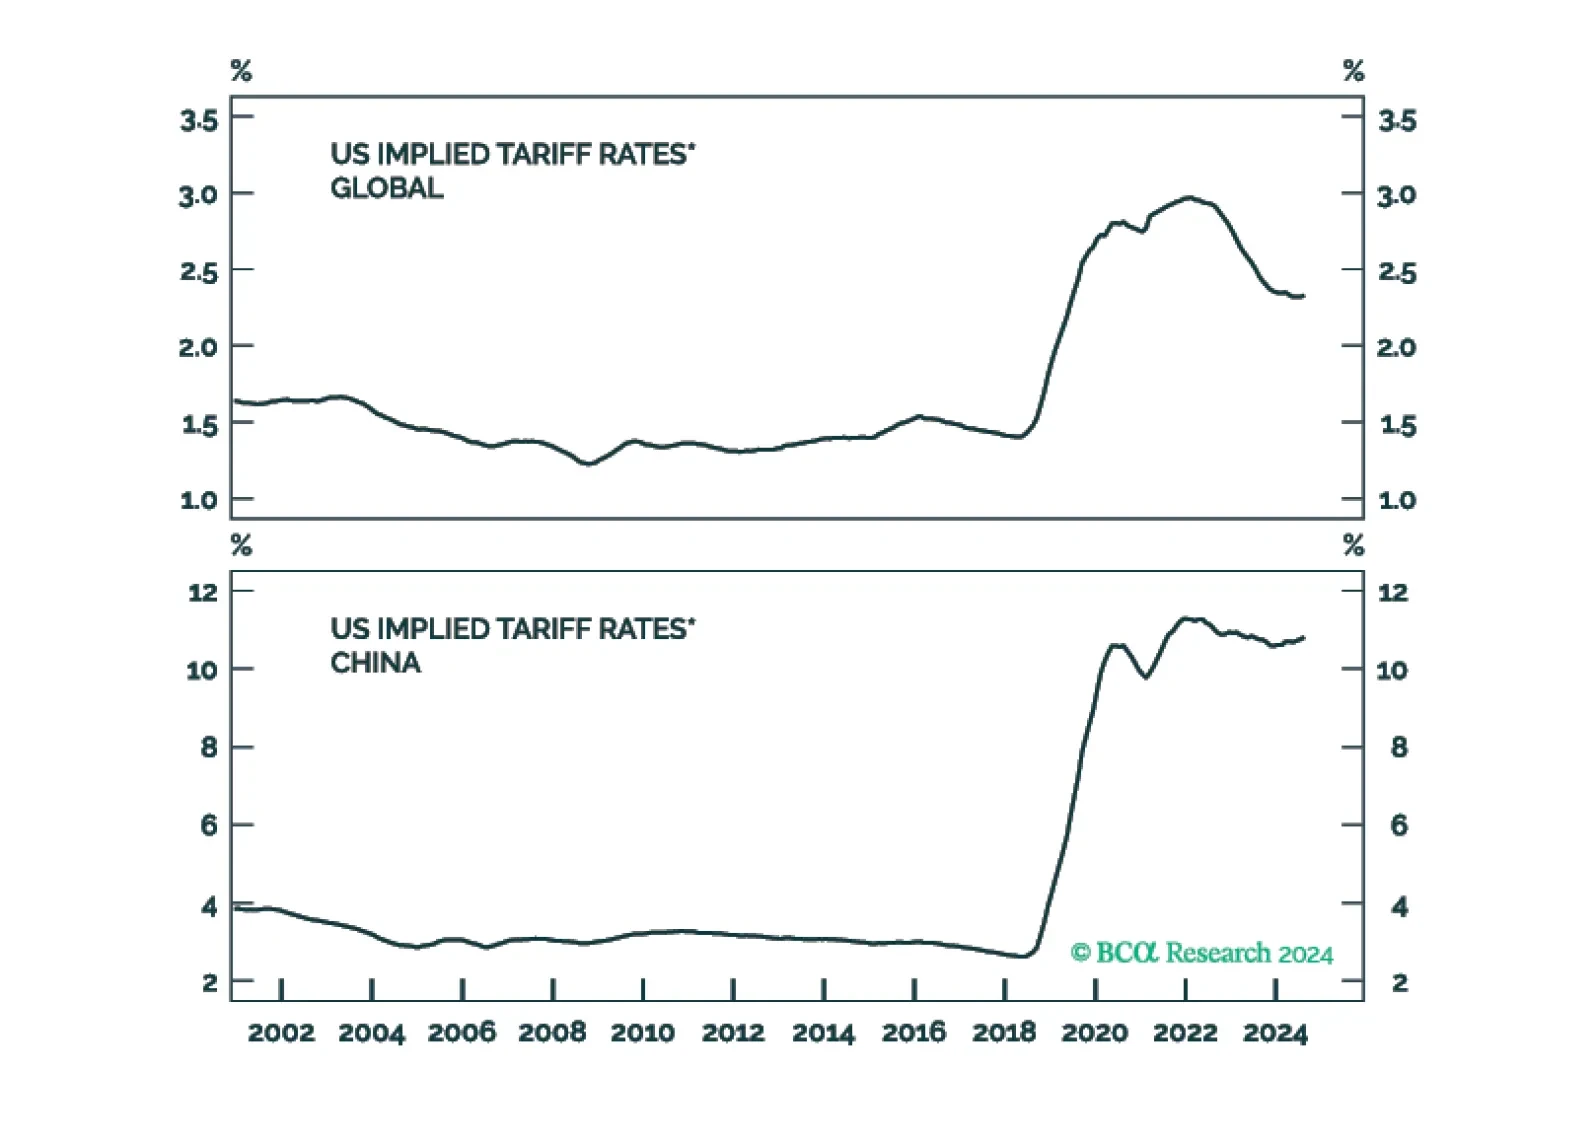
Back in 2016, there was widespread concern that if Donald Trump became president, he would start a trade war. As it turned out, Trump did become president and he did start a trade war, but the US economy continued growing anyway. In a study published in August 2019, the Congressional Budget Office concluded that Trump's tariffs reduced the level of US real GDP by 0.3% - not immaterial but not earth-shattering either.
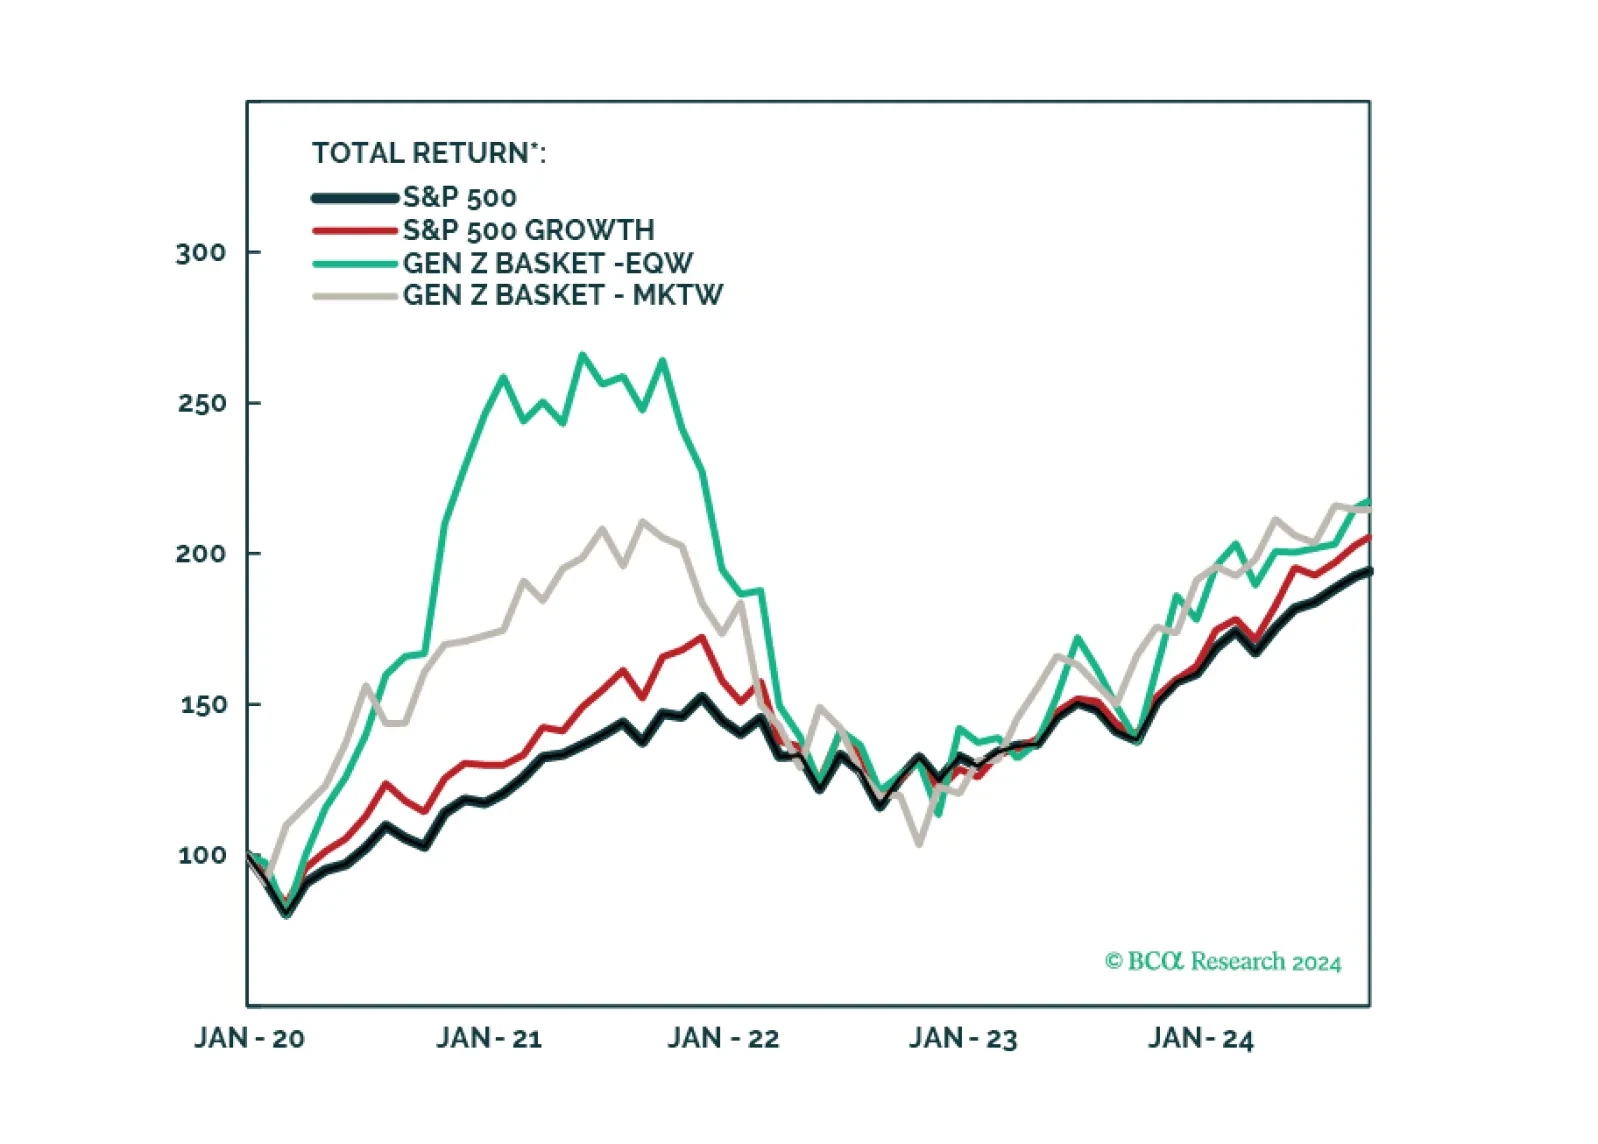
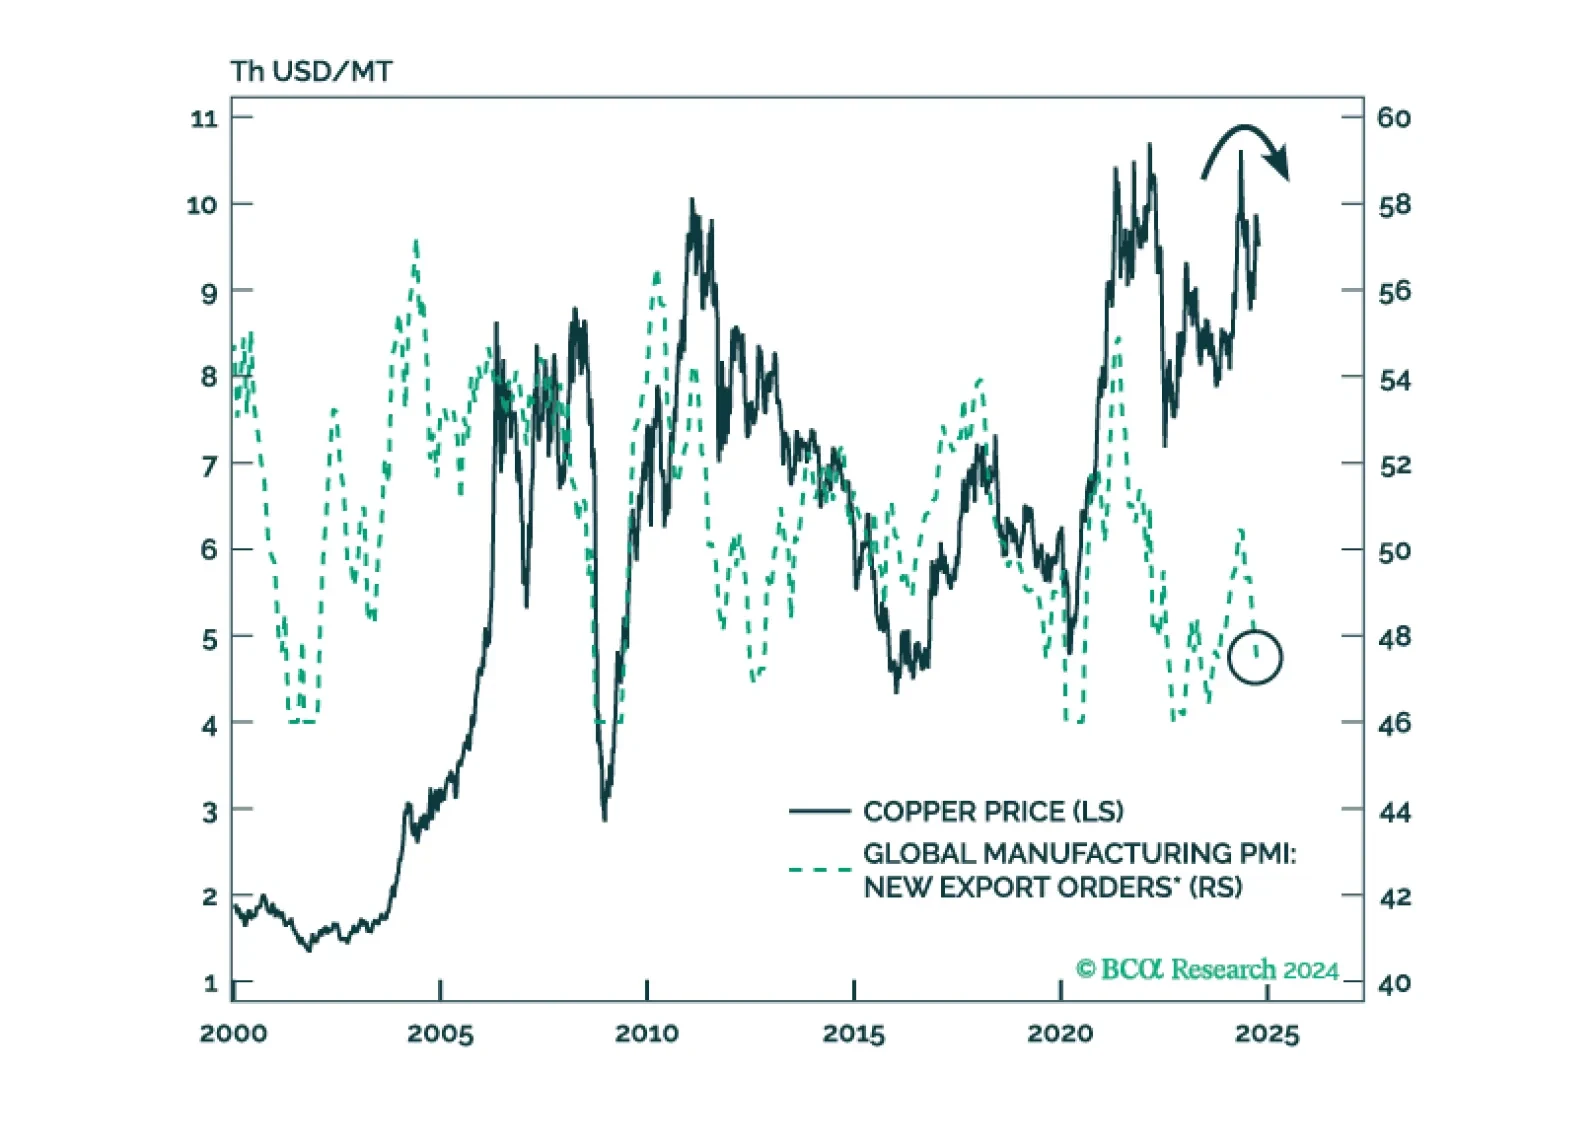
It is premature to bet on a copper demand acceleration over the coming months. Rather, copper prices are vulnerable to the downside. We believe that a better opportunity to turn bullish on copper prices and copper mining stocks will emerge in the coming six-to-nine months.
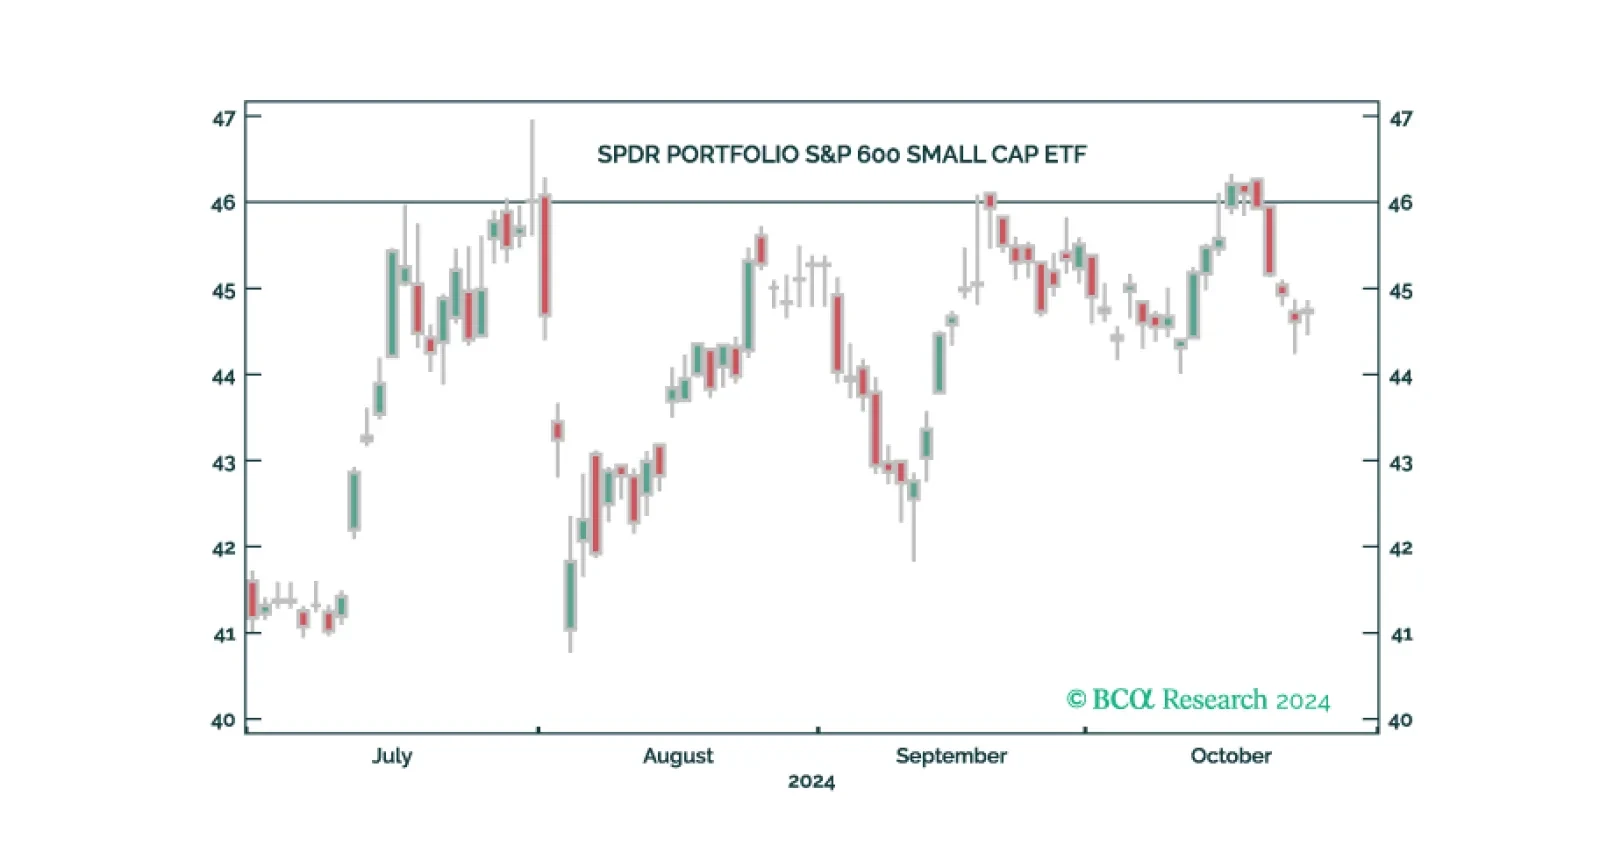
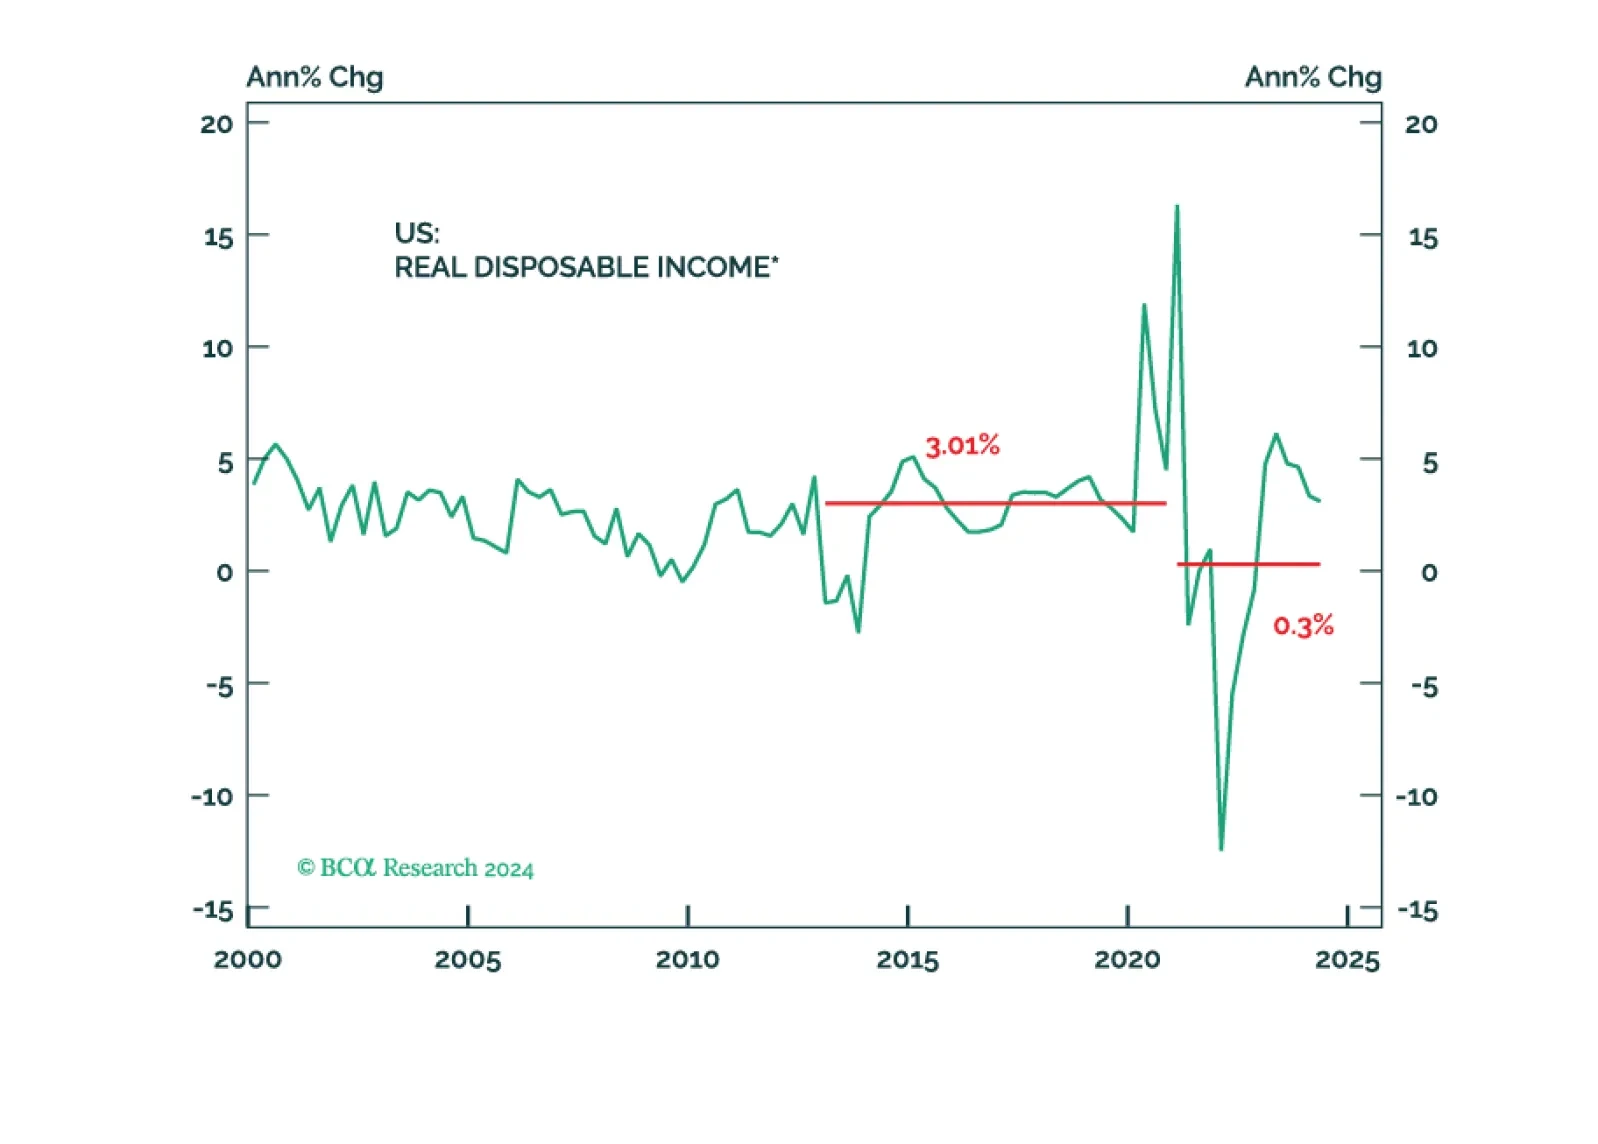
Middle-aged households have lagged youngish and older households since the pandemic and the 40-to-54 cohort is worse off than it was at the end of 2019. The fragmenting of the seemingly monolithic US consumer widens the path to a recession and we reiterate our defensive asset allocation recommendations.
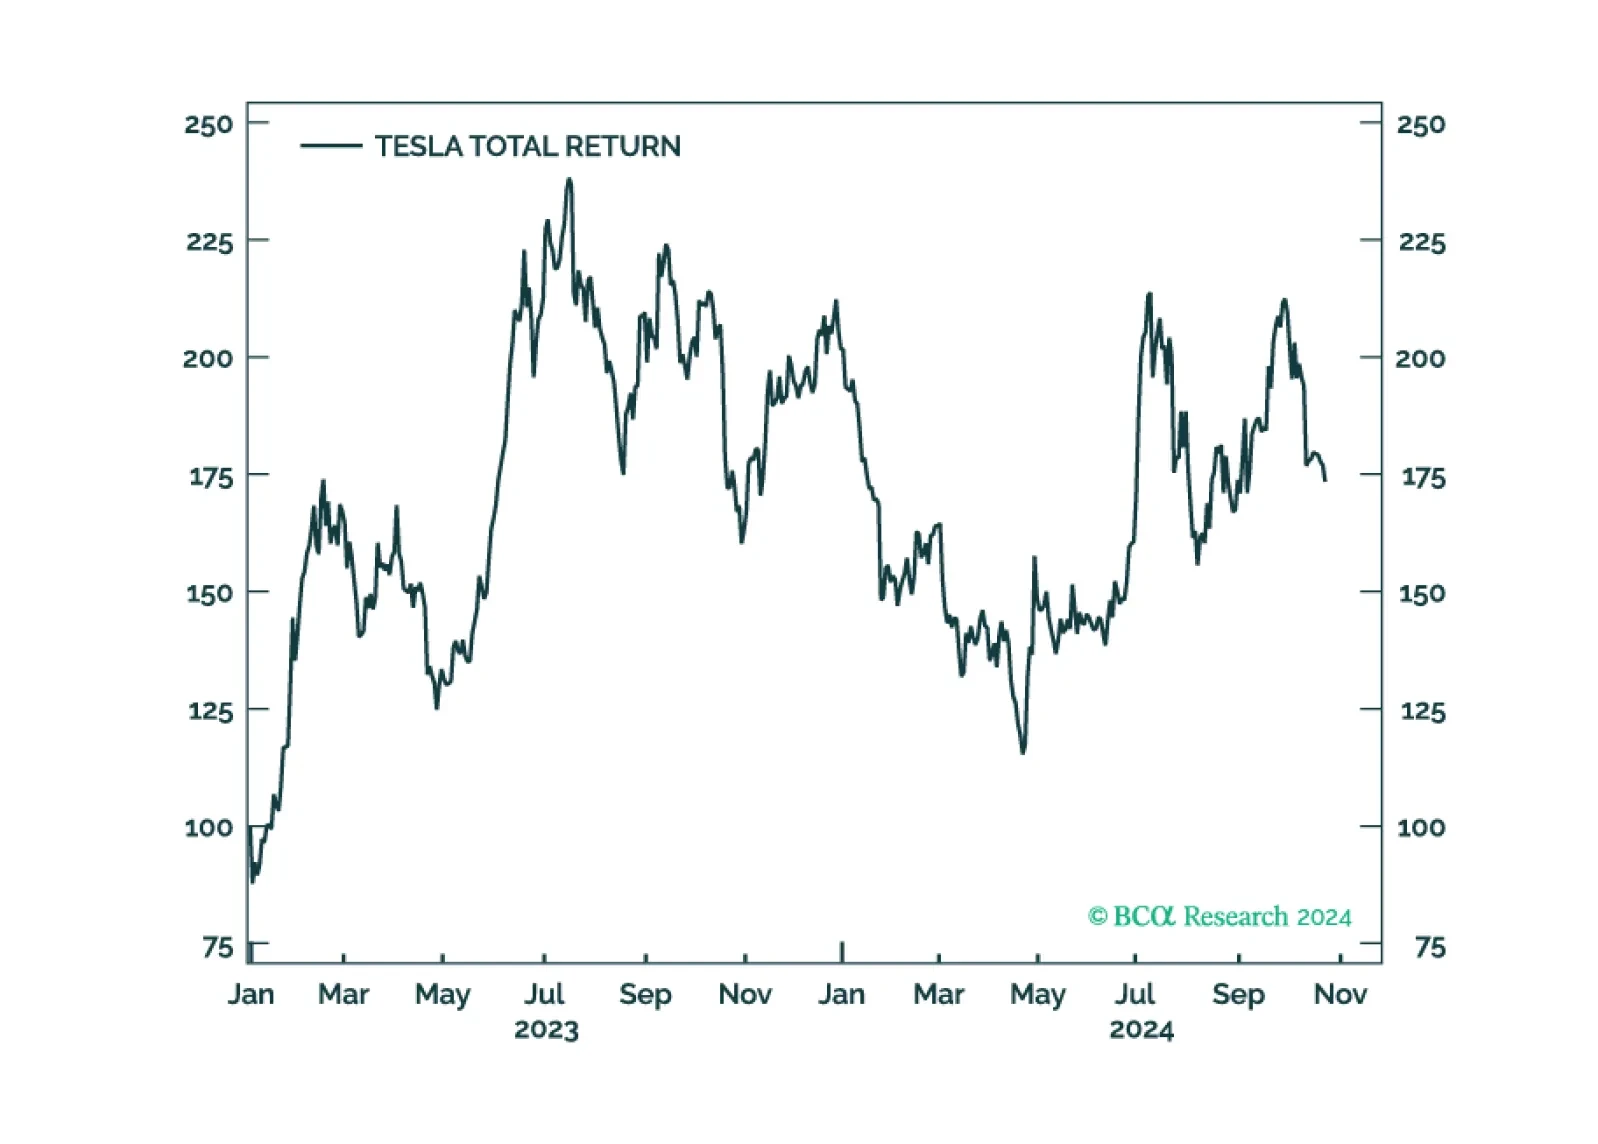
Upgrade Auto & Components Industry Group from an underweight to an overweight as it is dominated by Tesla, whose outlook has brightened.
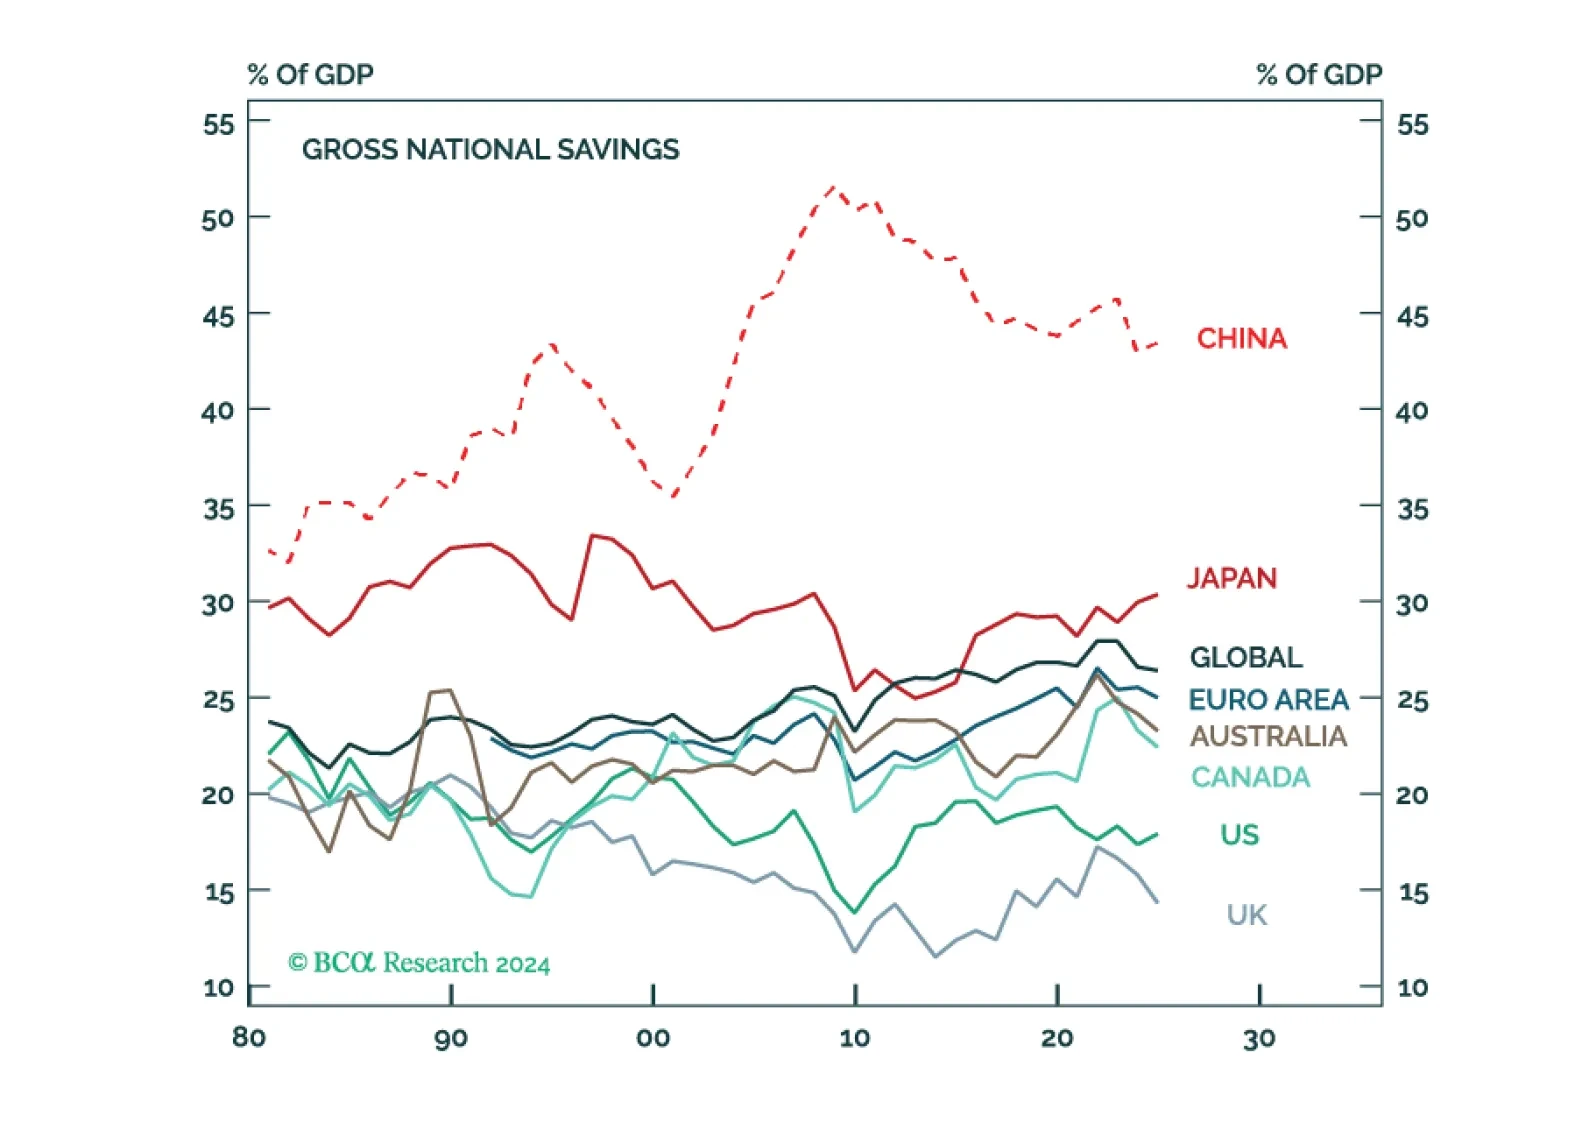
In this report, we discuss why we are lifting our US recession probability from 60% to 65% and explain why China’s latest stimulus announcements are welcome, but probably are “too little, too late.”