Latest from BCA Research
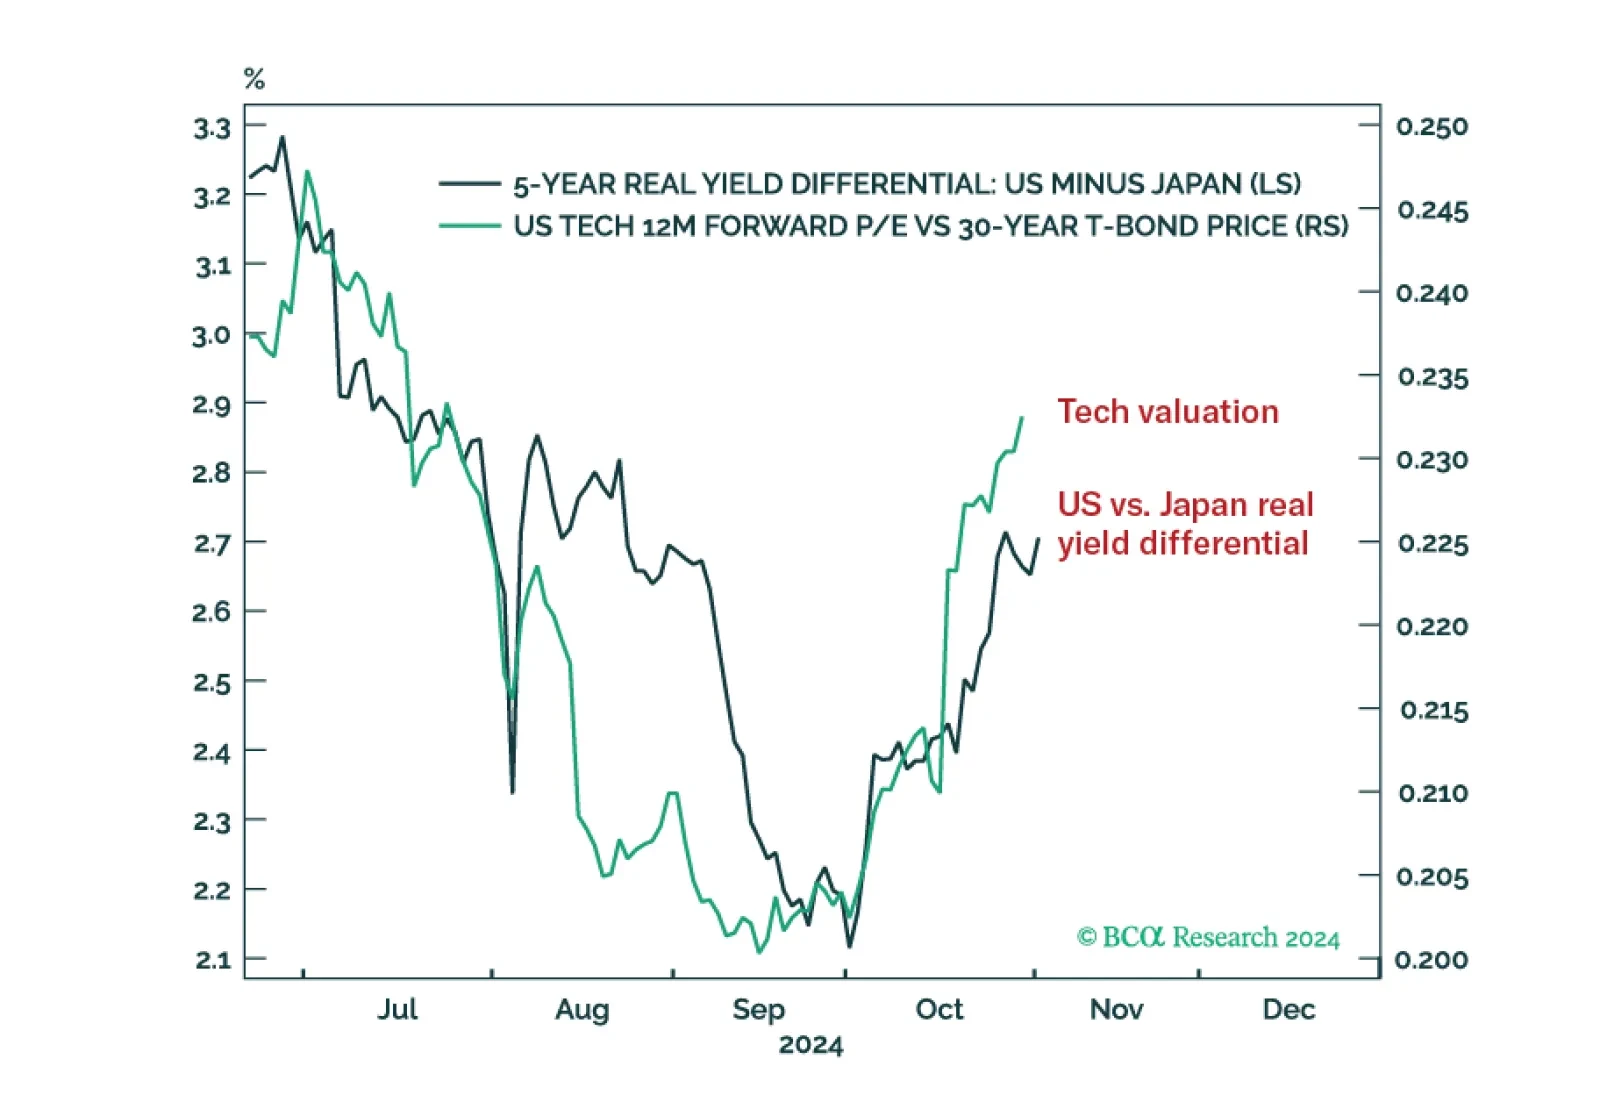
The most important transmission mechanism of a Trump presidency on the stock market will be via its impact on the US-Japan real yield differential. This is because Japan’s extreme negative real yield versus the US is the dominant source of global liquidity right now, and thereby the main driver of stock market valuation. In the short term therefore, higher US bond yields mean higher stock prices. The longer-term implications are more concerning though.
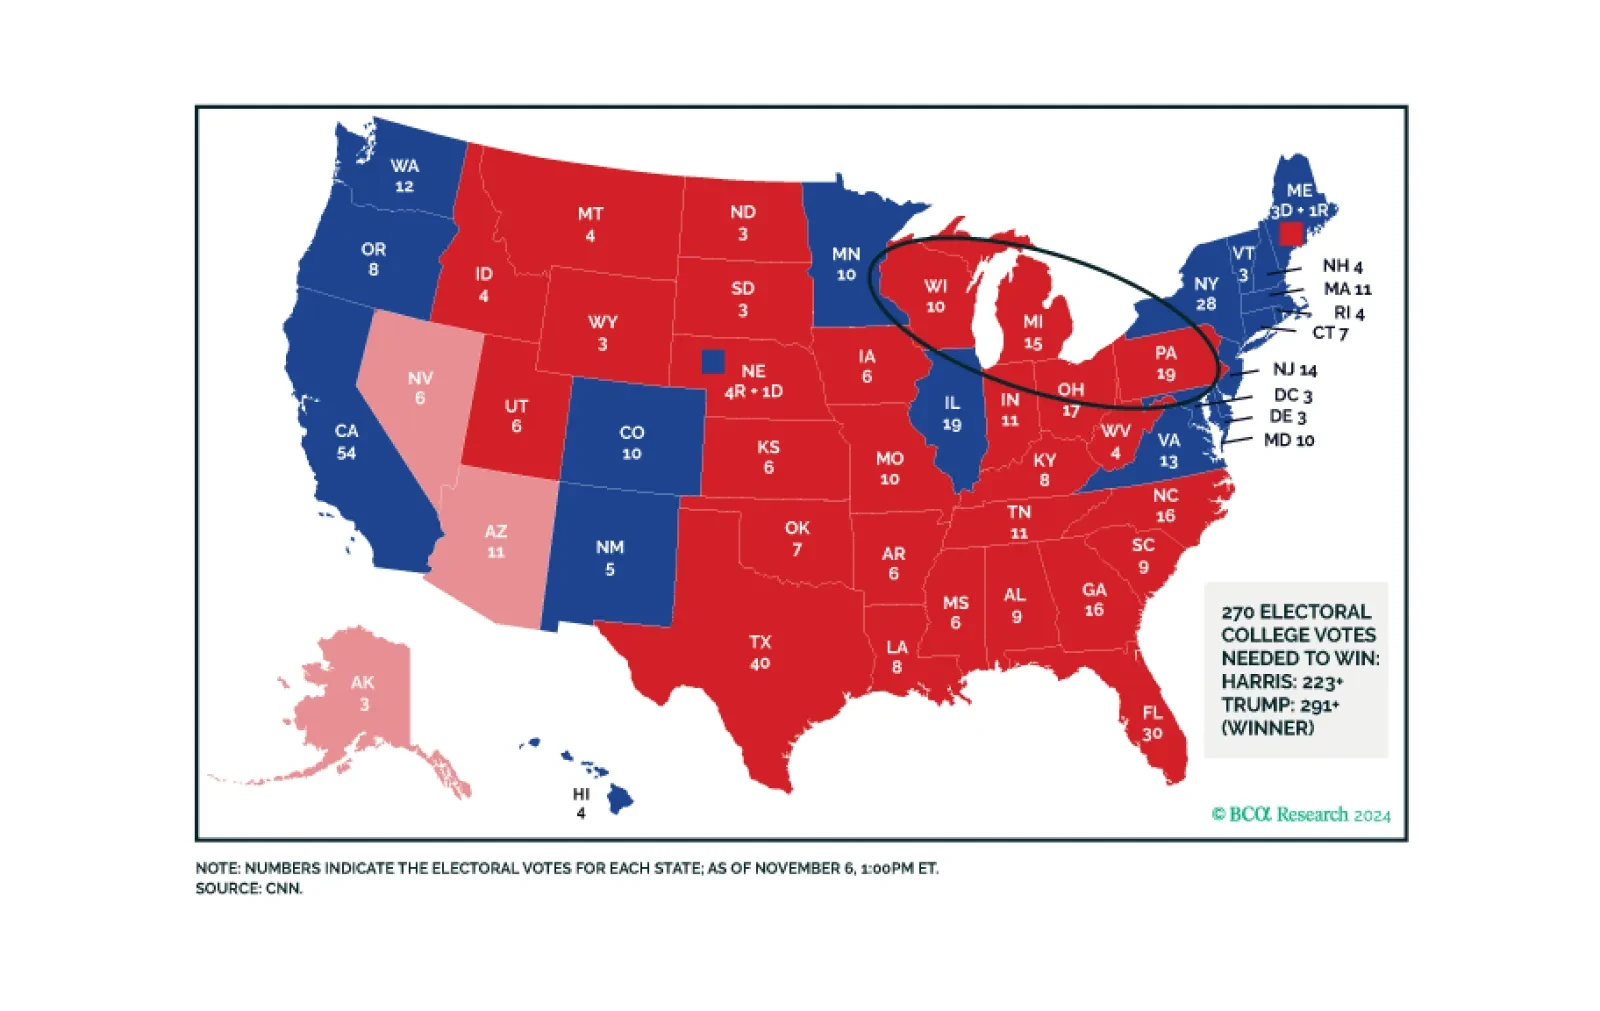
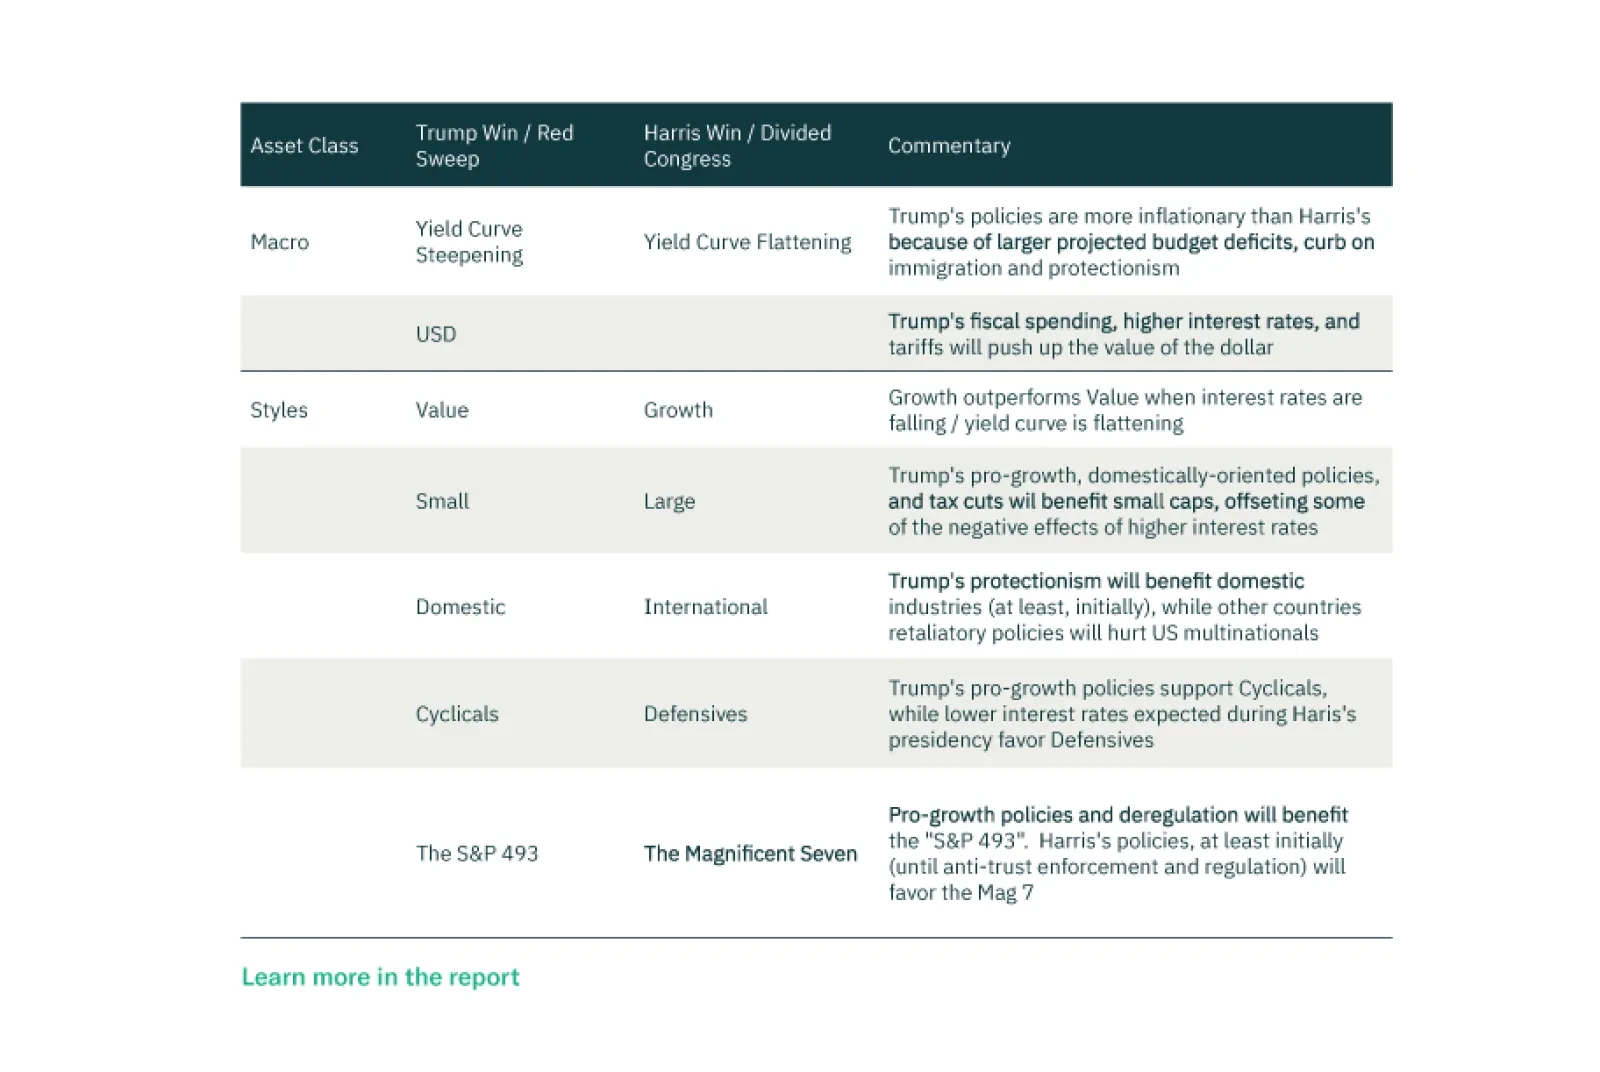
The most likely outcomes for the US elections are a “Red Sweep” and a “Blue Gridlock.” The following is a brief discussion of likely policies associated with each election outcome. We also present a post-election US Equities Cheat Sheet, in which we summarize winning trades for each scenario over the tactical investment horizon.
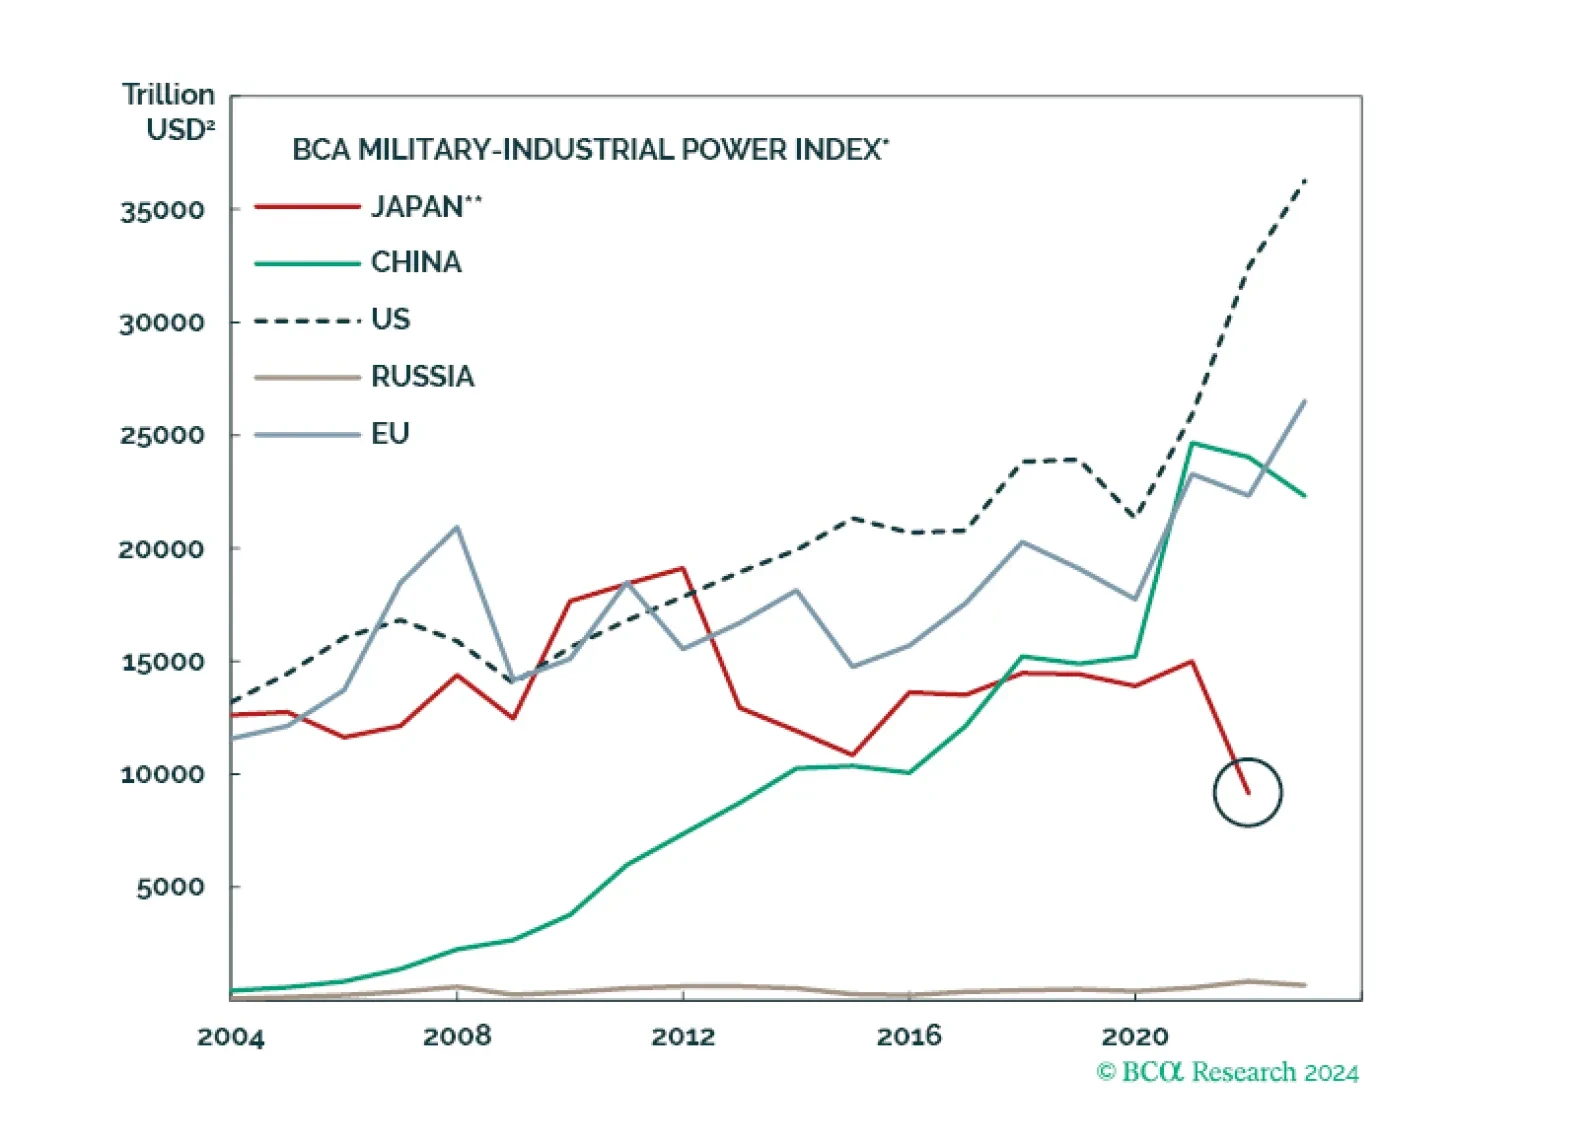
Over the next few months, Japan’s new government will ease fiscal policy, which will improve domestic demand on the margin. Monetary policy may tighten further in the short run but not too much over the long run. The geopolitical setting drives Japan into accommodative economic policy.
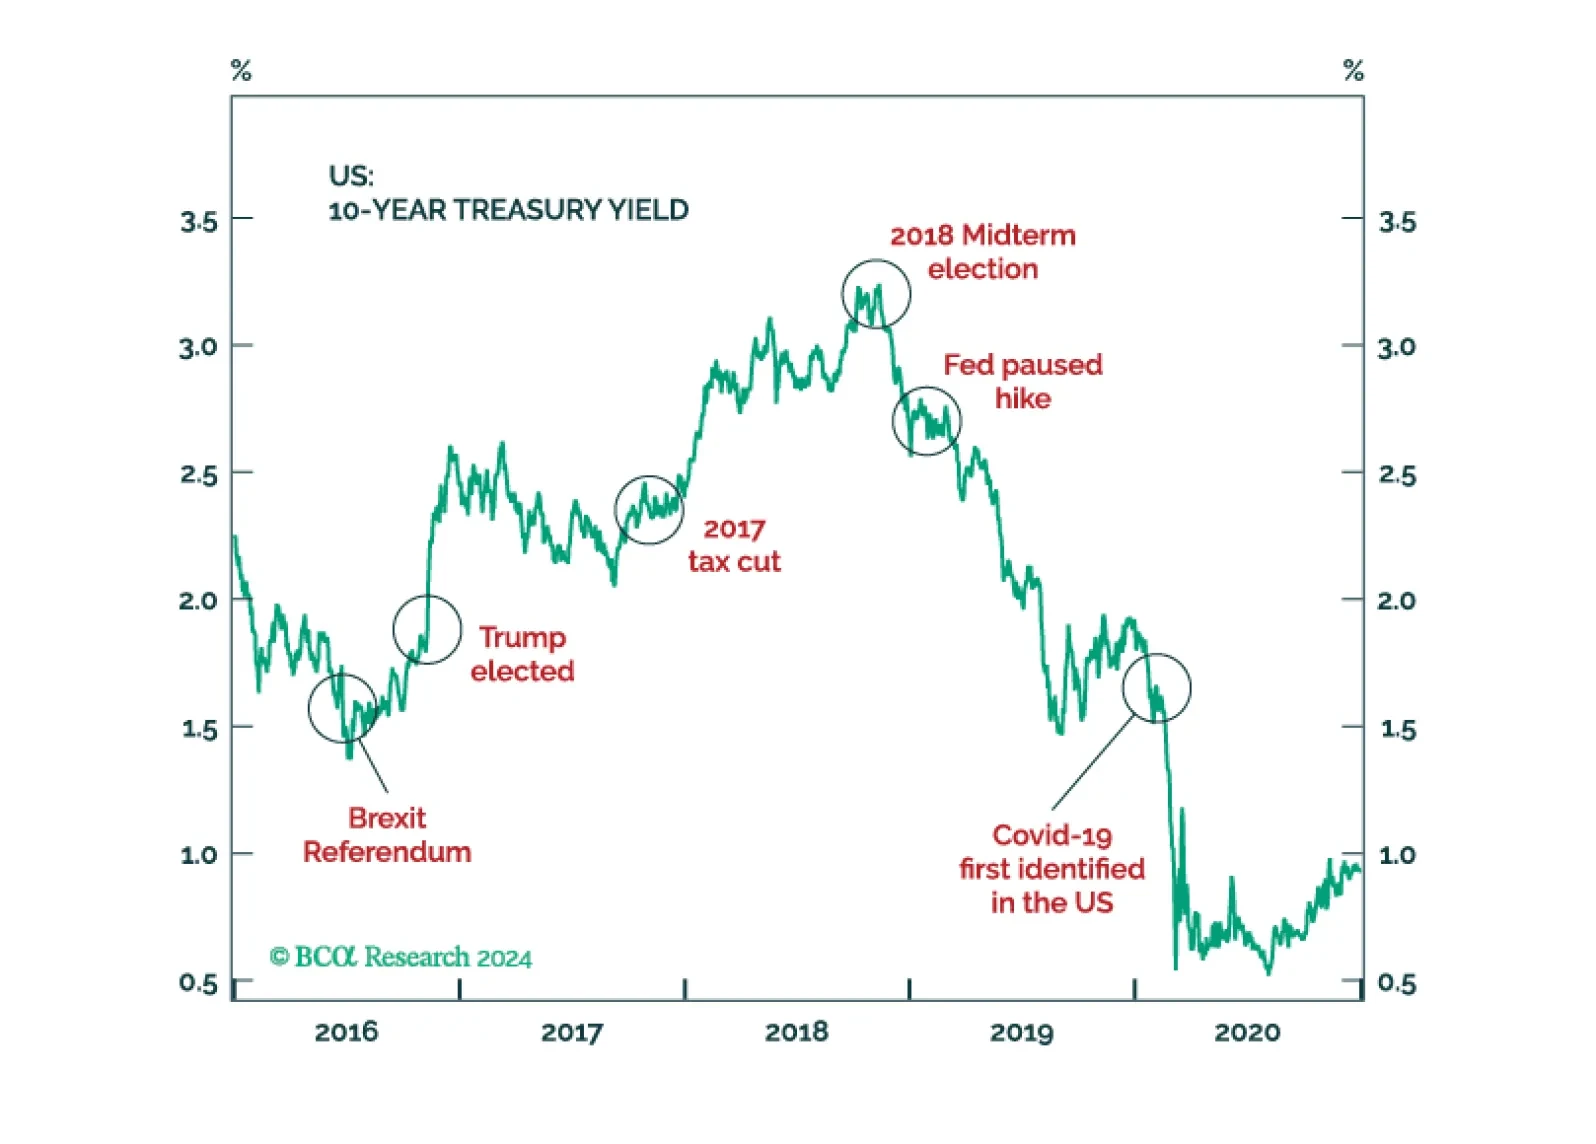
The Election Day is finally upon us. No, there is no final “silver bullet” forecast contained in this email. Just our long-term forecast of how the election will, no matter who wins, impact the markets.
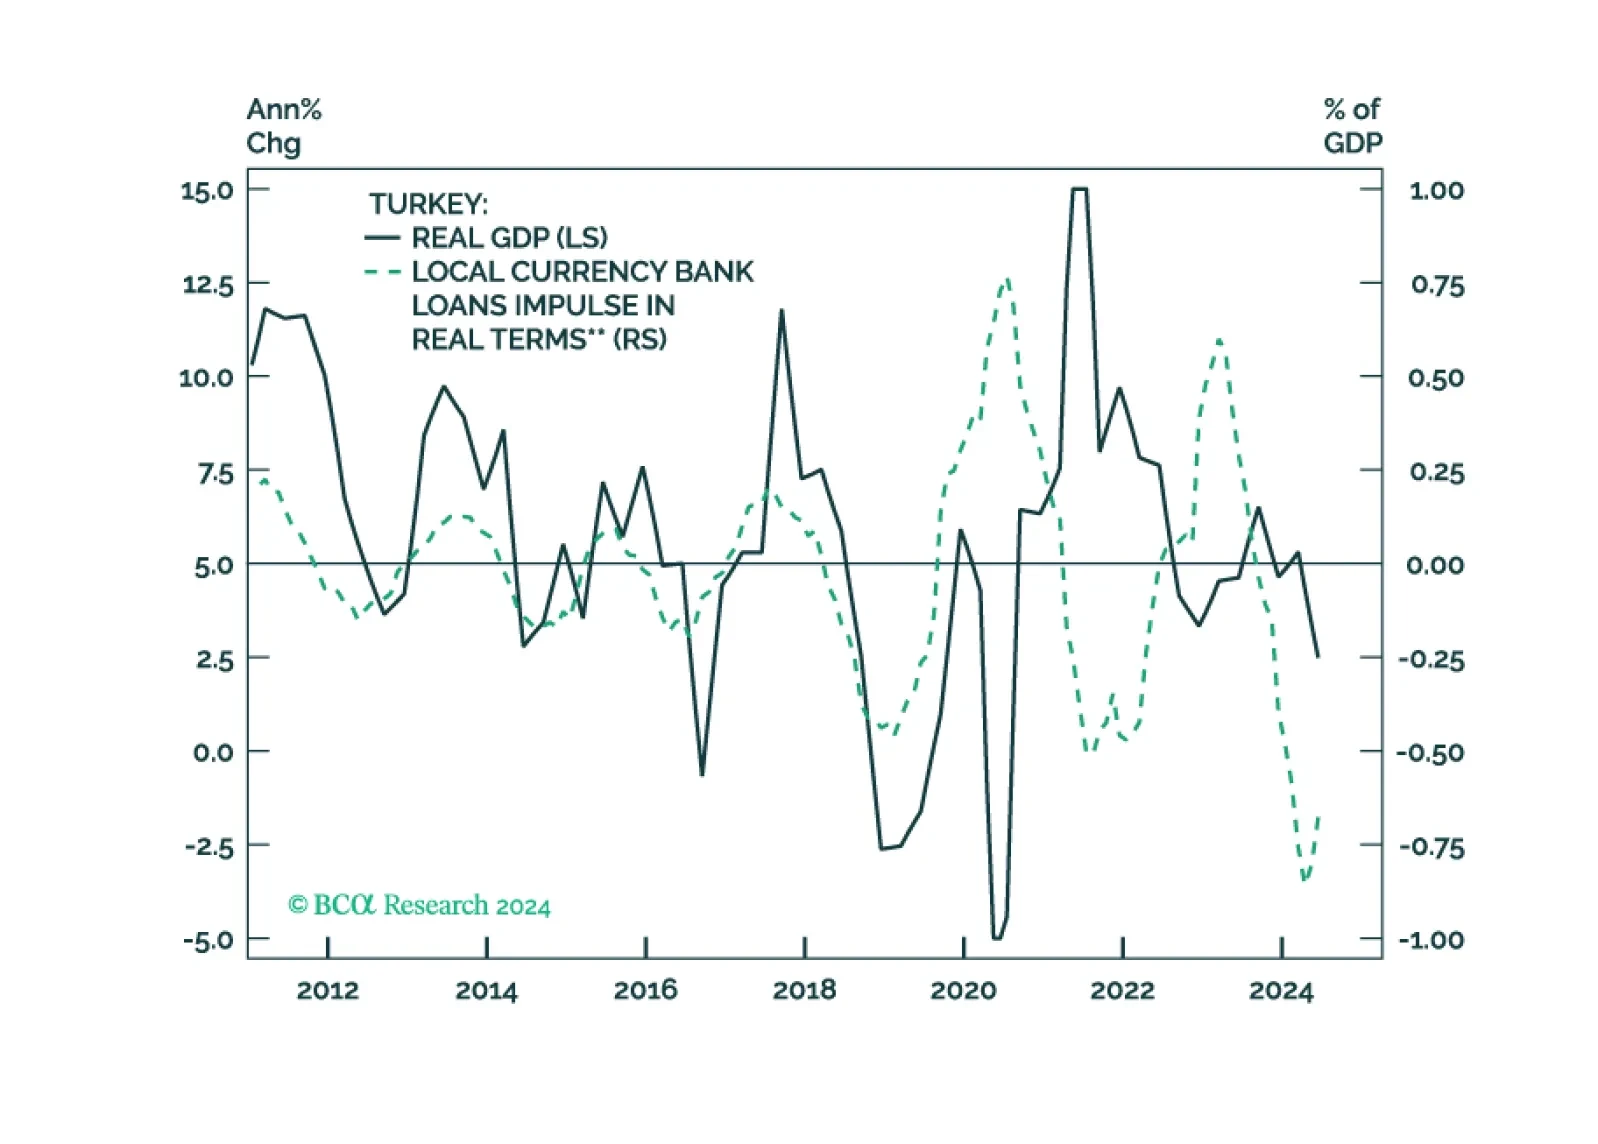
Turkey has a path toward sustained disinflation. But that will require tight macro policies for an extended period. The question is, will the authorities tolerate the consequent growth slowdown, even a recession, and surging unemployment, as the necessary cost to break the back of inflation?
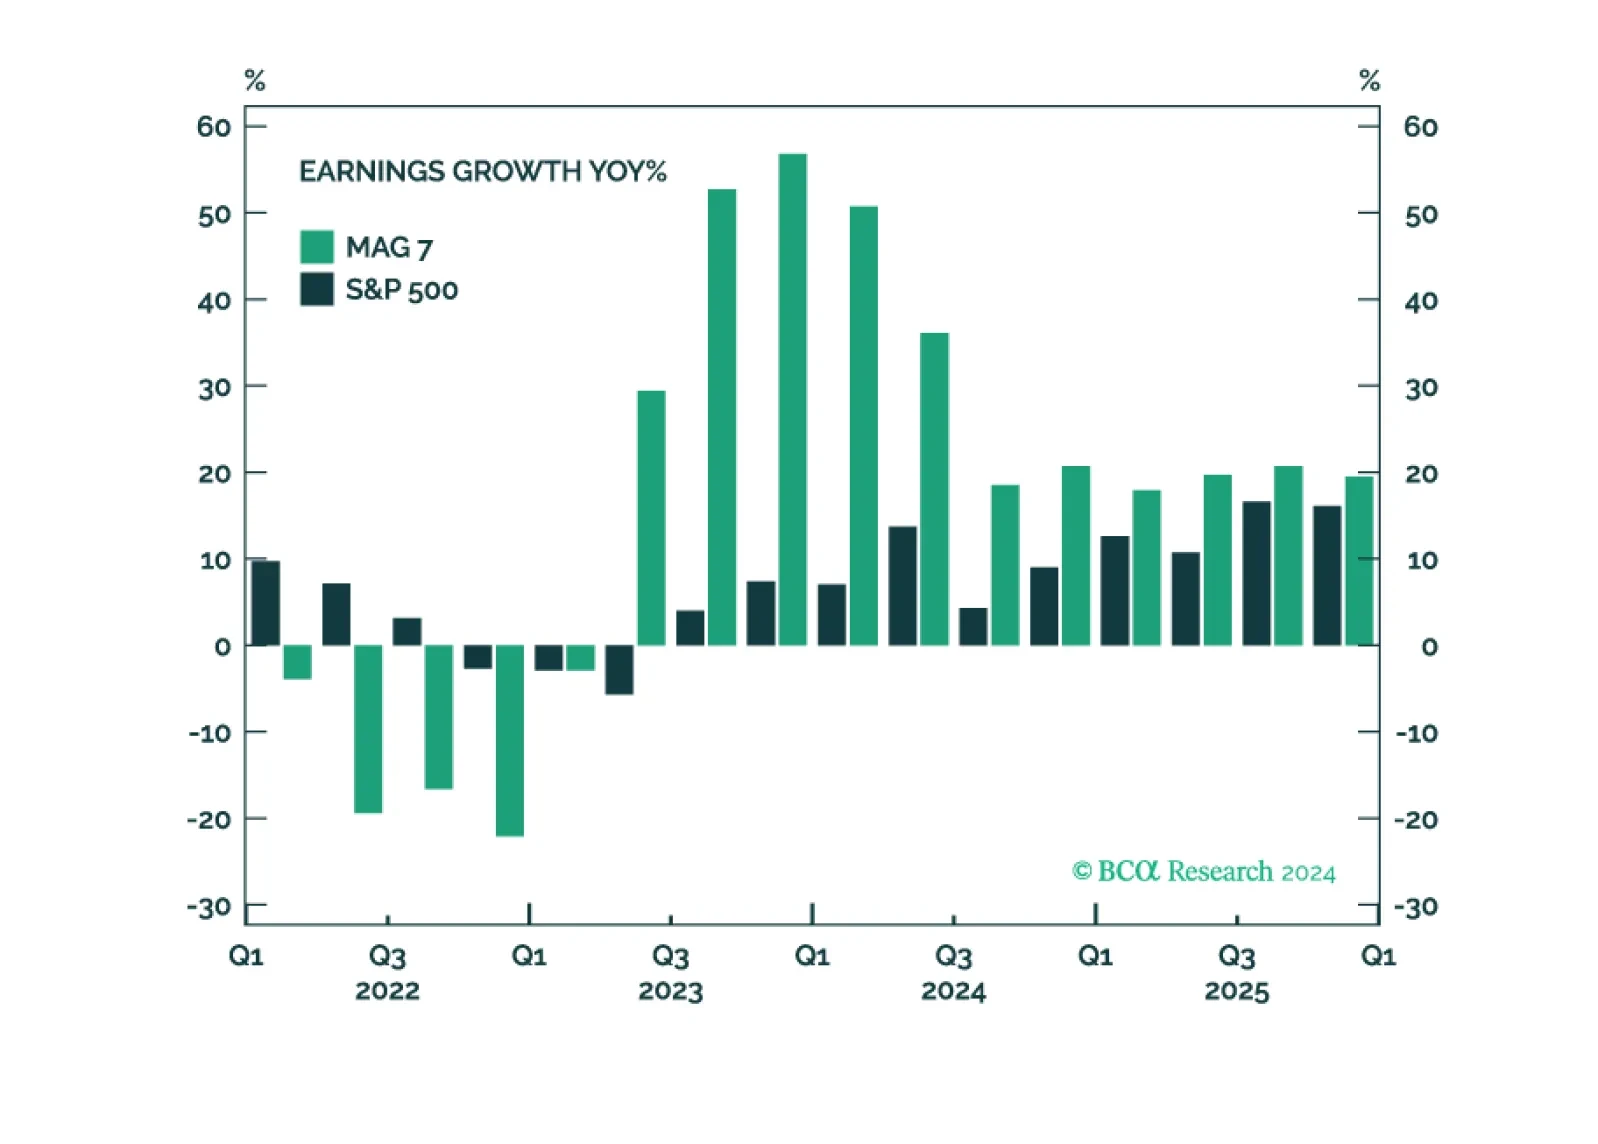
This week, we are sending you a sector chart pack. In the front section of this publication, we briefly review October's performance and then switch our attention to the earnings season and outlook for the Magnificent Seven.
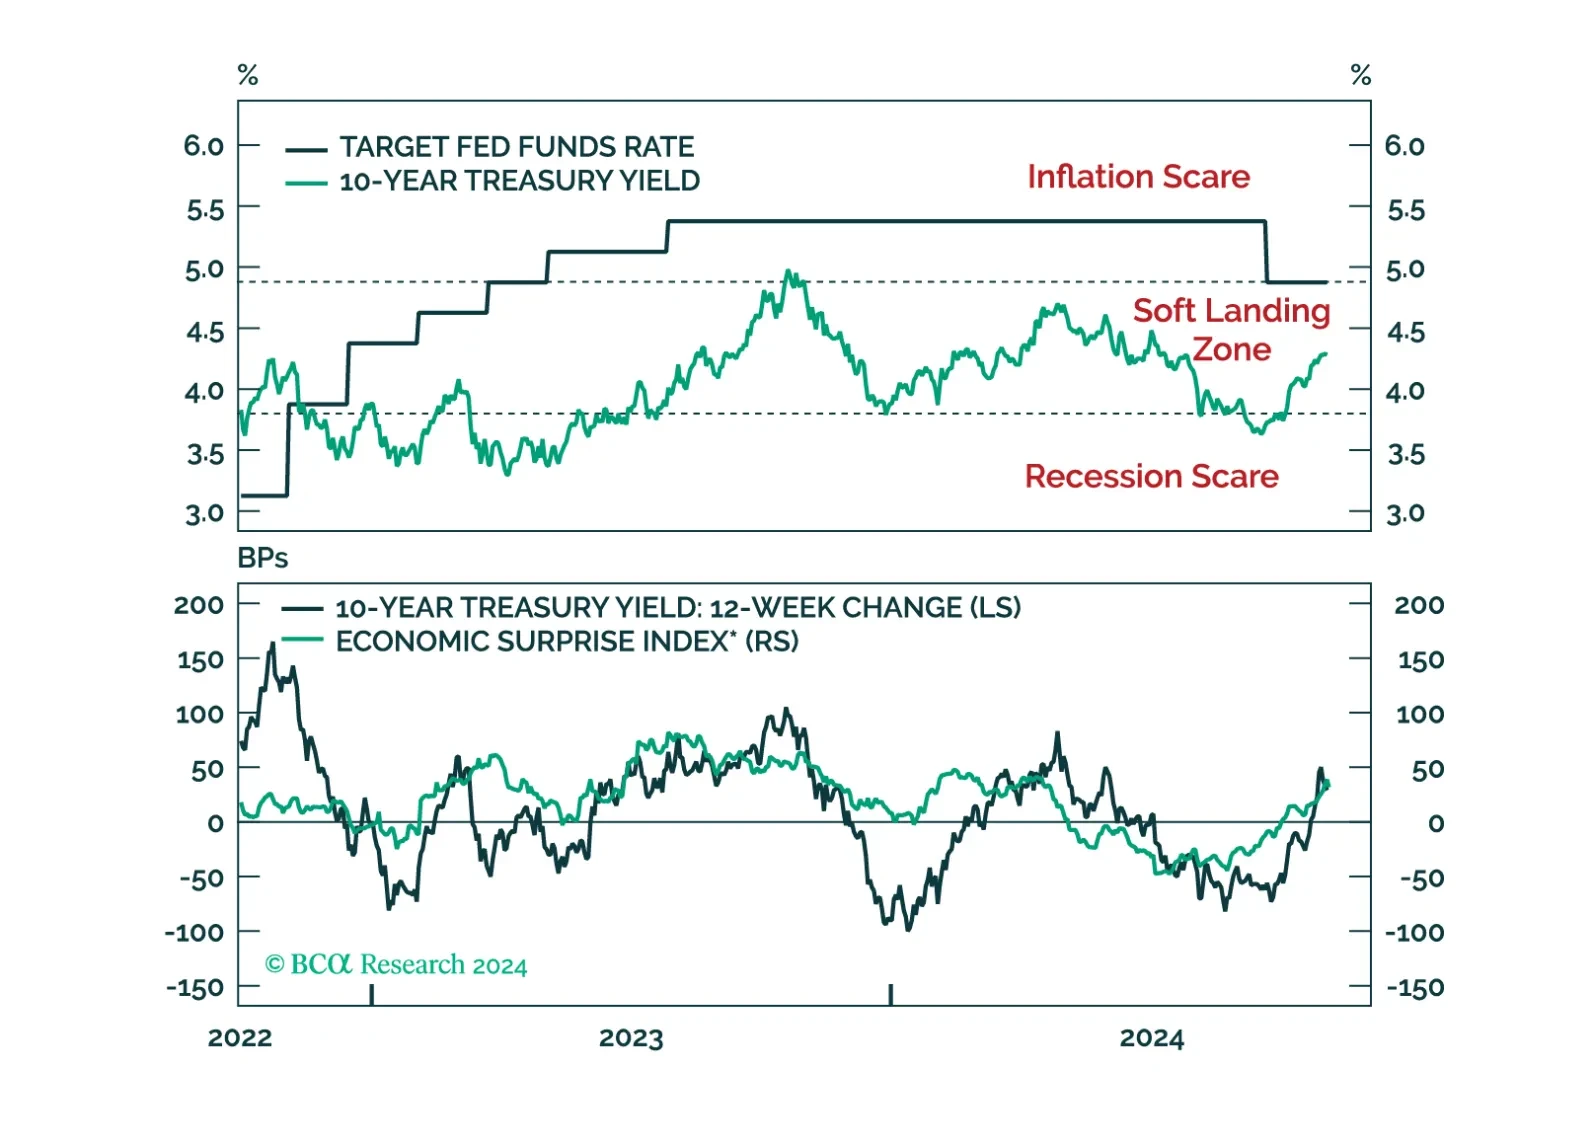
A reaction to this morning’s employment report and a preview of the potential bond market implications of next week’s US election and FOMC meeting.
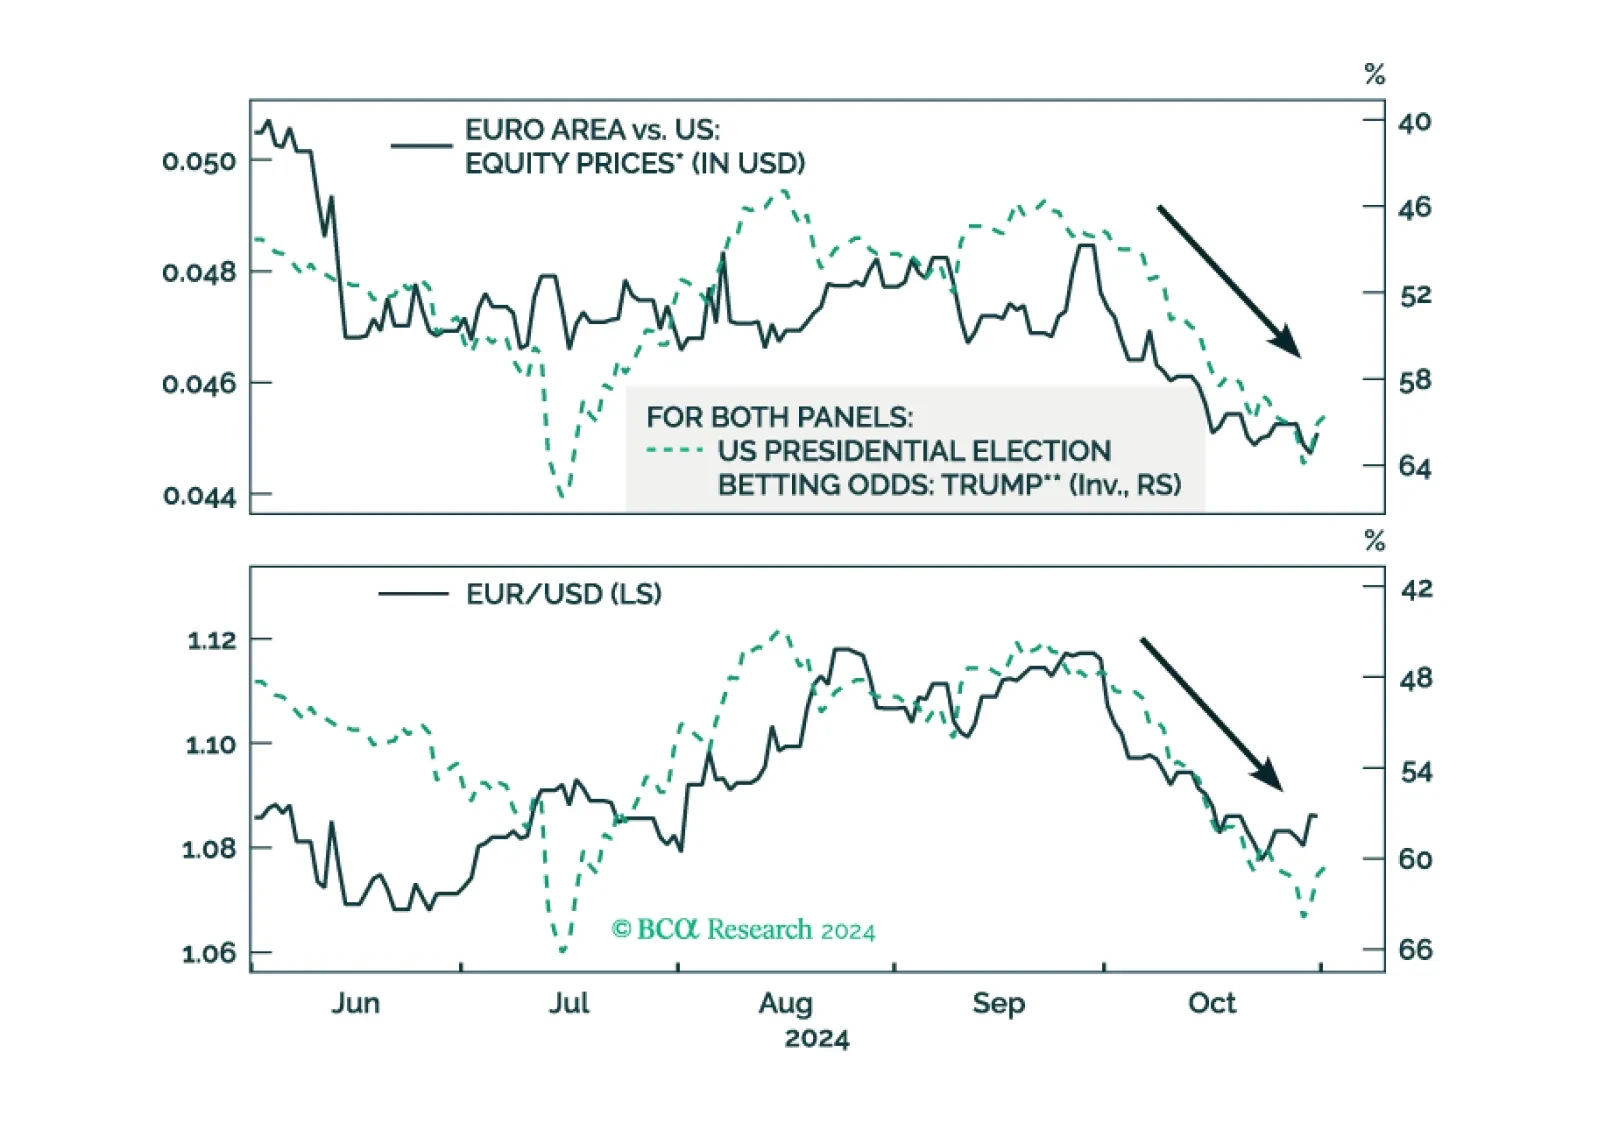
As the odds of a Trump victory rise, European assets underperform US ones. What would be the immediate impact of a Trump victory on European stocks?

Can Powell achieve a soft landing? There are some indications he is doing it. We examine why our negative stance was wrong and analyze the four growth engines that kept recession at bay. Half of these forces remain while the other half have run out of juice. While this might be enough to keep the economy going, we maintain our defensive positioning. Equities have priced a very benign outcome. Meanwhile, rising rates in anticipation of a Trump win are pushing the economy away from the soft-landing path. We hedge the possibility of further upside in yields in case Trump gets elected by downgrading duration to neutral.