Skip to main content

Latest from BCA Research
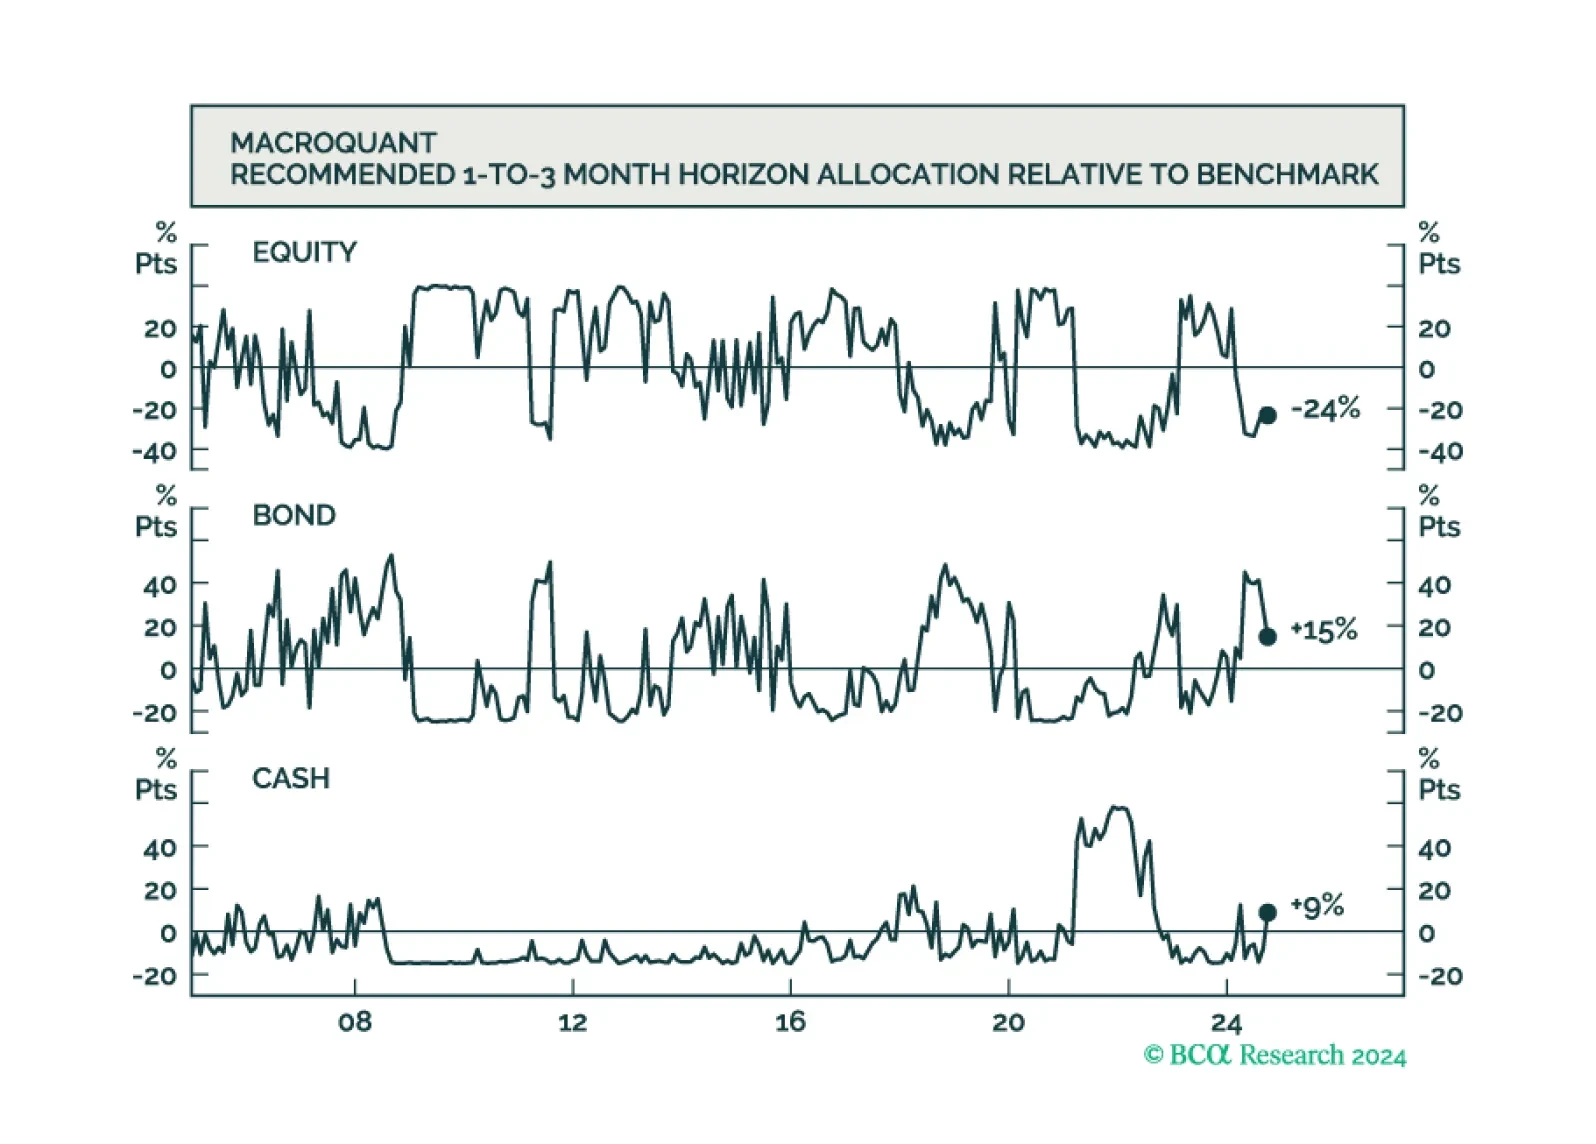
MacroQuant expects global equities to weaken in November. As such, the model recommends underweighting equities and overweighting bonds and cash.
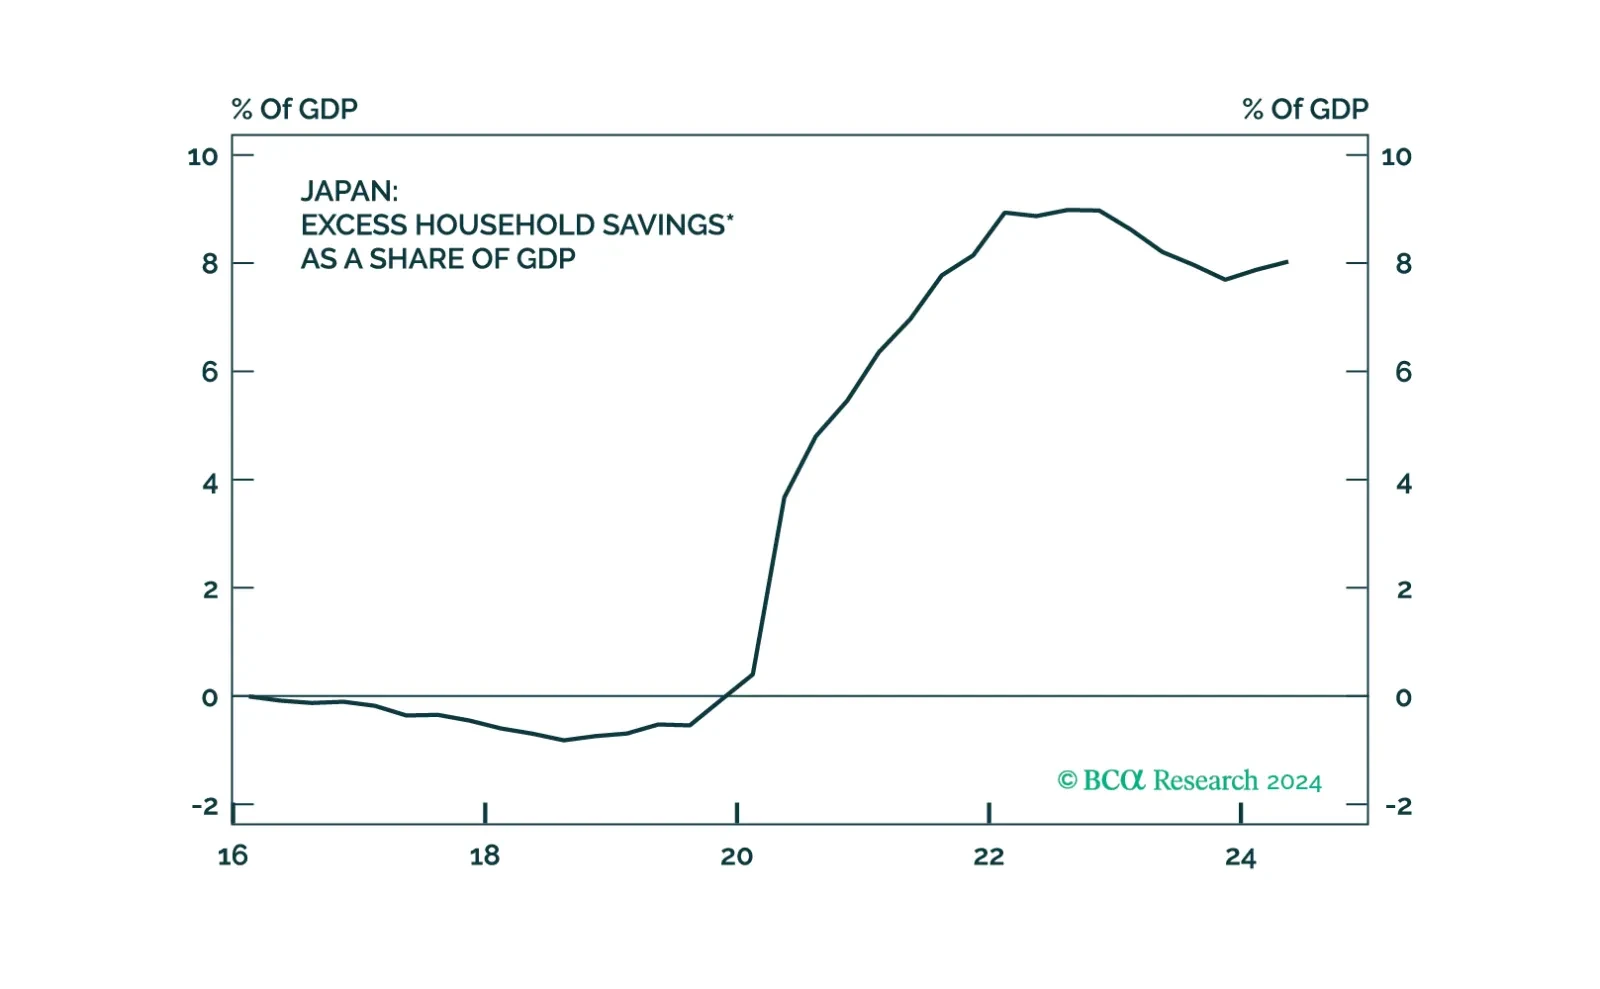
The latest Bank of Japan meeting did not alter our high-conviction views of being long the yen and underweight JGBs.
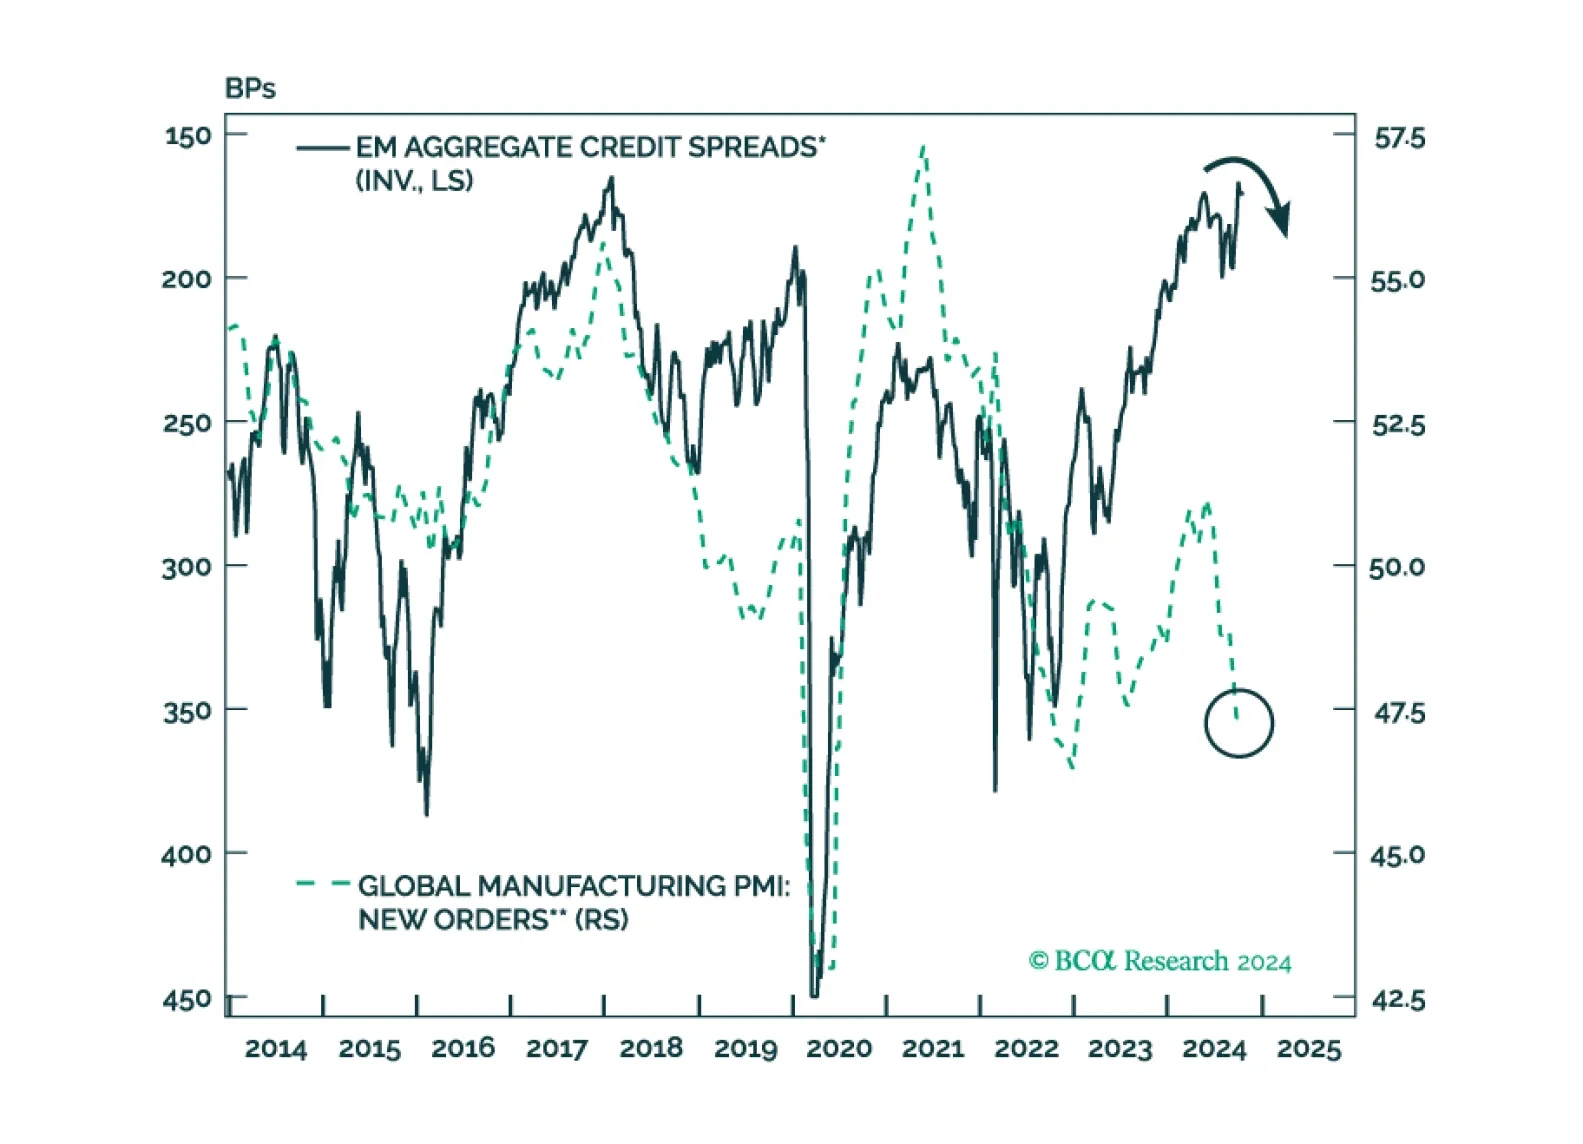
Special Report EM credit markets have recently defied the selloffs in EM equities, currencies, local currency bonds, and commodity prices. Such a decoupling is unusual. Resilient US growth and Fed easing are not sufficient to justify very low EM credit spreads.
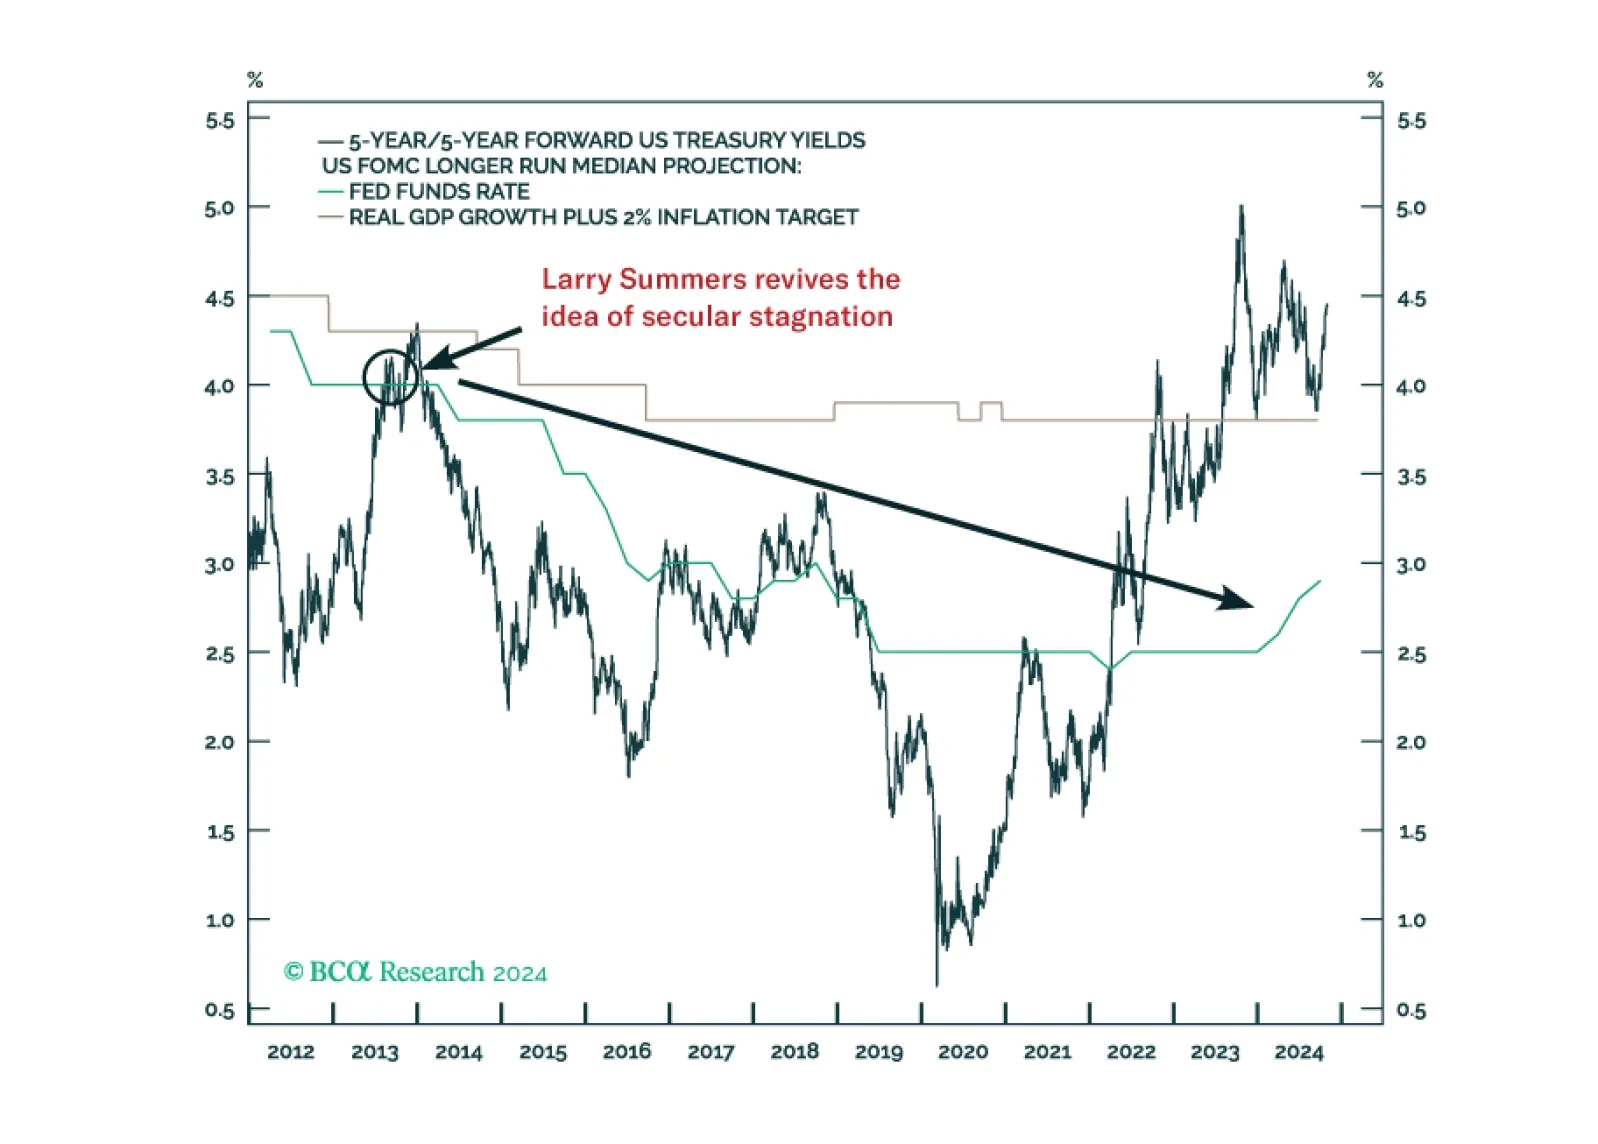
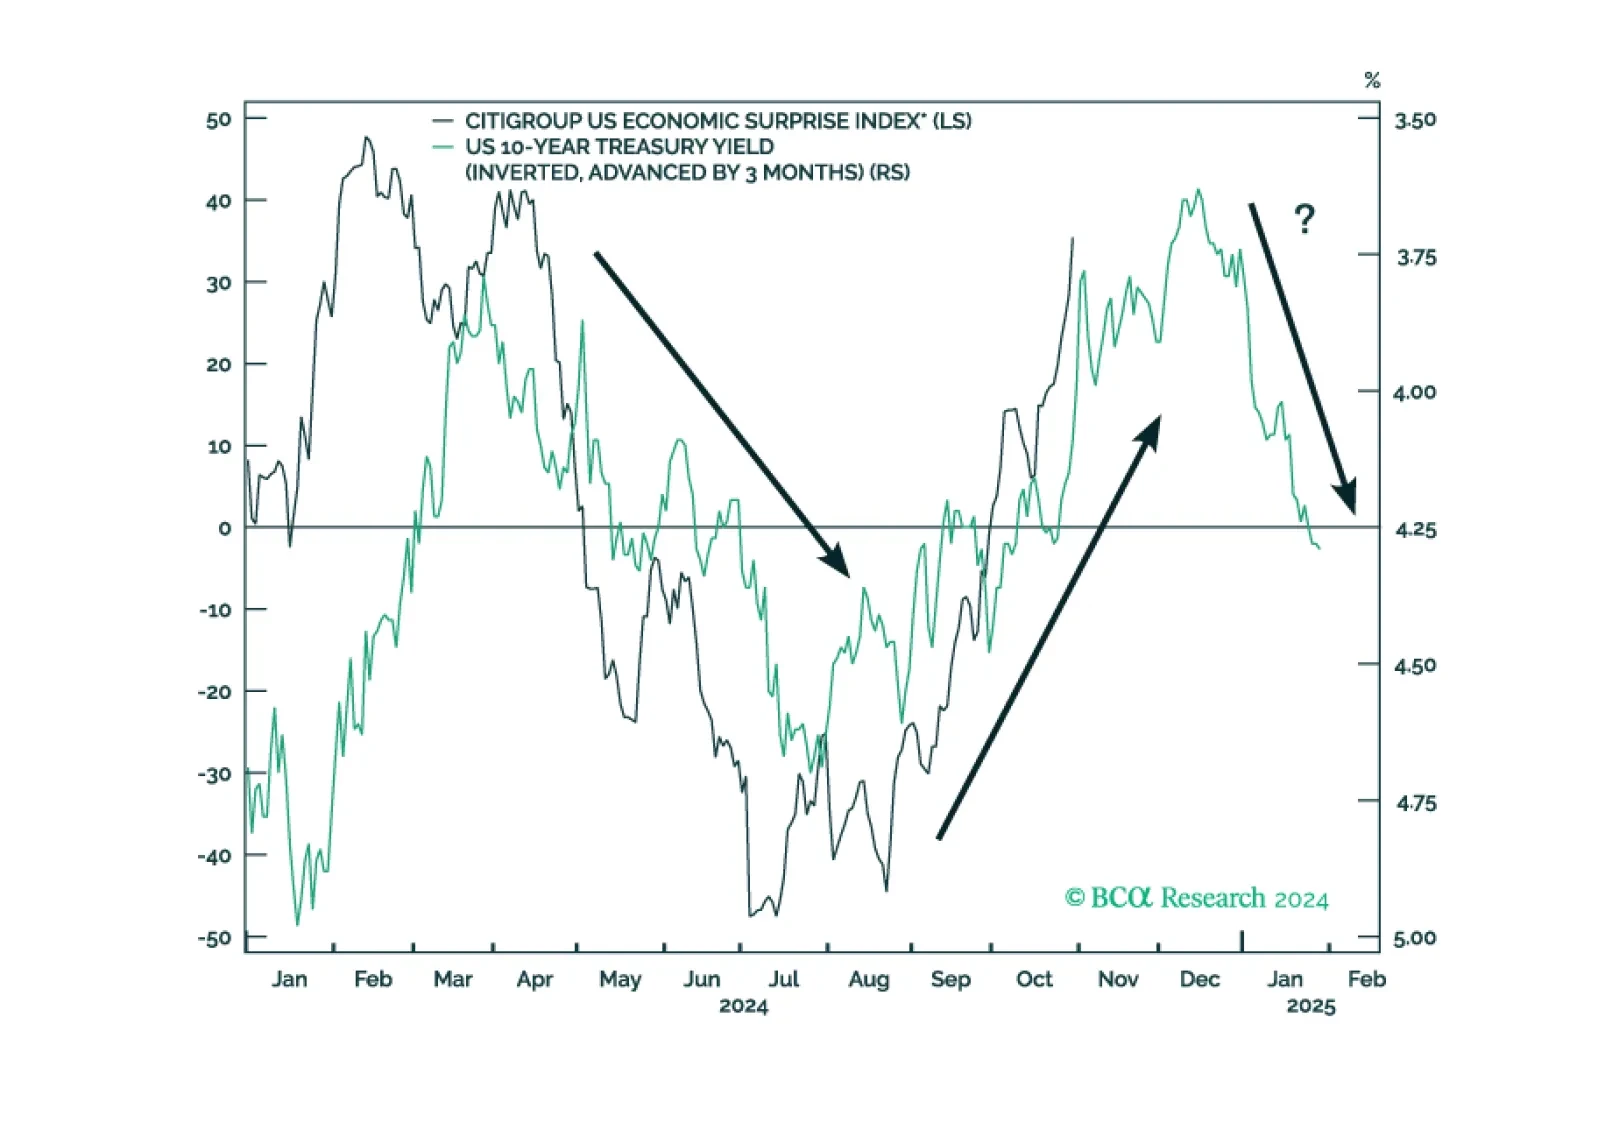
Bank Credit Analyst In Section I, we explain how recent positive data surprises are connected to expectations of Fed easing, meaning that they are self-limiting. Yields will rise even further if US economic data continue to surprise to the upside, which will put the US back on a recessionary path. A Republican sweep has the potential to be positive for US economic growth over the next year, but trade action under a second Trump presidency will likely be aggressive and economically damaging unless deftly offset by sufficiently large fiscal thrust. In Section II, we explain why the Fed is not politically biased, but has become structurally dovish because of the GFC, its shaken confidence in the “stars”, and its ability to forecast the economy. Over the next year, the Fed may appear to be acting in a politically biased way even if it is merely responding to economic developments. The Fed’s independence could be challenged under a Trump presidency if trade action is not severe.
We update our 12-month return projections for different US fixed income sectors in soft-landing and recession scenarios.
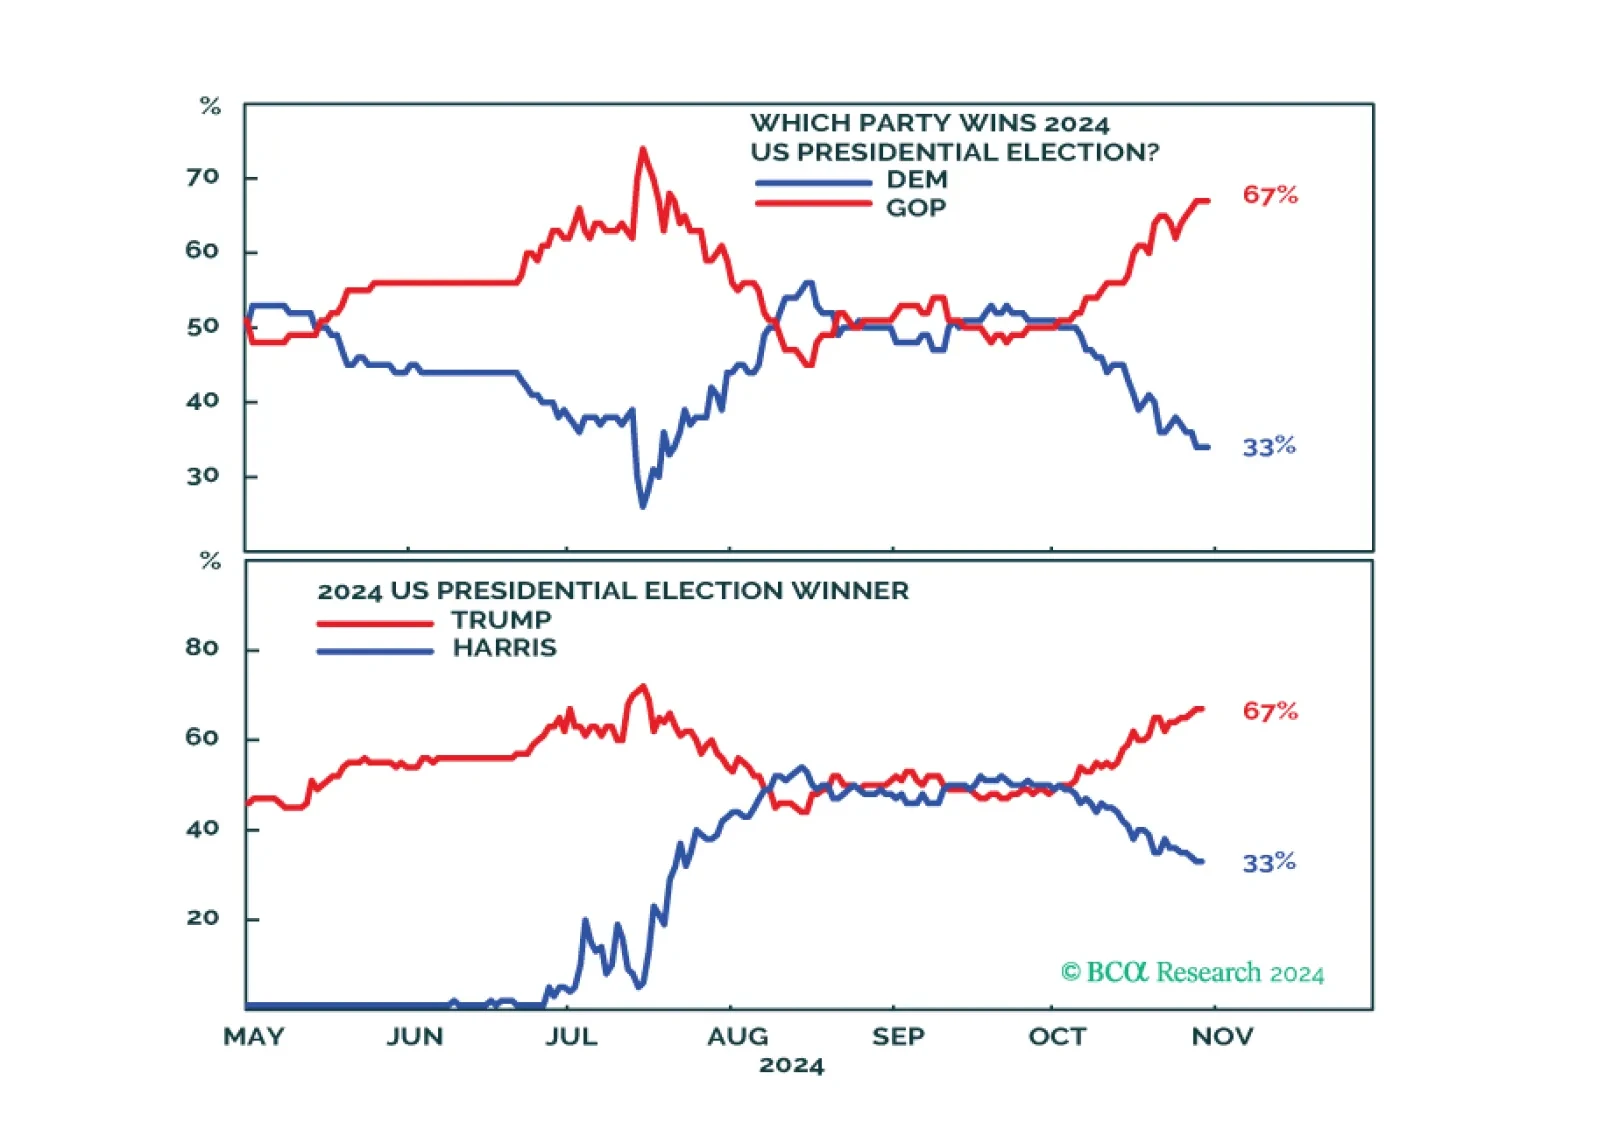
Trump may be favored, but Harris is now underrated. The Senate is highly likely to go Republican – Harris would be gridlocked if she pulled off a victory. If Trump wins it will be a full sweep. Expect volatility in the short term.
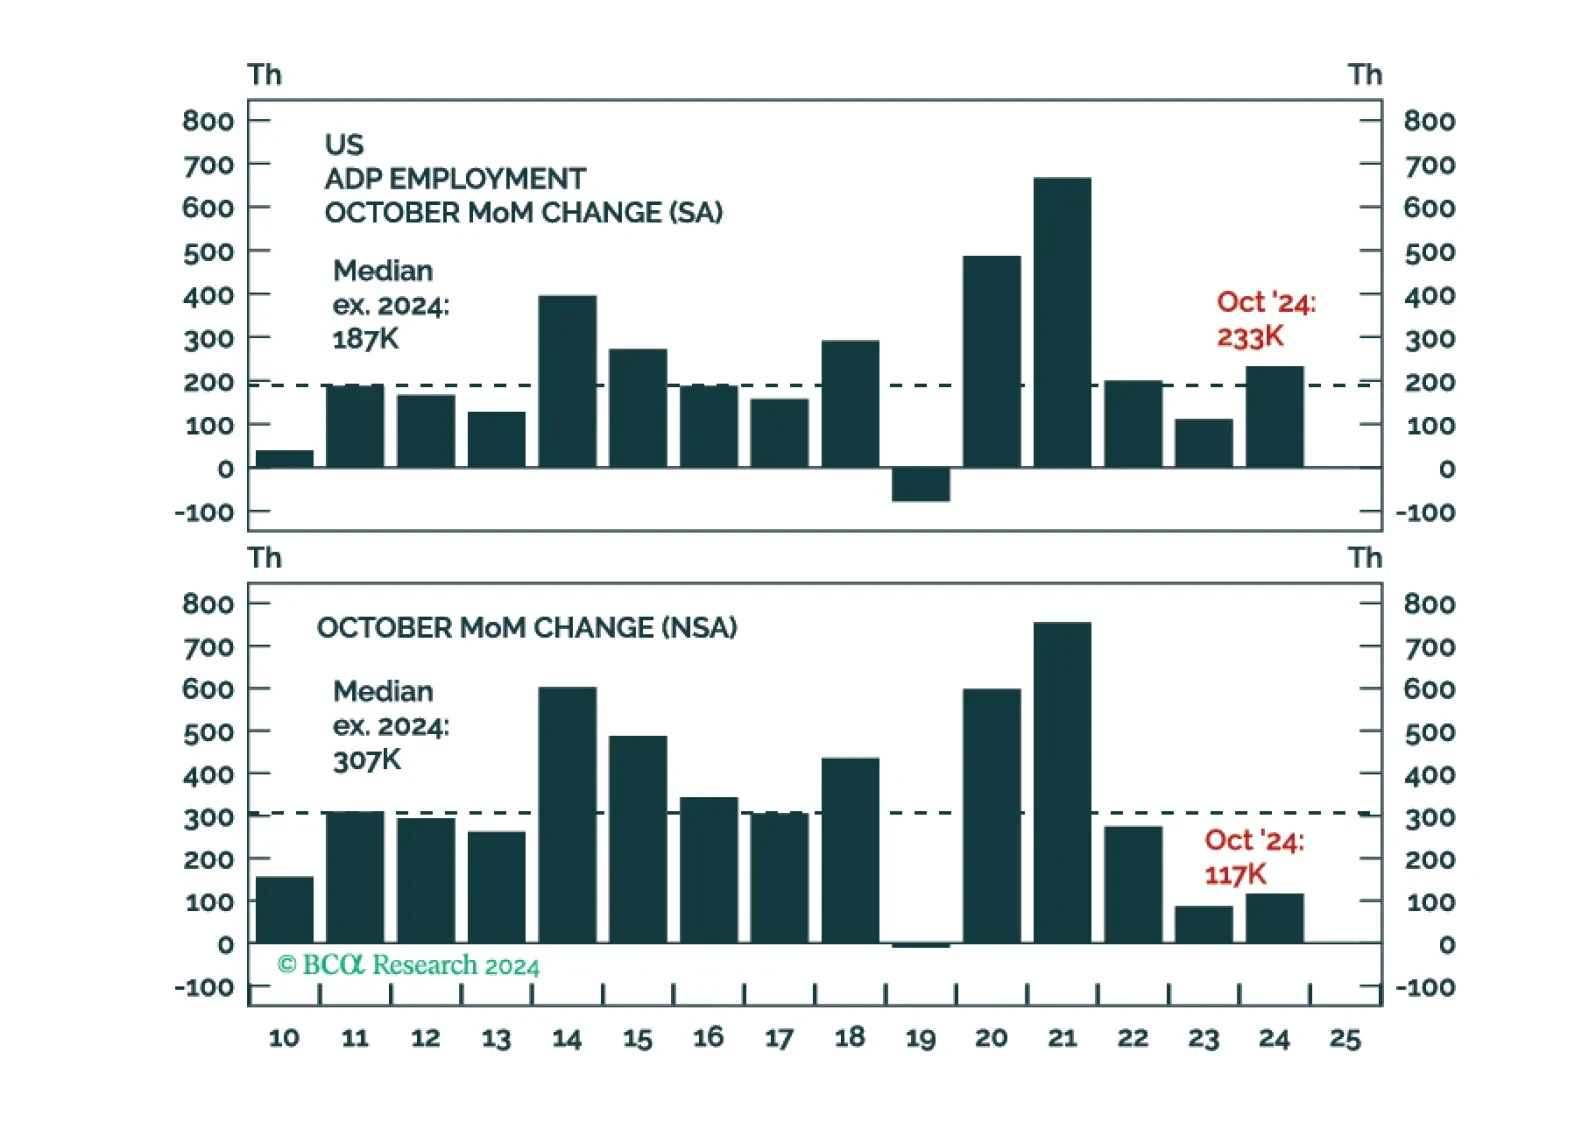
ADP's estimate of private payrolls rose by 233K on a seasonally adjusted basis in October, blowing away the consensus estimate of 111K.
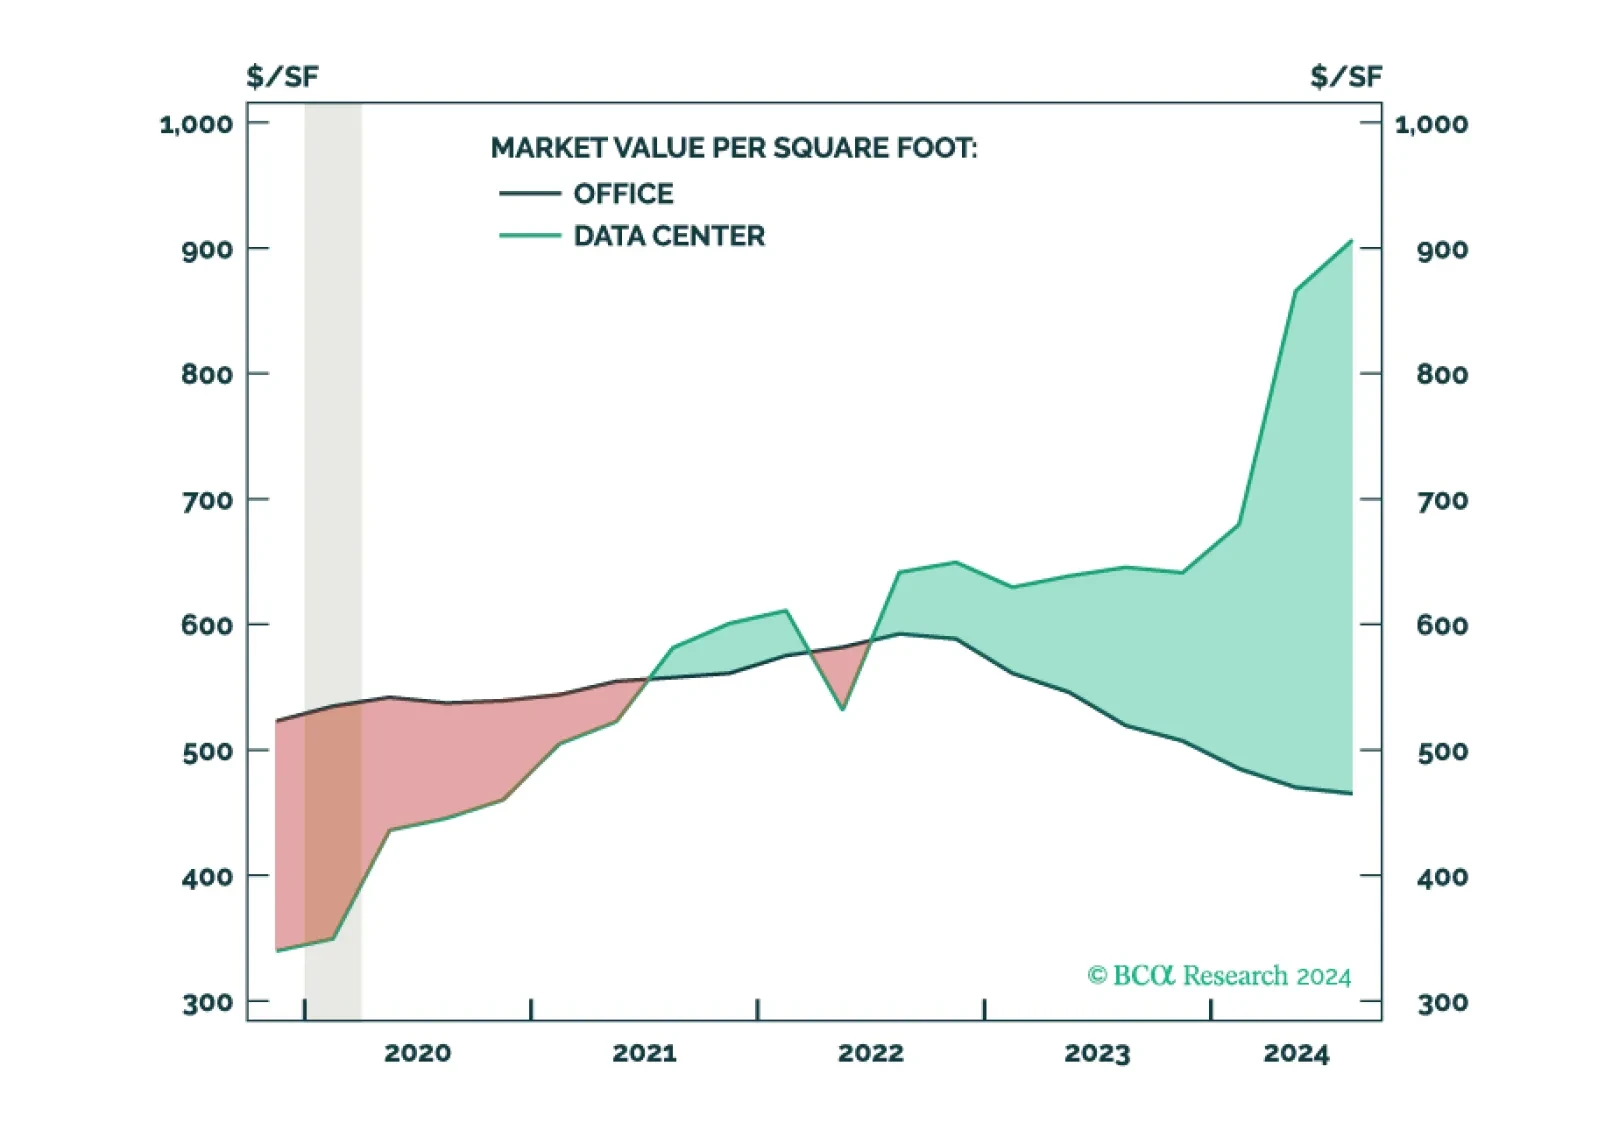
We prefer Non-Core Infrastructure and Venture Capital over Buyouts and Multi-Strategy Hedge Funds. We are now overweight Core/+ Real Estate. Investors need to recheck the bank regulation tailwind for their long-term assumptions on Private Credit.