 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
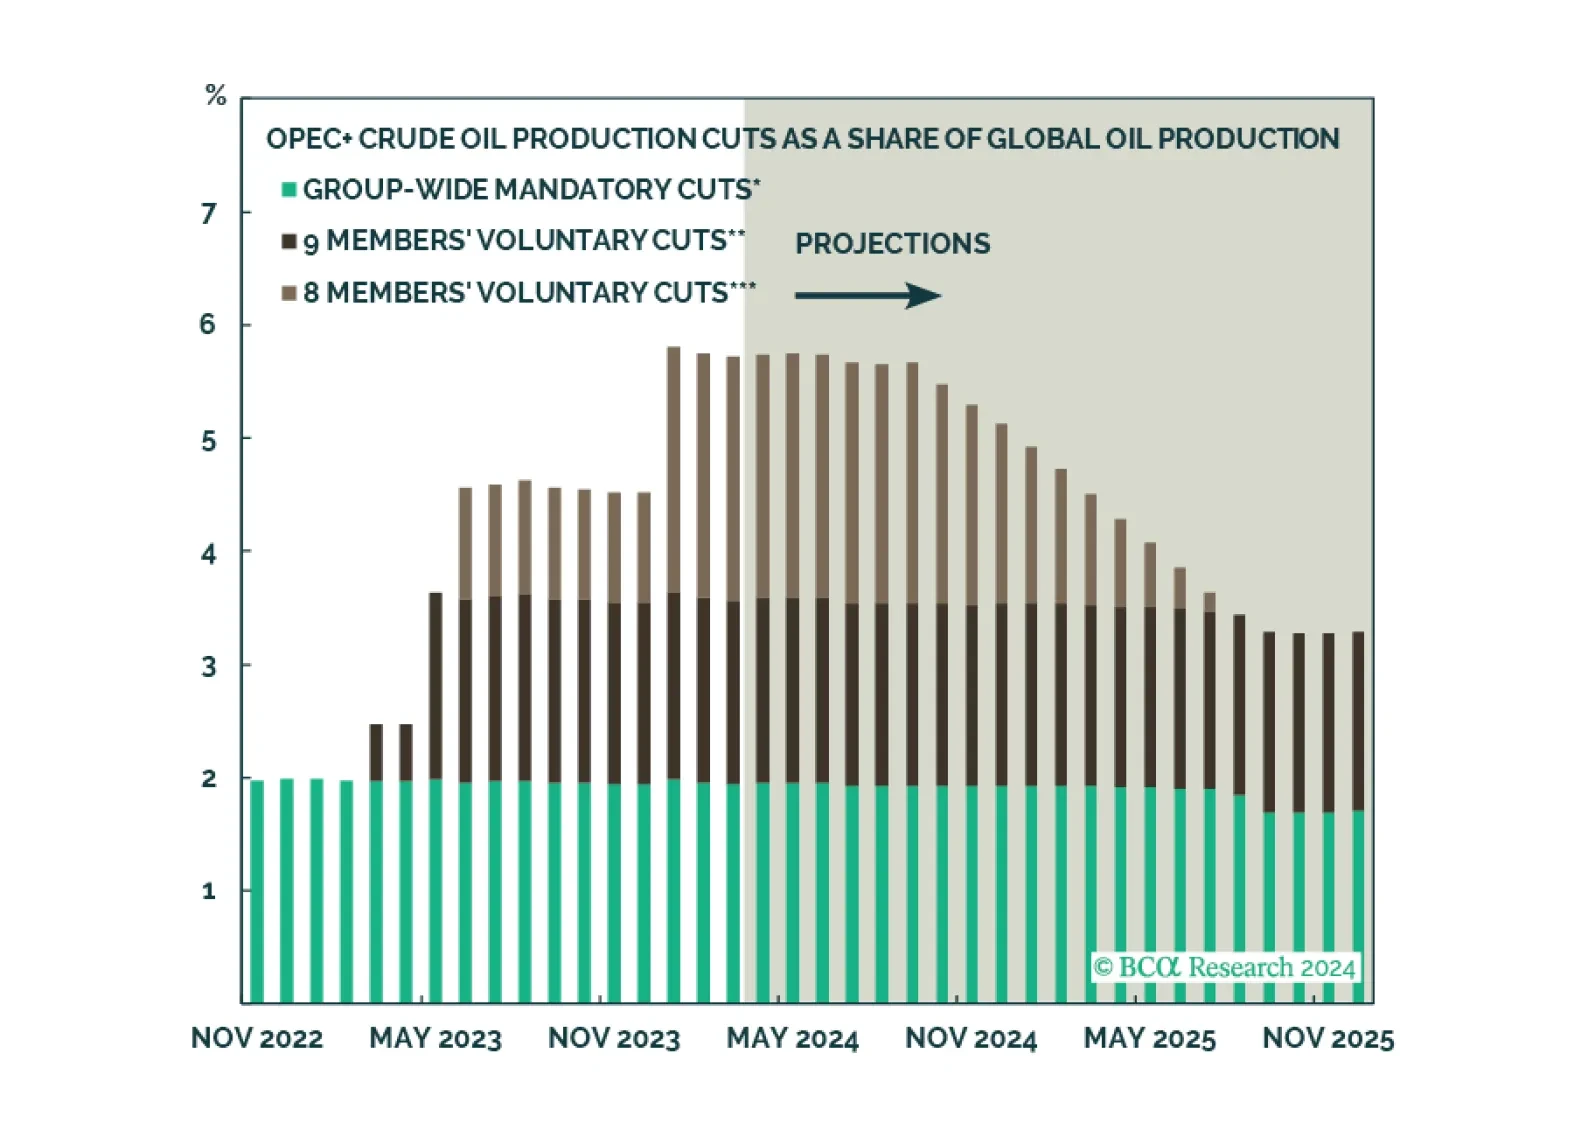
According to OPEC+’s revised production path, the group will begin unwinding some of its production curbs in Q4. This announcement suggests that the coalition might be shifting its strategy towards defending a price floor. Such a shift in OPEC+ strategy does not imply that the ‘OPEC put’ is completely dead. Rather, its strike price has been lowered.
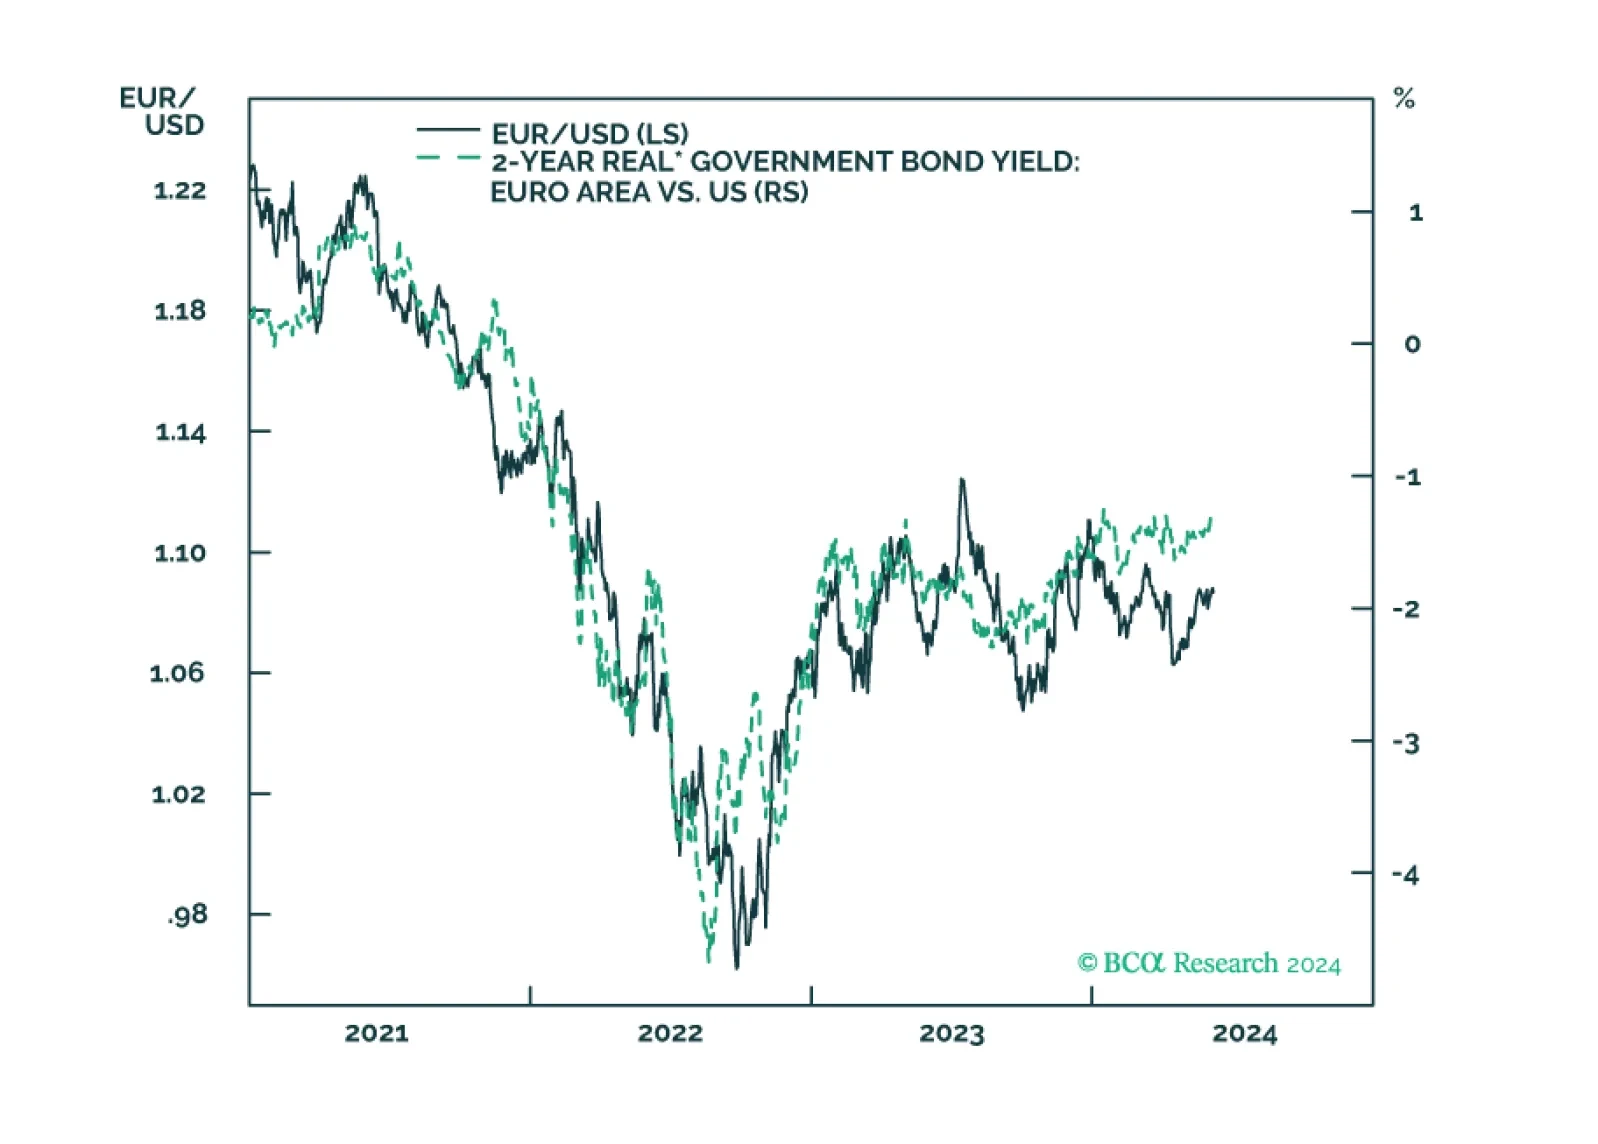
A short insight on the ECB and near-term implications for European asset markets.
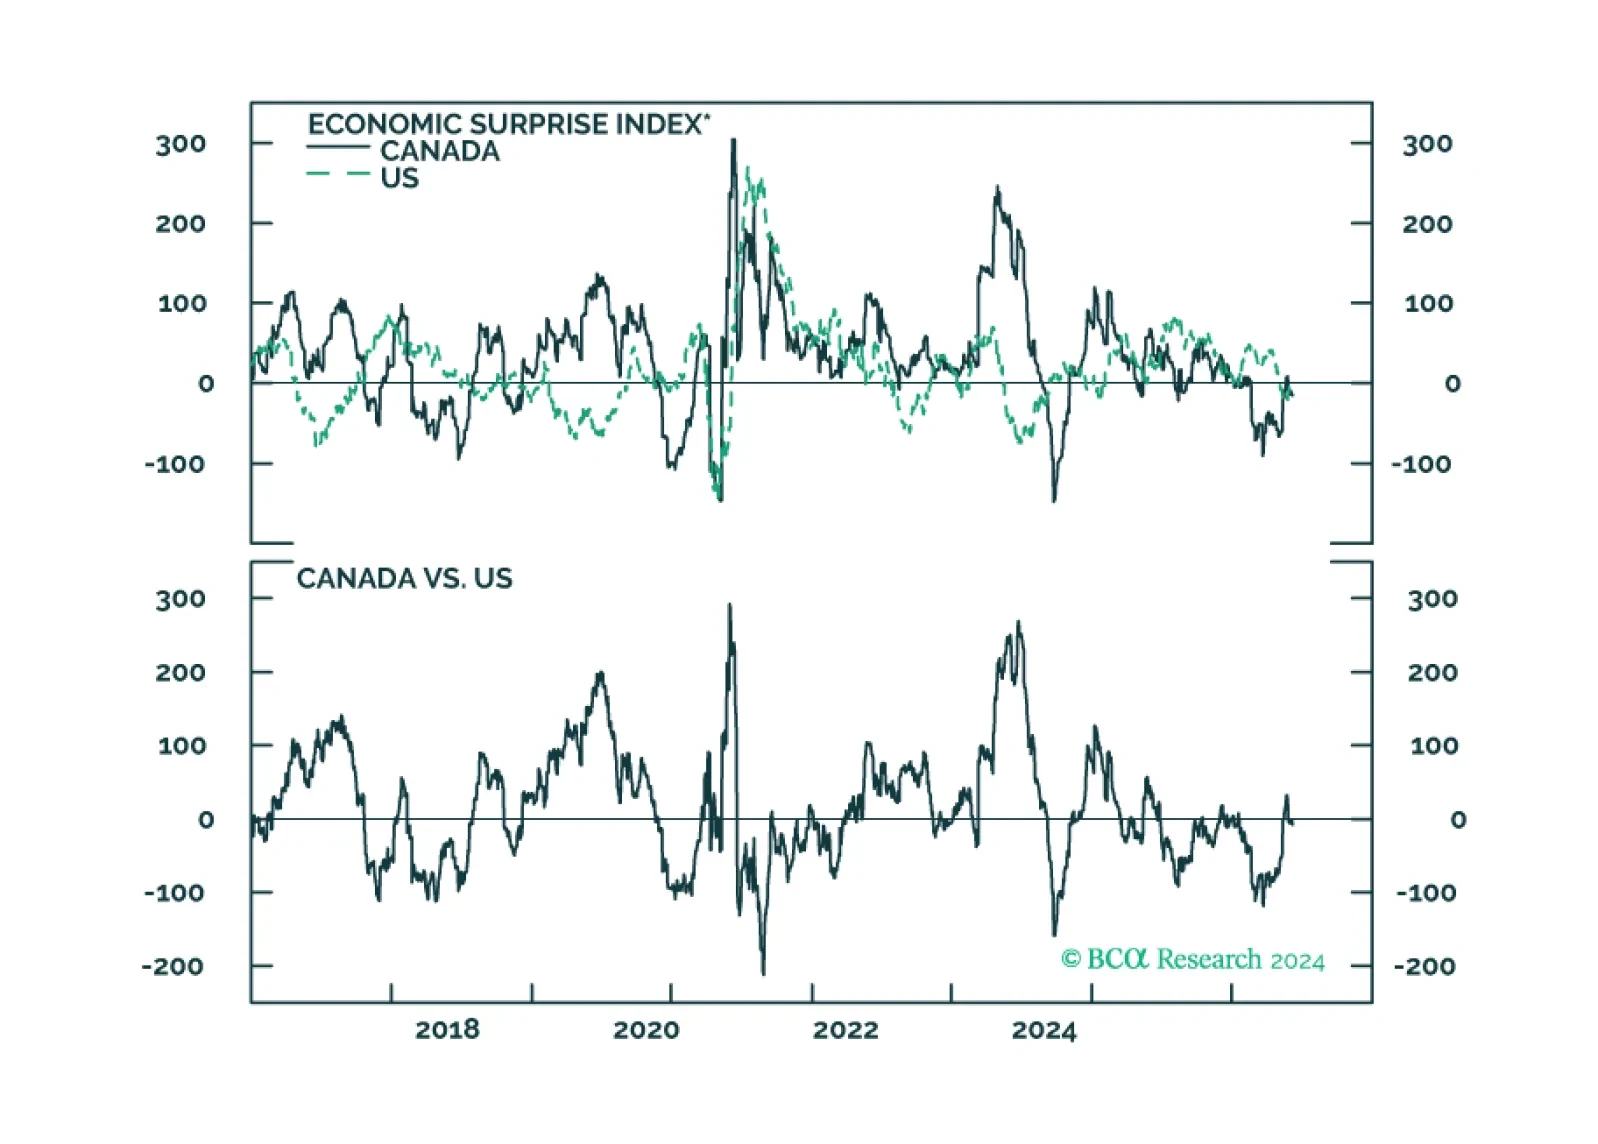
In this insight, we provide an update on the Canadian economy, given yesterday’s rate cut, and implications for Canadian assets.
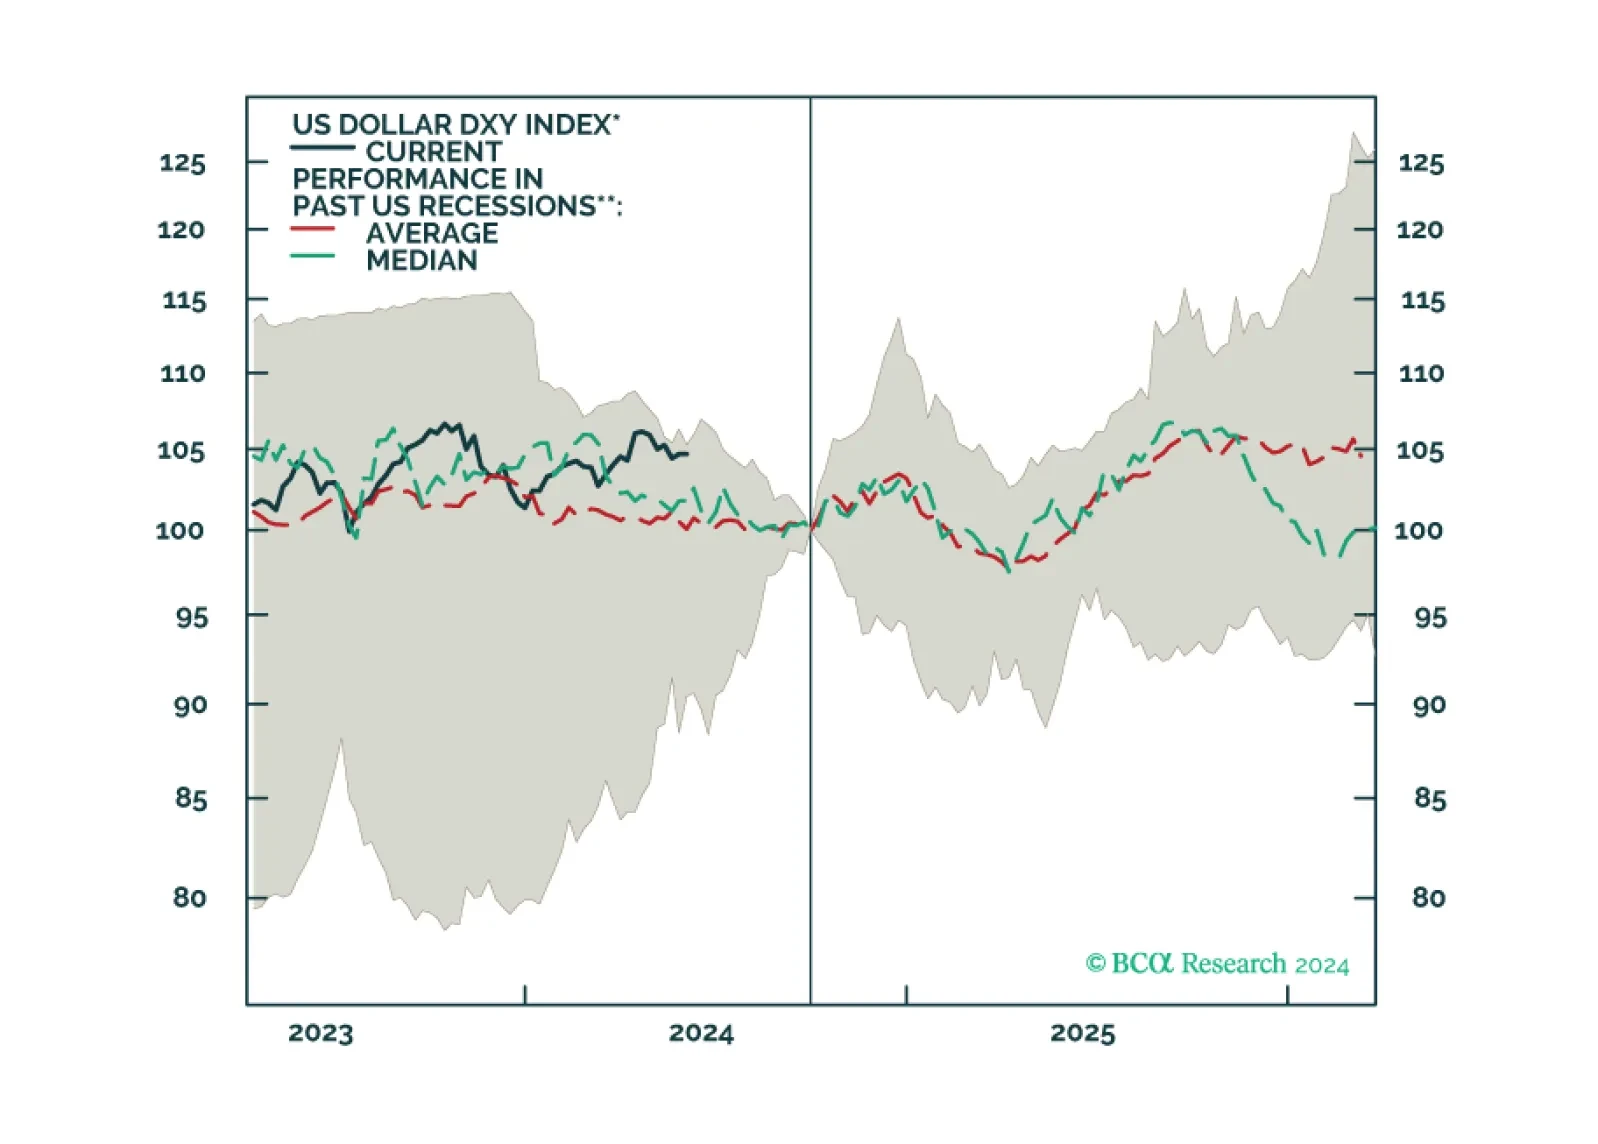
In this report, we gauge the outlook for the dollar given client visits in Africa.
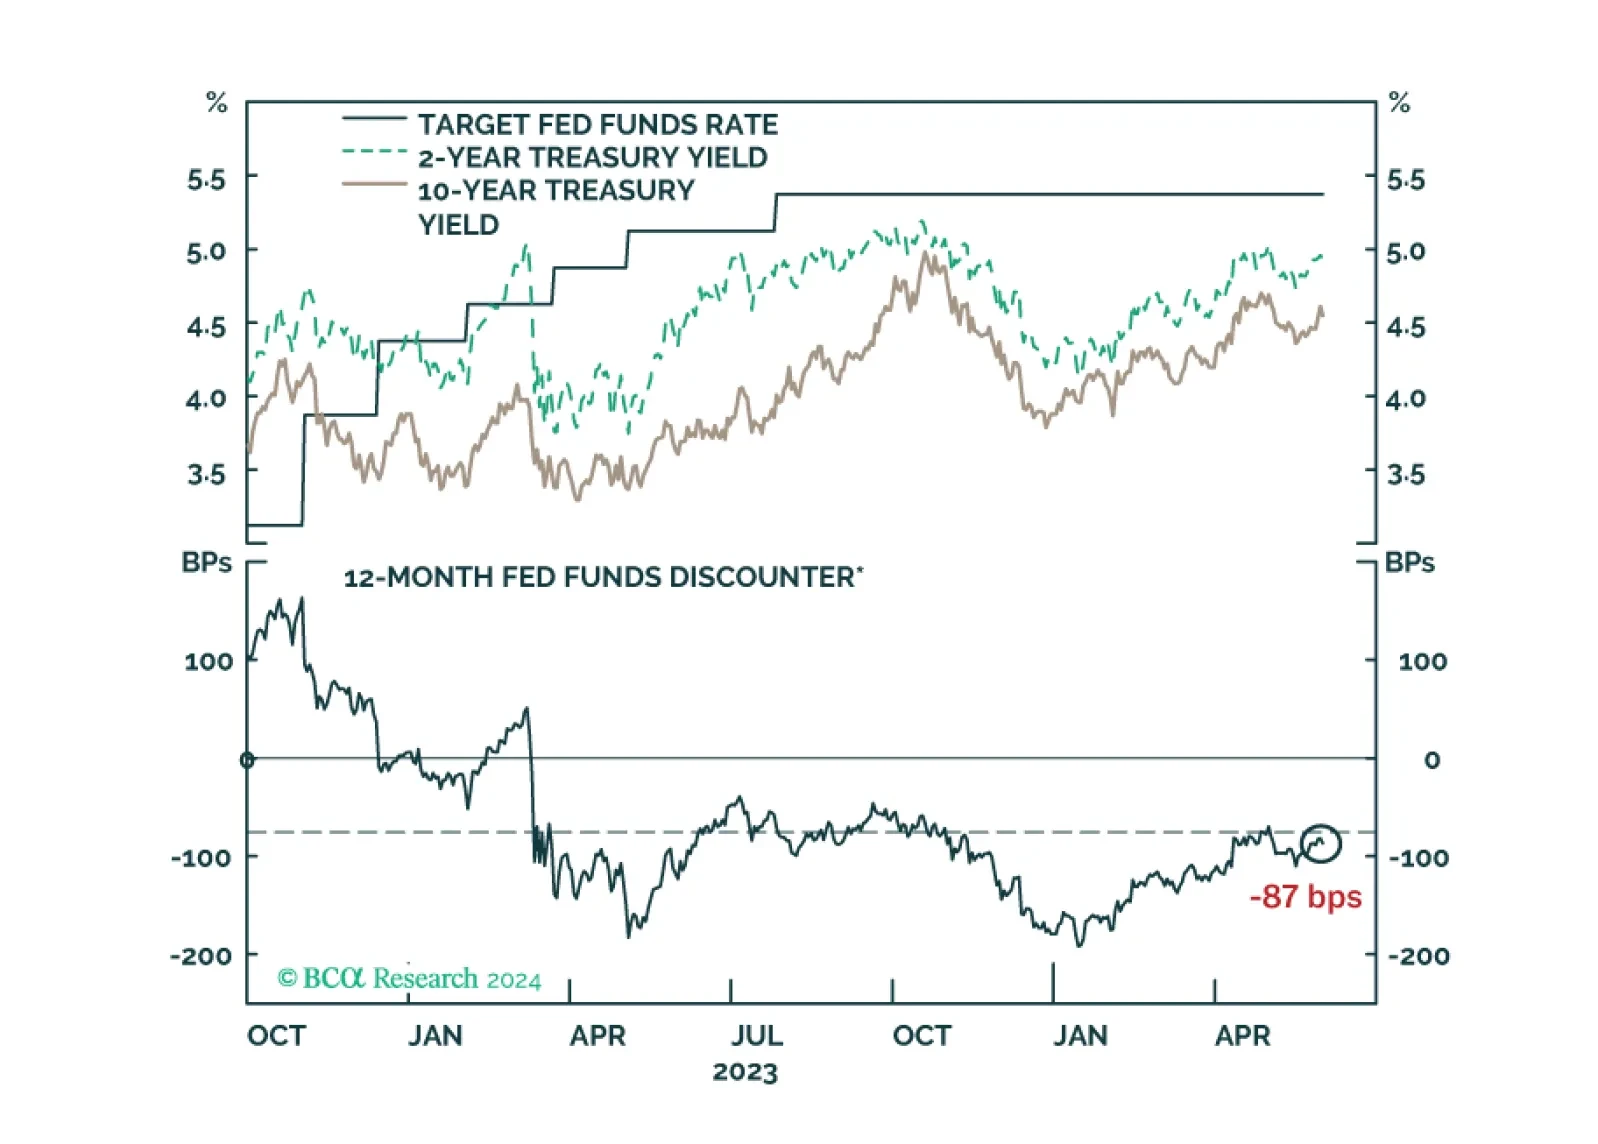
We comment on whether Treasury market valuation is sufficiently attractive to get long bonds and consider some of the common arguments for why yields may yet make new highs.
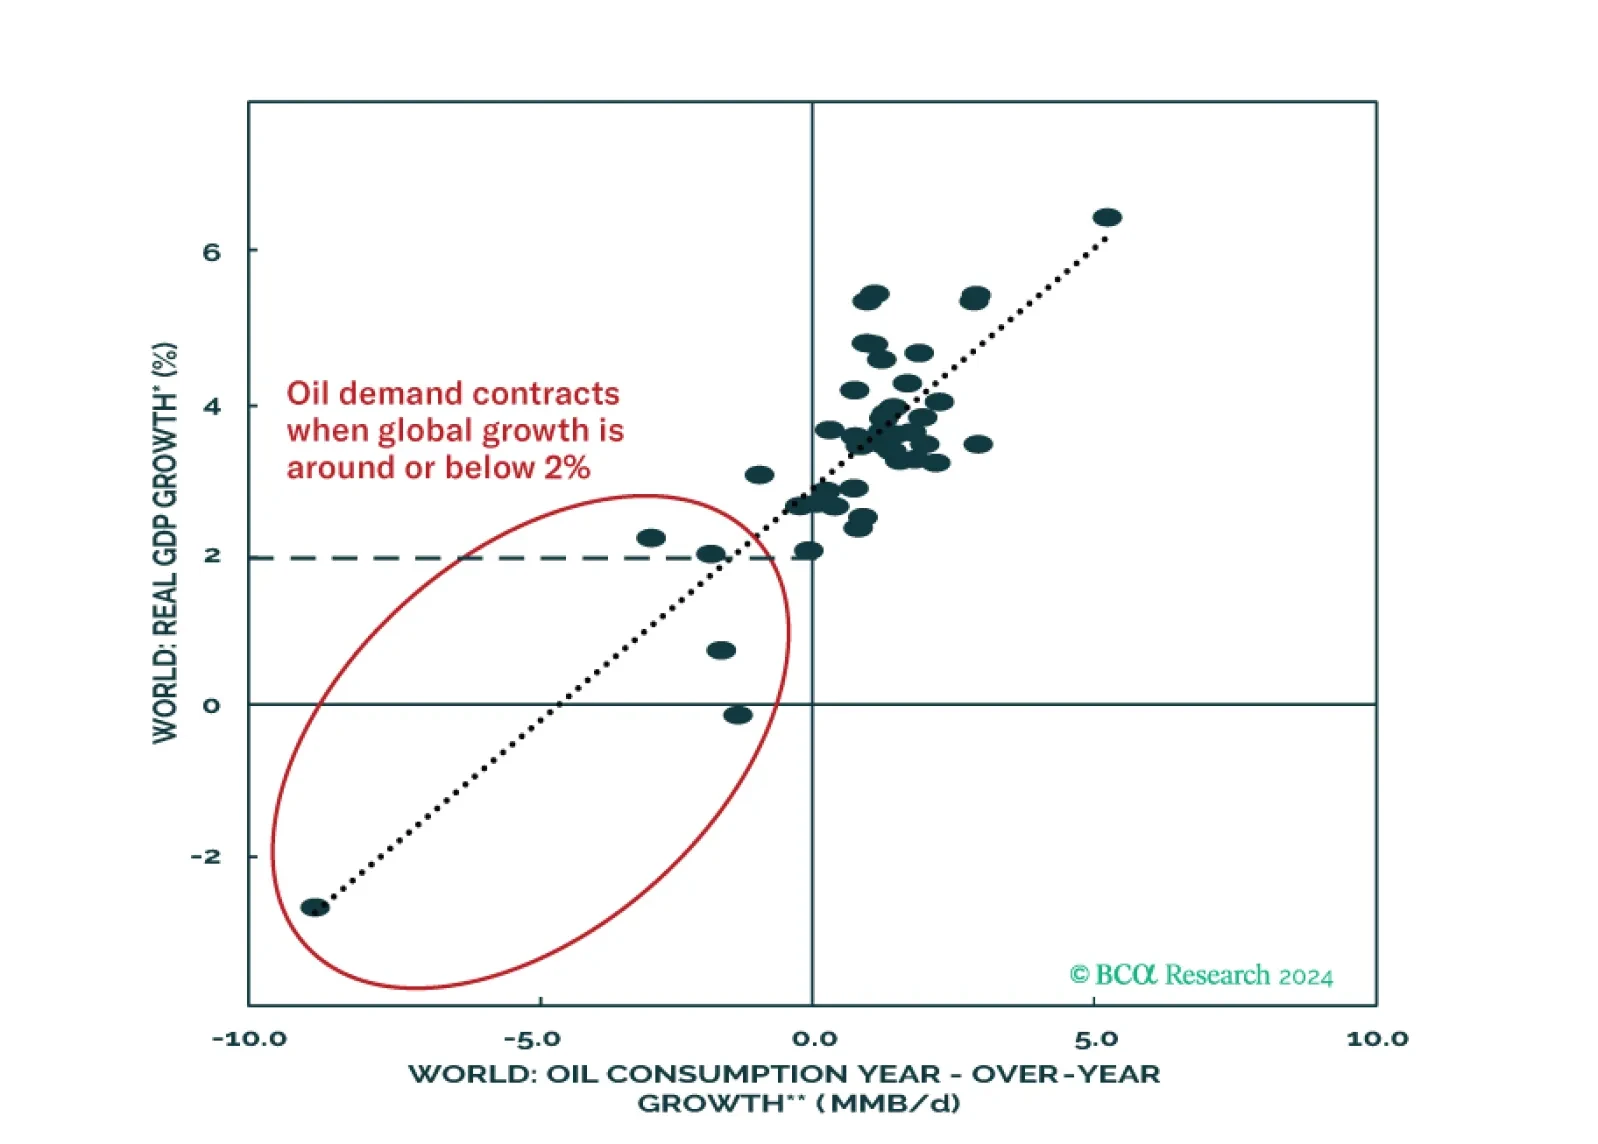
The three major oil forecasters – IEA, EIA, and OPEC – are forecasting oil demand growth until 2025 to be broadly in line with its range over the past four decades. On a cyclical horizon, we give high odds that a recession will begin within the coming 6-12 months, disappointing these oil demand forecasts. On a strategic horizon, the IEA projects EVs will displace 9% of global oil demand by 2035, serving as a long-term demand headwind.
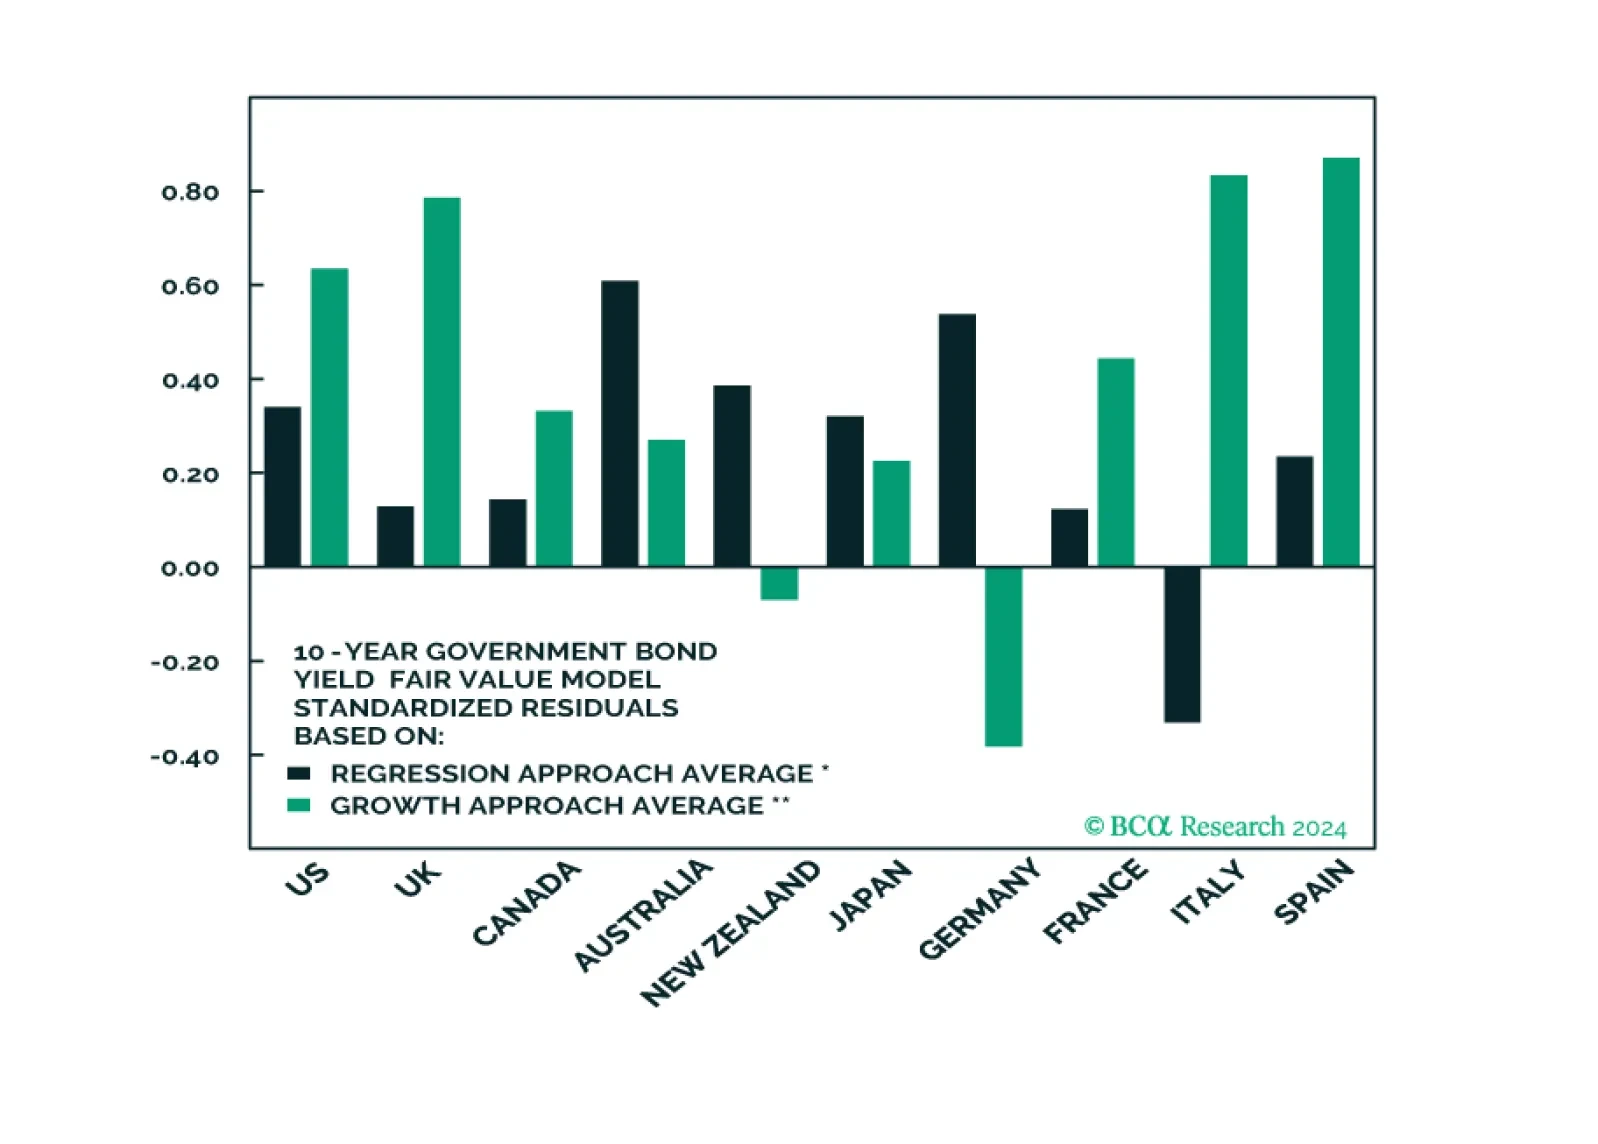
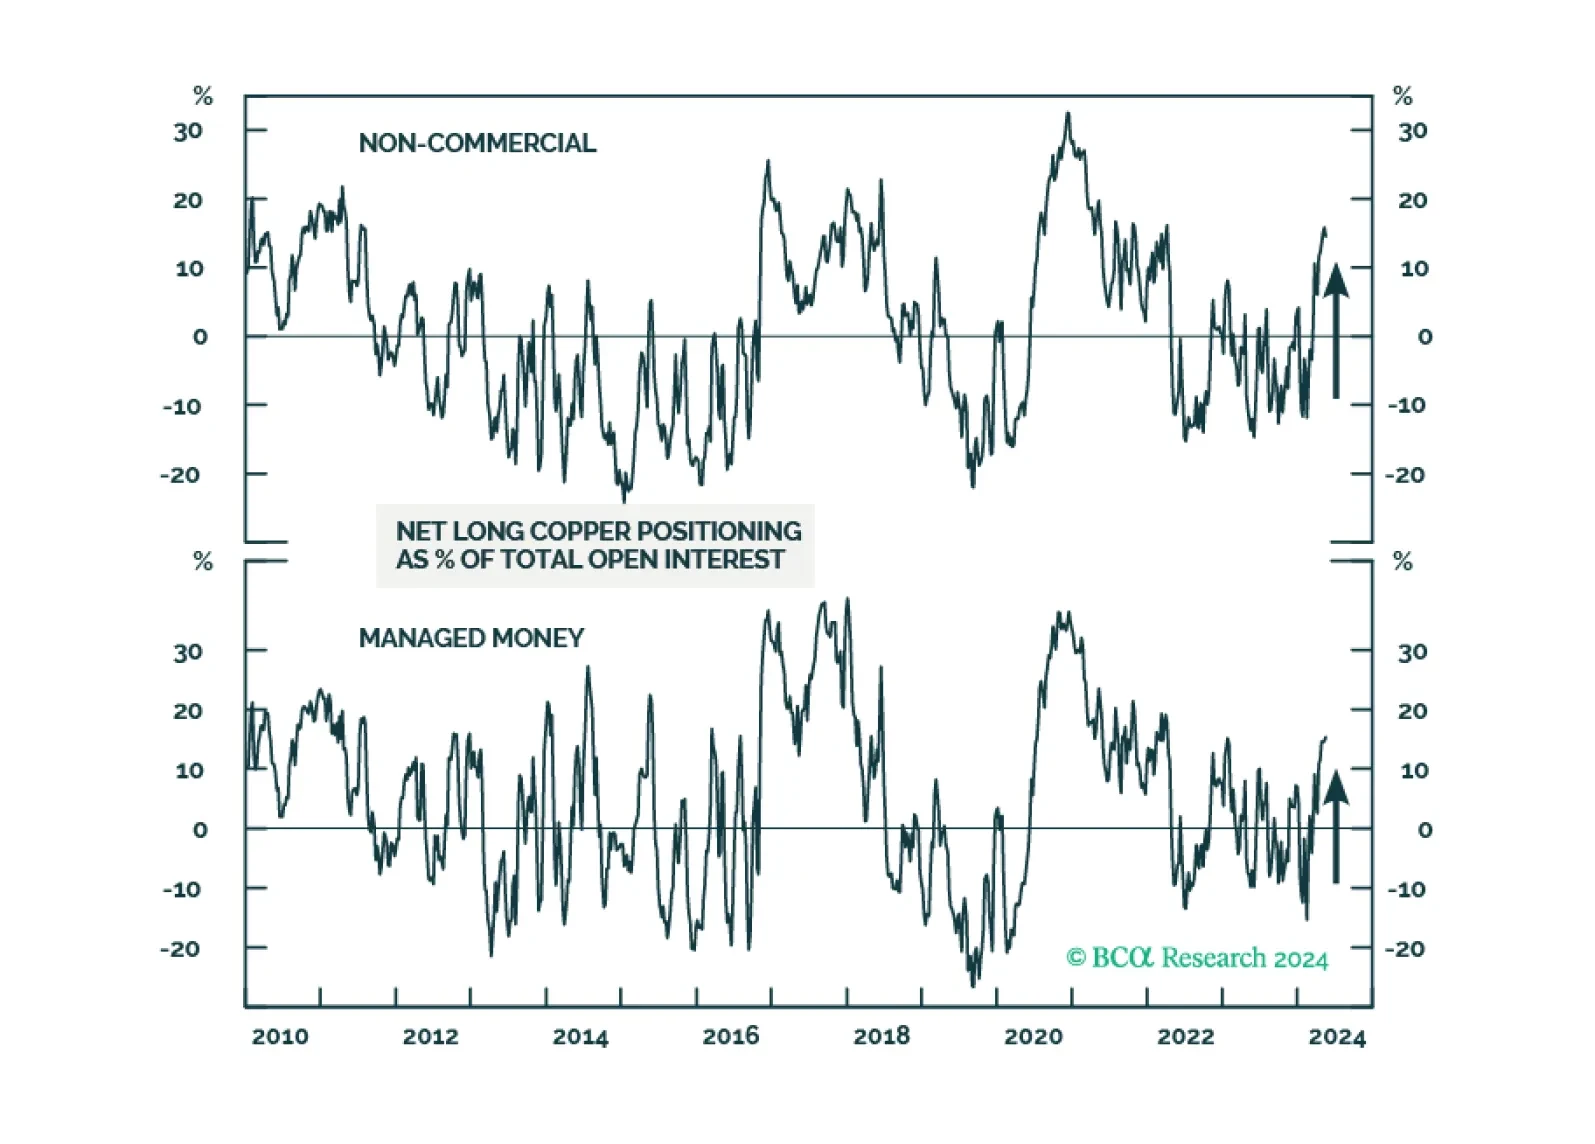
The sharp move higher in copper prices is missing a clear fundamental catalyst. Meanwhile, the cyclical outlook for the global economy in general, and manufacturing activity in particular, is unlikely to provide a tailwind. Given that aggregate copper inventories on global exchanges have been rising briskly, there are high odds that the copper price surge will soon reverse.