FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
Increasing gray-zone confrontations and another round of tariff and non-tariff barriers to trade are not being reflected in commodity prices. This is keeping inflationary pressures emanating from the real economy subdued. That said, inflation risks are increasing as threats to commodity supplies and supply chains grow. Standard monetary policy focused on aggregate-demand management is ill-suited for addressing these risks, and could exacerbate supply-side tightness. We remain long oil- and metals-producer equities exposure via the XOP and XME ETFs, and to commodities outright via the COMT ETF.
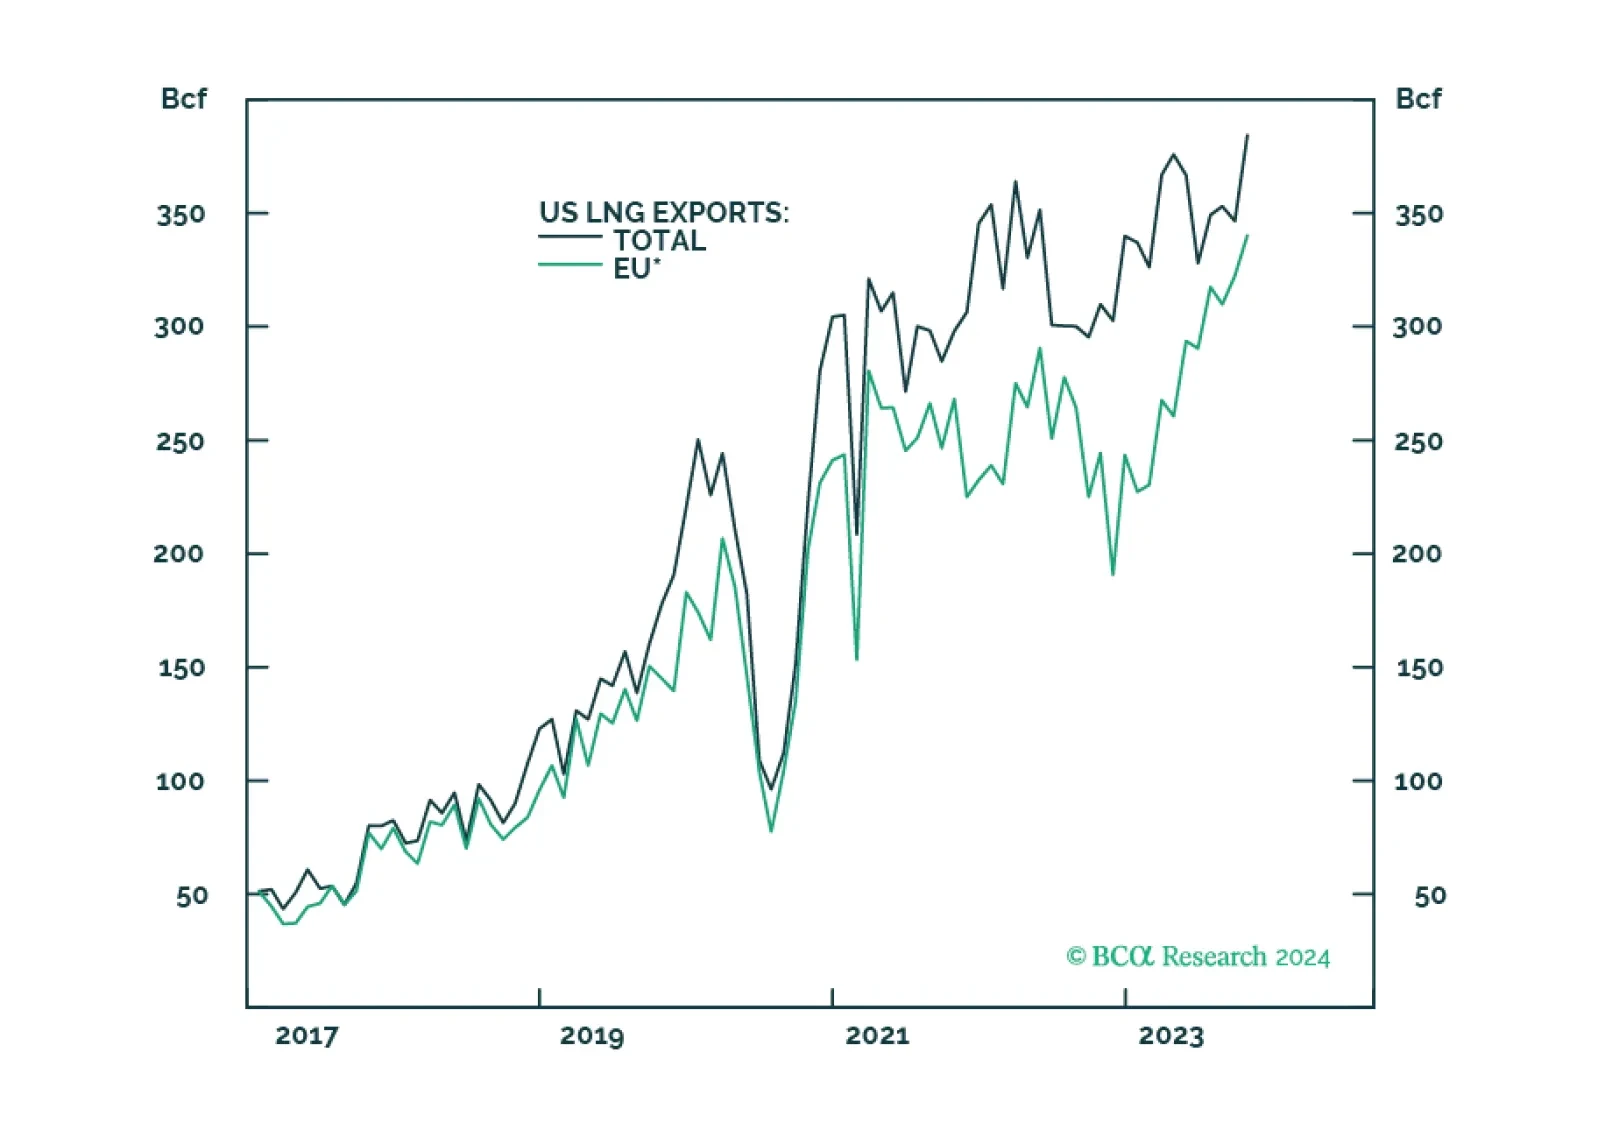
The attacks on Red Sea commercial tankers by Iran’s Yemeni proxies, the Houthi movement, are an inflation risk inasmuch as they lengthen voyage times for any shipping forced to avoid the Bab el-Mandeb Strait. The risk of an expansion of these attacks is, in our view, limited, given Iran’s inability to project naval power in the region.
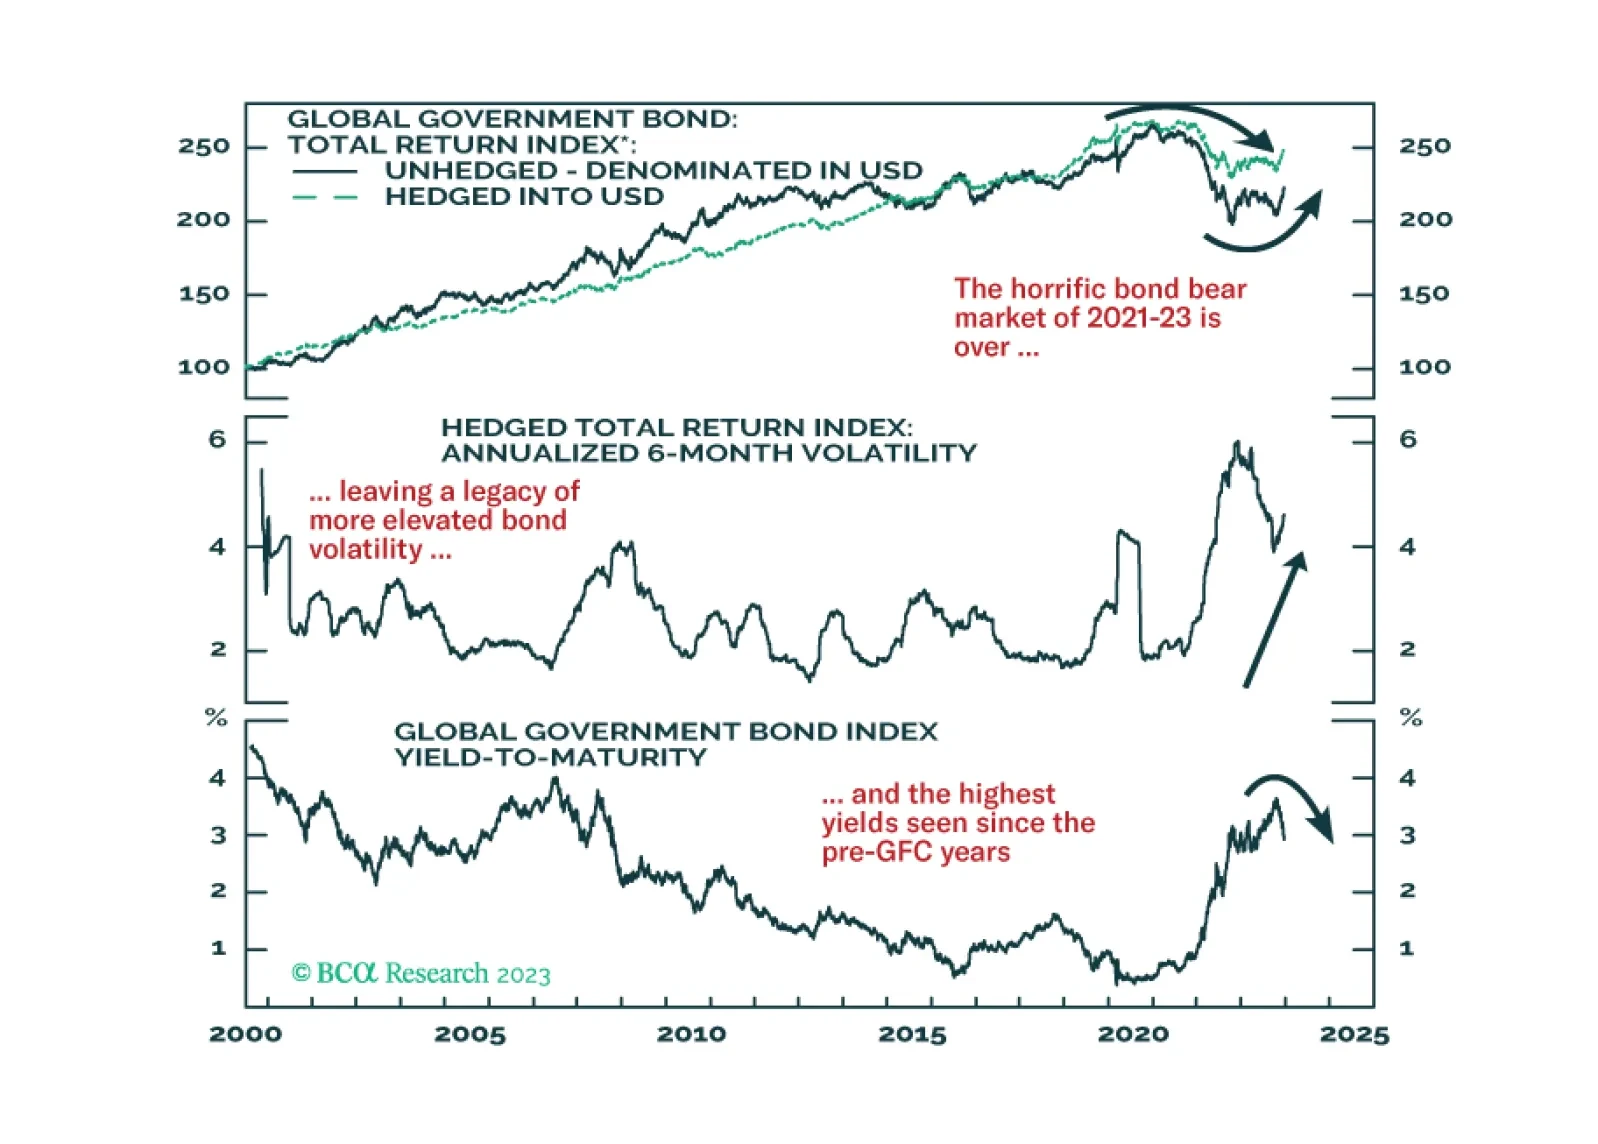
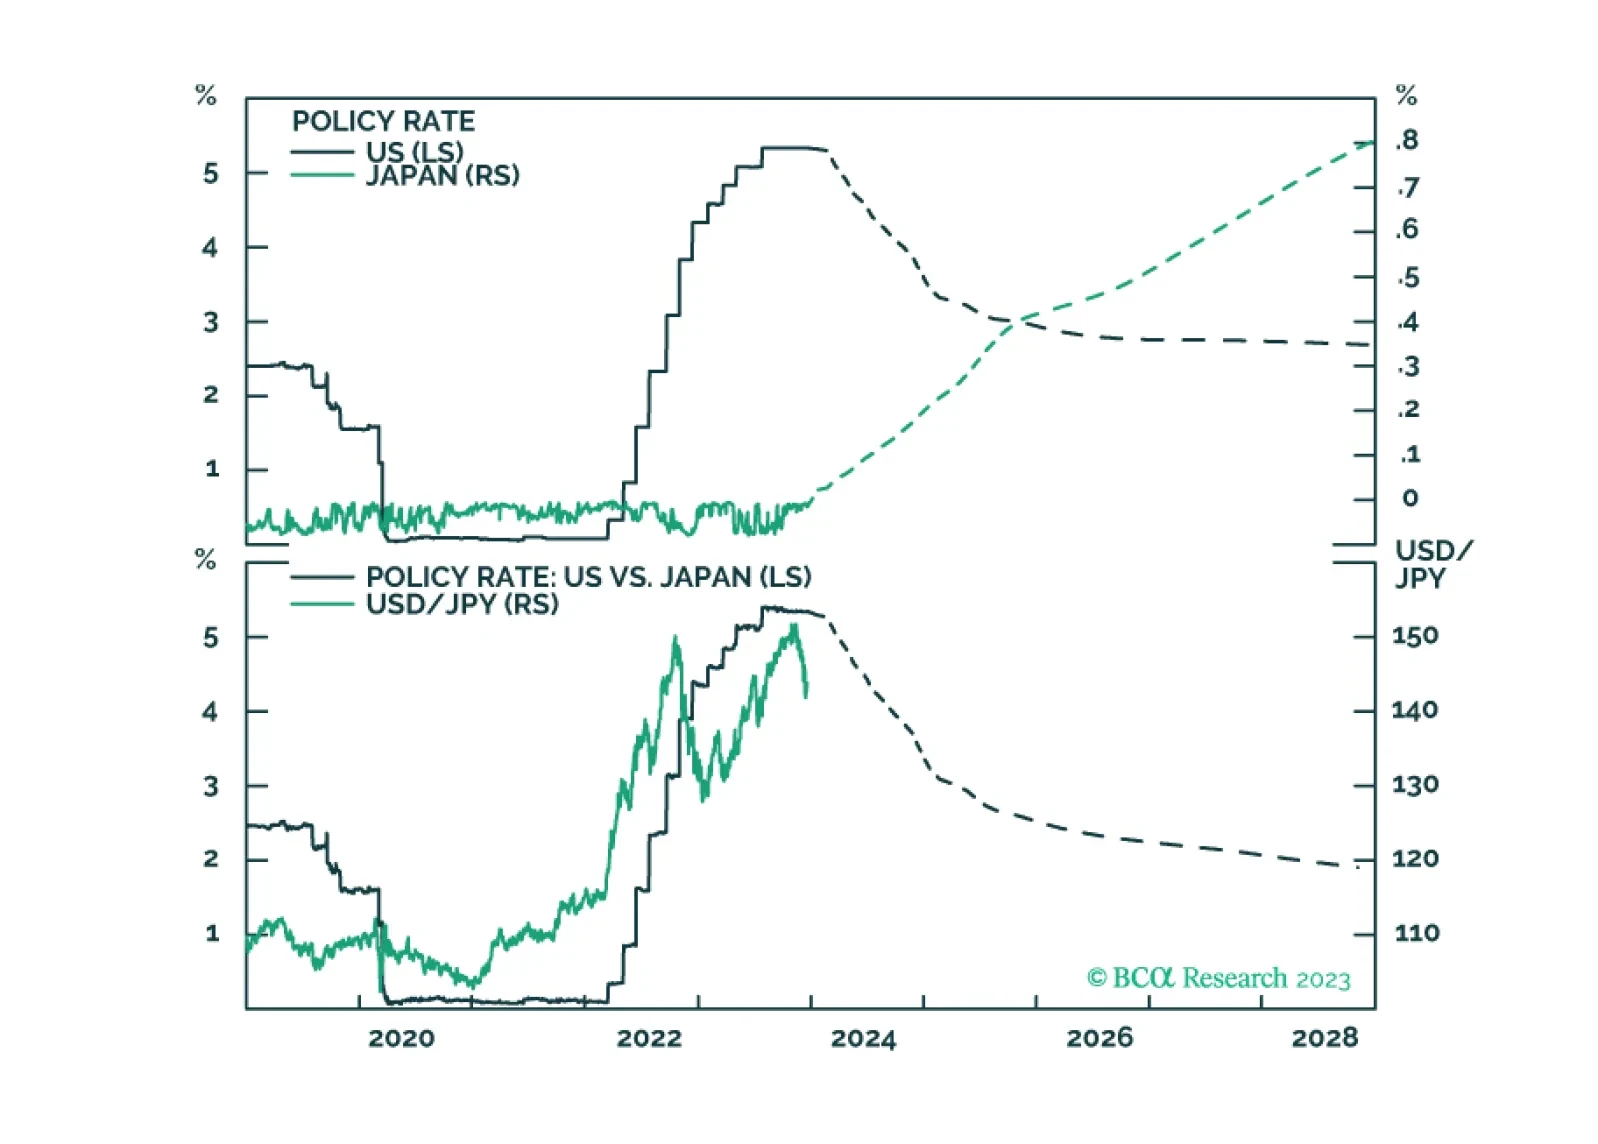
A post-mortem of our trades for the year, and also comments on future yen and sterling moves from the recent BoJ meeting, and the UK inflation report.
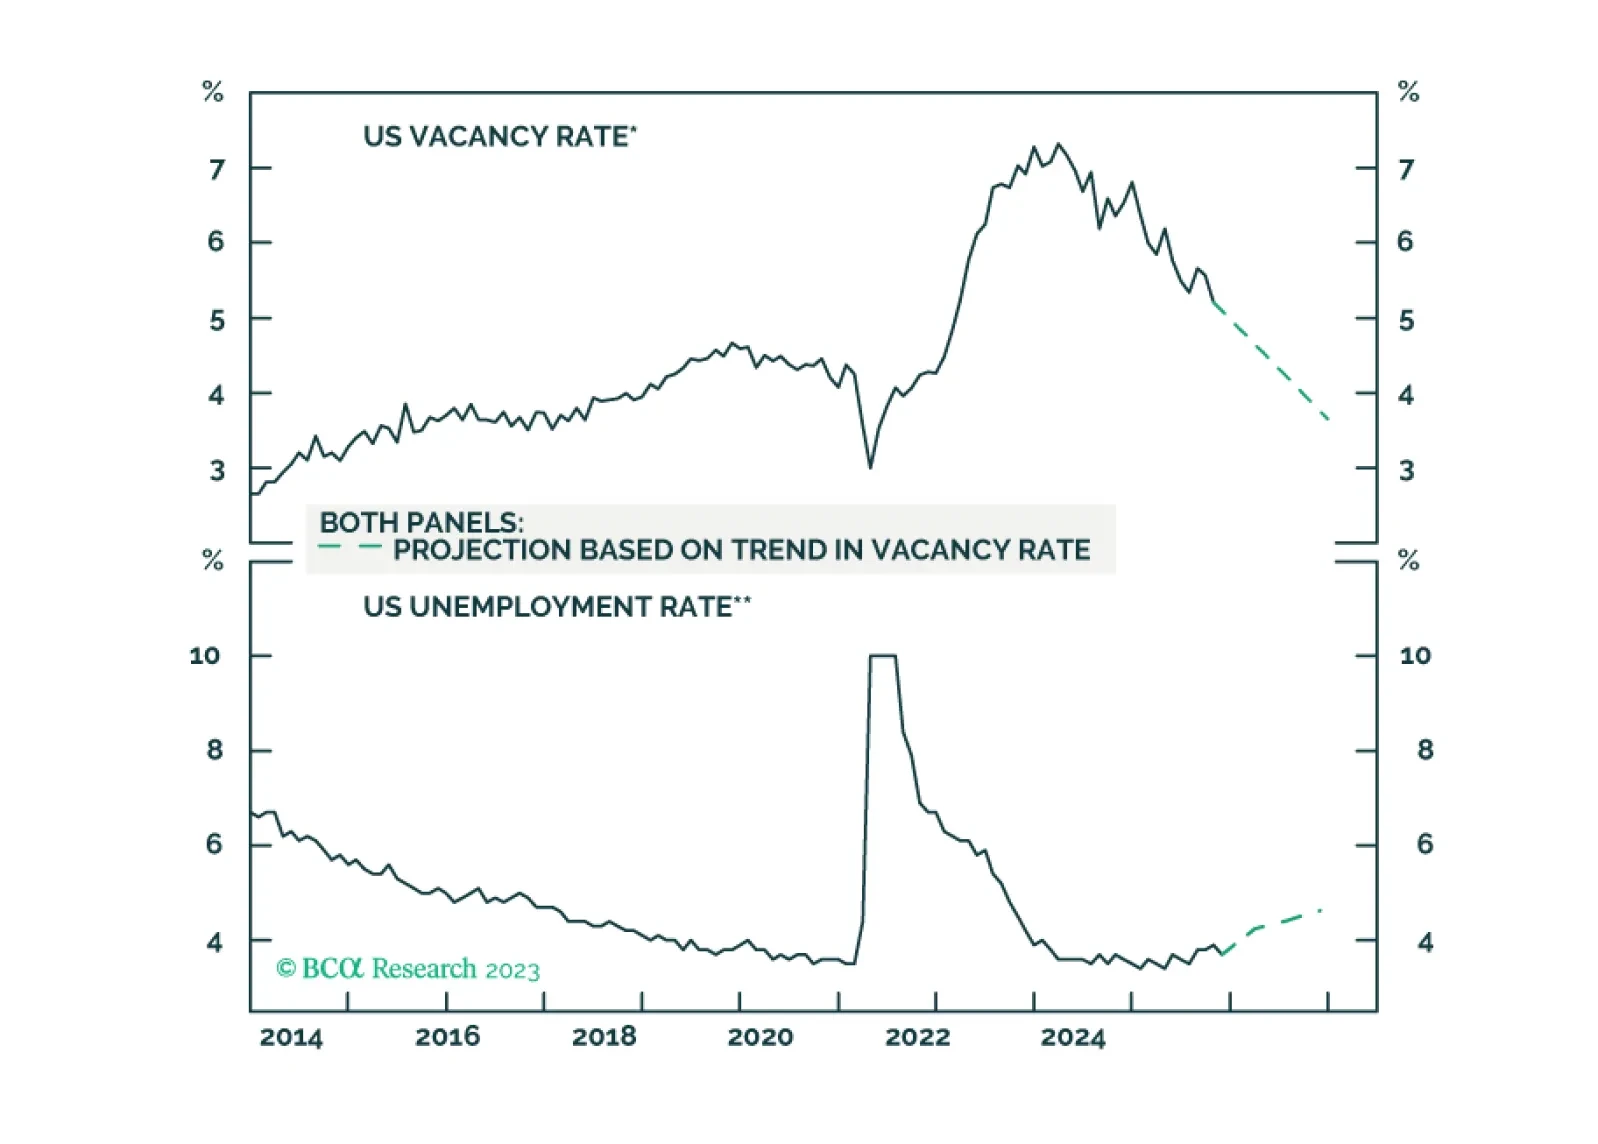
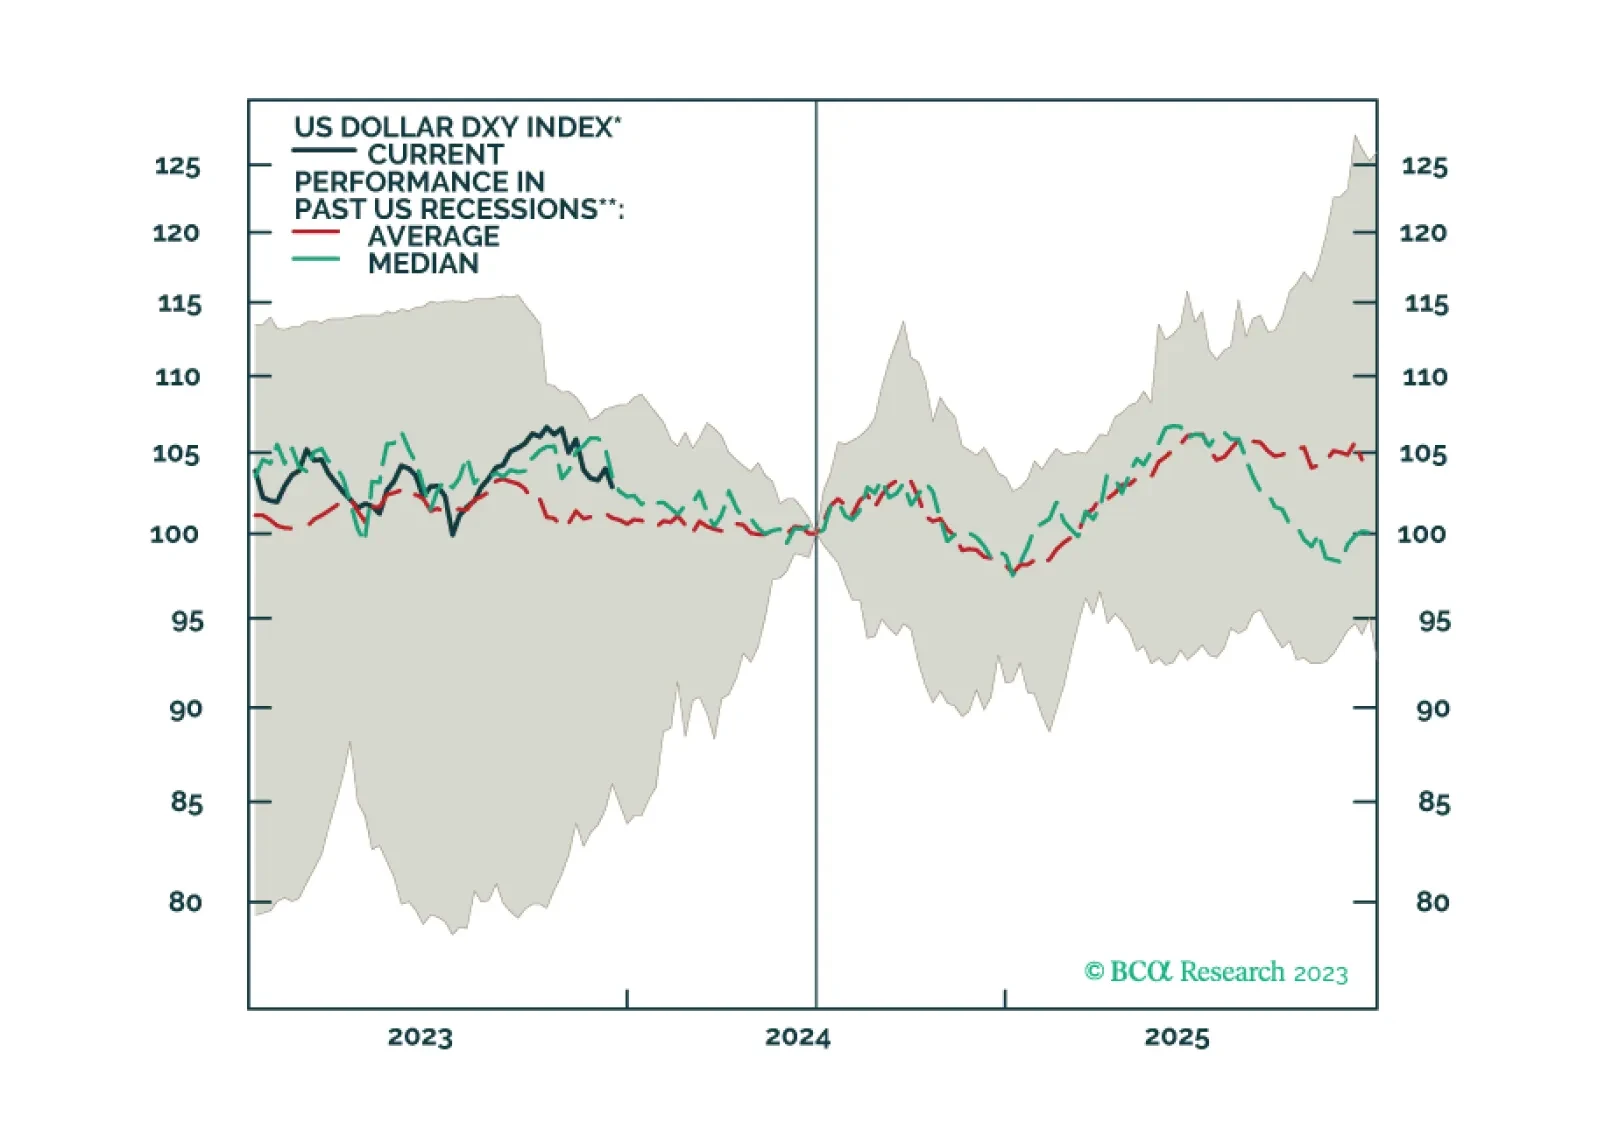
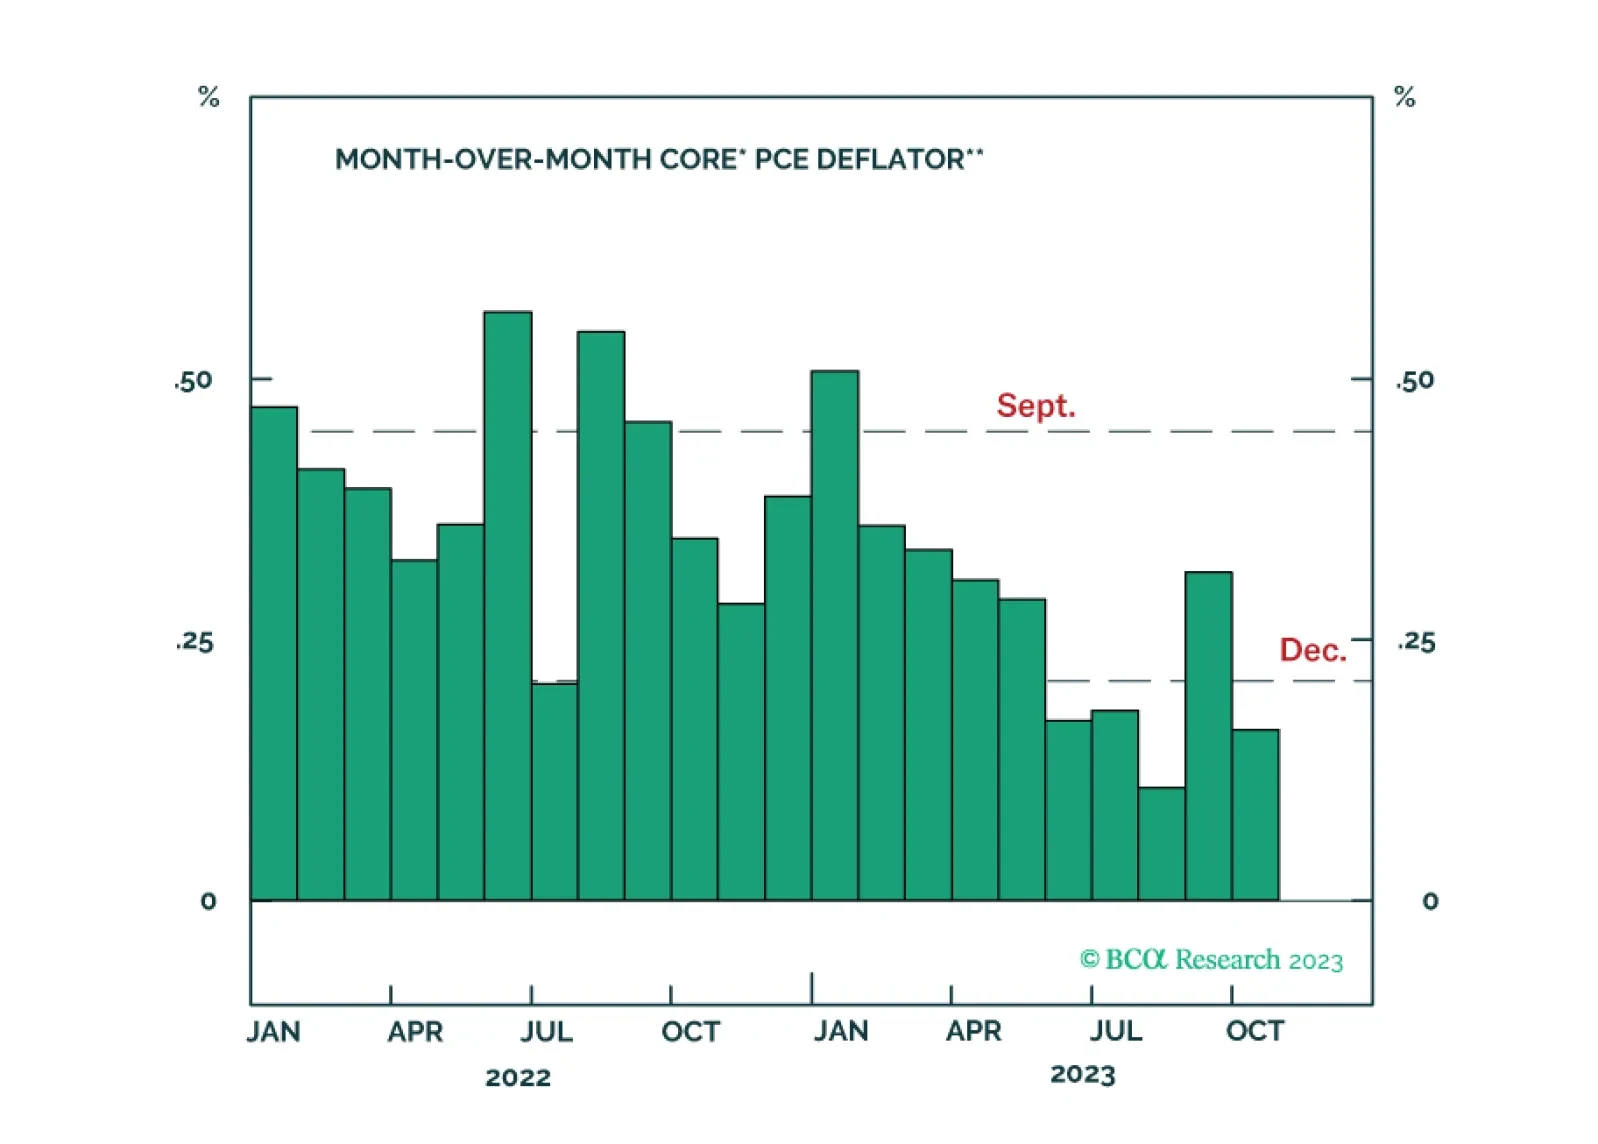
Our US bond team’s thoughts on this afternoon’s FOMC meeting and yesterday’s CPI release.