 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
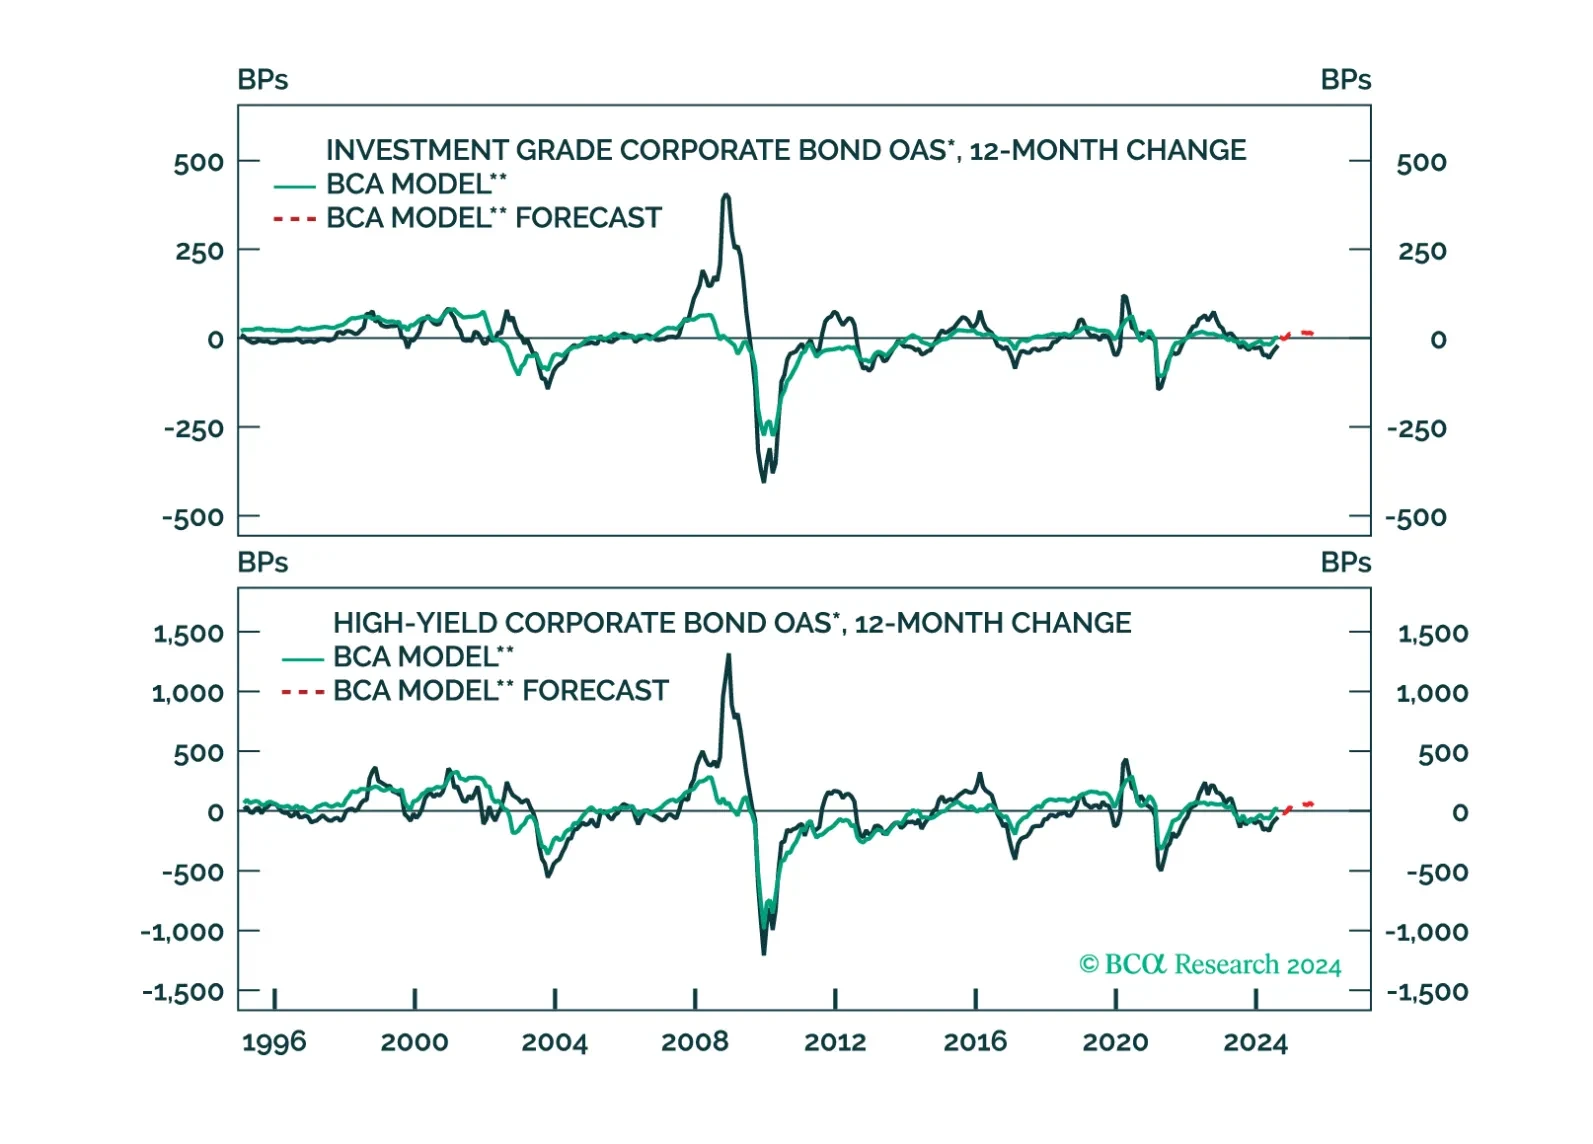
We update our corporate default rate model and consider the implications for corporate bond spreads.
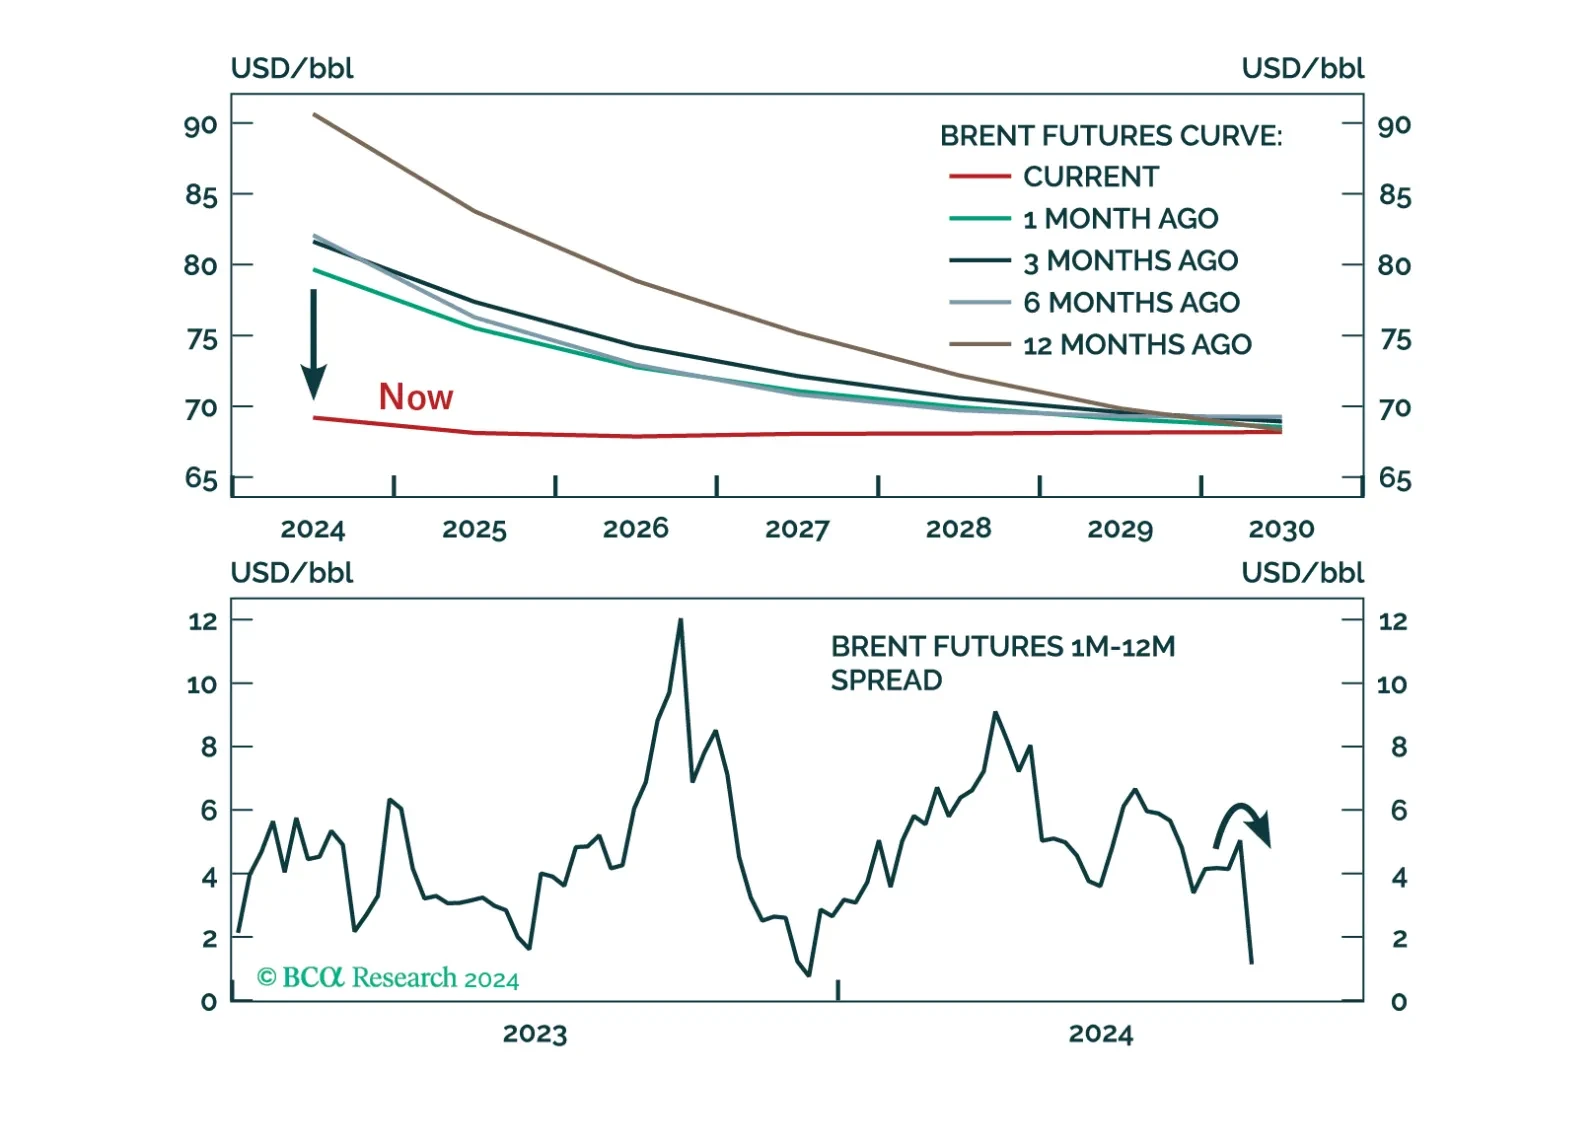
A bearish chill has engulfed oil markets. Earlier this week, Brent dropped to a near three-year low, falling below the trading range that had prevailed over the prior 18 months. In this Strategy Insight we detail why we do not believe that the worst has passed for oil markets. Rather, prices are likely to drop further over a six-to-nine-month horizon.
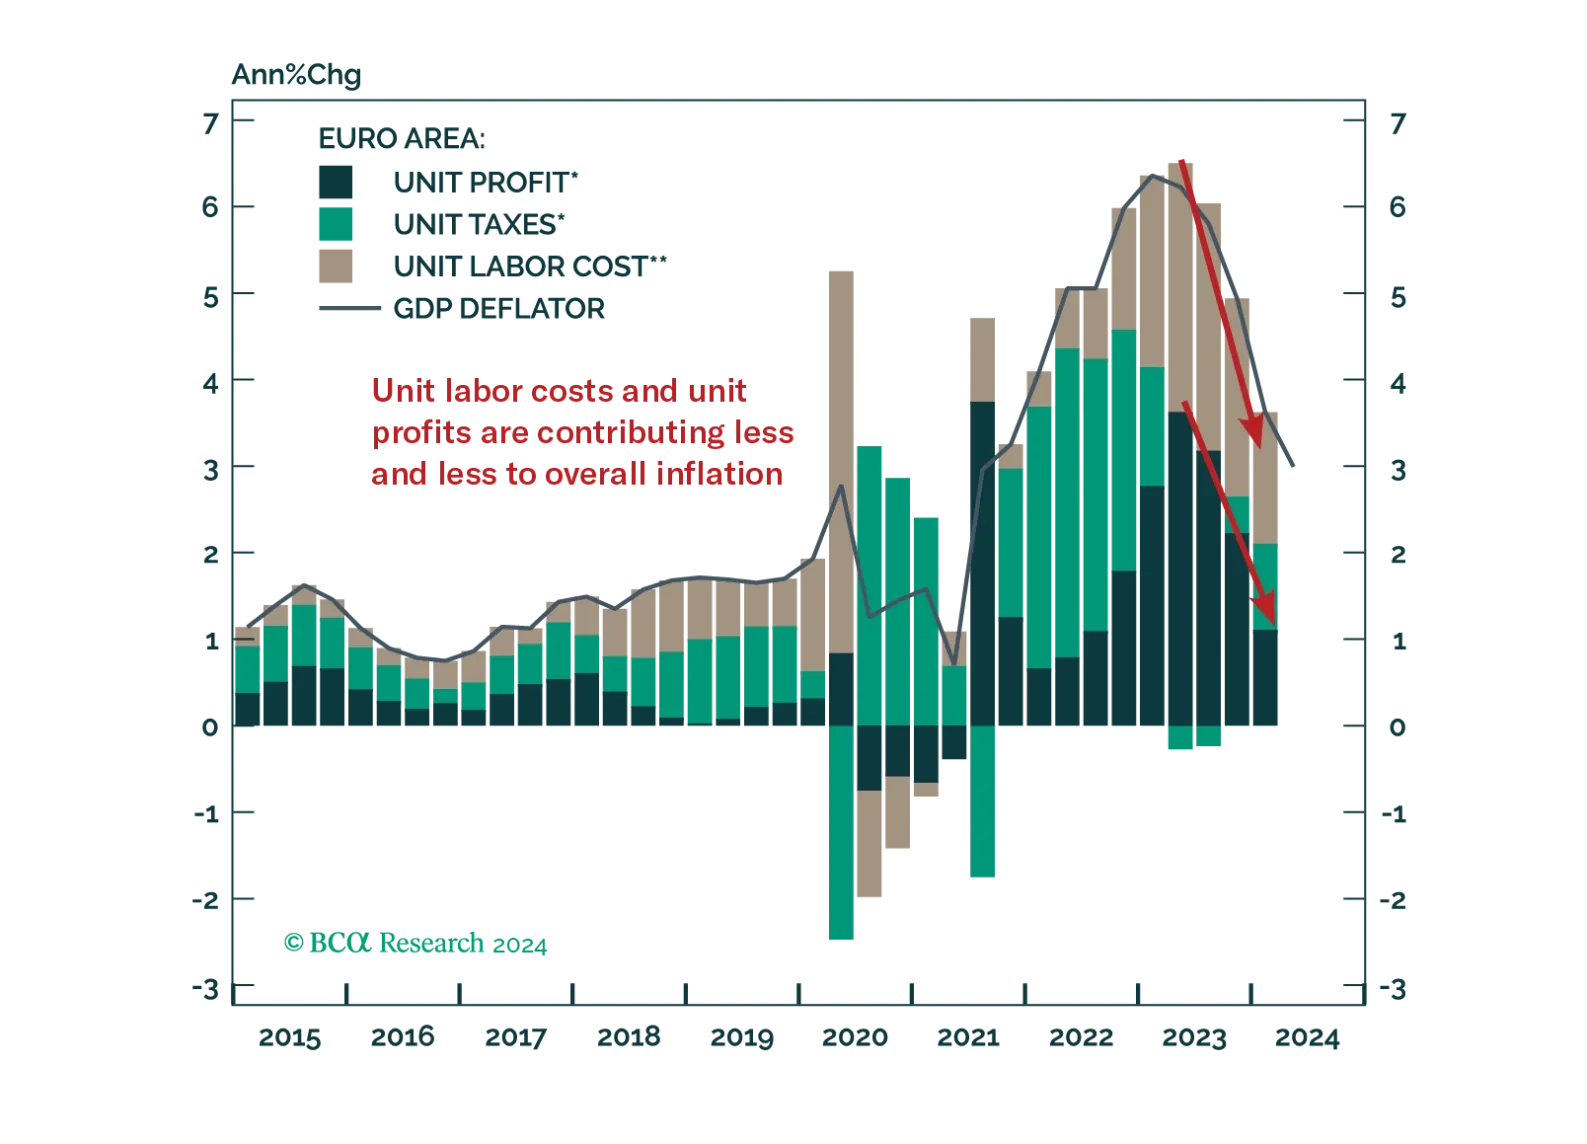
The ECB will cut rates once more this year; however, markets underprice how far it will ease next year.
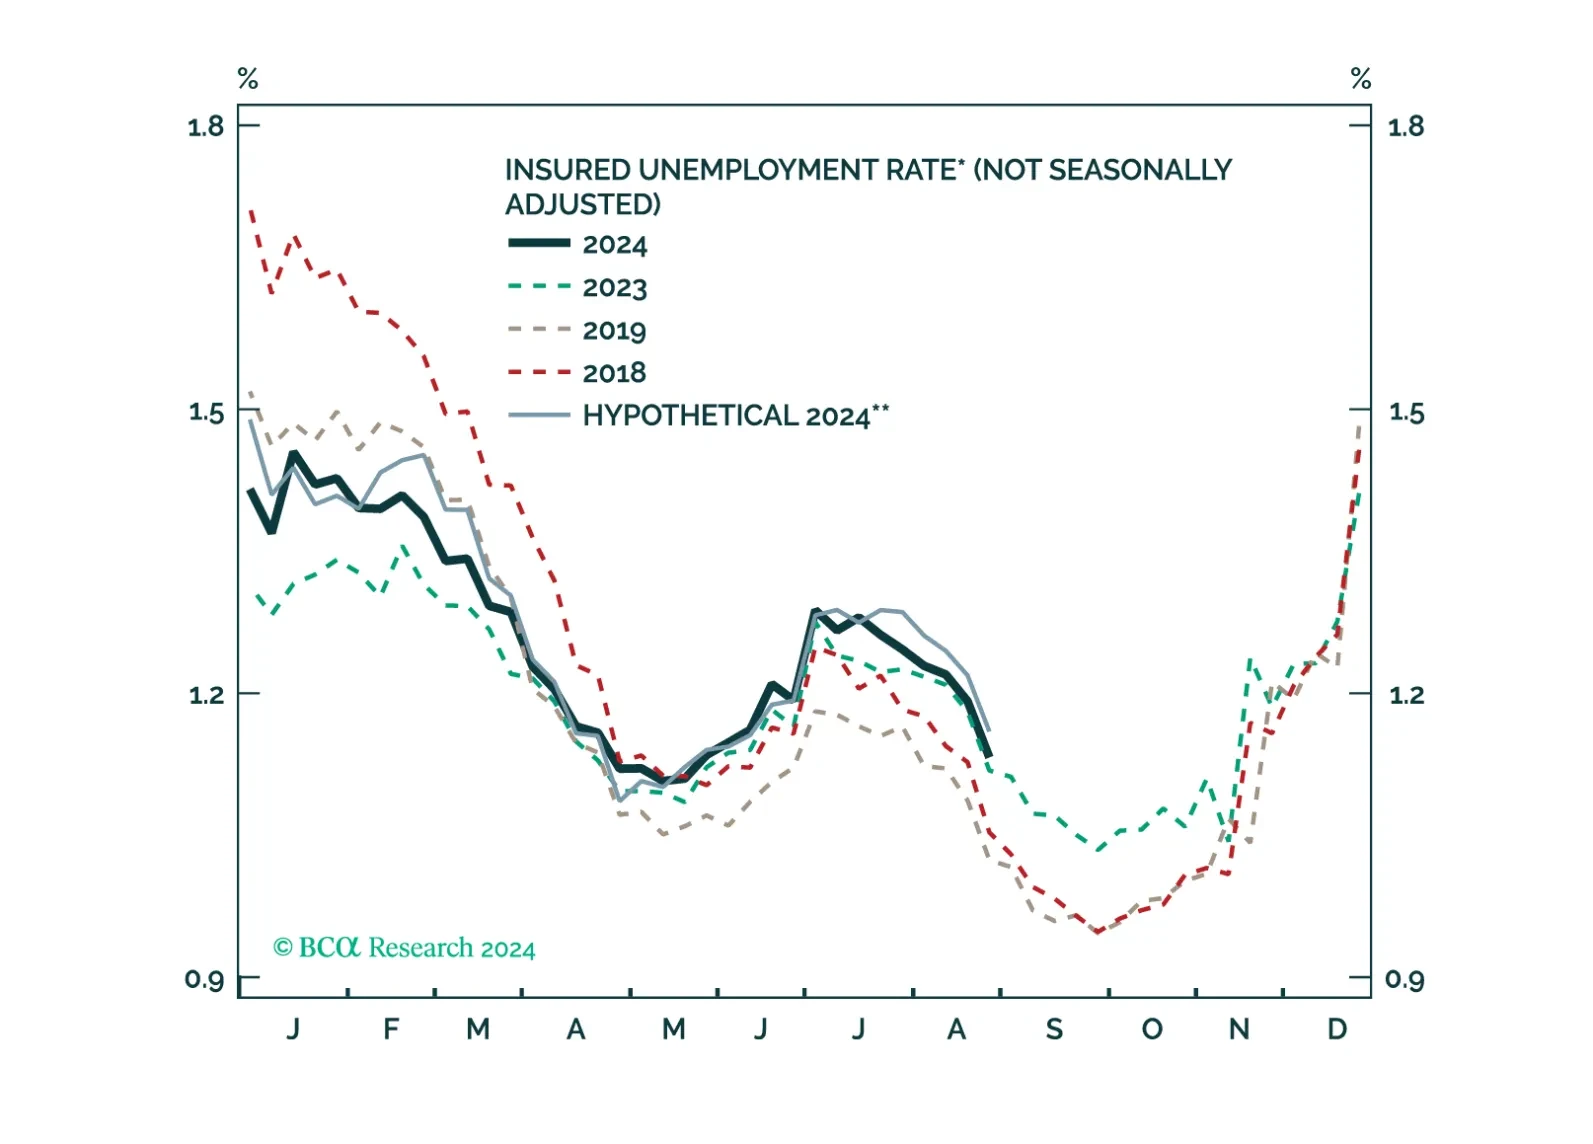
Some thoughts on this morning’s US claims report and a preview of next week’s FOMC meeting.
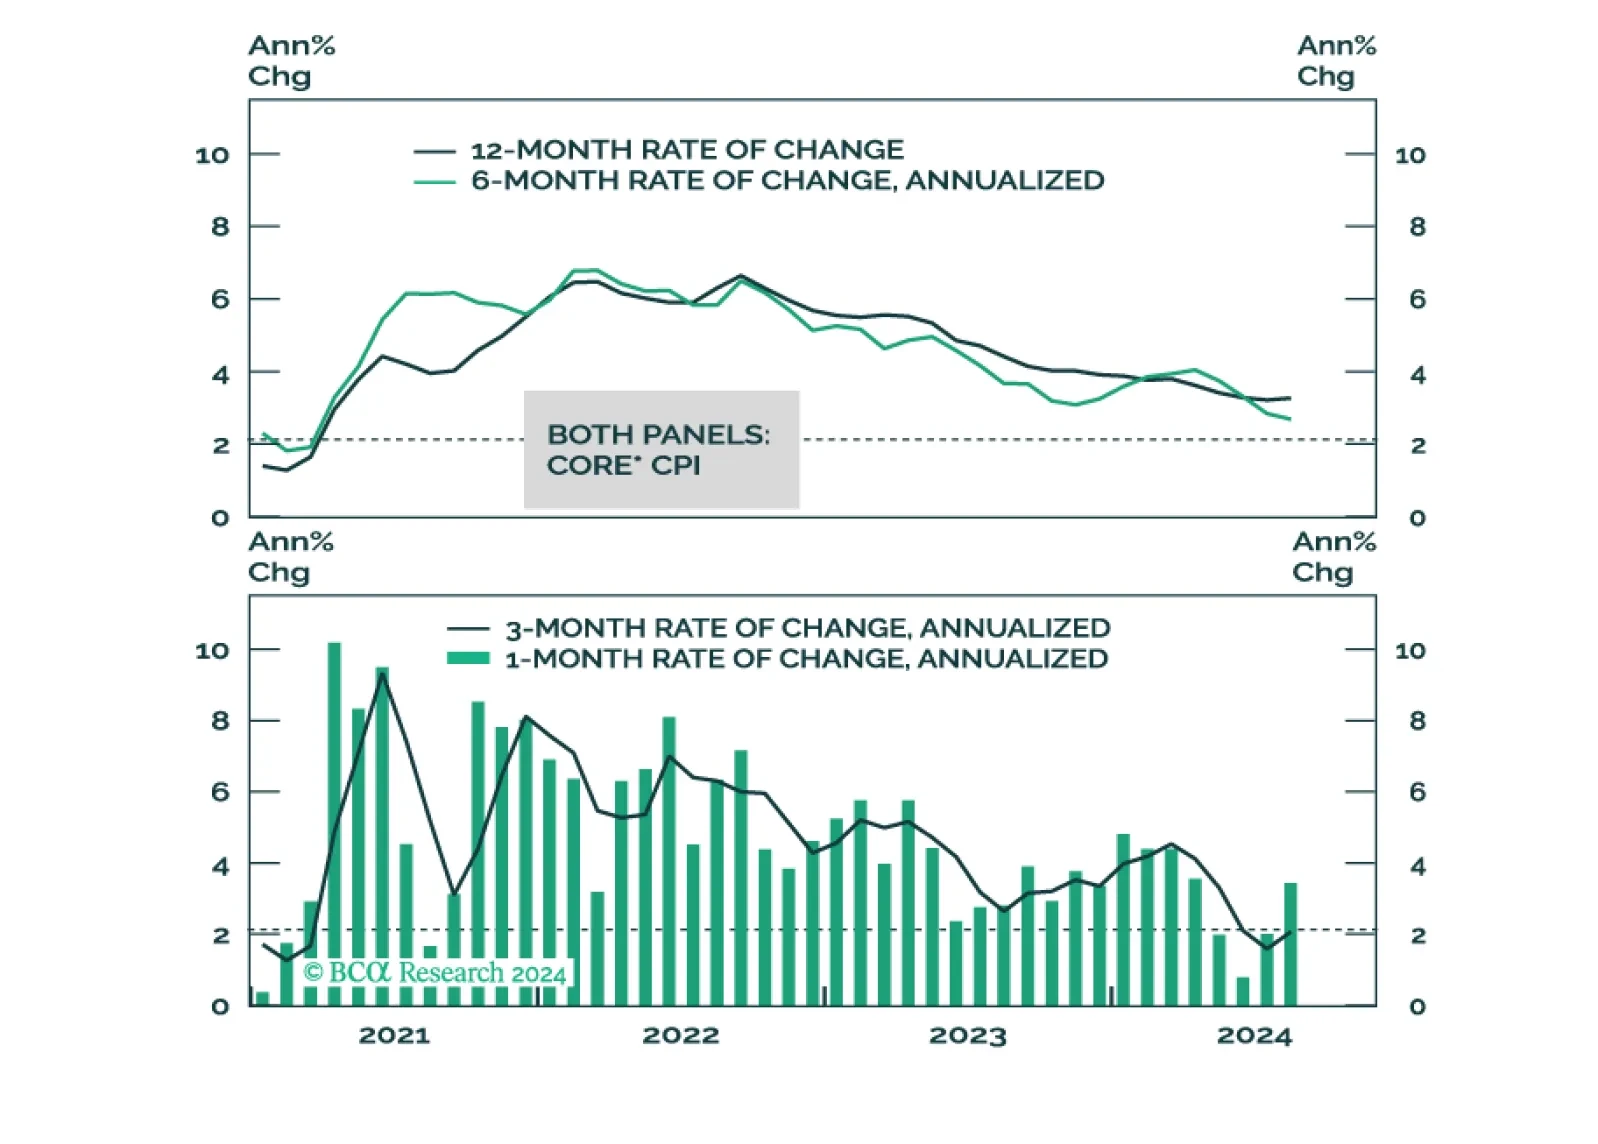
Our reaction to this morning’s CPI report and what it means for Fed policy.

This report looks at the latest developments in G10 economies and implications for bond and FX market strategy.
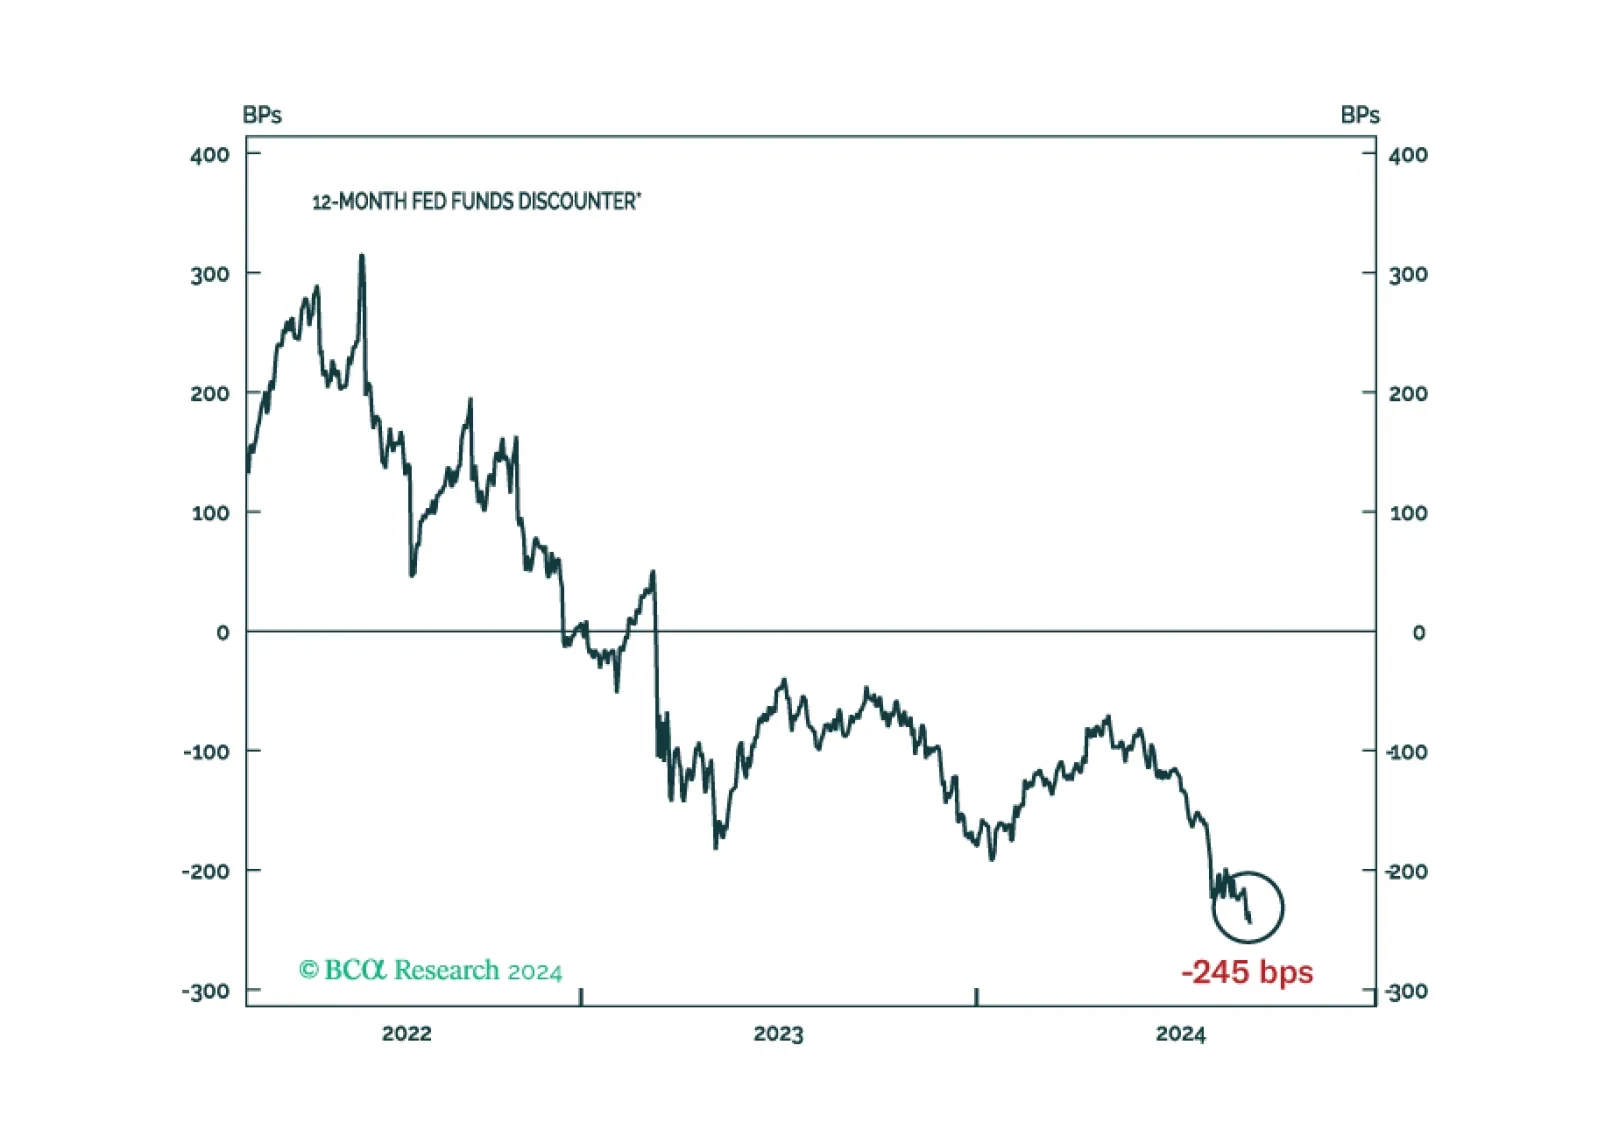
This morning's employment report, particularly the downward revisions to prior months, strengthens our conviction that the US economy is headed for recession.
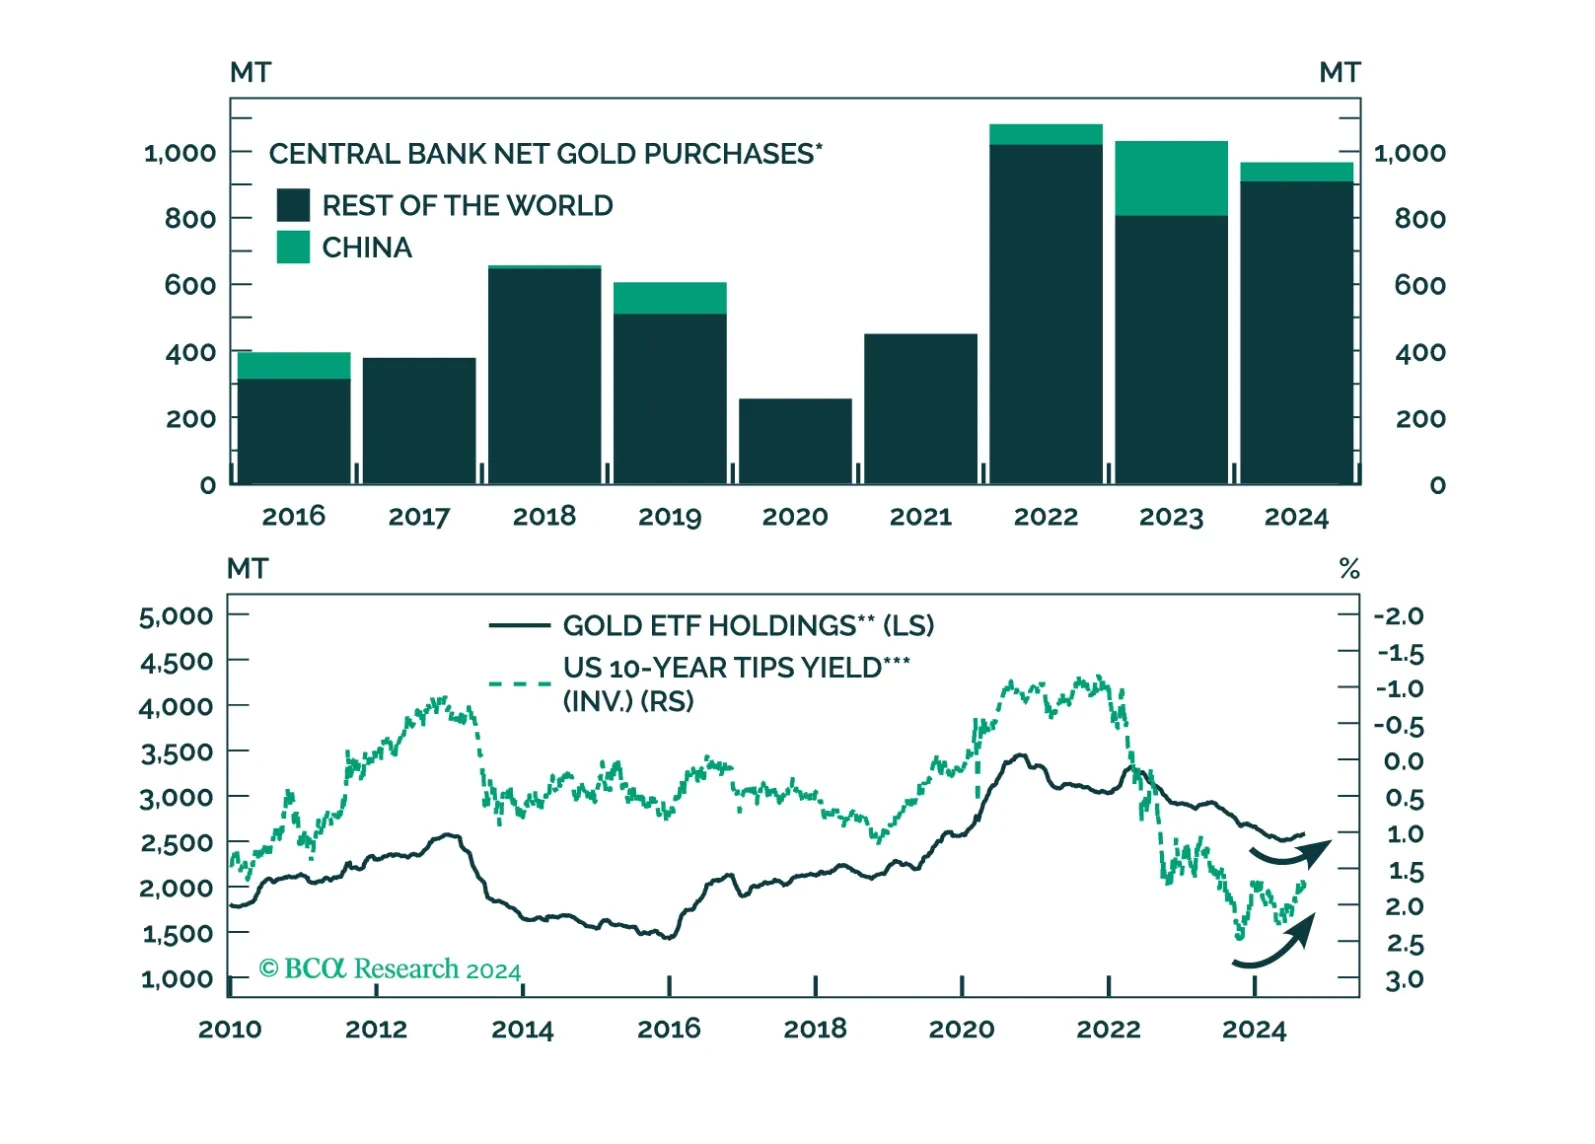
Central bank gold buying is likely to remain a tailwind for the yellow metal, supporting a continuation of the rally over the coming years. We maintain a long strategic position in COMEX gold and recommend an overweight to the yellow metal within commodity portfolios.