Bank Credit Analyst
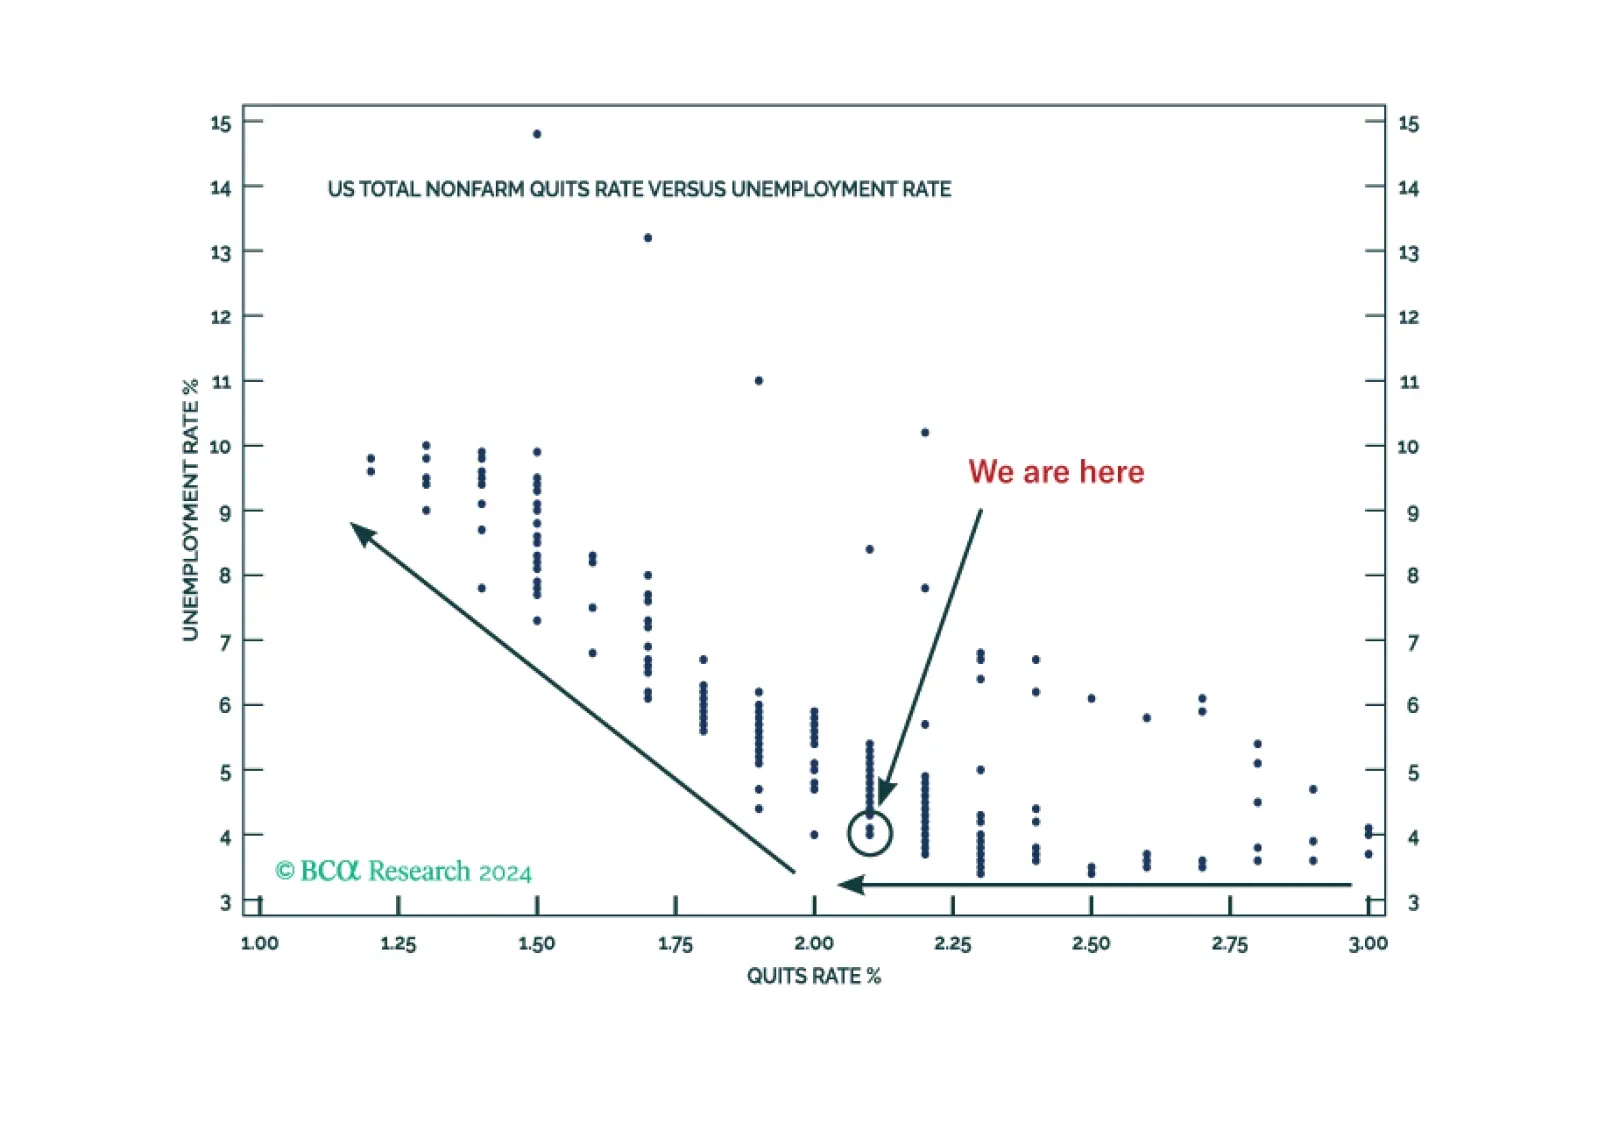
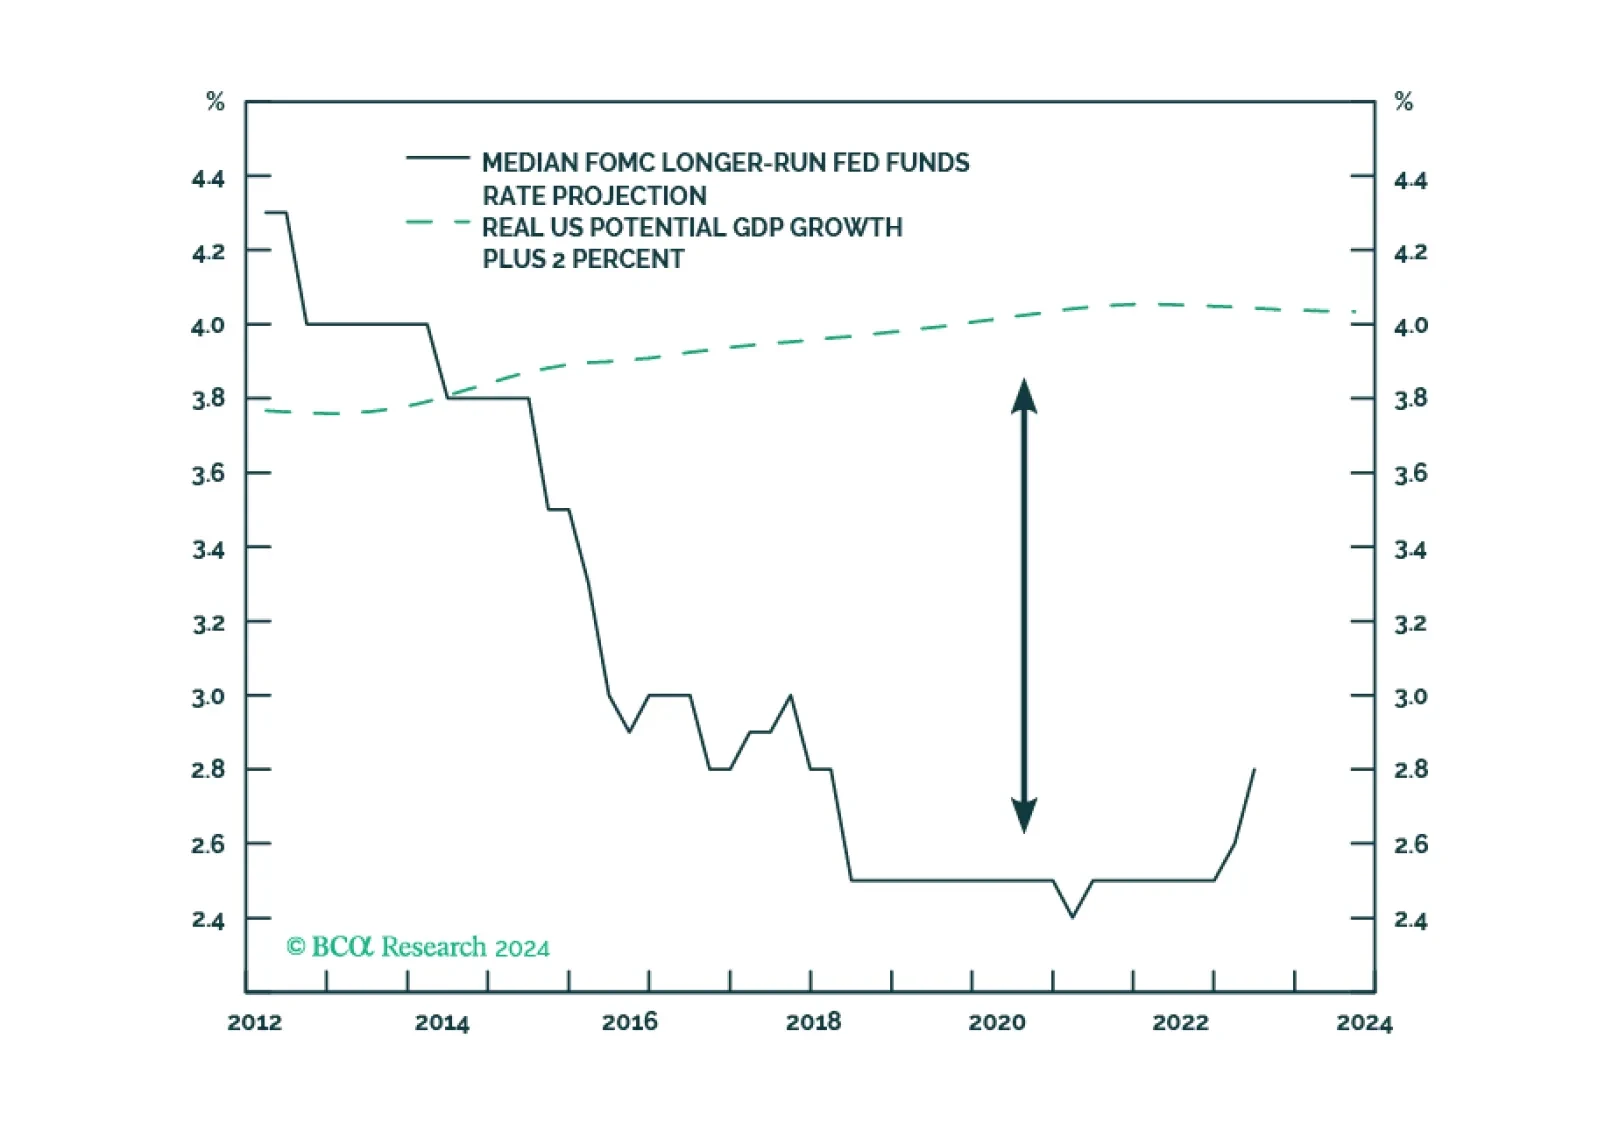
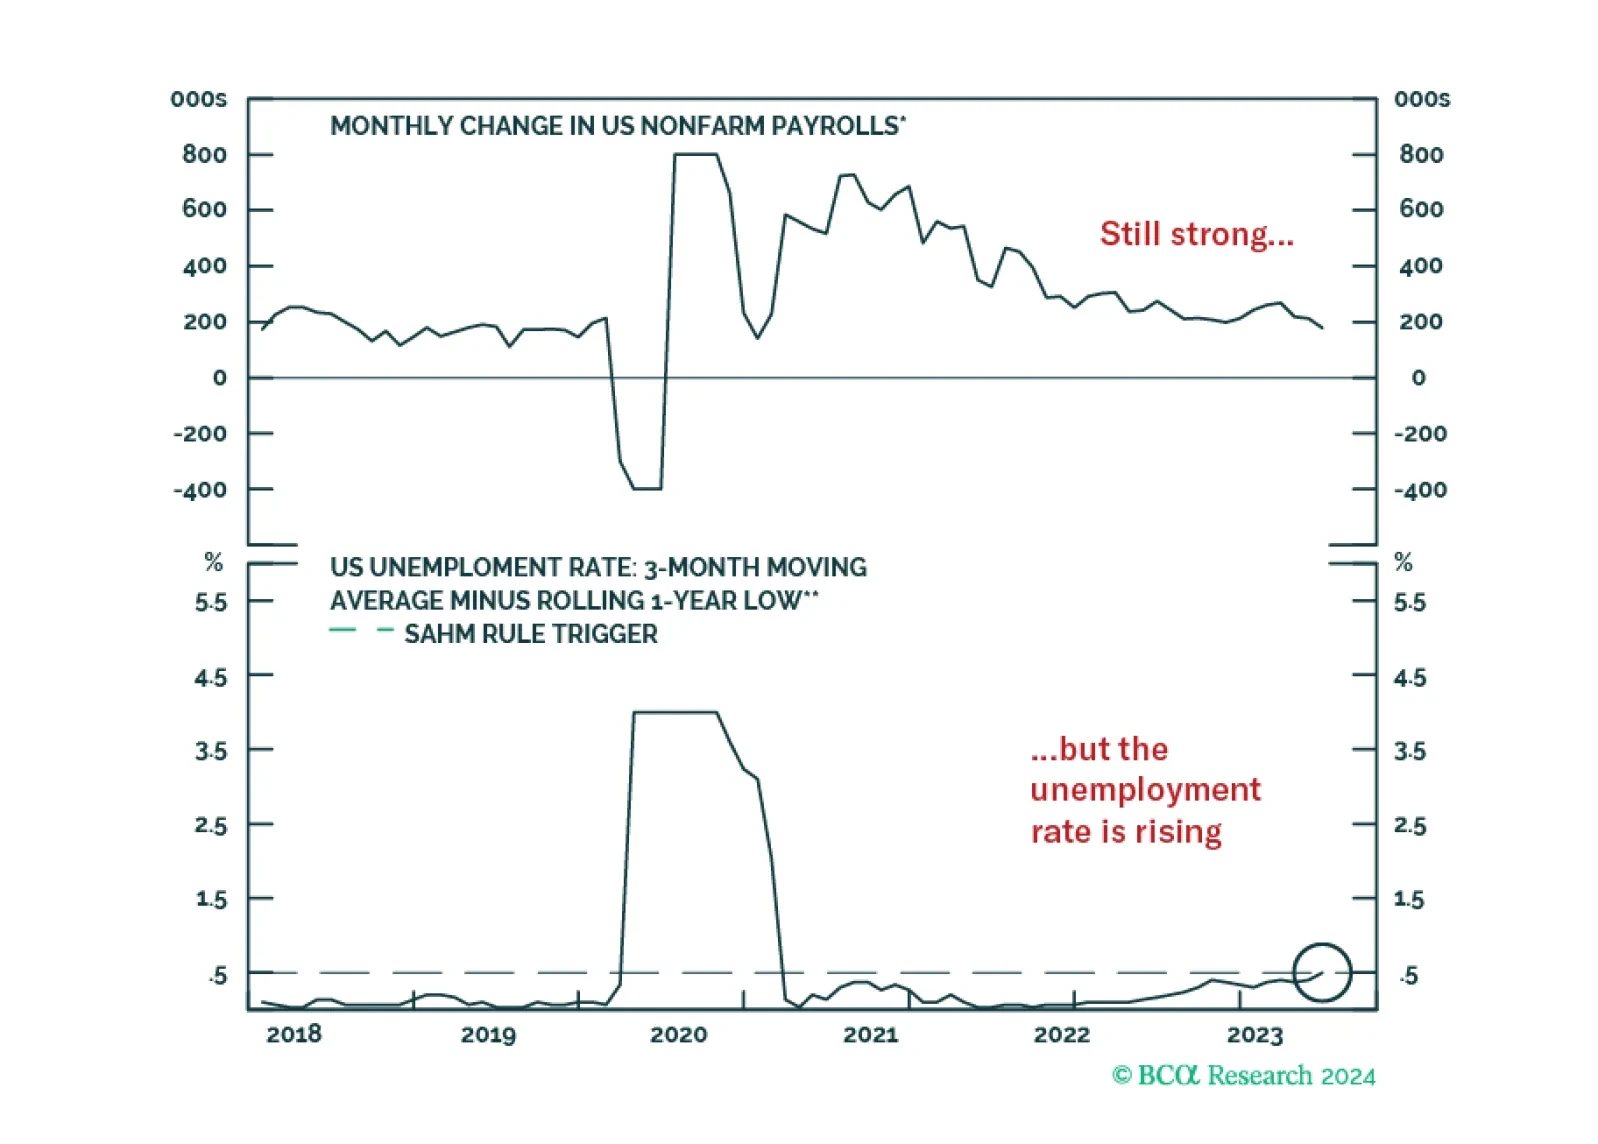
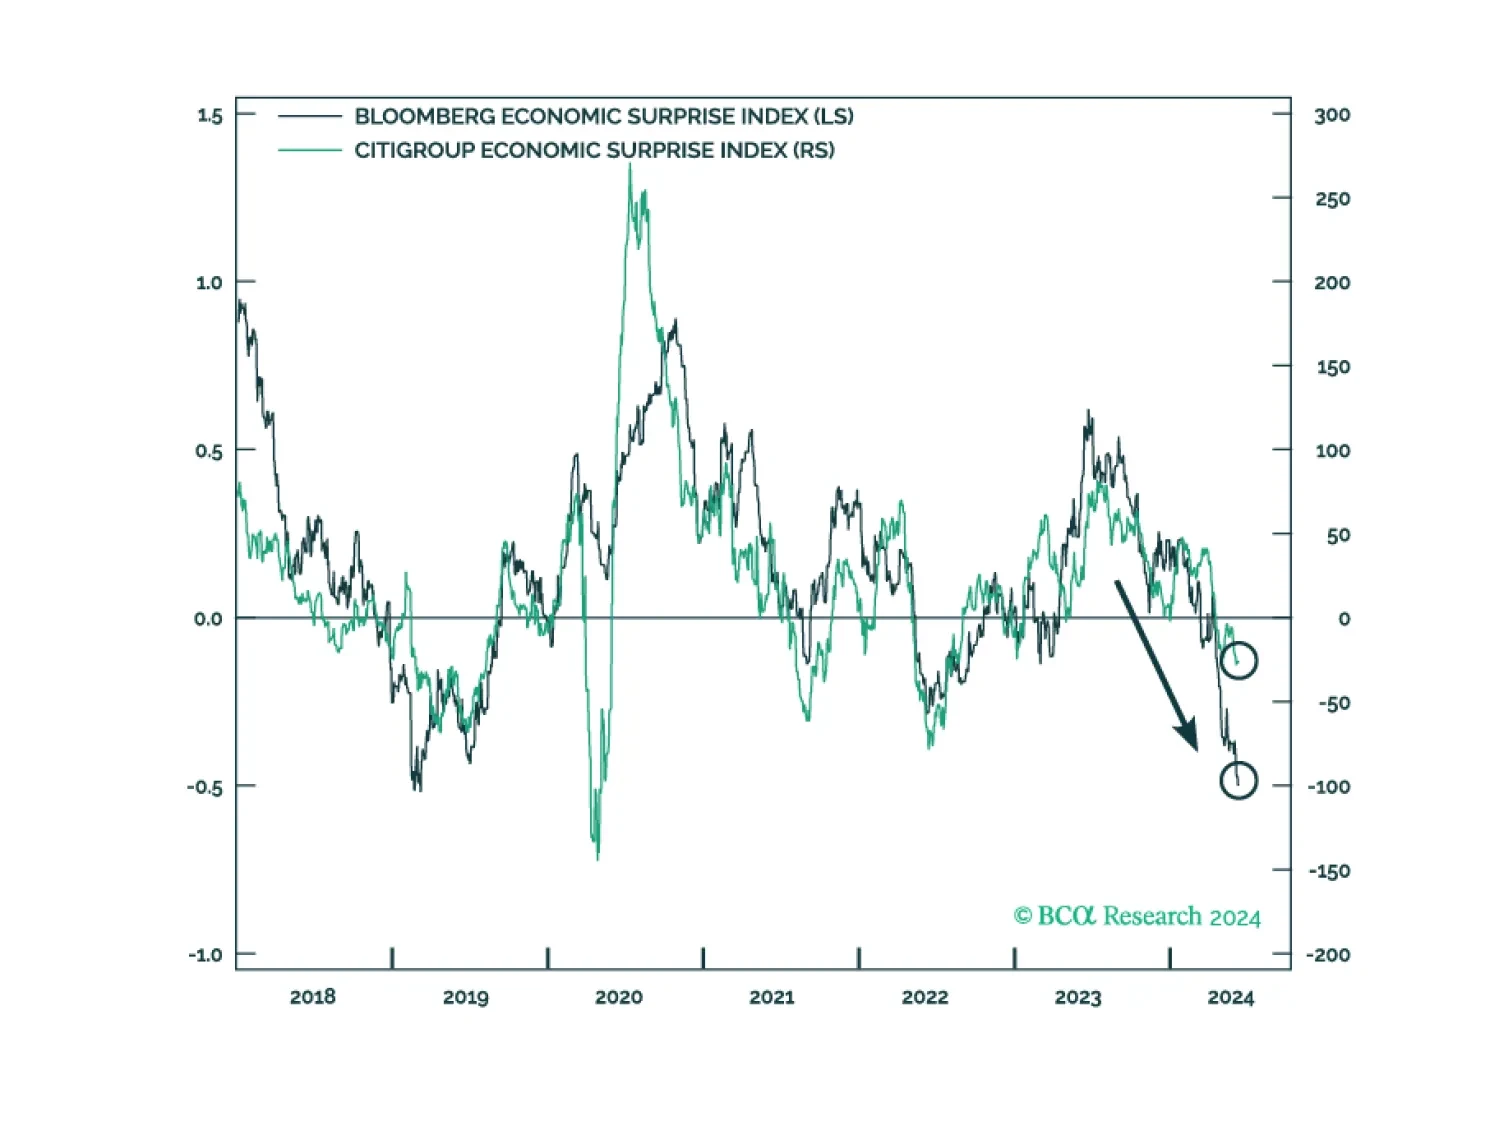
In Section I, we note that the US labor market is turning, and that the economy is indeed slowing to a recessionary tipping point. Disinflation continues, but not at a pace that would allow the Fed to cut aggressively outside of the context of a recession. We continue to expect that Donald Trump will win in November, and trade policy under a second Trump presidency represents a significant risk for investors. We continue to recommend conservative positioning over a 6-12 month time horizon. In Section II, we argue that the Fed should abandon the framework changes that it made in 2020, both to its inflation and employment objectives. If “structural dovishness” is made a permanent feature of Fed policy, investors can expect more frequent booms and busts in financial markets, and higher odds of future inflation overshoots.