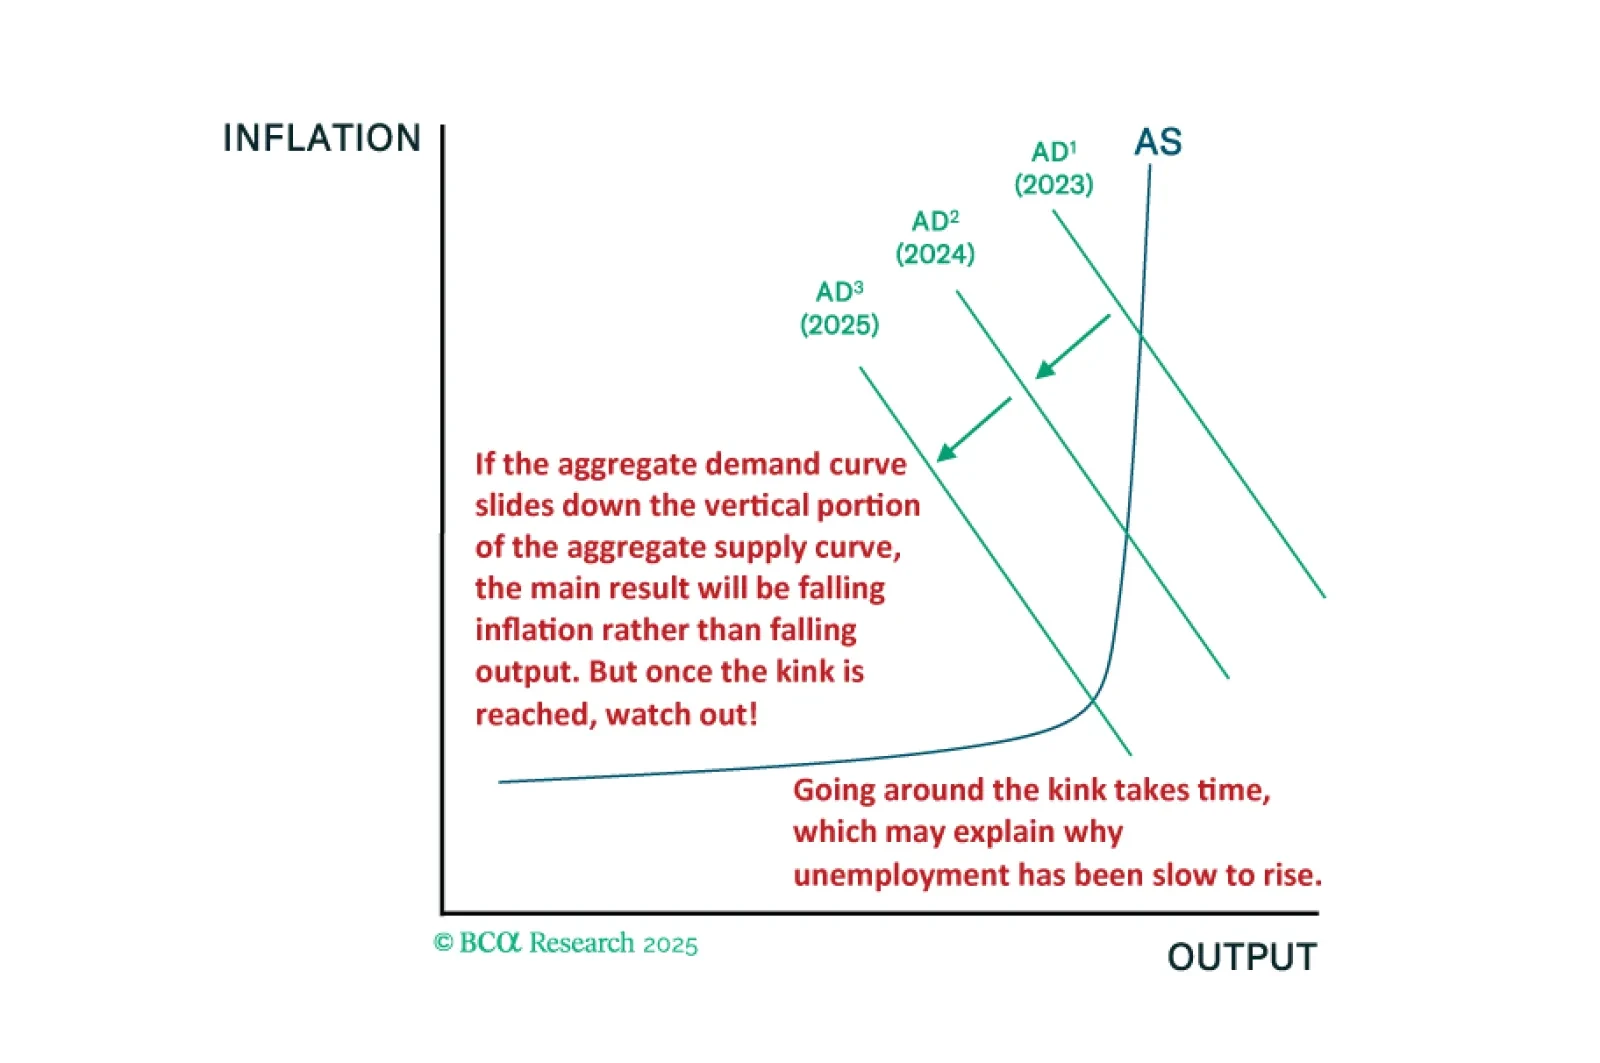
景気後退 - ハードランディング/ソフトランディング
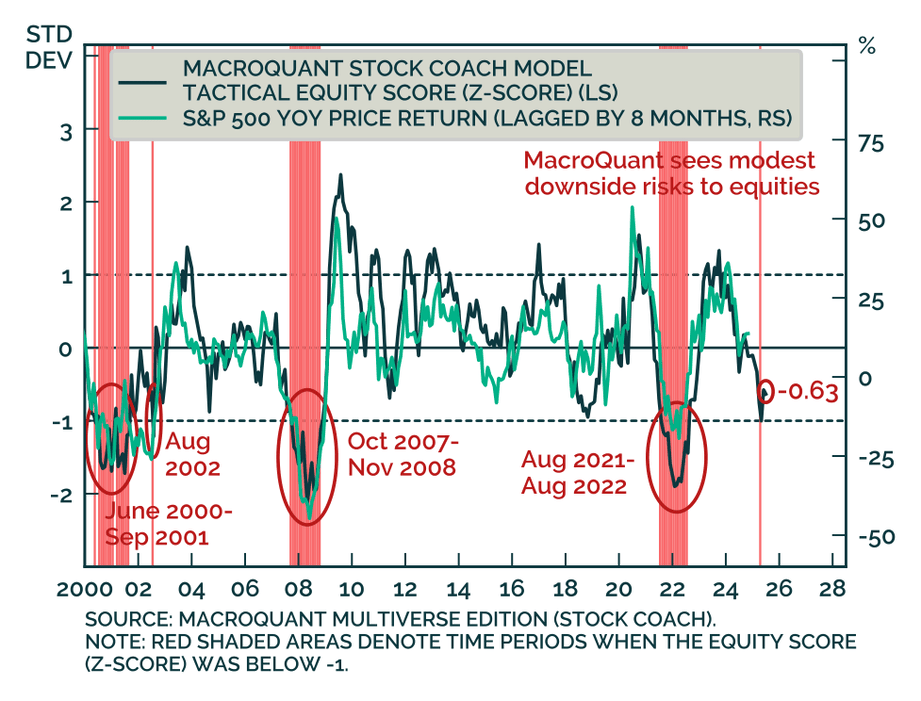
マクロクアント:重要な閾値に接近 マクロクアント:重要な閾値に接近 MacroQuantの株式モデルは、S&P 500に対する軽微な下振れリスクを示しており、控えめな株式のアンダーウェイトを支持しています。 私たちの今週のチャートは、Chanhyuck Leeが率いるグローバル・インベストメント・ストラテジーチームからのものです。…
米国の経済データが夏の数か月に安定の明確な兆候を示した場合、リセッション予測を撤回します。しかし、現時点ではそれは起きていません。株式への控えめなアンダーウェイトを維持しつつ、MacroQuantのエクイティzスコアが-1を下回った場合には、より防御的な姿勢を取ることを検討してください。
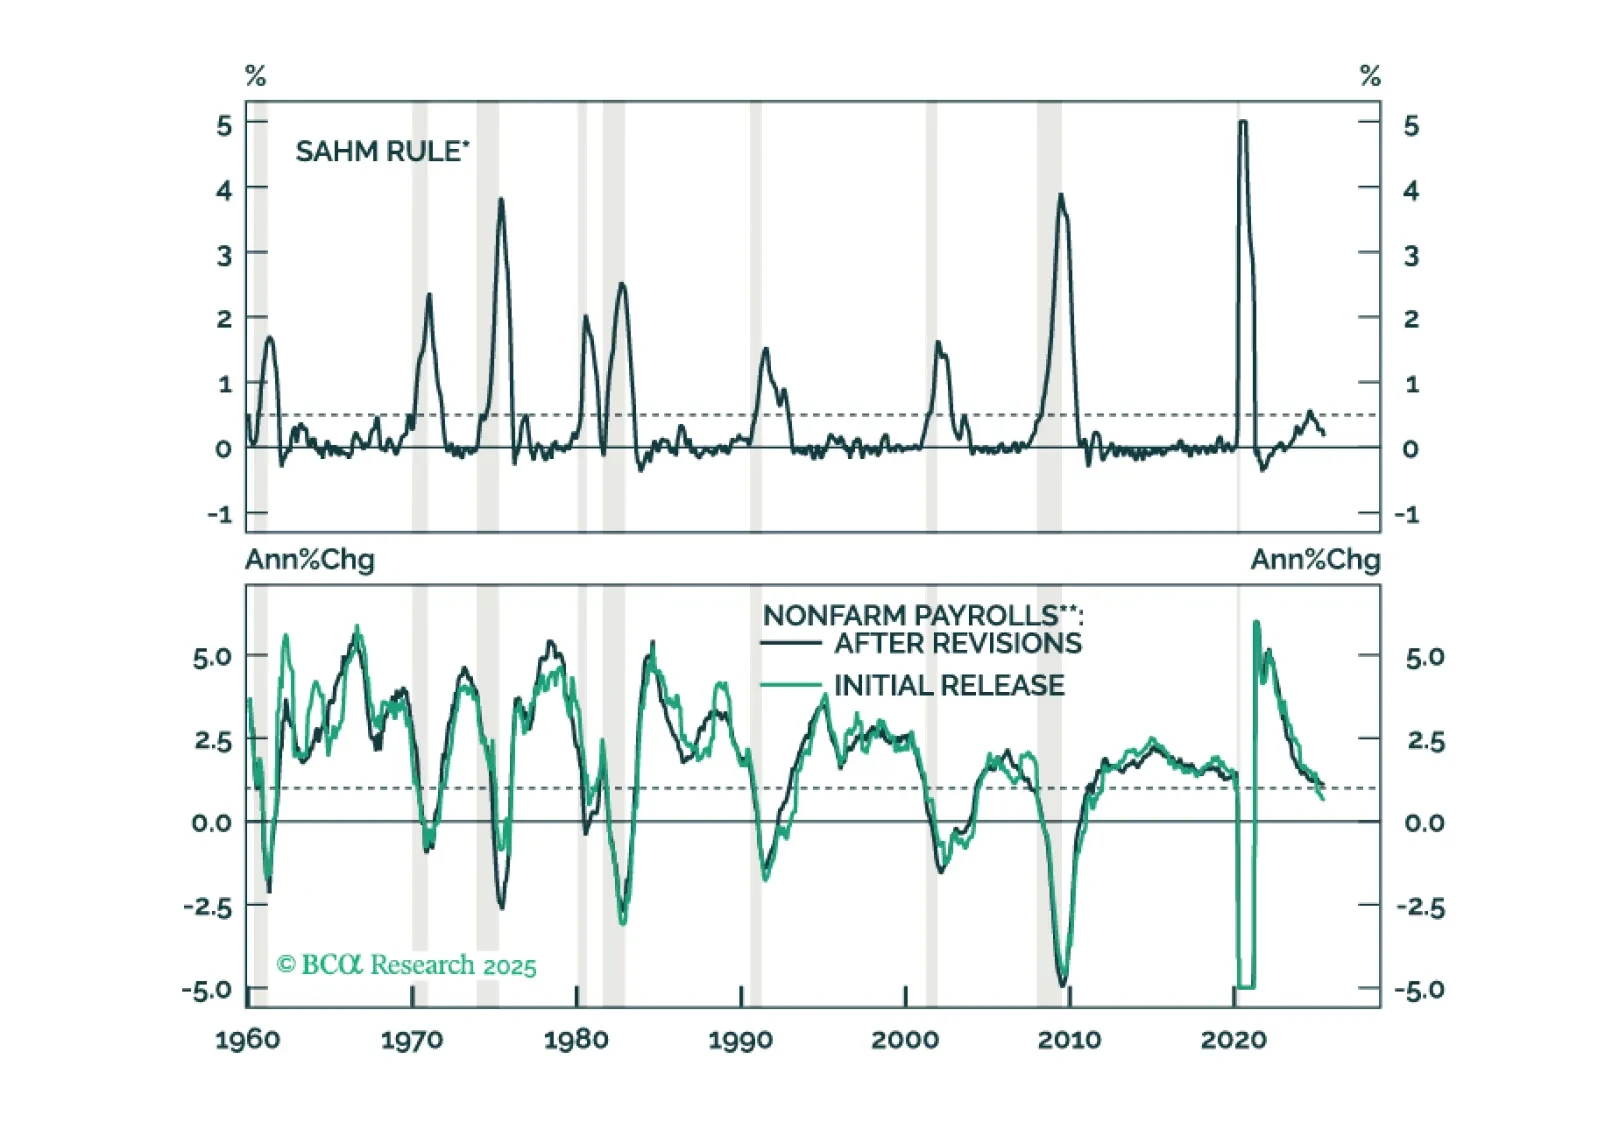
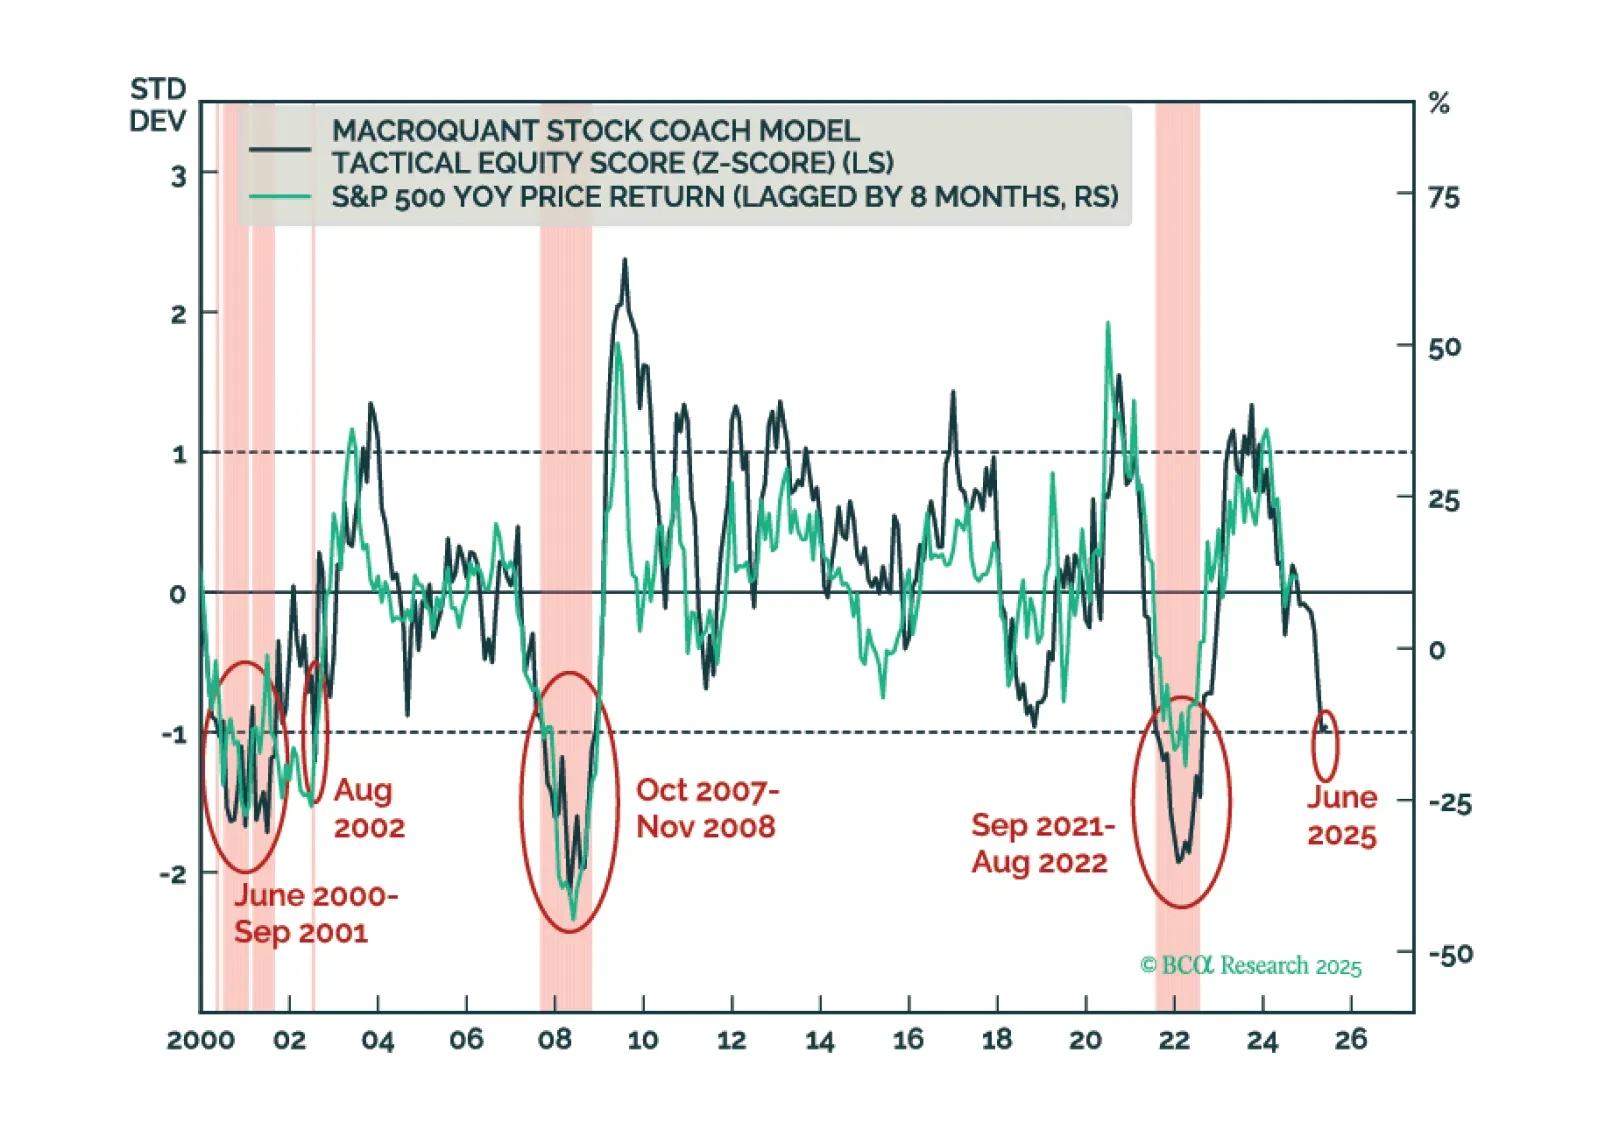
投資家はポートフォリオにおいて株式を控えめにアンダーウェイトにし、不況の具体的な兆しが見え次第、より積極的にディフェンシブな姿勢に転じるべきです。私たちはこれが数ヶ月以内に起こると考えています。

The US economy has held up better so far this year than we had expected. For the time being, investors should remain modestly underweight equities. A more aggressive underweight would be justified only once the “whites of the recession’s eyes” are visible.
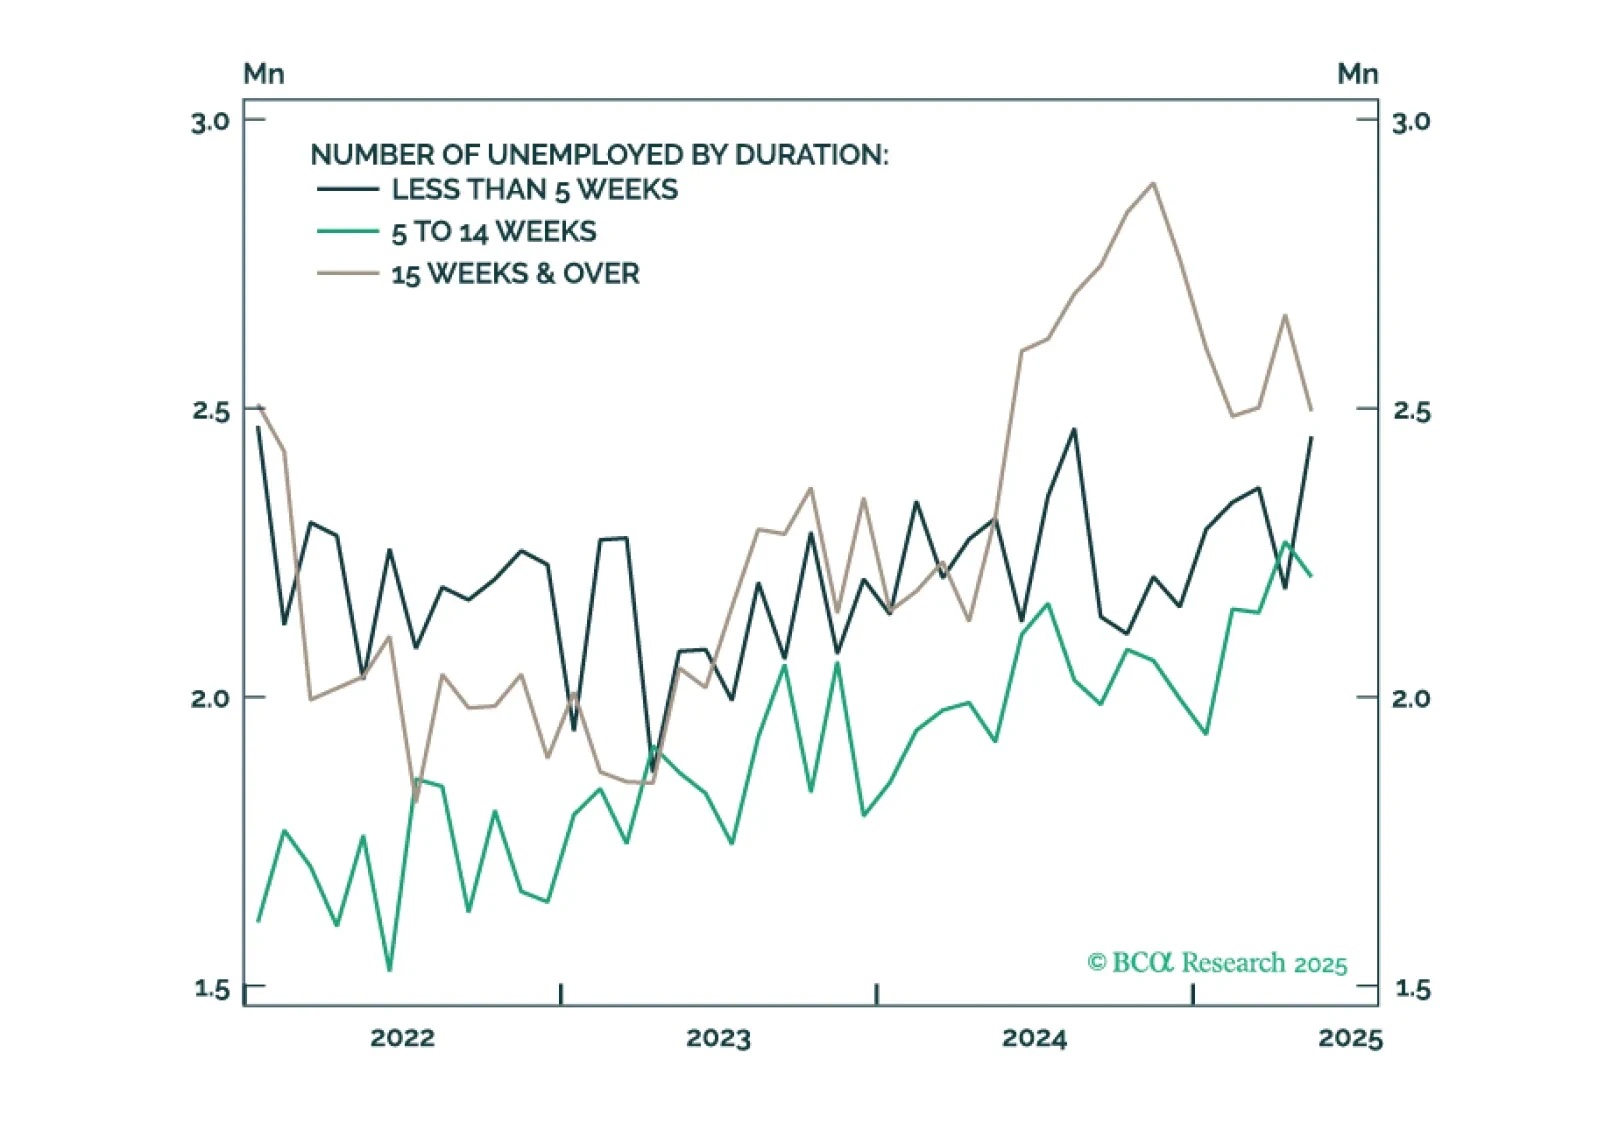
For now, measures of labor market utilization (like the unemployment rate) are only gradually weakening. But we know from history that these trends have a habit of quickly accelerating in advance of recession.
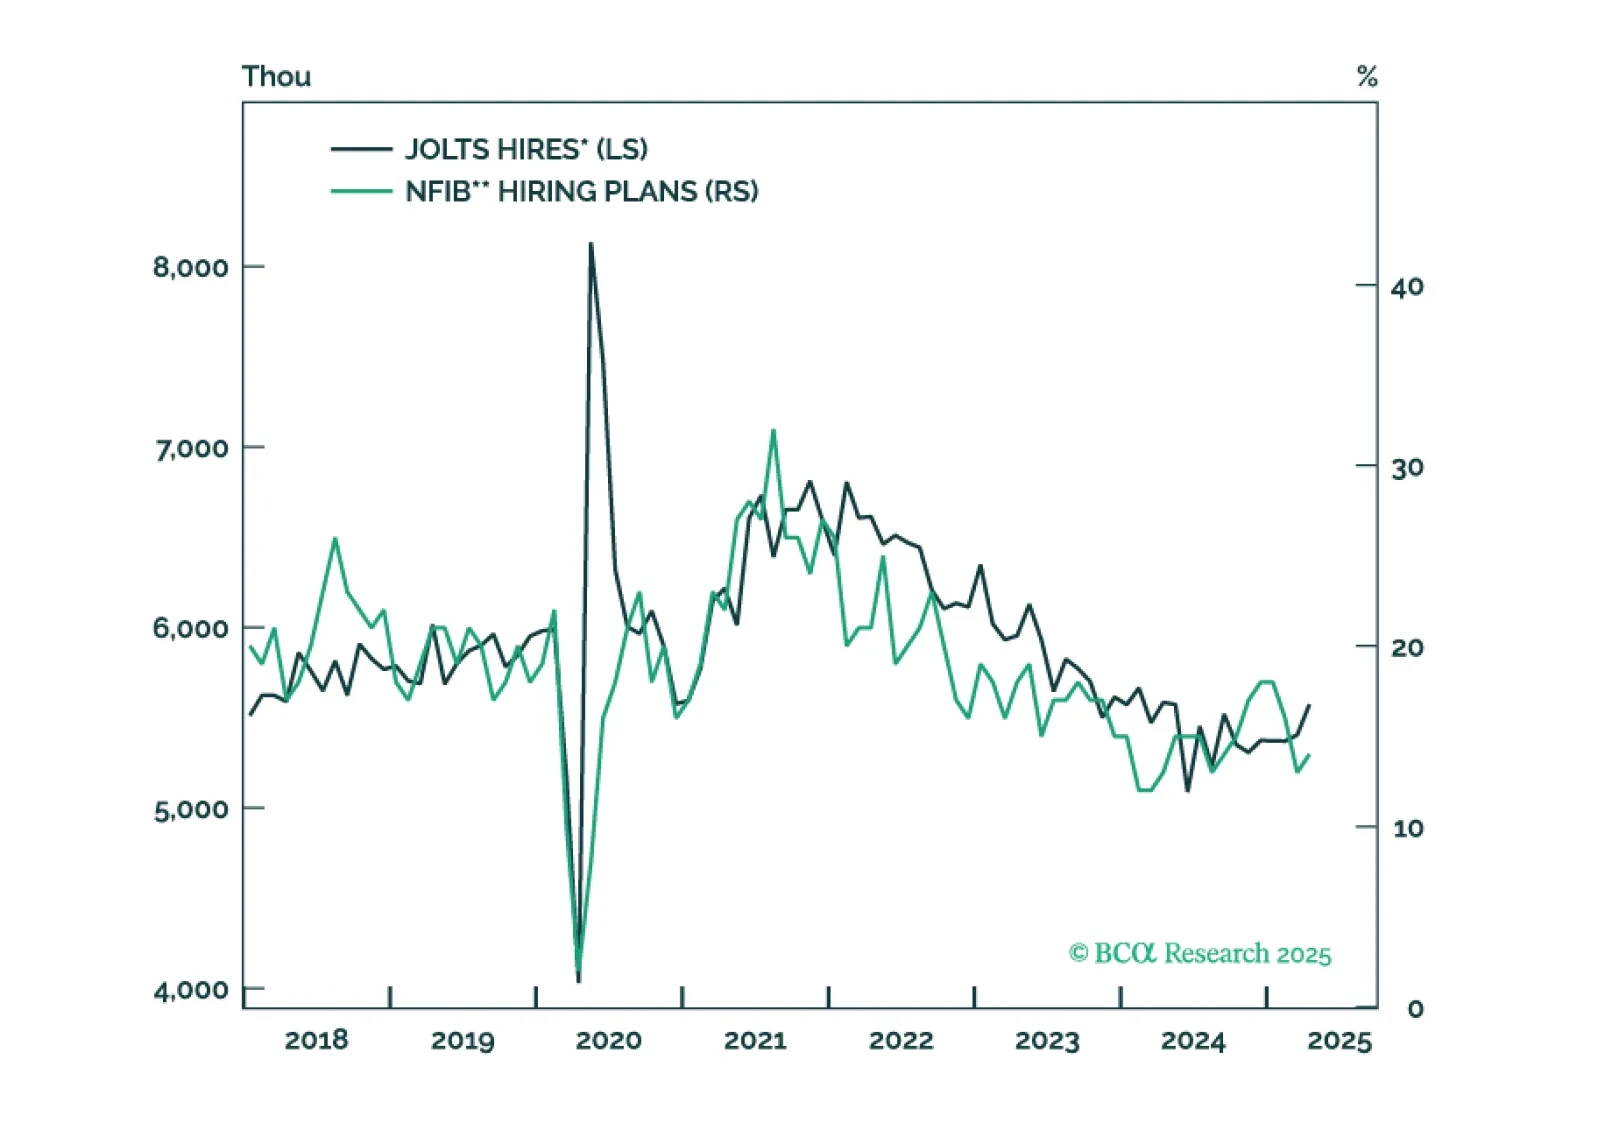
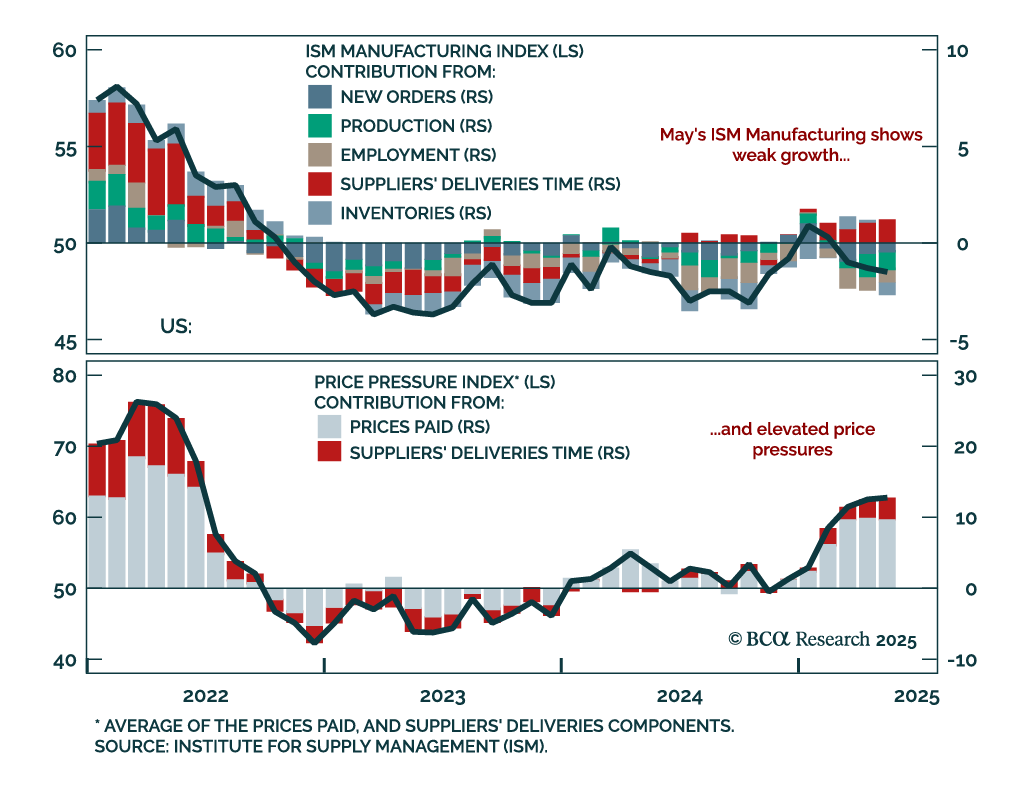
The May ISM Manufacturing Index missed expectations, reinforcing our view that recession risks remain underpriced. The headline fell to 48.5 from 48.7, while new orders and employment both rebounded slightly but remained below the 50-expansion threshold. New…