インドネシアルピア
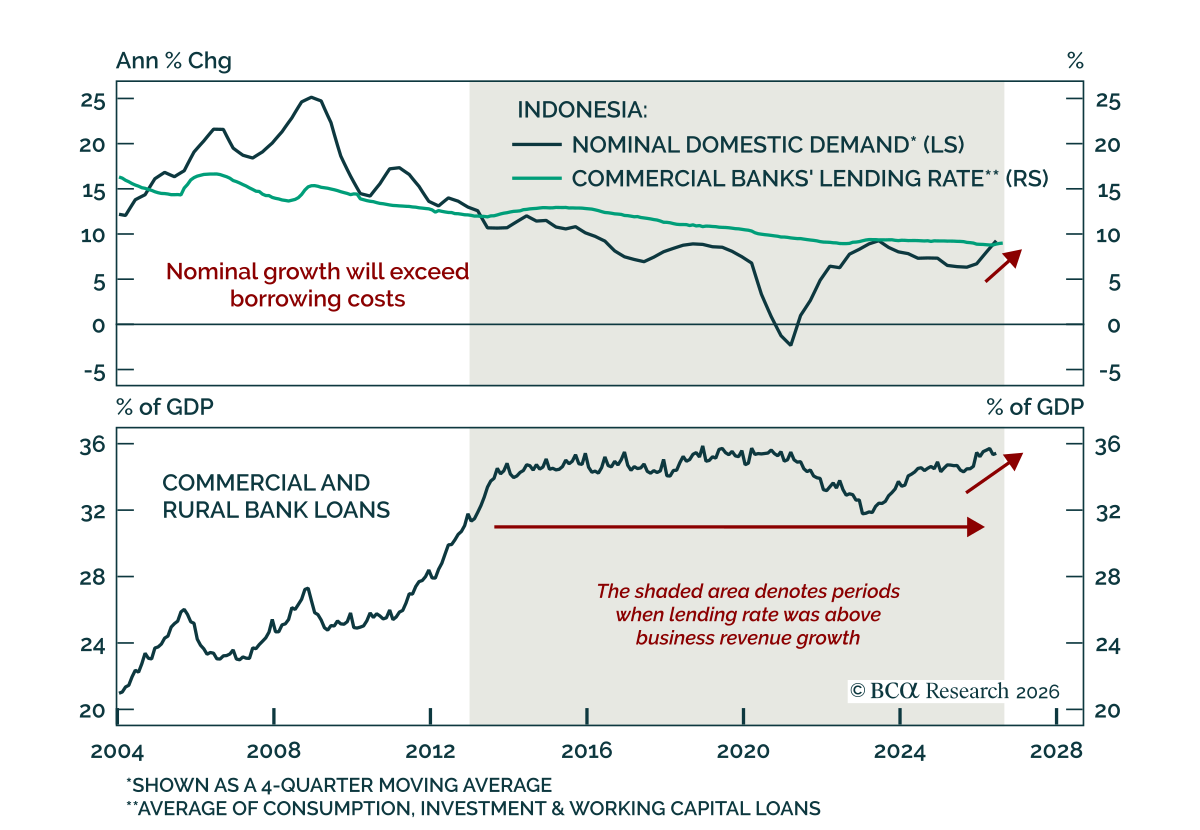
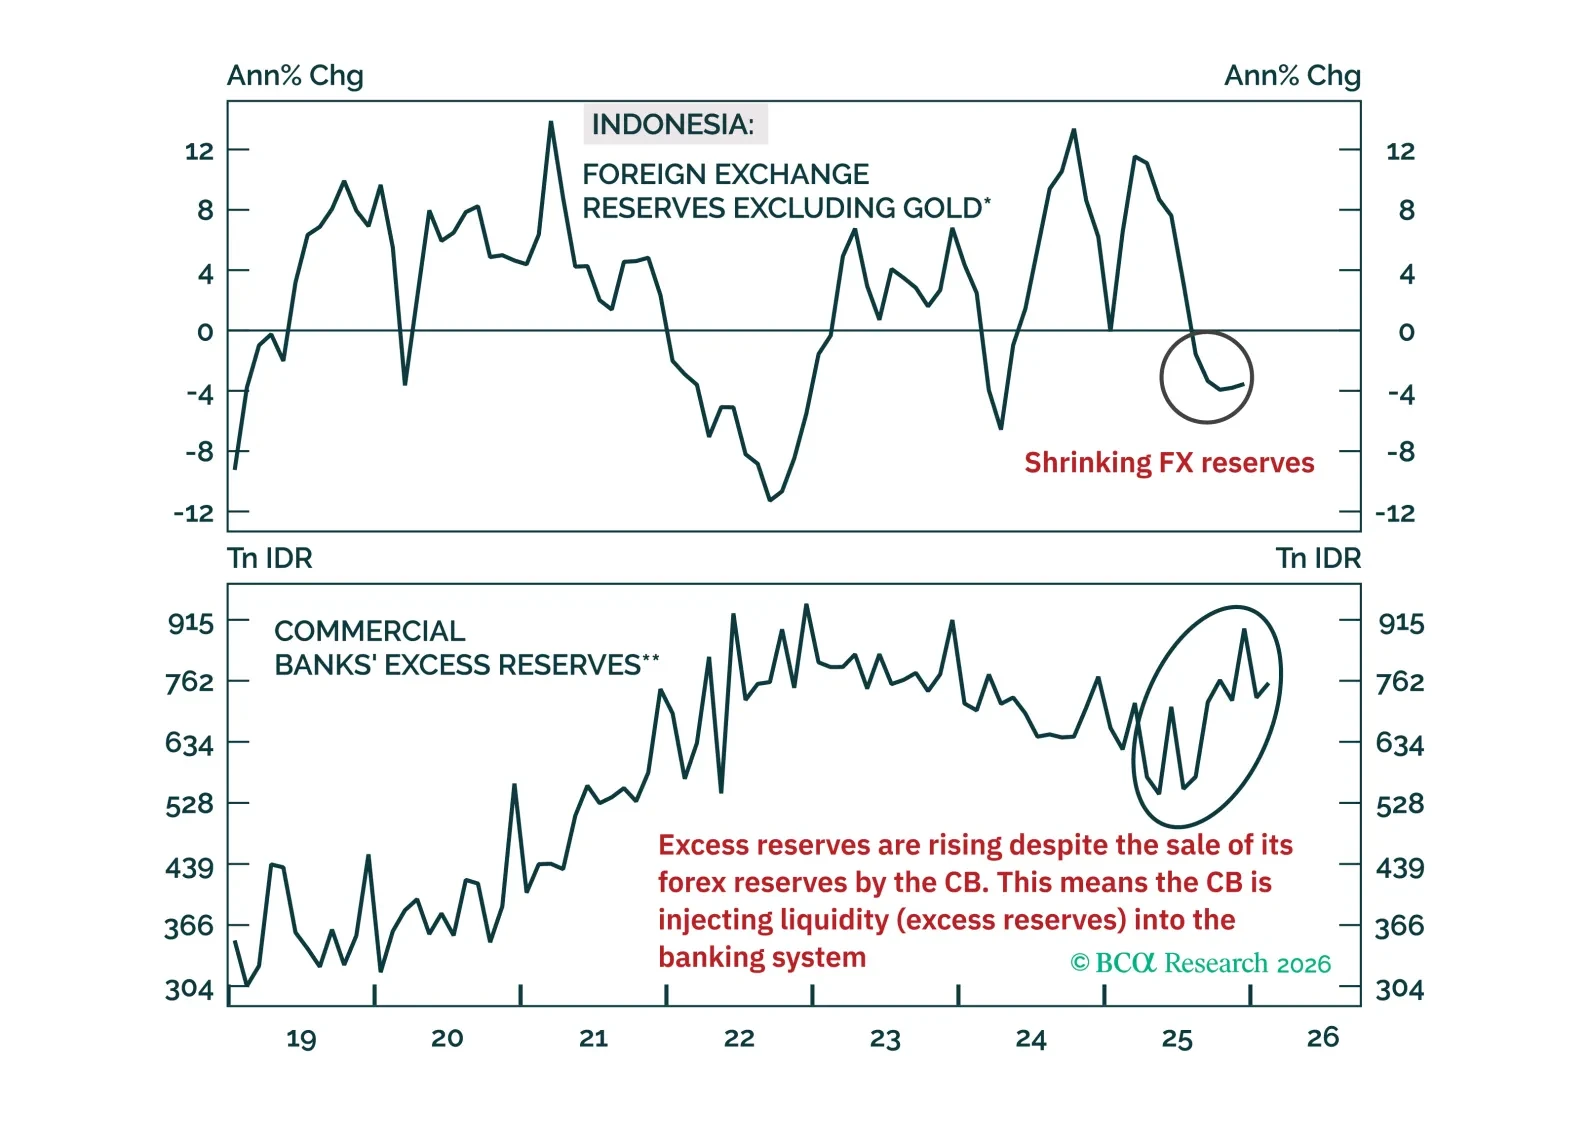
インドネシアルピアは今後も急落を続け、現地通貨建て債券の利回りは大幅に上昇するだろう。投資家は国内債券を為替ヘッジなしでショートすべきだ。
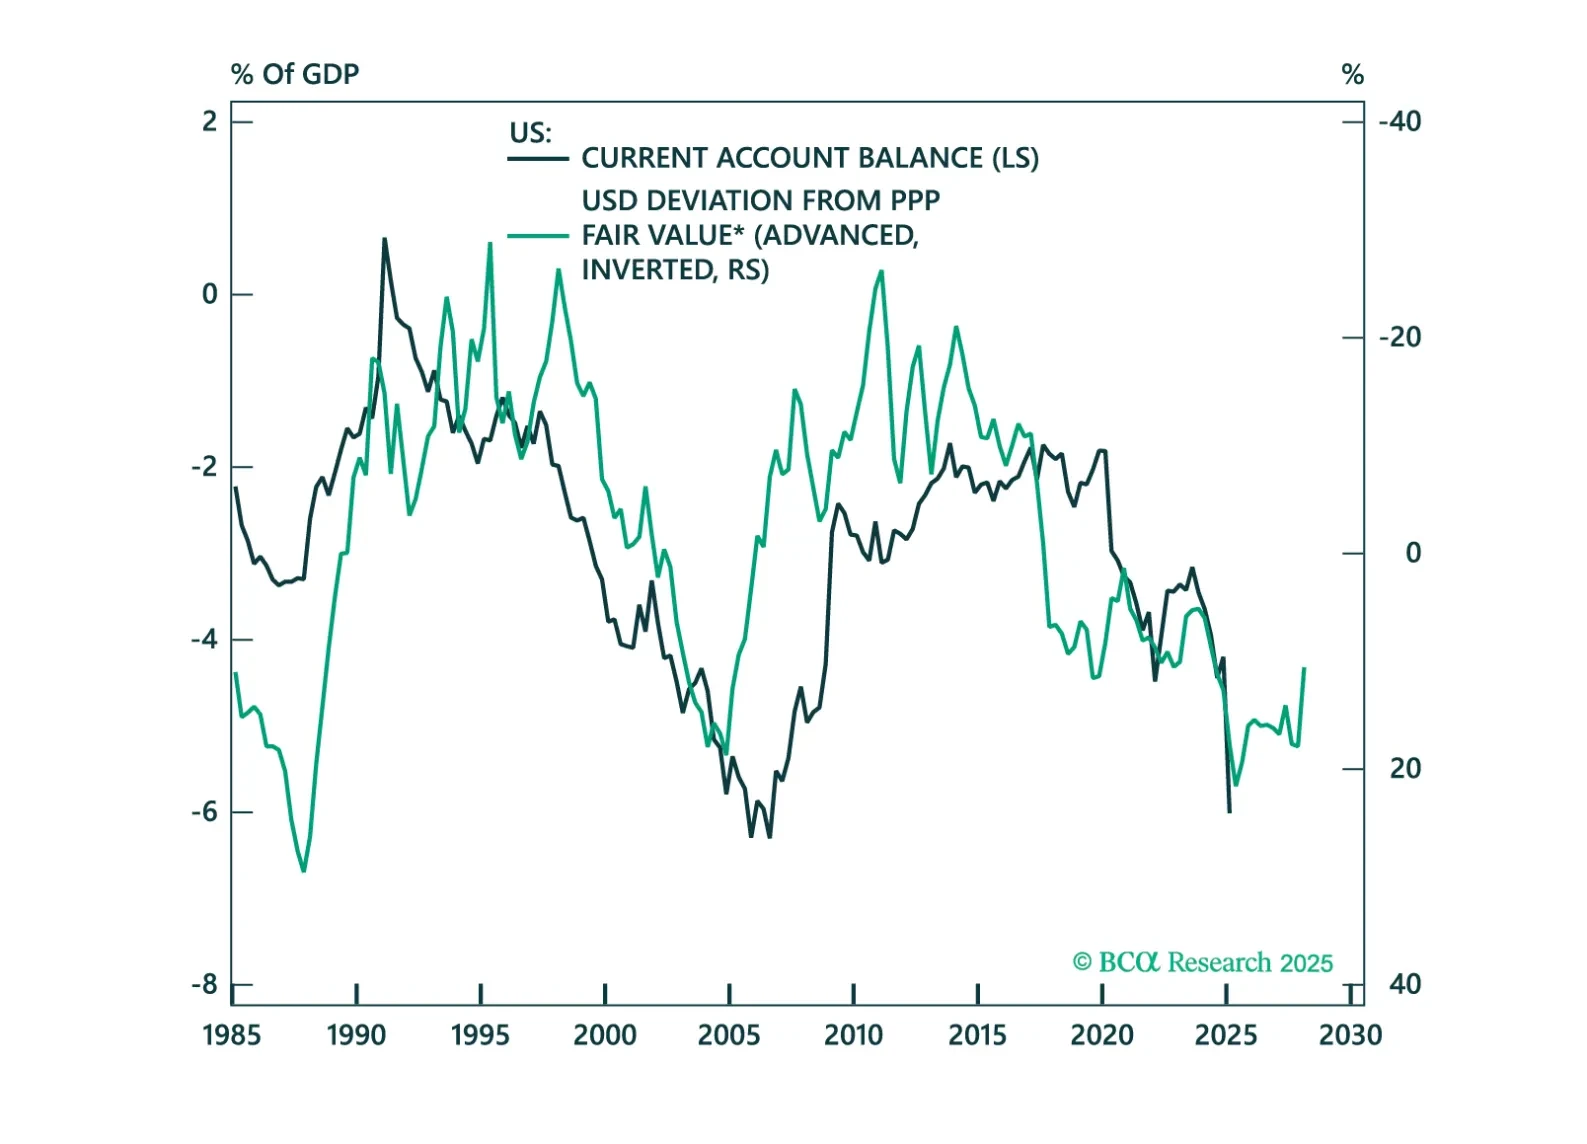
このチャートブックでは、先進国(DM)および新興国(EM)の各国の国際収支を検討します。米国の状況は良くありませんが、他のいくつかの国も同様です。
Global currency markets have entered a new era. This implies that the framework for analyzing exchange rates must also change. We introduce a new framework for analyzing EM currencies and classify them into resilient and vulnerable categories. Finally, we are adding more EM domestic bonds to our portfolio and making many changes to our currency trades.
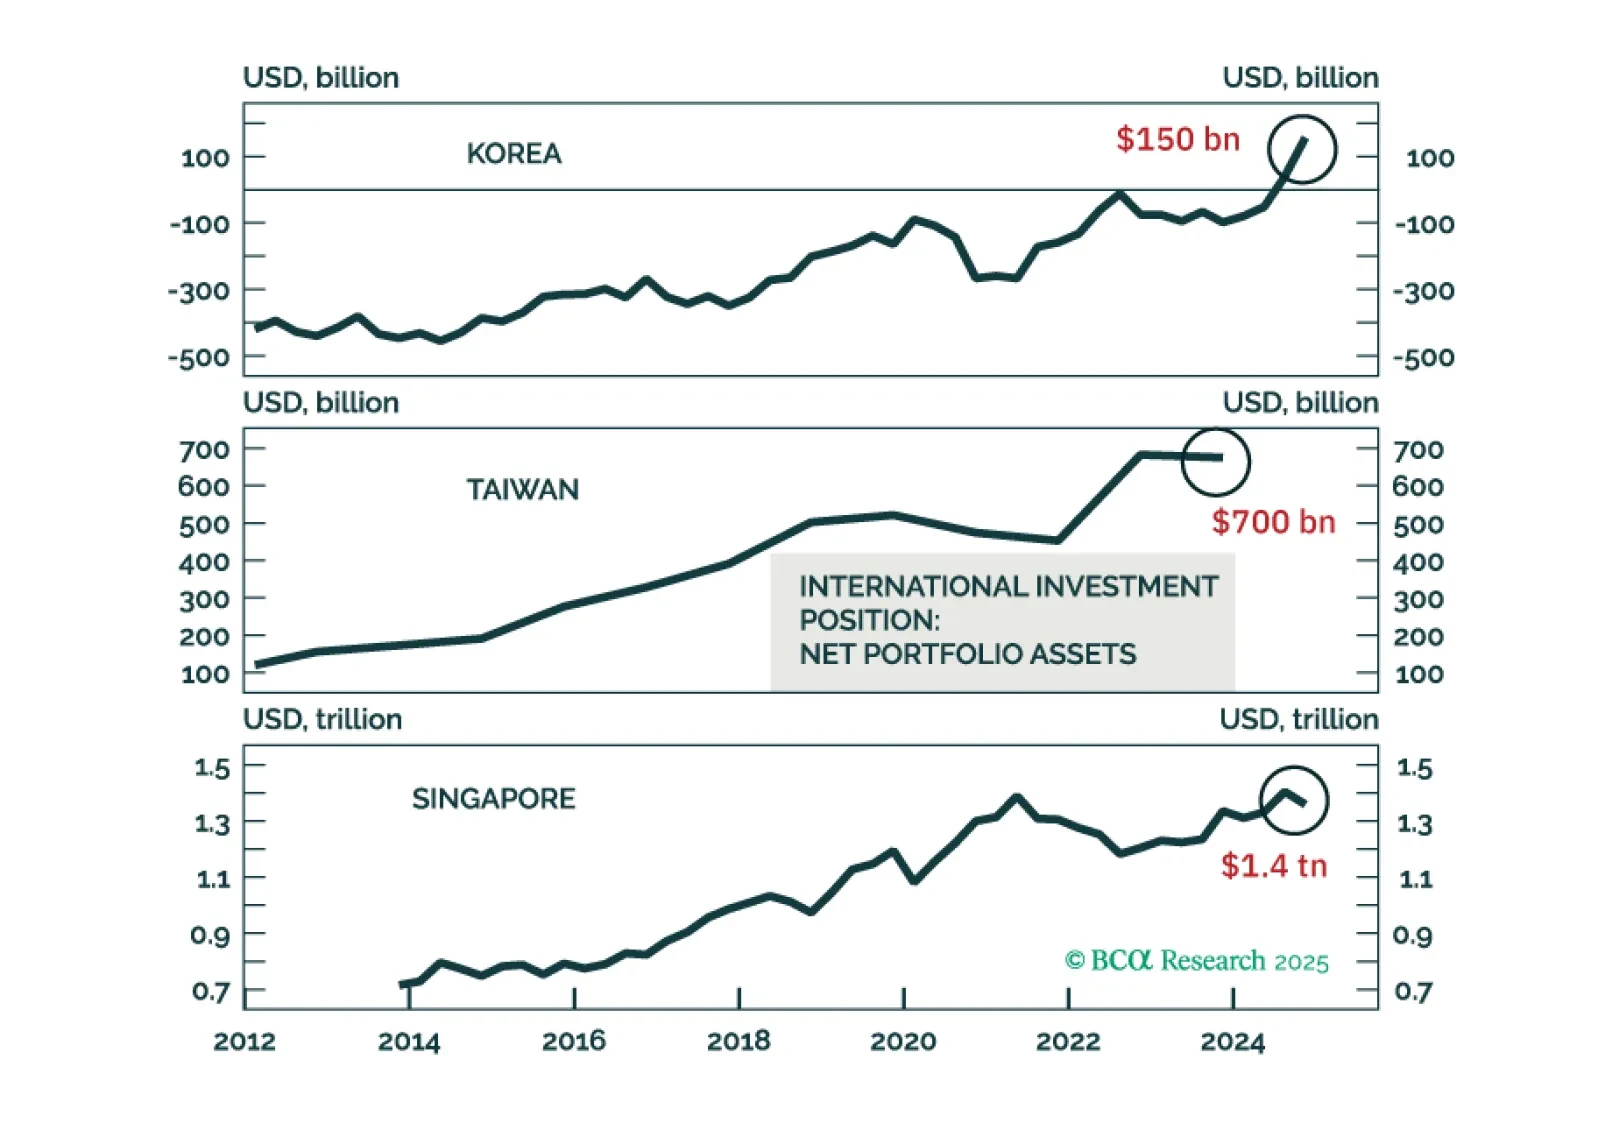
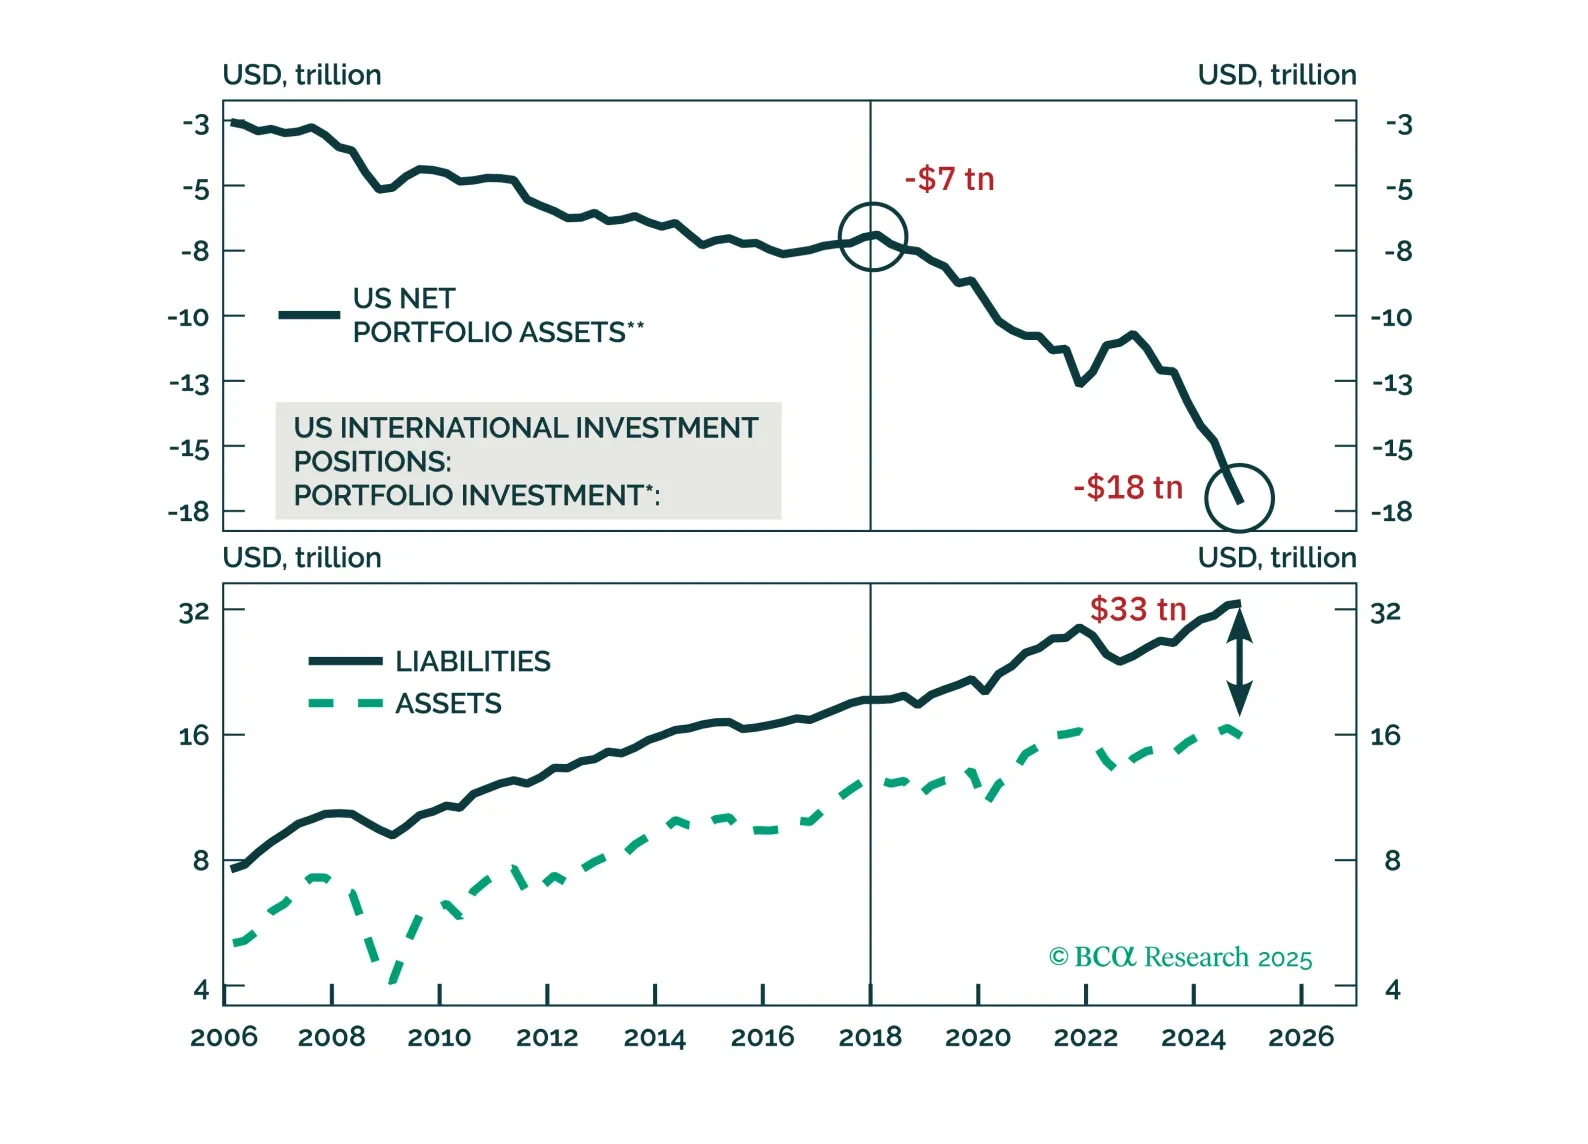
Taiwan, Singapore, and Korea's currencies might appreciate versus the USD, driven by capital repatriation from domestic private investors away from the US. This thesis is less pertinent to India, Indonesia, and the Philippines because they have large net foreign portfolio liabilities. Malaysia and Thailand fall in the middle, while China is an exception. Investors should play intensifying deflationary pressures in Asia by betting on lower interest rates in the region.