Sorry, you need to enable JavaScript to visit this website.
Saltar al contenido principal

Zona Euro

European sentiment data was mixed. The December Ifo Business Climate index for Germany missed estimates and was down 1 point to 84.7 from November. The decrease came from its expectations component, which fell to 84.4 from 87.2. Meanwhile, the December ZEW…
December flash PMIs for the core advanced economies showed service sector growth picking up. Manufacturing keeps contracting, and the US continues to outperform its DM peers. The US composite index beat expectations and increased to 56.6 from 54.9. Services…
Our Chart Of The Week comes from Mathieu Savary, Chief Strategist of our European Investment Strategy service. Mathieu sees a dimming outlook for European industrial stocks in the near term.The sector has been one of the strongest performers in Europe this…
Informe especial

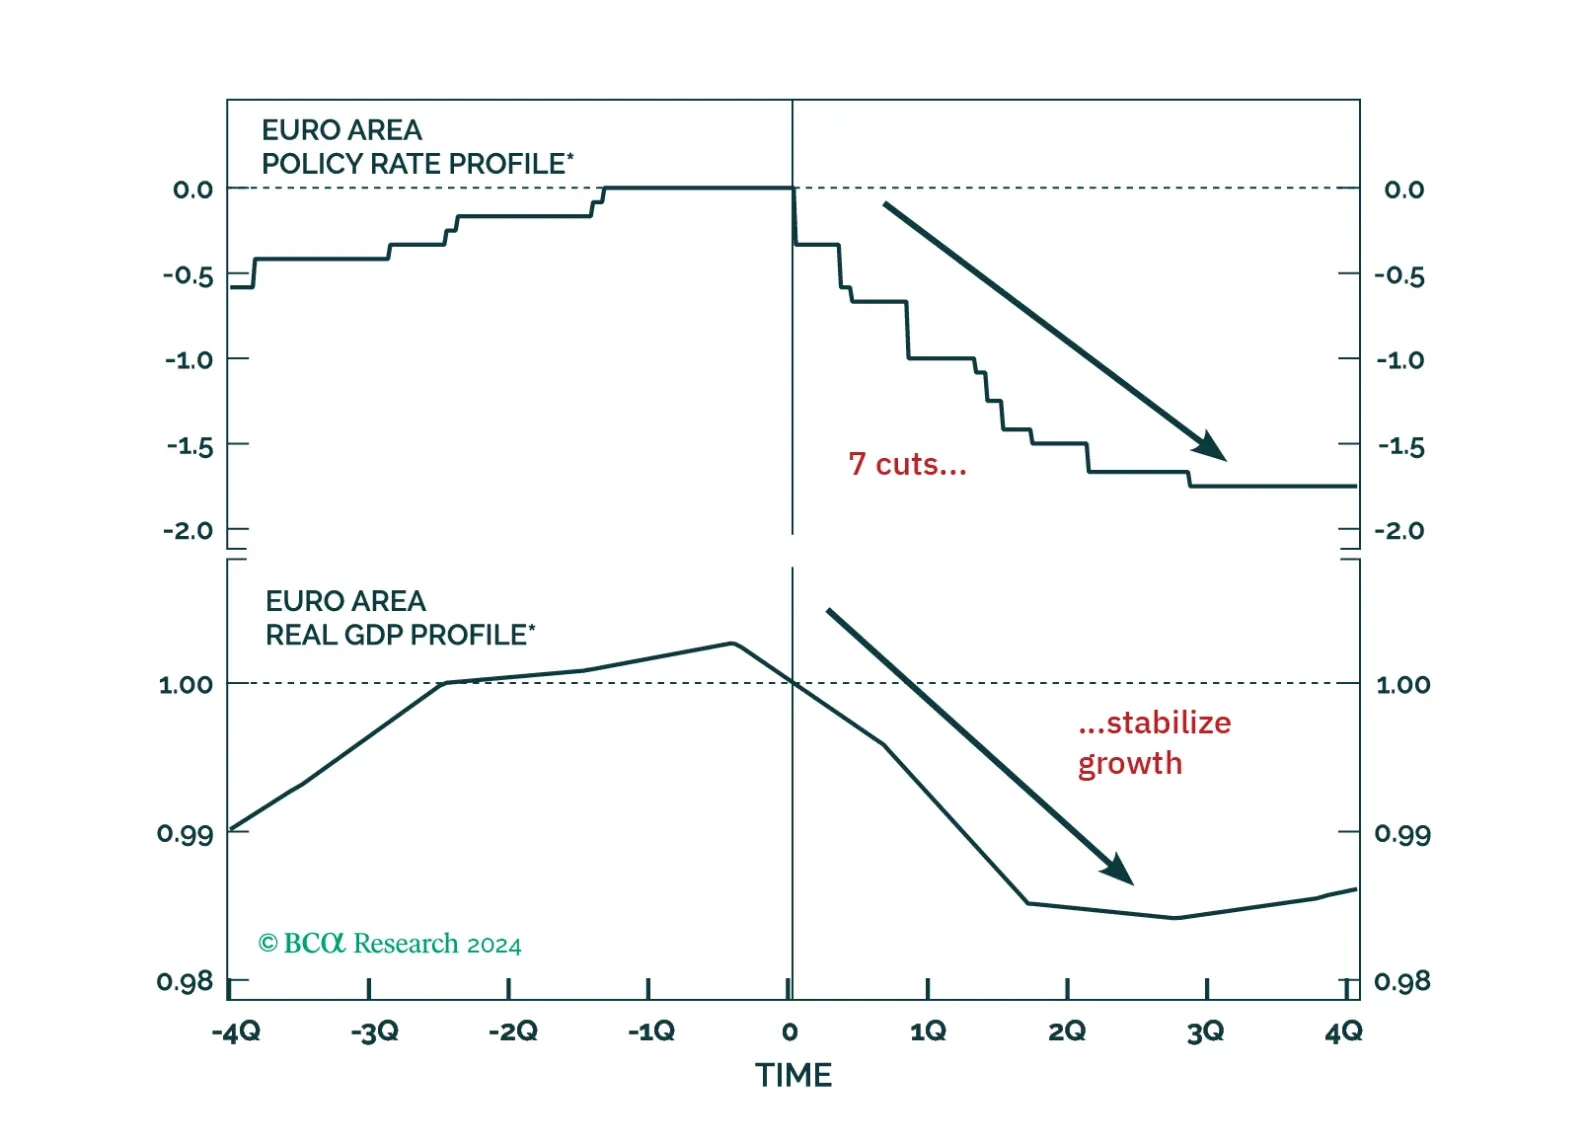
For our last publication of the year, we explore five key themes that will dominate the European macro landscape and markets next year. While the start of 2025 will be challenging for European assets, the latter part will offer some much-needed relief.
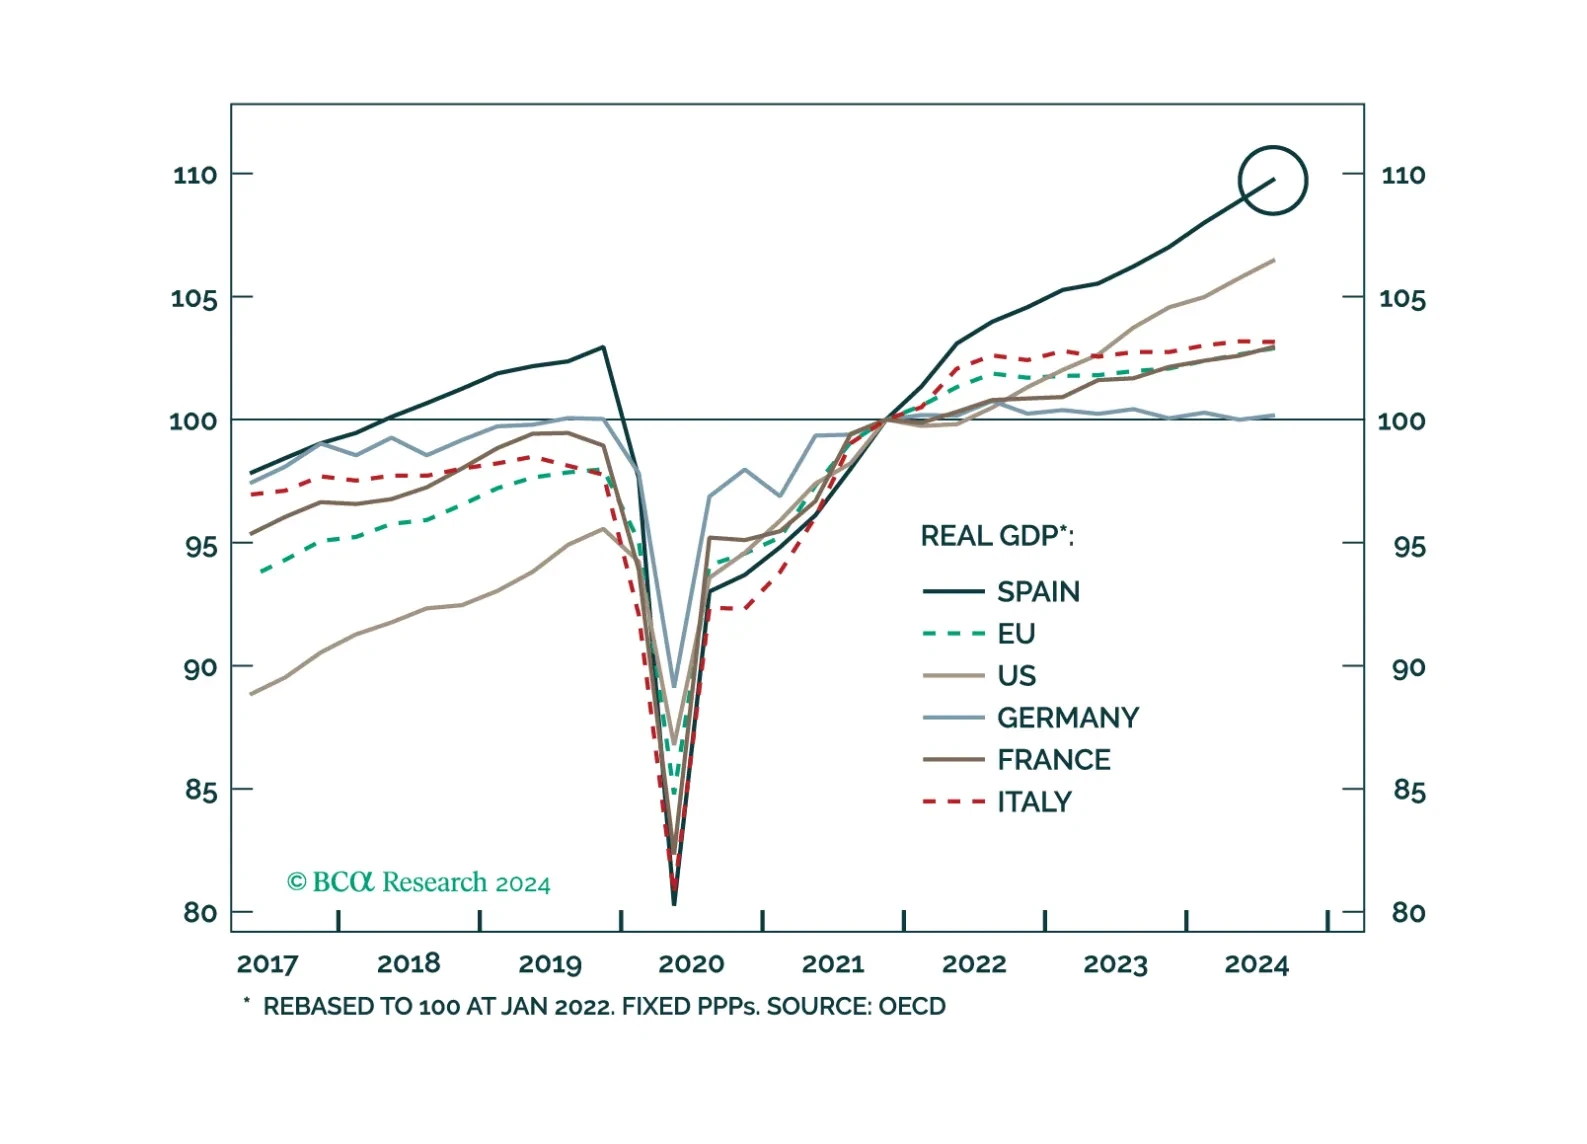
In the final installment of their “PIGS Have Wings” special series, our European investment strategists took a deep dive into the Spanish economy and financial assets. Spain outperformed most developed markets since 2022, with strong gains in both economic…
The December Sentix Economic Index for the Euro Area missed expectations, declining to -17.5 vs. -12.8 in November. Both the current situation and expectations components declined. As the first sentiment indicator for December, the Sentix confirms the recent…
Informe especial

Spain has outperformed most developed markets since 2022 – real economic output and risk assets alike. Can it last? 
German factory orders decreased less than expected in October, falling 1.5% m/m after rising 7.2% in September. Excluding major orders, which often distort the overall picture, core new orders rose 0.1%, after rising 2.7% a month prior. Despite the…

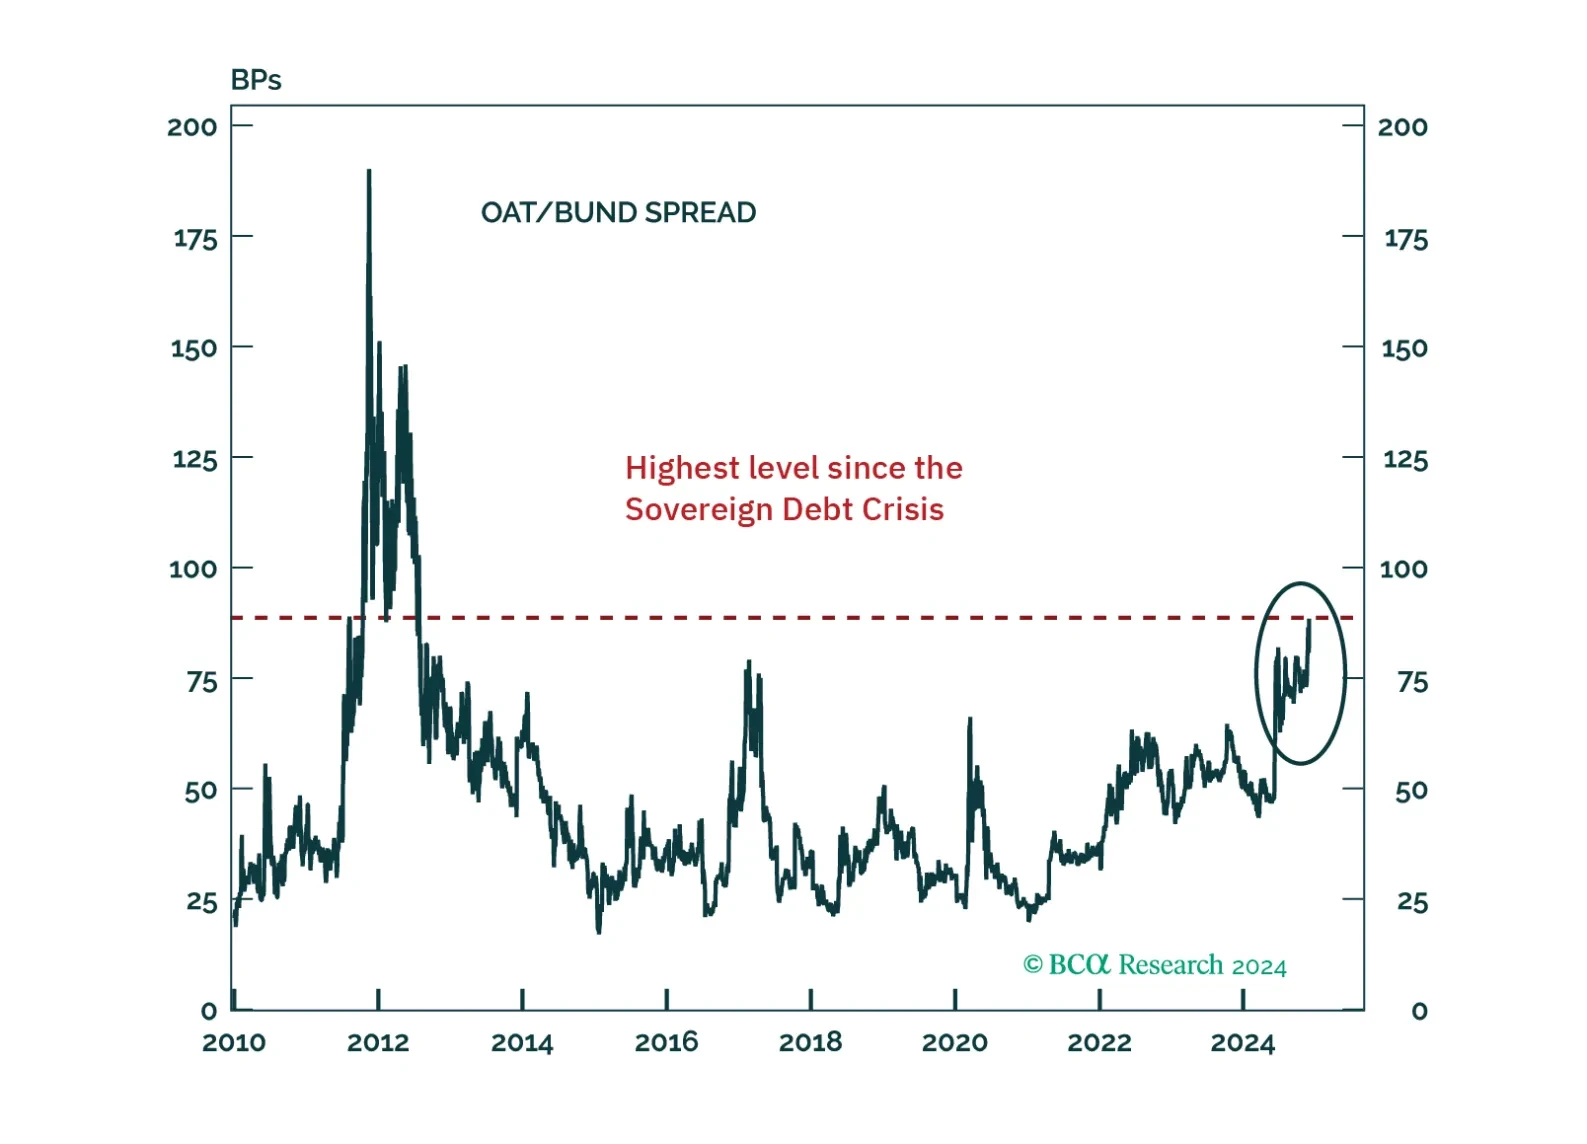
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors? 
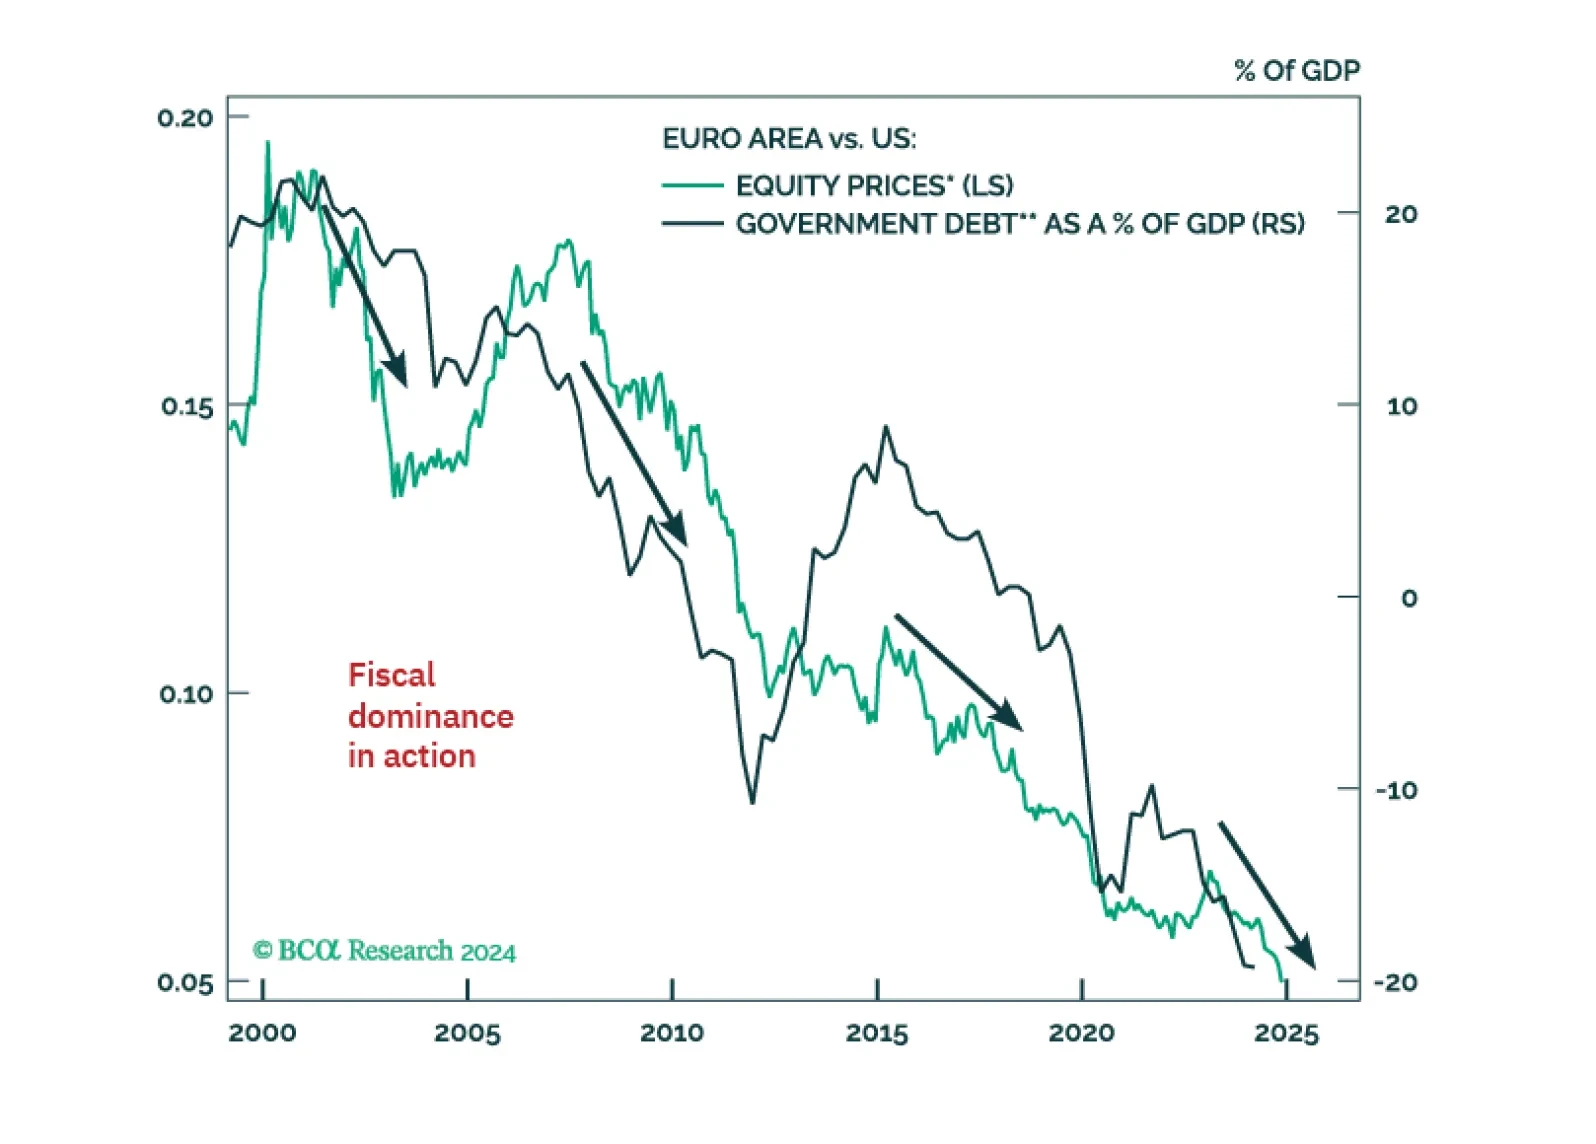
Los inversores han renunciado a los activos europeos, que ahora cotizan con descuentos excepcionales respecto a los activos estadounidenses. Sin embargo, una política fiscal estadounidense más restrictiva, el fin de la austeridad y del desapalancamiento en Europa, el tsunami de GNL a punto de golpear las costas europeas y el capex global impulsado por la Tríada Geopolítica Imposible significan que el momento de gloria de Europa pronto volverá.