Rupia india
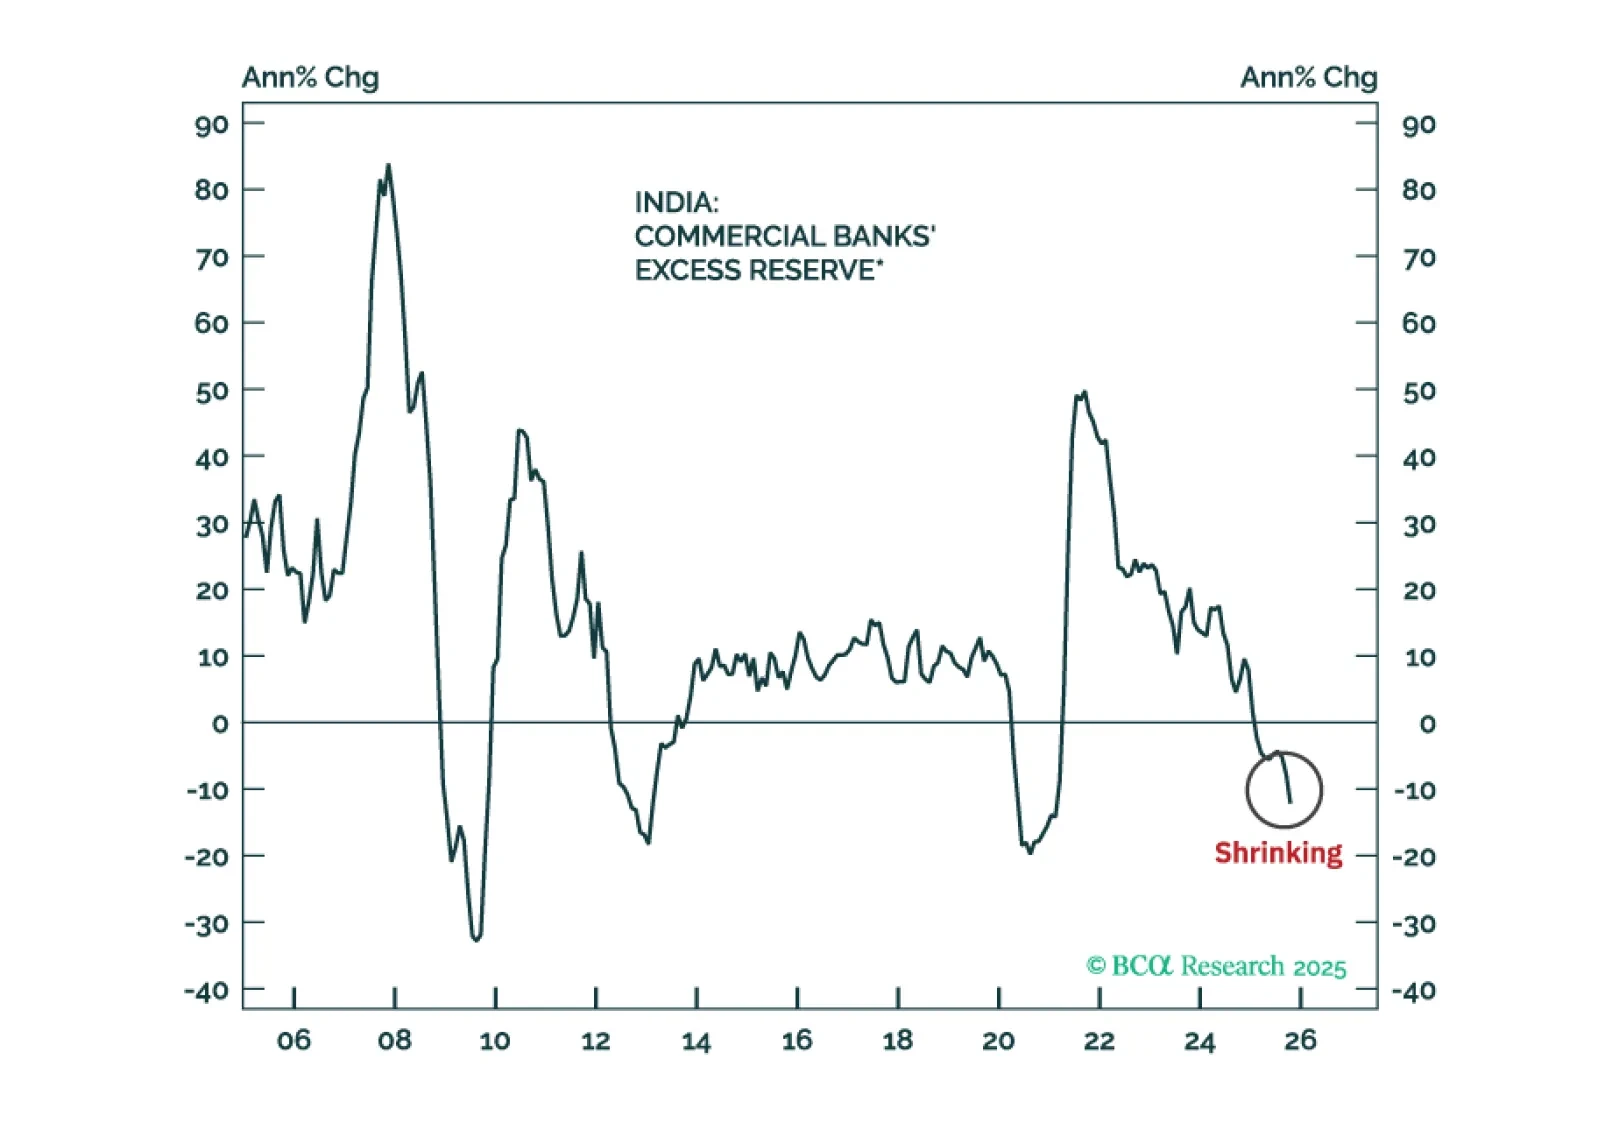

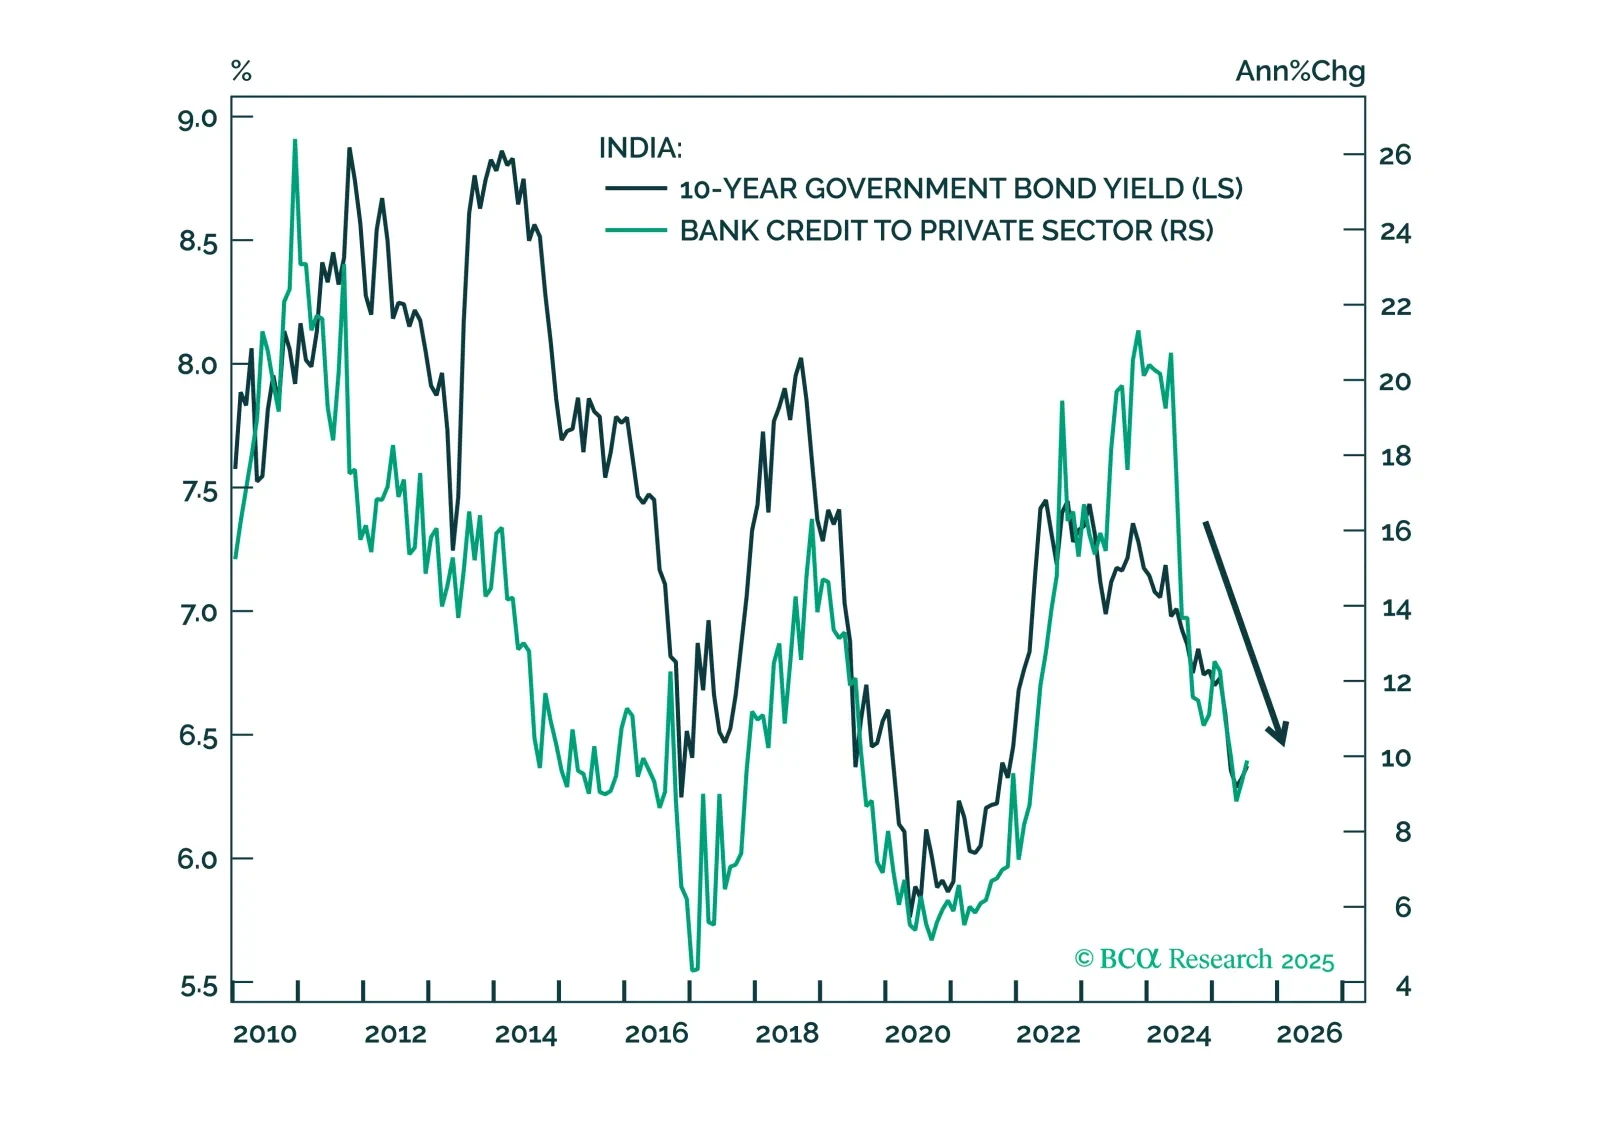
La rupia india sigue siendo vulnerable a una mayor depreciación debido al crecimiento ralentizado, una política interna restrictiva y flujos de capital frágiles. Los riesgos comerciales y un balance externo debilitado probablemente mantendrán al INR con un rendimiento inferior al de sus pares de Asia emergente.
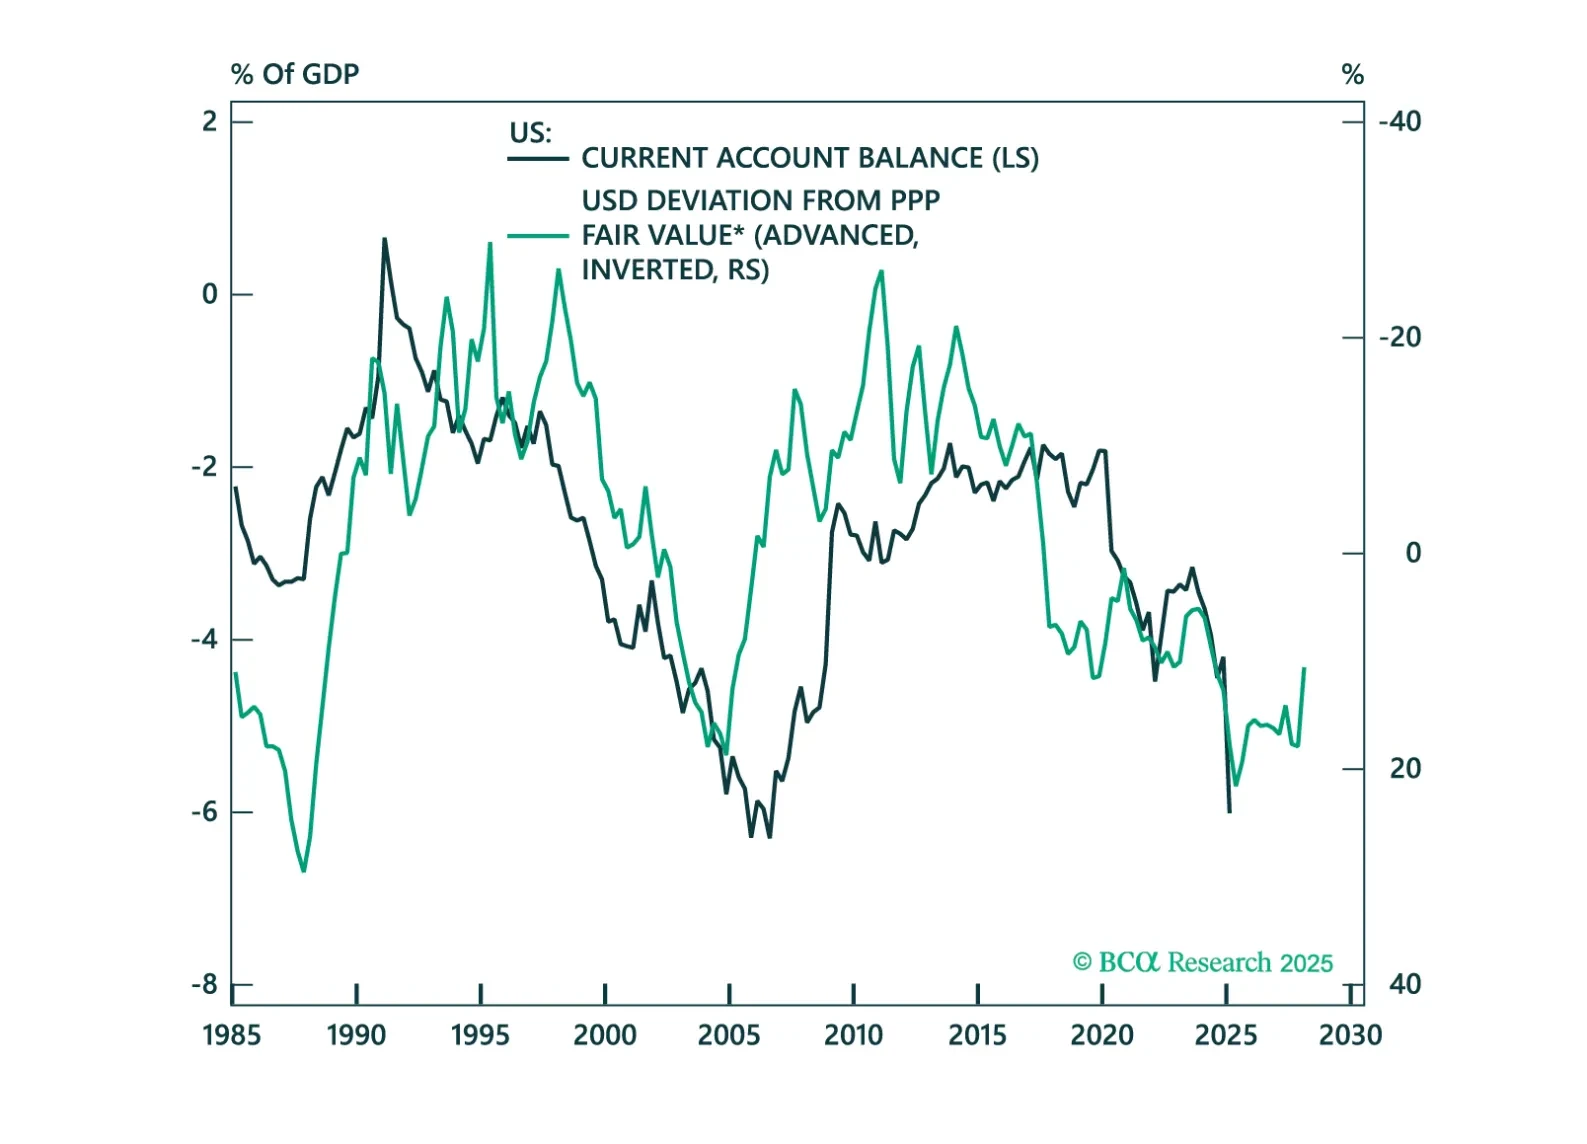
En este libro de gráficos, analizamos la balanza de pagos en países desarrollados (DM) y mercados emergentes (EM). A Estados Unidos no le va bien, pero a algunos otros países tampoco.
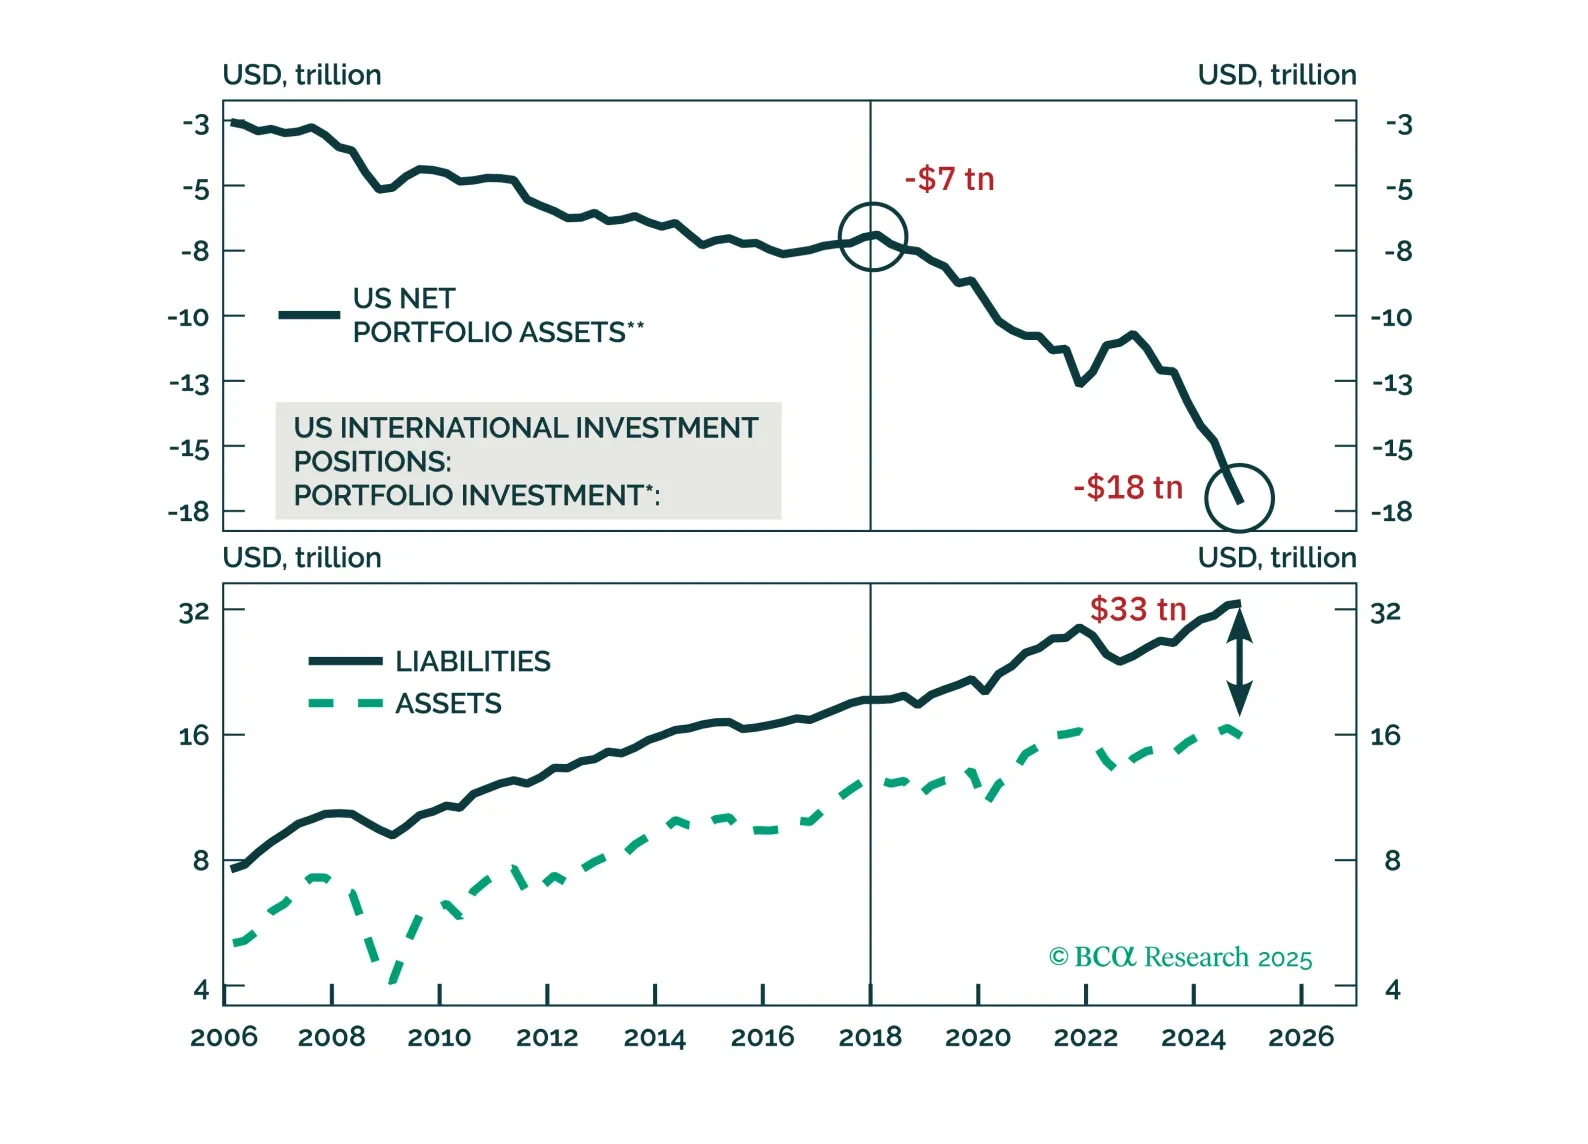
Global currency markets have entered a new era. This implies that the framework for analyzing exchange rates must also change. We introduce a new framework for analyzing EM currencies and classify them into resilient and vulnerable categories. Finally, we are adding more EM domestic bonds to our portfolio and making many changes to our currency trades.
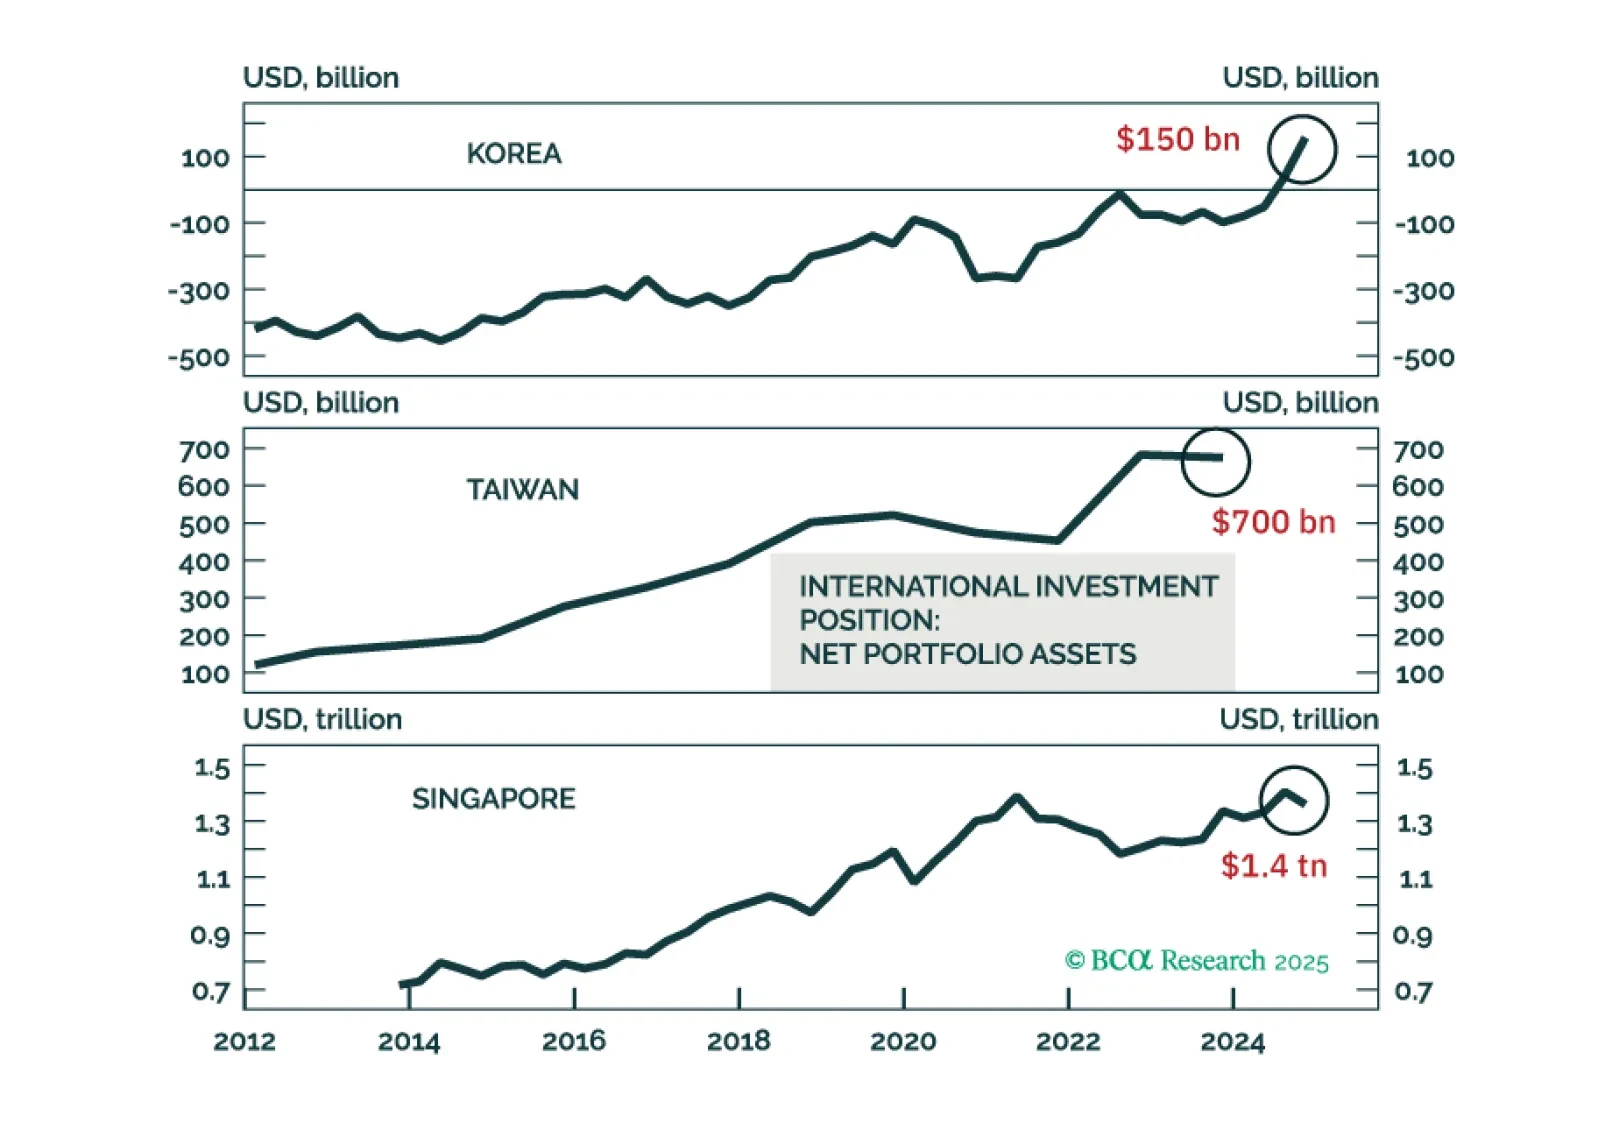
Taiwan, Singapore, and Korea's currencies might appreciate versus the USD, driven by capital repatriation from domestic private investors away from the US. This thesis is less pertinent to India, Indonesia, and the Philippines because they have large net foreign portfolio liabilities. Malaysia and Thailand fall in the middle, while China is an exception. Investors should play intensifying deflationary pressures in Asia by betting on lower interest rates in the region.
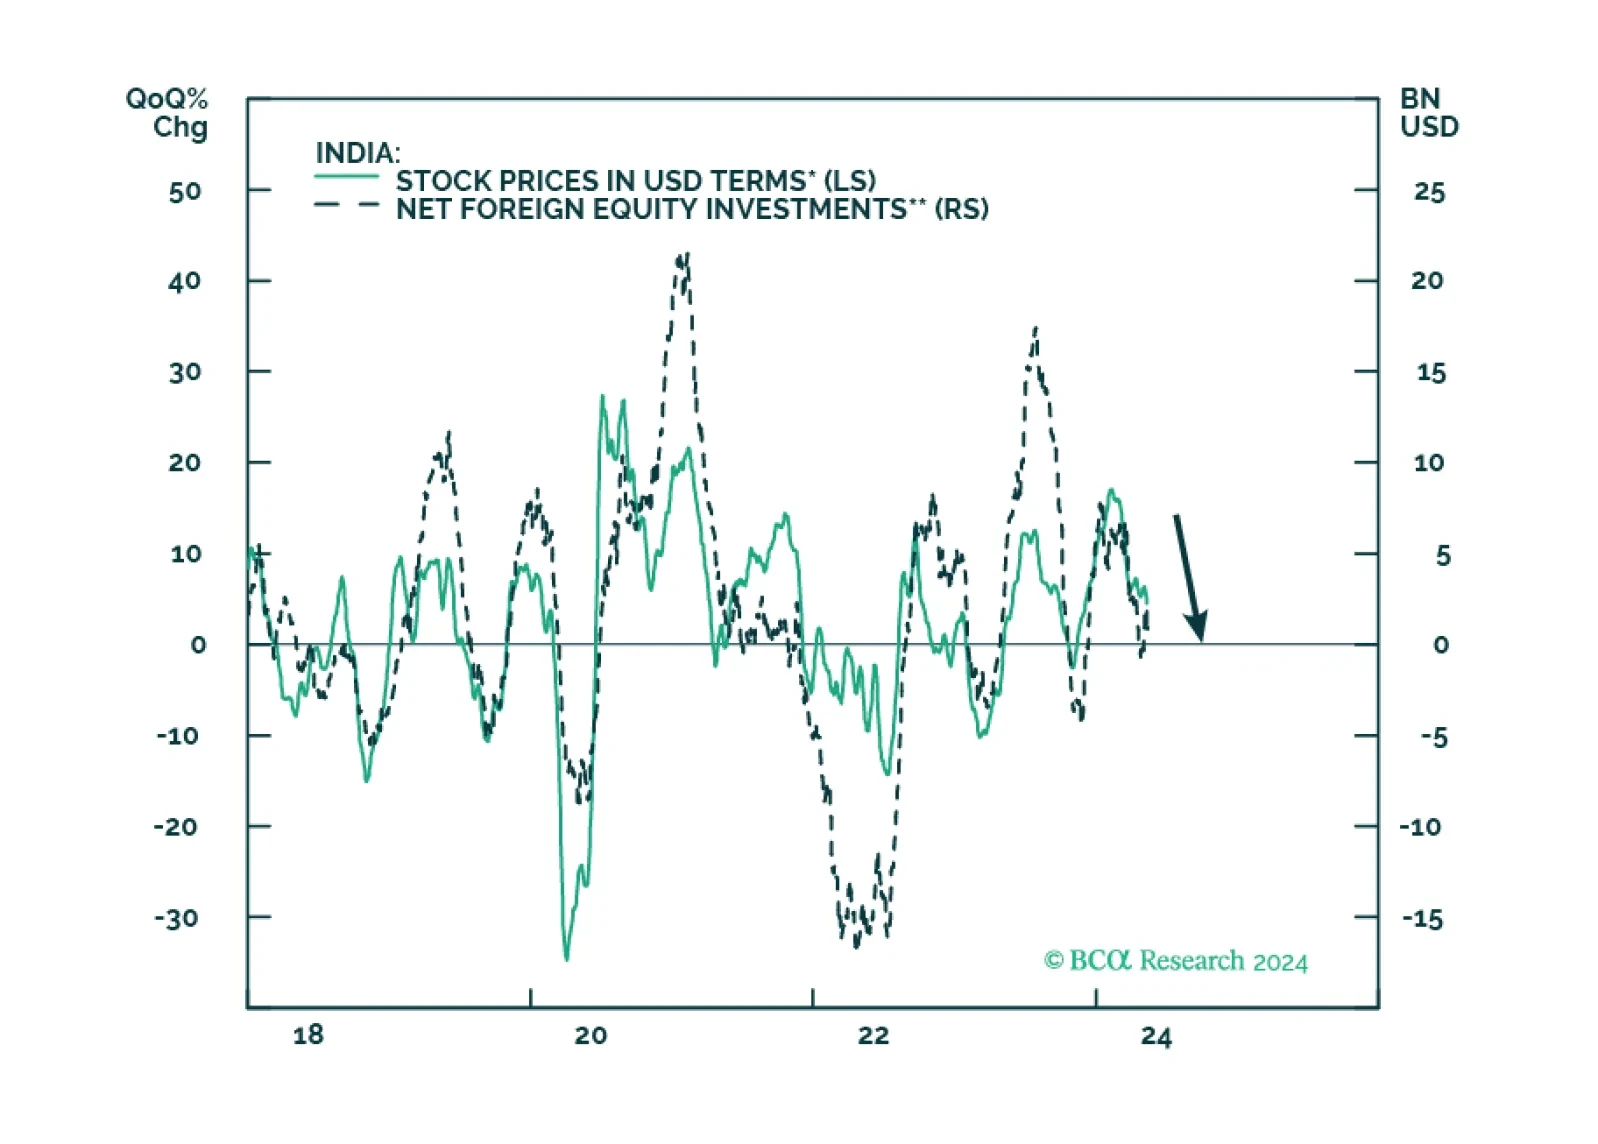
Modi and the BJP are at or near the peak of their political dominance, and their third term will be challenging as they must deal with harder reforms amidst a slowing domestic and global economic environment. In the long run, however, we remain constructive on India’s prospects, as its geopolitical and economic positioning are favorable and improving.