Mercados Fronterizos
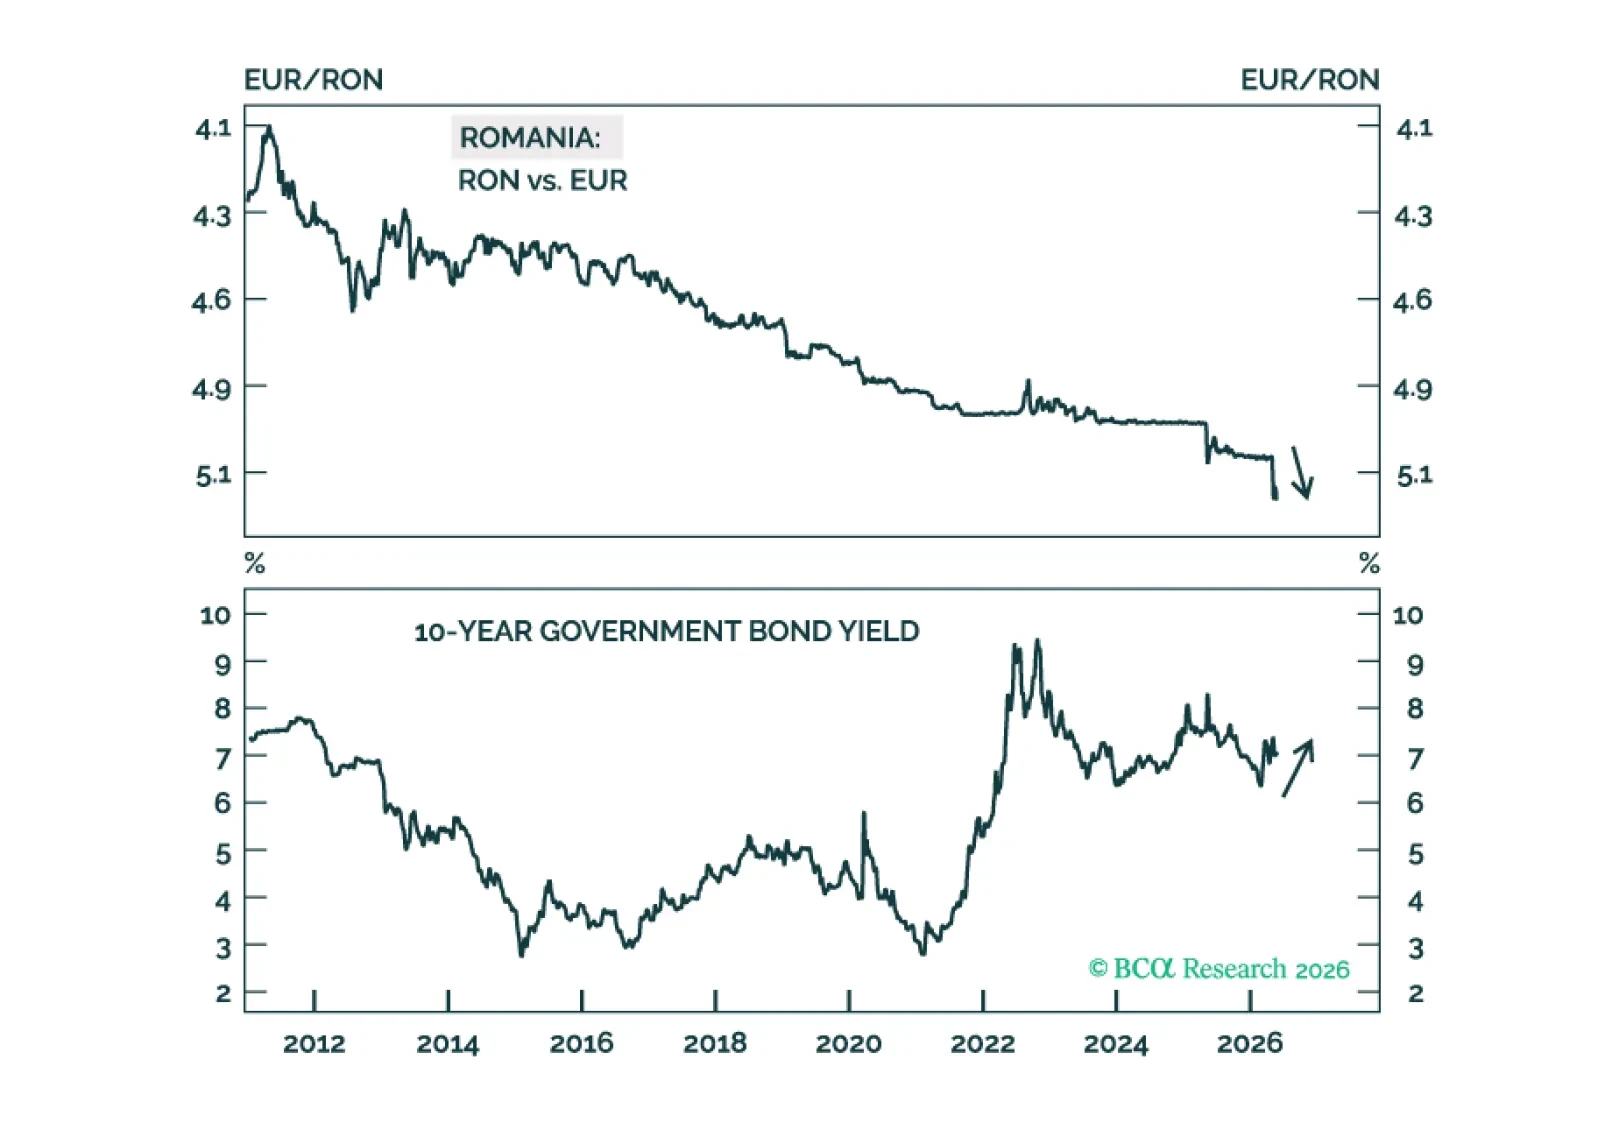
En Rumanía, amplios déficits fiscales y por cuenta corriente, alta inflación, tasas reales negativas, un tipo de cambio sobrevaluado y un crecimiento en deterioro indican una incipiente devaluación de la moneda. Los inversores deberían tomar posiciones cortas en la moneda de Rumanía frente al euro y mantener una infraponderación en bonos locales, acciones y crédito soberano.
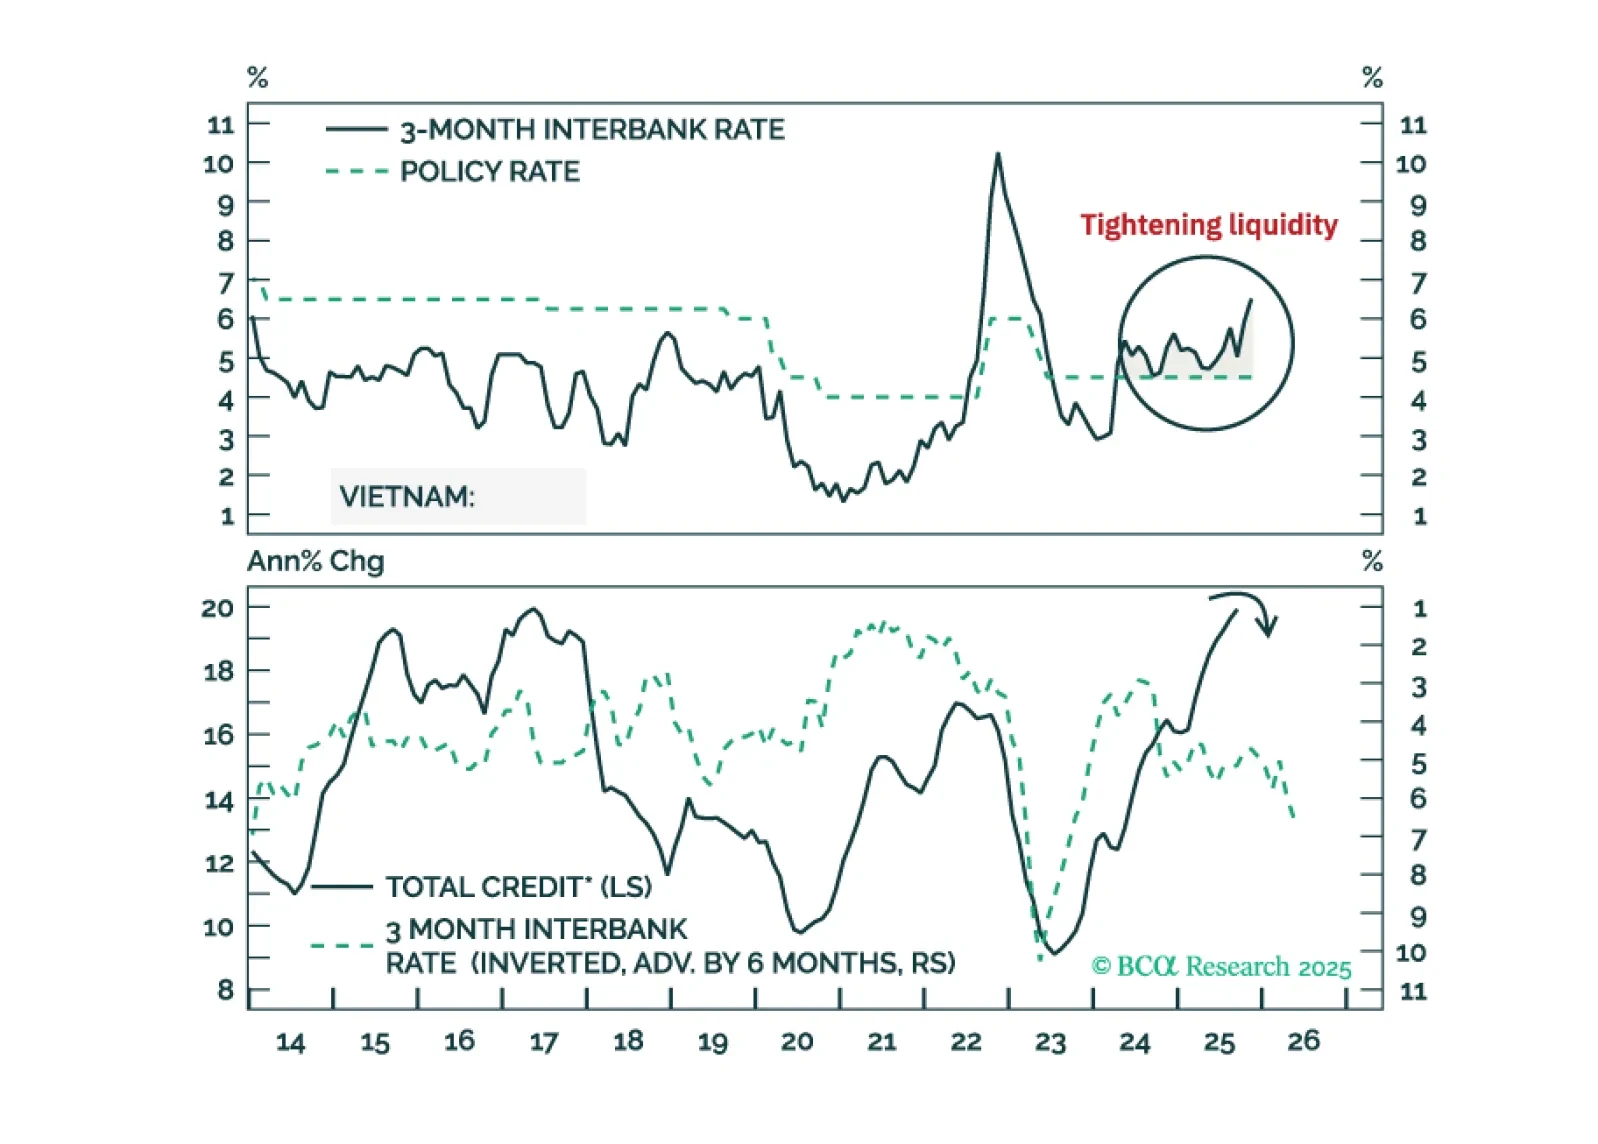
Mantenemos una postura optimista sobre el potencial de generación de alfa de las acciones vietnamitas a mediano y largo plazo. Pero nuestra perspectiva negativa sobre el beta global/EM nos hace adoptar una postura pesimista respecto a esta bolsa en términos absolutos a mediano plazo.
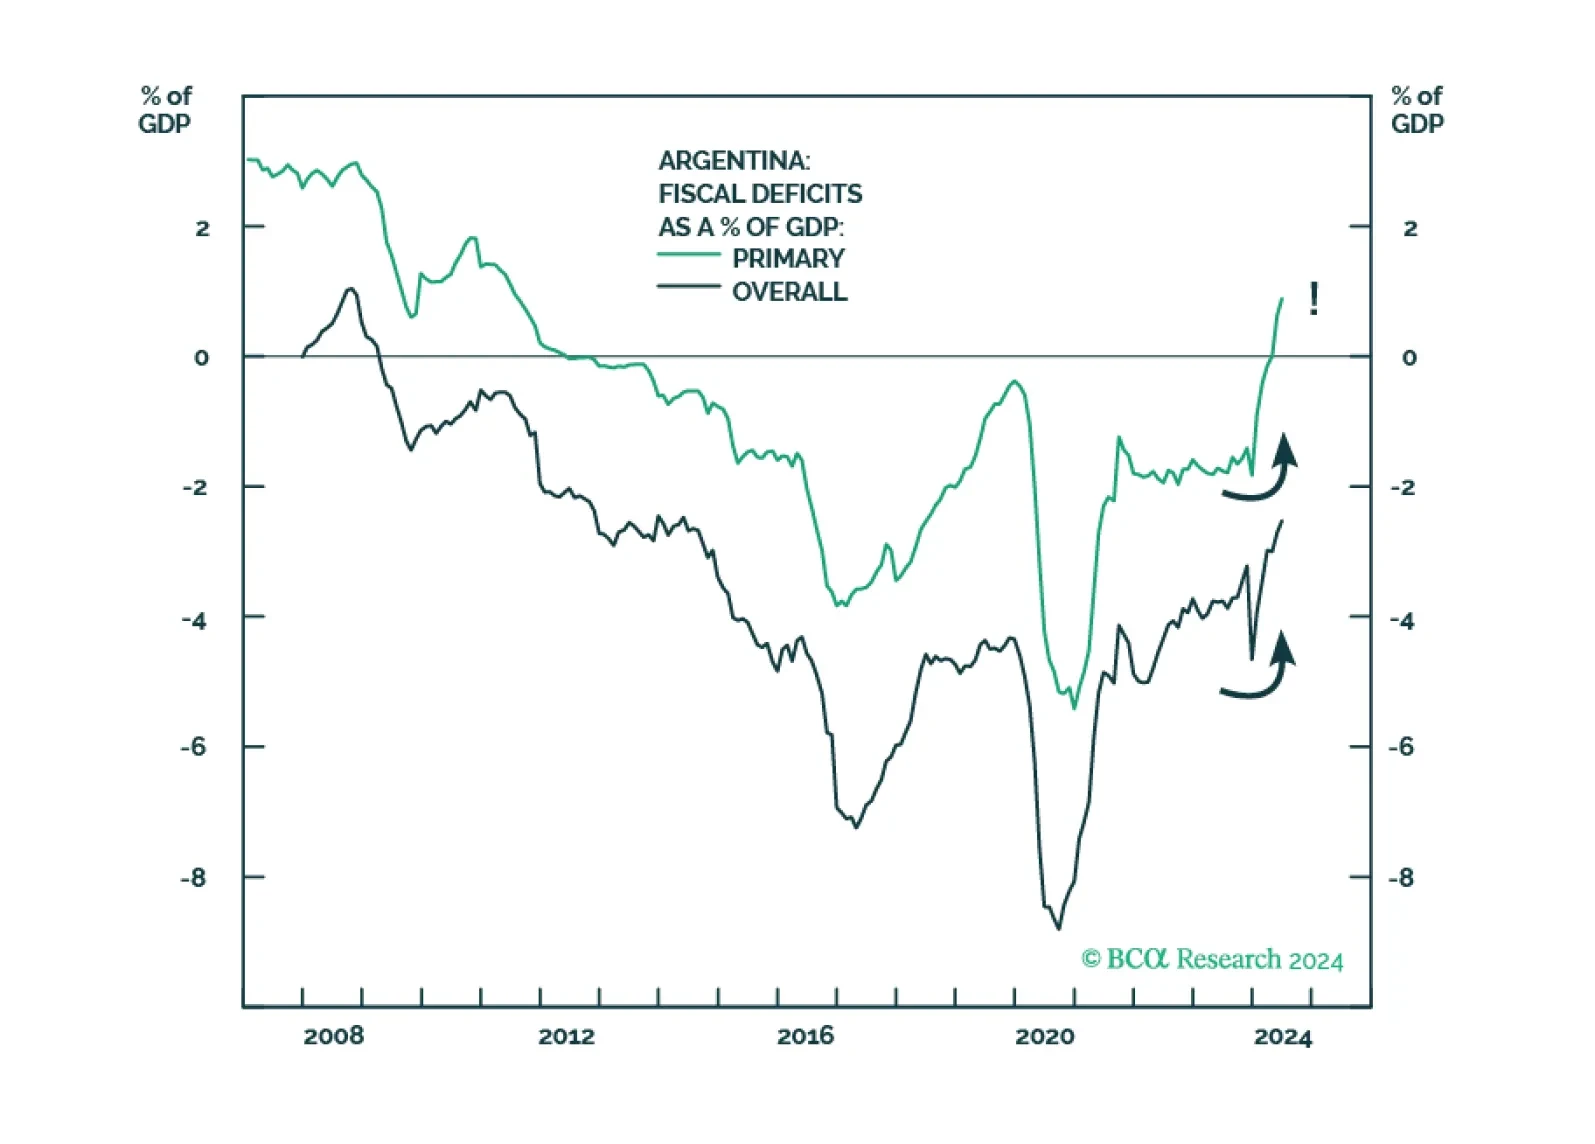
GeoMacro team partners with BCA’s Emerging Markets Strategy to examine political reforms in Argentina. Our colleague Juan Egaña argues that the time is not right to go long Argentinian assets and that Buenos Aires must avoid the mistakes of the Macri era: opening to foreign capital flows too soon without addressing structural macro imbalances. However, the Milei administration is on the right path with potentially global implications.
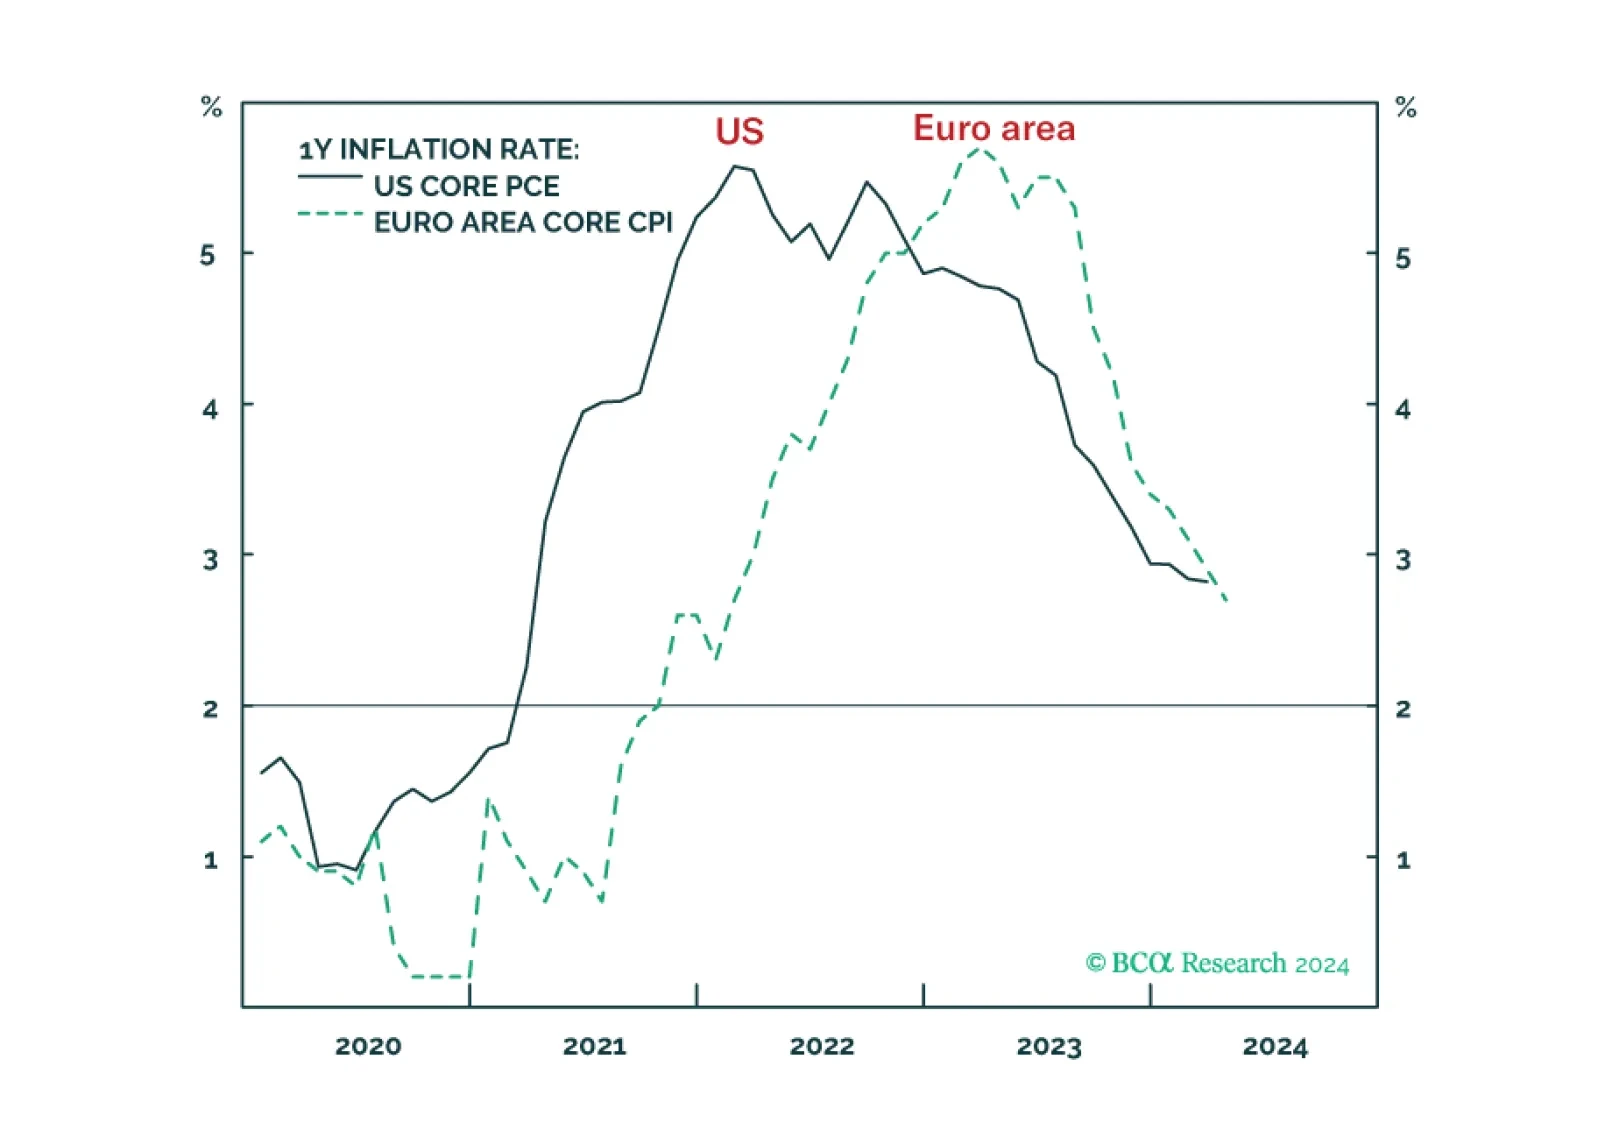
Wild hopes for US rate cuts got shattered, exactly as we predicted. But given the different incentives that the Fed and ECB now face, the relative pricing between the Fed and the ECB could widen further in the coming months. We discuss the implications for rates, the dollar, and the relative positioning in US versus European equities.
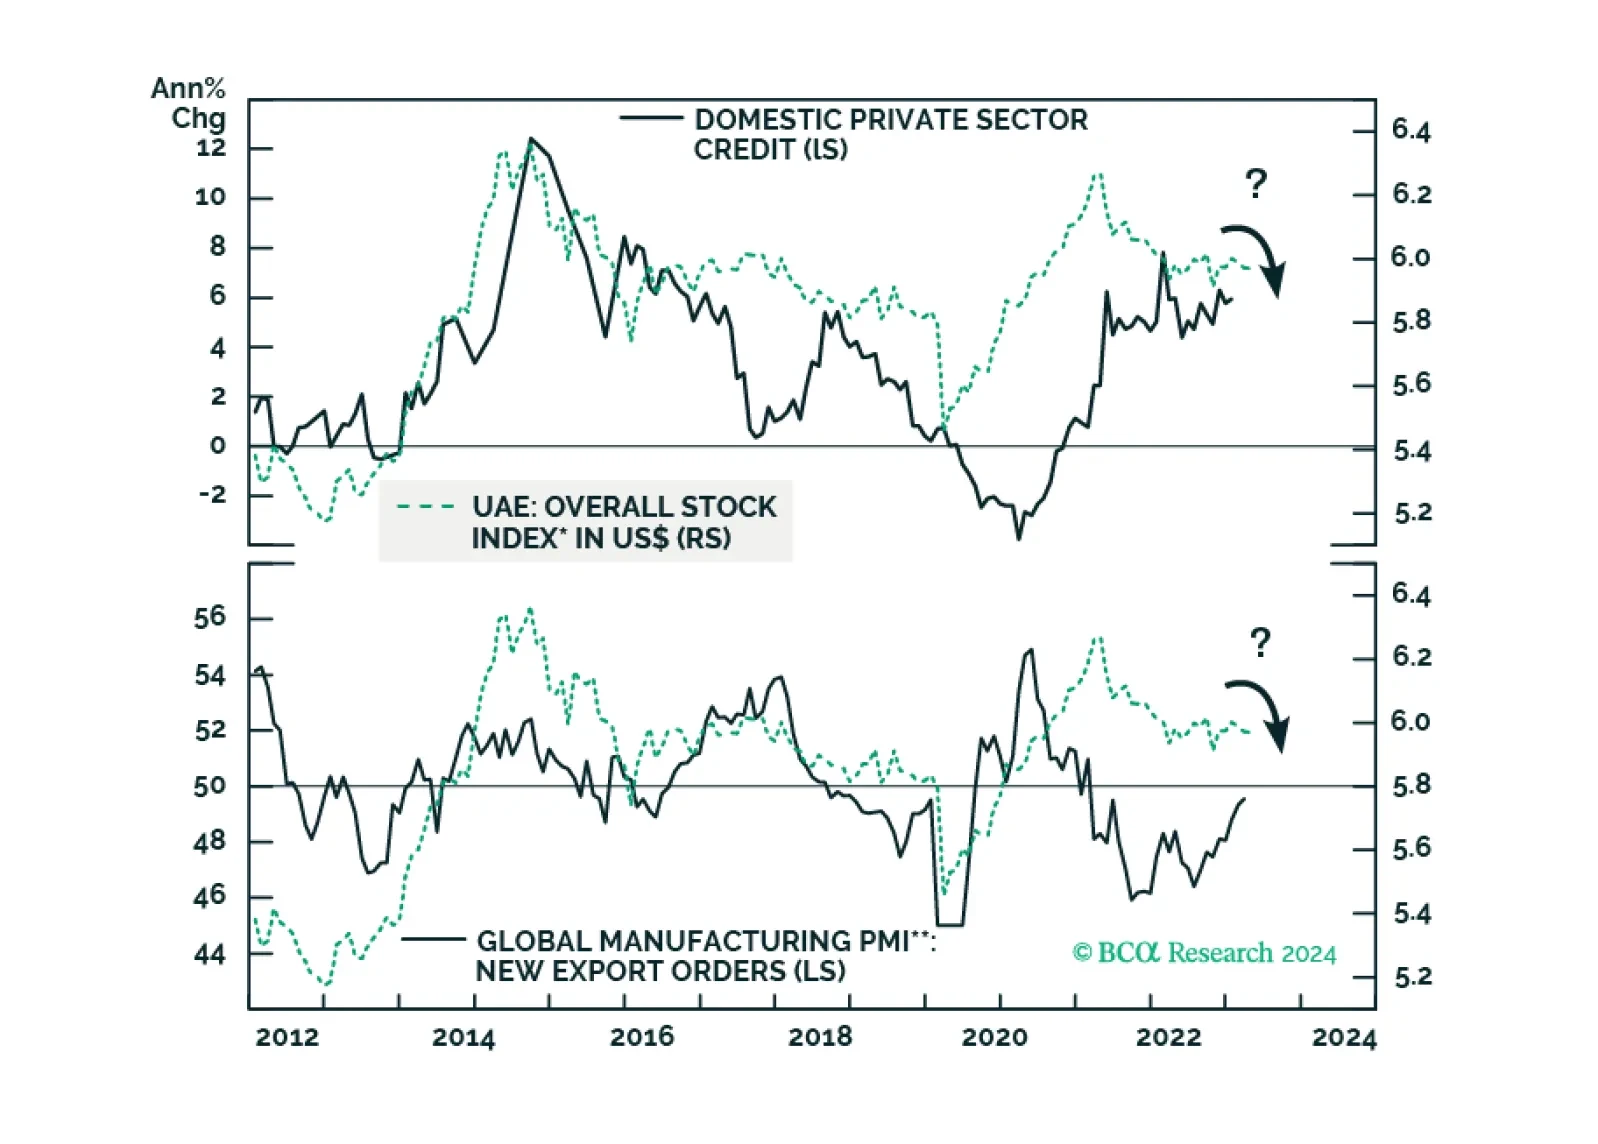
Subdued credit growth and weak global trade will remain headwinds for Emirati stocks. Surging property prices, which have led to a boom in real estate stocks, will also peak soon. Stay neutral on this bourse. Sovereign credit investors, however, should stay overweight UAE in EM credit portfolios.

The Saudi economy is facing internal and external headwinds. The geopolitical conflict is also escalating in the Middle East. EM equity portfolios should stay neutral on Saudi stocks. EM sovereign credit portfolios should upgrade Saudi Arabia from neutral to overweight.
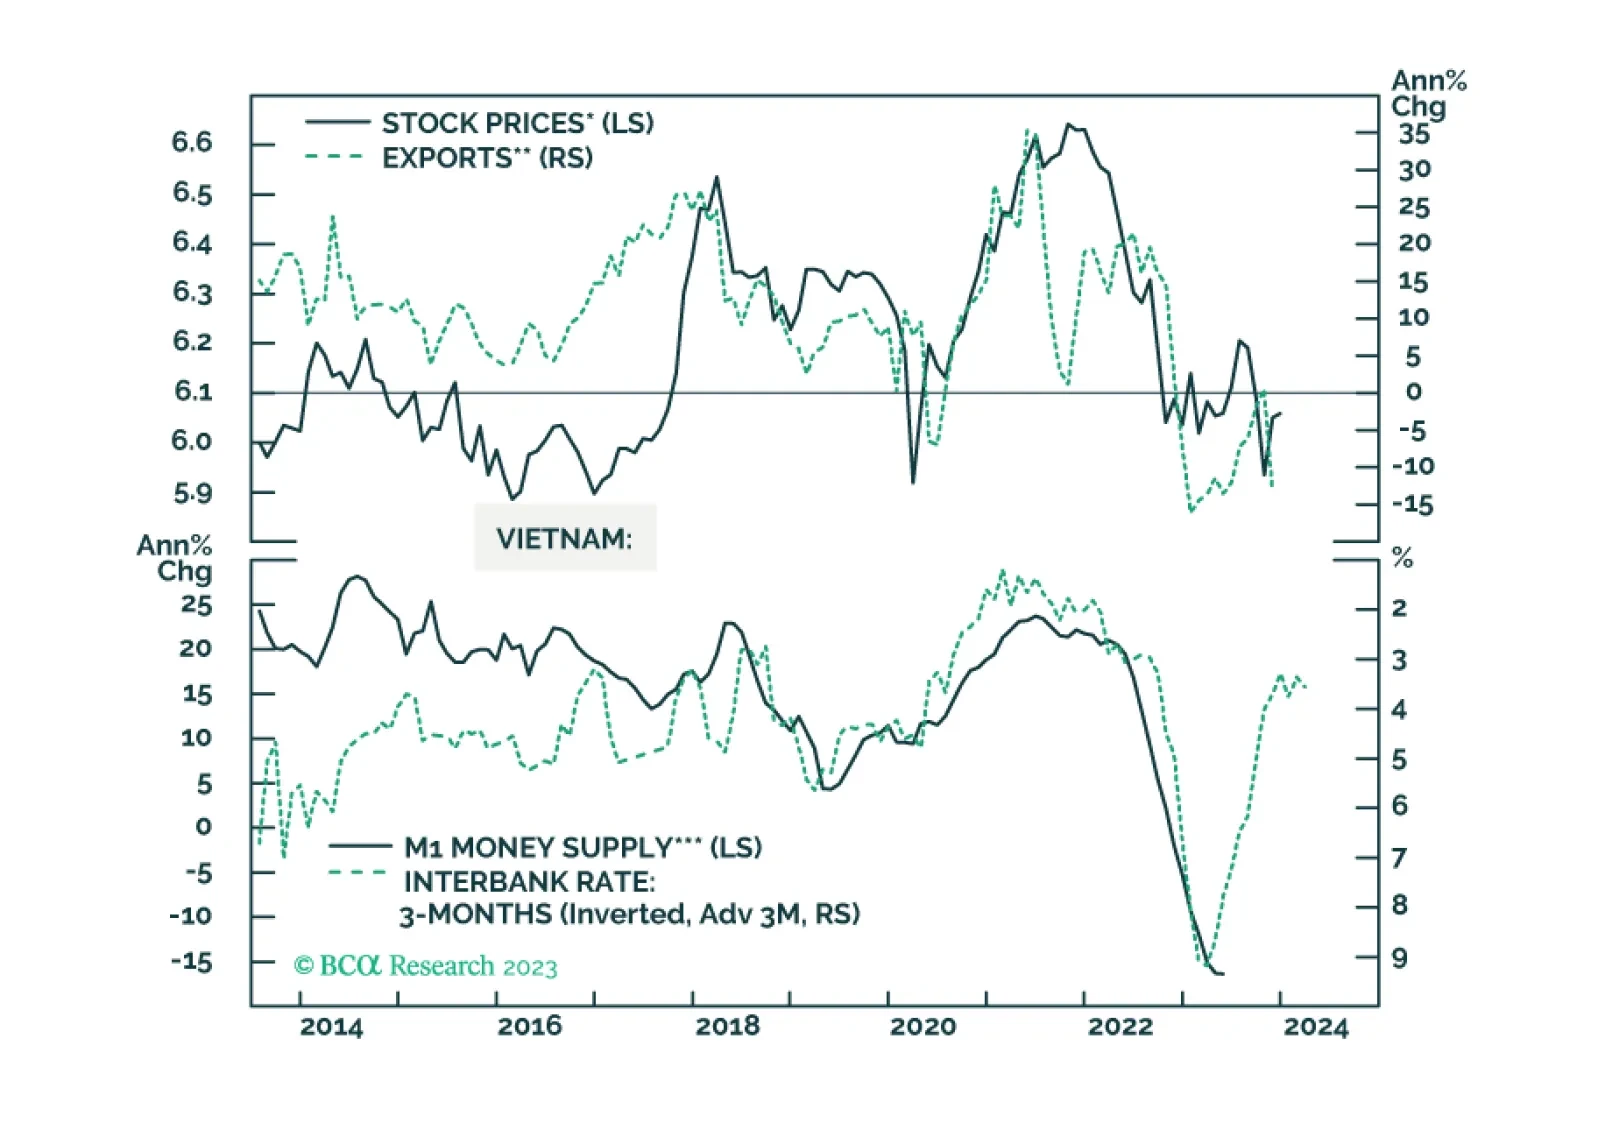
Vietnamese stocks may not see an immediate rally as global manufacturing and exports remain weak. But investors with longer-term horizons should stay overweight this market.

Vietnamese stocks can remain shaky for a few more months. But they have cheapened considerably, and equity portfolios with longer terms investment horizon should overweight them in EM, Emerging Asia and Frontier Market portfolios.
UAE markets are a simultaneous play on interest rates, crude prices, and global trade. None of them is presently favorable, with rising interest rates being the main threat to the UAE economy and stock market.