Gasolina
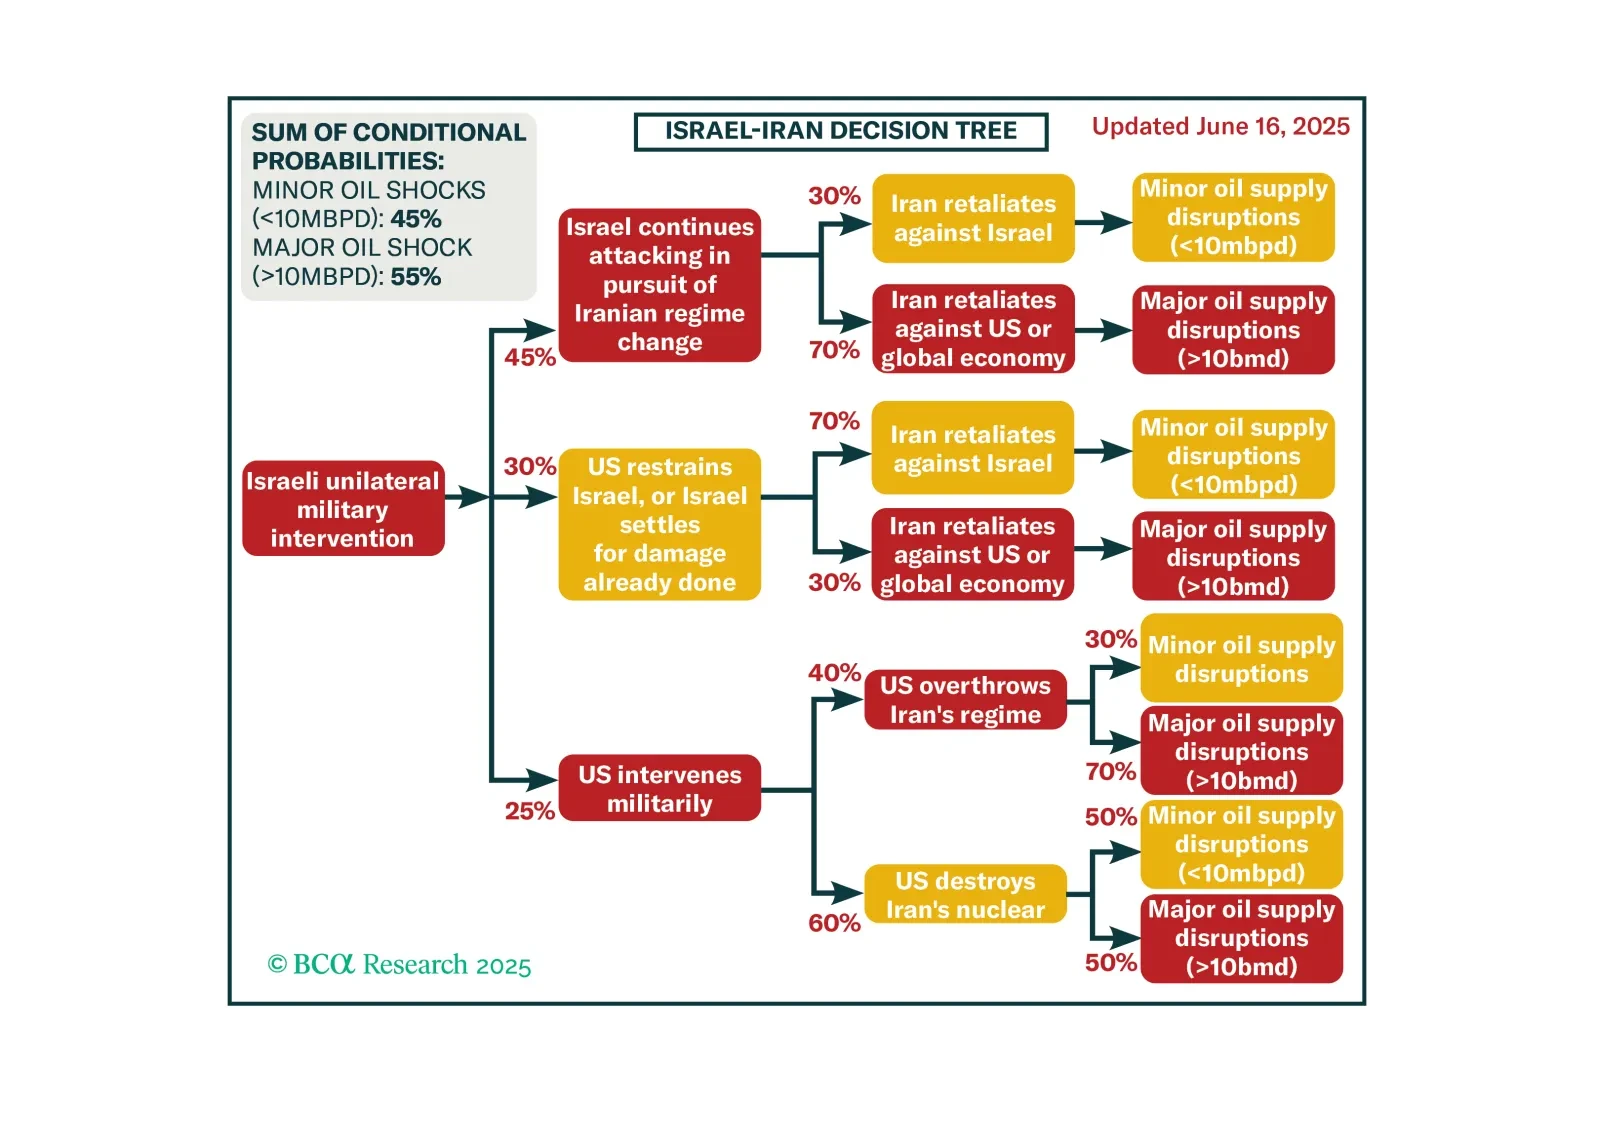
Los ataques de Israel a Irán continuarán hasta que Irán se vea obligado a atacar el suministro regional de petróleo para que Estados Unidos frene a Israel. Eso podría no funcionar. Los inversores deben prepararse para un impacto económico más amplio del conflicto.
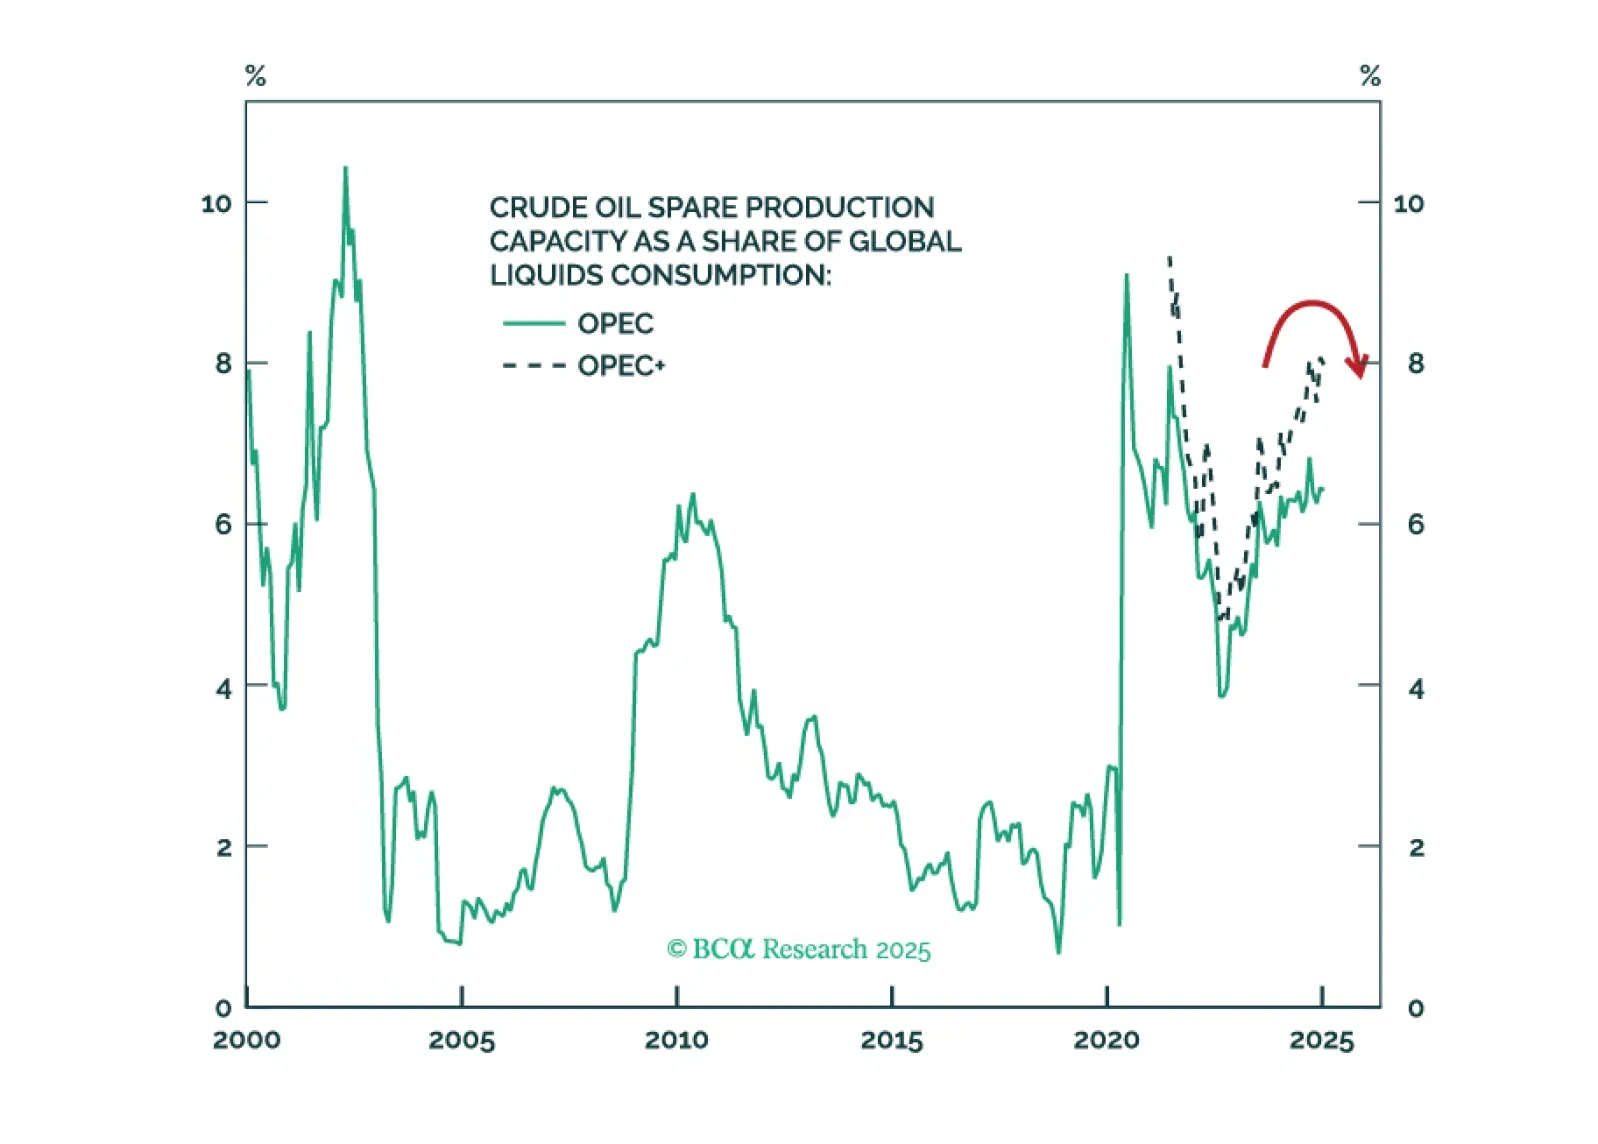
Investors should hold gold, build up some cash, tactically overweight US equities relative to global, and prepare for at least minor oil supply shocks – possibly major shocks – as the Israel-Iran war escalates.
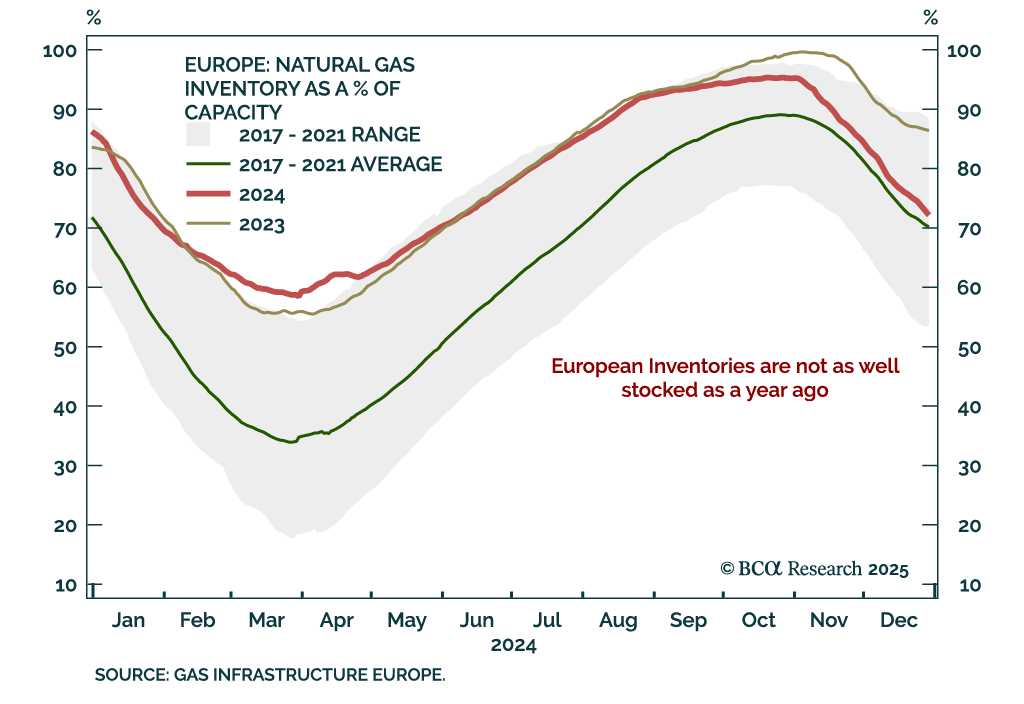
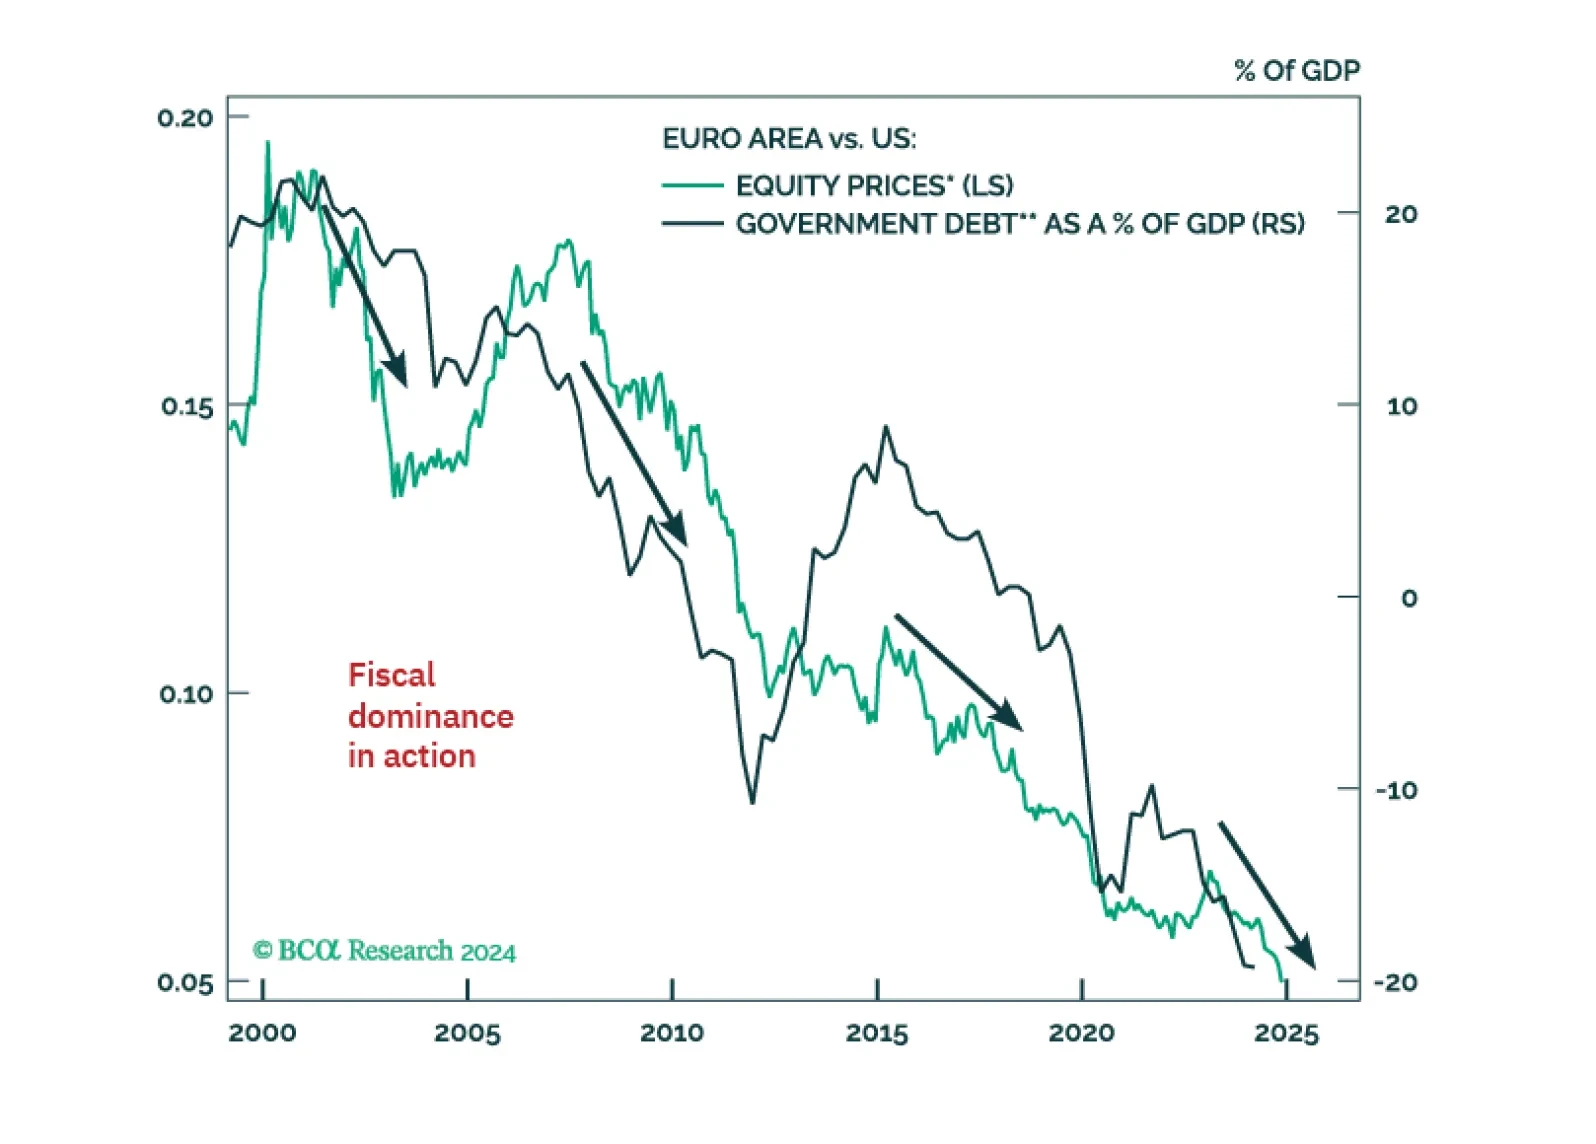
Los inversores han renunciado a los activos europeos, que ahora cotizan con descuentos excepcionales respecto a los activos estadounidenses. Sin embargo, una política fiscal estadounidense más restrictiva, el fin de la austeridad y del desapalancamiento en Europa, el tsunami de GNL a punto de golpear las costas europeas y el capex global impulsado por la Tríada Geopolítica Imposible significan que el momento de gloria de Europa pronto volverá.
Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.

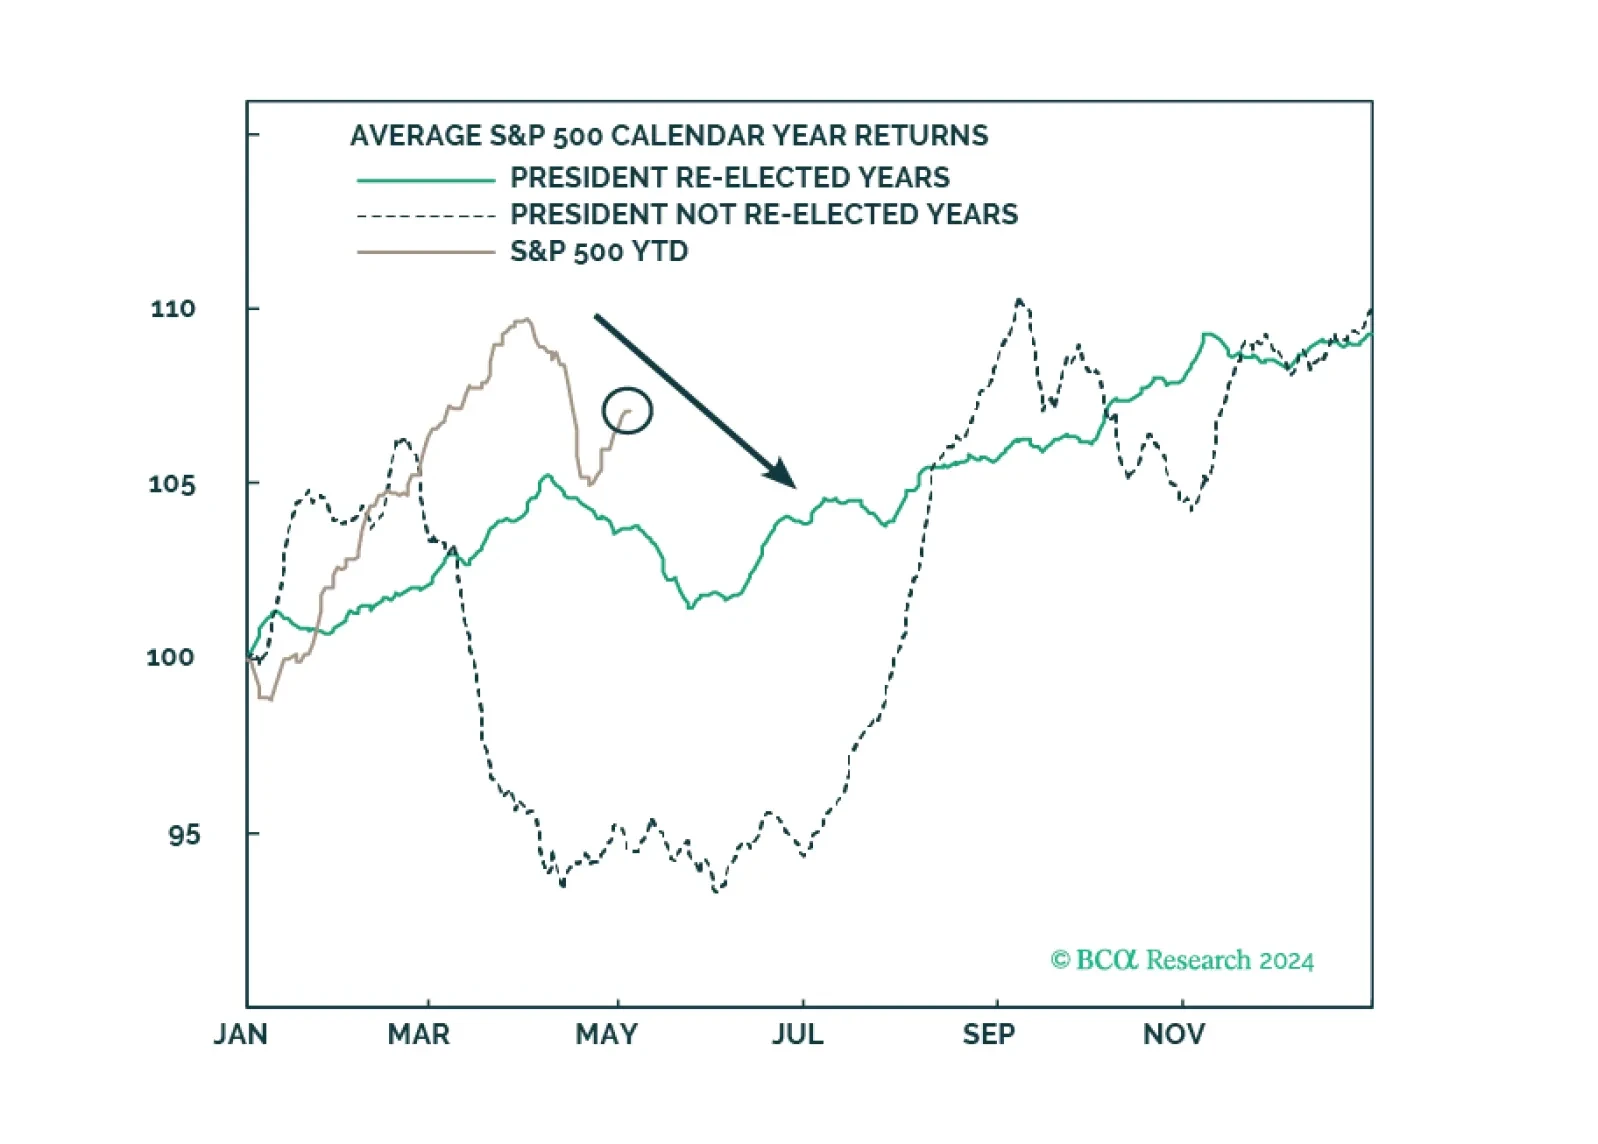
Investors should prepare for economic data to weaken even as policy uncertainty and geopolitical risk skyrocket ahead of the US election.
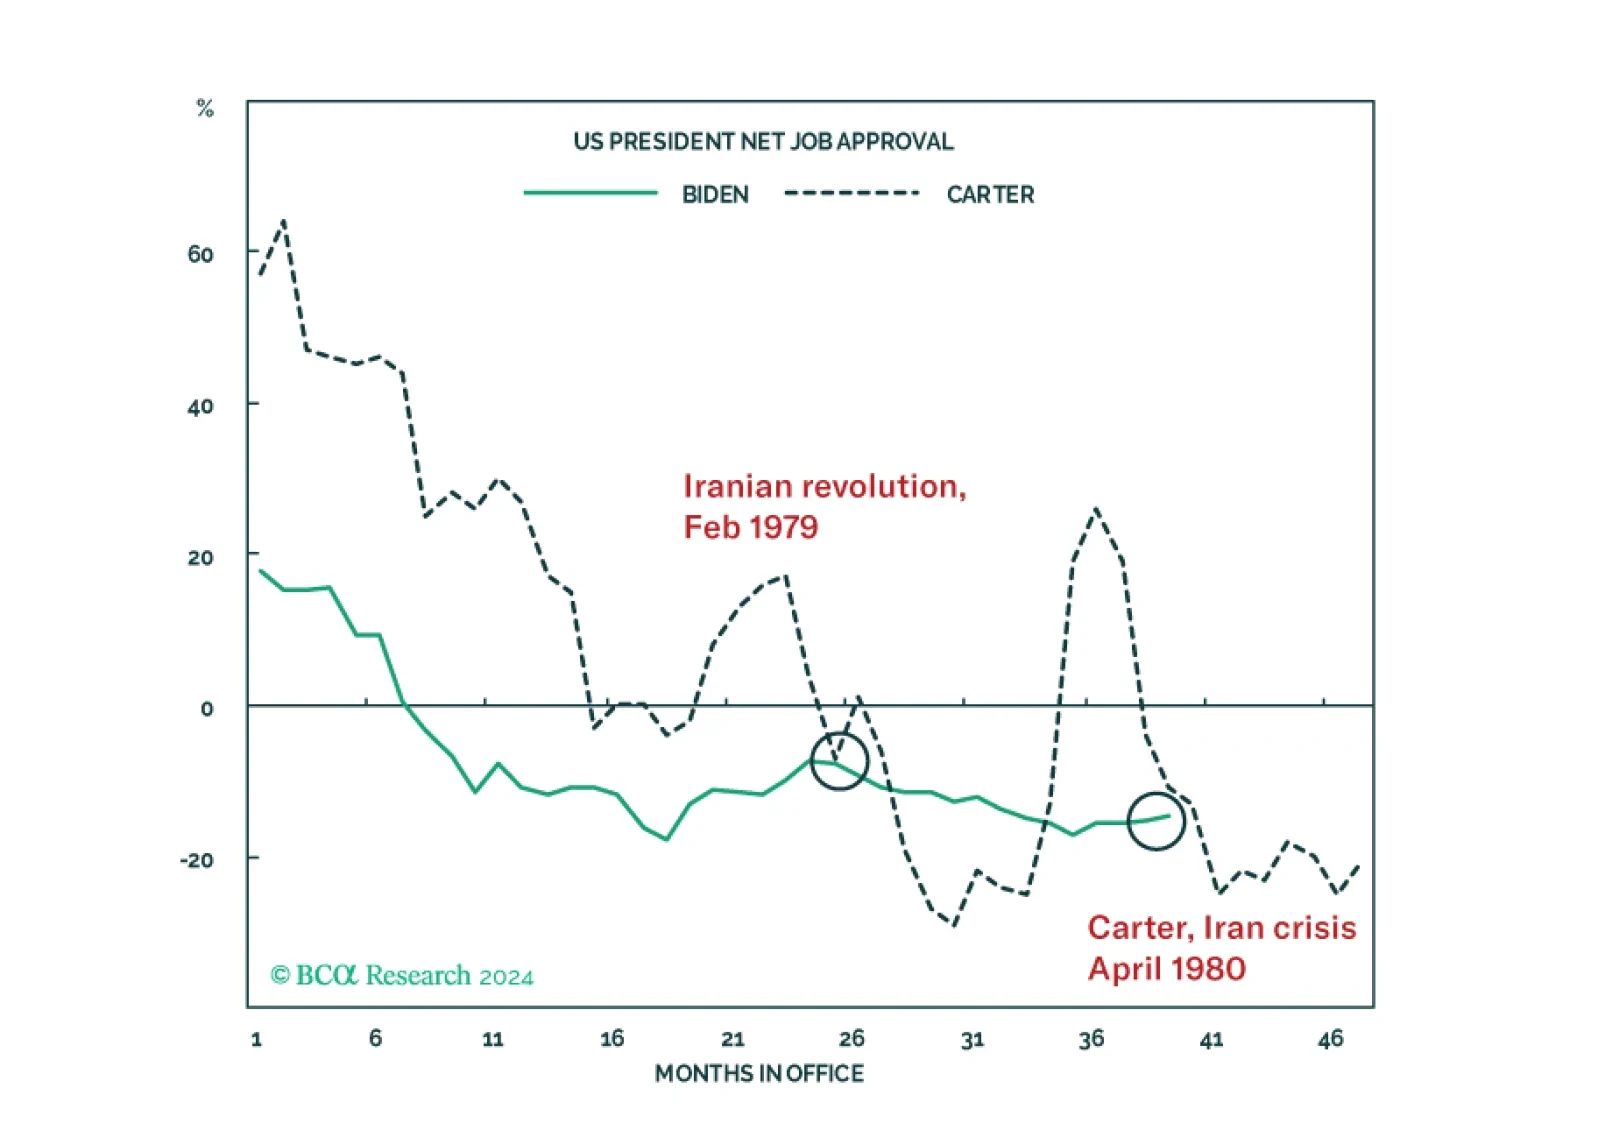
Our quant models suggest Democrats are still slightly favored for the White House. Our Senate model favors Republican control, though Montana and Ohio are the weak links that could deliver Democrats a de facto Senate majority in the event they keep the White House. But there are still six months before the vote. An oil shock from the Middle East or other negative economic news would force a major change to these models.

We are strategically bullish on the outlook of the energy sector. Domestic and external political constraints asserted themselves, restraining the most negative impulse against this sector by the Biden administration. Go long energy versus cyclicals (ex-tech).