 FICC
Find out more
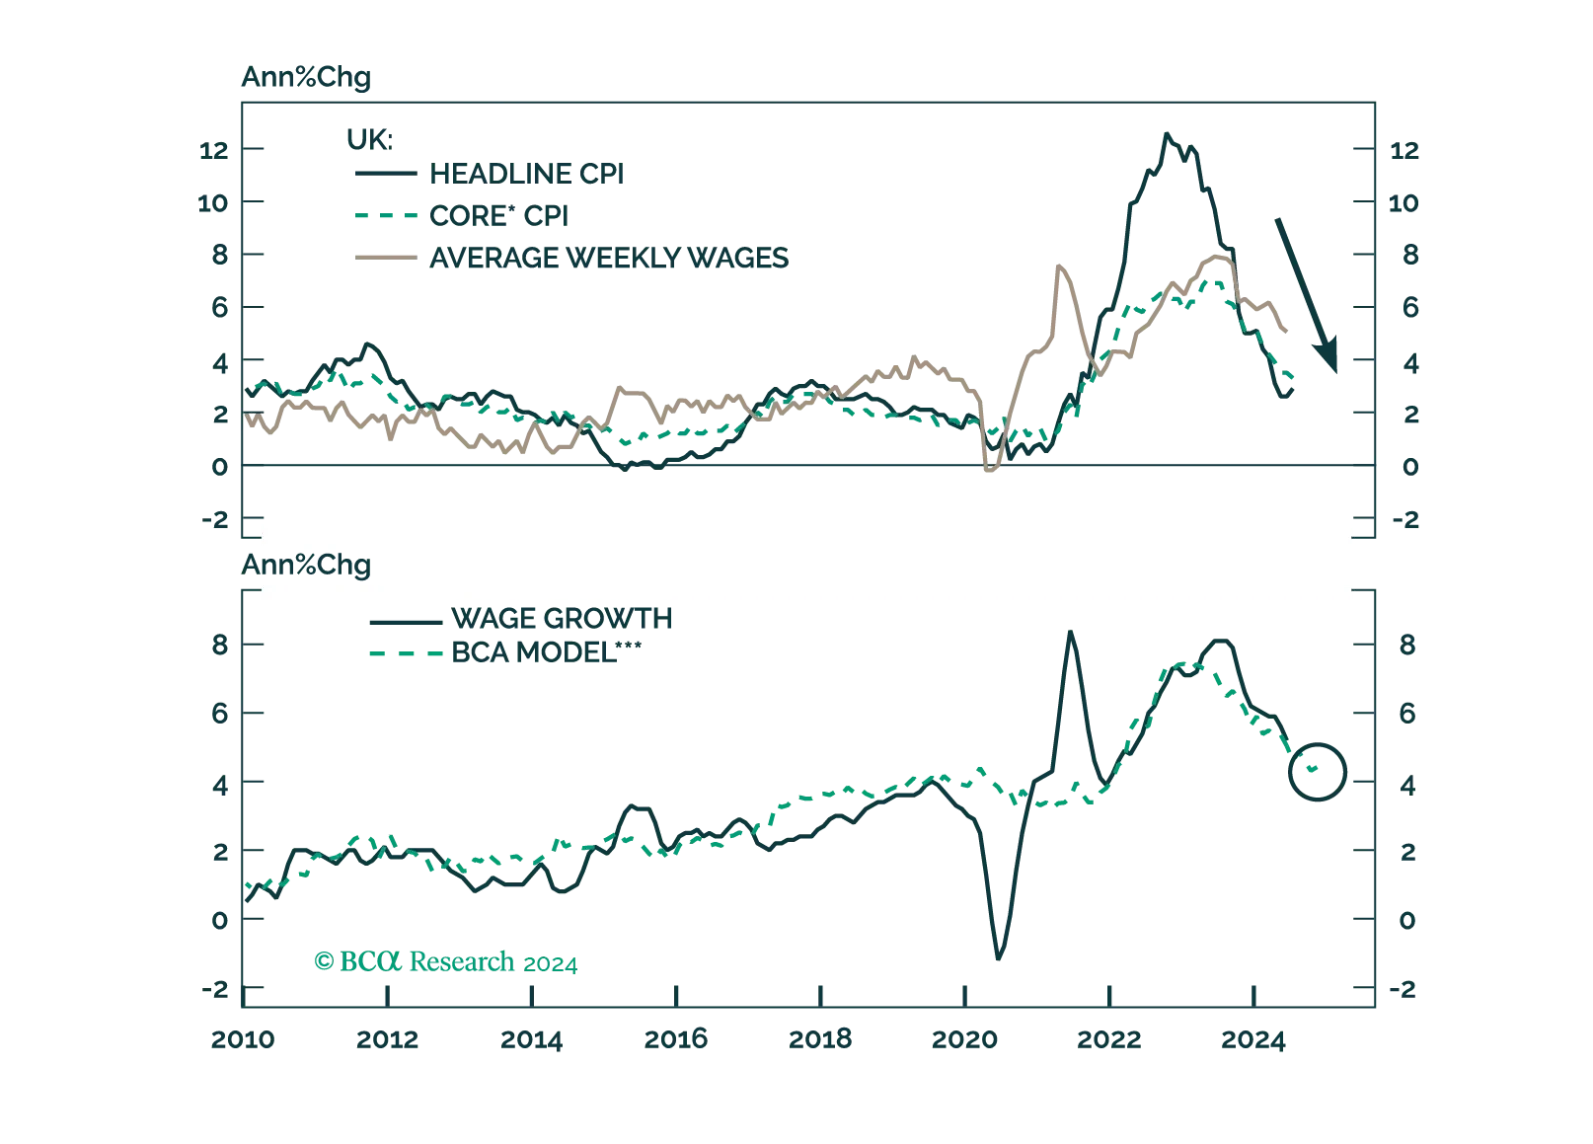
What do the mixed signals sent by the UK economy mean for the Bank of England, and what are the implications for Gilts and the British pound?
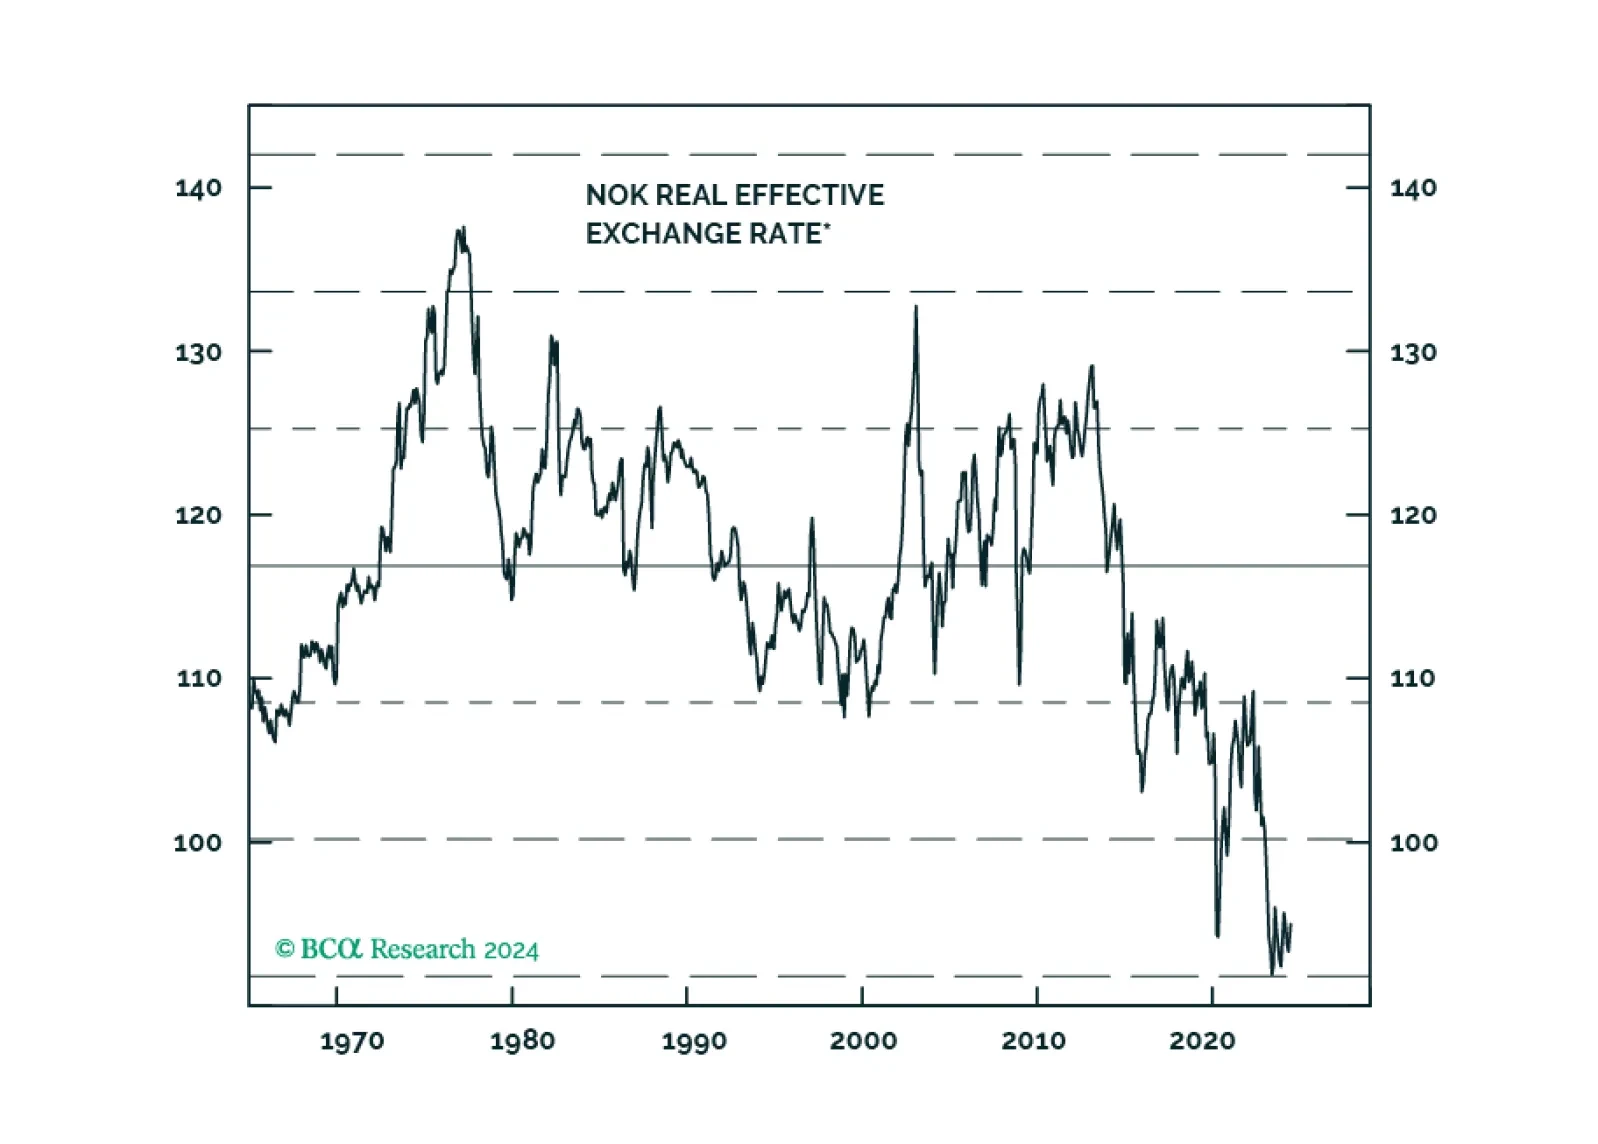

In this monthly review, we give our take on where bond yields and the dollar are headed. This is within the lens of revisiting our fundamental indicators.

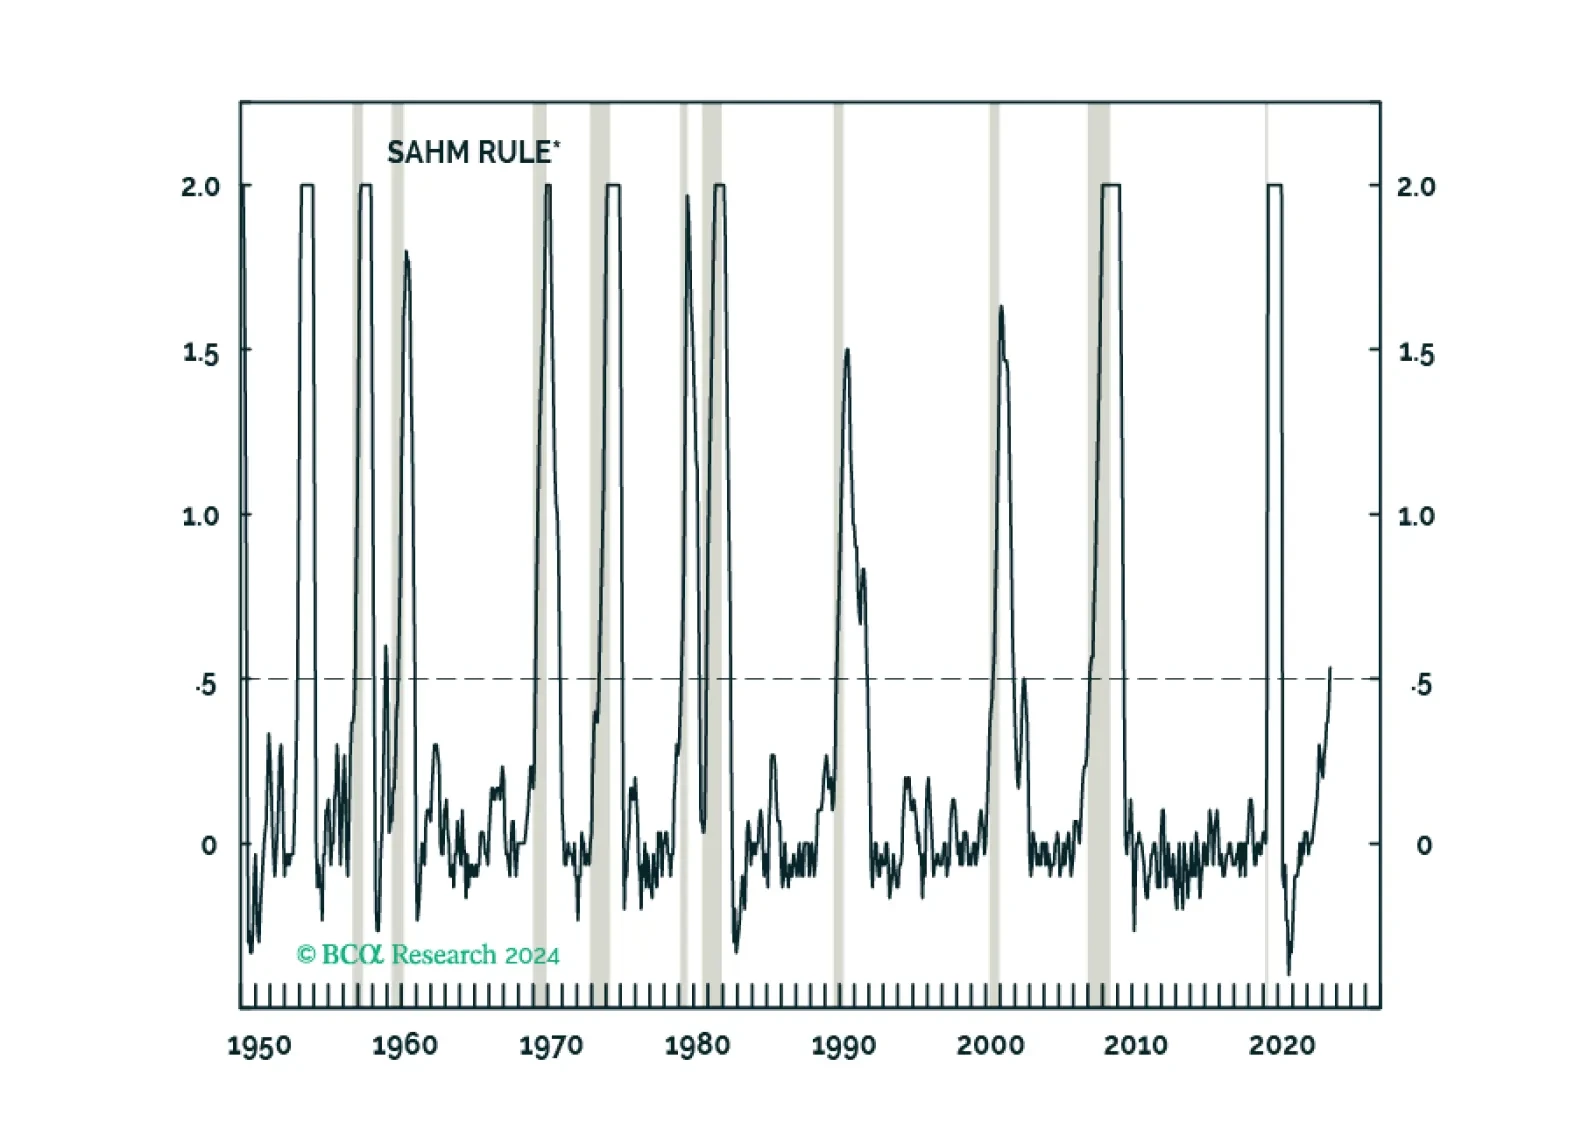
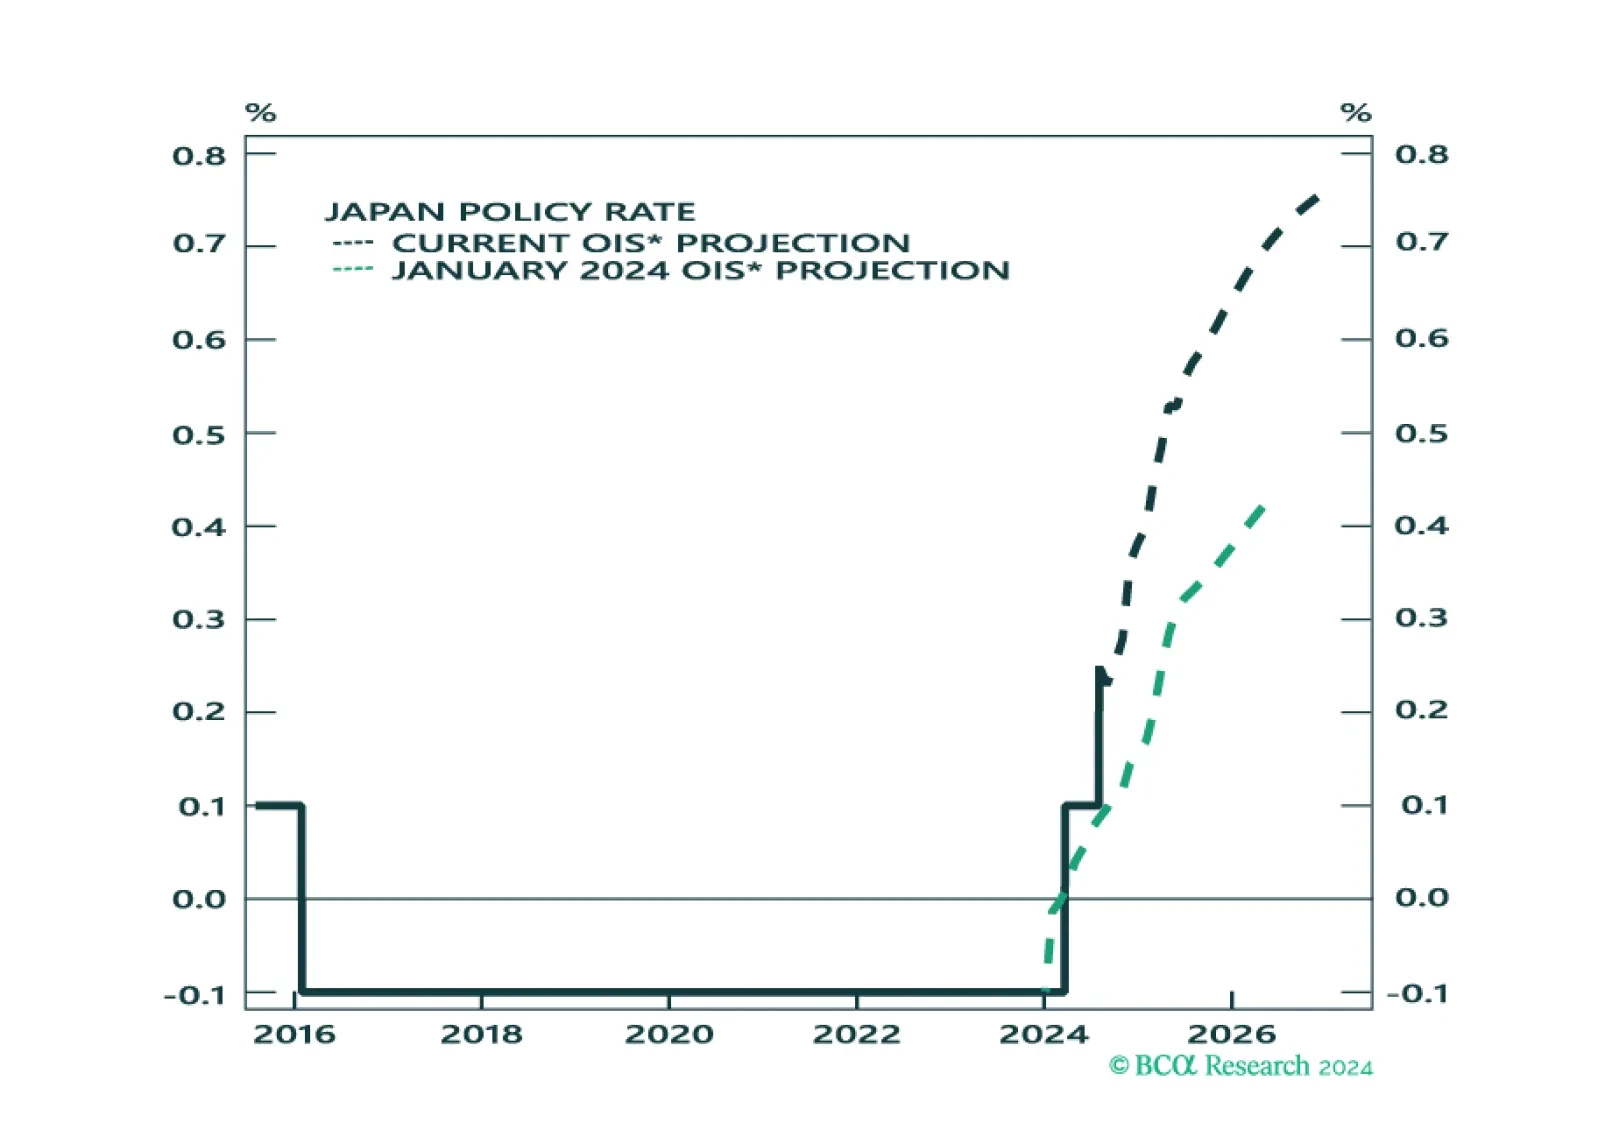
We assess the investment implications of the BoJ and Fed meetings, and give our take on the next policy moves. We also assess the impact on asset markets.
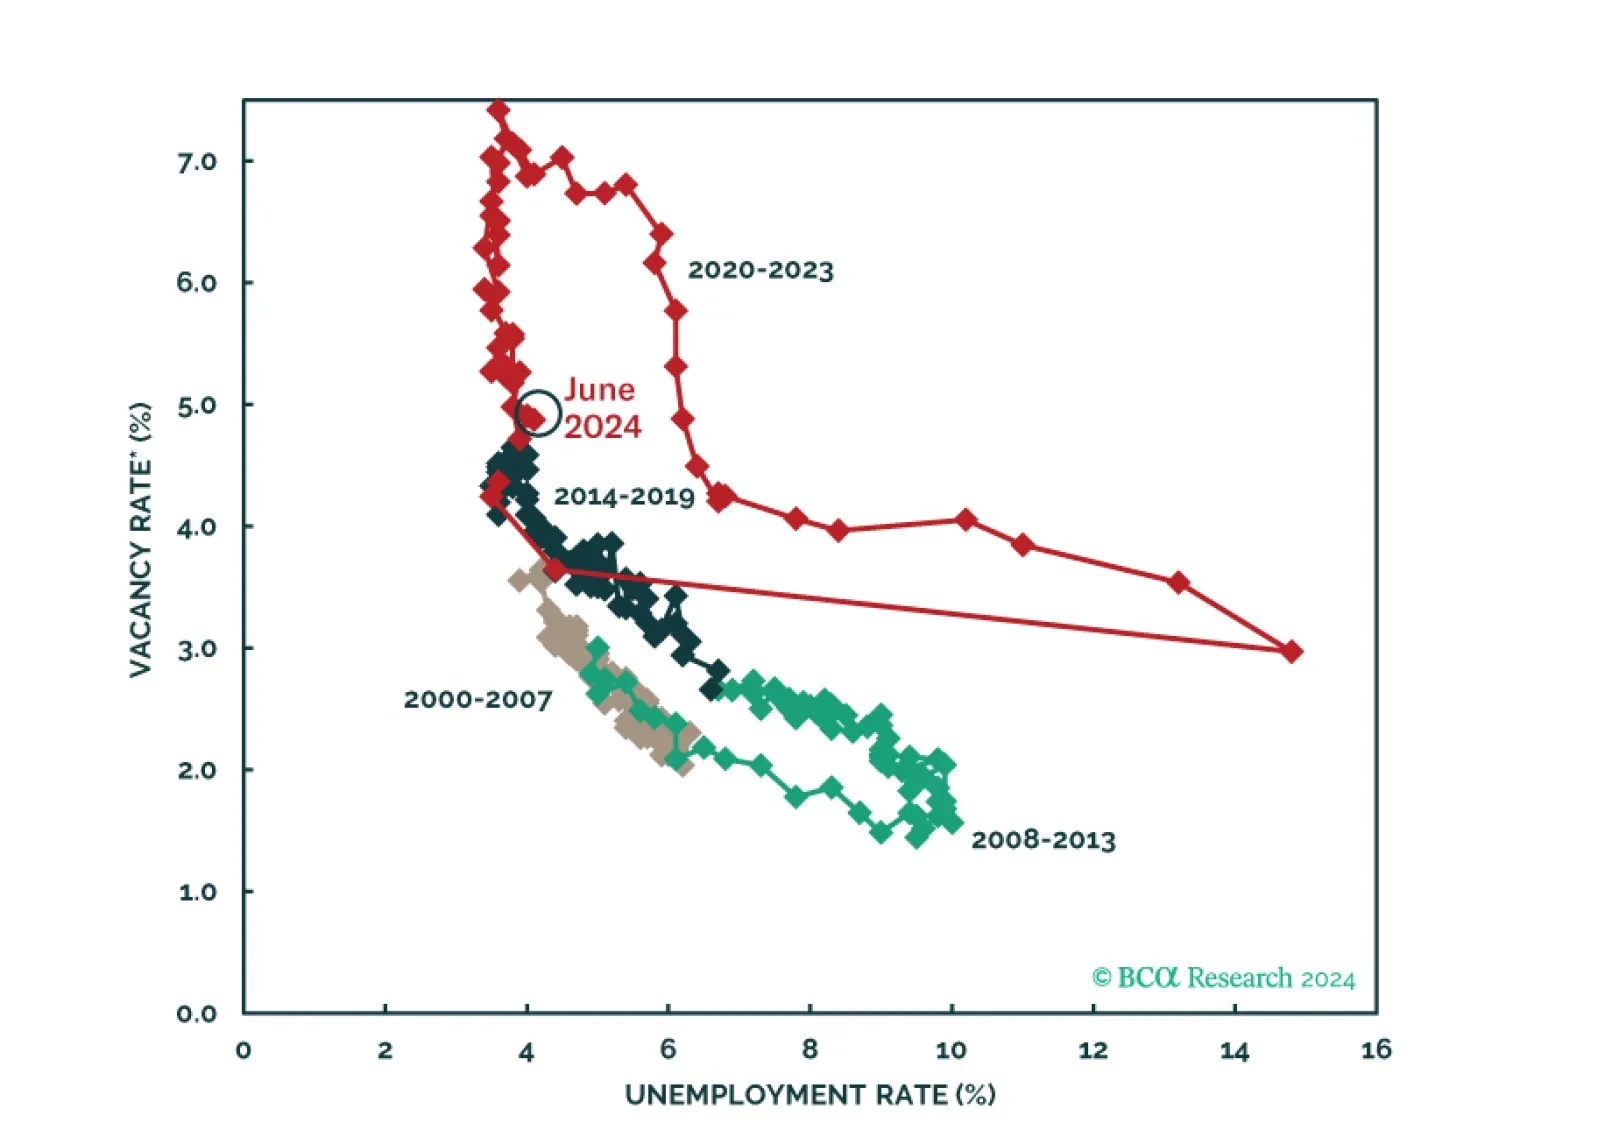
The Fed kept rates steady today, but teed up an initial rate cut in September while putting more emphasis on the employment side of its dual mandate.
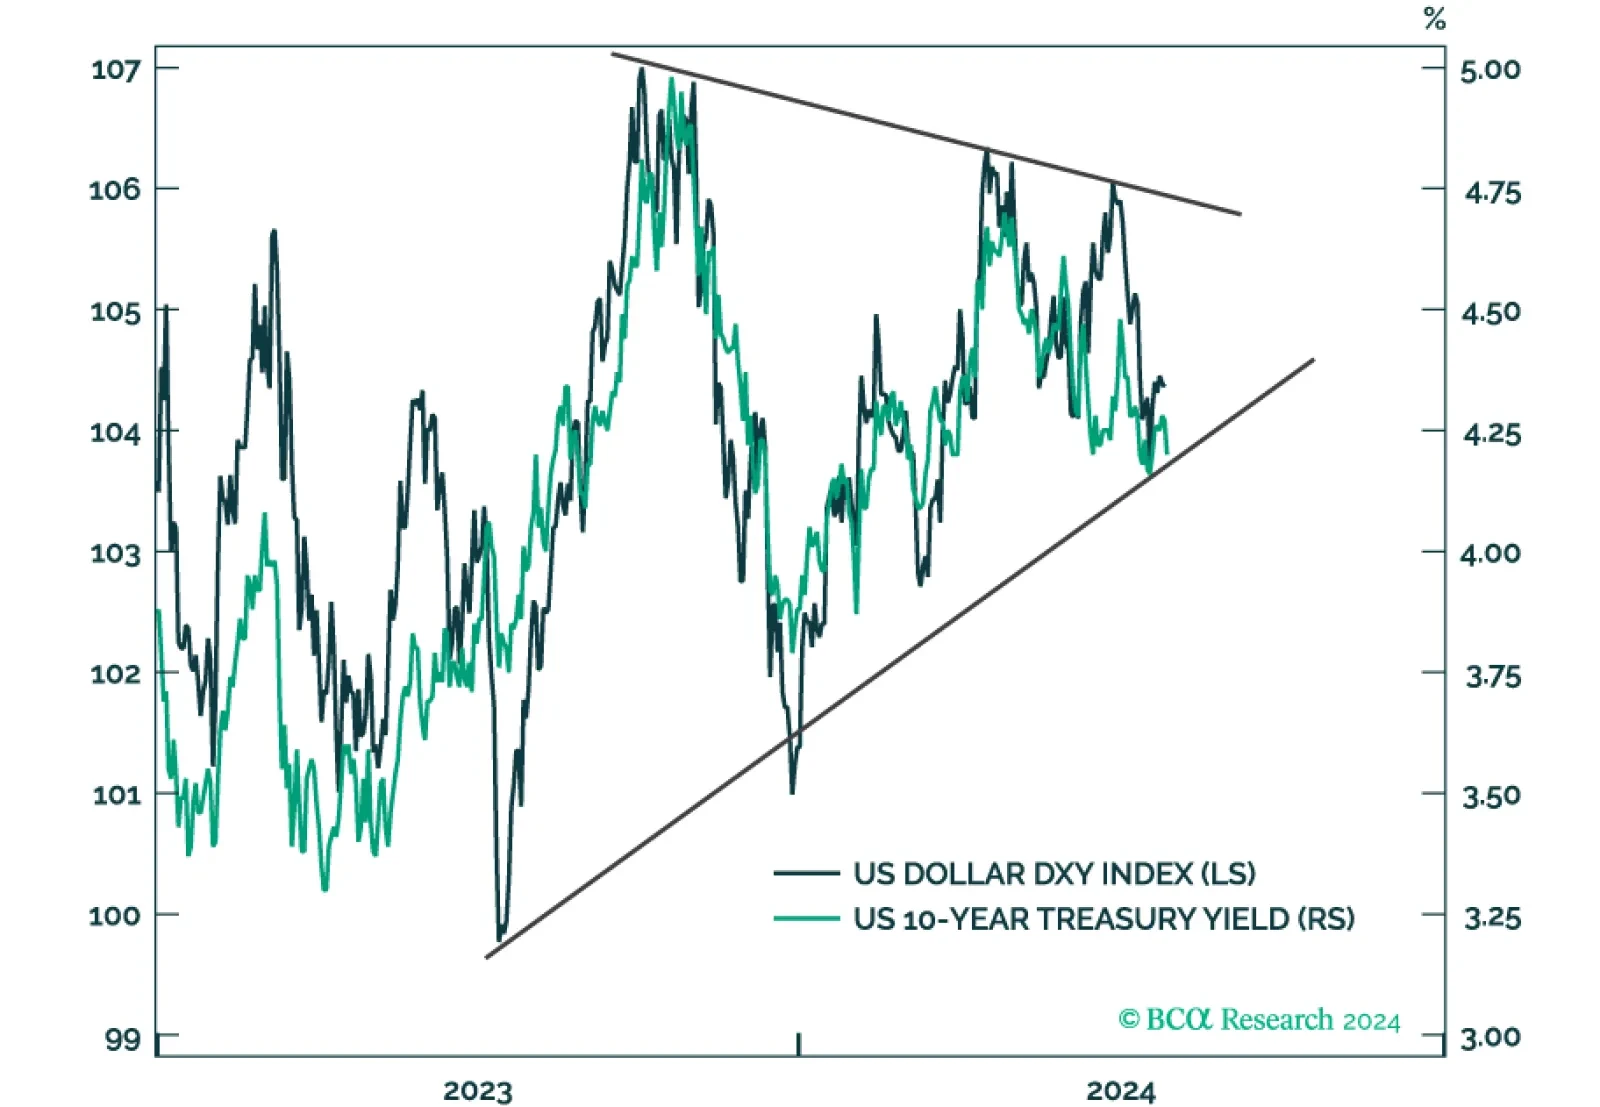
This report takes a look at bond and FX market technical indicators and calibrates the decision to increase portfolio duration and get long the US dollar.
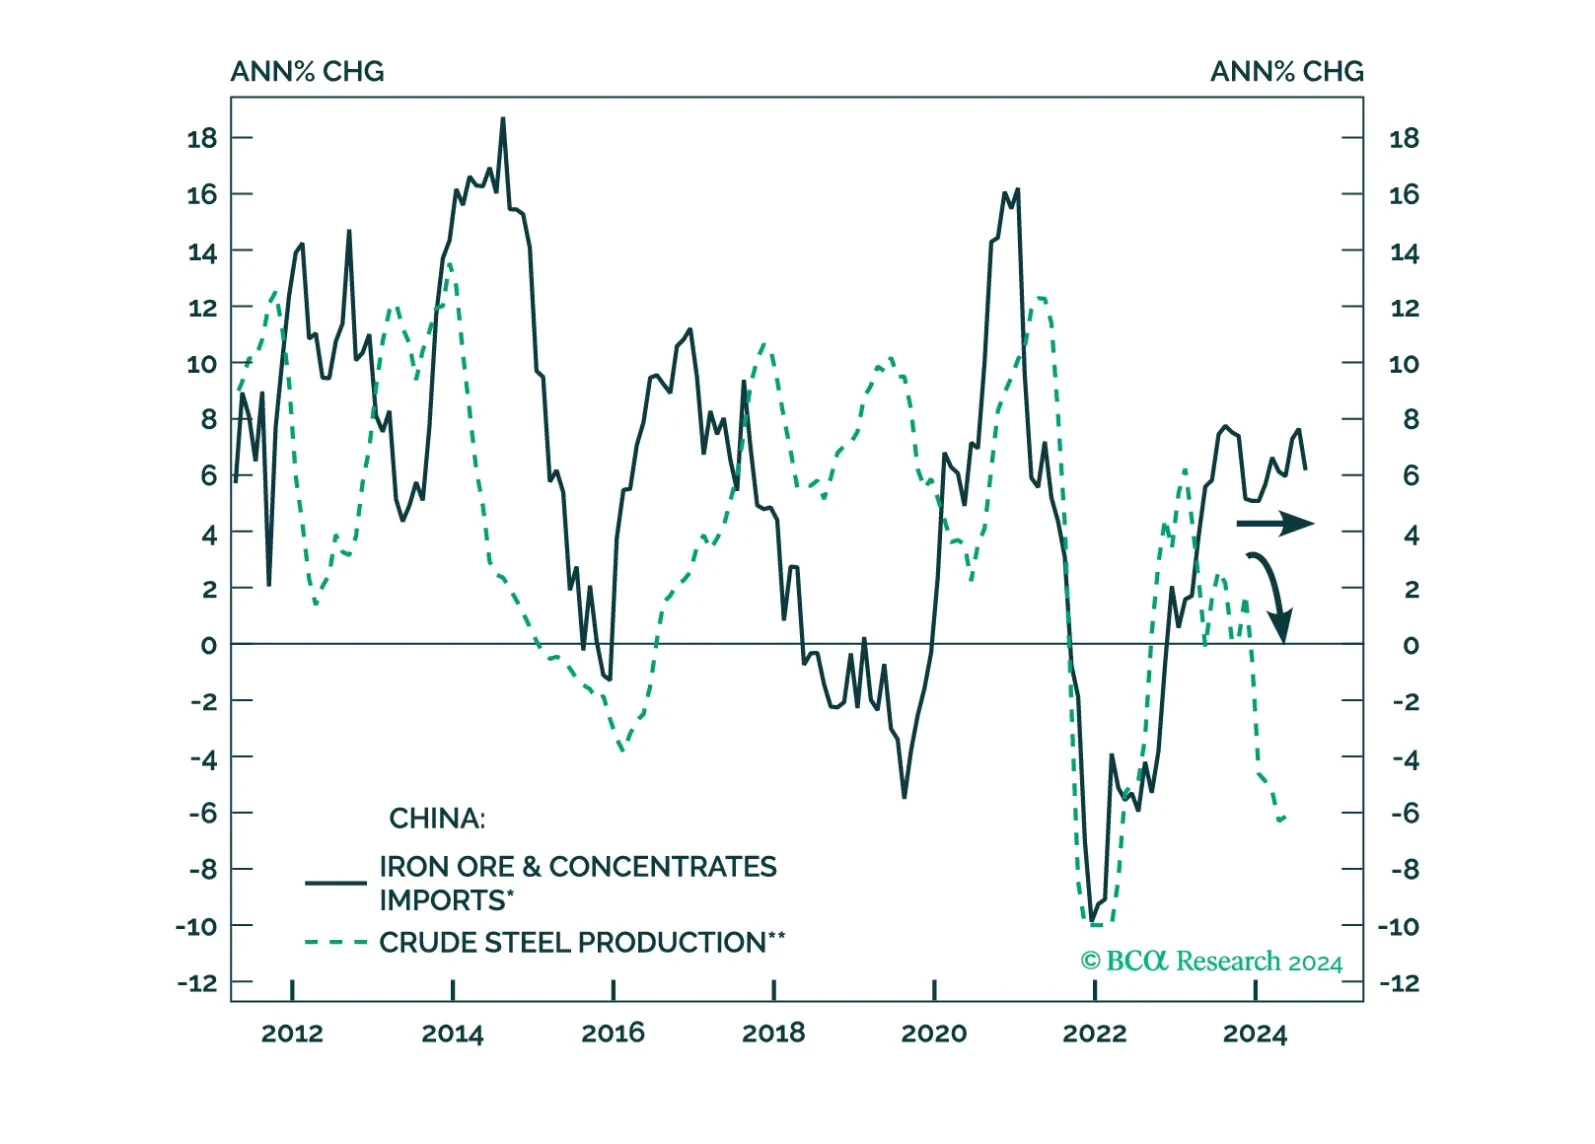
The absence of a catalyst that will boost Chinese steel demand dims the odds that iron ore and steel prices will recover over the coming six-to-nine months. Instead, we expect ferrous metals to face further downside into year-end.
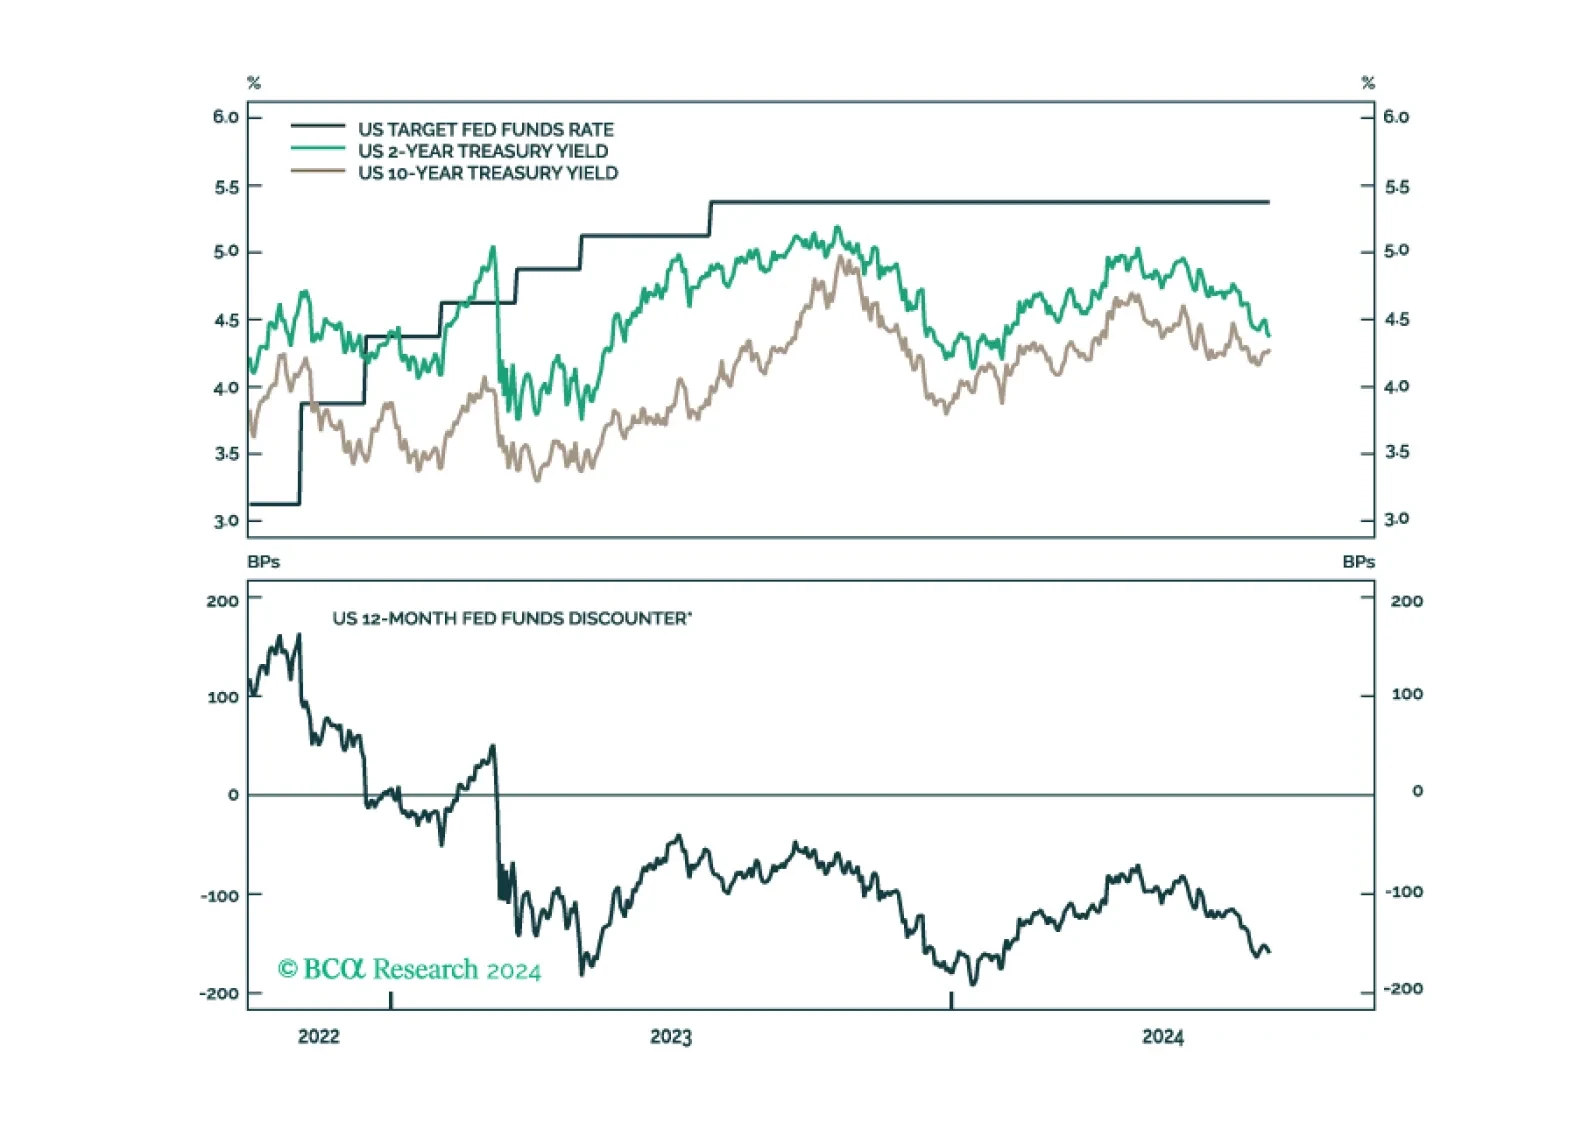
After this morning’s jobless claims number, we have now seen enough deterioration in our preferred labor market indicators to increase portfolio duration from “at benchmark” to “above benchmark”.