 FICC
Find out more
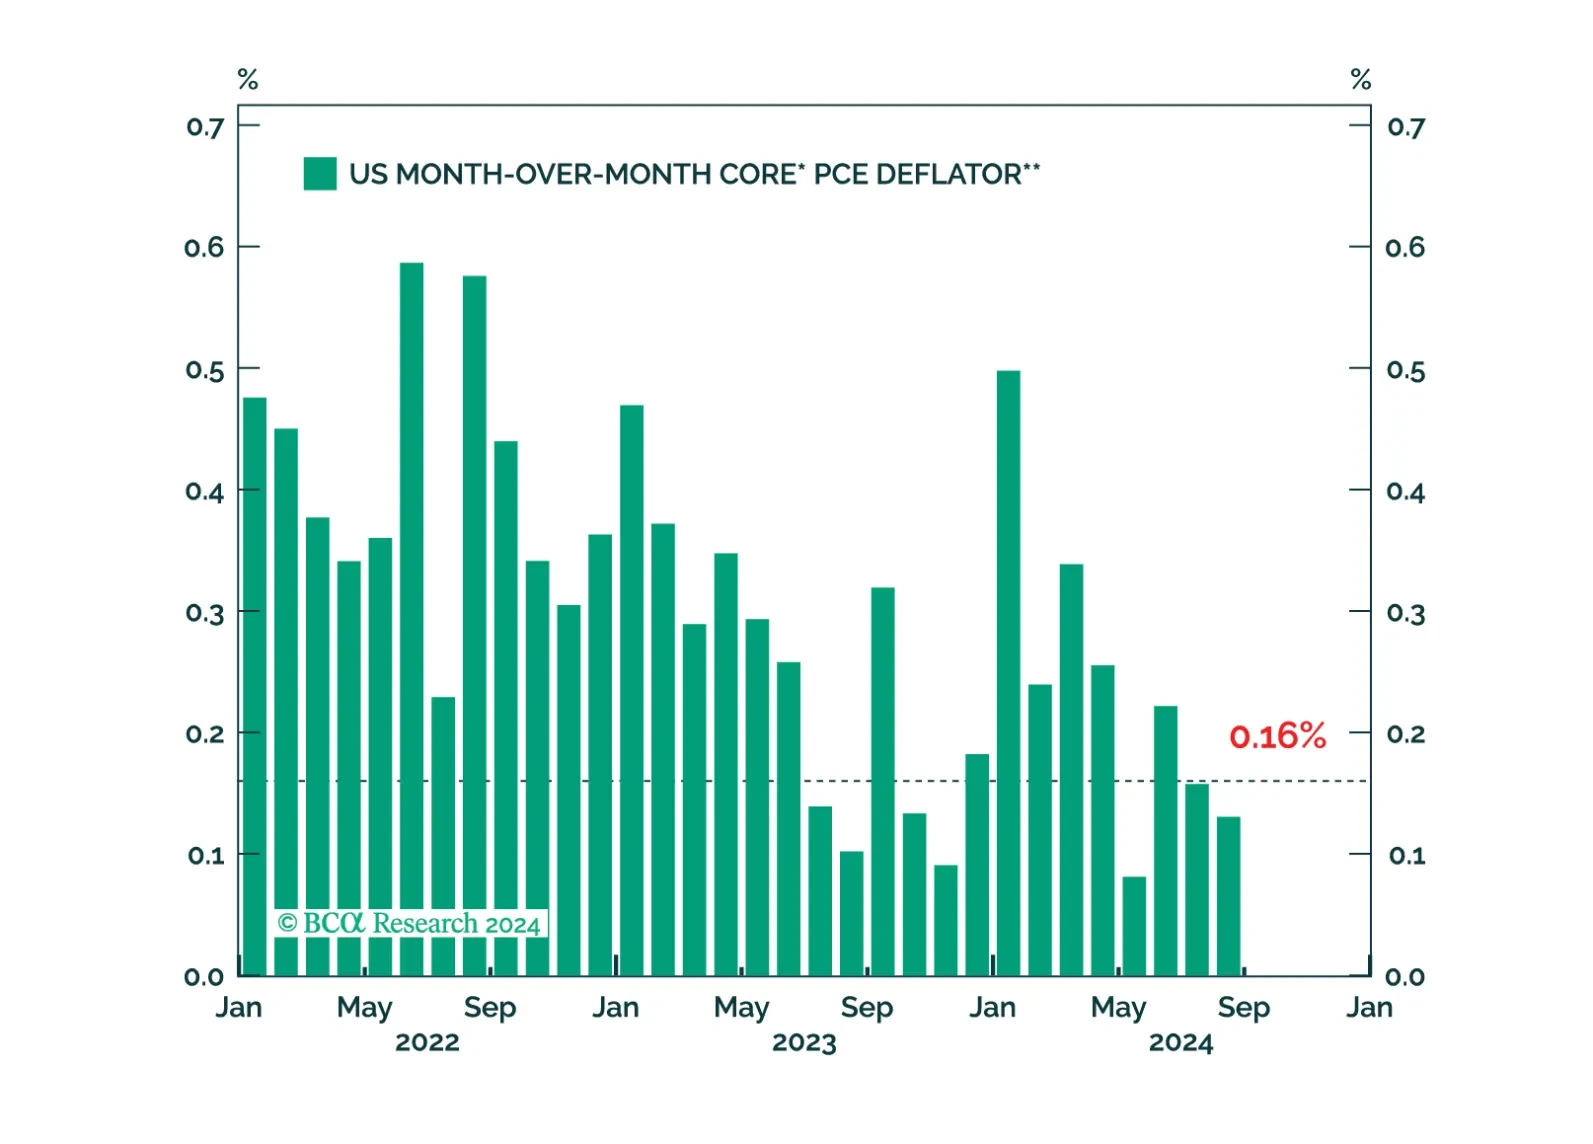
We consider the possibility that lower interest rates could lead to an increase in household borrowing, prolonging the economic recovery.
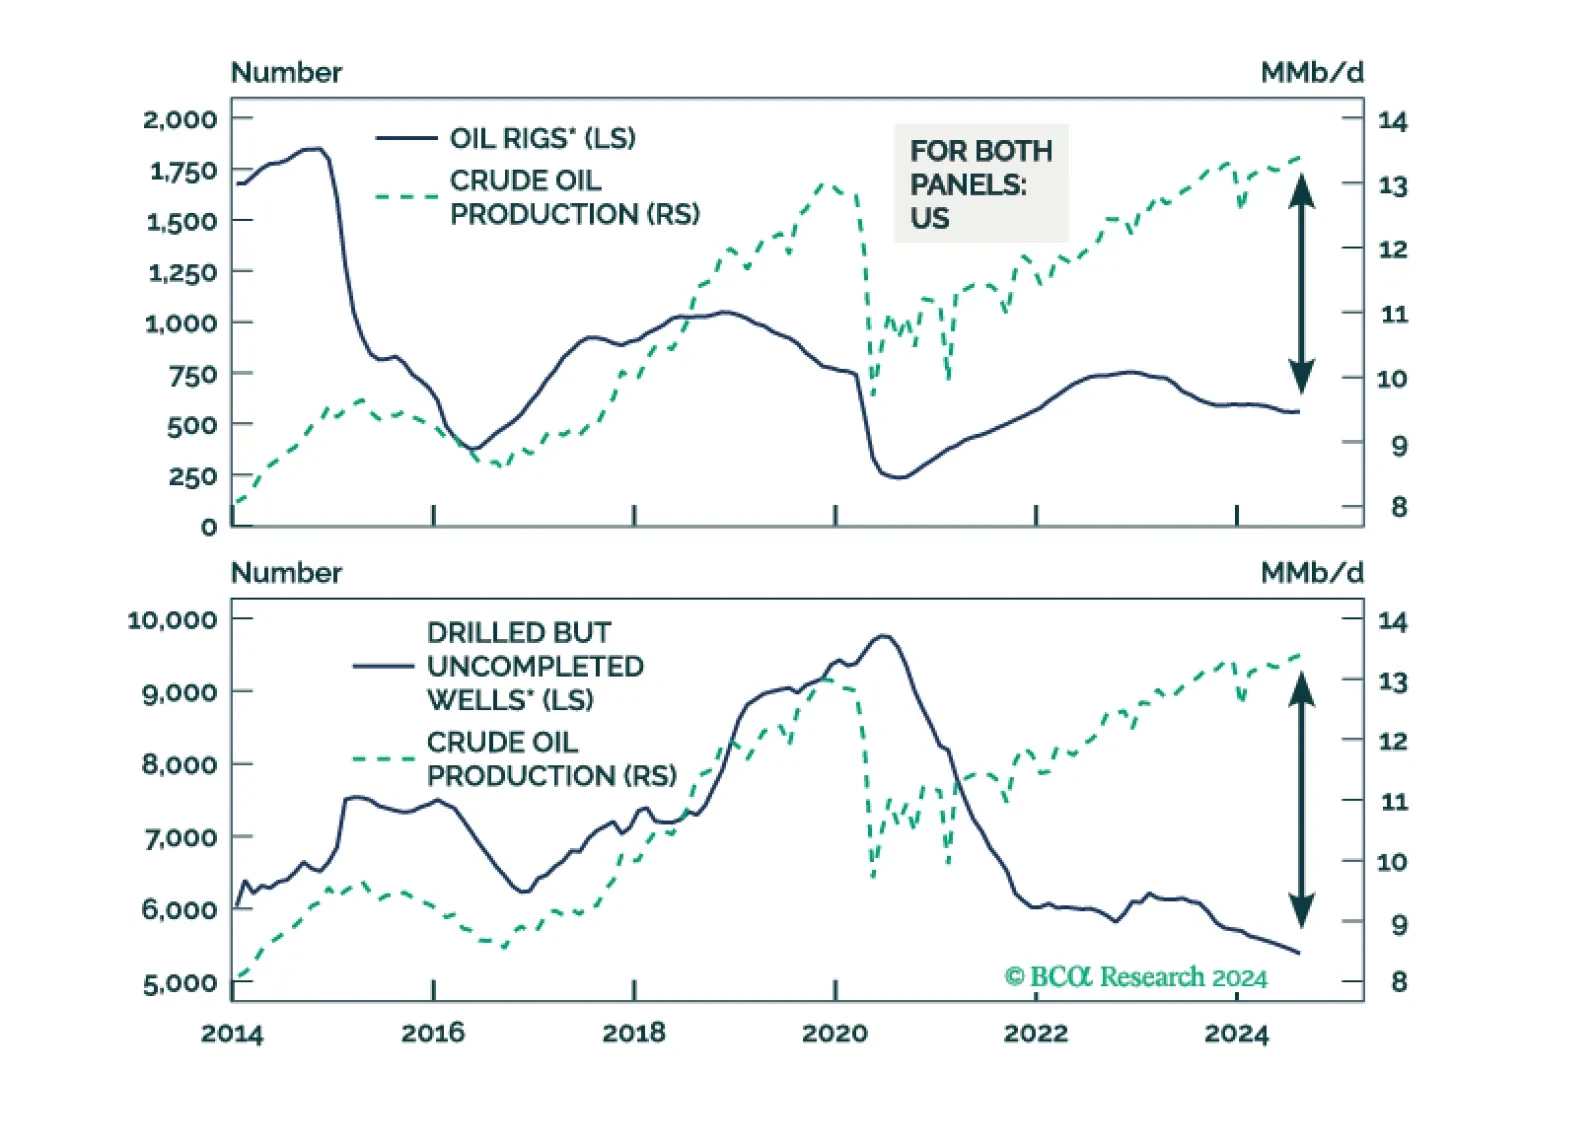
US crude oil output has not peaked. It will continue to increase. A continued expansion of US production, even if it is moderate, along with a possible increase in OPEC+ output, will lead to an oversupplied oil market. Moreover, we expect the demand headwind from the business cycle slowdown to weigh on crude prices. Over a 6-to-12-month horizon, the path of least resistance for oil prices is to the downside.
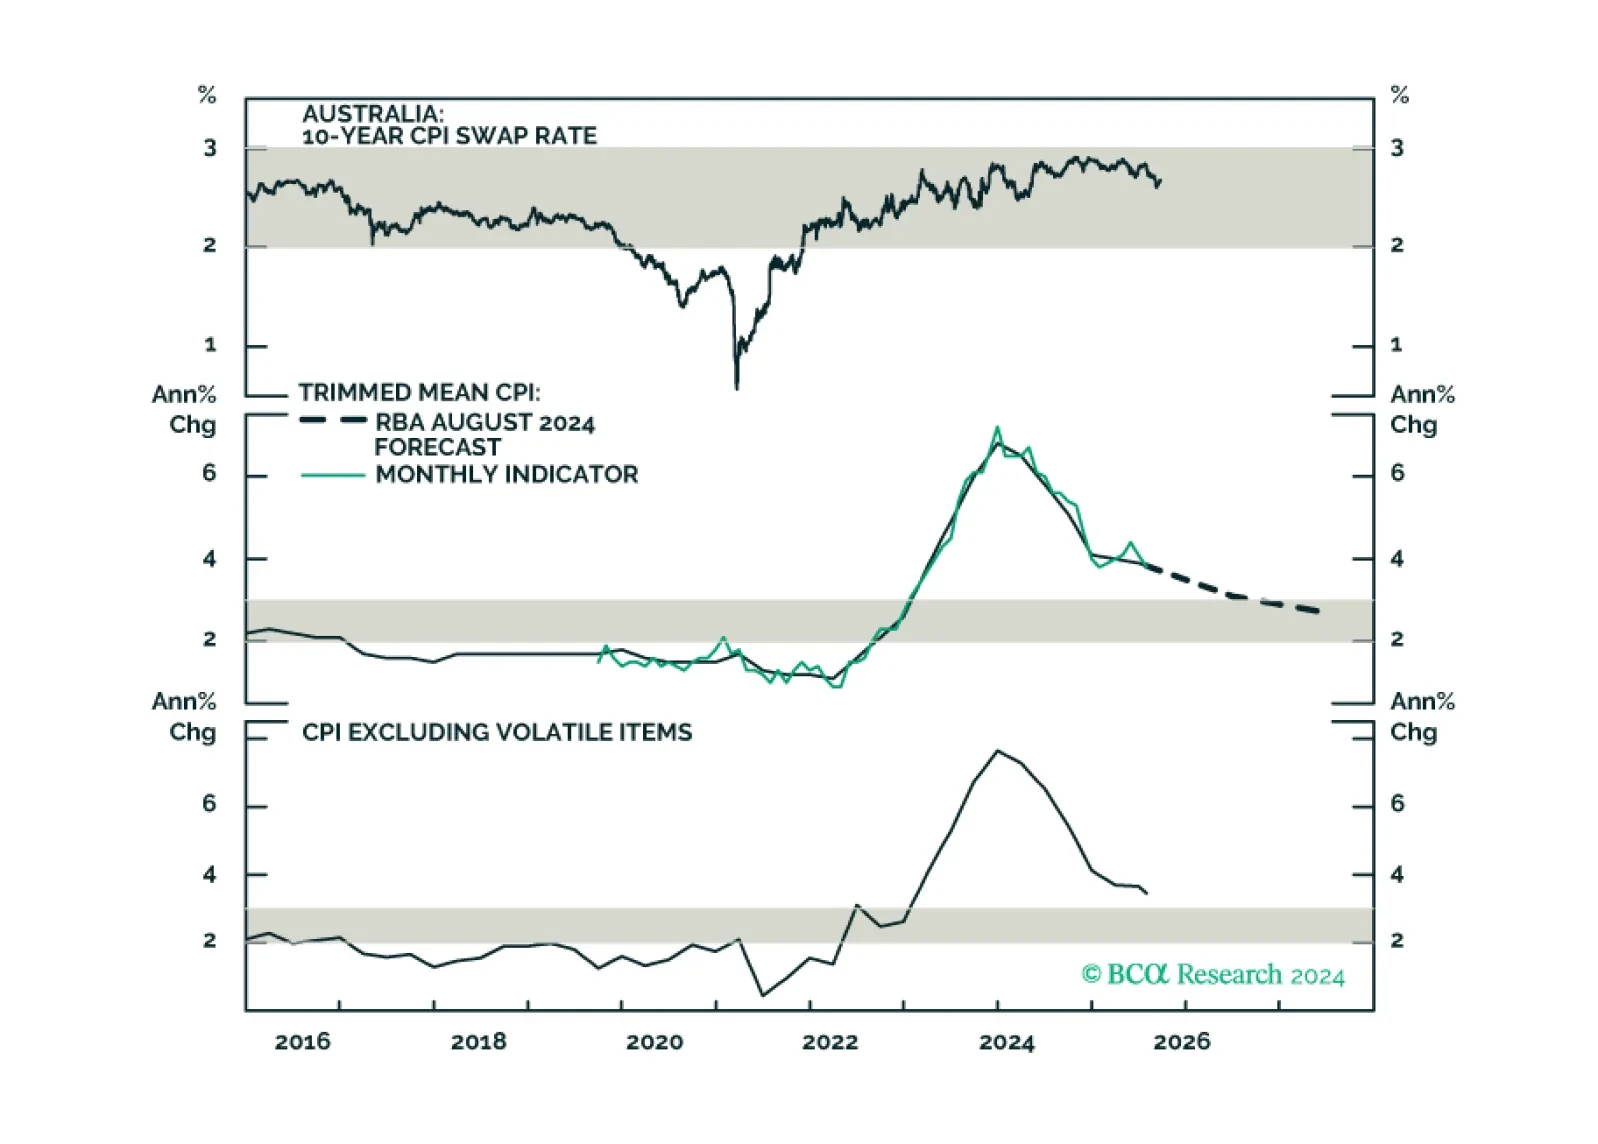
This insight parses through the RBA’s latest policy decision, and makes recommendations on whether to expect any rate cuts in 2024, and beyond.
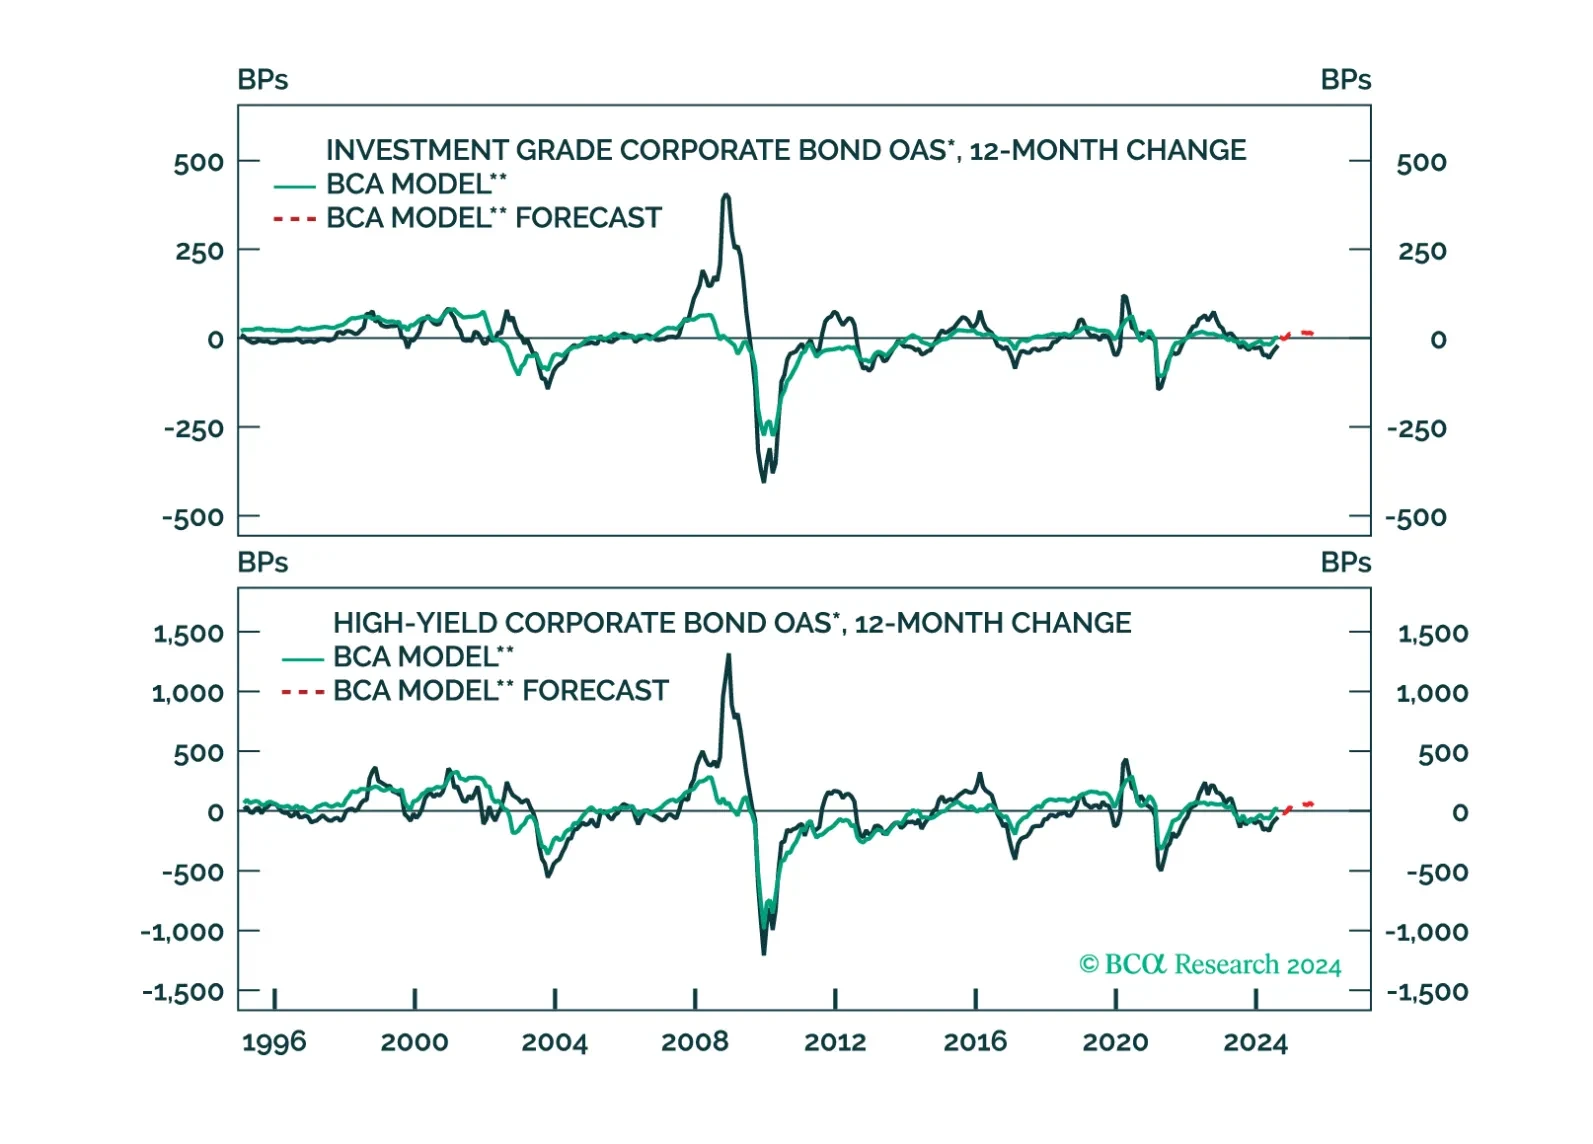
We update our corporate default rate model and consider the implications for corporate bond spreads.
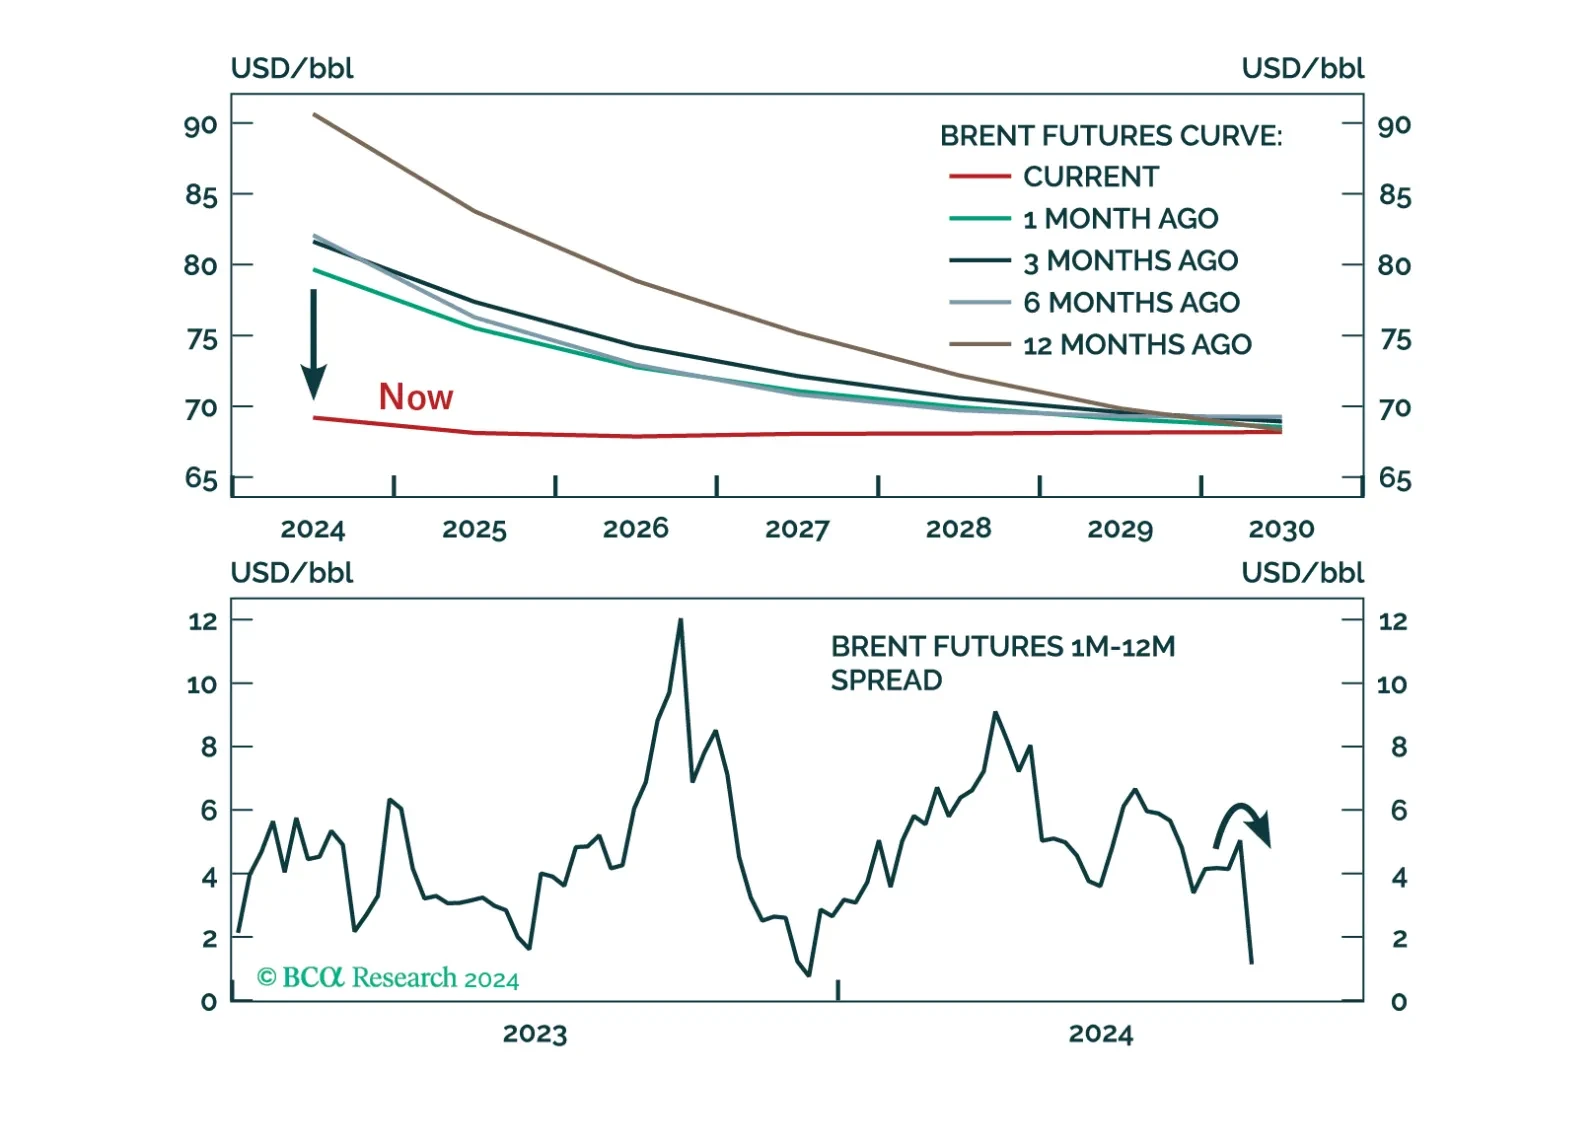
A bearish chill has engulfed oil markets. Earlier this week, Brent dropped to a near three-year low, falling below the trading range that had prevailed over the prior 18 months. In this Strategy Insight we detail why we do not believe that the worst has passed for oil markets. Rather, prices are likely to drop further over a six-to-nine-month horizon.
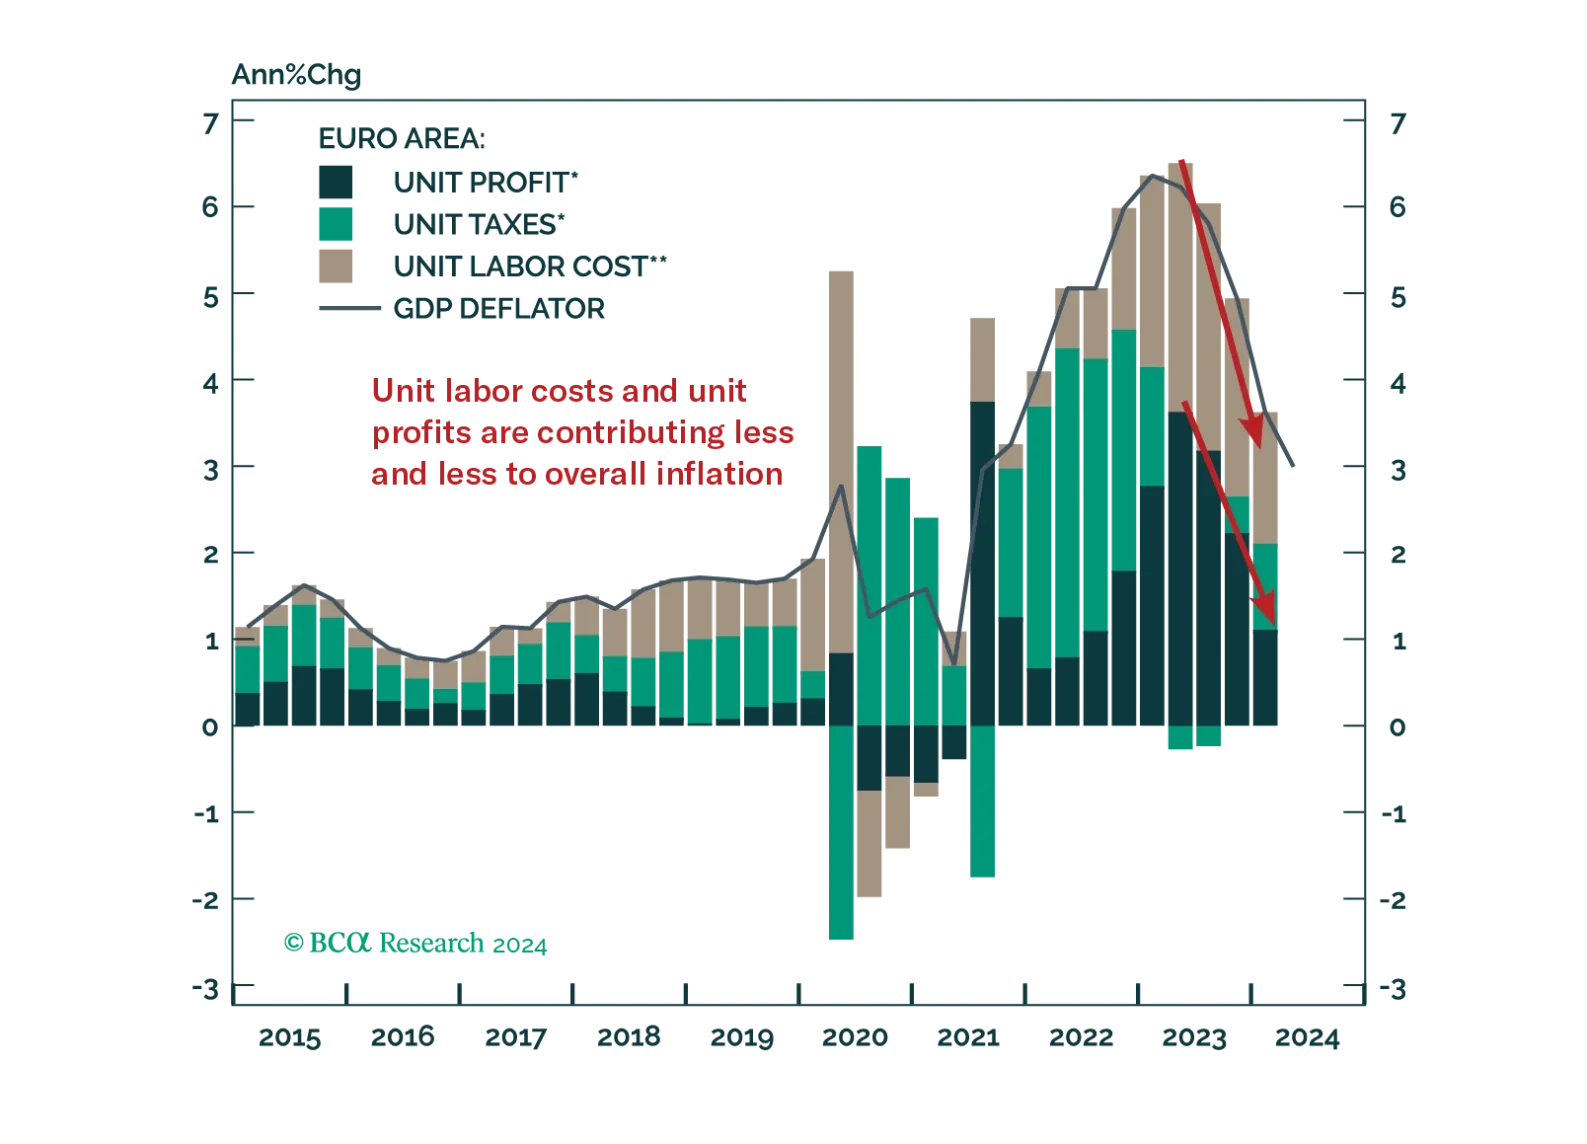
The ECB will cut rates once more this year; however, markets underprice how far it will ease next year.
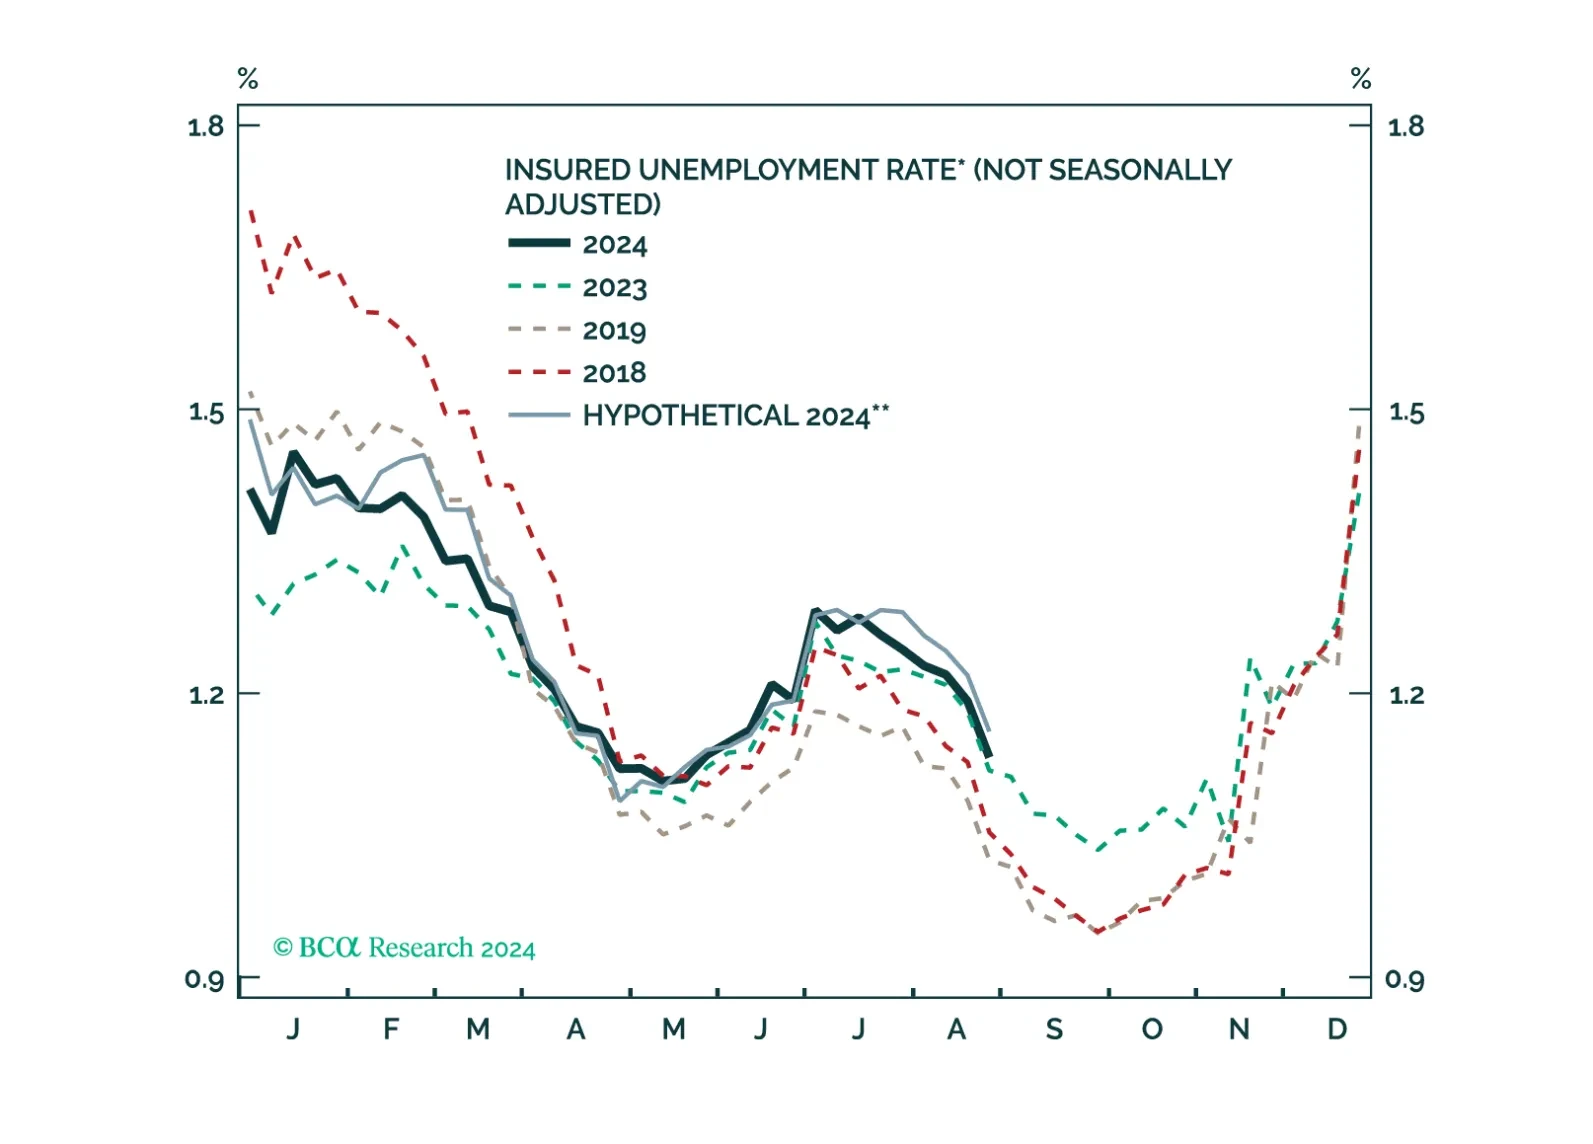
Some thoughts on this morning’s US claims report and a preview of next week’s FOMC meeting.
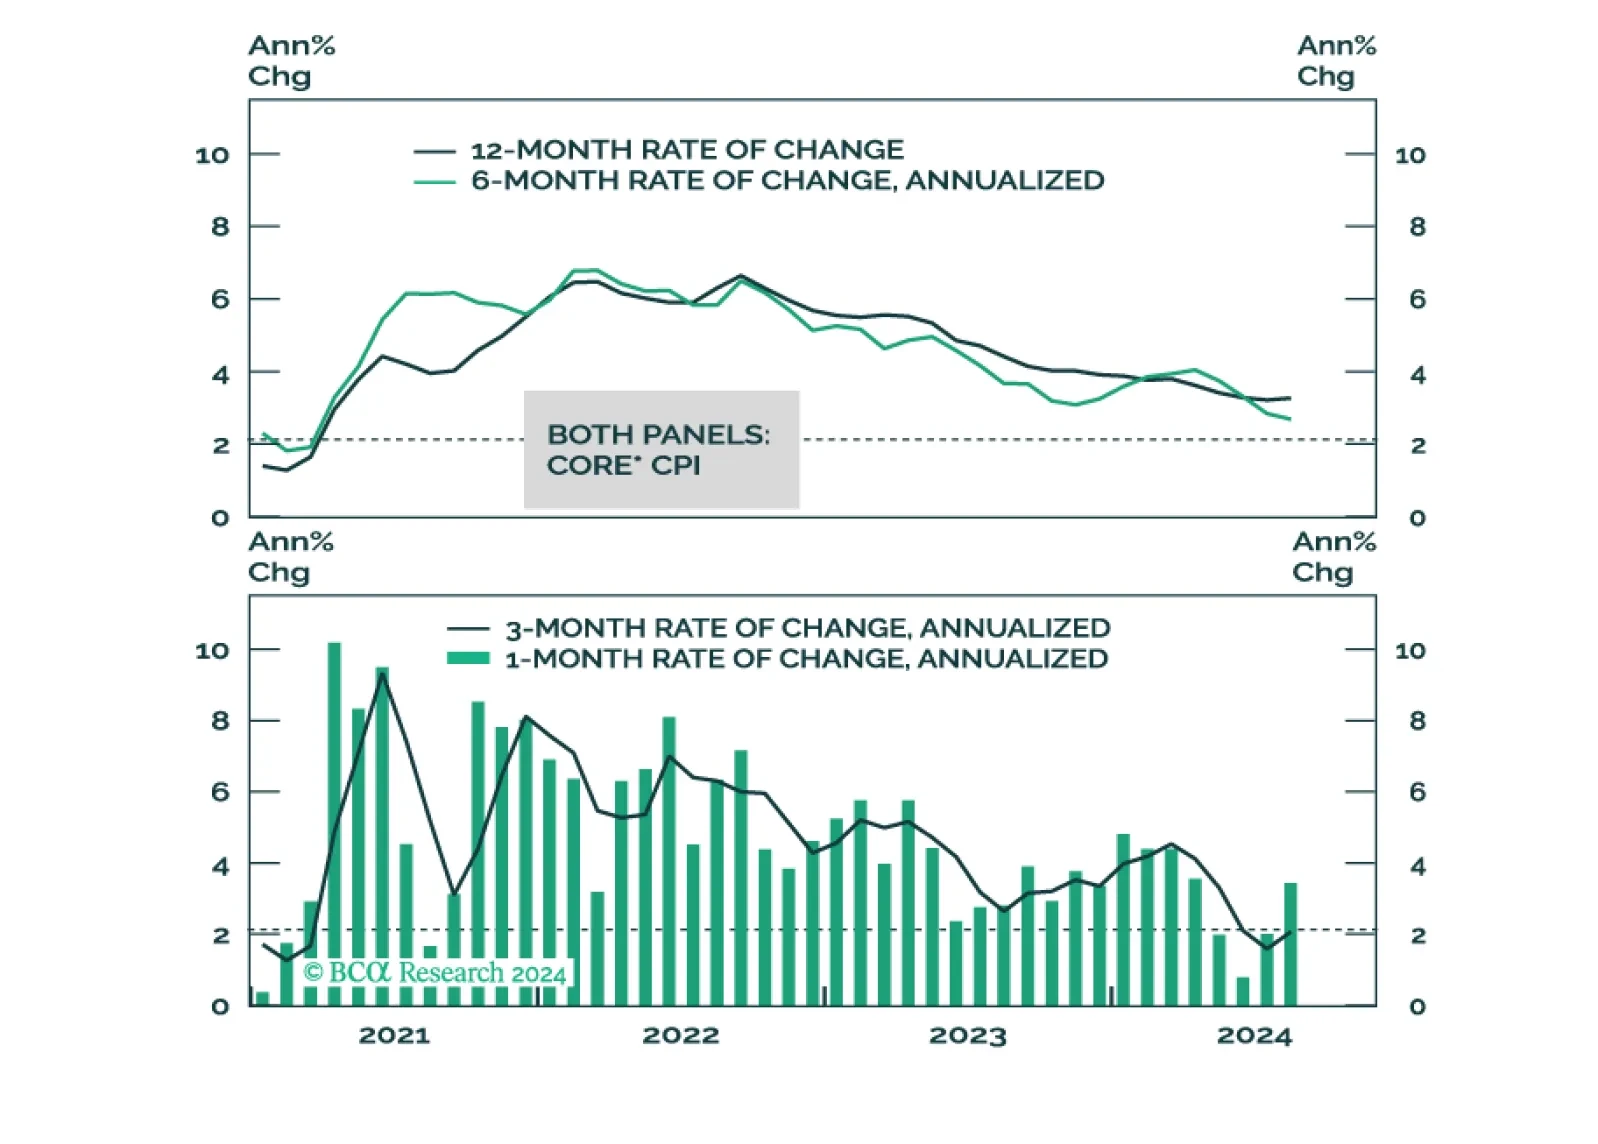
Our reaction to this morning’s CPI report and what it means for Fed policy.