Skip to main content
Explore FICC

FICC | Bonds

Actionable asset allocation recommendations for your bond portfolio, drawing on macro analysis of interest rates and global debt market dynamics. Typically published weekly.
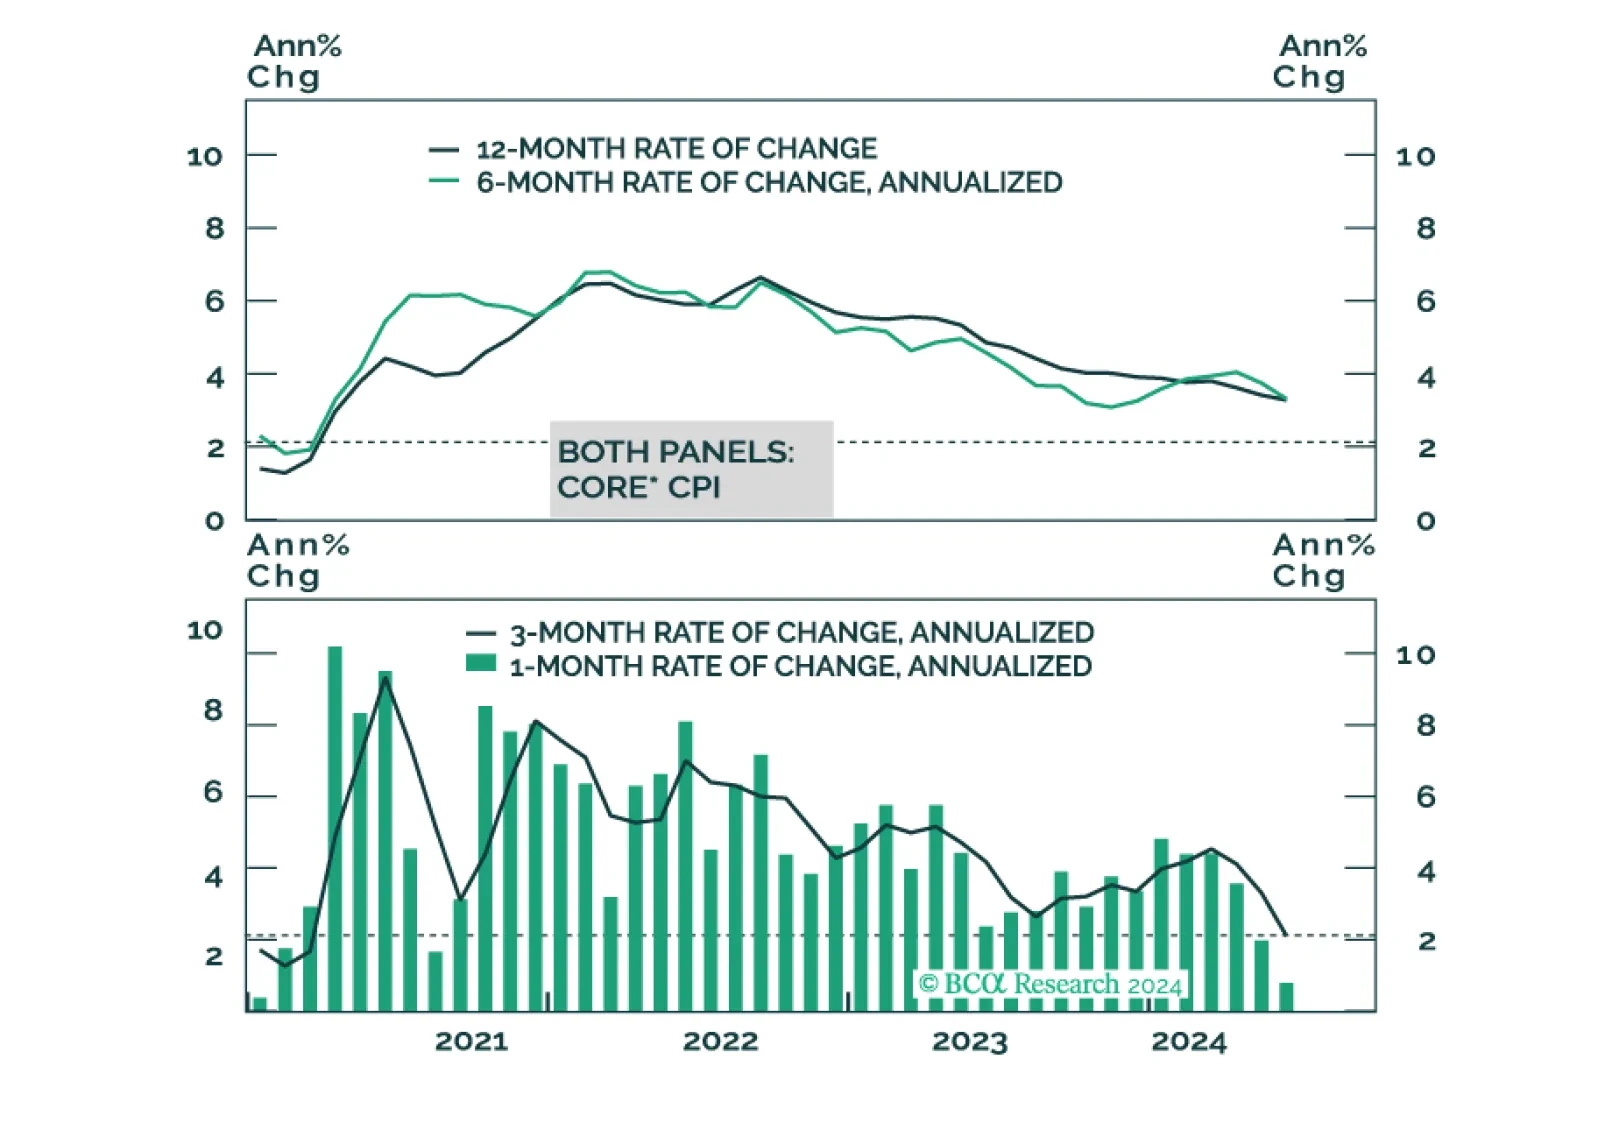
In light of last week’s employment report and this morning’s CPI, it’s time for the Federal Reserve to cut rates.
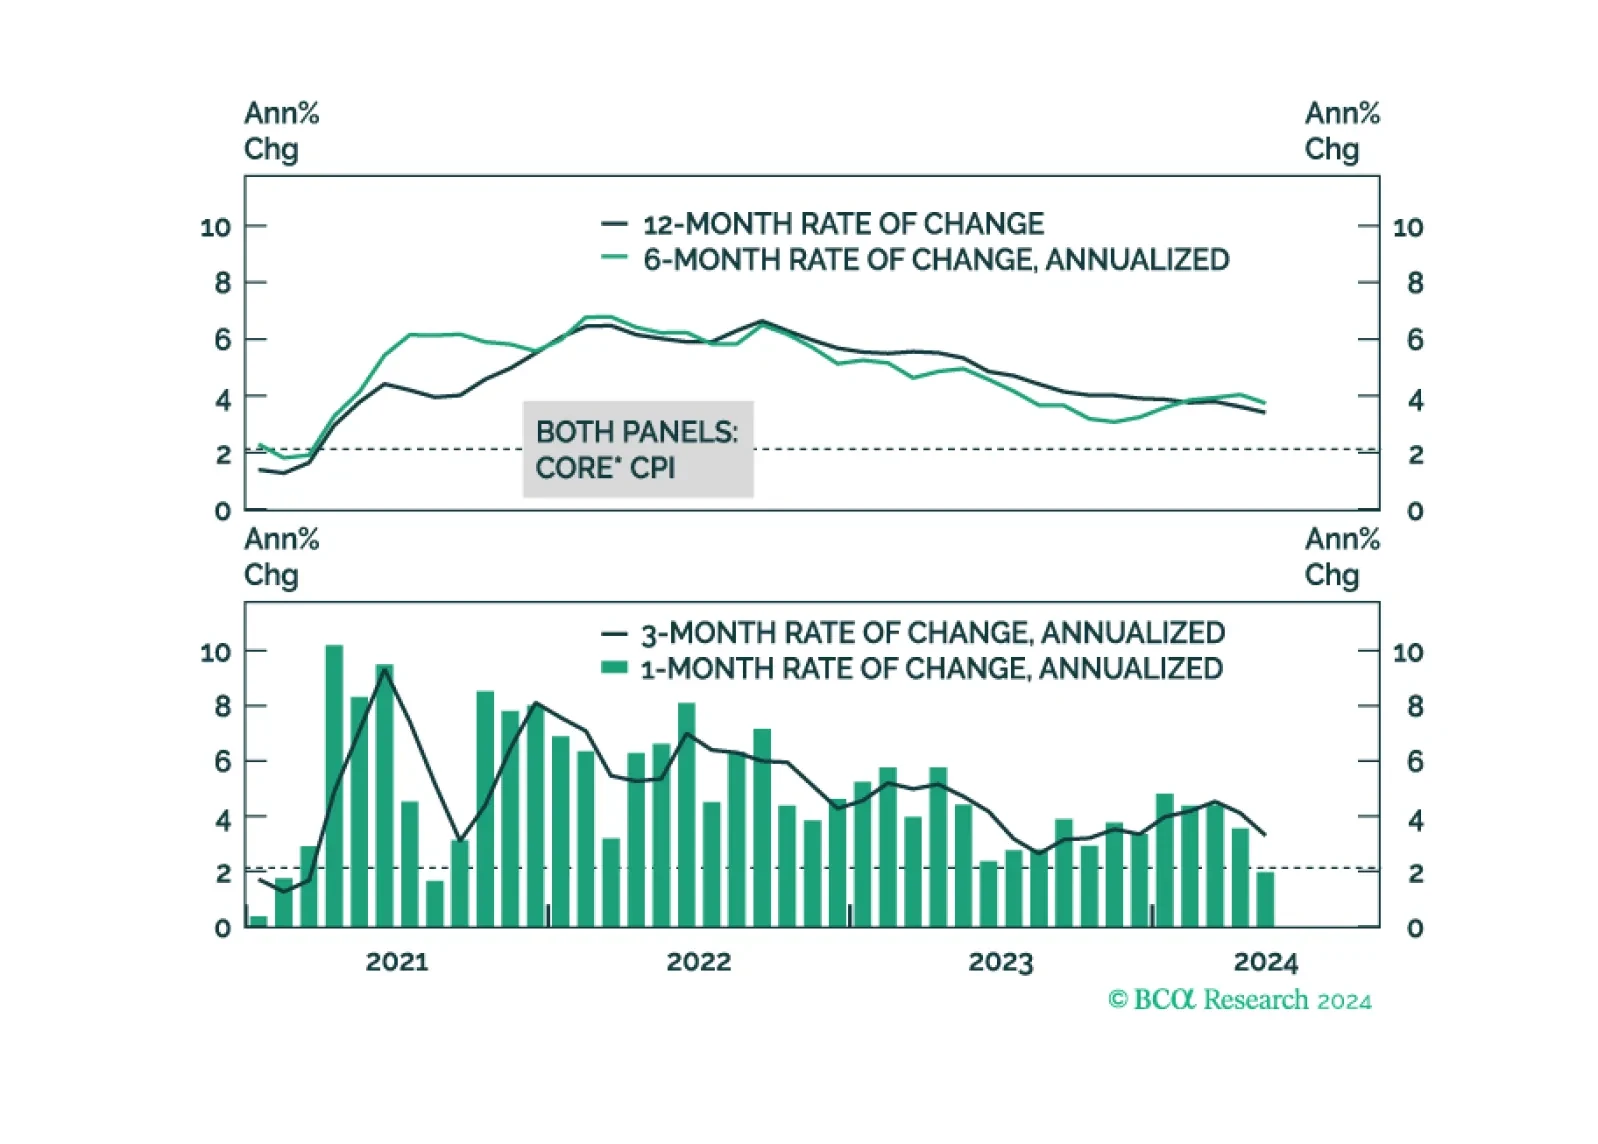
Special Report We consider the outlook for CPI inflation over the next 12 months. Our baseline forecast calls for core CPI to hit 2.40% during this timeframe and for headline CPI to fall between 1.74% and 2.49%.
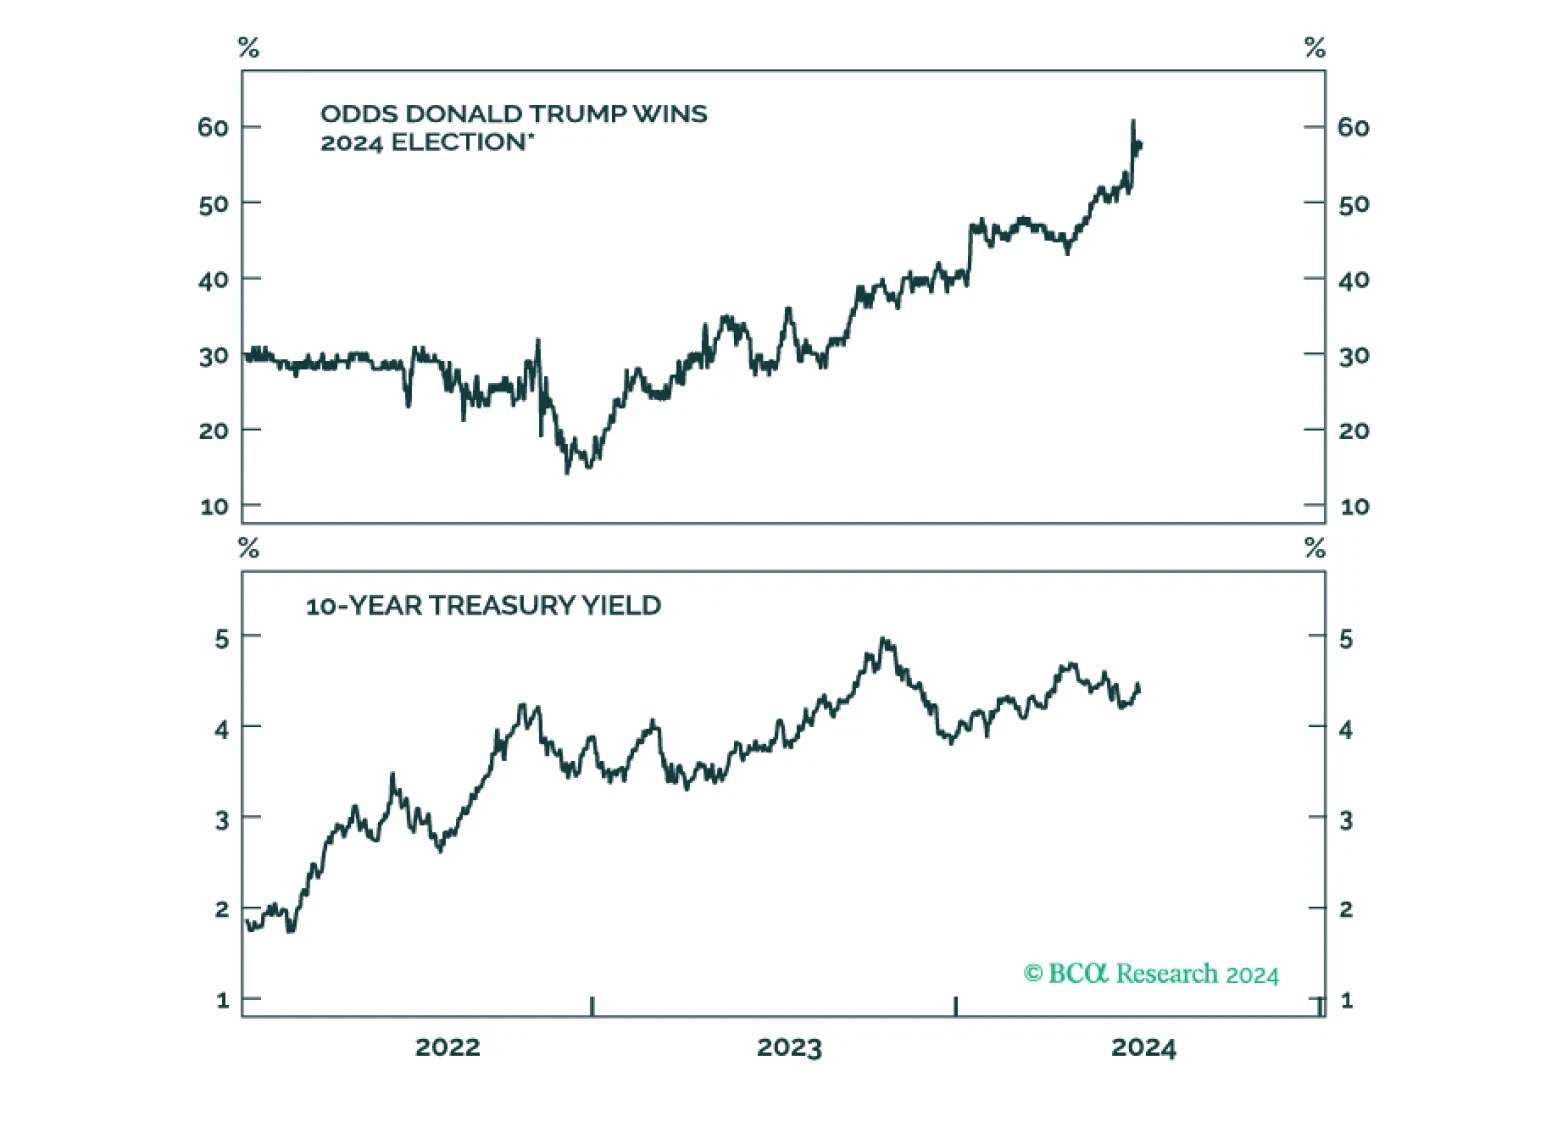
In this week's report, we review the impact of political developments, as well as incoming fundamental data, on our positioning.
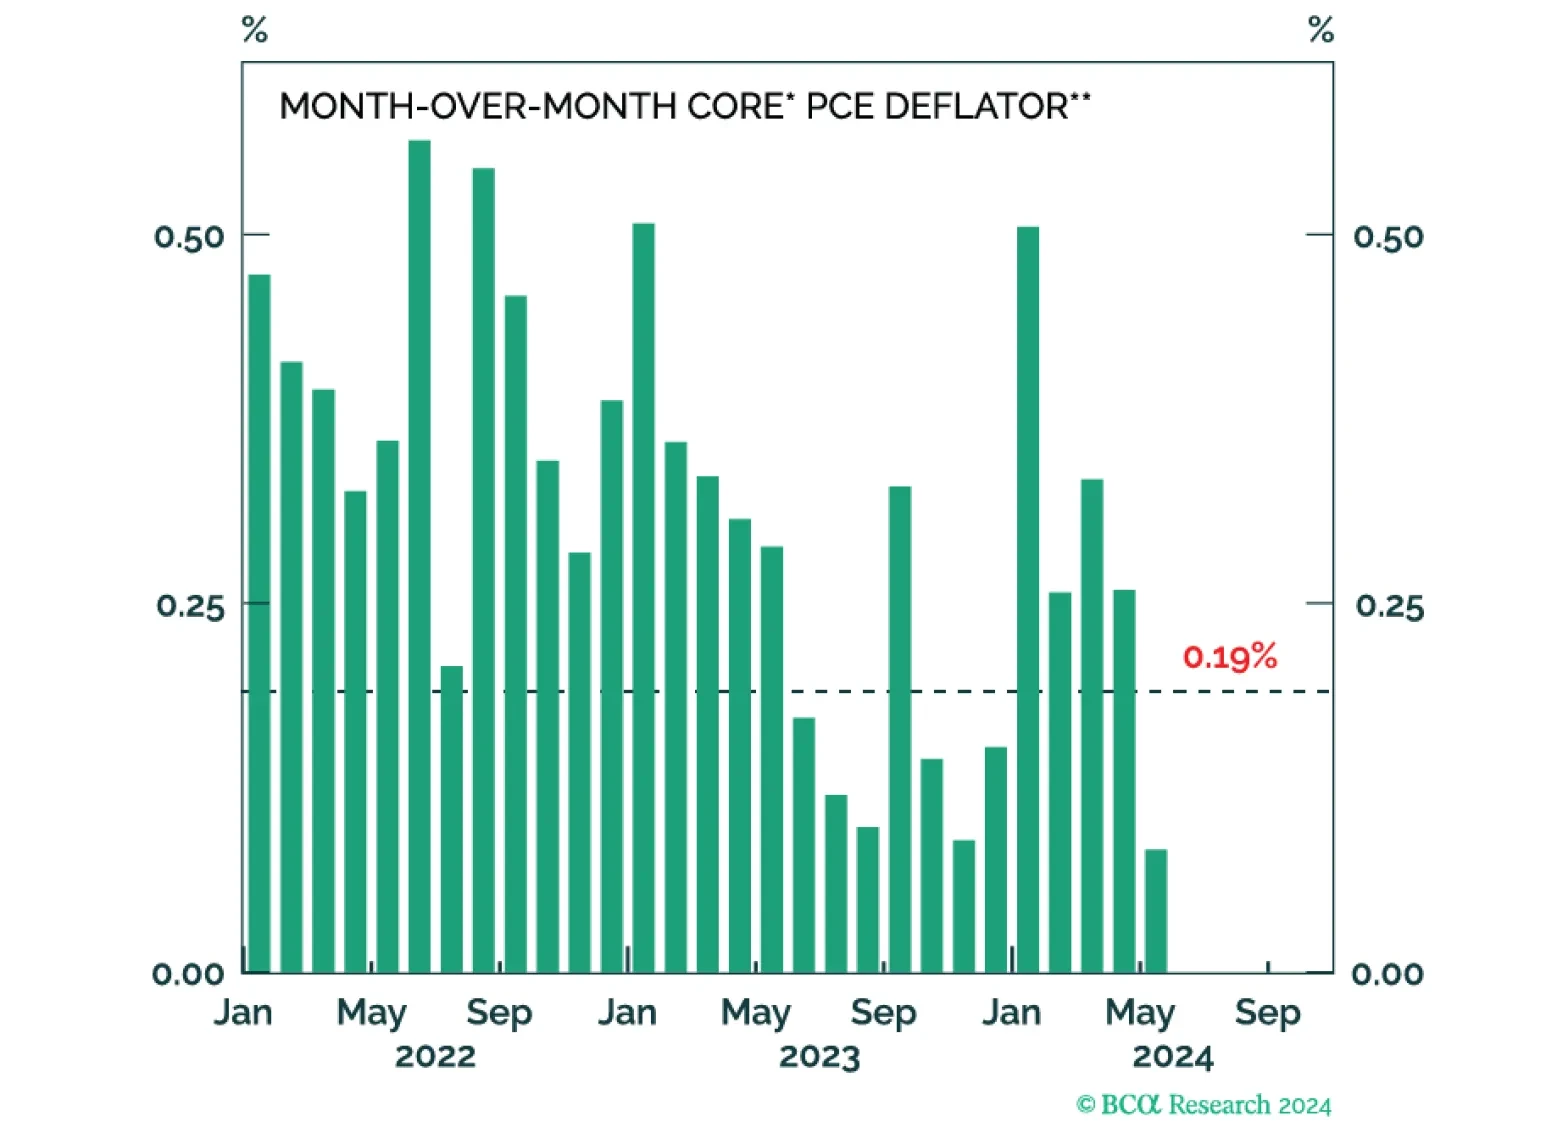
Our labor market indicators have softened meaningfully during the past month but aren’t yet signaling an imminent recession. That said, the Fed can no longer ignore the labor market with the unemployment rate above 4% and rising.
Our Portfolio Allocation Summary for July 2024.
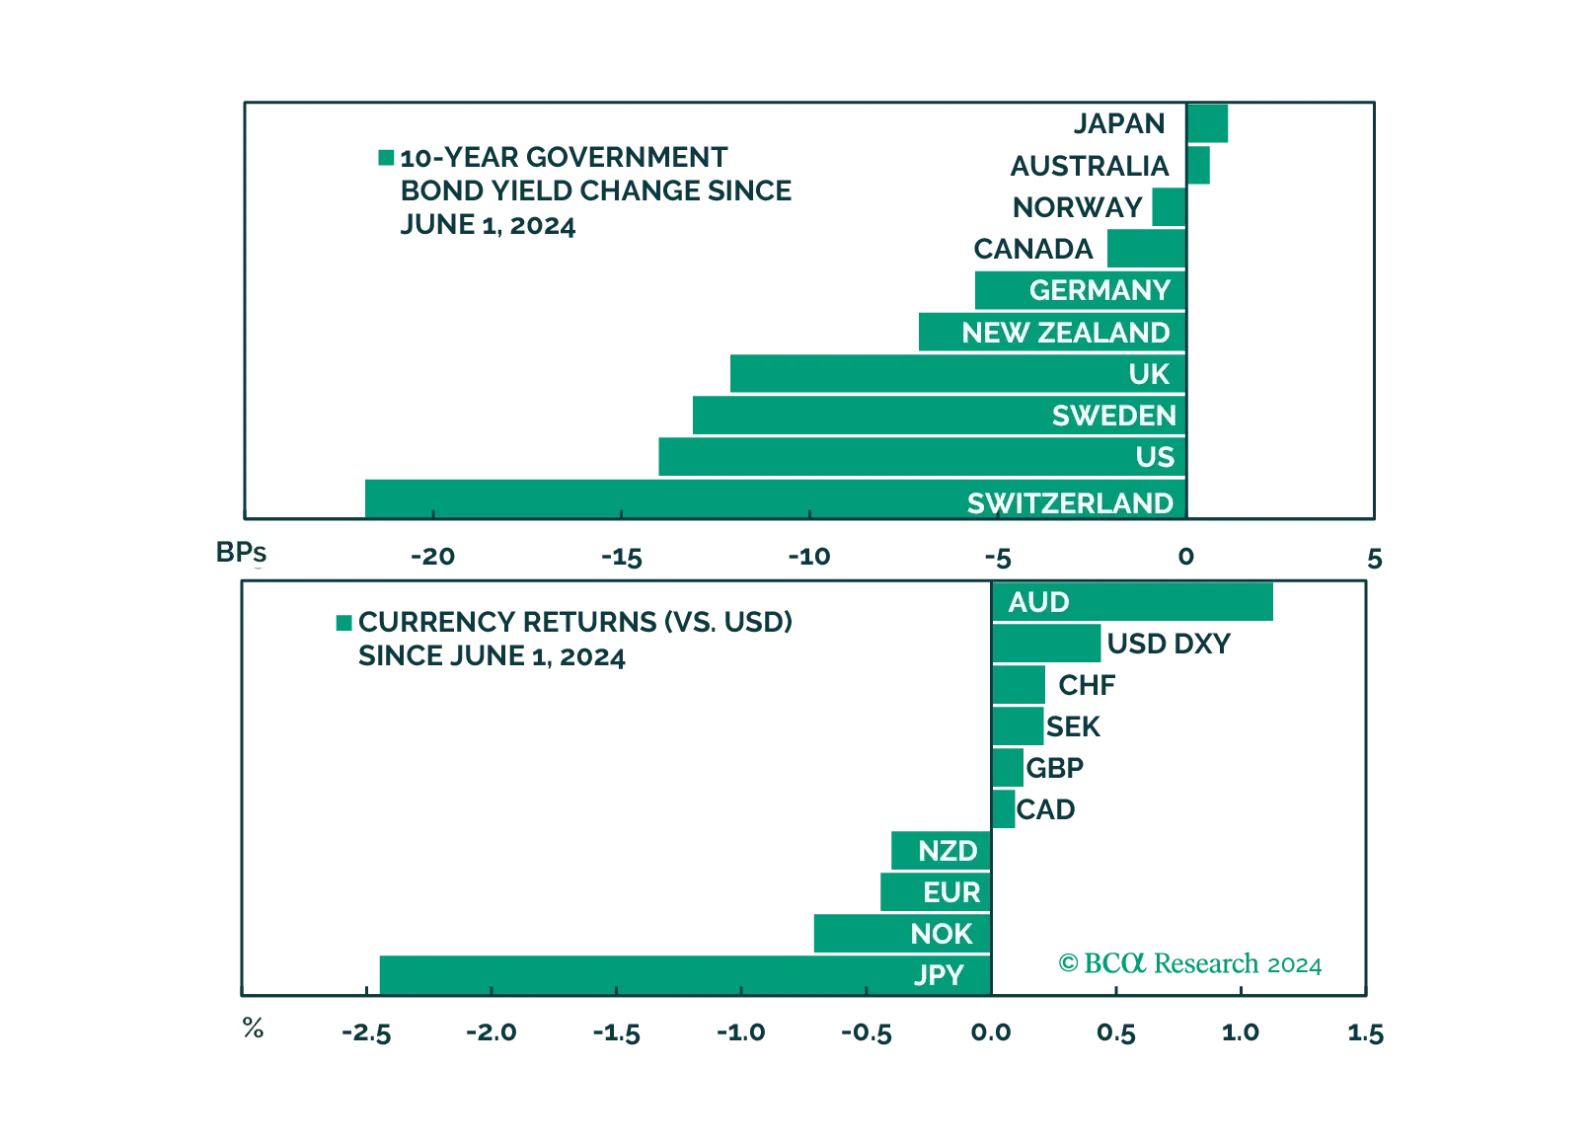
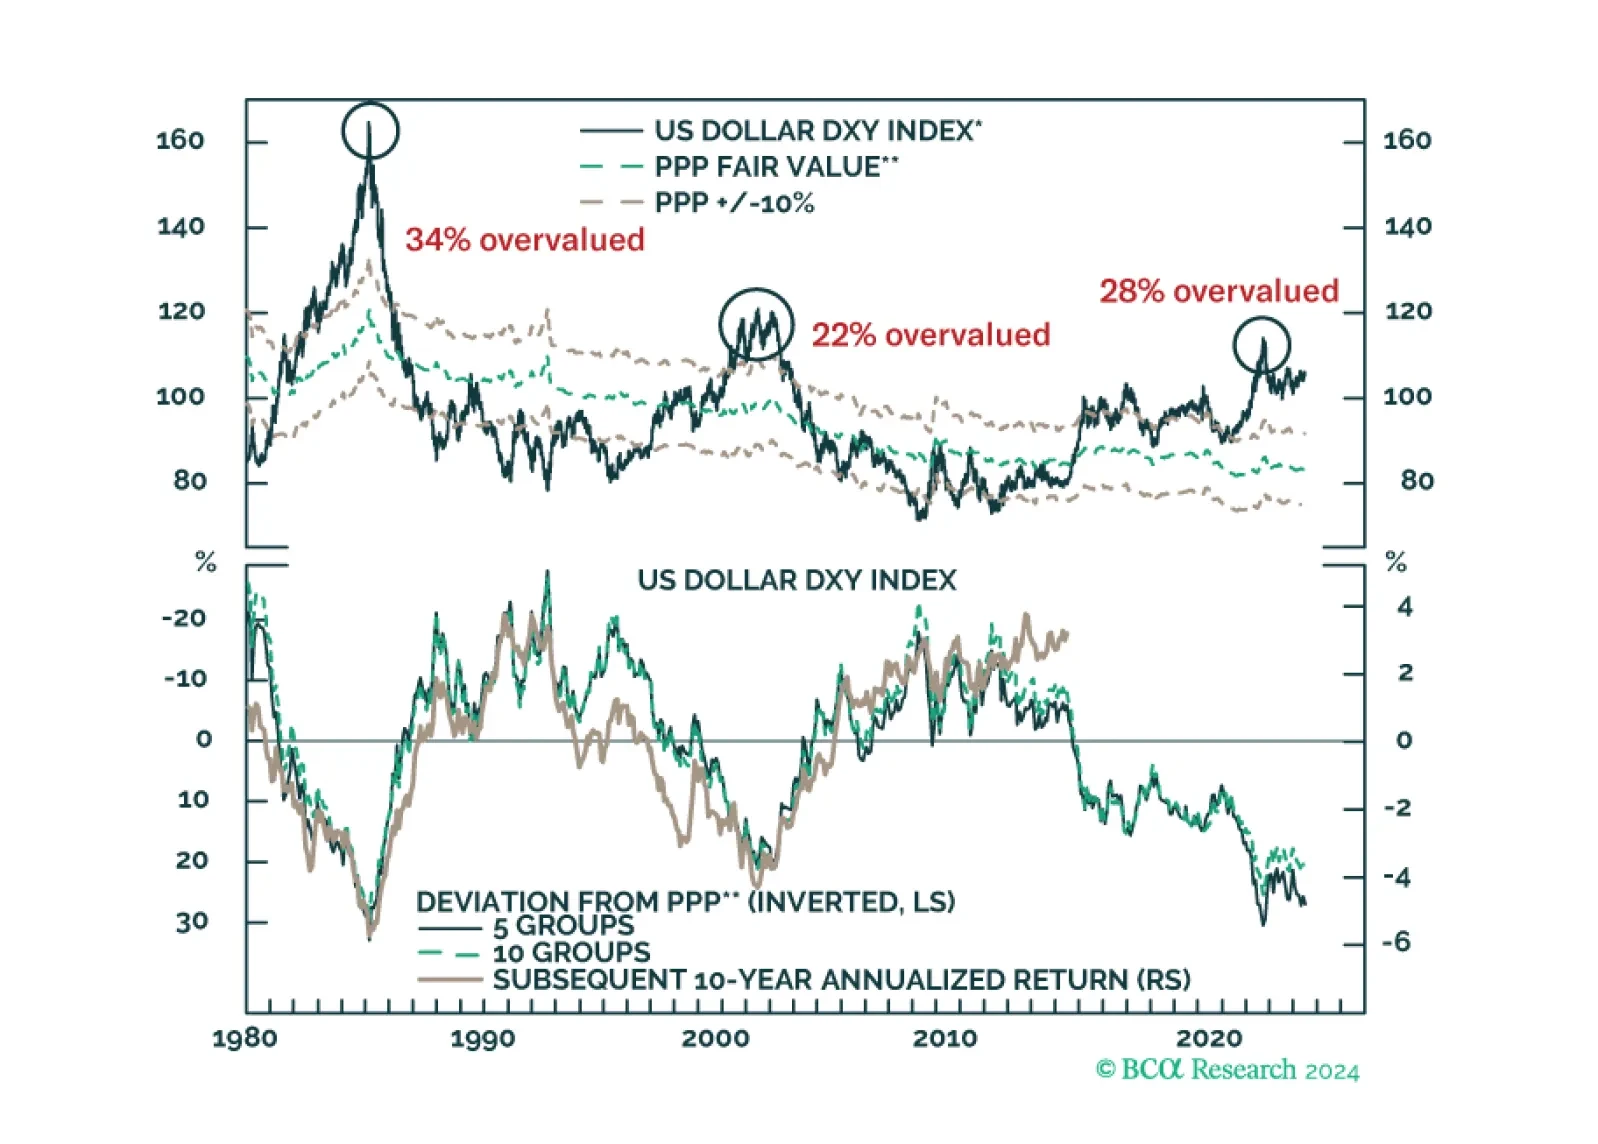
Special Report In this report, we try to gauge how long the exceptional performance of the US can last, but from a more nuanced angle – inflows into US assets and the impact on the dollar and bond yields. Our work suggests that investors should not make any huge bets on the dollar today, but should be short over the longer term (3-5 years). Empirical evidence also suggests you want to be long US bonds into any downturn, relative to global-ex-US duration-matched government securities, but that view becomes less certain if the global economy avoids a downturn in the next few months. What is interesting in this report are high some conviction views across currencies, bonds and precious metals.
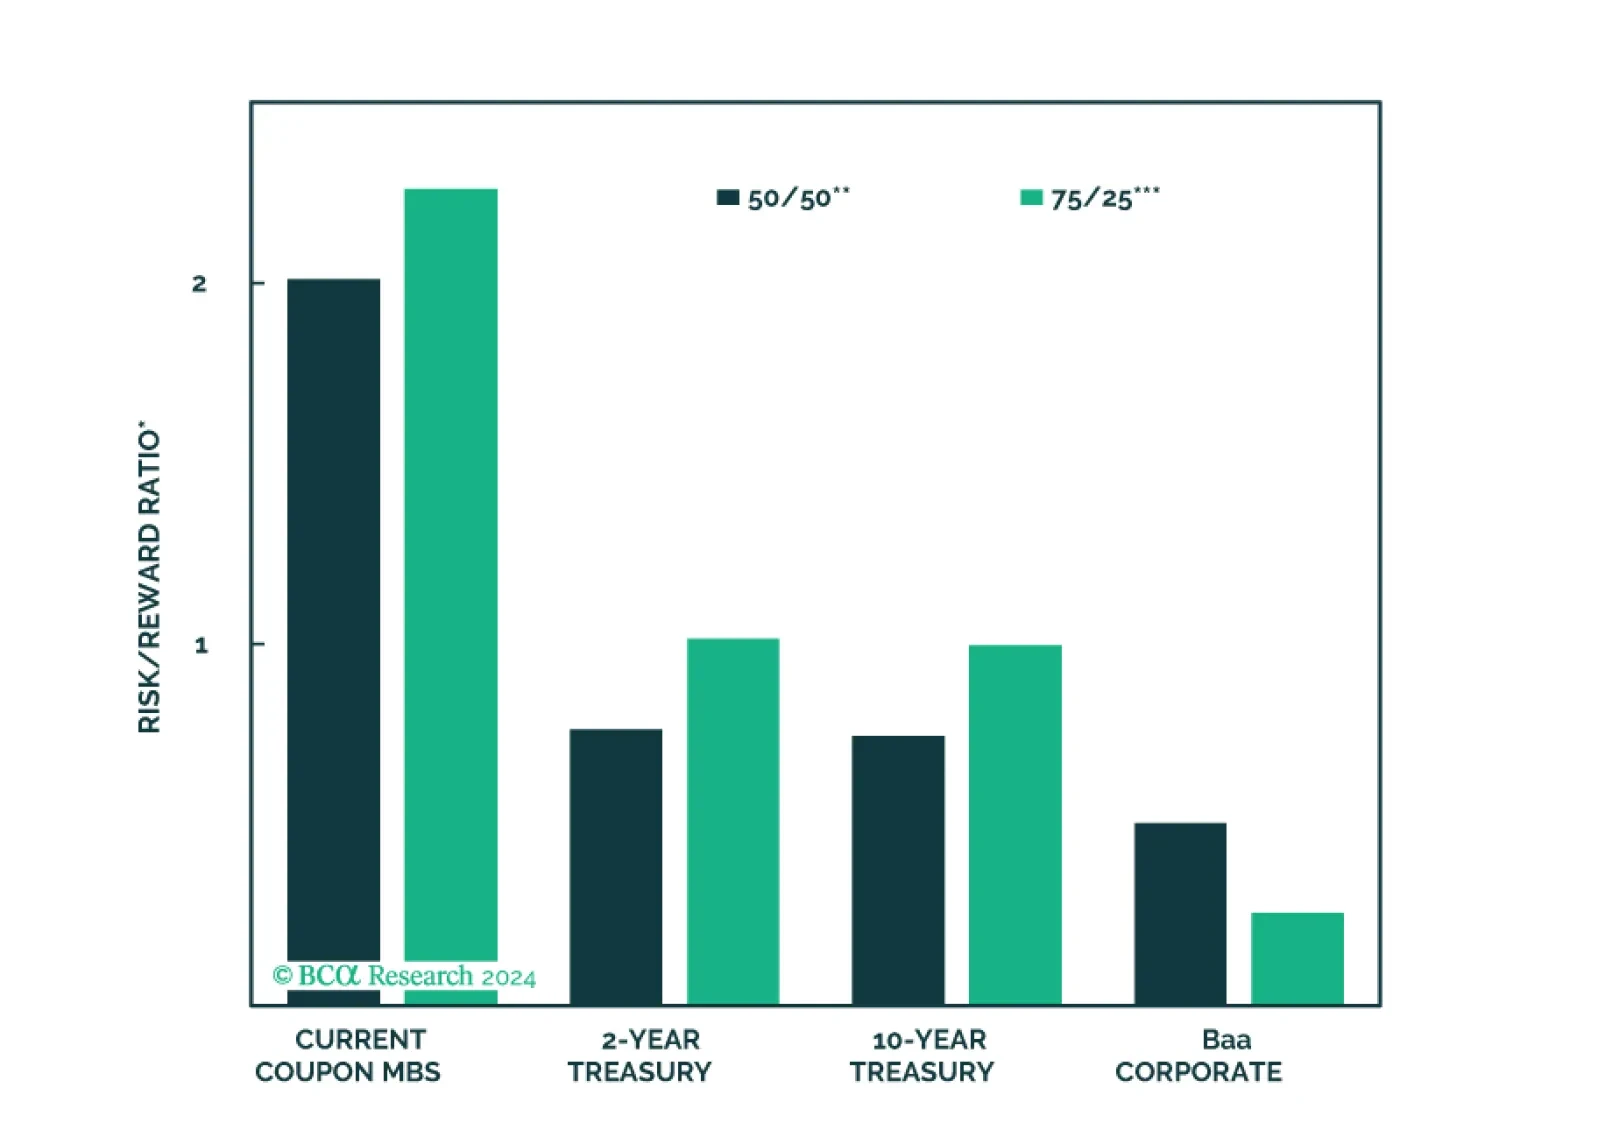
Special Report We consider the relative merits of four different fixed income investments in the current economic environment: 2-year Treasuries, 10-year Treasuries, Baa-rated corporate bonds and current coupon Agency MBS.
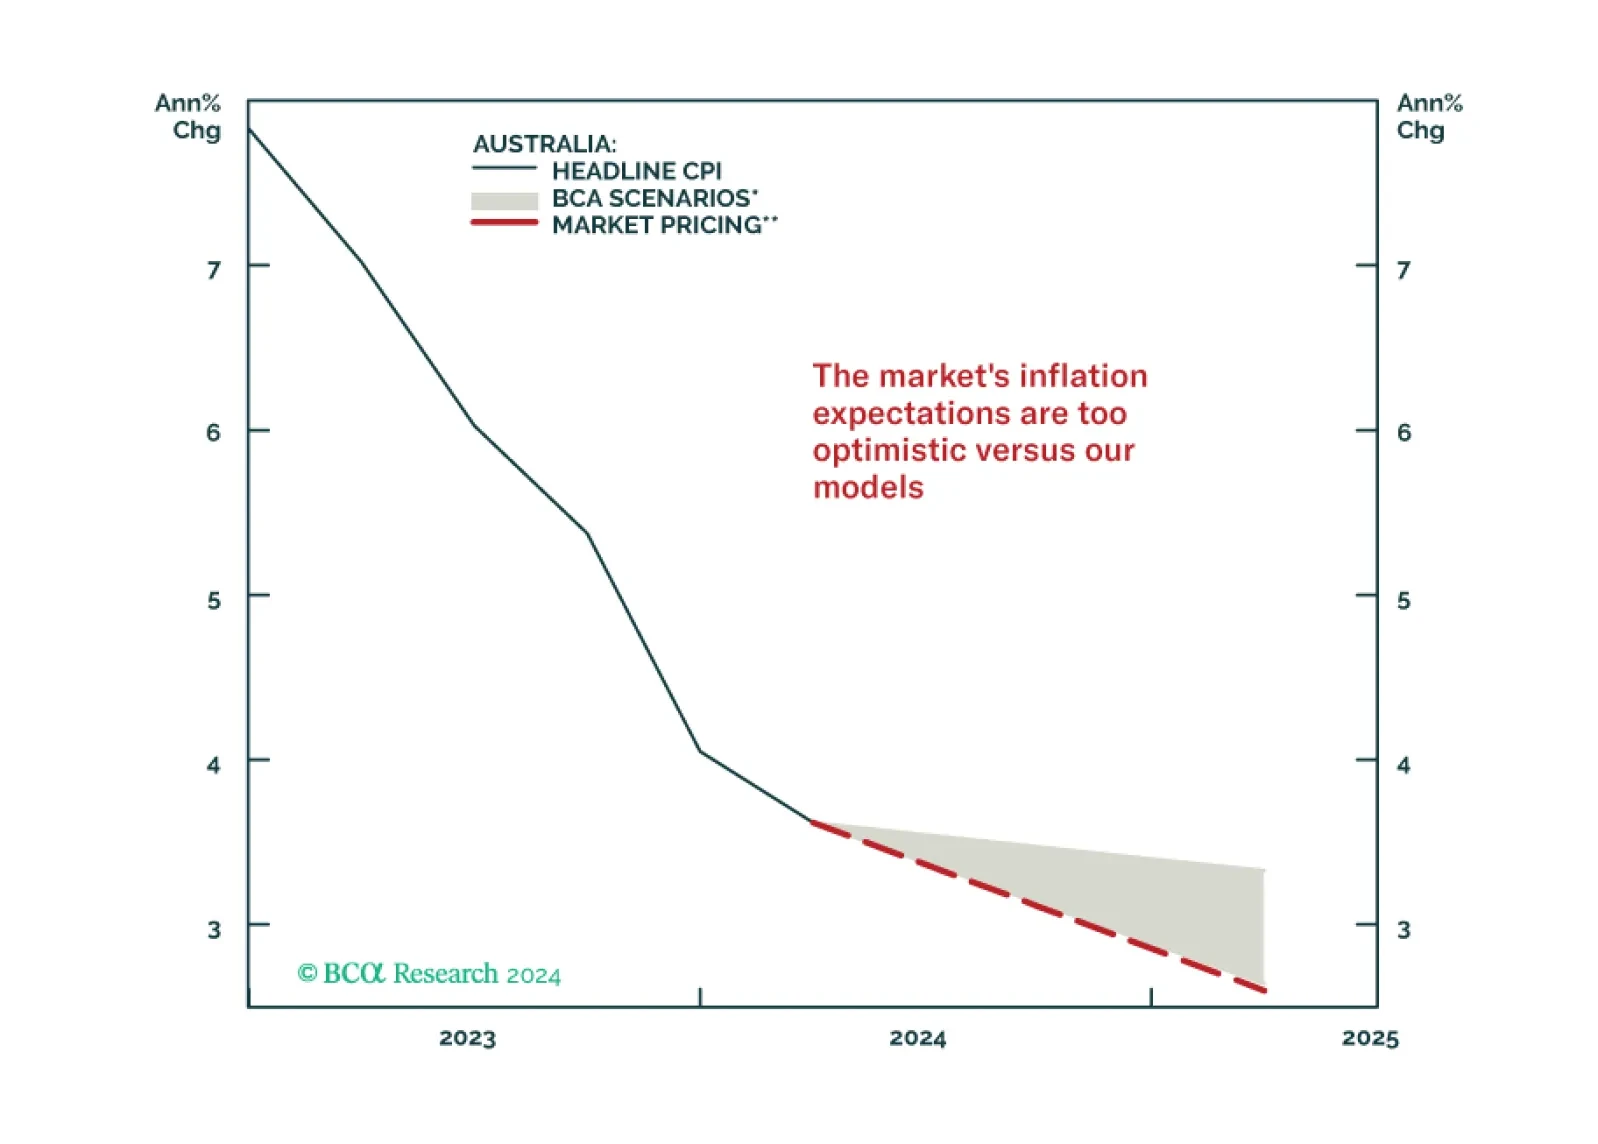
In light of this week’s RBA decision to keep policy on hold, we look at the best possible trades in fixed income markets. In our view, inflation-linked bonds, relative to nominals remain a good bet.
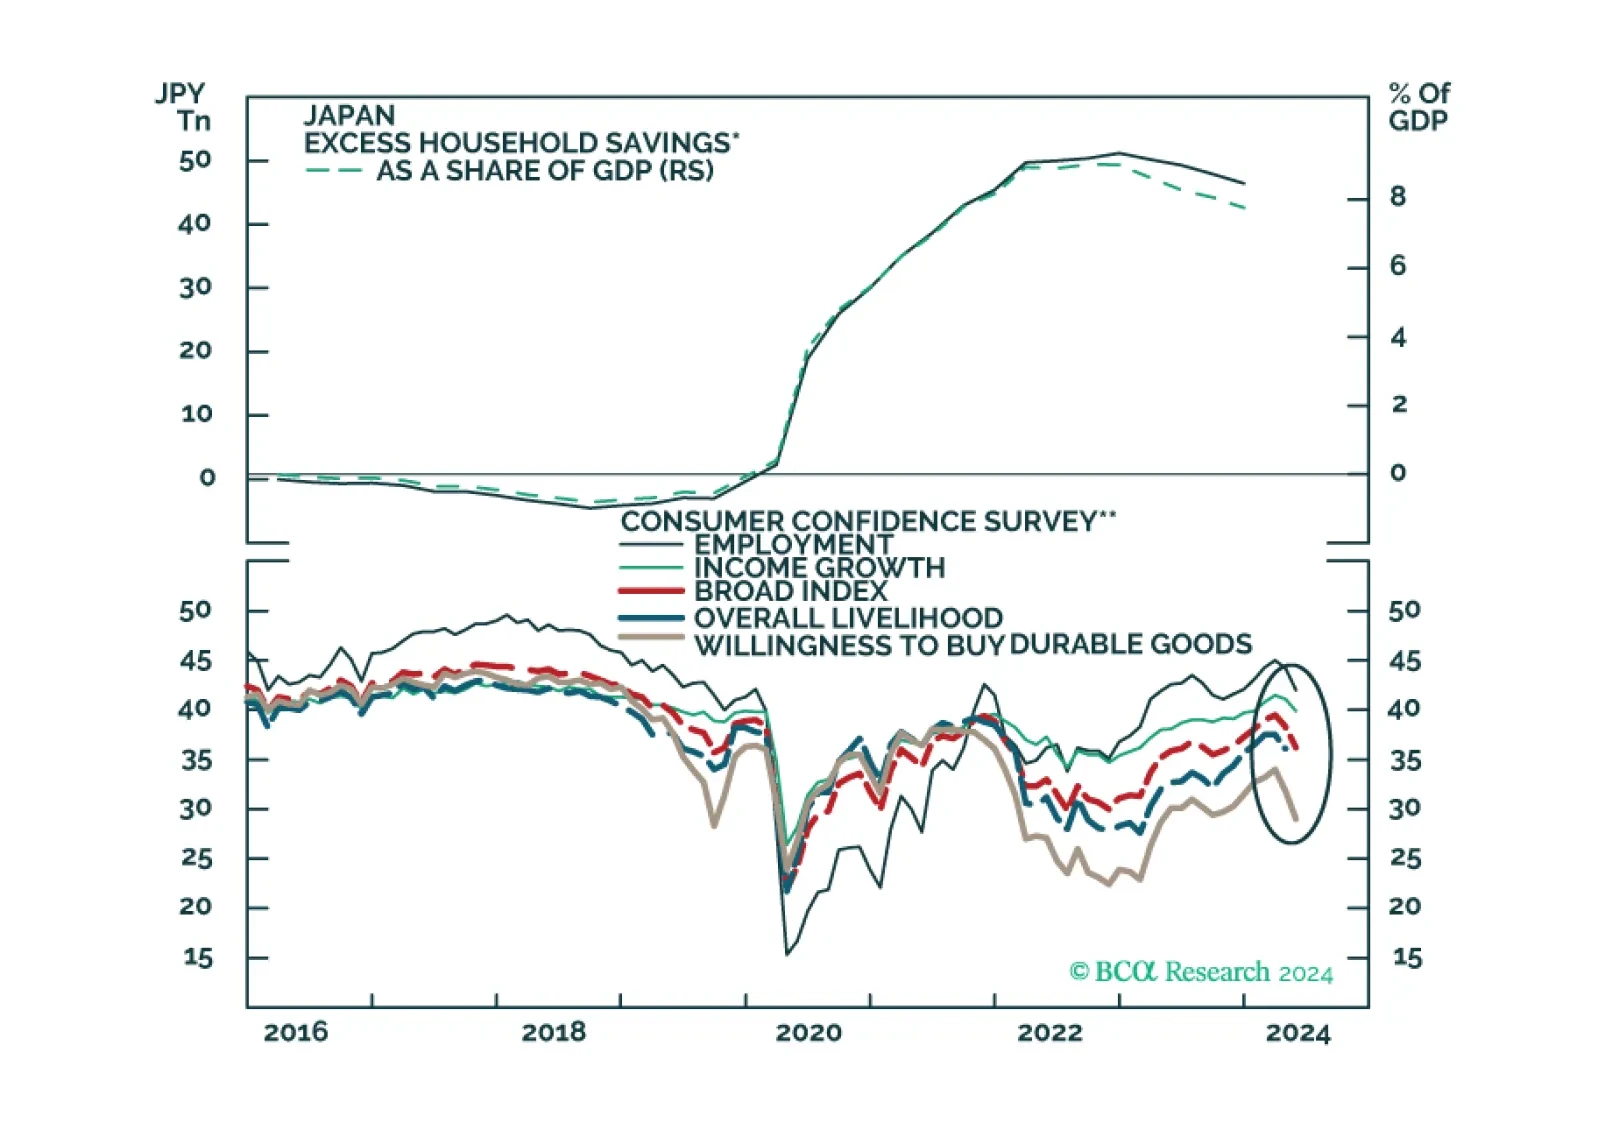
In this insight, we update our thinking on the recent BoJ move in terms of positioning for the yen and JGB yields.
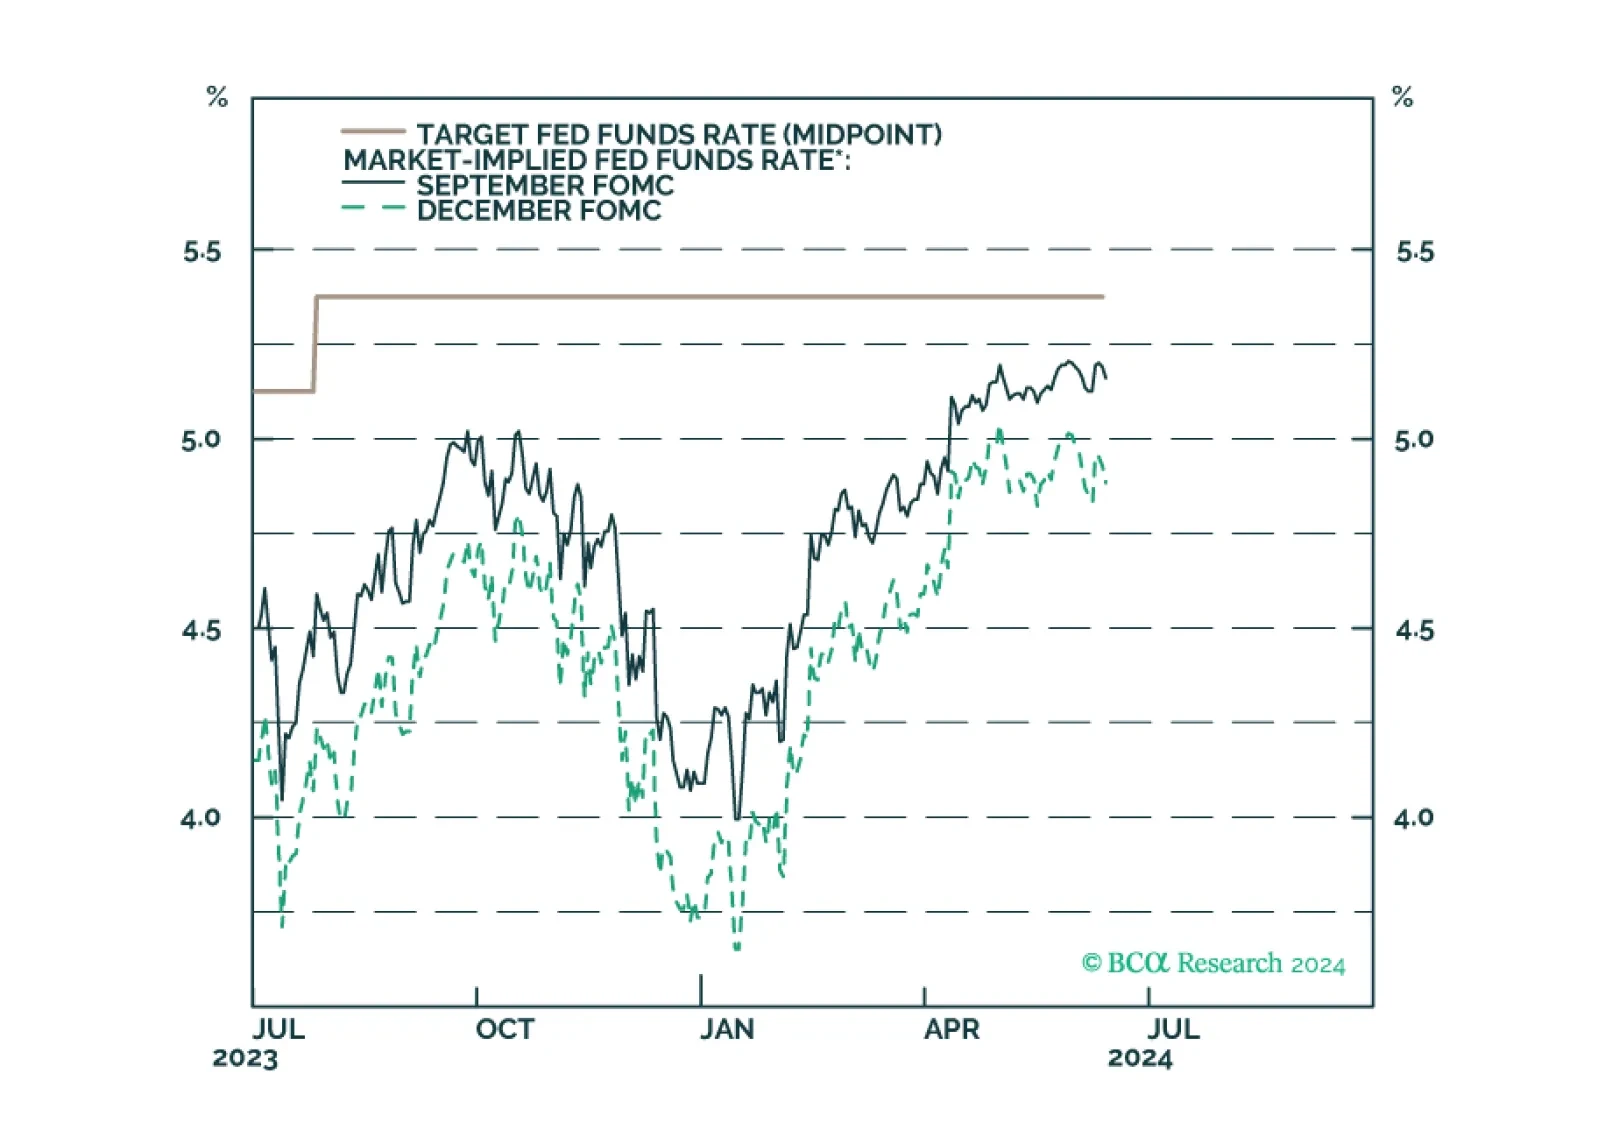
Our reaction to this morning’s CPI report and this afternoon’s FOMC meeting.