 Explore FICC
FICC | Bonds
Actionable asset allocation recommendations for your bond portfolio, drawing on macro analysis of interest rates and global debt market dynamics. Typically published weekly.

Our thoughts on the bond market’s reaction to the election and this afternoon’s FOMC meeting.
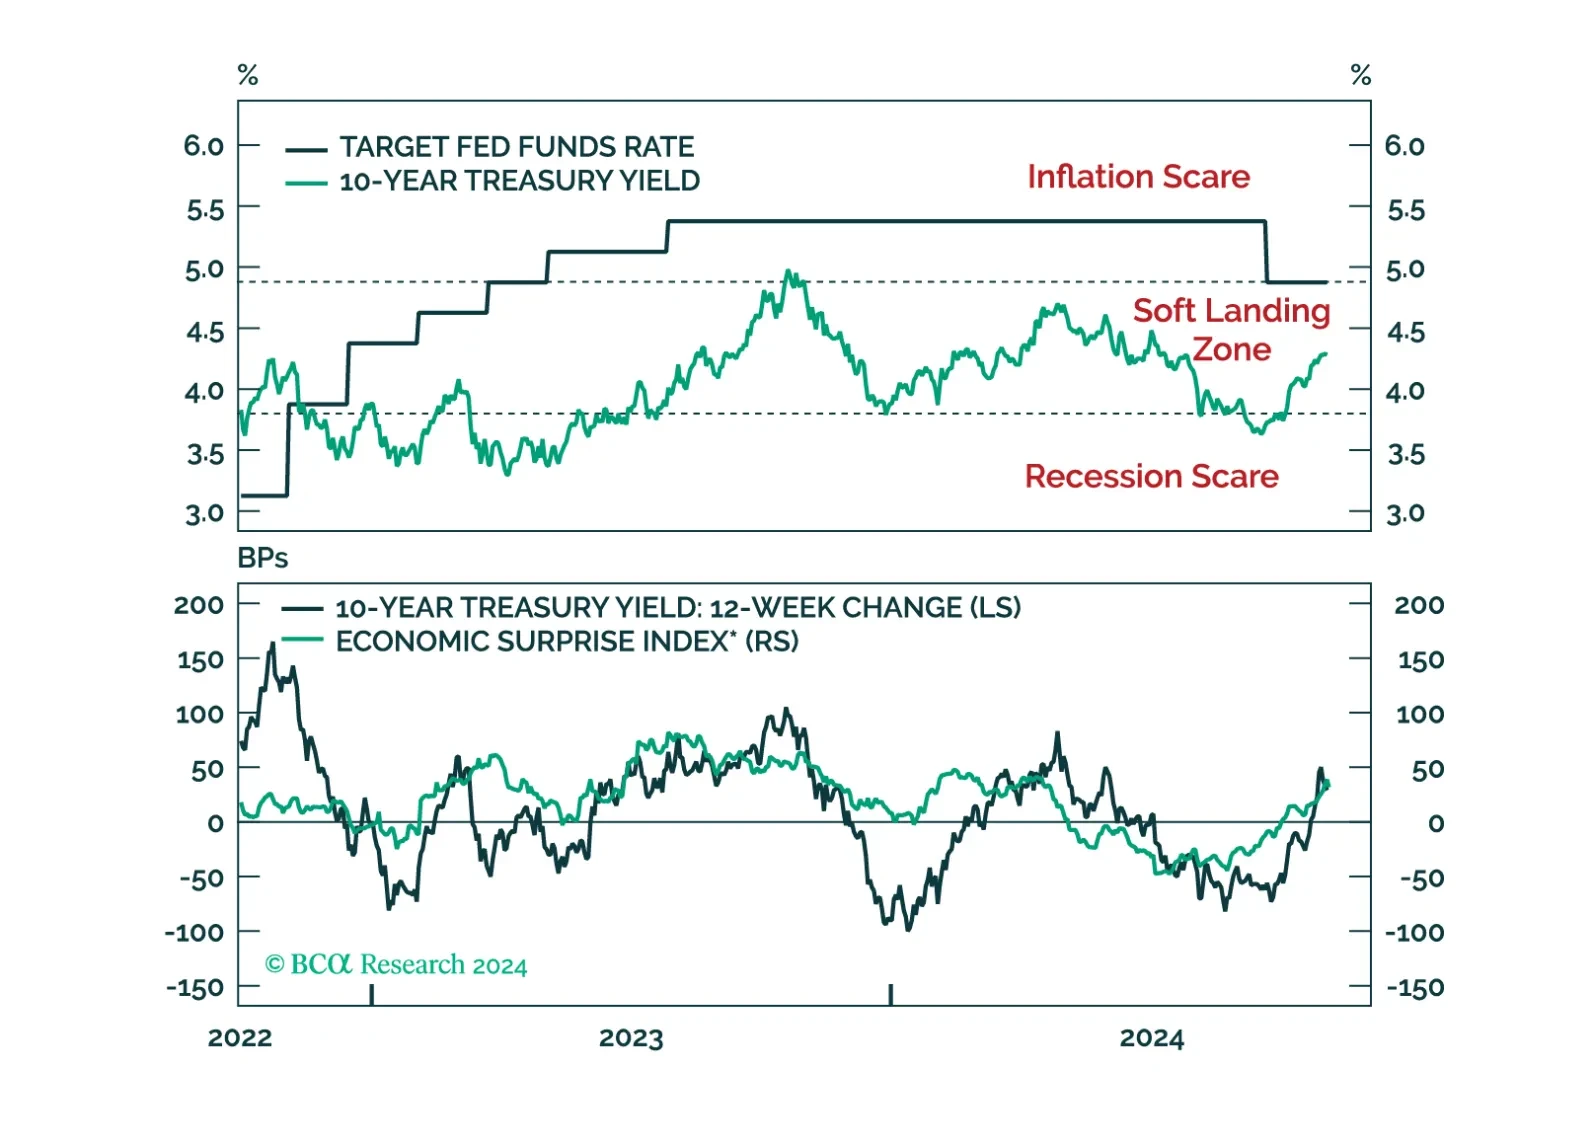
A reaction to this morning’s employment report and a preview of the potential bond market implications of next week’s US election and FOMC meeting.
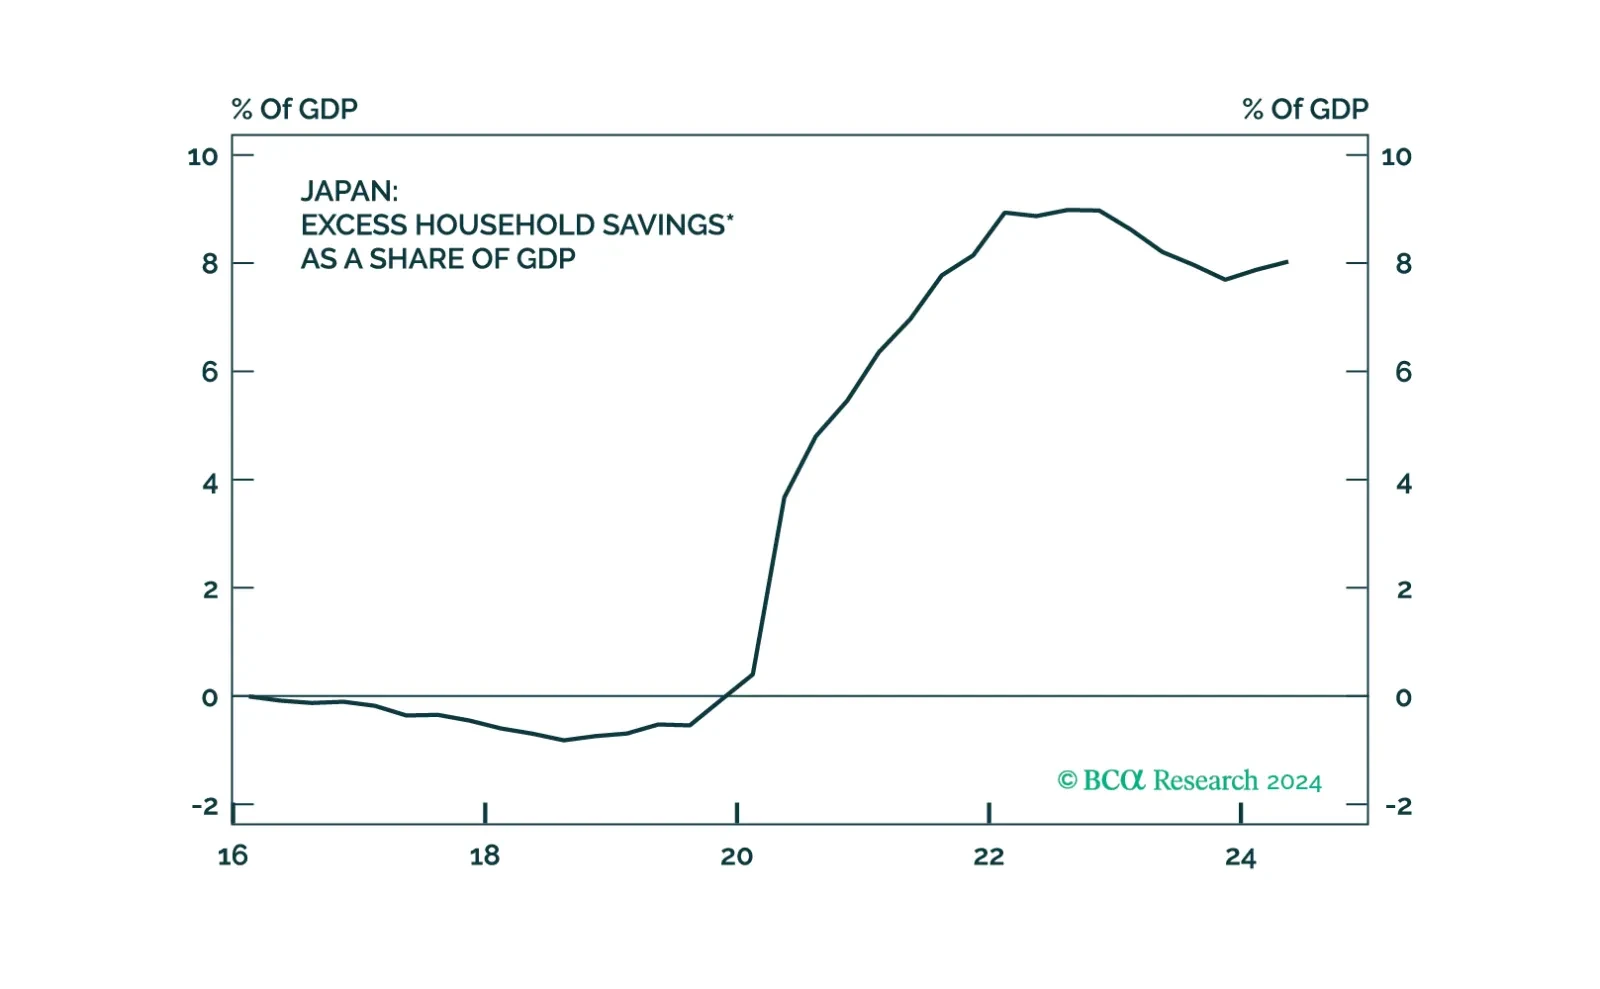
The latest Bank of Japan meeting did not alter our high-conviction views of being long the yen and underweight JGBs.

We update our 12-month return projections for different US fixed income sectors in soft-landing and recession scenarios.
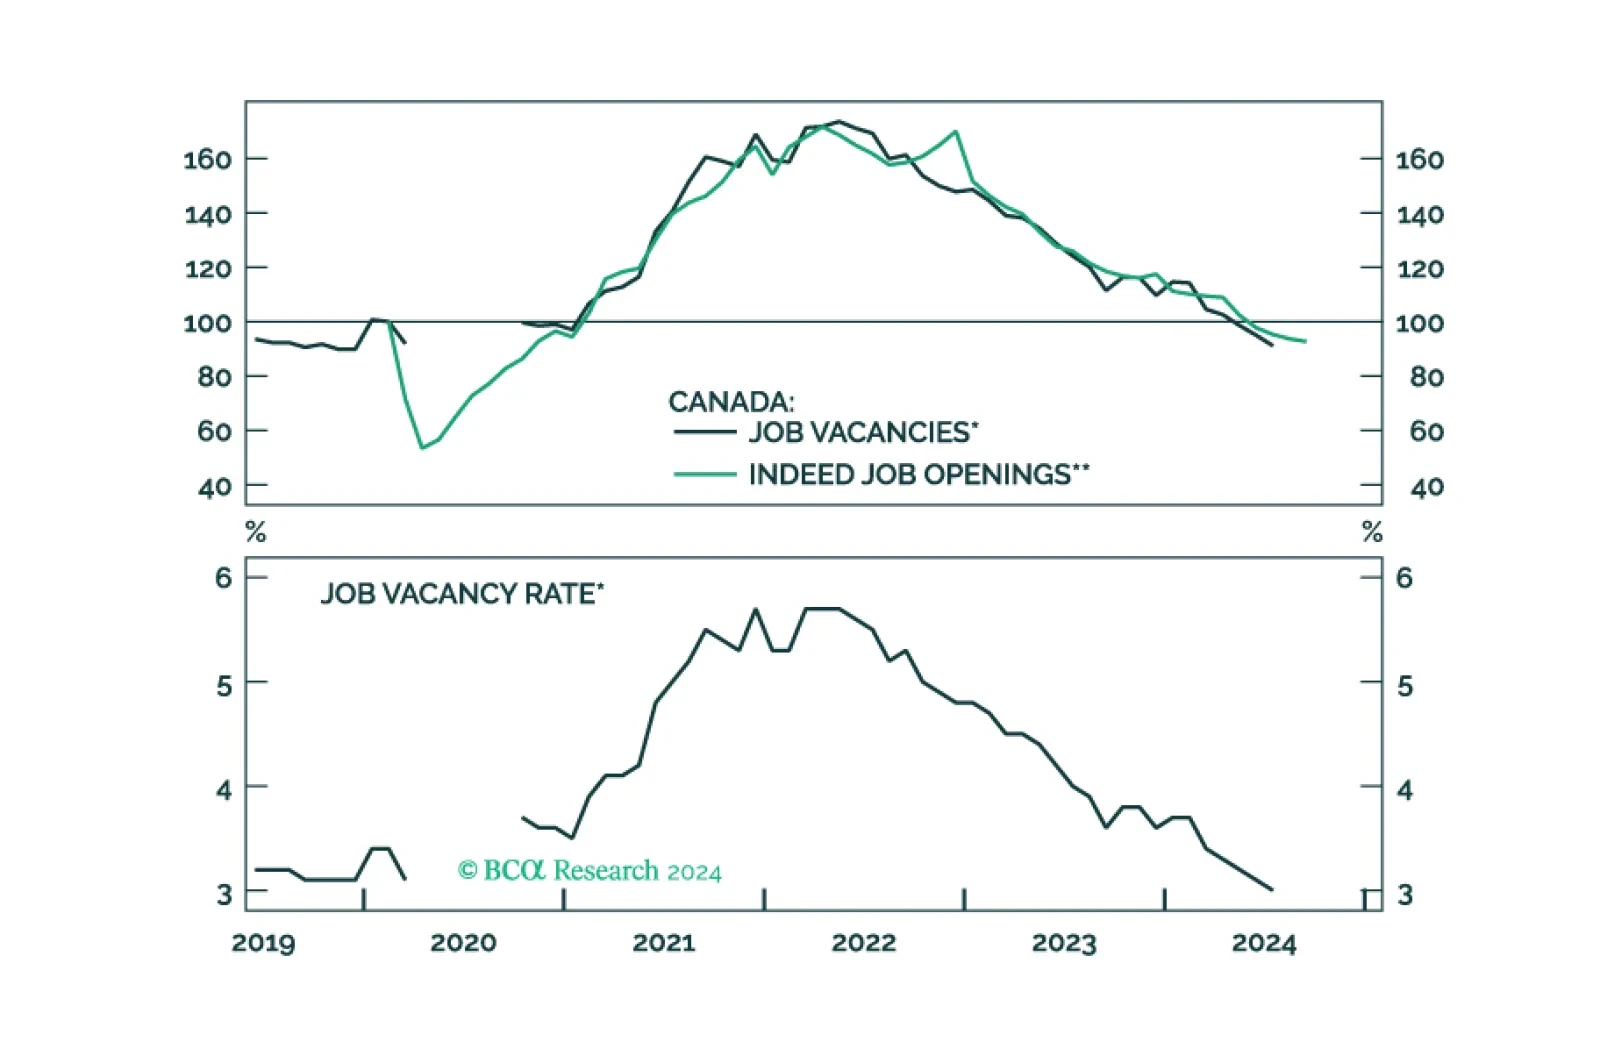
In this Insight, we evaluate if there is more juice in our macro bet of being long June 2025 CORRA versus SOFR futures, and correspondingly, being short the CAD, for investors with a 1-3 month horizon.
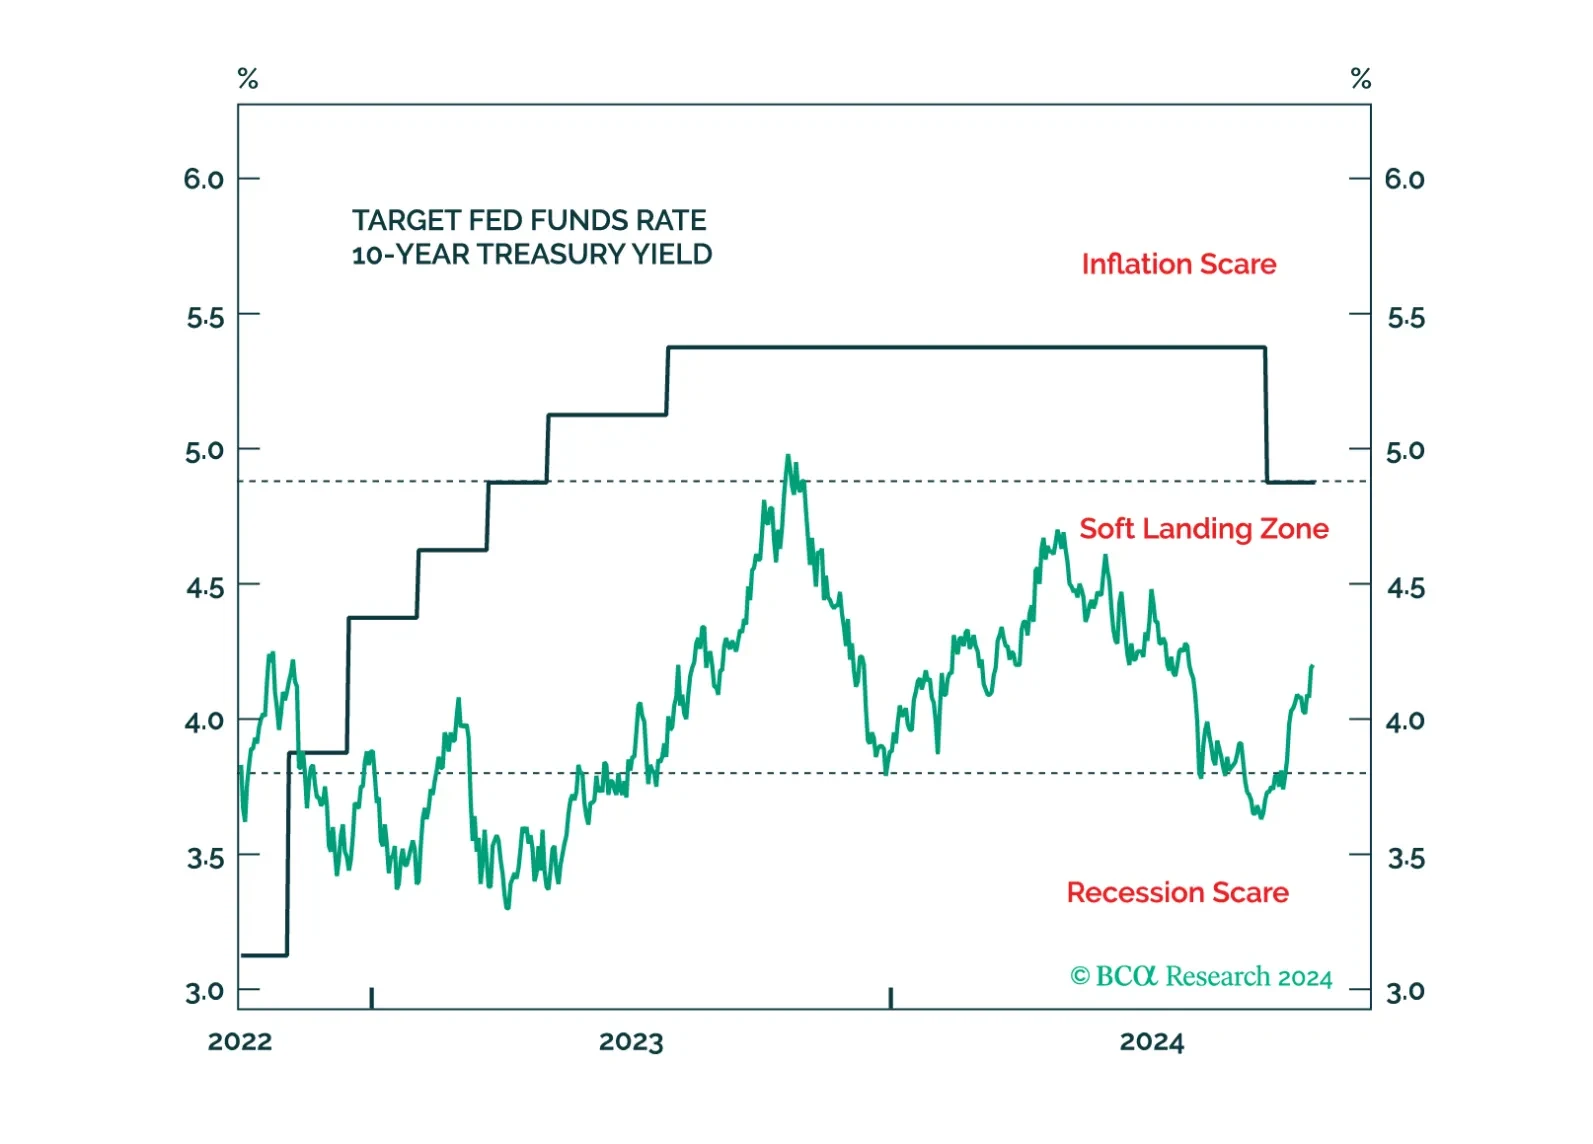
A Donald Trump victory would send bond yields higher during the next few weeks, but yields will fall in 2025 no matter the election outcome.
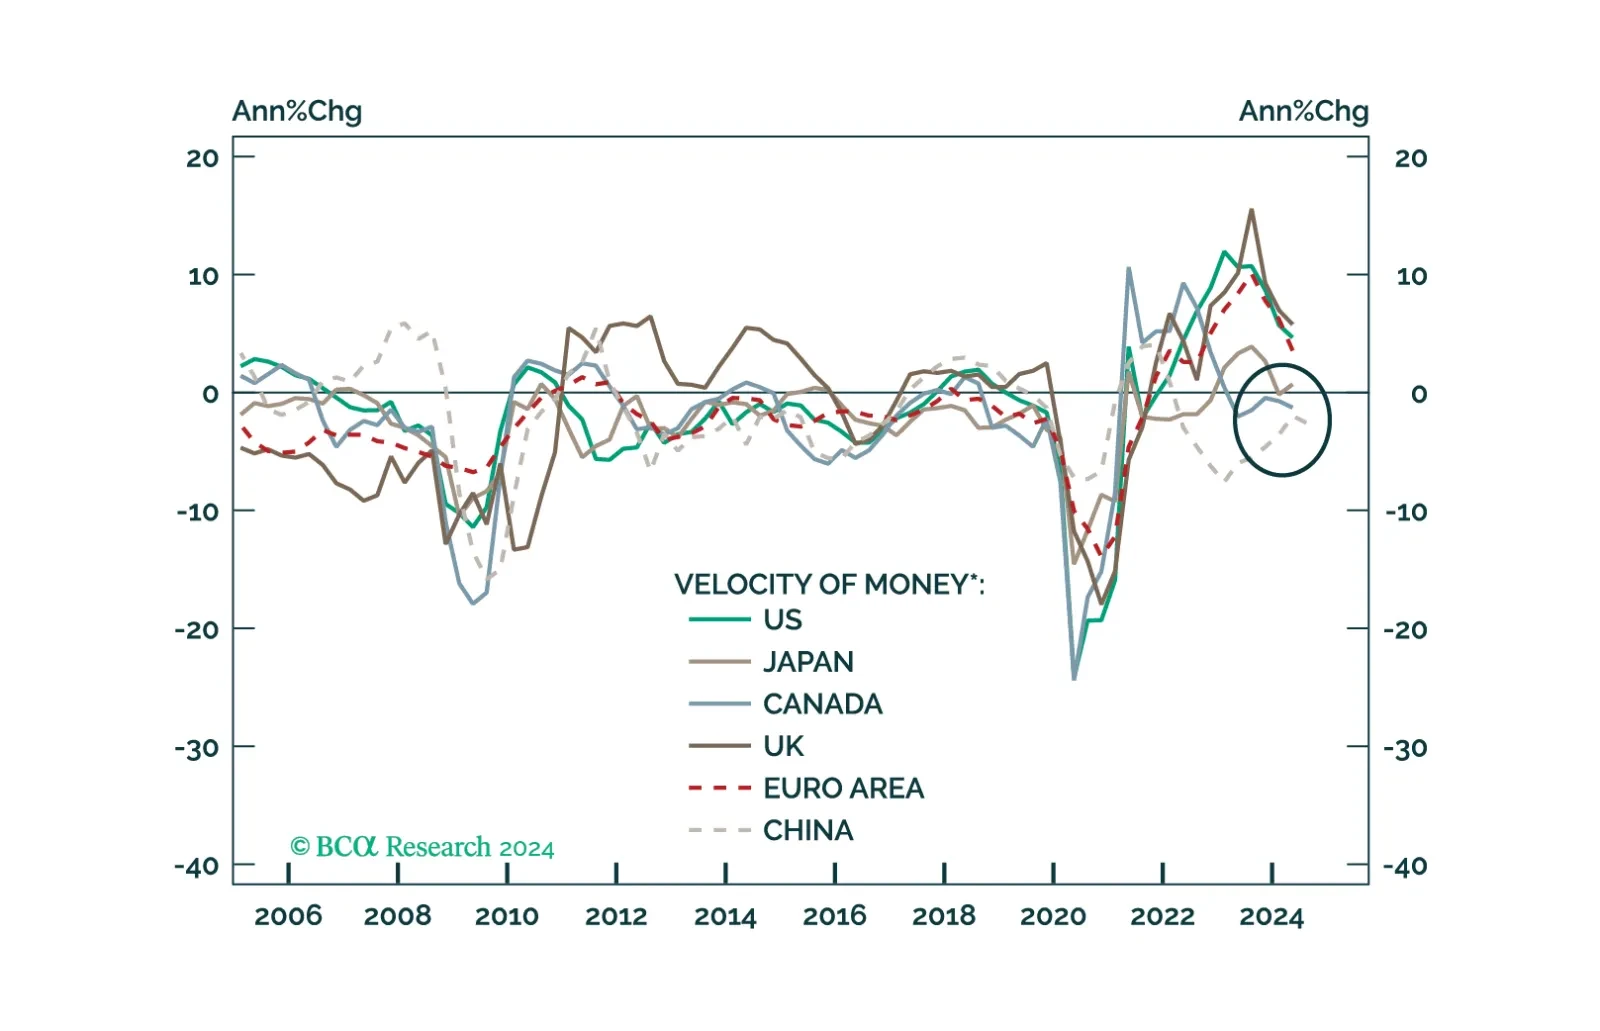
This Insight looks at the likely direction of bond yields and the dollar, from the lens of money velocity.
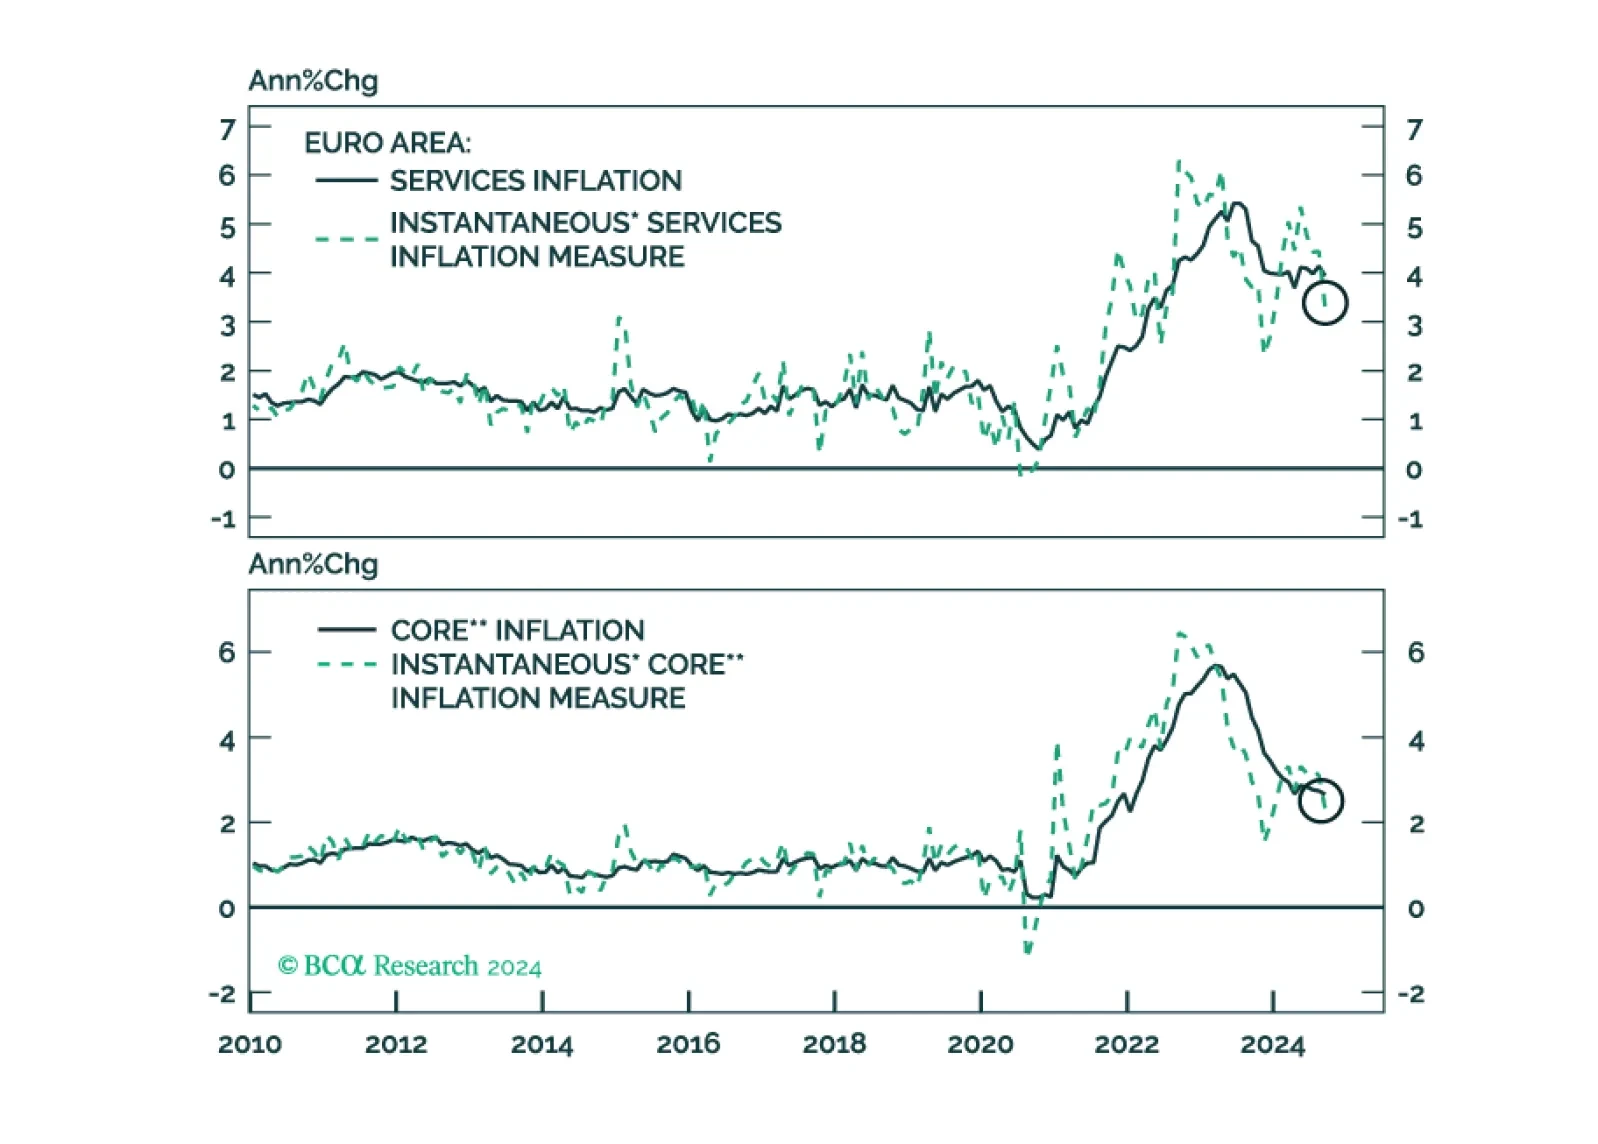
Yesterday, the ECB solidified its recent dovish tilt in response to weaker growth and decreasing inflationary pressures. It is now set to cut rates 25bps each meeting. How low will the ECB deposit rate ultimately go and what does this imply for yields and the euro?
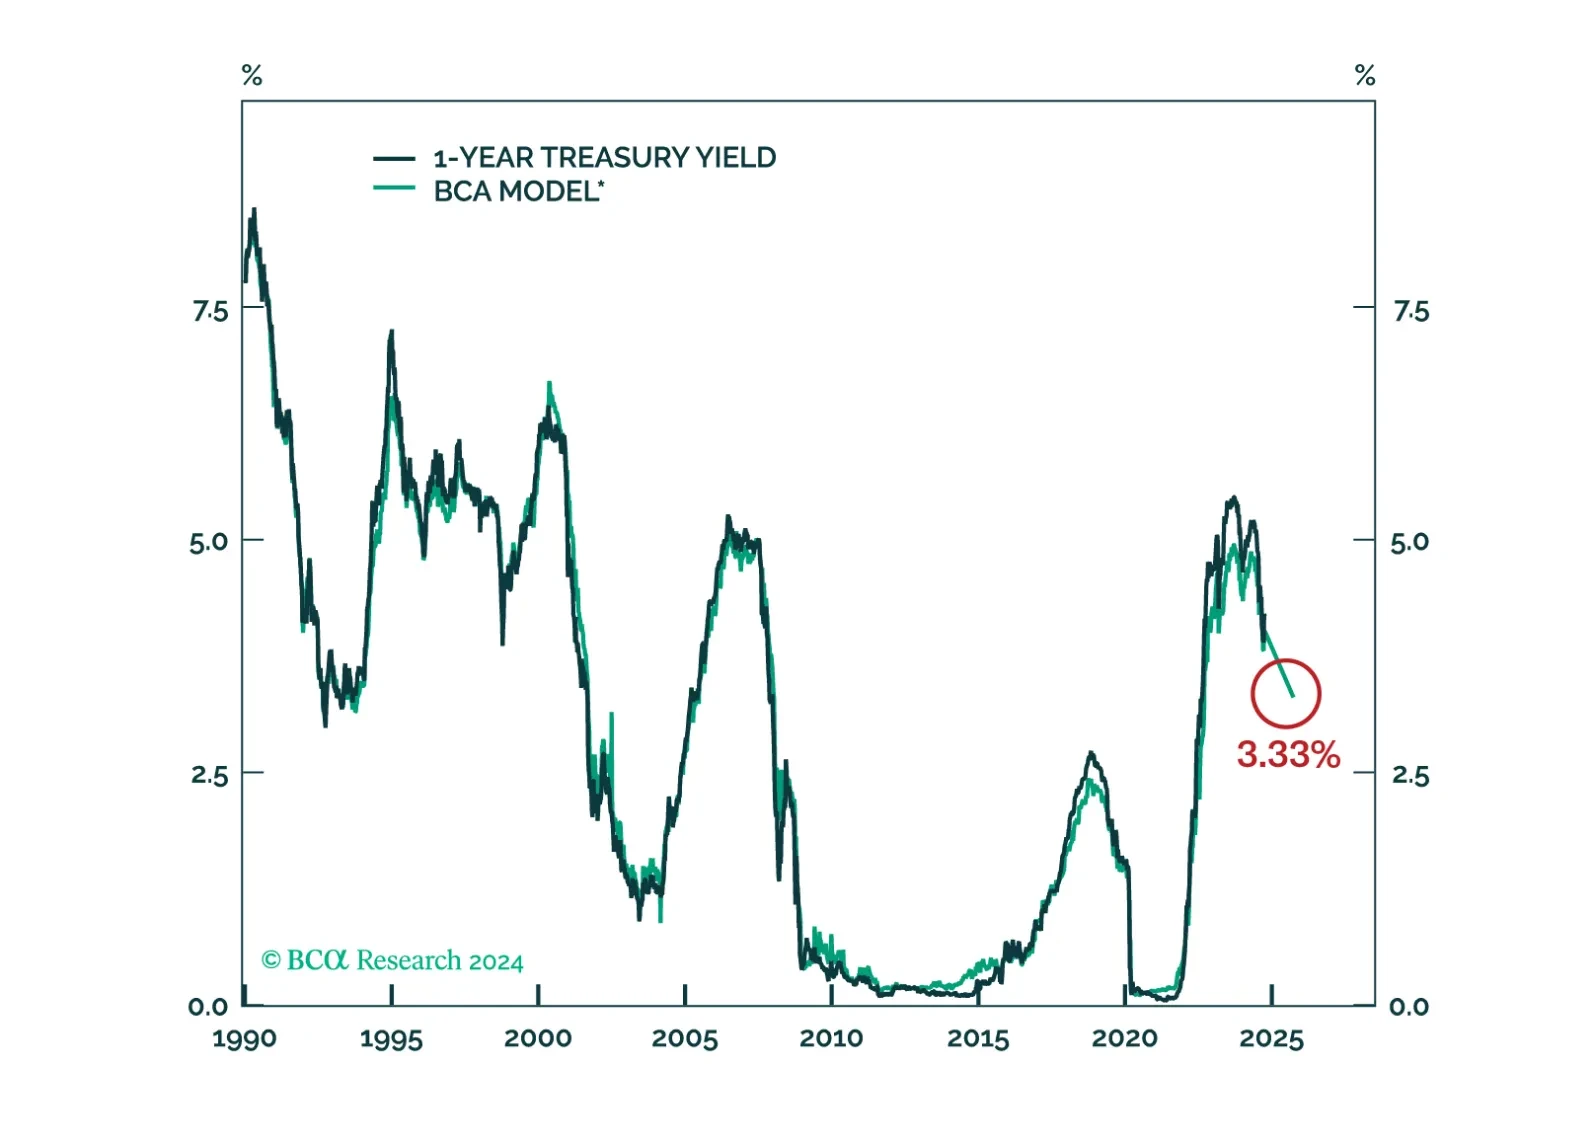
We estimate where Treasury yields might go in a soft landing economic scenario.
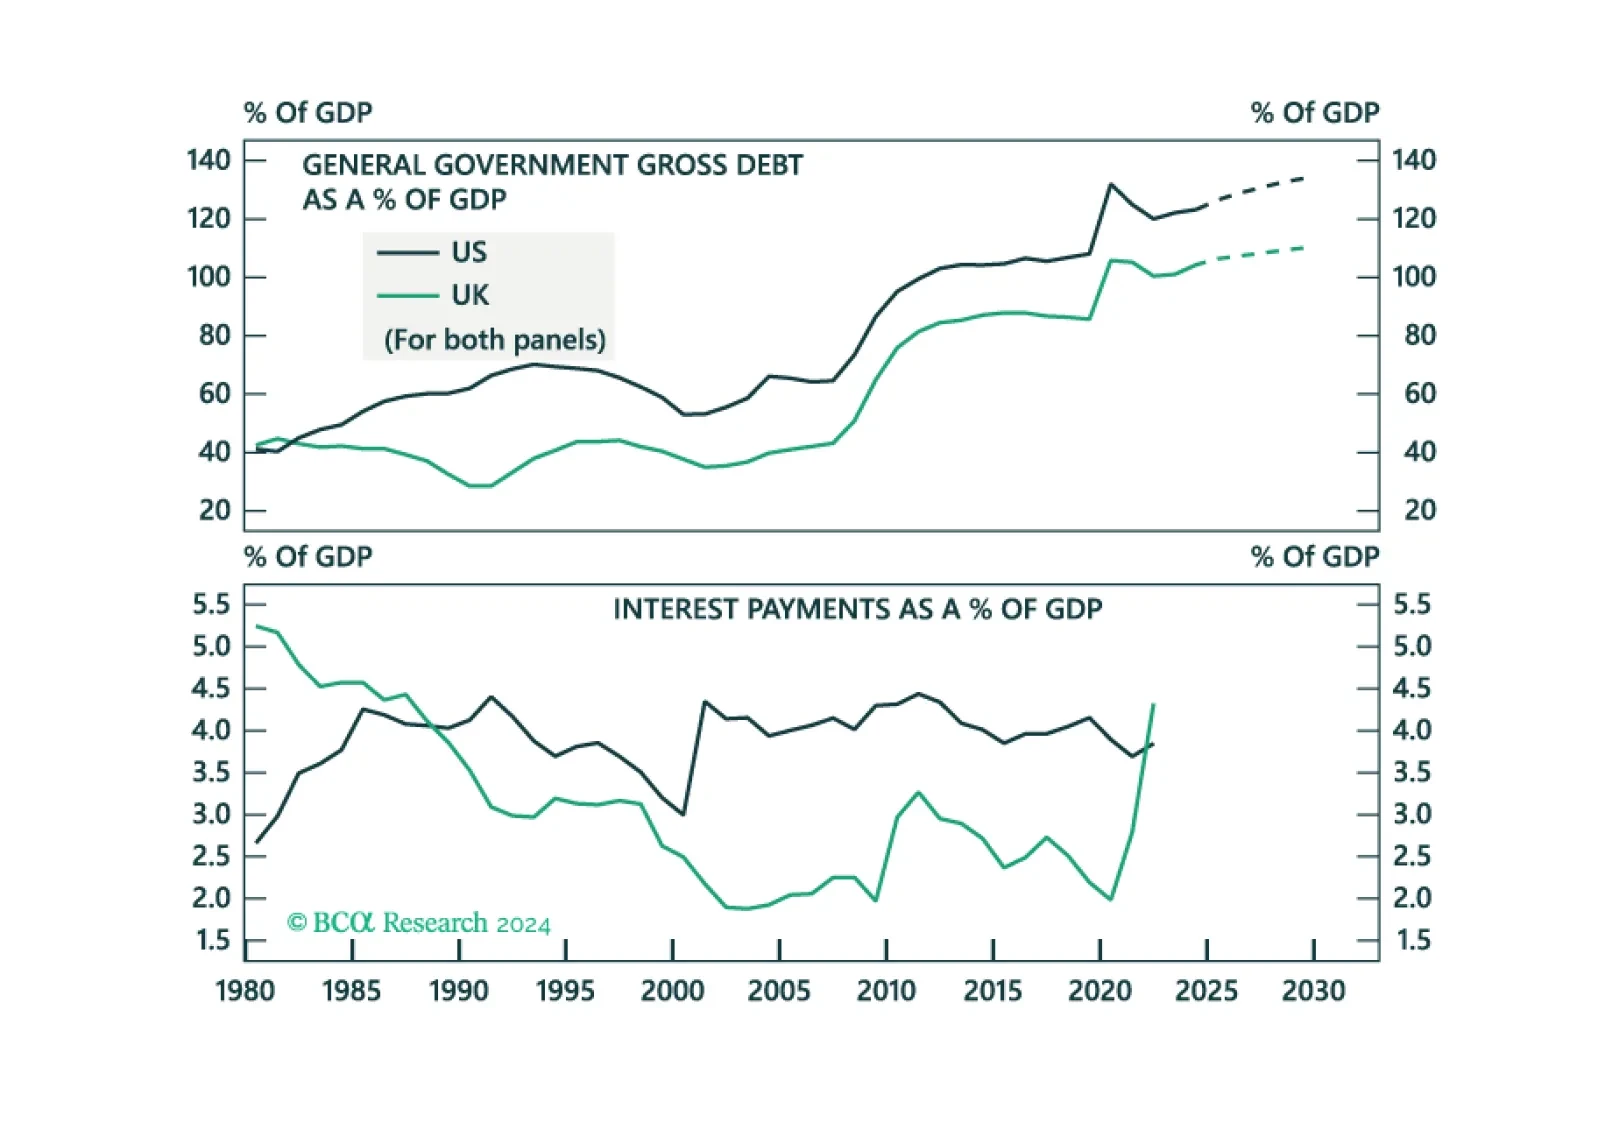
In this Insight, we assess whether investors should expect fiscal turbulence in the UK, that will drive UK yields higher and the pound lower.