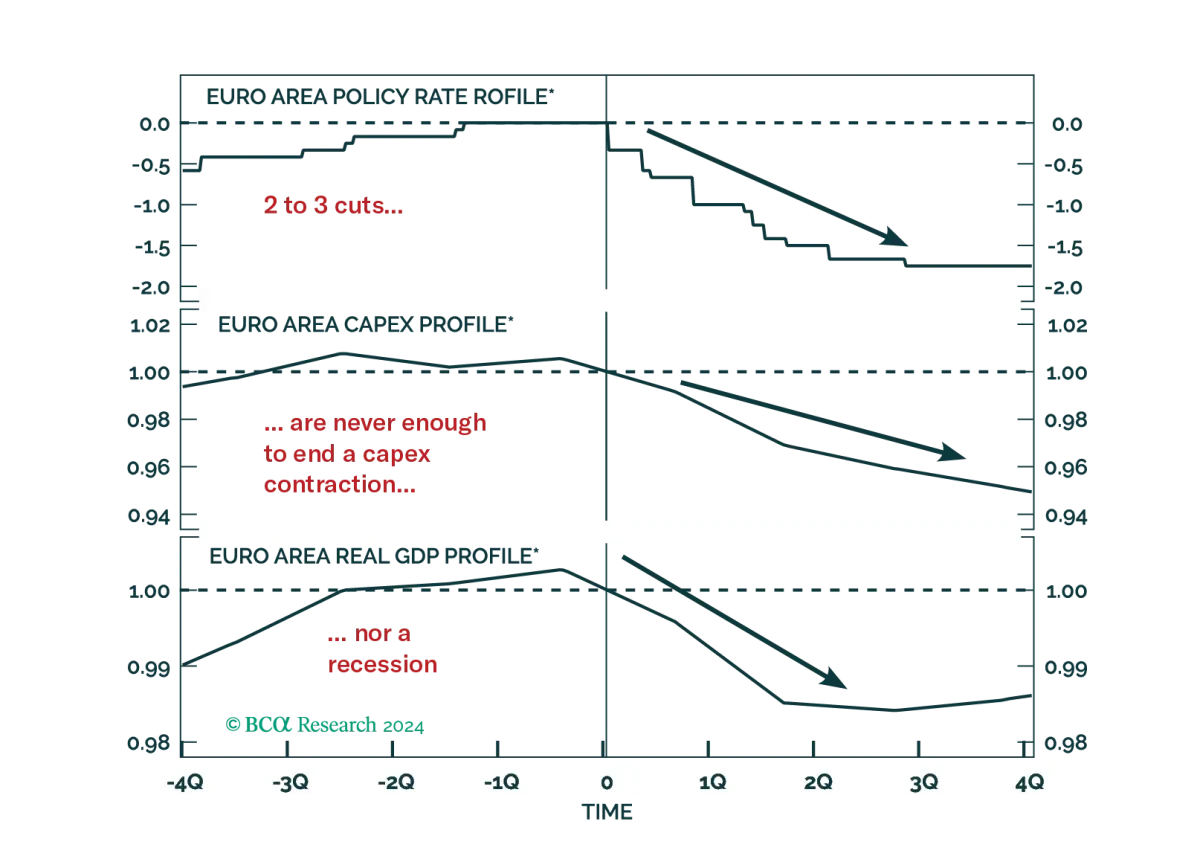
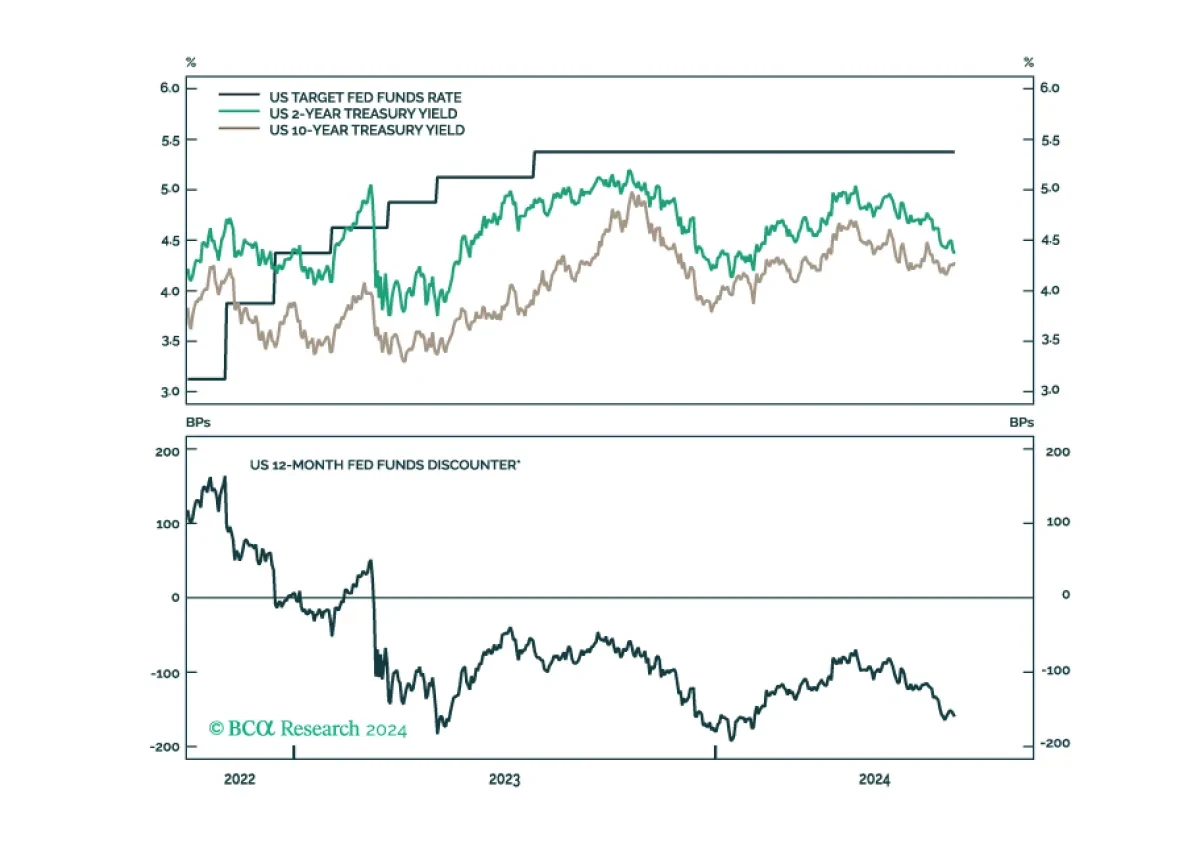
Investors hope that the ECB rate cuts priced into the curve will be sufficient to achieve a soft landing in Europe. History argues against this view, but will this time be different?...
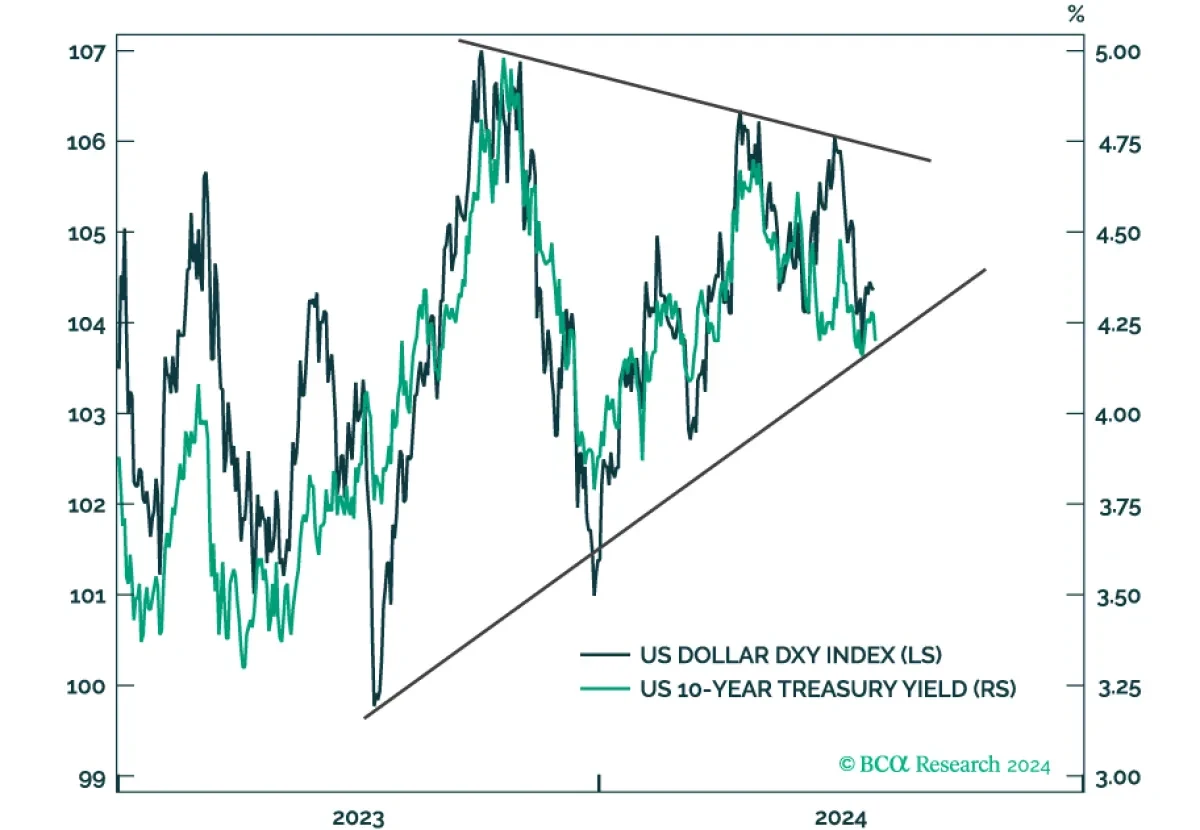
This report takes a look at bond and FX market technical indicators and calibrates the decision to increase portfolio duration and get long the US dollar....
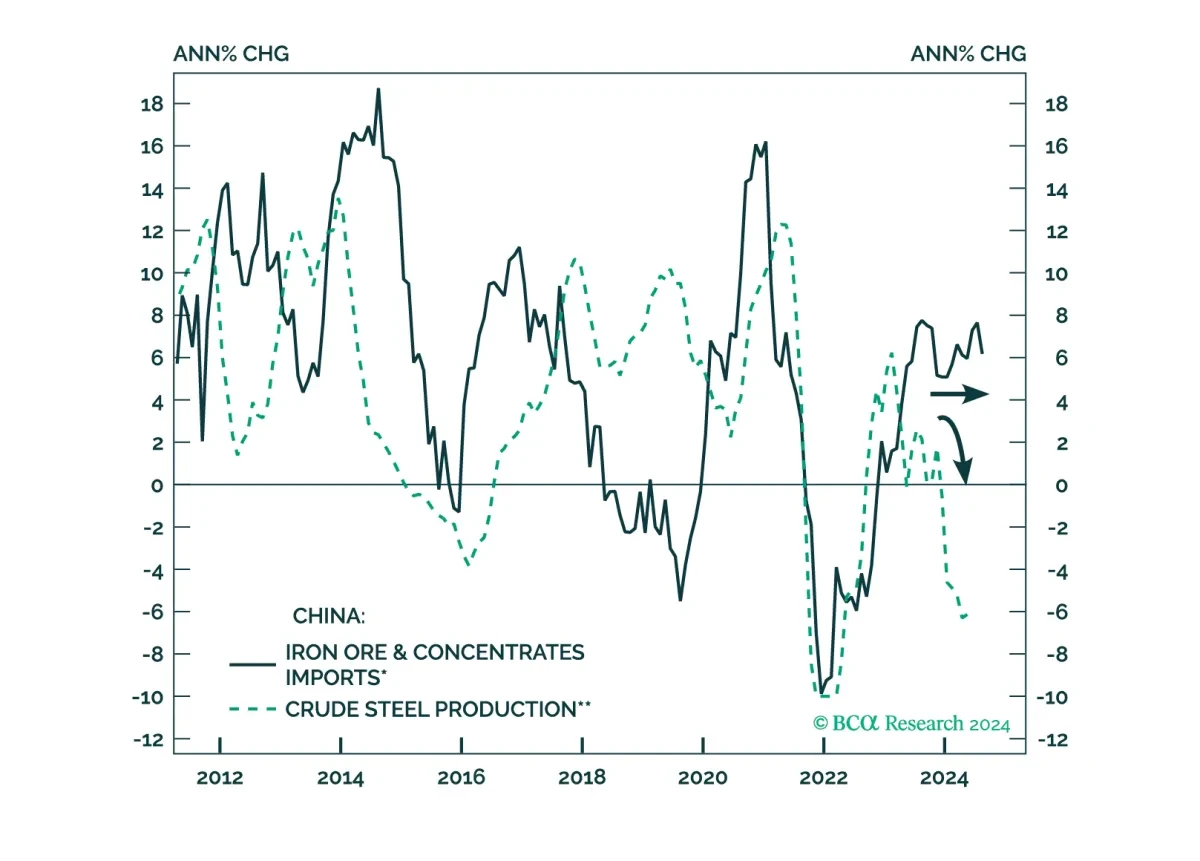
The absence of a catalyst that will boost Chinese steel demand dims the odds that iron ore and steel prices will recover over the coming six-to-nine months. Instead, we expect ferrous metals to face further downside into year-end....
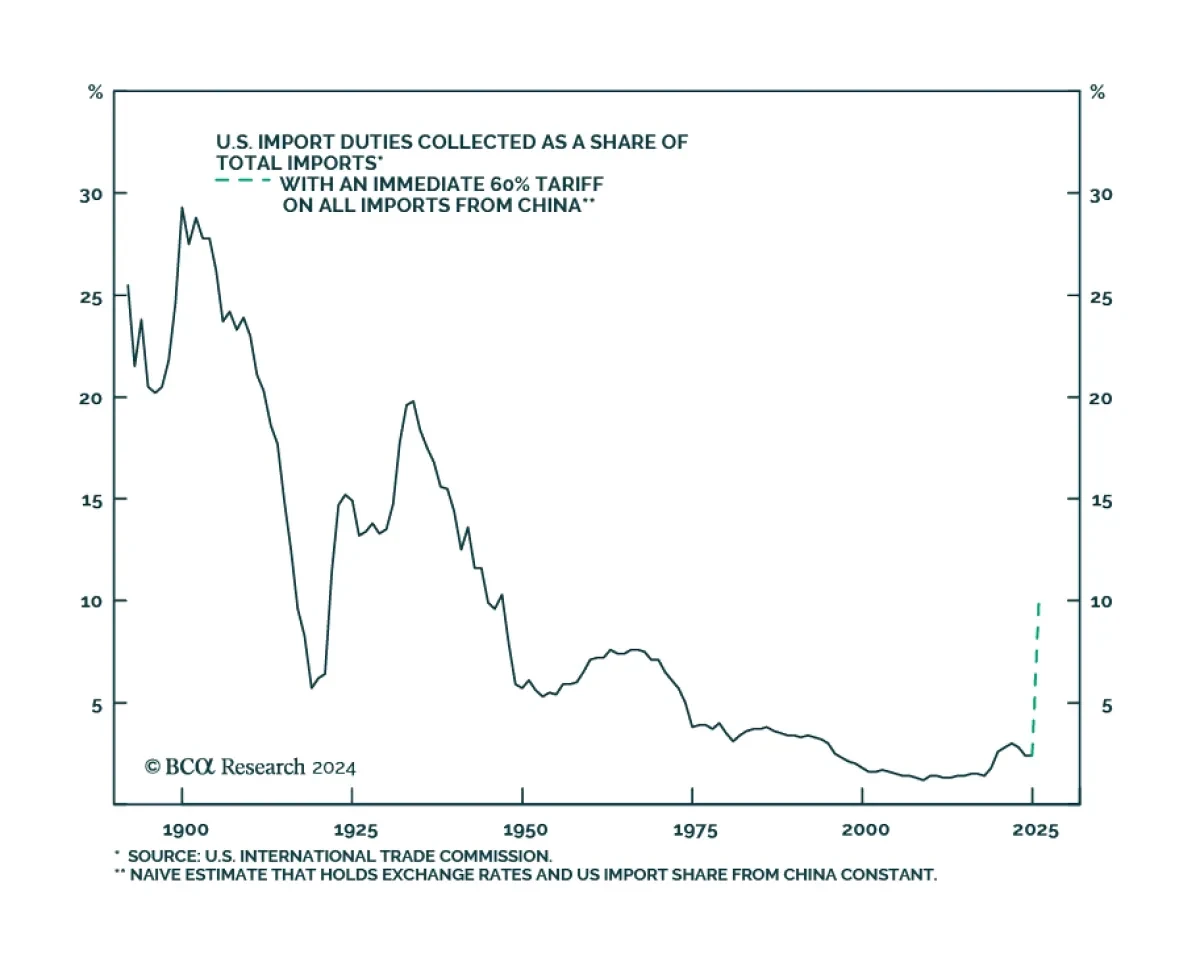
According to BCA Research’s Bank Credit Analyst service, trade policy under a second Trump presidency represents one of the greatest cyclical risks to investors. A key question for investors is whether tariffs are prioritized early in the administration or saved for later. Our colleagues expect the ...
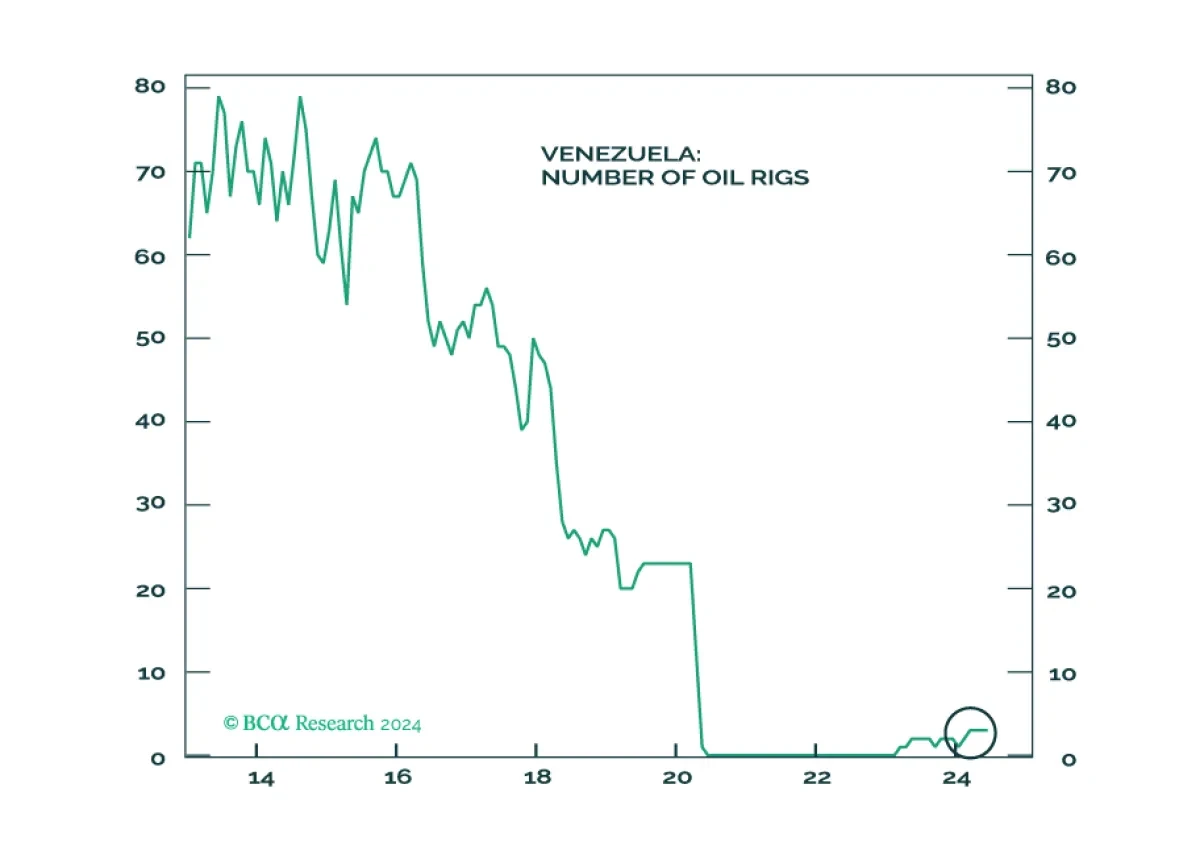
Oil markets will not be impacted by Venezuela in the near term, but by shocks from the Middle East. Maduro’s ability to stay in power in the short-term removes an avenue of oil supply relief. The same avenue is cut off if Trump is reelected. Geopolitical shocks in Venezuela could present tactical bu...
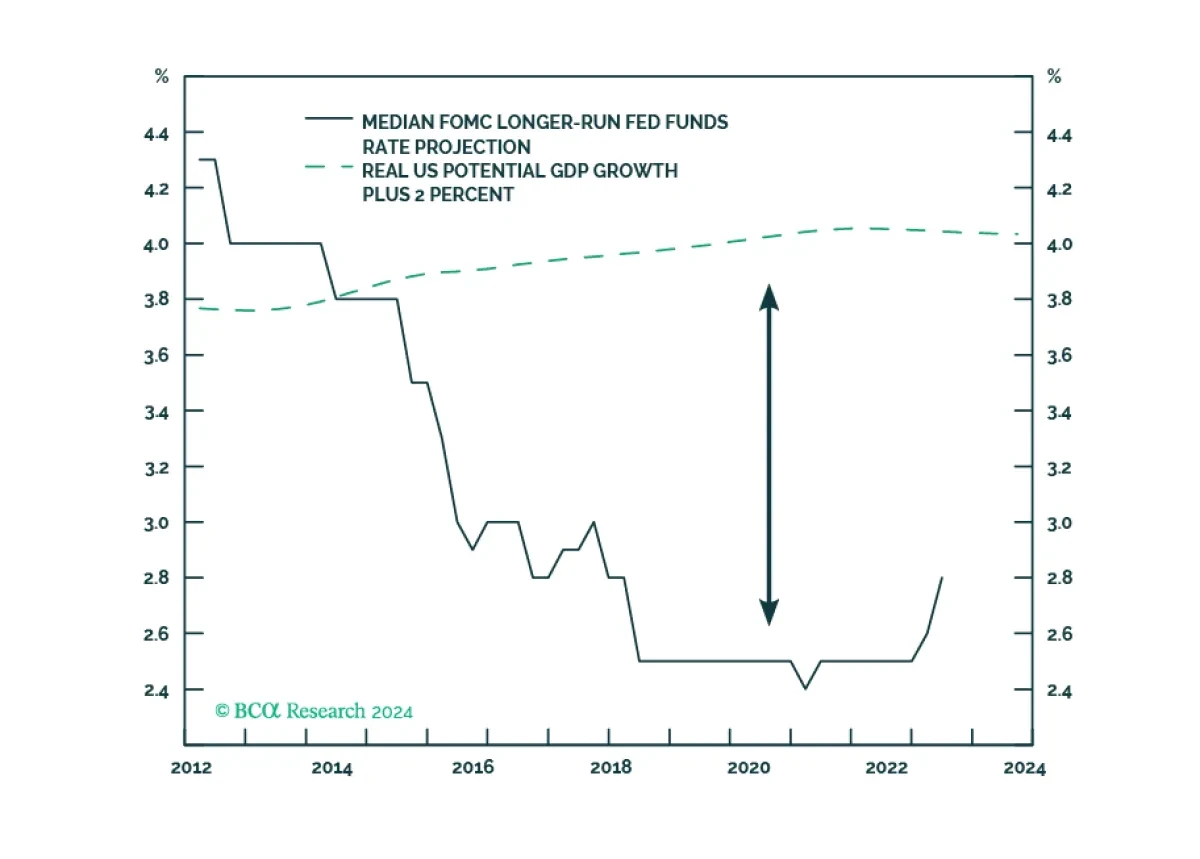
In this Special Report, Jonathan LaBerge of The Bank Credit Analyst argues that the Fed should abandon the framework changes that it made in 2020, both to its inflation and employment objectives. If “structural dovishness” is made a permanent feature of Fed policy, investors can expect more frequent...
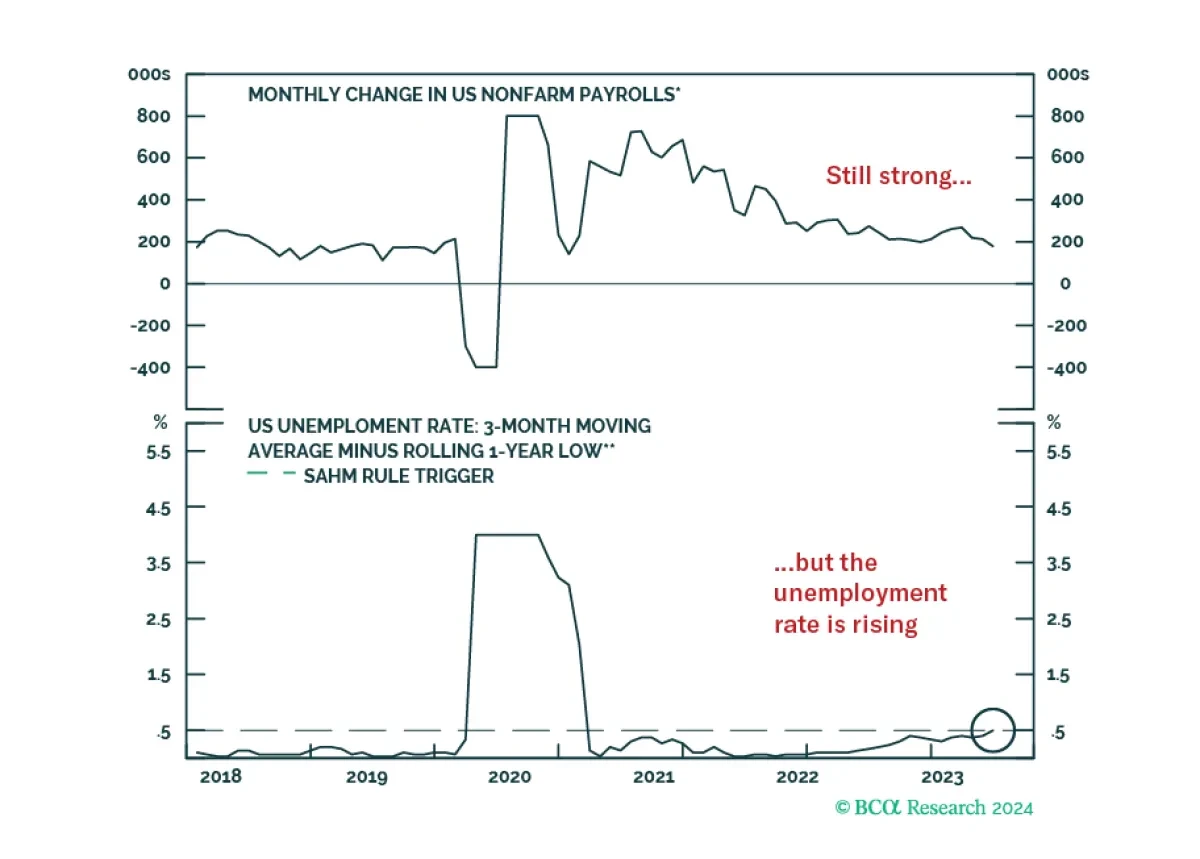
In Section I, we note that the US labor market is turning, and that the economy is indeed slowing to a recessionary tipping point. Disinflation continues, but not at a pace that would allow the Fed to cut aggressively outside of the context of a recession. We continue to expect that Donald Trump wil...
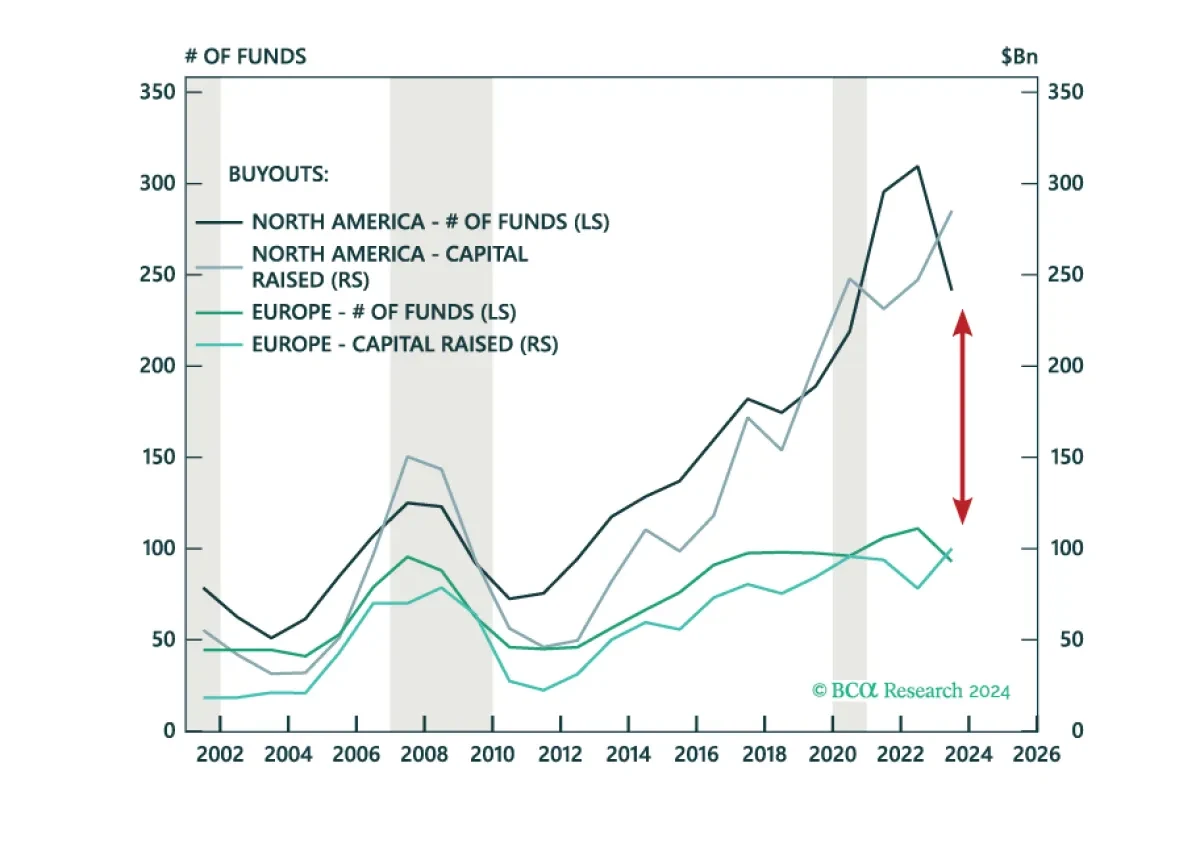
We are growing positive on Growth assets with recession expectations increasing our optimism on entry points. Equities are led by APAC Private Equity, North America Venture Capital, and Europe Buyouts. Our outlook continues to improve on CRE within the Inflation & Diversification bucket while we are...
After this morning’s jobless claims number, we have now seen enough deterioration in our preferred labor market indicators to increase portfolio duration from “at benchmark” to “above benchmark”....