Latest from BCA Research
This week we present our Portfolio Allocation Summary for November 2022.
While there is much variability in company profitability, earnings contractions have commenced and appear to be broad-based. We expect earnings growth to deteriorate further into year-end. Companies are reporting concerns about the trajectory of future economic growth and the uncertainty that it brings. Consumer spending on goods has slowed sharply, while spending on discretionary services has surprised on the upside. Business-to-business spending is still strong.
Europe is hampered by a lower trend growth rate, but has room to grow faster than the US over the next two years. How can investors profit from this outlook?
Financial markets slumped with the tough talk that followed last week’s FOMC meeting, but investors should recognize that the tone of the Fed’s communications is conditioned upon the inflation backdrop. Once it improves, Chair Powell and his colleagues will be able to relax their rhetoric.
In this report, we identify 5 key signposts that will mark a turn in the dollar. These include technical conditions, foreign real interest rates, US (and global) yield curves, Chinese economic conditions and geopolitics. We then assess whether it is time to short the dollar.
The Fed will slow the pace of rate increases but the terminal rate will be higher than initially expected. The Fed will not pivot any time soon. Economic pain is unavoidable. Equities will bottom shortly before economic growth bottoms.
As the FOMC explicitly acknowledged this week, monetary policy operates with substantial lags. We see the risks to stocks as tilted to the upside over the next 6 months but are neutral on global equities over a 12-month horizon.
US equities had a strong October after a positive start to the earnings season with USHQ and the benchmark returning 9.05% and 4.89% respectively. USHQ outperformed in all sectors except Energy and Industrials. The BCA Score Long/Short also performed well following strong returns from the Value, Safety, and Technical composite factors.
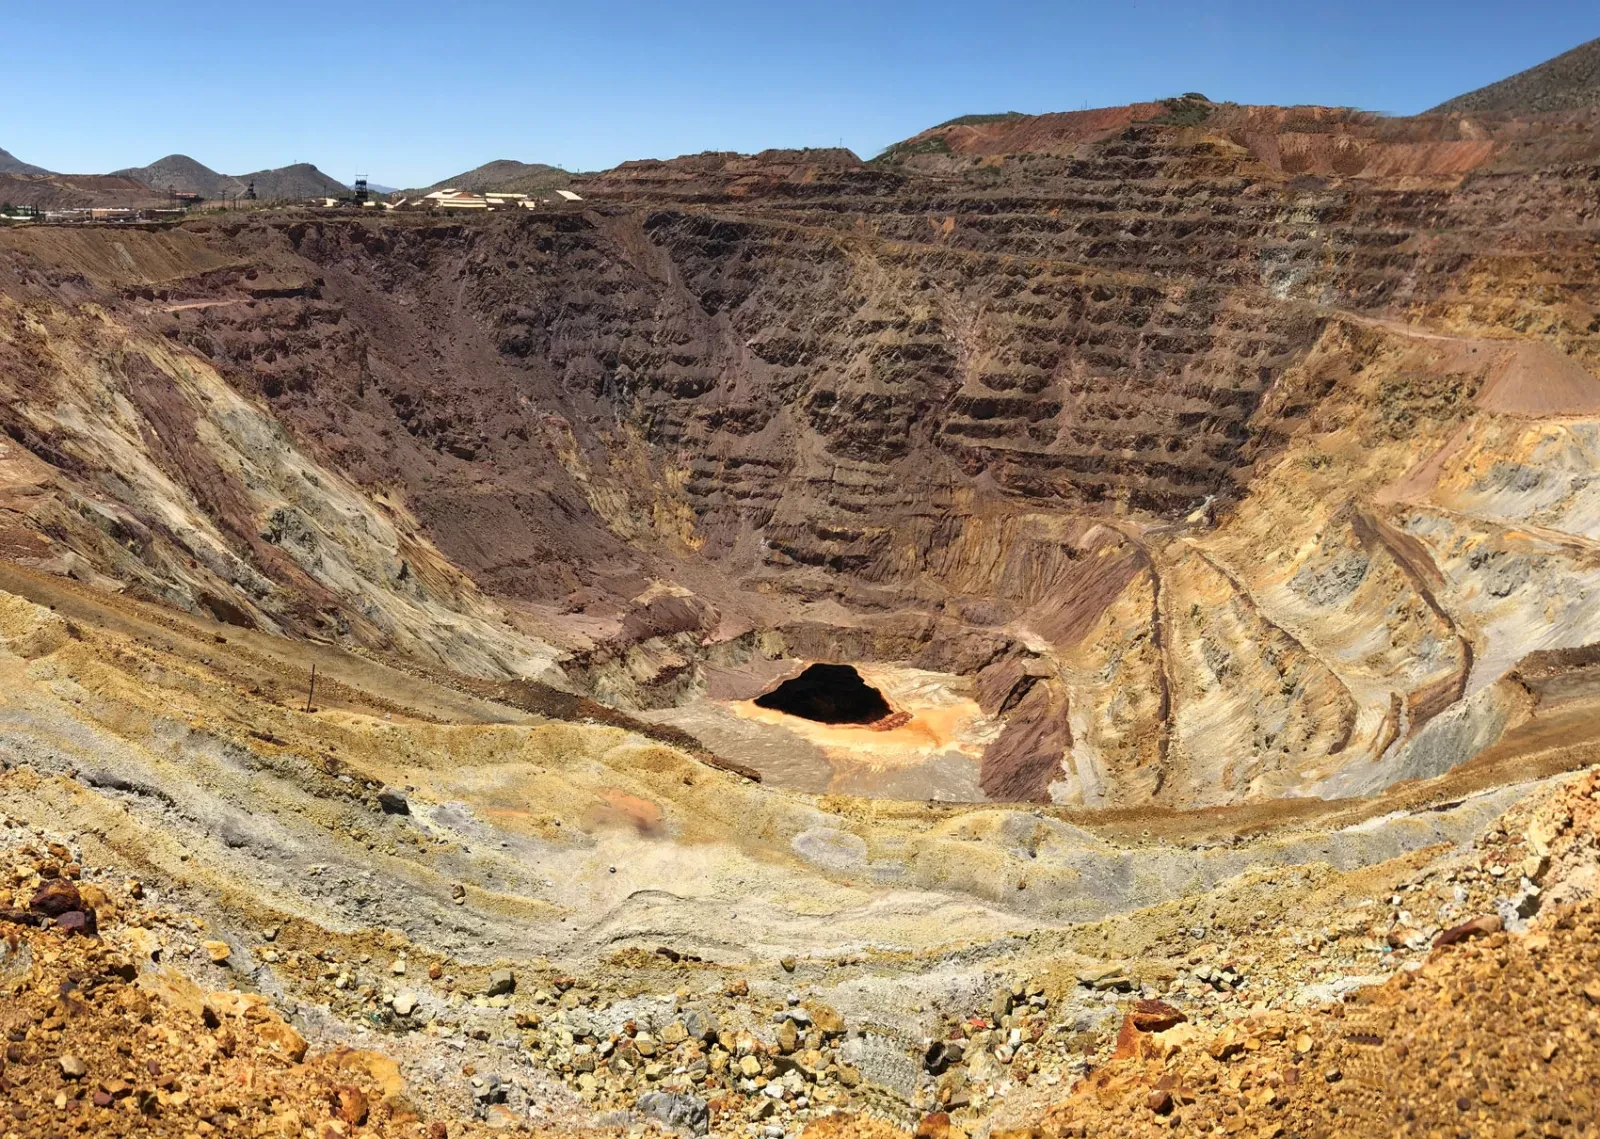
Copper markets will remain tight on the back of growing physical deficits and pressure on capex. Policy-rate increases by central banks, uncertainty over re-opening in China and its fiscal-stimulus plans in the short run restrain risk taking. In the long run, the implications of China’s inward turn will keep supply-concentration risk for metals high, given its dominance of base-metals refining globally. Notwithstanding the disconnect between physical and futures markets, we remain bullish metals mining equities, and remain long the XME ETF.
Provided that US inflation is due to excess demand rather than supply constraints, demand destruction will likely be needed to bring core inflation below 3.5%. Such growth contraction is positive for counter-cyclical currencies like the US dollar. In China, the Party's focus is to alleviate structural inequality and a long-term confrontation with the US; and authorities are not yet panicking about the cyclical state of the economy. Hence, an economic recovery is unlikely in the coming months.