Latest from BCA Research
In this report, we look at the possibility of a dollar decline during any pending recession. In our view, the evidence is mixed. We are probably in one of the most anticipated recessions in recent history, and the dollar has risen a lot. But the dollar also tends to rise during most recessions. We recommend a neutral stance on the DXY, with a bet on some trades at the crosses.
Excess job vacancies in the US and UK reflect a labour market that cannot efficiently match unemployed workers with vacant jobs. This is because excess job vacancies reflect the shortage of labour supply in the 50 plus age cohort, whose skills are difficult to replace. In economic jargon, the post-pandemic ‘Beveridge curve’ has shifted outwards. Absent an unlikely shift in the Beveridge curve to its pre-pandemic version, killing US wage inflation will mean killing jobs. And killing jobs will mean killing profits. We go through the investment implications.
We expect oil inventories to resume drawing and EU sanctions on Russian oil imports to tighten markets. We remain bullish oil and continue to expect 4Q22 and 2023 Brent prices to average $100/bbl and $116/bbl, respectively. We remain long the XOP and COMT ETFs.
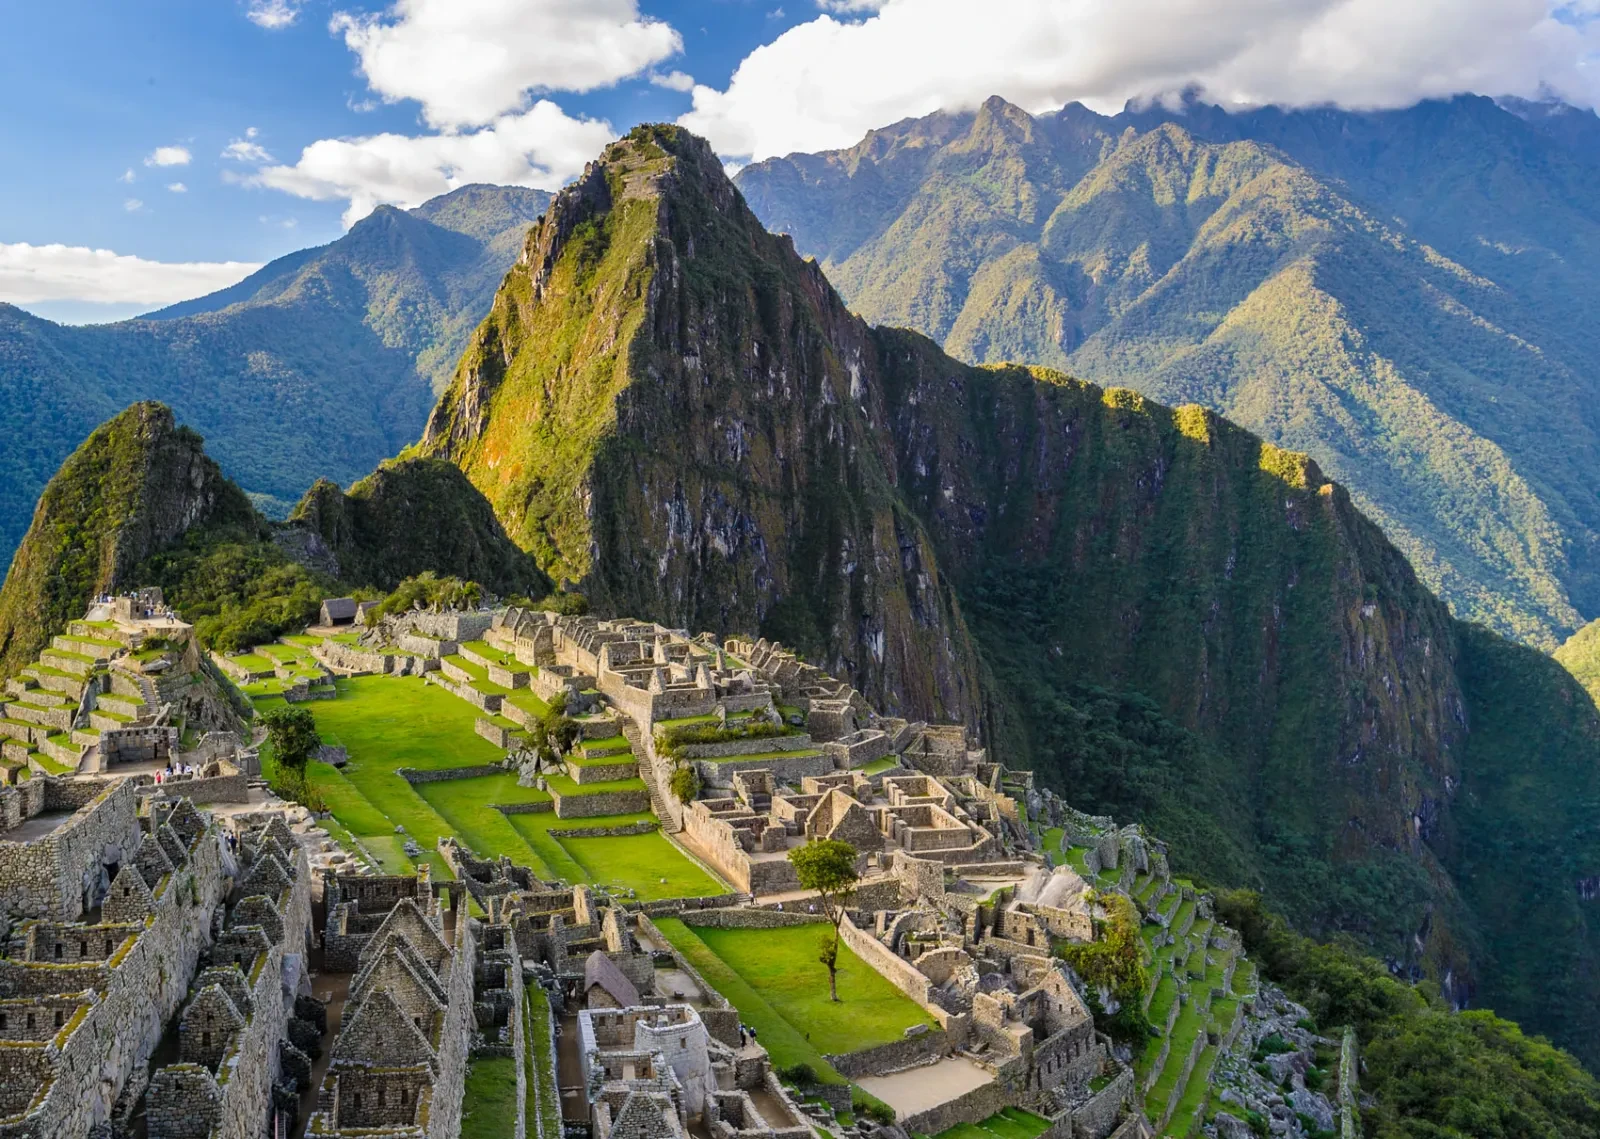
Peru is not suffering from economic or financial excesses: genuine inflation is subdued, fiscal and monetary policies are orthodox, and external accounts are healthy. While political instability has risen anew, markets will likely push through the political noise. Given this, we are upgrading Peruvian equities and local and sovereign USD bonds to overweight within their respective EM portfolios.
China is on the verge of experiencing a full range of deflation. Poor domestic demand will likely continue into 1H 2023 amid the ailing housing market, subdued private-sector sentiment and the zero-Covid policy, warranting a cautious stance on Chinese equities.
Airlines have staged an impressive recovery this year, exceeding all expectations. While companies are optimistic, we are cautious. Just as pent-up demand for travel will fade, headwinds from slowing growth and high inflation will intensify. While it is highly likely that Airlines will continue to rally into the yearend, we will stick to our underweight as our three-to-six-month outlook remains negative.
The latest CPI and PPI releases, the modestly less hawkish turn in Fed officials’ comments and evidence that consumers continue to spend with some relish support our constructive near-term views on equities and the economy.